Home Blog Page 947

Merricks v Mastercard: after nearly four years of highs and lows, the Supreme Court endorses a more lenient test for certification of competition claims in the UK

matercard

By Gurpreet Chhokar

Special thank you to Simon de Broise, Senior Associate at Collyer Bristow, for his contribution to this article.

In a hotly anticipated ruling, on 11 December 2020, the Supreme Court handed down its judgment in Merricks v Mastercard[1], a collective action seeking £14 billion in damages on behalf of a class comprising 46.2 million consumers, spanning across a 16-year infringement period, in relation to anticompetitive interchange fees set by Mastercard.

The Supreme Court dismissed (by a majority) Mastercard’s appeal against the criteria established in the Court of Appeal for the certification of collective proceedings by the Competition Appeal Tribunal (the CAT).

UK collective proceedings regime

Amongst the reforms ushered in by the Consumer Rights Act 2015 (CRA), which came into force on 1 October 2015, were updates to UK private competition law enforcement, intended to make it easier for individuals and small SMEs to bring proceedings in the UK.

The CAT already had jurisdiction to hear “opt-in” collective proceedings, whereby individual claimants are required to expressly join claims, but only one case was ever brought under this regime – demonstrating its shortcomings as an effective method of redress. The reforms enacted in 2015, introduced “opt-out” collective proceedings, in addition to the existing opt-in proceedings. Opt-out proceedings automatically include all UK domiciled claimants (those domiciled outside the UK must opt-in) unless they wish to expressly opt-out. Further, the CAT’s jurisdiction was extended to hear both follow-on claims (where a regulator has already issued an infringement decision) and stand-alone claims (where no prior infringement decision exists).

Key features of the collective proceedings regime include:

  • A process of “class certification” by the CAT – whereby the claim’s suitability, and the suitability of the class representative to represent everyone in the class, are assessed before a collective proceedings order (CPO) is made.
  • The ability to award aggregate damages without having to make an assessment of the damages to be awarded to each class member.
  • Safeguards to prevent unmeritorious claims– including the prohibition on damages-based agreements between claimants and their lawyers, restrictions on the type of person who can act as “class representative” and checks and balances in relation to legal costs funding arrangements.

As for the certification criteria, for a CPO to be made the CAT must be satisfied that: (i) the class representative is someone who the CAT could authorise to act as a class representative; and (ii) the claim is eligible for inclusion in collective proceedings[2].

The CAT will only authorise a class representative if it is “just and reasonable” to do so and will have regard to certain criteria when determining this[3]. As to whether the claim is eligible for inclusion in collective proceedings, having regard to all circumstances, the CAT will need to be satisfied that the collective proceedings are: (i) brought on behalf of an identifiable class of persons; (ii) raise common issues[4]; and (iii) are suitable to be brought in collective proceedings[5]. As to suitability, which was the main issue in the Supreme Court’s ruling, the CAT is to take into account all matters it thinks fit, including but not limited to matters such as whether collective proceedings are an appropriate means for the fair and efficient resolution of the common issues, the size and the nature of the class and whether the claims are suitable for an aggregate award of damages etc.

Background to Merricks v Mastercard

A European Commission decision of 19 December 2007 found that Mastercard had breached European competition laws in relation to the setting of multi-lateral interchange fees (MIFs) that were charged between issuing banks (on behalf of cardholders) and acquiring banks (on behalf of merchants) for transactions using Mastercard issued credit and debit cards.

In September 2016, Mr. Walter Merricks, the class representative made a CPO application to commence collective proceedings on an opt-out basis for damages arising from the Commission’s decision. Mr. Merricks (both class representative and a class member) has held various senior positions in legal and public institutions, including the Financial Ombudsman Service, and has dedicated his career to legal and consumer affairs. The proceedings are being funded by a third-party funder. The proposed class was very wide in that class members did not even have had to own or use Mastercard credit or debit card for their purchases. Mr Merricks alleged that the price increases which merchants passed-on in respect of the MIFs were applied to all purchasers, not just those purchasers using cards (though business customers using Mastercard are excluded).

The Merricks v Mastercard case had a far from straightforward procedural history, having taken Mr. Merricks nearly four years to reach this point. The CPO application hearing was held in the CAT in January 2017.The CAT refused the CPO application sought by Mr. Merricks. Broadly, the CAT did not think that the claims were suitable for collective proceedings, specifically because: (i) the claims were not suitable for an aggregate award of damages; and (ii) Mr Merricks’ proposals for distribution of any aggregate award did not respect the compensatory principle which the CAT considered was an essential requirement of any distributive scheme.

Subsequently, after various rounds in the appellate courts, the Court of Appeal (the COA) in November 2018 confirmed that it did have jurisdiction to hear and determine Mr. Merricks’ appeal insofar as it raised a point of law.

On 16 April 2019, the COA handed down its judgment in relation to Mr. Merricks’ CPO application[6]. The COA, in large part, rejected the CAT’s interpretation of the certification criteria and allowed Mr Merricks’ appeal. Unsurprisingly, given the breadth of the class and the damages involved, Mastercard made an application to appeal the COA’s judgment to the Supreme Court.

The Supreme Court found that the CAT had made five errors in law when considering Mr Merricks’ CPO application.

Key findings in Supreme Court’s decision

This was the first collective proceedings case of this kind to reach the Supreme Court, the UK’s highest court for civil appeals. There was a 3/2 majority in the Supreme Court, with Lord Briggs giving the main judgment on behalf of the majority.

The Supreme Court found that the CAT had made five errors in law when considering Mr Merricks’ CPO application. Lord Briggs said that his reasons largely concurred with the COA but provided his own reasoning in full.

First, the CAT had got the “common issues” question in relation to the passing-on of the overcharge to the class members by merchants wrong (otherwise known as the merchant pass-on issue). It was a common issue and should have been “a powerful factor in favour of certification”[7]. In Lord Briggs’ view, the remainder of balancing exercise carried out by the CAT never recovered from this starting point.

Second, the CAT treated the suitability of the claims for aggregate damages as if it were a hurdle rather than merely a factor to be weighed in the balance. For context, at the CPO hearing before the CAT, Mr Merricks’ experts had put forward a methodology supporting an award of aggerate damages. After cross examination of the experts by the CAT, as well as Mastercard’s counsel, the CAT was concerned about the availability of data, therefore making the quantification of damages unreliable on a class-wide basis. The majority of the Supreme Court agreed with the COA that whether a claim was suitable for aggregate damages was one of many relevant factors in the suitability assessment under Rule 79(2) and not a condition.  

Third, the CAT failed to make a comparison between collective and individual proceedings when having regard to the difficulties in relation to quantification of damages of the pass-on merchant issue. An individual claimant would have faced the same difficulties when seeking compensation for increased retail prices across various sectors of the market. If such obstacles would have been considered insufficient to deny a trial to an individual claimant who could show an arguable case as to suffering some loss, then by equal measure they should not have been sufficient to deny certification for collective proceedings[8].

Fourth (and the most serious error in the majority of the Supreme Court’s view), was that the CAT was wrong to move away from the basic principle that courts should try to quantify claims even if there are difficulties quantifying damages due to lack of evidence. Indeed, it was pointed out that these were problems grappled with by the courts and tribunals daily. Instead, the CAT (wrongly) focused on the possible limitations of the data available at trial in arriving at its decision that the claims were unsuitable.

Fifth, the CAT was wrong to regard the compensatory principle as an essential element in the distribution of aggregate damages. There was no requirement to assess individual loss when claiming aggregate damages. The majority held that this was a clear error in law. The CAT’s interpretation was at odds with the very purpose of the legislation – being the ability to award aggregate damages in collective proceedings, thereby avoiding the need for individual assessments of loss.

Finally, a further interesting aspect of the Supreme Court’s ruling is Lord Briggs’ remark that “the certification process is not about, and does not involve, a merits test”[9], which he went on to explain is subject to two exceptions: (i) where a separate application for strike-out or summary judgment is made at a CPO hearing; and (ii) where the court is required to assess the strength of the claims in the context of a choice between opt-in and opt-out proceedings[10]. However, as to what this merits analysis would entail for the second exception was not developed.

Future implications

Depending on which side one finds oneself, the Supreme Court’s judgment will have many implications on future collective proceedings. These include:

  • Damages do not have to be apportioned to reflect individual loss on a purely compensatory basis.
  • Lack of data/evidence does not act as a hurdle when bringing collective proceedings; the CAT must try to quantify the claim as best as it can with what information is available.
  • Parties have more clarification around the “suitability” requirement – which is to be determined according to whether a claim is more suitable to being brought on a collective basis as compared to an individual basis.
  • With a more lenient test for certification, it is likely that more claims will pass the certification stage and proceed to trial. Of course, claimants will still be exposed to hurdles which arise in any litigation.
  • The ruling facilitates the principle of access to justice, particularly for consumers and smaller SMEs (who were at the heart of the CRA 2015 reforms). However, those SMEs and institutions on the wrong side of competition law have increasing exposure to collective proceedings and potentially large damages pay-outs.

A green light has been given for those collective proceedings postponed pending the Supreme Court’s ruling on the certification test. These cases will now be able to proceed in the CAT. Waiting in the wings is the Justin Gutmann v First MTR South Western Trains Limited CPO application in relation to rail ticket fares/boundaries. As this is a stand-alone claim and so no prior existing infringement decision exists, there may be an interesting debate on the merits. Also, worth mentioning are the two competing opt-out collective actions, namely, Michael O’Higgins FX Class Representative Limited v Barclays Bank PLC and Others and Mr Phillip Evans v Barclays Bank PLC and Others, which concern the FX cartel. The European Commission fined five banks for participating in two cartels in the Spot Foreign Exchange market for 11 currencies. Here, the CAT will have to decide between two competing class representatives (which is the first time it will have had to do this). Whilst the Supreme Court’s ruling has provided much needed clarity, the CAT will still have to deal with many interesting and novel issues.  

The Supreme Court’s ruling is a timely reminder for companies to ensure that they are fully compliant with competition law.

Re-visiting compliance

Once again, the Supreme Court’s ruling is a timely reminder for companies to ensure that they are fully compliant with competition law. Companies not only risk substantial fines from regulators, but they are also exposed to private damages claims, and, now, a potential increase in collective proceedings.

Broadly, companies should think about the following:

  • Risk identification

What are the key competition law risks? Depending on the nature of the business or operations, these can take the form of cartels, or other types of anti-competitive agreements such as granting exclusivity (or imposing other terms of sale or purchase), refusal to supply, excluding competing firms from a market etc.

  • Risk assessment

Assessing the risks identified and categorising them as low, medium or high depending on the level of the risk. How many staff are exposed to the identified risks? For example, senior management, those dealing directly with competitors (i.e. sales departments, procurement and purchasing), and those attending trade associations.

  • Risk mitigation and Re-review

Companies should implement training, policies and procedures, both at a general level and a more targeted level, in the case of certain categories of employees. Examples include ensuring employees obtain approval before joining any trade associations, instructions/checklists on what employees should do if they receive commercially sensitive information from a competitor, designating an individual as a competition compliance officer etc. Importantly, companies should re-review the steps above regularly as risks and legal requirements will evolve over time.

Looking ahead

The Merricks v Mastercard case will be remitted to the CAT for a re-hearing and if the CPO application is successful, it will proceed to trial. The Supreme Court’s judgment is a resounding triumph for Mr. Merricks, as well as claimants more generally, with a more lenient test for certification of claims being adopted. This is a welcome boost for the collective proceedings regime, which has had a chequered history since its inception, and will hopefully further increase the effectiveness of private enforcement of competition law in the English Courts. It is likely that we will now see more proceedings pass the certification stage in the foreseeable future, thereby facilitating greater access to justice and redress for consumers and small SME’s affected by anticompetitive conduct. There is no doubt that this is a big win for claimants.

About the Author

Gurpreet

Gurpreet Chhokar is an associate with expertise in high-value competition damages claims before the High Court and Competition Appeal Tribunal. Gurpreet has a particular interest in the private enforcement of damages as a result of anticompetitive breaches, as well as consumer redress.

References

  • [1] UKSC 2019/0118 (the Judgment)
  • [2] Rule 77 of Competition Appeal Tribunal Rules (CAT Rules)
  • [3] Rule 78 CAT Rules
  • [4] “common issues” means the same, similar or related issues of fact or law (see Rule 73(2) CAT Rules)
  • [5] Rule 79 CAT Rules.
  • [6] [2019] EWCA Civ 674
  • [7] Paragraph 66 of Judgment.
  • [8] Paragraph 71 of Judgment.
  • [9] Paragraph 59 of Judgment.
  • [10] Rule 79(3)(a) CAT Rules

Finetero Review – A Generous Stocks CFDs Offer?

trading

Finetero Background

Finetero is an online trading brand that aims to provide multi-asset trading at your fingertips via an optimized trading offer crafted over the years. Operating since 2018, the company continues to experience exponential growth on the back of high-end trading specs.

Maintaining security, liquidity, and enabling a safe and efficient trading environment for all clients is one of the main goals, putting Finetero high on the global rankings.

Stocks in leading markets continue to benefit from massive inflows and thanks to the Finetero offer, traders can get involved with thousands of CFDs, taking advantage of both rising and falling markets. Are ultra-fast order execution, an industry-leading trade engine, and powerful security guaranteed when trading with Finetero? Let’s explore its offering and see whether this an optimal place to trade stocks.

Finetero logo

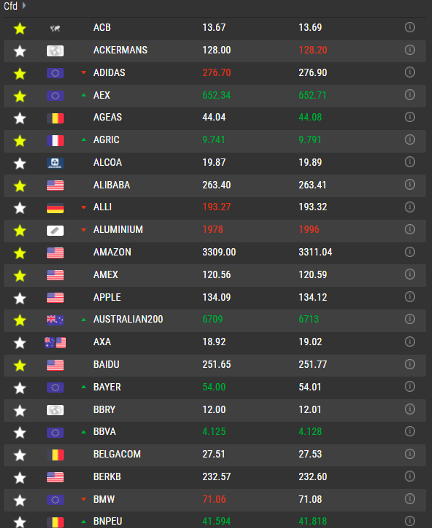
Finetero Stocks CFDs offer

Few would have thought that a global pandemic will ultimately be positive for global stocks. However, that is exactly what’s happening as retail and institutional entities see financial assets as a hedge against the diminishing purchasing power of fiat currencies.

Because Finetero offers CFDs on stocks, traders working with this brand can take advantage of the market volatility, in both bullish or bearish trends, with up to 1:10 leverage, and flexible spreads. Advocating for full transparency, Finetero offers all the relevant information on its website or via the dedicated customer support team available every day.

Alibaba, Bayer, Bank of America, Johnson & Johnson, Apple, Amazon, Google, Netflix, BMW, Coca-Cola, Ferrari, and other brands can be traded at Finetero, given the diversity of the asset coverage.

Finetero stocks CFDs

Trade stocks CFDs with professional software

A complex asset list is not enough to ensure optimal trading conditions and the trading platform plays a key role in whether traders can benefit from liquidity or accurate pricing. Finetero works with multiple liquidity providers and offers support for the popular MetaTrader 4, a platform with 15+ years of reputation.

Retail CFD traders continue to view MT4 as a viable trading solution even for stocks, considering the advanced charting, support for EAs, price alerts, and other customization features. Downloadable for desktop, smartphone, or tablet, this platform can be used on any type of device.

Additionally, Finetero offers a WebTrader as the second platform of choice, to ensure broader diversity. Same as MT4, this is another reliable platform worth considering, thanks to its simple user interface, flexibility, and the wide array of tools built into it.

Main Trading Benefits

An online education center, variable spreads starting at 0.1 pips, 50% stop out levels, and many different features associated with the 5 trading account types currently available, are some of the main benefits for those deciding to trade stocks CFDs with Finetero.

The brand is constantly focused on providing added value via trading tools and features with proven efficiency. Trading Central resources, access to event room, or private trading sessions, are also part of the offer and can serve as a guide for retail traders looking to expand their market knowledge.

Finetero capabilities

Pros and Cons

  • Competitive trading conditions for stocks CFDs
  • Popular and reliable trading software
  • Online chat support for all customers


  • Few advanced educational resources
  • Customer support available in English

Finetero Conclusion

Favored by the increased interest in stock trading, Finetero is a brand providing a very interesting offer for retail traders in various countries around the world. Its commitment to ensuring optimal conditions is one of the many reasons why this is a reliable trading brand. Further support is granted via multiple resources, with the main goal of teaching traders how to make rules-based trading decisions and get involved in the markets professionally.

6 Risk Management Strategies for Online Traders

online trading

Risk management must always form part of your core trading strategy – whether you are a professional or amateur online trader. Protecting the money you make is the sure way to make a consistent profit and secure a long, successful trading career.

Risk is a critical prerequisite to successful online trading. Besides, without a risk management strategy, traders who generate substantial profits over months can lose it all in one or two bad trades. Also, using indicators alone to make a profit can only get you so far, especially if you fail to protect your positions.

So how do traders develop the best techniques to curb and mitigate the risks of the market? This article discusses six strategies you can use to protect your trading capital and profits.

1. Use the One-Percent Rule

Capital protection should be the priority of any trader, hence the use of the one-percent rule. It requires you not to risk over one percent of your trading capital in one trade. The conservative rule ensures that you never risk more money than necessary in one trade.

2. Formulate a Trading Plan

Before you start trading, you need to have a trading plan with a suitable risk-reward ratio (R: R). It’s a strategy to follow while entering or exiting a trade, and you should always research it thoroughly to ensure consistency and longevity. Always define trading parameters, money management, and entry-exit points.

3. Stop-Loss and Take-Profit

Stop-loss is a limit you set at a particular price point to cut your losses and close your position when a trade goes against your expectations. Take profit is when a trade favors you. Always predefine your stop-loss and take profit before placing any trade.

4. Position Sizing

It’s the size of a particular stock that you are trading. Position sizing is essential in managing risk. It helps if you base every stock position you take on a criterion that depends on your trading capital and the risk you take in each trade. The formula to use to find your ideal position is as follows:

  • Position Size = Risk Amount/ Stop Loss

The formula helps you manage and execute your trades.

5. Portfolio Diversification

Never put all your money in one instrument or stock. Instead, diversify your investments across market capitalization, industry sector, and geographic region. Apart from helping you manage risk, it also opens your investment opportunities.

6. Hedging

Hedging refers to a risk management strategy that allows you to avoid potential losses in risky situations. It enables you to create another trading position that protects (hedges) your current stock position against unknown market movements and risky scenarios. Hedging minimizes your risk of losing money and mitigates market volatility. It also involves derivatives like futures and options contracts.
The Bottom Line

There is no clear answer to how to avoid trading risk definitively, but using one or more of the strategies above can help you better manage and mitigate it. You could also turn to software solutions, such as the Aryatrading trading website, and use an online trading community’s collective intelligence to automate your risk management.

Tips on Where to Get Finance Homework Help

study

Everyone has to deal with finance at some point every day, whether you like it or not. However, when you go beyond calculating numbers to more challenging aspects of finance, you realize that you need an expert in finance. You can easily get a finance homework assistance at Domyhomework123.com.

Finance is a broad subject with different topics like investment management, financial reporting, financial evaluation, etc. Most students in college have at least one subject that has to do with finance. If you found yourself struggling with your finance assignment, you need help, and we would show you how to get it.

5 Tips on Where to Get Finance Homework Help

Getting help with your finance homework doesn’t take much. However, you should know that you need to help yourself first before you can get help. These tips would help you help yourself and show you how to get outside help.

1. Develop some interest

Yes, we know finance can be incredibly boring. But, if you want to do the homework with any success, you need to deal with your mindset. It might not become your favorite subject by any shot, but you can come to find it interesting.

How do you do it? You can start by applying finance theories and principles taught to real-life situations. For instance, you can use your budgeting knowledge to create a budget for your monthly grocery expenses. Activities like this make the subject more relatable and exciting.

2. Do it early

You would be tempted to leave the assignment till last. Don’t yield to that temptation. It is best to do tasks that you don’t have much interest in first. It would also help you finish the work without panicking or rushing. This tip ensures that you can put in your best efforts and score high.

3. Try it in pencil

You are bound to make mistakes, especially when you don’t understand the subject well. Doing the exercises in pencil means that you can erase it easily when you miss a step. You won’t need to cancel out all your work and restart like with a pen.

4. Ask your teacher

But it is an assignment! Yes, we understand that, but your teacher would be pleased to guide you through if you have attempted parts of it. Don’t expect your teacher to do the assignment for you, though. You can also get help from a neighbor, friend, or colleague who knows the subject better than you. You might even find that it’s only a little part of the homework that you missed.

5. Go online

There are answers to almost anything online today. If you don’t want to talk to your teacher or any other knowledgeable person near you, you can get help online. Whether you are looking for someone to explain the exercise to you or writing services like online dissertation writing services that would do it for you, online is a sure bet. However, you should ensure that the site or service you choose is trustworthy and has experts in the field.

Conclusion

Finance doesn’t have to remain the bane of your existence forever. You can not only get help for your finance homework. You might even come to love your finance subjects with time and these tips.

International Trade in 2021: Challenges and Opportunities

Int shipping

By Charles Hollis

What does 2021 hold in store for international trade? The trading environment presents a complex picture, with issues such as the COVID-19 pandemic, trade rivalry between the US and China, and increased demands for services being among the myriad variables. Charles Hollis of Falanx Assynt gives some perspective on what to look out for in the coming year.

The past few years have witnessed increasing geopolitical instability, posing greater uncertainty for international trade and investment. The advent of the global COVID-19 pandemic in 2020 has massively compounded the challenge to globalised economic networks and contributed to economic instability. The World Trade Organisation (WTO) projects a 9% decline in trade of goods for 2020.

One impact of the pandemic particularly damaging to emerging economies is volatility in the prices of raw materials as demand has declined in the face of lockdown. Hydrocarbon prices have been notably hard-hit, creating significant political problems for countries where hydrocarbons have been a major source of government revenue – the Gulf producers, such as Saudi Arabia and Iraq; Libya, Algeria and Russia; Nigeria and Angola in sub-Saharan Africa; and Venezuela in Latin America. The revenue shortfalls and resulting budget deficits will add to uncertainty, economic hardship and political instability in these economies. Popular protests have already broken out in states such as Iraq, Algeria and Russia as the effects of declining revenues exacerbate underlying political tensions.

One impact of the pandemic particularly damaging to emerging economies is volatility in the prices of raw materials as demand has declined in the face of lockdown.

Political instability will continue to increase globally, with greater impact on emerging markets. Lebanon, a previously stable state, is sinking into an ever-greater malaise. Ethiopia, for a number of years seen as one of Africa’s success stories, is looking an increasingly risky market, with conflict and disruptions posing major challenges for movement of goods.

The pandemic has led to a drastic rise in sovereign debt across emerging markets, which means that restructuring will be a priority for heavily indebted countries. However, many of these debts, particularly in Africa, are owed to Chinese entities who are proving more reluctant to participate in multilateral restructuring mechanisms, such as the IMF and Paris Club (which have proved to be the most effective channels for debt relief in the past), and consequently the necessary debt-relief programmes are more difficult to agree.

But the outlook for international trade and investment is not all negative. The political shift towards climate policy and a green recovery will create new jobs and trade opportunities in the longer term. The global trade in services is on the rise, with the WTO predicting that service exports will overtake goods trade exports in the next decade. This shift will benefit nations in the west, as the service industry is a key strength of many developed economies.

The new US administration is likely to be positive for international trade, as Biden will restore predictability to international relations, although bipartisan agreement in Congress on a robust approach towards China and Russia will ensure that tensions will persist at the “Great Power” level. Despite this, there remains a high likelihood that the US will seek rules-based outcomes rather than confrontation, in an effort to ease overall tensions.

The role of China generally, the increasing focus on its human rights record and its growing stand-off with the US and other states in the Asia region and beyond will pose a growing and generalised political risk that should colour the thinking of any business with an international presence and interests. This will be the overarching geopolitical dynamic over the coming decade. It is likely to have spill-over effects across secondary markets and on domestic public opinion, which may affect trade and investment opportunities for companies globally.

It is therefore critical for businesses to take account of political risks and ways to anticipate them, understand them and mitigate them. We at Falanx Assynt deliver this to global companies through our rigorous, reliable and highly respected predictive analysis of key emerging markets and critical global themes.

For more insight on Assynt’s intelligence predictions for this year, access our top five global forecasts for 2021.

About the Author

Charles Hollis

Charles Hollis is the managing director at Falanx Assynt Ltd, global intelligence consultancy and leading provider of geopolitical, strategic and business risk analysis. Charles spent fourteen years serving at home and overseas with the British Foreign and Commonwealth Office. He has led client projects on market entry, business intelligence and investigations, as well as political risk and government affairs issues.

Making Sense of the Far-right March on the US Capitol

Far-right March on the US Capitol

By Anthony A. Gabb, Ph.D.

The storming of the US Capitol on January 6th, 2021 by an angry far-right mob was an exigent distraction of historic proportions. Indeed, it may be an augur of what is to come. Even so, a president with neo-fascist white supremacist sentiments and an angry far-right mob are necessary but insufficient conditions for fascism. The road to fascism requires fascists who want complete control of all the organs of the system, the presence of an existential communist threat, and uncontrolled disorder in the streets. That said, it would be a mistake if this distraction causes us to overlook that above all the real enemy of working people is the ruling elite mob, not unmoored far-right mobs. The storming of the US Capitol is a visible sign of the system in crisis.

It is a rare occurrence when the US Capitol is stomped. Least by a neo-fascist and white supremacist (some of whom were armed) mob supported by the president himself. The president used demagogy to stir up and convince these people that the election was stolen. Incited, they came prepared to even kill to take back their country.

The mob stormed the Capitol to overturn the results of the 2020 presidential election in favor of President Trump. The attempted coup failed. It failed because the time for fascism had not arrived in the US-not yet.

The images of the Capitol in the aftermath of the riot had all the hallmarks of chaos. The rioters failed to overturn the election results, as well as to siege power from the US government. The relatively easy access into and exit out of the Capitol building suggests that there may have been other inside collaborators with the mob, in addition to the president. When it was over, five people had died in the mayhem including two Capitol police, one by suicide. So far, a small number of those who participated in the riot have been arrested. Possibly, one unintended consequence of the rampage is splintering and restructuring of the Republican (Trump’s base could form a new party) and Democratic (liberal base could form a new party) parties.

Also, the riot creates an opening for the state to install new oppressive measures and laws. Predictably, these measures will place further restrictions on workers’ rights. For example, social media’s restrictions on Trump’s antics to what they perceive as dangerous, may be used selectively to restrict freedom of speech. As the economic, COVID-19, and environmental crises continue, mob activities and other forms of resistance could intensify. Globally and in the U.S.A., far-right gangs have been growing in membership. Unquestionably, they must be resisted and vigorously put down wherever they appear.

Before Mr. Trump became president, there was already a whole host of problems, which have gotten worse. Food insecurity was on the rise. Wages were stagnant. Wealth disparity between the rich and the rest was widening. Medical care was not accessible to large swaths of the population. There was a shortage of affordable housing. There was an increase in racist attacks. Concerns about global warming had risen to a level of urgency. Then COVID-19 sent the economy into a tailspin. It is likely that many of those who participated in the riot have experienced or are experiencing some of these insecurities.

As these conditions become worse, people will become desperate and angry. It is not surprising that an exemplar of the oligarchy and a demagogic insider like Mr. Trump comes along and presents himself as an outsider who will solve all these problems. But neither Trump or the Republican party nor Biden or the Democratic party can or will fix these problems. And the far-right will continue to have appeal.

Before and since the mob’s march on the Capitol, fascism has been mentioned countless times. This compels me to say a few words about fascism. Fascism is the most extreme form of capitalism. It is an alliance between the government and corporate interests who finance, orchestrate, and put in motion uncontrolled “mass gangs” that come from the middle class, working class and poor. Its leaders use lies and innuendos and resort to methods of divisiveness and civil war to purge and annihilate first and foremost militant workers and communists. Then, they call for peace. After which fascists are given complete control of all state institutions, including education, the police, the prisons, the military, the courts, the press, social media, and religious institutions.

Fascism is invoked when the ruling elite believes there is an existential communist threat, and the normal tools of oppression (police, military, judiciary) are unable to restore order. The mob that recently stormed the US Capitol was not socialists and communists. The riot was brought under control within a few hours. To the extent that there are communist organizations in this country, they are disparate and atomized. Evidenced by the defeat of Trump, there is no consensus to install fascism in the US by the ruling elite-at least not right now. Make no mistake though that at the first sign of any existential threat, the ruling elite from business and finance and their political agents, the Republicans and Democrats, will not hesitate to organize and orchestrate far-right fascist mobs to crush legitimate dissent-this would not be the first time. The working class needs a working-class political party, worker-controlled unions, and other worker organizations that are completely disconnected from the establishment to advocate in its interest.

About the Author

Anthony A. Gabb, Ph.D. is a retired Professor of economics. He has taught economics for 40 years, 32 of which was at St. John’s University, New York. His most recent work includes “Can the Fascist Germ Rise to Epidemic Levels in the USA Today?” and “Financial Oligarchy Feudal Aristocracy”. He has published and delivered dozens of papers, a book chapter, and a book review, interviewed by The New York Times, Corriere della Sera, and has appeared on Channel 1 New York.

Britain’s Top Firms Failing Black Leaders

FTSE 100

Green Park’s Annual Business Leaders Index Records no Black Chairs, CEOs or CFOs at FTSE 100 Companies for first time in six years.

Despite years of public commitments from government and business to increase ethnic diversity at leadership levels, the number of Black individuals at the top of Britain’s biggest companies has fallen to zero. 

Research compiled by executive recruitment and diversity consultancy agency Green Park and released today in conjunction with the UK’s first ever Race Equality Week, reveal that for the first time in six years, there are no Black Chairs, CEOs or CFOs, in the FTSE100.

The early findings from the Green Park Business Leaders Index 2021 reveal that while the numbers of most other minority ethnic groups in these top positions have increased by a small amount since its first report in 2014, the number of Black leaders at FTSE 100 companies has stalled and then dropped to zero*. As a result, only ten of 297 (3.4%) leaders in the Top 3 roles have ethnic minority backgrounds, the same proportion as when Green Park began their FTSE analysis in 2014.

At FTSE100 board and executive committee level, the percentage of Black Executive Directors and Non-Executive Directors (1.1%) has also fallen since Green Park’s first report in 2014 (1.3%). This compares unfavourably with increased percentages for other minority ethnic board members (Muslim, Hindu and Sikh, and Chinese and East Asian) across the same period.

The prospects for future increases in Black representation at the highest levels of British business also look slim, with numbers in the leadership pipeline decreasing over the past year from 1.4% to 0.9%.  This drop in the pipeline is reflected across ethnic minority groups more widely, with ethnic minority representation falling over the past year from 10.7% to 9%.

Trevor Phillips, Chair of Green Park, said: “These figures put some flesh on the bone of last year’s protests. We know there is no shortage of qualified candidates to fill these roles if companies are willing to look. Yet the snowy peaks of British business remain stubbornly white. We cannot go back to business as usual. It is time that shareholders, consumers and employees start questioning whether Black Lives Matter is just rhetoric rather than reality. That is why we have put our backing behind Race Equality Week. Corporate leaders need to stop telling us how much they care and do something to show us that Black lives really do matter.” 

The figures released today are an early insight into the findings of the Green Park Business Leaders Index 2021, an analysis of the gender and ethnocultural diversity of FTSE leadership. They are being released to mark the UK’s first ever Race Equality Week, with hundreds of organisations and individuals uniting in activity to tackle the challenges faced by ethnic minorities in the workplace.

Co-founded by Green Park following the Black Lives Matter movement of 2020 and disproportionate impact of the COVID-19 pandemic on ethnic minority communities, the Race Equality Week movement and slogan – ‘Let’s not go back to normal’ – are further validated by today’s findings.

Green Park is calling for organisations to act now to tackle issues facing race equality, not only because it is the fair and moral thing to do, but because the success of British business post Brexit relies on it.

As part of the organisation’s contribution to Race Equality Week, Green Park is proposing to tackle a crucial issue for many candidates for senior positions – the belief that they may be recruited as “diversity window-dressing” – but excluded from key decisions such as major appointments or acquisitions being taken by a leadership team which is all male or all-white. The company’s board has instructed that under the “Green Park Rule” any spending decision above 1% of turnover must be made by a diverse group; if this is not possible, the fact should always be reported to the board and noted in the company’s annual report.

About the Green Park Business Leaders Index

This research examines the backgrounds of 6,172 individuals in total and covers the leadership of the UK’s largest quoted companies, the FTSE 100 as of December 2020. The findings split senior leaders into three tiers of seniority: Top 3 (Chair, CEO and CFO); Top 20 (Board, and Executive Committee, including Top 3); Pipeline 40 (Senior leaders who report into the Top 20).

Data is cross analysed using several sources, many of which are publicly available including annual reports, London Stock Exchange listing information, company websites and LinkedIn. In the case of the executive level employees considered in this report, virtually all names are published on the relevant organisation’s website or annual report. Observed gender and ethnicity are then cross analysed with the output of a unique program Origins, designed by Professor Richard Webber; lead developer of consumer classification systems Mosaic and Acorn. Origins uses a database of 1.2 billion individual records globally, with 2.5 million family names and 0.8 million personal names, to generate algorithms that can associate individual names to key protected characteristics, namely gender, and ethnic or national (ethnocultural) origins.

About Green Park

Green Park is an award-winning consultancy that offers Executive Search, Interim Management, Board Advisory, Diversity & Inclusion and Managed Service People Solutions across the private, public and third sectors. Championing diversity and inclusion, Green Park is changing the face of leadership by helping organisations think differently about talent in the UK’s top boardrooms. Our aim is to help organisations to attract, identify, develop and retain trusted, inclusive, authentic and, most of all, highly effective leaders from different backgrounds to leverage the power of collective difference. In 2018, Green Park placed a new diverse leader on a board every 14 days!

A Deeper Insight Into Database Management Systems – What Is Indexing?

Management system

A modern database management system has a technique for the data structure that helps you retrieve data records from any system file. This technique is known as indexing. The index generally is a table with two columns. You will find a copy of the candidate or primary key in its first column. In contrast, its second column has a group of pointers containing the address for the disk block that keeps the storage address of the key’s particular value.

The index will-

  1. Take the search key as an input
  2. Effectively return a set of records that match this input

An insight into the different types of index in the database management systems

The following are the different types of indexing you can find in the database management systems-

The index is defined as per its attributes for indexing. There are two primary types of methods for indexing, and they are-

  1. Primary and
  2. Secondary

An overview of the primary index

The primary index is organized, has two fields, and a fixed file size. The first field has a primary key, and the second file points to the particular data block. There exists a one-on-one relationship between these two entities in the table. The primary index, again, can be divided into two kinds. They are-

  • The dense index and
  • The sparse index

The dense index refers to the record created in the database for each search key that is valued in it. It helps the user to search the database faster. However, it requires greater space for storing the records of the index. In this method, the records keep the search key’s value that points to the real record on its disk.

The sparse index refers to the index’s record that surfaces for just some values in this file. The sparse index assists you to resolve the problems of dense indexing present in the database management system. In the above indexing technique, the group of columns for the index contains a similar address for the data block, so when the data has to be retrieved, the address for this block data can be easily fetched.

However, one should note that the sparse index contains records for just some search key values. It requires less space and lesser maintenance overheads for insertions and deletions; however, compared to the above index for the location of records, it is much slower.

An overview of the secondary index

When it comes to the secondary index in the database management system, the field can be created with a specific record for every record. This should entail the candidate key and is often referred to as the non-clustering index too.

The technique is two-leveled in nature and can be deployed for reducing the size of the first level mapping at this level. Experienced DBAs say that a large volume of numbers is chosen, making the mapping small all the time.

The above can be better understood with the help of an easy illustration. In the case of a bank’s database, you will find the data is sequentially stored as per the account number, and you will find all the bank accounts of a particular branch of one bank, say XYZ Bank.

You can maintain a secondary index in the mysql database management system for each search key. This index record is the point of record with all the groups of pointers to them in the particular value of the search key.

Clustering index

The clustering index is not a pointer, and the records are stored in the index independently. There are cases where this index is made on non-primary key columns. They do not need to be unique for every record. Professionals from the esteemed company in remote database management and administration, RemoteDBA.com, say that the user can make two or even more columns for getting unique values in such a case. In this way, an index can be made and named a clustered index so that the user can recognize the record quicker.

For instance, let us assume an organization has recruited several employees in different departments. In such a case, the clustering index in the database management system must be made for employees in the same department. This is considered one cluster, and the index points refer to the cluster as a whole. In this case, the department_ no is the non-unique key.

Understanding the multi-level index

Skilled professionals in database administration and management state a multi-level index is made when the primary index does not sync in with the memory. In this method, the user can reduce the volume of disk accesses to shorten any record stored on the disk as a sequential file to make a sparse base on the file.

B-Tree Index

This is a popular type of data structure in the database management system widely used for tree-based indexing. This format is multi-level and has binary search trees that are aligned. The leaf nodes in this index denote the real data pointers. These leaf nodes are also interlinked to the list of links that permit the B tree to offer both sequential and random access.

Skilled and experienced DBAs state that the B-Tree index should have the following traits-

  1. The lead nodes should have at least two to four values
  2. The path from the root to the leaf is generally equal in length
  3. These non-leaf nodes, besides the root node, generally have around three to five children nodes.
  4. Each node is neither a leaf nor a root node has n/2] and n children between them.

Professional experts in database performance tuning, management, and administration state indexing in database systems help you decrease the complete number of input and output operations required for retrieving that data so that you do not need to access the row in the database system from the index structure. In this way, you can get faster searches, and the retrieval of data becomes simpler for users.

How to Successfully Manage Remote Teams in 2021

remote teams

By Jeya Thiruchelvam

As a result of COVID-19, remote working has become the norm for many employees and attitudes to remote and flexible working are changing dramatically.

In September 2020, XpertHR surveyed 148 HR professionals and found that more than half (54.7%) of businesses plan to increase the amount of permanent homeworking in their organisation in the future. And 35.1% of organisations that did not use homeworking prior to the pandemic plan to now have at least some permanent homeworking arrangements.

But employers must be aware of some the challenges of managing remote workers. At the start of the pandemic, remote working was a novelty for many employees, but it is now starting to have an impact on some people’s health and wellbeing.

Remote working does not suit all employees, and employers should implement measures to support them, especially if the workforce is divided between some people working remotely and others in the office.

Here’s how managers can be more confident when managing remote workers in 2021.

Ensure managers have the right skills

Managers of employees who work remotely need to be more skilled at certain things such as communicating, relationship-building, coaching, and managing by results.

If most of the interaction with an employee is by email, Teams or Zoom, managers can’t rely on body language and facial expressions to help convey their message or to better understand what an employee is saying, increasing the chance of a misunderstanding. So, managers of employees working remotely need to be excellent communicators, not merely competent ones.

Managers need to let go

Often managers find “letting go” uncomfortable. But they need to trust their team and not micro-manage them. Managers must know their team too, and recognise each employee is an individual with their own unique combination of strengths and weaknesses and particular set of personal circumstances and life commitments.

Managers should also have confidence in their ability to guide and support their team, and to create a positive environment where new ways of working can be explored. But confidence doesn’t mean arrogance; managers should understand their own weaknesses and work on those.

Good communication and engagement are paramount

Managers must make time for regular catch-ups with employees and know them well enough to recognise when they might be struggling but reluctant to admit it. This is an important part of looking after an employee’s mental wellbeing.

Ensure employees know they need time away from their desks, and encourage communication with their colleagues, such as having a virtual coffee or Friday afternoon drinks, which can promote good mental wellbeing. Also remind employees of any benefits provided by the employer, such as employee assistance programmes.

Plan new working arrangements carefully

At the start of any new working arrangement, managers should agree some regular events (virtual or face to face) everyone can commit to regardless of their working pattern. 

Agreeing these events as a team, through group discussion where there is cooperation and compromise, will mean employees should feel more committed to attending them.

Managers should plan and diarise the events they want everyone to attend well in advance. This means team members can more easily plan and, if necessary, change their work schedule so they can attend an event.

Set objectives to measure performance

Managing employee performance while working remotely can be challenging. Measuring an individual’s performance by results and not by their presence in the office or the hours they work is the best approach.

A person’s presence at work does not necessarily mean they are working. Equally, when someone is working from home, or on the move, this does not mean they are not working or slacking. Often, it is the reverse. Given the freedom to work in their own way, employees almost always get on with the job and appreciate being trusted to choose when and where to work.

To assess an individual’s performance by their output, managers must conduct a thorough objective-setting process. The focus should be on agreeing with team members their outcomes over a specific period and how these outcomes will be measured, and giving them the freedom to choose how they will meet their objectives.

This flexibility will give individuals the chance to use their knowledge and experience – the individual doing a job is usually the one who knows best how to do things better or differently.

After objectives have been set, managers should monitor progress. Creating regular opportunities to review, reflect and provide feedback against required outcomes is even more important when an individual is working flexibly and there are fewer opportunities to observe directly or provide in the moment advice or feedback.

Coach and facilitate

For remote workers, a coaching management style will be more effective than a “command and control” approach as there is less scope to help trouble-shoot problems when they arise. Team members therefore need to develop the skills to solve problems independently.

A coaching management style means managers guiding individuals to work out things for themselves. Managers must be approachable and recognise that employees will be stretching themselves and may need guidance. It is essential they don’t reprimand someone for asking obvious questions or suggest someone is incompetent if they can’t see an obvious solution straightaway.

Giving employees the confidence to deal with problems more independently is something that will benefit both the business and the employee in the long run.

Give constructive feedback

Managers’ recognising good progress and outcomes is crucial for team motivation. Equally, if there are issues with the progress or outcomes that a particular individual is achieving, managers must feed this back promptly, so that they can improve.

It can be demotivating if a team member thinks they are doing a reasonable job because no one has said anything to the contrary only to be presented with a lot of negative feedback at their annual performance review when it is too late for them to do anything about it.

To conclude

Remote and flexible working can be hugely beneficial for both employees and employers. Allowing employees input and control over how, where and when they work means they are more invested and more likely to perform better.

For employers it can boost productivity, engagement, and commitment from their workforce. While COVID-19 thrust this way of working on many organisations now is the time to reflect and take advantage of the benefits it can bring in 2021.

This article is based on the XpertHR line manager briefing on leading a flexible working team written by Peter Thomson.

About the Author

Jeya Thiruchelvam

Jeya Thiruchelvam is a managing editor on the employment law team at XpertHR. She is particularly interested in race, disability and sex discrimination law. 

Prior to joining XpertHR, she worked as an employment solicitor for six years, regularly hosting training seminars and contributing articles to local and regional publications. 

How to Get Rid of a Car with Negative Equity in Vegas?

cars

If the market value of your car is worth less than your debt, it means that your vehicle has negative equity. If you are in negative equity with your car, it can be the worst-case scenario for you. 

Let’s take a simple example. Say you owe $30,000 for the car or you received a title loan in Las Vegas for that amount. You’ll get the market price of your vehicle after you do some research and let’s assume it’s $25,000. That means you’re in negative equity of $5,000. 

What to Do About Negative Equity in Your Car

There are two options to get out of car equity that is negative. Number one is paying the equity as well as the loan amount for the car until you’re out of negative equity. Or number two, which is to sell your vehicle and take the loss. 

However, we’re going to tell you about a few more options which you can choose in this situation. The best decision will be based on your loan amount, credit score, and the time frame for which you’ll be paying the loan. 

How You Get Rid of a Car with Negative Equity 

● Calculate the negative equity of your car

First of all, start calculating the negative equity. You need to make sure how deep you are in terms of the gap between the market price and the debt. 

Before that, you need to determine what your car is worth. It can be done by using different tools available on the various online platforms. 

You cannot rely on a single source when it comes to car evaluation. We suggest that you should use multiple sources, as it will give you an accurate price estimate. 

Let’s consider the same example taken above in which you are $5,000 underwater. 

So, before you consider reselling your car or refinancing, you need to take into account all the possible conditions that can arise.

Ask yourself if you’re in a position financially to pay the remaining amount, which is $5,000 in this case. If you’re able to pay this amount by any means, then this is your best option for getting out of negative equity in the car.

● Discuss with your lender

Even if you are not in a position to pay the amount of the negative equity, there are several different ways that can help you get rid of your car.

The very first step would be giving a call to your lender. Explain the situation and then ask him for solutions that might help you with this problem. Even if there are no options available, there’s no harm in asking.

One of the options can be paying some extra amount of debt every month. It can help you get out of negative equity earlier. You might still have an obligation to pay the loan. But paying it will become more comfortable, and you can make the best out of a bad situation.

You might have to cut down on some of your expenses, but at least it will give you zero or positive equity when you shop for a new car at a later stage.

● Consider taking a new loan

If your lender cannot do anything to help you, you’ll need to consider taking a new loan. If you have a good credit score, refinancing at a low-interest rate can be a good deal.

When you are refinancing a loan with negative equity, you need to be very careful about the terms that the lender is putting up in front of you. 

The lender might tempt you with low EMI or monthly payments. But make sure that you read all of the agreement carefully. Lower monthly payments can extend a loan from a year to many more.

The major problem with cars is that they lose their value very quickly. They go down by nearly 10% in the first year and then by 50% in five years. So, the quicker you repay your loan, the faster you’re getting rid of negative equity in your car.

● Consider selling your car

We would always suggest you keep your old car and try to pay off as much negative equity as you can. However, if you’re through with all the options given above and none of them are working for you; you need to consider the last option.

If you reach the final decision that you want to sell your car, focus on getting the highest price possible. Try covering as much of the negative equity as you can. 

If your car is maintained correctly and is in excellent condition, you can get the right amount for it. Basic design retouches here and there, and some mechanical repairs can also boost the cost of the car.

However, if your budget is low, at least give it a good wash and wax. After you sell the car, do remember that you need to pay your loan amount. The balance amount might get included in the loan amount of the new vehicle. 

If you don’t want to sell your car, you can lease it. Although leasing is one of the options which we don’t recommend fondly, it is still an option. 

Keep in mind that no matter what option you pick, you need to pay the initial loan.

The bottom line

Getting rid of a car with negative equity can be stressful. 

You need to think very clearly. While trading your old car might get you a new one, it won’t nullify your debt. Rather than searching for an option which will cost you the most, try searching for an opportunity which will be less of a hassle and give you the best results.

It can be calling your lender and asking him for the best option for repaying your debt or paying off your negative equity amount. 

Whatever the option you might choose, knowing a little bit better about how to get rid of a car with negative equity will give you a broader vision on the topic and help you find the best deal.

EDITOR'S PICK OF THE WEEK

China economic growth

China’s Challenging Search for a New Model of Economic Growth

By Danny Leipziger China cannot continue to rely on exports to drive its growth, but what are the alternatives? China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...

WISE DECISION MAKER GUIDE

POWER INFLUENCERS

Emerging Trends

The Future of Global Trade