Home Blog Page 1068

Earn Billions in North Korea: Here’s How

Business, commerce and finance in North Korea concept, 3D rendering

By Shepherd Iverson

This is not a parody for THE ONION, but a pragmatic proposal to reunify Korea with your money, in exchange for resource ownership, construction contracts, licensing agreements and temporary business sector and market monopolies in northern Korea worth billions.

North Korea ranks 10th among nations in mineral reserves, with large deposits of magnesite, ore, coal, gold, zinc, copper, silver, rare earths, and other minerals worth an estimated $6-10 trillion.

What makes this proposal possible is the abundance of profitable resources and prospective enterprises in the Hermit Kingdom that would come under South Korean (or your) control after unification. North Korea ranks 10th among nations in mineral reserves, with large deposits of magnesite, ore, coal, gold, zinc, copper, silver, rare earths, and other minerals worth an estimated $6-10 trillion. Everything is up for grabs in northern Korea, including temporary monopolistic control over entire economic sectors in finance, energy, public utilities, telecommunications, manufacturing, healthcare, tourism, transportation, automotive products, construction materials and contracts for public infrastructure; ownership or licensing agreements for control over mines, seaports, airports, ski resorts, tourist attractions, and construction contracts for railroads, tar roads, a gas pipeline, energy generation, and a multitude of necessary projects. If you get in now, after unification these safe government-authorised investment vehicles will result in enormously profitable ventures, many with secure long-term revenue streams.

There are only a few people in the world with the enterprise and ability to consider this proposal. If I were to write a promotional it would read: SEEKING PROMISES FROM BILLIONAIRES, CORPORATIONS, PRIVATE EQUITY FIRMS, AND INTERNATIONAL BANKS TO INVEST IN A NO-RISK FUND THAT WILL PRODUCE ENORMOUS PROFITS AND INCREASE THE STABILITY OF OUR WORLD.

Impossible? What if the Kim regime can be disarmed and Korea unified by promising personal rewards to its elites? Imagine you control a multi-billion dollar fund and North Korea is an underperforming corporation run by an incompetent board of directors – the Kim family and a few ultra-elites – who will not negotiate a deal. In this regressive situation, it is logical to offer its shareholders – political and military elites – a higher price for their shares to persuade them to overrule their board of directors – a friendly corporate buyout.

Pyongyang elites must be assured of an uptown future. To reassure those who depend on their positions in power for their means of survival that they will continue to prosper under new political leadership in a free-market economy, I propose the institution of a Reunification Investment Fund to provide elites with a golden parachute after they bring about unification. In this Triangular Benefit Unification Model, the South Korean government guarantees large profits to private enterprises that in turn, promise money to Pyongyang elites for unifying Korea and transferring political power to Seoul.

I estimate this buyout will cost $30 billion – $4.3 billion dispersed per year for 7 years. The top 1,000 North Korean elite families are promised $5 to 30 million; 11,000 upper elites – including all generals – would become millionaires; 51,200 lower level political and military elites receive $100,000 to $500,000. In total, 112,200 elites receive on average one-quarter-million-dollars each and may now live in the free world as affluent citizens of a democratically united Korea. The apparent audacity of this proposal is assuaged by the fact this is a no risk investment, since money is not released until after unification and the formal transfer of political and military power. Details may be discussed, but surely some amount of incentive will motivate elites to make Kim an offer he cannot refuse.¹

On the surface it may seem counterintuitive, unethical, and even immoral to pay an enemy after decades of human rights abuse. However, upon closer analysis, almost everyone in the North Korean pyramid of power has been replaced in recent years, and this new generation of elites may be viewed less as perpetrators and more as victims of an ignoble history. Most who will benefit are merely innocent inheritors of their fathers’ ill-begotten estate (position and power) and were not complicit in its acquisition or in the malevolence that followed. We do not punish the descendants of slaveholders or the children of thieves and murderers. This payment would amount to a bailout for the sins of their ancestors – without moral hazard.

For practical reasons, promising personal and financial security to the House of Kim may ease the deal and prevent bloodshed.

For practical reasons, promising personal and financial security to the House of Kim may ease the deal and prevent bloodshed. Denial of complicity in palace purges and other atrocities may preserve Kim’s public image; his father and the relic henchmen he has already dispatched from positions of power may be scapegoats for decades of malfeasance and unconscionable human rights abuse. If Kim does not acquiesce, with $20-30 million promised to each of the 200 most prominent families, they might take matters into their own hands. Or a coup d’état may be sponsored by well-compensated military elites. Since safety is more precious than power, young Kim would have little choice but to accept this offer.

North Koreans are ready for change. Digital visions of personal freedom and material prosperity have saturated cultural impressions, creating modern aspirations and a new social context for political change that has not existed before.

North Koreans are ready for change. Digital visions of personal freedom and material prosperity have saturated cultural impressions, creating modern aspirations and a new social context for political change that has not existed before. After decades of silent transformation the mere existence of a $30 billion fund sitting in escrow ready to pay elites vast sums upon unification may be a game changer. This fund will provide a stable platform for peacefully managing the political transition, while international development banks and the South Korean government will provide the larger capital foundation for successful economic reintegration. The alternatives would cost trillions and might result in catastrophic loss of life.

For decades, cloistered foreign policy professionals in Washington have failed to make a deal. Although the grim trajectory of geopolitics may seem unstoppable, we need not continue down this road leading into the abyss. Instead, we may think outside the box and create novel solutions to unique contemporary geopolitical problems. We need private and public leaders who can bring out the best in us; those who perceive the big picture and understand the ideas that move humanity forward are often initially considered crazy, disruptive, or impossible; luminaries who can show us what we should want, while smartly employing incentives to get us there. Indeed, from time immemorial practical reason and creativity has helped us overcome nature, now in a digital nuclear age we must be smarter and more innovative in order to save us from ourselves.

Business entrepreneurs understand opportunity costs, and to counter threatening entropic global forces should be willing to invest large and long in a more secure world order. If they neglect their fiduciary responsibility in such matters, they do so at their own peril – and ours. Although this particular plan for enlightened self-interest is an impossible proposition for all but a few WORLD FINANCIAL REVIEW readers, for those in position, this idea might be worth billions and create an opportunity to stand for a moment on the world stage in Oslo Norway.

About the Author

Dr. Shepherd Iverson taught in the Institute for Korean Studies at Inha University in South Korea from 2009-2017. His academic papers, articles, and op-eds on disarming North Korea have appeared in international journals, Asian newspapers, and Forbes Magazine. Professor Iverson’s ideas are presented in detail in his new volume: Stop North Korea! A Radical New Approach to Solving the North Korea Standoff (2017).

Reference

1. Details of this plan and the payout are in my book, Stop North Korea! A Radical New Approach to Solving the North Korean Standoff (North Clarendon, Vermont: Tuttle Publishing, 2017).

2018: A Foreign Policy Wild Ride in Trump’s America

Foreign policy in america

By Markos Kounalakis

Surprise is an element that Trump relishes both in deal-making and in policy. America and the world need to get ready for a wild ride in 2018. Guessing what the world will look like in the Trump era is a risky game. President Donald Trump came to office with no governing track record and his time in the Oval Office has been full of contradicting policies and statements that make only one thing certain: Unpredictability.

The last line of defense in checking President Donald Trump’s foreign-policy power is the old guard of the Republican Party, and those watchmen are about to go quietly into the night.

A 2018 Republican sweep would cripple two key Senate committees, moving them from painfully ineffective to plainly inconsequential. The Senate Foreign Relations Committee and the Senate Armed Services Committee are supposed to oversee the foreign-policy and the national-security apparatus. Trump has brought them to heel.

He has belittled the outspoken Foreign Relations Committee Chairman, Sen. Bob Corker of Tennessee, who became a lame duck by giving up a 2018 re-election bid (Disclosure: Corker held my presidential appointment from Senate confirmation in 2016). Sitting out alongside him is another committee member, Trump-critic Sen. Jeff Flake of Arizona, leaving a handful of cowed Republicans and the minority Democrats to try to counter Trump policy tweets and fight for a systematically well-formulated foreign agenda.

Chairing the Armed Services Committee is Sen. John McCain of Arizona. A hale McCain is a formidable leader, whether in military conflict or D.C. turf wars, but he is publicly disrespected and humiliated by Trump, who once said the former P.O.W. was “not a war hero.” The once powerful McCain is suffering a grave illness that may take him off the policy battlefield sooner than he deserves.

Without the present and vibrant check Corker and McCain provide on Trump’s instincts and inclinations, the man is granted full reign over global affairs. Indeed, there are almost no judicial checks on a president’s foreign policy, and the checks within the administration are minimal. Secretary of State Rex Tillerson is all but sidelined and his State Department is going through a convulsing re-organisation that makes diplomats cogs, not wheels, of diplomacy.  Secretary of Defense Jim Mattis has been given both full authority and responsibility for military matters, but the decision to militarily deploy remains with the Commander-in-Chief.

That leaves legislative instruments available to congressional committees – the power of subpoena, confirmation, and budget. But a 2018 rout by Republicans riding Trump coattails and parroting his messaging would further diminish the majority party’s resistance and dwindle the number of critical senators keeping the administration from usurping all power to decide matters of war and peace. 

The odds of retuning a full Republican-led Senate and House of Representatives is diminishing by the day following the Senate-hopeful Roy Moore’s loss in Alabama and the increasing number of Republican congressmen who are dropping out of their difficult reelection bids.  November elections are not decided this early in the 2018 political cycle and what may appear as growing Democratic momentum in the early part of a still peaceful year can quickly shift into a bandwagon of rallying round the flag patriotic fervor should the United States be attacked or threatened or if President Trump initiates a military engagement abroad.  Congress would have little say and less power in the outbreak of hostilities.

The Constitution says only Congress can “declare war.” The reality, however, is that every American military engagement fought since World War II was an undeclared war.

Already, Congress’ check on presidential power in foreign affairs and security is weak. The Constitution says only Congress can “declare war.” The reality, however, is that every American military engagement fought since World War II was an undeclared war. It’s been a police action, a response, a kinetic military action, an extended military engagement, but never a war. Korea, Vietnam, Iraq, Afghanistan, and likely any fight picked by the current administration will find its legal justification in the 2001 Authorisation for the Use of Military Force (AUMF), which is in desperate need of an overhaul.

Presidents end run Congress on war powers, but what about legislation? Congress recently tried to tie the president’s hands on Russia and force him to up the sanctions regime and punishment for Moscow’s multiple sins. He signed the bill, but undermined the legislative maneuver by sitting on his hands.

Few Republicans today have the fortitude or ability to debate, criticise or resist Trump’s foreign policy.  The House has a foreign affairs committee, chaired by Ed Royce (R-CA) who has so far voted with Donald Trump 96.1%. In Royce, Trump has a reliable ally and rubber stamp.  This Trump loyalty has come at a significant political cost to the congressman, with Royce deciding he would be defeated in a reelection bid in his increasingly Trump-policy resistant home state of California. 

Presidential power is not absolute, however. A president needs to sell his policies to the people and maintain democratic support for those policies every two years so that elected representatives can return the citizens’ electoral verdict to Washington. Recent results favoring Democrats in Virginia and elsewhere could indicate a brewing midterm backlash against Trump. 2018 will determine whether Americans have faith in Trump’s conduct and character. If that faith translates into Republican majorities, those representatives are likely to grant the president the unbridled foreign policy power he sought when he declared, “I alone can fix it.”

Trump could deservedly achieve more power before next year’s election with a positive North Korea outcome, whether negotiated or otherwise. A North Korean success would prove to lawmakers and the American people that his tough talk and confrontational style works. That would reinforce and strengthen the time-tested notion of executive privilege in foreign affairs. 

Ironically, failure in North Korea could also favor Trump politically as an America threatened or under attack would likely rally citizens behind its president.  As the world prepared for the 2018 Winter Olympics, a slight thaw warmed otherwise chilly relations between North and South Korea, with Pyongyang making overtures towards talks and participation in the quadrennial sporting event. A consequent nuclear freeze or agreement to control North Korea’s ballistic threat could give Trump a huge political boost and the world a sigh of relief.  It would also make a 2018 Republican electoral victory more likely with the inevitable and unstoppable presidential tweets and speech rightly boasting and bragging of a difficult deadlock solved.  In the meantime, the world must take a wait-and-see approach.

A 2018 Republican House and Senate would allow Trump to test Mel Brooks’ theory that “it’s good to be the king.” Then again, if recent electoral victories and a stronger anti-Trump field portend a Democratic sweep next year, Congress will make sure administration bad actors are investigated, foreign follies go unfunded, military actions are constrained, and partisan appointments languish.

Foreign Policy Players in Trump Administration

Waiting in the West Wing, however, and impatiently anticipating wholesale global disruption are two high-visibility politicians, promoting and positioning themselves to be the next wave of foreign affairs leaders. The Iran protests at the beginning of 2018 have provided them a more prominent platform, Trump aligned policy, and clear boost to their power, even though they both hail from the economically and politically marginally important state of South Carolina. 

Senator Lindsey Graham’s and Ambassador Nikki Haley’s loud anti-mullah voices are heard both at the White House and on the world stage. Graham and Haley are actively making the case for Iranian regime change, a strategy partly developed at a Heritage Foundation that was until recently led by South Carolina’s former Senator Jim DeMint. The Carolinas have not had this much influence on American foreign affairs since North Carolina Senator Jesse Helms chaired the Senate Foreign Relations Committee at the turn of the millennium.

The Southern Haley-Graham Iran strategy supports multiple proxy wars against Tehran-allied and underwritten bad guys. The Islamic Republic of Iran subsidises and supports Yemen’s Houthi rebels, Assad’s murderous Syrian forces, Lebanon’s Hezbollah terrorists, and the turncoat Iraqis trained and equipped by Iranians to kill Americans. The list is long and Haley-Graham encourages the fights on all of Iran’s foreign fronts.

Now the battlefront has suddenly turned to Iran’s homeland. Street protests have flared-up and anything can happen. Demonstrator body counts are rising throughout the country. In this unpredictable environment, Trump-whisperers, golf buddies, and prominent politicians with a global platform have inordinate power over policy while reinforcing the president’s political instincts, belligerent rhetoric, and assertive policies. Haley-Graham tops the list of those foreign policy influencers.

U.S. Ambassador to the United Nations Nikki Haley, the former South Carolina governor, came to office almost a year ago and soon let it be known that “there’s a new sheriff in town” and that Israel-bashing and Iran-coddling was over. Haley is the highest profile woman in an administration where only Ivanka Trump seems to have total access and influence. Haley is presumed to have presidential ambitions and is stirring up conservative political support by attacking the U.N., everyone’s favorite whipping boy. Picking on a fully-deserving Iran is a winning issue and a no-brainer.

The U.N. platform allows Haley to pursue institutional reform in a target-rich environment. Attacking perceived anti-American states at the United Nations gives her positive press and builds her foreign policy cred. In the process, Haley gets to reward foreign friends while busily “taking names” of egregious global offenders and Trump antagonists.

The United Nations provides a grand stage for grandstanding and Haley took the floor last month to accuse Iran of providing rockets to Saudi-attacking Yemeni rebels and violating the Obama-signed nuclear deal. In her relentless effort to undermine Iran’s despicable regime and build an international coalition, she put on display missile parts as “concrete evidence” against Ayatollah Ali Khamenei’s bad behavior – “we are not going to sit back and watch this,” she warned.

Less assertively, former-Trump-critic-turned-Trump-friend Lindsey Graham is augmenting his Trump access. Senator Graham is a Vietnam veteran who was relentlessly critical of President Obama’s foreign policy, an exceedingly positive attribute in Trump’s White House. Mild-mannered, tough-talking Graham is now a tee time buddy and clubhouse chum of the nation’s latest golfer-in-chief. In the process, he has become a significant player in the administration’s foreign policy-making. His Iran position is unequivocal: “We’ve got a chance to deliver some fatal blows to really bad actors in 2018.”

If Haley has dreams of occupying the Oval Office, Graham is said to be eyeing the Secretary of State job that Trump is working to make vacant. Wall Streeters say that incumbent Rex Tillerson needs to stay in office a full year before a Bush 41-era tax loophole allows him to fully defer a $71 million tax bill. The countdown to Tillerson’s 366th day in office is well underway and Iran-hawk and former presidential candidate Graham has ingratiated himself as a Trump convert and improbable defender, perfectly positioned to step into a State Department leadership vacancy.

South Carolina’s favorite son and daughter are bolstering President Trump’s support for Iran’s street protesters The Iranian situation is fluid and volatile.

Democracies around the world are harboring the hope that this is a Persian-version of Tunisia’s Arab Spring, but also fear a Libyan-style revolution that devolves into more bloodshed and chaos. The Haley-Graham combo has proven politically effective at home, but the question is whether it will be as diplomatically successful in Iran.

The Post-Impeachment, Post-Indictment, Post-Trump Scenario

Michael Wolff’s “Fire and Fury” bestseller paints a picture of a dysfunctional Trump White House on the verge of collapse and on the edge of internal overthrow.

Figuring the odds for a 25th Amendment action is best left to bookmakers, however, not book authors. Whatever the odds, foreign leaders always need to hedge their bets. On their minds, if not their tongues, is what life would be like under a President Pence.

Traditional foreign allies look to Vice President Mike Pence and his visits for American reassurance and resolve, continuity and commitment. The veep’s outwardly quiet demeanor and unfailing Trump loyalty has earned him the right to travel the world on the president’s behalf, carrying with him the credibility of presidential access and influence. Pence’s absence from the pages of Wolff’s book will certainly endear him further to President Trump, who perceives a White House otherwise under siege by internal enemies.

NATO looked to Pence for love early in this administration, when POTUS was flirting with Russia and tired of buying European gifts and taking them on military theater dates on his dime. Trump avoided talking about “commitment” and changed the subject when it came to the sacred mutual defense vows of Article V. But Pence never wavered, never failed. Europe’s affection for Pence is returned and, if Germany’s Angela Merkel survives her latest leadership challenge, the love can blossom anew.

Australia, too, had a rough patch with America. Prime Minister Malcolm Turnbull had an early spat with Trump, punctuated by phone hang-ups and hurt feelings. Pence made peace by successfully going on what Australian media called a “charm offensive” to repair any damage and rebuild the relationship.

Around the world, Pence is a practiced and predictable politician in the American conservative presidential mold, unlikely to stray from the mainstream of post-World War II orthodoxy that sees America’s role as the world’s policeman. When he was in Congress, he was staunchly pro-Iraq War. His intensely Christian social conservatism could influence his privileging foreign policies and partners who align with traditional Judeo-Christian values.

Pence’s Middle East trip, his first visit there as vice president, gave the world strong clues as to how he will deal with prime ministers and potentates in the ever-contested region. From Syria to Egypt, Russian presence and influence is growing by the day. Iran and Saudi Arabia are militarily engaged in proxy wars against each other. Pence’s speech in the Israeli Knesset gave insight to his approach toward Israeli-Palestinian peace.

The Middle East is but one part of an evolving America First strategy that pits foreign nations into one of two clear categories – friend or enemy.

The Middle East is but one part of an evolving America First strategy that pits foreign nations into one of two clear categories – friend or enemy.  Friends are not necessarily traditional allies, as the Trump policies excoriate many of those countries as defense and security free-riders who are seen as financial parasites, exploiting economic and trade policies that give them access to American consumer and financial markets while relying on American security guarantees to give them the wherewithal to expend their national resources on aggressive industrial policies and underwritten export strategies. 

Enemies are no longer traditional ideological adversaries, as some countries have managed to endear themselves to the Trump administration by providing investment, jobs, and capital to American markets while alleviating America’s security burden in the Middle East and elsewhere. This “transactional” evolution of America First leaves few regions and nations outside of the binary friend-enemy framework, with both a marginal strategic understanding of these nations within the Trump Administration and a traditional lack of focus on their significance and relative growth, power, and importance in the 21st century. 

A peaceful presidential transition, whether before or on Jan. 20, 2021 – or even if Trump leaves office in 2025 after a second term – creates an opportunity for a policy reset. Trump’s disruptor-in-chief tweets and feats have crushed compacts, rejiggered alliances, starved institutions, and destroyed foreign policy assumptions.

As for Pence, every vice president is always a heartbeat away from assuming power. Health is the main concern, as the 71-year-old President Trump has been as transparent about his medical history as he has been with his tax returns. Health aside, President Trump is facing potentially fatal political challenges from a toxic “Moscow Mueller” cocktail made up of one part Putin spirits, a squeeze of lip-puckering palace intrigue, and slightly sweetened with Russia-related investigations of friends and family.

Not every political sector may see a President Pence as a refreshing change of pace as some global leaders do. The prospect of a Pence administration has American progressives scared witless.

Not every political sector may see a President Pence as a refreshing change of pace as some global leaders do, however  the prospect of a Pence administration has American progressives scared witless. They worry the fiercely devout former Indiana congressman and governor would actively pursue his long-embraced and deeply-felt conservative agenda. Pro-choice activists are particularly concerned about his anti-abortion stance and already troll him by donating in his name to Planned Parenthood. As one Huffington Post headline put it, “Trump might blow up the world, but Pence would set the clock back to 1954.”

Broader political uncertainties loom, too. On domestic policy issues, it’s unclear if middle America would choose President Trump – a former Democrat with a free-spinning moral compass – over the clear-cut, clean-cut Pence. In foreign policy, however, the U.S. foreign policy establishment (called “The Blob” during the Obama years) weighs-in heavily in Pence’s favor, with Europeans all but counting the days to a potential ascension.

The next president may inherit a dirty mess but will start with a relatively clean slate on foreign policy. Whoever becomes the next president will be handed an incredible amount of latitude to develop a new foreign policy agenda entirely free of previous commitment or policy inertia.

If that next president is Mike Pence, his foreign policy decisions are easy to anticipate, if not entirely predict. Crises faced by Oval Office occupants have a way of testing presidential character, instincts and reactions. Just ask George W. Bush, who ran for president with the promise of pursuing a “humble” foreign policy.

The fear of most political analysts today, however, is that Trump’s perspective on power and his unyieldingly America First assertive stance in the world could easily invite or devolve into a violent conflict with an adversary nation.  A compliant and continuing 2018 reelected Republican Congress would be all but assured in the case of a war-tense or terror-filled Autumn.

Regardless of how 2018 shapes up, the last year has caused foreign policy analysts to experience whiplash, political observers to eat their hats, and a global populace sitting on the edge of their seats, watching a dramatic, unpredictable, and existentially relevant performance unfold. 

About the Author

Markos Kounalakis, Ph.D. is a senior fellow at Central European University and visiting fellow at the Hoover Institution at Stanford University. He is a nationally syndicated foreign affairs columnist for McClatchy newspapers. Dr. Kounalakis’s new book, “Spin Wars & Spy Games” on the geopolitics of global news networks is scheduled for release in May 2018 by Hoover Press.  Markos can be reached at [email protected] or on Twitter @KounalakisM.

Yellen’s Twin Legacies – Powell’s Dilemma

By Jack Rasmus

As Yellen leaves the Powell Fed with two contradictory legacies, the question of the day is which will the Powell Fed now follow? Does it continue Yellen’s policy of relatively slow and occasional rate hike? Or does it raise rates faster, and in increments more than 0.25%? More important, what might be the effects of more rapid rate hikes on financial markets? Will it be 2006-07 all over again?

This past February 2018 Janet Yellen, chair of the US Federal Reserve bank since 2014, was replaced by the Trump administration with the new Fed chair, Jerome Powell. Yellen leaves the Powell Fed with two contradictory legacies. The question of the day is which will the Powell Fed now follow? What role will the Trump administration’s tax cuts and spending programs play in influencing the choice? And is the Powell Fed now in a ‘no win’ situation, regardless which policy direction it takes?

Yellen’s Fed represents a continuation of the policies of her predecessor, Ben Bernanke – just as Bernanke’s policies continued Alan Greenspan’s, his predecessor. All three Fed regimes are defined by their shared policy of decades-long, massive liquidity injections – beginning with Greenspan’s assumption of the Fed chair in 1987 and continuing through the third of Yellen’s four year term in 2016.

The legacy of their thirty years of unremitting liquidity injection has been excessively leveraged, debt-fueled investment in financial markets that generated asset demand driving financial asset prices into unsustainable bubble territory. With Greenspan it was the savings & loan industry bust in the late 1980s, the US contribution to the Asian currency bubble of the late 1990s, then the US tech stock bubble of 1999-2000, and, together with Bernanke at his side, thereafter the subprime mortgage bond and derivatives twin bubbles of 2004-07.

Yellen’s First Legacy

Like her predecessors, in her first three years at the Fed helm Yellen chose to continue the Greenspan-Bernanke policy of excess liquidity. As the following Table 1 shows, Yellen continued the Bernanke QE program of Fed dirvect bond buying in her first year as chair.

In 2015-16 thereafter, she continued to ‘rollover’ prior debt that was maturing, thereby keeping the Fed balance sheet at $4.5 trillion instead of allowing it to decline. The net liquidity injected into the economy by the Yellen Fed during its first three years, composed of new and rolled over debt, was thus likely in excess of $500 billion.2

A comparison of Yellen vs. Bernanke money supply growth further illustrates the Yellen continuation of the Greenspan-Bernanke excess liquidity policy and its effect on the US money supply. The virtual free money from the Fed clearly continued during the first three years of her term, as Table 2 indicates. The Fed benchmark rate remained in the 0.25%-0.5% range through 2016.

When measured in terms of the M2 money supply, more of the Fed’s liquidity actually entered the US economy on an annual basis during Yellen’s first three years than had even under her predecessor, Bernanke. Vast amounts of that liquidity flowed into financial markets, both in the US and abroad.

In 2017 the Yellen Fed began seriously raising its benchmark rates – albeit gradually. That policy shift of ‘rate hike gradualism’ is also a legacy – the second – of the Yellen Fed.  Excess liquidity initially, the first legacy, followed by gradualism in rate hikes constitute the Yellen Fed’s ‘twin legacies’.

The policy shift to gradually higher rates actually began under Bernanke, announced in 2013 but never implemented.

The policy shift to gradually higher rates actually began under Bernanke, announced in 2013 but never implemented. Bernanke in 2013 no doubt remembered the consequences of his prior shift and rate hikes in 2006-07 – a shift which contributed toward precipitating the 2007-08 housing-derivatives bubbles implosions. Bernanke announced his intention to raise rates in mid-2013 but then ‘blinked’ amidst widespread market negative reactions, in the US and across emerging markets.  He likely did not want to leave a legacy that on his watch the Fed’s policy shifts precipitated two – not one – market crashes. The 2007-09 was enough. Let someone else preside over the second. 

Bernanke’s legacy was threefold:  continuing his mentor, Greenspan’s policy, excess liquidity, followed by too high and too rapid rate hikes in 2006-07, thereafter by still even more excess liquidity post-2008.  If excess liquidity was the fundamental source of the bubbles and crisis, in some perverse logic then still more liquidity was envisioned as the solution short term.

Yellen’s legacies would be continuing the three decade long ‘Great Liquidity Put’ set in motion by Greenspan and Bernanke, and then to actually implement the Bernanke ‘rate gradualism’ policy shift in 2017, announced by Bernanke in 2013 but quickly shelved for the rest of his term. The differences between the Bernanke and Yellen legacies were thus minimal: both contributed to the GLP and, whereas Bernanke announced his intention to raise rates gradually in 2013 but didn’t, Yellen began doing so in her last year. The Yellen Fed was thus but an addendum to the Bernanke–except for the latter’s disastrous accelerate rate hikes in 2006-07 that helped precipitate the crash. That experience now looms large on the horizon for the Powell Fed.

The Bernanke Put: Greenspan’s on Steroids

Assuming the Fed chair in 2006, Bernanke attempted to reverse the prior two decade long policy of excess liquidity. By 2007, he had quickly raised the benchmark federal funds rate to 5.25%. However, after years of artificially low 1% rates under Greenspan’s Fed, raising rates too high and too quickly, to 5.25%, played a central role in precipitating the housing and derivatives bubble busts – the first commencing in 2007 and the latter in 2008.

The lesson of 2006-07 was clearly: after years of artificially low rates around 1% fueling debt-driven financial asset bubbles, rates could not rise to 5% or more, and certainly not that quickly in 2006-07. Today rates have been low, at 0.25% for almost eight years. And it’s unlikely that rates will have to rise anywhere near 5.25% to precipitate a similar markets’ response.

In the six years that followed the 2008 crash Bernanke would absorb the lesson of decades of excess liquidity, followed by too rapid rate hikes in 2006-07 only partially. To contain the 2008 crisis (fundamentally caused by excess liquidity enabled debt driven financial bubbles) he would resort to injecting even more liquidity in 2008-09. The ‘Bernanke Put’ would succeed the Greenspan’s Put by magnitudes.4  As a consequence, the Fed’s benchmark rate came down from a high of 5.25% to 0.25% in just months, and would remain there for eight more years. 

The Fed rate collapse of 2008-09 was enabled by means of quantitative easing (QE) injections of $4.5 trillion (and more if refinancing debt maturity rollovers are counted), special Fed auctions, central bank currency swaps, and traditional bond buying open market operations. Per some estimates, perhaps as much as $8 to $10 trillion in liquidity was added by collective means to the global banking system by Bernanke during his tenure at the Fed.

If Bernanke failed to heed the dangers of excess liquidity and debt driving financial bubbles, by 2013, he apparently did absorb the lessons of 2006-07– i.e. not to raise rates too high, too fast in an effort to try to retrieve excess liquidity.  In 2013, instead of raising rates too rapidly once again, he carefully suggested publicly that the Fed might begin raising rates once again in the near future–albeit very gradually and slowly. He also announced the Fed might even consider selling off some of its bloated $4.5 trillion debt.

Just the talk of rising US interest rates in the US precipitated a near panic in emerging market economies. EME currencies quickly depreciated, in turn accelerating capital flight from EME markets.

However, just the talk of rising US interest rates in the US precipitated a near panic in emerging market economies (EMEs).  EME currencies quickly depreciated, in turn accelerating capital flight from EME markets.  Bernanke backtracked quickly in the face of what was called then the ‘taper tantrum’. But as he reversed his announcement, he made it clear in late summer 2013, up until leaving office in February 2014, that it still was the Fed’s intention to eventually raise rates – as well as begin selling off the Fed’s bloated balance sheet (which would further raise rates) – at some yet undefined future date and at a slow rate. His Fed thereafter ‘marked time’ until his departure in February 2014 and replacement by Yellen. However, in the interim he had laid the groundwork for the Yellen Fed to implement his policy of rate hike gradualism.

Yellen’s Second Legacy

The Yellen Fed began clearly as a virtual extension of the Bernanke Fed: in the early years it continued to provide excess liquidity, like the Greenspan and Bernanke Feds before. Moreover, the Yellen Fed continued to do so for three more years, and only in the last year of her term cautiously began to seriously implement the Bernanke policy of gradual rate hikes.

It took the Yellen Fed two years before it would make even a token increase in rates, and then only a tepid 0.25% hike at the end of 2015. It took another full year before another token hike occurred, in December 2016.  Neither together was sufficient to discourage the financial asset bubbles that were growing, still being fueled by the prior eight year policy of continued liquidity provided by the central bank. 

It was only in 2017 that the Yellen Fed started to rise noticeably, in hikes of 0.25% well spread out over the year. From 2014 through 2016, the excess liquidity policy continued to feed financial asset markets expansion. The 2017 rate gradualism policy was modest and slow and clearly intended not to discourage financial markets from their steady run up that was set in motion back in 2010. The 2017 rate increases, which raised Fed rates to a level of 1.5%, were thus a cautionary hike in anticipation of potential aggressive Trump fiscal policy on the horizon, as well as a response by the Fed to the emergence of what was called the ‘Trump Trade’–i.e. rising financial markets, especially equities, in anticipation of business-investor tax cuts coming and the release of ‘animal spirits’ boosting business investment.

However, clearly the Bernanke-Yellen policy of rate hike gradualism was becoming less gradual by 2017. Gradualism was being slowly redefined. It was not 2014-16 token gradualism, but nor was it yet 2006-07 of rapid rate hikes! However, signs began to appear in 2017 that perhaps a repeat of 2006-07 (and perhaps its consequences) was not too far away.

Trump promises of accelerating fiscal policies – tax cuts and spending alike – were being taken seriously by financial markets in 2017.

Trump promises of accelerating fiscal policies – tax cuts and spending alike – were being taken seriously by financial markets in 2017. The so-called ‘Trump trade’ was boosting financial asset markets. In the face of that, the additional 1% hike in the Fed benchmark rate in 2017 did little to dampen financial asset market speculation and inflation. Stock markets in particular were now being driven by the new ‘animal spirits’ based on little but expectations of a great windfall in profits and capital gains from the Trump tax cuts.

By year end 2017, the thirty year, 1987 through 2016, ‘Grand Liquidity Put’ of Greenspan-Bernanke-Yellen clearly had come to an end. Fiscal policy would now drive monetary. Unlike the preceding period when monetary policy by central banks was the lead and fiscal austerity followed in its wake.  By early 2018 it now appears the gradualist Fed rate hikes policy–announced and aborted by Bernanke in 2013 and begun to be implemented 2016-17 by Yellen – will soon be replaced with more accelerated rate hikes 2018-19. That raises the new scenario that future Fed policy may consequently look more like 2006-07 – with all its consequences – overlaid with a new taper tantrum in emerging markets that will dwarf the aborted reaction of 2013.

Yellen’s Legacies; Powell’s Dilemma

The Powell Fed now faces a dilemma:  Does it continue Yellen’s policy of relatively slow and occasional rate hikes, allowing financial markets to escalate still further into bubble territory, driven now by new forces of fiscal stimulus and the release of global investor ‘animal spirits’?  Or does it raise rates faster, and in increments more than 0.25% as in the past, to confront the new fiscal stimulus and investor expectations? More important, what might be the effects of more rapid rate hikes on financial markets? Will it be 2006-07 all over again? How high must rates go until it does? The Fed says it doesn’t care about financial markets. But it is expected to say that. In truth, its past track record shows it clearly does care.

The Powell dilemma may be answered not by the Fed. Not by central bank monetary policy. In 2018 monetary policy may be relegated to a secondary role and forced to follow fiscal once again – something that has not been the case for decades. The Powell Fed may have its direction chosen for it – i.e. by the Trump-Congress fiscal policy already set in motion. By the Trump tax cuts, the accelerating US war spending, possible infrastructure spending, etc.

Yellen’s legacy of ‘rate gradualism’ will likely be abandoned – as trillion dollar annual US budget deficits loom now for years to come as a result of Trump tax cuts and spending plans. That fiscal policy shift already means the Fed will now have to borrow significantly more – in the next two years alone at least $600 billion more to fund the $300 billion in Trump tax cuts and $300 billion in additional budget deficit spending (and perhaps more if defense spending continues to rise as projected next year or Congress itself funds more than Trump has requested).

Beyond the next two years, in the longer run, perhaps $10 trillion more in US deficits over the coming decade, should certain assumptions by Trump and Republicans prove erroneous: i.e. should US GDP not exceed the projected 3% plus annual growth rates; should a recession occur sometime in the next decade which is highly likely; should foreign buyers of US Treasury debt slow their purchases, should US defense spending continue to accelerate; and should the Trump tax cuts cost more than initially reported.

Estimates of next year’s US budget deficit by JP Chase Bank research is already $1.2 trillion, and other sources project even higher. Most independent sources estimate average annual deficits of $1 trillion or more for a decade to come. That’s more than the $10 trillion, to be added to the current US national debt of $20 trillion. And that’s a mountain of Treasury bonds to be sold by the Fed, which will no doubt require more rapid, significant, and sustained Fed rate hikes to finance. The 30 year ‘Grand Liquidity Put’ is over. Central bank Fed monetary policy is henceforth the tail on the fiscal dog.

The question now being asked by ‘Fed watchers’, bankers, and business press pundits is whether Powell will continue Yellen policy of gradually raising Fed rates (not likely) or will he raise Fed short term benchmark rates even faster, perhaps four times or more in 2018, as has been signaled–and even further thereafter in 2019? And will the Fed under Powell accelerate the sell off of its balance sheet – announced by Yellen, but not yet really begun, thus driving rates higher even faster?

A next set of questions is whether a flattening yield curve now underway, and a slowing real US economy by late 2018-early 2019, bring the new rate hike and tightening Fed policy to a halt? Could it even mean, in the medium term, a return to a policy of rate reduction and cheaper money once again? How soon before rising rates precipitate another financial instability event?

Put alternatively: how high (and fast) will Fed rates rise in the short run, 2018-19, before the prior liquidity fueled financial asset bubbles of 2009-18 created by Greenspan, Bernanke, and Yellen begin to burst?  The 10% February 2018 stock market corrections may be but a harbinger of things yet to come – a dress rehearsal correction that often occurs before the more sustained corrections that follow weeks, sometimes months, later.

Three to four rate hikes in 2018 may lead to history repeating itself. The Fed’s rate hiking in 2007-08 – from a 1% Fed funds rate to more than 5%–precipitated the crash of the bubble in subprime mortgages that spread via derivatives contagion to the rest of the credit system. A similar experience in 2018-19 may be in the making, albeit with new causal transmission mechanisms and other financial asset markets. It won’t be mortgages and credit default swaps next time. Fed rate hikes may burst the current bubbles in stocks and junk bonds–this time transmitted by derivatives in the form of exchange traded notes & products linked to passive investing and quant hedge fund algorithm-induced automated selling. Or it may come from emerging markets, now overloaded with dollar denominated corporate debt, that collapse with massive capital flight and recessions provoked by rising domestic rates that shut down their own economies. It may even originate in China where, even if contained there, will send unknown psychological contagion effects across the rest of the global economy.

When rising rates driven by fiscal policy inevitably meet the financial fragility that exists in key sectors of the US economy, it may bring about the abrupt termination of the Fed rate hike policy about to accelerate at the Fed.5

The last time the Fed reversed course and raised rates in 2006-08, rates rose beyond 5% before the bubbles imploded. Given the fundamentally more fragile US economy today, it may take far less a hike to precipitate the same!

The last time the Fed reversed course and raised rates in 2006-08, rates rose beyond 5% before the bubbles imploded. Given the fundamentally more fragile US economy today, it may take far less a hike to precipitate the same! 

As this writer has been arguing elsewhere recently, what’s different today from 2006-07 is that it will almost certainly not take a 5% Fed funds rate to precipitate another crisis. A Fed funds rate of 2%-2.5% may prove sufficient. A 10 year Treasury bond rate of 3.5% could provoke the same.  Either could set in motion a serious contraction of bond or stock Exchange Trade Funds’ prices, accelerated by Quant hedge fund algorithmic trading, and amplified by the mass influx of passive index investing in recent years.

While that may not be the immediate short term scenario, it may not be far from the midterm truth, circa 2019-20!

About the Author

Dr. Jack Rasmus is the author of the recently published book, ‘Central Bankers at the End of Their Ropes: Monetary Policy and the Coming Depression’, Clarity Press, August 2017, which has been previously reviewed on this magazine. He blogs at drjackrasmus and his twitter handle is @drjackrasmus.

References

1. See Jack Rasmus, ‘Yellen’s Fed: From Taper Tantrum to Trump Trade’, in Central Bankers at the End of Their Ropes, Clarity Press, August 2017, Chapter 14, p. 260.

2. Some argue that the ‘rollover’ of debt does not matter because an equal amount of debt was retired compared to the issue of the rollover. But this ignores the effect of the money multiplier as the liquidity enters the economy. The principal may be retired, but the ‘multiple’ of the liquidity is not and it contributes as well to the financial asset bubble expansion.

3. https://fred.stlouisfed.org/categories/32329?tg=gen.

4. See Jack Rasmus, ‘Bernanke’s Bank: Greenspan’s ‘Put’ on Steroids’, Chapter 5 in Central Bankers at the End of Their Ropes: Monetary Policy and the Coming Depression’, Clarity Press, August 2017, pp. 106-41.

5. For tis writer’s analysis of how the US economy has become more ‘fragile’ in recent years–based upon variables of debt, income, and terms of debt servicing, see Jack Rasmus, Systemic Fragility in the Global Economy, Clarity Press, 2016.

AIIB: Experiments in Scaling-up Development Finance

By Daniel Poon

Since its launch in January 2016, what are the significant developments on the operations of the Asian Infrastructure Investment Bank (AIIB)? In this article, the author discusses the operational features of AIIB and provides insights into the bank’s lending operations by adopting an institutional perspective on China’s experience with its own national development banks, such as the China Development Bank.

The middle of last month marked the second anniversary of AIIB, but many are still debating: will it be any different from existing multilateral development banks (MDBs) like the World Bank or the Asian Development Bank (ADB)?

Unlike most major MDBs, the Bank is majority owned by developing countries with China as its largest shareholder. This could make the AIIB more attuned to the interests of developing countries, but not necessarily so.

In fairness, two years is too short a time span for a definitive verdict on the nature of the Bank’s operations. Thus far, it has expanded its initial membership of 57 to 84. The Bank has extended loans to 24 infrastructure projects (in which three are fund of funds investments) in 12 countries. Total loans amount to $4.2bn, which has mobilised an additional $17bn from other public and private investors.

For now, India is the top borrowing country in terms of number and value of AIIB investments. India has received five investments worth $4.07bn, of which $1.07 bn was contributed by the AIIB.

For now, India is the top borrowing country in terms of number and value of AIIB investments. India has received five investments worth $4.07bn, of which $1.07 bn was contributed by the AIIB.

Overall, this is a good start, but does not suggest anything especially innovative about the Bank’s way of doing business.

The debate about the AIIB stems in part from an oversimplification of the challenges of setting up a new MDB, essentially from scratch. The World Bank has been in operation for over 70 years; in 2017 it disbursed $43.9bn and had a total full-time staff of under 12,000. By comparison, at the AIIB’s first annual Board of Governors meeting in June 2016, it had a total staff of 39, and anticipated a total staff of 100 by the end of that year.

The AIIB regards 2016 – 2020 as its “start-up phase”, and 2021 – 2027 as its “growth phase”. This gradual approach is also consistent with China’s overall style of pragmatic economic reform and opening-up.

So it will take some time before AIIB can match the lending scale of those with a longer history. And rightly so, solid multilateral institutional foundations and practices do not simply fall from the sky. Indeed, the AIIB regards 2016 – 2020 as its “start-up phase”, and 2021 – 2027 as its “growth phase”. This gradual approach is also consistent with China’s overall style of pragmatic economic reform and opening-up.

But as the AIIB ramps up, certain features that allow for institutional experimentation seem to be moving into place. In a recent interview, Jin mentioned that, “We must have creative spirit, and neither clone the World Bank nor copy the ADB. Instead, we should review and absorb good experiences and strive to build a multilateral financial institution with advanced 21st century governance concepts.”

Some of this “creative spirit” is already apparent: to reduce administrative costs and loan approval times, the AIIB board of directors is unpaid and non-resident; also, bidding for AIIB projects is not confined to member countries. On environmental and social safeguards, some have expressed concerns over the Bank’s reliance on corporate and country reporting systems, but others believe this could promote greater borrowing capacity in recipient countries.

A more contentious issue, however, is that of AIIB’s loan capacity and loan conditions: can the Bank strike a balance between high-standards and safeguards on project loans, while improving the speed and size of loan dispersion without resorting to strict policy conditionalities?

It is still too early to assess these aspects, although China is clearly far less willing to impose wide-ranging policy conditionalities. Existing studies have generally focussed on estimating AIIB’s scale of lending by super-imposing the operational features of existing MDBs.

From an institutional perspective, however, China’s experimental approach to its own national development banks – such as the China Development Bank – could also suggest an inclination for experimentation with the AIIB.

For starters, the AIIB has secured a triple-A rating from the three major international credit ratings agencies. This rating is contingent on the Bank respecting its (maximum) statutory loan-to-equity ratio of 2.5, which allows the Bank to tap international capital markets at low-cost. (The Bank plans its first international bond issuance in the second quarter of this year.)

This conservative statutory ratio is consistent with those of existing MDBs. But the Bank’s articles of agreement also includes little-noticed provisions for a “special funds” mechanism that is managed by the AIIB and that can channel finance to AIIB infrastructure projects, but whose resources are held separately from the Bank’s shareholder equity.

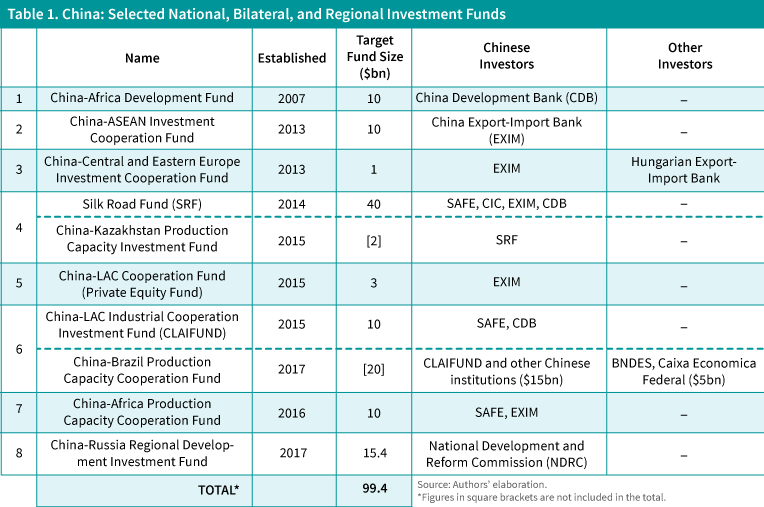
The idea is that outside public and private investors can contribute resources to these special funds, and it just so happens that China has also created several stand-alone investment vehicles that have a combined target fund size of almost $100bn – such as the $40bn Silk Road Fund, the $10bn China-Africa Development Fund, and the $15bn China-Russia Regional Development Investment Fund, among others (see table 1)

Most of these vehicles have received their capital from China’s national development banks (and other Chinese institutions), which, in turn, leverage the equity capital received from the country’s foreign exchange reserves to raise cheap financing from domestic capital markets.

It is not inconceivable that at some point some of these various vehicles could selectively finance AIIB infrastructure projects through the special funds mechanism, especially as the Bank garners further expertise managing projects in different regional settings.

AIIB’s institutional design appears to maintain a de jure loan-to-equity ratio aimed at safeguarding access to international capital markets, while also creating a conduit that allows for de facto infrastructure financing to be scaled-up above the statutory limit.

In sum, the AIIB’s institutional design appears to maintain a de jure loan-to-equity ratio aimed at safeguarding access to international capital markets, while also creating a conduit that – in indirectly tapping China’s domestic capital markets (and foreign exchange reserves) – allows for de facto infrastructure financing to be scaled-up above the statutory limit.

Keeping AIIB’s institutional context in mind, some Chinese scholars have suggested that China’s overseas development finance will come less in the form of official development assistance, and more in the form of “other official flows” (OOF), OOF-like loans and OOF-like investments from national development banks and other state-backed entities, due to the nature of large infrastructure projects.

In this vein, Zhou Xiaochuan, governor of the People’s Bank of China, positioned the role of development finance as in-between that of concessional and commercial finance, but “slightly tilted” toward the latter.

It is this apparent inclination to experiment with innovative financial arrangements that could allow the AIIB to improve upon existing MDB practices, at least in terms of extending large and rapid infrastructure project loan dispersions. To be sure, the only special fund that currently exists provides grants to low income member countries for project preparation.

But AIIB’s articles of agreement appears to leave room for wider experimentation with scaling-up via the special funds mechanism, and it is this broader backing of China’s financial institutions that may, in due course, reveal AIIB’s distinctive operational features.

This commentary is based on a background paper co-authored with Ricardo Gottschalk, prepared for the first session of UNCTAD’s Intergovernmental Group of Experts on Financing for Development, 8-10 November 2017.

About the Author

Daniel Poon is an economist with the United Nations Conference on Trade and Development (UNCTAD), Division on Globalization and Development Strategies. He previously worked for the International Labour Organization and the North-South Institute (Canada). His main research interests and publications involve China’s industrial strategy, development finance and South-South economic relations.

Women in Tech: How Email Expert Andrea Loubier is Leading the Email Revolution

Interview with Mailbird CEO Andrea Loubier

Email communication plays a vital role in today’s highly digitised and complex business environment. However, being overwhelmed and frustrated by emails is inevitable. In our interview with Mailbird CEO Andrea Loubier, we talked about the occurring changes in today’s email world, on effective email management and how being a woman in the tech industry could be of advantage in navigating a company to be in the vanguard of technological innovation.

Before finding your niche in the technology sector, you were immersed in other industries. Could you tell us your career journey?

First corporate job out of college was with a market research firm. I was there for 6 years and worked my way up every year. I was very committed and dedicated to my role at that company. I worked very hard. The next job I had was with a software company, and up and coming one that was growing fast and I heard they treated their employees amazingly well. So I was there for one year before asking myself what I wanted to do next, and decided I wanted to work with technology and also gain some international business experience. So I packed up my life and moved to Bali, Indonesia, met my two co-founders for Mailbird and began to create a business and solution for millions around the world out of nothing. I always have a tendency to enter management roles, some say I have a type A personality. I like to plan, organise and execute.

Presently, you’re the CEO of Mailbird. What makes this executive role significant for you?

It’s significant because it gives me the feeling of ownership in what I put my life into, from the very beginning. It means I get to lead and be the person who represents the company and the brilliant people behind it at Mailbird.

Email is vital in modern business correspondence. What are the significant developments you have witnessed over the years? Is it fair to say that email platforms have indeed evolved?

Email is probably one of the greatest things that came from the invention and mass adoption of the Internet. It’s the best way to communicate cross boarders, fast and efficiently.

Email is probably one of the greatest things that came from the invention and mass adoption of the Internet. It’s the best way to communicate cross boarders, fast and efficiently. Over the years, it’s clear that people are becoming overwhelmed with managing information that comes through their inbox. So now you see many email platforms evolving with the increase of shared information to help people reduce the management of it, with smart features that automatically do things for you or simply make things faster by the milliseconds. That precious time is everything today, and email platforms are getting smarter, so people and businesses can spend their time efficiently. For our focus, we are looking to de-cluttering and unifying all those communication apps that are built on top of email into one unified platform with Mailbird. So you have all your email accounts from any provider, plus your other communication channels like Messenger, WhatsApp or even WeChat for those in China fully integrated into Mailbird’s unification platform.

From aspiration to fruition – now we have Mailbird. What’s the story behind Mailbird? Why is your company known as the Sparrow for Windows?

Myself and my two Danish co-founders, both named Michael, all expressed problems and our deep disdain for email. It’s stressful. I get too much of it. It’s not enjoyable to use. We saw Sparrow, a native email client for Mac only that provided a clean, stripped down, simple native Gmail experience in a nicer user interface. Nothing like Sparrow existed for Windows, and we believed we could take it a step further by supporting all email providers, and not just Gmail. Then the big differentiator and ideas started flowing, how email can evolve with all the new productivity and communication apps used across different generations and use cases, from personal to business, from grandparents to teenagers. A beautiful experience, fast and easy to use, smart unified email and communication platform that’s good enough for businesses and easy enough for the not-so tech savvy.

In reference to your experience, what are the greatest demands of consumers today and how should those things be addressed strategically?

With Mailbird, we focus on delivering the best-unified email experience to the world by ensuring emails are sent and received and interaction inside the Mailbird app is fast.

Consumer today demands speed, convenience and customisation. In all experiences a customer/consumer experiences with a brand, business, product or service those three things should be designed into that experience so the end user feels good and associates positive experiences with these businesses. With Mailbird, we focus on delivering the best-unified email experience to the world by ensuring emails are sent and received and interaction inside the Mailbird app is fast. We ensure that it’s easy to do repeat actions in Mailbird and all the core features you need make managing communication and information exchanges very easy and accessible from anywhere including making it convenient to use both email from any email provider and account and messages in Whatsapp accessibly convenient from one platform, again being Mailbird. Customisation is a key part of building a great user experience, and they can personalise Mailbird in such a way that fits them best, including layout and apps and how all functions are working and visuals are displayed.

With your knowledge of the email world, what do you think are the limitations with all email platforms?

It cannot replace face-to-face or real time communication. Emotions and tone are a big part of how we communicate, and because it’s easy for written/typed communication to easily be misinterpreted, it’s best to have a face to face discussion over a matter to ensure there is no misunderstanding. Otherwise, email is a wonderful tool for asynchronous communication, organising priorities and communicating to a large audience without having to have hundreds of thousands of people gather to hear you speak.

We all sometimes get preoccupied with our emails. How can we avoid that? What makes an efficient email management?

To avoid being totally consumed by email, the best tip is to ensure you schedule your time with email and limit it.

Yes, we all do. It happens, we are human. I believe more training should be done during education on information management via email or any online communication that occupies our lives if not managed. To avoid being totally consumed by email, the best tip is to ensure you schedule your time with email and limit it. This will force you to go through this process of filtering first, deleting and archiving or quick acknowledgements. Then prioritising those that need an immediate response. Next, create a task list from things that you need to execute from emails and ensure its prioritised as well by importance. Another strategy we advise email users is to create a task list the day before your next work day, and don’t check emails first when you start the day. Instead work on the first prioritised task in your list. Turn your messenger, internal chat apps and email off. If something is urgent, email is a secondary form of communication to a real time phone call or face to face meeting. Be sure to set expectations with those you work with, it helps to let them know how you structure your day to ensure the most productive use of your time and the best execution of prioritised tasks.

Apparently, innovation is crucial in any industry. In your line of business, how can you say that you’re at the frontier of innovation?

I believe innovation is a continuous journey that adapts and pivots with changes in human behaviour and new problems that develop with the rapid increase of technology use in our lives. Mailbird has innovated the email experience and use of technology by its unique features that provide new ways of managing the increase of information we need to process online today that come through our inboxes and other communication and productivity apps. We started with enabling people and businesses to manage an unlimited of email accounts from any email provider to be managed from one tool, finally. This was unified inbox. We added inbox clearing features like Snooze to ensure you clear things off your plate, in this case your inbox, and manage them at a more appropriate time rather than having it occupy your inbox. It’s clean inbox management, so you work with things that you need to, and remove things that you don’t need to deal with at that moment or day. The next step is unifying your apps and email inboxes further, with seamless integration and customisation of what you need to get things done, because everyone is different here, and this is why this is critical and a favoured differentiator for Mailbird against the competition out there. Soon we will unify further by making our platform available cross devices and operating systems. No more management of several different apps and tools, only one tool for all communication and productivity that is easily customised.


What do you think is the greatest obstacle that aspiring leaders/entrepreneurs need to grapple with? What advice can you give?

People have a tendency to focus on what is not possible rather than just starting with what is possible… Once you grasp the fact that entrepreneurs are not super humans, and that you need help to do things…the easier it is to start.

The first is just starting, again here people have a tendency to focus on what is not possible rather than just starting with what is possible. I made the decision to quit my job, move to Bali, and build my first tech company, Mailbird. I had never done any of these things before. If I didn’t know something I researched it and talked to people who have done it before. Once you grasp the fact that entrepreneurs are not super humans, and they don’t know everything, that you need help to do things…the easier it is to start. Another thing is not basing business decisions on assumptions, but hard data and validated research instead. Talk about your business early on, find all the small first steps to take right away, talk to people and get feedback and start building upon your idea for the business. Be prepared for big learnings, small adjustments and making calculated risks. Finally, don’t over think things too much…just start, and embrace the “learn as you go” process. Finally, find the right people to support you and the right tools, like Mailbird, to manage the intense flow of information you’ll need to manage when you start your first business. I also encourage more women to experience the greatest journey ever of starting a business, it’s exciting, empowering and repositions our world to accept diversity and recognise the value that women bring to the world.

You are a proof that women can indeed be on the forefront of technological endeavours. How was your experience? What are the advantages and drawback of female leadership in this kind of business?

It’s fantastic to be a woman in tech, and you don’t have to come from an IT background to do it either. I think that’s the first barrier that some might tell themselves, man or woman, when considering pursuing a technological endeavour, “I can’t because I didn’t study IT”. So many of us focus on what we cannot do, rather than what we can do. I guess it is human nature to be self-doubting, but somehow I made the decision to start an IT company, without a degree in programming or computer engineering, by focussing not on what I couldn’t do, but what I could. I can’t code, but I can find someone who can and I’m great with people so I will succeed in building an incredible team. I’ve worked in management, marketing and software companies (even though I wasn’t a computer engineer in these companies). You take what you can do, and that is how you do it. When I started Mailbird in Bali, Indonesia 5 years ago, I felt like I was the only female tech CEO in Asia, which was kind of cool. It was more the reactions of people when I told them I started an email software company, surprised that I, a woman was the lead in creating and building this business that is very tech heavy and tech focused. Advantages are there are opportunities that support women founders, drawback is people still not take you seriously enough because you are a women in a industry where you are the minority, which somehow ends up being associated with not being good at it. Lack of inclusion and assumptions about women in executive tech roles are a daily battle, simply because people are still getting used to this. What many don’t realise, are the major strengths that women can bring to the success of a company that other “typical”, male, technical executive’s lack, one being consumer focussed thinking women are still the dominant consumers in the world today. Women have a tendency to also be very skilled at building relationships, and the longer you run your business, the more you understand the importance of partnerships and relationships to help you succeed and grow.

In your journey toward the C-suite leadership, who/what were your greatest inspirations/motivations or influencers?

Companies like Sparrow, Uber, Airbnb and Facebook are obvious pioneers in fast growing companies. Those that motivated and influenced me most though were Jessica Mah, Hermione Way and Sheryl Sandberg. All amazing women who made a name for themselves in a male dominated industry of tech. Today I try to ignore the hyperbolic success of these unicorn tech startups, and consider the valuable steady, linear growth companies.

All leaders have their own impressive lifestyles that help them strengthen their inner selves. Could you share to us your daily routines that make you an incredibly successful CEO?

I travel a lot, and no matter where I am in the world, I see no boundaries for where I can accomplish great things. The location independent productivity lifestyle is one that has never been seen before. People are able to make money online now rather than relying on industrial 9 to 5 jobs. So no matter where I am, I will find a community of like-minded location independent entrepreneurs. I like to stay healthy and active to balance work and life with health as the pinnacle of my priorities, because if you aren’t in good health then everything else around you suffers. I have routines in how I work, I challenge myself every day and ensure I’m always available to my team across the globe. I set up a weekly meeting with teams in my company to ensure we communicate, solve any obstacles or tensions, and keep design and innovative thinking and learning at the forefront for development. I am also a coffee addict, my day never starts without a coffee. I make sure to take breaks, and although I might be flexible and work on weekends on public holidays when everyone else is off, I do make an effort to cut off completely from work. It’s all about balance for me.

Thank you very much, Andrea.

About the Interviewee

Andrea Loubier is a travel addict, who is obsessed with spicy food. A third culture kid who is crazy, passionate about entrepreneurial initiatives for women, improving the unification of online communication and building businesses from the ground up. Andrea is a thought leader for startups founded by brilliant women in Southeast Asia. She is the CEO of Mailbird.


The Economic Moral Hazards of the International Criminal Court – and the Philippines Withdrawal

By Dan Steinbock                                                 

As the Philippines is withdrawing from the International Criminal Court, ICC is blaming the Duterte government. In reality, the withdrawal is still another example of the erosion of the ICC’s credibility, its failure at judicial independence and gross bias against the emerging world.

In February, the ICC said it was investigating allegations that the Philippines president had committed “crimes against humanity” by facilitating extrajudicial killings and other rights abuses in the war against drugs. These charges, which have often relied on flawed data, have been pushed by two Duterte critics. Known for his coup efforts, controversial senator Antonio Trillanes has spent much time in Washington and Europe to gain support, while the obscure Jude Sabio has gained notoriety as a hit man lawyer. What’s not known is who funds the two and why leading Western media companies have bought their stories with hardly any source scrutiny.

Philippine polls indicate that more than 70 percent of Filipinos stand behind Duterte and are more satisfied with his government than any previous one.

In Manila’s view, the ICC can only investigate criminal cases if domestic courts are unable or unwilling to do so, and neither applies to the Philippines. Moreover, Philippine polls indicate that more than 70 percent of Filipinos stand behind Duterte and are more satisfied with his government than any previous one.

Yet in March, the controversial UN’s High Commissioner for Human Rights (HCHR), Prince Zeid Ra’ad al-Hussein, joined the ICC debacle saying that Duterte needed a psychiatric evaluation. During Zeid’s tenure, the HCHR has repeatedly been accused of efforts at domestic policy intervention, which impinges on state sovereignty. As Zeid played a central role in the founding of the ICC from the mid-90s to 2010, his statement triggered valid concerns in Manila about the institution’s neutrality.

The withdrawal of the Southeast Asia’s most rapidly-growing economy from the ICC would not be either the first or the last of its kind. The credibility of the ICC is under erosion. The case of the Philippines is just the latest nail in the coffin.

Targeting the poorest and the weakest

For a decade or two, the ICC has suffered from an odd inclination to go after the poorest countries in Africa, which has suffered the worst and longest from colonial massacres and plunder – and still does. The prosecution of President Uhuru Kenyatta led to the Kenyan parliament’s call for withdrawal from the ICC and the call on more than 30 African member states to withdraw their support.

The frustration led to a special African Union (AU) summit in 2013 in which Uhuru accused the ICC of being “a toy of declining imperial powers.”

ICC Prosecutor Luis Moreno Ocampo charged Uhuru as an indirect co-perpetrator in the violence that followed the 2007-08 Kenyan crisis. Uhuru is a popular, highly-regarded politician and the son of the famed anti-colonial leader Jomo Kenyatta. After a three-year juridical chaos, the ICC charges were dropped in March 2015 for lack of evidence. If the case undermined the ICC’s credibility, wasting resources and causing gratuitous political turmoil, why was Uhuru targeted?

Certainly, his political opposition hoped to benefit from his demise. It was led by Raila Odinga and his Orange Democratic Movement, which was reportedly named after the Ukrainian “Orange Revolution” as billionaire George Soros’s Open Society funded the pro-Odingakey NGOs, and Kenyan think-tanks to stop President Uhuru from the 2013 general election due to the ICC trials. As the ICC process began to penalize Kenya’s political leadership, economic growth almost halved to 4.6 percent in 2012 stabilizing thereafter but at a significantly lower level than in 2010.

In the past few years, many African leaders have reproached the ICC of “mishandling complex African issues,” and several countries, including South Africa, intend to withdraw from the ICC. In addition to President Uhuru, almost 40 individuals have been indicted by the ICC, including Ugandan rebel leader Joseph Kony, Sudanese president Omar al-Bashir, Libyan leader Muammar Gaddafi, Ivorian president Laurent Gbagbo, and Congolese vice-president Jean-Pierre Bemba.

Many cases suggest a pattern of sequence and orchestration: promising development, political destabilization in the name of “democratization,” financial speculation, new leaders, weaker development.

ICC’s compromised former prosecutor

Since fall 2017, even Ocampo’s ICC role has elicited questions. While his legal expertise is highly-regarded, his ties to Soros-supported organizations stem from the early 1990s, when Soros began to infuse funds into a real estate conglomerate (IRSA), a prominent backer of Ocampo’s NGO in Argentina. In the mid-‘90s, Ocampo began to work for Transparency International, a corruption watchdog that has been criticized for bias against developing countries, overseeing work on Latin America. A decade later, he participated in a roundtable by Soros’s Open Society called “Restoring American Leadership – the International Criminal Court.”

When the UN Security Council assigned Ocampo the task of investigating war crimes in Libya, which was soon hit by airstrikes of France, Britain, the US and other countries, Ocampo reportedly shared confidential information about ongoing investigations with a party to the conflict; the French foreign minister’s cabinet chief.

Ocampo indicted Gaddafi and his son Saif al-Islam for war crimes in 2011 before leaving his job at the ICC for a lucrative career in private practice. According to a French investigative website Mediapart, and a Spiegel team, he then agreed to a contract worth $3 million over three years, plus $5,000 a day, to “protect” and advice an influential Libyan oil billionaire Hassan Tatanaki who had close links with the Colonel Muammar Gaddafi and was deeply involved with the Libyan civil war; Ocampo used insider information to protect his client from possible prosecution by the ICC.

More recently, Tatanaki has been linked to a Libyan militia accused of extrajudicial killings and other rights violations. Reportedly, the contract was terminated after three months, with the ex-prosecutor earning $750,000. Yet, he used ICC employees to continue to carry out PR work for Tatanaki and was paid to do so, which was still another potential breach of the ICC’s code of conduct.

As the champion for transparency, Ocampo made millions of dollars in such deals routing monies to his offshore companies in several tax havens, as evidenced by the Panama Papers. Ironically, he used what he had learned about corruption to benefit from illicit capital flows. As he later said, he wanted to “make some more millions” because the ICC salary (€200,000) was inadequate for his needs.

Unsurprisingly, perhaps, the ICC secured its first verdict only in 2012, when Ocampo’s nine-year tenure at the ICC was about to end. Last fall, the ICC said that its current prosecutor Fatou Bensouda had asked Ocampo to “refrain from any public pronouncement or activity that may — by virtue of his prior role as ICC prosecutor — interfere with the activities of the office or bring it into disrepute.”

Who controls the ICC

Usually, economic power translates to political control. The ICC is not an exception. Yet, the ICC’s funding is not transparent. It is financed “primarily” by its member states. The contributions of each state are determined by the method used by the UN, which roughly corresponds with a country’s income. In 2017, the ICC’s budget was €145 million. About two-thirds came from only 10 countries, more than half from Europe’s former colonial powers and the rest from Japan, South Korea, and Canada.

Economic power translates to political control. The ICC is not an exception. Yet, the ICC’s funding is not transparent. The lack of transparency and accountability creates potential for gross moral hazard.

In the world economy, the EU accounts for about a fifth of the total; its funding of the ICC is thus three times its share of the global economy. Yet, according to the ICC, “additional funding is provided by voluntary government contributions, international organizations, individuals, corporations, and other entities.”

The lack of transparency and accountability creates potential for gross moral hazard. For instance, multinationals that have funded war lords in Africa to extract oil, gas, minerals and conflict diamonds might be particularly interested in targeting African politicians in the ICC.

Critics believe that as the ICC ignores the governments and focuses on their leaders, it may support flawed investigations that ignore the role of the governments while tacitly supporting regime change through new leaders. In some cases, prosecution of leaders in the ICC has made them less likely to peacefully step down. Also, success in investigations requires state cooperation, which the ICC mandate shuns and that can result in inconsistent and discriminatory selection of cases.

Unsurprisingly, the half a dozen countries that voted against the ICC Statute in 1998 included both the US and China. While President Clinton signed the Statute, he knew that it would never be ratified on Capitol Hill.

More recently, the US and Russia have said they no longer intend to become ICC members and thus have no legal obligations arising from their signature of the Statute. China’s view is that the ICC goes against the sovereignty of nation states.

Advanced economies’ court?

It was the Rome Statute of the International Criminal Court that led to the creation of the ICC in 1998. Nevertheless, its ability to investigate and prosecute is severely restricted by its mandate and, due to its creation in 2002 it can only prosecute crimes after that date. That conveniently suspends the worst genocides, crimes against humanity, war crimes and crimes of aggression – the four core international crime categories that the ICC claims to focus on.

Today, there are more than 120 state parties to the Rome Statute. Over 30 countries have signed but not ratified the statute, and there are more than 50 non-signatory countries. Let’s look more closely at the countries that are parties to the Rome Statute and those that aren’t.

The most populous middle-income economies remain outside the ICC. Only the smaller populations of high-income economies see the ICC as useful.

The overwhelming majority of the world populations have not joined the Rome Statute. The most populous middle-income economies remain outside the ICC. Only the smaller populations of high-income economies see the ICC as useful. Among the poorest economies, half have joined the ICC and another half hasn’t.  Many have been forced to adjust to major powers’ status quo (Figure 1a).

The economic story is even clearer. It has been very much in the interest of the high-income economies to join the ICC. Conversely, it has been very much in the interest of the less prosperous middle-income economies to stay away from the ICC, along with low-income countries (Figure 1b).

Figure 1 Parties and Non-Parties of the ICC:

High-, Middle- and Low-Income Economies, 2017

A. By Population (millions)

B. By Gross Domestic Product (GDP, $ millions)Sources: ICC, IMF.

In Asia, neither China nor India is a signatory. In Southeast Asia, both relatively wealthier countries (Singapore, Brunei, Malaysia) and emerging economies (Indonesia, Thailand, Vietnam, Myanmar, Lao) have not signed the Statute.

The simple reality is that, in the past two decades, the ICC’s credibility has deflated and its judicial independence has been compromised.

Cambodia did ratify the Statute in 2002, which may be currently contributing to elevated tensions in the country. The Philippines signed the Statute in 2000 but did not ratify it. That’s what most US partners did at the time emulating Washington’s stance. Yet, President Aquino did sign the Statute in February 2011, right before he aligned Manila’s foreign policy with President Obama’s security pivot to Asia geopolitically – but in contrast with almost all BRIC and ASEAN economies.

The simple reality is that, in the past two decades, the ICC’s credibility has deflated and its judicial independence has been compromised. Distressingly, it has shown gross bias against emerging and developing economies. A membership in such an international court is no litmus test for the advocacy for human rights in which the Philippines has a long history.

Featured Image: President Rodrigo Roa Duterte Graces Meeting Local Chief Executives from Luzon © ROBINSON NIÑAL JR./PRESIDENTIAL PHOTO

About the Author

Dr Dan Steinbock is the founder of Difference Group and has served as research director at the India, China and America Institute (USA) and visiting fellow at the Shanghai Institutes for International Studies (China) and the EU Center (Singapore). For more, see https://www.differencegroup.net/  

The original commentary was published by The Manila Times on March 20, 2018.

Everything Changes, Nothing Changes

Financial trading stock concept with businessman touching global network and data exchange to check worldwide market stock over cityscape night view

By Graham Vanbergen

Just by looking at the everyday scenario across today’s industries, one can deduce how globalisation quite significantly changed things over the years. And, with the immense potential of globalisation in disrupting the status quo, we are presently confronted with the question “what lies ahead for us all in the next ten years”?

In my article, “The duel between big tech and big government,” I pointed out that the world was a very different place just five years ago. People were not discussing how big data would be the number one traded commodity in the world, that artificial intelligence and automation would threaten our way of life or that a small number of transnational corporations would be potentially reshaping global politics.

We have come to believe, mistakenly, that the rules based international order and post Cold-War calm would prevail. Globalisation was the answer – humanity would collaborate and prosper in mutually beneficial trade.

When we look back over the last one hundred years we see dramatic change every twenty years or so and right now, the world is in the middle of its next great change.

Much to our dismay, the opposite is materialising. When we look back over the last one hundred years we see dramatic change every twenty years or so and right now, the world is in the middle of its next great change.

One hundred years ago this March, the First World War was raging in Europe. Germany had realised that their only remaining chance of victory was to defeat the Allies in the “Spring Offensive”. By August over one million American troops joined the counter-offensive and by November the German empire had collapsed. The world declared “never again”. Yet twenty years later in 1938, Europe was on the cusp of being torn apart once again in the bloodiest fight humanity had ever witnessed. Japan was to be the only nation to experience a nuclear attack by America.

Advance another twenty years to 1958, Datsun and Toyota went on sale in the U.S., the computer chip was invented and the first American satellite was launched from Cape Canaveral. The former was a signal of globalisation. The latter instigated profound change to how humanity would manage and reorganise itself.

The same year, the Peace symbol, now used by the Campaign for Nuclear Disarmament was created – twenty years later the world was in the midst of a terrifying Cold War that took humanity to the very brink of destruction.

In 1978, the first computer game, Space Invaders was a craze, Japanese car imports now account for half the U.S. import market and the first ever Cellular Mobile Phone went live. Globalisation is just about to move up a gear.

In 1998, the iMac desktop pc is launched, Google.com the domain name is registered, the European Central Bank is established and Osama Bin Laden makes his first global appearance.  The European Union expands with the entry of Cyprus and Czech Republic, Estonia, Hungary, Latvia, Lithuania, Poland, Romania, Slovakia and Slovenia. Globalisation is in high gear.

In 2007 America had already reached its high point for power and influence, so had the European Union and globalisation was now moving at its highest pace ever. But in 2008, the Lehman Brothers bankruptcy triggered the global financial crash; banks and systemically important institutions were bailed-out at extraordinary taxpayer cost. The illusion that central banks and governments were in control was shattered. Austerity is rolled out as the new financial ideology of the West.

The events of the above lead us to where we are today – half way through radically changing times.

Regionalism, anti-immigration, euro- scepticism and anti-globalisation are the driving forces of an ever growing angry and disgruntled electorate.

In 2018, the core weakness of the EU is now exposed for all to see.  The two former communist bloc countries of Poland and Hungary face the risk of becoming the EU’s first rogue states. Nationalist parties have caused power shifts in half of its member states – mostly those who joined 20 years earlier. Regionalism, anti-immigration, euro- scepticism and anti-globalisation are the driving forces of an ever growing angry and disgruntled electorate. Youth unemployment and inequality are set to divide the generations. The recent Italian elections embody all of the above.

Russia has emerged not as the superpower it once was but as a regional power player with renewed global ambitions and an invigorated confidence to protect its interests beyond its own borders.

China, an economy built on exports and modern economic reform, woos the West and then unexpectedly hands over dictatorial powers to it leader Xi Jinping, effectively resorting back to its historical dictatorial past.

In 2018, the U.S.A. seems to be accepting that it is unable to manage the power it had acquired over previous generations. Its influence is waning; the impending power vacuum it will create will be a dangerous time.

At this moment in time the world is in the midst of huge change defined by the dysfunction of an economic policy that imploded ten years ago. This moment has already recorded the slowest post-recession growth ever –  including that of the Great Depression, yet it is a period that is also defined by rampant inequality. Domestic political tension has moved the relative calm of social democracy just a decade ago towards social division and the emergence of hard right politics and extremism.

Gobalisation is decelerating as countries and regions centre their attention domestically, causing geo-political alliances to rapidly change.

Globalisation is decelerating as countries and regions centre their attention domestically, causing geo-political alliances to rapidly change.

Just as the fight for global resources, technical supremacy and political power continues with many geo-political ploys and pitfalls ahead, the fight for domestic control is yet to play out. One thing we can all be sure of, 2028 is going to be a radically different era to the one we have all known.

As we look back, inevitably, everything changes, but somehow nothing changes.

Graham Vanbergen’s business career culminated in a Board position in one of Britain’s largest property portfolio’s, owned by one of the biggest financial institutions in the world. Today he is founder and contributing editor of TruePublica.org.uk and director of the Equity Research Centre that focusses on Britain’s housing crisis.

The Venezuelan “Petro” – Towards a New World Reserve Currency?

By Peter Koenig

As this article goes to print, Globovision TV quotes Venezuelan President Nicolas Maduro announcing the launch of a new cryptocurrency, the “Petro Oro”. It will be backed by precious metals. The launch of the new cryptomoney is scheduled for the next week. No details of quantities offered for sale are available at this point.


“I do not want to rush things, but we have a surprise regarding the petro and the gold, which will have the same dimension as it has been related to oil, but it is the theme of next week,” the President says. The first public offering, the ‘Pre-sale’ of 38.4 million of the oil-backed “Petro” on 20 February, has raised US$ 735 million equivalent which is considered a great success.

Imagine an international currency backed by energy? By a raw material that the entire world needs, not gold – which has hardly any productive use, but whose value is mostly speculative – not hot air like the US dollar. Not fiat money like the US-dollar and the Euro largely made by private banks without any economic substance whatsoever, and which are coercive. But a currency based on the very source for economic output – energy.

The Petro is a largely government controlled blockchain currency, totally outside the reach of the US Federal Reserve (FED) and Wall Street.

On February 20, 2018, Venezuela has launched the “Petro” (PTR), a government-made and controlled cryptocurrency, based on Venezuela’s huge petrol reserves of about 301 billion barrels of petrol. The Petro’s value will fluctuate with the market price of petrol, currently around US$61 per barrel of crude. The Petro was essentially created to avoid and circumvent illegal US sanctions, dollar blockades, confiscations of assets abroad, as well as to escape illegal manipulations from Florida of the Bolivarian Republic’s local currency, the Bolívar, via the black-market dollars flooding Venezuela; and, not least, to trade internationally in a non-US-dollar linked currency. The Petro is a largely government controlled blockchain currency, totally outside the reach of the US Federal Reserve (FED) and Wall Street – and it is based on the value of the world’s key energy, hydrocarbons, of which Venezuela has the globe’s largest proven reserves.

In a first batch Venezuela released 100 million Petros, backed by 5.342 billion barrels of crude from the Ayacucho oil fields of Orinoco; a mere 5% of total proven Venezuelan reserves. Of the 100 million, 82.4% will be offered to the market in two stages, an initial private Pre-Sale of 38.4% of so-called non-minable ‘tokens’, followed by a public offering of 44% of the cryptomoney. The remaining 17.6 million are reserved for the government, i.e. the Venezuelan Authority for Cryptomoney and Related Activities, SUPCACVEN.

“Venezuela is the first nation to launch a cryptomoney, entirely backed by her reserves and her natural riches.”

When launching the currency, on 20 February 2018, Vice-president Tareck El Aissami declared, “Today, the Petro was born and we will formally launch the initial pre-sale of the Venezuelan Petro. Venezuela has placed herself in the vanguard of the future. Today is a historic day. Venezuela is the first nation to launch a cryptomoney, entirely backed by her reserves and her natural riches.” President Maduro has later affirmed that his country has already entered contracts with important trading partners and the world’s major blockchain currencies.

Can you imagine what this means? – It sets a new paradigm for international trade, for safe payment systems that cannot be tampered with by the FED, Wall Street, SWIFT, New York courts, and other Washington puppets, like the European Central Bank (ECB), the unelected European Commission (EC) and other EU-associated Brussels institutions. It will allow economic development outside illegal ‘sanctions’. The Petro is a shining light for new found freedom from a hegemonic dollar oppression.

What is valid for Venezuela can be valid for other countries eager to detach from the tyrannical Anglo-Zion financial system. – Imagine, other countries following Venezuela’s example, other energy producers, many if not most of whom would be happy to get out from under the Yankee’s boots of blood dollars inundating the world thanks to uncountable wars and conflicts they finance – and millions of innocent people they help kill.

Rumors have it, that in a last-ditch effort to salvage the faltering dollar, the FED might order the IMF to revert to some kind of a gold standard, blood-stained gold. – Of the 2,300 to 3,400 tons of gold mined every year around the globe, it is estimated that about a quarter to a third is illegally begotten, so called ‘blood’ gold, extracted under the most horrendous conditions of violence, murder, opaque mafia-type living (and dying) conditions, child labor, sexual enslavement of women, many of whom way under-age, abject poisoning of humans with heavy metals, mercury, cyanite, arsenic and more, contamination of surface and underground water ways, vast illegal deforestation of tropical rain forests – and more. That’s the legacy of gold, the MSM, of course, doesn’t talk about.

That’s what the west based its monetary system on until 1971, when Nixon decided to replace gold with the fiat dollar which then became de facto the world’s major reserve currency, albeit declining rapidly over the last twenty years. In desperation, Washington might want to apply another gold-based international norm to salvage the faltering dollar. Of course, a norm designed to favor the US, with the rest of the western and developing world destined to absorb the astronomical US debt.

Since the world’s major goldmining corporation and the illegal gold-digging mafia networks work hand-in-hand, smuggled gold works its way intricately into the dominium of shady traders, many of whom also deal with so-called white gold (drug powder), washing gold and drug-money simultaneously, thereby confounding and obscuring the origins of either. Eventually this illegal gold is purchased by major gold mining or refining corporations mixed with ‘legal’ gold, so that the illegal portion is no longer traceable.

Though not free from socio-environmental damage, petrol-energy may gradually convert into alternative sources of energy, like solar, wind and aquatic power or a combination of all of them.

Therefore, every ounce of gold that would back our money, the purchases of our livelihoods would be smeared in blood, in children’s abuse and death, in murdered and enslaved women and men, in poisoned water ways and in a contaminated environment. But the world wouldn’t go for it. No more. There are healthier and more transparent physical assets to back up international currencies, i.e. the Petro, backed by energy. Though not free from socio-environmental damage, petrol-energy may gradually convert into alternative sources of energy, like solar, wind and aquatic power or a combination of all of them.

What the world is to aim for is a monetary system based on each nation’s or group of nations or societies economic output. Today it’s the other way around – it’s the fiat money, designed by the Anglo-Zionist masters of finance, that defines economies. Thus, economies in our western world are prone to be manipulated by the rulers and their institutions – FED, IMF, World Bank, World Trade Organization (WTO) – that support the debt / interest-based monetary rules – they are purposefully maneuvered into booms and busts. With every bust, more capital is transferred from the bottom to the top, from the poor to an ever-smaller elite. The energy-based Petro is a first step away from this sham.

Imagine the Petro was to become the new OPEC currency! The world would need Petros, as it used to need US dollars to buy hydrocarbon energy. But Petros are blockchain-safe, less vulnerable for manipulation. They are not coercive, they are not made for blackmailing ‘unwilling’ nations into submission; they are not tools for violence. They are instruments of equitable production and trade. They are also instruments of protection from the fiat money abuses.

Source: TeleSUR / http://geab.eu/en/top-10-countries-with-the-worlds-biggest-oil-reserves/

The world’s ten largest hydrocarbon reserve holders have a capital base of 1.4 trillion barrels of crude. Not bad to start a worldwide cryptocurrency, based on energy, controlled by energy and by all those who will use energy – that might become a world reserve currency, at par with the Chinese economy- and gold-backed Yuan, but much safer than the fiat currencies of the US-dollar, Euro, British Pound and Japanese Yen.

The Petro, a secured cryptocurrency based on energy that everybody needs, might become the precursor for an international payment and trading scheme.

We are talking about a seismic paradigm shift. Its potential is unfathomable. The move away from the US-dollar hegemony might result in an implosion of the western monetary structure as we know it. It may stop the predator empire of the United States in its tracks, by simply decimating her economy of fraud, built on military might, exploitation and colonization of the world, on racism, and on a bulldozing scruple-less killing machine. The Petro, a secured cryptocurrency based on energy that everybody needs, might become the precursor for an international payment and trading scheme towards a more balanced and equitable approach to worldwide socioeconomy development.

Featured Image: Venezuelan President Nicolas Maduro’ s post on Twitter with the hashtag with his twitter account @NicolasMaduro

About the Author

koenig-webPeter Koenig is an economist and geopolitical analyst. He is also a former World Bank staff and worked extensively around the world in the fields of environment and water resources. He lectures at universities in the US, Europe and South America. He writes regularly for Global Research; ICH; RT; Sputnik; PressTV; The 21st Century; TeleSUR; The Vineyard of The Saker Blog; and other internet sites. He is the author of Implosion – An Economic Thriller about War, Environmental Destruction and Corporate Greed – fiction based on facts and on 30 years of World Bank experience around the globe. He is also a co-author of The World Order and Revolution! – Essays from the Resistance.

Ensuring Olympic Success – After the Games

South Korea’s 2018 Winter Games was located in Pyeongchang

By Dr. Dan Steinbock

As Olympic torch is moving toward emerging economies, it is time to come up with innovative solutions and appropriate cost controls to finance the games. In this commentary, Dr Steinbock assesses the rising economic costs and cost overruns of Olympic games, outlines the lessons and preconditions for economic success in the future and offers three generic Olympic scenarios that could guide Olympic planning in the foreseeable future. 
To avoid cost overruns, South Korea’s 2018 Winter Games was located in Pyeongchang, the smallest city to host the Olympics since Lillehammer 1994 in Norway. Nevertheless, South Korea is expected to spend $13 billion on the games; nearly double the $7 billion originally projected, which has again ignited public debate about Olympic cost overruns.

In 2022, Beijing will become the first city to host both Winter and Summer Olympics. Can the costs be contained?

Rising economic costs

Hefty price tags and cost overruns have become all too common in Olympic Games.

Hefty price tags and cost overruns have become all too common in Olympic Games. The $15 billion costs of London 2012 Summer Olympics (76% cost overruns) and the $22 billion Sochi Winter Olympics (289% cost overrun) contributed to heavy indebtedness in the pre-Brexit UK and economic erosion in Russia.

In Brazil 2016, costs were projected to be less than $5 billion, yet reportedly more than doubled amid economic, political and security challenges.

Moreover, the Olympic building frenzy has left too many cities with decaying stadiums and empty transit systems, as evidenced by Athens’s dilapidated venues and $11 billion in debt that contributed to the Greek debt crisis; and the recession that swept Nagano, Japan, after the 1998 Winter Olympics.

Nevertheless, there are positive examples as well. In the Los Angeles 1984 Summer Olympics, budget awareness showed that the games can generate actual profit.  Moreover, in summer games, only few hosts – including Beijing in 2008 – have managed to keep cost overruns reasonable. 

In the 2022 Winter Olympics, the estimated budget in Beijing will be $3.9 billion, less than one-tenth of the 2008 Summer Olympics financing. That illustrates the new objectives.

Preconditions for success

Cost control is the first economic precondition for Olympic success.

Cost control is the first economic precondition for Olympic success. In 1984, the L.A. Summer Olympics committee rejected the idea of new sporting structures and focused on modified and upgraded existing venues. Other success stories involve new structures that have been repurposed after the Olympics.

The second precondition is environmental sustainability. In 2014, the International Olympic Committee (IOC) introduced the Olympic Agenda 2020, which promotes sustainability and cost control to control economic and environmental damage. The quest for sustainability requires new competition venues to be built with renewable technologies, as well as energy saving and environmentally-friendly materials.

The third precondition rests on successful media deals to finance the games. In 1984, the L.A. Olympics sought to make the games a global TV event; an objective that was supported not just by Hollywood and the industry mecca, but efforts to sprinkle more than 40 venues throughout almost 500 square kilometers. It was Olympic branding that fostered continuity across very different locations.

Fourth, to promote sports economy, China is rolling out a national campaign to encourage 300 million people to participate in winter sports by 2022. The venues will be distributed in three zones which will foster winter sports in and around Beijing after the Olympics. If successful, this would be an important investment in long-term human capital: “Healthy mind in a healthy body,” as educators put it.

Fifth, Olympics can provide critical “seed funding” to local tourism in need for sustained investment. Even though Brazil’s Olympics suffered from cost overruns, it did attract a record 6.6 million international tourists. To avoid waste of resources, local governments and property developers should consider a sustained focus on local tourism and infrastructure, accommodations and environmental protection.

The final precondition involves a lasting legacy. Under a 1979 agreement, 40 percent of the surplus created in the 1984 L.A. Olympics would stay in Southern California. As the surplus amounted to $233 million, the local share was $93 million. Thanks to the great seed fund for the future, the LA84 Foundation has awarded more than $230 million in grants to youth organizations ever since 1984.

Olympic scenarios for the future

In the future, the probable scenarios for Olympic Games include three basic trajectories. In the Dead-End Scenario, the Olympics will continue as before in which case the historical pattern of soaring costs and cost overruns are likely to contribute to major economic losses, social divides and environmental damage.

In the Cost-Control Scenario, a track-record of successful planning, rigorous cost-control and ability to repurpose the Olympic facilities will play the key role. Despite noble goals, Pyeongchang 2018 failed to achieve such cost-consciousness. Beijing 2022 seeks success in such efforts.

Why not organize the games in multiple cities across borders? If countries seek scale economies through regional trade agreements, why couldn’t they celebrate sports regionally as well?

The Regional Scenario could be an option for smaller emerging economies. Today, Olympics take place in several cities but one country. Why not organize the games in multiple cities across borders? If countries seek scale economies through regional trade agreements, why couldn’t they celebrate sports regionally as well?

It is not the size of the stadium that matters but the audacity of our dreams in our quest for excellence.

About the Author

Dr. Dan Steinbock is the founder of Difference Group and has served as research director at the India, China and America Institute (USA) and visiting fellow at the Shanghai Institutes for International Studies (China) and the EU Center (Singapore). For more, see https://www.differencegroup.net/

The original, slightly shorter commentary was published by China Daily on February 22, 2018

The Philippine Dream Could Be Within the Reach

President Rodrigo Roa Duterte is flanked by lawmakers as he leads the Ceremonial Signing of the 2018 General Appropriations Act (GAA) and Tax Reform Acceleration and Inclusion (TRAIN) in Malacañan Palace on December 19, 2017. ALBERT ALCAIN/PRESIDENTIAL PHOTO

By Dan Steinbock  

If the government’s focus remains on inclusive economic development, the Philippines could become a bright spot in the global landscape.

Today, there is a huge gap between the Philippines as it is portrayed by many international observers and the country’s fundamental economic realities.

The Duterte win was the triumph of ordinary Filipinos. Accordingly, there is only one way for the government to succeed. It must deliver the country’s economic promise.

Unlike its predecessors since 1986, the Duterte administration has potential to do so – unless the year-long efforts at regime change by foreign interests in cooperation with domestic political opposition prove successful.


From fickle finance to long-term jobs and capital

The basic difference between the Aquino and the Duterte administration can be illustrated with their different objectives, as evidenced by IMF data. When the Aquino administration began its rule, portfolio capital inflows increased dramatically, along with other investment and derivatives. However, foreign direct investment flows were in the negative.

Such financial flows and derivatives reflect short-term interests by foreign financial interests. These flows are fickle, can cause dislocations and have little loyalty to markets they seek to exploit.

The contrast could not be greater with the Duterte administration. When it began its rule, foreign investment flows increased but portfolio and other financial investment dived.

Foreign direct investment (FDI) tends to reflect longer-term interest by multinational corporates. It brings jobs and capital and is far less erratic relative to financial flows. It seeks stability.

Initially, the Aquino administration promised to bring FDI into the Philippines, but since it was never able or willing to change the legislation accordingly, foreign capital has remained marginal in the Philippines until recently.

Historically, that amounts to lost opportunity costs over three long decades.


Investment-led infrastructure growth

The Tax Reform for Acceleration and Inclusion (TRAIN) seeks to create a more just, simple and effective system of tax collection. The wealthy will have a bigger contribution and the poor stand to benefit more from the government’s programs and services.

The BRIC-style agenda of the Duterte administration is gaining momentum. The most obvious signals are the ones analysts tend to emphasize. Domestic demand has proved solid. The growth rate of private consumption could remain close to 6% annually. Last year, remittances soared at record $28 billion, thus supporting consumption growth. 

In the foreseeable future, the government’s strong infrastructure push and tax reform plans are likely to maintain momentum. The Tax Reform for Acceleration and Inclusion (TRAIN) seeks to create a more just, simple and effective system of tax collection. The wealthy will have a bigger contribution and the poor stand to benefit more from the government’s programs and services.

Investment growth has potential to stay robust in medium-term, as long as the ”Build, Build, Build” program prevails, especially if the government can raise infrastructure spending to 5% of GDP.

Due to the growth momentum, energy prices and the infrastructure program, inflation could rise up to 4% in 2018. If the inflation trend prevails, which is likely, Bangko Sentral is likely to tighten policy rate from 3.5 to 4.0 by the year-end.

In the current year, the peso could soften from the current 51.40 up to 54.00 relative to the US dollar. However, as the dollar has not appreciated as much as initially expected and as the Chinese yuan has proved stronger than initially expected, the dual impact in Asia could reduce some of the currency pressures.


Toward FDI records, softer external balance

What about foreign direct investment (FDI)? Well, net flows of FDI totaled $7.9 billion from January to October 2017, reflecting confidence in the economy. In the coming years, FDI inflows are expected to rise by magnitude, as they should after three decades of missed opportunities by previous administrations.

In exports growth, the Philippines recently enjoyed a recovery. However, a sustained double-digit increase in imports and decline exports widened the trade deficit to what critics call a “record high” $4 billion in December. Nevertheless, these figures must be seen in the context: What they reflect is the huge infrastructure program, which is bound to increase demand for imports in the foreseeable future – they illustrate an investment in the future, not misguided priorities as often in the past.

Due to import growth, net exports may stay in the negative. Yet, for the full year 2017, total external trade actually grew 9.9%, exceeding the 5.8% growth in 2016. In the longer-term, the Philippines needs to push harder its exports growth. In this quest, it can follow the example of Japan in the postwar era, the newly-industrialized Asian tigers in the late 20th century and China more recently.

External balance will soften, but the critics’ stated fears are inflated. The 19.5%-debt service ratio remains below the international benchmark range of 20% to 25%. The foreign reserves ($81billion) are well above the IMF reserve adequacy metrics and relatively highest in the region. They are ten times bigger than monthly imports and five times bigger than short-term external debt.


From “people last” policies to expansion through inclusion

Due to the steep Philippines income pyramid, growth must be both accelerated and inclusive. In the Aquino years, the top of the pyramid gained, ordinary Filipinos came second. The political net effect was the Duterte election triumph.

Without adequate land reform in the postwar era and with weak job-creation in the past, job opportunities have been inadequate.

Since only a fraction of the population dominates most of the economy, nine Filipinos out of ten hold very little true economic power. Of these, two or three struggle to remain in the fragile middle class, while every fourth or fifth lives in abject poverty.

Without adequate land reform in the postwar era and with weak job-creation in the past, job opportunities have been inadequate. For decades, governments have coped with the challenge by exporting more than 10 million people. If the Philippines is to become a BRIC economy, that has to end. BRIC economies create jobs at home; they do not export them abroad.

Initially, the “people last” policy evolved almost half a century ago, when land reform failed, industrial takeoff was halted, and infrastructure modernization was suspended. As growth became exclusive, job creation began to linger.

The recent government blueprint for appropriate job creation through employment and entrepreneurship from 2017 to 2022 suggests that the administration seeks to overcome the challenge.

Now the strategic objective is to achieve full employment at 5% unemployment rate, which requires the creation of 7.5 million jobs, especially in key employment-generating areas, including manufacturing, food processing, construction, tourism, IT business process sector and retail trade.

The government is in the rich track, yet barriers remain high.


Toward “people first” growth

Brazil enjoyed strong BRIC growth but was also able to reduce the steep gap between the rich and the poor. That, too, is the goal of the Duterte administration.

Internationally, Duterte’s economic objectives are reminiscent of those in Brazil during President Lula’s golden years in the 2000s. In both cases, the highlight is on elevated growth through inclusion. Under his rule, Brazil enjoyed strong BRIC growth but was also able to reduce the steep gap between the rich and the poor. That, too, is the goal of the Duterte administration.

Indeed, in the Philippine economic pyramid, potential output could be far higher than it is today.  Despite the rhetoric of inclusion in the Aquino era, the Philippine labor participation rate has been around 61%. In view of the country stage of economic development, that should be far higher, as in Vietnam (78%), China and Thailand (69%), Indonesia (66%) and even Myanmar (65%).

The current rate is the net effect of decades of “people last” policies – the country’s economic promise remains strong.

Currently, the base case for economic growth is 6.5%-7% in 2018-19. There is structural potential for 7%-7.5%. But to be an upper-middle-income economy toward the end of the Duterte rule, the country’s economic growth must become more inclusive. It must become growth by, growth of and growth for ordinary Filipinos.

Featured Image: President Rodrigo Roa Duterte is flanked by lawmakers as he leads the Ceremonial Signing of the 2018 General Appropriations Act (GAA) and Tax Reform Acceleration and Inclusion (TRAIN) in Malacañan Palace on December 19, 2017. ALBERT ALCAIN/PRESIDENTIAL PHOTO

About the Author

Dr. Dan Steinbock is an internationally recognized strategist of the multipolar world. and the founder of Difference Group. He has served as at the India, China and America Institute (USA) , the Shanghai Institutes for International Studies (China) and the EU Center (Singapore). For more, see https://www.differencegroup.net/ 


The commentary features the highlights of Dr Steinbock’s highly-anticipated economic briefing at the Nordic Chamber of Commerce of the Philippines on January 31, 2018. It was released by The Manila Times on February 12, 2018

EDITOR'S PICK OF THE WEEK

China economic growth

China’s Challenging Search for a New Model of Economic Growth

By Danny Leipziger China cannot continue to rely on exports to drive its growth, but what are the alternatives? China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...

WISE DECISION MAKER GUIDE

POWER INFLUENCERS

Emerging Trends

The Future of Global Trade