Home Blog Page 1067

We Won’t Get Fooled Again…Or Will We?

By Richard Westra

With the suspected chemical attack in the remaining rebel-held suburbs of Damascus on 4 April, it is apparent that the use of chemical weapons is indeed hard to solve. Needless to say, it is during these times that the citizenry needs to know better.


This isn’t happening, is it? Doesn’t anyone remember the British Iraq Dossier plagiarised from a U.S. doctoral student thesis? Or what about then U.S. Secretary of State Colin Powell making a fabricated presentation to the United Nations on the case for illegally attacking Iraq for its purported weapons of mass destruction? Fifteen years later Iraq, once a functioning, relatively well-to-do middle-income economy, is now a 21st century wasteland. Yet, somehow, so-called intelligence at that time dictated it was necessary to attack a sovereign state with a “preemptive strike” to forestall their attack on us.

Well, here we are again. But why now it may be asked? First, the world’s attention has recently been riveted on rogue state Israel unleashing its U.S. supplied military in a turkey shoot of unarmed Palestinian women and children protesting their lockdown in the giant open-air prison known as the Gaza Strip. So, while President Trump was trying to get back to his lost “America First” agenda, proclaiming an exit for U.S. involvement in Syria, guess what? There’s Israeli war mongering Prime Minister Benjamin “Bibi” Netanyahu braying in Trump’s ear, Israel first! And then we have the “Desert Stormy” factor to distract the U.S. domestic mass public from Trump’s alleged peccadillo’s.  

For his part, somewhat ironically, as he has been busy trying to bring France’s powerful unions to heel under the banner of fiscal prudence, French President Emmanuel Macron is now quick to squander the resources of his citizens on firing missiles into the air over Syria.

Let’s not forget British Prime Minister Theresa May. Before one shred of evidence was in, May and her buffoonish Secretary of State Boris Johnson had been hissy-fitting over an alleged deadly nerve agent attack on ex-spy Sergei Skripal and his daughter Yulia by, of course, who else, arch villain Russia. Yet, encumbered by the Brexit fiasco, facing waning popularity at home and, with the Skripal’s now recovering from the alleged diabolical assassination plot showing it up as almost an amateurish gag, why not bomb Syria! 

It seems lost on a world so easily manipulated by mainstream media talking heads that even if, and this really is a big if, chemical weapons were used in Syria several days ago, that the government of Bashar al-Assad is the culprit. Think about it. Finally after over a half decade of death and destruction the motley collection of jihadist groups that had been armed and financed by the U.S and its allies were staging a desperate last stand in Eastern Ghouta.

In fact most groups, except for the international terrorist Nusra Front, had already left. This means that if accounts of chemical weapons usage are to be believed, these were perpetrated either by Assad’s forces on his own people recently liberated from under jihadist truncheons and now seen waving Syrian flags in the streets. That would be nonsensical. Or, such usage would have occurred in the last area controlled by the Nusra Front the fighters of which, instructively, were getting ready to board busses and leave the following day.  

What is not fully grasped by most of us watching this theater of the absurd play out in front of our eyes is that there is actually another war going on in Syria besides that captured under the rubric of a Syrian civil war between Assad and an “opposition” supported by Western powers.

However things don’t stop there. What is not fully grasped by most of us watching this theater of the absurd play out in front of our eyes is that there is actually another war going on in Syria besides that captured under the rubric of a Syrian civil war between Assad and an “opposition” supported by Western powers. Another war of influence among Islamists pitting Saudi Arabian Wahabism and Qatari Salafism which, though largely cut from the same head chopping cloth, is playing out among their state sponsors. Ring a bell? Suddenly, Saudi Arabia and a close group of allies beholden to the Saudis blockade Qatar claiming Qatar is supporting terrorists? You’ve got it. And now that all of their jihadist proxies are dislodged from Damascus suburbs, noise is being picked up on a “deal” being cut to end that blockade. In fact the U.S.-Britain-France axis of destruction seems to be placating the Saudi’s by ratcheting up their arms sales to them and offering support for a Saudi led “Arab force” to step in to take over the occupation of Syrian territory controlled now by the U.S.?   

What is the saddest part of this whole story is that Syria along with Iraq and Libya were all erstwhile Soviet client states that were fiercely secular and imbibed inward focussed economic models. Such regimes resisted the neoliberal wholesale extroverting of dollarised, third world and middle income economies.  

Libya, as is well known, was the wealthiest economy on the African continent under Muammar Gaddafi’s tutelage. The current collapse of Syria’s economy is worse than that suffered by Germany during World War Two. And all of these secular states had been strong supporters of Palestine against Israeli occupation and apartheid.

History is littered with corpses left by their imperial exploits. Ditto France. Even the U.S coming out as a nation required a brutal Civil War where both sides slaughtered hundreds of thousands of “their own people”.

Were the hands of these regimes bloodless? No. Saddam’s brutality against communists and other democratic opposition to satisfy Western oil interests is legendary. But is there really any regime from the U.S. to Israel that can take any moral high ground today? The British..? History is littered with corpses left by their imperial exploits. Ditto France. Even the U.S coming out as a nation required a brutal Civil War where both sides slaughtered hundreds of thousands of “their own people”.   

When will the citizenry of supposed democracies around the world with their ostensibly “free” press ever begin to connect the dots? Or will all just sigh as platitudes and falsities are delivered by their governments justifying but another breach of what remains of international law? If there ever was an episode which illustrated the “manufacturing of consent”, this is the textbook example.

Featured Image: https://telanganatoday.com

About the Author

Richard Westra is Designated Professor in the Graduate School of Law, Nagoya University Japan. His recent books include Socialism in the 21st Century, Unleashing Usury, and Exit from Globalization.

The Future of Bitcoin Governance and Trading

By John Christopher Norwood

Bitcoin exploded into headlines and investment portfolios in 2017, and rightly so. Business Insider reports that the world’s first and largest cryptocurrency today started the year at a value of just under $1,000 and skyrocketed to $14,500 by December 29 – a rise that equates to 1,300%.

This stunning growth has taken financial markets, governments, and the rest of the world by storm. Just five years ago very few could have predicted that Bitcoin will be a household term, in the same way that not a lot of people could have foreseen just how powerfully big data, social media, and artificial intelligence would reshape our world.

The Bitcoin frenzy may have died down a bit, but the cryptocurrency continues to hover at a strong US$8,450 as the overall cryptocurrency market eyes an impressive US$350 billion market cap. However, as amazingly futuristic these numbers and pieces of technology are, this is still – mind-blowingly, excitingly, decidedly – just the beginning.

Varying levels of governance 

Being a relatively new phenomenon, Bitcoin has yet to find a place in the larger established frameworks that govern financial exchanges. This is the same for the hundreds of cryptocurrencies on the market, and governments across the globe are still working to better understand how cryptocurrencies work and how best to regulate their use. The global debate not only revolves around the legality of Bitcoin and other cryptocurrencies, but also on matters such as taxability, regulation, and monitoring of mining activities, among many other vectors for use. Bitcoin prices are known to fluctuate according to different government decisions on their legality, which can vary and change sporadically.

In China, private individuals can hold and trade Bitcoins, but financial firms cannot. Meanwhile, Northern America is one of the friendliest regions for Bitcoin, and is home to 2,442 Bitcoin merchants.

For instance, in countries like Indonesia and Vietnam, it is legal to hold and trade Bitcoin, but illegal to use it as payment for goods and services. In China, private individuals can hold and trade Bitcoins, but financial firms cannot. Meanwhile, Northern America is one of the friendliest regions for Bitcoin, and is home to 2,442 Bitcoin merchants. Although Bitcoin is not officially recognized as legal tender in the US or Canada, they are still very much accepted on financial markets. European countries are also open to Bitcoin, being home to 2,060 Bitcoin merchants.

On the far end of the spectrum, other countries have banned or outlawed Bitcoin altogether. Bolivia has fined and even arrested some individuals over use of the cryptocurrency since 2014, while the Indian central bank has rejected cryptocurrencies in general.

Still others, which form the majority, have no current strong policies to govern Bitcoin use, but will likely begin development for them in the near future. Expect that even more European countries will have stronger stances on Bitcoin use and regulation, while countries like China and Korea will have larger crackdowns on Bitcoin mining.

A growing array of trading opportunities

The continuing debate on cryptocurrencies and their place in the world has not hampered the growth of investment and trading opportunities for Bitcoin. As cryptocurrency markets mature, large-scale institutional investments are expected to bring in more capital and financial products. These will open up opportunities for even more people to cash in on cryptocurrencies outside of Bitcoin exchanges.

One of the ways the market is already doing this is in Bitcoin spreads, which Nadex explains would allow investors to track and profit off of Bitcoin without actually owning them. This works by allowing investors to trade the price of cryptocurrency, which jives well with Bitcoin’s high volatility.

Meanwhile, Bitcoin exchange traded funds (ETFs) are getting more popular as a cheaper way to invest in and trade Bitcoin.

Meanwhile, Bitcoin exchange traded funds (ETFs) are getting more popular as a cheaper way to invest in and trade Bitcoin. Like any other kind of ETF, Bitcoin ETFs are marketable assets that can profit from tracking indices, where stakeholders can have a specific percentage.

Last but not least are Bitcoin stocks, which are smaller companies that invested into Bitcoin that offer dividends to shareholders. These come with risks, but have a looser correlation to Bitcoin price movements than the other Bitcoin-related investments.

In conclusion, there is much and more to be expected from Bitcoin and other cryptocurrencies in terms of investment opportunities and government policy. With billions at stake, it is likely that Bitcoin’s wild journey will get even more exciting.

For further information:

1. Business Insider: http://www.businessinsider.com/bitcoin-price-in-2017-review-2017-12
2. The World Financial Review: http://www.worldfinancialreview.com/?p=26619
3. CCN: https://www.ccn.com/bitcoin-price-surges-5-to-8450-as-cryptocurrency-market-eyes-350-billion/
4. How Much: https://howmuch.net/articles/bitcoin-legality-around-the-world
5. Lifewire: https://www.lifewire.com/where-is-bitcoin-illegal-4156601
6. Nadex: https://www.nadex.com/markets/cryptocurrency/bitcoin

About the Author

John Christopher Norwood is a Florida-based financial advisor and writer with a passion for all things crypto. When he’s not in front of a laptop talking with clients or typing away about the latest in cryptocurrency, John likes playing soccer and hanging out by the beach with his wife and three dogs.

On the Joy of Not being a Listed Company

By David De Cremer

Being a listed company sure is beneficial and puts on an immediate and direct effect on the different aspects of the company. But will these effects stay in the long run or is it just for temporary convenience? In this article, Ren Zhengfei, Huawei’s founder and spiritual leader, talks about how Huawei’s conviction and determination on staying as a private company led it to where it is today.


It is a trend that no one in China can deny: Chinese companies flocking to go public. In 2015, when stock prices were crashing, the Chinese government introduced an embargo on new initial public offerings (IPOS) for a period of four months. Ever since the lifting of this freezing period, IPOS are receiving faster approval to facilitate financial contributions to the Chinese economy. In fact, according to the Wall Street Journal, in 2017, Chinese companies made up about one-fourth of the companies listed across the world. Interestingly, many of these companies decided to go public in the US. Reasons for this are that many Chinese companies do not meet the more stringent Shanghai and Hong Kong listing standards and consider the US to be a much more international market. At the same time, however, many also believe that China is set to continue having positive GDP growth, which is reflected by the increasing number of Chinese companies debuting on the Shanghai and Shenzhen stock exchanges. Important to note in this respect is that when entering the competitive market in China it does help to have a big company behind you. For example, when Chinese Search engine Sogou (SOGO) went public, their debut became a “big thing”, mainly so because heavyweight Tencent owned about 39 percent of the company. One thing that is, however, very clear: the demand for Chinese IPOS is high and has caused somewhat of a herding behaviour – companies keep coming to go public.


Going public as the Holy Grail in China or maybe not?

Being a public company or not, it is imperative that you have motivating leadership and dedicated hard-working employees.

Chinese examples like Tencent and Alibaba are inspiring as they were profitable when they went public. Right now, it is, however, acknowledged that these two companies are outliers and that in contrast, many smaller publicly listed companies have proven to be unprofitable. For example, Chinese education firm “Four Seasons Production” went public at the end of 2017 and immediately suffered a decline in value. This observation is slowly installing the feeling among companies that they do not necessarily have to rush to go public. As an example in case, Ant Financial Services Group has communicated to have no need to go public, despite being backed up by one of the two greats, that is, Alibaba.

This decline for companies to go public is an interesting evolution, particularly since achieving IPO is still seen somewhat regarded as a vaunted prospect. Companies do realise that going public requires intense preparation and, even more importantly, after having gained public status may not always facilitate (but rather complicate) decision-making within the company when it comes down to innovation, vision and purpose. Therefore, populating your company with external shareholders may not be a holy grail after all. In line with this assumption, Vermeulen (2010, p.196), noted, “that the idea that the primary beneficiaries are the company’s shareholders is not a law of nature … it’s a choice.” Indeed, although going public have a number of benefits, it is not a written law that any company should obey to. Shareholders invest money once a company goes public but how to grow for example, in innovative and value-driven ways will nevertheless still depend on your employees. At the end of the day, the same organisational challenge as always stands: being a public company or not, it is imperative that you have motivating leadership and dedicated hard-working employees. As it is acknowledged nowadays that a focus away from your employees to a focus on investors may bring many challenges, it has become clear as well that discussions have come to the fore whether employees should maybe become the primary stakeholder. As a response, some companies take pride in being employee-owned.

In the Chinese market, the most famous company being employee-led is the telecom giant Huawei. This Chinese telecom giant employs more than 170,000 people and serves more than 3 billion customers. In the fiscal year of 2016 Huawei´s revenue reached CNY521.574 billion (US$75.103 billion) and CNY37.052 billion (US$5.335 billion) in net profit. Since its foundation by Ren Zhengfei in 1987 Huawei is and has always been a private company owned largely by its employees (about 98.5%). This employee-owned status has often been looked upon in both stifling as admiring ways by Huawei’s competitors. Despite these conflicting attitudes, so far, their employee-owned status has worked out in very beneficial ways for Huawei. In fact, in its early days, Ren Zhengfei noted during a private meeting that “If we do not go public, we might someday take over the world.” It is Huawei’s conviction that it has gotten where it is today, and has been able to overtake some of its Western counterparts, because it has a long-term vision. The idea is shared within Huawei, that the reason why they have been able to survive beyond, for example, Motorola, Acatel-Lucent, and Nortel, is because they are not a listed company, and as such are not greedy and more willing to persevere. In fact, the company makes 10-year plans, while its competitors struggle to follow near-term fluctuations of the capital market. In their view, the capital market, so to speak, is a cold-blooded and impatient animal.


Distinguishing direct from indirect influence

Of course, very good reasons exist to go public. The major advantage of being listed is that it gives access to money that does not have to be repaid. If your stock jumps by going public, a direct and immediate effect on the company’s performance will be achieved. An important question, however, is whether such immediate financial input effect really makes your company a more vital, resilient and thus a competitive organisation on the longer term?

One of the values that Huawei nowadays focuses on exactly concerns their desire to be a highly vital and dedicated work place (De Cremer, 2017). According to Ren Zhengfei, organisational vitality can be developed and maintained by installing a spiritual work culture. In his view, in such a type of culture, employees are provided freedom of work to demonstrate their entrepreneurial spirit by introducing changes, innovations and projects they would like to pursue. Rewarding this kind of dedication and entrepreneurial success within the company not only allows the company to be able to rely on dedicated and passionate employees but also to innovate in ways that serves the values and long-term perspective of the company. In this process, every employee is treated as a “hero” who can contribute to the long-term survival of the company. Or, as Ren Zhengfei, puts it: “We want engines big and small to drive our team forward.”

The sustainability and growth of Huawei is empowered by an internal force rather than an external one – a force which can make the difference between being a successful private versus listed company, respectively.

All of this makes clear that the sustainability and growth of Huawei is empowered by an internal force rather than an external one – a force which can make the difference between being a successful private versus listed company, respectively. Indeed, as Vermeulen (2010) mentioned when talking about going public as a source of money: “I would say this source comes at a cost” (p. 194). According to Vermeulen this cost includes that the top of the company will have less time to devote to the internal workings of the company and thus be less effective in leading employees in motivating and inspiring ways. He considers this to be an enormous indirect cost.


Not going public requires strong leadership

A consensus exists among management scholars that the tone of the top is extremely important in creating a work culture that can motivate, cultivate, inspire and facilitate innovative and dedicated teams of employees. Those leading the company are usually regarded as role-models and employees at lower levels of the organisation tend to emulate the behaviours and decisions of those at the top. Therefore, if top management turns out to be largely absent – because of an extensive focus on external shareholders – any company will suffer on the longer term. A problem is that such longer-term indirect costs are not observed easily and even more difficult to measure. And, this situation represents a problem in the contemporary business world. Indeed, if you cannot clearly measure something, then it does not exist.

For Huawei the indirect effects as discussed above are one of the main reasons for not being listed. In fact, one of the main responsibilities of Huawei leadership is to promote organisational vitality that encourages employees to work hard in passionate and enthusiastic ways. By not being listed, the focus of leadership is on feeding the vitality of the organisation. They achieve this by ensuring that the energy levels of employees are promoted and channeled in such a way that teams make decisions on the long-term. Such a long-term focus promotes dedication and identification with the important values of the organisation. Not experiencing the stress associated with short-term targets and pressures, it allows employees to focus on working towards the fulfillment of the organisation, which is to make the customer happy. As Ren Zhengfei notes, “Too many “pies” will eat away at the very essence of the organisation, which is the worst form of death for an organism.” If the company remains private and its remuneration is on par with global industry standards, plus yearly dividends, it will not only attract and retain talented people, but also serve to maintain their will to fight on the long-term for the values that Huawei stands for. Up to now, Huawei has struck a successful balance.

Of course, being able to get your employees aligned with such a long-term perspective requires strong leadership. More precisely, it needs a kind of leadership not afraid of sacrificing the immediate influx of external capital to the benefit of having more time at hand to build the right organisational culture. Huawei’s founder and spiritual leader Ren Zhengfei is someone who holds this leadership ambition dear to heart. According to Ren, in order to cultivate teams of spirited young people, senior managers have the responsibility to provide guidance to these young managers. And, this guidance should not simply be a part of their formal contract with the company but go beyond it. Specifically, Huawei urges its senior leadership to take responsibility for the mistakes young managers make and put in effort to correct and re-direct where necessary in active ways. In essence, top executives delegate operating authority to local managers, but they have to keep oversight as they remain responsible. Executives therefore need to be proactive. In other words, these executives need to be able to guide and reinvent people who failed in another job so that they can adapt to the demands of a competitive business setting Huawei operates in. As Ren indicates, “Our managers need to have in-depth understanding of people to fully unleash the potential of each employee.” The ambition should be that all the diamond mines underneath [i.e. the potential of their employees] will be ours.”

It is clear that the choice for not going public invites those in leadership positions to stand up and help improve capabilities of employees during training and practice to help them grow and develop. This kind of leadership is effortful and requires dedication to the development of one’s workforce, but according to Ren Zhengfei, this should be the motivation of every talented manager in the company. As Ren says, “Our outstanding employees have to build their aspirations as world leaders”. As the famous saying in China goes: “When heaven is about to place a great responsibility on a man, it always first frustrates his spirit and will, exhausts his muscles and bones, exposes him to starvation and poverty, harasses him by troubles and setbacks so as to stimulate his spirit, toughen his nature, and enhance its abilities” This should be the motto for leaders at Huawei.


Will Huawei go public?

For Huawei the near future is to develop further spiritual leadership and an intrinsic sense of motivation to remain a vital organisation that survives.

In a speech during a market conference in 2017, Ren mentioned: “There is still a big gap between Huawei and Apple in terms of strategic insights. One reason is that we do not have as much capital of Apple”. As a response, Ren notes further that “a brand is a type of trust that a company’s management team brings to customers, we must gradually improve our capabilities and avoid a rush for quick results.” These statements make clear that Huawei sees most benefit for the growth of the company in further shaping and improving their work culture. For Huawei the near future is to develop further spiritual leadership and an intrinsic sense of motivation to remain a vital organisation that survives (De Cremer, 2017). In the words of Ren Zhengfei: “We [Huawei] need to have the right values, and work hard to create value for society … We need to have the right spiritual pursuits.” In addition, Ren also points out that “but great as American companies are, their American strategists have to succumb to the will of the capital market”, thereby making clear his desire to remain a private company that controls its own faith and strategy on the long term. Therefore, it seems that an initial public offering for Huawei is not about to happen soon.

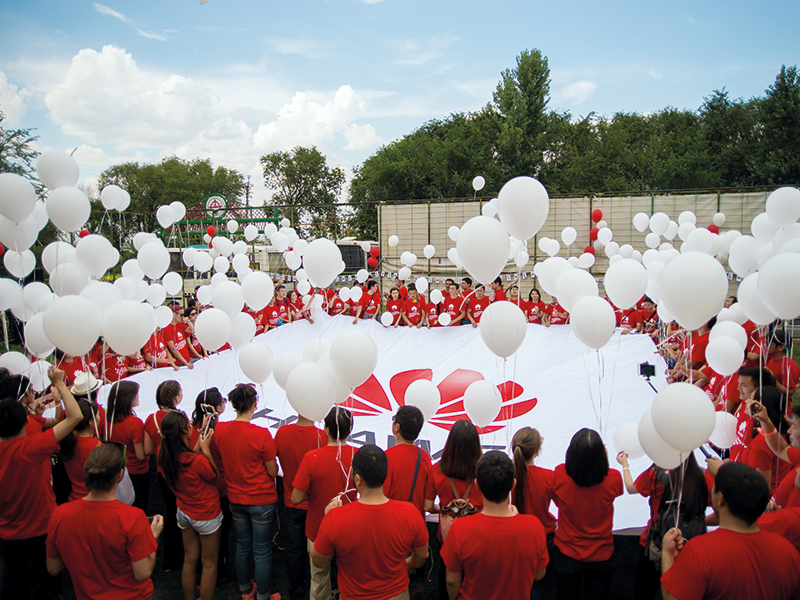
Featured Image: Team building at Huawei Kazakhstan Photo Source: http://www.huawei.com/en/press-events/media-kit/gallery

About the Author

David De Cremer is the KPMG professor of management studies at the Judge Business School, University of Cambridge, UK, a co-founder and co-director of the One Belt One Road research platform at the University of Cambridge and a visiting professor at HSBC Peking University Business School. Before moving to the UK he was a professor of management at China Europe International Business School in Shanghai. He is the author of the book Pro-active Leadership: How to overcome procrastination and be a bold decision-maker and co-author of “Huawei: Leadership, culture and connectivity”.


References

1. De Cremer, D. (2017). Organisational vitality: The life line of your company. The European Business Review, November-December, 44-50.

2. Vermeulen, F. (2010). Business exposed: The naked truth about what really goes on in the world of business. Financial Times Prentice Hall.

Betting Big on CPEC

"the khunjerab pass at china-pakistan border in xinjiang autonomous region, china. click for more:achinaai"

By Xiangming Chen, S.K. Joseph and Hamna Tariq

With the launch of the China-Pakistan Economic Corridor (CPEC), one fundamental question to ask is if this ambitious project will transform Pakistan and boost China’s ambitious Belt and Road Initiative (BRI). In this article, the authors assess the potential and prospect of CPEC in terms of its various opportunities and constraints and examine the economic potentials and social impacts of CPEC from the Pakistani national perspective using a subnational and local lens as well as from the Chinese vantage point and draw the broad implications of this two-sided analysis of CPEC toward a preliminary policy oriented conclusion.


Perched 4,693 metres above sea level in the Karakoram Mountains on Pakistan’s northern border with the southwestern region of Xinjiang, China, Khunjerab Pass, with an international border gate, stands lonely against the stunning snowy mountains around. On the Chinese side, besides an isolated army border control station and few adventurous tourists, the Pass is accompanied by a few scattered yurts and rarely seen white mountain yaks. Yet this place in a remote corner of the world heralds larger looming significance for both China and Pakistan. Its location defines the Pass as the only existing crossroad point for the ambitious China-Pakistan Economic Corridor (CPEC) that both countries have committed to building. While there are relatively few freight lorries running along the highway (G314) leading from Kashgar, China’s westernmost city and closest city to the Pass, CPEC is touted as a difference-maker for boosting Pakistan’s economic development and China’s Belt and Road initiative (BRI). As Pakistan’s Prime Minister Shahid Khaqan Abbasi is quoted in the Long Term Plan (LTP) for China-Pakistan Economic Corridor (2017-2030), “Pakistan-China bilateral ties are time tested; our relationship has attained new heights after the China-Pakistan Economic Corridor that is a game changer for the region and beyond”.1

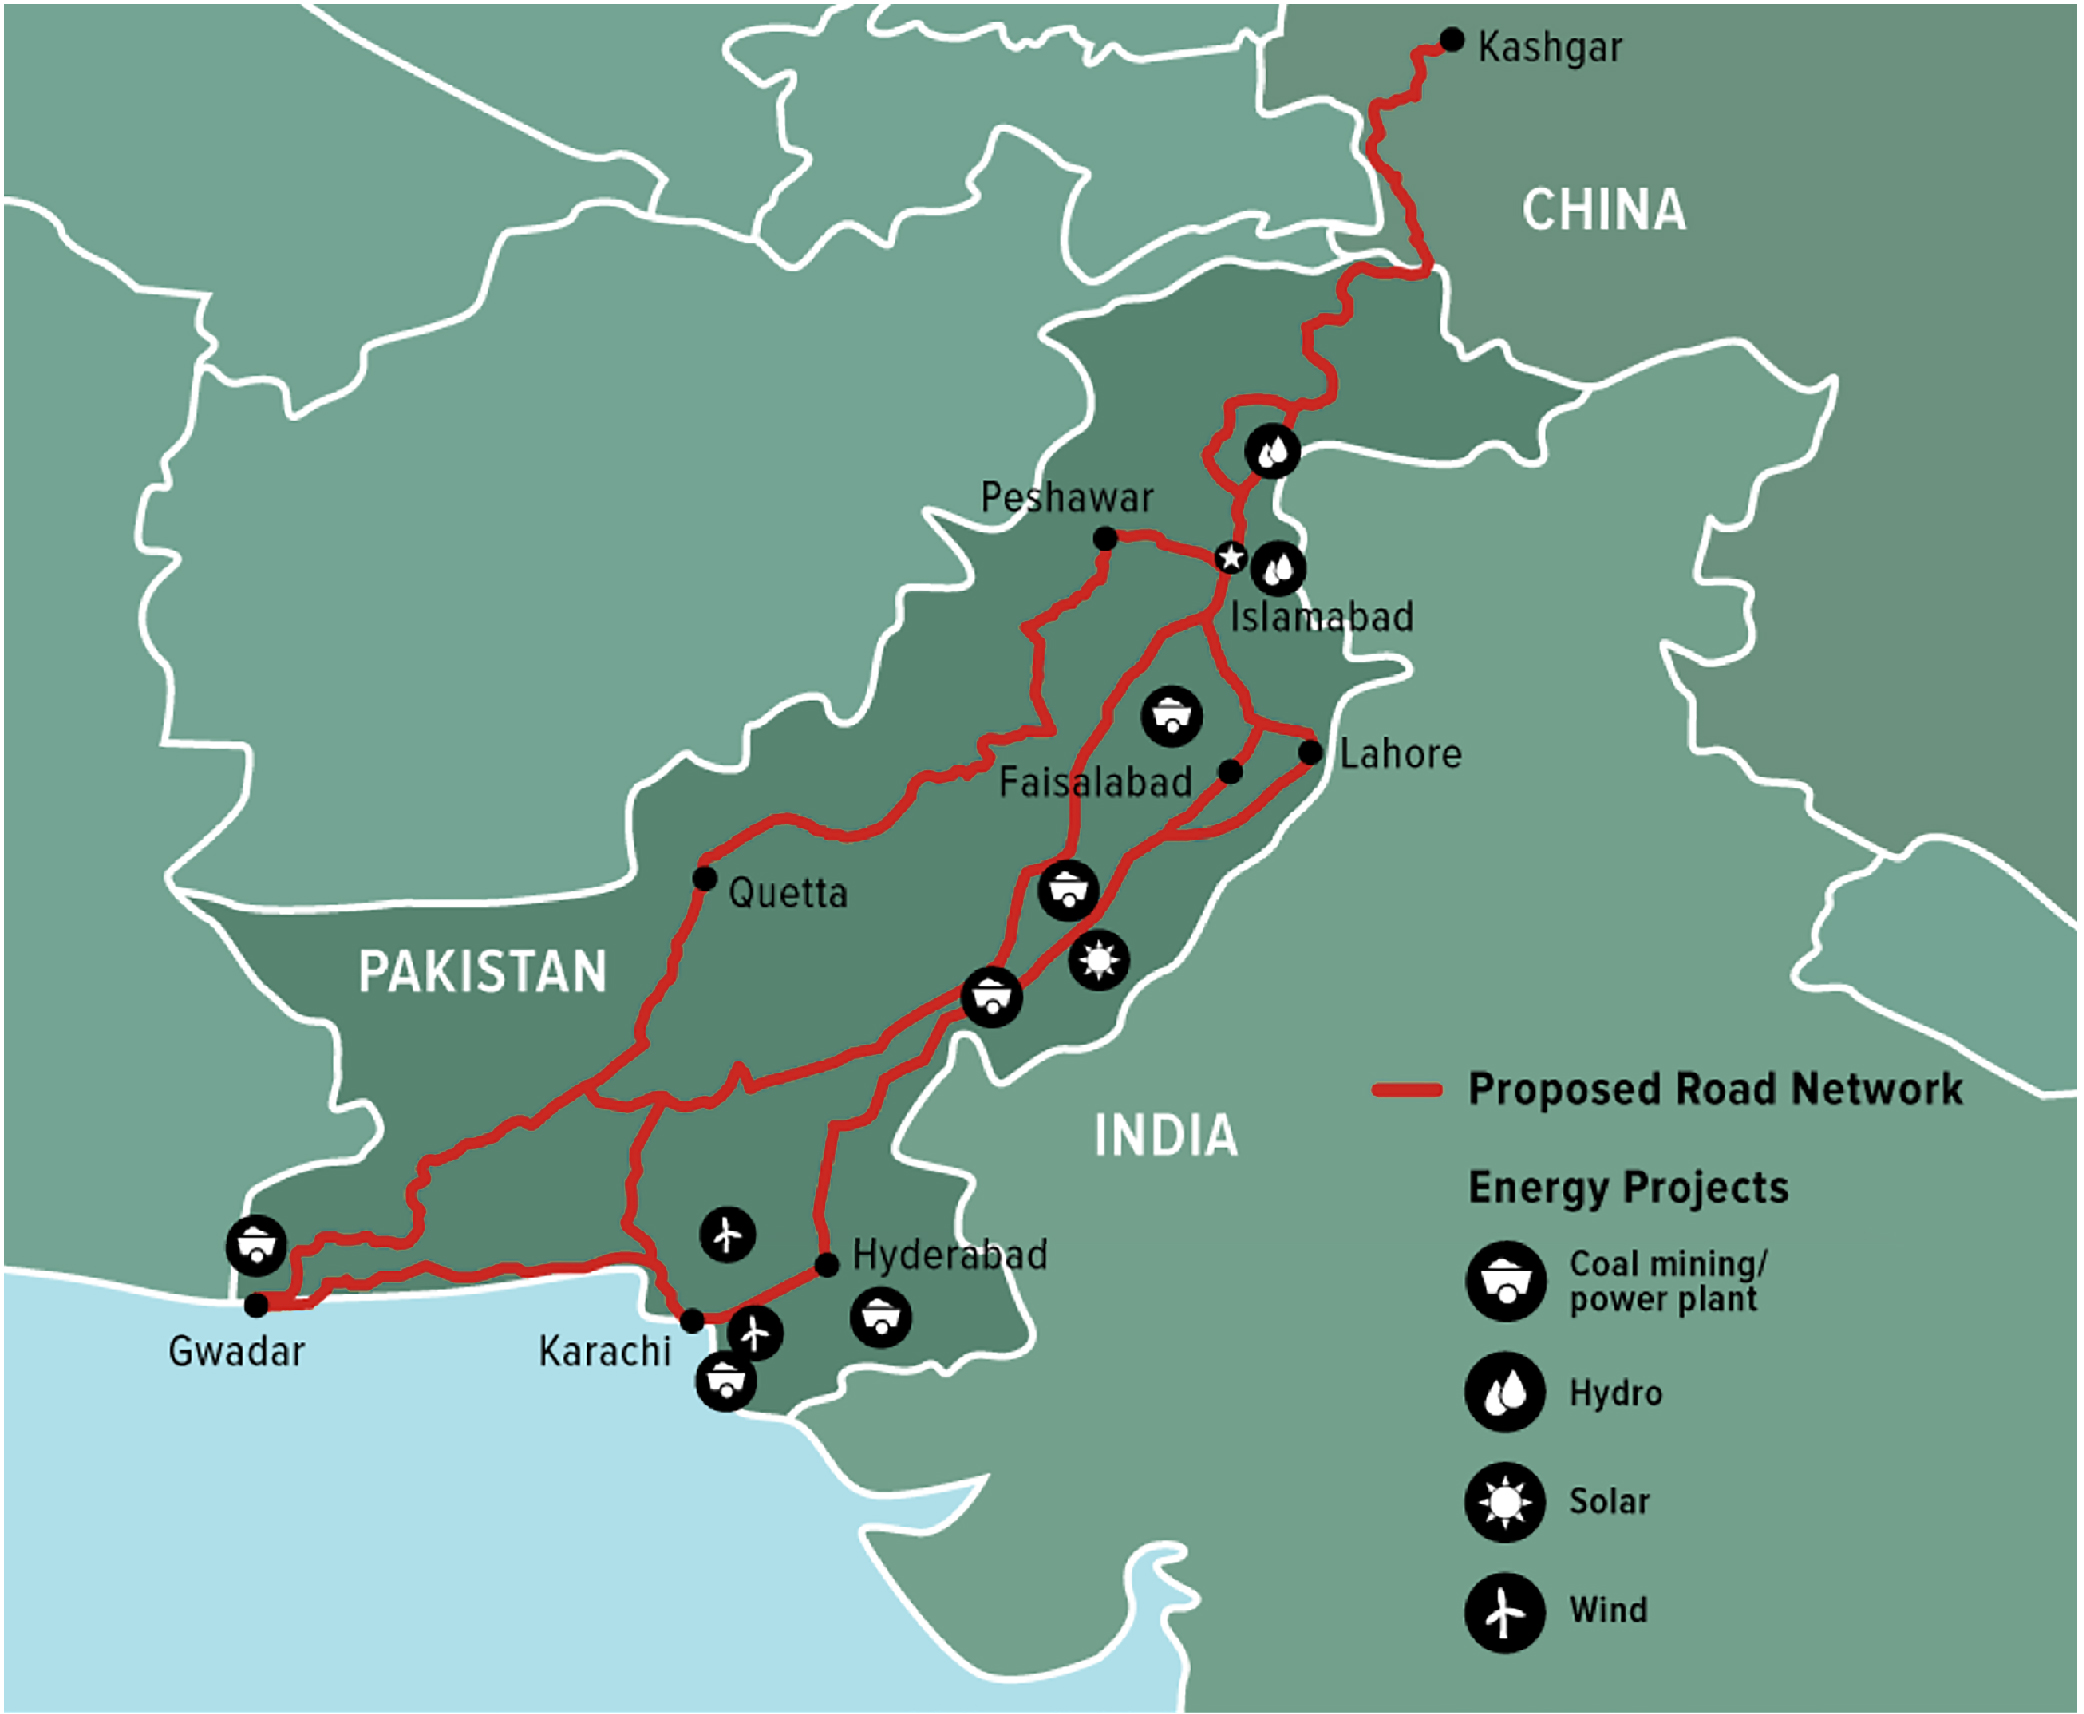
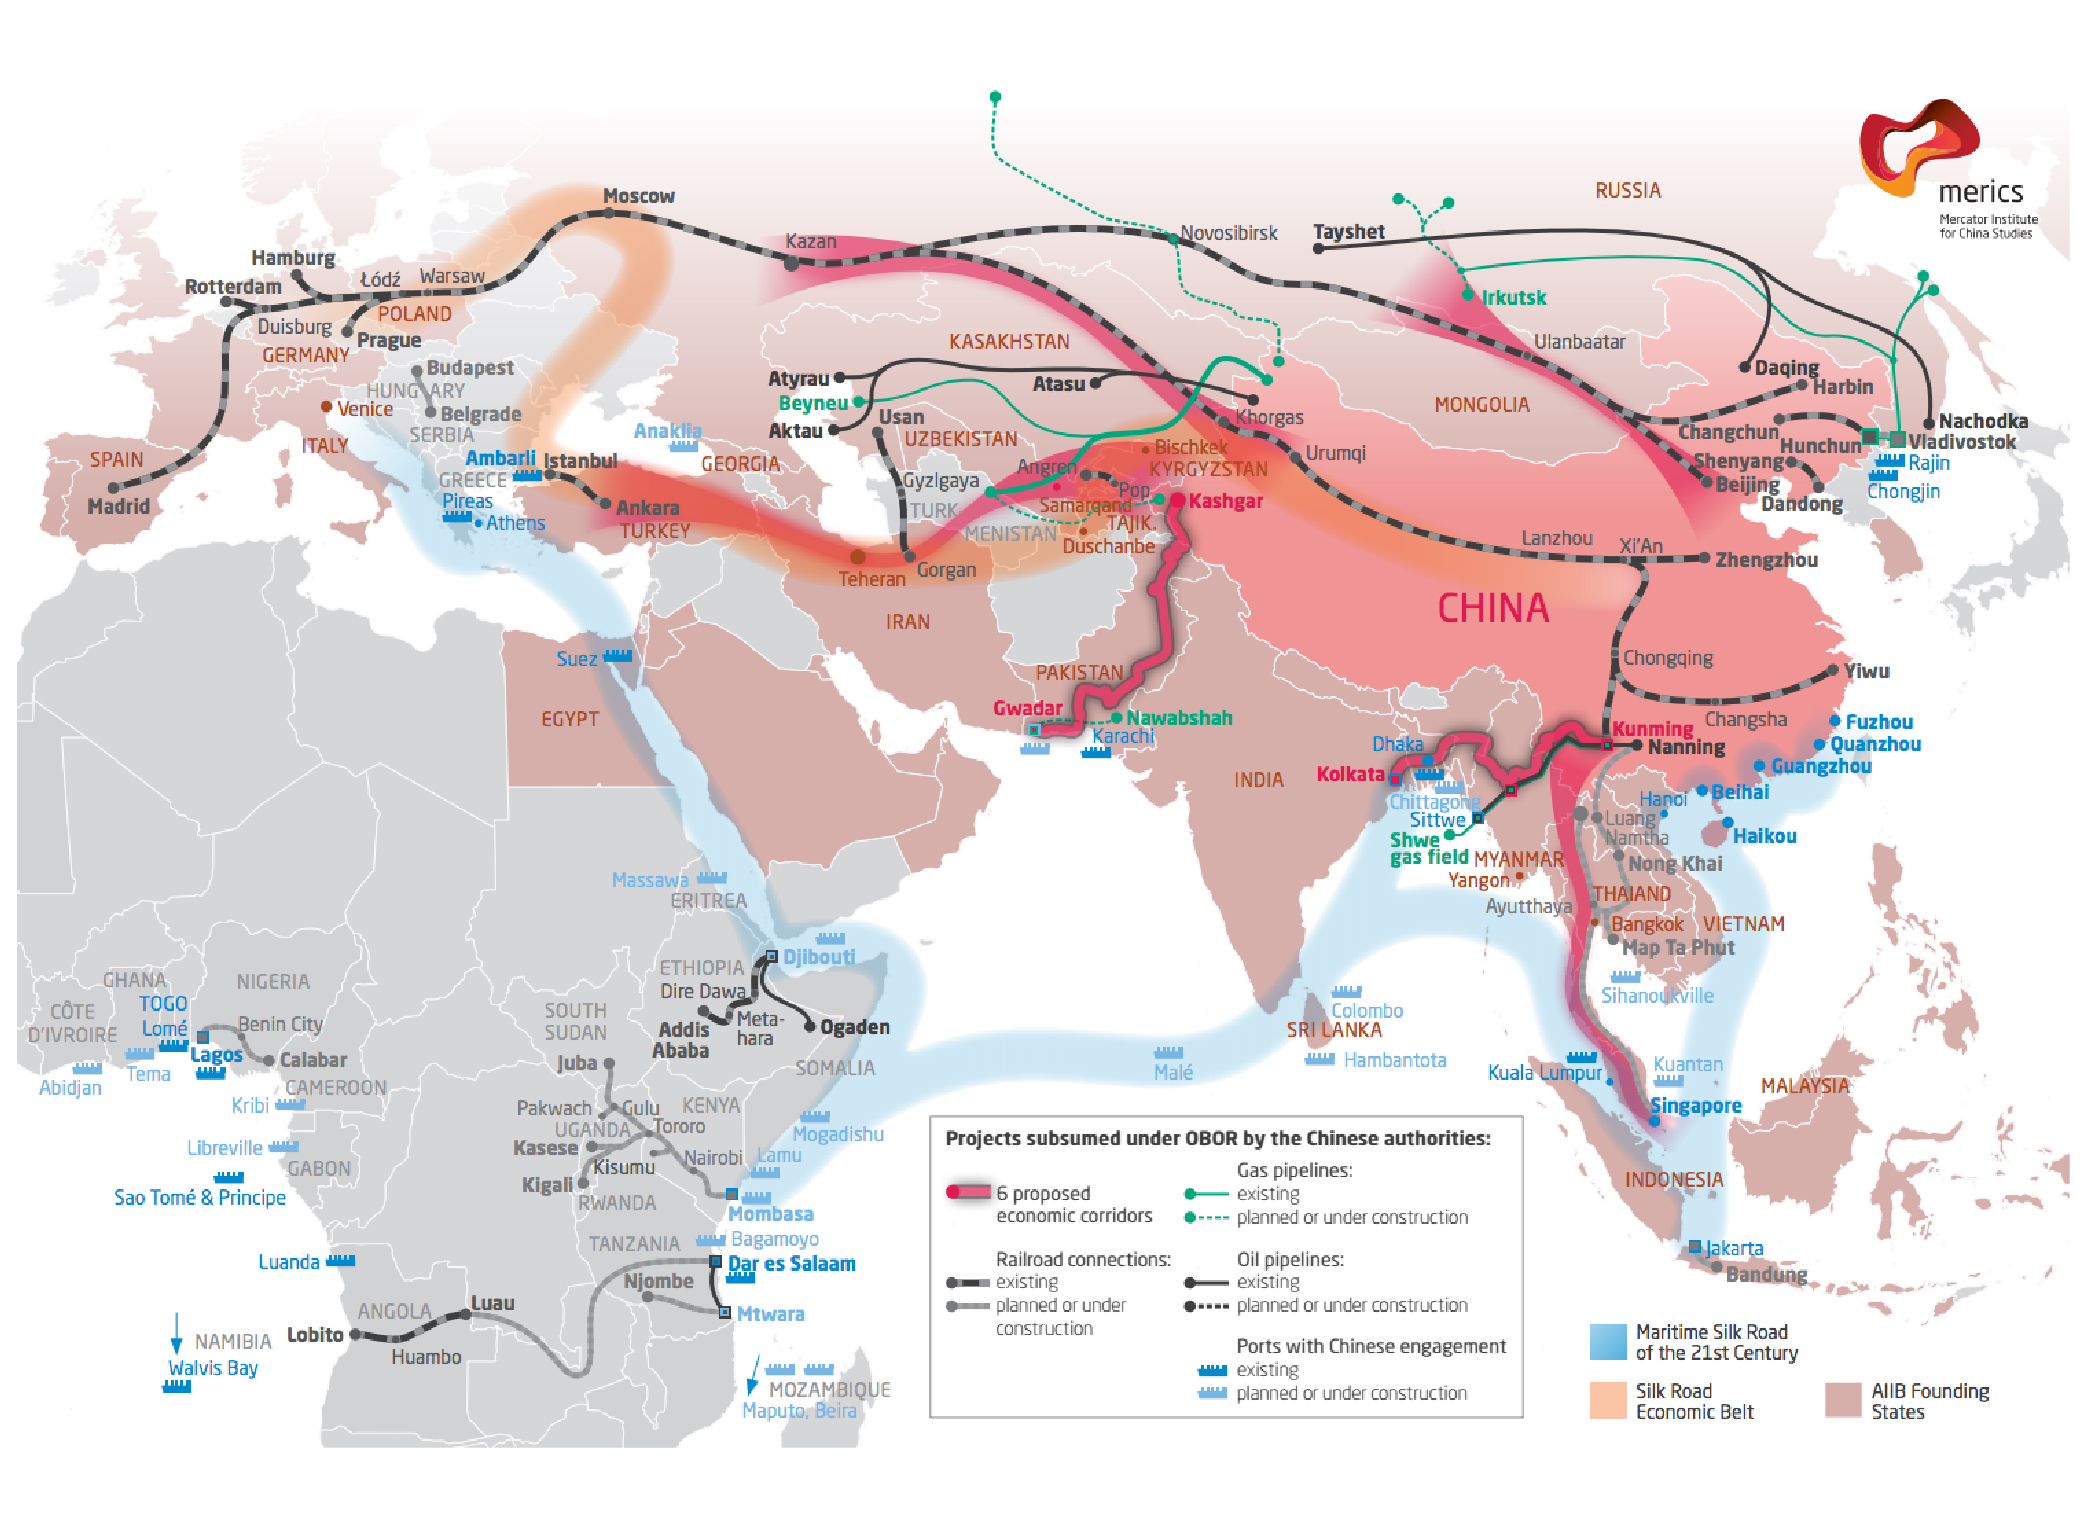
With over $50 billion up from the original $46 billion for infrastructure construction mostly financed by China, CPEC is the single largest capitalised project ever mounted in Pakistan. It comprises the (re)construction of Gwadar port on the Indian Ocean, roads, railways, power stations and other facilities that aim to create sea-land transport connections between Gwadar and Kashgar. This south-north corridor through the length of Pakistan (see Map 1) is capable of stimulating national and regional economic development at a scale and speed not seen before. From Kashgar as China’s terminus of CPEC, this overland corridor will create the shortest access to sea for the country’s northwestern region and thus generating new growth momentum for this vast but lagging region. If successfully implemented, CPEC can serve the crucial overland bridge for linking China’s Belt and Road (see Map 2).

MAP 1: The Proposed $46-Billion China Pakistan Economic Corridor
Source: Wall Street Journal, U.S. Global Investors

MAP 2: The Geographical Scope of the Belt and Road Initiative (BRI) with Six Corridors
Source: Mercator Institute for China Studies, Berlin

Despite its hype for both Pakistan and China, as well as its broader regional and global importance, CPEC is just beginning to attract more attention as an ambitious cross-border project and a salient issue for research, although the latter has not kept pace with the project’s on-the-ground development.

CPEC from Pakistan’s National Perspective

As a result of Xi’s visit, a total of 51 agreements were signed between China and Pakistan having a total worth of $46 billion now over 50 billion which also included the development of CPEC. The originally intended $46 billion investment for CPEC has since been raised to $62 billion.

In April 2015, Chinese President Xi Jinping visited Pakistan. This was the second visit of China’s top leader to Pakistan since the beginning of the 21st century after Hu Jintao’s visit to Pakistan in 2006. During his visit, Xi stated, “this will be my first trip to Pakistan, but I feel as if I am going to visit the home of my own brother”, thus amplifying the friendly relations between both countries.2 As a result of his visit, a total of 51 agreements were signed between China and Pakistan having a total worth of $46 billion which also included the development of CPEC.3  The originally intended $46 billion investment for CPEC has since been raised to over $50 billion. The amount exceeds all foreign direct investment Pakistan has received over the last several years and is considerably more than all the aid Pakistan has received from the US since 9/11.4 This is more than 20% of Pakistan’s 2016 gross domestic product.

This project is basically a collection of infrastructure projects in Pakistan to develop Pakistan’s shattered economy. CPEC includes construction of modern transportation networks, numerous energy projects and creation of special economic zones. CPEC eventually aims at linking Pakistan’s port of Gwadar on the Indian Ocean to China’s landlocked Northwestern region of Xinjiang through a vast network of highways and railways. If this project becomes reality, Pakistan will be having a massive new network of roads, highways, railways and pipelines. The road will cover approximately 3,000 kilometers from Gwadar to Kashgar. The internal motorway is also a part of this project, which will be about 1100 kilometers long stretching from Lahore to Karachi, in addition to the Karakorum highway from Kashgar via Khunjrab Pass to Islamabad (Map 1). This is by far the largest infrastructural project ever mounted in the history of Pakistan. Several projects are already underway and are expected to be completed by as early as 2018, with the short-term plan of CPEC to be completed by 2020, the mid-term by 2025 and long-term by 2030.5


Economic potentials

Pakistan will reap several much needed benefits from CPEC that can and will improve the country’s development. First, CPEC is expected to enhance Pakistan’s employment opportunities along the route. Although thousands of Chinese workers have been assigned to construct the railways, pipelines and roads, most construction workers are locals. CPEC is projected to generate 2,320,000 jobs ultimately reducing Pakistan’s unemployment rate from 5.5% to 3.9%.6 According to Pakistan’s Minister of Planning and Development Ahsan Iqbal, at least 300,000 jobs have been created by CPEC thus far.7 A lot of these jobs will be for building three routes of roads to connect Gwadar to Kashgar, a considerable improvement over the only road now.

Stronger and more expansive transport infrastructure is expected to stimulate faster economic growth through more trade and investment. In fact, after the official launch of CPEC in 2013, Pakistan’s GDP annual growth rose from 4% to 5.5% in 2016. According to an IMF estimate, investment in CPEC will add $3 to $13 billion in output to Pakistan’s GDP through 2024.8 Other external advantages include greater trade through Gwadar port, which will play out its key location for facilitating trade among South Asia, Central Asia and the Middle East.  Pakistan will also benefit from improved energy supply as more China-invested and – built power stations come online. This, in conjunction with more special economic zones (SEZs) being built along the new or enhanced roadways, will allow Pakistan to strengthen its limited manufacturing sector, from assembling parts and components to localised production of parts, and encourage more Chinese companies to build factories in Pakistan as envisioned by the LTP for CPEC.9

CPEC will also improve Pakistan’s tainted international reputation. Tourism which currently makes up a small part of Pakistan’s earnings can benefit. The cross-border region where the road from Kashgar starts is considered to be a mountaineer’s paradise, since it is home to five of the “eight-thousands” (peaks above 8,000 metres), as well as more than 50 mountains over 7,000 metres. It is home to the world’s second highest peak K2 (Mount Godwin-Austen) straddling the China-Pakistan border and the Nanga Parbat, the world’s 9th highest peak in the Gilgit-Baltistan region of Pakistan. Previously, foreign tourists had been hesitant to climb these wondrous peaks, but due to increase securitisation for the Chinese officials and transformative infrastructure construction, this breathtaking region is now deemed safe.10 Local demand for traveling within Pakistan is increasing year on year, with an expected number of 50-plus million domestic tourists forecasted by the Pakistan Tourism Development Corporation (PTDC). CPEC is also expected to stimulate coastal tourism along the development axis between Karachi Port and Gwadar port as the two coastal centers or anchors of CPEC. 

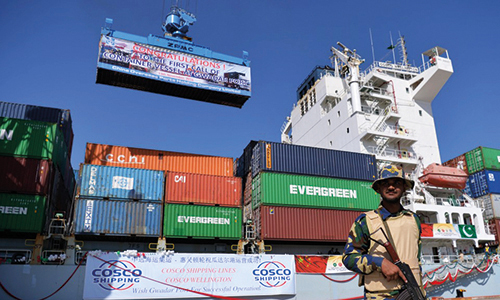
The Pakistani government is betting that faster economic growth and lower unemployment through CPEC can alleviate poverty and thus reduce the threat of terrorism, especially in very poor and restive Baluchistan province. Pakistan has deployed a Special Security Division of 9,000 Pakistan Army soldiers and 6,000 paramilitary forces dedicated to the security of individuals working on CPEC, to prevent Chinese nationals from getting harmed.11 The LTP for CPEC calls for more rigorous safety precautions in the Gwadar region, especially at the port and in Gwadar Free Zone (see Photo 1). The management of Khunjerab Port will also be strengthened with 24-hour video surveillance along the China-Pakistan Highway from the border to Gwadar port.12 These security measures add cost to both the realised and potential economic benefits of CPEC.
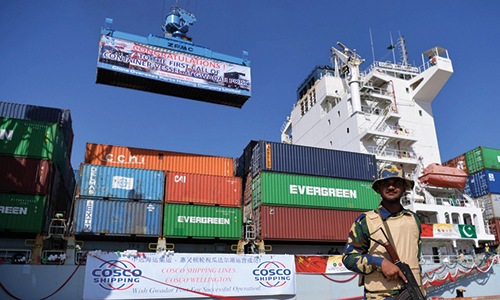
Photo 1: A Pakistani security guard at Gwadar port, in front of a Chinese container ship
Source: http://cpecvela.com/cpec-effects-on-regional-connectivity/


Social impacts

CPEC goes above and beyond its economic influence and has led to unforeseen social impacts that have left many Pakistani residents stunned. Mandarin Centers have cropped up to teach Mandarin to children as young as eight. Schools have realised the extent of Chinese influence on Pakistani Society and have also started teaching Mandarin courses in class.13 Thousands of Chinese have settled not only in Gwadar and remote areas along the infrastructure routes and connections but also in the major cities of Lahore, Islamabad and Karachi. Chinese superstores in Lahore sell spices exclusively imported from China. Lahore even has a traditional Chinese medicine hospital linked to CPEC (see Photo 2).

Photo 2: A traditional Chinese medicine hospital linked to CPEC, Lahore, Pakistan
Source: Photo by Hamna Tariq

Most interestingly, the Pakistani media has attempted to appease a new national audience that has been exposed to growing Chinese influence. Chinese soap operas have replaced popular Turkish ones. The “Shan Masala” ad showing a Chinese woman in Pakistani clothes bringing Biryani to a Pakistani home has appealed to many locals. The Pakistani movie “Chalay Thay Saath” shows a budding romance between a Chinese male visitor to Pakistan and a Pakistani girl. While it may be too early to gauge the full social impact of CPEC, the latter has already triggered direct sociocultural repercussions for Pakistani society despite the wide cultural and religious differences between the two countries.


Turning a Local Lens to CPEC

While the national perspective on CPEC has revealed its large scale and broad impact, we turn to a local lens to shed light on the highly differentiated positions and roles of Pakistani cities in CPEC. Gwadar emerged as the first choice for the starting point of CPEC from southern end of the proposed corridor. A small fishing village on the coast of Makran with underdeveloped paved roads, schools and hospitals, Gwadar relied on exporting limited quantity of seafood caught by small finishing boats.

Since becoming the lynchpin of the CPEC, this small fishing village has been slowly transformed into a growing modern city. Due to the joint efforts of Pakistani and Chinese governments, Gwadar deep sea port has been built at a total cost of $288 million14 and handed over to China Overseas Port Holding Company (COPHC) for operation. It is capable of handling container offload of 300 to 400 million tons annually.15 According to a local businessman, “the construction site was a century old fisherman’s settlement called Mullah Band. The Pakistani government had to pay owners in the area to move out of the area. They were promised a school, hospital and playground but progress has been slow.”16 Over the past ten years, a high school with the playground has been established for students in Gwadar. An emergency hospital had been established under CPEC at a cost of $2.44million.17 Despite positive spillover effects from these investment projects, some local residents complain about not given priority for employment at the port. According to a local laborer, “when CPEC started I was happy that people like me will have lot of opportunities to make a decent living by working at the construction site but China has brought either its own workers or people of Punjab (the most populous province of Pakistan). They are taking away our living.”18

If China and Pakistan want CPEC to be successful, then both countries need to make a serious effort to engage local people in the development process by providing more employment opportunities.

The Baloch National Movement, a regional group advocating autonomy for Baluchistan where Gwadar is located, is against CPEC. Its leaders see CPEC as making the cause of obtaining autonomy even more difficult because a powerful China will be heavily vested in the region. Therefore, if China and Pakistan want CPEC to be successful, then both countries need to make a serious effort to engage local people in the development process by providing more employment opportunities, which leads people to question China’s motives for CPEC.

While a deep sea port has been developed at Gwadar, SEZs have been planned to its northeast, in the province of Sindh. This includes Dhabeji, Thatta where 1000 acres have been set aside for the potential setup of cement, steel, pharmaceutical and chemical plants.19 Due to Dhabeji’s proximity to Karachi and ease of connectivity through M3 motorway to the north and Markran Coastal Highway to Gwadar, Chinese investors have shown a great interest in this SEZ. Many local businessmen in Sindh also are very optimistic about SEZ in Dhabeji because they are hopeful that Sindh will return to its glory days of industrialisation of the 1970s when Karachi and its surround areas thrived with industrial activity. As a local businessman put it, “I am already buying land in Dhebeji to setup a restaurant in the vicinity of the proposed plants because factory workers will buy lunch and dinner between their shifts. I remember in 1970, Karachi and urban areas were lucrative business ventures for us. Lots of foreigners also visited the area for business dealings.”20 CPEC will prove to be a major impetus for generating employment activity in Sindh province because government has signed a memorandum to provide tax holiday to plant owners and incentives on hiring local workers. Local governments in Pakistan are trying to compete for Chinese investment, which has surpassed that from the US. Between 2013 and 2017, Chinese investment in Pakistan amounted to $1.2 billion compared to US investment at $505 million. Relative to Chinese investment’s intention to improve the economic situation of average Pakistanis, many perceive American companies such as Philip Morris and Proctor & Gamble as investing only to enrich their subsidiaries in Pakistan.21

CPEC will prove to be a major impetus for generating employment activity in Sindh province because government has signed a memorandum to provide tax holiday to plant owners and incentive on hiring local workers.

In northern Pakistan, Gilgit is the last major city before CPEC reaching the Chinese border and Kashgar. The most important section of the highway running from Burhan, Hasan Abdal to Kashgar is called Karakoram Highway or KKH with a total length of 887 kilometers. Under CPEC, KKH is going through upgrades including the construction of second lane to facilitate the traffic flow at a cost of $1.26 billion from China’s Import-Export Bank as a low interest loan.22 This has reduced the commuting time from Islamabad to Gilgit from 28 hours to 16 hours. The immediate effects of KKH enhancements are felt as domestic tourism has significantly increased. According to a local businessman, “it is due to CPEC that now we have a reliable highway connected both to the Chinese border and our city. The new road has brought 500,000 Pakistani tourists. I get my shipments from China on time and my customers are happy. I buy Chinese items because they are in demand such as dinner sets, clothes, appliances etc.”23 CPEC has begun to generate some sustainable economic activities in this remote region and lessen its dependence on government’s monetary support.

Another prominent CPEC project is a data cable from Gilgit to Islamabad at a total cost of $44 million.24 The data cable will increase the Internet bandwidth for people in northern Pakistan. It will allow local businessmen to stay in touch with their Chinese counterparts through phone and the Internet. As this area has always been a historic trade route between traders in Xinjiang and Gilgit, enhancing road and communications linkages will further strengthen cross-border trade ties. Similar to the Pakistani government’s effort to secure Gwadar port, the Chinese government has provided funding for security vehicles to patrol the KKH regularly to maintain law and order in the area.25

The locals have mixed feeling about CPEC and its effects on Gilgit. On one hand, the business community is very content that highway improvement makes it easier to trade as cargo can move with less delay; but at the same time, the businesspeople want projects that can and will do even more for economic development. People of Gilgit are happy to see more lorries pass through and drivers stop to buy food and spend money on lodging. In addition, they hope CPEC projects can generate employment on a larger scale. They want to see SEZs like the ones proposed in Sindh and elsewhere in Pakistan. The Pakistani government should take plight of people in Gilgit very seriously because since the independence of Pakistan, this area has remained very underdeveloped. With CPEC, Pakistan has a great opportunity to develop this area and demonstrate its true commitment towards the people of Gilgit. From a geostrategic point of view, developing this area with an increased Chinese business presence will help to deter India’s long-standing claim for Gilgit Baltistan as an Indian territory. It may even create an opening for both India and Pakistan to resolve this territorial dispute and co-exist more peacefully on the Subcontinent.


CPEC from the Chinese Side

As an integral part of the BRI, the implementation and success of CPEC matters a great deal to China and its new stature and role in the global economy, much more than just solidifying an already close relationship with Pakistan.

From the Chinese side to echo Pakistan’s Prime Minister, CPEC represents, in President Xi’s own words, “a strategic decision by our two governments and peoples to build a China-Pakistan community of shared destiny.”26 More strategically, China sees CPEC as the only one of the six corridor-shaped components27 of the BRI that can truly link the overland Belt and maritime Road (see Map 2). The BRI includes over 60 countries, about 65% of the global population and close to 40% of the world’s GDP. Since its launch in 2013, China has invested $60 billion in BRI-related projects and is committed to invest $800 billion over the next five years.28 Enshrined into the Charter of the Chinese Communist Party (CCP) in 2017, the BRI is advanced as heralding China’s new inclusive approach to globalisation by “promoting the connectivity of Asian, European and African continents and their adjacent seas and establishing and strengthening partnerships among the countries along the Belt and Road.”29 As an integral part of the BRI, the implementation and success of CPEC matters a great deal to China and its new stature and role in the global economy, much more than just solidifying an already close relationship with Pakistan.

The strategic significance of CPEC has attracted China’s investment and operational priorities that are compatible with Pakistan’s. Gwadar port again stands out. Moving oil and goods from the Middle East and Eastern Africa through Gwadar to Xinjiang is over 10,000 kilometers shorter than going around to China’s coast by sea. It also avoids sailing through the narrow and vulnerable choke point of the Strait of Malacca. China has pushed very hard to finish the upgrading of Gwadar port, which became operational in November 2016. Moreover, China helped Pakistan to complete the first phase of the construction of Gwadar Free Trade Zone in 2017, a whole year of schedule, and has already sunk $270 million into the project, with the remaining three phases to be completed by 2030 when CPEC is scheduled to wrap up.

Up north, China has been assisting Pakistan to build the Karot Hydropower Dam Project on River Jehlum, a tributary of the Indus River, located in Punjab province. With an installed capacity of 720MW and costing $1.4 billion, the Karot Dam will be Pakistan’s fifth largest and add considerable power supply to Pakistan’s most populous province and beyond. Broken ground at the beginning of 2016, the dam will create over 2000 jobs and be completed in 2020 through built-operate-transfer (BOT). After 30 years of operation, it will be transferred to the Pakistani government. The project has already attracted a $300 million loan from China-led Asia Infrastructure Investment Bank (AIID) and the first ever targeted financing by the Silk Road Fund linked with the BRI.30   Gwadar port and Karot dam exemplify China’s infrastructure-centric approach to working with Pakistan on CPEC.


Kashgar is the key

If Gwadar, Karachi and Gilgit are key Pakistani cities for CPEC as discussed earlier, Kashgar of Xinjiang region, as China’s terminus of CPEC, holds the key to China’s major efforts to make CPEC successful. Kashgar and other western cities began to benefit from growing investment and more favourable policies under China’s “Go West” development initiative launched in 2000. But the BRI and CPEC have accelerated the infusion of domestic resources to Kashgar. In advancing both spatially targeted initiatives, the Chinese government has designated the most wealthy coastal cities of Shenzhen and Shanghai as partners for directly supporting Kashgar’s development. This administrative fiat led the Shenzhen government to give $1.5 billion for building a new campus for the University of Kashgar. Companies from Shenzhen and Shanghai have set up factories in Kashgar’s Economic and Technological Development Zone established in 2010. For example, with government financial incentives and guaranteed orders for army uniforms, a clothing company in Shenzhen has set up a large factory in the zone and sent technical supervisors to train the large number of Uyghur women hired locally (see Photo 3). More recently, the Chinese state elevated an expansive region encompassing the city of Kashgar to a national level SEZ, with the package of special incentives originally granted only to Shenzhen and three other coastal SEZs. This designation is clearly intended to further elevate Kashgar’s crucial status and role in anchoring the Chinese end of CPEC.

Photo 3: A Chinese foreman is supervising Uyghur female workers in a clothing factory set up by a company from Shenzhen, Kashgar, China
Source: Photo by Xiangming Chen

As an ancient Silk Road city, Kashgar is well located to facilitate the success of CPEC as a crucial nexus for the BRI. Its historic bazaar, which served as a central market for the Silk Road for over 2,000 years, received a facelift in November 2017 when the Kashgar government announced that the bazaar would be relocated to the brand new and much more spacious Kashgar Central and Western Asia International Trade Center. An important project for 2018 built by wealthy Zhejiang province, the center will cost $708 million, have 1.35 million square metres of construction space, house over 10,000 vender stalls and create nearly 100,000 jobs for the central market and its various auxiliary facilities.31 Once completed, the new central market will attract more traders from Central and South Asia such as Kazakhstan and Pakistan who have trekked long distances to shop at the old bazaar (see Photo 4). However, cross-border trade between China and Pakistan will continue to be limited by the single-lane road over high mountains through the Khunjerab Pass, which lies several driving hours away from the city of Kashgar itself.    

     Photo 4: Pakistani shoppers at the central bazaar, Kashgar, China
Source: Photo by Changhong Xu


Conclusion

The challenging natural terrain on either side of the Khunjerab Pass forms a formidable barrier to creating a smooth and sustainable long corridor of commerce between Gwadar, Pakistan and Kashgar, China. It also symbolises the equally, if not more, challenging geopolitical obstacles to the success of CPEC. India sees CPEC as a threat as it runs through or by the contested territory in Kashmir that India claims as its own. India is also worried that Pakistan and China use CPEC to counter India in jostling for influence in South Asia and beyond. In response, India has invested $85 million in Iran’s Chabahar port located near the Pakistani border and Gwadar port. Pressuring Pakistan on doing more to contain terrorism and in sympathy with India regarding CEPC, the US government has recently threatened to withdraw its massive aid to Pakistan. In quick and strong response, Pakistan decided to adopt the Chinese yuan (RMB) as an international currency, allowing deals to be done directly between the Pakistani rupee and Chinese yuan. The concern by both India and the US about the potential use of Gwadar port by the Chinese navy could lead to more tension surrounding CPEC.

While some of the external environment may not be favourable to CPEC, the Pakistani government has firmly committed to the project’s economic rationales and goals in spite of recent changes in its top leadership.

While some of the external environment may not be favourable to CPEC, the Pakistani government has firmly committed to the project’s economic rationales and goals in spite of recent changes in its top leadership. As former Prime Minister Shaukat Aziz told CNBC, “When you build a road or a highway through an area where there is none, you create economic activity, you create jobs, secondly new cities come up along that route, thirdly you have industrial estates coming so a lot of job creation takes place.”32 He went on to say, “We have seen over the years that in areas that have grown fast and where economic growth is strong, extremism and terrorism reduces.” This logic may have influenced the decision to choose Gwadar port in and road route through Baluchistan province, whose insurgency movement has threatened political stability and led the Pakistani government to introduce special security to the region. The same rationale has also motivated the Chinese government to channel heavy investment into Kashgar for CPEC (see earlier) to improve the standard of living for the Uyghur population as an economic means of countering its potential receptivity to the influence of extreme Islamic ideology from across the border. It remains to be seen if CPEC can ultimately deliver this big combined economic-political benefit for both sides.

Given the long-term horizon of CPEC stretching toward 2030, it is critical to anticipate the uncertain future of Pakistan serving the large loans from China financing the massive infrastructure projects now and going forward.

Finally, given the long-term horizon of CPEC extending toward 2030, it is critical to anticipate the uncertain future of Pakistan serving the large loans from China financing the massive infrastructure projects now and going forward. According to the Gwadar port revenue sharing and control agreement, China Overseas Ports Holding Company will receive 91% share of the revenue while only 9% will go to Gwadar Port Authority for the next 40 years. Moreover, for the next 20 years Pakistan would have to repay $3.5 billion annually for loans taken under CPEC. CPEC loans may add $14 billion to Pakistan’s total public debt, raising it to $90 billion by June 2019.33 Due to China’s strict loan conditions, Pakistan has recently excluded the $14 billion Diamer-Bhasha dam on the Indus River in Pakistan-occupied Kashmir from CPEC, as this project also appears intrusive to India’s controlled Kashmir. Putting this uncertain or even risky prospect aside, Pakistan is betting big on CPEC as a potentially transformative development project. And China is also betting big on it as the key to implementing the BRI. As both governments work to make CPEC successful, its ultimate impact should be measured by how it can really benefit the communities and people along this lengthy cross-border corridor. 

Featured Image: The Khunjerab Pass at China-Pakistan border. 

Acknowledgements

Field research by Joseph and Tariq in Gilgit, Gwadar, Islamabad, Karachi and Lahore in Pakistan during July 2017 and January 2018 was supported by student research grants from the Thomas Urban China Research and Teaching Endowment and the Luce Foundation LIASE grant respectively through the Center for Urban and Global Studies of Trinity College. Chen’s field visit to Kashgar, Xinjiang, China in August 2017 was supported in part by the Paul Raether Distinguished Research Fund at Trinity College. Some ideas and analyses in this article were presented and discussed at a Mini Symposium on the China-Pakistan Economic Corridor (CPEC) by Joseph and Tariq as part of the Global Vantage Point Series at the Center for Urban and Global Studies of Trinity College on November 28, 2017. We thank Shafqat Hussain, Shafiq Parvez and Chinmay Rayarikar for sharing their interests in and understandings of CPEC.

About the Authors

Xiangming Chen is Dean and Director of the Center for Urban and Global Studies and Paul Raether Distinguished Professor of Global Urban Studies and Sociology at Trinity College, Connecticut. He is also a distinguished guest professor at Fudan University and an adjunct professor in the Graduate School of Shanghai Academy of Social Sciences, Shanghai. His most recent book is Global Cities, Local Streets: Everyday Diversity from New York to Shanghai (with Sharon Zukin and Philip Kasinitz), published by Routledge in 2015 (Chinese edition, 2016; Korean edition, 2017).

S.K. Joseph is currently a senior at Trinity College, Connecticut, majoring in International Relations. He takes an interdisciplinary approach to economic and social development and its effects on the society.

Hamna Tariq is currently a sophomore at Trinity College, Connecticut, majoring in Urban Studies and International Studies. Her research focusses on the political, economic and social impacts of the China-Pakistan Economic Corridor on Pakistan.


References

1. Long Term Plan for China-Pakistan Economic Corridor (2017-2030), Ministry of Planning Development & Reform Government of Pakistan: accessed from www.cpec.gov.pk.

2. Ishaan Tharoor, “What  China  and  Pakistan’s  special  friendship  means,”  The Washington Post,  April 21st 2015: accessed from https://www.washingtonpost.com/news/worldviews/wp/2015/04/21/what-china-and-pakistans-special-friendship-means/?utm_term=.958f0ad4ecf5.  

3. Arushi Kumar, “China pressuring Pakistan on terrorism,” The Diplomat, September 17, 2017: accessed from https://thediplomat.com/2017/09/china-pressuring-pakistan-on-terrorism/.

4. Riaz Ahmed and Hong Mi, “China-Pakistan Economic Corridor and its social implication for Pakistan: How will CPEC boost Pakistan’s infrastructures and overcome the challenges?” Arts and Social Sciences Journal (April 2017),  2: accessed from https://www.omicsonline.org/open-access/chinapakistan-economic-corridor-and-its-social-implication-on-pakistan-how-will-cpec-boost-pakistans-infrastructures-and-overcome-t-2151-6200-1000265.php?aid=88335.

5. Same as Note 1.

6. “CPEC  to   generate  2.32  million  jobs  in  two  years,” The  News,  January  5th  2017:  accessed  from  https://www.thenews.com.pk/print/176948-CPEC-to-generate-232m-jobs-in-two-years-report.

7. Silk Road Rebirth: Writing a New Chapter for the Silk Road (in Chinese), a report by Cushman & Wakefield Greater China, 2018.

8. Same as Note 7.

9. Same as Note 1.

10. “How will CPEC boost Pakistan’s economy,” Deloitte, 2017: accessed from https://www2.deloitte.com/content/dam/Deloitte/pk/Documents/risk/pak-china-eco-corridor-deloittepk-noexp.pdf.

11. Raza Khan, “15,000 troops of Special Security Division to protect CPEC projects, Chinese nationals,” Dawn, August 12th 2016: accessed from https://www.dawn.com/news/1277182

12. Same as Note 1.

13. Shazia Hassan, “How Pakistan is becoming China’s land of opportunity,” Dawn, June 7, 2017: accessed from https://www.dawn.com/news/1337997.

14. Zofeen Ebrahim,“ What’s happening at Pakistan’s Gwadar port,” Chinadialogue, June 2017: accessed from https://www.chinadialogue.net/article/show/ single/en/9869-What-s-happening-at-Pakistan-s-Gwadar-port-.

15. Shahrukh Syed, “Gwadar port to handle 300-400m-ton load of goods annually: Chinese report,” Pakistan Observer: accessed from https://pakobserver.net/gwadar-port-to-handle-300-400m-ton-load-of-goods-annually-chinese-report/.

16. Presentation by Hamna Tariq (see the Acknowledgements section).

17. Benram Baloch,“Hospital under CPEC project inaugurated in Gwadar,” Dawn Newspaper. May 8, 2017: accessed from https://www.dawn.com/news/1331742.

18. From an interview in Gwadar by S.K. Joseph.

19. Salman Siddiqui, “Dhabeji zone attracts investors ahead of inclusion in CPEC,” The Express Tribune, October 13, 2017: accessed from https://tribune.com.pk/story/1529692/dhabeji-zone-attracts-investors-ahead-inclusion-cpec/.

20. An interview by S.K. Joseph.

21. Ismail Dilawar, “China’s Silk Road push in Pakistan edges out U.S. investments,” Bloomberg L.P., April 12, 2017: accessed from https://www.bloomberg.com/news/articles/2017-04-12/china-s-silk-road-push-in-pakistan-edges-out-u-s-investments.

22. National Highway Authority, Ministry of Communications, Government of  Pakistan: accessed from https://www.google.com/maps/d/u/0/viewer?mid=1Ypl-rj2JVeefZ7SgKF9yNHV41zk&ll=30.506664016184775%2C68.9295112290497&z=4.

23. Interview by S.K. Joseph.

24. Kashif Mughal, “CPEC fiber optic cable between Pak-China.” PakChina, May 23, 2016: accessed from http://pakchina.pk/cpec-fiber-optic-cable-between-pak-china/.

25. Same as Note 23.

26. Same as Note 1.

27. The Belt and Road initiative (BRI) is geographically structured along six corridors, and the maritime Silk Road; 1) New Eurasian Land Bridge, running from Western China to Western Russia; 2) China – Mongolia – Russia Corridor, running from Northern China to Eastern Russia; 3) China – Central Asia – West Asia Corridor, running from Western China to Turkey; 4) China –Indochina Peninsula Corridor, running from Southern China to Singapore; 5) China – Pakistan Economic Corridor (CPEC), running from South-Western China to Pakistan; and 6) Bangladesh – China – India – Myanmar Corridor, running from Southern China to India; Maritime Silk Road, running from the Chinese Coast over Singapore and India to the Mediterranean.

28. Same as Note 7.

29. Vision and Actions on Jointly Building Silk Road Economic Belt and 21st-Century Maritime Silk Road, issued by the National Development and Reform Commission, Ministry of Foreign Affairs, and Ministry of Commerce of the People’s Republic of China, March 28, 2015: accessed from http://en.ndrc.gov.cn/newsrelease/201503/t20150330_669367.html.

30. Same as Note 7.

31. Reported by the Kashgar city website, November 14, 2017.

32. “China-Pakistan railroad will help curb extremism,” Jessica Hartogs with former Pakistani PM, Special to CNBC.com, May 18, 2016: access from CNBC.com.

33. “Sri Lanka leases Hambantota Port to China: Is this the beginning of Chinese debt trap in South Asia?” Shelly Mahajan, the South Asia Program at Hudson Institute, January 14, 2018: accessed from http://www.southasiaathudson.org/blog/2018/1/14/sri-lanka-leases-hambantota-port-to-china-is-this-the-beginning-of-chinese-debt-trap-in-south-asia.

The “Secret Code” of Success

Sucess businessman climbing on stair against conrete wall with key hole door ,sunrise scene city skyline outdoor view .

By Ben Laker, Mark Ridley and Ian Mills

What is the greatest formula for high-level success? In this article, the authors highlight the significance of fulfilment, control, resilience, influence and communication in making performance at its best. Armed with this insight, when recruiting in the future, leaders will be far better equipped to investigate the deeper motivations and beliefs that drive the best-of-the-best.

Based on 20,000 hours of comparative analyses across the spectrum of performance and interviews with the world’s most iconic leaders from organisations including Adidas, Cisco, GSK, JP Morgan, Microsoft, Oracle, Steinway & Co. and Vodafone, a recent study from Transform Performance International (LID Publishing, 2017), presents the most rigorous global evaluation of how leaders behave and are driven, which in doing so reveals the “secret code” behind consistent and high-level success.

Insights from this study are fascinating and suggest that five core beliefs are held by all leaders, referred to as Destination Beliefs because many of those interviewed regard their professional (and personal) life as an ever-expanding journey. Whilst they acknowledge the importance of the belief in shaping their mind-sets and behaviours, they point out repeatedly that these core beliefs are aspirational, evolving continuously, and certainly not finite.

But this was not the whole story. It was clear that the Destination Beliefs are necessary components of a leaders’ belief system, but what really separated the top performers from the lower performers was how those beliefs were interpreted and synthesised internally. Put simply, for each Destination Belief the interviewees described attitudes towards the belief which spanned a spectrum.  These were the 10 sub-beliefs, referred to as Journey Beliefs because they demonstrate how we respond to what happens to us on the journey.

High performers are constantly evaluating themselves against a personal progress goal to be the most professional, productive person they can be.

What is most interesting is that the interviewees experience and even wrestle internally with journey beliefs from either and/or both ends of the spectrum. The most successful leaders respond to certain journey beliefs with greater intensity than they do to others. And it is their response to the intensity of the journey belief which then drives a behaviour. Journey Beliefs lay out in front of leaders the path that they will walk through. And whilst much may have been said and written about having the “right kind of attitude”, now, for the first time, it can be measured in a specific population. Here, finally, is a causal chain of five components, a formula for success – The Secret Code.

Fulfilment is the first component. It’s a state of satisfaction that comes from knowing you’ve either achieved, or are on track to shift performance from good, to better, to best. High performers are constantly evaluating themselves against a personal progress goal to be the most professional, productive person they can be. They know the extent to which a potential customer (internal or external) engages with them is a reflection of their personal style of Communication (more on this later), credibility and persuasiveness.


They understand the concept of Control, the second element. They believe in having a plan, and regularly evaluate where they want to be, where they are, and what the gap is. They show a sense of personal accountability for their success or failure. When failure comes (it does even for top performers), they don’t blame the economy, their company, or the marketing department. They embrace it as something they own, because when you own a problem, you can do something to change it. Failure is therefore seen as a temporary setback on the road to inevitable success, where every mile of asphalt, every pothole, every bridge, tollgate, and detour is seen as something you can control.


Resilience comes next. It is connected to Control as it represents your ability to bounce back from setbacks and get back on track. Like Control, Resilience is revealed through taking action. Like a muscle that grows after exercise, or a chunk of coal that gains value after being squeesed under pressure, resilient leaders face whatever the world throws at them, convert the stress to positive energy, and get busy shaping their own destiny. Resilience means being adaptable to change, and showing a “can do” approach when the pressure is on to meet deadlines, advance the sale, win the deal and hit quota. Resilience is a fundamental building block for achieving Influence as a leader.


Influence is the fourth piece in this jigsaw. As a leader, you need to gain influence with others to open doors, get on the calendar, gain stakeholder support, and win business. You also need influence with people in your own company to secure resources, support or the pricing needed to win specific deals. You need influence to plug in to the internal grapevine and know about changes, risks or opportunities before they’re general knowledge. Some people see this type of behaviour as being political – and they’re right. You will always encounter politics on the job. People will always be jockeying to be noticed, gain allies, build a power base, or exert influence over their work environment. It requires extra effort to navigate this, which is why resilience is needed as a foundation. Influence is gained by networking, talking to a lot of people, and using the wisdom of crowds to your advantage so you’re never caught by surprise. When you know in advance what changes are coming, how people feel about them, what they most want, and whose opinion matters most, you can take action faster and more precisely than others. You build a track record of success. You gain partisans and friends in all the right places. This gives you Influence. A key building block to do all this is your ability to communicate.


Communication is the fifth piece of the puzzle. You can never over-communicate with your colleagues or with a customer. Speed and clarity are the keys. Speed is important because today people ingest and send information in person, or by phone, video, email, blog and tweet. If you can’t say it in 200 characters or less, some people switch off. So instead of long meetings, letters or emails every few weeks, try having shorter exchanges every few days. The important thing is to stay front of mind. Clarity is important because there’s so much noise competing for people’s attention, your message needs to be precise and stand out from the static. Try thinking of every communication as a three-part story: you need an attention-grabbing headline, a reason it matters and a call to action. This applies to what you write and what you say. The lesson we took from the interview analysis was clear. High performers think about how they communicate. They recognise that communication is never about one-size-fits-all. In short, they are flexible, chameleon-like. And they are like this because they come from a place where they believe that they have a duty to help others understand, to enable the asking of questions; in short, to generate dialogue.


Let’s summarise:

• The better your communication, the more conversations and ideas you explore with people, and the more opportunities you can uncover to pursue your personal goals for fulfilment.

• The more fulfilled and confident you become, the more gravitas you project, and the more control you exert over your environment.

• The more in-control you are, the easier you evade obstacles. But even when you can’t, you deal with challenges in a way that builds your emotional, mental, or spiritual muscles; your resilience.

• The more resilient you are, the more you choose to act rather than be acted upon; the more people and events you will influence.

• The more influence you gain, the more doors open to connect you with other influencers. You become better informed, hear of opportunities before others, and greatly improve the quality of your communication with others.

• The better your communication, the more conversations and ideas you explore with people, and the more opportunities you can uncover to pursue your personal goals for fulfilment . . . and so on.

How did these Journey Beliefs manifest themselves? In summary, top-performers believe in giving themselves permission to be better than they ever dreamed possible. Low-performers believe that success comes from avoiding failure. Top-performers hold themselves accountable for their success: low-performers are happier to attribute lack of success to factors which they perceive to be outside of their control.  The highest-performing group look for ways to work smarter when facing tough times; the lower-performers talk about working even harder. High achievers know that having influence comes through demonstrating flexibility, not brute force due to position or power. And finally, the top-performing leaders regard communication as an ever-deepening dialogue, whereas lower performers tend to view communication as more transactional and transmission-centric.

The highest-performing group look for ways to work smarter when facing tough times; the lower-performers talk about working even harder.

As you can see, the Secret Code is a self-actualising, self-supporting cycle of behaviour and beliefs. The implications for leaders are huge. Let’s liken their performance to the body of a racing car. We see the shape, the style and color, assembled and ready to hit the road. A person’s education and skills might be likened to fuel in the tank; the more they have, the further they’ll go. Their needs, ambition and hunger might be likened to spark plugs that ignite the fuel to create combustion to drive the wheels. Within this analogy, where do  belief systems fit in? They’re at the driver’s feet: the accelerator and brake. It doesn’t matter how suited to any role a psychometric assessment says a person is, if deeply-held beliefs make them drive with the brakes on.  

About the Authors

Dr Ben Laker (@drbenlaker) is Professor of Leadership and Director of Impact and Global Engagement at Henley Business School, University of Reading and Visiting Fellow at Birkbeck, University of London. He is often asked to attend United States House Select Committee hearings that supply public policy recommendations to the United States Congress and the Biden-Harris administration. In his next public address, at the British Embassy in Helsinki, Benjamin will explore Europe’s energy crisis and examine the implications of windfall taxes on energy companies with lawmakers from around the world.

Mark Ridley is Founding Partner at Transform Performance International. Mark is a driving force behind this highly successful UK-based firm. An inspirational coach and co-author of 100 Big Ideas to Help You Succeed (LID, 2013), he has worked as a strategist, chair and facilitator with global brands, investment houses and academic institutions for over 25 years, in 60 countries, inspiring leadership and coaching talent, growing sales and transforming the way people communicate. He facilitates regularly at major conferences and events worldwide and is an acknowledged expert in sales leadership, emotional intelligence and collaborative excellence.

Ian Mills is Managing Partner at Transform Performance International, Ian is a co-author of 100 Big Ideas to Help You Succeed (LID, 2013) and numerous white papers. He has been a salesperson and led sales organisations in the fast-moving consumer goods, financial and technology sectors. Since 1999 Ian has been a leading light in the building of a globally successful performance improvement consultancy that has delivered solutions in over 60 countries. From Lima in the west to Beijing in the east, he has led behaviour change and transformation projects with corporations such as Hewlett-Packard and Maersk.

Going Beyond the Boundaries: Renta 4 on Discovering the Growth Potential of the MILA Market

A conversation with Mr. Tristán González del Valle Chavarri, Institutional Business Director at Renta 4 Banco and Chairman at Renta 4 Luxembourg

As the dividing line between technology and finance continues to blur, players in the finance industry are challenged to adapt to new realities. In this interview with Mr. Tristán González del Valle Chavarri, Institutional Business Director at Renta 4 Banco and Chairman at Renta 4 Luxembourg, we tackle the challenges facing the finance industry, the investment climate in the MILA Market and Renta 4’s innovative investment strategies and services which are greatly tailored to the needs and requirements of their customers. 


In today’s fast-paced business environment, what do successful directors like you have in mind every single day?
In my opinion today the important thing is to understand the customers better each day and to identify what their needs and expectations are. It is essential that clients feel confident, secure and see that there is transparency. Our job is to provide added value and confidence in the management of the client’s assets.
Specifically in the MILA market, our proposal is to transfer our successful Spanish business model to these countries, adapting it to the social and economic idiosyncrasy that each of them lives.


Specifically in the MILA market, our proposal is to transfer our successful Spanish business model to these countries, adapting it to the social and economic idiosyncrasy that each of them lives.

With your professional career mainly developed in the finance industry, you’re a witness of the drastic changes within this sector. What do you think are those developments that have the greatest impact on the present and future landscape of this industry?
After the 2008 financial crisis, it has become clear that the market has shifted towards greater transparency and risk control. The accessibility of information by clients has to be one of the basic pillars of the industry and all these changes have led to a general decline (which has not yet ended) of the costs for the final customer.


What you stated above proves that the finance industry has indeed evolved. Being the Institutional Business Director at Renta4 Banco, how do you and your team approach the aforementioned developments?
Renta 4 is always very active in terms of training and we have been making a very significant effort in the last six months – training directors and sales representatives about the implications of MFID2 (Markets in Financial Instruments Directive II) and the consequences and effects for the clients.
From the institutional department we have adapted all the documentation material, presentations, etc. so that the investors have maximum access to the information with complete transparency.


Renta 4 Banco is one of the top financial institutions that offer investment products and services. What makes your investment strategies and services unique and first-rate?
When someone gets inside a Renta 4 branch he’s talking only about financial services and products and never about other banking commercial products. Also one of our main goals is to educate our clients and prospects on the financial industry, regulations and other relevant issues.


In relation to your products and services, can you give us a succinct idea about Renta 4 Banco’s investment platforms?
Renta 4 Banco stands out among its competitors for its high in-house technological development in the late 90s. One example of our continuous development is our Fondotop platform, considered one of the best distribution platforms in the market, in which the client can search, analyse, choose, buy and manage the funds that he wants among more than 4,100 funds. In Fondotop the client can find a qualitative and quantitative analysis to build up his portfolio. On the web the client can also find online seminars on funds to be trained, because we believe that customer education is fundamental.


How efficient are your platforms in addressing the investment needs of your retail, institutional and international clients? How do you make sure they have comprehensive investment portfolio/profile?
In our platform clients (retail and HNWI) find updated information on regulations, investor profile, products and analysis. Seventy percent of the income on intermediation from private clients comes from the platform. Institutional clients don’t use the platform.


We launched MILA Fund convinced of the high growth potential of the MILA region for the coming years and the attractiveness for European and South American investors to invest in countries that are showing stability in economic terms and political maturity.

Let’s talk about the MILA Market. In 2016, you launched the MILA Fund. What’s significant about the investment climate of the countries of the Pacific Alliance that you pioneered an investment fund therein?
In Renta 4 Luxembourg we launched this vehicle convinced of the high growth potential of the MILA region for the coming years and the attractiveness for European and also South American investors to invest in countries that are showing stability in economic terms and political maturity. In this way, making our MILA fund available to all investors is a clear sign of our confidence in the region’s integration project. For example, Chile, Colombia, Perú and México have better investment grades by the qualifying agencies than many Eurozone countries.


Since then, what are the significant developments/events that transpired both for your company and the market itself?
Supported by the research local Renta 4 teams in Chile, Peru and Colombia, during these two years we have focussed on positioning the fund in undervalued companies and those with the best future prospects and visibility. We maintain our investment style of investment process (own analysis) and fundamental value.
It has been two complex years for the region due to the involution that has brought about the return of trade protectionism on the part of the United States, and that has impacted the confidence of investors, especially in Mexico. In our experience, this type of setback is only circumstantial and becomes a great opportunity when viewed with more perspective towards the future.
The continuous growth of these markets in the last 10 years is creating an emerging middle class that is consolidating consumption in these countries.


What’s the difference between investing in the MILA market and in the Eurozone?
Markets are increasingly global and the differences tend to be reduced more and more, however, there is still a clear divergence between the perception that investors have of what represent developed and emerging markets. Despite this greater convergence, the view remains that markets like MILA enjoy higher expected returns in exchange for being more exposed to the oscillations of the cycle. The stability of the middle classes and the huge potential of their private consumption represent a big opportunity for companies.
However, we must not forget that the average age of these countries is much lower than that of the countries of the Eurozone and the labour market shows increasing employment rates.


With the increasing complexity of the playing field, how do you make your company resilient? What helps you counterbalance the degree of risk?
Renta 4 is an independent bank, offering exclusively financial services, without risk to the Spanish market and is formed by a network of 61 domestic offices and four international branches in which there are teams of experienced professionals listening to the client and that leads the client to feel safe.
Our investment team (research and fund managers) is highly qualified and experienced – a result of this is the significant number of awards obtained.


To achieve resilience, how do you make sure that your approach toward your customer relations and innovation is holistic?
Without excesses we try to have an as wide and complete range of products as possible. In our Luxembourger range of funds we have classes available for different types of clients (retail or institutional) and in the two main world currencies (euro and dollar). Specifically customers of MILA countries still prefer to have their investments in USD.
We are constantly listening to the needs of our customers in order to tailor made our offer to their requirements.


Do you think there will still be major shifts within the industry in the coming years? In what aspects?
Yes, clearly there would be continuous change. The industry is always subject to move – shifts that may come from regulators, technology or customers. It is clear that these changes should always be based on good understanding but what will be the next one I don’t know, unfortunately I don’t have the crystal ball.
Many believe that at this moment there is an excess of changes due to regulators but I believe that if it is for the benefit of all parties, the industry will always be open to changes for the better.


As Renta 4 already has exposure in various markets, what are your future undertakings/projects?
Our goal is to consolidate the international expansion that started in 2012 and finished last year with the launch of the “Fiduciaria” in Colombia. Our main objective is to integrate the business models of those three countries to become a Regional structure for South America.
Luxembourg has a significant role in the consolidation of these projects. Today we’re a UCITS Man Co1 with different strategies and we plan to develop the Man Co to a “Super Man Co” (UCITS + AIFMD2) to be agile and dynamic in developing alternative strategies for our Institutional South American client.


To those who aspire to succeed in this industry I recommend maximum honesty and transparency, have a strong spirit of flexibility, be curious to try to have total information.

Within the span of your professional career, what are the most significant things you have discovered/learned? What would be your advice for those aspiring to succeed in this industry?
What I have learned in these years is that one cannot remain seated in his achievements, as the world in which we live and work changes more and more quickly. For the one that does not change, does not evolve, quickly the market drop him off.
So first of all my advice to those who aspire to succeed in this industry is that I recommend maximum honesty and transparency, have a strong spirit of flexibility, be curious to try to have total information. It’s “much more important to sleep well than to eat well”.


There could be people out there who are wondering about the status quo of the investment industry, what message do you want to get across to them?
The client has entrusted us to manage their savings. As such my only responsibility to them is to manage risk and not to buy risk.


Thank you, Mr. Gonzalez del Valle Chavarri.

About the Interviewee

Mr. Tristán González del Valle Chavarri is currently the Director of the Institutional Business Development of Renta 4 Banco Group in Spain, Latin America (Chile, Colombia, Perú) and Luxembourg. In the past he has been Partner in Belgravia Capital and had other important experience in Latin America and in Southern Europe (Italy, Portugal). Mr. Gonzalez del Valle speaks fluently English and Italian.

When Technology Meets Finance: An Interview with CFO, Rabobank Asia Niels Boudeling

Finance leaders are aware of the tremendous impact of technological advancements and of the need to improve their business strategies to keep their competitive advantage. In our conversation with Niels Boudeling, CFO at Rabobank Asia, we explored the changing landscape of the finance industry and the impact of digitisation to the roles of CFOs. We also talked about his career journey as well as his pieces of advice for people who aspire to become successful CFOs in the future.

Presently, you are the Chief Financial Officer at Rabobank Asia. Before joining Rabobank Asia, what are the roles you fulfilled in the early stages of your career? 

I started my career as an auditor in Rotterdam, The Netherlands and since then I have always worked in financial roles. Compared to current careers in Finance, I know that my career is more traditional with an increasing level of responsibility over time, leading to a variety of management, senior finance and CFO roles in The Netherlands, Switzerland, Germany, U.K. and now in Hong Kong.

In today’s business climate, the role of CFO is fundamentally changing. At Rabobank Asia, what are the duties/responsibilities you primarily deal with? How has your role changed over the years?

“Due to the more challenging competitive landscape, my role in initiating strategic decision-making has become more important.”

Indeed, today’s business climate is much more challenging than when I started in Hong Kong in 2014. I believe I just experienced the tail end of the golden years for banks in Hong Kong. We are now dealing with a changing competitive environment. This change has also affected my role as CFO. For example, the discussions about business performance have become more intense, managing expectations versus reality. Due to the  more challenging competitive landscape, my role in initiating strategic decision-making has become more important. What type of bank do we want to be? How are we going to make a difference for our Clients? Cost awareness and cost reduction have become even more important than before. At the same time, my task to promote long-term value creation, by stimulating the business to find new opportunities to grow the top line, has not changed.

Could you tell us the present demands of the finance functions that you prioritise and your approach to be effective in it?

I currently prioritise the creation of a truly efficient data flow in our Hong Kong hub. Eventually, this development will be introduced to all of our locations in Asia.  It starts upstream (at the input stage) with a strong emphasis on data quality. Rather than manual adjustments during the reporting process we focus on first-time-right data input. This requires acceptance by colleagues in commercial, operational and risk departments of their role in getting data right and their understanding of the consequences of data errors. An interesting transition!

Straight-through-processing of data, from front office to mid office to back office systems, and ultimately, into a Single Point of Truth (SPOT) is the second important development I am spending a lot of time on. The SPOT contains hundreds of data fields, or attributes as we call them, and contains risk data, customer data and, of course, financial data.
At the downstream end of the data flow, a large variety of reports is currently being automated. We do this by using advanced mapping tables which connect the SPOT with the reporting applications.

The combination of these three steps should enable my team to free up time from low value add activities, like error correction, and use this time for high value add activities such as scenario planning, forecasting and the identification of business opportunities. A clear example that technology is making our jobs in Finance much more exciting!

What are the internal and external challenges you closely monitor to assure the attainment of your financial objectives?

CFOs are nowadays facing a high number of challenges and must have the courage to take unpopular standpoints. Internal conflicts that come to mind are decisions about outsourcing versus automation of activities. Or, should the firm engage in new activities or new products? The right position in every decision within the triangle of risk, returnand efficiency should be meaningfully discussed by the decision-makers. In my view, the CFO has an important role in that discussion.

External challenges lie in the ever-evolving regulatory landscape. With solvency and liquidity requirements increasing, the costs associated with carrying liquid assets are increasing too. This needs fine tuning through the use of optimisation models and continuous maintenance. New regulation on access to current accounts and payments (PSD2) may bring new competitors. And new accounting standards, such as IFRS 9, affect the bottom line.

These new regulations put pressure on our returns and operating model. They also make data availability more important: regulators are considering to get constant access to near real-time data, signalling a shift in monitoring from a more traditional principle-based approach to a rule-based approach.

To address the implications of the convergence of technology and finance, what are the strategic policies, procedures or standard that you think should be put in place?

“Finance and IT cannot operate in silos any longer…This is a prerequisite for optimising our business value and process efficiency. It’s not a stretch to understand the logic of common objectives and KPIs for CFOs and CTOs.”

Finance and technology go hand-in-hand and with the increased interest in good data, the reliance by the finance function on the IT team is more noticeable than ever before. Finance needs the support from IT to ensure that all required data fields are captured in systems and that these systems are set-up in such a way that they enable data quality controls throughout the data flow. Therefore, Finance and IT cannot operate in silos any longer. I see that finance and IT professionals work more and more often in cross functional teams (XFTs). A big advantage of this is that it broadens everybody’s skillset and it stimulates finance professionals to embrace new technologies. This is a prerequisite for optimising our business value and process efficiency. It’s not a stretch to understand the logic of common objectives and KPIs for CFOs and CTOs.

Today’s business environment is indeed increasingly becoming complex due to technological innovations. To add, CFOs are challenged by economic uncertainties and issues on cyberspace, with all these in mind, what is your view on the future of the finance industry?

It is difficult to talk about the future of the finance industry without distinguishing time frames. In the short term, the abundance of liquidity, low interest rates, low commodity prices and increased global competition require banks to continue soul searching: what are we going to do where? Tough choices have already been made, are currently being made and will continue to be made in this time frame. Which attributes constitute a competitive advantage that allows banks to escape the arena of commoditised products where margin pressure requires large volumes to compensate set-up costs?

In the medium term, most commoditised products, like payments, transfers and simple loans will be processed by companies outside the traditional banking industry, some of them Fintech companies, but perhaps the more important competitors for retail banks will be large online retailers which will integrate banking services in their retail value chain.

In the long term the distinguishing factor for banks will be the quality of their advice and the ease of doing business with them (location, network, channel integration). Most products and services will be automated or operated outside the traditional finance industry. In my view banks will become smaller in terms of balance sheet and number of employees, more specialised and more event driven.

Evidently, the industry today is surrounded with risks and a plethora of opportunities, what do you think are the things that present and future CFOs need to explore?

Present and future CFOs have more data available to them than previously. Not only data collected within their own businesses, but also data from competitors, potential clients or best practices from completely different industries. There is a wealth of data to explore. The combination of advanced data analytics and machine learning (A.I.) could give insight in business opportunities. Machine learning could help CFOs to only analyse data pairs for which the correlation actually makes sense. Because at the same time there is a risk that CFOs drown in this sea of data.

For those aspiring to become CFOs, what are the fundamentals associated with such role as well as pieces of advice and realisations that you can share with them?

“Aspiring CFOs should understand that their role will become much more human resources oriented as they will manage a more diverse finance team in the future.”

Aspiring CFOs should have the independence and courage to say no to a business proposition but at the same time aspiring CFOs should have a certain level of entrepreneurship in their DNA that encourages them to take calculated risks and be a critical best friend for their business stakeholders. Aspiring CFOs should also understand that their role will become much more human resources oriented as they will manage a more diverse finance team in the future. The CFO will most likely not be the best accountant and a CPA qualification alone is no guarantee to become CFO. This means that there will be more competition from disciplines outside the Finance domain for the CFO role. In terms of skills, aspiring CFOs should hone their influencing skills. If no action is taken on an otherwise good financial analysis, the finance function has still not accomplished its mission.

There can be a lot of pressure when leading your company towards the attainment of your financial objectives, how do you make sure that you maintain a healthy lifestyle, both in your professional and personal life? What’s your daily grind?

I notice that going to the gym in the morning makes a positive difference for me during the day. I feel more energised and return home with energy left. It only takes me one hour, so I try to do this on Monday, Wednesday and Friday. During the weekend we often explore Hong Kong’s great hiking routes.

Sports help to be fit and at the same time it is important to sharpen the mind to be future-proof. Frequently ask yourself the question: “What have I learned today?”

We all have our own motivations, who/what is the particular person, thing or words of wisdom that keep you going?

What keeps me going is teamwork. I get a lot of energy from a strong team spirit. If there is so much trust within the team that disappointments are overcome without playing the blame game and successes are shared, I am at my best. Therefore team building and team member selection are important for me.

In reference to your career journey, what’s the secret to one’s success in this industry?

“I believe that future CFOs will have experience outside the finance domain. Operations, Risk Management or Treasury are interesting areas for any future CFO.”

There is no golden bullet for success in this industry and eventually you need some luck to be at the right time at the right place with the right background and skills. Nevertheless, I believe that there are several factors that will most likely contribute. First of all I believe it is useful to have experience in different industries, like manufacturing, retail and auditing. It’s interesting to see how the best practices from one industry are very useable in another industry.

Secondly, I would recommend to everybody who has the ambition to become a CFO in a MNC to experience living abroad for a while. It’s a great exercise in flexibility and a good test for your assumptions and prejudices.

Thirdly, I believe that future CFOs will have experience outside the finance domain. Operations, Risk Management or Treasury are interesting areas for any future CFO. I also believe that a good business school will broaden your view and enable you to engage in meaningful discussions about business and strategy.

Finally, what I would recommend to any aspiring CFO is to never stop learning, to have an open mind and the courage to ask the “WHY?” question frequently. Why are we doing this?

 Thank you very much Niels for sharing with us your invaluable insights.

About the Interviewee

Niels Boudeling is CFO Asia for Rabobank, a large cooperative bank with its roots in The Netherlands. Responsible for finance, control and taxation in Hong Kong, Singapore, Mumbai, Shanghai and Jakarta Niels is constantly searching for the right balance between commercial opportunities, risks and efficiency.

Before joining Rabobank, Niels worked at Cartier, MontBlanc, FootLocker and Paxar in the UK, Switzerland and Germany in variety of CFO and Senior Finance Managers roles. He started his career in 1981 as an Auditor for KPMG in the Netherlands.

Niels holds a Master of Science in Accountancy from Nyenrode University, an executive Master in Finance and Control from Maastricht University, an MBA from RSM/Erasmus University and is a Registered Controller.

The QFC, a Platform for Growth in Qatar and Beyond

By Haitham Al-Salama

Looking for top business and investment destinations in the Arab world? Dr. Haitham Al-Salama, Chief Economic Advisor at Qatar Financial Centre (QFC) and Special Advisor to the Minister of Finance, highlights in this article the favourable investment climate of Qatar and how QFC’s platform can help companies in their business expansion endeavours in the region.


Having continually been ranked as one of the top economies globally in competitiveness, communications and innovation, Qatar boasts one of the strongest and fastest growing economies in the region and continues to attract international investors and businesses to its shores.

The well-developed, competitive local market and highly developed value chain supports the needs of investors. Its market strength makes it the ideal location for businesses looking to expand to Qatar, the wider region and other parts of the world, including Africa and Asia.

Backed by a coordinated government strategy and strong investments in key economic enablers such as its infrastructure, Qatar’s GDP continues to grow at substantial rates. This growth was well under way before Qatar won the rights to host the 2022 FIFA World Cup.

The Qatar National Vision 2030 (QNV 2030), a long-term blueprint released in 2008 that envisions a “diversified economy in which the private sector plays a prominent role”, includes a project pipeline worth some $200bn that both local and international companies in various economic sectors can benefit from.

In addition, as a market that is not saturated, but instead continuously growing with abundant opportunities in a number of areas, Qatar’s growing market strength makes it an ideal location for businesses and investors.  

How the QFC can help propel businesses 

The QFC platform is exclusive, offering its own legal, regulatory, tax and business infrastructure, allowing 100% foreign ownership and 100% repatriation of profits and allowing businesses to trade in any currency.

The QFC platform is exclusive, offering its own legal, regulatory, tax and business infrastructure, allowing 100% foreign ownership and 100% repatriation of profits and allowing businesses to trade in any currency.

Our competitive tax regime of 10% corporate tax on locally-sourced profits is unmatched and unlike other financial centres in the region, the QFC does not impose an “end date” on this guarantee. We boast a robust and transparent tax regime, and companies set up under the QFC also benefit from Qatar’s extensive Double Taxation Agreements with over 60 countries.

Our firms also benefit from a regulatory environment that conforms to international best practices and features an independent court with judgments enforced in the State of Qatar, regulatory tribunal and dispute-resolution centre.

We offer businesses the right platform to expand locally, regionally and international and we take care of all logistics so that they can focus on growing their business.


The QFC offers many additional benefits, including:

• 100% foreign ownership

• 100% repatriation of profits

• Trading in any currency

• Quick and easy set up

• Firms can conduct business with any business in Qatar in any currency

• We offer a one-stop-shop for businesses including help with set up, immigration, visas and other

• We also offer access to an independent and transparent legal environment based on English common law and an independent Employment Standards Office

• Access to Qatar’s business community, especially now with our expected move to Msheireb Downtown Doha which will serve as a new financial and business capital for Qatar

• Exemption of taxes when applicable or a competitive 10% tax on locally sourced profits


Utilising the QFC platform

The QFC is preparing for the Qatar 2022 FIFA World Cup™ and beyond by providing the necessary legal, regulatory and financial support to local and international firms that are essential to Qatar’s journey towards economic maturity, diversity and sustainability.

The QFC platform can be utilised to support a variety of services that relate to Qatar hosting the 2022 FIFA World Cup™ including all types of consulting services, legal services, IT services, marketing and brand management services, PR firms, advertising agencies, recruitment firms, accounting/audit firms to name a few.

The best thing about being a global financial and business centre is that we can welcome a wide array of businesses from various sectors to join our platform. It has also allowed us to put Qatar on the map and reiterate the growing business opportunities available.  


How the QFC is adding to Qatar’s diversification goals

Through our offerings we attract a growing volume of businesses from Qatar and across the world; currently the QFC hosts 461 businesses from a diverse range of sectors.

At the QFC, our mission is, and has always been, to drive economic development and diversification. We continue to focus on attracting firms that will serve Qatar’s purpose to diversify its economy, in-line with the Qatar National Vision 2030.

Through our offerings and unique platform, we attract a growing volume of businesses from Qatar and across the world; currently the QFC hosts 461 businesses from a diverse range of sectors. We also successfully enable local companies to expand beyond Qatar and tap into new markets.

We are playing a key part in the QNV 2030 roadmap by helping promote Qatar as a whole, and the vast opportunities there are in this thriving nation. Last year we conducted roadshows across Asia, Europe and the UK and we are seeing a lot of interest from these markets. We are planning more roadshows to continue to show international businesses how they can benefit from Qatar’s multi-billion investment portfolio.

About the Author

Dr. Haitham Al-Salama is Chief Economic Advisor at Qatar Financial Centre and Special Advisor to the Minister of Finance. He has over 15 years experience spanning the fields of healthcare, policy and management within governmental and non-profit organisations. He is a recipient of a number of awards including Oxford University’s Honorary Senior Research Fellowship and the League of Arab States’ 25th Anniversary Distinguished Student Award.

Are Smaller Firms More Export Competitive? A Study of Brazilian Firms

Interior Of Busy Modern Open Plan Office With Staff

By Roque Zin, Paulo Barcellos and Syed Akhter

This article analyses the export performance of Brazilian firms from 2002 to 2010, when the Brazilian currency became stronger.  Firms were classified according to their size (micro, small, midsize and large) and to exports volume in American dollars (USD). The Revealed Comparative Advantage Index (Balassa, 1965) was used to analyse the effects of currency fluctuations on export performance.1 Results indicate that despite unfavourable conditions caused by currency appreciation, smaller firms increased exports volume and improved competitiveness more than large firms.


1. Brazilian exports and exchange rate fluctuations

From 2002 to 2010, Brazilian products became more expensive in foreign markets due to the Real (Brazilian currency) appreciation from approximately USD 0.28 to 0.60.  This was due to global economic developments, changes in Brazilian economic policy, and an increase in the inflow of foreign direct investments.

In 2002, 2,639 export companies were located in RS state representing 13.64% of the total of Brazilian export companies. In 2010, the number of RS export firms dropped to 2,531 or 11.54% of the total. Over the same period, RS state exports increased 139.46%, but that growth was well below the national increase of 234.51%. 

Smaller companies are subject to greater financial restrictions and, therefore, have limited access to capital markets to seek protection mechanisms to mitigate exchange rate effects.

Considering that the number of export companies declined in RS and exports increased at a lower rate than the national average, it could be argued that RS firms lost export competitiveness.  Based on these preliminary data, the question that guided this study was whether competitiveness loss was due to the exchange rate.  Also, has it affected firms of all sizes equally or have smaller (micro, small, midsize) firms experienced greater adverse effects compared to large ones?

Smaller companies are subject to greater financial restrictions and, therefore, have limited access to capital markets to seek protection mechanisms to mitigate exchange rate effects.  Another issue to be considered is the exported product. In general, smaller firms do not export commodities whose quotation is established by the international market, and the price increase may offset the loss of exported volume due to an adverse exchange rate. Having in mind the territorial dimension of Brazil and the large variety of firms, the study was concentrated in RS state, which is not a big commodities producer and even so has representativeness in the country exports volume.

2. Competitiveness, exchange rate and the RCAI

Competitiveness may be defined as the capability of a country, a particular industry sector, or a firm to profitably operate in the global market.  Many conceptual models have been developed to identify factors that are associated with competitive advantages of a firm.  External to the firm, systemic factors can change the competitive environment that alters the competitive advantages of a firm. 

A relation between long-range growth and devalued exchange rates in developing countries was found, reaching to the conclusion that price change due to exchange rate devaluation is of fundamental importance for economic growth.

In examining the role of different external factors, many authors have emphasised the significance of exchange rate fluctuations in influencing companies’ international performance. The exchange rate is the main variable for exports growth due to its favourable impact on competitiveness. One author states that after thirty years he “remains convinced that the exchange rate is one of the chief obstacles to many countries’ growth”.2 A more competitive exchange rate increases demand for exports.3 Favourable exchange rate is a strategic variable for the growth of countries. A relation between long-range growth and devalued exchange rates in developing countries was found, reaching to the conclusion that price change due to exchange rate devaluation is of fundamental importance for economic growth.4

The Revealed Comparative Advantage Index (RCAI) is one of the indicators more commonly used to evaluate the competitiveness of a country’s product in relation to international trade. Based on Ricardo’s law of Comparative Advantages created in 1817, the RCAI is used to evaluate product competitiveness in world markets, regional markets or a specific national market. Comparative advantage is a basic idea for explaining trade relations among countries that are not easily understood. As such, some researchers state that the theory might have been valid two centuries ago but it is irrelevant today.  However, it is concluded that the advantages theory is important to explain international trade, but the concept alone can hardly explain something so broad and complex.5

A study in Italy has shown that comparative advantage may be altered over time. Changes in industrial sectors and in various regions involving the performance of the Italian economy over 30 years were observed. The conclusion was that the comparative advantage of traditional sectors remained, while the performance of sectors which were not competitive some decades ago improved. Some regions also improved their competitiveness indicators.6 Comparative advantage regarding production fragmentation among countries was also analysed. The study concluded that the comparative advantage concept, when used in its original way, loses its explicative power for international trade. However, it is still useful when the global trade flow is considered as disaggregated into a production chain.7


3. Research method

This study refers to the period from 2002 to 2010 when a strong appreciation of the Brazilian currency occurred, followed by a remarkable devaluation. As a matter of fact, the exchange rate increased from USD/R$ 0.2831, in 2002, to 0.6005, in 2010. This change has altered the price relation (USD/Real) of products and affected companies’ competitiveness in the global market. In this study, the RCAI was used to analyse RS firms’ performance vis-à-vis that one of similar Brazilian companies. Based on data supplied by the Foreign Trade Office of the Brazilian Government (SECEX), a database of Brazilian and RS firms’ exports according to company size was created. In accordance with SECEX criteria, the size of a firm is determined by the number of employees and the amount of exports. In instances where a firm can fit into different size categories, it is classified under the greater criterion.8

RCAI uses variables generated a posteriori to measure the participation of the exports of a product in relation to a reference zone of this same product; then, that quotient is compared to total exports of that economy with total exports of the reference zone. RCAI determines the relative competitiveness of a sector in relation to others. RCAI is calculated for RS companies classified by size resulting in their performance vis-à-vis the performance of similar size Brazilian ones.

Most Brazilian firms determine costs in Reals, converted to USD when goods are exported. If the product export price in USD is maintained, the firm will receive a lower amount in Reals for the unit sold. This would mean a competitiveness loss for Brazilian companies and, thereby, a reduction of the exported amount, or a price increase in dollars that would result in a reduction of the exported volume. After exports go down, product profit margins for sold goods may deteriorate, what is observed from 2002 to 2010. However, exports present an increase during that period. From 2002 to 2010, according to Table 1, Large size firms experienced an increase of 150.84%. In general, these firms sell agricultural or mineral commodities, which experienced a price increase in world markets. The price increase offsets the exchange rate disadvantage Brazilian firms then faced.

A fact that deserves attention is the increase of smaller (micro, small, and midsize) firms’ exports. All of them increased sales in world markets despite the expectation that the currency appreciation would result in a loss of competitiveness and, thereby, a decrease in sales. Given the characteristics of RS state, which does not have large mineral reserves and is a grain producer, the question that must be investigated is its performance in relation to the Brazilian one. Having in mind the firms’ size, how was the sales evolution in the international market? 


4. Main findings and questionings

Data analysis shows that smaller (micro, small, and midsize) firms improved their RCAI from 2002 to 2010, while large firms did not, and, still worse, their RCAI kept falling in the period.

From 2002 to 2010, RS large export firms lost competitiveness compared to firms in other size categories. The RCAI for micro firms increased from 1.423, in 2002, to 1.985, in 2010, representing a growth of 39.49%. Small firms presented a growth rate of 75.25%, from a RCAI of 1.062 to 1.748, over the same period. Midsize companies, however, have grown only 19.00% (RCAI from 1.205 to 1.434), while large companies have lost competitiveness in the same period of time. Competitiveness reduction was not significant once the RCAI has shown just a slight decrease of 0.59%, from 0.980 to 0.974.

Data analysis shows that smaller (micro, small, and midsize) firms improved their RCAI from 2002 to 2010, while large firms did not, and, still worse, their RCAI kept falling in the period.    

One of the outcomes of this study is to leave some questions open for future investigations that could shed light on the following research questions: (1) are there structural issues in RS state that influence the growth of smaller firms’ exports notwithstanding the number of smaller export companies’ decrease? or (2) do internal management issues explain their performance? Future studies may investigate smaller firms that have increased their exports to find out whether their performance is due to price changes, new markets, higher productivity, competitive strategies or other factors. 

This study is important for economic and foreign trade policies because smaller firms do not sell commodities and their performance signals that they may be developing some competitive advantages which need to be investigated.  A more detailed study may help these firms to expand their participation in world markets. 

About the Authors

Roque A. Zin is a Faculty member at the Graduate Program in Production Engineering at the University of Caxias do Sul, in Brazil. He also acts as a finance advisor for business firms. 


Paulo F. P. Barcellos is a full Professor at the University of Caxias do Sul Graduate Program in Business Administration. He is the author of the book Coal/Natural Gas: an energy strategy for Mercosur in the 21st century, published in Portuguese. 

Syed H. Akhter is a full Professor and former Department of Marketing Chair at Marquette University, in the USA. He is a Fulbright scholar and is the author of two books: Global Marketing and Strategic Marketing.


References

1. Balassa, B. (1965).Trade and Revealed Comparative Advantage. Washington, D.C.: The World Bank.

2. Thirlwall, A. P. (2011). Balance of Payments Constrained Growth Models: History and Overview, PSL Quarterly Review,64 (259), 307-351.

3. Williamson, J. (2005). The Choice of Exchange Rate Regime: The Relevance of International Experience to China´s Decision, China & World Economy, 13 (3), 17-33.

4. Rodrik, D. (2008). The real exchange rate and economic growth: theory and evidence. Brooking Papers on Economic Activity.In: http://www.brookings.edu/~/media/Files/Programs/ES/BPEA/2008_fall_bpea_papers/2008b_bpea_rodrik.pdf.

5. Deardorff, A. (2005). How Robust is Comparative Advantage? Review of International Economics, 13 (5), 1004–1016.

6. Benedictis, L. (2005). Three Decades of Italian Comparative Advantages. Oxford, UK: Blackwell Publishing.

7. Baldone, S.; Sdogati, F.; Tajoli, L. (2007). On Some Effects of International Fragmentation of Production on Comparative Advantages Trade Flows and the Income of Countries, The World Economy 2007, Oxford, UK.

8. SECEX (2012), Ministério do Desenvolvimento, Indústria e Comércio Exterior, Brazilian Government. In:

• http://www.desenvolvimento.gov.br/sitio/interna/interna.php?area=5HYPERLINK

• “http://www.desenvolvimento.gov.br/sitio/interna/interna.php?area=5&menu=3287&refr=608″&HYPERLINK

• “http://www.desenvolvimento.gov.br/sitio/interna/interna.php?area=5&menu=3287&refr=608″menu=3287HYPERLINK

• “http://www.desenvolvimento.gov.br/sitio/interna/interna.php?area=5&menu=3287&refr=608″&HYPERLINK

• “http://www.desenvolvimento.gov.br/sitio/interna/interna.php?area=5&menu=3287&refr=608″refr=608

Cryptocurrency: Advancing Kazakhstan’s Economy and Investment?

Kazakhstan’s Economy and Investment

By Samantha Brletich

Aimed at developing markets, cryptocurrency, and attracting investment, Kazakhstan created the Astana International Financial Center (AIFC). Such move, however, is not a panacea for Kazakhstan’s feeble investment climate as it has to take institutional and legislative steps – if it is to build greater economic partnerships and diversify its investments.

Kazakhstan has been implementing measures to increase investment including marketing campaigns, reforming laws, market reforms, and engaging with Europe. Oil & gas production and export, mineral deposits and mining, and transportation form the backbone of its economy. Kazakhstan, despite being run by an authoritarian, is fairly open-minded concerning economic agreements and finance. Kazakhstan has managed to operate its mixed economy – characterised by private sector freedoms and state planning – to become the largest economy in Central Asia. Integrating cryptocurrencies further advances Kazakhstan’s efforts to become an innovation hub and top-tier investment partner in the region.

As Kazakhstan continues to promote itself as the land of innovation and as the bridge between Europe and Asia, the adoption of cryptocurrencies, or creation of a state cryptocurrency, has been considered an alternative to attract investment.

As Kazakhstan continues to promote itself as the land of innovation and as the bridge between Europe and Asia, the adoption of cryptocurrencies, or creation of a state cryptocurrency, has been considered an alternative to attract investment.  The government announced in July 2017 for Kazakhstan to become the “the most [favourable] business climate” for cryptocurrency and financial technology (fintech) companies.1  The Astana Times reported on 23 November 2017, that Kazakhstan established a Kazakhstan Blockchain and Cryptocurrency Association (KABC).2 The Association was created to regulate the lucrative cryptocurrency markets and work with the country’s national bank regarding cryptocurrencies.1

Kazakhstan may issue the state- sponsored CryptoTenge, to regulate and integrate into its financial framework and to explore non-extractive industries. The currency would be a fiat currency, recognised as legal tender which is state-controlled. The issuance of the CryptoTenge would make Kazakhstan the first country in Central Asia with its own cryptocurrency and mark significant progress in Kazakhstan’s digital economy, diversifying Kazakhstan’s economy and the use of alternative financial instruments. Kyrgyzstan in June 2014 planned to issue its own cryptocurrency called GoldenRock,3 however as the status of this cryptocurrency is unknown, Kyrgyzstan declared the use of cryptocurrency as a form of payment illegal.4

Kazakhstan created the Astana International Financial Center (AIFC), an innovation hub aimed at developing markets, cryptocurrency, and attracting investment; the AIFC will have its own courts based on Common Law and the language will be English.5 Deloitte highlights that “the Fintech regulatory Sandbox, a special regime for innovative projects within the [AIFC provides] unique advantages for attracting capital to different projects from around the world.”6 Furthermore, deregulation of blockchain technology “enables financial services to be performed not just by established banks but also by specialised start-up companies.”7 

The AIFC signed an innovation pact with Maltese investment firm EXANTE. The working group led by the AIFC and established in July 2017, will regulate the cryptocurrency, establish the ecosystem, and “and [improve] the investment climate in Kazakhstan for development and support of innovative technologies.”8 Kazakhstan will receive EXANTE’s blockchain platform, Stasis, “the platform provides governments with an efficient platform to tokenise fiat currencies and transform them into digital versions on a block chain securely.”9 Stasis, which enables virtual instant payments with no risk of de-evaluation or hyperinflation of digital assets and the mobile application, selling blockchain-based bonds, will bring in investors.10

Cryptocurrency markets present Kazakhstan with the opportunity to become a regional leader in fintech. Cryptocurrencies would allow Kazakhstan to tap into unexplored markets in Asia and build economic relationships with cryptocurrency-friendly countries such as Singapore and Japan. Also the establishment of a cryptocurrency will modernise and make Kazakhstan’s economy more competitive and if successful, lessen the dependence on its extractive industries or make business easier in these industries.

The use of cryptocurrency would promote small and medium business entrepreneurship, because of its low cost and instant transactions, which remains a driver in Kazakhstan’s economic growth. Kazakhstan’s e-commerce sector remains underdeveloped and was projected to reach $5 billion by the end of 2017.11 Online shopping only accounted for 10-12% of all Internet services. 9 Kazakhstan can generate more investment by creating user-friendly cryptocurrency platforms and encourage businesses/merchants to accept cryptocurrency allowing for more cash payments and investment. The tourism, hospitality, and online merchant sectors would benefit from this move because of Western businesses and high-profile global events including the recent EXPO 2017 Astana. Therefore, cryptocurrency may boost non-extractive industries strengthening other sectors of the economy.

Also, cryptocurrency is part of the larger effort of the Kazakhstan Government to create digital economy. The “Digital Kazakhstan Program” was submitted for state approval in early December 2017,12 and focuses on four key initiatives – (1) creating digital silk road to secure infrastructure; (2) developing a creative society and skills to support the digital economy; (3) digital transformation of the economy; (4) and  creating a proactive digital economy which aims to improve electronic and mobile government systems.13 The program is to be implemented in two phases: the first phase was scheduled for 2016-2019 and the second phase is schedule for 2020-2025.14

Cryptocurrency advances Kazakhstan’s multi-vector foreign policy goal of economic development with foreign countries. Kazakhstan is party to the Eurasia Economic Union (EaEU) (also referred to as the EEU), and other multi-national political and economic organisations including the Shanghai Cooperation Organisation. The EaEU has a free trade policy and allows  for workers and goods to move within the common economic space – two areas that Kazakhstan  can improve for investment. Once Kazakhstan’s digital economy is developed, Kazakhstan can influence the economic policies of its powerful neighbors, Russia and China. Once other EaEU countries establish their cryptocurrencies, the EaEU can become a regional cryptocurrency market. In late December 2017, Vladimir Putin was considering creating a common cryptocurrency for the EaEU and the BRICS economic organisations. If Russia proposes a common cryptocurrency, Russia would dominate the EEU and the FSU states in cryptocurrency limiting the regional influence of Kazakhstan.15

By not utilising cryptocurrencies, Kazakhstan would miss multiple opportunities to advance their own digital economy, exploration of blockchain technology, and regional leadership role.

And it is not unrealistic that Kazakhstan would propose a regional cryptocurrency for Central Asia and the Customs Union to create a multi-cryptocurrency common economic market. Kazakhstan’s current regional cooperation with Europe and Asia indicates Kazakhstan seeks a higher position in the international system. Kazakhstan’s and South Korea’s blockchain regulatory bodies, KABC and the Korea Blockchain Industry Promotion Association (KBIPA) respectively, that agreed on cooperation “with Korean companies, known for their innovativeness, provides unique opportunities for Kazakhstan’s business.”16 By not utilising cryptocurrencies, Kazakhstan would miss multiple opportunities to advance their own digital economy, exploration of blockchain technology, and regional leadership role.

KZ Cash is the first regional cryptocurrency in Kazakhstan that was launched by a citizen of Kazakhstan and not by the government.17 KZ Cash became active on 21 October 2017 according to the social media feed.14 The cryptocurrency’s website, lists KZ Cash will be accepted by hotels, restaurants and other companies in the tourism industry to promote growth.18 The payment platform, Smart Pay, also created by a Kazakh citizen, provides merchants, hotels and retailers to offer the option of paying with bitcoin.19 The website cites Kazakhstan’s geographic location along the “Great Silk Road” guaranteeing its success.15 Kazakhstan’s geographic location would also ensure the success of its Crypto Valley, located in Astana, for the country.20 Furthermore, Kazakhstan’s improved investment climate and its developing digital economy would attract technology companies. The Crypto Valley would supplement the already operating Technopark and the Business Incubator, and the Science Park Astana Business Campus at Nazarbayev University opening in 2018.21

Cryptocurrency and the AIFC is not a panacea for the country’s investment woes. Institutional reforms must be undertaken to improve investment. In July 2015, President Nazarbayev declared five presidential reforms to improve investment as part of the “Kazakhstan 100 Steps” modernisation program, supported by the Ministry of Investments and Development: (1) creation of a modern government apparatus, (2) rule of law, (3) industrialisation and economic growth, (4) one shared future, (5) and a transparent and accountable state.22 The Government signed the 2015 New Entrepreneurial Code and new Labour Code to improve investment creating “single windows” for companies and offices where businesses obtain government services.23 Kazakhstan in November 2015, amended legislation on migration and employment to increase worker access; the rules were to take effect in January 2017.24 Kazakhstan also developed a new national investment strategy, supported by the Kazakh Invest National Company, and created a special export strategy embodied by the Kazakh Export National Company.

Foreign ownership and foreign business access to agricultural land, bureaucracy and unevenly applied laws, corruption, fickle legislation without exemptions and grandfather clauses, and government interference contribute to a less-than-ideal investment climate. Improving human rights (including freedom of speech and press) and labour conditions would attract more investment from foreign governments and businesses. It would also improve Kazakhstan’s overall reputation. In March 2015, Kazakhstan implemented constitutional reforms reducing presidential powers and allowing for a possible political transition; however, reforms did not impact Nazarbayev’s powers. Kazakhstan is still considered “not free” by human rights watchdog, Freedom House.25 An improved human rights record would expand Kazakhstan’s role in the UN and other intergovernmental organisations such as the Organisation for Economic Cooperation and Development, which it is seeking membership from.

Kazakhstan’s development of fintech can support new economic partnerships on cryptocurrency and strengthen relations with its Eurasian and Asian partners who are also developing their own digital economies.

With an improved investment climate and a probable cryptocurrency, Kazakhstan can become a modern investment partner. Kazakhstan’s development of fintech can support new economic partnerships on cryptocurrency and strengthen relations with its Eurasian and Asian partners who are also developing their own digital economies. Kazakhstan must balance innovation and democratic reforms with economic state control and regulation. With support of state programs, Kazakhstan strives to maintain their position as the most investor-friendly country in the region. Only after the creation of the CryptoTenge or the introduction of another cryptocurrency in the country, will investors be able to determine if cryptocurrencies’ impact on Kazakhstan’s economy.

About the Author

Samantha Brletich is a freelance writer and researcher on the region of Central Asia and the Former Soviet Union. She focuses on extremism and terrorism, governance, economics, and multi-lateral policy in the region. She has a Master’s in Peace Operations Policy from George Mason University in the United States.

References

1.Haig, Samuel. Kazakhstan Seeks to Become Regional Hub for Cryptocurrency Industry. News, BitCoin.com. https://news.bitcoin.com/kazakhstan – seeks – to – become – regional – hub – for – cryptocurrency – industry/

2.Dyussembekova, Zhazira. Kazakh organisations form Blockchain and Cryptocurrency Association. The Astana Times. https://astanatimes.com/2017/11/kazakh – organisations – form – blockchain – and – cryptocurrency – association/

3. Lyon, Nina. First Country of the Eurasian Economic Union to Issues Its Own Cryptocurrency. CoinIdol.com https://coinidol.com/kyrgyzstan – to – issue – cryptocurrency/

4. Rizzo, Pete. Kyrgyzstan: Bitcoin Payments Violate State Law. CoinDesk. Kyrgyzstan: https://www.coindesk.com/kyrgyzstan – bitcoin – payments – violate – state – law/

5. Astana International Financial Centre. Homepage. http://www.aifc.kz/

6. Deloitte (13 July 2017). Kazakhstan becomes the second government to embrace the cryptocurrency market system. https://www2.deloitte.com/ru/en/pages/about – deloitte/press-releases/2017/kazakhstan-becomes-the-second-government-cryptocurrency-market-system.html, accessed 4 December 2017.

7. Rysaliev, Aktan. Kazakhstan: Making a Tentative Foray into Digital Money. EurasiaNet.org. http://www.eurasianet.org/node/80266

8. Deloitte. Kazakhstan becomes the second government to embrace the cryptocurrency market system. Deloitte. https://www2.deloitte.com/ru/en/pages/about-deloitte/press-releases/2017/kazakhstan-becomes-the-second-government-cryptocurrency-market-system.html

9. Statis. Homepage. www.stasis.net

10. Bitcoin Exchange Guide. Kazakhstan Cryptocurrency – Nation’s Exante Stasis Blockchain? https://bitcoinexchangeguide.com/kazakhstan – cryptocurrency/

11. Export.gov. Kazakhstan – E-Commerce. https://www.export.gov/article?id= Kazakhstan – ECommerce

12. Kazinform.com. Digital Kazakhstan programme to be submitted to Head of State for approval. Kazinform.com. http://www.inform.kz/en/digital – kazakhstan – program – to – be – submitted – to – head – of – state – for – approval_a3092695

13. Zerde, National Infocommunication Holding JSC. “Digital Kazakhstan” state program. https://zerde.gov.kz/en/activity/program – control/digital – kazakhstan/

14. Digital Kazakhstan. Homepage. www.digitalkz.kz

15. RadioFreeEurope/Radio Liberty. Russia’s Central Bank Considering Cryptocurrency Within EEU, and BRICS. https://www.rferl.org/a/russia – central – bank – consider – cryptocurrency – eeu – brics/28943879.html

16. Tengrin News. Cryptocurrency exchange. Kazakhstan and South Korea agreed on cooperation https://tengrinews.kz/kazakhstan_news/kriptovalyutnaya – birja – kazahstan – yujnaya – koreya – dogovorilis – 333534/

17. Cash_KZ. Tweet. https://twitter.com/cash_kz/status/ 9 2 1 7 8 9 1 4 1 3 2 6 7 1 2 8 3 2

18. KZ Cash. Introduction. https:// kzcash.kz / index. php ? option = com _ sppage -builder&view= page&id = 17&lang=en

19. Votilov, Alexandr. Kazakhstanis can pay with bitcoins of purchases in stores. Forbes Kazakhstan. https://forbes.kz/finances/finance/kazahstantsyi _ mogut _ oplachivat _ bitkoinami _ pokupki _ v_ magazinah

20. EFE. Expo 2017 Astana complex to become Crypto Valley. https://www.efe.com/efe/english/business/expo-2017-astana – complex – to – become- crypto – valley/50000265 – 3385089

21. Mayor’s Office of Astana. Astana Business Campus Will Open Its Doors in 2018. http://astana.gov.kz/en/modules/material/8519

22. Ministry for Investments and Development, Republic of Kazakhstan. 100 Concrete Steps. http://mid.gov.kz/en/kategorii/100-konkretnyh-shagov-0

23. United States Department of State, Bureau of Economic and Business Affairs. Kazakhstan. https://www.state.gov/e/eb/rls/othr/ics/2017/sca/270019.htm

24. Export.gov. Kazakhstan – 9.2-Labor. https://www.export.gov/article?id = Kazakhstan – Labor

25. Freedom House. Kazakhstan: Authorities Arrest Editor of Last Independent Newspaper. https://freedomhouse.org/article/kazakhstan – authorities – arrest – editor – last – independent – newspaper

EDITOR'S PICK OF THE WEEK

China economic growth

China’s Challenging Search for a New Model of Economic Growth

By Danny Leipziger China cannot continue to rely on exports to drive its growth, but what are the alternatives? China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...

WISE DECISION MAKER GUIDE

POWER INFLUENCERS

Emerging Trends

The Future of Global Trade