Home Blog Page 1069

What it Takes for Chinese Companies to Succeed Abroad

Shanghai skyline at the Bund with Oriental Pearl Tower downtown Pudong panorama in China

By David De Cremer

International expansion is one of the keys to a firm’s success and stability. In this article, the author outlines how Chinese companies can become truly international in reference to the procedures and philosophies in place for one of China’s truly global companies, which is Huawei.

For several years now, the Chinese government is endorsing the ideas for their companies to “go out” or “go global”. The message of this endorsement is clear. It indicates that the second largest economy in the world means serious business and therefore global ambitions for its companies have moved centre stage. This ambition is further spurred via grandiose projects like the One Belt, One Road (OBOR) initiative that was launched at the end of 2014 by President Xi Jinping. This initiative focusses on motivating Chinese State and private companies to look overseas. Despite the fact that this kind of global ambition is frequently communicated by the Chinese government, critical observers do ask the question whether the true fully-functioning Chinese multinational company really exists. For example, it is still a difficult task for most Westerners – or even an impossible task – to name five global Chinese brands. Companies like Haier, Huawei, Alibaba and Lenovo are increasingly becoming household names in the West, but not all of them have achieved yet the status of a global company. In fact, most of these companies still operate predominantly in China. Of course, the fact that the Chinese market is the biggest worldwide makes that in terms of total revenue these predominantly operating local companies are doing comparatively well at a global level.

A problem with Chinese companies going abroad is that in the past they adopted predominantly a short-term focus by trying to acquire new technology and financial gains as quickly as possible. What to do with the acquired foreign company and its work force on the long-term was less of a concern to them. It made that Chinese companies did not really know how to operate in markets outside of China. As a result, negative stereotypes around the motives of Chinese companies going global quickly and firmly emerged. In fact, these stereotypes are still dominant in the mind of Western companies and governments. But things are changing. Uplifted by the ambition of the government to make China great again (see the interesting parallel with the language used by the current US president), China’s largest companies have become more sophisticated in their international ambitions and explorations. For example, the super star company Alibaba is very much aware that in order to grow further and succeed in gaining an international reputation they need to acquire a more global mindset. And this global mindset will be necessary because the founder of Alibaba, Jack Ma, has set very ambitious targets. He wants to see his company earn $1 trillion in gross value by 2020 and serve an astonishing number of two billion customers by 2036. Of course, any company is allowed to have inspiring dreams and goals, but actions do speak louder than words and Alibaba seems to have taken this wisdom seriously. Alibaba’s global footprint is steadily growing through investments being made in the neighbouring countries like in the India-based marketplace Snapdeal and in payment platforms in Thailand, South Korea and the Philippines. The real test, however, still lies in how Alibaba will fare when entering the European and US markets.

As mentioned earlier, Chinese companies may have moved from a short-term approach to a more long-term one, it does not mean that transforming a local Chinese company into a global giant has become easier. Because of the recent economic and political turbulence, the West is concerned more than ever about the fact that economic nationalism is on the rise in China. This observation makes that Chinese companies are looked upon as maybe not having at heart an open trading system. For example, the OBOR initiative is seen – because of its emphasis on developing infrastructure such as ports, roads, airports and railways – as primarily an economic rescue plan for China to deal with its overcapacity problem of, among others, steel, glass and cement.  The existence of these obstacles means that Chinese companies with global ambitions need to be well prepared and acting in proactive ways to shift a local mindset to a global one.

In the fiscal year of 2016 Huawei’s revenue reached CNY521.574 billion (US$75.103 billion) and CNY37.052 billion (US$5.335 billion) in net profit and most of this revenue comes from outside China making them a truly global performing company.

To study more closely the different steps Chinese companies need to include in preparing their organisation to enter the global market, I examined the procedures and philosophies in place for one of China’s truly global companies, which is Huawei. In the last decade, this telecom giant has succeeded in becoming a household name in Europe and Latin America (although it is still banned from doing business in the US).  The company was founded in 1987 by Ren Zhengfei and is an employee-owned company (about 98.5% of the company is owned by its employees). In the fiscal year of 2016 Huawei’s revenue reached CNY521.574 billion (US$75.103 billion) and CNY37.052 billion (US$5.335 billion) in net profit and most of this revenue comes from outside China making them a truly global performing company. To illustrate further the international nature of the company, as of Q3 2017, Huawei employs more than 32,000 international employees, working in over 160 countries. Over 19,000 Chinese employees work outside China. Having achieved such international reputation for a Chinese company requires continuous preparation and persistence to develop and train its work force to work and compete at a global level. Below, I will discuss several points on how Huawei approaches this challenge.

An important aspect of their (human) globalisation strategy concerns the way Huawei prepares Chinese employees when they are assigned to work in another country. The company usually prepares them in multiple aspects, including safety, health, language, customs paperwork, laws and regulations, local customs and etiquette.

1. The Use of Clear Policies and Processes

Working in a Chinese setting includes strong discipline and willingness to conform. Because teamwork is regarded in China as primarily following the instructions of leaders, Chinese employees often have difficulties to adapt to more Western management structures and ways of working. When arriving in a new country, Chinese employees therefore have many questions on how to proceed with their job and achieve success. A first barrier that international Chinese assignees thus face concerns the complex management structures, policies and lengthy work processes. It takes a lot of effort to figure these out. To address this pain point, Huawei has developed a comprehensive guide: Pre-departure Briefing and Guidelines for International Assignees from China. This guide provides all necessary information for Chinese employees to be assigned overseas, helping them better prepare themselves for the assignment.

2. The Use of a Language Proficiency Test

Companies investing in the language proficiency of their employees will lead to stronger and more committed relationships with clients.

Chinese companies do not have many staff on the payroll being multilingual and experienced in working in other countries. This makes that language is a barrier for international assignees. Wanda chairman Wang Jianlin identified this linguistic problem as a serious concern when he addressed students in Oxford. He said: “English is our greatest challenge. We have a lot of senior employees in Wanda. However, when going global in tourism, sports and entertainment, inadequacy in English is a huge challenge.”

Although many Chinese companies rely on the help of translators (as Western companies also do when entering the Chinese market), it is no secret that companies investing in the language proficiency of their employees will lead to stronger and more committed relationships with clients. Huawei proactively helps its employees improve their language proficiency and take on language assessment tests. The company will centrally register for recognised language tests (e.g. TOIEC) for its employees on a voluntary basis. The HR staff members then follow up on the assessment results to ensure that language will not be a problem for their international assignees. Furthermore, the company will also try to teach international employees in different locations the basics of Chinese in an effort of cultural exchange. As one Chinese employee told me, “When I was in Argentina, teams were composed of Chinese and Argentinean employees. We sat together to get to know each other, had our meetings together and visited customers together. The local employees taught us their customs, and we also had a Chinese language class for the local Argentinian team. In one of the teams I was the teacher as I am fluent in both Mandarin and Spanish.”

3. Training on Security, Laws and Regulations

As many Chinese companies, Huawei also has encountered the fear of Western companies that their Chinese counterpart will not adapt to foreign legal, regulatory, tax and political environments. Generally speaking, Chinese companies are usually met with suspicion and concerns about security as corporate governance is perceived as lacking or being limited in the eyes of the West. To deal with this, Huawei has developed an iLearning platform and topic-specific MOOC courses. Huawei employees can access these courses anytime they want to learn about cyber security, laws and regulations, and how to integrate into a diversified culture. Employees can also take exams for each of these courses. Each course has been assigned an instructor to provide timely support to learners. The test results are directly linked up with the international assignment process. Employees must pass required certifications to be eligible for an international assignment.

4. A Focus on Employee Health

Huawei believes that physical health is the prerequisite for everything they do. In fact, recently, its founder, Ren Zhengfei, has stressed the importance of Huawei as possessing organisational vitality to survive in the long term.1 This logic is actually the first line of the motto of Huawei University, which is “be healthy and strong”. The general idea is that physical exercise unites people. Huawei is thus concerned about the health of its international assignees and has taken three measures to address this issue. First, Huawei purchases business travel insurance for all international assignees to address their health problems during their assignments outside of China. Second, Huawei has all international assignees vaccinated and their health checked and prepares first aid kits for them. Third, in tough work environments (e.g. high altitude, tropical climate), Huawei provides high-quality accommodation and working environments for their employees and rents houses with screen doors and window screens to protect them from infections. The primary aim is to help their staff stay healthy in order for them to better focus on their career development in overseas offices.

5. A Focus on Cultural Assimilation

It is necessary to develop sophisticated and detailed procedures with the aim to help international assignees to adjust working with global standards while at the same time integrate in local cultures.

Another stereotype that exists includes the perception that Chinese companies have difficulties to escape their own national corporate culture and business practices. As a result, Chinese employees are perceived as not willing to integrate in local foreign cultures. As a response to this, Huawei tries to help international Chinese assignees integrate into a foreign culture in four ways. First, the company provides updated cultural guides and tips to help employees adapt to local culture quickly. Second, Huawei has administrative services available to all international assignees that might need help for living in a foreign country. Third, the company ensures that each international assignee will be assigned to a mentor who will help them adapt to their new workplace effectively. Fourth, to help international assignees understand their roles more clearly and improve their skills within that role, the company organises all kinds of contests within product lines. Finally, at the same time, Huawei also attempts to organise other activities to help international assignees better integrate into the local culture, including talks with new international assignees, welcome parties, visits to local facilities and so forth.

In conclusion, recent numbers show that Chinese companies are increasingly spending more money abroad than ever before. In this process of international expansion, the challenge remains for Chinese companies to prepare their work force to adopt a global mindset when it comes down to working and living in cross-cultural environments. For this reason, it is necessary to develop sophisticated and detailed procedures with the aim to help international assignees to adjust working with global standards while at the same time integrate in local cultures.

About the Author

David De Cremer is the KPMG Professor of Management Studies at the Judge Business School, University of Cambridge, UK, where he heads the Department of Organisational Leadership and Decision-Making. He is the author of the book Pro-active Leadership: How to overcome procrastination and be a bold decision-maker (2013) and co-author of “Huawei: Leadership, culture and connectivity” (2017).

Reference

1. De Cremer, D. (in press). Organisational Vitality: The Lifeline of Your Company. The European Business Review

Strategic ALM and Integrated Balance Sheet Management: The Future of Bank Risk Management

Finance, banking concept. Euro coins, us dollar banknote close-up. Abstract image of Financial system with selective focus, toned, double exposure.

 By Moorad Choudhry

The traditional approach to asset-liability management (ALM) practice in banks operated as a reactive process following product origination by the customer-facing business. In the Basel III era a more proactive approach to ALM is required, in order to manage the balance sheet from an effective viability and sustainability standpoint. The article describes proactive “Strategic ALM” discipline and its implementation process. 

Banks are by their nature risk taking institutions. This is a requirement of their business, because their corporate clients may wish to tailor their funding to meet the precise needs of their business, so as to achieve some certainty in this area, enabling them to focus on what they do best. Similarly, retail clients may wish to access banking products and services to meet their personal needs, such as purchasing a house or investing for a child’s education. To meet this demand, banks offer the lending terms, maturities, rate options, currency, optionality, and contingencies demanded by their clients, and take on the range of risks that such tailoring represents. Because banks have a wide range of clients with varying borrowing and deposit requirements, exposures may to some degree offset each other, but will not match completely in terms of timing, amount and currency. This is more evident as products become more complex and offer more alternatives.

Therefore a key area of focus for banks is managing their capital, funding, liquidity and interest-rate risk requirements. These all fall under the umbrella of the asset-liability management (ALM) discipline in a bank. When a bank borrows more than it needs, there can be inefficiencies in terms of capital use. This can also result in added interest rate risk, and a loss when lending on. However, failure to have sufficient funding results in the bank having to rely on central bank liquidity, poor market perception and loss of investors, which could ultimately lead to failure. Thus, ALM becomes the most important aspect of a bank’s risk management framework.

In this article we suggest that the discipline of ALM, as practised by banks worldwide for over 40 years, needs to be updated to meet the challenges presented by globalisation and Basel III regulatory requirements. In order to maintain viability and a sustainable balance sheet, banks need to move from the traditional “reactive” ALM approach to a more proactive, integrated balance sheet management framework. This will enable them to solve the multi-dimensional optimisation problem they are faced with at present.

The Origins of Asset-Liability Management (ALM) 

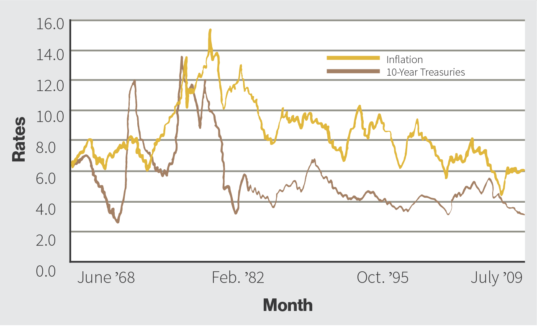
Historically, interest rates were stable and liquidity was readily available to banks in developed nations. Banks focussed primarily on generating assets to increase growth and profitability. However, in the 1970s changes in regulation, inflation, and geopolitics led to greater volatility and thus increased risk from asset and liability mismatches (see Figure 1).  This led to the development of Asset-Liability Management (ALM) as a formal discipline, where both sides of the balance sheet are integrated to manage interest rate, market, and liquidity risk. In essence however, this discipline remained reactive in nature, with Treasury and Risk having little or no input to the origination and deposit raising process.

Figure 1: US Treasury yields and US inflation historical levels

Source: St. Louis Fed.

Traditionally, ALM was defined by four key concepts:

• Liquidity, defined as

◦ Funding liquidity: the continuous ability to maintain funding for all assets
◦ Trading liquidity: the ease with which assets can be converted into cash

• Term structure of interest rates: the shape of the yield curve at any given time depends on interest rate expectations, liquidity preference, and supply and demand from different borrowers and lenders. ALM strategy would consider how changes to the shape of the yield curve in the short and medium term will impact the bank.
• The maturity profile of the banking book
• ALM would report and monitor the maturities of all asset and liabilities to measure and control risk
• Interest rate risk, essentially the risk of loss of net interest income due to adverse movements in interest rates or interest rate spreads.

In essence however, “ALM” as undertaken in all banks has always been a reactive process, and despite its name has rarely, if ever, managed to integrate origination policy across both sides of the balance sheet. As a discipline, such an approach is no longer fit-for-purpose in the era of Basel III.

The Strategic ALM Concept

Consider exactly how ALM is undertaken in virtually every bank today, irrespective of size, business model or location. A business line in a bank, following an understood medium-term “strategy” articulated either explicitly or implicitly (but in reality aiming usually simply to meet that year-end’s budget target), goes out and originates customer business, be this originating assets or raising liabilities. It will most likely have little interaction with any other business line, and only the formal review interaction with the Risk department. This is often described as creating a “silo mentality” in the organisation, and is typical of all but the very smallest banks. In some banks an individual business line may have practically zero interaction with Treasury. In this respect it will be similar to all other business lines.

Each of these business lines will proceed to undertake business, ostensibly as part of a grand strategy intertwined with other business lines, but in reality to a certain extent in isolation. The actions of all the customer-facing desks in the banks will then give rise to a balance sheet that must be “risk managed”. And the ALM part of this risk management process is then undertaken by Treasury, in conjunction with Finance and Risk.

There is little, or no, interaction between business lines and little, or no, influence of the Treasury function or the risk “triumvirate” of Treasury, Finance and Risk in the balance sheet origination process. In other words, ALM is a reactive, after-the-fact process. The balance sheet shape and structure is arrived at, if not by accident certainly not by active design and certainly not as the result of a process that integrates assets and liabilities origination. The people charged with stewarding the balance sheet through the economic cycle and market crashes have very little to do with creating the balance sheet in the first place. Does this represent best-practice risk management discipline, with separation of duties, four lines of defence, and so on? In a word, no. There is no problem with one department originating assets and another one managing the risk on them. The issue with the traditional approach to ALM is that the balance sheet that is arrived at often lacks a coherent shape, or logic, and this makes the risk management of it more problematic.

There is little, or no, interaction between business lines and little, or no, influence of the Treasury function or the risk “triumvirate” of Treasury, Finance and Risk in the balance sheet origination process. In other words, ALM is a reactive, after-the-fact process.

One would not wish to have a balance sheet that was composed overwhelmingly of illiquid long dated assets funded by wholesale overnight deposits, or a liabilities strategy that concentrated on raising wholesale or corporate funding that was treated punitively by Basel III liquidity requirements. Another example observed by the author involved the funding of trade finance assets (overwhelmingly very short term) by 10-year MTNs.1

In the era of Basel III, it is evident that balance sheet risk management must become more proactive. The shape and structure of the balance sheet must be arrived at because of an integrated approach to origination. What does this mean? Quite simply, the discipline of ALM must recognise that asset origination and liability raising has to be connected. For the ALM process to be fit-for-purpose for the 21st century, banks must transition and adapt from a traditional reactive ALM process to a proactive strategic ALM process.

Addressing the three-dimensional (3D) balance sheet optimisation problem

The market environment is creating a 3D optimisation challenge for banks, or at least those banks that are serious about competing and serious about being well-respected by customers and peers. This challenge requires banks to run optimised balance sheets in order to maximise effectiveness and stakeholder value; however when we speak of “balance sheet optimisation” we do not mean what it used to mean in the pre-crash era, basically working to maximise return on capital (RoC). Today optimising the balance sheet has to mean structuring the balance sheet to meet the competing but equivalent needs of Regulators, Customers and Shareholders. This is the 3D optimisation challenge that we speak of.

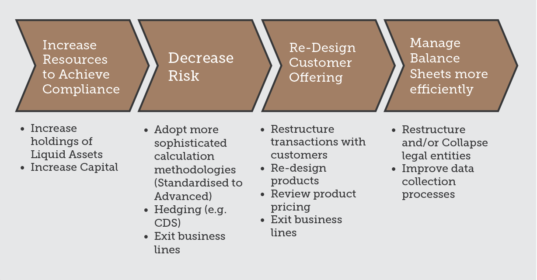
A bank’s risk management practice is an integral part of meeting this optimisation challenge. From the Board level downwards, policy must be geared towards achieving this goal, and strategic ALM is a vital part of the optimising process. However before we consider this let us refresh the regulatory aspects first. We will not cover the myriad requirements of Basel III capital, liquidity and leverage requirements here, which are discussed in depth in other publications. The essence of implementing the demands of Basel III as stipulated by regulators is that many bank’s business models will have to change, to ensure compliance. Figure 2 illustrates this in stylised fashion.

1. These illustrations are made to emphasise a point, but they are a few of the very many examples observed by the author at different banks over the years.

Figure 2: Mitigating the Impacts of Basel III

© Christopher Westcott 2014, 2017. Reproduced with permission


The inescapable conclusion since the bank crash of 2008 is that banks must manage their balance sheet more efficiently. This gives rise to the 3D optimisation problem. We articulate it thus:

1. Regulator requirements: banks must adhere to the capital, liquidity and leverage ratio requirements of their regulator. With only a handful of exceptions, this means meeting the demands of the Basel III guidelines. The larger the bank, and/or the more complex its business model, the more complicated and onerous this requirement becomes. Related stipulations such as the Fundamental Review of the Trading Book (FRTB) add to the regulatory demands imposed on banks. Every bank must meet its supervisory requirements;

2. Customer franchise requirements: this is not necessarily anything new. In a competitive world, any bank would always wish to meet the demands of its customers. In a more constrained environment this requirement becomes more urgent of course, and this gives rise to the challenge. For instance, a “full service” bank will wish to provide all the products that its customers may demand, and sometimes these products will not be the most optimum from the viewpoint of (1) above. To illustrate one case: the deposits of large corporate customers and non-bank financial customers are considered “non-sticky” under Basel III rules and so carry a greater liquidity cost for banks. From that perspective such deposits are not optimum from a regulatory efficiency view, but the bank must accept them if it wishes to satisfy this part of its customer base;

3. Shareholder requirements: this aspect is of course also not new. The shareholder has always demanded a satisfactory rate of return, and so all else being equal a bank will always want to maximise its net interest income (NII) and enhance or at least preserve its net interest margin (NIM) through changing economic conditions and interest rate environments. But of course the balance sheet mix that meets this objective will not necessarily be the one that is most efficient for (1) and/or (2) above. One example: from a NII perspective a bank will maximise its funding base in non-interest bearing liabilities (NIBLs) such as current accounts (“checking” accounts) or instant access deposit accounts, whereas the demands of Basel III liquidity will often call for an amount of contractual long-term funding, which is more expensive and thus inimical to NII.

We see therefore that the demands of each stakeholder are, in a number of instances, contradictory. To maximise efficiency a bank will need to work towards a balance sheet shape and structure that is optimised towards each stakeholder, and it is not a linear problem. Hence, the 3D optimisation challenge arises.

This illustrates unarguably the need for a new approach to balance sheet origination and the role of the ALM function. This we term “strategic ALM”.

Principles of strategic ALM practice

Strategic ALM is a single, integrated approach that ties in asset origination with liabilities raising. It works to break down “silos” in the organisation, so that asset type is relevant and appropriate to funding type and source, and vice versa. We define it as follows:

A business strategy approach at the bank-wide level driven by balance sheet ALM considerations

Strategic ALM addresses the three-dimensional optimisation problem of meeting with maximum efficiency the needs of:

• the regulatory requirements
• the NII requirements
• the customer franchise requirements

and must be a high-level, strategic discipline driven from the top down. It is by nature proactive and not reactive.

Implementing a strategic ALM process will make it more likely that the bank’s asset type(s) is relevant and appropriate to its funding type and source, and that its funding type and source is appropriate to its asset type. By definition then it would also mean that a bank produces an explicit, articulated liabilities strategy that looks to optimise the funding mix and align it to asset origination. Thus, strategic ALM is a high-level, strategic discipline driven from the top down.

Proactive balance sheet management (BSM) is just that, and not the “reactive” balance sheet management philosophy of traditional banking practice. Proactive BSM means the asset-side product line is managed by a business head who is closely aligned (in strategic terms) with the liabilities-side product line head. To be effective the process needs to look in granular detail at the product types and how they are funded/deployed; only then can the bank start to think in terms of optimising the balance sheet.

Implementing strategic ALM practice is not a trivial exercise, and can only be undertaken from the top down, with Board approved instruction (or at least approval). Hence we consider an essential prerequisite, which is the Board articulated risk appetite statement, followed by a look at the importance of ALCO.

Implementing Strategic ALM

The approach to implementing an effective strategic ALM practice has several strands. We describe each in turn.

Recommended Risk Appetite Statement

The Risk Appetite Statement is an articulated, explicit statement of Board appetite for and tolerance balance sheet risk, incorporating qualitative and quantitative metrics and limits. It becomes the most important document for Board approval. This may appear to be a contentious statement but it is self-evident when one remembers that the balance sheet is everything. The over-riding objective of every bank executive is to ensure the long-term sustainability and viability of the bank, and unless the balance sheet shape and structure enables this viability, achieving this objective is at risk.

Figure 3 shows a template summary risk appetite statement drafted by the author when he was Treasurer at a medium-sized commercial bank. This statement received Board approval. It is applicable to virtually all banking entities irrespective of their business model, although large multinational banking institutions will need to develop the list of risk metrics much further. It provides a formal guide on the desired Board risk appetite framework, including a description of each of the risk appetite pillars and the key measures that will be used to confirm on a monthly basis that the bank is within risk appetite.

Figure 3: Example Board risk appetite statement

© Moorad Choudhry 2011, 2017

As we see from Figure 3, for each of the measures identified an overall bank-wide “macro-tolerance” is set, which is then broken down into tolerances for individual business lines (e.g. Retail, Corporate). The range of quantitative limits is user-defined; for example, in the section on liquidity limits:

• a vanilla institution with no cross-border business may content itself with setting limits for the primary liquidity metrics such as loan-deposit ratio and liquidity ratios, as well the regulatory metrics such as LCR and NSFR;
• a bank transacting across currencies will wish to also incorporate FX exposure tolerance;
• a bank employing a significant amount of secured funding will wish to add asset encumbrance limits.

The Board risk appetite statement is the single most important policy document in any bank and should be treated accordingly. It requires regular review and approval, generally on an annual basis, or whenever changes have been made to the business model and/or customer franchise. It also should be updated in anticipation or in the event of market stress.

Armed with the Board risk appetite statement, which must be a genuine “working” document and not a list of platitudes, with specific quantitative limits, the implementation of a strategic ALM process becomes feasible. As well as the Board risk statement, the other ingredient that is required to make strategic ALM a reality is an asset-liability committee (ALCO) with real teeth. One cannot emphasise enough the paramount importance of a bank’s ALCO.

Given this, what is the most effective way to ensure above-satisfactory and effective governance from Board perspective?

Elements of Strategic ALM: paramountcy of ALCO

Consider the executive committees, below Board level, that are responsible for the strategic direction as well as the ongoing viability and sustainability of the bank. Which of them has responsibility for oversight of balance sheet risk? Perhaps it is one or more of the following:

• Executive committee (or “management committee”): this is the primary committee responsible for running the bank, chaired by the CEO;
• Risk management committee: chaired by the CRO, responsible for “managing” all the risk exposures the bank may face, from market and credit risk to technology risk, conduct risk, regulatory risk, employee fraud risk, etc.;
• Credit risk committee: chaired by the head of credit or the credit risk officer, this committee is responsible for managing credit policy including credit risk appetite, limit setting and credit approvals. As credit risk is the single biggest driver of regulatory capital requirement in banks (in some vanilla institutions representing 75%-80% of total requirement) it can be seen that the credit risk committee is also a balance sheet risk committee;
• ALCO: the asset-liability committee, a template Terms of Reference for which were described in the author’s text The Principles of Banking.

While all of these committees have an element of responsibility for the bank’s balance sheet, it is the ALCO that is responsible for this and nothing else. It alone has the bandwidth to discharge this responsibility effectively and to help ensure that the balance sheet shape and structure is long-term viable. The executive committee that is most closely concerned with balance sheet risk on a strategic and integrated basis (both sides of the balance sheet and all aspects of risk) is ALCO. Given this, what is the most effective way to ensure above-satisfactory and effective governance from Board perspective? We suggest that it is to ensure the paramountcy of ALCO, as illustrated in the organisation chart given at Figure 4.

Figure 4: Recommended bank executive committee organisation structure

© Moorad Choudhry 2011, 2017


The key highlight of the structure shown at Figure 4 is that ALCO ranks pari passu with the ExCo and that it also has an oversight role over the Credit Committee. The former ensures that balance sheet strength and robustness is always given equal priority with shareholder return, and the latter ensures that ALCO really does exercise control over the assets and liabilities on the balance sheet, as suggested in its name. For instance, it would be ALCO, and not ExCo or the Risk Committee, that would design, drive and monitor the bank’s early warning indicator (EWI) metrics, as it would be the committee with the required expertise and understanding of the balance sheet.

With this structure in place, implementing strategic ALM practice can become a reality.

Elements of Strategic ALM: integrated balance sheet origination

At its heart the objective of the strategic ALM process is to remove the “silo mentality” in place at banks in order to ensure a more strategically coherent origination process. This will help the bank to arrive at a balance sheet shape and structure more by design than by well-intentioned accident.

In the first instance, a bank’s liquidity and funding policy should not be concerned solely with its liabilities. The type of assets being funded is as important a consideration as the type of liabilities in place to fund those assets. For a bank’s funding structure to be assessed on an aggregate balance sheet approach, it must measure the quality and adequacy of the funding structure (liabilities) alongside the capital and asset side of the balance sheet. This gives a more holistic picture of the robustness and resilience of the funding model, in normal conditions and under stress. The robustness of funding is as much a function of the liquidity, maturity and product type of the asset base as it is of the type and composition of the liabilities.

Typical considerations would include:

• Share of liquid assets versus illiquid assets
• How much illiquid assets are funded by unstable and/or short-term liabilities
• Breakdown of liabilities:

◦ Retail deposits: stable and less stable
◦ Wholesale funding: secured, senior unsecured
◦ Capital: subordinated / hybrid; equity

As part of an active liabilities strategy, on the liability side ALCO should consider:

• Debt buy-backs, especially of expensive instruments issued under more stressful conditions at higher coupon;
• Developing a wide investor base
• Private placement programme
• Fit-for-purpose allocation of liquidity costs to business lines (FTP)
• Design and use of adequate stress testing policy and scenarios
• Adequate risk management of intraday liquidity risk
• Strong public disclosure to promote market discipline

On the asset side, strategic action could include:

• Increasing liquid assets as share of the balance sheet (although  liquidity and ROE concerns must be balanced)
• De-linking the bank – sovereign risk exposure connection

◦ The LCR HQLA does not have to be exclusively sovereign debt, but claiming a “shortage” of eligible assets is disingenuous: the HQLA can be exclusively cash

• Avoiding lower loan origination standards as the cycle moves into bull market phase
• Addressing asset quality problems.

◦ Ring-fence NPLs and impaired loans? (A sort of “non-core” part of the balance sheet that indicates you are addressing the problem and looking at disposal)

• Review the bank’s operating model. Retail-wholesale mix? Franchise viability? Comparative advantage?
• Limit asset encumbrance: this contradicts pressure for secured funding

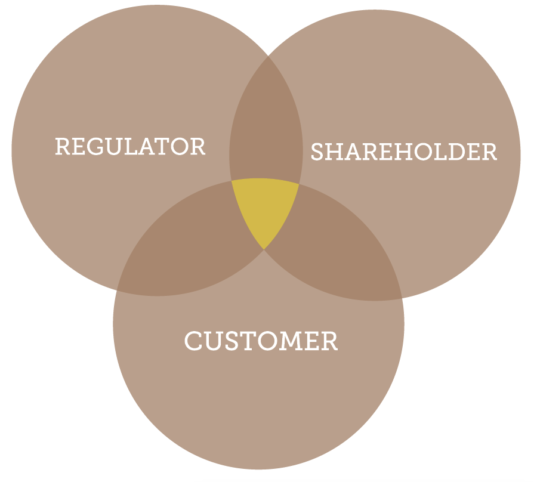
In essence, as far as possible a bank’s balance sheet should aim to maximise those assets and liabilities that hit the yellow-shaded “sweet spot” shown in the Venn diagram at Figure 5, where the requirements of all three stakeholders are served. Of course, a “full service” commercial bank will still need to offer loan and deposit products that meet customer needs but may be less optimum from a regulator or shareholder requirement perspective. This is the nature of banking and must be accepted. Nevertheless for efficiency and optimisation reasons,the process of strategic ALM is still needed so as to ensure maximisation of the origination of assets and liabilities that cover off all three stakeholder needs, and minimisation of the origination of product types that meet the needs of just one or two stakeholders.

Figure 5: Product mix optimisation

© Moorad Choudhry 2011, 2017


We emphasise strongly one of the bullet points above, namely

Strong public disclosure to promote market discipline.

A bank that discusses the structure and strength of its balance sheet is assisting the industry as a whole, as regulators point to it (off the record, it is unlikely that a bank supervisor would make this point formally) as a benchmark and as its peers look to it when comparisons are made by analysts.

We present at Figure 6 a summary high-level asset-liability policy guide, to be followed as part of the strategic ALM process.

Figure 6: Summary of asset-liability policy guide

© Moorad Choudhry 2011, 2017

Conclusions

Bank assets and liabilities are inextricably linked. Banks cannot manage risk and return without considering both sides of the balance sheet at the same time and continuously throughout the business origination process. All areas of the bank must come together to understand interest rate and liquidity risks in setting and pursuing high level strategy.

Traditionally “ALM” meant managing liquidity risk and interest-rate risk. But this isn’t full “ALM” if what one wishes to manage is all the assets and all the liabilities from one integrated, coherent aggregate viewpoint. The balance sheet is everything – the most important risk exposure in the bank. Managing ALM risk on the balance sheet therefore is managing everything that generates balance sheet risk. Proactive ALM or what we call “Strategic ALM” is self-evidently best-practice in the Basel III environment, where one can’t expect to originate assets and raise liabilities in isolation from each other and still “optimise” the balance sheet.

ALM is an all-encompassing discipline and one that should be understood by all senior bankers, particularly the executive committee.

We have addressed a number of factors with respect to implementing strategic ALM, from a high-level standpoint. The correct approach to ALM discipline demands a keen appreciation and understanding of other related factors, including:

• product type and behaviour;
• behavioural tenor characteristics of assets and liabilities (something required to some depth now anyway with implementation of Basel III);
• relevant reference interest rate benchmarks;
• the Libor-OIS spread, the Libor term premium and determinants of the swap spread;

as well as other related aspects such as peer benchmarking and understanding net interest margin (NIM) behaviour. ALM is an all-encompassing discipline and one that should be understood by all senior bankers, particularly the executive committee.

In the Basel III era, in order to meet the 3D optimisation challenge faced by banks one must seek to achieve maximum balance sheet efficiency, and that calls for the risk “triumvirate” of Treasurer, CFO and CRO, operating through ALCO, to have a bigger influence in origination and customer pricing. This is now the future of risk management practice in banks. Without this approach, it will be difficult to optimise the asset-liability mix that addresses the “3D” problem of regulatory compliance, NIM enhancement and customer franchise satisfaction.


About the Author

Professor Moorad Choudhry lectures on the MSc Finance programme at University of Kent Business School. He was previously Treasurer, Corporate Banking Division at The Royal Bank of Scotland, and is author of The Principles of Banking.

Why We Need to Reform Financial Regulation

US president signing financial reform

By Markus Demary

The US Republican Party plans to repeal the Obama-era financial regulation. While their approach will bring regulatory relief to financial firms, it will also increase the risks of financial crises. Introducing regulatory relief through a small banking box would be a better way of making the financial system more efficient.

Reforming financial regulation from time to time is necessary. Existing rules do not effectively apply to new business developments and technologies and they might become inconsistent to global approaches to financial regulation. Alternatively, reforms are necessary for making the financial system more resilient to shocks. That is why it is necessary to scrutinise the existing regulation on a regular basis. This approach is pursued in the European Union with the public consultations on the bank capital requirements regulation, on the cumulated effects of financial regulation and on the creation of a Capital Markets Union. These are approaches – with industry and consumer advocates’ cooperation – to improve the existing regulatory system. The US Financial CHOICE Act, which passed the House of Representatives on June 8, 2017,1 represents a different approach, however, it is the replacement of the old regulatory system with a much older one.


A Small Banking Box is Worth Discussing

Still, the Financial CHOICE Act contains some valuable ideas worth discussing.2 Many experts have good reasons to be critical about the US response to the financial crisis of 2008 coded in the Dodd-Frank Wall Street Reform and Consumer Protection Act. For one, Dodd-Frank has raised the regulatory burdens for financial firms, it restricted the access to loans for households and it added a lot of complexity to the resolution process of failing banks.3 Regulation also made the European financial system more complex. Therefore, the European Union is discussing a so-called small banking box, which aims at decreasing the regulatory complexity for smaller banks. The lighter regulatory environment is based on the fact, that these banks are less exposed to the risks of the global financial system because of their focus is to finance their local community.

A small banking box might therefore be correct for these unintended consequences of Dodd-Frank.

Similar to the idea of a small banking box, the Financial CHOICE Act aims at providing regulatory relief to a subset of banks. While the subset consists of smaller and systematically insignificant banks in the small banking box, it is well-capitalised banks in the Financial CHOICE Act. Banks qualify for the lighter regulatory environment through the option of a “Capital Election”. Thereby, banks with an unweighted equity capital ratio (leverage ratio) of more than 10 percent would be able to switch to a less strict regulatory framework than Basel III. This approach is similar, but different from the idea of a small banking box because the lighter regulatory environment can also apply to larger banks. The “Capital Election” idea is based on the assumption that highly capitalised banks should be able to absorb losses without the need for regulatory intervention.4 While this might hold for smaller banks, it does not hold for larger banks that are highly interconnected with the rest of the financial system through their assets and liabilities. The lighter regulatory environment can reinforce risks to the financial system, if it will be applied to larger banks.

However, as long as banks are small and not too much interconnected to other parts of the financial system, a small banking box might reduce the compliance costs for these smaller banks without increasing the risks for the financial system. Many of the smaller banks cannot employ a large staff of experts to deal with complex regulations, but Dodd-Frank forced them to employ expensive experts or to shut down business, which needs a lot of regulatory knowledge. It is harmful for smaller banks that many of the existing regulations with all their complexity target larger banks, while they apply to all banks, independent of their size. A small banking box might therefore be correct for these unintended consequences of Dodd-Frank.

The small banking box makes sense from the microprudential point of view – that is, from the perspective of the single bank risk.5 However, it neglects the macroprudential view, i.e. the effects of herd behaviour on the financial system or cluster risks in banks’ balance sheets due to common risk exposures. That is where the Basel III equity capital regulation provides instruments to address such macroprudential risks. Addressing these risks is still important, but banks that operate exclusively in their local community might be overregulated under this approach. Therefore, the regulatory relief within the small banking box should not be based solely on the equity capital ratio of the banks, but on the absence of any systemic importance through size, interconnections or common risk exposures.

A small banking box without an assessment of the systemic unimportance of banks would undermine the macroprudential approach. It would then increase the risk that the banks operating under “Capital Election” would be heavily involved in real estate financing with non-recourse loans. In case of a debtor’s default, banks have only access to the property but not to the remainder of the borrower’s assets. Therefore, the US banking sector is more vulnerable to losses from bursting real estate bubbles compared to the European economies where non-recourse loans are less common.

Resolution Rules Need to be Reformed

The Financial CHOICE Act seeks to abolish the Orderly Liquidation Authority (OLA), based on the Dodd-Frank Act, as a resolution institution for failing banks. Instead, banks in distress should be liquidated via the normal bankruptcy code.6

In normal insolvency proceedings, for example in case of a failing non-financial firm, creditors use a judicially controlled process to decide on the resolution of the remaining assets. This way, the resolution measures are financed via the sale of assets of the company in distress.7 The liquidation of financial firms is more complex, because their assets and liabilities are connected to other parts of the financial system.8 Disruptions of the payment system, for example, will stop the economy from functioning smoothly. While this approach may be appropriate for smaller distressed banks, which are unconnected to other parts of the financial system, it is not suitable for the resolution of a major investment bank. The latter is very likely highly connected to other parts of the financial system through its assets and liabilities. A normal insolvency proceeding of a large investment bank would that way be impossible without repercussions and contagion effects on the financial system

The Financial CHOICE Act seeks to abolish the Orderly Liquidation Authority (OLA), based on the Dodd-Frank Act, as a resolution institution for failing banks.

Because of the impossibility of liquidating large banks without disruptions to the financial system via the bankruptcy code, creditors can expect that the government will protect them with public money. This will cause the ratings of these large banks to experience an upward bias. The decline of their refinancing costs is called the too-big-to-fail subsidy in the literature. There are estimates that this subsidy consists of a rating improvement of 2.2 rating notches on average.9

One expected effect of the resolution rules in Dodd-Frank is that the too-big-to-fail subsidy for large banks would be lower than under the bankruptcy code. This would also reduce the competitive advantage of larger banks over smaller banks because the latter do not profit from this implicit subsidy. Therefore, the abatement of the OLA is incompatible with a small banking box. A better approach would have been to restrict the OLA to large banks, while applying the bankruptcy code would stay at the centre of resolving failing smaller banks.

The OLA is needed because the very short maturities of an investment bank’s liabilities on the interbank market are highly interconnected. Freezing these liabilities could lead to liquidity shortages among creditors and even disruptions to the settlement of payments. However, repercussions on the financial system could also occur through the sale of assets on a large scale. This would cause the prices of comparable assets to fall, which then could lead to balance sheet losses at other banks.8 Therefore, the so-called systemically important functions of a major bank cannot simply be resolved in a bankruptcy process, but they must be in an orderly fashion over a longer period of time.

A restriction of the bankruptcy code for smaller and unconnected banks that qualify for a small banking box would be a more effective approach. Since the failure of these banks put only small risks onto the financial system, they can be liquidated without major repercussions on the financial system.

The Financial CHOICE Act Should Only Apply to Smaller Banks

The Financial CHOICE Act may be conclusive if it only applies to smaller banks, which are less connected to the other parts of the financial system. Although the Dodd-Frank Act is not perfect in all respects, it provides a regulatory framework that is able to mitigate macroprudential risks. Instead of rushing to repeal Dodd-Frank, Democrats and Republicans should better have aimed for a reform of the Dodd-Frank Act by applying a small banking box. A lighter regulatory environment for smaller banks operating on the local level would lessen their compliance cost and it would improve the financing of the economy without endangering the stability of the financial system.

Featured Image: US President Donald Trump signing an executive order on financial system regulation at the White House in Washington, Feb. 3, 2017. © Reuters

About the Author

Markus Demary is a Senior Economist in the research unit financial and real estate markets at the Cologne Institute for Economic Research (Institut der deutschen Wirtschaft Köln) and a lecturer for Behavioral Finance at Ulm University. Markus studied economics at the Rheinische Friedrich-Wilhelms-Universität Bonn and holds a doctoral degree from the Christian-Albrechts-Universität zu Kiel.


References

1. See Alan Rappeport, 2017, Bill to Erase Soöme Dodd-Frank Banking Rules Passes in House, The New York Times, June 8, 2017, https://www.nytimes.com/2017/06/08/business/dealbook/house-financial-regulations-dodd-frank.html
2. See HCFS – House Committee on Financial Services, 2017, The Financial CHOICE Act: Creating Hope and Opportunity for Investors, Consumers, and Entrepreneurs, A Republican Proposal to Reform the Financial Regulatory System, https://financialservices.house.gov/UploadedFiles/2017-04-24_Financial_CHOICE_Act_of_2017_Comprehensive_Summary_Final.pdf
3. See Markus Demary, 2017, The US Should Not Roll Back Financial Regulation, LSE Business Review, http://blogs.lse.ac.uk/businessreview/2017/09/06/the-us-should-not-roll-back-financial-regulation/
4. See Markus Demary, 2017, The US Should Not Roll Back Financial Regulation, LSE Business Review, http://blogs.lse.ac.uk/businessreview/2017/09/06/the-us-should-not-roll-back-financial-regulation/
5. See Markus Demary, 2017, The US Should Not Roll Back Financial Regulation, LSE Business Review, http://blogs.lse.ac.uk/businessreview/2017/09/06/the-us-should-not-roll-back-financial-regulation/
6. See Ben Bernanke, 2017, Why Dodd-Frank’s Oderly Liquidation Authority Should Be Preserved, https://www.brookings.edu/blog/ben-bernanke/2017/02/28/why-dodd-franks-orderly-liquidation-authority-should-be-preserved/ [abgerufen: 20.06.2017]
7. See Sabrina, Pellerin and John Walter, 2012, Orderly Liquidation Authority as an Alternative to Bankruptcy, Federal Reserve Bank of Richmond Economic Quartlerly, Vol. 98 (1), 1-31
8. See Sebastian Schich and Sofia Lindh, 2012, Implicit Guarantees for Bank Debt: Where Do We Stand?, OECD Journal: Financial Market Trends, Vol. 2012, Issue 1, S. 1-22
9. See Andrei Shleifer and Robert Vishny, 2011, Fire Sales in Finance and Macroeconomics, Journal of Economic Perspective, Vol. 25, No. 1, 29-48

Will the Chinese Rise Destroy Pax Americana in the Middle East?

By Timo Kivimäki

China has started to make its presence felt in the Middle East. Most commentators assume this to lead into the destabilisation of the already fragile region. This article will show, however, why China’s economic interests and identity will prevent it from dangerous intrusive political manipulation in the Middle East.

Competition for power and global dominance that often comes with it have often been belligerent in world history. This is particularly true during times of power transitions. Jia Qingguo and Richard Rosecrance1 have reminded that out of seven such hegemonic competitions,2 only the US-British hegemonic competition in the 1940s was peaceful. This makes many political scientists worried about the rise of China,3 not the least in the Middle East. Chinese new investments for 2017 in Saudi Arabia alone were worth more than US$70 billion. Furthermore, the country finished the construction of a major naval base in Djibouti. Should we be worried? Will China challenge US dominance in this precarious and dangerous region? Will the Chinese rise destroy Pax Americana in the Middle East?

China’s increasingly globalised economic interests has made it more interested in developing its global power. On 7 September 2013, President Xi Jinping initiated an ambitious global infrastructure plan later dubbed “One Belt, One Road”. The plan aims to create a physical infrastructure to support China’s economic interaction with the world. This vast infrastructure project has merged with the development of financial infrastructure that in turn supports the financing of global economic activities crucial for China’s growth.  China has also started ensuring, through military means, that its assets and trade routes are secure. The Chinese “logistics and fast evacuation base” in Djibouti is the first clear example of this tendency.

By competing China will undoubtedly challenge US commercial interests, and its growing financial infrastructure may eventually challenge the dollar’s position as the world’s reserve currency. But how will this affect politics and security? The United States will not intend to disrupt Chinese trading routes or harm Chinese investments.  Chinese security infrastructure is not there to attack US military interests. So, Chinese military installations should not be a direct threat to US security interests or US security order in the Middle East. Will Chinese political power turn US allies against the Pax Americana that harm the US interests in the expansions of democratic peace?

Will China Turn the Middle East Against Pax Americana?

China’s increasing activity in the region may change some of the rules of international relations, but many of the threats in current world politics literature stem from the fallacy of repeating history. The threat of China directly negatively impacting the expansion of the zone of liberal democracies is one of these unwarranted perceived threats.

When the US globalising economic interests in the 1940s required a more active international role, theorists pondered how the enhanced engagement of the US would affect the Pax Britannica. However, US globalising economic role did not require colonial expansion. Therefore, the US wanted to dissociate communism and anti-colonialism so that the anti-colonial popular sentiment would not push the third world into communism. Communist third world was not compatible with US economic interests, as the US needed the third world to engage in liberal economic interaction with the US and the West. History did not repeat itself: the US leadership did not turn out to be similar to the UK leadership.

Today, the world expects China to use its hard and soft power to influence the political system, culture, and world view of developing countries. This was what the US leadership required.

In the most recent presidential speech at the end of the party congress, President Xi Jinping repeated China’s anti-hegemonic stance: “no matter what stage of development it reaches, China will never seek hegemony or engage in expansion.”

China has strong global economic interests and especially its need for energy resources affects its international role. China has vast energy resources on its own, so the share of energy it imports is not particularly high (it was 15% in 2014 according to the World Bank). What makes China dependent on foreign energy, though, is the fact that its economy despite a slowdown is still growing rapidly – and its government is obsessed with continuing on this path. However, a trading partner does not need to be led by a communist party to trade with China. An open liberal state would probably be more open to economic interaction with China. Thus, while the United States needed to control domestic political developments in the world there is no reason why China should need that. Specialists of world politics that think this is necessary, are victims of the fallacy of repeating history.

If we interpret Chinese diplomacy and soft power from this angle, China’s policies seem to make much more sense than if we assume that China wants to repeat the American model of hegemony. The fact that China mainly needs energy resources and markets for its products means that its diplomacy is tuned to convincing the world, and especially energy producers, of the benefits of economic relations with China rather than convincing others of the virtues of Chinese political system. As a result, China has little soft power, that is power to attract, but there is still a generally favourable attitude towards trading with China. On average, China is 17% more popular in oil-exporting countries and 11% less popular in oil-importing countries. Clearly China has selected its friends, and made them willing to trade rather than change their political systems.4

Chinese rejection of intrusive influence into countries’ domestic policies is also in line with China’s policies as an anti-hegemonic power. The Five Principles of Peaceful Coexistence from 1954 emphasised this, while the Principles of Foreign Aid emphasise the same commitment to non-interference. Unlike the expectation of the global media, this has not changed even slightly in the recent years. In the most recent presidential speech at the end of the party congress a few months ago President Xi Jinping repeated China’s anti-hegemonic stance: “no matter what stage of development it reaches, China will never seek hegemony or engage in expansion.” Since China does not need to manipulate Middle Eastern political systems, and since doing so would contradict its international interest and identity, we should not assume Chinese intrusive hegemony in the Middle East. The world has changed, and China is not in the same position against the communist bloc as the United States was. Thus, we should not think China would repeat history and try to turn the Middle East against Pax Americana.

Will China Sabotage the Expansion of the Zone of Liberal Democratic?

Indirectly however, China’s increasing economic role in the Middle East will affect US economic power. China will not join US efforts to democratise the Middle East. Instead it may offer no-strings-attached economic options for the regional autocrats. In fact, this may be the appeal China has in the region. China may be popular exactly because it differs from the United States since it does not set political conditions to its cooperation. As Western critique against Saudi Arabia’s authoritarianism grows, high-profile visits and trade deals between Saudi Arabia and China tend to get more frequent. Could China, then, become a spoiler of Western pro-democracy critique, sanctions and interventions? Could this hamper democratic and peaceful progress in the Middle East and prevent the expansion of the liberal democratic peace there?

Sanctions are more effective in absence of countries that refuse to join them,5 and thus the rejection of interference in domestic politics does reduce the effectiveness of US-led democracy support. However, in a region with a lot of strategic interests, support of democracy has not been effective even without countries that sabotage such efforts. If we look at the post-World War II record of US support of governments, and compare the democracy scores by using Polity IV data, we can see that an average enemy of the United States in Muslim Middle East has been more democratic than an average US ally. Using the same data we can also see that changes towards democracy have more often reduced than increased US support while changes towards autocracy have more often increased than reduced US support.6 Furthermore, US’ military means to fight autocracies and protect civilians have neither helped the region or its democracy. Strong motives related to oil, support of Israel and resistance of communism and Islamism have pushed the interests of democracy to a secondary priority, and this, not Chinese respect of sovereignty of authoritarian states, has sabotaged progress.

China is therefore not a direct threat to Pax Americana in the Middle East. However, by offering an alternative, China may still challenge the American rules of diplomacy in the Middle East.

Counting from the Uppsala Conflict Data Program data on conflict fatalities and Systemic Peace Project’s State Fragility Index data, it is possible to calculate that also military interventions in autocracies have weakened state structures and increased the number of fatalities of conflict and autocratic repression. While democracies have been peaceful with each other, externally forced democratisation has not improved the state of democracy or contributed to liberal democratic peace. Disrespect for national sovereignty of Middle East states has not served the interests of peace or people in the region. The lack of respect for sovereignty of autocratic states has meant that in addition to national autocracy there is now a tendency to international autocracy, where operations are conducted regardless of the preferences of people who are affected by them. This is why not just Middle Eastern despots but ordinary people too, seem to consider relations with the sovereignty-respecting China more beneficial than with the United States. Opinion polls about civilians in countries like Iraq tend to show strong resentment to foreign military presence.7 External threat that ordinary people recognise and fear is one of the most effective ways for autocrats to consolidate their powers. In face of external aggression, there is a perception that the country needs national unity under a strong leader.  Hence, Chinese economic relations with no political strings attached may hamper some democracy-promoting projects in the Middle East, but not the progress of democratic peace itself.

China is therefore not a direct threat to Pax Americana in the Middle East. Its economic needs drive its policies in the region. Those needs do not require the manipulation of other countries. Thus, China is not going to intentionally turn the region against the United States. However, by offering an alternative, China may still challenge the American rules of diplomacy in the Middle East. The region is not used to a very strict adherence to the principles of sovereignty. This may change once China becomes more prominent in the region. Yet, the change of rules may not negatively affect the process towards democratic peace, in fact it may do the opposite. Not offering an external threat to consolidate authoritarian domestic order may be exactly what is needed for the natural process of democratisation and pacification of states.

Featured Image: Iranian President Hassan Rouhani and Chinese President Xi Jinping (R) review troops during a welcoming ceremony in the capital Tehran. Chinese President Xi Jinping arrived on January 22, 2016 in Iran on the third leg of a Middle East tour aimed at boosting economic ties with the region. © AFP

About the Author

Timo Kivimäki is Professor of International Relations, and Director of Research at the Department of Politics, Languages and International Studies at University of Bath. In addition to purely academic work, he has been a frequent consultant to the Finnish, Danish, Dutch, Russian, Chinese, Indonesian and Swedish governments.


References

1. Jia Qingguo and Richard Rosecrance, 2010, “Delicately Poised: Are China and the US Heading for Conflict”, Global Asia 4, no. 4, 72-81.
2. Spain versus Holland in the 16th century, Holland versus England in the 17th century, Britain versus France in both the 18th and 19th centuries, France and Britain versus Germany in the 20th century, Germany versus Russia in 1914, Soviet Union vs. Germany 1941, US vs. Great Britain 1940s, The Soviet Union versus the US 1950-1990.
3. John J. Mearsheimer, 2001, The Tragedy of Great Power Politics. (New York: W.W. Norton).
4. Andrew Kohut, June 23, 2014, “America’s Global Image Remains More Positive than China’s,” Pew Global Attitudes Project, July 18, 2013, http://www.pewglobal.org/2013/07/18/americas-global-image-remains-more-positive-than-chinas/; Timo Kivimäki, “Soft Power and Global Governance with Chinese Characteristics,” The Chinese Journal of International Politics 7, no. 4, 421-47, https://doi.org/10.1093/cjip/pou033.
5. Thomas J. Prusa, 2007, “Economic Sanctions Reconsidered, 3rd Edition, Gary Hufbauer, Jeffrey Schott, Kimberly Elliott, Barbara Oegg. Peterson Institute for International Economics”, September 2008, Journal of International Economics 76, no. 1,135-37, https://doi.org/10.1016/j.jinteco.2008.06.002; Gary C. Hufbauer et al., 2007, Economic Sanctions Reconsidered, Third Edition: Database (Washington D.C.: Peterson Institute for International Economics)
6. Timo Kivimäki, 2012, “Democracy, Autocrats And U.S. Polices”, Middle East Policy XIX, no. 1, 64-71; Timo Kivimäki, July 3, 2013, “The United States and the Arab Spring”, Journal of Human Security 9, no. 1, 15-26.
7. Murtaza Hussain, April 15, 2016, “Young Iraqis Overwhelmingly Consider U.S. Their Enemy, Poll Says”, Global Research, http://www.globalresearch.ca/young-iraqis-overwhelmingly-consider-u-s-their-enemy-poll-says/5520310; Sean Rayment, October 23, 2005, “Secret MoD Poll: Iraqis Supports Attacks on British Troops,” Telegraph, https://www.globalpolicy.org/component/content/article/168/37188.html.

Building Trust in Artificial Intelligence Predictions

By Vyacheslav Polonski and Jane Zavalishina

Whether you like it or not, we will soon all rely on expert recommendations generated by artificial intelligence (AI) systems at work. But out of all the possible options, how can we trust that the AI will choose the best option for us, rather than the one we are most likely to agree with? A whole slew of new applications is now being developed that try to foster more trust in AI recommendations, but what they actually do is training machines to be better liars.

Have you ever wondered what it would be like to collaborate with a robot-colleague at work? With the AI revolution looming on the horizon, it is clear that the rapid advances of machine learning are poised to reshape the workplace. In many ways, you are already relying on AI help today, when you search for something on Google or when you scroll through the Newsfeed on Facebook. Even your fridge and your toothbrush may be already powered by AI.

We have come to trust these invisible algorithms without even attempting to understand how they work. Like electricity, we simply trust that when we turn on the light switch, the lights will go on – no intricate knowledge of atoms, energy or electric circuits is necessary. But when it comes to more complex machine learning systems, there seems to be no shortage of pundits and self-proclaimed experts who have taken a firm stance on AI transparency, demanding that AI systems are first fully understood before they are implemented.

At the same time, big corporations are already eagerly adopting new AI systems to deal with the deluge of data in their business operations. The more data there is to collect and analyse, the more they rely on AI to make better forecasts and choose the best course of action. Some of the most advanced AI systems are already able to make operational decisions that exceed the capacities of human experts. So whether we like it or not, it’s time to get ready for the arrival of our new AI colleagues at work.

The Watson Dilemma

As in any other working relationship, the most essential factor for a successful human-machine collaboration is trust. But given the complexity of machine learning algorithms, how can we be sure that we can rely on the seemingly fail-safe predictions generated by the AI? If all we have is one recommended course of action, with little to no explanation why this course of action is the best of all possible options, who is to say that we should trust it?

This problem is perhaps best illustrated by the case of IBM’s Watson for Oncology programme. Using one of the world’s most powerful supercomputer systems to recommend the best cancer treatment to doctors seemed like an audacious undertaking straight out of sci-fi movies. The AI promised to deliver top-quality recommendations on the treatment of 12 cancers that accounted for 80% of the world’s cases. As of today, over 14,000 patients worldwide have received advice based on the recommendations generated by Watson’s suite of oncology solutions.

However, when doctors first interacted with Watson they found themselves in a rather difficult situation. On the one hand, if Watson provided guidance about a treatment that coincided with their own opinions, physicians did not see much value in Watson’s recommendations. The supercomputer was simply telling them what they already know, and these recommendations did not change the actual treatment. This may have given physicians some peace of mind, providing them with more confidence in their own decisions, but did not result in improved patient survival rates.

On the other hand, if Watson generated a recommendation that contradicted the experts’ opinion, oncologists would conclude that Watson was not competent enough. For example, a Danish hospital reported to have abandoned Watson after discovering that its oncologists disagreed with Watson in over 66% of cases. When doctors disagreed, Watson was not able to explain why its treatment was plausible, nor how the AI programme arrived at its conclusion. Its machine learning algorithms were simply too complex to be fully understood by humans. This caused even more mistrust and disbelief, leading many physicians to ignore the seemingly outlandish AI recommendations and stick to their own expertise in oncology.

A Crisis of Confidence

If Watson generated a recommendation that contradicted the experts’ opinion, oncologists would conclude that Watson was not competent enough.

Despite all the technological advancements, we still seem to deeply lack confidence in AI predictions. This can be explained by a combination of technological and psychological factors: the algorithmic complexity of AI systems, the fear of losing control of a situation and the anxiety of interacting with something we do not understand. This is reinforced by fairly common cognitive biases, such as confirmation bias and the somewhat irrational belief in human superiority over machines.

Usually, building trust with human co-workers implies repeated interactions that help us better understand our colleagues. For thousands of years, humans worked with each other through explanation and mutual understanding. If we can understand how the others think, we can form reasonable expectations about what they are going to do next. This understanding typically facilitates a psychological feeling of safety, resulting in a more open and collaborative work culture.

By contrast, when a supercomputer like IBM Watson produces a recommendation, this outcome is typically based on thousands of weak signals in the data and their interactions. In theory, there might be a detailed explanation, but it is often too difficult for humans to trace back. Even trivial AI recommender systems face the same problem, because they tend to provide recommendations out of a “black-box”. Too often, it is difficult to convey to human collaborators that the machine has learned the right lessons without being explicitly programmed to do so. As such, the complexity of AI decisions continues to challenge the human mind, provoking more scepticism and mistrust.

In Machines We Trust?

If AI is to live up to its full potential, we have to find a way to get people to trust it, particularly if it produces recommendations that radically differ from what we are normally used to.

There are two ways out of this crisis of confidence. The first one is more scientific: rigorous trials, experiments and measurements of outcomes that are causally linked to the new AI systems. This approach is widely used in applications, ranging from digital marketing to industrial production. But in many cases the costs of this approach are too high both in monetary and ethical terms, e.g. when expensive equipment is involved or when human life is at risk. As a case in point, when IBM Watson suggests a new oncology treatment, its recommendations need to be heavily scrutinised. This involves recruiting patients, testing of results and the publication of studies in peer-reviewed scientific journals. It is easy to see that this approach may not be always feasible, especially in the context of time-sensitive medical decisions.

The other approach to building trust and confidence in machine predictions is through post-hoc explanation. In addition to the primary optimisation function, a secondary algorithm is implemented that generates detailed explanations of what is going on inside the machine, akin to a translator from machine speak to human speak. For example, the fintech “unicorn” Stripe uses this technique to make customers trust its anti-fraud decisions that are made by machine learning algorithms. Similarly, the political technology start-up Avantgarde Analytics has recently begun implementing machine learning algorithms to target campaign messages to potential voters. In the interest of transparency, a secondary algorithm is tasked to provide detailed explanations to voters on how their data is being used during the election campaign.

The Machiavellian Machine

Another AI company, SalesPredict, went one step further by asking: can we generate not just any explanation, but the most effective explanation? As early as 2014, they developed a recommender system for sales lead scoring that used machine learning to optimise for the plausibility of an AI explanation. In this case, the machine was instructed to optimise for the likelihood of its recommendation being accepted by a human collaborator. Using reinforcement learning techniques, the AI considered people’s emotional perceptions and evolved the way it communicated its recommendations. If the human operator first rejects an AI recommendation, the machine will try again to come up with something that makes more sense to the human. In other words, the AI tries to design a more persuasive explanation for its human colleagues – regardless of what is actually going on inside the model. As Chief Data Scientist of SalesPredict writes, it was about getting the user excited, rather than producing the most accurate prediction.

By teaching the AI to identify a persuasive and plausible human-friendly explanation, we are essentially teaching the machine to be a better liar. And this is especially problematic if the machine is built on notions of social influence and irrational decision-making from behavioural psychology.

Even though this “workaround” works well in some contexts, it could result in some unintended social consequences. In particular, the danger of this approach is that by teaching the AI to identify a persuasive and plausible human-friendly explanation, we are essentially teaching the machine to be a better liar. And this is especially problematic if the machine is built on notions of social influence and irrational decision-making from behavioural psychology.

Since the machine optimises for the probability of a solution being accepted by a human collaborator, it may prioritise what we want to hear over what we need to hear. This could produce overly simplified, human-digestible predictions that tend to forego potential gains in productivity. Just think about what happened when a Wired editor decided to like everything in his Facebook Newsfeed; after two days, the algorithm prioritised clickbait content until his feed consisted exclusively of cat videos and BuzzFeed lists.

There is a clear trade-off between AI explainability and efficiency that taps into a deepening sense of disquiet. Pushing for more human-friendly AI solutions might just as well mean making the AI less efficient and more insincere. In other words, instead of asking “how can I find the most accurate and fair solution to this problem”, the machine could ask: “what do I need to say to make the human believe me?” Taken to its logical conclusion, what we have might have accomplished here is building the next generation of supercomputers that are trained to expertly manipulate humans in the rush to gain acceptance and plausibility.

An Algorithmic Leap of Faith

People have always been mistrustful of new technologies. But history shows that even the biggest sceptics eventually concede and get used to new technological realities. For example, in the early days of automobiles, British policy-makers introduced the Red Flag Act. This act required cars to be accompanied by three people, and at least one of them was supposed to wave a red flag in front of the car at all times. Of course, this act
undermined the advantages of using an automobile in the most fundamental way. But society simply did not trust these “horseless carriages” enough to allow them on the roads without these additional safety precautions.

The Red Flag Act was repealed 30 years later; not because automobiles became significantly safer in 1896, but simply because people got used to them. The crippling anxiety faded away and there was a collective desire to take advantage of all the benefits of driving a car. As history shows, moral panics are frequently followed by a more pragmatic approach to technology.

There are notable parallels here for the regulation of AI. Advantages offered by advances in machine learning will eventually outweigh the initial scepticism about its implementation. But if regulators continue to stubbornly press for more AI explainability, they could undermine the very potential of machine learning, akin to a new Red Flag Act for AI. In turn, the increased public scrutiny of algorithms would put the heat on developers to create more manipulative AI systems that produce plausible but misleading explanations at scale.

Obviously, this is not exactly the best starting point for a good working relationship between humans and machines. It takes a giant leap of faith to allow machines that are smarter than us into our lives; to welcome them into a realm of work historically led by humans; to allow them to shape our decisions and everyday experiences. In this future, trust is the most essential ingredient in virtually every type of human-machine collaboration.

The bad news is that it only takes one Machiavellian machine to shatter the foundation of trust. But the good news is that we can build more confidence in machine predictions if we learn from past mistakes, conduct proper experiments and judge AI systems fairly by the results they produce, rather than the explanations they come up with.

About the Authors

Dr. Vyacheslav Polonski is a researcher at the University of Oxford and a member of the World Economic Forum Expert Network. He is also the founder and CEO of Avantgarde Analytics, a machine learning startup specialising in algorithmic campaigning. He holds a PhD in computational social science and is a frequent speaker at international conferences on AI accountability and governance.

Jane Zavalishina is the CEO of Yandex Data Factory – an industrial AI company belonging to Yandex, one of Europe’s largest internet companies. Jane is a regular voice at international events on AI-related topics. She also serves on the World Economic Forum’s Global Future Councils. Jane was recently named in Silicon Republic’s Top 40 Women in Tech as an Inspiring Leader.

Digitisation asks Fundamental Questions of the Accountancy Sector

By Ben Laker

Estimated at $23 billion, the Digital transformation market is growing rapidly across the globe, with 23 percent of activity residing in the UK, 21 percent in Australia and 20 percent in the US.

According to Source Global Research $5 billion of the $23 is serviced by the Big Four consulting firms, who together hold 21 percent of the market. 12 percent is captured by Deloitte, the current market leader who conclude that “strategy, not technology, drives digital transformation”. This view challenges widely held consensus, but supporting research within the MIT Sloan Management Review and Deloitte digital business study suggests that the strength of digital technologies – social, mobile, analytics and cloud – doesn’t lie in the technologies individually. Instead, it stems from how companies integrate them to transform their businesses and how they work, a finding consistent with our own research. New capabilities make new solutions possible, and needed solutions stimulate demand for new capabilities, for as Capgemini Consulting suggest, all sectors are urgently required to “unleash the transformation potential offered by digital innovation”. Yet despite this, many sectors remain somewhat lethargic to change. One sector in particular is accounting, of whom digitisation asks three fundamental questions.

When will robots be doing our taxes?

Currently, the sector is subject to pressure on margins as customers are being guided by the likes of HMRC to take advantage of simplified and streamlined ways of collecting and submitting accounting data. Other customers are taking advantage of cloud based solutions and undertaking many routine accounting activities in advance of invoking the service of their accountants. This means that many of the traditional accounting services are being automated or undertaken as part of “customer self-service”. As a result and from the audit firm’s perspective many routine tasks are being simplified and rationalised and these process improvements are being passed on to the end customer due to the service becoming more and more commoditised. This perspective is executed against an ever increasing requirement and expectation of quality and integrity of opinion – which essentially means everyone wants it done cheaper, but with more accountability on the shoulders of accountants.

It is this accountability which according to Vasant Dhar, professor at the Stern School of Business, means that robots are indeed coming close to the audit process. They provide the only solution to meet a growing expectancy of integrity of opinion. Humans are likely to get more and more comfortable with machines helping with taxes explains professor Dhar. “Eventually, many of us will trust them enough to compose the entire return for us to sign.”

What value added services are accountants developing?

The rise of automation and added competition in the accounting industry is creating pressures to compete for business using pricing alone. However, this is a losing proposition. Firms looking to compete on price require more clients in order to cover costs, leaving accountants less time per client to provide quality services that can retain existing clients, generate better margins and reduce the immense pressure to add clients.

As a result, the accounting profession looks to focus on other “added-value” services to compensate for the decreasing revenue streams from traditional service offerings. This will drive a cart and horse through traditional model of the accounting industry as they will need to consider other ways of adding value and creating new revenue streams. As a result many firms will transition from typical compliance-related work, such as taxes, payroll and general bookkeeping, defined as Type 1 services.

The future lies in Type 2 services, which provide opportunities to deepen existing relationships through upselling, or selling more expensive versions of existing services, and through cross-selling, or providing new services to existing clients. However, this type of activity requires a complete change of beliefs, and this leads to a third question, more fundamental than the previous:

What beliefs held by the accountancy profession should change?

Our recent research study across the spectrum of performance comprised of 20,000 hours of analyses and interviews with thousands of employees from organisations including Deloitte and PwC. We conclude that the secret code behind consistent, high-level success in sales is the beliefs held, not behaviours demonstrated.

We conclude that the secret code behind consistent, high-level success in sales is the beliefs held, not behaviours demonstrated.

As we believe, so we will behave. Beliefs are at our very core, and in order to behave in a way that leads to step change, accountants need to radically shift their thinking. Re-education processes exist for the traditional audit partner who will see their role and revenue streams change. However, traditional training and development programmes focus on behaviours, not beliefs. This means that the focus is on the symptom, not the route cause. As such, audit partners will waste their time and firm resources, and not leverage Type 2 service opportunities.

Only training and development that focus on beliefs will lead to a change in mindset as well as a potential change in capability, and the way in which they interface with their clients. Beliefs provide us with the motivation to deploy certain talents or skills. They may promote or inhibit certain behaviours. And they have a major impact upon our sense of self, of who we are, and why we do what we do. It was Sir Winston Churchill who said, “To improve is to change. To be perfect is to change often.” We may not ever be perfect, but we can believe that it’s good to try. If we hold this belief, we are prepared to accept that the way we have done things in the past may not be what leads us to future success. We are also accepting the premise that change is good. Who knows, we might even become better than we ever thought possible. As someone else said, “It’s only failure if you stop trying.”

This article includes insights from The Sales Persons Secret Code (LID, 2017), a global study into how salespeople behave and driven, which reveals the secret code behind consistent and high-level success. Based on 20,000 hours of research, this book is for any sales professional, or indeed anyone involved in the sales process of their company, who wants to learn the secrets of successful selling. www.salespersons-secret-code.com

About the Author

Ben Laker is Leader of the Analytics Practice at Transform Performance International. Ben helps Fortune 500 firms including Apple, American Express, Cisco, Dow Chemical and Liberty Global to do more, more quickly with more certainty using machine learning and big data derived from world-class research. A Harvard Business Review contributor and prolific author of thought-leadership, his insights are published by Forbes, The New York Times and The Economist among others.


Notes

1. https://www.capgemini-consulting.com/technology-transformation
2. https://www.wired.com/2017/02/robots-will-soon-taxes-bye-bye-accounting-jobs/
3. https://dupress.deloitte.com/dup-us-en/topics/digital-transformation/digital-transformation-strategy-digitally-mature.html

Meghan Markle Marriage to Prince Harry Proves US Taxes Can Be a Royal Pain

wedding of prince and meghan markle

By Robert W. Wood         

Worldwide, the IRS can create a degree of uneasiness for nearly anyone who has any US connections. Apple, Google and other tech giants may famously have billions in untaxed profits sitting offshore. But individuals who are American citizens or permanent US residents (holding green cards) must still report their worldwide income to the IRS. For them, offshore does not mean untaxed.

Plus, if you hold a green card, you are conclusively presumed to be a US resident taxpayer who must report worldwide income, even if you only occasionally visit the US.  Even entirely foreign individuals and companies that have any US source income must report to the IRS. And reporting can mean audits, statutes of limitation, and worry. In short, nearly everyone, it seems, has some fears about the IRS.

Even if you are rich and famous – and perhaps even if you are royal – you may need to be constantly alert for tax missteps. The anticipated nuptials of American actress Meghan Markle and British Prince Harry seem like a fairy tale that can bring a smile to almost everyone. Leave it to complex US tax laws to spoil it with tax problems.

The taxes at stake could be huge. Buckingham Palace has announced that Markle will become a British citizen after marriage. Yet tax lawyers are the first to point out that Meghan Markle’s US citizenship could cause major tax headaches for Britain’s royal family.

Taxes and Asset Disclosures

After all, unless she renounces her American citizenship, no matter where she lives, she will have to continue filing US tax returns, plus the Foreign Bank Account Reporting forms known as FBARs, every year. Even if all of her income is earned in the UK (with all taxes paid in the UK), that doesn’t matter. She must still report her worldwide income to the IRS.

Perhaps even worse, she must keep disclosing her non-US assets too. As a new member of the Royal Family, that could become a sticky wicket for Britain. One can just imagine that the IRS could be rubbing its institutional hands together with anticipation just thinking about that tax audit.

It isn’t just income that the IRS wants to know about. It’s assets too, maybe even some royal ones.

Many a dual country couple innocently starts filing US taxes together, and that can be a very costly mistake. Year in and year out, 95 percent of married couples file joint tax returns, often as a knee-jerk reaction. Yet that simple step makes each spouse liable for everything on the return – and anything that might not be on the return.

Markle will surely be advised to file taxes separately. Thus, Prince Harry will surely, therefore, not be caught within the US tax net. But if they have children, what about all of them viz. the IRS? If they are born as dual US and UK citizens, they could have big tax problems too.

Of course, taxes are only part of the problem. The disclosures in this case might be as bad. It isn’t just income that the IRS wants to know about. It’s assets too, maybe even some royal ones.

FATCA

FATCA, the Foreign Account Tax Compliance Act, is a uniquely American law. It was passed in 2010, and is now ramped up worldwide. It requires an annual Form 8938 filing with the IRS that could end up involving royal assets.

FATCA spans the globe with an unparalleled network of reporting. America requires foreign banks and governments to hand over secret bank data about depositors. Non-US banks and financial institutions around the world must reveal American account details or risk big penalties.

Markle may well follow London’s former Mayor, Boris Johnson, now Britain’s Foreign Secretary. Having been born in New York but raised in Britain, Johnson was a dual citizen of the US and UK But he had a well-publicised run-in with the IRS over a London home sale. The sale proceeds were tax-exempt in the UK, but they were taxable in the US, despite the fact that then Mayor Boris had not lived in the US for decades. The ensuing tax bill eventually led him to renounce his American citizenship.

Renouncing citizenship is clearly trending. The number of renunciations for the first quarter of 2017 was 1,313. The second quarter’s list went up to 1,759, the second highest quarterly number ever. The total for calendar 2016 was 5,411, while 2015 had 4,279 published expatriates. Despite the official list, many who leave are not counted, although both the IRS and FBI track Americans who renounce.

Expats have clamored for tax relief for years. Even if you are not royal, America’s global income tax compliance and disclosure laws can be a burden, especially for US persons living abroad. Many foreign banks do not want American account holders.

Americans living and working in foreign countries must generally report and pay tax where they live. But they must also continue to file taxes in the US, where reporting is based on their worldwide income. A foreign tax credit often does not eliminate double taxes. Annual foreign bank account reports called FBARs carry big civil and even criminal penalties. The civil penalties alone can consume the entire balance of an account.

Expensive Exit

Ironically, even leaving America can be costly. America charges $2,350 to hand in your passport, a fee that is more than twenty times the average of other high-income countries. The US hiked the fee to renounce by 422 percent, as previously there was a $450 fee to renounce, and no fee to relinquish. Now, there is a $2,350 fee either way.

The State Department said raising the fee was about demand and paperwork. Perhaps, but in any case, the number of American expatriations kept increasing. Moreover, to exit, one generally must prove 5 years of IRS tax compliance. And getting into IRS compliance can be expensive, and worrisome.

There is a certain Kafkaesque air to it all. For some, a reason to get into compliance is to renounce, which itself can be expensive. Apart from all of the compliance costs, the US also has an exit tax on renouncing. If you have a net worth greater than $2 million, or have average annual net income tax for the 5 previous years of $162,000 or more, you can pay an exit tax.

It is a capital gain tax, calculated as if you sold your property when you left. It isn’t just for US citizens. A long-term (8 year) resident giving up a Green Card can be required to pay the exit tax too. Sometimes, planning and valuations can reduce or eliminate the tax. Even so, the tax worries can be real, even for those who will not face it.

Mistakes v. Willfulness

To be sure, Ms. Markle and Prince Harry surely have an elite cadre of tax advisers. In that sense, tax missteps from this soon to be royal pair seem unlikely. But many others are not so lucky and may make material and often innocent mistakes. Under US tax law, some mistakes can be forgiven.

However, some errors clearly are not forgivable, and it can be surprising how the criteria are applied. You may believe your inadvertence was non-wilful, but the IRS may not agree. And with FATCA and over 50,000 voluntary disclosures on offshore banking and financial arrangements that name names, the IRS has a treasure trove of data.

Taxpayers should consider their facts carefully, and get some advice about their own circumstances.

If you knew you were supposed to accurately report to the IRS and you failed, the IRS may say you were “wilful”. That legal term can mean large civil penalties or even potential criminal liability. What’s more, the IRS and prosecutors use a concept of “wilful blindness”.

Essentially, willful blindness involves a conscious effort to avoid learning about the IRS income tax rules or about FBAR reporting. Willfulness involves a voluntary, intentional violation of a known legal duty. In taxes, it applies for civil and to criminal violations. The failure to learn of filing requirements, coupled with efforts to conceal the facts, can spell willfulness. Watch out for conduct meant to conceal, such as:

  • Setting up trusts or corporations to hide your ownership.
  • Filing some tax forms and not others.
  • Keeping two sets of books.
  • Telling your bank not to send statements.
  • Using code words over the phone.
  • Cash deposits and cash withdrawals.
  • Moving money from one bank to another when banks don’t want undisclosed American accounts.

Even if you can explain one failure to comply, repeated failures can morph conduct from inadvertent neglect into reckless or even deliberate disregard of the rules. Taxpayers should consider their facts carefully, and get some advice about their own circumstances. Is all of this worry enough to dampen a Royal marriage?

Surely Meghan Markle and Prince Harry will navigate the US tax morass deftly. And their marriage is still a nice story. But for many people caught within the US tax and disclosure net, it can be hard to get to a fairly-tale ending.

Photograph by Matt Dunham / AP

About the Author

Robert W. Wood is a tax lawyer representing clients worldwide from offices at Wood LLP, in San Francisco (www.WoodLLP.com). He is the author of numerous tax books, and writes frequently about taxes for Forbes.com, Tax Notes, and other publications. This discussion is not intended as legal advice.

A Review of Central Bankers at the End of Their Rope By Dr. Jack Rasmus

Close-up Of Businessman Examining Coins With Magnifier On Desk

By Lawrence Souza


Introduction

If you talk to some monetary, fiscal, macroeconomic, and financial institutional and capital market economists, some would argue that Central Banks are at the end of their rope; have lost their credibility and risk losing their independence.

Dr. Jack Rasmus book, Central Bankers at the End of Their Rope? Monetary Policy and the Coming Depression is the latest in a growing literature building the case against the U.S. Federal Reserve (the Central Bank of Central Banks), European Central Bank, Japanese Central Bank, The Bank of England, People’s Bank of China, etc.; their unorthodox monetary policy response to the financial crisis; policy response to asset price bubbles, financial (market) crisis (crashes), and recessions since 1995; lack of macro-prudential supervision and oversight; and consistent policy mistakes based on their lack of understanding of how the world and economy really works, dates back as far as 1929 (See supporting Literature in the Appendix).

In Dr. Rasmus book, he looks at:

1. Problems and Contradictions of Central Banking

2. A Brief History of Central Banking

3. The U.S. Federal Reserve Bank: Origins and Toxic Legacies

4. Greenspan’s Bank: The Typhon Monster Released

5. Bernanke’s Bank: Greenspan’s Put (Option) on Steroids

6. The Bank of Japan: Harbinger of Things That Came

7. The European Central Bank under German Hegemony

8. The Bank of England’s Last Hurrah: From QE to BREXIT

9. The People’s Bank of China Chases Its Shadows

10. Yellen’s Bank: From Taper Tantrums to Trump Trade

11. Why Central Banks Fail

12. Revolutionising Central Banking in the Public Interest: Embedding Change Via Constitutional Amendment

Dr. Rasmus builds a methodical case against historical and current central bank ideologies and orthodoxy; and makes prudent and wise recommendations for structural and institutional macroeconomic, monetary policy and political change.

The conclusion, it’s not too late to address the systemic and systematic risks to central banking, regulation and supervision, financial institutions and capital markets, and the real economy and labor markets.

However, considering the real economic realities of the current political, party and policy environment, along with Wall Street’s control over monetary (Federal Reserve), fiscal (Treasury) and regulatory (Comptroller/SEC/FDIC/etc.) policy in Washington, that a political solution could actually be accomplished. Dr. Rasmus is correct in his recommendations and his analysis.

We are all at the end of our rope, and thank you Dr. Jack Rasmus for bringing another critical analysis of the current and future state of global central banking, and for proposing bold policy recommendations to avert another severe financial crisis, great recession and depression.


REVIEW

Rapid technological, demographic, economic, cultural, sociological and political change has changed the way central banks analyse, manage and respond to business cycle peaks, troughs (recessions), financial crisis, and macro-prudential bank supervision; and central bank policy responses have failed consistently over time, due to limitations of their data, models, ideology, epistemology, bureaucracy, and politics.

But one modern response to these limitations has been consistent over time, inject or try to inject massive amounts (trillions of U.S. Dollars, Yen, Euros, Pounds, Yuan, Peso, Rubble, etc.) of liquidity (credit) to back-stop and set a support under asset prices. Since these asset price bubbles and asset price collapse (financial/currency crisis) have become more frequent since 1995 (Peso Crisis, Thai Baht, Russian Default, Y2K/911, Housing Bubble, Financial Crisis, etc.), global central bankers do not have the intellect, culture, knowledge, data, models, tools, resources, balance sheet, etc. to deal with crisis going forward.

Dr. Rasmus recommends limiting the independence (ad hoc decision making) of central banks by instituting a (rules based) Constitutional Amendment defining new functions for the central bank, new monetary targets and tools to modernise and drive global central banks into the 21st century.


Problems and Contradictions of Central Banking

In response to these economic and financial disruptions, central banks have responded consistently by injecting massive amounts of liquidity into the system with no limitations.

Globalisation, technologicalisation and deregulation/integration have accelerated capital flows and accumulation, and concentration to targeted and non-targeted markets across the world. This process continues at a rapid pace, and depending on the recipient, can be economically, financially and politically (institutionally) destabilising, destructive and deconstructive. It is not a matter if this will happen, but when, again! Which country, industry, company, and demographic will be affected, disrupted, destroyed and wrecked.

In response to these economic and financial disruptions, central banks have responded consistently by injecting massive amounts of liquidity into the system, with no limitations due to their misunderstanding of how the economic and financial system really works. Through the use of unorthodox monetary policy tools and targets, in the face of total deregulation and free flow of capital (shadow banking and derivatives trading), central banks are at this point where they cannot control or manage the system. We are in unchartered territory.

Only to bail it out, the private banking system – other strategic affiliated institutions, corporations, businesses and brokerages – again and again, by printing massive amounts of fiat currency (seigniorage), to buy (defective/defaulted) securities product (derivatives), accumulate more sovereign-corporate-personal debt, with even more crowding out effects, has had no real eventual long-term impacts on real economic growth, wages, and productivity; and social welfare or standards of living.  Only asset prices bubbles and a massive redistribution and concentration of wealth.

It is estimated, between the U.S. Federal Reserve Bank, Bank of England, and European Central Bank, $15 trillion direct liquidity injections, loans, guarantees, tax reductions, direct subsidies, etc. have been used. If you add in China and Japan, the total gets to as high as $25 trillion, and if you add in other emerging country (Asian, Latin America, and Middle-East) central banks, the total gets as high $40 trillion.

This is only the present value (cost basis), if you project the total cost (interest and principal payments) out over a 30 to 40 year period, the estimate total cost is as high as $80 to $100 trillion. Thereby, making the global financial and economic system eventually insolvent and bankrupt, and central banking ineffective and perpetually in a liquidity trap, as the velocity of money has collapsed. There is no real money going into real long-term (capital budgets) assets, only short-term  financial assets.

This is the contradiction of Central Banking: liquidity-debt-insolvency nexus, the moral (immoral) hazard of perpetual bail-outs, growing concentration of wealth at the extremes, growing perception that Negative/Zero Interest Rate Policy (N/ZIRP) can fix under-investment in capital (human/physical) and deflationary (disinflationary) trends, and that bank regulation-supervision is bad for the economy, financial services (institutions) industry, and for institutional and retail investors (savers) in the long run.


A Brief History of Central Banking

A Brief History of Central Banking, walks us through the origins of central banking, from the Bank of England (1694) as the lender of last resort for private banks, and its monopoly position in issuing government bank notes and currency (1844/1870s), and bailing out the banking system due to crashes and development of new types of currencies (paper, gold, notes, etc.).

An uncontrolled growth in the money supply in the U.S. led to financial speculation in gold and bonds (1830), and depression (1837-43). No central bank was established, not even after banking crashes (1870/1890s/1907-08), but only by 1914 as the U.S. entered WWI, and needed to decouple its currency from gold, raise tax revenues, and be able to monetise its sovereign debt through the use of a fractional reserve banking system, did the government then decide that they needed a central bank.

The role of the central banks were to maintain monopoly control over the production of money, act as a lender of last resort and fund raising agents, provide a clearing-payment services system between banks, and supervise bank behavior.

The goal, was price stability, supply of money growth targets, full employment, interest rate and currency exchange rate determination. They were to do this though the use of tools (rules): reserve requirements, discount rates, and Open Market Operations (OMO); and now, Quantitative Easing (QE)/Tightening (QT) and special auctions and re-purchase agreements.

The U.S. Federal Reserve Bank(s) was also given this monopoly position, along with tools and independence. This has led to some toxic legacies (credibility issues).


The U.S. Federal Reserve Bank: Origins and Toxic Legacies

The U.S. Federal Reserve Bank system was originated from a consortium of private banks looking to centralise the Federal Reserve System: JP Morgan, Kuhn, Loeb, Chase, Bankers Trust, First National, etc.  Particularly after financial instability (illiquidity/capital/reserves), bank crashes (lack of supervision) –  1890s/1907, and the rise of the U.S. as a global economic power.

Congress passed the Federal Reserve Act on December 13th 1913: twelve district banks and national board located in Washington D.C. The real power resided in the member banks that owned their respective districts. They could issue their own currency and notes, exchange for gold and foreign currency, invest in agricultural and industrial loans, and received dividends from earnings.

After the Great Depression and bank reform acts (1933/1935), the Federal Reserve Board of Governors and the Open Market Committee became the two powerful institutions within the Federal Reserve System.

The continual mismanagement, ideological mistakes, and lack of understanding of how the real world works, was witnessed again under Bernanke, now Yellen, and who knows who is next.

However, the Fed experienced two decades of failure (1913-1933) due to lack of supervision, stock market and loan speculation, asset price bubbles/crashes, depressions, bank closures and bailouts, excessive extension of liquidity (margin), protection of government finance and wealthy investors, hyperinflation (deflation/disinflation), false targets (gold peg/production/employment), inaction and incompetence (discount rate/open market operations), institutional narcissism and egotism, power and elitism, bureaucratic control, etc.

Bank acts were put in place by Roosevelt, and other regulation and operations were put in place through the 1970s and 1980s: Glass-Stegall, 1935 Bank Act, Reg U, tax reform, policy, Treasury-Fed Accord, Operation Twist, Bretton Woods, Humphrey-Hawkins/Resolution 133, fighting hyperinflation-stagflation-recessions, Reg D, Plaza Accords, state and shadow bank regulatory efforts, international banking (currency/note) issues, liquidity escalations, and eventually the Greenspan typhon.

From 1913 to 1933, the two decades of failure after the Federal Reserve was created; it continued into the 1940s-1950s, 1960s-1970s, 1980s-1990s, 1990s-2000s, it continued and continues to this day, and looks like it will continue into the future.


Greenspan’s Bank: The Typhon Monster Released

Greenspan, influenced by Ian Rand – liberal-post-modern philosophy – set in motion an un-orthodoxy in Federal Reserve, Monetary Policy, and Macro/Political Economic rationalisation, a stark contrast to the Volker era. Greenspan believed in markets, and lase fair-free hand economic ideology (deregulation); and did not believe in limits to the Market and Technology-Labor Productivity, limits to the Federal Reserve’s power to dictate markets and the economy, and limits – in the end – to the ability to inject massive amounts of liquidity into the financial system to drive (support) asset price bubbles. This belief, or lack of, lead to multiple crisis and bailouts of the system.

The continual mismanagement, ideological mistakes, and lack of understanding of how the real world works, was witnessed again under Bernanke, now Yellen, and who knows who is next (Powell)?


Bernanke’s Bank: Greenspan’s Put on Steroids

Bernanke was minted from the same Greenspan mold, a true believer that excessive liquidity injections cold solve massive capital market and economic failures with little cost. It was the financial crisis and the coordinated efforts between the Federal Reserve and the Treasury (and other hidden interests), that was the test case in the Federal Reserve ability to manage severe man-made financial-economic crisis. The result, a new nationalisation-corporatist-financial oligopoly industrial model, leveraged through Zero Interest Rate Policy (ZIRP)/Negative Real Interest Rate Policy (NRIRP), Quantitative Easing (QE), and Credit Enhancements/Liquidity Injections.

However, the outcomes from these efforts were disastrous:

1. Political Populism (Political-Economic Institutional Deconstruction/Destruction)

2. Massive Capital-Labor Substitution (Productivity Lag)

3. Massive Concentrations of Wealth (Inter-Generational Wealth Transfer)

4. Flat-Declining Real Wages (Social Welfare/Standards of Living/Poverty)

5. Unfunded Pension Liabilities (Crisis)

6. Recession(s) Twice as Deep/Twice as Long (Structural)

7. Rising Un-Funded Pension Liabilities

8. Collapse in Labor Participation Rates (High Under-Employment)

9. Collapse in Velocity of Money (Currency Turnover)

10. Rise of Shadow (Unregulated) Banking System (Disintermediation)

11. Massive Use-Trading of Un-Collateralised (Over-The-Counter/OTC) Derivative Trading

12. Excessive Use of Financial Engineering to Support Asset Prices

13. Global Economic-Political Instability (Global Cyber-Cold War)

14. Global Hyper-Inflation/Banking Crisis/Credit Defaults (Sovereign)

15. Massive Over-Leveraging of Government, Corporate and Personal Balance Sheets

16. Over Accommodative Monetary/Fiscal Policy (Negative Nominal/Real Interest Rates/Change Accounting Rules/Low Effective Tax Rates)

17. Global Tax Evasion (Avoidance)

18. Ballooning of the Federal Reserve Balance Sheet (Bonds/Reserves)

19. Ballooning of the Federal Budget Deficit and Debt ($500-800 Billion Per Year/+$20 Trillion)

20. Continuous Belief in Supply Side Economics (Trickle Down Theory/Deregulation)

21. Continuous Belief in Monetary System/Real Economy Aggregates (Inflation/Interest)

22. Continuous Bail-Outs of Financial/Economic System (Insolvency/Bankruptcy)

23. Etc. Etc. Etc.

All of these beliefs, techniques and tools have been used by other Global Central Governments and Banks (BOJ/ECB/BOE/PBOC), with similar, disastrous, and disappointing outcomes. A focus is on saving the financial institutional system in the short-run, using extreme and un-orthodox monetary policies (tools), with a lack of concern or understanding of long-run economic, social, cultural, and political consequences and outcomes.

A perfect example, are policy responses of the Bank of Japan (BOJ).


The Bank of Japan (BOJ): Harbinger of Things That Came

Over the last 17 years (1990 – 2017) the BOJ has implemented an aggressive form of unorthodox monetary policy (Negative – Nominal/Real – Interest Rate Policy/Quantitative Easing): printing massive amounts of money, buying massive amounts of sovereign-corporate (infrastructure) bonds, driving bonds yields negative, and driving domestic investors/savers and financial institutions literally crazy.

With no real effect on the Real Business Cycle (RBC), resulting in perpetual recessions and disinflation/deflation. These unorthodox monetary policies (mistakes/failures) have had the effect of causing asset price bubbles/busts (banking crisis), negative effects on standards of living, and negative effects on financial (dis)intermediation and fiscal policy (mistakes).

The BOJ has responded to these failures by introducing more accommodative (QE) policies, along with over accommodative fiscal policies (sovereign debt levels at historical levels) with no real positive effects. Fiscal policy mistakes (tax increases in a recession), have only exacerbated economic outcomes.

Japan will be the ultimate experiment in monetary-fiscal policy mistakes, as they will have to resort to even more extreme measures to try to get themselves out of their existential structural crisis. The ultimate fiscal-monetary response could be, with unintended political-economic-cultural consequences, associated with a massive and coordinated debt forgiveness, by both fiscal/monetary authorities.

At some point they will not have the tax revenues to service the sovereign debt payments, and will theoretically fall into default, and will ask for forgiveness, not from bond holders, but from the BOJ, that owns the majority of the debt.

Monkey see, monkey do. The BOJ has set the (bad) model for other central banks to follow, not only the U.S., but also the European Central Bank (ECB).


The European Central Bank (ECB) under German Hegemony

Years after the financial crisis, the ECB finally started the process of cleaning up its banking system, and started an aggressive process of Quantitative Easing (QE), introduction of other unorthodox policies (Refinance Options/Covered Bond Purchase/Securities Markets, etc.), and drove nominal interest rates negative as far out as 10 year maturities; negative; with a limited effect of driving down the value of the Euro to stimulate exports, economic growth, and hit inflation and unemployment targets.

The actual ECB structure (dominated by Germany – Bundesbank) was a major impediment to its ability to respond to the crisis: austerity, inability to devalue the Euro, fear of hyper-inflationary trends, and misspecification of monetary policy targets: inflation, productivity, employment, wages, and exchange rates.

Poor performance (contagion), bank crisis (runs on banks), social unrest (populism), massive debt issuance, and deflation (liquidity trap/collapse of money velocity) was the costly (stagnation) result of these policy mistakes. This – along with their lack and hesitant response to bank runs in Spain-Greece-other EU countries – has had a negative impact on the central bank’s independence and credibility, in regards to their ability to respond to future financial and economic crisis.

When the ECB was dealing with the aftermath of the financial crisis, the Bank of England (BOE) across the pond, was trying to immunise itself from the global crisis and its aftermath, only to vote itself into another existential crisis of national identity (BREXIT from the European Union), with long-term economic consequences, testing the limitation of the BOE.


The Bank of England’s (BOE) Last Hurrah: From QE to BREXIT

The Bank of England (BOE) was founded in 1694, the first central bank, and in 1844 under the Bank Charter Act, was given independent monopoly control over bank notes and currency, money supply, bank supervision, lending of last resort, and fiscal government bond-placement agency. By the 1990s, monetarism took hold and the main target was inflation (price stability), and the Monetary Policy Committee was established to conduct open market operations, set interest rates, and reserve requirements.

Globalisation, and having London as the center of money center global trading – currency, credit and interest rate derivatives and floating rate Euro notes and bonds – created excessive liquidity/credit and asset price bubbles, particularly in the U.S. commercial property markets from 2004-2007, eventually led and met with an asset price (housing/mortgage/RMBS/CMBS/equity) bubble and banking collapse (insolvency/QE, nationalisation, etc.), similar to the other industrialised economies.

The total cost of these QE (negative real and nominal interest rates) programs, in addition to other credit facility programs, is well over a trillion pounds, with no real ability to achieve their inflation, Gross Domestic Product (GDP), or employment/labor participation targets. The global push toward deregulation (giving Wall Street back its ability to lever up and take down the system, again) and BREXIT, is certainly making the BOE’s job of conducting monetary policy problematic, leading to policy ineffectiveness (failure), lack of credibility and jeopardising its independence.

These events, have contributed to the significant devaluation of the pound; yes, making U.K. exports cheaper, stimulating export growth as a contribution to GDP; but has caused political-populous parliamentary uncertainty and economic stagnation (high deficits/debt levels); and import price inflation, pushing down consumer purchasing power, standards of living and social welfare in the short and long run.

The big worry, not only for the BOE, but also for the Fed, ECB, BOJ, etc., is the coordinated unwinding of the bank balance sheets (sovereign and MBS bond portfolios), one mistake, could shift and invert global yield curves, pop asset price bubbles in stocks, bonds and real estate, and send us all into a global recession-depression.

Similar policy responses to the global economic-banking crisis, is also being witnessed in Asia. Yes, we already talked about the BOJ being the first mover in applications of unorthodox monetary and fiscal policy, with no real outcomes on wages, growth or inflation, other than fiscal debt levels and continued stagnation, the other, is the People’s Bank of China (PBOC).

The real difference between the PBOC and the rest of the global central banks, is total lack of transparency (opaque) into the balance sheets of the government, financial institutions, government (State-Owned Enterprises – SOEs) owned corporations, public and private Multinational Corporations (MNC), and state and local finance.


The People’s Bank of China (PBOC) Chases Its Shadows

The modern era of the PBOC started in the early 1980s – as a fiscal agent (under Ministry of Finance), public-private bank, clearing foreign currency exchange transactions, etc. in coordination with the China Construction Bank, Industrial and Commercial Bank of China, and Agricultural Bank of China.

Opening up the economy to massive (speculative) extension of credit and Foreign Direct Investment (FDI), under a neo-liberal model, resulted in speculative asset price (real estate, equity and debt) bubbles and busts (defaults) in the 1980s and 1990s, resulting in government intervention and deflation.

The Asian Contagion of the late 1990s required massive bank and corporate bailouts (recapitalisations). The 2000s, have seen a modernisation of the PBOC as a central banking institution through banking reforms, conversion of SOEs to private-public firms (privatisation toward a more Japanese Keiretsu system), push for more export oriented policies (higher-value commodities-services), and large government sponsored infrastructure projects (commercial-residential-dams-roads-power plants, etc.),

Prior to the Financial Crisis (FC), the PBOC was moving to a modern rules-tools oriented application of monetary policy: interest rate and price targeting, constant growth in the money supply, and use of open market operations. Low borrowing costs spurred massive amounts of lending and borrowing (money supply growth) by both fiscal institutions, government and state-private owned enterprises, leading to asset price bubbles.

China is using more and more debt to fix bad debt problems, and the simulative multiplier-accelerator effect on the economy is deteriorating quickly.

Which also lead to over-capacity, miss-allocation of resources, inflation, environmental degradation, political-economic corruption, currency manipulation (peg), etc. Since the China economy was still at this time decoupled from the Western global financial system, it was able to avoid most of the damage caused before the Financial Crisis.

But after the Financial Crisis, the PBOC had to accelerate the move toward liberal monetary finance, driving interest rates extremely low (real interest rates negative) to keep government and corporate (personal) borrowing costs low, to stimulate the economy/consumption/investment, to keep it from falling into a severe recession (depression/deflation), and had to deal with Non-Performing bank Loan (NPL) portfolios to avert a banking crisis. Rapid growth helped to mask these problems, but these were only land mines, waiting to be found and dealt with at a future date.

Banks and asset management companies had to be bailed out, dissolved, liquidated, etc. Trillions and trillions of monetary liquidity and fiscal stimulus had to be injected to the economy, targeted toward housing, infrastructure and manufacturing, causing asset prices again to inflate. By 2014, only to deflate again by 2016. These injections of fiscal and monetary stimulus exacerbated asset price volatility (real estate/equities/bonds).

The next financial crisis in China will come from the excessive extension of credit from both fiscal and monetary authorities, and will come from government and corporate bond market defaults, as the system is severely  over leveraged. China is using more and more debt to fix bad debt problems, and the simulative multiplier-accelerator effect on the economy is deteriorating (decelerating) quickly.

Global central banks have been coordinating their monetary policy efforts over the past 10 years, and the U.S. Federal Reserve Bank has become the de facto Central Bank of Central Banks (CBCB). Based on new disclosures, we have found out that the U.S. Federal Reserve conducted global QE by buying other foreign sovereign debt during the financial crisis, and provided credit-liquidity facilities to global banks.


Yellen’s Bank: From Taper Tantrums to Trump Trade

There was Paul Volker, then there was Alan Greenspan, then Ben Bernanke, now Janet Yellen, and who knows who is next (Jerome Powell). All of these Fed presidents dealt with extraordinary conditions (some self-inflicted), wars, financial crisis, recessions, asset price bubbles/bursts, etc.

It was not till Alan Greenspan, that the Federal Reserve decided excessive accommodation and liquidity was the solution to all crisis, and asset price bubbles were not a concern if they were real, and not a monetary illusion. However, he now admits that he was wrong in the way he understood how the world really works, which means he made policy errors and mistakes.

Bernanke was a protégé of Greenspan, and responded to the Financial Crisis with the largest monetary response (QE Infinity) in modern monetary history combined; and Yellen, continued his legacy of over accommodation, to escort us into one of the biggest debt-asset price bubbles in modern Fed history.

And if history is any indicator of the future, once the Fed(s) decide to conduct a coordinated unwind of their balance sheets, the popping of asset price bubbles will be like balloons at New Year’s Eve party in Time’s Square, only everyone will walk away from the party with the worst hangover of their life, and no one will be able to sober up fast enough to drive to the next party.

In the end, the Fed accumulated over $4.5 trillion in bank reserves/balance sheet (bonds), made up mostly of mortgage backed securities and U.S. government Treasury notes and bonds, the average size of the balance sheet prior to the financial crisis was $500 to $800 billion. This is the largest subsidisation, and theoretically (and really) the largest nationalisation (Fed implemented) process, of the financial system and the economy in modern post-WWI history.

This could also be considered Fascist Finance (FF), as it involves the largest global money center banks, multinational corporations, and governments in the world –  now a Global Corporatist System – operating under unorthodox monetary policy, outside pluralistic-democratic institutional oversight.  As we can now see, again, the systematic dismantling, deconstruction and destruction of financial institutional governmental regulatory oversight, is in place.

Since these were mainly reserves creation, and an addition to the monetary base, and not really the money supply, the policy effects (QE/(Zero-Negative Real Interest Rate policy) have been mute.

The Fed has not been able to hit its inflation or GDP targets for the past 10 years (well below potential), there is secular and cyclical productivity declines, extremely low labor participation rates (high under employment rates), real wages are stagnant and still declining, and we are in a disinflationary/deflationary secular trend.

The cause is a collapse in the velocity of money, driven by alternative forms of money creation and flows across the globe (cryptic-digital currencies-shadow banking, etc.); the lack of fiscal labor market policy to lower under-employment and raise labor market participation rates; and other social, cultural, political and economic disruptions. Making it now impossible to conduct monetary policy.

The real risk going forward will be from a series of financial deregulation, coming from the Trump Administration and the Republican controlled House and Senate; along with a coordinated effort to unwind (Quantitative Tightening – QT) the Feds (and other global central banks) balance sheet, and a race toward interest rate normalisation, sucking liquidity out of the system, only to lead to a stock, bond and real estate bubble burst.

With the Fiscal Debt totaling over $20 trillion, the Feds Balance Sheet totaling $4.5 trillion, the potential for continued -perpetual war (defense spending) and entitlement expenditures, and political and policy uncertainty (next Federal Reserve President) there is little room for monetary and fiscal solutions to fight the next financial and economic crisis. Leading to the conclusion of continued stagnation, crisis, recession, wars and depression.

It is now obvious why Central Banks fail.


Why Central Banks Fail

After reading Dr. Jack Rasmus book, Central Bankers at the End of Their Rope? and if you read his book, Systematic Fragility in the Global Economy,  along with other books and interviews surrounding this literature, it has been clear, and it is now crystal clear, why central banks fail, they:

  • Are a creature of the global capitalist system;
  • Support, promote and protect financial institutions and companies;
  • Use myopic (static) intellectual and epistemological frames (models) to analyse economic data, markets, and institutions to develop and implement monetary policy;
  • Are influenced by political (executive/legislative) parties and lobby when making and communicating policy;
  • Are expected to support (moral hazard) and coordinate national fiscal policies (debt) and priorities (compromising their independence and credibility);
  • And be the lender, portfolio manager, and market maker of last resort to mitigate capital market (economic) failures;

These failures emanate from the fact that they are given (have been given over) the monopoly power and authority (independence) to control the money supply, clearing system, exchange rates, interest rates, supervision, etc. However, we are finding out, that they are not as in control as we think, and are not looking out for our best interest.

The solution to the existential crisis in global central banking is not a technological solution, but a democratic-pluralistic political solution. Based on moral philosophy and ethical outcomes.

There is a mythology surrounding the Fed, and illusion of omnipotence, and control, this is evident when measured by its balance sheet, lack of understanding how the world really works, and inability to hit monetary and real economic targets: inflation, labor participation rates, real wage growth, and higher broad based social welfare and standards of living.

We are finding that our Keynesian (Keynes) and Monetarist (Fisher/Friedman) economic ideologies are not correct, and are not working, deregulation and printing of massive amounts of money to bail out and subsidise inefficient and corrupt financial institutions (lobby), after every man-made and self-inflicted crisis, is not working, and we are at the end of our rope.

We now, cannot keep doing this, we are out of money. However, with Crypto-currencies, and other unproven systems of monetary accounting, could set the stage for monetary collapse, if this experiment turns out wrong.

The solution to the existential crisis in global central banking is not a technological solution, but a democratic-pluralistic political solution. Based on moral philosophy and ethical outcomes.


Revolutionising Central Banking in the Public Interest: Embedding Change Via Constitutional Amendment

What is needed is a revolution in central bank thinking. There are many excuses for monetary (central bank) failures:

  • Too much discretion (money supply growth/credit expansion/asset price bubbles), and not enough adherence to monetary policy rules (money growth targets);
  • Conflicting fiscal (expenditures/spending) vs. monetary (inflation/interest rate) policy;
  • Asymmetric information (capital) flows (bottleneck) through banking system (adverse selection/moral hazard/principal agent problem);
  • Wrong monetary targets (inflation); dual mandates (production/employment/inflation/wage trade-off);
  • Global savings glut (uncontrollable off shore capital inflow);
  • Need for new monetary tools (open market operations/QE/QT/discount rates/reserve requirements, etc.);
  • Executive/legislative intrusion in monetary policy functioning;
  • Etc.

However, the real reason why central banks fail are:

  • Mismanagement of money supply (credit) growth and allowing banks, and other near- bank institutions, to access Federal Reserve credit/liquidity facilities;
  • Fragmented, failed and non-existent systemic and macro-micro prudential systemic bank supervision (Dodd-Frank);
  • Inability to achieve (real-nominal wage) inflation (labor participation) rates;
  • Failure to address, mitigate and/or control run-away asset (real estate/equity/bond/commodity) price inflation (bubbles/bust);
  • Deterioration, decomposition, and failure in the elasticity of (zero-negative) interest rates (liquidity trap/technology) to stimulate real economic growth (employment/wages);
  • Re-direction of investment capital away from higher yielding real (long-term) capital investments to lower yielding-speculative monetary (short-term) financial investments (derivatives/floating-rate notes);
  • Ineffectiveness of traditional monetary policy tools (federal funds rate/discount window/reserve requirements), and reliance on non-traditional un-orthodox (QE/credit-liquidity facilities) monetary policy tools with unintended negative consequences (deflation/asset price bubbles);
  • Myopic political-economic monetary policy ideologies and errors in epistemological thinking (Taylor Rules/Philips Curve/Zero-Negative Interest Rate Policy/unlimited balance sheet expansion).
  • Etc.

What is needed is a revolution in central bank thinking.


CONCLUSIONS

A revolution is needed, in mainstream ideological thought, in regards to Global Central Banking. A revolution in accepted institutional norms and beliefs of how central banking actually works. There needs to be a dialectical shift from the established and accepted thesis of central banking authority. If there is not, there will be a revolution against central banks, and a battle will occur to wrestle authority, control and independence from central banks.  And this battle will no doubt be destructive and deconstructive, leading to economic and financial crisis, and eventually lead to some anti-thesis (executive or legislative branch control) over the central bank(s) for the next 30 to 60 years.

Currently, the Federal Reserve is:

  • Controlled by private sector banker interests,
  • Control of the Federal Reserve Bank of New York (Open Market Operations),
  • Private sector banker selected leadership of Federal Open Market Committee,
  • Private sector bank access to insider information on monetary policy,
  • Iron-Triangles between Fed staff and private banking sector and lobby,
  • Circularity between Fed private sector banks,
  • Influence of private sector bank lobby in Fed Chair selection,
  • Record campaign finance contributions to congressional committee members,
  • Revolving door between the Fed, bank supervisors, Treasury, and banks,
  • Etc.

Regulatory and legislative proposals have been brought, only to be blocked and abandoned, due to pressure from Wall Street lobby. And those policies that have been enacted (Dodd-Frank), the bank lobby has systematically reversed and repealed oversight over the years, or implemented bank friendly legislation. This legislation, and lack of supervisory regulatory oversight, has been passed through (and ignored by) executive and congressional initiatives, and the public administrative bureaucracy.

The solution, is the democratisation of the central bank, bringing it into pluralistic (public) oversight, with a focus on real, not financial, economic outcomes.


Proposed Constitutional Amendment

The solution, a proposed constitutional amendment to require the democratic election of the national Fed governors by U.S. citizens, serving six years; and the Treasury secretary shall decide monetary policy in the public interest; and be proactive in achieving stability for labor, households, businesses, local governments, and financial institutions and industry, etc.

Dr. Rasmus, recommends a constitutional amendment enabling legislation through five sections, and 20 articles:

SECTION #1: Democratic Restructuring

  • Article #1: Replace 12 Fed districts with four, presidents elected at large.
  • Article #2: FOMC replaced by National Fed Council (NFC), members limited to six-year terms, and 10 year limit on returning to private banking sector.
  • Article #3: Fed districts to not be corporation, and issue stock, pay dividends, retain no profits. Taxes to be levied on Fed transactions to pay for operating costs.
  • Article #4: No additions to Fed districts by legislative or executive orders, or appointments.

SECTION #2: Decision Making Authority

  • Article #5: NFC and Treasury Secretary to determine monetary policy (tools).
  • Article #6: QE to be used to invest in real assets.
  • Article #7: NFC purchase of private sector stocks and bonds, and derivatives, prohibited.
  • Article #8: No Fed bank supervision, a new consolidated banking institution created.

SECTION III: Banking Supervision

  • Article #9: Same as Article #8.
  • Article #10: Separate supervisory departments by banking and financial services industry segments.
  • Article #11: Separate legislation by depository from non-depository institutions.
  • Article #12: Supervision includes all markets and companies in derivative industry.
  • Article #13: Conduct regular stress tests on banks and non-banks.

SECTION IV: Mandates and Targets

  • Article #14: Replace current Fed targets with those targeting real wage growth.
  • Article #15: Expand authority of NFC to lend directly to businesses and households.

SECTION V: Expand Lender of Last Resort Authority

  • Article #16: Expanded to include non-banks businesses, local-state governments, etc.
  • Article #17: Non-bailout of Non-U.S. domiciled banks and financial institutions.
  • Article #18: Create a Public Investment Bank (PIB) as lender of last resort to provide liquidity to households and non-banks.
  • Article #19:  Create a National Public Bank (NPB) for direct lending to households and non-banks.
  • Article #20: Bain-ins thresholds and limits protect depository diluted from bail-outs.


FINAL COMMENTS

In the post-World War II (WWII) era the economy and financial markets and institutions have gone through nine cycles.  Over time the amplitude and volatility of these cycles have narrowed as our cultural, social, political and economic institutions developed.  However, the most recent business, financial institution and credit cycle experienced a significant drop – and volatility – in aggregate demand and asset prices, not seen since 1949, a point in history when our central banking and financial institutions were developing.

The long-term goal of effective formulation and administration of public, monetary and fiscal policies is efficient allocation of capital and resources, higher risk-adjusted returns, social and economic stability, and high and rising standards of living and social welfare.

The reality is we have witnessed the systematic deconstruction of pluralistic, democratic and capitalistic institutions – through the political process – by private interest in society and economy, creating perverse redistribution of wealth and resources, to the point of massive social and cultural, and economic and capital market failures.

It is believed by most neo-post Keynesian economists, that the current economic, institutional, and capital market failures could have been avoided through centrist political, monetary and fiscal policies, and that the recent financial crisis could have been averted through the separation of investment and commercial banking activities, and enforcement of public and private property rights through effective enforcement.

The long-term goal of effective formulation and administration of public, monetary and fiscal policies is efficient allocation of capital and resources, higher risk-adjusted returns, social and economic stability, and high and rising standards of living and social welfare.

Dr. Jack Rasmus’s book, Central Bankers at the End of Their Rope?: Monetary Policy and the Coming Depression, enables us to understand historical and recent economic and capital market crisis, and how to recognise and understand the development, administration and deconstruction of financial institutions and markets.

Institutions were built on pluralistic political and capitalistic economic ideologies, and when these ideologies are confronted, come under attack by private interests, policy outcomes are distorted or destroyed.

The process of pluralistic, democratic and capitalistic institutional construction and development has taken 80 years; however, it took 30 years, and particularly the last ten years, to deconstruct these institutions to the point of systematic failure.

The process associated with institutional destruction, deconstruction and distortion, manifests in the extreme redistribution of political power, social benefits and economic wealth, and can reach the point where redistributions become so extreme, they cause systematic social, economic and market failure.

These failures are reflected in increased volatility in social and economic indicators, capital market pricing and investment risk, and resulting reductions in risk-adjusted returns, inefficient allocation investment capital and resources, and falling employment and real income growth rates, standards of living and overall social welfare.

“Over the past 95 years, society and the economy have witnessed great prosperity, wars, depressions, recessions and revolutions.  We have just witnessed a revolution in economic ideological thought – from Keynesianism to Monetarism – and in its wake of institutional destruction and market failure… what synthesis will form and how will we as a society be remembered.” Dr. Lawrence A. Souza (2014).


About the Author

Dr. Lawrence A. Souza, DBA/CCIM/RICS/CRE is an Adjunct Professor in Finance at St. Mary’s College, School of Economics and Business Administration (SEBA). He has over 28 years of experience in the commercial real estate investment advisory industry, providing economic and investment consulting services to individual and institutional real estate investors. Prior to St. Mary’s College of California, Pillar6 Advisors, LLC, Johnson Souza Group, Inc., and New York Life Insurance Company/NYLIFE Securities LLC, Dr. Souza worked for Charles Schwab Investment Management (CSIM) as Managing Director – Index Services; Chief Economist – Managing Director with Global Real Analytics (GRA); and Investment Advisor for Quantum Financial Network (QFN).


References

1. Abhijit Banerjee-Esther Duflo, Poor Economics.
2. Andrew Napolitano, A Nation of Sheep.
3. Andrew Ross Sorkin, Too Big To Fail.
4. Anthony Downs, Real Estate and the Financial Crisis.
5. Arthur Miller, Death of a Salesman, The Crucible, A View from the Bridge, Timebends, and A Life.
6. Barry Eichengreen, Exorbitant Privilege: The Rise and Fall of the Dollar and the Future of the International Monetary System.
7. Carmen Reinhart-Ken Rogoff, This Time is Different: Eight Centuries of Financial Folly.
8. Charles Kindleberger, Manias, Panics and Crashes: The History of Financial Crises.
9. Clyde Prestowitz, The Betrayal of American Prosperity.
10. Dambisa Moyo, How the West was Lost: Fifty Years of Economic Folly – and the Stark Choices Ahead.
11. Dambisa Moyo, How the West Was Lost: Fifty Years of Economic Folly, and the Stark Choices Ahead.
12. Damon Vickers, The Day After the Dollar Crashes.
13. Daniel Yergin, The Prize: The Epic Quest for Oil, Money and Power.
14. David Brooks, Bobos in Paradise: The New Upper Class And How They Got There.
15. David Harvey, The Enigma of Capital and the Crisis of Capitalism.
16. David Harvey, The New Imperialism.
17. David Ricardo, The Principals of Political Economy and Taxation.
18. David Skeel, The New Financial Deal: Understanding the Dodd-Frank Act and its Unintended Consequences.
19. Diane Coyle, The Economics of Enough: How to Run an Economy as if the Future Matters.
20. Edmund Phelps, Structural Slumps and Rewarding Work.
21. Eric Weiner, The Shadow Market: How Wealthy Nations/Investors Secretly Dominate the World.
22. Frank Portnoy, FIASCO: Blood in the Water on Wall Street.
23. Friedrich Nietzsche, The Will to Power.
24. Garber Mate: Scattered Minds: A New Look at Origins and Healing of ADD.
25. Gary Stern, Too Big To Fail: Hazards of Bank Bailouts.
26. George Cooper, The Origins of Financial Crisis: Central Banks, Credit Bubbles.
27. Glenn Hubbard, Seeds of Destruction: Why the Path to Economic Ruin Rugs Through Washington, and How to Reclaim American Prosperity.
28. Gretchen Morgenson, Reckless Endangerment.
29. Harry Dent, The Great Depression Ahead.
30. Jerome Corsi, America for Sale.
31. John Bogle, The Battle for the Soul of Capitalism.
32. John Cassidy, How Markets Fail: The Logic of Economic Calamities.
33. John Mauldin, Endgame: End of the Super Debt Cycle.
34. Joseph E. Stiglitz, Freefall: America, Free Markets and the Sinking of the World Economy.
35. Judge Richard Posner, A Failure of Capitalism.
36. Justin Fox, The Myth of the Rational Market: A History of Risk, Reward and Delusion on Wall Street.
37. Kim Phillips-Fein, Invisible Hands.
38. Liaquat Ahamed, Lords of Finance.
39. Manfred Max-Neef, From the Outside Looking In: Experiences in Barefoot Economics.
40. Mark Zandi, Financial Shock: A 360° Look at the Subprime Mortgage Implosion, and How to Avoid the Next Financial Crisis.
41. Max Weber, The Protestant Ethic and the Spirit of Capitalism.
42. Michael Lewis, The Big Short: Inside the Doomsday Machine.
43. Naomi Klein, The Shock Doctrine.
44. Nicole Gelinas, After the Fall: Saving Capitalism from Wall Street and Washington.
45. Noam Chomsky, Failed States, Necessary Illusions, and Manufacturing Consent.
46. Pat Choate, Saving Capitalism: Keeping America Strong.
47. Paul Kennedy, Rise and Fall of the Great Powers.
48. Paul Krugman, The Return of Depression Economics and the Crisis of 2008.
49. Paul Muolo, Chain of Blame: How Wall Street Caused the Mortgage and Credit Crisis.
50. Paul Sperry, The Great American Bank Robbery: The Unauthorized Report About What Really Caused the Great Recession.
51. Peter Ingersoll, Real Estate Tsunami Survivors Guide.
52. Raghuram Rajan, Fault Lines: Hidden Fractures Still Threaten the World Economy.
53. Randall Lane, The Zeros: My Misadventure in the Decade Wall Street Went Insane.
54. Robert Barbera, The Cost of Capitalism: Understanding Market Mayhem and Stabilizing our Economic Future.
55. Robert Reich, Aftershock: The Next Economy and America’s Future.  Robert Scheer, The Great American Stickup: How Reagan Republicans and Clinton Democrats Enriched Wall Street and Mugged Main Street.
56. Robert Shiller, Animal Spirits: How Human Psychology Drives the Economy and Why It Matters for Global Capitalism; and The Subprime Solution: How Today’s Global Financial Crisis Happened, and What to Do about It.
57. Roger Lowenstein, The End of Wall Street.
58. Roman Frydman, Beyond Mechanical Markets: Asset Price Swings, Risk and the Role of the State.
59. Satyajit Das, Extreme Money: Masters of the Universe and Cult of Risk.
60. Simon Johnson, 13 Bankers: The Wall Street Takeover and Next Financial Meltdown.
61. Stephen Breyer, Making Our Democracy Work.
62. Steve Fraser, Wall Street: Americas Dream Palace.
63. Susan Casey, The Devil’s Teeth: Great White Obsession/Survival.
64. Suzanne McGee, Chasing Goldman Sachs: How they Melted.
65. Thomas Sowell, The Housing Boom and Bust.
66. Timothy Carney, Obamanomics.
67. V.S. Soloviev, Politics, Law and Morality; Michel Foucault, Power/Knowledge.
68. William Bonner, The Empire of Debt: The Rise and Fall of an Epic Financial Bubble.
69. William Holstein, The Next American Economy: Blue Print for a Real Recovery.



Bitcoin, Cryptos and Financial Asset Bubbles

BRUSSELS, BELGIUM - MARCH 9, 2017 : Golden Bitcoins.

By Jack Rasmus

At less than $1000 per coin in January, Bitcoin prices surged past $11,000 this past November. It then corrected back to $9,000, only to surge again by early December to more than $15,000. Given the forces behind Bitcoin, that scenario is likely to continue into 2018 before the bubble bursts. This article will in part address those forces behind Bitcoin’s bubble, and why the bubble will continue to grow near term.


What’s a financial asset bubble? Few agree. But few would argue that Bitcoins and other crypto currencies are today clearly in a global financial asset bubble.  Bitcoin and other crypto currencies are the speculative investing canary in the global financial asset coalmine.

One can debate what constitutes a financial bubble – i.e. how much prices must rise short term or how much above long term average rates of increase – but there’s no doubt that Bitcoin price appreciation in 2017 is a bubble by any definition. At less than $1000 per coin in January, Bitcoin prices surged past $11,000 this past November. It then corrected back to $9,000, only to surge again by early December to more than $15,000. Given the forces behind Bitcoin, that scenario is likely to continue into 2018 before the bubble bursts. As of mid-December, Bitcoin is trading at $17,009 and predicted to surge higher. Some analysts are even predicting the price for Bitcoin will escalate to $142,000, now that trading has gone mainstream on the CBOE and other commodity futures exchanges. The question of the moment, however, is what might be the contagion effects on other markets?

This article will in part address those forces behind Bitcoin’s bubble, and why the bubble will continue to grow near term. But Bitcoin and other crypto currencies are but one case example of financial asset price acceleration underway in global markets that also are either in, or approaching, bubble territory – a condition typical of a late credit cycle reaching its limits.

Other asset bubble candidates include equities markets, especially in the USA, Japan and some emerging market economies (EMEs); corporate junk bond markets globally; and high risk bank loans – particularly in Europe, Japan and Asia – emerging on a base of trillions of dollars of pre-existing non-performing bank loans.

In the following, the determinants and driving forces behind the growing financial asset bubbles are discussed, with special focus of Bitcoin and crypto currencies which have a potential of “contagion” to other financial markets more than most commentators today like to admit.

Less debatable are potential contagion effects from global equities, now approaching bubble territory in some regions like the USA and Japan. Or corporate junk bond markets worldwide. Or high risk leveraged loans, the return of CLOs, and the late-cycle trend increasingly apparent among banks toward covenant-lite lending terms, as the search for yield becomes ever more desperate everywhere.

Red Flags and Forewarnings

There are no lack of “red flags” being raised by various legitimate sources forewarning that the global economy is now producing levels of financial fragility that may lead toward one or more significant financial instability events within the next few years.1


Bank of International Settlements

There are no lack of “red flags” being raised by various legitimate sources forewarning that the global economy is now producing levels of financial fragility that may lead toward one or more significant financial instability events within the next few years.

One consistent source in recent months raising the red flag has been the Bank of International Settlements.  This past summer, the BIS warned in its review that the magnitude of non-financial corporate debt globally was actually far larger than reported by most – especially outside the US, in dollar terms, and often held off balance sheet.

Of course, debt alone is not solely the problem. Debt can keep on rising, but once its cost (interest rate) begins to rise as well, or is not otherwise obtainable or obtainable only on adverse terms. Then the problems begin.  And with the problems come decelerating asset prices that lead to credit disappearing, with eventual spillover to the real economy which then contracts in tandem with financial markets. That latter, real contraction then exacerbates the financial, and the two sectors thereafter feed on each other in a downward spiral, until government policy makers otherwise find a way to put a floor under the asset deflation. That’s exactly what happened in 2007-2009. The BIS is warning the early stages of escalating debt accumulation that leads to just such a scenario may be appearing once again, noting specifically that the central banks since 2008 have been the main culprit with their monetary easing “fueling bubbles in asset prices”.

That the central banks of the advanced economies are the ”fundamental” force and cause behind the debt escalation is irrefutable. Since 2008 in particular, led by the Federal Reserve, the central banks in the USA, Europe, Japan and China have pumped around $25 trillion in QE, QE rollover and traditional bond (and stock and other securities) buying operations into the global economy2. Changes in global financial market structure in recent decades have exacerbated the development, as have technology trends responsible for accelerating money demand, velocity, and development of non-fiat (central bank) forms of money substituting for credit.

This has led Claudio Borio, Director of the Monetary and Economics Department of the BIS, in that publication’s most recent quarterly Review in December 2017, to conclude “The vulnerabilities that have built around the world during the long period of unusually low interest rates have not gone away. High debt levels, in both domestic and foreign currency, are still there. And so are frothy valuations, in turn underpinned by low government bond yields – the benchmark for the pricing of all assets. What’s more, the longer the risk-taking continues, the higher the underlying balance sheet exposures may become. Short-run calm comes at the expense of possible long-run turbulence.”3


Central Bankers and Global Investors

Borio is not alone.  Mohammed El-Erian, Chief Economic Advisor to Allianz, the giant global financial company, and frequent commentator on the global economy, has added that liquidity and volatility risks over the past few months have risen noticeable and “have spread to virtually every corner of the public markets…structurally amplified by the proliferation of certain ETFs”4 – (more on which shortly below).

Mervyn King, former governor of the Bank of England, also recently raised concerns about non-bank debt levels and ratios that are today higher than at year end 2007 at the start of the last financial crisis. King added the dominant theme of the post 2008 period has been the rolling over of debt instead of its deleveraging during a period of excessive low interest rates for eight years. And, as he further noted, once rates rise “we shall see the force of what economist Joseph Schumpeter described as “creative destruction”…that will correct the misplaced pattern of investments induced by inappropriate exchange rates and excessively low interest rates”. King goes on to ominously warn that despite more capitalisation banks “are still vulnerable to runs” and it would take only a “a few interconnected defaults” to set in motion “a reappraisal of the effective leverage of the financial system”– aka a wipeout of valuations by means of massive financial asset price deflation.

The Peoples Bank of China Director, Zhou Xiaochuan, echoed King this past October, warning of trouble and unpopular decisions on the horizon, as the global economy was at risk of entering “a sharp correction, what we call a ‘Minsky moment’..”– after the economist, Hyman Minsky, who wrote that banking under capitalism was inherently unstable and prone to repeated financial crises.6

Former US Federal Reserve Bank Chair, Alan Greenspan, warns of bond prices that are “in a bubble”.  And outgoing Fed chair, Janet Yellen, worried publicly in her most recent press conference about “the US debt trajectory”. Ironically, those central bank chairpersons most responsible to the massive, excess liquidity injections since 1985, that provided the ultimate foundation for the unprecedented debt leverage in financial markets, are the same that now warn of its pending consequences in unsustainable asset prices.

Research department analysts of some of the world’s largest banks have also been joining in raising the alarm. Bank of America-Merrill Lynch’s latest survey of its investors revealed that those indicating equities were over-valued now exceeded those similarly indicating such on the eve of the 2000 dot.com stock bust. Similarly, Deutschebank credit analysts have recently calculated that global asset prices are the most elevated ever, including before the 1929 crash.7


Global Business Press Commentators

Increasingly, editorialists in the global business press have begun writing increasingly on the emergence of financial asset bubbles, growing excessive debt levels and ratios, the failure of corporations and households to deleverage since 2008, complacency of investors, failure to see the new causes of the next crisis by looking in the rearview mirror only at the previous one, overly sanguine estimations of future global economic growth, accelerating income inequality and so on.

Perhaps representative of this tribe is the dean of global business commentary, Martin Wolf, at the Financial Times global business daily, who worries of the lack of “no corporate deleveraging” since 2008, the prospect of highly leveraged banks prone to losses, emerging market dollarised corporate bonds exposed to currency risk, non-bank corporate debt growing faster than productive capital, low investment and high indebtedness in general, and high political risks.8


Corporate Chief Financial Officers

Even those players “down in the weeds” of the business world have begun expressing concern about the state of financial asset markets.  According to a quarterly poll of companies in North America with more than $1 billion in revenue by Deloitte in the third quarter 2017, its “CFO Signals Survey”, only 29% of CFOs surveyed expressed optimism, down from 44% in the preceding quarter.9


BITCOIN Bubble: Canary in the Financial Asset Coalmine?

Discussion of the forces driving the Bitcoin bubble – as well as the numerous emerging other crypto-currencies – requires distinguishing between causal factors that are “fundamental”, “enabling”, or just “precipitating”.  That’s true not only for Bitcoin and cryptos, but as well for other emerging bubbles in equities, junk bonds, high risk bank lending and low quality, dollarised emerging market debt – i.e. the other emerging financial bubble candidates.

The key fundamental forces driving Bitcoin’s bubble are technology and excess liquidity. Bitcoin is both software tech and fintech.


Blockchain as Technology Driver

The technology is called “blockchain” which serves as the underlying platform for Bitcoin and emerging crypto-currencies. Blockchain provides global peer-to-peer transactions over the Internet, cutting out middlemen, and thus saving business and consumers significant costs.  It is software that in effect creates for users an “online digital wallet”.  It is blockchain software tech that is giving rise to digital currencies, the hottest new area of fintech.  Software tech companies doing Blockchain development create their version of crypto currency, often giving it in exchange to an investor funding the company.  A crypto currency developed by the software tech company thus serves as a kind of de facto “digital equity offering”.10 And investors are rushing in. A kind of investor herd mentality has emerged. The hottest business conferencing product today is explaining Bitcoin and cryptos opportunities to would-be investors, as well as to other senior managers who want to avoid being blindsided by the new technology.

Discussion of the forces driving the Bitcoin bubble – as well as the numerous emerging other crypto-currencies – requires distinguishing between causal factors that are “fundamental”, “enabling”, or just “precipitating”.

The potential market for blockchain is immense – $134 trillion of transactions in the global banking sector alone.  Given the huge potential for cost saving across industries, Blockchain software development companies are proliferating globally at a rapid rate, and speculative investors are throwing record funding at them in hope of striking it rich with the one whose version of Blockchain becomes the quasi-standard and/or is early to market.

In the process, the Blockchain tech companies spin off their version of digital currency. Some cryptos, like Bitcoin and Ethereum, are considered “blue chip”, while many others are “small cap” cryptos.  As of several months ago there were at least 200 such companies, most of which were engaging in, or preparing, an initial public offering to raise financing, an ICO (initial coin offering).

Given the herd mentality, media hype, and demand, multiplying ICOs result quickly in IPO initial prices rising. Bitcoin’s price appreciation is serving as a kind of potential and benchmark for the “me too” ICOs. The latter’s price appreciation then spills over, driving up the price of other cryptos and Bitcoin.  The ICOs are feeding off of each other.


Enabling Forces Driving Bitcoin-Cryptos Bubble

If Blockchain and software tech company ICOs are driving Bitcoin and other crypto pricing, what’s additionally creating the bubble?  Bitcoin prices started off 2017 less than $1,000 a coin. But have accelerated through 2017. So what’s behind it the past year?  Who is buying Bitcoin and cryptos, driving up prices, apart from early investors in the companies?

Initially, pre-2017, it was mostly “retail” buyers from the tech community who believed government “fiat” money was going to be eclipsed by digital currencies. It shared some similarities to pre-2000 herd investing in anything that had an “e” or a “com” associated with it. It was analogous perhaps to a day trader becoming obsessed with “social media” or Facebook, except now the objective was money and not communication. It was cultural and even philosophical.

The absence of government regulation and potential taxation of speculative profits from price appreciation has served as another important driver of the Bitcoin bubble bringing in still more investors and demand and therefore price appreciation.

But that initial techie demand source was soon eclipsed by buyers who realised that speculative profits from accelerating Bitcoin prices were not taxed by government. And without a central clearing house it was not likely the government would soon regulate and tax.  So the absence of government regulation and potential taxation of speculative profits from price appreciation has served as another important driver of the Bitcoin bubble bringing in still more investors and demand and therefore price appreciation. No regulation, no taxation has also led to price manipulation by “pumping and dumping” by well-positioned investors.

Another factor driving price is that Bitcoin has become a substitute product for Gold and Gold futures. Buyers who were highly speculative and risk taking, who might have otherwise invested heavily in gold and gold futures trading, see Bitcoin and cryptos as a better speculative play.  Gold has become less volatile, and speculative profits come from volatility.  Gold no longer has it; Bitcoin does. Bitcoin is thus “as good as gold”, and in fact even better as a speculative play.  As a gold substitute, Bitcoin and cryptos may therefore be diverting investment from gold, further driving demand for the former by sucking it away from the latter. That may explain Gold’s recent chronic lack of price volatility, at least in part. Like Gold, Bitcoin is therefore more a commodity, as well as a kind of substitute for stock in initial public offerings by software tech companies.

What Bitcoin is not, as yet, is a form of general currency, except in very select cases.  It is still accepted for transactions by relatively few.  As a medium of exchange, a basic characteristic of currency and money, Bitcoin is still in development stage. But as a volatile commodity, highly profitable speculative play, it has already established itself. And in today’s world of ever-desperate search for yield, as markets begin to “top out” late in the credit cycle, Bitcoin has become something of a kind of “commodity lodestar” for investors conditioned to high risk and high profitability success in financial markets since 2009.

But what’s really driving Bitcoin pricing in recent months well into bubble territory is its emerging legitimation by traditional financial institutions.  This has come in various forms. First is the imminent acceptance of it by the commodity clearing houses, in particular the CME and CBOE.  This means that futures and derivatives trading on Bitcoin are set to begin in December 2017. Bitcoin ETFs are likely not far behind. Thus further speculative profit opportunities appear on the horizon, which stimulates its initial demand. And it’s this derivatives investing opportunity that mainstream finance is interested in. The “shorting” of excessive Bitcoin price appreciation by mainstream big investors now looms large. The CME and other clearing houses on the horizon thus make basic Bitcoin speculation legitimate, and that’s pulling in more demand.

Reportedly, big US hedge funds are also poised to go “all in” once CME options and futures trading are established. Declarations of support for Bitcoin has also come lately from some sovereign countries and plans to develop widespread markets for it – as in Japan. That also legitimises it. Other sovereign players, like Mexico and Indonesia, have raised their opposition – no doubt fearful of cryptos currencies’ potential long run threat to their controlling their own fiat money supply and therefore interest rate central bank monetary tools.

Among traditional commercial bankers a form of legitimation, albeit cautious, has also recently emerged, serving to justify Bitcoin demand.  While CEOs of big traditional commercial banks, like JPM Chase’s Jamie Dimon, have called Bitcoin “a fraud”, they simultaneously have declared plans to facilitate trading in the Bitcoin-Crypto market, no doubt as an initial step to later more direct participation.


Government Regulation

A question remains whether government regulators will soon intervene to regulate Bitcoin and other cryptos in the near term. The answer is “not so long as Bitcoin et. al. remain a commodity speculative play”, in this writer’s opinion.  The winds of financial regulation are dissipating, especially in the USA. That works against it.  Moreover, the fact that the US government has given the green light to the CME and other clearing house to establish trading in options strongly suggests the government will wait and see what transpires.  Should Bitcoin expand its development into a transactions based currency, however, that will precipitate government intervention.  Should it fail, it would mean a loss of control of the money supply, a problem also growing for the Fed and other central banks due to other technological and global forces.  Governments will protect their fiat currencies.  In fact, more likely is that they will eventually issue their own official “digital” currency at some point. Thereafter, other digital currencies will in effect become counterfeit and illegal tender.


Bitcoin as “Digital Tulips”

Bitcoin demand and price appreciation may also be understood as the consequence of the historic levels of excess liquidity in financial markets today. Like technology forces, that liquidity is the second fundamental force behind its bubble.  To explain the fundamental role of excess liquidity driving the bubble, one should understand Bitcoin as “digital tulips”, to employ a metaphor.

The Bitcoin bubble is not much different from the 17th century Dutch tulip bulb mania. Tulips had no intrinsic use value but did have a “store of value” simply because Dutch society of financial speculators assigned and accepted it as having such.  Once the price of tulips collapsed, however, it no longer had any form of value, save for horticultural enthusiasts.

What fundamentally drove the tulip bubble was the massive inflow of money capital to Holland that came from its colonial trade in spices and other commodities in Asia. The excess liquidity generated could not be fully re-invested in real projects in Holland.  When that happens, holders of the excess liquidity create new financial markets in which to invest the liquidity – not unlike what’s happened in recent decades with the rise of unregulated global shadow banking, financial engineering of new securities, proliferating liquid markets in which securities are exchanged, and a new layer of professional financial elite as “agents” behind the proliferating new markets for the new securities.11


Central Bank Excess Liquidity as Fundamental

The second “fundamental” factor behind the Bitcoin and crypto-currency bubble therefore is the massive amount of liquidity injected into the global economy by central banks in the US, Europe and North Asia in recent decades. Today far more money capital exists worldwide than can be, or is being, invested in making real goods and services. The excess does not remain idle. The combined liquidity injection since 2008 by the major central banks of US, Eurozone, Britain, Japan and China alone amounts to nearly $25 trillion since 2008. Led by the Fed, the central banks of the major economies noted have injected much of that $25 trillion directly themselves by means of their “Quantitative Easing” programs.  The chronic low interest rates that followed for eight years have allowed non-bank businesses to issue trillions of dollars (and dollar equivalent) corporate debt in the form of corporate bonds, commercial paper, etc.12 

Along with record corporate profits, also in the trillions since 2008, they’ve distributed to shareholders trillions of dollars by means of stock buybacks and dividend payouts.  In the US alone buybacks-dividends have exceed $1 trillion every year for the past five.  Rates have been so low for so long, multinational corporations have issued record bond debt to pay dividends and finance buybacks – in the process keeping nearly $3 trillion in their offshore subsidiaries in order to avoid paying US taxes.

At the root of it, the foundation of it, has been central bank monetary policies of QE and zero bound interest rates that have created a mountain of excess liquidity – far more than is investible in real assets in the advanced economies.  Accumulating within the investor class, trillions of dollars, euros, yen, etc. are still on the sidelines.  Institutional investors in particular must find an outlet for the liquidity.  Much of it goes into financial asset markets. (Other offshore to emerging markets, the rest hoarded on balance sheets or diverted to tax shelters).  As traditional stock and bond markets “top out”, the need for yield is diverting a significant portion of the excess liquidity into fintech, and some of that into cryptos. And as the primary blue chip crypto, increasingly into Bitcoin today and, tomorrow, into futures, options, and other derivatives based on it.


Bitcoin Bubble Potential Contagion

A subject of current debate is whether Bitcoin and other cryptos can destabilise other financial asset markets and therefore the banking system in turn, in effect provoking a 2008-2009 like financial crisis.

Deniers of the prospect point to the fact that Cryptos constitute only about $400 billion in market capitalisation today.  That is dwarfed by the $55 trillion equities and $94 trillion bond markets. The “tail” cannot wag the dog, it is argued.  But quantitative measures are irrelevant. What matters is investor psychology.  A big enough crash in cryptos could provoke a move out of other financial assets as a precautionary action. As other financial markets themselves surge into near, or actual, bubble territory investors increasingly look for a timing event to “cash in” and move to the sidelines. And the higher the rise of equities – especially in the US and Japan – goes the greater the potential psychological sensitivity to any major financial asset contraction anywhere.

A bitcoin-crypto crash could have a contagion effect on other commodity prices; or on ETFs in general and thus stock and bond ETF prices.

A Bitcoin and cryptos severe price devaluation event could provoke such a response, especially as other traditional financial institutions – commercial banks, hedge funds, clearing houses etc. – become more deeply involved in crypto markets as investors, facilitators, or in other ways.  For example, should cryptos develop their own ETFs, a collapse of crypto ETFs might very easily spill over to stock and bond ETFs – which are a source themselves of inherent instability today in the equities market.  A related contagion effect may occur within the Clearing Houses themselves.  If trading in Bitcoin and cryptos as a commodity becomes particularly large, and then the price collapses deeply and at a rapid rate, it might well raise issues of Clearing House liquidity available for non-crypto commodities trading. A bitcoin-crypto crash could thus have a contagion effect on other commodity prices; or on ETFs in general and thus stock and bond ETF prices.

Stated more speculatively, as Bitcoin and other crypto-currencies continue to ‘go mainstream’, will the new financial asset play the role similar to the toxic ‘Subprime Mortgage Bond’ in 2008? Just as subprimes precipitated a crash in the derivative, Credit Default Swaps (CDS) at the giant insurance company, AIG, in September 2008 – setting off the global financial crash that year – could the Bitcoin and crypto-currency bubble precipitate a collapse in the new derivative, Exchange Traded Funds (ETFs) in stock and bond markets in 2018-19, ushering in yet another general financial crisis?


Concluding Remarks & Predictions

In an increasingly integrated global financial asset markets world new forms of potential contagion may be lurking yet unforeseen.  Financial fragility should not be underestimated throughout the system, especially as it appears the credit cycle is nearing its peak, when historic capital gains have been reaped, and the psychology of investors looks increasingly at whether to “time the market”, cash in and move to the sidelines and wait.  It wouldn’t take much, or a very large market, to precipitate such a move. And once the momentum began, no government or central bank counter-action could stop it next time.

The US and global economy today are approaching the latter stages in the credit cycle, during which financial asset bubbles begin to appear and the real economy appears to be at peak performance (the calm before the storm?). This scenario was explained in this writer’s 2016 book, “Systemic Fragility in the Global Economy”. And in my follow-on book, “Central Bankers at the End of Their Ropes”, I predict should the Federal Reserve raise short term US interest rates another 1% in 2018, as it has announced its intent to do in 2018, it could very well invert the US Treasury “yield curve” and set off a credit crash leading to Bitcoin, stock, and bond asset price bubbles bursting.


About the Author

Dr. Jack Rasmus is author of the just published book, “Central Bankers at the End of Their Ropes? Monetary Policy and the Next Depression”, Clarity Press, July 2017, and the previously published “Systemic Fragility in the Global Economy”, also by Clarity Press, January 2016. For more information: http://ClarityPress.com/RasmusIII.html. He teaches economics at St. Marys College in Moraga, California, and hosts the radio show, Alternative Visions, on the Progressive Radio Network. He blogs at jackrasmus.com and his twitter handle is @drjackrasmus.


References

1. (2016). For this author’s quantitative index of financial fragility as predictor of instability, see the appendix equations in Jack Rasmus, “Systemic Fragility in the Global Economy”, Clarity Press, January.
2. Jack Rasmus. (2017). “Central Bankers at the End of Their Ropes?”, Clarity Press, August. See the review of this book by Dr. Larry Souza in this issue of the European Financial Review.

3. Claudio Borio. https://www.bis.org/publ/qtrpdf/r_qt1712_ontherecord.htm
4. Mohamed El-Erian and Huw van Steenis. (2017). “Economic prospects caught in a tug of war”, Financial Times, October 19, p. 18.

5. Mervyn King. (2017). “Warning Signs About the Global Economy”, Wall St. Journal, September 25, p.R6.

6. Gabriel Wildau and Tom MItichell, (2017) ‘Zhou’s ‘Minsky Moment’ see as reform signal to party elites’, Financial Times, October 23, p. 3.
7. Adam Samson. (2017). “BofA raises fears over “irrational exuberance”, Financial Times, November 15, 2017, p. 20; and Deutschebank, Global Financial Data, September 19.
8. Martin Wolf. (2017). “Fix the roof while the sun is shining”, Financial Times, December 6, 2017 p. 9.

9. Ciara Linnane, “Finance chiefs are becoming increasingly pessimistic about the future”, Marketwatch, Sept. 23.
10. For a survey and tutorial on blockchain, see “Blockchain Security and Demonstration”, by Yao Yao, Jack Rasmus-Vorrath, and Ivelin Angelov. https://github.com/JackKRasmus-Vorrath/Blockchain_Security_and_Demonstration/blob/master/MSDSProject_BlockChain_Final_v2.pdf
11. (2016). See chapters 11 and 12 of “Systemic Fragility in the Global Economy”, Clarity Press, which addresses the proliferating of unregulated shadow banking, new securities, and new highly liquid financial asset markets worldwide, and the relative shift to financial asset investing (from real asset) that has been underway in the 21st century.

12. In the US alone, more than $6 trillion in corporate bonds have been issued

The Duel Between Big Tech and Big Government

cyber law concept with 3d rendering robotic hand holding gavel judge

By Graham Vanbergen

Just five years ago you had no notion that “big data” would overtake oil as the number one traded commodity in the world, never heard of Bitcoin, that social media would play a significant role in reshaping global politics, that artificial intelligence and automation would threaten our way of life. The power politics duel between big tech and government is on.  At this pace of change, what do you think the next few years will bring?


It is difficult to believe that in such a short time frame, global politics, led by a chaotic American administration would only arrive because technology pushed the boundaries of propaganda and social influence and with it a new and dangerous era of isolationism and protectionism. Threats to the world order that has dominated for the last seven decades are now commonplace.

It’s actually quite a scary moment in time.

Tech firms have captured an amazing 42 percent of all the rises in the value of America’s stock market since 2014.1

Last year, Ford fired is boss Mark Fields for his complacency about technology despite near record profits in a challenging year, whilst Ford’s competitor General Motors goes all out in developing a range of autonomous electric cars.

Today, plastic cards make up 66 percent of transactions. Collectively, electronic transfers make up almost 99 percent of all global transactions – welcome to the cashless society – it’s already arrived.

Gene editing, a new form of personalised health care is about to arrive and trigger a total transformation of the expectations of health care and human longevity. The insurance industry is about to radically change with it as personalised data drives both product and pricing.

Half dozen crypto-currencies led by Bitcoin are now worth $650 billion in a market now overrun by hundreds of crypto-currencies.

We are, right now, on the threshold of a new era, just as industrialisation was in the mid eighteenth century. Then, it was a period of huge social and economic change that transformed human life from an agrarian society to an industrial one. It involved the extensive re-organisation of both the economy and the world we lived in. Centralised factories powered by coal and steam changed life radically and with it the institutions that supported society literally collapsed over a period of 70 years as society went through profound change. Politics was forced into dramatic change too.

Industrialisation and globalisation as we understand it are already becoming the old days and the time that civil society has to prepare for such fundamental and unstoppable adjustment is considerably shorter than that of the last industrial revolution.

For those whose jobs will be replaced by automation this time around, it’s the speed of the change that will cause huge political dissention.

Within just a few years driverless technology will see taxi drivers, bus drivers and America’s biggest workforce – the truck driver, moved towards obsolescence.  Multilingual artificial intelligent systems will replace another massive workforce – customer service workers. Then factory jobs will decline as reliance on human labour is replaced by more cost-effective manufacturing. Algorithms will be managing just about everything in daily life for ordinary citizens. For those whose jobs will be replaced by automation this time around, it’s the speed of the change that will cause huge political dissention.

Technology has already proved that it will propel a few people into ultra-wealth and political influence. The decisions of less people you can count on one hand will determine what half of humanity can see and read each and every day. The high profile owners of Amazon, Google and Facebook have amply demonstrated this already.


Already we can see the effects of these technologies on the economies of the western world. Conventional economics, such as it is, dictates that low unemployment drives wages up but at 4.1 and 4.2 percent unemployment in the US and UK, average earnings have, in real terms, fallen. This is in the backdrop of swiftly rising corporate profits, inequality and rapidly accelerating poverty – a deliberate result of the current political neoliberal ideology.2

From a political standpoint we have evidence of what is likely to happen next. The new technologies of the last industrial revolution were harnessed in such a way, as to manifest itself as a creeping authoritarianism that, for instance, gave rise to the crushing of trade union movements and any notion of societal income distribution.

Today, Britain’s recent Trade Union Act, Public Space Protection Orders, the “Snoopers Charter” along with the approaching abolition of the Human Rights Act are all dire warning signs. The alarming reduction in press freedom and censorship of social media and independent news outlets is another.

US constitutional attorney John Whitehead, counsel in the Paula Jones’ sexual harassment lawsuit against President Clinton describes what is emerging in America: “We are inching ever closer to a constitutional crisis the likes of which we have never seen before, and “we the people” are woefully unprepared and ill-equipped to deal with a government that is corrupt, unjust, immoral, unaccountable, non-transparent, fascist and as illegitimate as they come.”

Whitehead is describing the failure of the state in rapidly changing times.

This is evidenced by a truly Orwellian system built by Palantir, a data-mining company constructed by President Trump’s tech advisor Peter Thiel, who contributed to Trump’s ascendency to the Whitehouse in the social media coup over democracy. The Intercept describes this new technology as “deploying a new intelligence system, that will assist in President Trump’s efforts to deport millions of immigrants from the United States”.3

It is a “system providing its users access to intelligence platforms maintained by the Drug Enforcement Administration, the Bureau of Alcohol, Tobacco, Firearms and Explosives, the FBI, and an array of other federal and private law enforcement entities. It provides agents access to information on a subject’s schooling, family relationships, employment information, phone records, immigration history, foreign exchange program status, personal connections, biometric traits, criminal records, and home and work addresses.”

What this shows is that would be tyrants, now armed with new and ever more powerful tools will be able to attack and punish their perceived enemies whilst controlling ordinary citizens with frightening technologies. Social credit scoring systems are due for nationwide implementation in just two years time in China. Behave in a way that the government does not approve of and you will be penalised.

Many researchers say machine-learning algorithms are being given far too much power already. They are invisibly influencing decisions on all manner of important issues to society. The corporations who build them create the image that they are unbiased and objective. Edward Snowden’s 2013 revelations of government surveillance tools demonstrated you cannot trust government with technology or the corporations that build them.

There is a certain inevitability about these new technologies, just as it was in the 1850’s. A “crisis of governing” atmosphere already exists in the democratic west where politicians are now no longer beholden to constituents or their communities but to online supporters. They are no longer looking to persuade people with ideas; they are merely identifying those most likely to vote for them and will exclude everyone else. This is how communities will fall apart in the near future.

The likely scenario further down the line is that working age adults could well be facing chronic unemployment and plummeting living standards as a result of the fourth industrial revolution. Reactionary and revolutionary forces may gain a foothold to defend economically crushed communities, as politicians simply no longer respond to their needs.

The pace of change is quick. The transfer of power will be to an ever more authoritarian government or a tech regime. Either way, feasible democratic options are likely to evaporate in years to come.

Contempt for politicians will rise even further, not only among citizens but from the tech industry, which often assumes that a short-term governing party is little more than an obstacle to be overcome anyway.

Things will probably get worse before they have any chance to get better. For instance, after years of dismal reports and data, climate change has simply not got politically scary enough. Does it have to get violent before they listen?

At the beginning of the information technology revolution in the 1990s there was widespread hope that it spelt doom for authoritarians on the grounds that they would not be able to control it. The opposite has happened. The Internet has not democratised anywhere near as much as we have been led to believe.

In the meantime, excuses for government’s are quickly running out. First it was the inflationary period, then unemployment, then public debt, then financial deregulation so that citizens could borrow money to buy the type of things they wanted but could no longer afford. Everyone is tired of this failed economic experiment.

As demonstrated with Trump, the duel is already on as tech firms attempt to gain control of politics as they now understand they have the capability to dictate who gets into power.

The pace of change is quick. The transfer of power will be to an ever more authoritarian government or a tech regime. Either way, feasible democratic options are likely to evaporate in years to come.

About the Author

graham-webGraham Vanbergen’s business career culminated in a Board position in one of Britain’s largest property portfolio’s, owned by one of the biggest financial institutions in the world. Today he is founder and contributing editor of TruePublica.org.uk and director of the Equity Research Centre that focusses on Britain’s housing crisis.

References

1. The Economist: https://www.economist.com/news/business-and-finance/21733460-conventional-firms-have-last-got-their-technology-act-together-2018-will-be-year
2. The Guardian: https://www.theguardian.com/business/2017/oct/18/real-wages-fall-despite-low-levels-of-unemployment
3. The Intercept: https://theintercept.com/2017/03/02/palantir-provides-the-engine-for-donald-trumps-deportation-machine/

EDITOR'S PICK OF THE WEEK

China economic growth

China’s Challenging Search for a New Model of Economic Growth

By Danny Leipziger China cannot continue to rely on exports to drive its growth, but what are the alternatives? China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...

WISE DECISION MAKER GUIDE

POWER INFLUENCERS

Emerging Trends

The Future of Global Trade