Home Blog Page 1062

Islamic Economics in Presidential Election 2019: Synthesis of Tension in Political Islam in Indonesia

By Ahmad Dahlan

The issue of political Islam and the state in Indonesia apparently continues to roll ahead of the 2019 presidential election as President Joko Widodo from the Indonesian Democratic Struggle Party (PDIP) took Professor Ma’ruf Amin as a vice presidential candidate. Ma’ruf Amin is an ulema, scholar, and an expert in Islamic economics.


The declaration of cleric Ma’ruf Amin as President Jokowi’s running mate in next year’s presidential election has surprised many as the announcement occurred just hours after former Consitutional Court chief justice Professor Mahfud MD appeared to confirm he was the vice presidential choice of Widodo.

What also made the decision astonishing is the fact that Jokowi was nominated as a presidential candidate by the Struggle Indonesian Democratic Party (PDIP), the ruling party which had been perceived as a nationalist-red party and not too open to Islamic policies, although in the past presidential election, PDIP was supported by a mass Islamic-based party, particularly the United Development Party (PPP), the National Awakening Party (PKB), and several NU cadres.

Is the election of Amin as Jokowi’s Vice President candidate aimed at alleviating tensions over political Islam within the country or Jokowi is purely  seeking victory?


Issues Exacerbating Political Islam in Indonesia

Indonesia is panicked by the extreme ideology of right Islam which had given birth to many militant-jihad attacks.

There are three recent major issues related to the exacerbation of political Islam in Indonesia. First, the left-wing issue relating to the rise of communism. Of course, prejudice about the rise of communism is inseparable from the parties involved in the September 30 movement. “According to historians, in 1965 – 1966 Islamic youth and paramilitary groups with military backing massacred between 500,000 and one million suspected communists across the country.”¹

Second, the right-Islam issue is terrorism and Daulah Islamiyah. Indonesia is panicked by the extreme ideology of right Islam which had given birth to many militant-jihad attacks. Unfortunately, many Muslims are trapped in a circle of terrorism which is allegedly affiliated with the IS (Islamic State) movement in Iraq and Syria, and are willing to commit suicide terrorism. Even the latest Indonesia church attacks in Surabaya is very ironic, because the attacks were committed by a family of suicide bombers.2

Third, bilateral trade and development relations between Indonesia and China continue to be passionate. Xiao Qian (Chinese Ambassador to Indonesia) said in 2017 that the value of Indonesian exports to China reached U.S. $ 28.5 billion (up 35%), and Indonesian imports from China reached U.S. $ 34.8 billion (up 8.3%).3 This bilateral trade relationship is often politicised and linked to communism.

These three issues directly or indirectly create tension against the socio-political-economic conditions of Muslims in Indonesia. Can Amin address these problems? Also, what is the role of Islamic economics in neutralising Indonesia’s economic development going forward?


Ma’ruf Amin As Expert in Islamic Economics

PDIP seemed to be more interested in Ma’ruf’s position as an expert in the field of economics (Islam) and Chair of the National Sharia Council, which oversees and gives fatwas on the Islamic economic system in Indonesia – roles that are rarely known by the Indonesian people.

In the socio-political aspect, the appointment of Amin could be correct to alleviate the issue of SARA (ethnicity, religion, race and between groups) or identity politics.

According to the Chairman of the Central Leadership Board of PDIP, Andreas Pareira, the Ma’ruf Amin election could reduce the identity politics attacks aimed at Jokowi. To recall, in the 2014 presidential election, there were groups who spread the issue about Jokowi being a non-Muslim and his affiliation with the Indonesian Communist Party (PKI).4

In my opinion, PDIP seemed to be more interested in Ma’ruf’s position as an expert in the field of economics (Islam) and Chair of the National Sharia Council, which oversees and gives fatwas on the Islamic economic system in Indonesia – roles that are rarely known by the Indonesian people. With his breadth of knowledge and expertise in economics, his victory in the upcoming 2019 presidential election and tenure could help advance macroeconomic policies (national economic development) based on Islamic economics, and encourage the growth of sharia financial and banking institutions in Indonesia.


Relation of Political Islam and Islamic Economics in Indonesia  

If you look at the establishment of the first Islamic bank in Indonesia, it was considerably late compared to other Muslim-majority countries. Some findings suggest that this can be attributed to President Soeharto’s regime (New Order) and his policies towards Islam.

Interestingly, it was Soeharto who provided political-economic support for the establishment of the first Islamic bank (Bank Muamalat) at the time when the Islamic trend is giving a stronger sociological effect.

In an interview with Perwaatmadja (founder of the first Islamic bank in Indonesia and had served in the Islamic Development Bank), he explained one thing that Moerdiono (at that time the minister of state secretary) emphasised is the idea of ​​ Islamic bank establishment is not in line with the Indonesian Islamic State (NII).5 In fact, the idea of ​​establishing an Islamic bank is far from the mission of establishing an Islamic state.

Soeharto immediately carried out political and regulatory policies by issuing a Government Regulation (PP) concerning banks with the profit sharing principle,6 and he drive to pool the core capital so the Islamic bank could be realised in Indonesia. It is rare that President Soeharto quickly agrees with the Islamic policies/issues, especially if driven by political parties (pure politics).

This reflects that the use of Islamic economic system and banking as a way to change authorities’ views on political Islam is very effective and does not cause much Islamic tension with the state or Islamic phobia.

Meanwhile, it was suspected that Suharto’s support for the establishment of the Indonesian Muslim Intellectual Association (ICMI) was an opportunist strategy, because of his political stance that saw positive changes about “Islamisation” especially among the middle class.7

Also, Effendy’s research found that the relationship of the Islam and state was not easy. It had an impact on the political role of Islam to participate fully in Indonesian political development, especially in the 1970s and 1980s. Then the deadlock found common ground in 1992 when both accommodated interests.8

That conflict can be seen today in Jokowi-Ma’ruf tandem (a Nationalist-Religious tandem). Perhaps, PDIP wants to have a memorable victory in the upcoming 2019 presidential election the same way as the victory of Ganjar-Taj Yajin, in the Central Java Governor election (2018). If you look at the surveys, Jokowi has better electability than Prabowo.

Today, Islamisation is already in the public space, which was pioneered by the rise of the Islamic economy in Indonesia since 1990s. The political space before that barely allowed the formalisation of Islam/sharia now acknowledges many regulations such as sharia banking laws and sukuk.

Again, in the context of Islamic political economy, basically the Islamic economic system or the personification of Islamic economics like the election of Ma’ruf – which is perceived to be a synthesis and a way to reduce the political Islam tensions in Indonesia did not come suddenly, but has been in a very long process.

Referring to Hefner in the late 1980s, new modernists (young Muslim thinkers) began to emerge. They campaign not to conquer the country, but to renew education and culture with new (global) discourse on democratisation and human rights. They stated, the ultimate goal of Muslim politics is not to create a centralised state with monopoly rights to politics and culture, but the building of Muslim civil society that is able to balance the state power, and promote public culture about pluralism, public participation and social justice.9 Political structure which is the focus of Islamic economic thought and movement has been in motion since the 1980s and were discussed in various books and literatures. Again, at that time, the political Islam relationship and state was known as antagonistic (not mutually agreed).10 Hefner explained that between 1983 and 1985, the Indonesian government required all mass organisations to be founded on the Pancasila ideology. The New Order regime often interfered in Muslim organisations.11

Today, Islamisation is already in the public space, which was pioneered by the rise of the Islamic economy in Indonesia since 1990s. The political space before that barely allowed the formalisation of Islam/sharia now acknowledges many regulations such as sharia banking laws and sukuk.

Also, there has been various civil Islamic political economic organisations such as the Islamic Economic Community (MES), the Association of Islamic Economics Experts (IAEI), Indonesian Islamic Bank Association (Asbisindo) among others which carry out activities and encouragement for the government to support policies on development of Islamic economics system and Islamic financial institutions in Indonesia.

The positive impact that the Islamic economic system/sharia has is that it can ease tensions in political Islam, and the integration of the word “Islam/sharia” in the financial and business economic systems in Indonesia has created internal inclusiveness (among Muslims) because Islamic economics does not contain sensitive differences (khilafiyah).

The Islamic economics also creates external inclusiveness where Islamic financial institutions do not only belong to Muslims but can be owned and accessed by all people regardless of religion, race, ethnicity and class, even from the Chinese group. To note, some Islamic banks are only business units of conventional banks whose majority shares are owned by Chinese people. This model is difficult to be realised in other Islamic institutions.

These are the best conditions and moments about Islamic economics and its personification

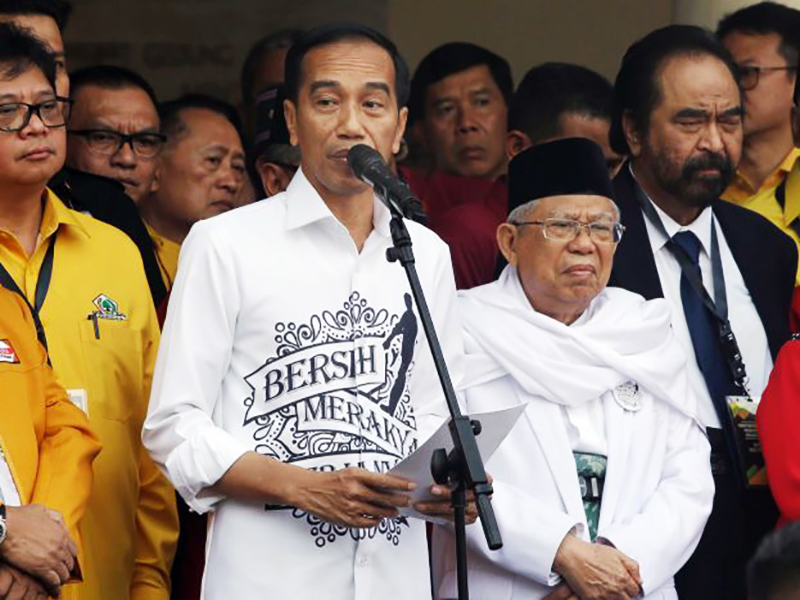
Featured Image: The battle lines for Indonesia’s 2019 presidential election were drawn when Mr Widodo (left) chose Mr Amin (right) as his running mate. (AP: Tatan Syuflana)

About the Author

Ahmad Dahlan is a doctor in Islamic Economics and Finance, and lecturer at the Faculty of Economics and Islamic Business, IAIN Purwokerto, Indonesia. He wrote many books, articles, competitive researchers; was active in the Sharia Economic Community Expert Council (MES); and served as a Deputy Chair of the Indonesian Economists Association (IAEI), Banyumas Regency. His article, “Political Economy of Islamic Banking in Indonesia,” was recently published in the American International Journal of Social Science (June 2018).

1. Lamb, Kate., “Beware the red peril: Indonesia still fighting ghosts of communism.” The Guardian. October 1, 2017.  https://www.theguardian.com/world/2017/oct/01/beware-the-red-peril-indonesia-still-fighting-ghosts-of-communism.

2. Horten, Alex. “Family of suicide bombers kills at least 7 in Indonesia church attacks.” The Washington Post. May 13, 2018. https://www.washingtonpost.com/news/worldviews/wp/2018/05/13/family-of-suicide-bombers-kills-at-least-7-in-indonesia-church-attacks/?utm_term=.3ea39b4b9fb9.

3.“Dubes: Nilai perdagangan Indonesia-China meningkat.” Antaranews.com. January 30, 2018.  https://www.antaranews.com/berita/681839/dubes-nilai-perdagangan-china-indonesia-meningkat.

4. “Jokowi-Ma’ruf Amin: Politik Identitas VS Isu Ekonomi,” Tempo.co. August 20, 2018.  https://fokus.tempo.co/read/1118744/jokowi-maruf-amin-politik-identitas-vs-isu-ekonomi.

5. Karnanen Anwar Perwaatmadja, interview, Tuesday, July 12, 2016 at Jakarta. The sentence were processed by the author.

6. At that time invited PP No. 70, 71 and 72 concerning banking based on profit sharing principle.

7. Hefner, Robert W. “Islam, State, and Civil Society: ICMI and the Struggle for the Indonesia Middle Class.” paper. Mujani Saiful. “Kultur Kelas Menengah Muslim dan Kelahiran ICMI: Tanggapan Terhadap Robert W. Hefner dan Mitsuo Nakamura.” on the Nasrullah Ali Fauzi (ed.), ICMI Antara Status Quo dan Demokratisasi, (Bandung: Mizan, 1995), p. 76-77.

8. Bahtiar Effendy, Islam and the state: the transformation of Islamic political ideas and practices in Indonesia, thesis (doctoral), (Ohio: Ohio State University, 1994), p. 214.

9. Hefner, Robert W. “Public Islam and the Problem of Democratization”, Sociology of Religion, Oxfort Journal, Published by: Oxford University Press, Vol  62, No 4, 2001, p. 504.

10. Hadiz Vedi R., “Indonesian Political Islam: Capitalist Development and the Legacies of the Cold War.” Journal of Current Southeast Asian Affairs. 30, 1, 3-38.

11. Hefner. Public Islam, p. 505.
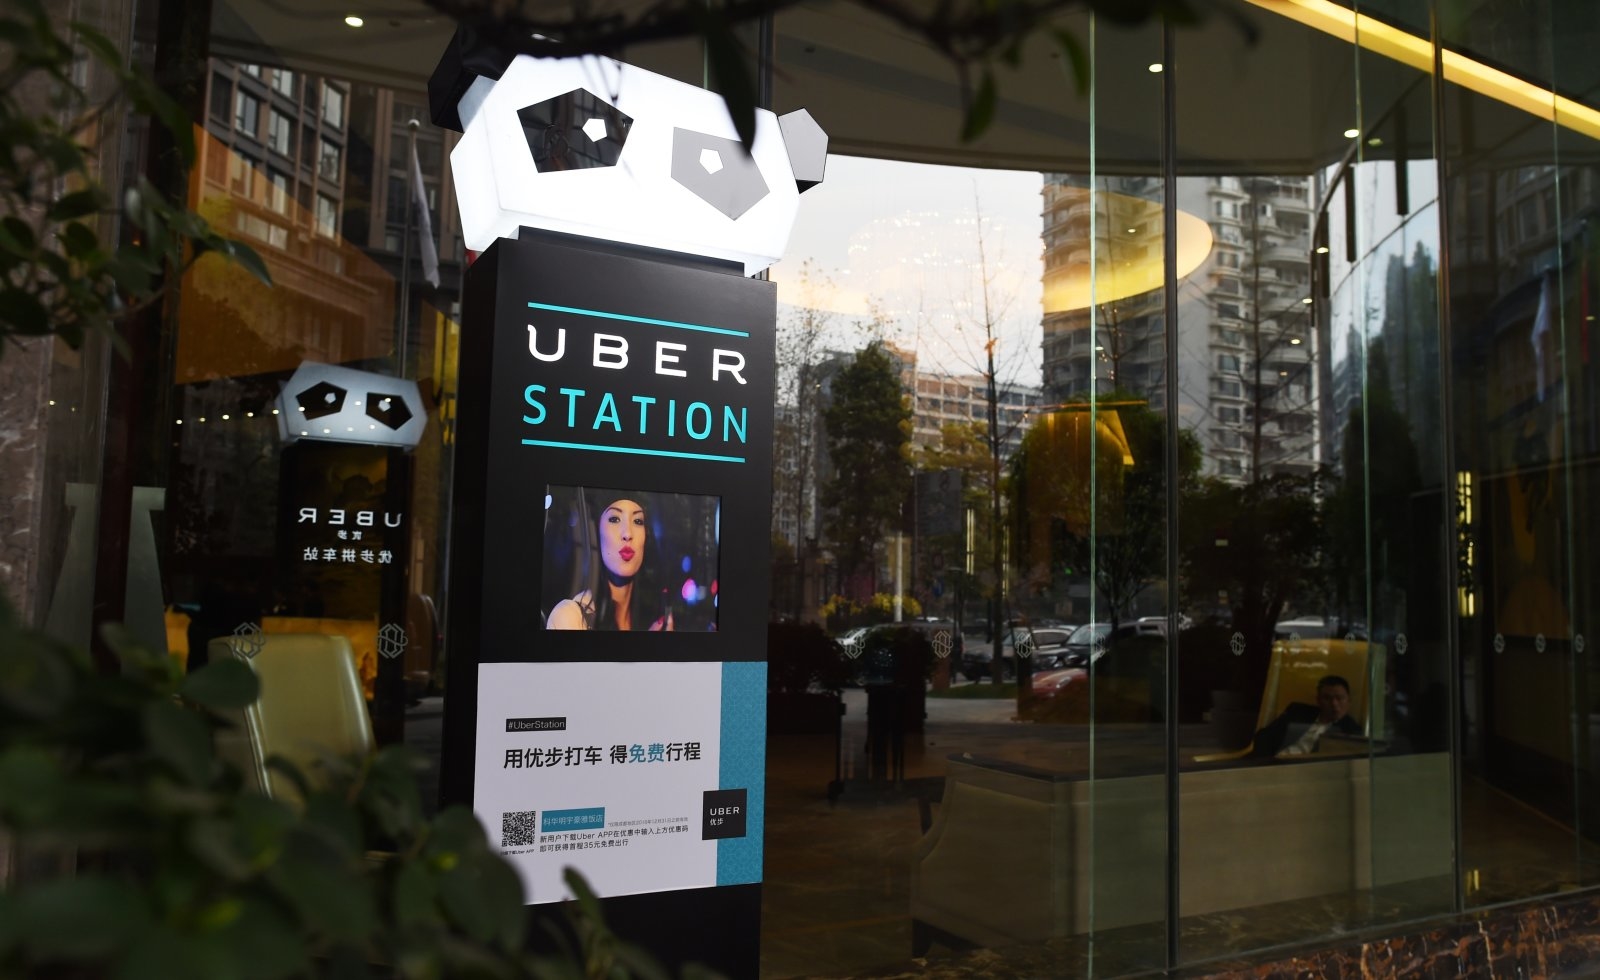
Platform Strategy and Uber’s Exit from China

An Uber Station is seen outside a hotel in Chengdu, in southwest China's Sichuan province on March 20, 2016. China's transport minister warned online taxi-hailing companies on March 14 over subsidies leading to "unfair" competition, as US giant Uber and homegrown rival Didi spend billions in their battle for market share. / AFP / GREG BAKER (Photo credit should read GREG BAKER/AFP/Getty Images)

By John Colley

This article assesses the necessary conditions for effective platform strategy by considering the evolution of the ride hailing industry and Uber’s late entry to China. Conclusions include the consequences of being slow in markets dominated by network effects and the importance of local knowledge and connections. Attrition-based competition may arise as a consequence of the ease of raising funds.

After just two years in the Chinese ride hailing market, Uber chose to leave after losing undisclosed sums by at least $2Bn. Uber was a late entrant to China in 2014. Following a battle with incumbents Didi Chuxing, it was forced to negotiate an exit due to mounting losses and increasing shareholder pressure. The Chinese Uber position was sold to Didi Chuxing in return for 17.7% of their business. It remains unclear whether this holding ultimately has any real value. At that time, Uber CEO Travis Kalanick was also Chairman of the Chinese operation and had a personal interest in the business. In 2017, he was subsequently unseated as CEO of Uber following a plethora of PR and legal crises. Business strategy was also a significant concern. Since the exit from China, Uber has similarly withdrawn from Russia and South East Asia. The battle in India with Ola is also resulting in major losses and there are unconfirmed reports of negotiations there too.

What can be learned from this debacle about both “platform strategy” and “doing business in China”?

What does this tell us about leadership in a Silicon Valley business world awash with cash, where raising funds appears easier than generating profits?

China’s taxi market

In China, Uber’s real problem was their late arrival and competitors’ consolidation to form a powerful coalition of Didi Dache and Kuadi Dache from which emerged Didi Chuxing. Didi had backers with deep pockets in Tencent, Alibaba, sovereign wealth fund CIC and Apple. A consequence was Didi claiming an 80% market share with Uber a comparative minnow in China. Taking on an established business with a dominant market share and vast resources in their home market is highly risky, without a better product or ability to attack poorly-serviced niches. Uber had started in 2009 but did not enter China until 2014. Five years is a significant lag in a world of platform start-ups where late arrival usually creates an impossible position.

Uber had other problems. It lacked local connections and knowledge, both of which are critical in many Asian markets, in China particularly. In China, Uber employed 600 people which is inadequate given the size of the market and the number of cities requiring connections to be established. There, product adaptation is critical due to local requirements such as cash, language or differing modes of transport. Uber, like many U.S. companies, is keen to have a standardised approach. This normally keeps costs down but does not entirely address local need. Instead of local adaptation, U.S. businesses tend to support with enormous marketing and promotion budgets. The objective is to adapt to the demands of the product. Uber’s strength of having an international app is also their weakness; it requires a high degree of standardisation.

In China, Uber’s real problem was their late arrival and competitors’ consolidation to form a powerful coalition of Didi Dache and Kuadi Dache from which emerged Didi Chuxing.

As an inward looking country, China may not have understood Uber’s potential benefits for the ride hailing market. China wants technology and employment from western companies and are keen to see benefits being retained internally. Uber brought little of either as their app is not proprietary, and in the Chinese context, 600 employees is not significant. However without Uber’s competition, it is fairly certain that Didi will cut driver subsidies and increase customer fares. There was some evidence of this following the merger of Didi Dache and Kuadi Didi. Competition is necessary to ensure both users and drivers get a good deal. Competition also usually stimulates demand through high levels of promotion and low fares. This in turn creates more driver employment and cheap and efficient transport. With Uber gone, demand is much more likely to flatten out. There will be opportunities no doubt for local firms to fill niches, as a virtual monopoly supplier may lose its competitive edge.

In highly competitive Chinese markets, foreign firms are realising that margins are thin. The lure of enormous volumes in a rapidly expanding market draws western firms. However, they are often ill equipped to compete in such different markets. Uber chose not to use local partnerships and local knowledge to forge connections. This can be imperative in many country markets. However, in China, where many western firms do use partnerships, they may make more progress. The major risk though is that instead of buying out the local partner, they sell out to them leaving their expertise and technology in China. SABMiller experienced this when disposing of the Snow beer business which had 20% of the market but with narrow margins. Politically, the government has a significant say in the future of industries and the ultimate trajectory of western firms in China. 

Platforms and Network Effects

Technology investors are not only flush with funds but they are also targeting new platforms. Platforms create markets by linking buyers and sellers efficiently. First mover advantage followed by rapid expansion is generally viewed as critical to long-term success. This initially involves incentivising the participation of both buyers and sellers. The participation of more sellers attracts more buyers which in turn attracts more sellers. These are termed as two-sided network effects like in the case of Amazon, Airbnb, and virtually all other platforms. As there are high levels of transparency, price competition should be fierce. Facebook is another example, in which a social network infrastructure has been constructed. This offers the opportunity to connect with a large number of people and deters users from moving to other social media platforms. These network effects create a “winner takes all” end game in which the first mover, backed by appropriate levels of resource, win. Late entrants need to move very rapidly to minimise the time the first mover has sole access to the entire market. They achieve this by investing much greater resource and creating novelty features which might attract users away from the first mover. Even in these circumstances, the second mover has a major uphill task.

Whilst Facebook, Amazon, and Google have the capacity to make enormous financial gain by dominating a market with their platform, Yahoo, LinkedIn, Twitter, and Snap Inc (Snapchat) have all struggled to monetise their user base. Twitter has only recently started to make money from being President Trump’s main communication channel for policy. This has drawn more advertising income.

The core belief for ride hailing is that users want cheap and responsive transport. Responsiveness means that suppliers generally require a large fleet of taxis providing constant availability. As self-employed drivers want large numbers of fares and to minimise down time, they are attracted to a firm that maximises the number of fares. In return, Uber, through low customer pricing, attracts more trade and in this way attracts more drivers. There is some evidence that Uber pays drivers less per trip but the sheer volume of work more than compensates the driver.

Ride Hailing Investments

In the case of ride hailing apps, investors are backing a number of start-ups with big money generated from becoming winners across global markets. Examples include Uber, and Lyft in North America, Didi Chuxing in China, Grab in South East Asia, and Ola in India. Investment has now vastly exceeded $50Bn in the industry. Uber has raised $22Bn in 18 funding rounds,1 whilst Didi Chuxing has raised $15Bn. The huge sums of investment have resulted in battles of attrition across the globe where ride hailing businesses incentivise recruitment drivers and subsidise customer fares. The intention is to achieve the “winner takes all” position then cut the subsidies once the competitors have left. The consequence of this strategy is that Uber lost $4.5Bn in 2017 and is a long way from convincing the market of its $68Bn valuation unless it can rapidly curtail haemorrhaging cash. Uber plans a share placing in 2019 so that the investors and founders can start to realise some of their paper gains.

The core belief for ride hailing is that users want cheap and responsive transport. Responsiveness means that suppliers generally require a large fleet of taxis providing constant availability.

In an attempt to resolve this situation, Softbank has invested around $20Bn in various ride hailing providers, with $9Bn in Uber and significant investments in Didi Chuxing, Ola, Lyft, and Grab.2 Since then, there has been some market withdrawals to reduce the various battles of attrition raging across the globe. Softbank has offered the view that Uber should consolidate back to North America and Europe. There it has strong positions and more transparent and accessible markets in which local knowledge and government contacts are less critical.


Will the Winner Really Win?

The major concern for all ride hailing apps is that there are low switching costs for both drivers and customers. It costs little for a customer to have two or three ride hailing apps on their phone and select the cheapest and most responsive. Similarly, drivers often work for several taxi companies at the same time they are genuinely self-employed. Should a “winner” emerge and attempt to increase fares, customers may look to other apps, and the speed with which drivers can also transfer may mean that local competition arises again. This could be a problem for Didi Chuxing in China.

The reality is the relative ease of raising funds to invest in platform strategies is financing wars of attrition between competitors with similar offerings. Some cannot hope to win. Being first is important followed by rapid development of local knowledge and connections and coupled with the finance to move rapidly with major substance. If not, first to markets dominated by network effects then new players may have to wait for changes in technology before they can meaningfully compete. If local players can move first and raise funds, their advantage of local knowledge and rapid movement should allow them to win the battle. Didi Chuxing has 52% of the global market, although most of it is in China. Grab and Ola have strong positions in their home markets and are ranked third and fourth behind second placed Uber. Uber has a presence in over 70 country markets, over twice the number of Didi, Grab, and Ola.3  Outside of North America, Uber has been first to many European markets where it has strong positions, which suggests long-term dominance. However, it has arrived later in Asia where local competitors may have already created dominant positions. One suspects that Uber will have to consolidate to little more than Europe and North America if it wants to make money as the 2019 IPO approaches.

Overall

The ease of raising funds for platform funding is contributing to futile competition in the ride hailing industry. Some incumbents have such strong positions with network effects, funds and local knowledge and connections a new entrant has little prospect of success. There are lessons for other developing platform investments.

Being first is important followed by rapid development of local knowledge and connections and coupled with the finance to move rapidly with major substance.

Entrepreneurs who start and develop platform businesses are rarely the right people to take them forward into rapid growth and eventual maturity when cultural values, ethics, structure, and processes matter.

Finally, China is a difficult market for western businesses where local knowledge and connections, technology and employment are important necessities to compete effectively. Competitors move rapidly to copy products and compete whilst many are government owned and do not have to make profits. It is not a level playing field but some western businesses do flourish in China. However, many western businesses are still pondering their losses and considering their options.

About The Author

John Colley is Professor of Practice in Strategy and Leadership, Pro Dean, at Warwick Business School. Following an early career in Finance, John was Group Managing Director of a FTSE 100 business and then Executive Managing Director of a French CAC40 business. Currently, John chairs two businesses and advises private businesses at board level. Until recently he chaired a listed PLC.


References

1. “Uber Fundraising”.  https://en.wikipedia.org/wiki/Uber

2. “Softbank to Switch $20Bn ride hailing stake into Vision technology fund.” Financial Times. https://www.ft.com/content/87e31a34-47d8-11e8-8ee8-cae73aab7ccb

3. “Uber is still the leader in global ride hailing”. The Drive. http://www.thedrive.com/tech/22362/uber-is-still-the-leader-in-global-ride-hailing-report-says


The Political Personality of Donald Trump

By Winston Nagan and Samantha Manausa

What kind of a personality is Donald Trump? In this article, the authors share their insights on what type of leader Trump is by looking at various perspectives, and whether his traits are compatible with what the democracy requires as well as what his recent conducts as president indicate about the political history of America.

Donald Trump, in poetic terms, resembles the Green Knight in the poem Sir Gawain and the Green Knight. The Green Knight storms into the aristocratic and sophisticated castle of King Arthur. He represents the unruliness and unkemptness of crude, untethered nature. Donald Trump’s personality is a complex combination of natural forces, many of which have a psychopathological edge to them. From the point of political psychology, he is the quintessential illustration of the power-oriented and directed personality. There is nothing necessarily bad about a leader seeking power. However, the methods he uses to get power may reveal complex personality traits, some of which are infused with latent psychopathologies. Since he has achieved power, these pathologies have even begun to express themselves in the form of a lethal leadership behaviour. The idea of a political personality that is oriented to power is expressed in scholarly terms as the “private motives of the actor displaced on public objects and rationalised in the public interest.” Clearly, Trump displaces something on public objects and provides garrulous justifications such as “Make America Great Again”, “Beware of Outsiders”, and “We are Under Threat and I have a Solution”. Trump was able to wedge himself into the political process by appealing to a minority of white voters who were still wallowing in shock and awe over the election of a black president.

Trump used birtherism with relentless tenacity to tarnish or obscure the truth. He did this intentionally, which indicates that his intention of exploiting lower class racism may be grounded in a deep pathology in which he gets personal gratification from it.

We have probably underestimated the psychological effect of this change in American politics. Not only was President Obama black, but he was also intellectually skilled and politically competent, matters which severely affected the collective eco-structure of the lower class, the economically deprived white electorate. Regardless of its depressed socio-economic status, this minority had always comforted itself by assuming superiority over blacks in the social status hierarchy. That last refuge of security and whiteness is now threatened by a change in national leadership to a black president. Trump, who, notwithstanding his economic status, has a perspective that is largely lower class and laced with crude vulgarity, probably felt his own whiteness threatened. Thus was born the idea that the president, elected by the American people, did not carry a real mantle of authority. This idea went mainstream in the form of birtherism and the assumption that President Obama could be humiliated by being forced to produce his birth certificate. That this lie endured for so long is a matter of concern which certainly requires further investigation. The explanation probably lies with the administration of President George W. Bush, whose advisors suggested that political truths are largely contingent and can actually be minimised if not obliterated by the repetition of a lie, provided one has the resources to flood the media with the lie. The lie will come to be regarded alongside the truth, compromising truth itself and undermining the veracity of the principle of public life. Trump used birtherism with relentless tenacity to tarnish or obscure the truth. He did this intentionally, which indicates that his intention of exploiting lower class racism may be grounded in a deep pathology in which he gets personal gratification from it.

Trump has appropriated these ideas – namely, the purposeful repetition of a lie and the management of the airwaves – as central features of his administration. Lie after lie so overwhelms the media that there is virtually no discussion of the central issues in his policies. It would be tedious to attempt to recount all the lies relevant to the body politic; the very tediousness of it implies that Trump has utilised lies with great success. The lies he proclaims are shameless, and often come into conflict with previous lies that he has espoused. It is clear that the lies he spews about his opponents are motivated only by a desire for political advantage. There exists no fundamental model of ethics or morality in his utterances.

What is clear is that Trump’s personality has a number of traits that are pathological in some degree and would appear to be incompatible with what a real democracy requires.

So, what kind of a personality is Donald Trump? The technical literature offers us a multitude of perspectives through which his personality can be understood. First, although a person’s principle traits may be indicative of personality development, that person may have elements of narcissism in his personality. In a more exåtreme form, narcissism may be a psychopathic disorder. In general, however, it straddles the line between egregious behaviour and tempered behaviour. Trump’s administration is saturated with narcissism; both his campaign and presidential platforms all tend to focus more on Trump than on his ideas or plans. Another framework of personality is more concerned with symptoms of obsession and compulsion. This could be reflected in Trump’s obsession with denigrating others who are deemed “outsiders”, such as Muslims and Latin American immigrants. This can also indicate a psychopathic disorder. Other pathological perspectives would consider the Machiavellian outlook, and would find Trump to be a radically manipulative personality. It is true that leaders need some measures of this to be successful. However, in extreme forms, manipulation is done only for the sake of manipulation, representing yet another form of psychopathological behaviour. Similarly, the normal personality may also have a streak of paranoia. In a sense, Trump’s impatience with criticisms or challenging questions from the media are indications that there is a small level of paranoia in his political style. Finally, two compelling perspectives are those of the authoritarian personality and totalitarian personality. Trump has shown a tendency toward authoritarianism, though they were somewhat subdued during his campaign. It is difficult to see him in totalitarian mode, but this is possibly a latent feature of his outlook. What is clear is that Trump’s personality has a number of traits that are pathological in some degree and would appear to be incompatible with what a real democracy requires. His recent conduct as president, which includes threats to withdraw security clearances of intelligence officials, banning a White House reporter from a correspondence reception, indicating that the new Russian assault on American democracy will target Democrats and not Republicans, dismissal of national security advisors and the Secretary of State, and more, indicate that we may be in for a rough time in the political history of our nation.  

About The Authors

Winston P. Nagan is Professor of Law at University of Florida, and the Founding Director, at the Institute for Human Rights, Peace and Development and Fellow, Royal Society of the Arts. He is an alumnus of the University of South Africa, where he did his B.A (Law); Brasenose college, Oxford, where he got an M.A (Juris); Duke School of Law where he did LL.M. and later Yale School of Law, where he obtained his Doctorate degree in law.

Samantha R. Manausa is an undergraduate with honors at the University of Florida, studying religion, political science, and Spanish language. She is currently researching contemporary global issues as a junior fellow of the Institute of Human Rights, Peace and Development at the Levin College of Law, University of Florida.

The Demise of Global Britain

By Graham Vanbergen

The almost universal collapse of British foreign policy could not have been timed any more accurately than right now – a time of real and perceived deepening uncertainties around the world. Graham Vanbergen argues that Without Brexit, merely a scheme of political self-harm devised solely by the ruling Conservative party decades ago, Britain would now be revelling in its new-found powers by being the global super league mediator with its characteristic calm and cool Britannia charm.

Unfortunately for Britain, it decided to be the forerunner of isolationism by abandoning the close relationships it had built that firmly anchored America with an ever more confident European Union. Both were trading partners that were more recently advancing on a more adversarial trajectory, now currently locked in a war of words and finger-pointing with all the possibilities of a crumbling relationship that could lead to a future trade war.

“Keep Calm – It’s only a trade deal.”

Britain with hundreds of years of diplomatic experience could have been the trusted umpire of Atlanticism while taking full advantage of its position in the meantime.

Today, global Britain is witnessing the complete opposite of “taking back control”. If anything, as the London School of Economics recently put it, the real Brexit dividend, if ever there was one, is that we are facing “a decade of economic underperformance against its peers.” 1

After the two years since Britain’s EU referendum, it has become clear there never was a plan B. Aspirations of reviving its past global influence have fallen into what looks like a nightmarish delusion espoused by the political and media mouthpieces of the right wing. Far from being a small island nation punching way above it weight – Great Britain, as it was once known, is the now the weakest link of the global power super league.

Britain has already lost so much influence in the world in just those two years. With fast-changing geopolitical alliances and strategies at play today, the world requires a calm head. Britain’s attributes and skillsets in cyber-warfare and defence, energy, security and diplomacy could have been key. Years of policymaking and planning now lay in tatters.

Europe and America have demonstrated that political extremists are on the rise – and Britain’s liberal democratic values would have been invaluable at a time like this. Sadly, Britain is now in the same boat as those stoking nationalistic sentiment and trampling all over civil liberties and human-rights whilst political infighting consumes the attention of everyone and everything.

Weak and wobbly

In the meantime, Britain is not just facing the challenge of negotiating Brexit – it is demonstrating in front of the world stage its incompetence and more than anything that it lacks the confidence to do so in a manner befitting a world power.

The Financial Times wrote this month that: “The British prime minister’s insistence that the UK could leave the EU without a formal agreement was always an empty threat. It was never taken seriously in Brussels, still less in Whitehall.”

Even more recently there has been talk of a no-deal Brexit with the EU. And as the FT opines the result of that would be acrimony and an isolated Britain – “guaranteeing chaos on all sides” and a “series of co-ordinated unilateral actions would be required to avoid a national crisis.”2

Unfortunately for Britain, it would then be reduced to asking the EU for help simply to function – a far cry from Conservative party promises at the last election of a strong and stable government.


The expected economic Crash?

Although Britain’s economy has not yet crashed due to the Brexit vote as some had predicted, growth and productivity are now rapidly slowing and investment in the UK is currently on hold – pending years of squabbling with the unknown. There is no chance that Brexit will be over any time soon no matter who decides what.

A survey of 600 Eurozone corporations by UBS recently found that as much as three-quarters of companies headquartered in EU countries – plan to shift at least some of their investments away from the UK. About 10 percent intend to leave the UK entirely.

One thing that is becoming clear, the Brexit decision is now having a negative impact on daily life. And the one bit of good news there is – employment, hides a nasty truth. According to the latest figures, the UK’s employment rate stood at 75.6% of the working age population, the joint highest since comparable records began in 1971. However, the UK now has the weakest wage growth in the G7 – a fall from the top to the bottom in little more than 18 months. It now also boasts the worst performance in wage growth in all the 34 OECD countries – except Mexico and Greece – an accolade many have taken note of.3

The news about Brexit just keeps getting worse now that organisations are investigating its reality to determine their own prospects.

A survey of 600 Eurozone corporations by UBS recently found that as much as three-quarters of companies headquartered in EU countries – plan to shift at least some of their investments away from the UK. About 10 percent intend to leave the UK entirely. For instance, according to the Society of Motor Manufacturers and Traders, investment in Britain’s car industry has been reduced by almost 50 percent already.4

No one, not even the Conservatives knows what kind of Brexit might be agreed at this late stage. Why would any organisation invest in a business environment like that? And while most reasonable people would agree there is likely to be some economic transition cost, Brexit is little more than a game of Russian roulette encouraged by a party ill at ease with itself and the world around it.

Crisis after crisis – then tension

Britain has suffered more than many as a result of the banking-induced disaster that still pervades civil society a decade after its almost universal implosion. Austerity has caused a crisis of daily life, not least a health crisis, a housing crisis, a social care crisis, a pensions crisis, a poverty crisis and much more.

The prospect for Britain does not look anywhere near as rosy as hard-Brexiteers would have you believe. Two elections in 2022 and 2027 will define the next decade and enduring its political tensions will permeate through every family, every community, every corporation and the decisions they all make. The opportunity to make hay with the Brexiteers dream of a new economic era looming on the horizon appears to be a just a mirage the further down the road we go.

Muted wage growth and anticipated restrained investment decisions will cause a weakened economy to contract further. The combined effects of a soon to be felt fall in house prices and commercial buildings will signal what is in store. What confidence remains will evaporate in uncertainty and instability – a self-perpetuated recession will grip the nation. However, Britain has weathered these storms before.

Some of Britain’s post-war recessions have been brutal. In the mid-1970s recession, the economy contracted 6.1 percent between 1973 and 1975. In the early 1980s recession, it was 5.2 percent. The Great Recession we have just experienced caused the economy to contract by 6.2 percent whilst doubling the national debt to nearly 90 percent of GDP – way beyond that of both world wars. Unemployment spikes reached an eye-watering 11.9 and 10.7 percent in the 1980s and 90s respectively – but the nation ploughed on.


Not just economic threats

The greatest post-Brexit threat for Britain is that its legitimacy as a global power has completely disintegrated in little more than a couple of years and by the time its economy has recovered and politicians have stopped fighting, the world will have moved on without her.

What the Brexiteers won’t tell you though is the sheer body of information becoming available as institutions prepare themselves for the storm ahead. And there are threats other than economic ones.

Again, in front of the world stage, democracy in Britain has taken a savage beating. The Electoral Commission’s investigation into the official pro-Brexit referendum campaign was leaked, revealing colluding campaigners such as “Vote Leave” guilty of seriously breaking electoral laws on multiple accounts. So far, politicians have failed to act amid insignificant fines. Stories are emerging of Think Tanks and charities pushing Brexit for climate deniers, pharmaceutical and agribusiness corporations with disinformation, propaganda and fake news.5

The Scottish nationalists are already salivating over the Brexit bomb and its resultant fallout. Will the Scottish National Party go for an early referendum in spring 2019 or wait for a couple of years when the full extent of the Brexit apocalypse will have become apparent to all? The point is that the British Union is much less likely to survive when all is said and done.6

All in all, the greatest post-Brexit threat for Britain is that its legitimacy as a global power has completely disintegrated in little more than a couple of years and by the time its economy has recovered and politicians have stopped fighting, the world will have moved on without her.

The hard-right vanguard of Boris Johnson, Jacob Rees-Mogg, Liam Fox, et al driving Brexit into rough waters equals little more than political anarchy for Britain. Being millionaires and with the benefit of revolving doors, they will, no doubt be ready to jump ship like David Cameron did once reality and the repercussions and resentment starts to bite back in the years to come. 

About the Author

Graham Vanbergen’s business career culminated in a Board position in one of Britain’s largest property portfolio’s, owned by one of the biggest financial institutions in the world. Today he is founder and contributing editor of TruePublica.org.uk and director of the Equity Research Centre that focusses on Britain’s housing crisis.


References

1. Zenghelis, Dimitri. “The real Brexit ‘dividend’: a decade of economic underperformance and political crisis,” LSE. (2018): http://blogs.lse.ac.uk/politicsandpolicy/the-real-brexit-dividend/

2. “The Dire Consequences of a No-deal Brexit,” Financial Times https://www.ft.com/content/0ebec84c-8e64-11e8-bb8f-a6a2f7bca546

3. “UK Wage Growth Weakest in G7 since Financial Crisis,” Financial Times https://www.ft.com/content/c4437c9e-7ec4-11e8-bc55-5 0daf11b720d

4. “A Third of European Firms to Cut Investment because of Brexit – Survey,” Reuters. (2018): https://www.reuters.com/article/uk-britain-eu-investment/a-third-of-european-firms-to-cut-investment-because-of-brexit-survey-idUSKBN1JM1MS

5. Vanbergen, Graham. “Brexit: The Great Con That Will Ruin Britain,” TruePublica. (2018): http://truepublica.org.uk/united-kingdom/brexit – the – great – con – that – will – ruin – britain/

6. Deer Chris. “Is the SNP Reviving the Idea of Another Scottish Independence Referendum?” New Statesman. (2018):  https://www.newstatesman.com/politics/scotland/2018/04/snp – reviving – idea – another – scottish – independence – referendum

Opportunities and Challenges of International Retailing in China

Night view of Nanjing Road in Shanghai.

By Lisa Qixun Siebers

The performance of foreign retailers in China has shown a reversed U shape since their market entry in the 1990s. By the destruction of digitalisation, large retail giants continue to reduce both the number and the size of their stores, protecting bigger loss but worsening their sales too. They launched omnichannel retail after China’s online sales had started to soar in 2010 and introduced the experience-based retail ecosystem mostly in collaboration with local companies. However, their long-term performance will largely rely on the local consumption demands and institutional environment.

China has become the world’s largest e-commerce market, accounting for 40% of the value of worldwide e-commerce transaction by 2017, up from less than 1% ten years ago. China’s online retail market has also become the world’s largest, with a 38% annual growth rate of US$830 billion by 2017, compared to 14% in the U.S. In 2016, China’s internet users reached to 731 million, overtaking the combined number of the European Union and the U.S.; 20% of the internet users rely on mobile only, compared with 5% in the U.S., and China’s mobile payment has 11 times the transaction value of the U.S. The online competition has boosted customer-centred and experienced-based innovation in a physical shopping environment, represented by Life Mall (e.g., Parkson from Malaysia) and themed department store – Fashion Gallery (e.g., the New World from HK). Most of the foreign retailers have also started to emphasise private labels or owned brands, such as Carrefour’s Quality Line and French Touch brands. For foreign retailers or brands to succeed, it is important to understand the key development stages of China’s retail sector and what foreign retailers have experienced in the market in order to set up potential effective strategies they may implement in the future.

To increase online sales, many foreign retailers have collaborated with Chinese online platforms such as Alibaba and JD.com or social media platforms such as WeChat owned by Tencent Group to increase sales through e-tailing.

1995 – 2005 market development

China opened its retail market in the mid-1990s, when foreign retailers started to enter by introducing retail formats that were new to Chinese consumers, such as supermarkets and hypermarkets. They were obliged to adapt to the local environment such as laws and regulations after entry and used adaptation strategies to penetrate the market. China retail sector fully opened in 2004 following the World Trade Organisation agreement, when foreign retailers obtained all freedom to expand in the country. Until then, they have cultivated the shopping habits of Chinese consumers who switched their shopping from merely local open market to sometimes supermarkets, especially the middle class enjoyed more shopping in modern retail format. During this period, price was the key competitive factor.

2006 – 2010 market competition

After fully openning China’s retail market, competition has increased. Domestic retailers started to benefit from foreign retail knowledge transfer and capable human resources who change their jobs between foreign and domestic retail organisations. The Chinese government also encouraged domestic retailers to compete with foreign rivals. For example, the merge of two large Chinese supermarkets Lianhua and Huanlian in 2010 formed the largest supermarket chain in China, managed by state-owned parent company Bailian Group.

2010 – date growth potential

Benefiting from the increase in the number of middle class and the improvement of technological infrastructure, China’s internet sales started to soar in 2010, resulting in the declination of large-sized physical stores. Some foreign retailers exited from China, e.g. Best Buy; some sold majority of their shares to local companies such as Tesco and B&Q. Majority of foreign retailers closed stores that did not make a profit, including Wal-Mart and Carrefour.

Since 2015, the Chinese central government called for participation of provincial governments, the general public, and online retailers to encouraging digital players to experiment before enacting official regulations. Since 2016, the Chinese central government has encouraged high-level offerings of both products and services and collaborations between physical stores and online platforms, calling for retail stores to improve their uniqueness, core competencies, and differentiation. In 2017, the first cybersecurity law became effective, which includes measures to protect personal information, security requirements for network operators, and restrictions on personal and business data transfers. There are intensive activities undertaken by retailers both online and offline. On the one hand, the majority of retailers started to emphasise their online businesses; on the other, online retailers started to open physical stores. For example, Alibaba’s Hemashengxian (‮٢٠‬马٪ح鲜) sells fresh food in residential areas to provide convenience to customers.

To increase online sales, many foreign retailers have collaborated with Chinese online platforms such as Alibaba and JD.com or social media platforms such as WeChat (the Chinese twitter) owned by Tencent Group to increase sales through e-tailing (electronic retailing). For example, Wal-Mart formed a collaboration with both JD.com and Tencent in 2016 and mid-2018 respectively. By August 2018, some stores of Wal-Mart in Shenzhen (where its headquarter is located) have achieved 50% of its total monthly sales online; Carrefour is collaborating with Tencent too; RT-Mart is collaborating with Alibaba; and new entrants Macy’s, Costco, Woolworths, and Sainsbury’s chose to enter online first by collaborating with Alibaba’s Tmall. Virtual platforms help to enhance customer experiences by offering fast information flow and providing convenience in purchasing and delivery.

Consequently, there is also a trend of continuously expanding physical stores, especially shopping malls, where experience-based shopping environment has been intensified. Many shopping malls have been upgraded to include entertaining and services centres such as floors for dining, children’s playground, gym and so on. Some retailers use high-tech to provide the advanced virtual environment, such as B&T (the new name of B&Q in China) introduced online showroom in store in 2017, by which consumers can see how products look like when in a room by clicking on the screen while passing by these products. Others open flower shows or mini zoos in their shopping malls to attract customer flow. These possibilities attract more retail investors in physical stores. For example, the British department store House of Fraser opened its first store in Nanjing in 2016, named East Fulaide (东‮$‬و:ض来‮<‬w, meaning Eastern happiness and virtue), offering over 20 private labels.

Challenges forward

Aging population and reduction of birth rate

By 2014, China has had over 0.2 billion aging population, which is expected to increase to 0.4 billion by 2030. Because China had a high birth rate between 1962 and 1972, after 2020 this population is becoming aged consumers. The case of the aging population in China is different from that of the U.S.A., Europe, and Japan because of these people age before having become middle class. This situation worsens combined with the one-child policy that impacted the same population. There are an increasing number of households without young residents, which will impact on retailing.

The average birth rate against the number of women of childbearing age was 1.05 in 2017, meaning that by every other generation, the population will be cut in half. As a result of both an aging population and low birth rate, the retail consumption is expected to reduce.

The birth rate in China faces severe challenges. The second child policy implemented by the Chinese central government in 2017 has not seen effective results. Small-sized families will continue to dominate the retail market. The average birth rate against the number of women of childbearing age was 1.05 in 2017, meaning that by every other generation, the population will be cut in half. The dependency ratio will change from 5.8 laborers supporting one aged man in 1988 to 1.9 labours to one aged man in 2030. As a result of both an aging population and low birth rate, the retail consumption is expected to reduce.        

Residential retailing

The ways of consumption have changed as the population born in the 1990s have become the main consumption force, challenging existing ways of retailing. An increasing number of consumers in this group are becoming middle class or new entrepreneurs. They are not only hard working adopting traditional Chinese working culture but also adopt a lifestyle for enjoyment. Considering this group of consumers and the increase of small-sized household and aged population, in the coming decades, a retail transformation that provides life solution in residential areas is expected to be popular. In the current situation, residential grocery stores simply sell goods to community residents. Their competitive advantage focusses on prices. There is a need to transit from this price competition to value improvement, emphasising both communities and fresh supermarkets in the communities.

Competing with rural retailing

Rural consumers account for about 30% of Chinese online purchasers, about 186 million out of a total of 668 million online purchasers according to data in China Daily in 2015. Under the Chinese central government’s support, the growth of e-commerce in rural areas overtook that of cities in 2016 and reached US$133 billion, about a five-fold increase from 2014, making up 17.4 percent of the whole e-commerce sales. The three Chinese e-tailing giants (Alibaba, JD.com, and Suning) have stepped up their efforts to develop rural e-commerce since 2015. This fast rise of rural e-tailing also put pressure on foreign retailers to enhance their online sales strategies. New alliances with local online platforms have become an important approach for foreign retailers to enhance customer experiences, transfer store information, and provide convenient services.

Although there is growth in online sales from both city and rural areas, the overall retail growth in China is expected to slow down in the next two decades, mainly due to the expected increase in costs as a combination of results from low birth rate, aged population, and changes in shopping behaviours.


Expected slow retail growth

Although there is growth in online sales from both city and rural areas, the overall retail growth in China is expected to slow down in the next two decades, mainly due to the expected increase in costs as a combination of results from low birth rate, aged population, and changes in shopping behaviours. Currently, online shoppers are mainly younger consumers. For those retailers which target at the population who were born in or after the 1990s, it is important to offer a lifestyle that fit these generations. Moreover, such institutional issues as dealing with state-owned enterprises and local government as well as seeking local human resources remain as challenges faced by international retailers in China. Crucially, the strength of the capital determines long-term success. Most foreign retailers including the currently fast-growing convenience stores may make a profit between 8 and 20 years. This can be an advantage for large retail giants with strong capital, for example, Lawson has just started to make a profit after its market entry in 1996 from Japan. From the holistic picture discussed from foreign retailers’ market entry stage to their processes of digitalisation, while there is potential growth in the market, it is apparent that market competition and institutional impacts may put some foreign operations at a disadvantageous position if without appropriate strategies. 

About The Author

Lisa Qixun Siebers is Associate Professor of International Business at Nottingham Trent University, UK. She obtained her first degree in economics in China and MBA and Ph.D. degrees in the UK. She has been investigating foreign retailers’ expansion in China from the 1990s to date and has disseminated her work in books, journals, news articles, and online resources. Her monograph entitled Retail Internationalisation in China: Expansion of Foreign Retailers was published in 2011.

How to keep the Philippine economic future on track

A money bill looking like a growth graph with an upwardspointing arrow symbolizing economic relationships.

By Dan Steinbock              

The Philippines is on the right path, if the government can continue to balance between strong growth amid international uncertainty, while pushing reforms that raise living standards. Inflation and foreign investment tell the story.

According to the just-released report by the International Monetary Fund (IMF), Philippine real GDP grew by 6.7% in 2017 and by 6.3% in the first half of 2018 on a year-to-year basis, led by strong public investment.

The current challenge is inflation, which rose to 6.4% in August 2018. That’s an average of 4.8% percent year to date, which is above the inflation target band of 2−4%.

The medium-term challenge is the infrastructure program, particularly foreign investment which supports investment growth – and which has taken off dramatically in the Duterte era.

The forces behind inflation

Self-induced policy mistakes play a role in higher-than-expected inflation. The IMF attributes more than half of Philippine inflation to price increases in food, beverages and tobacco, particularly rice.

The National Food Authority administrator resigned a month ago after failures to purchase enough rice grains from local farms to stave off the need to import. The IMF supports the Philippine policymakers’ plan to replace the rice import quota system with one based on tariffs, while stressing the need to support small farmers affected by the reform.

As monetary policy has been accommodative, inflation has been driven by adjustments in excise taxes, rising oil prices, the weaker peso, and above-trend growth. That’s why Bangko Sentral raised its benchmark interest by half a percentage point last week. Inflation remains the top concern of Filipinos, as evidenced by the recent Pulse Asia survey.

The IMF supports the Philippine policymakers’ plan to replace the rice import quota system with one based on tariffs, while stressing the need to support small farmers affected by the reform.

The effort to curb inflation must remain elevated, however, because inflation may remain a challenge in the foreseeable future. First, while real GDP growth is projected at almost 7% over the medium term, inflation has also been projected at above the 4% upper target bound in 2018 and around 3−4% during 2019–20. Recent monthly figures exceeded the target bound by margin that’s too wide. Second, in normal times, mild discrepancies could be tolerated. But these are no normal times, as evidenced by the Fed’s rate hikes, strengthening dollar and escalating trade wars.

That’s also why Philippines is not alone in this battle. In my last column, I showed how the U.S. rate hikes and the dollar have penalized emerging Asian currencies causing significant damage in Asia’s most rapidly-growing economies, including India, Indonesia and the Philippines.

That’s why Indonesia’s central bank raised its policy rate to 5.75% last Thursday. The Bangko Sentral has raised rates by 150 basis points since May, which is its most aggressive tightening since 2000. Indonesia’s rate hikes this year also amount to 1.50 percentage points. India’s central bank has already raised its rate to 6.5% and is expected to hike ratesates for the third time in October.

The difference of capital flows in Aquino and Duterte eras

Following surpluses before 2016, the current account deficit widened to 0.8% of GDP in 2017, driven mainly by imports of capital goods, oil and raw materials, reflecting strong investment growth. According to the IMF, the Philippine current account deficit is projected to remain manageable. In this view, Philippine output would stay above potential in 2018-20, even though the current account deficit may widen to 1.5% of GDP in 2018 driven by a continued rise of capital goods imports, mostly financed by foreign direct investment (FDI).

The U.S. rate hikes and the dollar have penalized emerging Asian currencies causing significant damage in Asia’s most rapidly-growing economies, including India, Indonesia and the Philippines.

Here’s the difference between the Aquino and Duterte governments: In the Aquino era, early optimism and promises to change the FDI legislation paced an increase of capital flows in the early 2010s. But these flows represented mainly portfolio and other investments, not foreign investment. Eventually, these capital inflows reversed into significant outflows. In the Duterte era, early optimism and promises to bring in more FDI have paced a dramatic increase of capital flows, which could be sustained until early 2020s (Figure).


Figure: Great Difference: Capital flows in Aquino and Duterte Eras*

* Capital Flows (In billions of U.S. dollars, + = inflow) 

Source: Data from IMF(September 2018)


True, the current account balance declined in 2017, as the critics complain, but it did so mainly due to higher investment, which reflects Philippines attractiveness as an investment destination, and higher oil prices, which are not under the control of domestic policymakers. Moreover, last year FDI inflows more than offset the outflows in portfolio and other investment.

In the Duterte era, early optimism and promises to bring in more FDI have paced a dramatic increase of capital flows, which could be sustained until early 2020s.

It is also true that international reserves have declined in the Duterte era. However, Philippine reserves remain higher than in most emerging economies worldwide – and significantly higher than in India and Indonesia which cope with similar challenges.

That’s precisely why the overwhelming majority of Filipinos oppose any effort at a destabilization of the Duterte government. That’s why they stand behind its economic program and the war against drugs and corruption. They want no return to the past. They want the economic future that has eluded them far too long.

The original commentary was released by The Manila Times on October 1, 2018

About the Author

Dr. Dan Steinbock is the founder of Difference Group and has served as research director at the India, China and America Institute (USA) and visiting fellow at the Shanghai Institutes for International Studies (China) and the EU Center (Singapore). For more, see https://www.differencegroup.net/

Dubai is Boosting Startups and SMEs – Are You Capitalising?

Spectacular skyline of Dubai, UAE. Futuristic modern architecture of a big city at sunset. Aerial view.

By Neil Petch

In this article, the author outlines the latest and most exciting entrepreneur-friendly initiatives from the Dubai Department of Economic Development (DED), and summarise how they can help catalyse your business activities in the UAE.

It’s good to know that the UAE government continues in its determined push to make it as easy as possible for entrepreneurs to start and grow an enterprise. Proof of this proactivity is in the avalanche of new initiatives aimed at cutting red tape and fostering growth. There are also services available like this accelerator program Dubai as well, aimed at startups.

Commenting on the World Economic Forum website, Dr. Aisha Bin Bishr, Director General of the Smart Dubai Office explained: “We have established an international reputation as an economic and investment centre. And we have achieved this success by diversifying our economy through vast development in sectors such as tourism, real estate, retail, travel, logistics, and finance.”

In fact, the city’s Department of Economic Development (DED) has gone into overdrive to help entrepreneurs start and grow their ventures.

There’s a wealth of information out there, so to help out, I’ve pulled together the latest and most exciting  entrepreneur-friendly initiatives from the Dubai DED (below), and I’ve summarised how they can help catalyse your business activities in the UAE.

What Dubai’s DED does for you

The Dubai DED is a government body that “is entrusted to set and drive the economic agenda of the emirate of Dubai.” Its objective is to support the transformation of Dubai into “a diversified, innovative service-based economy that aims to improve the business environment and accelerate productivity growth.”

This is great for Dubai as a city, but what about for your venture specifically?

The good news for startups is that the Dubai DED initiatives help business owners launch and expand their operations without the need for lengthy processes and administration. Here’s how:

The good news for startups is that the Dubai DED initiatives help business owners launch and expand their operations without the need for lengthy processes and administration.


1. Freeze on government fees

The recent decision to freeze government fees (such as business licensing and real estate approvals) for the next three years in Dubai was met with much praise, and relief.

The fee freeze comes at a time when many SMEs are facing challenges in securing funding for working capital and business expansion, with banks implementing tighter lending standards. Even more welcome after the UAE’s introduction of a 5% value-added tax (VAT) this year.

State news agency WAM reported in March that the move is aimed at “promoting Dubai’s economic competitiveness, enhancing social stability and supporting investments in Dubai.”

2. E-commerce

Dr Bin Bishr says digitalisation has played a key role in the transformation of Dubai into a global city, and regional business and tourism hub, opening up opportunities for startups and SMEs.

On the e-commerce front, help is at hand for licenced e-traders working from home. In a joint venture, the Dubai DED and Emaratech – part of the Investment Corporation of Dubai – have unveiled plans to launch DubaiStore, the first local online marketplace to focus on SMEs and home-based e-traders.

The new initiative, entitled Digital Economy Solutions (DES), will focus primarily on promoting businesses, and there’s no danger of direct competition since DubaiStore does not own or sell any products of its own.

Due to be launched in the third quarter of 2018, it will provide a platform for these licensed e-traders. Consumers can access a range of products, many of which are not found in the retail market, creating a new sales avenue for SMEs.

Digitalisation has played a key role in the transformation of Dubai into a global city, and regional business and tourism hub, opening up opportunities for startups and SMEs.


3. Stimulating competition

The support doesn’t stop there. The Dubai DED is implementing a new package of government reforms to stimulate competition and achieve sustainable economic development in Dubai, WAM reports. It includes:

• Proposals to allocate 20% of government tenders to SMEs – enabling smaller businesses to gain a foothold in government programmes that might otherwise have seemed out of reach.

• Exemptions from fines and trade violations – to reduce the financial burden on businesses.

•  A retail cost reduction programme – to reduce operating costs in the retail sector and ensure retail real estate rent increases are fair and reasonable.

• A local production and procurement support programme – to encourage companies to procure goods and services from local suppliers rather than from abroad. This will support entrepreneurship and increase domestic investment in production by involving local commercial banks in extending facilities and financing to local firms, as well as enhancing cash flows in the SME sector.

•  Continued support – to establish, grow and expand startups by attracting the world’s leading business incubators and accelerators with a global network of resources.

The Dubai government’s new package of reforms also includes developing low-cost family tourism systems through a timeshare basis, and the introduction of a mortgage law to enhance demand and prices in the real estate sector.

In terms of the government tender reform, it’s worth noting that before a business can submit a tender for a government job, they must first register with eSupply, the online eSupply portal operated by Dubai eGovernment and procurement firm Tejari. Also, as per dubai.ae, the official portal of the Dubai government, companies must be certain that they can meet departmental requirements before they’re considered eligible for hire.

There are also plans to encourage more involvement from international companies. The new reforms include a proposal for a consultative council whereby international companies will be invited to participate in shaping legislative changes needed to enhance investments and competitiveness. This will be managed by Dubai Chamber of Commerce and Industry according to Reuters.

This is a great time to create and innovate in Dubai, and those who take advantage now stand all the more chance of gaining significant competitive advantage.


4. Business as usual

Don’t forget, as well as these reforms, the Dubai DED also provides services to protect day-to-day business operations. This includes support with IP/trademark or agency complaints, payment vouchers, NOC registration and grievances. Assistance is also provided in the form of legal assistance such as help with sale of share contracts and advice on business laws and regulations.


5. Digital transformation

So we’re clear the Dubai DED offers a wealth of support for entrepreneurs, but this is only part of the story. As previously mentioned, Dubai is undergoing a massive programme of digital transformation set to bring major benefits for startups and SMEs alongside the rest of Dubai. Indeed according to Digital Middle East by Digital McKinsey, the UAE government leads the Middle East in digital adoption.

The transformation is being driven by the government initiative Smart Dubai which describes itself as “anchored in the vision of His Highness Sheikh Mohammed bin Rashid Al Maktoum to make Dubai the happiest city on earth.”

Launched in 2014, the Smart Dubai initiative is now working towards a 2021 strategy that has six main action areas:

• A smart, liveable and resilient digital city

• A connected, lean government

• A globally-competitive economy powered

   by disruptive technologies

• An interconnected society with easily-

   accessible social services

•  Smooth transport provided by autonomous    

   and shared mobility solutions

• A clean environment via cutting-edge

   ICT innovations

   As such, Smart Dubai is developing new technology such as Internet of things (IoT) systems, data analytics, blockchain, hyperloop projects, innovative 3D printing, autonomous vehicles and drones, robotics, and artificial intelligence (AI) applications.


Moving forward – Dubai DED and your business

Entrepreneurs seeking to start or grow a business in Dubai should work with a company formation specialist to ensure they tap into the best support available when working with the Dubai DED. This is a great time to create and innovate in Dubai, and those who take advantage now stand all the more chance of gaining significant competitive advantage. 

About The Author

Neil Petch is the Chairman of Virtugroup. With a history of business successes, he is well known in the UAE and beyond as a visionary entrepreneur with a passion for helping others establish and grow their own businesses. He founded Virtuzone in 2009 and quickly established it as the region’s leading company formation expert, before launching Virtugroup, a holding company that has a wider mandate of supporting startups from establishment; to successful market entry; and all the way through to exit.

Personal Finance: Positioning Breastfeeding on Family Balance Sheet

Young beautiful mother, breastfeeding her newborn baby boy at night, dim light. Mom breastfeeding infant

By Sa’idu Sulaiman

This paper argues that most of the benefits of breastfeeding enhance the financial well-being of a child bearing family which is an asset appearing on its balance sheet. It then recommends that gender roles such as breastfeeding and child care need not to be valued in monetary terms only.

There are three types of finance; public finance for government and its institutions, corporate finance for businesses, and personal finance for groups and individuals. As the concern of this paper is personal finance, it is pertinent to define it and mention its scope.

Personal finance refers to the financial decisions which an individual or a group of individuals such as a family must make to plan for a prosperous future. The decisions border on sourcing, investing, spending money as well as budgeting. These constitute the scope of personal finance. Sourcing money for personal use may involve savings from wages and salaries, taking loans, obtaining financial assistance from relatives, friends, charities, etc. The sourced funds can be invested in several ways such as personal development through pursuit of education, enhancement of a healthy living among family members, venturing into farming, horticulture, etc. Spending money would involve expenditure on food, shelter, and on means of transport and entertainment facilities for one’s family, among others. Personal budget entails forecast about the income that would be received by an individual or a family and the expenditures to be made in a specified period, which can be a week, a month or a year.

Family finance, which could be another name for personal finance, covers all income, expenses, and financial accounts related to the maintenance and upkeep of an entire family household. Its scope covers sources of income to the family which includes wages, investments, savings accounts, trusts, etc, while the expenses include mortgage or lease payments, car payments, utility bills, clothing, education, taxes, grocery bills, retirement plan contributions and other sundry purchases.1

In the process of making financial decisions, one is expected to take into account various financial risks and future life events that may affect current and projected income level, and plan for them.2 Life events for a family that bear children must include venturing into breastfeeding or resorting to its alternatives. Each choice made has implications for family finance because there are costs and benefits in both short and long run. Put in another way, breastfeeding and its alternatives must appear on the lists of family assets and or liabilities, and subsequently, of family balance sheet.  In corporate finance, the balance sheet is financial statement indicating the position of a company’s assets acquired by using its capital and liabilities as at a given date in its life.

This paper aims to shed light on where to put breastfeeding on the balance sheet of a child-bearing family. Doing this is an attempt to provide an answer to the question “is breastfeeding an asset or liability to a child-bearing family?”


Benefits of Breastfeeding

A document provided by the World Health Organization says breastfeeding is an unequalled way of providing ideal food for the healthy growth and development of infants. Exclusive breastfeeding, as recommended by the World Health Organisation, is feeding of infants with breast milk without any additional food or drink, not even water, during the first six months of their lives. Breast milk provides all the energy and nutrients that the infants need for the first months of life, and continues to meet half more of their nutritional needs during the second half of their first year. During the second year of infants’ life, one-third of their nutritional needs come from breast milk. The document further reveals that breast milk promotes infant’s sensory and cognitive development, and protects it against infectious and chronic diseases. The advantages of exclusive breastfeeding include reducing infant mortality caused by diseases such as diarrhea or pneumonia, and facilitating quicker recovery during illness. For mothers, breastfeeding contributes to their health and well-being and reduces the risk of ovarian and breast cancer. Other benefits of breastfeeding are that it helps to space children, increases family and national resources, etc.3 Breastfeeding has long-term benefits for a baby, lasting right into adulthood. Breastfeeding reduces baby’s risk of cardiovascular disease in adulthood and the longer a mother breastfeeds her baby, the longer the protection lasts and the greater the benefits. Breastfeeding lowers the mother’s risk of osteoporosis (weak bones), obesity, etc.4   

The United Nations Children’s Fund (UNICEF) also states that breastfed children have lower rates of childhood cancers, including leukaemia and lymphoma, and are less vulnerable to pneumonia, asthma, allergies, childhood diabetes, gastrointestinal illnesses and infections that affect their hearing. Another benefit of breastfeeding is that it saves money as it eliminates the expense of infant formula and other costs in money, time, energy and sufferings related to illness and death caused by artificial feeding. Most families in developing nations cannot afford the cost of substitutes to breast milk. In Vietnam, for instance, a year’s supply of breast milk substitute costs $257, which is high when compared to the country’s per capita gross national product (GNP) of only $320.5

The advantages of exclusive breastfeeding include reducing infant mortality caused by diseases such as diarrhea or pneumonia, and facilitating quicker recovery during illness.

Motee and Jeewon report that several studies have highlighted innumerable benefits of breastfeeding for infants, for mothers and the society; they include lowered risk of otitis media, gastroenteritis, respiratory illness, sudden infant death syndrome, necrotising enterocolitis, obesity, hypertension in infants; and reduced risk of breast and ovarian cancer, Type 2 diabetes, and postpartum depression among mothers who breastfeed and their babies. Benefits that accrue to the society that embraces breastfeeding include decrease health care related costs and fewer absences from work.6


Disadvantages of Breastfeeding

Every coin has two sides. Breastfeeding has some disadvantages or problems. These include breast engorgement, sore nipples, milk insufficiency, and societal barriers such as employment, length of maternity leave and medical complications such as mastitis and breast abscess.7 Other problems associated with breastfeeding are that it requires an ample time commitment from mothers, especially when babies feed very often, it brings discomfort to mothers at the initial stage, it requires mothers to be aware of what they eat and drink because what they consume can be passed on to their babies through the breast milk. Lastly, medical conditions such as HIV/AIDS and consumptions of certain medicines can make breastfeeding unsafe. Although experts believe that breast milk is the best nutritional choice for infants, breastfeeding may not be possible for all women; as such the decision by certain mothers to breastfeed or to resort to alternatives to breastfeeding can depend on their lifestyle, conformability and medical situations.8

Most of what that has been said about the benefits and disadvantages of breastfeeding have financial implication for family finance, and therefore, can be used as basis for regarding breastfeeding practice among child-bearing families either an asset or a liability. The fact that the breastmilk becomes freely available when a child is born means that it is a blessing and gift from God. A blessing cannot at the same time be a liability, in fact the liability comes when a couple has to be buying cow milk or infant formula for their baby for several months when its mother dies or is incapable of breasting the baby due to certain illnesses.

On account of being a money-saving practice, breastfeeding enhances the financial condition of the families that embrace the practice because they do not have to spend money on infant formula and other substitutes to breast milk.


Positioning of Breastfeeding on the Balance Sheet of a Child-bearing Family

On account of being a money-saving practice, breastfeeding enhances the financial condition of the families that embrace the practice because they do not have to spend money on infant formula and other substitutes to breast milk. On account of its power in reducing risks of contracting diseases by babies and their mothers, breastfeeding reduces family spending on medical services and medications. In addition, a healthy family can also be a wealthy family because an improved health condition of a family or a community forms part of its human capital. The micro evidences from a study by Hoyt Bleakley also show that childhood health is an input in producing other forms of human capital.9  One can, therefore, justify the positioning of breastfeeding practice by a child-bearing family or couple on the same place with other assets appearing on its balance sheet.

As for the mentioned disadvantages or problems of breastfeeding, it needs to be stated that every human undertaking that brings income or other benefits also entails some problems. Working in a bank, for instance, has its own disadvantages which differ from the problems of going into farming or joining military service. Moreover, every chosen action has an opportunity cost. When an individual chooses to incur a given cost from available alternatives, the Ricardian principle of comparative cost advantage should be observed.10 This principle is applicable to gender roles in a family. A child-bearing family should, for example, compare costs associated with abstaining from breastfeeding because of the office work done by a mother with the cost of employing another person to do the work. Firms employing women should also compare the options of allowing mothers to go on long vacation (at least six months for exclusive breastfeeding) or of employed men who, by their nature, are not fit for breastfeeding of babies. Gender differences are real and they greatly determine gender roles. Despite being a woman academic and philosopher, Helena Cronic debunks the notion that gender differences are merely social constructs, saying:

Men and women look unalike, walk unalike, talk unalike. They differ on who is more competitive, single minded and risk taking; who is more likely to climb Everest, drive too fast, become President of the United States, commit murder, or win a Nobel prize… 11

These and similar differences, she adds, transcend religion, culture, politics, education, social class and ethnicity. They are universal.

In conclusion, it suffices to say that most of the benefits of breastfeeding enhance the financial wellbeing of a child-bearing family, and therefore, constitute an asset that can be added to the family balance sheet. So, there is the need for the continuous enlightenment of people getting married on the benefits of breastfeeding to supplement the activities of the annual World Breastfeeding Week observed in the month of August of every year. Gender roles should be assigned to male and female members of families in line with their biological characteristics, approved values and cultural norms with a view of enhancing their health status and financial position. Finally, individuals, governments and organisations should value the contributions made by women to societal development through breastfeeding, child care and other domestic services, in their own right, instead of attacking value to monetary rewards attached to paid jobs done by women. 

About the Author

Sa’idu Sulaiman is a Chief Lecturer of Economics at the Sa’adatu Rimi College of Education, Kano, Nigeria. He is also an author of books such as 12 Facts about Protectionism and the Global Economy, 9 Requirements for Quality Research and Academic Papers, Unforgettable Experiences in Abuja, Manchester and London, and two recent novels, The Desperate Migrant and What Matters Most.

References

1.“Family Finance”, retrieved on August 27, 2017 from http://www.investorwords.com/19074/family_finances.html

2.Refer to “What is Finance? Meaning, Definition and Features of Finance”, retrieved on August 27, 2017 from http://www.technofunc.com/index.php/domain-knowledge/finance-domain/item/what-is-finance-meaning-definition-features-of-finance

3.WHO (2017). Exclusive Breastfeeding, retrieved on August 27, 2017 from http://www.who.int/nutrition/topics/exclusive_breastfeeding/en/

4.“Benefits of breastfeeding” (reviewed on 28/02/2017) retrieved on August 27, 2017 from http://www.nhs.uk/Conditions/pregnancy-and-baby/Pages/benefits-breastfeeding.aspx 

5.For details, refer to the UNICEF’s brochure entitled Breastfeeding: Foundation For a Healthy Future. Retrieved on August 28, 2017 from https://www.unicef.org › pub_brochure_en     

6.Motee A, Jeewon R. “Importance of Exclusive Breastfeeding and Complementary Feeding among Infants”. Curr Res Nutr Food Sci 2014;2(2). Available from  http://www.foodandnutritionjournal.org/?p=814 doi : http://dx.doi.org/10.12944/CRNFSJ.2.2.02

7.ibid.

8.See  the article “Breastfeeding vs. Formula Feeding” reviewed in February 2015 by Elana Pearl Ben-Joseph, MD. The Nemours Foundation. Retrieved on August 28, 2017 from http://m.kidshealth.org/en/parents/breast-bottle-feeding.html?WT.ac=

9. See Bleakly, Hoyt (2010).  “Health, Human Capital and Development” Annual Review of Economics, 2010;283-310.  Doi: 10.1146/annurev.economics.102308.124436. Retrieved on August 30, 2017 from  https://www.ncbi.nlm.nih.gov/pmc/articles/PMC3800109/

10.David Ricardo, a renowned British economist, argues that there would be gains from trade if each nation specializes in the production of the commodity in which it has a comparative cost advantage in producing and then buys the other commodity from the other nation. 

11.For details refer to Cronin, Helena (2006). “Darwinian Insights into Sex and Gender”, Microsoft Encarta 2006. Microsoft Corporation.

A Message from London: Pay Your “Zakat” Locally

Istanbul, Turkey - January 22, 2015: The mullas collect the sadaqat (donations) at the entrance to the New Mosque in the city center

By Greget Kalla Buana

Zakat (Islamic alms giving) is now consi-dered as an alternative resource to help achieve the SDGs. London, the capital of a developed Muslim-minority country, has a unique approach to encouraging Muslims to pay zakat, resulting in a significant amount of almost the same with that in Indonesia, the world’s most populous Muslim-majority country.

In the last few weeks before Ramadan, an advert from the National Zakat Foundations urging Muslims to pay their zakat locally in the UK was posted at the Hainault Street bus stop. This particular campaign caught the attention of and earned praise from UK Muslims. In 2016, number of UK Muslims surpassed three million of which one-third resides in London. More specifically, data from the 2011 census stated that one out of eight Londoners is Muslim making the city a home to large Muslim community.

Such phenomenon has portrayed UK Muslims’ undeniable power to play a major role in helping the society through a religious charitable fund called zakat. Zakat is a mandatory giving paid by eligible Muslim earning above certain threshold, which, when it has reached a specified amount, is commanded to be given to the deserving people (eight group of beneficiaries according to Quran). This social part of Islamic finance has an enormous potential and been considered as an alternative resource to help achieving the Sustainable Development Goals (SDGs).

An end to poverty and inequality is the biggest challenge now to be addressed through the SDGs. Given the principles of Islam in favour of socially inclusive development, funding from Islamic finance, such as zakat, has the chance to play an important role. Zakat and the SDGs overlap in terms of compatibility and embeddedness with the five foundational goals of Islam (Maqasid al Shariah).

With the annual worldwide value of zakat alone estimated at U.S.$200 billion to U.S.$1 trillion, it has a tremendous potential to fill the $2.5 trillion financing shortfall to achieve the SDGs. Reported by the National Zakat Foundation, the annual value of zakat paid by UK Muslims alone could be as much as U.S.$353 million. However, over 98 percent is distributed abroad whilst less than the remaining two percent (U.S.$6.7 million) is for domestic causes.

Zakat is a mandatory giving paid by eligible Muslim earning above certain threshold, which, when it has reached a specified amount, is commanded to be given to the deserving people.

Following the global trend, particularly in a Muslim-majority country, a different perspective has been continuously happening around the mechanism of zakat collection – either it is supposed to be ruled by the government or private sector and between formal and informal giving. The UK has illustrated a new story. Instead of pushing people to pay their zakat by mentioning a specific institution, the National Zakat Foundation preferred having a jargon “locally” to evoke that it does not really matter where you would like to pay the zakat as long as it is through a local group. Noting that world-class zakat organisations are also based in London, namely Human Appeal, Islamic Relief, and Muslim Aid, they are not competing with each other. This reflects the spirit of brotherhood in Islam.    

Compared to Indonesia, as mentioned by the National Zakat Agency (Baznas), only three percent (U.S.$480 million) of the potential was realised within last year given that some people are continuing predilection toward short-term and interpersonally oriented. The lack of public trust to non-certified zakat institutions and such behaviours of the payer exacerbated the condition. Having said that zakat is only assigned to those who are capable, when there are more poor people, more needs to be spent for their welfare. In other words, the zakat collected is not sufficient for the poverty alleviation strategy. This is contrary to the UK situation where only small percentage of zakat is disbursed domestically.

Lesson learned from London is, instead of coping up too much into the debate between formal and informal mechanism, they prefer “local” as the most persuasive terminology.

In exploring the correlation between Muslim population and zakat collection, both UK and Indonesia can learn from each other. In addition, comparing these two countries reveals commonality among so many different characteristics of demography, political economy, and socio culture. According to the World Giving Index 2017 by Charities Aid Foundation, the average UK’s and Indonesia’s participation rates for donating money in the last five years were 71 and 70 percent, respectively. The amount of zakat paid by UK Muslims is nearly as much as that of Indonesian Muslims actually do. However, UK deploys the zakat mostly abroad while in Indonesia zakat cannot address the internal problem of extreme poverty.

The word “locally” in the billboard has delivered a strong message. For the case of Indonesia, the huge potential of zakat is largely untapped and overlooked, presumably because informal giving remains much larger than contributions made through formal organisation. Lesson learned from London is, instead of coping up too much into the debate between formal and informal mechanism, they prefer “local” as the most persuasive terminology. Put simply, “pay your zakat locally” reflects a more enforcing meaning than just “give” that is commonly used for charitable action. By paying zakat locally, the ad reassures the payers two points: (1) to put their zakat money in any nearby competent authority and (2) to watch where the money goes, meaning that they consciously understand how their money can give impact to surrounding or nearby society. Same approach could be implemented by Baznas and other zakat authority in other countries.

About the Author

Greget Kalla Buana is an Islamic Finance Specialist at the United Nations Development Programme and graduated from Master of Islamic Finance and Management, Durham University, UK. His work experiences have always been in Islamic finance sector, such as Dompet Dhuafa (Indonesia Humanitarian NGO which is also a consultative member of ECOSOC, using Islamic finance instruments as fund resources), Islamic Banking Department of Indonesia Financial Services Authority, and UNDP where they established partnership with Islamic Research and Training Institute of Islamic Development Bank. 

Hindu Nationalism and the Consolidation of Hate Politics in India

By Kalim Siddiqui

When we look back, since the demolition of the Babri Masjid a quarter of century ago, it seems a well-planned and well-thought act, as it paved the way for the dramatic rise to power of Hindu nationalists. It raises a question: is there really an irreconcilable contradiction between liberal democratic institutions and the takeover of the state by the extreme far right Hindus?

For the last quarter of a century, Indian polity seems to be undergoing a historically unprecedented process of change and the irresistible rise of far right Hindu parties (i.e. BJP, RSS, Shiv Sena also known as Hindutva) to dominate the areas of culture, educational institutions, judiciary and administration. It raises a question: is there really an irreconcilable contradiction between liberal democratic institutions and the takeover of the state by the extreme far right Hindus?

The ascendency of the BJP (Bharatiya Janata Party) in politics has coincided with a sharp rise in sectarian hatred and attacks against Muslims. Then, a number of riots took place in north and west part of India where thousands of Muslim lives were lost and the police was criticised for acting in partisan manner. Jurist B.N. Srikrishna in the Commission on Enquiry Report on 1992 riots in Bombay (now Mumbai) indicted Bal Thackeray, then leader of the Shiv Sena, to incite riots. The Commission also indicted the police who have indulged in violence, looting and attacks against Muslims. Moreover, those responsible of burning properties and killing Muslims in Mumbai who were identified by the Srikrishna judicial commission are now in power and despite the judicial inquiry report, almost no one was punished. This happened despite India being a home to a tenth of the world’s Muslims of around 180 million people, making it the largest Muslim country after Indonesia and Pakistan.

When we look back, since the demolition of the Babri Masjid a quarter of century ago, it seems a well-planned and well-thought act as it resulted in huge electoral dividends for the Hindu extremists, especially BJP and its allies. Clearly, the mobilisation to attack and destroy the mosque was a political move, as L.K. Advani, then leader of BJP, acknowledged during the Rath Yatra that he is “a political, not a religious leader”.

The mobilisation by the far-right Hindu groups is based on religious identities, which is shaping the Indian politics towards Hindu nationalism. This means a further subordination and subjugation of minorities.

The mobilisation by the far-right Hindu groups is based on religious identities, which is shaping the Indian politics towards Hindu nationalism. This means a further subordination and subjugation of minorities. These semi-fascist groups achieved legitimacy by claiming that Hindus were subject to discriminatory treatments, even though this is completely false as the upper-caste Hindus dominate all institutions and are very powerful politically, economically and culturally. The far right has spread lies that Hindus have received unfair deal in the post-independent India. They are changing educational syllabus, and textbooks to incorporate views of history based on mythology and religious texts as they define it. To accomplish this, Hindutva sympathisers are being appointed to top positions in the country’s prime educational and cultural institutions to promote extremist ideas of Hindu nationalism. Such steps will mark the end of secular India and the creation of a Hindu nation. However, Hinduism remains a very varied religion and India is a very diverse country with an ancient, pluralist tradition.

It is important to emphasise that in India, the BJP government is run by the RSS (Rashtriya Swayamsevak Sangh), which not only provides the cadres and money but also the muscle during elections. The RSS officials also serve as secretaries in the BJP. The RSS/BJP main agenda is to establish “Hindu Rastra” and to undermine secularism in India.1 Their strategy of arousing fear of the alien, particularly Muslims and Christians is the cornerstone of the Hindutva movement. As a result, atrocities against Muslims in the country have risen sharply, since Narendra Modi became Prime Minister of India three years ago. In India, cow slaughter is banned in most states. Since Modi and his party assumed power in 2014, this beef ban has been used by Hindu nationalists to justify their attacks on innocent Muslims in public.

The recent report on mob violence in India says since 2015, in cow vigilantes attack 34 persons (mainly Muslims) have been murdered and these attacks are not spontaneous expressions of mob anger, but product of incitement to violence and hate propaganda.

The recent report on mob violence in India says since 2015, in cow vigilantes attack 34 persons (mainly Muslims) have been murdered and these attacks are not spontaneous expressions of mob anger, but product of incitement to violence and hate propaganda. As the report Lynching Without End (2017): “The shift in method, from mass violence to low intensity individualised ones, being perhaps a deliberate strategy by those behind the violence, to at once avoid too much public scrutiny, whilst also ensuring that the minorities [Muslims] are constantly under attack” (Indian Express, New Delhi, 17 March, 2018).

Last month Hapur, near Delhi, two Muslim men were attacked on the street while police stood by guarding the mob. One of the two was kicked and dragged along as he lay unconscious and later died of his injuries. The other, an elderly man, was pulled by his beard and dragged through a field and attacked by the BJP members. A recent report by news organisation called IndiaSpend noted that “Muslims were the target of 51% of violence centred on bovine issues over nearly eight years (2010 to 2017) – and they comprised 84% of 25 Indians killed in 60 incidents. As many as 97% of these attacks were reported after Narendra Modi’s government came to power in May 2014.”2

On 17 July 2018, the Supreme Court of India condemned the rising incidence mob lynching in India and asked the Indian parliament to draft legislation that would stop people from taking the law into their own hands. The attackers are often members of BJP.

India’s Prime Minister Narendra Modi is creating a dangerous precedent before the next general election, setting the tone for an India whose syncretic values and democratic principles are under threat. He was Head of the State of Gujarat when thousands of Muslims were killed in front of the police in the riots of 2002. As he gears up for re-election, that legacy looms large over the whole country.

Moreover, Hindu far right parties would like to declare India as a Hindu nation, which poses a challenge to its multi-faith constitutional commitment. Harsh Mander, activist and former bureaucrat, says there is a “growing climate of hate” in India. “We have a political leadership now in the country that has created an environment which is permissive of acting out hate speeches and hate actions. Lynching of this kind is a growing phenomenon in many parts of the country.”

Despite the hate propaganda and exaggeration of occurrence of violence about the past between Hindus and Muslims, the truth is very different. As eminent historian Professor Mukhia noted: “there is no record of what we know as communal riots anytime from around 1200 (establishment of Delhi Sultanate) to the first quarter of 18th century, when the Mughal state had started to run its downward course. The first communal riots was recorded in 1713-14 in Ahmedabad on the day of Holi rivalry, instigated by two rivals in the jewellery business, one Hindu and the other Muslim. This was brought under control within two days”.3

The present government of BJP in India is not a normal right wing political party but it is a mass political front of semi-fascist organisation, the RSS, which describe itself as “cultural” and “non-political” organisation, but has declared its intention to transform India’s political, cultural and social life.

In fact, the present government of BJP in India is not a normal rigt wing political party such as the Republican Party in the United States or the Conservative Party in the UK or the Christian Democratic Union of Germany (CDU), but it is a mass political front of semi-fascist organisation, the RSS, which describe itself as “cultural” and “non-political” organisation, but has declared its intention to transform India’s political, cultural and social life. The RSS was founded in 1913 and its founders had nostalgia for a Hindu Golden Age, which totally ignores caste subjugation, atrocities against women and the socio-economic marginalisation of Dalits at hands of upper caste Hindus. There was plenty of evidence of RSS that the organisation had been inspired by German and Italian fascism and also had collaborated with the British colonial rulers. The RSS declares itself “cultural” organisation, which is to exempt any kind of accountability and scrutinising that is required of political parties.

About the Author

Dr. Kalim Siddiqui teaches International Economics at University of Huddersfield, UK. He is an economist, specialising in Development Economics and has written extensively on development economics, economic reforms as well as on the political economy of development. He may be reached at [email protected]


References:

1. Siddiqui, Kalim. 2016. “A Critical Study of Hindu Nationalism in India”, Journal of Business and Economic Policy 3(2):9-28. ISSN 2375-0766. (Print), 2375-0774 (Online) USA. http://jbepnet.com/journals/Vol_3_No_2_June_2016/2.pdf

2. IndiaSpend. 2017. “Dead In Cow-Related Violence Since 2010”, http://www.indiaspend.com/cover-story/86-dead-in-cow-related-violence-since-2010-are-muslim-97-attacks-after-2014-2014

3. Siddiqui, Kalim. 2017. “Hindutva, Neoliberalism and the Reinventing of India”, Journal of Economic and Social Thought, 4(2):142-186, June.  ISSN 149-0422


EDITOR'S PICK OF THE WEEK

China economic growth

China’s Challenging Search for a New Model of Economic Growth

By Danny Leipziger China cannot continue to rely on exports to drive its growth, but what are the alternatives? China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...

WISE DECISION MAKER GUIDE

POWER INFLUENCERS

Emerging Trends

The Future of Global Trade