Home Blog Page 1077

China’s Position on Climate Change – Truly Sustainable?

By Kerry Brown and Benjamin Barratt

Back in 2009, the world would not have thought that China will be taking a leadership role in humanity’s struggle against climate change. Today, Kerry Brown and Benjamin Barratt discuss how China’s position has transformed and why it will stick.

With the election of Donald J. Trump as president of the USA in 2016, the issue of the global effort to combat climate change underwent a potential transformation. In his campaign at least, Trump had been at best ambiguous, and at worst antagonistic to the idea of human activity impacting on temperatures, and the potentially disastrous consequences that might come from this. While not withdrawing from the Paris Convention at the time of writing (May 2017) the US has gone from being proactive and engaged in this space to being passive, and possibly even opposed.

That immediately opened up space for the Chinese, the other essential constituent in the international effort. This in itself is a remarkable moment. In a key area, China, not the US, is displaying leadership. This is one of the most powerful illustrations of just how prominent China has now become, and how global the read of its influence.

This in itself is a remarkable moment. In a key area, China, not the US, is displaying leadership.

It is ever more noteworthy because less than a decade ago, when the Copenhagen Summit was convened in 2009, China would not have been placed amongst the more positive and co-operative players. Despite recognition domestically, by politicians and academics within the People’s Republic, that climate change was a serious problem, and that more needed to be done in terms of use of clean technologies and reduction of reliance on fossil fuels (the key contributor to greenhouse gases), the attitude remained that economic growth was the priority, and that it was the responsibility of the developed world, and in particular the US and the EU, to take the lead in cutting emissions.

At Copenhagen, China was accused of leading a 77 strong cohort of developing nations in opposing a stronger joint communique at the end. This wrecking role attracted savage criticism. China was painted as a spoiler, a nation that was standing between the rest of the world, and the attempts to find a sustainable solution to combatting climate change. By 2014, a series of events started to disrupt this narrative, marking the transition in a short period to China being a leader, rather than opponent, for global efforts.

There were three key moments in this path to change. Firstly, from the elevation of Xi Jinping as party Secretary in 2012, China’s whole domestic political story changed. GDP growth started to slow down. The government proposed that economic growth alone was not the key thing. There were other equally important targets. One of these, conveyed in the China Dream idea, was of a clean, pleasant environment. Chinese cities blighted by thick smogs that threatened lives became a huge and very visible impediment to this. This meant that the government started to reprioritise and place providing a better living environment at the heart of its programme.

That led in 2014 to the surprising joint agreement between China and the US on the side lines of the Asia Pacific Economic Meeting (ASEM) that year to mutually agree a cap on carbon emissions. For the first time ever, China legally committed to having a peak by 2030, and then aiming for reductions after then. That the two most important players in this space were willing to signify their work together was a huge symbolic and practical step.

It was a step like this that made the even more dramatic events in Paris a year later possible. In front of the rest of the world, China reversed its strategy from Copenhagen in 2009 and played a proper leadership role, making a meaningful international accord possible.

What were the reasons behind this change, and will it prove sustainable? All signs at the moment are that for Xi Jinping and his government, regardless of what the Americans eventually do, they will abide by their commitments made in Paris, and that they will continue to support further efforts. This might seem generous and altruistic. But in fact, it is simply an acceptance of the overwhelming scientific evidence of a clear link between human activity and rising temperatures, and, more importantly, a clear acceptance that as a global problem, China has to take a major role in this whatever the rest of the world might think.

If we take air quality, the reasons for why China might take this more proactive stance are clear. Within China, air pollution in the form of thick, obscuring smog, has become a widely publicised side effect of a rapidly evolving economy dependent on fossil fuels and heavy industry. What is a present, but largely invisible threat to public health in Trump’s America, has become a visible symbol of environmental degradation in China.

It is simply an acceptance of the overwhelming scientific evidence of a clear link between human activity and rising temperatures, and, more importantly, a clear acceptance that as a global problem, China has to take a major role in this whatever the rest of the world might think.

The most recent Global Burden of Disease estimate for deaths associated with air pollution in China stands at 1.6 million per year, a problem that will become more acute as its population ages and becomes more susceptible to disease. Such a high number reflects the severity of the situation. Daily average concentrations of PM2.5 (fine dust in the atmosphere small enough to enter your lungs when breathed in) across China frequently exceed 250 µg/m3, which is 10 times the World Health Organisation guideline (25 µg/m3). After initial reticence to publish data, the Chinese government has rapidly expanded its network of air quality monitoring stations and issues smog alerts when levels exceed certain thresholds. These data also provide a means to evaluate, and publicise, its efforts in bringing down pollution levels via a raft of emissions control legislation. As many of the main culprits for this public health crisis, principally coal burning, are also high on the list of climate change contributors, improvements will have dual benefit; a win-win situation for climate and health.

As a government focussed on delivering more for the rising urban based, service sector working, high consuming middle class, ignoring the very clear impact this has on the health and quality of life of this core group would be political folly, even in a non-multi party system such as the one China currently has. The Chinese government therefore has a profound reason for addressing these concerns. If it manages to clear up the air across China, and particularly in its cities, it will, to put it more simply, be more popular. If it fails to do this, then its legitimacy will be questioned. And it might be one of a number of issues that create the sort of accumulation of grievances that might threaten the stability of the one party state.

It is intimately linked to its own vision of how to maintain its power, and to the creation of what it calls its central mission – a rich, proud and strong country in the next decade.

This stark possibility means that China’s commitment to combatting climate change is very unlikely to weaken or change. It is intimately linked to its own vision of how to maintain its power, and to the creation of what it calls its central mission – a rich, proud and strong country in the next decade. Having polluted cities and ill, resentful inhabitants would be a massive barrier to achieving this goal.

That it has such domestic importance is a good thing for the rest of the world. While Trump in Washington can dismiss the lobbying of most groups around needing to combat climate change, it is unlikely he will be able to push away the intercession of his largest trading and economic partner. China has unique leverage here. And the fact that its president, Xi, draws such a strong link between his domestic prosperity and addressing this issue is a good thing. It means that he has, and will, continue to support not just China, but America and the rest of the world in their efforts to fight climate change. This, above all else, is why the Chinese position on this issue is unlikely to change, and is sustainable.

Featured Image: A solar farm in Xinjiang. China has pledged to generate 20% energy from sources that are not fossil fuel, including solar, by 2030. © Gilles Sabrié

About the Authors

Kerry Bown (left) is Professor of Chinese Studies and Director of the Lau China Institute, King’s College, London. Benjamin Barratt (right) is Senior Lecturer in Chinese Environment at the Lau China Institute and in the Division of Analytical and Environmental Sciences at King’s.

Singapore: Designing the Future in the Midst of Uncertainty

By Lester Gunnion

The Singapore government has a vision of transitioning to higher-value-added industries, and thus boosting productivity, by focussing on skill development, innovation, and global integration. However, this process is likely to face both external and internal challenges.


Singapore’s real GDP growth has slowed in recent years. Average annual growth rate in 2016 and 2015 was less than half that in 2014 and 2013. The slowdown links back to sluggish global trade – a critical factor driving Singapore’s economic performance. However, the recent uptick in global economic growth and business sentiment is spurring an improvement in global trade. This is likely to support slightly quicker real GDP growth in Singapore in 2017. While an improving external economic environment is important for the near term, the overarching narrative over the medium to long term will remain centred on Singapore’s internal transition to its future vision of the economy. The Singapore government is planning a transition to higher-value-added industries by focussing on skill development, innovation, and greater global integration. This assumes importance as low-skilled, low-cost manufacturing and services are more likely to shift to developing economies in Asia with abundant labour pools. The planned economic transition also focusses on boosting productivity, especially because Singapore’s population is aging rapidly. This process is likely to face both external and internal challenges.


A Review of Recent Economic Performance

In 2016, Singapore’s real GDP grew 2.0 percent from a year ago, about the same as in 2015 (Figure 1). The manufacturing sector recovered in 2016, growing 3.6 percent after declining 5.1 percent in the previous year. Manufacturing growth was supported by growth in the electronics cluster and the biomedical cluster, particularly in the final quarter of the year. Electronics manufacturing was supported by growing demand for semiconductors due to a cyclical upswing in the global information technology industry. The biomedical cluster was supported by an increase in demand for pharmaceuticals and medical equipment. Growth in the construction and services sectors of the economy moderated in 2016 compared with 2015. The goods-producing and services sectors of the economy each contributed 0.7 percentage points to overall real GDP growth. Ownership of dwellings and taxes on products accounted for the remainder.1

Consumption, both private and government, slowed relative to the previous year. Private consumption grew just 0.6 percent, down from 4.6 percent in 2015. Gross fixed capital formation declined in 2016 after weak growth in the previous year. Exports and imports also slowed relative to the previous year. Exports of goods and services grew 1.6 percent, down from 2.6 percent in 2015.2


In Q1 2017, Singapore’s economy contracted 1.3 percent quarter over quarter on a seasonally adjusted annualised basis. Manufacturing declined from the previous quarter, but the electronics cluster continued to be buoyed by strong demand. Construction recovered relative to the previous quarter but remained weak relative to a year ago due to continued weakness in private construction. Service industries also declined relative to the previous quarter.3 Total exports, measured in constant 2012 Singapore dollars, declined from the previous quarter, but exports in the first four months of 2017 were up 5.7 percent relative to the same period a year ago.4

An Uptick in Global Trade and Singapore’s Plan for Growth in the Future

In its latest World Economic Outlook (WEO) report, the International Monetary Fund (IMF) indicates that global GDP growth is likely to strengthen to 3.5 percent in 2017 from 3.1 percent in the previous year.5 Brighter prospects for economic growth in developed economies, particularly in the United States and European Union, are important factors behind the projection of quicker global growth. Additionally, quicker economic growth in the first quarter of 2017 in China has temporarily allayed fears of a sharp slowdown there. Another factor behind the improved outlook is improving business sentiment, backed by improved corporate earnings.

The uptick in trade is likely to benefit Singapore’s economy in the short run. With trade (exports and imports) accounting for 320 percent of GDP,8 robust global trade will remain critical to the success of Singapore’s future economic plans.

All these factors augur well for global trade. In the WEO forecast, global trade volume is projected to increase 3.8 percent in 2017, up from 2.2 percent in 2016.6 Other indicators, such as the container throughput index, international air freight volumes, and the global purchasing managers’ index (PMI), all point toward improving global trade in the near term (Figures 2a and 2b). Even the World Trade Organization’s World Trade Outlook indicator notes that global trade momentum is likely to continue at a moderate pace through the second quarter of 2017.7 The uptick in trade is likely to benefit Singapore’s economy in the short run. With trade (exports and imports) accounting for 320 percent of GDP,8 robust global trade will remain critical to the success of Singapore’s future economic plans.


The Singapore government has put in place a focussed strategy to maintain economic growth. This strategy includes building workforce skills, developing industry transformation maps, enhancing innovation, enabling digitisation, and deepening international connections. The government has targetted five clusters for growth: advanced manufacturing, applied health sciences, smart and sustainable urban solutions, logistics and aerospace, and Asian and global financial services. These clusters are areas in which Singapore has existing comparative advantage; they are also areas where the government projects will generate demand in the future.

As Singapore attempts to move up the value chain, it is also moving away from a reliance on low-skilled, low-wage foreign labour. The government has set quotas for foreign workers in certain sectors. Furthermore, businesses are required to pay a tax on each foreign worker employed, dependent on the worker’s qualification as well as the foreign worker quota imposed on the sector. Tax rates are lower if the worker has the necessary academic and skill-based qualifications. The quota and tax system is designed to regulate the number of low-skilled foreign workers in Singapore, boost wages, and increase overall productivity by encouraging skill development.


Likely Challenges to Singapore’s Transition Strategy

Singapore’s planned transition to an economy of the future comes with challenges. First, there are external challenges; the momentum in global trade could be dampened if developed countries adopt a protectionist stance. Global policymakers are beginning to show some concern about this. For example, the IMF’s WEO report states that pressures for “inward-looking” policies are growing in the developed world due to low productivity and income inequality.9 China’s broad slowdown also poses a risk. Improved growth in Q1 2017 is unlikely to reverse the broad slowdown in growth. Weaker global trade could hamper Singapore’s plans of both achieving growth through export-oriented future growth clusters as well as fostering deeper international connections.

There are internal challenges to the plan as well. At the top of the list is Singapore’s aging population. Increasing life expectancy and a decreasing fertility rate mean that Singapore’s population will have an increasingly large proportion of old people. The old-age support ratio (OASR) is the ratio of working-age Singaporeans (20 to 64 years) to those 65 years and older. The OASR in 2016 was 4.7. By 2030, the OASR is likely to fall to 2.3.10 While an aging population is one of the reasons behind Singapore’s transition strategy, it is also likely to deter future growth, especially since the focus is on boosting productivity rather than expanding the workforce, which would put the city-state’s infrastructure under strain. Unfortunately, productivity growth has been weak and has been outpaced by growth in average monthly earnings (Figure 3), though an improvement in Q4 2016 offers hope. Year-over-year growth in output per employed person has averaged just 0.5 percent over the last eight quarters.11 Year-over-year growth in average monthly earnings averaged 3.6 percent over the same period.12


The Short-Term Outlook

Singapore’s short-term economic outlook will be determined by the future path of global trade. Trade policies in the developed world as well as fiscal and monetary accommodation in China are key factors in the near to medium term. If trade momentum holds up, then business sentiment is likely to rise, which, in turn, will support business investment. Budgetary measures such as expanding tax rebates and providing support to businesses faced with higher wage payouts are also likely to lend support. Furthermore, starting public sector infrastructure projects early is likely to compensate for weak private sector construction spending in the near to medium term. Singapore’s private consumption expenditure, which has stalled in recent quarters due to low consumer confidence and rising labour force redundancies, is likely to remain subdued in the near term. However, improved access to on-the-job training and likely gains in real wages due to a tight labour market could help improve spending in the medium term.

Singapore’s short-term economic outlook will be determined by the future path of global trade. Trade policies in the developed world as well as fiscal and monetary accommodation in China are key factors in the near to medium term.

Despite some favourable developments, real GDP growth in Singapore is unlikely to be significantly higher than in the previous couple of years. The Ministry of Trade and Industry forecasts growth of between 1.0 and 3.0 percent in 2017.13 This is likely to be the new normal for Singapore as it grapples with an uncertain external environment and internal structural challenges in its transition to an economy of the future.

This article was originally published by Deloitte University Press on the 20th of June 2017.

About the Author

Lester Gunnion is an Economist and a Senior Analyst at Deloitte Research, Deloitte Services LP. He contributes to Deloitte’s Global and Asia-Pacific economic outlooks, covering the economies of Russia, South Africa, Singapore, Thailand, and Vietnam. Lester also contributes to Deloitte’s economics blog, Behind the Numbers, as well as thoughtware on economic issues in the United States in the quarterly periodical, Issues by the Numbers.

References

1. Ministry of Trade and Industry, Economic Survey of Singapore, 2016, February 17, 2017, https://www.mti.gov.sg/ResearchRoom/SiteAssets/Pages/Economic-Survey-of-Singapore-2016/FullReport_AES2016.pdf.
2. Ministry of Trade and Industry, “Singapore’s GDP grew by 2.5 percent in the first quarter of 2017”, April 13, 2017, http://www.singstat.gov.sg/docs/default-source/default-document-library/news/press_releases/advgdp1q2017.pdf.
3. International Enterprise Singapore via Haver Analytics, “Singapore merchandise exports, percentage change year-on-year, NSA, millions of 2012 S$.”
4. International Monetary Fund, World Economic Outlook, April 2017, http://www.imf.org/en/Publications/WEO/Issues/2017/04/04/world-economic-outlook-april-2017.
5. World Trade Organization, “Latest trade indicator signals sustained momentum in second quarter”, https://www.wto.org/english/news_e/news17_e/wtoi_15may17_e.htm.
6. World Bank, “Trade (percentage of GDP),” http://data.worldbank.org/indicator/NE.TRD.GNFS.ZS?locations=SG, accessed May 31, 2017.
7. International Monetary Fund, World Economic Outlook.
8. Population SG, “Singapore’s population challenge in a nutshell”, October 31, 2016, https://population.sg/articles/singapores-population-challenge-in-a-nutshell.
9. Department of Statistics via Haver Analytics, “Singapore productivity: Output per employed person, percentage change year-on-year, SA, 2010=100.”
10. Department of Statistics via Haver Analytics, “Singapore: Unit labor costs: Overall economy, percentage change year-on-year, NSA, 2010=100.”
11. Ministry of Trade and Industry, “MTI maintains 2017 GDP growth forecast at 1.0 to 3.0 percent”, February 17, 2017, http://www.singstat.gov.sg/docs/default-source/default-document-library/news/press_releases/gdp4q2016.pdf.


G20 – Is the West Governed by Psychopaths?

By Peter Koenig

In this article, the author elaborates on the contentious first agenda of the recently held G20 summit at Hamburg, Germany. In a world where the Masters fom the West have created, funded, and armed these “terrorist” groups, how could they plan to fight it, too? Peter Koenig boldly predicts, it’s just a matter of time before the West completes its suicide.

“Welcome to Hell!” is the slogan with which G20 protesters greet the self-appointed leaders of the world to their summit on 7 and 8 July 2017 in Hamburg, Germany, under Madame Merkel’s auspices to discuss the calamities of our globe and how to resolve them. Never mind that the distress of Mother Earth has been mostly caused by those who represent the West, and now pretend to fix it.

How utterly arrogant – and hypocritical!

In the wake of the summit, police were beating on aggressively against the demonstrators, most of them peaceful, unarmed; but some of them violent and hooded, as old tradition dictates, so they will not be recognised as police themselves or patsies of the police. Many people were hurt, several to the point of hospitalisation. And the meeting just began.

At the onset of the summit, Donald the Trump, the chief-psychopath, is running amok declaring with echo, “America First” – “America First” – trying to justify his decision for the US to quit the Paris Climate Accords. In a cheap attempt to hit Russia under the belt, he offered Europe gas sales, so Europe would no longer be “hostage” to Russia. How arrogant, again. The Donald doesn’t seem to have a clue what he is doing, other than thinking the world is his puppet. By far most Europeans rather buy hydrocarbons from Russia than being in the bloody and ruthless claws of the United States of America – and those dark forces that pull the strings behind Washington.

It remains to be seen to what extent the psychopath-in-chief will have his European, Australian and Canadian vassal-psychopaths lined up and dancing to his tune.

Before the summit, “informal” talks between the odd couple, Donald Trump and Angela Merkel, took place. They apparently focussed on North Korea, Syria, and Ukraine – all countries where the US is intent to destabilise and push for “regime change” – the sort of interference in sovereign nations’ affairs Trump promised during his campaign he would abandon as President. The dark one-eyed Masters didn’t allow it. And he isn’t man enough to stand up for what he was elected. Well, let’s face it – he could lose his job, or worse.

Nobody has elected the G20, nor the G7. “G” stands for Grand or Great. That’s how they see themselves. Everybody takes them for granted, the self-appointed megalos. Nobody seems to question their legitimacy. People only protest against what they stand for. That the G20 are sidelining the official body, the United Nations, is of no concern. Perhaps, because the UN has itself become a puppet of the invisible Masters, manipulated by their executioners, the US of A. So, has any international court that otherwise could hold them accountable for the crimes they committed over the century, or longer and keep committing. The G7, embedded in the G20, are the aggressing driving force for wars, destruction, merciless killing and perpetual chaos.

How hypocritical: you create them, fund them, and you fight them. Lying to the people. How much longer will they swallow the lie?

The G7 – Canada, France, Germany, Italy, Japan, UK and the US – all western nations (Japan follows the western game plan), are also the main creators of terrorism. They fund, feed, train and arm such reputed Islamic terror groups as ISIS/IS, Al Qaeda, Al Nusra – and others that fit the model of their war strategy (sic) of the moment.

Yet, it just emerged – would you believe – that the number one item on the rather fuzzy Hamburg agenda was fighting worldwide terrorism. How hypocritical: you create them, fund them, and you fight them. Lying to the people. How much longer will they swallow the lie?

This reminds of the prominent former German Chancellor, Helmut Schmidt’s words, shortly before his death, in an interview on terrorism to the German paper “Die Zeit”, on 30 August 2007: “I suspect that all terrorists, whether they represent the German RAF, the Italian Brigate Rosse, the French, the Irish, Spanish or Arabs, are relatively modest in their disdain for humanity. They are largely surpassed by certain forms of state terrorism.” – When the journalist asked back, “Are you serious? Whom are you referring to?” Schmidt: “Let’s leave it at that. I really mean what I say” (http://www.zeit.de/2007/36/Interview-Helmut-Schmidt/seite-7 – in German).

Only western megalo-psychopaths could have thought of “creating”, of nominating themselves into an alliance, of which the ultimate goal is to forge a New World Order (NWO), at times also called, One World Order, referring to an unspoken One Anglo-Zionist Government. That’s where we are headed; towards military oppression and financial subjugation of a small Zionist-headed financial and military elite.

It’s still time to wake up, to take our lives into our own hands, shed the mainstream propaganda and blood-thirsty lie-media, ignore them; get out from under the fraudulent privately owned fake dollar monetary system. There are alternatives available. We have to see them, then choose them. It is up to us to let go of the ever oppressing west. But each one of us, has to see the light, the little spark, that tells him or her – that there is something drastically wrong with the life we live, have been living for the last hundred years, that peace is just around the corner, but we have been duped into wars, after wars, after bloody conflict – and wars again. We are dozed with the idea that conflict and aggression is the Big Normal, as it is always inspired and provoked by “others” – mostly by the east. Yes, we believe it. It’s comfortable, and it would be inconvenient having to admit that we have been living a lie – a blatant lie all or most of our lives. Admitting it, and standing up for justice, would be saving ourselves and civilisation – maybe even humanity.

We are dozed with the idea that conflict and aggression is the Big Normal, as it is always inspired and provoked by “others” – mostly by the east.

What and who are these G20? They are the G7 enlarged and disguised in their evil intentions, by 13 other economic power brokers, also often referred to as “threshold countries”, including Russia, China, Brazil, India, Indonesia, Argentina, Mexico, South Africa, Australia, South Korea, Turkey and the EU. Spain is a permanent observer. Of course, the (western) world’s key financial enablers and political institutions, like the IMF, World Bank, Federal Reserve and the UN with its regional sub-hubs, are not missing in Hamburg.

The G20 control two thirds of the world population, 90% of the globe’s economic output and 80% of world trade. Their agenda in Hamburg is semi-secret, except for the items that might interest the populace at large, like fighting terrorism. But certainly, under the guise of “security and terrorism”, they will also discuss, led by the Trump team, how to subdue renegades, such as Iran, Venezuela, Bolivia and, of course, the eastern most link of the new axis of evil, North Korea. Fortunately, there are Russia and China at the table, and Trump with all his arrogance, may have to watch out for not becoming the laughing stock of the summit.

NATO, economy and terrorism go hand-in-hand. Without terror no wars. Without wars no production of weapons, and without military-security industrial complex, the western world’s economy has reached a dead-end. The US depends for more than 50% of its economic output on the war and security machinery with its associated services. Europe, if she continues her status as a US vassal, will in no time march along the same footsteps. Hence, terrorism is a must. Peace is a no-go.

Soon NATO forces facing the Koreas? – Why not. NATO sounds good; the alliance of the willing – led by Washington, hiding behind the NATO emblem. In the land of the lawless, impunity is borderless.

Did you know, that at the opposite end of the globe, Washington’s foremost neocon vassal, the President of Colombia, has asked NATO for support in the fight against “delinquency” – i.e. the FARC, with whom they signed a fake, make-the-world-believe peace agreement, largely disarmed them as part of the deal, and now FARC has been tricked. President Santos (the Peace Nobel – sounds like Obama and Kissinger!), and his Washington Masters want to completely wipe out that important peasant movement, the only resistance against the US supremacy over their land, and against Washington’s continuous support of the drug cartels.

As the illegitimate G20 and G7 – NATO is just taken for granted. But be aware – it’s a criminal institution made for killing societies and subordinating sovereign nations.

Never mind that NATO has nothing to do with South America, or with Asia, or the Middle East, for that matter. The atrocious NATO killing machine will do their work in the process of subjugation anywhere in the world, while most people just close their eyes and ears, and remain mute. As the illegitimate G20 and G7 – NATO is just taken for granted. But be aware – it’s a criminal institution made for killing societies and subordinating sovereign nations. Washington’s current plan is controlling Russia, via NATO’s eastern European border aggressions, and China, by constantly provoking and threatening North Korea’s sovereignty.

That’s why the G20 will not miss talking about NATO prerogatives in war and conflict resolutions and, of course, in fighting terrorism. Surely, Russia and China will not fall for it.

After debating supportive mechanisms like wars and the lie-propaganda – Goebbels would be proud – economy and finance will have centre stage. How to speed up financial globalisation to attain in the shortest span of time “Full Spectrum financial and monetary Dominance”? – The western economy is running on empty – its main thriving force is greed and instant profit by a few. Privatisation of all state assets is part of the final run. The people are left behind. The people, the lot that needs to consume to fulfil for an ever-tinier elite the abject target of greed for “more and more”, the insatiable appetite. These people will soon vegetate in a sucked-dry space, robbed of social infrastructure and welfare.

What’s left is the enslavement by debt. To survive, people may commit to the “debt-row”, gradually converting into the death-row. As un-behaving countries are forced to do – swallowing debt against being fed minimal rations for survival. Greece is the epitome of this razors-sharp knife that slashed throats as well as the last goblet of the lifeline to survival. Solidarity is nowhere.

The dying beast is lashing out, right and left and above and beneath. It is desperate; itself on death-row, but if it must die, then dying we must all – the deadly grip of the rabies-diseased dog that won’t let go. And won’t let go. And won’t let go to the last minute – or until death reigns over us all. That’s the risk we are running. A nuclear holocaust where, as Mr. Putin said already on a number of occasions, nobody will survive. The G20 know it.

But never forget – whatever the G20 do and decide is without legitimacy, as they themselves are not legitimate. The police in Hamburg has no right to suppress a movement against the illegitimate power of insane dictators that formed a conglomerate of illegitimate gangsters.

What’s left is the enslavement by debt. To survive, people may commit to the “debt-row”, gradually converting into the death-row. As un-behaving countries are forced to do – swallowing debt against being fed minimal rations for survival.

The oppressive police in Hamburg, ordered by Merkel, to suppress dissent, is but a forewarning for what is to come when Europe is being fully militarised. For those who are not aware, there is currently a “ghost town” being built by the Bundeswehr in collaboration with NATO, for hundreds of millions of euros, in one of Germany’s most modern military training camps, in Sachsen-Anhalt, not far from Hamburg. Starting in 2018, the artificial town will be ready for training NATO and EU military forces for urban warfare, to suppress possible upheavals and protests in the wake of neofascist economic measures – à la Greece – being forced upon Europe. Merkel and the NATO “leaders” (sic) predict that the people may not just take it.

Therefore, the preparation to suppress possible dissent in European cities. Police and military will not shy away from killing their own brothers. We are witnessing how this is done, and has been done for the last seven years to an entire nation – beautiful Greece, the land that has given us the philosophers, mathematicians and scientists we still laud and admire – and the true concept of democracy which the west has used and abused for its trickery and deceit. Today, what’s left is a pipe-dream; and a powerful slogan being used by the most undemocratic tyrannical nation and her vassals to accuse those who do not bend to their dictate.

The G20s are playing the game as long as they are allowed to. Most of them are aware that it may be their end-game, that the future is in the East, that the West is passé, that it is just a matter of time before the West completes its suicide with greed, aggression and lies.

Featured Image: G20 summit 2017 in Hamburg, Germany.

About the Author

koenig-webPeter Koenig is an economist and geopolitical analyst. He is also a former World Bank staff and worked extensively around the world in the fields of environment and water resources. He lectures at universities in the US, Europe and South America. He writes regularly for Global Research, ICH, RT, Sputnik, PressTV, The 4th Media, TeleSUR, TruePublica, The Vineyard of The Saker Blog, and other internet sites. He is the author of Implosion – An Economic Thriller about War, Environmental Destruction and Corporate Greed – fiction based on facts and on 30 years of World Bank experience around the globe. He is also a co-author of The World Order and Revolution! – Essays from the Resistance.

Navigating the Investment Minefield

By H. Kent Baker and Vesa Puttonen

Fraudsters are always on the look out for prey – investors they can manipulate and take advantage of. The authors discuss 8 traps you should look out for in navigating through the investment minefield. After all, vulnerability, if not gullibility, and can be costly.

The investment world can be a scary place, especially given that some people want to take advantage of you by setting investment traps. A trap is something that can lead to losses of capital or opportunities to make productive investments. Given that many investment traps are difficult to detect, what chance do investors have navigating the investment minefield and emerging unscathed? The answer is not much unless they become aware of the traps that are strewn along their path and sidestep them. Although succumbing to such traps is unlikely to be fatal, it can seriously harm personal wealth, affect achieving financial goals, and damage self-esteem. Our purpose is to expose eight common investment traps so that you can avoid falling victim to them.

Trap 1. Becoming a Victim of Investment Fraud and Other Scams

Have you ever been a victim of investment fraud? If not, you probably know someone who has. The countless number of investment frauds, scams, cons, schemes, and swindles demonstrates how easily skilled fraudsters can dupe unsuspecting investors. In his book Swindling Billions: An Extraordinary History of the Great Money Fraudsters, Kari Nars estimates that fraud victims around the world have lost hundreds of billions of dollars in the last decade to investment fraud.1 Anyone with money is at risk of investment fraud. Even highly successful, financially intelligent people can fall prey to investment fraud. For example, Bernie Madoff’s infamous Ponzi scheme fooled thousands of individuals, including celebrities, as well as financial institutions and universities. A Ponzi scheme is a form of investment fraud that involves the payment of purported returns to existing investors from funds contributed by new investors.

People also have a psychological need to feel special. Fraudsters play upon this need by convincing them that they are part of an “exclusive club” and are being given special access to an investment opportunity.

Investors fall for scams for many reasons. Some people are gullible so fraudsters prey on their trusting nature. Other investors are irrational and driven by emotion, which makes them particularly susceptible to becoming victims of investment fraud. Because investors are attracted to financial gain, the lure of “get-rich-quick” schemes flames their innate desire to become financially better off. In an uncertain financial environment, investors often turn to others who appear or proclaim to be experts only to have these people take advantage of them. On other occasions, investors can be overly optimistic, which makes them more likely to be hoodwinked than others. People also have a psychological need to feel special. Fraudsters play upon this need by convincing them that they are part of an “exclusive club” and are being given special access to an investment opportunity. Finally, investors are more vulnerable when they believe they are knowledgeable. Although this sounds counterintuitive, those who have some experience in investing or believe they are experts are more susceptible to investment fraud than others. Such investors think they know more than they actually do or that they are too smart to fall for a scam.

To avoid being scammed, you should be aware of several major warning signs. One common warning sign is someone touting an investment with high guaranteed returns with little or no risk. Claims of huge gains with almost no risk are illusions or “phantom riches” for unsuspecting investors. All investments carry some degree of risk. Fraudsters dangle the prospects of easy money to entice you to buy. Investments that seem too good to be true probably are. Another red flag is an investment hyped as a “once-in-a-lifetime deal”. You should also be suspicious of claims that “everyone is buying” and resist pressure to buy quickly. No reputable investment professional should push you to make a quick decision. Although not applicable to all investments, you should be suspicious of investments, such as common stocks or equity mutual funds, providing consistently stable returns regardless of market conditions. Returns generally vary over time due to market volatility. A final warning sign concerns investments or strategies that are overly complex. If you don’t clearly understand the investment, walk or better run away.

Trap 2. Misrepresenting Risky Products as Safe

Many investors are attracted to investments promising stable returns. This desire helps explain why so many “stable returns”, “capital guaranteed”, and “low volatility” products are available in financial markets. Although these descriptions may accurately describe some products, less scrupulous individuals or firms may misrepresent risky products as safe. Risky investments offer the potential of high returns but they also have a large chance of loss of capital or underperformance. As Robert Arnott, an American entrepreneur, investor, editor, and writer, notes, “In investing, what is comfortable is rarely profitable”. In most cases, you can’t eat your cake and have it too. Investments always involve risk-return trade-offs.  

Many examples are available around the world in which various parties have misrepresented risky products as being safe. Notable examples include mortgage-backed securities in the United States, preference shares in Spain, money market funds with floating rate notes in Finland, and Minibonds in Hong Kong. Let’s examine the case of Minibonds, which is a brand name for a series of structured financial notes. Using the term “bond” to describe these products is misleading but was intended to inspire confidence. The return paid by these structured products was linked to a basket of shares, a stock market index or the creditworthiness of various publicly-listed corporations. Both the return and the consumer’s original investment depended on the ability of the issuing investment bank to make the payments due under the structured product. Lehman Brothers was the investment bank. In total, more than 43,700 consumers bought HK $20.23 billion (US $2.6 billion) worth of Lehman Brothers structured products through retail banks. When Lehman Brothers collapsed in September 2008, the supposedly “low-risk” Minibonds generated huge losses for individual investors.

Trap 3. Making Unrealistic Return Expectations

Having unrealistic return expectations is a common investment trap. This is especially true of new or inexperienced investors who enter the market at a time of extreme exuberance because they become disillusioned when they start experiencing paper losses. The possibility of missing out on such high returns is simply too much to bear. However, investors, even professionals, are notoriously poor market timers. Greed and overoptimism have been the ruin of many investors. You would be wise to heed the warning provided by investment firms that “past performance does not guarantee future results”.

Investors need to be aware of several misconceptions that lead to making unrealistic return expectations. One fallacy is that a good company such as one that has experienced rapid growth in the recent past makes a good investment. In fact, shares of “good companies” may or may not turn out to be “good investments” by providing good returns. Although good companies might have generated excellent past returns, the current valuation should reflect all company features. Therefore, any good firm characteristic that is priced by the market is associated with lower, not higher, return expectations.

Another fallacy is that economic growth is good for stock returns. This misconception leads to the belief that investing in countries with strong economic growth such as emerging markets offers better returns to equity holders than countries with less vibrant economies. The faster growth is typically associated with stronger earnings growth, which many investors associate with higher expected stock returns. This misguided idea of excessive return expectations has been a major sales pitch for emerging market mutual funds. This growth trap seduces investors into overpaying for the equities in emerging markets. Empirical evidence on the link between economic growth and returns to shareholders shows that shrinking industries and slower-growing countries offer some of the best-performing investments.2

Trap 4. Falling for Mutual Fund Traps

Although mutual funds offer many advantages, some traps can snare unsuspecting investors. One common trap is investing in past winners. Mutual fund companies generally advertise their best-performing funds.3 This tactic creates a relatively one-sided image of the company’s offering of mutual funds and directs investor attention toward past performance reinforcing the habit of selecting mutual funds with the highest realised returns. For most investors, buying past winners is not a value enhancing strategy after expenses and fees. Top performers do not typically stay on top for very long. Thus, this year’s top funds can easily become next year’s duds. Still, research indicates that investors should avoid poorly performing funds because their performance may persist for many years due to high expenses and fees.4

Additionally, some conventional wisdom about investing in mutual funds lacks empirical support. For example, investors are often encouraged to buy established mutual funds with experienced portfolio managers that have good long-term track records. Although this might seem like sound advice, recent evidence shows that young actively managed funds tend to outperform their older peers because the new entrants are more aware of the latest techniques. Furthermore, performance tends to deteriorate as funds grow older. Researchers find that funds with three years or less in age actually outperform funds with more than 10 years of history by almost 1 percentage point annually.5 Thus, investing in younger, rather than older, funds may be less risky.

Trap 5. Overpaying for Products and Services

You’re probably familiar with the saying “you get what you pay for”. In commercial transactions, the quality of goods and services often increases as the price increases. That is, paying more can mean getting better quality merchandise. However, paying more for investment products and services does not necessarily lead to higher performance or returns.

A recent phenomenon in the mutual fund industry is closet indexing. Closet indexers are funds that closely track a benchmark while claiming to be active and charging fees similar to those of truly active managers. You can achieve a similar result by investing directly in a less expensive index fund. In some cases, funds become closet indexers as they grow in assets. This fact helps to explain why some superstar managers fail over time. Buyers should be wary of funds charging a fee for active management but whose performance barely varies from the index. Research shows that closet indexers are doomed to underperform after considering fees and that closet indexing is rife in US active funds.6 

A fund of funds (FOFs) is an investment strategy in which a fund invests in other types of funds. This strategy applies to any type of investment fund, from a mutual fund to a private equity fund to a hedge fund. In general, a FOF strategy tries to achieve broad diversification and appropriate asset allocation with investments in different fund categories. FOFs appeal especially to small investors who don’t want to invest directly in securities. A drawback is that investors basically pay double for an expense that is already included in the expense figures of the underlying funds.

Trap 6. Investing in Complex Products

Never invest in something you don’t understand. If you do, you are inviting disappointment. The amount and complexity of different kinds of investment products available in today’s markets can be overwhelming. The complexity of financial products has increased steadily, even after the financial crisis of 2007-2008, and is more prevalent among distributors with a less sophisticated investor base. Additionally, financial complexity increases when competition intensifies.

Never invest in something you don’t understand. If you do, you are inviting disappointment.

Although the typical investor should avoid investing in overly complex financial products, this may be easier said than done. Structured products have been a success story in retail finance. Low interest rates drove investors in search of structured products apart from traditional asset classes such as equities, fixed income, and real estate. Structured products tend to have complicated contract terms making the valuation of the product difficult for retail investors. Conditions can include different averaging methods for starting and ending values and caps limiting the maximum price increase of the underlying asset (e.g. stock index) in which the investor will participate. The proper valuation of these products requires complicated financial modelling, which results in the product-issuing financial institution having a clear information edge over its clients. Evidence shows that financial complexity in European markets has been steadily increasing. The more complex a retail structured product is, the more profitable it is for the bank.

Trap 7. Engaging in Gambling Disguised as Investing

According to some Wall Street skeptics, the stock market is the capitalist casino, a place where gambling wears a thin mask called investing. However, this cliché doesn’t adequately differentiate between gambling and investing and represents a misinformed view. Investing isn’t simply gambling by another name because gambling is a no-win venture whereas investing isn’t. Despite some superficial similarities between the two concepts, major differences exist between gambling and investing. The main difference is that an investor’s expected return is positive whereas a gambler’s expected return is negative. Two areas where gambling is disguised as investing, at least for individual investors, involve foreign exchange and excessive online trading.

Currency trading is a zero-sum game. This means that in FX trading, one’s win is always another’s loss. In fact when accounting for commissions and other expenses, FX trading becomes a negative-sum game. Online trading platforms targeted to unprofessional investors are gambling disguised as investing. After going online, investors tend to trade more actively, more speculatively, and less profitably than previously. Evidence shows that individual investors destroy value through active trading.

Trap 8. Relying on Unsupported Promises

Some financial products are sold using marketing claims unsupported by evidence. For example, long/short equity funds claim that they can provide a “free-lunch”. The phrase “there’s no such thing as a free lunch” is often used to describe situations in which investors are unable to consistently make large profits without bearing the risk of a potential loss. Other examples of unsupported promises involve investment letters and investment clubs.

This diverse market of newsletters consists of around 1,300 different newsletters in the United States and Canada with an annual industry revenue of more than $3.4 billion. These numbers indicate a clear demand for investment newsletters. Several studies on investment newsletter performance find that securities recommended by investment newsletters don’t outperform appropriate benchmarks and thus don’t generate positive abnormal returns. The media attention given to a few well-performing investment clubs created a public consensus that investment clubs tended to outperform the markets. Evidence suggests the opposite. One academic study denounces the widely suggested claims of general outperformance of the clubs. Of a sample of 166 investment clubs, 60% underperformed the market.7

Lessons Learned

Heeding the following lessons should reduce your chances of becoming a victim of investment traps.

Don’t let anyone talk you into buying a financial product you don’t fully understand. You may recall the admonition, “If something sounds too good to be true, it probably is.” Although this is good advice, the problem is determining when “good” becomes “too good”.

Don’t assume that laws in place will automatically protect you from any kind of foul play. You are responsible for checking the true content of the offering.

Do your due diligence and don’t simply rely on those making the claims. You should ask questions and keep a healthy sense of skepticism. If someone makes a questionable claim, ask for evidence. Being inclined to easily trust anyone who is trying to sell you something gives way to vulnerability, if not gullibility, and can be costly.

Check with relevant regulatory authorities for any complaints or investigations involving those offering the products.

Don’t assume that laws in place will automatically protect you from any kind of foul play. You are responsible for checking the true content of the offering. 

Don’t let greed overcome your good judgment. Although not speaking about investments, Stephen Hawking, an English theoretical physicist, cosmologist, and author, notes: “We are in danger of destroying ourselves by our greed and stupidity.” If your internal alarm bell rings, listen to it and find another investment. 

This article draws on some themes from the authors’ book Investment Traps Exposed – Navigating investor Mistakes and Behavioral Biases published by Emerald Publishing in 2017.

About the Authors

H. Kent Baker, CFA, CMA is University Professor of Finance at American University’s Kogod School of Business in Washington, DC. He is the author or editor of 28 books and more than 165 refereed journal articles. The Journal of Finance Literature recognised him as among the top 1 percent of the most prolific authors in finance during the past 50 years. Professor Baker has consulting and training experience with more than 100 organisations. He has received many research, teaching and service awards including Teacher/Scholar of the Year at American University.

Vesa Puttonen is Professor of Finance at Aalto University School of Business in Helsinki.  He has published 16 books and more than 30 journal articles on different aspects of Strategic Finance, Risk Management, Behavioural Finance, and Investing. Professor Puttonen has worked as Senior Vice President at the Helsinki Stock Exchange and as Managing Director at Conventum Asset Management (Helsinki). He is a faculty member of MBA Programs in Helsinki, Hong Kong, Singapore, Poland, China, Iran, Taiwan, and South Korea.

References

1. Kari Nars. 2009. Swindling Billions: An Extraordinary History of the Great Money Fraudsters. London: Marshall Cavendish Business.
2. Jay R. Ritter. 2012. “Is Economic Growth Good for Investors?” Journal of Applied Corporate Finance 24 (3), 8 – 18.
3. Jonathan J. Koehler and Molly Mercer. 2009. “Selection Neglect in Mutual Fund Advertisements.” Management Science 55 (7), 1107-1121. Congsheng Wu. 2009. “Mutual Fund Advertisements.” Investment Management and Financial Innovations 6 (2), 68 – 76.
4. Matthew R. Morey. 2016. “Predicting Mutual Fund Performance.” In H. Kent Baker, Greg Filbeck, and Halil Kiymaz (eds.), Mutual Funds and Exchange-Traded Funds – Building Blocks for Investment Portfolios, 349 -363. Hoboken, NJ: John Wiley & Sons, Inc.
5. Lubos Pastor, Robert F. Stambaugh, and Lucian A. Taylor. 2014. “Scale and Skill of Active Management.” NBER Working Paper No. 19891. February.
6. Antti Petajisto. 2013. “Active Share and Mutual Fund Performance.” Financial Analysts Journal 69 (4), 73 – 93.
7. Brad Barber and Terrence Odean. 2000. “Too Many Cooks Spoil the Profits: Investment Club Performance.” Financial Analysts Journal 56 (1), 17 – 25.

Wikipedia as Illustration of the Truth-Seeking Rationale for Freedom of Expression

By Mark Cenite

Empirical evidence for the truth-seeking rationale for freedom of expression – the assertion that truth prevails in a free marketplace of ideas – is difficult to interpret. Analysis of how Wikipedia functions, and the accuracy of its content, provides preliminary indications of the validity of the truth-seeking rationale and its limits.

A rationale for protecting freedom of expression that ranks among the most cited is the truth-seeking rationale. According to this rationale, information and opinion should circulate free of government controls. The sanguine conclusion is that truth, or at least the best ideas, will prevail in the end. The evidence for this sweeping conclusion is limited and disputable, as this article demonstrates. Given the paucity of solid evidence from other contexts, this article suggests that Wikipedia can serve as an illustration of how relatively unfettered expression can lead to the best content prevailing, at least in some circumstances. 

Despite the limited evidence for it, citations of three famous sources of the truth-seeking rationale are frequent. An early expression of the rationale is from English poet John Milton’s Areopagitica (1644), his defense of free speech, in which he uses a metaphor of Truth and Falsehood wrestling and Truth winning in a fair match.1 Areopagitica has been cited 478 times in law review articles published since 1982 that are available in LexisNexis Academic; there are also 49 citations of it in federal and state cases available in the LexisNexis database from throughout United States legal history.2 Another source for the rationale is English philosopher John Stuart Mill’s On Liberty (1859), in which he advanced the argument that truth will prevail and that a side effect of the struggle to identify the truth is that participants in the debate, and those in the audience, may gain a keener appreciation of the truth that finally emerges. A search for citations of Mill’s On Liberty and “free speech” returns 1,683 hits from law reviews and 65 hits from the US cases since Mill’s publication of the work.3 Justice Oliver Wendell Holmes is often cited for the view the truth would prevail in the “marketplace of ideas”, though Holmes did not actually use the exact phrase, but instead words with similar meaning: “[T]he best test of truth is the power of the thought to get itself accepted in the competition of the market.”4 A LexisNexis search for “Holmes” and “marketplace of ideas” yields 2,979 hits in law reviews and 193 hits in cases.

In the sentence after Holmes advanced this “marketplace of ideas” rationale, he wrote that it “is the theory of our Constitution. It is an experiment, as all life is an experiment. Every year, if not every day, we have to wager our salvation upon some prophecy based upon imperfect knowledge.”5 Is the rationale merely a prophecy? What are the results of the ongoing experiment? What evidence can one cite of the free marketplace of ideas actually creating conditions in which the best ideas prevail? We shall discuss national comparisons and a famous study of the incidence of famine in liberal democracies.  Though the illustration is imperfect, we argue that analysing Wikipedia as a contemporary example of a well-functioning free market of ideas is preferable to making a statement, on blind faith, that truth emerges.

Evidence for the Truth-Seeking Rationale: National Comparisons

One might say that the truth-seeking rationale is being tested regularly, if one contrasts debates in societies that enjoy more freedom of speech with others. In free societies, does truth displace falsehood? If we simply look at the national level, there are too many confounding variables to make comparisons rigorously. The most difficult question is how to assess the outcome variables: How does one choose the variables to examine to assess which ideas are true (or best) and whether they have prevailed? A less complex but real concern is assessing the level of freedom of expression in nations; ratings and rankings of organisations like Reporters Without Borders and Freedom House are fraught with controversy for being subjective, biased, or imprecise.6

Free expression is a factor that facilitates discovery of better arrangements for distributing basic resources; the best ideas prevail, at least in this very narrow context. 

Limited evidence supporting the rationale comes from Amartya Sen, the Nobel Prize winning economist, who found that there has never been famine – widespread hunger that results in part from human error – in a functioning democracy with a free press.7 He suggested this correlation is not spurious, but may actually be a result of causation. Sen suggests that in free societies, citizens and the press take the steps necessary to intervene in the sequence of missteps that results in famine. Free expression is a factor that facilitates discovery of better arrangements for distributing basic resources; the best ideas prevail, at least in this very narrow context.  

Despite the weakness of the evidence for it, the truth-seeking rationale has become something of a cliché in free societies. The rationale has its detractors, however, such as legal scholar Alexander Bickel, who wrote, “[W]e have lived through too much to believe it”, for one must ask “whether our experience has not taught us that even such ideas [as proletarian dictatorship, segregation, or genocide] can get themselves accepted” in the marketplace of ideas.8 Legal scholar Lee Bollinger wrote that if truth emerges in the long run, it may be too late for many who suffer through the process.9 “Market failure” theorists point out that just as entirely free markets sometimes fail to produce the best outcomes and can benefit from government regulation, the marketplace of ideas can fail: lack of economic resources can prevent some from participating in debates that are controlled by wealthy media owners and dominated by voices backed by big promotional budgets.10 Sceptics of the truth-seeking rationale abound; the founding Prime Minister of Singapore, Lee Kuan Yew, was among those who emphasised that freedom of expression would lead to “a mess” unless people were sufficiently educated for a well-informed, rational debate: “This free-for-all, this notion that all ideas should contend and there will be blinding light out of which you will see the truth – ha!”11

Wikipedia as Marketplace of Ideas

Given the paucity of good tests of the truth-seeking rationale, we ask: To what extent does Wikipedia approximate a free marketplace of ideas? And to what extent do the best ideas prevail there? The tentative conclusion of this article is that Wikipedia provides suggestive evidence that a marketplace of ideas operates surprisingly well for truth discovery.

Wikipedia, founded by Jimmy Wales in 2001 and governed by the nonprofit Wikimedia Foundation, has long ranked as one of the most-visited Internet sites.12 Anyone can write or amend Wikipedia articles. A user can register for a screen name, but one of the core, immutable rules of Wikipedia is that one does not need to register for a username to make edits.13 Wikipedia mandates a “neutral point of view”: Contributors are to make articles that emphasise the facts that people agree upon and, when covering controversies, mention disagreements and attribute them to their sources.14 Users can tag content that departs from content guidelines.15 Wikipedia has administrators who have powers to do things like lock a page temporarily when users get involved in “edit wars” (repeatedly changing the content of a page)16 or when “vandalism” occurs, including violations of guidelines such as adding abusive language, nonsense, or personal attacks to an entry.17

Is Wikipedia a Functioning Free Market of Ideas?

No one claims Wikipedia is perfect, and the ease with which one may make changes has been the target of jokes and critiques.18 How well does Wikipedia approximate a free exchange of ideas? Contributions might be likened to a grand debate in the town square among all who wish to contribute – no matter how ridiculous, misguided or inaccurate their views. As in a debate, there is no guarantee that one’s contributions will be accepted. Users are encouraged to correct each other’s errors, update information, and to call attention to bias. The difference from a debate is that in Wikipedia the conclusion is digitally written down, and collectively edited and rewritten, to reflect at least a temporary consensus.

Wikipedia is like a free marketplace of ideas in that it lacks vetting at the point that a contribution is made.

Wikipedia is like a free marketplace of ideas in that it lacks vetting at the point that a contribution is made. In free speech jurisprudence, the most disfavoured type of censorship is prior restraint, a kind of censorship in which content is vetted and suppressed (or restrained) prior to its circulation; subsequent punishment (after publication) is seen as a preferable way to control expression, and better yet is no punishment at all, but simply more debate on the issue (sometimes called “counter-speech”).19 On Wikipedia there is an absence of anything remotely analogous to prior restraint – there is not any sort of editorial vetting of content prior to circulation. There is also absence of prior restraint in a more classic legal sense on Wikipedia: Wikipedia generally does not carry out the many requests from governments around the world to remove content.20  Government agents can make their own alterations to content, but they are individual users like any others.21

The comparison of Wikipedia to the free press is an imperfect analogy. However, the freedom of Wikipedia contributors from any constraints – freedom from editing before publication as well as freedom from government censorship – creates a platform that may be one of the closest approximations of an international free marketplace of ideas.

Does the Best Content Prevail on Wikipedia

In a free marketplace of ideas, truth is supposed to prevail, according to this rationale. Does it? There is limited but encouraging evidence regarding the factual accuracy (the truth or falsehood) of the entries. In a frequently-cited study published in Nature, experts compared the entries on 42 scientific topics in Wikipedia and in the Encyclopedia Britannica, whose articles are written by paid subject experts.22 For example, both sources’ articles about the centre of our solar system, the sun, were examined. Across the pairs of articles, there were four errors in each source that were judged serious. On average, each of the Britannica articles contained 3 errors that were judged minor, compared to 4 minor errors in each Wikipedia article. Wikipedia is different in other ways, however; entries are far more up-to-date, and its scope is more comprehensive.

In a 2012 preliminary study conducted by Wikimedia Foundation in cooperation with Oxford University, Wikipedia articles in multiple languages were compared to entries in other encyclopedias in those languages. Across multiple disciplines, expert judges found Wikipedia articles superior in accuracy and references, though Wikipedia was weaker in style and overall ratings for some articles.23 The Journal of Oncology Practice also found similar accuracy of Wikipedia entries and a professionally edited database of medical information, though Wikipedia was judged less readable.24

What to conclude from these studies? Wikipedia’s free marketplace of ideas seems to have produced a high standard of accuracy compared to expert authors. Lower readability and style ratings for Wikipedia, plus the slightly higher rate of minor errors in one study, are perhaps compensated for by the more comprehensive and up-to-date coverage.

Preliminary Conclusions

Wikipedia provides a useful example for teaching and for illustrating the truth-seeking rationale in action because its input is free of any sort of restraints and the output is high quality. Because it is designed to allow contributors freedom from central control, and because its operators resist efforts to censor it, Wikipedia operates as an ongoing test of the whether truth prevails when, to paraphrase Milton, truth and falsehood grapple freely. So far, the accuracy of Wikipedia has proven reassuringly comparable to other sources that are authoritative by traditional measures.

Wikipedia provides a useful example for teaching and for illustrating the truth-seeking rationale in action because its input is free of any sort of restraints and the output is high quality.

Wikipedia’s “edit wars” and “vandalism” are also potentially revealing. Perhaps crowdsourcing of the truth in a free marketplace of ideas works best when more neutral subjects are involved, such as the mundane scientific entries about the sun in the Nature study. But when matters of passionate dis-agreement are involved – such as articles about controversial figures like Donald Trump – Wikipedia’s authorities, its editors, intervene in the free market and block some contributors or lock the page. Once again, the comparison to regulation is thought-provoking; even in many relatively free societies, regulations control some kinds of expression, including offensive content. The rare instances in which Wikipedia’s editors intervene suggest that the marketplaces of ideas may function best when it is relatively, but not completely, free.

About the Author

Mark Cenite is Associate Chair (Academic) at the Wee Kim Wee School of Communication & Information, part of Nanyang Technological University in Singapore. He has a law degree from Stanford Law School and a PhD in Communication from the University of Minnesota. He is a winner of multiple awards for teaching Law in Singapore, and has also taught Law in the United States and Hong Kong. 

References

1. “And though all the windes of doctrin were let loose to play upon the earth, so Truth be in the field, we do injuriously, by licencing and prohibiting to misdoubt her strength. Let her and Falshood grapple; who ever knew Truth put to the wors, in a free and open encounter.” John Milton, Areopagitica(1644).
2. Results reported here were from searches conducted on 19 September 2016 in the LexisNexis database in the category “US Law Reviews and Journals” from all available dates (since 1982), and in the category “US Federal & State Cases” from all available dates. The search term used was simply the title “Areopagitica.”
3. The search terms were “Mill” within 5 words (/5) of “On Liberty” and the term “free speech”.
4. Abrams v. United States, 250 U.S. 616, 630 (1919) (Holmes, J., dissenting).
5. Abrams, 250 U.S. 616, 630 (Holmes, J., dissenting).
6. Reporters Without Borders is available at https://rsf.org; Freedom House is available at https://freedomhouse.org. A podcast criticising the methodology of Reporters Without Borders is Bob Garfield’s interview with Max Fisher, “No, US press freedom is not in dire decline,” WNYC’s On The Media, Feb. 14, 2014, at http://www.wnyc.org/story/press-freedom-not-decline
7. Amartya Sen, Development as Freedom(1999).
8. Alexander Bickel, The Morality of Consent71, 76-77 (1975).
9. Lee C. Bollinger, The Tolerant Society74 (1986).
10. Jerome A. Barron, Access to the Press: A New First Amendment Right, 80 Harv. L. Rev. 1641-1678 (1967).
11. “Intellectual Free-For-All Not for the Masses, Says SM Lee,” Business Times (Singapore) (Oct. 6, 1995).
12. See Alexa Internet, http://www.alexa.com
13. “Wikipedia: Rules,” https://simple.wikipedia.org/wiki/Wikipedia:Rules
14. “Wikipedia: Neutral point of view,” https://simple.wikipedia.org/wiki/Wikipedia:Neutral_point_of_view
15. “Wikipedia: Tagging pages for problems,” https://en.wikipedia.org/wiki/Wikipedia:Tagging_pages_for_problems
16. “Wikipedia: Edit War,” https://simple.wikipedia.org/wiki/Wikipedia:Edit_war
17. “Wikipedia: Vandalism,” https://simple.wikipedia.org/wiki/Wikipedia:Vandalism
18. “Will Wikipedia Mean the End Of Traditional Encyclopedias?” The Wall Street Journal (Sept. 12, 2006).
19. Thomas I. Emerson, The Doctrine of Prior Restraint, 20 Law and Contemporary Problems648-671 (1955), at: http://scholarship.law.duke.edu/lcp/vol20/iss4/10
20. Wikimedia reports that Wikipedia received 243 requests to take down content from January through June of 2016 and none were granted. See https://transparency.wikimedia.org/content.html
21. There are some caveats to the argument that Wikipedia is free of government control, for authorities can of course punish contributors in their jurisdictions, and nations including China block Wikipedia, thus blocking not only readers but contributors. See Jimmy Wales, “State of the Wiki: Free Expression and Wikipedia,” speech at Wikimania 2015, at https://www.youtube.com/watch?v=6p50HVv1rU4
22. Jim Giles, Internet Encyclopaedias Go Head to Head, 438 Nature900-901 (15 December 2005).
23. Imogen Casebourne, Chris Davies, Michelle Fernandes, & Naomi Norman (2012), Assessing the Accuracy and Quality of Wikipedia Entries Compared to Popular Online Encyclopaedias: A Comparative Preliminary Study across Disciplines in English, Spanish and Arabic. Retrieved from: http://commons.wikimedia.org/wiki/File:EPIC_Oxford_report.pdf
24. Malolan S. Rajagopalan, Vineet K. Khanna, Yaacov Leiter, Meghan Stott, Timothy N. Showalter, Adam P. Dicker & Yaacov R. Lawrence, Patient-Oriented Cancer Information on the Internet: A Comparison of Wikipedia and a Professionally Maintained Database. 7 Journal of Oncology Practice 319-323 (2011), at http://www.jop.ascopubs.org/content/7/5/319.full

Patient Capital in the Context of the Belt and Road Initiative (BRI)

By Justin Yifu Lin and Yan Wang

As the world is carefully watching China’s Belt and Road Initiative, many new opportunities continue to spring from the country’s endeavour. In this article, the authors elaborate on New Structural Economics and “going beyond aid” as an ideal development objective for trade, aid, and investment in relation to developing countries.

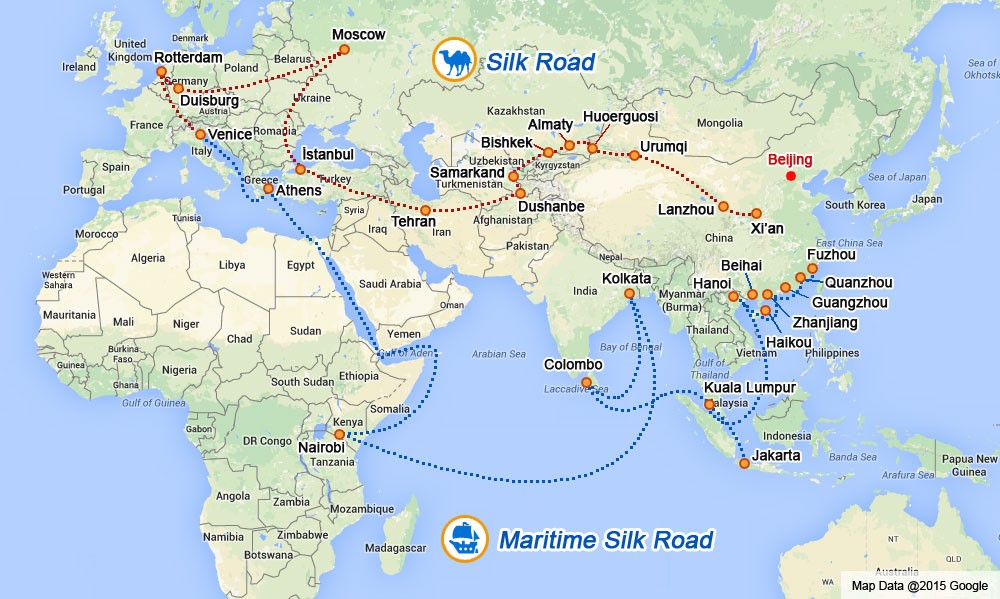
Against the backdrop of Brexit and the “Paris-exit” by the Unite States, China-led “Belt and Road Initiative (BRI)” was welcomed by many, as shown by its Forum held in Beijing with 29 heads of state attending and over 100 countries represented. What is the rationales behind the “Belt and Road Initiative (BRI)?1  What is the theoretic foundation of South-South Development Cooperation (SSDC)? How does it differ from Aid? How to finance the BRI and other infrastructure gaps in the developing world?

The idea that the Official Development Assistance (ODA) must be concessional is questionable. Economic development is the main purpose of ODA, yet some of the more effective instruments of facilitating structural transformation, such as equity investment and large non-concessional loans for infrastructure are excluded from the OECD definition of ODA. Our new book, Going beyond aid: Development Cooperation for Structural Transformation, published by Cambridge University Press,2 is an attempt to explore these rationales and provide a theoretic foundation based on New Structural Economics.3 In our view, we need to “go beyond aid” with a broader concept including trade, aid and investment for development objectives. Differing from the OECD definition, South-South Development Cooperation (SSDC) combines trade, aid and public and private investment, utilises comparative advantages of each countries and their intimate know-how on development, and hence is more effective in overcoming bottlenecks in partner countries. Whereas, the OECD definition of ODA separates aid from trade, delinks aid with private investment and foreign direct investment, and therefore, “comparative advantage”, a trade concept, cannot be utilised in official aid. 

The rationales of BRI are related to China’s own structural transformation, and are deeply rooted in its thousand-year history of Confucianism, who said, “One who wishes himself to be successful must also help others to be successful; one who wishes to develop himself must also help others to develop.”

The New Structural Economics (NSE) starts with the observation that the nature of modern economic development is a process of continuous structural change in technologies and industries, which raises labour productivity, and hard and soft infrastructure, which reduces transaction costs, making possible the continuous increase in per capita income in an economy.4  According to the NSE,  the most effective and sustainable way for a low-income country to develop is to jump-start the process of structural transformation by developing sectors of its latent comparative advantages, which the country has low factor costs of production determined by its endowment structure but  high transaction costs  due to inadequate hard and soft infrastructure. The government can help transform the sectors with latent comparative advantages into the nation’s competitive advantages by reducing transaction costs through special economic zones or industrial parks with good infrastructure and an attractive business environment. If a developing country adopts this approach, it can immediately grow dynamically and launch a virtuous circle of job generation, export expansion and poverty reduction, even though overall infrastructure and business environment in the nation may be poor.

The rationales of BRI are related to China’s own structural transformation, and are deeply rooted in its thousand-year history of Confucianism, who said, “One who wishes himself to be successful must also help others to be successful; one who wishes to develop himself must also help others to develop.”

First, China has proposed to enhance global connectivity by BRI in part because it has demonstrated comparative advantages in building infrastructure, including hydroelectric power stations, highways, ports, railways, and telecomm. China’s labour cost for project site foremen is one eighth of those in OECD countries. The vast domestic market and railway network allow China to realise “economy of scale” that other countries can’t have: the overall construction cost for high speech rail is only two thirds of those in industrial countries. Based on China’s own experience, building infrastructure sooner rather than later could facilitate international trade by lower transaction cost.5

Second, China has constructed many Industrial Parks and Special Economic Zones overseas, in part as it has successful experiences. In addition, China has comparative advantage in 46 out of 97 subsectors, mostly in manufacturing sectors, and is using them to help other developing countries achieve win-win. As labour cost rises in China, its labour-intensive industries are relocating to other lower-wage developing countries, providing millions of job opportunities. This is already happening in Southeast Asia and in East Africa as shown by examples of Huajian Shoemaking Company located in Eastern Industrial Zone of Ethiopia, C&H Garments in Rwanda and China JD Group, a giant apparel firm in Tanzania.6

Third, a new concept of “patient capital” can be utilised to finance the BRI and infrastructure gaps. Based on a culture of Confucianism, China and several East Asian economies are ranked high in “long term orientation” index.7  In our new joint paper we propose a concept of “patient capital” as those capitals to be invested in a “relationship” in which the stakeholder/investor is willing to take a stake in the host country’s development, aiming for a win-win.8 Owners of patient capital are equity-like investors but willing to “sink” money in the real sector or unlisted infrastructure projects for a long time – as long as 10 years and above. And they are willing and better able to take risks. In addition, we find that Net Foreign Asset is positively and significantly associated with Long Term Orientation index. On the other hand, countries with Short Term Orientation and low savings rates would see their Net Foreign Asset positions deteriorating and their foreign debt mounting.

China is a late comer – as it has just started to use its comparative advantage in patient capital to help releasing infrastructural bottlenecks to achieve win-win solutions. In terms of cross border M&A, China started to be a net suppliers in 2008. In terms of Net FDI (outflows minus inflows), China’s Outward Foreign Direct Investment (OFDI) in 2016, stood at $183 billion dollars, second only to the United States, had exceeded the inflows for two consecutive years (UNCTAC 2017). In addition, China also provides significant overseas lending through China EXIM Bank and China Development Bank. In recent years, each bank has been lending about $100 billion overseas.9

Patient capital plays an important role in infrastructure financing. Successful countries with future orientation (as in Spence 2008) have seen their infrastructure better financed. Other evidence of rising patient capital can be seen by the rising number of Sovereign Wealth Funds (SWFs) and government-sponsored “Strategic Investment Funds (SIFs)” established by countries like Kazakhstan, Malaysia, Mexico, Morocco, Nigeria, Philippines, Senegal, South Africa and Vietnam.10 The number of Multilateral Strategic Investment Funds (MSIFs), including those for infrastructure, are rising as well. This trend is in tune with our proposal of establishing a “Global Structural Transformation Fund” in our 2013 paper for the UN Post-2015 agenda.11 Using recent PrEQin data, it shows that “the median net internal rates of return (IRR) for private infrastructure funds across all vintages remains consistent at around 10%” (2015). The best performance can be seen in Temasek, Singapore’s SWF: By investing in Asian emerging market economies, its annual shareholder return reached a steller 15 percent since inception (Temasek Annual Review 2016). The point is that, if the patient capital can be invested in the bottleneck releasing infrastructure, the economic and financial returns could be higher than the “risk-free bond yield”.  

China is shifting from bilateralism to multilateralism showing its willingness to work with partners from the North and the South. The establishment of AIIB, New Development Bank and the Silk Road Fund, provide new momentum in the global development arena.

Currently China’s large amount of patient capital has been used at home. Along with the gradual opening of China’s capital account, more patient capital is going to be exported as more enterprises and banks “going global”. Patient capital often comes with technology, management skills and implementation capacity in infrastructure and manufacturing, the export of which will have strong impact on global connectivity and development. Using NFA as an imperfect measure, “China is likely to emerge in the next few years as the world’s largest net creditor”,12 and a proportion of these net foreign assets would be in fact patient capital, suitable for infrastructure, manufacturing and employment generation.

China is shifting from bilateralism to multilateralism showing its willingness to work with partners from the North and the South. The establishment of AIIB, New Development Bank and the Silk Road Fund, provide new momentum in the global development arena. China is trying to learn from partners to overcome its own constraints in governance, labour and environmental standards. And during the two-way learning process, new ideas, new theories and new concepts /definitions are going to emerge – our book being one of them. We are cautiously optimistic that a common ground can be found for partners from the North and the South to work together on multiple win approaches to achieve the goals of sustainable development by 2030.

Chinese President Xi Jinping declares opening of the Leaders’ Roundtable Summit at the Belt and Road Forum (BRF) Beijing, China, May 2017
© Xinhua/Ma Zhancheng

About the Authors 

Justin Yifu Lin is Director, Centre for New Structural Economics; Dean, Institute of South-South Cooperation and Development; and Honorary Dean, National School of Development at Peking University. He was the Senior Vice President and Chief Economist of the World Bank, 2008-2012. He is the author of 32 books including Going beyond Aid: Development Cooperation for Structural Transformation, the Quest for Prosperity: How Developing Economies Can Take Off, Demystifying the Chinese Economy, and New Structural Economics: A Framework for Rethinking Development and Policy. 

Dr. Yan Wang is Senior Visiting Research Fellow at the Centre for New Structural Economics, Peking University. She previously worked as Senior Economist and Team Leader in the World Bank for 20 years. She has received twice the SUN Yefang Award in Economics (the highest award in economics in China), and her major joint publications include Going beyond Aid: Development Cooperation for Structural Transformation (2017 by Cambridge University Press).

References

1. The Silk Road Economic Belt and the 21st-century Maritime Silk Road, also known as the Belt and Road Initiative (BRI), is an international development cooperation initiative proposed by Chinese President Xi Jinping that focuses on connectivity and cooperation amongst Eurasian countries with respect to the overland Silk Road Economic Belt and the Maritime Silk Road.
2. Lin, Justin Yifu and Yan Wang. (2017a). Going beyond Aid: Development Cooperation for Structural Transformation.  Cambridge University Press.
3. Lin, Justin Yifu. 2010. “New Structural Economics: A Framework for Rethinking Development.” Policy Research Working Paper 5197, World Bank, Washington, DC. and Lin, Justin Yifu. 2011. “New Structural Economics: A Framework for Rethinking Development.” World Bank Research Observer 26 (2): 193–221.
4. See Lin and Wang 2017a.
5. Hofstede 1990, 2010
6. Lin, Justin Yifu and Yan Wang. 2017b. “New Structural Economics: Patient Capital as a comparative advantage”, in Journal of Infrastructure, Policy and Development, Vol. 1, No.1.
7. Dollar, David. 2016. “China as a Global Investor”, Brookings Institution. https://www.brookings.edu/research/china-as-a-global-investor/
8. Halland, Havard, et al 2016. “Strategic Investment Funds: Opportunities and Challenges”, World Bank Policy Research Working Paper October 2016
9. Lin, J. Y., and Y. Wang. 2013. “Beyond the Marshall Plan: A Global Structural Transformation Fund.” paper for the United Nations Post-2015 High Level Panel on development agenda. May 22, 2013.
10. Dollar, 2016.

Grand Vision: China’s OBOR in Context

By Anoush Ehteshami

China celebrated the progress of its ambitious One Belt, One Road initiative in Beijing in May 2017. The OBOR is vast in scale, dwarfing the last major multilateral development initiative of our times, the US-led post-War Marshall Plan for the reconstruction of western Europe. It is also geographically vast, encompassing virtually all of Asia, much of Europe and Africa’s eastern regions. This Initiative has the potential to transform Eurasia and also major parts of Africa, so what it is about and what does it tell us about its architect?

Introduction

The BRI is vast, building six vast economic corridors – China-Mongolia-Russia, New Eurasian Land Bridge, China-Central and West Asia, China-Indo-China Peninsula, China-Pakistan and Bangladesh-China-India-Myanmar – across Eurasia and it is set to become the centrepiece of China’s development strategy, according to Vice-Premier Zhang Gaoli.1 Combined, these corridors will create an intricate network of 56 European and Asian countries working alongside each other, generating billions of dollars in investment capital and revenue, and creating employment opportunities across Asia and much of Europe and Africa. China today projects its influence westwards, in the context of the BRI, through investment, construction, extraction and commerce – through the exercise of soft power on a massive scale. The sum of $4 trillion allocated to the OBOR has the potential to be transformational in its impact. Inter-OBOR trade of over $2.2 trillion is anticipated. The OBOR is also the focus of China’s direct investment largesse, which provides the vehicle for the mobilisation of Chinese businesses in Asia. So, in 2015 44% of China’s engineering projects were in the OBOR countries, but the figure had jumped to over 52% in 2016.2 This will inevitably rise as projects across the Initiative’s frontiers get under way. That China has embarked upon it is a measure of the country’s self-confidence and a public expression of its efforts to become the heart of Asia – to become Asia’s “indispensable power”.

That China has embarked upon it is a measure of the country’s self-confidence and a public expression of its efforts to become the heart of Asia – to become Asia’s “indispensable power”.

So, the (BR) Initiative should not be taken lightly by outside observers; nor should it be viewed in isolation of China’s other strategic policies. These other policies take different forms and manifest themselves differently too. The OBOR (and the associated AIIB) forms the latest the ring of the circles in China’s strategic priorities in Asia, which combines cooperation with ASEAN as a strategic imperative, and the strengthening of the Shanghai Cooperation Organization as a security priority, as the other. Together, it seems to me, these spheres form China’s three circles of influence in Asia. These, in different but complementary ways, contribute to China’s efforts of building security and economic bonds across its neighbourhood. Using different mechanisms arguably enhances and accentuates China’s strategic reach as each of these circles has the material power to change and shape countries’ policies and regions well beyond their immediate areas of attention. Together they multiply China’s policy instruments and give it a credible voice across continents – from the Pacific to the Atlantic.

China’s New World Order

Viewed as a major foreign policy initiative, the articulation of BRI and the construction of it represents a concerted effort to build what the English School of international relations might see as the building of what could be termed an “international Asian society” based on shared norms and rules. What Hedley Bull, arguably the founder of the English School, might point to as illustration of “conscious of certain common interests and common values”.3 Indeed, the Chinese leadership’s statements regarding the BRI have come very close to invoking values long cherished by the liberal bend of international relations community: Elements of cosmopolitanism are discernible for example – in the ways through which the tendency of peoples in different countries embracing each other as fellow Asian citizens is being promoted,4 and also the unserved promotion of the market. So, in March 2015 President Xi strongly promoted the OBOR initiative at the Boao Forum for Asia and articulated a vision of harmony, mutual respect and cooperation consistent with what he said would be a new “common community” in Asia emerging in the wake of this initiative.5

Unlike the post-1945 American Marshall Plan for western Europe, the BRI has apparently been accepted unopposed by the marginal states, emerging powers, as well as the established giants of Asia.

A community of partners along the OBOR will emerge thanks to the network of relationships that the Initiative would give birth to. For the Chinese leadership, this will come to represent a “chorus of countries” working together along the route (in Bull’s terms, “share in the working of common institutions”6). This will not be, President Xi emphasised, a “solo of a single country”. Common community and common destiny will go hand-in-hand. The OBOR has envisaged the building of a concert of inter-state and inter-communal relations. This is a pre-emptive Marshall Plan unleashed on a massive continental scale, but unlike the post-1945 American Marshall Plan for western Europe (which the Soviet Union saw as a direct assault on its interests in Europe), the BRI has apparently been accepted unopposed by the marginal states, emerging powers, as well as the established giants of Asia. In presenting the Initiative as an expression of common destiny, moreover, the Chinese leaders have invoked the cognitive power of the Initiative, with proclaims common goals without invoking ideology or notions of superior values. The strategy is not about making Asia communist, nor about the imposition of China’s values, or the imposition of its (rich) civilisation on others. It is, rather, about practical inter-state engagement.


Further, China’s strategy westwards (Central, South and West Asia) should be viewed in the broader context of its complex position in the international system and a relationship which is shaped by the “continual tension in the dual-identity of China as a rising power and at the same time a developing country”.7 The notion of a rising/emerging global power – terms which have been used by Western leaders and international NGOs alike about China – impose on China certain expectations that it simply is not, yet, equipped to meet. The conditionalities which follow the assumptions regarding major power status imposed on China, moreover, are expectations which Beijing either does not intend to accept at all – seeing these as a straightjacket – or are simply beyond its abilities as a still-developing country to fulfil.8 Furthermore, it is a long leap of faith to assume that a dominant China in a post-American multipolar world order would necessarily act in the same way as its twentieth century Western predecessors did and develop a “vision” or “agenda” for global leadership – aim to reshape the world in its own image.9 China is keen to separate notions of great power status from assumptions about hegemony. Evidence, arguably, speaks to China seeking to become Asia’s “indispensable power”.10 Evidence also points to the reality that China’s rise is so conditioned by its dual-identity that it will continue to devote energy towards securing its position and interests at the subsystem level in Asia. Surrounding areas are China’s first priority. Working on the assumption that the BRI is a key element of Beijing’s grand strategy, embedded in its strategy of building an international Asian society, it is possible to argue that to legitimise Beijing’s drive westwards it has to articulate the idea of a “common destiny”. But this not only has to be associated with being the founder of the OBOR, but being welcomed, indeed desired, by the countries and communities which are to find themselves along China’s new “Silk Lanes” (on land, rail and sea).

China Dream 2.0

China must be seen as the embodiment of the Initiative, and for this to gain momentum it must create a set of principles and priorities which will drive the BRI. The first of these principles is surely historical legacy; that there are real historical parallels to draw on for the purpose of building the belt and roads and pipelines. In terms of observations regarding the Initiative’s strategic aims and planning, it is significant that China has “packaged” the proposed transport links in maritime, concrete and steel terms. These make an unprecedented transport strategy! The like of this Initiative has not been seen anywhere in the world and the scale of the operation surpasses the infrastructure that past European empires had built in parts of Asia, Africa and Latin America. The Initiative is not only multifaceted and multidimensional but is, in its approach, integrated and comprehensive.

Cognitively and materially China has opened up itself to Eurasia and has taken this risk in order to secure its own place, to change Asia’s economic dynamics in its own favour, to improve the socio-economic conditions of its western regions, to check other powers’ influence in its own backyard, and to tie into its own sphere of influence a whole host of resource-rich countries who can guarantee the necessary ingredients for China’s maturing economy for decades to come. The BRI then is not hegemonic but pragmatic. Further, the Initiative and the AIIA in this broader context, I venture, are not about China looking back, reliving an old “China dream”, but looking forward and creating the conditions for the fourth stage of what Kim has articulated as the three transformations of the “evolving Asian system”.11 The fourth phase which China has begun with the BRI has given Asia’s new regionalism centre stage.

A Word of Caution

But China and its BRI partners will need to be mindful of four potential complications. The first issue relates to the adverse effects of geopolitical tensions, which could destabilise the whole project while also keeping potential investors away. Secondly, can China afford to spend the estimated $1.0 trillion needed for the very many planned projects? The question is does it have the resilience and the conviction, as well as the reserves, to be able to continue to prioritise the BRI without prejudicing its other priorities? Thirdly, can Beijing continue to promote and “sell” the BRI if and when local resistance forces its partner governments to stay commitment-neutral or be pressed to renegotiate terms of projects? And finally, how will China manage the resistance being raised in India, the United States, Japan and other quarters against this ambitious and Asia-changing Initiative? Can it avoid alienating these powerful actors while pressing ahead with the wide-ranging and multiple-geography projects which can have a transformatory impact on so many Asian and African countries? Can China build a new Eurasia in its own image without appearing to be wiping out the images imprinted on so much of Asia and Europe by the United States? These are searching questions and not ones that the Chinese leadership are unfamiliar with, but Beijing’s response will only become clear once one of its fast-moving projects hits the buffers; only then will we know if this massive investment initiative was worth the price.

Chinese President Xi Jinping, waves with leaders attending the Belt and Road Forum May 2017 © AP Photo/Ng Han Guan

About the Author

Professor Anoush Ehteshami is Professor of International Relations in the School of Government and International Affairs, Durham University. He is also the Nasser al-Mohammad al-Sabah Chair in International Relations and Director of the HH Sheikh Nasser al-Mohammad al-Sabah Programme in International Relations, Regional Politics and Security. He is, further, Director of the Institute for Middle Eastern & Islamic Studies (IMEIS) at Durham, one of the oldest and noted centres of excellence in Middle Eastern studies in Europe.

References

1. He Yini. (2015). “China to Invest $900b in Belt and Road Initiative”, China Daily, 28 May.
2. Ibid.
3. Hedley Bull. (1977). The Anarchical Society: A Study of Order in World Politics (Basingstoke: Macmillan, 1977), p. 13.
4. Joseph Grieco, G. John Ikenberry and Michael Mastanduno. (2015). Introduction to International Relations: Enduring Questions and Contemporary Perspectives (New York, NY: Palgrave).
5. Boao Forum for Asia, 24 May 2016.
6. Bull, op. cit.
7. Suisheng Zhao, “Core Interests and Great Power Responsibilities: The Evolving Pattern of China’s Foreign Policy”, Xiaoming Huang and Robert G. Patman (eds) China and the International System: Becoming a World Power (New York, NY: Routledge, 2013), p. 53.
8. Jian Yang, “The Rise of China: Chinese Perspectives”’, in Kevin J. Cooney and Yoichiro Sato (eds) The Rise of China and International Security: America and Asia Respond (London: Routledge, 2009), pp. 13-37.
9. Chengxin Pan. (2012). Knowledge, Desire and Power in Global Politics: Western Representations of China’s Rise (Northampton, AM: Edward Elgar).
10. Suisheng Zhao. (2012). “China’s Foreign Policy as a Rising Power in the Early Twenty-First Century: The Struggle between Taoguangyanghui and Assertiveness”, in Hongyi Lai and Yiyi Lu (eds) China’s Soft Power and International Relations (New York, NY: Routledge), pp. 191-211.
11. Samuel S. Kim. (2014). “The Evolving Asian System: Three Transformations”, in David Shambaugh and Michael Yahuda (eds) International Relations of Asia (London: Rowman and Littlefield), pp. 33-58.

Green is Good: Revealing the Hidden Benefits of Sustainable Housing

By Trivess Moore, Ralph Horne, Yolande Strengers and Cecily Maller

Sustainable housing has wider environmental, social and wellbeing benefits which do not neatly fit into traditional economic considerations. Policy makers must adapt the way they develop minimum performance regulations if we are to move beyond the argument about capital costs and deliver a transition to low carbon housing.


Since the 1970s oil crises, energy efficiency has been on the agenda. Housing accounts for a sizeable chunk (10-25%) of greenhouse gas emissions in developed countries. Report after report suggests there is ample scope for cost-effective improvement through energy efficiency and renewable energy generation.

Yet, a commonly touted barrier to achieving these changes is the high cost of sustainable housing.1 Various vested interests claim that build and retrofit costs are high and savings are indeterminate. While the argument rages over cost-effectiveness, almost all sides seem to be missing the main game: There are a raft of other non-economic environmental, social and wellbeing benefits that make sustainable housing a more compelling and affordable policy response.

Housing accounts for a sizeable chunk (10-25%) of greenhouse gas emissions in developed countries. Report after report suggests there is ample scope for cost-effective improvement through energy efficiency and renewable energy generation.

In this article we discuss the arguments for and against increasing sustainability standards in housing performance, and point out the often unacknowledged benefits of sustainable housing through a mixed methods evaluation of a low-carbon housing development in Victoria, Australia.2 Our analysis makes the case for combining traditional Cost Benefit Analysis (CBA) with other social science methods to reveal the true costs and benefits of sustainable housing.


Beyond Minimum Standards

Minimum standards based regulations specify building elements such as insulation levels, energy labelling of appliances, and the general specifications of building design and materials. Generally, building energy performance regulations focus on improving the building “skin” or thermal envelope, to reduce the energy required for heating and cooling. These regulations have seen increasing sustainability requirements over the past decade or two, but current minimum requirements are still significantly below the performance required to deliver low/zero energy housing.3 They have also been heavily criticised for the assumptions they make about how occupants use energy in the house and for not including technologies such as energy generation.

There are increasing examples of low/zero energy housing developments around the world such as Park Dale (Wakefield, UK)4 and Lochiel Park (Adelaide, Australia).5  These developments are demonstrating what is possible for new builds or retrofitting of existing dwellings. Moving from one off examples to mass production of low energy housing continues to be a significant challenge. In countries like Australia, the majority of new housing (and retrofits) is delivered to minimum regulatory requirements. Therefore, improving these regulations is critical to delivering improved sustainability across the residential sector.

Research is increasingly demonstrating a range economic, social and environmental benefits associated with low energy housing.

Arguments for improving building regulations, and in turn sustainable housing outcomes, often come down to the claim of additional capital costs related to any additional “sustainability” requirements. Even in the face of increasing evidence that low energy housing does not necessarily cost more upfront, the perception that it does is holding back regulatory development in the face of housing affordability challenges around the world.

However, the argument that sustainable housing adds an unreasonable capital cost to housing fails to consider the through-life benefits that such housing provides. Research is increasingly demonstrating a range economic, social and environmental benefits associated with low energy housing. For example, households living in sustainable housing have lower (or eliminated) energy bills which help control living costs and reduce the risk of energy poverty – an increasingly important outcome in the context of rapid utility price increases occurring around the world.6 There is also increasing research highlighting improved health and wellbeing outcomes from low energy housing such as reduced stress from paying energy bills, reduced temperature related health issues, and improved mental wellbeing.7 These benefits have been found to be even greater for low-income or vulnerable households.8

The problem is that policy makers increasingly require hard monetised benefits in, say, health care savings, if sustainable housing beyond minimum standards are to be justified. Without a defined economic cost, and with contingent, long-term or flow-on effects, such benefits are not easily captured in traditional policy making evaluative tools such as CBA. As a result, policy analysis often wrongly concludes that zero carbon housing is unaffordable.

If these wider benefits can be properly considered the justification for zero carbon housing becomes clearer. Our three-year, mixed-method evaluation of a small sustainable housing development in regional Victoria, Australia demonstrates these benefits.

Low-Carbon Housing Case Study

Commissioned by Victorian Department of Health and Human Services (a state government department in the southern part of Australia), our study of low-carbon housing used both quantitative and qualitative methods to evaluate housing policy, environmental performance and occupant wellbeing.

The Department received funding to build four two-bedroom, nine-star-rated (under the Australian National House Energy Rating Scheme – predicted heating and cooling energy load of 25 MJ/m2/year for climate zone 27), houses were built to maximise passive solar principles; achieving a performance level similar to the German Passivhaus standard. The design elements and technologies used included (partial) reverse brick-veneer construction, double-glazed windows, solar hot water, a 1.5-kilowatt solar photovoltaic system and a shared 5,000-litre rainwater tank. The houses were built without air conditioning but did have ceiling fans and gas heating in the living area.

We evaluated these low-energy houses against seven control houses built to Department standards, with a six-star NatHERS rating (predicted heating and cooling energy load of 108 MJ/m2/year). We also compared the results to a technical model of standard industry practice. We conducted a traditional cost-benefit analysis, technical performance analysis (utility consumption, internal temperature), three rounds of interviews with the householders during different seasons, and a personalised household sustainability assessment.

Through a traditional CBA lens, the low-energy housing was not financially viable. Even if the Department could capture the savings to the householders, payback was only achieved within 40 years for one of the four dwellings in a high-energy-price future. This was due to higher-than-expected capital costs for the sustainability initiatives.

This meant they could buy children Christmas presents, avoid personal debt and lay-by, or go on a holiday. Householders described how this led to reduced stress and better mental health.

However, this analysis did not include broader benefits. For example, resale value could be up to A$40,000 higher per unit. The technical performance analysis also identified significant benefits for the low-energy households illustrated through the qualitative research. Interviews with residents highlighted positive social outcomes supporting the technical data. The benefits they described included improved health and personal finances. For example, these householders said they had extra spending money due to low (or no) utility bills. One occupant told us:

Look, I haven’t paid any off my power bill in six months and I’m still in credit.

This meant they could buy children Christmas presents, avoid personal debt and lay-by, or go on a holiday. Householders described how this led to reduced stress and better mental health.

I do go clothes shopping on occasion now instead of thinking,“Oh God, I have to go and lay-by that.”

We found that these low-energy households:

• were A$1,000 a year better off because of reduced utility consumption (including solar feed-in tariff);
• purchased 45% less electricity than the control households (and 73% less than the standard industry practice);
• consumed 22% less water (30% less than the industry standard);
• had 40% less CO₂ environmental impact from power use (63% less than the industry standard); and
• were comfortable with the indoor temperature of their house for 10% more of the time (even without air conditioning) using adaptive thermal comfort criteria.

Extreme weather events magnified the comfort and health benefits. On a second consecutive day above 41 degrees Celsius, the nine-star houses were up to 16.6 degrees Celsius cooler (without air conditioning) compared to the Department’s standard six-star house (which had air conditioning). This meant householders could stay at home during heatwaves rather than needing to seek alternative accommodation, which happened sometimes for the control households. One low-energy occupant said:

…in summer I would sit down at the supermarket, you know, because it was cool … [Now] I can stay home and veg out.

The research demonstrated that the housing sector’s over-reliance on cost-benefit analysis may be overlooking important benefits (and detriments) of different housing arrangements. Combining qualitative and quantitative evaluation methods can help uncover a more detailed and complete picture of how housing affects people’s lives.

Our research also highlights how sustainable housing benefits extend beyond the environment. These flow-on effects can improve the living conditions of some of the most vulnerable members of society. This, in turn, potentially reduces pressure on health and other support systems and sectors.


Combining Sustainable and Affordable Housing

Our study is part of an emerging body of research that challenges the idea that sustainable housing is unaffordable. The evidence increasingly shows that sustainability and good design can improve affordability when non-monetised social, health and well-being benefits are considered, and when understandings of “affordability” move beyond capital costs.

Policy makers should be “valuing” sustainable housing in more innovative and pioneering ways. This does not necessarily mean we need to find a way to put an exact economic value on non-economic benefits within existing cost-benefit frameworks. Rather, as our case study demonstrates, other methods can be combined with traditional CBA approaches to improve evaluations of sustainable housing developments.

There is still a role for CBA to help inform policy development. However it is clear that relying solely on this method is failing to capture the extent of the benefits of low-energy housing. Policy makers must adapt the way they develop minimum performance regulations if we are to move beyond the argument about capital costs and deliver a transition to low carbon housing.

This article is based upon an article published by the authors in The Conversation on the 25th August 2016 which is available via

About the Authors

Trivess Moore is a Research Fellow at RMIT University’s Sustainable Building Innovation Lab (SBiLab) in the School of Property, Construction and Project Management. He has a strong research interest in socio-technical transitions to a low carbon urban future, with a focus on sustainable and liveable housing.

Ralph Horne is Professor of Geography and is Deputy Pro-Vice Chancellor, Research and Innovation for the College of Design and Social Context at RMIT University, and Director of the Cities Programme, the urban arm of the United Nations Global Compact.

Yolande Strengers is a Senior Research Fellow at the Centre for Urban Research, RMIT University, where she co-leads the Beyond Behaviour Change research program. Her research is grounded in sociology and geography; it seeks to understand socio-technical change, and possibilities for intervening in everyday life to achieve sustainability outcomes.

Cecily Maller is Vice-Chancellor’s Senior Research Fellow at RMIT University’s Centre for Urban Research. She is co-leader of the Beyond Behaviour Change Research Program and a lead researcher for the Clean Air and Urban Landscapes Hub funded by the Australian Government.

References

1. http://dx.doi.org/10.1016/j.enbuild.2013.11.084
2.
3. http://dx.doi.org/10.1016/j.eist.2013.12.003
4
5. https://doi.org/10.1016/j.egypro.2014.12.372
6
7. https://doi.org/10.1016/j.socscimed.2015.02.005
8. http://dx.doi.org/10.1080/09613218.2016.1139906

US-China Ties in the Shadow of the Mueller Investigation

By Dan Steinbock                                        

In the foreseeable future, the Trump administration will be constrained by the special counsel’s Russia investigation. How will it impact the White House’s relations with China?

It was a strange month. First, the Department of Justice (DOJ) dismissed James Comey, Director of the Federal Bureau of Investigation (FBI), who the centre-right Democrats blame for Hillary Clinton’s 2016 electoral loss. In turn, the centre-left Sanders-supporters attribute the loss to Hillary Clinton’s gross abuse of public office and funds, Bill Clinton’s corrupt Global Initiative, collusion with the Democratic Leadership Committee (DLC) and mainstream media.

Barely a week later, the DOJ appointed Robert Mueller, former director of the FBI (2001-13), as special counsel overseeing the investigation into Russian interference in the 2016 elections. Meanwhile, Hillary Clinton claimed she was “right” about the “vast Russia conspiracy”.

Of course, there is little doubt about the ultimate outcome of the Mueller investigation. He served loyally under President George W. Bush and Vice President Dick Cheney. So from the Trump White House perspective, the end is pretty much known. It is the process that has potential to undermine his presidency.

But what will happen to Trump’s ties with China as White House begins its fight for political survival? The short answer is that those areas of the Trump agenda that require legislation (e.g., tax reforms) will remain more vulnerable to direct and indirect constraints associated with the Mueller investigation. In contrast, those areas of his agenda, which can be implemented mainly through executive action (e.g., trade policy), will be less exposed to such constraints. Finally, those areas of the agenda that are somewhere between executive and legislative action may prove easier to implement as well (e.g., sanctions).

Commercial ties with China

During the 2016 campaign, Trump threatened to use high import tariffs against nations that have a significant trade surplus with the US, particularly China ($347 billion), Japan ($69 billion), Germany ($65 billion), Mexico ($63 billion), and Canada ($11 billion). Nevertheless, trade pragmatism prevailed in the Mar-a-Lago meeting, where Trump and President Xi Jinping announced a 100-day plan to improve strained trade ties and boost cooperation between two nations. But if the plan cannot offer major breakthroughs after the summer, trade hawks may return and deficit rhetoric could escalate toward the year-end.

Right after his inauguration day, just as he had pledged, President Trump used executive order to pull out of the Trans-Pacific Partnership (TPP), President Obama’s legacy deal. In his campaign, Trump had promised to renegotiate key US free trade agreements, including the North American Free Trade Agreement (NAFTA). Indeed, as trade policy relies mainly on executive action, the administration may try to renegotiate deals rather than to reject them, if only to minimise the downside risk.

The positive spin has already been introduced. As US Trade Representative, Robert Lighthizer, puts it, the administration will not seek to “overturn” NAFTA trade but to “expand” it. NAFTA renegotiations are set to start soon. When the talks begin after mid-August, they will be followed closely by other bilateral trade agreements that will soon be on the table (South Korea, Japan, and Taiwan). Since negotiations are likely to endure through the fall, major trade friction that would undermine global growth prospects may not be likely until 2018.

The proposed tax reforms are a different story. Mueller’s investigation is likely to overshadow Trump efforts at tax overhaul, which relies on legislative consensus and the perceived strength of the Trump administration. Yet, legislative support will be challenging in the current conditions, and the administration’s staying power is now subject to both counsel’s investigation and political speculation.

Mueller’s investigation is likely to overshadow Trump efforts at tax overhaul, which relies on legislative consensus and the perceived strength of the Trump administration.

Moreover, even if the Trump plan could reduce US corporate rates significantly, that might not be adequate to “reshore” US companies’ overseas profits and corporate operations. There has been no major outflux of foreign firms from large emerging economies, which offer 3-4 times faster growth than the US or Europe.

Fiscal policy requires consensus among the Senate, House and Executive branch of the government, which are internally divided and externally under extensive scrutiny. In the long run, inadequate fiscal support could undermine Trump’s huge $1 trillion infrastructure initiative, affecting the dollar and import growth – and thus the Chinese renminbi, Chinese exports and investment.

Strategic ties with China

Recently, a US Navy destroyer sailed close to a disputed South China Sea island controlled by China. It was the first time under President Trump. Intriguingly, USS Dewey’s “freedom of navigation” (FON) operations were timed right after China and ASEAN agreed to draft a code of conduct in the South China, which has potential to reduce the risk of military clashes in one of the world’s busiest waterways.

As Trump hopes to launch a Reagan-style military rearmament program, some observers expect him to push assertive military measures around the world. However, they may ignore the fact that the “America First” program is focused on domestic priorities, as evidenced by Trump’s tougher stance against German trade surpluses and EU members’ “free riding” behind the US-funded NATO.

Since sanctions and other economic coercive measures fall under executive actions, Trump’s strategic maneuverability is less restricted in these areas. Then again, both Republican neoconservatives and Democratic liberal internationalists support sanctions against North Korea, and, with some qualifications, against Iran.

North Korea’s nuclear blackmail is strongly opposed by the White House and objectionable in Beijing as well. In the case of Russia, sanctions will prevail and possibly broaden. Trump’s reset efforts are likely to remain frozen through the special counsel’s investigation and more challenging to implement after that investigation. In the case of Iran, Trump is likely to push sanctions outside the nuclear deal as far as possible, which will be cheered by Iran’s hardliners who oppose the recently re-elected moderate President Hassan Rouhani.

Nevertheless, Trump’s hard stance is in line with his rearmament program and closer ties with the Gulf Cooperation Council, Israel and particularly Saudi Arabia with which he recently signed a huge $110 billion weapons deal.

The Pandora’s Box

As far as the White House is concerned, the Mueller investigation may well undermine Trump’s most ambitious strategic goal: the Russia reset. As he pledged in 2016, Trump has sought, publicly and privately, an anti-terrorism coalition with President Putin. At each stage of the talks, the mainstream media’s “Russiagate” narrative – allegations that Trump himself or his “associates” have been treasonously compromised by the Kremlin, and for which no actual evidence has yet been produced – “has intervened in ways that jeopardise, if not sabotage, the diplomatic process”, as veteran Russia expert Stephen F. Cohen has noted.

Seeking to revive his stalled policy agenda in Congress, Trump is developing his “war room” within the White House to combat leaks, disclosures and the investigation about his associates and Russia. That means the return of his toughest and most confrontational campaign aides, including former campaign manager Corey Lewandowski, deputy manager David N. Bossie and, of course, chief strategist Stephen K. Bannon, his rough radical-right champion.

If necessary, the war room could go offensive. Since the 1990s, Bossie has used the darkest Clinton controversies to battle both Bill and Hillary Clinton and, when warranted, could resort to the controversial “nuclear card,” which rests on the controversial Wikileaks disclosures and associated testimonies, to steer public spotlight toward the gross abuse of public funds by the Clintons, Democratic leadership, and the 2016 deaths of Democratic operatives who were hoping to testify against such abuses and corruption before their odd deaths (including Seth Rich, Shawn Lucas, John Ashe and Victor Thorn).

If necessary, the war room could go offensive.

Historically, the appointment of special counsel has often been accompanied by unintended consequences and collateral damage. The Mueller investigation is not likely to be an exception. When necessary, Trump’s war room will resort to offensive actions that will drag into the daylight the darker side of the Democratic leadership. As a result, America’s international clout, which has eroded almost two decades, may suffer new, more extensive, even irreparable harm.

Since the Mueller investigation is likely to slow down those parts of the Trump agenda that require legislative support, it may well steer the administration’s interest toward bold, executive actions. As long as the White House and Beijing can concentrate on cooperation, the constrained focus could take the bilateral ties on a new, broader level faster than anticipated. However, if cooperative benefits are seen as inadequate in the White House, Beijing or both, the result could be a challenging lose-lose scenario. Consequently, failure in US-Chinese talks is not an option.

The original commentary was released by China-US Focus on June 9, 2017.

About the Author

Dan Steinbock is the Founder of Difference Group and has served as Research Director of International Business at the India China and America Institute (US) and a Visiting Fellow at the Shanghai Institutes for International Studies (China) and the EU Centre (Singapore). For more, see http://www.differencegroup.net

Corporate Scandals – Cauldrons of Spilt Trust

By Douglas Bryson & Glyn Atwal

Trust is a big word. In this article, the authors elaborate on the elements and issues around corporate scandals, the breakage of trust, and how all these are anchored on brand identity.

It could be argued, if corporations were actually people, it’s the brand that is the soul of the organisation. It is more than just made up “marketing glue” which holds the organisation together – it helps to define the corporate “personality” and conveys symbolic and emotional connections with others. Norms of interpersonal behaviour are often applied as the relationship develops between individuals and brands. Individuals develop trust and loyalty with some brands, while remaining cautiously wary of others. Thus, everyone has their own circle of trusted brands. And obviously, not everyone will like or trust a brand, furthermore, sometimes that is not even a brand’s objective.

However, when it is the objective to have more than just a market transaction, and a brand relationship sours, there are occasionally extraordinary scandals. “Triggered” critics are quick to anger, stir the pot and heat up a cauldron of anti-brand sentiment. As sorcerers of yore, they point their elongated fingers at those “manipulative professional marketers” for duping the less judicious portion of the public as to the “real nature of corporations”, i.e. vehicles of mass exploitation, often for the profit of invisible shareholders and ultimately at the expense of Mr. or Ms. Anybody, or Mother Nature. There is an undertone of an “I told you so” factor, that brands should not be trusted or anthropomorphised. Brands that attract this damaging sort of attention are categorised as malevolent. Recovery can be a long and arduous venture for the brand, if redemption is possible at all.

Anti-brand sentiment is no longer an extreme, but it’s evolved into a mainstream phenomenon, facilitated by near instantaneous communication via the web and the widespread use of social media.

There exists a wide diversity of groups that have prepared well-rehearsed mantras of criticism that include environmentalist organisations targetting energy companies and all sorts of polluters and industrial scale exploiters of the natural world, there are anti-capitalists waging wars foremost against large corporations and private financial institutions, and anti-globalists taking on global brands such as Starbucks or McDonald’s or any firm that homogenises or reduces the cultural diversity within human societies.

Increasingly, anti-brand sentiment is no longer an extreme, but it’s evolved into a mainstream phenomenon, facilitated by near instantaneous communication via the web and the widespread use of social media. Brand failures and scandals progressively seem to be omnipresent. The string of recent and high-profile corporate scandals, including Rolls-Royce, Uber, Wells Fargo, Wargaming, Volkswagen and United Airlines are not country or industry specific. Each scandal has its very own dynamic, yet a worrying common factor is that stakeholders – customers, shareholders, and media amongst others – are willing to generously “punish” the company for what is widely deemed as irresponsible or anti-social behaviour. The companies that were loudest at verbalising their “human” side of their contributions to society are the companies that suffer from the most backlash. We see these examples as brands that have failed with fundamental breaches of trust. They have spilt this precious resource given to them by customers that were led to believe there was a social side to the company, but they saw, quickly and suddenly, that the mask dropped. Perceptions of companies that were thought to respect social norms of behaviour, were abruptly fractured when customers saw or even only heard of an event that placed maximised profits before people. The perceived social relationship is shattered and brands remain as vacant symbols of companies that are transaction driven, “cold hearted” and acting in the manner opposite to which it signalled to the public. Concurrently, social media has dramatically lowered the cost to the individual of seeking what used to be considered “irrational” revenge – irrational because it cost so much to get satisfaction. Interestingly, now it doesn’t even have to be the “wronged” party to set off revenge seeking behaviour designed to chastise the brand or cause it financial harm.

It is now so easy to get payback against a brand that misbehaves that following that so-called irrational path of human nature is easier than at any time in history. So the irrational seems much less so. It has in fact become a rational manner to control companies’ indiscretions. Behavioural economists explain revenge seeking behaviour as a socially adaptive phenomenon whereby probable severe punishment for violation of trust keeps potential perpetrators from breaking that trust. Thus social norms exist in interactions and keeping the trust leads to maintaining society in good order. We suggest that the threat of punishment of brands has swung more towards a degree of certainty in major cases, as a result of mobile telephone and social media technologies. Now revenge against a brand is conceivably minutes away from a breach of trust, a blunder or a mere act of human behaviour by a brand representative that has been interpreted as an intentional affront by a customer. Further, once the revenge seeking behaviour is started, other social media users reverberate and at times even amplify negative messages about the brand. The brand loses its costly “humanised” personality. The unpleasant face of a straight out money transaction replaces it.

#Boycottunited

This public reaction sent shockwaves through Wall Street that sensed that the scandal could lead to wider financial ramifications. Nearly $1 billion was temporarily wiped off the company’s market value.

A perfect example of this is the recent case of United Airlines. When a passenger was filmed being forcibly and violently (with blood) removed from an overbooked aircraft, the brand was almost immediately under intense, public scrutiny. Conversations about United quickly dominated social media and unsurprisingly, online commentary expressed very negative sentiments and a form of rapacious attack developed, sparked by collective outrage and a shared desire to punish the brand. #Boycottunited was just one of many hashtags which characterised the intensity of public outrage in this case. This public reaction sent shockwaves through Wall Street that sensed that the scandal could lead to wider financial ramifications. Nearly $1 billion was temporarily wiped off the company’s market value.

Disturbing video was first sent via social media within minutes of the incident by other passengers on the flight, igniting the media firestorm which continued in the public domain by popular network US talk show hosts, such as Jimmy Kimmel, who were quick to mock the airline. Even President Donald Trump was reported to have called the incident “horrible” in an interview with the Wall Street Journal. What had appeared to be a miserably handled, isolated incident had now attracted the attention of US policymakers. The United Airlines Chief Executive Officer Oscar Munoz was asked to attend a congressional hearing.

It was in effect a corporate crisis spun well beyond control; a domino effect exists that unexpectedly placed the company and its brand on the defensive and in financial peril. United Airlines had spent millions of dollars on a slick brand advertising campaign: “Fly the friendly skies”, and was now under the spotlight of a hostile public, viscerally revolted by what was perceived as a brand created by lying marketers spinning lies to hide the real company motive – maximising profit. Now many wonder, how can customers and potential customers “un-see” the video of a bloodied passenger being forced to debark the intentionally overbooked plane so that United employees in transit could have seats?

Some Internet users even posted new suggested slogans for United Airlines to replace their brand’s slogan with, for example “Deals that can’t be beat, passengers that can…” or “We put the hospital in hospitality.” These weren’t only typical long-standing anti-brand activists, but ordinary people who were using social media space to let off steam and make their views and opinions public. They also felt the betrayal of the promised social norms, such as being treated with dignity, by an economic decision that is trivial in the eyes of almost anybody witness to the event. One very public incident had an extensive impact on the trust people had had in the brand. The cauldron of trust boiled over with all of the heated criticism and spilt due to a hyper reactive market. No longer will people be flying “friendly skies” with United Airlines. Loyalty, trust and understanding have been replaced by a dollar amount for a specific service.

Internal Intangible Losses

“Experts” were quick to calculate the immediate economic cost for United Airlines, as is done with other companies that experience a fall in sales and decreased stock market value following a corporate crisis. However, this adjusted stock price fails to take into account many of the intangibles that impact corporate viability. Markets often do not behave as classical economists would like people to believe; at times their models fail to bear a resemblance to reality. The rise of the relatively new field of behavioural economics attempts to explain why people often fail to react in the manner long predicted by classical economics. Trust and reputational impact after brand failure of many high-profile brands can be felt for many years, or even prove fatal; it is just too difficult to know if trust can ever be regained, if customers can be convinced to remain or if trust is even needed. Guestimates are nonetheless attempted as many economists stick to their assumptions, dogmas and their calculus.

Nevertheless, for companies such as United Airlines, there are also the internal “human costs” that are likewise as significant as the diminished customer trust, loyalty and loss in reputation. Surprisingly, this is an omission in the business press commentary. We refer the “internal human cost” as to the loss of employee trust in, and commitment to the employing company. A public crisis might lead to a massive spiral downturn in employee morale and can leave employees angry, disoriented and demoralised. Employees at every level within the organisation can feel that senior management has let them down. For example, Volkswagen took the decision to cut 30,000 jobs in order to generate cost savings in light of the “Dieselgate” emissions scandal. It is no wonder that employees are left asking, “Why should we honest and hard-working employees pay the price for the blunders of our superiors?” Employee discontent and ultimately disenfranchisement can have an irreversible impact beyond lost productivity, but also affect key performance indicators such as innovation, loyalty, motivation to provide superior customer service, and turnover intention.

Fundamentally, customers and potential customers need to know who they are doing business with. Further, employees need to know as well. People need to know that the brand image will match the brand behaviour. Take the example of Ryanair, a low-cost airline based in Ireland. Customers are given close to no service at all. It is known to be a no frills airline; everything that can be charged as an extra, will be charged as an extra. This poses no long term problem because Europeans do not expect more from a Ryanair brand flight than an unassigned seat. Ryanair’s website focusses on cheap flights. Booking a ticket will reveal the minimum you will actually pay. You will be charged for any baggage excess and check-in agents are predictably not the sympathetic type. However, this does not harm the brand – it is just a brand of pure market transaction, not one with the social norms of trust and loyalty for superior and friendly service.

Beyond Textbook Solutions

Public relations experts often propose “off the shelf” advice on how to deal with the immediate fallout of corporate scandals, often providing minor tailoring to post-crisis campaigns in order to attempt to rebuild the reputation of the brand. We believe that very often these so-called “text-book” solutions are in fact far too superficial; as a marketing tactic, it is similar to using a “Band-Aid” for a broken limb, or searching for a limb that was never there. Yes, some campaigns might help to reposition the brand or at least change the conversation, but consumers are on their guard if relationships have been damaged. As with companies accused of “greenwashing”, consumers can easily detect a “Public Relations Redemption” campaign that arouses the impression of a company’s efforts at brand image salvation.

With hindsight, we have the luxury of suggesting that in the first instance executives need to take a few steps back and consider how to prevent scandals from starting. First of all, employees should be explicitly taught which social norms are being communicated and followed with customers in relation to that brand and to understand precisely what it means to break the trust if that is applicable. This understanding should guide their on-the-job behaviours. In some companies, this might involve a radical and fundamental shift in management mentality as well. There are decisions to be made regarding social norm driven relationships and brand personalities, and purely economic market driven perspectives where brands are just labels. This is simply a branding fundamental truth that is not always clear.

Failed leadership and communication about what the brand stands for provides a blind spot for employees. We suggest this is where most scandals have their roots.

It is fair to assert that no company of repute is immune from a damning corporate scandal, especially those that have chosen to build a friendly brand personality. These come with their hot cauldrons of trust, ready to spill and scald those involved in the scandal or worse. All executives need to be clear that there is a false belief that scandals are for other companies. This means that executives and managers need to closely examine internal communications within their own organisation. We suggest this is where most scandals have their roots. Failed leadership and communication about what the brand stands for provides a blind spot for employees.

We have identified three closely related questions that need to be addressed, devised following lessons from management theory and highlighted by recent corporate scandals. We believe providing top down leadership in these areas will dramatically reduce the risk of corporate blunders occurring, such as those that have plagued United Airlines, amongst others.

Do You Have the Right Corporate Culture?

Corporate culture is not a new idea. It refers to the instilled employee work related value system, which leads to appropriate decision-making and ultimately employee behaviour. Yet it is surprising how many top managers blindly ignore its importance. Strong corporate cultures are more reliable in determining the employees’ red line between what is deemed as being acceptable and ethical for internal and external stakeholders. For example, Samsung was under immense competitive pressure to counterattack the unshakable success of Apple’s iPhone. Did excessive time pressure cultivate a “work culture of negligence” which led to a premature market launch and recall of the now infamous exploding Galaxy Note 7? Then there are companies driven to extremes in search of growth. Volkswagen was resolute to become the world’s biggest car manufacturer and identified the US diesel vehicle market as a market growth opportunity. Executives were evaluated on meeting ambitious growth targets. Did this instil a culture of “growth at all costs” at Volkswagen that resulted into the diesel emission scandal? In a similar disposition, Wells Fargo’s incentive structure had put excessive value on bank retail employees meeting aggressive sales targets. Did a culture of “results at all costs” lead to the opening of two million fake bank and credit card accounts?

The Volkswagen emissions scandal started on 18 September 2015 when the US Environmental Protection Agency found that Volkswagen had intentionally programmed turbocharged direct injection (TDI) diesel engines to activate some emissions controls only during laboratory emissions testing. 

Executives certainly need to cultivate a strong corporate culture that considers long-term results, but a deeper examination of corporate values, their nature, focusses and priorities, might avoid the scalds that the company suffers when employees misstep due to unreasonable, poorly prioritised or conflicting values as signalled by managers. This failure results into employees bumbling, acting irresponsibly and damaging the brand. Executives need to explicitly question whether goals regarding relationships with society and customers, methods and results are not driven by short-term objectives. Brands that survive have the most potential to add value, and the corporate culture needs to be clear and sustainable. Obviously, this is an issue that must be negotiated with other stakeholders, particularly investors who may exert pressure for companies to deliver immediate returns. Employees need to know what the overall long-term values of the company are, and this means CEOs need to ensure the appropriate corporate culture is encouraged at all levels of the organisation.

Do You Have Managers or Leaders, or Both?

This is also very much tied in with the corporate culture in that the answer sets the tone of communication throughout the organisation. Strong leadership is undoubtedly essential for an organisation’s success. However, this is too often misinterpreted as a top-down chain of command in which open communication across management hierarchies, ideas, dissent and grievances are uncommon or even absent. We and many others argue that effective leadership in a hierarchy requires a different set of behaviours. Employees look for guidance on desired behaviours and shared values from superiors. This basic idea, that leadership is more than management, and includes communication by setting the appropriate examples for values and behaviours is indeed taught in business schools, but despite this, all too often it is punished in actual practice. Ingrained corporate hierarchies often stifle natural leadership growth and ignore the important roles of coaching and mentoring.

Leaders need not only to embody the values of the organisation, but seek to communicate, and seek to receive different perspectives within a climate of mutual respect.

Clearly, leaders have to do more than merely meet financial objectives. Managers can do that. Leaders need not only to embody the values of the organisation, but seek to communicate, and seek to receive different perspectives within a climate of mutual respect. A leadership style that remains “open”, i.e. one that rejects the discussion stopping statement “I know”, as opposed to “closed”, will ensure that issues are not only openly communicated but improve the level and quality of overall decision-making. Well, this is how the theory goes and it is largely based on relatively flexible military, hierarchical organisations dating from World War II.

Obviously, executives need a more sophisticated palate that has been developed since the 1940s which also considers backgrounds such as national context(s), industrial context, organisational role, size, employees’ skill sets, teamwork requirements, and numerous other variables specific to the leader’s purview. However, after a detailed analysis of each case has been made, we suggest the question is posed: “Do you have managers or leaders, or both?”

Do You Have Effective Checks and Balances?

In order to avoid crises, solid corporate governance is needed. This requires a range of “hardwired” checks and balances to order to be effective. For example, US and UK companies rely on a single board of directors to hold management to account. This in theory should ensure oversight of corporate social responsibility and compliance to an ethics charter. However, all of this can only be possible if the board of directors has the authority to enforce oversight activities, which also implies that boards should not become too lackadaisical in their role or too trusting of incumbent top management. Corporate “cosiness” has often been one reason cited when directors have failed to act on potential or actual wrongdoings. A greater emphasis on the diversity and an increase in the number of independent directors can also act as a safeguard and help to ensure scrutiny is sufficient and items requiring action will seriously be dealt with.

Employees need to be empowered to report wrongdoings in a way that will never hamper their career development.

However, good governance needs to be integral to all organisational policies and procedures. Although legal complexities continue to muddle the legal status of “whistle-blowers”, corporations need to recognise that these individuals are an asset to staying on the safe end of critical issues. Since they are on the front-line, best placed to find problems, they should be safe in their jobs to “red flag” potential or actual illegal or unethical activities, which if not caught early, might boil over with time. As cliché as it sounds, employees need more than encouragement. They need to be empowered to report wrongdoings in a way that will never hamper their career development. If ever an employee is harmed when trying to help maintain legal or ethical compliance, it goes without saying that all future transactions will not be based on societal norms, such as trust and loyalty, but they become economic transactions where any really dangerous legal or ethical violations are somehow “not noticed”. Ask yourself “what price you would charge your employer to be held back in your career, passed over for promotions and raises, or even let go for no apparent reason?” Clearly, that price will never be paid – who would ask for it? – thus, the function of whistle-blower would never be fulfilled.

Corporations with a positive whistle-blower policy are also likely to value and exhibit a more “openly communicative” corporate culture. Suppression of whistle-blower behaviour can only send mixed messages, or worse, about company legal and ethical compliance. For example, the Chief Executive Officer Jes Staley of Barclays has faced immense pressure over his attempts to go against company policy and unmask a “whistle-blower” at the bank. Ultimately, the whistle-blower remains safely protected, while Staley has been investigated and reprimanded by the bank. CEOs do not walk on water in serious companies with healthy corporate cultures.

Staying Cool and Keeping the Trust

While every “known” company or brand is increasingly susceptible to a rapidly developing scandal, we argue that if organisations are equipped with the right set of values framed in a strong corporate culture, led and managed appropriately for the organisational context, they are more likely to be able to prevent scandals through the very act of being transparent and behaving as they suggest they will. The value congruence of the corporate brand’s personality, with the organisational culture and actual actions, are keys in keeping the cauldron of trust cool, avoiding crises, scandals and scalds. To act otherwise rapidly opens the door to communication failures within and outside of the company. When people don’t know how to interact with a brand, they will at the very least likely avoid it.

Featured Image: CEO Oscar Munoz testifies before the House Transportation and Infrastructure Committee about oversight of US airline customer service. Photo Coutesy: http://www.cnbc.com

About the Authors
Douglas Bryson is Professor (Titulaire 1) at Rennes School Business, France. His expertise focusses on Research Methods & Data Analysis, Consumer Behaviour and International Brand Management. Prior to switching to academia, Douglas worked for the Department of National Defense, Maritime Command, in Canada.


Glyn Atwal is Associate Professor of Marketing at Burgundy School of Business, an international Graduate School of the French network of Grandes Ecoles. His teaching, research, and consultancy expertise focusses on Brand Management. Prior to academia, Glyn worked for Saatchi & Saatchi, Young & Rubicam, and Publicis.

EDITOR'S PICK OF THE WEEK

China economic growth

China’s Challenging Search for a New Model of Economic Growth

By Danny Leipziger China cannot continue to rely on exports to drive its growth, but what are the alternatives? China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...

WISE DECISION MAKER GUIDE

POWER INFLUENCERS

Emerging Trends

The Future of Global Trade