Home Blog Page 1032

How To Save Money Sending Your Child To A Top-Tier University

The quality of university that your child attends can make all the difference when they start looking for a high-powered, high-earning role.

Sending your offspring to an elite university can be costly, but by being savvy and choosing wisely you can find ways to save yourself some of your hard-earned cash.

In this article we share some of our top tips on how to make university cheaper for you and your child, whilst still ensuring that they enjoy the best possible experience.


Start Their Savings Account Early

Parents should set up a fund for their child’s education as soon as they’re born, if possible. It should be placed in a high-interest savings account, or an ISA, so that it can earn as much interest as possible. If your child is already older and you haven’t established a nest egg for their education, then don’t worry; invest in bonds and stocks to grow your money quickly and create wealth that they can spend on their education. You can take the six financial steps to make sure you are better prepared for your children’s education fund.


Find Accommodation With All Inclusive Facilities

Where your child lives during their university years is an important part of their educational experience. To ensure that your child makes the most of their time at university and networks with all the best people, you should search for accommodation that has social spaces and facilities included in the accommodation fees. Properties provided by premier student accommodation provider Collegiate have a range of amenities like private cinemas, gyms and dinner party rooms, so you can rest assured your child is mingling with the crème de la crème of university society in a high-end space.


Review The Fees

Tuition fees and the cost of living are the two biggest expenses for any university student, so the first thing you should do is learn more about the fees charged by each of the world’s top universities. You should also explore the bursaries, grants and low-interest loans available to students to see if there is any way to reduce these costs. By knowing what the costs are ahead of time you’ll be able to plan long before your child even applies for university.


Give Them An Allowance And Stick To It

Students often struggle to budget when they’re at university, particularly if this is their first taste of freedom. Even if you have a lot of money to lavish on your child, you should give them a set allowance every month or quarter to give them the chance to practice managing their money effectively, and to teach them the real-world value of currency. Sit down with them before they attend university and devise an allowance that will give them the chance to enjoy their lives whilst learning to budget and use their money wisely.

The university experience is about much more than just the education your child receives; it’s also about the chances they have to network and connect with some of the world’s future leaders, thinkers and pioneers. By following these tips, you can help your child to attend an elite school and save some money for their future.

The Madrid Climate Disaster

By Peter Koenig

Does anyone know what COP25 stands for? Probably very few. Its unimportant. As unimportant as the whole roadshow itself. Just for the hell of it, for those who read this article, COP means Conference of the Parties (COP) to the United Nations Framework Convention on Climate Change (UNFCCC). The 25 stands for the 25th year that such annual conferences have taken place – every year in another country – what a tourist bonanza for the hundreds, if not thousands of attendees and participants who travel – by air – many of them business class, to these most questionable, even useless conferences.

The first of the COP summits took place in Berlin, Germany, in March 1995. The COP’s Presidency rotates among the 5 UN recognized regions and so do the conferences – to make “eco-tourism” most of the time for the same UN and government bureaucrats and jokers more attractive. I can’t help thinking of the enormous cost of these conferences – travel, food, lodging and everything in between – for two weeks – in the case of COP25 Madrid (2-16 December 2019), two days more than planned, because after the scheduled two weeks no agreements were reached, so it was decided to add two days. Add to this all the preparatory meetings and related travels – tens of millions of dollars, possibly more, are spent for nothing, absolutely zilch, nada. That’s the officially recognized outcome at the end of the extended COP25 in Madrid – nothing.

There are UN staff, directors mostly, at the UN in Geneva and in New York, who earn huge salaries in the hundreds of thousands a year, for doing what? Some of them are directing their staff to preparing the extravagant but mostly useless COPs – and of course, they are also attending them. When I see monetary figures like this, and we are now talking of only one kind of UN conferences, it occurs to me that this is money stolen from the poor. It is taken from the very people whom the UN is committed by its Charter to help. – How many simple drinking water supply and sanitation systems could you build with all this money? How many millions of people could you serve with the money wasted for such conferences with safe drinking water and safe sanitation?

According to the WHO-UNICEF Joint Monitoring Program (JMP), some 2.1 billion people have no safe drinking water at home and more than twice this number lacks safe sanitation. At the same time, these agencies also monitor the death toll among less than 5-year-old children from unsafe water and sanitation, from the lack of hygiene, from diarrheal diseases – nearly 400,000 die per year. In addition, contaminated water and poor sanitation also contribute to the transmission of cholera, dysentery, hepatitis A and typhoid. This does not even take into account those who die due to a famine-reduced immune system.

Precious money deviated from the UN system by men-invented rather unproductive, but usually lush conferences – of which the COPs are just one category – could save millions of lives.

This is a real environmental issue, in fact more vital than just environment, it is environmental health. It is certainly competing in importance with the man-made CO2 issue. Climate change is happening, no doubt, it always did for the 4.5 billion years of Mother Earth’s existence. But the way the west is dealing with it is a sheer farce; no, it’s actually worse, much worse, it’s criminal, because it’s knowingly made into a commercial globalized profit-making enterprise. Knowingly, because the elite that pulls the strings behind these events – the same who finance Greta Thunberg – are well aware of what they are doing and why they are doing what they are doing. It helps none, but global corporate finance. Those who suffer most are the people living in the Global South which is, as with most natural disasters, most affected by naturally occurring climate change.

It’s still worse, because the western propaganda message promises actions towards saving the world from climate change which are entirely deceptive. So, the poor are again being lied to. They are being lured into making huge investments with huge loans – the World Bank, IMF and bilateral lending institutions, let alone Wall Street, stand ready – loans and interest which the borrowing countries have to repay. If they can’t, they have to give their collateral, meaning, let the west privatize their public services and assets, and grab their natural resources for a pittance. That’s how it works – the west preventing climate change from happening.

Not to mention the enormous arrogance with which the eminent COP attendees pretend humans can control Mother Earth’s temperature fluctuations, i.e. to less than 2 degrees C. Or arguing, whether “we” (almighty humans) should agree on limiting a temperature rise in the next 30 or 50 or 100 years to 2 or 3 degrees C, exceeds any reasonable level of human absurdity and conceit. Our assumed power over nature is at best ridiculous.

The Intergovernmental Panel on Climate Change (IPCC) is the United Nations body for assessing the science related to climate change. IPCC has 195 members and some 2000 scientists who contribute to IPCC’s work. Any serious scientist knows that the main cause for climate change are variations of solar activities, but they sell us CO2 as chief villain, knowing well, that the world, especially the western world, functioning under a turbo-neoliberal corporate and finance driven capitalist system, based on ‘eternal’ consumption and eternal growth – which drives the ever-growing profit margins – will not change its behavior vis-à-vis nature, unless it collapses under its own weight. Not with a million COPs it will change its profit-making thinking and business motives. – These mostly famous scientists know it. If they don’t follow the line, they risk losing their reputation and, who knows, their jobs?

Ice core records studied by scientists, combined with many types of proxy records to reconstruct past atmospheres and environmental conditions, back from thousands to many millions of years, suggest that climate changes in large cycles, and within them, in smaller cycles. For example, it appears that between 2.6 and 5.3 million years ago, during the Pliocene Epoch, CO2 levels were comparable to those of today. Models suggest global temperatures were 3 to 4 degrees C warmer than pre-industrial levels (https://www.co2.earth/historical-co2-datasets).

Similar patterns were repeated 400,000 to 600,000 years ago. What is important to notice though, is that temperatures rise first, followed by CO2 levels which is logical, since the sun is heating the earth. It is the complete opposite to what today’s climate gurus are telling us. In the second half of the 1900s, NASA studied during some 30 years temperature fluctuations in the Pacific Ocean, investigating causes and effects of El Niño. The result was similar; the higher the water temperature of the Pacific, the more CO2 was released by the sea into the atmosphere. High CO2 levels are eventually followed by lower temperatures (https://www.globalresearch.ca/%e2%80%a8climate-and-the-little-green-women-and-men/5691215 and https://earthobservatory.nasa.gov/features/OceanCarbon). 

The world still runs mainly on unrenewable energy, mostly hydrocarbons, oil, gas and even coal – the chief producers of CO2. Of course, we should stop using hydrocarbons and convert our economic systems to renewable energies. Hydrocarbons with their carbon dioxide output pollute the air, soil, surface and underground water ways. They contaminate even our food. Their secondary and tertiary products, plastic bottles and plastic-related packing materials, most of which are not biodegradable and contaminate our oceans, our landscapes, and kill wildlife.

The world still runs mainly on unrenewable energy, mostly hydrocarbons, oil, gas and even coal – the chief producers of CO2.

But who convinces the highly profitable petrol titans, packaging giants – not to mention the pharma industry which also thrives on petrochemicals – to turn the wheel back to the 1950’s and 1960s, when we went to the corner stores to buy our staple food, like rice, sugar, flour, potatoes in bulk, put it in used and reusable paper bags. We were not unhappier than we are today. To the contrary. Cancer rates were considerably lower. In 1960, CO2 levels in the atmosphere stood on average at 316 ppm. We had no cell phones. Time moved slower. And – importantly – in the fifties and sixties we lived even in the west in a world more or less in balance; we used less than the total of the resources Mother Earth generously provides for us.

In the mid-sixties, during the post-WWII economic boom, we started rapidly exceeding the world’s resources balance. Today, the west, or Global North, uses some 4 times as many resources as Mother Earth can provide. In Africa and some parts of Asia that ratio is between 0.5 and 0.6. – But no worries, there comes a point when Mother Earth will self-regenerate, that means with a break from us, destructive humans. Looking at geo-history – that has most likely happened already a few times: Civilizations disappeared – often “suicide by greed” – and once Mother Earth has recovered, she may give mankind another chance. She has a lot of patience.

In 2009, at the time of the (in)famous Copenhagen Climate Conference, the average level of CO2 in the air was 386 ppm. The goal was to reduce the level to 350 ppm ten years later. The Copenhagen Climate Conference coined the “350-sologan”. In November 2019, the carbon dioxide level has exceeded 410 ppm – and rising. It is an illusion to believe that Big Business, Big Industry, Big Finance – and Big Growth-driven Profit – will yield to environmental or climate concerns.

And again, those who call the shots know it, but they keep fooling the world, making the purposefully brainwashed and poorly informed populace believe that special taxes, for example on flying, or other taxes on hydrocarbon-based energy, will make a difference; or that “carbon credits” will improve the environment. This is of course nonsense. And the taxes eventually end up in the pockets of the usual villain, the globalized private banking system, instead of being dedicated to intense research into alternative energies. Such efforts happen only in China and Russia.

In the west, intense research into solar energy, the ultimate renewable energy, is not allowed to happen. The big energy lobbies, hydrocarbon, nuclear, and even hydropower, will block any such attempt. Can you imagine, the sun provides the earth with more than 10,000 times as much energy per day than what we use in the entire world in the same period.

Carbon credits are the most ludicrous deceitful banking invention of the last 50 years. How do they work? – A huge corporation in the Global North, instead of making the necessary investments to reduce their CO2 output, it buys “carbon credits” from a country in the Global South, where the pollution level is below a certain limit, so the northern corporation may continue postponing the CO2-reducing investments, and the country in the global south should theoretically invest the money it got from the “carbon credit” sale into alternative energy or otherwise environmentally friendly projects. It hardly ever happens. Many of these countries lack the projects and / or the absorptive capacity for the required investments. And even when it does happen, the carbon dioxide pollution of the monster corporation in the north continues. What a farce!

Maybe one day, in the not too distant future, the breakthrough will happen. It must, if we, mankind, want to survive and not collapse as civilization under the weight of our own wasteful, growth-based luxury lifestyle. We suddenly see the light – the sunlight – and use it, instead of CO2 generating hydrocarbon – and we free ourselves from this horrendous petro-corporate dependency. Our arrogant climate control attitude, temperature-rise fixing and human-manipulating by centigrade – gone – out of the window. Our linear 30, 50- and 100-year projections gone. Finito. What a feeling! – A feeling of real freedom. A full change-over of lifestyle. This moment may come faster than we think. The Chinese, always bashed by the west, have been concentrating at least the last decade much of their research on efficient and sustainable renewable energy – sun energy is in their focus. The East is the future. The East is where the sun rises.

About the Author

Peter KoenigPeter Koenig is an economist and geopolitical analyst. He is also a water resources and environmental specialist. He worked for over 30 years with the World Bank and the World Health Organization around the world in the fields of environment and water. He lectures at universities in the US, Europe and South America. He writes regularly for Global Research; ICH; RT; Sputnik; PressTV; The 21st Century; Greanville Post; Defend Democracy Press, TeleSUR; The Saker Blog, the New Eastern Outlook (NEO); and other internet sites. He is the author of Implosion – An Economic Thriller about War, Environmental Destruction and Corporate Greed – fiction based on facts and on 30 years of World Bank experience around the globe. He is also a co-author of The World Order and Revolution! – Essays from the Resistance. Peter Koenig is a Research Associate of the Centre for Research on Globalization.

First published by the New Eastern Outlook – NEO

Things You Need to Get in Check Before Taking Up a Loan

There’s a popular saying that no one is self-sufficient in life, and this also applies to the financial world. In other words, there comes a point where you need money to fund a particular need, but you currently don’t have it or it is inaccessible at that particular moment. It could be an investment need, perhaps you want to purchase a car, or maybe you need to buy a home. You may also have a self-improvement need or a matter of urgency that requires the money quick ASAP. The list of reasons for borrowing are literally endless.

One thing we can all agree on is that in such a scenario, borrowing becomes an automatic option to fund your needs. This is a phenomenon that has been with us since time immemorial, and its part of what keeps banks and other lending institutions in business. But while taking a loan will always seem the most convenient alternative when you’re short on funds, it doesn’t necessarily mean that it’s always the best. True, many individuals and giant business organizations have managed to achieve huge accomplishments with the help of loans, but one thing is for sure… borrowed money will work best for you if you understand the ins and outs of lending.

On this note, let’s look at a few things you need to get in check before taking up a loan.


Justify your reason for borrowing

As earlier mentioned, there are numerous reasons why people approach lenders for a loan. But before you make that application, it’s important to ask yourself whether you really need the money or not. This is because, amid the many uncertainties in life, a loan can either help you or ruin your financial health. Also, some loans carry more risk than others. A mortgage loan, for instance, is better in many ways compared to a personal loan taken up to cater to ordinary expenses. Ensure that you really need to borrow before you do so.


Your credit score

Most if not all banks and other lenders will always scrutinize your credit history before approving you or even considering you for a loan. Remember, they’re in business to make a profit, and the slightest negative element they note on your credit history could cause them to doubt or question your ability to pay their money back. Before you borrow, therefore, you’ll want to ensure you have a credit history and that your credit score is at least in the “good” range, which is about 700 or above in the US. And loans aside, the guys at Money Expert say that your credit score is affected even your insurance installments, credit card repayments, and monthly installments when leasing a car can all affect your credit, either positively or negatively. Before getting a loan, it’s best to ensure all your monthly bills are cleared and up-to-date if you can. A good credit score can fetch you better deals in the world of lending, including fairer repayment plans and lower interests. For this reason, you’ll want to ensure your credit report has no negative listings that could put your creditworthiness in a bad light.


Your income and loan costs

Borrowing is always easier than paying back, especially since loan repayments often have interests and penalties attached to them. While getting a loan could seem like the only choice you have to fund emergencies after you’re out of a job or a big business deal, it’s best to take up a loan that you’re sure you can afford to repay within the time frame agreed upon. Late payments and defaults are among the major reasons loans become burdensome, not forgetting the damage they can do with your creditworthiness.


Your identity documents

No lender will approve you for a loan without standard identity documents that have been certified. Depending on the type of loan you wish to apply for and where, some of these could include social security, national ID, a valid passport, property documents, PIN certificates, and so forth. Be sure to contact the lender you wish to apply for your loan from to get a list of required documents before making your application.


Collateral (do you need it?)

Secured loans often require you to provide collateral, which is usually an asset that the lender could claim a lien on, in the event you’re unable to repay their money owed. A collateral could be an asset, such as real estate property, household equipment, company assets, your car, and other property owned under your name. But before you go ahead and sign on the dotted lines, is the loan worth risking your property on?

If well managed, a loan can get you out of a miserable situation. It can help you grow personally or business-wise. However, the opposite is also true if you don’t consider your options carefully. All the same, the above are just a few things to get in check before taking up a loan.

Six Steps To Set Up An Online Business

The number of online businesses is at an all-time high, and the trend is showing no signs of slowing down. If you’re here, the chances are that you already have a fantastic idea for an online business. However, bringing an idea to fruition and actually establishing an online business is an intense journey. Despite the route, with careful planning, the process is much easier than it seems.

If starting an online business is the route for you, keep reading on to know how you can do that.

Here are six steps to starting your very own online business:

Start With A Business Idea

While you may have an excellent business idea in mind, it’s vital to confirm it with market research. For starters, you can employ a consultancy that can do the research for you and potentially connect you with the target audience you’re planning on catering to. 

If you’re sure about your target audience, you should go through forums to determine what people are discussing, or you can generate a survey on feedback platforms, like Helpfull, and get thousands of suggestions. These discussions can lead you in the right direction by helping you refine your business idea and can even provide you feedback if you decide to post your business idea.

In the case where your business idea isn’t fully developed yet, you should consider products and services in the niche you’re interested in and try to figure out how you could improve these existing offerings.

Decide On A Business Name & Secure The Domain

Choosing a name for your online business is not an easy feat. There are multiple things you should consider. For instance, you might be able to generate more interest if your name incorporates trending keywords in your niche. 

Once you have a few potential business names in mind, you should run this list through a database to confirm whether the name is already taken or not. You should conduct a similar search on social media, too.

When your business name is finalized, you should secure the domain name by purchasing it before anyone else does. Even if there are a few months left into the official launch of your business, knowing that nobody else can get their hands on it will give you peace of mind.

The most obvious choice for a domain name is to use your brand name. However, if this is not available, then you add a hyphen or use a domain extension such as .me or .net.

Determine Your Revenue Model & Create A Business Plan

Your revenue model is one of the crucial aspects of your online business. It would help if you determined how you’ll be generating money, whether it’s by selling products and services or through affiliate marketing. Additionally, you may also require investors.

The revenue model is dependent on the kind of website you’re intending on setting up and the type of collaborations you’re aiming at making. If you’re planning on targeting investors, then creating a business plan will help consolidate the main aspects of your business. In fact, even if you’re not targeting investors, a business plan will help direct your focus to what’s essential.

If you’re struggling to draft a business plan yourself, you can always hire a business plan consultant who can help organize your approach and direct your focus to your primary goals.

Build Your Website

Your website is at the very core of your online business. First, you need to determine the web hosting you will opt for. The web hosting you choose, which includes shared hosting, cloud hosting, dedicated servers, and virtual private servers, is determined by the server space you require, the level of privacy you desire, and the speed you need from your website.

When you’re building your website, you need to ensure the aesthetics match the overall look and feel of your website. The easiest way to build a website is by using WordPress, which allows you to experiment with multiple paid and free templates, ensuring you’re bound to find something that fits best.

Prepare Your Offering

Once the foundation is up and running, it’s time to actually bring your offerings into play. If you’re selling physical products, you need to ensure the products are ready to be shipped when you start getting orders. On the other hand, if you’re offering a service, such as a SaaS software, then the product needs to be ready at this stage. Conduct user tests to ensure that customers can use the product easily.

Execute Your Marketing Strategy

Before you launch your business, the world needs to know about it. Every business’s marketing strategy varies, and what works for one company won’t necessarily work for another. Since you’re starting an online business, you need to focus on different marketing channels, such as social media marketing, content marketing, and paid ads.

If online marketing seems like a daunting task, there are many online business marketing strategies that you can focus on to get a headstart. These strategies will help you gain traction and generate buzz for your online business.

One of the best ways to attract attention to your business is through email marketing. By finding prospects’ email addresses, you can directly reach out to your target audience and garner their attention before the official launch.

Conclusion

The day your online business officially launches should be filled with different activities, such as PR interviews and social media announcements. What happens after launch day depends on your effort and how you can adapt to what your new business throws your way.

Running a successful online business isn’t easy, and it’s essential to be ready for the challenges. However, once you take steps in the right direction, you’ll start seeing great rewards in no time.

Do you have an online business of your own? What steps do you think are necessary? Let us know in the comments below!

What To to Expect When You Have a Medical and Health Insurance

Having health insurance is like a safety net; even when things surprise you and go for the worse, you will still have peace of mind that the insurance will have you and your family’s back. Financial problems should be the least of your troubles when you are faced with health issues, that’s why your health insurance comes to the rescue to put your mind at ease.


What is Health Insurance?

Health insurance is what will help you in paying for your health care whenever you need medical attention. Insurance plans cover specific fields that can vary from routine checkups and doctor visits to major medical crises and treating serious illness or injuries. There are different plans that you can choose from. These plans distinguish between what the insurance will cover and what you will have to pay for yourself. Most plans don’t cover cosmetic procedures and other unnecessary surgeries that you can live without. However, some plans will cover you in case you need to seek medical attention for anything that’s bothering you.


Medicare Advantage Plans

These plans are a type of Medicare health plan that is provided by other companies that sort of work with and are approved by Medicare to provide different benefits for people to suit their needs. Specialized agents have managed to gather all types of information you might need about the Medicare advantage plan. The medical specialists over at www.MedicareWire.com makes sure that you are fully aware of everything you are buying. Every insurer has its own plan with its corresponding costs and the amount that the plan covers. You will find different coverage percentages with different prices for you to be able to choose the one plan that will suit your needs. With these plans, you can rest assured that most of Medicare services are covered. However, these types of services aren’t directly paid by Medicare. There are four different parts of these plans that cover different areas.

Different Advantage Plans

  • Part A

Part A is the hospital insurance that covers any expenses needed when you are staying at a hospital for treatment. Most of the time, people don’t even have to pay for part A as it’s usually covered by the Medicare tax deductions from your paycheck every month.

  • Part B

This, on the other hand, is the medical insurance that covers doctor visits, lab tests, screenings, using medical equipment, ambulance, and other outpatient services. Part B is considered to be more expensive than part A because it involves more costs.

You can use your work, insurance, or your spouse’s health plan to be able to have access to part B advantage plan that provides you with a lot of services for discounted prices or without any extra cost.

  • Part C

If you have decided to go for the Medicare Advantage (or MA), then you should expect to be paying for parts A, B, and B premium. Then you should try to find the best private insurance company to provide you with the benefits you need. Unlike other parts, part C covers dental and vision care which aren’t covered by other parts. Some plans even have extras such as wheelchair ramps, shower grips, meal delivery and even covers transportation expenses that come with all these doctor visits.

  • Part D

Part D plans are used specifically for prescription drugs to cover their costs. You can buy a part D plan from a private insurer who deals with Medicare and you are good to go.

The important thing to know is that not all plans cover all the benefits you want. You need to carefully read what you are subscribing to in order to know your rights. Knowing what you can do with full coverage and what you need to pay the full price will help you a lot in maintaining financial stability that doesn’t get affected by random hits.

Advantages of Medicare Plans

After you have decided between getting the original Medicare or the Medicare advantage plans and the exact parts you would want to be covered by, it’s time to contemplate your decision by weighing the pros and cons of choosing Medicare advantage plans. The main difference between original Medicare and the others is that with the original, you don’t have to be referred to see a specialist. You are almost likely will be covered throughout the united states. Medicare Advantage plans, on the other hand, offer extra benefits that you won’t find with the original.

  • The most important advantage you get with Medicare advantage plans is better coverage, discounts, and benefits that you get. With these plans, you can rest assured that you will be paying next to nothing for a service that otherwise who has cost you a fortune.
  • Every plan with Medicare has a maximum expense limit; once you pass it, you won’t be able to use the plan for the rest of the year. Medicare original is kind of better for not limiting your expenses regardless of the maximum out-of-pocket amount that you have spent.
  • Medicare Advantage plans are essentially less expensive if you compare their prices and your cost-sharing with the Original Medicare and what it covers. The best thing you can do to get the best of both worlds and get all the benefits that come with these plans along with the original Medicare advantages is to get Medicare supplement plan along with enrolling in a stand-alone Medicare prescription drug plan.

There are certain things you need to focus on when you are choosing your health insurance plan. This plan will determine the benefits you get and the out-of-pocket expenses that you will need. Choosing between original Medicare that covers hospital stays and most doctor visits will cost you a small amount that you might not even notice because it gets deducted every month from your paycheck. Going for Medicare advantage plans, on the other hand, means that you will get more benefits and will have the option to cover everything starting from a simple routine checkup to getting your prescription drugs without worrying about the money. The choice merely goes back to your needs.

Why You Need DeBounce to Secure Your Email Marketing

Many say that we are living in a new digital age, which isolates us more and more, away from the customer. That communication is increasingly “in the cloud,” a whirlwind of automatic, purposeless email. But this is where the importance of email marketing becomes clearer. Using tools (many free), studying metrics and automation, you can create a fantastic and individualized experience. A unique communication for each customer.

It is true that there are currently several ways for you to communicate with your customer. From support via Whatsapp, a short video on Snapchat, or even posting to your company’s Medium. No matter, the simplest form of interaction remains email marketing.

What’s more, besides being a communication tool, email marketing plays a very important role in your new user acquisition strategy.

How important is email marketing?

Email marketing is especially important in delivering relevant content to your user through proper nutrition flow. The purpose of this flow is to take this user from a discovery stage of your product or service to the purchase decision.

But what if you deal with the wrong emails?

Dealing with the wrong emails will only prevent your email marketing from reaching your goals. They are just wasting your time and worse, they can harm your business in the long run. For that you need a tool that is able to prevent you from these useless emails. You need a tool that is sophisticated enough to detect these emails and get rid of them forever from your system. You need DeBounce. This is the best email verification tool on the market to detect inactive emails and also emails that are used only to enjoy your services without any desire to pay for anything.

DeBounce.io can detect wrong emails easily and remove them out of your system

DeBounce is able to detect emails that are no longer active. The point is e-mails that were made and used but are not used anymore. You don’t want to send messages to emails that won’t be read, this is why DeBounce is able to prevent you from wasting time.

What about bad emails? This is my term for e-mails that are made specifically to deceive your system. Suppose you offer a free service period that can be extended by paying, then you are the sitting duck. You are the target of people who only want your free service without the slightest desire to buy. You don’t want to deal with these people and the best solution for you is to make sure they are removed from your system. DeBoounce is able to do that simultaneously.

In other words, testing one by one email, trying to find out whether they are fake or not is past. Let DeBounce do it automatically and get rid of them forever. Email marketing is effective but only if it has potential goals. Haphazard email marketing only leads you to a loss, both in terms of time and financially.

Trump Impeachment: A Pointless Charade?

Trump impeachment

We all knew this day was coming, and now it’s finally arrived, it feels a little like an anti-climax. Donald J. Trump has become just the third American President in history to be impeached, and the story already seems stale. We’ve sat through hour after hour of news coverage and testimony to get here, and yet we all knew that his impeachment was inevitable. That was all down to a simple matter of mathematics in the House of Representatives. The same simple matter of mathematics may also explain why it feels like an anti-climax – we all know how this is going to end.

In order for Trump to be convicted in a trial held in the Senate – a trial that will possibly happen as early as next February – two-thirds of all the members of the Senate have to vote in favor of removing him. That simply isn’t going to happen. The vote to impeach him was split down party lines, with two Democrats refusing to go along with the motion. If Nancy Pelosi, Adam Schiff, and the other major players can’t persuade everyone in their own party to back them, what hope do they have of persuading Republican senators to vote their way when it really matters? The answer, as everybody surely already knows, is none.

Pelosi and Schiff knew they were gambling when they moved to impeach the President, but there are times when it makes sense to gamble, and there are times when it makes none. If the odds are in your favor, gamble. Even if the odds are unforeseeable, as they would be in an online slots game, it might still make sense to gamble if you believe you have a chance. Anyone who’s ever bet money on an online slots website like Dove Casino has stood a chance of coming away with a win. The odds of coming away with a win in online slots might be slim, but they’re better than the odds of the Democrats seeing Trump removed from power via this route. Short of a miracle occurring, Trump will be cleared of the charges against him when the time comes. What happens next will then be all-important, and it might be the biggest self-own in American political history.

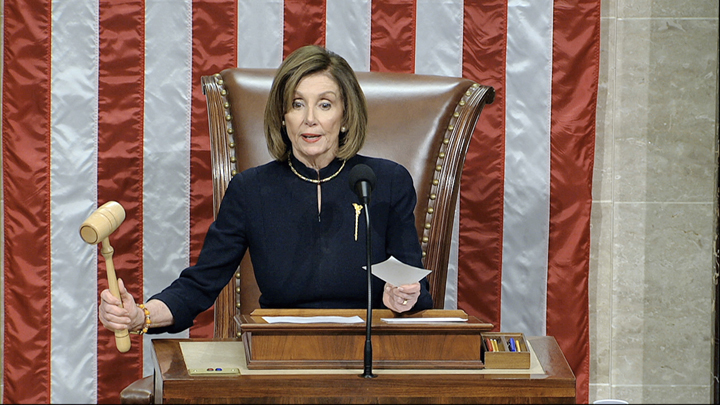
House Speaker Nancy Pelosi of Calif., announces the passage of the first article of impeachment, abuse of power, against President Donald Trump by the House of Representatives at the Capitol in Washington, Wednesday, Dec. 18, 2019. (House Television via AP)

We’ll never know if Trump stood a chance of being re-elected if the Democrats had simply left him to do his job, and got on with theirs. They’ve never, for a single second, accepted the result of the last election. They were hoping the Mueller report might bring him down, and they’ve jumped on the Ukraine scandal with every inch of their might. 2020 is an election year, and the Democrats should be focused on that, but it feels like they’re still contesting the 2016 election. For every move they make against Trump, they give him the chance to portray himself as being persecuted and victimized, and that stance plays well with his base. Every time the Democrats try to tighten the net with a move like this, they make it more and more certain that Trump’s supporters will vote him back in. What they risk doing at the same time is alienating people who may otherwise have voted for them.

Voters don’t like being told that they’ve got something wrong, and the hard fact of the matter is that Trump won the 2016 election. The smart thing for the Democrats to do would have been to lick their wounds, regroup, and focus on 2020. Instead, they’ve invested almost all the time since then trying to overturn that election result. In other words, their actions are showing the voters that they believe that the voters got it wrong. If Trump is impeached and removed, the 2016 election result is effectively null and void. That won’t play well with floating voters.

If you’d like to see evidence of that fact in action, look what just happened in the United Kingdom. Opposition parties have spent the past three years trying to protest or overturn the result of the 2016 referendum on membership of the European Union. When the country went to the polls, they heavily voted in favor of Boris Johnson, the Conservative Party, and their pledge to ‘Get Brexit done.’ People who wouldn’t usually vote for the Conservatives did so because they felt that the referendum result hadn’t been respected, and they wanted to teach the opposition parties a lesson. If the Democrats aren’t paying attention to this, they run the risk of the same thing happening to them.

With no realistic prospect of Trump being removed from office as a result of this impeachment, the Democrats may even have increased his chances of being re-elected. When the Senate clears him of all charges, he’ll be able to declare that he’s been vindicated and that the Democratic Party has wasted the nation’s time and money in pursuing a course of action that was never going to go anywhere. Trump will be portrayed as a great leader who has overcome injustice and adversity. The Democrats will be portrayed as desperate, grasping, and most importantly of all, failing and lacking in judgment. It’s not a good look to start an election year with, and it’s a position that’s likely to be almost impossible to recover from.

Whether or not Trump has actually done the things he’s accused of isn’t for us to say. We’ll have a chance to assess the evidence just as everybody else will when the matter proceeds to trial. We strongly suspect, though, that no matter what comes up at the witness box or in the paperwork, the Democrats will call it a smoking gun, and the Republican will call it immaterial. Everything is now so partisan that facts and evidence no longer seem to matter at all. These are dangerous political times, and care and nuance have never been more important when making big moves Unfortunately for the Democrats – and for reasons we may never fully understand due to the obvious futility of their impeachment efforts – the most significant move they’ve made in the past twelve months has been to shoot themselves in the foot before they’ve even started running.

Trapped in the Past? Moving Banking Beyond the Prison Paradigm

By Jouk Pleiter

Some banks are so established that, as customers, we think of them as part of the fabric of our lives; as immovable institutions. Maybe that was once the case. But the rise of a new, modern business environment is undermining that position. Apple pay and Facebook’s Libra are good examples of the market fracturing as big technology companies make strategic encroaches into finance. Similarly, digital-first challenger fintechs are driving consumer expectations to new heights. There is no room for complacency as incumbent businesses across the board are faced with the neo-reality that they must digitise or lose market share.

In some cases, banks are responding and innovating themselves, recognising that the landscape is shifting and they must shift with it. Others, though, have fallen for their own image, and remain convinced that they are in fact immovable institutions. They rely on shaky assumptions that the regulators will prove a block to the neobanks encroaching too far, and that inertia will keep customers sitting tight with their current providers.

Banks are responding and innovating themselves, recognising that the landscape is shifting and they must shift with it.

In other words, these banks see bars – bars keeping the neobanks out, and bars keeping customers in – a prison paradigm. They may find themselves in for a surprise when trends such as open banking and digital-first customer expectations will see customers move more willingly and freely than in the past. They may find that they are stuck with an outdated business model and mindset that no longer serves the market and sees them haemorrhage customers. They may, in fact, find that those bars were a more effective trap for the bank than the customer.

So – why is the prison paradigm so flawed – and what can banks do about it?

Reading the Regulators

Banking is a highly regulated sector. Incumbent banks employ vast teams and invest in various technologies to keep compliance in check. So, we can understand why they might not believe that neobanks – with young, lean teams learning as they go – will clear all the regulatory hurdles.

And in a sense, they’ve been right so far. Most of the neobanks that have made headlines have revolutionised payments but not developed the ability to take deposits and arbitrage those funds, nor to offer a broad suite of financial products – hallmarks of a true bank. There is much more compliance work to come. Slip-ups such as Monzo’s pin number storage fiasco also undermine the idea that neobanks are grown-up enough to really rival the incumbents.

But, will it stay that way? In many countries, regulators see their role as encouraging innovation in the banking sector, rather than acting as a block on it. The UK FCA’s regulatory sandbox is a good example. Don’t expect regulators to give challengers a free pass by any means, but don’t assume they’ll act to supress the new competition either.


Banks which don’t adapt will find their own resistance to change more powerful than their customers’. For traditional banks, creating a digital platform which is driven by consumer preferences must be the priority in this neo-reality.

Customers Untethered

Inertia can be a powerful thing – but it’s important to realise it cuts both ways. Yes, a certain number of customers may be quite sticky: perhaps they’re older and mistrust new techie brands, perhaps they just have other priorities. This can be an advantage for incumbent banks as they go through their own digital transformation.

However, it shouldn’t be taken for granted. Over time, digital-first banks will only become more sophisticated and switching will only get easier. That sticky segment will be whittled away. Banks which don’t adapt will find their own resistance to change more powerful than their customers’. For traditional banks, creating a digital platform which is driven by consumer preferences must be the priority in this neo-reality.


The Cost of Inertia

What happens if these banks fail to adapt and innovate? Look at what is already happening. There are a growing number of people who use a traditional bank as their primary account to receive their salary, but then immediately transfer an amount to a neobank for their monthly spending, giving them the benefits of instant alerts and rich features. For now, that is still profitable for the incumbent, but they are losing grip on the customer’s relationship with their money.

Some neobanks, like Starling, are already starting to build an ecosystem of financial partners, offering services like loans and pensions. They have realised that the future will be a digital hub, which provides the customer with the primary relationship with their finances, connecting them to other service providers.

For banks, the choice is whether to try and capture that position as the digital hub themselves, or else be relegated to a second-tier service provider. Even worse, it is feasible that banks are pushed into a utility role, providing the pipework for other companies who capture the higher value businesses.


Escaping the Prison Paradigm: More Than Tech

What is a bank to do? In short, it must become digital-first.

Many interpret that as an investment in technology, which is important but only one part of the process. Think of all the banks that have built an app and stopped there. That is an investment in technology, but no one mistakes them for neobanks.

Investing in technology means making everything digital-first, and untethering it from cumbersome legacy systems. It’s not feasible to rip everything apart and start again, so think about how to build the new without entangling it with the old. Moving the business model towards an API ecosystem internally is one way to do this. Not only does this help move towards the digital hub future, it allows different development teams to work in parallel on different projects without hindering one another or the day-to-day operations of the bank.

Just as important as technology though, is a digital-first culture. Culture permeates the organisation and affects all decisions. If leaders are of the view that: “the bank is making money and has an app, so why rock the boat?” then innovation will be stifled. The app will persist, but stuck in a treacle-slow traditional development cycle, falling farther and farther behind the neobanks’ rapid development.

A bank led according to a digital-first culture however, will operate at a speed that resembles the start-ups. Approaches such as Lean, Agile and DevOps will be implemented. ‘Innovation’ and ‘digital’ won’t be siloed teams working in offshoot offices, but embedded throughout the bank.

For banks, becoming digital-first in their technology, culture and business model is easier said than done, and it requires major overhaul of teams, leadership and processes – but the time to do it is now.

Incumbent banks have trust, credibility, healthy balance sheets and customer relationships – for now. Neobanks will eat away at each of those advantages if banks let them, not to mention the influx of competition from the likes of Apple Pay and Google Wallet. Incumbent banks still have the edge today – just about – but those that don’t escape the prison paradigm will suffer for it.

As the founder and CEO of Backbase, Jouk Pleiter has always stood on the forefront of digital innovation – growing Backbase into a globally recognised Digital-First Banking provider, improving the digital customer interactions of more than 120 financial institutions around the globe, including ABN AMRO, Barclays, RBC, Metro Bank, Discovery, Chebanca!, Keybank, Citizens, and many more.

About the Author

As the founder and CEO of Backbase, Jouk Pleiter has always stood on the forefront of digital innovation – growing Backbase into a globally recognised Digital-First Banking provider, improving the digital customer interactions of more than 120 financial institutions around the globe, including ABN AMRO, Barclays, RBC, Metro Bank, Discovery, Chebanca!, Keybank, Citizens, and many more.

What You Need to Do Today to Create a Secure Future

Have you ever thought about what will happen to you and your family if you can no longer work due to bad health or any other issue? A good present doesn’t necessarily guarantee a good future. You can work hard today, but how long can you do it. Even if everything goes great, we will inevitably get old. No matter how good you are doing today, you will have trouble maintaining your lifestyle in the future if you don’t plan it today. Here are a few things you need to do today to ensure a secure future for yourself and your family.


Identify What Needs Planning

Most people worry about three issues they might face in the future.

  • Bad health
  • Low quality of life
  • Financial security

Though all three are somewhat dependent on financial integrity, you have to plan all three from the days of your prime. Think if there are any other issues you might have to face in the future and start planning how they can be tackled.


Consider All Types of Insurances

There is insurance for everything, and its sole purpose is to provide help in difficult times. You can get life insurance to secure the future of your family in case of your departure. Some insurances bear your medical expenses and even pay if you are unable to work. Take time to thoroughly study all types of coverages and consider subscribing for ones that best meet your requirements.


Plan After Retirement Income

Most people don’t understand this, but we have to work today for tomorrow. You won’t have this energy you have today when you’re old. That’s why many people start saving money that they can spend after retirement without having to work. If you have a 401(k), that’s great; but if you don’t, consider opening an Individual Retirement Account (IRA). Saving is, without a doubt, a great idea, but you can do even better by working smart. It is suggested to study a physical gold IRA, so you can also earn profits from your savings.


Maintain a Good Credit Score

Don’t spend more than you can afford. If you got yourself in debt, it will have a bad impact on your credit score. Today you can compromise on many little things like a small house, cheap car, old furniture etc. When you’re old, however, most of those little things become a necessity. If you have a bad credit score, you can say goodbye to any loan or investment you might need in the future. That’s not all, insurance companies charge you higher premiums if you have a bad credit history. Don’t spoil it for little things that aren’t a necessity.


Find Your Passion

What would you want to do when you’re old? You may not have the energy to do the job you’re doing now. On the other hand, many people don’t want to sit at home waiting for death even if they have a good source of income. That’s why you need to find your passion that can not only earn you a living but you also enjoy doing it. If it’s a new skill, start learning it. Make sure it is something you can do at an old age.

Generation VIP Online Casino

Generation VIP online casino is a fresh gaming platform founded in 2019. It has come up with new advancements and creativity in the gambling sector to fulfill the required needs to play better. Generation VIP is registered with the strongest license provider Malta Gaming Authority and get their games revised for better performance by iTech Labs.

Generation VIP is prospering well due to its capability of serving the players with a good selection of games, VIP rewarding schemes, promising returns of their investments and much more to suit players’ taste of gaming. Not only this the casino offers an extensive range of payment methods and accepts multiple currency exchange option that makes the experience so convenient, flexible and enjoyable. 

The gaming library is wrapping up all departments of playing and is offering more than 450 video slots games like Divine Fortune, Cosmic Fortune, and Redeem the Dream and many more tabletop games such as the popular one roulette, blackjack, and baccarat. Most Reputed gaming providers are powering the system as mentioned in the list below:

  • NetEnt
  • Pragmatic Play
  • GameArt Studios
  • Red Tiger
  • Playson
  • Scientific Games (SG)
  • Booongo Games
  • Nolimit City
  • Just for the Win (JFTW)
  • Synot Games
  • iSoftBet
  • Booming Games
  • Triple Edge Studios

The Generation VIP online casino is supporting the most innovative and modern live dealer games backed by Evolution Gaming and never let the player lose interest while gaming. The options that you get in the live dealer games are:

  • Roulette (Immersive, Lightning)
  • Blackjack
  • Baccarat (Baccarat Squeeze)
  • Dream Catcher

The VIP programs are the biggest attraction for any player slots in the field of gambling. Generation VIP casino has got a lot to offer to its players as they progress their way up to variant levels. The gamers start receiving offers and rewards soon after their sign-ups.  There are seven levels initiating from Beginner, Bronze, Silver VIP, Gold, Platinum VIP, and the last two Premium and Prestige levels are activated through invite-only option. Every progressing level has its own rewards that keep the player consistent and encourage like improved perks, better exchange rates for your points, free spins, express cashouts, monthly cashback and more. 

The most demanding feature by any player is to have the mobile casino because it provides the flexibility to enter the gaming session any time anywhere as per their availability. VIP Generation lets you play just by signing in through any device and you have the pleasure of playing anywhere anytime just by a click of a button, no hassle of downloading any app.   

The payment method at Generation VIP is most diverse since they offer a varied range of deposit and withdrawal options. Not only this the casino lets you choose from multiple currencies like NZD, EUR, GBP, NOK, SEK, USD, and CAD. 

The list of providers are stated under.


Deposit methods:

  • Visa
  • MasterCard
  • NETELLER
  • PayPal
  • Skrill
  • Trustly
  • ecoPayz
  • Trustly
  • Euteller
  • Zimpler
  • EasyEFT
  • Sofort
  • Instadebit
  • EPS
  • Bank transfers
  • Paysafecard


Withdrawal methods:

  • Visa
  • MasterCard
  • NETELLER
  • PayPal
  • Skrill
  • Trustly
  • ecoPayz
  • Trustly
  • Bank transfers

The customer care representatives are available around the clock to serve best to their customers via email, live chat, and phone. The operators are reachable between 06:00 to 23:00 GMT.

EDITOR'S PICK OF THE WEEK

China economic growth

China’s Challenging Search for a New Model of Economic Growth

By Danny Leipziger China cannot continue to rely on exports to drive its growth, but what are the alternatives? China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...

WISE DECISION MAKER GUIDE

POWER INFLUENCERS

Emerging Trends

The Future of Global Trade