Home Blog Page 1064

Can HR Level Up, Please? A Case Study

By Bart Tkaczyk

Human Resource Management (HRM) has been around for decades. Apparently, same goes for organisation-wide issues such as toxic workplace culture, inequality in the workplace and sexual harassment to name a few. With these problems continually hitting organisations, how can HR demonstrate its greater value to the organisation to boost its timeless distinction and relevance?

Although Human Resource Management (HRM) is not the basis of all business activity, it is the basis of all management activity.

Having said that, HR has suffered from a major identity crisis – for decades. In fact, Peter Drucker, a management guru, described HRM, or “personnel management” as it was known in the 1950s, as a “trash can activity”, embracing a range of unrelated, low-level management operations that are shunned by higher-status management specialisms.1 Of note, HRM replaced the term “personnel management” in the 1980s when HRM courses began to be delivered as part of MBA curricula at business schools in North America.

With so many particularly nasty problems hitting organisations nowadays, such as toxic workplace culture, inequality in the workplace and sexual harassment, how can HR demonstrate its greater value to the organisation today?2,3,4 HR strategising may be the answer.

HR Strategising: A Mini Case Study

Writing down an HRM strategy document is not an unhelpful act. Yet, in today’s more complex, more ambiguous and more resource-constrained times, constant strategising is a lot more crucial to driving performance and achieving organisational success than just producing a physical document entitled “HRM strategy” that, in many organisations, is merely a “dead document” more often than not.

At a management consulting firm in North America, HR has never lost its relevance. As a matter of fact, it has chosen to become a truly iconic function. HR strategising has always involved continuously – and critically – reviewing and reflecting on the question: What exactly are the intentions of our enterprise, formed or formulated, toward the management of our people that are implemented at the philosophy, practices, and policy (3P) levels?

Let’s now look at some of the signature elements they have crafted that help deliver on their strategic people management promise.5,6,7


Strategic HRM at the Philosophy Level

Case in point: Leading by using culture to maximum advantage.8 “Nine times out of ten, we hire people who are “positive energisers”. We’ve realised that happy consultants are better at building and sustaining high-quality connections both at work and outside the office, and being great with people is key in consulting. In fact, not only do positive energisers perform better, but those who are closely connected to a positive energiser perform better too”, shares the Chief HR Officer (CHRO).

Evidently, culture is big there. While some companies hire for job fit, they hire for organisational fit. Selection is always a social, “two-way” process. If somebody joins the enterprise with a remarkable skill set, yet not a great culture fit, the organisation will not be happy (such staff will not be high-performing, plus they may be breaking the norms), and the employee will not be on top of the world either as they may feel unrecognised.

If somebody joins the enterprise with a remarkable skill set, yet not a great culture fit, the organisation will not be happy, and the employee will not be on top of the world either as they may feel unrecognised.

Culture is all about execution, and so culture and strategy need to be aligned. There are three strategic HRM efforts taken for energising culture for “positively deviant” performance, that is to say, performance far above the norm:

• Principle 1: Select consultants for “culture fit” first – this will affect how the firm thinks, feels, behaves and performs. Make sure they can contribute to the culture too.

• Principle 2: Socialise positively, and provide the recruits with diverse Learning and Development (L&D) opportunities; for example, by means of “reverse mentoring”.

• Principle 3: Offer a “total reward” package. When designing reward strategies, go beyond tangible/financial or transactional rewards (e.g. base pay, shares-based schemes, pensions, etcetera). Rather, incorporate all management initiatives such as relational rewards (e.g. career development) or communal rewards (e.g. employee voice, or recognition for a job well done) that may add higher value to the experience of working in the firm.

The bottom line is, positive employees will energise the workplace – promoting high-quality links at work. Negative ones will de-energise it – promoting low-quality connections.


Strategic HRM at the Practices Level

Case in point: Reverse mentoring. Mentoring is about creating and sustaining a partnership that helps your mentee to continuously learn and develop. Although formal mentoring is not very popular (ATD research finds that only 29% of organisations have a formal mentoring program in place), it does matter (6 in 10 participants indicate that their formal mentoring programs help to meet learning goals to a high or very high extent).9

Reverse mentoring is a powerful HR practice. Therein, a male CHRO is mentored by a female middle manager so that the CHRO can gain a direct insight into the career barriers and major challenges that women leaders face at work.

“The ‘reverse mentoring’ practice is extremely effective because it improves on the career mobility – for example, by reducing internal promotion biases, it helps more women into senior roles. Every organisation needs to smash any glass ceiling patterns”, evangelises the Head of Diversity.


Strategic HRM at the Policy Level

Case in point: Consider some “intra-office dating” policy – potentially amorous “workers may ask out a co-worker just once. An ambiguous response such as ‘I’m rather busy tonight’ counts as a definite ‘No!’”, explains General Counsel.

HR needs to constantly strategise – at the philosophy, practices, and policy (3P) levels. By doing so, it can boost its timeless distinction and relevance, which in turn, could build its scaling power – and become universally recognised, even iconic.

Instances of making unwelcome sexual advances in the workplace have been a growing problem.10 Courts rule that there are two patterns of sexual harassment: “quid pro quo harassment” (form of sexual harassment in which sexual favours are requested in return for job-related benefits), and “hostile work environment” (a more subtle form of sexual harassment deriving from off-color jokes, lewd comments, and so on).

By way of illustration, among other things, the dating policy playbook at the management consultancy recommends:

•  “Romances with higher-ups/subordinates aren’t a good idea at all.” This may fuel rumors about somebody “sleeping their way to the top”.

•  “Peer-dating is acceptable”. The best situation is peers in two different departments with individual career plans.

•  “HR should step in when: (a) individual or collective performance is affected, (b) when confidentiality is breached, or (c) when other employees complain.”

•  “Come forward”. Employees are supported to “come forward” when they feel that sexual harassment is happening from an office relationship break-up.

•  “Sexual Harassment 2.0”. Any unwanted sexual advances via any technology (in the workplace or outside the office) should be immediately reported/disclosed.

• “No public displays of affection (PDAs) in the office”.

Irrespective of the case, sexual harassment is illegal, and the enterprise is responsible for controlling it.


Take-Away Message

Ultimately, to get its mojo back, HR needs to  constantly strategise – at the philosophy, practices, and policy (3P) levels. By doing so, it can boost its timeless distinction and relevance, which in turn, could build its scaling power – and become universally recognised, even iconic. HR had better level up and get transformed into a trusted business partner or else it will not be at the table – the board table, period. 

About the Author

Bart Tkaczyk, Fulbright Scholar at the University of California at Berkeley, Course Leader (mbasprint.com), management thinker and writer, is in the business of energising extremely good leaders around the globe to aim even higher. On Twitter @DrBTkaczykMBA.


References

1. Heery, E and Noon, M. (2008). Trash Can Activity. A Dictionary of Human Resource Management. Oxford: Oxford University Press.

2. HBR Podcast. (2018, May 3). Toxic Workplaces. Boston, MA: Harvard Business Review. https://hbr.org/podcast/2018/05/toxic-workplaces.html

3. ILR Review. (2017). A Special Issue on Inequality in the Workplace. ILR Review, Vol. 70, Iss. 1. Ithaca, NY: Cornell University, ILR School.

4. SHRM. (2018). Workplace Harassment Case Studies & Research. Alexandria, VA: Society for Human Resource Management. www.shrm.org/ResourcesAndTools/hr-topics/employee-relations/Pages/Workplace-Harassment-Case-Studies.aspx

5. As a snapshot of the consulting industry, see Tkaczyk, B. (2017). “A Balanced Approach to Professional HRD Consulting: Lessons from the Field”. Global Business and Organizational Excellence (GBOE), Vol. 36, Iss. 4, pp. 6–16.

6. For sample consulting methods, see Tkaczyk, B. (2017). The Practical Rigor of Management Consulting: Methods, Frameworks, and Impact. Alexandria, VA: Association for Talent Development.

7. For more insights into the consulting industry, see Tkaczyk, B. (2018). “Business Leadership for the Management Consulting Industry: A New Model for the Greater Good”. Rutgers Business Review (RBR), Vol. 3, No. 1, pp. 53–66.

8. Chatman, JA and Cha, SE. (2003). “Leading by Leveraging Culture.” California Management Review (CMR), Vol. 45, No. 4, pp. 20-34.

9. ATD. (2017). Mentoring Matters: Developing Talent with Formal Mentoring Programs. Alexandria, VA: Association for Talent Development.

10. Pearce, JA. (2010). “What Execs Don’t Get about Office Romance”. MIT Sloan Management Review, Spring, pp. 39-40.
Tourism: the Philippines’ Next Growth Engine

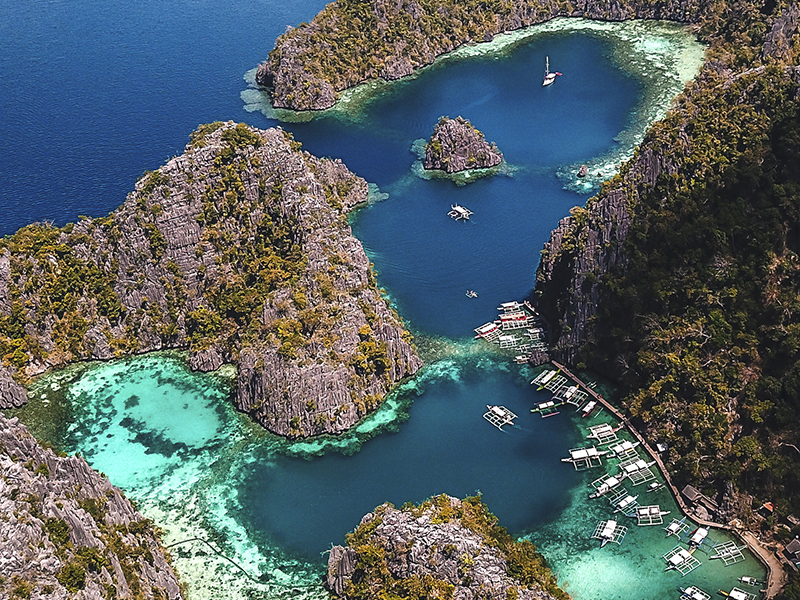
The beauty of the Palawan Islands, Coron Philippines

By Bernardo Villegas and Maria Cherry Lyn Rodolfo

Home to some of the world’s finest tourist destinations, the Philippines can indeed achieve significant economic headway by fostering its tourism industry. Discover how Dutertenomics and the government’s rebalancing strategy or pivot towards its Northeast Asian neighbours such as China, South Korea, Japan, and Taiwan are contributing to the positive outlook of the country’s tourism sector.


Under the Republic Act No. 9593 of 2009, Philippine tourism is recognised as an industry of national importance, an engine for investments, employment, growth and national development. Tourism has emerged as the third engine of economic growth in the Philippine service sector, next only to the remittances from Overseas Filipino Workers and the Information Technology-Business Process Management (IT-BPM) sector. Tourism’s contribution to the Philippine GDP reached 12.2% in 2017 and grew by 24.2% from the 2016 record.1 In terms of share to total Philippine export revenues, foreign tourism spending contributed 9.2%, next only to semiconductors and miscellaneous services. Its value expanded by 43.9% – from PhP 311.7 billion in 2016 to PhP 448.6 billion in 2017. The domestic tourism expenditure, accounting for 22.8% of household final consumption expenditure, reached Php 2.6 trillion in 2017, higher by 25.5% from its 2016 record.

There is good news to share with regard to tourism volume, a major component of the tourism expenditures. Domestic tourism, projected at 70 million in 2017,2 continues to serve as backbone of Philippine tourism, making it resilient to external shocks over the years. In 2017, the Philippines hosted 6.6 million foreign tourists or 11% higher than in 2016. For the first quarter of 2018, the number of foreign visitors increased by 14.8% from 1,784,882 to 2,049,094, half of them originating from South Korea, China, and the United States. These figures for the first three months of the year already represented 27% of the 7.4 million target number of visitors for 2018 under the National Tourism Development Plan. The not so good news is that the foreign tourism number of the Philippines is way behind its neighbours. In 2017, for example, the country attracted just 6.6 million foreign visitors compared to Thailand at 33 million, Malaysia 27 million, Singapore 16 million, Indonesia 12 million, Vietnam 10 million. One advantage of our neighbours is that they share borders with each other (unlike the Philippines where more than 98% of tourists enter and exit by air) and their road and airport infrastructure is very good to support multi-country trips and tour packages. The thrust of the new DOT leadership under Secretary Bernadette Romulo-Puyat to implement the National Tourism Development Plan, “to prioritize improving policies on access, connectivity, and security as well as enhance programs on tourism infrastructure”3 and to broaden and deepen the linkages of farming and agriculture with tourism markets in the value chain provide good opportunity to increase yields from longer stay and higher daily spending. By developing and offering diversified, competitive and sustainable product portfolios as well as efficient and seamless transportation across the Philippine archipelago, tourists will have better reasons to purchase multi-island and multi-destination packages thru the extensive network of airports and seaports across the country. Apart from investments in connectivity and access, tourist destinations need investments in destination infrastructure – rooms, water, sanitation, and power – to sustain growth. 

There is an upside in what is called Dutertenomics, i.e. if the massive infrastructure investment projects both from the government and private sector side (PPP) are actually implemented, the influx of foreign visitors and increase in the number of domestic travellers could even be beyond expectations. Note that a good number of the planned projects involve the improvements of airports in the major tourism destinations like Pampanga, Cebu, Bohol, Palawan, Iloilo, Bacolod, Davao and Cagayan de Oro. The utilisation of these airports for Philippine tourism will not only decongest NAIA that handled a total of 41 million passengers in 2017 vs. its design capacity estimated at 31.5 million passengers annually but also make tourists enjoy higher value for their money thru more direct flights to these international airports outside of NAIA. The opening of the second terminal in Mactan-Cebu Airport in June 2018 by Megawide and the Bangalore-based GMR Group will increase the annual passenger handling capacity of the airport from 4.5 million to 12 million. The construction of the new terminal in Clarkfield, Pampanga is designed to expand its current capacity of 4.5 million to 12 million by 2020. Tourists from the beaches of Central Visayas will find it easier to explore the cultural and natural destinations of the Northern Philippines and vice versa. Infrastructure such as railway to/from Manila to Clark and new toll roads that can be pursued by conglomerates such as Metro Pacific and San Miguel, will significantly reduce the commute time of those traveling north, by as much as sixfold. Cavite and Bulacan are too close to Metro Manila as locations for a new airport to solve the serious congestion problem of the National Capital Region. Both alternatives to NAIA will require very expensive reclamation of land which can be ecologically damaging in the case of Cavite; or in the case of Bulacan, worsen the problem of vanishing agricultural lands about which the Secretary of Agrarian Reform has been complaining.

Also contributing to a positive outlook is the rebalancing strategy being followed by the Duterte Administration in shifting greater attention to our closer relations with our Northeast Asian neighbours such as China, South Korea, Japan, and Taiwan – potential sources of increased tourism flows into the Philippines.  These Northeast Asian source markets already accounted for 53.1% of total foreign visitors in 2017.4 Its first quarter share reached 55% higher than its share of 52.7% during the same period in 2017 largely due to the double-digit growth of arrivals from China, Japan, Korea, and Hong Kong. The Chinese market that accounted for 18.13% grew the fastest at 54.53%. By the end of 2018, the Chinese market would have breached the 1.5 million mark. At a growth of 30% per annum in the next four years, tourists from China will reach the 4.5 million mark and emerge as the Philippine’s top source market by 2022. By that time, China could account for 37% of the country’s target of 12 million foreign tourists. There is a lot of room for growth for tourists from Japan, Singapore, Taiwan, and Malaysia, as well as Australia, and the United Kingdom.

Even more important than its contribution to GDP is the employment-generating potential of the tourism sector, especially in the countryside. For example, the proliferation of bed and breakfast facilities in the rural areas of Palawan, Bicol, Southern Tagalog, Central, and Eastern Visayas – catering especially to more than 70 million domestic tourists – offer employment opportunities to the families of the households of farmers who are among the poorest in the Philippines. As of 2017, the tourism sector was estimated to have a total employment of 5.3 million, representing about 13.2% of the total workforce in the country.5  In 2017, of the total employed in the sector, the Accommodation and Food and Beverage sector accounted for 33.0%; passenger transport 37.9% recreation, entertainment and cultural services 6.2%; retail trade on tourism-characteristic goods 6.6%; travel agencies and tour operators 0.7% and miscellaneous 15.7%.6  The Duterte administration is targeting to generate employment for 6.5 million persons by 2022, which would bring up the rate to 14.4% of total employee7 which is close to the employment rate of manufacturing today.

At a growth of 30% per annum in the next four years, tourists from China will reach the 4.5 million mark and emerge as the Philippine’s top source market by 2022.

It is providential that the current administration has embarked on a rebalancing of the trade, investment and cultural relations of the Philippines with the rest of the world. Without decoupling with its traditional partners such as the United States, Europe, and Japan, the Duterte administration has been giving more attention to its neighbouring countries in Northeast and Southeast Asian countries, especially to China, South Korea, and Taiwan. In 2016, the Department of Tourism profiled the various nationalities visiting the Philippines through the Annual Visitor Sample Survey conducted across the country’s various airports. As a strategic guide to tourism and travel establishments who want to cater especially to the Chinese, we present the results of the survey revealing the particular characteristics of the Chinese tourist market compared to other nationalities that visited the Philippines during the latest available survey period of 2016:

About 51.5 % of Chinese tourists were married and majority (49.3%) were travelling with their spouses, children, and relatives, a lot more so than other nationalities. This family-orientation may be considered a positive factor since the Philippines is also steeped in family-centered domestic tourism. It also bodes well for keeping a morally sound environment in the tourism destinations which usually are spoiled by backpackers and single individuals looking sometimes for the wrong kinds of fun and entertainment.

Koreans were the huge contributors in terms of foreign tourist receipts within average daily spending of $192.5. Chinese average daily expenditure per capita registered at a relatively low $63.4, although the study shows that while they cut back on spending for accommodation and food and beverage they spend heavily on entertainment and recreation and shopping. The Chinese prefer hotels and resorts for their accommodation, especially those travelling in groups, although their spending per capita is quite low based on the survey. There is bright opportunity for bed and breakfast establishments that can be registered with Airbnb. These enterprises can generate more employment in these areas where underemployment is the most serious problem. They can also be compatible with the efforts of the Government to give a big push to the development of small and medium-scale enterprises. A bnb establishment is usually run like a family business.

With regard to shopping, a good number of Koreans (71.2%) do it in tourist duty-free stores while the other four major nationalities (China, USA, Japan, and Australia) were more willing to go to the shopping malls, possibly due to longer average length of stay.

A relatively large number (55.1%) of Chinese visitors were motivated to go to the Philippines because of recommendation by friends and the presence of friends and relatives. Another 10.1% of them were motivated thru television/radio/film/video/internet, one of the highest among all nationalities.  This makes it very necessary for our travel and tourism enterprises to do a great deal of digital marketing targeted to the Chinese market.

Around 9.3% of Chinese respondents came to the Philippines to explore investment opportunities. The other nationalities averaged only 0 to 1%. This information jibes well with my own experience about large investors, especially in the infrastructure area. The majority of investors who have been asking for economic briefings regarding opportunities to invest in the so-called Dutertenomics list of infrastructures come from China. The next group would be the Taiwanese, who have been expressly told by their President “to go South”.

Good climate is the one thing that the Chinese liked in the Philippines much more compared to that of the other visitors. Other factors that international visitors found positive were the warm hospitality they received and the country’s beautiful sceneries and attractive beaches.  No wonder that since the start of more friendly relations with China occasioned by the more friendly diplomatic relations achieved by the Duterte Administration, we have seen a surge of Chinese visitors in key destinations like Boracay. Panglao, and Puerto Princesa.

The thing that the visitors most disliked about the Philippines, as expected, was the heavy and chaotic traffic. This perennial problem in urban areas like Metro Manila and Metro Cebu should be converted into an opportunity for other fop tourism destinations like Central Luzon, La Union, Aurora, Camarines Sur, Albay, Palawan, Bohol, Batangas, and Davao to attract foreign tourists away from these congested urban areas.  Fortunately, there are increasingly more direct flights to international airports outside Metro Manila that can be gateways for foreign tourists.

The development of the cruise tourism industry is an opportunity to complement the air arrivals by making the seaports in the country friendlier to international cruises. A study funded by USAID entitled “Developing the Philippines as a Cruise Destination:  National Cruise Tourism Strategy” outlined bright prospects for the international cruising market if more of our international ports which are gateways to tourism destinations are rendered more cruise ready. The principal ports ideal for cruising are Manila, Subic Bay, Cebu, Davao, and may I add Batangas City (which is the gateway to some of the most attractive beaches in the Southern Tagalog area). The secondary ports are Bohol (Tagbilaran and Catagbacan), Puerto Princesa, Coron (and surrounding islands), Boracay (Caticlan) and Ilocos Norte and Ilocos Sur (Currimao and Salomague).  In 2017, the number of port calls reached 139, up by 93% from the previous year and generated 97,338 cruise arrivals. For the period 2012 – 2017, the cruise arrivals expanded by an average of 20.2%. The main markets were China, Japan, South Korea, and Taiwan. Over the longer run, there will be increased traffic for cruises within the ASEAN Economic Community since our neighbouring countries, especially Indonesia, Vietnam, Thailand, and Myanmar are experiencing a rapid increase in their middle-income households who will have more discretionary income to go on cruises in the region. Whether or not these potentials will actually be exploited in the next five years will depend on the ability of the Duterte Administration to cut through the red tape, bureaucracy and political intrigues that unfortunately torpedo the best-aid plans. 

About the Authors

Bernardo M. Villegas is a Visiting Professor of IESE Business School in Barcelona, Professor at the University of Asia and the Pacific (UA&P) and Research Director of the Center for Research and Communication, Manila.  He has a Ph.D. in Economics from Harvard University (1963) and is a Certified Public Accountant, having been one of the CPA board topnotchers.

Dr. Maria Cherry Lyn Rodolfo is an Economic Consultant on tourism to both public and private enterprises and former Assistant Professor of Economics at the University of Asia and the Pacific.


References

1. Philippine Statistical Authority. Philippine Tourism Satellite Accounts. http://psa.gov.ph/content/contribution-tourism-economy-122-percent-2017. Accessed on June 8, 2018.

2. National Tourism Development Plan 2016-2022. Department of Tourism. 

3. http://tourism.gov.ph/news_features/opening_statement.aspx . Accessed on May 30, 2018.

4. http://tourism.gov.ph/tourism_dem_sup_pub.aspx.  Accessed on May 15, 2018.

5. Philippine Statistical Authority. Philippine Tourism Satellite Accounts. http://psa.gov.ph/content/contribution-tourism-economy-122-percent-2017. Accessed on June 8, 2018.

6. Philippine Statistical Authority. Philippine Tourism Satellite Accounts. http://psa.gov.ph/content/contribution-tourism-economy-122-percent-2017. Accessed on June 8, 2018.

7. National Tourism Development Plan 2016-2022. Department of Tourism.

Ease of Doing Business Act – the key to the Philippines’ Economic Comeback?

The Philippines has been vying for the ease of doing business act to be signed, and when it was on May 28, economists and business leaders are on the loose, trying to see if this act/bill will become the ultimate key to the country’s economic comeback. Compared to other ASEAN countries, the Philippines is struggling to cope up with the rising infrastructures and economies of its fellows. How well will the Philippines do in the international business market once the act comes into play?


President Rodrigo Duterte made a move to sign and approve of the “overdue” Ease of Doing Business and Efficient Government Service Delivery Act, or the Republic Act  No. 11032, with the presence of Congress leaders on May 28, 2018, Monday.1

The law mandates to make the country’s business environment more engaging and conducive to local and foreign investors. It also promises to make the application easier and faster, having to adopt a unified application form for local tax, building, sanitary and zoning clearances, and so on.

Although the business market is doing fairly well from an outsider’s perspective, the World Bank’s (WB) ranking says otherwise. According to their latest report, the Philippines stands at no. 113, with a Gross National Income (GNI) per capita ($US) of 3,580, and is lagging behind fellow Association of South East Asian Nations (ASEAN) countries like Singapore (no. 2), Malaysia (no. 24) and Thailand (no. 26).2

How well will the Philippines do in the international business market once the act comes into play?


Philippines vs. fellow countries in Asia

Ernst & Young Global Limited said in their report that the Philippines also has an expatriate-friendly environment, numerous developed cities and a strong telecommunications network. Lower labor costs and support from both the public and private sectors also make the country desirable for outsourcing. Thus, bringing in Business Process Outsourcing (BPO) and global in-house center (GIC) services, to cover the Information and Communications Technology (ICT) service sector demands.3

On the other hand, India is also known for being a primary industry for call centers. They have over a million employees working at their Business Process Management (BPM) industry, which is similar to the Philippines’. They also offer services including customer support, email support, web design, web development, content writing, proofreading, and accounting among many others.4

Foreign investors and clients usually find Filipinos’ high level of proficiency in English and familiarity with American culture a unique edge among international service providers, like India, and becomes an advantage when more service providers come and invest in our business environment.

Compared to other ASEAN countries, the Philippines is struggling to cope up with the rising infrastructures and economies of its fellows. Singapore, for example, stands at no. 2 worldwide for the ease of doing business rankings, with a GNI of $US 51, 880. Their economy has also been ranked as the most open in the world (2012 Global Enabling Trade Report), seventh least corrupt (2014 Corruption Perceptions Index), most pro-business (2012 World Bank Doing Business Report), with low tax rates (2013 Index of Economic Freedom) and has the third highest per-capita GDP in the world in terms of Purchasing Power Parity (PPP).

Foreign investors and clients usually find Filipinos’ high level of proficiency in English and familiarity with American culture a unique edge among international service providers.

As Singapore is highly urbanised, foreign investors and entrepreneurs would want to get their businesses in the country. One can feel really secure with the economy of Singapore, and doing business is relatively easier for their adoption of technological advancements.

However, because of the safe economy, government funding and low taxes, foreign investors whose businesses are not related to finance, biochemistry and industrial engineering might have a hard time in gathering a workforce. In addition, due to the very limited country size and strategic port location, it’s expensive to buy and rent land space in Singapore. The space might cost twice as much compared to neighboring Asian countries.

The law mandates to make the country’s business environment more engaging and conducive to local and foreign investors. It also promises to make the application easier and faster, having to adopt a unified application form for local tax, building, sanitary and zoning clearances, and so on.

Like its neighbor, Malaysia has the fourth largest economy in Southeast Asia, with a GNI of $US 9,850 , and is the 23rd most competitive country in the world, according to the 2017 Global Competitiveness Report. Malaysia’s growth in wages may be slow, but their labor productivity is increasing due to their numerous knowledge-based industries and adoption of digital technology.

Above the slow progress of their wages and salaries, some upper class Malaysians have delved into what they call “experiential luxury” that directly translates to not having to possess material things, rather the experience that those things and actions bring.

In effect, entrepreneurs and investors are looking into businesses in Malaysia that may bring “experiential luxury”, such as amusement parks and trampoline parks that are both exciting and definitely full of experience. 

Also, according to Martin Pasquier of Innovation is Everywhere, the proactive steps the government has taken to build a positive infrastructure for the Malaysian entrepreneurship scene has even come to grow foreign startups that find Malaysia an easier place to grow their business than back home. With Malaysia’s diversified population and quality economy, their stand remains in the world rankings.5

Thailand is doing great economic-wise as they are now found to be a newly industrialised country, heavily dependent on exportation. The country has the eighth largest economy in Asia, with a GNI of $US 5,640, where more than two-thirds are coming from their exports. The country also has a low unemployment rate of one percent as of 2014, due to most of the population doing own-account work or working in subsistence agriculture. Aside from rice, Thailand is also the world’s largest rubber exporter and world’s third-largest exporter of seafood, mainly shrimp.

According to the World Bank, Thailand is one of the ten ASEAN countries, aimed at creating a single market and production base, which enables the free flow of goods, investments, labor and capital within the community. Due to Thailand’s reputation as a hospitable business and travel locale, it hosts numerous trade shows, especially in the machinery, garment, and automobile industries. The country is a hotspot for foreign investment while the tourism industry is growing each year, as per the 2016 report of Alliance Experts.6

A report from ServCorp said that corporate taxes are higher in Thailand than in some other countries in Asia. Currently, there is a 30 percent tax on net profits by Thai companies. Every company registered in Thailand is required to submit audited financial statements and to file a tax return annually with the Thai Revenue Department.7


The Philippine economy in a few years

Last April, National Economic and Development Authority (NEDA) Director-General Ernesto Pernia said the country’s economic growth this year could surpass China’s 6.9 percent growth in 2017 and the World Bank’s forecast of 6.7 percent.8

A huge help in the leap would be the ease of doing business act, the future implementation of the National ID system, and the enhancement of the country’s social infrastructure and human capital investments that could help sustain and build economic growth.

Experts at FocusEconomics said that the economy is expected to grow at a robust pace this year and next on the back of a buoyant expansion in fixed investment, which is benefiting from strong public spending and favorable credit conditions at home. Prospects of an overheating economy and capital outflows due to faster monetary tightening by the U.S. Federal Reserve could, however, weigh on growth. Their panelists predict a GDP growth of 6.6 percent in 2018, unchanged from last month’s forecast, and 6.6 percent again in 2019.9

The newly signed act can bring a possible economic upsurge that would maintain the Philippines reputation as a flourishing nation, which is among the fastest-growing economies in Asia through the years.

FocusEconomics Consensus Fore-cast expects the economy to expand 6.6 percent in 2018, which is up 0.1 points from last month’s estimate. For 2019, they expect economic growth of 6.5 percent.

The Philippines is known to have large deposits of natural resources and as producers of gold, copper and chromite. The newly signed act can bring a possible economic upsurge that would maintain the Philippines reputation as a flourishing nation, which is among the fastest-growing economies in Asia through the years. It would continue to push economic development by attracting foreign investment and ongoing integration in the regional and global market.

Making Financial Advice Affordable to the Masses in the Age of Digitalisation

Business people discussion working concept

By Tim France-Massey

Many people in the UK struggle to navigate their way through uncertainty in the current financial climate and achieve their financial planning goals. However new regulations have resulted in a market influx of fintech companies and third-party providers, bringing to consumers innovative new technologies integrated into banking services that at last mean financial planning tools and advice – which were once only available to affluent clients – are now becoming available to everyone.


The financial services industry provides essential facilities, which are fundamental to support our modern economy and society. Given the current financial climate in the UK, many people are unable to achieve their goals, struggling to grow their savings, and make better financial decisions. Seeking advice for even standard queries – from sending children to university, to managing finances to ensure a comfortable retirement – can cost £1000s when speaking directly to a financial advisor or wealth manager.  

Customers, even those with high income, are often maintaining a spreadsheet to track all their banking and investments accounts across different institutions. Although low cost, this method is extremely time consuming and opens a new market which innovative fintech companies are beginning to tap into.

The problem is consumers today need financial advice more than ever before – with worldwide interest rates at rock bottom since the last recession, the UK savings ratio has plunged to an all-time low of 4.9%.1 The new Pension Freedoms has resulted in pensioners able to go into “Drawdown” instead of buying an Annuity, with nearly half a million retirees taking this option, and yet a third of them having no experience of being invested in the stock market.2 In fact, according to the FCA, only 6% of UK adults have had regulated financial advice in the past 12 months.3 Customers, even those with high income, are often maintaining a spreadsheet to track all their banking and investments accounts across different institutions – trying to build up a holistic picture of their net worth, spending trends and budget by themselves. Although low cost, this method is extremely time consuming and opens a new market which innovative fintech companies are beginning to tap into.


New regulations shake up the market

Earlier this year the financial services industry saw the implementation of the PSD2 regulations in Europe and the Open Banking regulations in the UK, which require banks to allow customer to give permission for FCA-regulated providers to access their current account data via Open Banking APIs. Therefore, the market has seen an influx of new third-party providers, larger technology giants and entrepreneurial fintech start-ups, who can access customer data easily, through the new regulations. New technologies such as robotics, artificial intelligence (AI), and blockchain are now being integrated into financial services, enabling companies to start bringing financial and wealth management advice – traditionally expensive, and only available to affluent clients – to virtually anyone.

The potential advantages of the Open Banking regulations include making it easier for consumers to get a clear view of finances, but also making it easier to shop around for a better deal. These benefits sound positive for the consumer, but the power of big data analytics to spot trends based on spending patterns is immense. Already there are fintechs who have developed transaction analytics algorithms that can determine consumers’ investment risk appetite, credit risk level, political affiliation, likely addictions, health issues, and even probability of divorce.

New technologies such as robotics, artificial intelligence (AI), and blockchain are now being integrated into financial services, enabling companies to start bringing financial and wealth management advice – traditionally expensive, and only available to affluent clients – to virtually anyone.

In fact, there are a number of money management apps from small fintechs already making waves in the market. Moneyhub is a complete money management app that uses screen scraping to provide a picture of total worth across multiple banks, card companies, investment platforms, and pension providers. It enables a comprehensive holistic view of consumers’ finances, showing spending patterns across all accounts, allowing consumers to create accurate budgets and track progress against it, and as the data builds up over time, can create a trajectory of net worth and cash flow projection. Moneyhub can even import the individual equities and funds in a consumer’s investment accounts and is able to tell whether they hold any of the worst performing investment funds. Additionally, Cleo is a Chatbot integrated into Facebook Messenger which similarly uses screen-scraping to aggregate accounts, help consumers budget, and sweep unused cash into a savings pot at the end of the month. Yolt, is another whose app leverages the Open Banking APIs to provide a 360-degree financial view.


Appealing to the new age banking customer

Many commentators predict that Open Banking represents a major threat to the incumbent banks, as it will allow the digital challenger banks like Monzo, Revolut and Starling to offer more targeted competing financial products. Yet there is the counter argument that many customers may be more likely to trust their old bank to be their data aggregator than the recent startups and challenger banks. In the wake of the recent furore around the misuse of Facebook data by Cambridge Analytica, many consumers may be justifiably wary about sharing their transaction data with an unknown entity. Despite the influx of new innovative services, banks are arguably in the strongest position of all when it comes to remaining at the top – as they have several advantages – such as a large number of customers, strong brand awareness, huge distribution networks, physical ownership of infrastructure and significant capital. However, traditional long-standing financial institutions have been burdened by legacy technology, strict regulations, and lengthy administrative processes – making them lag behind when it comes to providing digital customer experiences. To keep up with the challengers, financial institutions need to shift their focus to enabling better digital experiences, tapping into technology, to appeal to the banking customers of tomorrow.

One of the UK’s major banks has been the first to launch its own version of account aggregation services with a new app. The app allows customers to aggregate accounts from other banks alongside their owned accounts, with sending categorisation, a budgeting tool and a regular payment calendar. Given most mainstream banks have historically shied away from account aggregation technologies, owing to risk and data protection issues of screen-scraping financial data from competitor websites, this major bank is the first to take a leap, in hopes to offer to its customers more personalised financial service experiences.

To keep up with the challengers, financial institutions need to shift their focus to enabling better digital experiences, tapping into technology, to appeal to the banking customers of tomorrow.

Digital platforms, such as robo-advice, are already beginning to disrupt the market for investment advice. Initially launched by fintechs like Nutmeg and Scalable Capital in the UK, robo-advice services help consumers plan for a specific financial goal or grow their money faster than savings. This is done by allowing consumers to compare the potential gains over time, versus the different levels of investment risk, using algorithms to recommend a fund or to manage a portfolio of exchange-traded funds (ETFs). However, fintechs are now being joined by the established banks with their own robo-advice services, of which charge a minimal fee for counsel. These low costs are possible because digitalisation and automation technologies reduce the need for human involvement in the provision of support. Technology though, is only part of the answer. Understanding the customer’s needs, emotions, and capacity to understand new concepts is just as critical to designing a successful digital service.


Digital services to address growing financial planning needs

Whilst the uptake of robo-advice services is growing, they still only provide “simplified advice”, meaning they don’t assess a customer’s complete financial situation or consider other investments such as property or pensions, and in most cases can only address a single goal. Holistic money management apps do provide consumers with the foundation to manage day-to-day spending and make smarter decisions about how to meet financial goals, through borrowing or saving, depending on how much they can afford to put away or pay off each month. However, customers need to be able to set future goals and model scenarios for achieving them basedon different levels of risk, timeframe, and needs. Luckily, there are new digital services designed to address this need.

Another notable app on the market for long term planning, including retirement, is from 7 Investment Management, a boutique wealth manager in the UK. Using the app via a tablet device, consumers can drag and drop family structure, properties, assets, liabilities and goals, and get a digital long-term plan that immediately outlines when a user is likely to run out of money. Additionally, a large British insurance company have launched another planning service which helps to estimate income needs in retirement, and projects the future value of a pension pot. The planner is also equipped with tools to model the various options to drawdown, buy an annuity, or both, at retirement, and highlights if there is likely to be a shortfall. These free services available to all give consumers a reasonable idea of whether they are on track for a baked beans or champagne retirement.

There are now many tools available to allow consumers to get control of their finances, and judge whether they are on track to meet specific financial targets. However, the next step is to bring these services all into one place and to provide actual tangible advice. Currently, these services still fail to be able to tell consumers how they know a particular plan is the best option, if they are paying too much in interest or if they have forgotten something important when it comes to their financial planning, like life insurance.

As highlighted through research,4 most consumers don’t have a plan. They don’t know if they are financially healthy and on track, and don’t know where to go to get help. When they want the help, most banks do not offer it or if they do, the consumer simply cannot afford it. However, there is an existing demand. Clearscore, with over 4 million users in the UK, has revealed the huge appetite from customers to know their Credit Score and how to improve it. Similarly, there is emerging interest4 from customers to know and improve their financial health score.

Fintechs such as Lemonade Money offer a digital financial health check that looks holistically across short term income versus spending, liabilities and protection. Longer term goals to calculate a financial health score, giving suggestions to improve the score, access to related products, and in addition a Hero Money Coach. The UK banks aren’t far behind, with some now offering a one off face-to-face financial health check in branch, by phone or video. Outside the UK too, multiple banking groups have introduced financial health check apps that are part of the standard mobile banking app. These services are constantly updating and showing how financial behaviour over time affects a consumer’s financial health positively or negatively.

Most consumers don’t have a plan. They don’t know if they are financially healthy and on track, and don’t know where to go to get help. When they want the help, most banks do not offer it or if they do, the consumer simply cannot afford it.

Open Banking promises to allow consumers to use their data to get better deals on financial products and is opening the market to dozens of challengers offering innovative products and services which tap into modern day consumer wants and needs. Given that the regulations and its implementation are still only in its infancy, consumers are yet to see if large financial institutions or digital challenger banks like Fidor or Monzo will be the first to offer holistic financial planning tools and services for advice. However, as the landscape continues to develop, consumers can eventually expect these services to be a part of their everyday financial services experiences.

About the Author

Tim France-Massey is Director of Digitalisation, leading consulting engagements for major UK financial institutions from Wipro Digital’s London Lab. As Head of Digital and Data at Barclays Wealth, Tim led the digital transformation of Private Bank client and colleague propositions, and as Head of Mobile at RBS/Natwest, launched the UK’s first ever iPhone Mobile Banking App, a catalyst that helped lead to the widespread adoption of mobile banking.    


References

1. Office for National Statistics (ONS) 30 June 2017 (https://www.ons.gov.uk/economy/nationalaccounts/uksectoraccounts/bulletins/quarterlysectoraccounts/octobertodecember2017)

2. ThisIsMoney – YouGov Survey for Zurich UK (https://www.zurich.co.uk/en/about-us/media-centre/life-news/2018/third – of – retirees – relying – on – drawdown – are – first – time – investors)

3. FCA Financial Advice and Guidance: Quantitative research to inform the Financial Advice Market Review (FAMR) Baseline June 2017 (https://www.fca.org.uk/publication/research/famr-baseline-report.pdf)

4. Consumer interviews conducted by Designit, a Wipro company, in 2017

Singapore’s Governance, Prosperity, and Future Challenges

By Ian Austin

The Singapore government post-GFC has moved to “anchor” in selected sectors and the peak MNEs within these designs for long-term national economic growth, and it showed how the national polity through the varying 2011 and 2015 election results has placed new demands upon governance within the island nation. 


Singapore’s success story of attracting skilled professionals and multinational enterprises (MNEs) has been examined extensively as the small island state has, through rapid economic development, risen since the 1960s to become a global city.1 Singapore’s success has highlighted the crucial importance of good public governance; one able to adapt to new circumstances over time. The People’s Action Party (PAP) leadership’s highly pragmatic leanings, an international reputation for prudent financial management and an effective anti-corruption stance, has meant that foreign political and enterprise leaders have found the Singapore government easy to engage with. Recent efforts throughout the late 1990s and first decades of the 2000s to attract MNEs at the forefront of innovation (biotechnology, medicine, advanced electronics) have been built upon a foundation of a 30-year record of attracting and developing partnerships with MNEs looking to utilise Singapore at lower-level technical skills capacities (broad consumer electronics, shipping maintenance and others).

Recent efforts throughout the late 1990s and first decades of the 2000s to attract MNEs at the forefront of innovation have been built upon a foundation of a 30-year record of attracting and developing partnerships with MNEs looking to utilise Singapore at lower-level technical skills capacities.

The Singapore government’s relationship with private enterprise is clear; it has been willing to participate in the national economy as either a dominant state-owned enterprise (SOE), and done so across many sectors. At the same time, it has not sought to protect domestic enterprises at the expense of foreign MNE interests investing into the national economy. State-owned enterprises, government-linked corporations (GLCs), and state-encouraged enterprises, founded and developed by the government, have both secured domestic economic advancement, enhanced international trade activity, and provided valued partners to MNEs operations in the island state. Singapore Airlines, Changi Airport, the Port Authority of Singapore (PSA) and the SGX (Singapore Stock Exchange), to name a few, are all products of this effective state activism, and are now internationally recognised for excellence in their respective sectors. As a city-state with a small market and a large strategically located port, the government and commercial elite (the two being interchangeable) has been a constant champion of global free trade. Today, Singapore remains active in both bilateral and multilateral trade processes. The Singapore government argues that even when multilateral processes such as the Doha round of free trade talks break down, Free Trade Agreements (FTAs) remain the pathway forward for the city-economy.2  Singapore’s political and macroeconomic environment, therefore, are all attuned to the needs and wants of MNEs seeking a risk-free environment from which to launch their products and services into greater Asia. Indeed, there is little risk in stating that Singapore is without peer in enacting policy prescriptions that are favourable to MNEs operations, and supporting these with an array of practical infrastructure, legal, human resource and social initiatives. For all of these collective economic achievements, or because of them, however, the very nature of Singapore’s continuing interaction with the international economy over the coming decades will be shaped by the very same central question now confronting developed and developing economies alike. That question being: With dramatic changes taking place in macro-environmental areas, such as technological advancements and national demographic profiles, how will polity concerns over material and social/environmental inequality be managed by the nation’s stewards?

Singapore’s Economic Future

In the decade since the global financial crisis (GFC) (2007/08-2017/18), Singapore has consolidated its position as a successful economy highly attractive to MNE investment. Whilst Singapore, like so many other countries, experienced rapid economic declines in GDP growth rates throughout 2008 and 2009, the long-term soundness of its economic governance meant that by the end of 2010 the island nation was once again experiencing robust growth.3 The real and lasting impact of the GFC came then in the form of the intellectual reevaluation that took place within PAP leadership and the economic community over the strategic direction of future national economic progress. Further, China’s relentless emergence as a global economic powerhouse, seemingly unhindered by the economic calamity besetting the United States and Europe during the first decade of the 21st century, and India’s rise in international services placed the city-state with the challenge of operating within increasingly competitive international sectors. By all measures, Singapore post-GFC has countered these challenges.4 Singapore’s substantive state-backed investment funds, most notably the Government Investment Corporation (GIC) and Temasek Holding, over the last decade have been actively engaged in rapidly advancing the nation’s capacity to attract new growth sectors.5  More specifically, the Singapore government and its investment arms have sought growth sectors with attributes that make any GFC-like withdrawal from the island state either impossible or highly daunting and costly for the enterprise involved. The Singapore government has made it plain in the wake of the GFC that a crucial criteria for its engagement, political, policy and material, with MNEs will be the level to which they “anchor” themselves to the island nation.

Whilst Singapore, like so many other countries, experienced rapid economic declines in GDP growth rates throughout 2008 and 2009, the long-term soundness of its economic governance meant that by the end of 2010 the island nation was once again experiencing robust growth.

The most publicly-visible example of this anchoring policy has been the development of two large Integrated Resorts and Hotels complexes (IR&Hs, read casinos): Marina Bay Sands and Resorts World Sentosa. The impact of the IR&Hs upon the Singaporean economy since their opening in 2010 is undoubted and recognised by the continual utilisation of the Sands Marina Bay resort imagery as iconic of Singapore’s present and future.6 The logic of the PAP government’s decision to open IR&Hs (casinos) on the island state after many decades of most vocal opposition post-GFC is simply: the two massive casino development, whose accumulative investments totalled $US 12–14 billion, are entirely the product of state regulatory licenses: they simply cannot be relocated offshore. In return for this investment, and the significant domestic labour inputs required, the Singapore government has invested significant public funds to deliver to the ownership of the IR&Hs an international clientele profile. Equally, by design, the Singapore government rightly predicted that the development of the IR&Hs in themselves would see the clustering of high-end hotel and fashion brands in-and-around the Marina Bay Sands and Sentosa districts. International investors, professionals and clientele who associate themselves and their clients with the complete entertainment/lifestyle product surrounding the integrated resorts and hotels have added a new complexity to the nation’s service economy. The Singapore F1 Night Grand Prix, commenced in 2008, for example, stands as a pinnacle event in the effort to brand Singapore as a global city with its clustering of business, sports, design, leisure and entertainment interests.

Somewhat less visible has been the Singapore government’s moves to “anchor” international wealth management actors to the island nation’s future prosperity.7 Singapore has long been highly successful in attracting international financial sector enterprises. Since the GFC, the PAP has not only consolidated this position, but also enacted the Marina Bay Financial District to cement the island nation’s position as a top-tier international financial centre. The massive Swiss-based giant UBS, being but one example of an international wealth management actor who has been actively courted by the Singapore government elite (the GIC as the owner of 6.4 percent of UBS shares is one of the largest shareholders), and now making the island a global centre for various wealth generating operations.8 The sheer scale of the international banking and finance means that Singapore must be selective in its activities and focus on providing niche, but highly profitable services, most notably wealth management services (wealthy individuals or trusts). Along with traditional Western wealth management markets, Singapore has been even more successful in gaining market share within China, Russia, Latin America, Africa and the Middle East. There can be no doubt that Singapore’s ultimate aim is to surpass Switzerland as the home of private wealth management. Whilst this might have seemed fanciful prior the GFC, tectonic regulatory shifts in Europe and the United States have been altering the equation.9  Singapore’s position in Asia has proved decisive: the concentration of global wealth accumulation in the region continues unabated and Singapore has positioned itself as a most willing and capable servicer of this new wealth. The message from the Singapore authorities for greater Asia’s wealthy is uniform and assured: that high wealth individuals/trusts will find a welcoming and competent nation with a supporting regulatory and tax climate, including the vigorous enforcement of the strict privacy laws. As with the IR&H sector, the Singapore government’s combination of political, capital, education and other investments into the wealth management sector means that the cost of exiting the island state for any international entity would be high. Not least of all for the simple reason that the scale of accumulated state-directed wealth present makes the Singapore government a truly indispensable global client. As stated, by design, the Singapore government set out to anchor the leading banks and financiers within international wealth management sector to the island nation. International regulatory measures that have directly affected Switzerland to a greater degree than its Asian counterpart have no doubt been highly beneficial; but Singapore’s proactive endeavours have enabled it to define itself as a wealth platform for the Asian Century.


Singapore government has made it plain in the wake of the GFC that a crucial criteria for its engagement, political, policy and material, with MNEs will be the level to which they “anchor” themselves to the island nation.

Political Continuity and Change

Despite a near decade-long (2010 – 2018) record of economic growth and the transitioning of the economy into service sectors anchored through political-policy (legislative) and capital means, the long political paradigm of the PAP’s dominance over the island state has been far from smooth. The PAP’s popular vote dropped to 60.14 percent in the 2011 general election compared to 66.6 percent in 2006 general election, but rose again to 69.86 percent in the 2015 election.10 The reason for the significant 2011 election decline in PAP’s popular vote was widely ascribed, not least of all by the Prime Minister Lee Hsien Loong, as a need for the long-term governing party to listen fully and engage with the lived experience of the national polity. The 2011 election revealed that the distribution of wealth and social progress, and not the net material increase in Singapore’s wealth, was now a significant factor in the Singapore polities’ decision-making.11  In response, PAP executed policies, most notably legislative restriction on foreign labour entry, can be defined as a “Singapore-first” mandate. The nine percent upswing to the PAP in the 2015 general election revealed that these measures and others have met with broad domestic approval. Most significantly, they attracted a rare public response from the international investment community, and particularly the MNEs operating on the island nation, who have depended on the ability to bring in foreign sources and human capital when required. The PAP, always a champion of MNEs investment into the island nation, nevertheless delivered a forceful rebuttal to these enterprises’ call for adjustments. Put simply, the 2011 election result, and the PAP’s recalibration and success campaign in 2015, reinforced to all that no matter the historical dominance of a party, it is never far from threats to its legitimacy should the electorate decide that the local is no longer at its very heart; that no matter the extent of the economic advancements achieved, without communal connectedness, of a sense of shared and equitable progress, legitimacy dissipates.12   

Featured Image: Sands Marina Casino Photograph by Ian Austin

About the Author

Dr. Ian Austin is Senior Lecturer in International Business at Edith Cowan University. Most of his works examine Singapore as a wealth management centre and as a global city. He previously worked in Singapore for both private enterprises and the public sector.

References:

  1. 1. Low, L. 2010. Exploring New Engines for Growth. in Chong, T. ed. 2010. Management of Success Singapore Revisited. Singapore: Institute of Southeast Asian Studies.
  2. 2. Singapore FTA Network. http://www.fta.gov.sg/ accessed April 2, 2009.
  3. 3. Chong, T. 2009. Singapore in 2008: Negotiating Domestic Issues, Confrontations and Global Challenge.  pp. 289-304. Southeast Asian Affairs 2009. (Singapore: Institute of Southeast Asian Studies).
  4. 4. Singapore Department of Statistics https://www.singstat.gov.sg/ ; International Monetary Fund https://www.imf.org/~/media/Files/Publications/CR/2017/cr17240.ashx
  5. 5. GIC https://www.gic.com.sg/ ; Temasek https://www.temasek.com.sg/en/index.html
  6. 6. https://www.youtube.com/watch?v=sBPszhAIaQI Singapore “What’s Possible” campaign.
  7. 7. Robins, B. (March 10, 2014), Singapore turns its hand to wealth management The Sydney Morning Herald, www.smh.com.au/business
  8. 8. UBS Asset Management in Singapore https://www.ubs.com/sg/en/asset-management.html
  9. 9. Grant, J. (July 23, 2013), Singapore loosens Switzerland’s grip on wealth management, Financial Times, www.ft.com/cms/s/048c3630
  10. 10. Elections Department Singapore http://www.eld.gov.sg/
  11. 11. Yahya, F.B. ed. 2015. Inequality in Singapore, World Scientific Publishing: Singapore. 
  12. 12. The electorate of Malaysia on May 9th 2018 sent this very message in a most profound way toppling the long-term UMNO governing coalition in a largely unanticipated electoral route.

Event: Going Global Live takes place on 14 & 15 Nov at ExCeL London

Going Global is Europe’s leading exhibition dedicated to providing businesses with absolutely everything they need to expand internationally, and trade overseas, in this uncertain economic climate.

Packed with leading experts, over 70 educationally-rich seminars, unlimited 1-2-1 networking opportunities, interactive masterclasses and more than 60 of the world’s most innovative exhibitors; this is THE show to help your business trade in the world’s most lucrative cities, countries, and regions.

Going Global Live takes place on 14 & 15 Nov at ExCeL London. Visit the Going Global website for FREE tickets or alternatively contact Gavin Harris on 01872218007 or [email protected] to enquire about exhibiting & sponsorship opportunities.


Mainstreaming Islamic Social Finance

Hua Lamphong is the informal name of the station, used by both foreign travellers and locals. The station is often named as Hua Lamphong in travel guide books and in the public press.

By Ebi Junaidi and Primandanu FA

Over the years, Zakah (mandatory alms-giving), waqf (Islamic endowment funds) and Islamic not-for-profit microfinance have been regarded as traditional and miniscule in importance. In this article, the authors present the direct effect of such condition as evident in several phenomena as well as how creative ideas on contextualising centuries old of Islamic social funds in the current lifestyle can result to a sweet fruit of giving helping hands to the needy.


It was such a typical gloomy winter morning in Durham back in early February. Yet, students were so passionate to come to the Durham Centre for Islamic Economics and Finance’s Professional Speaker Series. This time, the talk invited Dr. Mahmoud Mohieldin, Senior Vice President of the World Bank Group. The topic was Sustainable Development Goals (SDGs) and the Role of Islamic Finance – which is as much as interesting as the speaker, Dr. Mohieldin. Indeed, he is the right person to discuss on this matter, as he is the World Bank’s person-in-charge for delivering the SDGs as well as having a distinguished expertise on Islamic Finance.

One of the highlights in the talk was the use of Islamic Social Finance in achieving the SDGs’ 17 goals and 169 targets. The Islamic Social Finance is expected to cover part of the $3.1 trillion investment gap needed by 2030. Investment gap in this case is the difference between the total investment needed and the development fund available.

The Islamic Social Finance expected to cover the investment gap includes Zakah (mandatory alms-giving), waqf (Islamic endowment funds) and Islamic not-for-profit microfinance – sectors that over the years have been regarded as traditional and miniscule in importance. Prof. Mohamed Azmi Omar, former Director General or Islamic Research and Training Institute (IRTI) once even said, Islamic Social Finance “failed to catch the fancy of the (Islamic finance) professionals and practitioners.” As a result, he added, “mainstream Islamic finance is now understood to comprise banking, insurance and financial market participation (only).”

The direct effect of such condition can be found in several phenomena. Firstly, there was very less education given to the community over the importance of the provision and payment of Islamic social finance. The recent controversy over the Indonesia government’s plan over zakat collection on Muslim civil servant is just one of the consequence of it, despite the fact that Indonesia is the home of most populous Muslim country in the world. Looking back, the dimension of many teachings over Islamic social finance were mostly “hereafter-motivated” without many references on the significant role that the Islamic Social Finance can play in the world, let alone in development and poverty alleviation.

Secondly, human resources allocation is very limited in this sector, as working or dedicating career and life in this field is considered inferior, compared to Islamic banks, insurance and/or other institutions and sectors. This is understandable as Islamic social finance might remunerate its management lower compare to other corporate level Islamic finance institutions due to its micro size as well as its effort to ensure only minimal percentage of funds managed is utilised in this manner.

Putting Islamic social finance with its philanthropy and not-for-profit nature in the frame of SDGs has given it the challenges it may well perform and at the same time allowed Islamic Social Finance to be pictured in the mainstream Islamic Finance.

Thirdly, infrastructure to support Islamic social finance’s necessary professionalism in both fund-raising and fund-using has been minimal. Many of the Islamic social finance institutions operate based on trust and utilise public figure to create their social credibility. In the future, it is very important to build a standard measure on integrity, transparency, and good governance in these institutions. Therefore, putting Islamic social finance with its philanthropy and not-for-profit nature in the frame of SDGs has given it the challenges it may well perform and at the same time allowed Islamic Social Finance to be pictured in the mainstream Islamic Finance.

Looking back, we should thank IRTI of Islamic Development Bank (IDB), who has initiated the very first global report of Islamic Social Finance back in 2014 – covering Indonesia and some other countries in South and South East Asia. The report has enhanced public understanding over the sector by providing comprehensive information over existing conditions of the sectors as well as the future development directions.

Since then, not only other series of reports have been produced but effort towards mainstreaming Islamic social finance has also been taken place. One worth mentioning is the special session in the World Humanitarian Summit of The United Nation in May 2016 on “Islamic Social Finance as a New Alternative for Humanitarian Financing”. The humanitarian purpose is indeed at the very heart of Islamic social finance, even more urgent compared to developmental purpose such as the SDGs.

Co-existence and cooperation of private and small Islamic social finance organisations as well as traditional Islamic institutions will strengthen their ability to reach their objectives as well as enable us to realise the full potential of Islamic social finance.

It is interesting that the opportunity targeted within this summit is not only zakah and waqf but also include the possible issuance of humanitarian sukuk, directing at impact investors. The success of International Finance Facility for Immunisation (IFFIm) for its $US 500 millions and $US 200 millions humanitarian sukuk back in 2014 and 2015, inspired many humanitarian organisations to follow suit.

It is important to note that mainstreaming Islamic social finance does not mean corporatisation of zakah, waqf and other funds. Corporatisation does bring efficiency to the fund management by creating a large network, big organisation and other resources that enable it to collect and channel more funds. Yet, existing private and small Islamic social finance organisations as well as traditional Islamic institution such as the Masjids, Baitul Mal Wat Tamwil (BMTs), Waqf institution, etc. have been there playing their role not only giving helping hands to those who were missed by larger institutions, but also as the source of social capital within community.

Co-existence and cooperation of private and small Islamic social finance organisations as well as traditional Islamic institutions will strengthen their ability to reach their objectives as well as enable us to realise the full potential of Islamic social finance. In the context of Indonesia, we are talking about IDR 270 trillion from zakah [based on Indonesia’s National Alms giving Institution’s (Badan Amil Zakat Nasional) (estimate), and IDR 180 trillion from waqf (based on Badan Waqf Indonesia (BWI)’s estimate) annually. These numbers plus the savers in non-profit Islamic microfinance and prospective ethical investors on humanitarian sukuk can indeed significantly play a role in humanitarian and developmental projects; projects that echo the very early intent of the birth of Islamic Economics and Finance.


“Blending” the social finance with existing Economic and Financial Institutions

There were two interesting events related to the intensification of Islamic social funds collection in Indonesia. The first is the introduction of “sazadah”, a program that enable investors of stock markets to pay their sadaqah (voluntary giving) and Zakat (annual Islamic alms giving) by their stocks. The launching was followed by the opening of 36 counters around Indonesia that enable philanthropists to consult as well as donate their stocks with no hassle. The initiative of paying these social funds in the form of stock is considered as the first ever in the world. The program targets not only Islamic finance investors but also conventional investors as long as the stocks donated are listed under the Jakarta Islamic Index.

It is important to note that the Sazadah program was initiated by private securities company, The Henan Putihrai Security. The company sought approval from Indonesia’s Ulama Council which agreed on the ground that stocks is considered as class of assets subject to Islamic annual obligatory alms giving. For channelling the funds, the company smartly cooperated with Indonesia’s official national Zakat Institution planning to finance its Zakat Community Development

This is not the first time that this security company held hands with zakat institution. Almost two years ago, the company introduced a program that allows investors to donate indirectly while performing transaction trough their Sharia Online Trading System (SOTS). Every brokerage fee paid due to trading activities will have 20% taken for donation. The so-called “berkah” (blessing) program has an annual subscription growth of almost 100%, which increases the donation amount transferred to projects under the zakat institutions.

The second event is the cooperation of BAZNAS with one of Indonesia’s electronic money provider, Go-Pay. The cooperation allows donations to be paid through Go-Pay platform directly to BAZNAS’ account. Last year, cooperation among the two has contributed to a targeted 10,000 poor recipient families. The cooperation was on better donation channelling system. Indeed, distribution of donation, especially during Muslim holy month of Ramadan, has been challenging. This have caused not only an unbalance distribution and exclusion of some of the most needed donation targets, but also, in the case where direct distribution was done, casualties and inhumane queuing practices have frequently occurred.

The above two events are indeed just examples of how creative ideas on contextualising centuries old of Islamic social funds to current lifestyle can result to a sweet fruit of giving helping hands to the needy. There are indeed many more ways to eventually enable us to locate Islamic social funds to a place it deserves –  a place that reminds people, in any regular activities they are involved in, that there is a space to contribute to their fellow human being socially. A noble cause that penetrates the everydayness, which is what mainstreaming aims for.

About the Authors

Ebi Junaidi is School of Economics Lecturer at Universitas Indonesia. He is currently pursuing his PhD in Islamic Finance at Durham University Business School. His research areas are Waqf, Trust, Venture Capital, Risk Attitude and Financial Decision. He is now the Chairman for Indonesia Islamic Economics Society-United Kingdom Representative.

Primandanu FA is currently pursuing Master’s degree in Islamic Finance at Durham University. He is now the General Secretary of Islamic Economics Society (MES-UK). He commenced his career at Capital Market Supervisory Agency in 2010 and has been working at Indonesia Financial Services Authority since 2013.

Identity Politics: Diversion from the Growing Economic Crisis?

concept of rich and poor in a person

By Ghada Chehade

Despite the reality of ever-increasing economic despair – including, and perhaps especially, for minorities – no one is willing to talk about class and economic issues. This is especially true among the so-called new left, which is more concerned with identity issues than class and politico-economic analysis. But lacking a larger analysis of the politico-economic system, identity politics is little more than a diversion and distraction from the larger issues that plague us all; and a convenient tool for the global establishment.


“It’s the Economy, Stupid”

We live in a world that often appears to be upside down; a world that has its priorities all mixed up. While we slip deeper into what can easily be described as the greatest economic depression of our time, no one on the “new left” (a.k.a. the liberal left) seems willing to talk about the bleak realities of ever-increasing economic despair. Instead, what we see and hear in the media, including the “left media,” in government, and across university campuses is an emphasis on special interest issues and personal identity. Rather than address the larger issues that plague the majority of people (including minorities) – i.e., the pitfalls of economic globalisation, unemployment and underemployment, mounting debt, the increased cost of living, economic austerity, imperial wars, etc. – we are distracted by the spectacle of identity politics and stifled by a liberal political correctness that imposes “tolerance” in a manner that actually limits freedom of thought and expression while serving the global establishment.

While identity politics claims to be concerned with helping minorities, it refuses to address economic issues, such as poverty and growing unemployment, which often disproportionately impact certain minority groups.1 One of the reasons that identity politics does not deal with class and economic issues is that it is rooted in postmodern theory, for which the explicit rejection of the centrality of class is somewhat of an obsession.2 Indeed, many proponents of identity politics are openly hostile towards classical or traditional left politics – which dealt largely with class, Empire, and economic issues – and its “failure” to address culture and identity. However, the traditional left has never denied the importance of racial, gender and ethnic division within classes. What it has emphasised, though, is the wider system which generates these differences and the need to join class forces to eliminate these inequalities at every point.3

Focusing on identity rather than class and economics negates the reality that many individuals are struggling financially at present;4 both within and across racial, gender and ethnic divisions. This is due in no small measure to the U.S.-led agenda of economic globalisation. As I explain elsewhere:

“Globalisation…exploits and relies upon global inequality and disparity. Globalisation exploits the developing world’s “comparative advantage” of cheap labour and lax regulations, and allows western companies to maintain the illusion of being domestic while benefitting from operating in countries where they pay far less for everything –  especially labour – and stand to gain immensely as a result.”

“This undermines western workers who have suffered mass underemployment due to economic globalisation and the offshoring of jobs and investment. And while it may be argued that globalisation benefits people of the developing world through employment…the harsh economic restructuring conditions that accompany globalisation and foreign investment actually hurt large segments within developing countries.5”

One result of globalisation in the west has been the collapse of the middle class. The loss of the traditional manufacturing economy (and the associated managerial and technical sectors) ushered in by globalisation, has forced much of the middle class to seek supplementary income. For instance, while services like Airbnb and Uber are regarded as hip and trendy modern conveniences, they are also indicators of a failing or degraded economy – what the mainstream media describes as a “transitioning economy.” But terms like the “sharing economy” and the “gig economy” are ultimately liberal euphemisms for those things that people must do to make ends meat. Because in reality, people don’t rent out their guest room or drive strangers around the city or sell used things online to make friends; they do it to make money. Making these supplementary outlets hip and trendy takes the stigma away from what is essentially and traditionally speaking being broke or poor. It also masks the growing reality of middle class economic decline and growing debt servitude, for minorities and non-minorities alike.

Class, poverty, and economic collapse are the elephants in the room that identity liberalism6, contemporary politicians, and the mainstream media refuse to address. Interestingly, and ironically, Donald Trump was able to persuade many of the older generations – including some Black and Latino populations – into voting for him by galvanising support around these populist issues. Of course, he has failed to deliver on any of his populist, economic promises. But his victory may be an indication of people’s growing economic desperation in the U.S.


Identity Politics as Diversion from Our Common Plight…and Protection for Wealth & Power

A politics that addresses identity and minority issues without examining the larger socioeconomic system and class relations cannot adequately address the disproportional disenfranchisement and economic despair experienced by minority groups. At the same time, a focus on identity and individual issues prevents us from seeing what we have in common, pitting different groups against one another and distracting them from – and from uniting over – their common economic plight.

While people may share a common race and heritage, wealth and the lack of wealth create a massive cleavage that identity cannot bridge.

Class, or economic situation, is the great unifier. At the present juncture, we may have more in commton with people of a similar economic situation than individuals of a similar ethnic, racial, gender, or sexual orientation identity. Poor people everywhere share something in common – their poverty or economic despair – and wealthy people everywhere also share something in common – their immense wealth – regardless of cultural or identity differences. For instance, while African Americans may share a common racial identity, the majority of black people in the U.S. have very little in common with the uber-rich Oprah Winfrey or the Obamas. The immense wealth, power and influence of Oprah or the Obamas puts them in a reality altogether different, and far more privileged, than the majority of everyday African American people in the U.S. The same can be said of any racial or ethnic group. While people may share a common race and heritage (or a common gender, sexual orientation, etc.), wealth and the lack of wealth create a massive cleavage that identity cannot bridge.

And the opposite is also true. While we may differ in pigmentation, ethnicity, sex, gender, sexual orientation, religion, etc., what more and more people presently have in common is that we are being increasingly impoverished and exploited by the global regime of greed and hegemony. At the same time, we are increasingly more politically disempowered, controlled, monitored, spied upon, and surveilled than we have ever been, especially in the west. Ironically, it seems rather convenient that the more austere the economy becomes and the more authoritarian the State becomes, the more identity issues and cultural issues are pushed to the foreground, especially in academia and the establishment media. If we stopped “celebrating” our differences and/or fighting over our differences long enough to see our common plight, we just might wake up to the reality that class, economic austerity, and western totalitarianism are among the most pressing issues of our time. Related to these, are issues such as war, interventionist foreign policy, and international sanctions, which are all deployed in the service of the global wealth and power establishment (i.e., Empire).

One of the biggest problems with identity politics is that it can mask how politically and economically disenfranchised we all are – and especially for minorities – by giving token victories and token representation in a rigged and corrupt system. This is especially true in the mainstream media and popular culture as well as in politics – which in places like the U.S. is beginning to look more and more like pop culture – where token representation for women and people of colour plays into the the distract, divide, and conquer agenda of the establishment. For instance, having more women and more people of colour in government jobs or in the media does little to address the larger issue of the inequalities of wealth and power. And I say this as a female person of colour.

One of the biggest problems with identity politics is that it can mask how politically and economically disenfranchised we all are – and especially for minorities – by giving token victories and token representation in a rigged and corrupt system.

What’s more, the endless “identity choices” we presently have – such as the ever-increasing number of gender choices – can hide, and distract us from, the lack of political and economic choice in contemporary society. For instance, in the United States, there is very little authentic political choice or variety given that the two overwhelmingly dominant political parties increasingly adhere to the same neo-liberal/neo-con political, economic, and foreign policy agenda. In reality, identity liberalism may even protect and excuse the perpetrators and/or perpetuators of this agenda by making heroes and saints out of minority politicians simply because they happen to be a member of a minority group. A prime example is the former Obama administration in the U.S. In his first term as president, Barack Obama and his Secretary of State, Hillary Clinton, continued the war mongering, imperial agenda of the Bush administration but received far less criticism and public outcry – especially from liberals and progressives – for it.

And during the 2016 presidential elections many in the identity liberalism camp insisted that Clinton should win simply because she is a woman. This type of identity reasoning is wholly irrational, apolitical and very dangerous. It divorces the political actions and crimes from the person in question and looks only at their identity. The “logic” is that having a female president will aid the cause and rights of women in the U.S. But what about the rights of the scores of women Hillary has helped to kill via murderous U.S. foreign policy; a policy that claims to “humanitarianly intervene”7 on behalf of people in some countries while completing ignoring or helping to create the humanitarian crisis in others countries (such as the U.S.-backed Saudi offensive against the people of Yemen or in the case of Palestine)? And that’s not to even mention how little Hillary did for the plight of American women during her tenure in politics. There were no policies or initiatives to create a paid maternal leave program, or to provide affordable childcare to working mothers, or help lift single mothers out of poverty. And Obama did even less for everyday African Americans. Where were his initiatives to create jobs for African Americans or reduce the poverty rates in black communities or address the overwhelming presence of drugs in these communities? Ironically, the same politicians that play the identity card do, and care, very little for the members of their particular identity or minority group once in power.

In closing, not only is identity politics or identity liberalism an inconvenient agenda for addressing minority issues, it may be an obstacle to it. Minorities are among the most economically disenfranchised in society, and one cannot begin to address “minority issues” without also critically examining the broader politic-economic factors at play at the present juncture. Indeed, the apolitical manner in which identity politics functions, and its refusal to address class and economic crisis, serves as a convenient diversion and distraction from the larger issues that presently plague minorities and non-minorities alike. These issues are linked to the inequalities of wealth and power and cannot be properly addressed without a broader analysis of class and the growing economic and social devastation wrought by globalisation and Empire. Without this level of analysis, identity politics can offer little more than token victories while feeding into the divide and conquer the agenda of the global establishment.

About the Author

Ghada Chehade is an independent socio-political analyst, writer and performance poet. Her doctoral research won the Award for Best Dissertation from the Canadian Association for the Study of Discourse and Writing (CASDW). She is a contributor on globalesearch.ca. Her emerging areas of interest deal with alternative scientific theories. She blogs at https://soapbox-blog.com.


References

1. Berthoud, R. (2002). “Poverty and prosperity among Britain’s ethnic minorities.” Benefits, Volume 10, Number 1, 1 February 2002, pp. 3-8(6)

2. Best, S. & D. Kellner. “Postmodern Politics and the Battle For the Future” http://www.uta.edu/huma/illuminations/kell28.htm [11/07/04]

3. Petras, J. (1997/1998). “A Marxist Critique of Post-Marxists” Links no 9.

4. Smith, D. (2011). “Rich Nations, Poor People: The Cause For Rising Poverty In The Western World.”https://www.economywatch.com/economy-business-and-finance-news/rich-nations-poor-people.23-11.html?page=full

5. Chehade, G. (March 2017). “Economic Globalization: Global Integration or Exploitation of Global Disparity?” The Global Analyst, Volume 6, Issue 3, pp. 22-25

6. I use the terms identity politics and identity liberalism interchangeably

7. This is a practice referred to as humanitarian imperialism. See Bricmont, J. (2006). Humanitarian imperialism: Using human rights to sell war. New York, NY: Monthly Review Press.

Helsinki – Trump and Putin – a Showdown for Summer Doldrums or a Genuine Attempt Towards Peace?

By Peter Koenig

The Helsinki Summit – or the Treason Summit, as some call it – of the 16th of July, has come and gone. It left a smell of burning hot air behind.

President Trump, opened the meeting by saying that up to now relations between the United States and Russia were bad, and confessing that the US was to blame for it. He wanted them to improve and hoped that this meeting – he indicated that others of similar nature may follow – may be a first step towards normalizing relations between the two atomic super-powers which together, he said, control 90% of the world’s nuclear destructive force. A timely admission, but ignoring the most dangerous and unpredictable atomic power, the rogue nation of Israel.

President Trump, opened the meeting by saying that up to now relations between the United States and Russia were bad, and confessing that the US was to blame for it.

If ever the promising dream-like sounds of Donald Trump of denuclearizing the globe were to see the light of day, Israel would have to be among the first countries to be de-nuclearized – which would be a real step towards world security and peace in the Middle East.

During the later Press Conference, Trump though voicing his appreciation for the ‘fine’ secret services of his country, he admitted that he trusted more Putin’s word on Russia’s non-interference than that of his secret service, “why would they interfere?”, for which he was trashed at home by his adversaries, the MSM, the democrats and even the Republicans. Now, back home, Trump has to accommodate the public, telling them he mispronounced ‘would’; he really meant “wouldn’t”… a first rate spectacle of idiocy that, surely, after a while will go away, as everything does that has no solution, but gambles with dishonesty.

There is no winning in the indoctrinated and brainwashed to the bones American public. It couldn’t be more obvious, how the media are rallying the American people for war with Russia. The greedy military needs war – and the economy of the US of A also needs war to boost her GDP, or rather for sheer economic survival. The topic of Russian interference in the 2016 Presidential Elections, will just not be dropped. After a zillion of proven false accusations, in a reasonable world it would fade away. Not in the US. It is a clear sign of the decline of the empire. It’s the desperate hopelessness of the naked emperor that speaks.

The greedy military needs war – and the economy of the US of A also needs war to boost her GDP, or rather for sheer economic survival

So, they call Trump treacherous towards his country – a President who dares saying the truth publicly is called by the slimy Democrats and the yet slimier Republicans – and foremost by the mainstream media – a case for impeachment.

There is an internal battle raging in the United States. It pulls the country apart. It’s the want of making America Great Again, by concentrating on internal production for local markets, versus the globalized aspirations – the drive for a dollar world hegemony and the full and total subjugation of the peoples and their resources of this globe. The latter will not be possible without an all-out war – and the elite doesn’t really want to live underground perhaps for years in protection of a nuclear fallout nobody knows how long it may last. Trump’s handlers are aware of the alternative, ‘building from within’. Is what Trump is propagating, “America First”, the right approach? – Maybe not, but the concept might be right, given the destitute state of the world, where sanctions and trade wars, also initiated by Trump, are creating havoc among former partners.

A regrouping of nations, aiming at self-sufficiency and selective trading partners according to cultural and political similarities might bring back national sovereignties, abolishing the corporate globalized approach that has been doing harm to 90% of the people. WTO, the monster made by the west to further advance corporate power over the weak, should and would become obsolete.

Trump’s contradictions are what defeats his credibility. He admonishes Madame Merkel for being enslaved by Russia for buying Russian gas instead of the US’s environmentally destructive fracking gas. “We put NATO in Europe to protect you from the enemy, Russia, yet you prefer buying Russian gas than dealing with those who protect you”.

It didn’t occur to any of the European NATO halfwits to tell Trump that all that NATO has done so far is destroying countries throughout the Middle East and the world, and that they, the Europeans, have supported the US in their senseless destruction, creating a flood of refugees which now threatens to suffocate Europe. – There was nothing, but nothing about protection by NATO. If anything, NATO was an aggressive force, moving ever closer to Russia and flanking China on the eastern front. None of this was said, though, by the European NATO puppets.

Trump then goes to Helsinki, meets Putin and says he likes him and he wants to be friends and make peace with Russia. – Of course. We all want peace. But who can believe him, when a few days before he accused Germany of playing into the hands of the enemy, Russia?

Remember, a year ago at the G7 summit in Hamburg, Trump was shaking Putin’s hand and said ‘I like him’. At the recent disastrous G7 conference in Canada, which turned out to be a G6+1 summit, before running off to Singapore to meet North Koreas Kim Jong-Un, Trump dropped a little bomb, “why not converting the G7 again to the G8 and include Russia?” – He left the group stunned and speechless. – So, his drive towards improved relations with Russia is nothing new. It’s just not accepted by the warriors in Washington.

The Helsinki summit looked and sounded like a summer show – just to continue the attention deviation maneuvers of the World Cup that ended the day before in Russia. – What’s going on behind the scenes? – It’s one of those hot summers when nobody wants to think, just to be entertained, never mind the farces and lies – like during Roman Empire times – it’s the modernized Colosseum, adopted to the age of cell phones, tablets and micro-chips. The Colosseum is the all-so transparent veil that should shield the world’s eyes from the empire’s auto-destruction.

Today’s gladiators are the peoples of entire countries, continents, slaughtered or made homeless by the millions, by teleguided missiles and bombs, causing the largest migration streams – by far – in modern history; 70 million worldwide and upwards are on the move. Generations without homes, education; generations without a future, drifting across the seas in desperate hope of survival.

Mr. Putin’s words in Helsinki were words of wisdom, propagating peace as a good thing and dismissing Russian interference in the American elections. Not even discussing the re-inclusion of Crimea. Period. He could have mentioned, instead, the hundreds of elections and regime changes that Washington initiated, manipulated and manufactured around the globe within the last 70 years alone, but he didn’t. Wise man; non-aggression. It is obvious, the “muttonized” world of Americans and European vassals don’t even think that far anymore. For them it’s natural that the ‘exceptional nation’ does what she wants with impunity – but the same rights wouldn’t apply to others.

President Putin handed Trump a list of steps and actions to consider to embark on a denuclearization process. Trump and those of the deep state elite who’s love for life is too great to risk a nuclear war, may just take advantage and do something about it.

The enigma Trump is perfect for the Deep Dark state – he is a roller-coaster of confusion and contradictions. To the NATO members, at the recent Brussels NATO summit, he ordered “pay up, or else’’ – which could mean, or we pull out of NATO. Though that is the desire of a large majority of Europeans, for Trump it’s a contradiction, as he pretends that NATO is supposed to defend Europe against her arch-enemy, Russia. But, then, in turn, Mr. Trump moves on, courting this very “arch-enemy’’, by responding to the peace bells Mr. Putin has been offering ever since he came to power, never a negative word against Washington, calmly calling the demonizers ‘our partners’.

Confused people can easily be taken off-guard and manipulated.

Who knows what the real agenda of the Trump handlers has in store. Trump’s bold statements on the side of President Putin, will make his demonization at home easier. Though the people at large clearly want peaceful relations between the two nations; everybody fears war, but they will continue to be indoctrinated by the CNN-NBC-BBC’s of this world. Let’s face it, after the collapse of the Soviet Union, there was and is no reason to make Putin and Russia America’s enemy. But Putin’s assertiveness in bringing Russia to the fore and onto the world stage again, was a good reason to upset the self-appointed Uni-Power, US of A.

Though the people at large clearly want peaceful relations between the two nations; everybody fears war, but they will continue to be indoctrinated by the CNN-NBC-BBC’s of this world.

The US super-power lives of wars, and this lifestyle requires enemies. Russia and China are ideal, as they control huge land masses with almost unlimited natural resources. They have done nothing of what the mainstream accuses them of. And if the President of the United States annuls the key enemy, turning him from foe to friend, such a President becomes a liability for the swamp of Washington – a liability, indeed – “or else”.

Featured Image:Vladimir Putin and Donald Trump shook hands in Helsinki by Wikimedia Commons 

About the Author

Peter Koenig is an economist and geopolitical analyst. He is also a water resources and environmental specialist. He worked for over 30 years with the World Bank and the World Health Organization around the world in the fields of environment and water. He lectures at universities in the US, Europe and South America. He writes regularly for Global Research; ICH; RT; Sputnik; PressTV; The 21st Century; TeleSUR; The Vineyard of The Saker Blog; and other internet sites. He is the author of Implosion – An Economic Thriller about War, Environmental Destruction and Corporate Greed – fiction based on facts and on 30 years of World Bank experience around the globe. He is also a co-author of The World Order and Revolution! – Essays from the Resistance.

How International Observers Undervalue the Chinese Bond Market

Three-dimensional synthetic works, China's economic and financial stock market

By Dan Steinbock    

Criticism is typical of vibrant international media. Yet, prejudiced biases in financial matters have the potential to harm investors worldwide. The Chinese bond market is a case in point.


Not only is China’s bond market growing explosively, but it has become diversified and provides broad investment options to both Chinese and foreign investors.

However, should you believe the hype, China’s bond era is about to “go through a rough patch” (CNBC), will be “tested by rising defaults” (Bloomberg) and may have “more defaults” in the future (Wall Street Journal). While China bulls might accuse such coverage of being excessive “glass is half empty” reporting, a more substantial problem haunts these briefings.

Essentially, such reports tend to assess the financial future of large emerging economies, which have relatively high growth rates but low living standards, with the same benchmarks as major advanced economies, which are amid secular stagnation but have high living standards.

As a result, such reports systematically undervalue financial futures in emerging economies, while overvaluing those in advanced economies. That’s misleading to investors at a historical moment of transition when financial might is following economic power toward emerging economies.

Low foreign participation as an investment opportunity

Rather than a great one-time opportunity for foreign investors, the low share of these investors in China’s bond market is often portrayed as a major liability. This is then explained by a higher number of corporate bond defaults, a weaker yuan versus the U.S. dollar or technical issues with the bond program that hinder foreign participation.

Here are the realities: not only is China the world’s second largest economy today, but China also has the world’s third-largest bond market, which was valued at about $12 trillion in year-end 2017. Currently, foreign investors own only 1.6% of the total market. That is not a problem, but an investment opportunity, however.

Here’s why: Since the early 1990s, the Chinese bond market has achieved an annualized average growth rate of almost 40%. Just as Chinese industrialization took off in the late 20th century and accelerated in the early 21st century, China’s financial sector is following in these footprints, but with a time lag.

In the West, that may seem like a delay, but let’s put this in context. In the U.S., the Treasury bond market was created as part of the funding plans for World War I. In other words, it took almost 140 years of independence to create the first bond markets in America. In China, the bond market was created in the early ‘90s; barely 40 years after China’s independence – that is, more than three times faster than in the U.S.

Here are the realities: not only is China the world’s second largest economy today, but China also has the world’s third-largest bond market.

It is the historical pace and structural importance of the Chinese bond market to ordinary Chinese and Beijing’s central government that should make it attractive to international investors as well. Here’s why: After four decades of the most rapid catch-up in world history, Chinese per capita incomes, adjusted to purchasing power, are today on average about $18,100; or 30% of those in the U.S. In America, multiple generations have contributed to the bond market; in China, barely one.

Due to the lower prosperity levels of individual Chinese and Beijing’s national growth plan, the Chinese bond market is a priority for the well-being of Chinese families and for Beijing’s economic welfare plans – a priority that now can benefit foreign investors as well.


China’s impending financial expansion               

In the past four decades, China’s economy has grown almost six-fold to more than 12% of the global economy. In the future, that share will continue to expand, as evidenced by the Chinese contribution to global growth, which has been around 30% since the 2008 global crisis. This is about 2.5 times more than its current share of the global GDP.

Relative to its rising economic importance, China’s role in the global financial market was limited until the early 2000s. Financial reforms started with pilot programs a decade ago and have dramatically accelerated, along with the internationalization of the renminbi. At the same time, sovereign paper, which dominated the bond market until the late 2000s, has been augmented by corporate bond issuance, particularly after the global crisis.

Not only is China’s bond market growing explosively, but it has become diversified, which provides broad investment options to both Chinese and foreign investors. Today, it comprises an expansive mix of sovereign, quasi-sovereign (policy banks), sub-government (municipal and state-owned enterprises, SOEs) and corporate bonds.

Not only is China’s bond market growing explosively, but it has become diversified, which provides broad investment options to both Chinese and foreign investors.

The rapid growth of the Chinese bond market is not likely to be exhausted any time soon. By 2020, China is likely to catch up with Japan as the second-largest bond market in the world. But the Chinese bond market has much more space to grow: relative to the $12 trillion economy, the bond market is less than 100% of China’s GDP. This ratio is far smaller than those in major economies. In the U.S., that ratio is closer to 200%. Moreover, China’s population base is more than four times larger than that of the U.S.


Caveats less valid today

Media caveats about China’s bond market focus largely on short-term forces and thus tends to neglect the long-term opportunities, while reflecting dated realities.

After fast appreciation earlier in the decade, a mix of RMB depreciation and rising onshore interest rates did alienate international interest in China bonds, especially after the 2015 correction. However, the fundamentals have changed.

First of all, the RMB trends have largely reversed and stabilized. Second, onshore interest rates are likely to remain around 3.5 – 4% in 2018. Third, the medium-term outlook of the RMB relies in part on China’s impending financial reforms, which are seen as critical to government policies, the middle class and to combat aging demographics. Fourth, the international landscape is signaling constraints of financial developments in advanced economies, due to secular stagnation, aging demographics, lingering growth and productivity. Fifth, trade wars may penalize global growth prospects but are also likely to speed up Chinese financial reforms, which will ensure easier access to the Chinese market for foreign investors.

Finally, while cases of defaults and downgrades in the Chinese bond market have increased in recent years, these have remained under the control of the government, particularly regarding the state-owned enterprises (SOE) and local government subsidiaries (e.g. local government financing vehicles, LGFVs) – which only a decade ago were often portrayed as fatal to China’s economy by a slate of “China crash” theorists.

The Chinese government may even have used some defaults as “demonstration effects” to signal the need for greater budget and market discipline, while the campaign against corruption has enhanced regulators’ grip over potential credit events in the future.

As the gap between media perceptions and investor realities has broadened, many investors have opted to ignore media reports that downplay opportunities, as evidenced by June data suggesting that overseas investors are pouring funds into China’s domestic bonds at record pace, despite what media portray as the “yuan’s jitters.”


Chinese bond market’s international takeoff

The future of Chinese bond market expansion is likely to mimic that of China’s role in the IMF’s reserve currency basket (SDR), which is today 11%. That’s less than that of the U.S. dollar (42%) and the Euro (31%), but more than the Japanese yen (8%) and the UK pound (8%).

Private-sector investors – pension funds, insurance companies and asset managers – remain largely underrepresented.

For all practical purposes, the Chinese bond market is likely to emulate the SDR allocations, which would imply that foreign participation has the potential to grow at least six-fold. Unsurprisingly, central banks and sovereign-wealth funds were the first to participate in RMB following its inclusion in the IMF’s SDR basket.

In contrast, private-sector investors – pension funds, insurance companies and asset managers – remain largely underrepresented. Yet, in the past few years, the likelihood of their entry has been boosted by a number of highly-regarded global index operators that have incorporated Chinese assets into their index space, including the IMF (SDR for global reserve currencies), MSCI (global equities) and Bloomberg-Barclays (BBGAI for global bonds).

It is the critical moments of historical transition— such as the coming explosion of the Chinese bond market as a part of the global bond market— that highlight the importance of unbiased financial observers, investment analysts and the international media.

Unfortunately, it is also such historical moments that are increasingly exploited by those Western geopolitical interests that try to sustain entrenched interests that may no longer be warranted. Such efforts seek to downplay and subdue dramatic changes in the international economic and financial landscape – but at the expense of retail investors, and even institutions, in the major advanced economies, particularly the United States.

About the Author

Dr. Dan Steinbock is the founder of Difference Group and has served as research director of international business at the India, China and America Institute (US) and a visiting fellow at the Shanghai Institute for International Studies (China) and the EU Center (Singapore). For more, see http://www.differencegroup.net/

The original commentary was released by China-US Focus on July 12, 2018.

EDITOR'S PICK OF THE WEEK

China economic growth

China’s Challenging Search for a New Model of Economic Growth

By Danny Leipziger China cannot continue to rely on exports to drive its growth, but what are the alternatives? China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...

WISE DECISION MAKER GUIDE

POWER INFLUENCERS

Emerging Trends

The Future of Global Trade