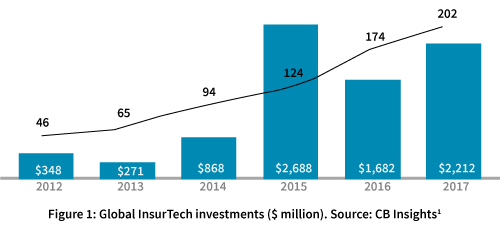Home Blog Page 1065

The European Divorce: How will Brexit Affect People on Both Sides?

The Brexit is one of the most highly contested political events of our time. It is fraught with difficulty, confusion, and uncertainty. When Britons voted to leave the European Union on June 23, 2016, talking heads and political pundits were convinced that the vote would be a resounding no. Instead, what transpired was an historic vote to leave the European Union by a margin of 51.9% to 48.1%. 17,410,742 votes in favour of a Brexit meant that the 16,141,241 votes opposed to a Brexit were saddled with an economic and political quagmire.

According to the results of that decision some 2 years ago, 46.6% of England voted to remain and 53.4% voted to leave. 55.8% of Northern Ireland voted to remain and 44.2% voted to leave. In Scotland, 62% of voters wanted to remain in the EU and 38% wanted to leave. In Wales, 47.5% voted to remain and 52.5% voted to leave. The vote itself was one thing, and there was mass hysteria stirred up on both sides of this prickly affair. The Pro-Brexit camp championed by the Tories got their way, but it didn’t take long before the complexities of a Brexit brought the chickens home to roost.


What issues are making a Brexit for Britain difficult?

EU talks with the UK have been hamstrung by several major obstacles, including what the UK is expected to pay for the right to leave the EU. This is known as the divorce bill, and it covers the UK spending commitments to the EU. Multiple aspects need to be factored in, including scientific research costs, current contracts, and the pensions for government workers across the EU. Fortunately for these bureaucrats, the United Kingdom has vowed to meet these commitments. Other issues include trade and tariffs, given that the European Union is the biggest trading partner of the United Kingdom. Bilateral agreements between these two economic power blocs need to be safely in place to ensure that fair trade takes place.

The rights of migrants in Britain and the European Union need to be factored into the equation. The Republic of Ireland has seen a slew of passport applications in recent months from people in the UK. Since they are scared to lose their EU membership, they are looking to secure Irish citizenship and the coveted passport. Border controls are another issue that are threatening to derail the current Brexit talks. Given that the United Kingdom and the Republic of Ireland are effectively the UK and the EU, the border with Northern Ireland is an important consideration vis-à-vis the single market. If Scottish voters decide to leave Britain this could further complicate matters.


How will international money transfers be affected by the Brexit?

Prior to the Brexit decision, companies operating in the United Kingdom and in the European Union had passporting rights to offer their services to customers in the single economic bloc. Put simply, this means that financial entities like banks, insurance companies, investment brokerages and the like had no foibles regarding transferring funds abroad. The Brexit threatens to derail the smooth processing of international payments transfers. The strength of the euro and sterling are dependent upon economic stability at home. If there is uncertainty in the UK, this means that £1 will buy fewer €1 as weakness persists. This does not bode well for UK citizens wanting to invest funds abroad at a later stage.

On the flip side, EU citizens will likely be pleased with a weaker GBP since this means that they can get more bang for their buck when they convert euros into sterling. The red tape that will likely accompany international bank transfers will add on to the costs of these international money transfers. As such, people on both sides of the equation are looking to fintech companies and non-bank entities to transfer funds. There is a growing sense of urgency among many folks in the UK to send money abroad before sterling depreciates. One of the better performing European countries is France, with the newly elected Emmanuel Macron.

Thanks to these non-bank companies, it is relatively easy to process, UK to France money transfers and safeguard the buying power of GBP now by converting it into EUR. These investments typically take the form of real estate and stock holdings. There are many advantages of shifting assets from the UK to France, including the extensive transportation network which is highly cost-effective in France. Other options include an efficient schooling schedule, and the highest number of paid vacation days in the world with a week off for every 7 weeks worked. For these and many other reasons, France is a highly prized destination for many Britons fearing the worst from a Brexit. Of course, there are some downsides such as a high VAT at 19% and a housing tax of 0.2%. Regardless, those with the money now are looking to shift it abroad at the best rates before the sterling devalues post 2019.

Dr Steinbock Update: Mexico’s Historical Election and Obrador’s Triumph

By Dan Steinbock                                                                        

For decades, the specter of Andrés Manuel López Obrador has haunted Mexico’s ruling elites. After July 1, his coalition triumph – after years of contested elections – could change the country’s domestic, regional, even international policies.


For a year or two, international media touted the neoliberal reforms of President Enrique Peña Nieto. However, as the “reform” narrative has proved hollow, Nieto’s approval rating has plunged from almost 50 percent to barely 10 percent. So the media narrative has been revised it by downplaying Nieto but focusing on the flawed portrayal of Obrador as Mexico’s Chávez who will undermine Mexico’s future.

Perhaps that’s why the Economist portrayed Obrador as “Mexico’s answer to Donald Trump” whose “nationalist populism” offers “many reasons to worry about Mexico’s most likely next president.” Similarly, U.S.-based economic hit men and political risk groups, including Ian Bremmer’s Eurasia Group, have framed Obrador’s popular front as a “significant market risk.”

With few variations, the same narrative has been replicated in leading US dailies (Washington Post, New York Times), weeklies (Time and Newsweek), and the UK-based Financial Times. Theirs is a story about the “firebrand leftist” whose biography is “replete with danger signals.”

What these ideological briefings will not report is that Obrador is neither an overnight phenomenon nor Trump-induced collateral damage. In reality, Obrador’s movement is a belated triumph for Mexico’s popular will, after decades of electoral fraud.


Change is coming

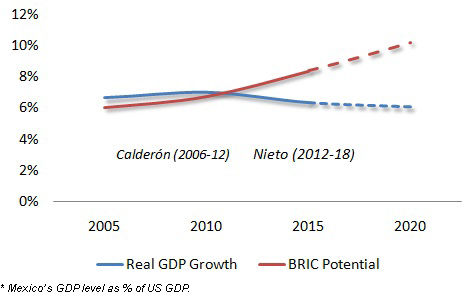
In the past six years, Nieto’s administration has sold Mexico’s public assets to foreign bidders and opened financial markets to speculation, while accommodating loyally Washington’s policies. At the same time, corruption, crime, narco-violence and rising murder rates have soared. While neoliberal elites portray the past decade as that of rising competitiveness, market realities prove otherwise. Mexico’s real GDP growth has fallen significantly behind its BRIC potential during the years of Calderon (2006-12) and Nieto (2012-18) (see Figure below).

But change may be at the door, finally. Obrador’s coalition “Juntos Haremos Historia” (Together We’ll Make History) rests on popular will, not on the needs of the oligarchic economic and political elite, or what Obrador calls the “power mafia.”

Sectorally, he is pushing for the rejuvenation of the agricultural sector. In particular, he would like to develop the agricultural economy of Southern Mexico, which has been hurt by cheap (and tacitly subsidized) U.S. food imports. In contrast to Nieto’s “energy reform” – which ended Pemex’s monopoly in the oil industry and brought foreign investors to Mexican energy markets – Obrador wants a popular referendum over the energy sector, knowing well that many Mexicans oppose are highly skeptical about the sale of national assets to foreign speculators.


Figure Real GDP Growth vs BRIC Potential, 2005-E2020*

After Trump’s inauguration, Obrador published a best-selling book called Oye, Trump, in which he takes a critical look at the American “Caligura on Twitter.” While he is politically too shrewd to challenge Trump head on, he is not an appeaser like Nieto. And unlike Nieto, Obrador also had no hurry to conclude the Trump talks about the North American Free Trade Agreement (NAFTA). Through the election campaigns, he supported the delay of the renegotiations of NAFTA until the elections, to have a say in the final outcome.

Obrador seeks increased spending for welfare, which should be a central political objective in a large emerging economy. He is also a strong proponent of cutting the salaries of the political elite to avoid penalizing ordinary Mexicans. He is willing to walk the talk: he has cut his own public-service salary, several times.

Instead of pushing elite educational objectives, Obrador seeks educational reforms through universal access to public colleges and proposes increases in financial aid to students and the elderly.

Obrador seeks increased spending for welfare, which should be a central political objective in a large emerging economy.

Like President Duterte in the Philippines, Obrador, having served in both Tabasco and as mayor of Mexico City, knows only too well how the ruling elite operates in the imperial metropolis. As a result, he is strongly for the decentralization of the executive cabinet by moving secretaries from the capital to the states – closer to the people that they should serve, further from the lobbies they tend to collude with.

In contrast to ‘law and order’ candidates that in the past have colluded with the drug kingpins, he wants to restore law and order and thus peace and stability, in order to focus on economic development. He might even seek to negotiate an amnesty for the key narco criminals.

Obrador’s platform reflects popular will. That’s why it has been marginalized by the oligarchic elites for decades – even with electoral fraud.


Decades of electoral fraud

Born in 1953, Andrés Manuel López Obrador, often abbreviated as AMLO, is everything but a new force or overnight phenomenon in Mexican politics. Starting his career in 1976 in the then-dominant Institutional Revolutionary Party (PRI) in Tabasco, on the Gulf of Mexico, he soon became the party’s state leader. In this capacity, Obrador saw intimately how PRI’s longstanding political monopoly began to crumble as domestic elites and foreign interests paved the way to Carlos Salinas’s presidency (1988-94).

Following a highly controversial electoral process and reported electoral fraud, Salinas who had been groomed at elite US universities, subjected Mexico to neoliberal reforms, which led to years of economic rollercoaster climaxing with the NAFTA. As a series of other presidents ensued – from Zedillo and Fox to Felipe Calderón and Enrique Peña Nieto – they all promised economic reforms, war against drugs and a better future. Yet, each, despite different parties, shared a common denominator: neoliberal economic policies – which were predicated on the continued embrace of NAFTA, the expansion of cartels, and bandwagoning of US policies.

Those were never Obrador’s political objectives. He resigned from PRI years before NAFTA and joined the Party of the Democratic Revolution (PRD), a social-democratic coalition that was formed after the contested election of 1988. Although early results suggested a clear win to Cuauhtemoc Cárdenas, the corrupt Salinas was declared the new president.

While he is politically too shrewd to challenge Trump head on, he is not an appeaser like Nieto.

In the 1990s, Obrador succeeded Cárdenas. In 1994, he run for Tabasco’s governor but lost to the PRI’s candidate. After the election, a supporter informed Obrador the PRI had spent $95 million dollars on an election in which half a million people voted. In 2000, Obrador became Mexico City’s mayor. After more national exposure, he entered the 2006 presidential election, representing a PRD-led coalition of center-left parties. Obrador’s ‘Coalition for the Good of All’ appeared to be winning until he was declared to have lost by 0.58 percent. That led to a massive, takeover of Paseo de la Reforma and the Zocalo in Mexico City, where protests endured for months.

In the 2012 election, Obrador again represented a coalition of PRD and various labor and citizen movements. However, Peña Nieto’s domestic and foreign supporters took a more proactive stance against Obrador’s popular movement. Despite mass popular opposition to Nieto’s perceived “corruption, tyranny and authoritarianism,” printed and televised media, particularly the pro-Nieto Televisa, downplayed or left unreported much of the criticism. A few years later, Bloomberg discovered that hired Colombian hackers had been paid hundreds of thousands of dollars by Nieto’s PRI to undermine his adversaries and manipulate social media. The election was contested, but despite post-electoral protests, claims of fraud, and Obrador’s formal request to invalidate the election, popular will was discounted – once again.

So Obrador left the PRD and founded the National Regeneration Movement (MORENA) creating his current coalition “Juntos Haremos Historia.” He concluded that to win in Mexico, an alternative candidate needs a broader popular front. So he tailored his platform accordingly. As a result, this time around, his pre-election ratings were almost twice as high as his closest rivals.

While Obrador’s success has been augmented by Trump’s protectionism and immigration phobias, his electoral success in 2018 is the direct result of personal integrity and political resilience.


Toward sovereign Mexico

As Mexicans elected new president until 2024, they also elected 128 members of the Senate for six years and 500 members of the Chamber of Deputies for three years.

If Mexico opts for a new direction, the consequences will be historical in domestically, regionally, even internationally. Not only the White House, but Mexicans may well review the role of NAFTA. Moreover, the drug trade that is maintained by mainly U.S. demand will be under new scrutiny as well. It is time; the cartel violence has taken the lives of more than 200,000 Mexicans.

With more than 122 million people, Mexico is the world’s 15th largest economy and its 11th most populous democracy; a large, emerging economy that could morph into one of the leading global economies by 2050. To win the future, one has to know where one comes from. Having written half a dozen books about Mexico’s history, Obrador is acutely aware of his country’s past, and the territories that were lost following U.S. interventions in the 19th century.

If Mexico opts for a new direction, the consequences will be historical in domestically, regionally, even internationally. 

Unlike his modern-day elite peers, Obrador’s political idols reflect Mexico’s decades of industrialization and modernization. He has written particularly warmly about Benito Juárez who had poor, rural origins but rose to national power and presidency (1858-72). Juárez won the War of the Reform and beat the French invasion. He was not an ideologue, but smart, pragmatic and – when necessary – ruthless. Despite his charm with the masses, Obrador’s nickname is El Peje, which refers to abasco’s freshwater gar – an ancient fish with an alligator’s face.

Ultimately, Obrador seeks economic development. In his world, “Mexico First” would be a poor match with a global economy. Yet, unlike Nieto and the neoliberals, he does believe that a sovereign Mexico belongs to the Mexican people.

Andres Manuel Lopez Obrador (Photo Credit: Raúl Pérez/ proceso.com)

About the Author

Dr. Dan Steinbock is an internationally recognized strategist of the multipolar world and the founder of Difference Group. He has served at the India, China and America Institute (US), the Shanghai Institutes for International Studies (China) and the EU Center (Singapore). For more, see https://www.differencegroup.net/


The original commentary was released by Difference Group on July 1, 2018.

United States Deficits 101

Financial games

By Richard Westra

Beginning in the 1980s the United States transitioned from its position as predominant national economy and workshop of the post-war world to a global economy, dependent on the world for the consumer goods demanded by its populace as tantamount to their “freedom” and for financing of it quadruple deficits, while remaining in the global driver seat due its currency being world money. There are no business-as-usual policy ways out of this morass.


In the aftermath of World War II (WWII) the United States (US) salvaged the international capitalist order by rebuilding it around three poles of prosperity. Erstwhile belligerents Germany and Japan were reconstructed through US beneficence as showcase economies for their regions while the US shaped development in the Americas. Yet, by the 1970s, as Germany and Japan surpassed US industrial prowess, their own multinational corporations (MNCs) now prowling world markets, the US economy became a victim of the very success of the international system it helped create.¹

The first casualty was the international monetary system “contracted” among major economies at Bretton Woods. Two key features of this system had potential conflict of interest written all over them. First, the possibility of maintaining exchange rate stability hinged on the exchange rate of all currencies in the post WWII international system being fixed in terms of the US dollar. The dollar exchange rate was then fixed in terms of gold. Only if dollars were accumulated in excess by this or that country would gold ever be brought into the equation and dollars be redeemed for it. Second, the currency of every country, including the US, was issued as “fiat money”. Fiat money, quite simply, is money issued as legal tender by the state or “created” through credit issuance by commercial banks, based not on anything of real value such as gold. Rather it is based on “high powered” money or government debt IOUs held by the central bank. Only on the basis of fiat money could major economies maintain welfare states and regimes of macroeconomic policymaking.

The US economy became a victim of the very success of the international system it helped create.

Much to its chagrin, as US competitiveness waned, international demands increased to exchange accumulating dollar surpluses for gold. In 1971, the US responded by closing the gold window to unilaterally exit Bretton Woods. But US difficulties did not end there. US waning global competitiveness had domestic origins in declining MNC profits and slowed investment that its casting of blame upon allies disguised. Responding to these travails, the US turned to the fiat money pump. This spurred domestic inflation as it weakened the dollar. According to accepted economic norms, declining international competitiveness is reflected in currency devaluation. In the post WWII order, the International Monetary Fund (IMF) was tasked with smoothing balance of payments deficits of the sort that the US economy began to experience from the early 1970s for the first time since 1891! Yet the US was not just another economy here. With the dollar as world money, combating its domestic recession while simultaneously expanding military adventurism abroad exported US inflation across the globe.²

Chimera of Globalization

As global grumblings about replacing the dollar as hub currency reached a crescendo, October 1979 saw US Fed chair Paul Volcker launch his “coup” raising interest rates astronomically.³ For the US, Volcker’s coup changed everything. First, the interest rate hike halted the inflationary spiral. Second, it dramatically appreciated the dollar in world markets. Third, it restored global confidence in the dollar as hub currency. Lastly, as US interest rates spiked, global money flooded into US dollar savings instruments and dollar denominated assets.

However, for the world economy as a whole and working people everywhere the story turns dark. With MNC profitability and global growth in the doldrums a perverse situation arose where interest rates outstripped rates of profit and global growth, impelling global money not only into US dollar denominated instruments but short term speculative opportunities being engineered on Wall Street and its international satellites. Further, not only in the US but globally, because borrowing turned on the US dollar as hub currency, every class of borrower from individuals to businesses, cities and countries found themselves beholden to creditors like never before. In the US, exploding budget deficits from the late 1970s and early 80s destroyed the social consensus over the welfare state and almost brought the US banking system to its knees.4

For the US, Volcker’s coup changed everything.

Hardest hit were the mass of third world states which had sought to build their own manufacturing infrastructure by taking advantage of the low real interest environment US dollar inflation engendered across the 1970s. Plunged into inescapable debt crises, former “miracle” economies like Mexico and Venezuela along with other borrowers around the world found themselves at the mercy of IMF “structural adjustment” programs enforcing neoliberal norms upon them, purging all of whatever pretensions leaders might have harboured to build national industrial economies. Instead, all manner of development institutions and public investment was exorcized while third world countries were compelled to promote “export led growth” that in practice meant allowing foreign MNCs to reorient economies toward mostly mineral and agricultural export for sale to the wealthy world.

Rapid appreciation of the US dollar against other major currencies worked in the US to price its goods out of global markets. If US MNCs had commenced outsourcing in the 1970s accompanied by a measure of attrition against unionized workers, during the 1980s organised labour was zapped as MNCs disintegrated their production systems disarticulating them across the globe. US MNCs by the 1990s reconfigured themselves as “brands” that didn’t actually make anything. Yet the information and technology (ICT) revolution empowered MNC brands to control global value chains (GVCs) through which goods produced in low wage, weak regulatory third world regimes, tenderized by structural adjustment programs, flowed.

From 1986, Japan eclipsed the US as the number one creditor economy in the world, with its foreign asset acquisitions and net creditor position vis-à-vis the global economy expanding into the 21st century.

With the US writhing in the throes of outsourcing convulsions, Japan in the late 1970s and early 1980s restructured its integrated industrial economy around ICT and “lean” production techniques. Japan’s MNCs also transformed their low value added supply systems by fostering a network of small and medium size subcontracting firms across the East and Southeast Asian region. Where Japan’s MNCs did make major foreign direct capital investments was in the US particularly in automobile production and parts supply. China enters the GVC equation at this juncture as its leaders became increasingly enamoured by the dynamic potential of special economic zones (SPZs) which had been operating with success producing for export to global markets from places such as Taiwan and Malaysia. By the mid 1990s Japan’s technology exports to affiliates in Asia, particularly China proliferated. Japan opened a large trade surplus during the 1980s which rose in tandem with a widening US trade deficit. Still believing during the 1980s that it could resurrect its industrial might, the US hit Japan with Plaza Accords that forced a gigantic appreciation of the Japanese yen. However, this did nothing to impact the US trade deficit that continued its meteoric growth. And, from 1986, Japan eclipsed the US as the number one creditor economy in the world, with its foreign asset acquisitions and net creditor position vis-à-vis the global economy expanding into the 21st century.5

Taking the world as a whole, when one looked statistically at what was going on evidence showed a huge increase in manufacturing taking place in East and Southeast Asia, particularly of ICT products. But this phenomenon has little to do with the previous capitalist drives toward fully integrated industrial economies as occurred in 1970s South Korea, for example. Rather, it was characterised by intraregional movements of “intermediate goods” or sub-products. This peculiar trade flow fed high and medium value added parts and components to China which emerged as the assembly hub and final exporter to the US and world at large. Economies in the region including South Korea witnessed significant jumps in their export dependency ratios. The result of this seismic shift in global manufacturing GVCs was the perverse international “imbalance” where the US represented over half of total global current account deficits with China accounting for almost a quarter of total global current account surpluses along with a third of the US trade deficit by 2007, while the share of the US deficit held by Japan and other Asian exporters ultimately fell.6


United States Transition to a Global Economy  

At the time of the Volcker coup, US policymakers and their ruling class masters certainly had no grand scheme in mind beyond quashing inflation and maintaining global status of the dollar. However, over the course of the 1980s, and certainly by the 1990s, US policymakers came to understand that even if the US abdicated its manufacturing economy, power of the US dollar as world money, anchored in nothing more than government IOUs would serve ruling class interests with a vengeance. The key question was then how such an excrescence might be brought about?

Processes euphemised as globalization where global production is broken down into GVCs which run through Asia, with China as the final assembly hub, was the initial play. Of course, there had to be something in this for advanced economy MNCs. This was concentrating on their “core competencies” such as design, intellectual property, finance, R&D and marketing. Remember, only a few percent of total value of an iPhone, for example, accrues to manufacturing in China. And, to add icing to the cake, MNCs showed spectacular profitability rises with financial gamesmanship buying and selling their own stock. Beaten down third world countries picked up the agricultural and minerals supply slack to advanced economies, much of this processed and marketed by major global MNC brands.7

But for the US, with a bloating trade deficit, swelling government budget deficits due to “supply-side” tax cuts for businesses and the wealthy plus unending US military escapades, this coupled with plummeting national savings due to the fact that working people were forced into debt just to make ends meet, the money had to come from somewhere!

In short, globalization in many ways is really just a sexed up term for the US becoming a global economy dependent upon a world economy it has spent decades remaking.

Step one, for the US, was to use the carrot of its stratospheric interest rates following the Volcker coup and stick of its power in the global economy to compel advanced economy allies to deregulate and liberalize their financial sectors. By 1986 that was largely completed. Wall Street thus became the vortex through which global finance ebbed and flowed. De facto deregulation and liberalization had already been forced upon the third world as a condition of debt relief and access to global credit. Given the predominant position of Wall Street and its international satellites, the short term, speculative casino orientation of Wall Street acted as a surreptitious industrial policy for the world ensuring that MNCs managing GVCs and countries hosting them no longer strived to resurrect integrated industrial economies without suffering the costs of delinking from the global economy shaped by US dollar power.

Step two for the US was to ensure that its dollar and dollar denominated assets never ever fall out of favor. Part of the answer here entails global “dollarisation”. With the dollar as world money states must either sell more than they buy to accumulate dollar surpluses. Or they have to borrow dollars to buy. Another part stems from volatility a global monetary of liberalised financial systems, unanchored currencies and financial activity oriented toward speculation, manifests. Countries are forced to hold US dollars as a significant component of their national reserves to battle back speculative attacks on their currencies. It is this latter point that drew China into the game outpacing even Japan in the purchase of US Treasury IOUs and holding of US dollar reserves. In fact, using the net international investment position (NIIP) which calculates a ratio of global external assets vs. liabilities as a metric to assess what is going on here, by the mid 1990s Japan’s positive balance was a near mirror image of the US negative balance. At the end of the first decade of the 21st century, the mirror image to US negative NIIP was furnished by a combination of Japan’s and China’s positive NIIP.8

The upshot of this is that the US is able to hold the world’s largest gross national debt. And notwithstanding its trade deficit, current account deficit, capital account deficit and savings rate deficit, with the dollar as world money remain as firmly in the global driver seat as it was after WWII when it was workshop of the world. With the dollar as world money the US gains an automatic borrowing mechanism giving it the global policy autonomy. Due to the US current account deficit being essentially financed by savings of the world US government spending on global military domination and other priorities can expand without “crowding out” private sector borrowing. Though the US savings rate has veered to naught borrowing in the US exercises little pressure on interest rates which easily been manipulated to zero. In the end, the US spends well in excess of its domestic savings plus government tax revenues without engendering price inflation.

In short, globalization in many ways is really just a sexed up term for the US becoming a global economy dependent upon a world economy it has spent decades remaking. There is no simple policy exit from this for the US or those countries whose ruling classes bought into it.

Featured Image: Financial games concept by Amankris

About the Author

Richard Westra is Designated Professor in the Graduate School of Law, Nagoya University Japan. His recent books include Socialism in the 21st Century, Unleashing Usury, and Exit from Globalization.


References:

  1. A. Saad-Filho, “Monetary Policy in the Neo-liberal Transition: A Political Economy Critique of Keynesianism, Monetarism and Inflation Targeting” in R. Albritton, B. Jessop and R. Westra (eds.) Political Economy and Global Capitalism: The 21st Century, Present and Future (London: Anthem, 2007) p 93.
  2. E. Altvater and K. Hubner, “The End of the U.S. American Empire?” in W. Vath (ed.) Political Regulation in the Great Crisis (Berlin: Sigma, 1989)
  3. G. Dumenil and D. Levy, Capital Resurgent: The Roots of the Neoliberal Revolution (Cambridge, Mass: Harvard University Press, 2004) p. 69.
  4. Altvater and Hubner, “The End of the U.S. American Empire?”
  5. Richard Westra, The Evil Axis of Finance: The US-Japan-China Stranglehold on the Global Future (Atlanta: Clarity, 2012).
  6. M. Hart-Landsberg, Capitalist Globalization: Consequences, Resistance, and Alternatives (New York: Monthly Review Press, 2013) pp. 31-9.
  7. W. Milberg and D. Winkler, Outsourcing Economics: Global Value Chains in Capitalist Development (Cambridge: Cambridge University Press, 2013).
  8. Westra, The Evil Axis of Finance, p. 166.

Trump’s Tariffs Undermining America’s Economic Future

China and US on trading

By Dan Steinbock

As President Trump is again suspending the opportunity for trade compromise, new US tariffs are not only alienating US allies and partners but undermining America’s own future prospects.


On Monday, US President Donald Trump threatened to impose a new 10 percent tariff on $200 billion of Chinese goods. That will not only re-escalate the trade war with China but contribute to new risks of collateral damage to the US economy.

And make no mistake: While China is the first target; the next ones will include some of the largest trading economies in Europe, East Asia and Americas.


US tech giants will not be immune

US semiconductor chipmakers, including as Intel and Qualcomm, generate $15 billion each in annual revenue in China. The two are amid a great unease as US government is considering tariffs on chips imported from China, which has a critical place in their supply chains.

Due to increasing global interdependency, US unilateral moves are undermining the profitability and future prospects of not just US and Chinese companies, but other companies that are held up by the trade war. While Qualcomm needs China’s approval for its $44 billion buy of NXP Semiconductors, the latter is linked with US relief for Chinese telecom giant ZTE, which Trump supports but US Congress may oppose. That means uncertainty to the Dutch NXP’s workers, suppliers and buyers.

Due to increasing global interdependency, US unilateral moves are undermining the profitability and future prospects of not just US and Chinese companies, but other companies that are held up by the trade war.

The leading global technology companies have an estimated $100-150 billion at stake in the US-China trade war.

For Apple and Intel, China accounts almost a fourth of revenues (read: $45 billion and $15 billion, respectively). In Broadcom and Microsoft each, a tenth of revenues ($9-$10 billion in each) come from China. After Google shut down its Chinese search engine in 2010, it has dreamed about a return. In turn, Facebook’s CEO Mark Zuckerberg hopes to launch his site in the mainland. Trump’s message to both is: Dream on.

The greater is the Chinese segment in US multinationals’ revenues, the greater headwinds they now expect. Boeing’s shares are down, as the US giant seeks for a cut in the $1.1 trillion that China will spend in the next 20 years to buy new airplanes. After all, Beijing could also purchase its planes from France.

How the trade wars will hurt America

The new Trump tariffs threaten to increase barriers to Chinese markets, while alienating Chinese consumers from US products and services, thus penalizing US export potential, investment projects and low-cost advantages.

Without a compromise, US businesses may lose $70 billion in energy, agriculture and manufacturing that China has offered to purchase, if the Trump administration will suspend tariffs on Chinese products. The energy story alone is alarming. When Washington in 2015 lifted its 40-year export ban for crude oil, China’s imports of US crude soared to 450,000 barrels a day. It is now one of the largest US markets. But as Trump tariffs will result in proportionate Chinese retaliation, those profits could dissipate.

Without a compromise, US businesses may lose $70 billion in energy, agriculture and manufacturing that China has offered to purchase, if the Trump administration will suspend tariffs on Chinese products.

In 2017, US exports to China soared to $130 billion. In the absence of a trade compromise, the most lucrative export groups, including civilian aircraft and engines, soybeans, passenger cars and semiconductors, industrial machines, crude oil, and plastic materials, are likely to feel new pressures in the coming months.

China could also defer the huge trade and investment deals that were signed during Trump’s visit to Beijing. As the US is erecting new barriers against Chinese investments in the US, China can respond in kind, while launching restrictions on imports of US services.


The worst is still ahead

Trump’s trade wars have only begun. The White House’s ultimate objective is to target America’s largest trade-deficit partners in Asia (China, Japan, and South Korea), Americas (Canada, Mexico) and Europe (Germany, Italy).

Misled by his trade-hawk advisors, Trump has opted for tariffs that the White House hopes will “break” China’s resistance, which will then serve as a warning to US NAFTA partners and allies in Europe and East Asia. Yet, wishful dreams aren’t economic realities.

That’s also why these countries plan to counter every Trump blow with proportionate retaliation.

What these tariffs could (and should) achieve is a united front of world’s major economies that support global trading regime that has ensured sustained global growth prospects since 1945. That’s why China, along with major European and Asian economies, is likely to challenge the US in the WTO dispute mechanism. That’s also why these countries plan to counter every Trump blow with proportionate retaliation.

In the US, that means accelerated economic erosion, volatility in global markets and new uncertainty as clouds are darkening over the post-global crisis recovery.

About the Author

Dan Steinbock is the Founder of Difference Group and has served as Research Director of International Business at the India China and America Institute (US) and a Visiting Fellow at the Shanghai Institutes for International Studies (China) and the EU Centre (Singapore). For more, see http://www.differencegroup.net


Insurtechs: Threat or Opportunity for Insurance Incumbents?

Hand holding abstract glowing medical icons on blurry interior background. Futuristic concept. Double exposure

By Karel Cool, Christophe Angoulvant and Brian Rogers

The article gives data on global investment in InsurTech ventures and discusses the most common strategies and business models these companies have pursued: technology-upgrade, customer-disintermediation, and transaction-enabling. The models are illustrated with a brief review of three companies: Shift Technology, Cuvva and ZhongAn. The article concludes with a discussion of whether and how InsurTech ventures are threats or opportunities for incumbent insurers.

How large is the InsurTech wave?

According to CB Insights, global InsurTech investment continues to climb. The number of investment deals reached a five year high in 2017 at 202, and the value of these investments at $2.2 billion was up 31% from 2016 (see Figure 1).

InsurTechs have sprung up in many segments, including car insurance (e.g. pay-as-you-drive), home insurance (e.g. intrusion, leakage detection, video expertise of insurance claims), health insurer services (e.g. tele-consultation, doctor appointment booking, health coaching programs) and retirement planning services (e.g. simulation tools such as robo-advisors, video chats). 

InsurTech in non-life insurance

InsurTech disrupters have especially targeted non-life insurance. Figure 2  gives a high-level view of the nonlife insurance supply chain.2 Taking the car insurance supply chain as an example, suppliers include car body shops and towing services. Administration and claims management refer to the back-office handling of policies and claims. Distribution and customer relationship are the client-facing activities performed by a variety of channels, including agents and brokers, call centers, price-comparison engines (such as Confused.com in the U.K.) and the insurers’ own sales channels. Figure 2 also shows where a number of the InsurTech firms have targeted their entry. We discuss below the most common strategies and business models these companies have pursued.

The “technology upgrade” business model

A first type of disrupter model targets some of the upstream activities in the insurance supply chain. The new entrants seek to improve the efficiency of incumbents by providing upgraded technological solutions, such as faster claims settlement (e.g. Snapsheet), machine learning towards fraud detection (e.g. Shift Technology), and data mining and analytics (e.g. Cytora). According to a recent count,3 the large majority of InsurTechs have adopted this model to enter the insurance sphere.

The technology upgrade model tends to be collaborative, generating win-win opportunities for insurers and start-ups alike. For example, Shift Technology, a Paris-based start-up, provides artificial intelligence solutions for insurance fraud detection and automated claims management (see sidebar – Shift Technology). Founded in 2015, the company now has 50 insurance clients and operates in 19 countries. While these InsurTechs disrupt activities the incumbents perform, they can also be valuable partners. Burdened by legacy costs and long overdue automation, traditional insurers have much to gain from working with start-ups in administration and claims management. The long-term competitive advantage of these InsurTechs is based on keeping a technology efficiency edge over the incumbents and continuing to create win-win opportunities.

Shift Technology
Paris-based Shift Technology was founded in 2014 to help insurance companies identify fraud in claims using artificial intelligence and machine learning. The company developed a product, called Force, which identifies in real time possible fraud in the claims that the insurance company receives. Shift claims a hit rate of about 80%, meaning that when insurance companies submit claims to Shift for verification, 80% of the alerts given by Shift are suspicious. The AI engine Force is very effective because it leverages a set of core algorithms that are designed to reveal generic fraud. These algorithms are tailored to insurance contracts of the country where the insurer operates, the insurance category (e.g. car insurance), and the client itself. This enables the development of situation-specific fraud scenarios and thus the effective detection of fraud. Shift claimed to have already examined over a 100 million Property & Casualty claims. It explicitly stated that it did not want to compete with the insurance companies, but to help them automate fraud detection. Shift noted that their processes yield their clients a significant return on investment with some obtaining a return of 900%. The newest service of the company is claims management (automation), which requires a closer cooperation with the insurance companies as effective claims management spans several functions (back and front office). They see great potential in this service as automated claims handling has given rise to more sophisticated fraud schemes. The company’s senior leadership states, “You can’t do automation without strong fraud detection.” The company employs about 100 staff; 70% have a technical background (Data scientists and IT developers), 10% are in sales, 10% in support functions and 10% in project management to support insurers. The staff is comprised of individuals from 25 countries who are proficient in 15 languages. (https://www.shift-technology.com)

The “customer disintermediation” business model

Opportunities for collaboration also exist downstream in the customer facing activities, but the relationship tends to be more competitive. Take Berlin-based simplesurance. As a digital broker, it offers its e-commerce partners a plug-and-play cross-selling digital solution that allows end-customers to buy insurance with just one click. While creating new business for traditional insurers such as Allianz, it also positions itself between the customer and the insurer as a new gateway or tollgate. While there are collaborative benefits in the short term, over the longer-term, simplesurance could become more of a competitor.

Cuvva, the mobile-only insurer from the UK4 is another such a player (see sidebar – Cuvva). Its pay-as-you-drive insurance by the hour is an extension of traditional insurance policies in the UK and as such does not lure away clients from incumbents. On the other hand, its subscription-based car insurance policy, which allows users who pay a minimal monthly fee to top up their insurance when the car is driven, and to switch off this extra payment when the car sits idle, is potentially disruptive for incumbents.

The InsurTechs that pursue customer disintermediation seek to compete by creating additional value, lowering prices, or both, to attract customers. Their long-term competitive advantage is dependent on efficiency, keeping costs low and innovating new customer value. The ongoing value creation actions by Cuvva illustrate this strategy and sustainability imperative.

Cuvva
London-based Cuvva (named after the English pronunciation of insurance “cover”) launched in October 2015. Its founder and CEO Freddy Macnamara needed insurance on an hourly basis so he could drive other people’s cars, but discovered this was almost impossible to do. He decided to start his own company and become a mobile-only intermediary in the insurance market, directly connecting drivers to insurance companies, to address this market need. Purchasing car insurance is something that people often view as cumbersome; therefore, he set out to use technology to make it as hassle-free as possible. Cuvva’s first product, called Cuvva for Sharers, targets customers in the United Kingdom seeking car insurance lasting anywhere from one hour to 28 days. They must be at least 19 years old and insuring a vehicle that is no more than 15 years old. To purchase insurance, users first need to download the Cuvva app. They are then asked to verify their identity and prove they own a valid driving license. Customers must give the app permission to query the database of the UK’s Driver and Vehicle Licensing Agency, which will flag up any potential problems. They must then upload a photo of their driving license, a photo of the car and a selfie taken through the app. Drivers must also state whether they have been involved in a car accident in the last five years. Cuvva then conducts administrative checks, including credit history and criminal record. Once this is cleared, Cuvva issues insurance almost immediately. People who purchase traditional annual insurance policies sometimes complain that they are paying to insure cars that sit idly in car parks or driveways. To address this, Cuvva announced in early 2017 plans to offer Cuvva as a subscription service, a different product aimed at city dwellers who take public transport to work and only use their cars for evening and weekend leisure activities – typically driving fewer than 8,000 km a year. By Cuvva’s estimation, infrequent drivers will be able to save up to US$700 to $1,400 a year compared to what they would spend on a conventional annual policy. While some may find traditional car insurance more convenient, the potential savings may attract many occasional drivers. Cuvva is now pioneering a subscription service for short-term taxi and private hire targeting the people who infrequently offer these services. By June 2017, Cuvva had sold more than a million hours of cover, with customers paying an average premium of about US$9 for the first hour and up to US$27 for a day. (https://www.cuvva.com)

The “transaction-enabling” business model

A new class of InsurTechs, led by Shanghai-based ZhongAn, is embracing a very different vision and business model. Rather than making existing insurance models more efficient, or substituting insurers in their supply chain, they are positioning insurance as a complement to transactions. The emergence of the many platforms with transactions of modest value, and buyers and sellers with short transaction histories, frequently make transaction risk a stumbling block. By offering tailored insurance products at “pocket money” rates, ZhongAn seeks to de-risk and enable these transactions.

ZhongAn’s most popular product has been the Shipping Return Policy. In the Chinese context, buyers are often concerned about the origin and quality of the products they buy. To remove the anxiety of return shipping costs, ZhongAn developed a policy for buyers who wish to return unsatisfactory products, and a policy for sellers to cover the shipping costs of a replacement product. The cost is a mere RMB 0.15–3.3 (€ 0.02–0.4) per policy for sellers, and RMB 0.2–9.9
(€ 0.03 –1.3) per policy for buyers. 

ZhongAn’s business model is similar to the original Google model in web search and transactions. Google’s AdWords and AdSense programs have allowed many millions of people to advertise their products and services at a very small cost to millions of customers, thus enabling transactions. Prior to these programs, similar transactions were much more difficult to complete, as advertising on alternative media was prohibitive for small transactions.

Similar to Google, ZhongAn’s business model has enabled millions of transactions between buyers and suppliers by de-risking the transactions at a very small cost.5 This creates benefits for buyers and sellers, and thus for the ecosystem, which in turns draws in more buyers and sellers, thereby accelerating the growth of the ecosystem. ZhongAn benefits from these positive effects, which is why its own growth has been stellar (see sidebar – ZhongAn Online P&C Insurance Co).

The long-term advantage in this business model is very different from that of Shift Technology and Cuvva. ZhongAn relies on its superior ability to tailor insurance products for discrete, temporary situations and offer the products at very modest premiums. The company analyses vast amounts of data on customer behaviour in different transaction scenarios and customers’ hesitation points in the decision-making process. The company states, “We have broken down the online [car insurance] purchase process into 45 parts, and monitor and analyse data flows from each part. If we notice that users spend too much time in one part, then we know something may be wrong with it, or it has potential to be optimised.”6

ZhongAn Online P&C Insurance Co
Shanghai-based ZhongAn was founded in 2013 as the first mainland insurance company in China to be granted a license for operating without physical outlets. Its principal investors are Alibaba, Tencent and PingAn. ZhongAn has pioneered a very different vision of non-life risks and insurance. Observing that people frequently encounter minor frustrations or “pain points” in daily life (e.g., returning a package by mail, dealing with train and airport delays), ZhongAn realised that many of these risks could be covered by an insurance policy, and that the cost would be minor if each event was priced separately. Insurance could thus become a repeat-purchase product rather than a one-off annual expense. In 2016, the average customer bought 10.3 policies from ZhongAn; the average premium per customer increased from RMB 4.0 (€0.5) in 2014 to RMB 9.9 (€1.25) in 2016. By being embedded in the ecosystems of Alibaba and several other ecosystems (e.g. Mogujie, Ctrip, Didi Chuxing, Xiaomi, Ant Financial and Bestpay), ZhongAn has been able to offer “pocket insurance” to millions of buyers and sellers. The company relies on big data analytics in every step of the insurance value chain, including product development and innovation, pricing, underwriting, risk management, claims settlement and customer service. The billions of transactions allow ZhongAn to collect extensive data on the behaviour of their customers. By observing how these customers behave in particular situations, the company can offer “scenario driven” customised products. By the end of 2017, the company had close to 300 insurance products that it could customise into thousands of insurance solutions, depending on the scenario that a customer faces at any given moment (e.g., flight delay, cancellation, unexpected weather that spoils an event). Its proprietary cloud-based platform, Wujieshan, plays a central role. Product development and deployment across the ecosystems are driven by a staff that consists of engineers and technicians (50%) and those with a finance background (25%). The R&D spending of approximately 6% of premiums written is unheard of in the industry. ZhongAn has achieved spectacular growth, with premiums rising from RMB 794 million (~€100m) in 2014, to RMB 3408 million (~€440m) in 2016 to RMB 5957 million (€760m) by the end of 2017. It has been growing in many insurance segments, including insurance for consumer electronics, consumer finance, travel, heath and auto. Since its IPO in September 2017, the company has achieved a market capitalization of USD 11.5 billion (23 March 2018) on the Hong Kong Stock Exchange. It is still unprofitable. While its claims ratio was roughly in line with industry expectations, its expense ratio remained very high due to the high payments to its ecosystem partners. It is now seeking to go direct to the customer, sidestepping the hefty commissions. (https://www.zhongan.com/corporate/who/?lang=en)

Opportunities for insurance incumbents

Very similar to the relationship between biotechnology startups and large pharmaceutical companies that built a biotech capability, incumbents that build a FinTech capability may significantly enhance their competitive position by selecting from a portfolio of FinTechs.

The burgeoning innovative activity of the FinTechs offers significant opportunities to the insurance incumbents. Disintermediation negatively affects incumbents’ revenues, but it also offers acquisition and partnership opportunities. Allianz, AXA, Generali, Munich Re and Swiss Re have been particularly active. Very similar to the relationship between biotechnology startups and large pharmaceutical companies that built a biotech capability, incumbents that build a FinTech capability may significantly enhance their competitive position by selecting from a portfolio of FinTechs.

The challenge from the transaction-enabling business models to incumbents is different from the technology-upgrade and customer-disintermediation models. As the former is embedded in the transactions of platforms, which often have critical mass characteristics leading to dominance in their ecosystems, it may prove difficult for latecomers to dislodge early InsurTech movers. Moreover, early movers may leverage their position across platforms and ecosystems into a long-term advantage. Incumbents need to analyse whether such transaction-enabling strategies can be applied in the markets they operate and whether and how they can pre-empt the position of transaction enablers. Similar to the field of web and mobile search, where Google built an almost unassailable position – and power, a similar reality may develop in some insurance markets.

About the Authors

Karel Cool (left) is Professor of Strategy and BP Chaired Professor of European Competitiveness at INSEAD. Christophe Angoulvant (center) is Senior Partner and Global Head of Insurance at Roland Berger. Dr Brian Rogers (right) is Research Editor at Swiss Re Institute.

References

1. CB Insights. Fintech trends to watch in 2018. January 2018.

2. C. Angoulvant, K. Cool and B. Rogers. InsurTech is hitting critical mass, INSEAD Knowledge, November 2017.https://knowledge.insead.edu/blog/insead-blog/insurtech-is-hitting-critical-mass-7791

3.Willis Towers Watson – CB Insights. Quarterly Insurtech briefing. January 2018. https://www.willistowerswatson.com/en/insights/2018/01/quarterly-insurtech-briefing-Q4-2017

4. B. Rogers, K. Cool and C. Angoulvant (2018). Disrupting the Car Insurance Industry. INSEAD Knowledge. January 2018. https://knowledge.insead.edu/blog/insead-blog/disrupting-the-car-insurance-industry-8126

5. ZhongAn also provides customer credit, credit insurance and many other services.

6. http://www.scmp.com/busness/companies/article/2131948/big-data-and-ai-future-car-insurance-according-chinas-first

7. Willis Towers Watson – CB Insights. Quarterly Insurtech briefing, January 2018.

Singapore as an ASEAN Asset Management Hub

Singapore, Singapore - January 16, 2015: Singapore skyline at night Marina Bay Sands with Gardens by the Bay in the foreground

By Francis Koh and Boris Liedtke

Singapore like other ASEAN countries is also confronted with the universal challenge of retirement funding. Nonetheless, the authors argue that Singapore can address such headwind through a number of policy changes and that Singapore is uniquely placed to be the premier Asset Management Hub for the ASEAN region.


At a time when many developed countries are rightly worried about the Damocles’ sword of retirement funding for their population, ASEAN countries are not spared. The region’s need to plan and save for an aging population is equally compelling. Singapore may be facing a relatively brighter outlook resulting from its carefully-crafted retirement saving schemes and a well-functioning financial market. Yet, Singapore, like other ASEAN countries, is also facing the exact same quintuple challenges of: (1) increased life expectancy; (2) surging medical cost; (3) lower long-term returns from investments; (4) slower economic growth; and (5) limited options to delay the statutory retirement age. However, Singapore, like other ASEAN countries, can address these headwinds through a number of policy changes, including increased savings, better access to capital markets and enhanced return on investments to provide a larger income stream in old age. We argue that Singapore is uniquely placed to be the premier Asset Management Hub for the ASEAN region and by doing so, assist the entire region to have a more seamless and efficient capital markets, promoting financial opportunities for the individual investor to obtain better returns.


Damocles’ Sword of Retirement Funding

The challenge of retirement funding is universal and is nothing new to the financial and political world. Through ever improving medical and pharmaceutical services, humanity has managed to continuously expand life expectancy in the developed and developing world during the last 100 years. In 1900, life expectancy was 47/50 years (for male/female) in the United Kingdom and the thought of saving for retirement was simply not on the minds of most people. By 1950, life expectancy had risen to 67 years but still merely just above the retirement age. Ten years later in 1960, it had increased to 71 years and continued to creep up to over 81 years around 2015. During the same period, the typical state pension age in the developed world has remained static at 65 years for men. This implies that using the 1950 life expectancy estimate, fund retirement was needed for about 2 years while by 2015, the required retirement funding would be needed for about 16 years, an eight–fold increase over a period of about 65 years..

The glass may be half-empty or half-full. We can consider the need for increased retirement funding as a “threat” or an “opportunity”, i.e. the increased requirement for retirement funding would need business solutions as much as political solutions. Expressing this long term trend in simple terms: an individual has to plan for 16 years of post-retirement funding (from 65 to 81 years old) after a period of working life spanning 48 years (from 17 to 65 years old). That is, two-thirds of our natural life would be working to pay for one-third in retirement.

What this may not take into account is that not only are individuals living longer, they may incur a higher cost of living in the retirement period. Typically, medical costs rise faster than the headline inflation rate. Therefore, there is a need to save even more for retirement. For decades, the health care costs in developed countries have outpaced the inflation rate of consumer goods by a substantial margin. In the U.S.A. during the decade 2005 – 2015, health care inflation was higher than the Consumer Price Index (CPI) every year, except in 2008. The result is that health care costs are adding about another 1.9% per annum over inflation to the need to fund for retirement. This is still benign. But, two trends – higher medical costs and longer life expectancy will interact to spiral over time. Put simply, better medical services are more expensive and thankfully allow us to live longer. As we live longer, the costs for every additional year we add to our life expectancy through better medical services becomes more costly than the previous year. It is estimated that the compounding effect of these two factors requires an additional 5% of retirement funding per year as a buffer

As we live longer, the costs for every additional year we add to our life expectancy through better medical services becomes more costly than the previous year.

Asia and the ASEAN region in particular are not immune from these trends. On the contrary, the need to save for retirement in the region is even more severe than in the developed countries. The current life expectancy in some countries in the region is relatively low but rising and rising fast (See Exhibit 1). .However, the time bomb for the region is ticking in 3 ways. Firstly, life expectancy in the region is improving much faster than it did for the comparable economic cycle in the developed countries. Put in another way, in these countries, life expectancies are improving faster because they are catching up economically and socially rather than just on medical grounds. Secondly, the demographic age structure in the region is skewed towards the “youth” (See Exhibit 2). Hence the much larger young population enjoying improved health care will lead to an explosion of population above all in the retirement age in the coming decades. Thirdly, the costs of medical improvement increasing above inflation will impact these countries just as strongly as the West without having the same level of accumulated savings.

The result of these trends are clear, the region sits on a ticking time bomb that can only be defused through substantial increase in savings for retirement. Yet the instruments for old age provision – both in the private and public sector are still rudimentary in the region with Singapore being the only exception.

The quintuple challenge, which we outlined above, applies to both developed and developing countries alike. Governments need to resolve the severe financial needs of the future. In the developed countries, a wave of changes has come about to lessen the costs for the state and corporations to provide for old age provision. Most notably in the corporate sector there was an increasing shift from “defined benefit” to “defined contribution” schemes and in the public sector simply an increase in retirement age. This has basically shifted the need to save for retirement away from these institutions towards the private individual. Governments have simply encouraged all individuals to take increasing personal responsibilities for their own retirement. In some cases, this was supported by recent legislative changes as in Germany. There is a need to have a more integrated financial industry for individual investors in ASEAN to allow for better retirement investing.

In the developed countries, the shift of responsibility from state to individual is relatively easy because it has a robust Asset Management industry, which can assist private individuals to save and invest through accessible fund management managers and investment products. The private sector infrastructure already exists to facilitate this shift for retirement savings from the public to private sector. The U.S. and European markets offer their citizens a tremendous range and choice of fund products which the Asian and ASEAN markets, in particular, lack. Thus, even if some ASEAN countries were to pass similar legislations to encourage retirement savings, the public would be challenged to find the appropriate products to invest in. There is a crying need for better access to global financial markets and retail investment products. There is a need to have a more integrated financial industry for individual investors in ASEAN to allow for better retirement investing. Hence, we advocate a common platform for the sale and purchase of financial products in ASEAN.


Singapore as an Active Regional Asset Management Hub

The multiple challenges of retirement funding should make all governments interested in planning ahead and regard these challenges as an opportunity and not just a threat. In this respect, Singapore is blessed by a number of unique features that give it a competitive advantage and an important role to create solutions for the region.

Firstly, Singapore has a well-established global financial market. It enjoys an AAA credit rating from all agencies with a stable outlook, with consistent GDP growth rates, low inflation, a stable and solid currency, a current account surplus, sustainable budget finances and substantial foreign reserves, among other attributes. It is and has been a regional hub in certain segments – FX, fixed income, derivatives, wealth management, and lately REITS. Secondly, Singapore has an excellent legal system and financial regulation with good corporate and political governance. Regulations are transparent and clear, fair and open. The financial regulator – Monetary Authority of Singapore (MAS) – is well-regarded.

These last two aspects of Singapore’s competitive advantages should not be underestimated for establishing an active regional asset management hub. Unlike any other financial services, asset management is by far the most long-term focussed. Investment horizon in financial services for trading markets (equities, FX, bonds), advisory (corporate finance, private banking) and retail banking services (cash deposit, mortgages, cash transfer and custodian) are managed in seconds, months, and years respectively. Yet none of them compares to saving for retirement, which can last for 40 years during the pay-in phase (25 to 65 years) and another 20 years for drawing down the funds in retirement. The length of this service means that political and economic stability are key. Put bluntly, there is simply no point in outperforming the market through good investment decisions for 20 years when during the 21st year, there are changes in the investment regulation, tax laws or a currency event to wipe out the accumulated retirement savings. Asset management more than any other financial industry requires stability measured in decades – currency stability, tax and regulatory stability, political stability, and investment stability. Singapore can be the preferred country that can provide this credibly in the region today. Other countries could develop this in the near future.


Towards Establishing a Regional Asset Management Hub

There is a need to have a more integrated financial industry for individual investors in ASEAN to allow for better retirement investing.

By outlining the importance and opportunities which asset management offers as a cornerstone for retirement savings, combined with our list of Singapore’s unique competitive advantages in this sector, we hope to kindle a broader interest to establish a regional asset management hub. However, the hardest part of these efforts is taking the first steps to achieve the end goal. How does Singapore go about establishing itself as a vibrant Asset Management hub for the ASEAN region?

Fortunately, in Europe, there may be another small country to learn from. It is Luxembourg, which has strategically started during the 1990s and early 2000s to become a regional hub without having the benefit of a large national population. Luxembourg, a country of barely half a million inhabitants, is now the second largest asset management market with over EUR 3.7 trillion assets behind only the U.S.A. How did Luxembourg manage to grow from having about EUR 50 billion of assets under management (AuM) in 1988, to EUR 845 billion in 2002 to EUR 3,741 billion in 2016, to become the leading asset management hub in Europe? (See Exhibit 3). What can Singapore learn from this development?

In order to understand the meteoric rise of Luxembourg into the second largest fund management market in the world, we need to distinguish between two phases during which Luxembourg outpaced its European rivals and established its unassailable lead in this sector over other financial hubs such as London, Frankfurt, Paris or Dublin. The starting point was not ideal. Given the small domestic market, Luxembourg was literally irrelevant in the 1980s as a fund management hub. Markets functioned on a “home bias” basis. European funds were conceptualised, established, registered, distributed, and managed on a national basis – German funds in Germany by German fund managers; French funds in France by French fund managers and so on. To grow from a national to a European platform, fund managers had to de facto establish offices in other countries.

Luxembourg, a country of barely half a million inhabitants, is now the second largest asset management market with over EUR3.7 trillion assets behind only the U.S.A.

As a result of the “home bias”, private investors had a limited range of products they could access, which tended to be denominated in their local currency and focussed on the domestic market. So a German private investor would typically purchase a Deutsch Mark denominated Equity or Bond fund invested in German corporations and similar a French private investor would purchase a French Franc denominated fund invested in French companies. If there was any substantial type of global diversification it was through global funds or U.S. funds investing in U.S. based assets. This meant that individuals in Europe actually increased their dependency on the well-being of the local economy. Their jobs, home values, as well as the value of their retirement funds correlated with the well-being of the economy of their own country. Regional diversification through retirement savings was literally non-existent.


Phase One Growth: Regional Distributions facilitated by Domestic Regulations in Luxembourg

RECIPROCITY – all countries were equally positioned and could sell their financial products in each other country.

 The European Union tried to tackle this issue much earlier with incredible political foresight combined with a naïve understanding of the industry. In 1985, the Undertakings for Collective Investment in Transferable Securities Directive 85/611/EEC was adopted (UCITS). This was to allow for open-ended funds invested in securities to be subject to the same regulation in every Member State. So, funds authorised in one-member state could be sold throughout the European Union without the need for further authorisation, moving theoretically towards a single market for financial services in Europe. The concept was based on reciprocity – all countries were equally positioned and could sell their financial products in each other country. However, the reality differed from the desired impact. Countries and their fund industry remained largely domestic. The incentive to suddenly launch a fund by a German fund manager investing in French assets and selling it to Italian private investors, simply had not enough upside to transform the industry. So for a period after 1985, nothing at all changed.

In 1988, Luxembourg became the first country in Europe to translate the European directive for Collective Investments (UCITS) into local law and in the same year established ALFI, the Association of the Luxembourg Fund Industry. Together with a number of foreign and domestic fund managers, a plan was worked out analysing the competitive advantages the market would require to make use of the new regulations. It was now possible to de juro launch a fund in any European member state and through the European pass-porting mechanism to distribute it with hardly any new restrictions. Fund managers were no longer required to open offices in every European country. Nevertheless, no other country or their national fund managers identified the potential for this. De facto, the industry continued in Europe without a change – i.e. it had remained domestic.

Luxembourg realised that more than the European regulatory framework had to change. It became the only country that forged ahead. It identified the need for a domestic regulatory environment in which funds could be:

1. launched quickly;

2. merged or closed upon request; and

3. regulated with liberal investment guidelines.

In respect to the first point, fund launches were becoming more time critical. The industry saw more and more specific product ideas, which it wanted to allow investors to access quickly while the idea was new. Hot investment themes like Tiger Funds, Asian Funds, Emerging Market Funds, High Dividend Funds, etc. – needed to be brought to market while the public was interested in them and while good investment opportunities (“alpha”) were still easily identifiable. However, the approval process for funds in most countries was relatively long and cumbersome. Luxembourg wanted to cut down on the time to launch a product. The financial regulator, CSSF, was staffed accordingly to allow a quick and efficient fund approval process. Market participants could now obtain approval for a new fund within a month rather than the almost 12-months period, which was common in other European markets at the time. This allowed fund managers to react quickly to new investment opportunities and hence provide a better service to their respective clients.

Additionally, the Luxembourg market realised that the industry needed to allow fund management companies to either close or merge funds that had not achieved a critical mass of investors. For a fund manager, launching a new product in Europe was a risky investment decision. Only if the product achieves critical mass by raising sufficient money from clients would it make financial sense. A product that had failed in the market could not be simply eliminated and hence consumed further resources of the fund management company (staff, money, marketing, etc.) for years and sometimes decades. So the product selection process was thorough and highly selective – hence limiting a broad product range. A market that permits more flexibility in closing or merging funds would be welcomed by the industry, as it would allow participants to easily correct failed product ideas. Luxembourg identified this opportunity and corrected domestic regulation accordingly. This allowed Luxembourg based fund managers to take more risk when launching products and then adapt to market reality quicker than in other locations. The alternatives elsewhere forced management companies to continue spending resources on small and unwanted products for years, long after they had become unviable. Consequently, Luxembourg triggered a wave of new investment products that allowed end-investors broader asset diversification.

Finally, the Luxembourg-based market participants realised that investment guidelines for funds needed to be liberal and changeable in a timely fashion. Here again other locations were extremely restrictive and conservative with typical investment guideline changes requiring months if not a full year for approval, if they were authorised at all. This was working against the trend of the financial industry of the 1990s. New products and structured investment solutions were allowing market participants to increase, reduce or diversify risks. Yet most funds could not easily take advantage of these products without going through a lengthy process to change their investment guidelines. Luxembourg identified this and streamlined the process allowing fund managers to quickly adopt their investable universe of assets as and when new products and structures were launched or markets had changed.

As a result of these three domestic regulatory changes, Luxembourg became the first choice for launching new funds in Europe. Above all, the speed to market of a new fund meant that international fund managers could launch a product first in Luxembourg, start its distribution in the whole European Community while still waiting for the approval in their home country, which they would submit in parallel. Soon, Luxembourg investment products became well-known among distribution channels all over Europe and through them to the retail investors.

It was during this phase that fund managers realised the potential of establishing a fund in a single country and distributing it throughout the continent. The regional offices were scaled back to carry out distribution functions and fund managers increasingly used Luxembourg as the launching platform for their products. Hence, the Luxembourg fund industry grew from EUR 50 billion in 1988 to EUR 845 billion in 2002 – a compounded annual growth rate of 22% over one and a half decades.

It should be noted that the firms were not required to shift their investment teams to Luxembourg. Their existing fund manager could remain in the home country of the Fund Management Firm. The Luxembourg-based fund would simply outsource the fund management function to the parent firm where the fund manager was located. This offered the industry a tremendous upside to explore synergies and efficiencies. A single fund management team in Europe could now cover hundreds of millions of potential customers throughout Europe.


Phase Two Growth: Growth of AuM facilitated by a Common Currency in Europe.

After 1988, one of the remaining hurdles that inhibited growth of an integrated European fund market was the issue of national currencies. Even when a Luxembourg Fund could be distributed in other countries, it was necessary to launch it in the respective national currencies. A French private investor was simply not yet comfortable in holding a Deutsch Mark or even less willing an Italian Lira denominated product. As a result, different share classes for each fund in various currencies remained the norm until 2002. Thus, a Luxembourg domiciled fund would have share classes denominated in different European currencies – German Marks, French Francs, and Italian Lira etc. The respective share classes were distributed in the country matching the currency. The funds, thus raised, would be exchanged into the currency of the operating fund where the fund manager would take the appropriate investment decision irrespective of the origins of the funds. So Italian Lira raised through Italian Banks distributing the Luxembourg based fund would be exchanged for USD where the fund manager of a US Equity Fund, potentially based in Germany, would invest in equities denominated in USD. The reverse was true when clients sold units in the fund. While this was not ideal, the model was obviously workable as the consistent growth rate of Luxembourg’s fund industry during Phase One reflect.

The Luxembourg UCITS Model allows retail clients to diversify their investments and to have better access to a broader range of financial products. The model has many advantages for the private investors to meet their growing needs to save for retirement.

Nevertheless, the complicated currency situation often resulted in FX exposure for investors and required currency management to hedge this risk on behalf of clients. Growth of the fund market in Luxembourg could not maintain its pace until the introduction of the EUR as a common currency for the European Community. From then onwards, a fund could be denominated in a single currency (EUR) and the same share class could be distributed throughout the region. The market, then, truly became border-neutral and Assets under Management in Luxembourg grew to over
EUR 2 trillion in 2007 and broke the EUR 3 trillion mark in 2014.

Thus, the Luxembourg UCITS Model allows retail clients to diversify their investments and to have better access to a broader range of financial products. The model has many advantages for the private investors to meet their growing needs to save for retirement. These include:

1. broader range of products, allowing for better asset diversification outside domestic markets; 

2. timely access to new product ideas and new asset classes; and

3. a competitive and efficient market of investment products which often translates into reduced and transparent fees.

Distribution channels throughout Europe have become so accustomed to the Luxembourg fund product that nowadays it sets the European standard. It is hard to imagine that this lead over other markets will be lost in the near future unless a regulatory or political event changes the fundamentals of the industry again. It is worth noting that the compounded annual growth rate (CAGR) of the assets under management in Luxembourg grew substantially faster during the first phase (22%) compared to the second phase after the EUR was introduced (at 11%). While both growth rates were rapid, it is observed that the adoption of a common currency was not the main reason for the growth of Luxembourg as an asset management hub.


Lessons for Singapore and ASEAN

Singapore has a similar opportunity to emulate the success of Luxembourg as an Asset Management Hub and thus benefit the economies of the entire region. The fund market in South East Asia and in particular in ASEAN remains highly fragmented. Each country maintains its independent regulatory environment for its fund industry, which inhibits economies of scale. This means that retail investors throughout the region, are largely limited to locally manufactured products. This is suboptimal for an individual saving for his retirement. It does not provide broader choice, with possible higher investment returns and lower risks. Home-based investing also introduces undiversified risks. It exposes the individual investor to more country-specific risks. If his own country goes through an economically challenging time, both his current wealth and retirement savings are affected.

It is argued that the whole of ASEAN would benefit from a more integrated financial market that allows individual investors to have access to a large variety of investment products, which are easily available through a common platform. Similar to Luxembourg and the UCITS directive, the region should harmonise its fund regulations under a common ASEAN platform through reciprocity, and allow products registered in any particular country to be distributed throughout the region without restrictions. This will give individual private investors in ASEAN access to a broader range of investment opportunities, better suited for their retirement needs.

If reciprocity is available, a saver in Singapore would now be able to invest in a fund which is registered in another ASEAN country and the same for savers in other ASEAN countries.

As an example, the robust REITS industry in Singapore has allowed many private investors to gain easy financial exposure to real estate through commercial, hospital and hotel REITS and ETF investing in REITS, with small amount of funds. What is more important, there are now REITs listed in Singapore, which are investing in real estate assets overseas, in China, Hong Kong, Australia, Europe and U.S This allows individual private investors to have exposure just as easily to the real estate market outside Singapore. These REITS are not easily accessible to private investors in the rest of the region. Typically, they would have to open an account in Singapore with a Bank and the local stock exchange as well as with a broker. Then, they have to transfer money from their home currency to Singapore, change it to SGD and invest. Similarly, when they want to take the dividends back to their country, they would have to access the foreign exchange market and then wire the funds home. All of these incur transaction costs and reduce investment returns. The same goes for access to mutual funds and hedge funds established and marketed in Singapore. Harmonised regulation of the fund industry across ASEAN along a European model of UCITS, will mean better access of the private sector for retirement investments and hence a better position to address the quintuple challenges of an underfunded retirement for the regional population.

At the same time, from the other side of the picture, it is very difficult for an Indonesian or Philippine listed firm to distribute funds in Singapore to access the retirement savings of the Singapore investor. Reciprocity is not available. Only a Singapore-registered fund can be marketed freely in Singapore.

If reciprocity is available, a saver in Singapore would now be able to invest in a fund which is registered in another ASEAN country and the same for savers in other ASEAN countries. This would allow capital in the region to flow to attractive investment products wherever registered. Here the developing nations of ASEAN will have a unique opportunity to see foreign capital in the form of retail savings flowing into their country. The same would be allowed in reverse, retail savings in say Indonesia could now easily flow via the fund industry to Singapore.

Singapore is well-placed to play a role as an Asset Management centre and in close collaboration with the other jurisdictions improve the strategic position of the fund industry throughout the region.

For many countries this would also mean a growth in distribution offices by international fund managers who would now be able to distribute a product locally without the need to maintain an expensive manufacturing office making the investment frequently unprofitable thus inhibiting growth of the industry locally. International fund managers are currently staying away from some of these markets due to restrictive regulations. A regulatory harmonisation will make it financially more attractive to establish marketing/distribution offices.

In respect to the second major development that pushed Luxembourg ahead – the introduction of a single European currency – we see it as highly unlikely that a similar currency might emerge between the ASEAN countries in the near future. National and economic interests remain to dissuade this development. However, this concern should certainly not hold back the attempt to harmonise regulations following the path of Europe. Let us not forget that Luxembourg saw its strongest CAGR in the industry during the first phase even before the introduction of the single currency. There is no reason why this would be different in ASEAN.

A similar initiative is driven by market efficiency considerations, the Asia Region Funds Passport (ARFP) proposal, spearheaded by Australia, Japan, South Korea, New Zealand, Philippines, Singapore and Thailand. The intention here is to establish a regional market for collective investment schemes and to facilitate cross-border offerings between these countries. The ARFP aims to reduce regulatory duplication by establishing standardised requirements for fund operators and benefit investors through access to a broader range of fund products while maintaining investor protection. However, the ARFP is a much bolder plan to bring together a number of very well-established investment and financial markets such as Australia and Japan with South Korea and smaller markets. All of the larger participants have developed local markets and are well connected to the global financial industry. Hence, it may be relatively more difficult for regulatory harmonisation.

 This paper proposes the Luxembourg model for ASEAN, with Singapore as a potential hub. It may be substantially easier to implement than the ARFP. In either case, Singapore is well-placed to play a role as an Asset Management centre and in close collaboration with the other jurisdictions improve the strategic position of the fund industry throughout the region. This will allow for a more integrated ASEAN financial market and better access to investment products for individual investors throughout the region. The end-goal is to benefit the entire region as individual investors and governments are looking for solutions to fund retirement in the years to come.

About the Authors

Francis Koh, Ph.D., CA (S’pore) is Professor of Finance (Practice) and Mapletree Professor of Real Estate at Singapore Management University (SMU) where he is the Founding Director of the MSc in Wealth Management Programme. He is the Faculty Advisor of SMU’s Investment Fund, Advisor of Helvetic Investment and Director of China Taiping Insurance in Singapore.

Dr. Boris Liedtke is Distinguished Executive Fellow at INSEAD Emerging Markets Institute and has over twenty years experience in the financial sector. He was the CEO of the largest bank by assets in Luxembourg and board member for Operations at the largest German fund manager.

Why Cryptocurrencies are not Currencies (yet)

By Mike Seiferling

Over the past few years, the terms ‘block-chain’ and ‘cryptocurrency’ have gained enthusiastic international front-page news and YouTube attention, largely due to the extreme appreciation and volatility in value of the latter (relative to mainstream fiat currencies). With many curious, speculative, and heavily entrenched, first time investors reaping incredible financial gains in 2017, a desire for ‘easy money’ seems to have overtaken the true social objective, or ‘currency’, side of cryptocurrency. Given that ‘cryptocurrencies’ now fall into a wide range of designs and purposes, this note only considers those with a goal of becoming true currencies (as defined below).


The purpose of this short article is to persuade the reader that cryptocurrencies are not true fiat currencies, and, remind readers of the true underlying social benefit from a universally trusted cryptocurrency that will allow everything from small remittance transfers to large international transactions the ability to avoid expensive intermediary ‘fees’ or ‘premiums’.

We can begin with a simple example: Suppose a person were to go out and buy a new car on Friday for 4 bitcoins (where 1 bitcoin = 5000 GBP), and, on Saturday 1 bitcoin was trading at 1/10,000 GBP, that person could have bought two cars by waiting one day. Because of this volatility, in fear of overpaying, it’s unlikely anyone will buy a car any day (unless they can accurately forecast the highs and lows of their currency of exchange). While this example may seem a bit extreme, the volatility of bitcoin over the 2017-2018 calendar year went from a low of 966 USD per BTC to a high of 19,197 USD per BTC. Once price stability can be achieved, a liquid means of exchange should naturally follow as buyers and sellers begin to trust that currency.

Building on this, an optimal currency can be defined as having, at least, four basic characteristics: (i) a store a value (over time), (ii) price stability (over time), (iii) a highly liquid means of exchange with near zero transaction costs, and (iv) the fulfillment of contract upon request. If we consider the US Dollar, British pound, Euro, or Japanese Yen (among many others), these fiat currencies possess all of these characteristics (more or less). If we consider cryptocurrency, (i) and (iv) are satisfied but (ii) and (iii) are not. The chart below should provide readers with some fairly straightforward evidence of why bitcoin (the most basic popular version of cryptocurrency) is not a currency based on our definition (nor are the majority of other cryptocurrencies).

Movement in Indexed Currency Values relative to USD (2017-2018)

The 2017-2018 crypto-hype (seen above) widely departed from what a truly innovative cryptocurrency was meant to be – a means for direct worldwide exchange of a trustworthy currency without having to stumble through expensive middle-people, procedural ‘fees’, and/or, unnecessarily long waiting times, for simple transfers of funds.

In terms of the social benefits, there are countless real-world applications. A simple example, experienced by any unfortunate traveler who finds themselves departing the UK from Gatwick airport for an international flight without having converted pounds into desired currency beforehand, will know that ‘Moneycorp’ will take advantage of their local monopoly on international fiat currency conversions, charging generous rates to convert one currency (i.e. GBP) into another. (i.e. EUR), even if you are only travelling a few hundred miles to buy similar goods and services at similar price levels (in terms of PPP). Competitive commercial banks do not fare much better, often charging processing fees along with spreads for any deposit in foreign currency.

A universally trustworthy cryptocurrency would ensure highly liquid near-zero transaction costs, as long as businesses in both countries were willing to accept/trust that cryptocurrency which possesses the four characteristics defined above.

A universally trustworthy cryptocurrency would ensure highly liquid near-zero transaction costs, as long as businesses in both countries were willing to accept/trust that cryptocurrency which possesses the four characteristics defined above. Effectively, this translates into compliance with conditions (i) through (v) above, where near-zero cost transactions between anyone anywhere at any point in time, to anyone else, anywhere else within seconds of the initial point in time, can occur under a stable exchange rate/price level. Thinking about this in terms of international trade and remittance transfers creates vast possibilities in cutting out costly middlemen/women, which are beyond the scope of this short note.

From an economic perspective, explaining the market value of popular cryptocurrencies is similar to explaining the market value of gold or diamonds – a relatively flat supply, relative to an exponentially increasing demand. The incredible gains experienced by initial participants are followed by a rush of speculative investors, fueling more speculative demand which continues to grow as the masses establish faith in the increasing ‘value’ of that asset, relative to its fixed supply. This type of phenomenon has been demonstrated, at least, as far back as MacKay’s seminal three chapters in “Extraordinary Popular Delusions and the Madness of Crowds” (1841).

From a national accounts perspective, at the moment, cryptocurrencies would, unfortunately, be best classified as, either, a nonfinancial assets (valuable), or, an addition to the category of financial assets: ‘SDRs and monetary gold’ (i.e. ‘SDRs, monetary gold, and cryptocurrency’). For practitioners, these can both, generally, be considered as a speculative store of value over time.

From a financial perspective, the current situation allows for professional investors to take advantage of the ‘pump and dump’ volatility created by an ambitious cohort of newly wealthy investors (QE in major economies has put a lot of liquidity into the global financial system), and, for late entry investors, to lose their shirts (see Mt. Gox for real world evidence of pump and dump).

The original objective of cryptocurrency, to cut out expensive and unnecessary middle-people, cannot be achieved until the price becomes internationally stable.

In short, cryptocurrencies are not yet a currencies because most cryptographer(s) (beginning with Nakamoto 2008) did not integrate fundamentals from long lived fields of accounting, macroeconomics and finance into their White Papers. In order to achieve (ii) and (iii) requires a more active monetary theory type approach where management of cryptocurrencies are continuously governed by the principals of supply (endogenous) and demand (exogenous). Fortunately, this could be achieved via algorithm which preserves the idea of no human intervention, however, would require an underlying asset (or set of assets) by which to benchmark the supply side of that algorithm.

Put more simply, the original objective of cryptocurrency, to cut out expensive and unnecessary middle-people, cannot be achieved until the price (relative to traditional fiat currencies or a well-defined set of underlying assets) becomes internationally stable so that it doesn’t matter what country your hard earned remittances to a foreign relative are sent/received, and; any purchase of a car with your e-wallet doesn’t depend on what day you buy it (or what country you buy it in).

About the Author

Mike Seiferling completed his PhD from the London School of Economics in 2012. He worked as an economist with the Statistics Department of International Monetary Fund between 2011 and late 2014. At present, he is Lecturer/Assistant Professor in Public Finance in the School of Public Policy at University College London (UCL).


The Gig Economy, Gigzombies, and Immigrants

Montreal, Canada - April 29, 2016: A blue and a black balloon are floating outside at a pro Uber rally.

By Anthony A. Gabb

The author tracks key economic forces that have resulted in technological innovations which have given birth to the gig economy that is threatening job security, the gigzombie who is the alienated worker in the gig economy, and misguided anger directed at immigrants.


The gig economy is the future workplace where temporary, unstable employment is commonplace and companies tend toward hiring employees who are all but in name performing the work of permanent workers, but are denied permanent employee rights.

This article explains sweeping changes that have resulted in the gig economy and migration patterns. The gig economy is the future workplace, once associated with less industrialised countries in the 1970s, where temporary, unstable employment is commonplace and companies tend toward hiring employees who are all but in name performing the work of permanent workers, but are denied permanent employee rights. It undermines the traditional economy and will aggravate unemployment, poverty and immigration. The gigzombie is the alienated gig employee, whose vitality has been sapped by rapid technological advancements that are changing the nature of work and increasingly threatening job security. Mr. Doug Scfifter, a New York City livery driver, wrote before he recently killed himself in front of New York’s City Hall, the gig economy “is the new slavery…I am not a slave and I refuse to be one.”1

Since the end of the post WWII economic expansion in the 19702, capitalism has been struggling with slow growth and flat wages. The gig economy, which is driven by technological innovation, is a restructuring response to cut production costs and increase profits. It is not a solution for unemployment and forced migration, yet estimates show that the gig economy will soon account for more than one half of all jobs.3 Capitalism manufactures unemployment which is necessary for its existence. Immigrants are not the cause of unemployment and the gig economy is not the solution for unemployment; they are manifestations of the logic of this system.


Explaining the Underlying Economics Forces of the Sweeping Changes

To understand these sweeping changes in the U.S. and global economies and migration patterns, it is important to understand the economic forces that have brought us to this point. The best explanation of the economic forces that have brought us to this point is the Marxist theory of the accumulation of capital (wealth). The theory assumes that labor is the source of all wealth. The drive for profits gives rise to technological change. Labor and machines working together create more wealth.  However, in order to create more wealth, workers are displaced by machines, which tends to cause unemployment. When the number of displaced workers, plus the increase in population is greater than the number of jobs created, the result is the reserve army of the unemployed (mass unemployment), misery and impoverishment, which triggers migration to places where people think there are jobs. Immigration laws, which are anti-labor laws, are used to manage the ebb and flow of the global reserve army of unemployed, by opening or closing the immigration spigot to make cheap labor available.

To summarise, to cut labor costs and increase profits, capitalists replace workers with machines, thereby producing the reserve army of the unemployed (mass unemployment) which is necessary for its own existence. Capitalists control unemployed workers, who are forced to accept lower wages and poor working conditions. As they move into and out of the workforce, they are used as a lever to discipline the employed to do the same, thereby destroying unions and depressing wages, making it easy to lay off workers without notice and replacing them with gigzombies (temporary and part-time employees), destroying the safety net, and keeping production costs down. In this respect, unemployed workers are as necessary as employed workers for the existence of capitalism. In proportion as wealth increases, unemployment rises, and the levels of unemployment, torment, ignorance and poverty grow. Capitalism is unable to create enough jobs for everyone who wants to work; it manufactures and uses the army of the unemployed, a necessary outcome of the accumulation of wealth, as a tool to perpetuate its own existence, by pitting employed and unemployed workers and native and immigrant workers against one other, making them compete for a limited number of jobs.

The reserve army of the unemployed, the workers’ “graveyard of immiseration and impoverishment,” is evidence that capitalism is unable to deliver sufficient jobs. This system blames workers’ jobless predicaments on them and/or encourages them to blame others, like immigrants. Immigrants are not the cause of unemployment; they are one of the manifestations of the process of production whose natural outcome is unemployment.

In addition to mass unemployment and migration, capitalism creates obscene levels of inequality; the rich get richer and the poor get poorer. Even mainstream “economists are skeptical that the benefits of growth (from the). . .  albeit fragile recovery…will reach working people whose wages have stagnated even as jobless rates have plunged.” “The World Economic Forum. . .  (recent) survey. . .warned of rising economic inequality. . . (and) . . .rising risks . . .adding that they threaten catastrophic consequences for humanity, and for the economy.”4


The Modern Workplace

There have been significant changes as the modern workplace transitions from the traditional forty-hour work week with benefits, to the gig economy, where there is a race to reduce labor cost, and immigrants are targeted and dehumanised. Immigrants remain another instrument of control for the capitalist due to the schism between them and the native workforce. The most important shifts in the workplace include those directly related to automation, and the state’s use of right-to-work laws to dismantle unions as well as restructuring the tax system.

Today, the gig workplace could be virtual, your home, a day-to-day temporary location, an Amazon or Walmart warehouse, driving your car as an UBER or Lyft independent contractor, and to a lesser extent the traditional office. It is a characteristic of temporary and part-time, flexible jobs, without benefits. It undermines the traditional economy of full-time workers who rarely change positions and instead, focus on a lifetime career. Technological innovation gives employers the ability to identify, calculate, and monitor how much you produce whether your office is in your home or somewhere else. In this increasingly automated workplace, machines supplied and used by workers maintain their oppressive function by managing the workplace from a distance allowing employers complete control over workers; as has been said, the machine incorporate and absorb the worker who is the appendage within it and extracts labor power from it. Already more than 34 percent of the workforce is employed as temporary part-time precarious employees and an additional 13 percent wish to join the gig economy.5 Expectations are the gig economy will soon make up half of all employees.

The transition to the gig economy has been advanced by right-to-work laws. Under provisions of the Taft-Hartley Act that require unionised workplaces to become “open shops”, employees must be allowed to work whether or not they join the union or pay dues. This makes it more difficult for workers to form unions. In part, right-to-work laws have devastated organised labor. A study by Cornell University’s, International Labor Relations School, found that wages for union members are generally ten to thirty percent higher than the wages for non-union workers.6 In the absence of union representation, labor costs decrease at the expense of workers, by reducing wages and benefits. These anti-union attacks are also evident in other industrialised countries. While the U.K. government is demanding health care by demanding give backs from workers, in France, unions are under attack from a government that wants to make it easier for businesses to fire employees.

The recent tax law passed by the U.S. Congress and signed by the President, an act of class-warfare that gives $1.5 trillion to corporations and the wealthy, has also contributed to the transition to the gig economy. Many find appealing the opportunity that it seemingly offers to cut taxes for small businesses, and are expected to continue to form independent contractor small businesses in order to take advantage of it. This, however, comes at a cost as employers shift the cost of wages and benefits, once hard-fought for by unions, onto employees.

In search of cheap labor, capitalists reconfigure and control global markets, by war, militarism, and persecution. The best evidence of this is in the Middle East where immigrants fleeing into Europe and elsewhere have become another instrument of control for the capitalist, because of the schism between the indigenous European and migrant workers. These migrants are greeted with physical and figurative walls, xenophobia, and other forms of misguided anger.


Composition of the Workforce

The composition and size of the workforce has dramatically changed due to cost-cutting technological innovations driving the transition to the gig economy. The most important changes include an increase in the reserve army of the unemployed; transitions from union to non-union employees, as well as full-time permanent status to temporary part-time independent contractors, consultants, and freelancers; increased migration; and the widening inequality gap.

The spectrum of the workforce (the proletariat) spans from active employed workers to the mass unemployed (reserve army of the unemployed) to those who have lost their class identity, people who are very poor and disenfranchised, “the lowest sediment of the relative-surplus population”, “vagabonds, criminals, prostitutes…”, (the lumpen proletariat).7 The active employed are distributed among the primary, secondary, and tertiary sectors. The reserve army of the unemployed includes the floating, latent, and stagnant unemployed. While there has been a proportionate decrease in the active employed, there have also been significant increases in the reserve army of unemployed.

The labor market is divided into three sectors of the economy: The primary, secondary, and tertiary. The primary sector includes all non-manufacturing workers in the extractive industries like mining, farming, and fishing; the secondary sector includes all industrial/manufacturing workers; and the tertiary sector includes service workers in the public and private spheres.

The reserve army of the unemployed is also divided into three sectors: The floating, latent, and stagnant unemployed. The floating unemployed is the most mobile group and moves more easily into and out of manufacturing jobs, depending on whether the economy is expanding or contracting. The latent unemployed, generally less mobile, include primary sector workers who migrate to urban areas where they compete with unemployed manufacturing workers. The stagnant unemployed, the least mobile and fluid sector, includes those who are able to work, those who cannot work, like the elderly, the disabled, the sickly, and the single parent households, and “orphans and [poor] children”. As the deindustrialisation of the economy becomes more acute, the floating and latent sectors and misery grow.

The size of the global industrial reserve army of the unemployed is over 1.5 billion. By 2030, not accounting for population growth, an additional 400 to 800 million will be displaced by automation.

Technological innovation has displaced a significant number of workers who have migrated from farming and manufacturing into the service sector, the fastest growing sector both in the U.S. and globally. As this trend continues it will result in an increase in the floating unemployed, especially where jobs are more easily automated, like machine operators and fast food service workers.  Since 1970, the workforce in the manufacturing decreased from 17.4 percent to about 10 of the workforce In the U.S. The supply of independent freelancers, contractors, consultants, and precarious and informal workers will expand.

Over the past fifty years, the number of workers displaced by automation plus the increase in population has far outpaced the number of jobs created, in the U.S. and global economies. The size of the global industrial reserve army of the unemployed is over 1.5 billion. By 2030, not accounting for population growth, an additional 400 to 800 million will be displaced by automation.8  In the U.S. the reserve army of the unemployed increased by over 70 million or 114 percent and globally, the number of unemployed increased by 780 million, or 111 percent. The U.S. population increased by 74 million and the global population increased by over 4 billion.9  These numbers are much bigger than the 47.5 million full time and part time jobs created in the U.S. and 920 million jobs created globally. These changes will all create downward pressure on wages and exacerbate unemployment, migration and inequality.

 As the reserve army increases, the level of poverty increases, proportionately. According to UNICEF, over 22,000 children die every day due to poverty and 1.3 billion live on less than $1.25 per day in extreme poverty. The U.S. accounts for 5 percent of the world’s population and over 20 percent of the incarcerated; over 2 million people, many of them due to the criminalisation of poverty, are incarcerated in the prison industrial complex of the U.S, and counting.10 Fifty percent of the labor force earns less than $27,000 per year and the bottom half of the population has less wealth than the top one percent. Eighty percent is struggling, living from pay check to pay check and the student debt has reached $1.3 trillion dollars.

The evidence shows that the active employed segment of the workforce in the gig economy is increasingly subjected to less than subsistence wages. The U.S. military is the biggest employer in the world with 2.2 million employees, Walmart is the third biggest employer in the world with 2.1 million employees, and MacDonald’s is fourth with 1.9 million employees. Many of these workers live pay check to pay check on sub-standard wages; many of them qualify for food stamps, a subsidy to employers’ profit margins. To add insult to injury, Walmart’s response, in part, is to sell online 13 square foot domiciles for $4,000. Just when you think it could not get any worse, recently Walmart closed sixty stores and 10,000 people lost their jobs; they found out they were fired when they showed up for work and the entrances to the stores were locked, that was the only notice they received.11 Mr. Doug Schifter, the New York City livery driver, wrote before committing suicide “I worked 100-120 consecutive hours almost every week for the past fourteen plus years [only to end up deeper in debt].”12

The role of labor unions is to serve as a voice for employees and act as their representative during collective bargaining negotiations. After peaking at 35 percent (21 million members) in 1979, today union membership in the U.S. is at an all time low, about 10 percent. About 28 states in the U.S. enforce “right-to-work laws” which makes it difficult to form or join a union. As union membership decline, migration, inequality, outsourcing, globalization, and unemployment increase, and wages and benefits decrease. In desperation many workers join the gig economy, while others have been forced into retirement, or slip into poverty. 

The rise in the global reserve army of unemployed which has worsened economic plight, as well as natural and human made disasters (like wars) and persecution, have contributed to increased migration patterns. These migration patterns have impacted economic, social and cultural dimensions in the U.S. and globally. On one hand, what often drives the public discourse on immigration are issues relating to the threat immigrants pose to host countries’ values and customs and that the government should manage immigration against such threats.  On the other hand, a circumspect review of immigration data dispels these myths about immigrants and their impact on the economy and cultural and social values. The truth is that immigrants inject new energy into academia, arts and sciences, and technological innovation.

The rise in the global reserve army of unemployed which has worsened economic plight, as well as natural and human made disasters (like wars) and persecution, have contributed to increased migration patterns.

Contrary to popular belief, “While some policymakers have blamed immigration for slowing U.S. wage growth since the 1970s, most academic research finds little long run effect on Americans’ wages. The available evidence suggests that immigration leads to more innovation, a better educated workforce, greater occupational specialisation, better matching of skills with jobs, and higher overall economic activity. Immigration also has a net positive effect on combined federal, state, and local budgets.”13

Furthermore, immigrants have lower rates of crime than the native-born because they don’t want to risk deportation. Most immigrants do not compete with low wage American workers because they occupy different niches and immigrants often lack English language skills. In addition, while the number of immigrants has increased, the number of murders has decreased in the U.S. Suggesting that contrary to popular belief, at the same time that the number of immigrants increased, there has been a dramatic fall in the number of murders in the U.S.14

Today, over 60 million people have been displaced by wars and natural disasters and there are over 160 million others living outside their countries of origin.15 In 1999, 4 million U.S. citizens chose to live in other countries and in 2016, that number more than doubled to 9 million. Many immigrants no longer see the U.S. as their first destination. In 1978, the U.S. was the first country people chose to move to, but by 2017, it was number sixteen. However, due to heightened economic plight in the less developed world, immigration has continued to shape the U.S. workforce. In 1970, there were 9.6 million immigrants in the U.S., or 4.7 percent of the population. In 2016, there were 43.7 million, or 13.5 percent of the population. The majority of immigrants in the U.S. are from India, China, Mexico, the Philippines, and Canada. Over fifty five percent had private health care coverage compared to 69 percent of U.S. born. Twenty nine percent use the public health care system compared to 36 percent of native born.

Meanwhile, as attacks on immigrants continue, wealth has become more concentrated in the hands of a few billionaire oligarchs. The number of billionaires in the U.S. increased from one in 1970 to 425 today; globally, the number of billionaires increased from two in 1970 to 2,043 today. The richest 42 people on the planet control more wealth than the poorest fifty percent of the world’s population. Over 65 percent of Americans have less than $1,000 is savings; 44 percent of them have less than $400. These repulsive levels of inequality rival the time of the Pharaohs. More and more “Free time…both leisure and time for higher activities,” is saved for the privileged few who engage in creative, fulfilling activities, while the majority of people engage in “alienated labor” just to stay afloat.


Conclusion: “Workers of the World Unite”

The availability of cheap labour as well as high levels of unemployment and the lack of unions in the less industrialised world have maintained and intensified temporary part-time employment that is now trending in more industrialised economies.

The data regarding unemployment, immigration, inequality, and poverty are staggering. Last year in New York City there were over 50,000 homeless children, 1.9 million children living in poverty, and 77,000 people in New York City were homeless. In the U.S. there were over 2.5 million homeless children and between 13.4 million and 16.5 million children living in poverty.16 The U.S. population has outpaced job creation by over 50 million. About 55 million workers in the U.S. are employed in the gig economy, most of them in temporary, part-time, low paid jobs, without any job security or benefits.

The global economy has followed similar trends. The world’s population increased by 3.4 billion and there has been a shift toward the service sector, which is already under pressure from automation. The availability of cheap labor as well as high levels of unemployment and the lack of unions in the less industrialised world have maintained and intensified temporary part-time employment that is now trending in more industrialized economies. More than 3 billion people live on less than $2.50 per day.

Migrant serfs, otherwise known as mostly retired elderly white people, who gave the best years of their lives, now live nomadic lives, in make-shift refugee trailer camps, which they set up serendipitously in the parking lots of big box warehouses where they work; they are constantly chased away by the police. Because their social security checks are generally less than $1,000 a month, they supplement it by working at Amazon and Walmart warehouses, many of them making sub-standard wages in exchange for robotic ten hour workdays. They can be fired without notice and don’t get paid extra if they take longer than the prescribed time to complete their assigned work.

Many of them have said that they work sometimes under horrible workplace conditions without any air conditioning or heating and are made to endure remarks from their superiors (such as “we appreciate you because of your mature work ethic and the example you set for younger gigzombies”). At the same time they are complemented for their work ethic, they are discouraged from talking to union organisers. It has been reported that Amazon warehouses have set up “Li’lMed” stations and Urine Color Charts outside bathroom walls for workers to check the color of their urine to monitor dehydration and to convey the feeling that the company cares about them.17  Recently, Amazon announced that it plans to universalise its “Li’lMed” health care approach. It wants to lower healthcare cost for workers and has plans to revert back to the days of the “company store” when employees depended on employers for everything. It plans to set up its own health care system, at first, to service its employees.  If it is successful, it could metastasise throughout the whole economy, allowing Amazon to privatise and provide universal health care for all of us.

Sadly, these elderly workers, who are made to compete with younger workers who are in their prime working age, have been known to say that they are happy with what they can get, the opportunity to subject themselves to such humiliation. Exhausted, even though they need the money, termination comes as a blessing in disguise, since it gives them recovery time to heal physically and emotionally. Evidently, capitalism not only produces misery and impoverishment, but it has no desire to help those in need. In this respect, the working conditions of the gig economy is reminiscent of the horrible working conditions experienced almost a hundred years ago, in the 1930s, by San Francisco longshoremen; there is a well known example of a reported incident after a 700 pound load accidently dropped on the foot of a longshoreman and broke several bones. Employers placed the worker on the no hire blacklist because they said he had weak bones.18

As economic crises become more frequent and deeper and unemployment, migration and inequality reach dizzying heights, and militarism and war persists, critics have called for a greater role for government. But these trends are systemic and ubiquitous and, as such, a greater role for government and the gig economy that is automated and stocked with gigzombies, are not solutions to these problems. Mass unemployment is a necessary outcome of the capitalist production process. Immigration, globalisation, outsourcing, and the transition to the gig economy are all manifestations of capitalism’s need to re-invent itself. The reserve army of unemployed is, indeed, the “graveyard of immiseration and impoverishment,” and is the necessary outcome of the logic of this system; as such, capitalism continues to produce its own “grave diggers.”

A collectivised system where the fruits of human labour are available to all, will set free the forces of labour for the benefit of everyone, not just a few.

In this respect, there are important lessons to learn from the revolutionary tradition in the U.S. This tradition has a long history that has inspired subsequent generations to demand a world free of misery, impoverishment, exploitation, oppression, and class distinctions. They understood that radical change is not just a thing of the past, but that it requires international solidarity, since the alternative is a life of abject poverty.

Capitalism is an economy driven by profits, which retards the development of humanity; when profit investment ventures dry up, the system shuts down. A collectivised system where the fruits of human labor are available to all, will set free the forces of labor for the benefit of everyone, not just a few. The solution to misery and poverty is international solidarity. The workers, the creators of wealth, want dignified and creative work, with a shorter work week and a livable wage with benefits. While the words of Marx were resounding for the nineteenth century working class, they still ring true today: “A study of the struggle waged by the English working class reveals that, in order to oppose their workers, the employers either bring in workers from abroad or else transfer manufacture to countries where there is a cheap labor force. Given this state of affairs, if the working class wishes to continue its struggle with some chance of success, the national organisations must become international.”19

About the Author

Anthony Gabb, Ph.D. is Associate Professor of economics at St. John’s University, New York. He has delivered and published dozens of papers, a book chapter and a book review. His most recent work, Financial Oligarchy Feudal Aristocracy, was published by The World Financial Review.  His work has appeared in The New York Times, Corriere della Sera, and he has appeared on Chanel 1 New York.


References

1.https://www.facebook.com/permalink.php?story_fbid=1888367364808997&id=100009072541151

2.Robert Gordon, The Rise and Fall of American Growth: The U.S. Standard of Living Since the Civil War, The Princeton Economic Series of the Western World, 2016

3.https://www.mckinsey.com/~/media/McKinsey/Global%20Themes/Future%20of%20Organizations/What%20the%20future%20of%20work%20will%20mean%20for%20jobs%20skills%20and%20wages/MGI-Jobs-Lost-Jobs-Gained-Report-December-6-2017.ashx

4.https://www.nytimes.com/2018/01/27/business/its-not-a-roar-but-the-global-economy-is-finally-making-noise.html

5.https://www.mckinsey.com/~/media/McKinsey/Global%20Themes/Future%20of%20Organizations/What%20the%20future%20of%20work%20will%20mean%20for%20jobs%20skills%20and%20wages/MGI-Jobs-Lost-Jobs-Gained-Report-December-6-2017.ashx

6.https://digitalcommons.ilr.cornell.edu/cgi/viewcontent.cgi?referer=https://www.google.com/&httpsredir=1&article=1176&context=key_workplace

7.Karl Marx, vol. 1, Capital (Moscow: Progress Publishers), pp. 600-604

8.https://www.bls.gov/opub/mlr/2017/home.htm

9.https://www.bls.gov/opub/mlr/2017/home.htm

10.Survival of the Richest w/ Donald Jeffries – YouTube

11.https://www.truthdig.com/videos/companies – like – amazon – exploit – itinerant – elderly – workers – lost – great – recession – video/

12.https://www.facebook.com/permalink.php?story_fbid=1888367364808997&id=100009072541151

13.http://budgetmodel.wharton.upenn.edu/issues/2016/1/27/the-effects-of-
immigration-on-the-united-states-economy

14.https://www.truthdig.com/articles/fascist-underpinnings-trumps-state-union/

15.https://www.ukessays.com/essays/cultural-studies/migration-in-the-era-of-globalization-cultural-studies-essay.php

16.https://www.unicef.org/publications/files/UNICEF_SOWC_2016.pdf

17.https://www.truthdig.com/videos/companies – like – amazon – exploit – itinerant – elderly – workers – lost – great – recession – video/

18.WBAI Letters and Politics, 1/10/18, Peter Afrasiabi https://www.wbai.org/archive.php

19.Karl Marx, International Workingmen’s Association 1867, meeting on June 4, 1867 the General Council, On The Lausanne Congress

Insurance Disruption and the Return to a Purpose-Driven Business Model

Insurance technology (Insurtech) concept, woman looking data information on smartphone.

By Amy J. Radin

With the accelerating speed of change brought by technological advancements, how will insurers sustain their purpose at the same time deliver shared value that supports economic returns as well as the well being of society? In this article, the author elaborates on these challenges facing the industry and presents some pragmatic c-suite actions to integrate into 2018 priorities.


Any leader in any company who sees a future for their business and career is feeling the pressure to innovate, find new ideas and business models, and create enduring client value that adds to the bottom line and strengthens the balance sheet. There is no one formula or set process to find and execute the ideas to achieve these goals. Clients set moving targets. Shareholders are unforgiving and demanding. Regulators are wary of new risks. Society expects companies to care about much more than the bottom line and to behave with authenticity.

The fast and furious forces of change stimulated by technology, demographics, lifestyles, and economic, environmental, political and regulatory impacts – or any number of these in combination – are easy to see. The question, “WWAD” – “What would Amazon do?” seeds an uncomfortable conversation happening inside corporate conference rooms. The answers are easy to intellectualise. The problem? They are hard to translate into results that matter. Execution takes new, nuanced combinations of leadership, skills, strategy and tactics. Innovation has moved from an abstraction that will matter at some distant date to a front-and-center deliverable that must show evidence of impact in the space of the calendar quarter.

The insurance sector is a self-confessed laggard when it comes to internalising and getting out in front of the speed of change. The underlying business model has not been challenged since demutualisation-induced disruption at the beginning of this century.

Innovation has moved from an abstraction that will matter at some distant date to a front-and- center deliverable that must show evidence of impact in the space of the calendar quarter.

While insurance carriers have been late to the innovation arena the possibilities of business model disruption have gotten increasing attention and investment beyond the incumbent players. Not surprising, as entrepreneurs and investors in search of mega-opportunities see insurance as a $5-trillion sector (premium dollars)1 that has stubbornly resisted change while sectors as wide-ranging as media, entertainment, retail, telecommunications and travel have been shaken to their roots by new entrants serving markets in new ways. Insurance today is a unique profit pool – massive, global, diverse and adhering to legacy business approaches – where the opportunity to create new sources of value and growth is difficult to achieve, but where there is room for impact.

Self-reinforced moats have shielded carriers: the sheer complexity of underwriting, policyholder management and communications, capital requirements, hydra-like distribution systems, and low consumer enthusiasm for the category. No surprise that products historically have either been mandated, or pushed by commission-driven sales processes.

According to Venture Scanner2 there are close to 1500 insure-tech startups seeking to change the sector. Since 2015 there are signs that the rate of growth in investments has continued to increase but at a slower rate. CB Insights reports that strategic investments by (re) insurers have shifted beyond the U.S. towards a more global footprint, particularly Germany, France, the UK and China.3

Innovators are experimenting in retail and commercial, in property & casualty, health, life and retirement lines. Solutions aim to do everything from replacing the traditional, intermediated model for distribution with digitally-centered direct to client alternatives, to new capabilities that automate elements of the value chain, and apply new data sources to underwriting, empowering either carrier or client with more knowledge.

Opportunity or threat, depending upon one’s position, is everyplace.

Safe bet that the technology is here or will be here soon enough to transform every element of the insurance value chain. But acquiring the technology is the easy part.

A more fundamental question faces the industry’s c-suite, which must be answered to frame the daily, short-term decisions that are creating the future, intentionally or not. It is the question of purpose.

As data analytics and technology capabilities move us into a world where risks can be underwritten, carriers may choose to skim within certain risk pools, pricing higher and risking people towards unaffordability.

Evidence of risk pools can be found even 5000 years ago, when shippers devised pools to protect against loss of cargo and crew at sea.4 The sector’s genesis and ongoing reason for being was the notion of the community contributing to a common fund from which many would not benefit, while the few would be protected in their time of need.

Even as insurance companies have introduced new products, brands have come and gone, and other aspects of the business have evolved, the basics have not changed – the creation and management of a risk pool that is sufficiently durable to pay claims over time, and engagement of a broad community of individuals to feel that their interests are served by participating.

But as data analytics and technology capabilities move us into a world where risks can be underwritten not just down to the level of individuals, but at the level of moments in their lives, carriers may choose to skim within certain risk pools, pricing higher and risking people towards unaffordability.

Signals of this exist today. Usage-based insurance (UBI) products, such as those offered by Metromile, Progressive and Allstate surface knowledge about an individual that allows policy tailoring to individual driving behaviour. UBI disrupts traditional risk pool principles. And, it is hard to imagine that UBI won’t hurt those with less favourable profiles. The full consequences to society may not be examined or understood until out into the future, but they are brewing.

In May of 2017, the New York Times carried a headline: New Gene Test Poses Threat to Insurers. The article described how data transparency and availability are disrupting underwriting for long-term-care insurance in the U.S. Challenged for years by inaccurate claims,forecasting and sky-high pricing, long-term care coverage faces further threat of adverse selection at a time when the population is rapidly aging and people voice greater concern about living too long – not dying too soon.

Carriers should take note that as innovators such as 23andme, with no stake in the legacy business model, create data asymmetry between a policy buyer and the carrier, the advantage flips to the buyer. With a $199 investment, all of us can now make more informed decisions about which risk pools we may fall into. Over two million people have already purchased a test kit, with broadcast media rolling out to scale adoption. Analogous use cases are certainly possible in other insurance lines.

The question is: Will insurers find a path to sustain their purpose under rewritten assumptions, and deliver shared value that supports economic returns as well as the well being of society? Insurance plays a role in our collective and individual wellbeing, and must find the balance between generating bottom line and social returns contributing to a sustainable future.

Pragmatic c-suite actions to integrate into 2018 priorities starting now:

• Do the work to reaffirm purpose. Efforts must be authentic, heartfelt and seen as the basis for action – not a slogan, not a project delegated to Human Resources, Marketing or Corporate Communications. Signals that this is happening well? In every meeting where decisions are being debated and driven, people are aligning those decisions to the purpose, not trading it off, and working hard to find the answers to living the purpose based upon a strong operating and financial foundation.

• Engage in serious experimentation to find the feasible paths to implementation. Take lessons from the startup world: First, have passion and make the leap of faith that these paths exist. Then, embrace hands-on iteration. Prototype and test concepts – including product, client interaction, distribution, servicing, underwriting and claims management – in other words, seek to challenge and redefine the major operating levers of the business.

• Be ready to invest in the workforce, culture and capabilities in ways that respect the great legacy upon which the sector has thrived for centuries. Acknowledge in word and action that it is time to achieve far greater talent diversity, and move from silos to a culture defined by collaborative behaviour, open communications, and a willingness to innovate.

Insurance reinvention is not a technology or data problem. It is a challenge that requires leaders to rethink purpose and then drive purpose into strategy, culture and execution, setting aside established notions of what works, and focussing more on what matters. Technology is an incredibly powerful enabler.

The floodgates are open and conditions demand reinvention. Any insurance player who thinks “this too will pass” or regulations will provide full protection may be able to buy time for a while. But chances are their business is already being disrupted and is ready for reinvention.

About the Author

Amy J. Radin is a recognised Fortune 100 Chief Marketing and Innovation Officer, advisor and investor, board member and thought leader. She delivers innovation for sustainable, business-changing impact. She has been at the forefront of how to rewire brands for value and growth, building a track record successfully moving ideas to performance at Citi, American Express, E*TRADE and AXA. Amy’s first book, The Change Maker’s Playbook: How to Seek, Seed and Scale Innovation In Any Company, will be published in Fall 2018.

References

1. https://www.plunkettresearch.com/statistics/Industry-Statistics-Insurance-Industry-Statistics-and-Market-Size-Overview/

2. https://www.venturescanner.com/blog/tags/insurtech%20company%20list

3. https://www.cbinsights.com/research/report/insurance-trends-lendit-2017/

4. https://finance.zacks.com/risk-pooling-insurance-1890.html


How TIME’s Bremmer Got Duterte Wrong

Currency in the Philippines

By Dan Steinbock

Today, global dominant media is often exploited as a tool of coercive diplomacy. The recent Time commentary on the Philippines president is a case in point. The real story is behind the story.


In early May, Time magazine released the feature story, “The Strongmen Era,” by Ian Bremmer, the venerable president of Eurasia Group. The cover featured the photos of Russian President Putin, Hungarian Prime Minister Urban, Turkey’s President Erdogan, and Philippines President Duterte. It was a promotional piece for Bremmer’s new book on globalization. As Duterte reject the term “strongman,” Bremmer penned a new attack.

Bremmer’s arguments are neither original nor deep. What makes them different is that the Eurasia Group is very close – too close, say critics – to U.S. economic, political and intelligence power, including the famed military-industrial complex, along with his role as Time’s editor-at-large and global affairs columnist.


Flawed data, compromised sources

In his sequel on Duterte, Bremmer relied largely on just a single report by Human Rights Watch (HRW), which he considers “highly credible.” Yet, the HRW has lost much of its reputation. Billionaire speculator George Soros has had leverage over HRW since the ‘80s. In 2010 Soros cemented the ties with a 10-year $100 million HRW donation. Since then, HRW’s record has been tarnished by allegations of partisanship and bias, which climaxed in the 2014 open letter by Nobel Peace Laureates criticizing HRW for intimate ties with the US government.

Moreover, the head of HRW’s Asia Division Phelim Kine continues to inflate data in reporting on the Philippines anti-drugs campaign; and Bremmer uses this flawed data without slightest source criticism. Relying on HRW, Bremmer blames Duterte for “sending anyone to jail for criticizing him,” yet the examples he comes up with are Senator Leila de Lima and Supreme Court Chief Justice Maria Lourdes Sereno.

In reality, de Lima is imprisoned for receiving substantial payola money from drug lords, abusing public office and paying off confidants, while serving as Justice Secretary in the former Aquino administration. In turn, Sereno, another Aquino appointee, got her office, thanks to partisan politics, but not to credentials, and she was ousted after grossly abusing her office.

Relying on HRW, Bremmer blames Duterte for “sending anyone to jail for criticizing him,” yet the examples he comes up with are Senator Leila de Lima and Supreme Court Chief Justice Maria Lourdes Sereno.

Finally, Bremmer relies on “international rights organizations” and UN officials that Duterte has tried to “harass and intimidate.” In reality, the Duterte government invited UN Special Rapporteur Agnes Callamard – who has been supported by Soros in the US and the UN – to a public debate, yet Callamard sneaked into Manila for a lecture at the request of Chico Gascon, a veteran Liberal Party leader, who promotes the misguided views that Bremmer takes for divine truths.


Links with the Philippine failed liberals, and Malloch-Brown (Soros)

The common denominator in all these cases is the ongoing meltdown of the Liberal Party (LP), which Washington has relied on in the Philippines since the late 1980s, despite the party’s internal decay. Human rights is the pretext in a geopolitical effort to corner the Duterte government, restore the LP and its special ties with the US.

Bremmer’s Time debacle is the latest in a long series, which began in May 2016, when he warned in the New York Times that “The Philippines Has to Know It Needs the US.” The Philippines needs Chinese infrastructure investment, but “if you deal with China without us… That will be bad for you and your country.”

And yet, as Duterte has recalibrated Philippines ties with the US in security and with China in the infrastructure, the country is positioned to grow at 6-7% annually for years. These realities are fully ignored in Bremmer’s pieces for Time, along with Duterte’s democratic and huge popular support – and by other global media that failed to report on the darker side of the Aquino era, its massive graft, proliferation of drugs, and high-profile corruption debacles.

And yet, as Duterte has recalibrated Philippines ties with the US in security and with China in the infrastructure, the country is positioned to grow at 6-7% annually for years.

In contrast to Nobel critics of human rights’ political exploitation, Bremmer’s case rests on HRW and Soros, who he deems the “advocate of liberal Western democracy.” Yet, the two may share more prosaic common interests. In 1998, the Financial Times reported that Soros’s commentary on the need for Russia to devalue its currency precipitated the country’s massive default on debt, which was created by Prime Minister Sergey Kiryenko’s cabinet. That’s also the year when Bremmer founded his consultancy which has advised Kiryenko, according to his own bio.

Moreover, the Eurasia Group is linked with Soros through Lord Malloch-Brown, the controversial chairman behind the election technology Smartmatic – which has caused political debacles around the world, including the Philippines – who has served as vice-chairman of Soros Fund Management and the Open Society Institute. Since 2016, Lord Malloch-Brown – who has been a longstanding advisor of the Aquinos and the Liberal Party – also became Senior Advisor of the Eurasia Group.

None of these associations were disclosed in the Time commentary.


Links with the White House and US intelligence community

Specializing in the former Soviet Union, Bremmer got his PhD in Stanford in 1994. The young policy wizard proved influential in think-tanks that work with, for and by the US government, multinationals and Wall Street. He founded Eurasia Group in the late ‘90s when the US pioneer of geopolitics Zbigniew Brzezinski used to warn that American hegemony can only survive if the US can dominate Eurasia and deter future rivals – such as Russia and China.

As the National Security Agency (NSA) intensified efforts to shape US foreign policy in the early 2000s, along with the State Department and Pentagon, its leaders listened Bremmer about oil, natural gas, terrorism and Iraqi reconstruction. The Group’s CEO is Robert Johnston, an energy specialist, who used to serve in UBS and Enron. Its head of research David Gordon has served in the highest posts of the CIA and the State Department. Evan Medeiros was recruited in fall 2015 to head the Group’s Asia branch. As Obama’s top advisor on the Asia Pacific, he was responsible for coordinating US policy toward Asia, including “modernizing” key alliances, such as the US-Philippines 10-year defense agreement.

He founded Eurasia Group in the late ‘90s when the US pioneer of geopolitics Zbigniew Brzezinski used to warn that American hegemony can only survive if the US can dominate Eurasia and deter future rivals – such as Russia and China.

There is nothing wrong about hiring the “best and the brightest.” But a revolving door between the government and the private sector comes with huge moral hazards. If the two are not kept in arm’s length, collusion becomes viable and political risk consultancies operating in the private sector risk morphing into arms of the government. That’s precisely the kind of “statism” – centralized state control – that Bremmer purports to oppose.

The original version was released by The Manila Times on May 21, 2018.

Featured image courtesy of: NOEL CELIS—AFP/Getty Images

About the Author

dan-steinbock-webDr. Dan Steinbock is an internationally recognized strategist of the multipolar world and the founder of Difference Group. He has served as research director at the India, China and America Institute (USA) and visiting fellow at the Shanghai Institutes for International Studies (China) and the EU Center (Singapore). For more, see https://www.differencegroup.net/

EDITOR'S PICK OF THE WEEK

China economic growth

China’s Challenging Search for a New Model of Economic Growth

By Danny Leipziger China cannot continue to rely on exports to drive its growth, but what are the alternatives? China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...

WISE DECISION MAKER GUIDE

POWER INFLUENCERS

Emerging Trends

The Future of Global Trade