Home Blog Page 1048

Blockchain, Poverty and Time Travel to 2030

By Namira Samir

We all know the story. Government made a forecast of its expenditures and revenues in every fiscal year; Government disbursed the funds, poverty rate decreased, income inequality stayed volatile. Everything was in balance until the UN announces SDGs (Sustainable Development Goals, a joint agreement to make the world in its best possible form by 2030, without a single person living in less than 1.90 US Dollar a day. Now policymakers have been craving for a solution to realise this demanding goal. Blockchain quickly intrudes into the life of many, including those sitting at the highest level of leadership. Sadly, many would think of it as a trivial revolution. Will time change our mind?


UN set an ambitious goal for year 2030, one of which is to completely eliminate poverty in its multidimensionality. The 193 member states concurred the agenda and adopted them since the year 2015.

Despite agreeing with this collective objective, Indonesia encounters tremendous challenges in tackling deprivation. It is, as we all aware, a home to diversity. Its population are divided into five main islands which encompasses 34 provinces with distinctive livelihood activities subjected to socio-economic conditions in that particular area.

Poverty, which happens to be the result of inability to fulfil basic necessities, is influenced by access to opportunities. Deprived households in regions with extreme distance from populous cities which have been associated with persistent growth tend to have far less opportunity for improvement.

Economics 101 would tell us that there are two main approaches on how a country can address poverty; macroeconomics and microeconomics. The former stresses on how external factors such as inflation, consumer buying power, and declined economic growth would cause turbulence that only makes the poor worse off. Meanwhile, the latter looks at poverty alleviation strategies from the internal capacity of the household. How deprived households can meet their basic needs.

Being in a constant battle with poverty, Indonesia has implemented a range of programmes and investments that derived from both macroeconomic and microeconomic approaches aiming to win the war of poverty. It invests heavily on infrastructure, with the planned budget for 2019 415 trillion rupiahs and the cumulative allocation for infrastructure, poverty and unemployment increased from Rp.1,343.1 trillion (2017) to Rp.1,454.1 trillion (2018)1.

Yet, the result of the assumed “pro-poor budget allocation” was not so favourable, with the latest data informs that poverty merely declined by 0.16 points from 9.82% (Mar 2018) to 9.66% (Sep 2018)2. With simple math, we know what this implies; Indonesia, if continuing the current ways of alleviating poverty, will be nowhere near the SDG 1 (No Poverty)3 by 2030.

Increased State Budget for poverty alleviation means nothing if there is no significant improvement on the livelihood conditions of the poor.  They have been waiting for opportunities to directly knock on their doors and said “This is the way out. We will guide you through the process and we will make sure that your family will be better off afterwards”.

The limitations of the Government State Budget suggest the need for new collaborative approach among communities to ensure that those who are poor can live in physical and spiritual prosperity, and acquire the same opportunity and benefit from growth,

The conventional way to address poverty is just like a one-man show, in which the Government happens to be the sole Actor, and its citizens are the audience. Whatever the Government says or do with its performance will determine its audience’s conditions. They might be happier, sadder, or perhaps remain unchanged with the performance.

But we must never forget to include the initial condition of the audience into our estimate. Some might come to the show with enormous happiness or extreme sadness. If the purpose of the show is to make everyone feeling satisfied, how can the Government resolve this inequity of emotional state and make everyone happy? Is it possible?

Happiness in this matter is in relation to having sufficient capabilities to make ends meet. The Government employs various instruments to make sure that its performance touches the lives of many, most importantly, the unfortunate.

The limitations of the Government State Budget suggest the need for new collaborative approach among communities to ensure that those who are poor can live in physical and spiritual prosperity, and acquire the same opportunity and benefit from growth, just like what is articulated on the Article 28H of the 1945 Constitution of the Republic of Indonesia4.

But the question is, how do we channel these resources and deliver them right away to the door of impoverished households?

It’s time to re-read the first paragraph.

Kate Raworth in her widely read book “Doughnut Economics” emphasised the need to look out for better ways of ending poverty. We must not be trapped in century years old strategies and instruments that will only make the prominence such as the SDGs merely a remark of ‘good progress’, and not an ‘incredible achievement’ in the development sphere.

The CAF World Giving Index 20185 lists Indonesia as the most generous in the world. This achievement must be seen as an opportunity to use our inner good deed to help others. The problem is that there was no scheme that allows us to help with our abilities, until blockchain enters.

With the blockchain technology, transfer of wealth and the ability to help each other becomes ‘borderless.’ You can be in one of the northernmost countries while still creating an impact on the deprived people in further South.

Blockchain technology started to actually gaining fame in 2016 with its offering of simplifying the way to perform transactions, while at the same time making everything traceable. When the idea was first presented, the first word that came to the minds of millions was “nonsense”. But here it is three years later and evidence of its positive impact on human lives could not be more affirming.

Blockchain as part of the Internet 2.0, is unlike the internet that we know. It is a new revolution which enables mass collaboration among the society.

A report by Stanford University in 20196 reveals that 55% of the blockchain-oriented initiatives are projected to contribute positive changes to individuals’ health, education and financial conditions.

So many lives are at stake due to changes which are happening in their area. Be it declined business activities, decreased consumer buying power, or economic uncertainty, among others, that risks the livelihood of not merely the poor, but also those who live slightly above poverty line.

Blockchain with its promise of better problem-solving, enables us to create solutions which were previously not being thought about.

Take for instance HalalChain, the first public blockchain that focuses on facilitating traceability and distribution of social funds such as zakat and cash waqf, as well as other Islamic financial products, all aiming to improve financial inclusion and alleviate poverty7. 

In response to high poverty rate in Muslim countries and among Muslim communities, HalalChain is working on creating a decentralised solution based on blockchain and Internet of Things (IoT) which enables the Government to execute its programmes specifically addressed to a targeted population.

HalalChain is one vivid example of a blockchain service provider that goes beyond “facilitating payments and verify records.” It seizes the opportunity of distributing wealth more equally through technology. 

As we all know, the real problem of realising the global goals is not the lack of fund, it is purely the absence of a reliable means of collecting them from various sources, including charitable giving and donations as well as alternative finance instruments.

With the blockchain technology, transfer of wealth and the ability to help each other becomes ‘borderless’. You can be in one of the northernmost countries of the world while still creating an impact on the deprived people in further South.

The advantage of using blockchain for poverty alleviation does not stop there. The Service Provider and the donors can also trace the usage of the funds provided to the chosen household and evaluate the impact individually and collectively.

It is time for this country to take the leap. It is only the right momentum to design a decentralised future to tackle poverty. Blockchain has a lot to offer but a dream will just be a dream, an action plan will just be an action plan if there are no concrete steps taken.

Surely, there are some critical challenges about using blockchain for poverty alleviation. For instance, for blockchain to be adopted nationally, it has to earn the public acceptance. This is a serious issue considering many still think of blockchain as cryptocurrencies.

Furthermore, we need to educate the public about the utilisation of technology in daily lives. Although Indonesia is among the world’s highest users of technology, its penetration rate is lower than many countries in Asia Pacific, with 60% of the population do not have internet access, a data by The International Monetary Fund (IMF, 2019) revealed.

We are only a decade away from our target to end poverty in all its forms. Regret will always arrive when the time that we have has gone and sorrow is everything that we will experience had we decided to make no changes in our current strategies on tackling poverty.

Adam Smith once said “No society can surely be flourishing and happy, of which the far greater part of the members are poor and miserable”.

Indonesia was built with high hopes and believe to make its citizens free from suffering. It is time for this country to take the leap. It is only the right momentum to design a decentralised future to tackle poverty. Blockchain has a lot to offer but a dream will just be a dream, an action plan will just be an action plan if there are no concrete steps taken.

What an interesting reminder time travel has given to this country, that one small change can lead to a very different outcome.

Are we ready for a revolution?

About the Author

Namira Samir is a development economist based in Indonesia with main interests in multidimensional poverty, regional inequality and Islamic social finance. She holds a master’s degree in Islamic Finance and Management from Durham University, UK. She can be reached at [email protected]

Creating an Enabling Environment for Renewable Energy in Resource-Rich MENA Countries

By Rahmat Poudineh, Anupama Sen, and Dr. Bassam Fattouh

In this article, we argue that investment in renewable energy sources is a no-regret strategy for hydrocarbon exporting economies of the Middle East and North Africa (MENA). It is also in line with some of the pre-renewable energy sector reforms in the region. Indeed, much of their ongoing energy sector reforms – such as the removal of fossil fuel subsidies – complement the move to a strong renewables policy. But their electricity markets, which are currently skewed in favour of hydrocarbons, will need to be carefully designed to support renewables. A holistic approach to energy policy, including establishing stable regulatory frameworks, robust independent institutions, and effective risk mitigation measures will be critical to advancing renewables in the region.


One might wonder that why resource-rich countries of Middle East and North Africa should be interested in renewable energy?

First, rapid energy demand growth is a serious issue in hydrocarbon-rich MENA countries. It is projected that the region’s primary energy demand will be doubled by 2030. Economic and population growth, rapid urbanisation, and heavily subsidised end users’ tariffs are the main factors behind soaring domestic energy demands. Just between 2000 and 2011, energy consumption almost doubled in Oman and tripled in Qatar. Other countries have also more or less a similar experience. The result is that many of these countries have had to divert increasing quantities of crude oil, fuel oil, diesel, and natural gas to satisfy domestic demand away from high-priced international markets. Given their heavy economic dependence on oil and gas export revenues, this puts them on a fiscally unsustainable path. The ability of renewable energy to substitute hydrocarbon fuels in most sectors of economy improves fiscal stability.

Second, energy security is of paramount importance for these countries. Contrary to popular belief, not all countries of the region are fully self-sufficient in terms of natural gas, which is the key fuel for power generation in the region. Indeed UAE and Kuwait are already net importers and there is a possibility that more countries in the region will become net gas importers in the future, if domestic demand is not contained or domestic gas production is not boosted. Other countries that seemingly look self-sufficient are also not very secured. For example, Iran is the third largest global producer of natural gas with 6.1 percent share of the world’s natural gas market. However, Iran’s gas production primarily satisfies subsidised domestic demand. Over the years, the gas production in this country has grown in tandem with consumption, limiting its ability to export any sizeable volume. If for any reason (for example, lack of investment due to sanctions), gas production does not keep pace with demand (or demand outpaces domestic gas production), the gas self-sufficiency of the country will be undermined. Investment in renewable sources can replace existing gas power plants that are used as base load and thus help to restrain or reduce gas demand.

Third, the Middle East region has one of the highest pollutant levels in the world with some of the major cities in Iran and Saudi Arabia being the worst affected. On some days, the recorded air pollution level exceeds 5 to 10 times the limit announced by WHO. Apart from frequent sandstorms that affect some parts of the continent, in recent years, industrial emissions and car emissions have significantly contributed to the poor air quality.

Some of the barriers in MENA resource-rich countries are also similar to other developing countries, but the options for investment incentives are different because of their dependence on oil/gas export revenues and massive domestic consumption of subsidised fossil fuels.

Fourth, the uncertainty about long-term oil demand is rising in the agenda of policymakers in the region. The topic of peak oil demand has especially received much attention in recent years and there are contradictory estimations about its occurrence and time frame. We do not know if and/or when there is going to be a peak oil demand because it is an uncertain phenomenon. However, one thing is certain: renewable investment will benefit MENA oil-rich countries whether or not there is a peak oil demand. The logic is simple: if it turns out that there is a peak oil demand, the optimum strategy for these countries is to maximise their oil export revenue in short to medium term before demand for oil is affected. Alternatively, if it became evident that there is no peak oil demand in a foreseeable future, renewable investment maximises their long-term revenue from hydrocarbon export (given their rising domestic energy demand).

This brings us to the second question on how to enable renewable investment in MENA resource-rich countries. Although, as mentioned above, these countries have different objectives to other developing countries in deploying renewables, the path to achieving these objectives is the same, and it involves creating investment incentives and eliminating or lowering the barriers to investment. Some of the barriers in MENA resource-rich countries are also similar to other developing countries, but the options for investment incentives are different because of their dependence on oil/gas export revenues and massive domestic consumption of subsidised fossil fuels.

Figure 1 illustrates a framework for enabling renewable deployment in the MENA. As seen to the right of the figure, governments must design policies that create incentives for investment. There are two extreme policy solutions to incentivise renewable investment in resource-rich countries:1


The government introduces a full renewable subsidy programme (in addition to existing fossil fuel subsidies), steering investment towards specific renewables. This requires long-term government support and commitment to create investor confidence.

The government eliminates barriers and lets economics determine market outcomes with respect to the quantity and type of renewable technologies, requiring the complete removal of fossil fuel subsidies (and internalising the cost of externalities) so that those forms of renewable technologies that are already competitive can kick in.

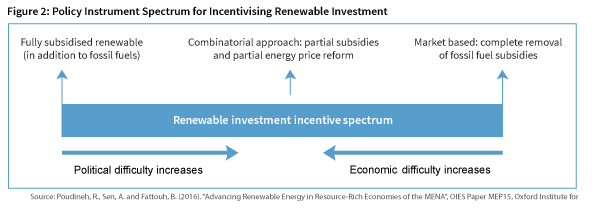
The problem with either of these polar solutions is implementation challenges. For example, market-based approaches are politically difficult to implement in the MENA because it entails full energy price reform within a short period of time to enable the market and that would be nothing short of a revolution. On the other hand, moving towards a fully subsidised renewable programme increases fiscal and economic pressures, particularly as it would be in addition to existing fossil fuel subsidies. Therefore, we argue that investment incentives for renewable deployment in these countries need to be provided through a combinatorial approach, involving partial energy price reform and partial subsidy programme. Figure 2 shows this as a dynamic process. Countries can start from the most feasible point on the policy instrument spectrum based on their current contexts, and gradually move towards phasing out fossil fuel subsidies over medium to long term. This not only reduces the fiscal pressure on government budgets, but also averts political risks by allowing businesses and households to slowly adapt to the new environment where energy carriers are priced at their full economic costs.


As seen in Figure 1, in addition to providing incentives, governments need to design appropriate policies around tackling barriers to renewables deployment, in the areas of institutional challenges, grid connection, and management and risk and uncertainties

The presence of an independent and robust regulatory entity is another key ingredient of unlocking renewable deployment in these countries, as governments often overturn regulatory decisions with respect to issues that are deemed politically sensitive such as electricy tariffs.

Future electricity markets will need new supporting institutions that complement the characteristics of a sector that is predominantly based on renewable energy. This includes renewable energy entities and regulators, their resources, competencies, laws, strategies, and activities. In recent years, many of the MENA’s resource-rich countries have established dedicated agencies to oversee the scaling up of renewable energy. Examples include Renewable Energy and Energy Conservation Directorate at the Ministry of Energy and Mines in Algeria, the Department of Energy (established in 2018) in UAE (Abu Dhabi), Saudi Arabia’s Renewable Energy Project Development Office (REPDO), and the Renewable Energy Organization of Iran (SUNA). However, these institutions are not sufficiently integrated with other energy institutions in these countries, which have been historically dominated by oil and gas, and their role is often confined to administering tenders for private renewable project developers rather than enforcing structural change. These agencies also face powerful state-owned utility companies that oversee generation, transmission, and distribution assets, which may view renewables as a disruption to their business models.

The presence of an independent and robust regulatory entity is another key ingredient of unlocking renewable deployment in these countries, as governments often overturn regulatory decisions with respect to issues that are deemed politically sensitive such as electricy tariffs. Institutions also require a rethinking of the scope and purpose of regulation as new actors may enter the system, or existing actors may change their role, requiring modification to the institutional setting of the power system.

Beyond the traditional concept of institutions in the form of top-down structures, electricity sectors with high penetration of renewables and distributed resources such as batteries and demand response require compatible regulation and operating procedure. This includes universally accepted interfaces, protocols, and standards to ensure a common communication vocabulary among system components within and between networks and the development of appropriate regulations and operativng procedures in conjunction with the development of technologies. Grid connection and management rules (e.g., priority access and priority dispatch) also need to be updated to account for growth of renewables.

No private investment, in any sector, will happen if the problem of risk is not dealt with. Renewable investors face a range of risks including political, policy and regulatory, technology risk, currency and liquidity risk, and finally, power off-taker risks. These risks not only affect the appetite of investors and innovators in renewable energy, but more importantly the cost of capital and ability to finance projects.

Political risks include political events that negatively impact the value of investment, such as war, civil disturbance, expropriation, and non-honouring of contracts. Policy and regulatory risks refer to changes in investment incentives (for example, removal of renewable subsidies), network codes, grid connection costs model, and permitting processes, among others. In resource-rich MENA countries, renewable investors face uncertainty in both where there is no specific renewable policy as well as after policy incentives are designed and implemented. Pre-implementation uncertainties include not knowing if, when, or what type of policy will be implemented to incentivise renewables, whereas post-implementation uncertainties are related to the stability, transparency, trust, and insurance for long-term support. Developers also face technology risks related to nascent renewable technologies which may not have a proven track record of operation in the MENA region, or where the local workforce may lack the skills needed to operate renewable technologies. The currency risk pertains to the volatility of domestic currency value with respect to foreign currencies. This is particularly important as most renewable power producers’ costs are in hard currency (e.g., dollar or euro because of loans), whereas their revenue is in local currency (e.g., feed in tariff paid in domestic currency). The credit and/or default risk arises when the market structure has only one offtaker of renewable electricity (e.g. public utility company) and power producers have no choice but to contract with the single buyer and bear the credit risk.

Several MENA countries have begun undertaking power sector reforms, with the aim of restructuring the energy sector, allowing private-sector participation, removing energy subsidies, and reducing reliance on the public budget.

Another important but often overlooked factor in unlocking the potential for renewable investment is that renewable policy should be integrated into the current power sector reform. The current ‘idealised’ model of liberalised electricity markets (comprising wholesale markets for in generation, and competition in retail supply, with network regulation in transmission and distribution), in which prices are set based on marginal cost of electricity, was pioneered in OECD countries and is based on a market designed for fossil fuel electricity with positive marginal costs. This ‘energy-only’ market relies on the price signal to organise both short-term coordination for dispatching, and long-term coordination for investment in generation capacity2.  The imposition of intermittent renewables that have near-zero marginal (but high capital costs) onto this market has led to a breakdown in this model and a tension between the goals of decarbonisation and liberalisation.

Several MENA countries have begun undertaking power sector reforms, with the aim of restructuring the energy sector, allowing private-sector participation, removing energy subsidies, and reducing reliance on the public budget. The challenge that they face is in designing a reform model that incentivises investment and delivers efficient outcomes, while simultaneously integrating a rising proportion of intermittent renewable resources. Failure to adopt a reform model that balances these goals and does so in alignment with their unique contexts could frustrate or reverse the process of reform at later stages.

Resource-rich MENA countries have the opportunity to design their electricity markets around the incorporation of renewables at the outset. They can further tap into years of international experience by adopting market structures that avoid the risk of market breakdown under fully liberalised electricity systems with a high share of non-dispatchable resources.  

About the Author

Rahmat Poudineh is lead senior research fellow of electricy programme at the Oxford Institute of Energy studies. He is experienced in the economics and regulation of electricity sector. Rahmat has published numerous academic articles on network regulation, electricity market design, power sector reform, renewable support schemes, and gas and power interdependence.

Anupama Sen is a Senior Research Fellow at the Oxford Institute for Energy Studies. She has published extensively on the applied economics of energy in developing countries, spanning the oil, gas and electricity sectors. Anupama is also a Fellow of the Cambridge Commonwealth Society and was a Visiting Fellow at Wolfson College, Cambridge.

Dr. Bassam Fattouh is Director of the Oxford Institute for Energy Studies and Professor at the School of Oriental and African Studies. He is widely published on oil and gas topics and his publications have appeared in academic and professional journals. He also acts as an adviser to governments and industry, and is a regular speaker at international conferences.

References
1. Poudineh, R., Sen, A. and Fattouh, B. (2016). “Advancing Renewable Energy in Resource-Rich Economies of the MENA”, OIES Paper MEP15, Oxford Institute for Energy Studies.
2. Roques, F. and Finon, D. (2017). ‘Adapting electricity markets to decarbonisation and security of supply objectives: Toward a hybrid regime?’, Energy Policy, 105, 584–96.

Guernsey Looks to Play its Part in Accelerating Green Finance on a Global Scale

Greening the financial system has become one of the key economic trends of developed countries as the world now works towards sustainable development. Guernsey, a country with just 25 square miles in land size houses Guernsey Green Finance that has played a significant role in the development and promotion of green and sustainable finance. Guernsey has carved its niche not just in merchant banking but also through its “green ventures” that ensure the environment is at the centre of all financial decision-making.

Guernsey is determined to live up to its reputation as a responsible global citizen, and its commitment to the Kyoto Protocol. Guernsey continues to support environmental stability and to import low-carbon electricity from France as part of our commitment as a community to lower our carbon use.

The global specialist finance centre of Guernsey has enjoyed a symbiotic relationship with the City of London for half a century it has specialised in financial services.

As I write this article, we have a presence at London’s historic Guildhall as the London Green Finance Initiative and the UK Government launch the UK’s Green Finance Strategy, which aims to boost sustainable finance and make the UK an international hub for expertise and funding that supports greener investment.

It is an approach which dovetails with Guernsey’s ambitions to play a part in the development of green and sustainable finance and ultimately, save our planet.

Guernsey is an island of just 25 square miles. We are part of Great Britain, though not the United Kingdom, and sit closer to France than to England.

Guernsey has developed specialisms in financial services since the 1960s when it started to carve a niche in merchant banking. Now, we look to support the City and the global financial services industry with our own specialisms, one of which is the development of green and sustainable finance.

Images For Visit Guernsey – Shot 2012


Guernsey is already home to the world’s first regulated green investment fund product, the Guernsey Green Fund.
But it is not just about making the most financially from the opportunities offered by green finance. Guernsey is determined to live up to its reputation as a responsible global citizen, and its commitment to the Kyoto Protocol. Guernsey continues to support environmental stability and to import low-carbon electricity from France as part of our commitment as a community to lower our carbon use.

Our financial services strategy encompasses a commitment to green and sustainable finance and is aligned with the United Nations’ Financial Centres for Sustainability (FC4S) international network and its assessment framework.

Over the years, Guernsey has developed as a specialist centre for the servicing of alternative assets, such as private equity, infrastructure and alternative debt. We are using that expertise to help to develop a global taxonomy for green and sustainable funds.

We have also been looking to provide a broad and comprehensive range of green and sustainable services. Guernsey is already home to the world’s first regulated green investment fund product, the Guernsey Green Fund. The International Stock Exchange, based in Guernsey, has introduced a green segment to its exchange, and we are actively reviewing the potential for the development of green insurance products.

Guernsey Finance has pursued this objective for the past 18 months, and has made rapid progress on the journey.

From developing the world-leading Guernsey Green Fund accreditation and securing membership of the United Nations’ Financial Centres for Sustainability network, we continue to drive further developments and innovations from Guernsey.

We have also been keen to work with others along the journey, including global public policy groups, and develop partnerships to exploit our leadership position in infrastructure services.

I am proud that we have made great progress towards working with the London Green Finance Institute. Earlier this year, industry representatives from Guernsey Green Finance met senior figures from the Green Finance Initiative to talk about how we could make progress together on climate finance.

Sir Roger Gifford, Chair of the UK Green Finance Initiative, said: “There is no greater imperative for bankers and investors than financing the transition to a low-carbon future. The UK has demonstrated global leadership in green and sustainable finance time and again but collaboration is key. It’s both natural and necessary, therefore, to combine with our colleagues in Guernsey and we welcome working with Guernsey Green Finance in support of climate finance.”


The London Green Finance Initiative did play a significant role in getting us to where we are today – Sir Roger visited Guernsey at the end of 2017 – and so we were delighted to agree a collaborative approach on this topic.

So now, as the UK seeks to take the lead in green finance, we are ideally positioned to support that drive to accelerate green finance.

The UK has said that it expects its own financial services sector to be at the heart of efforts to tackle climate change and reduce emissions to net zero by 2050.

Given the UK’s clear ambition in this space, it’s a real boost to Guernsey’s green strategy that we have already met with the Green Finance Institute’s leadership and agreed to work collaboratively.

The environment needs to be properly integrated into financial decision-making, and we need policy frameworks that can deliver investment at the scale required to solve these great environmental challenges. 

The UK’s new Green Finance Strategy should help boost sustainable investment, and will also expect companies with listed shares to disclose how climate change impacts on their work, reflecting the view that sustainability and climate change should now be considered as an operational risk for companies.

As the world now looks to shift to clean, resilient and sustainable economic growth, there is an opportunity to make London the go-to hub for green investment. This new strategy will help make the UK an international hub for expertise and funding that supports greener investment.

Included in it are plans to increase investment in sustainable projects and infrastructure, while ensuring the UK remains an international leader in decarbonisation, and meets its ambitious 2050 net zero carbon emissions targets.

“The UK has a long history of leading the way in tackling climate change, but we need to do more to protect our planet for future generations,” said John Glen, the UK’s City Minister, speaking at the strategy launch.

“The City has a vital role to play in securing a greener future for us all. By investing more in sustainable projects, it can not only protect our environment, but also help establish London as the pre-eminent international centre for green finance.”

“Today’s Green Finance Strategy will support this ambition, with new initiatives to boost funding for green ventures and ensure that the environment is at the centre of all financial decision-making.”

One of the important messages from the Guildhall was that aligning finance with sustainability is needed to deliver on the Paris Agreement on climate change and the UN Sustainable Development Goals, as well as the UK’s world-leading Climate Change Act and 25-Year Environment Plan.

The environment needs to be properly integrated into financial decision-making, and we need policy frameworks that can deliver investment at the scale required to solve these great environmental challenges.

The UK is in a unique position to green the global financial system. UK financial services, in particular the capital, expertise, and innovation in the City of London, are of systemic importance globally for defining and then ensuring the rapid adoption of sustainability -aligned financial services.

It is expected that green finance will be a core part of the UK’s forthcoming UN Framework Convention on Climate Change (COP26) Presidency in 2020.

The UK’s strategy is ambitious, and rightly so. The future for green finance is very exciting – and Guernsey is pleased to be more than playing its part on a global scale to accelerate our way to that future.


How the Guernsey Green Fund Works

By investing in a Guernsey Green Fund, investors can be assured that their investments have a positive environmental impact on the planet, which are being monitored against internationally recognised criteria.

• Establish a Guernsey fund from any of the island’s existing regimes

• Demonstrate compliance with the Guernsey Green Fund rules

• Provide assurance that the fund is run in accordance with green criteria

• Seek verification from a suitable independent third party that the prospectus meets notified green criteria, or a declaration from a Guernsey-licensed fund manager or administrator.  

By investing more in sustainable projects, it can not only protect our environment, but also help establish London as the pre-eminent international centre for green finance.
The Guernsey Green Fund provides market confidence in the product from the regulatory wrapper, reassurance that funds are invested into green assets, and offers a platform through which investments into green initiatives can be made. It enhances investor access to the green investment space by providing a trusted and transparent product. As demand rises, we expect that capital-raising will become easier for funds with the certification. We are looking to create a global benchmark.

About the Author

Dominic Wheatley is Chief Executive of Guernsey Finance, the promotional agency for Guernsey’s financial services sector. Guernsey Finance seeks to promote and connect Guernsey as the leading finance centre in chosen markets, particularly the UK, Middle East, South Africa, South-East Asia and North America. Guernsey is a member of the United Nations’ Financial Centres for Sustainability (FC4S).

VP Bank – an international bank with tradition and innovation


VP Bank Group is an internationally active private bank focused on rendering asset management services for financial intermediaries and private individuals. In addition, VP Fund Solutions, the fund competence centre, gives easy access to top-notch fund solutions.

VP Bank is one of the largest banks in the Liechtenstein financial centre. In addition to its headquarters in the Principality of Liechtenstein, VP Bank Group is present with offices in five other locations around the globe: Switzerland, Luxembourg, Singapore, Hong Kong and the British Virgin Islands. The target markets for Europe include Liechtenstein, Switzerland, Germany, Luxembourg, Russia and Ukraine. In Asia, they include Singapore, Hong Kong, Indonesia, Malaysia and Thailand. The Russian market development efforts are carried out mainly at the Zurich site as the competency centre for Central and Eastern European markets.

VP Bank Group has a sound balance sheet and a strong capital base. An ”A” rating from Standard & Poor’s vouches for the financial strength. The shares of VP Bank are listed on SIX Swiss Exchange.

VP Bank Group has a sound balance sheet and a strong capital base. An “A” rating from Standard & Poor’s vouches for the financial strength. The shares of VP Bank are listed on SIX Swiss Exchange. A large proportion of its equity capital is in the hands of three anchor shareholders: foundations with a guarantee for continuity, independence and sustainability.

VP Bank’s workforce of more than 930 employees administer clients’ assets totalling almost CHF 48.5 billion. Its client advisors are supported by a global network of partner firms that contribute to the outstanding international know-how of VP Bank Group.


Tradition and innovation for more than 60 years

Founded in 1956 in Vaduz, Liechtenstein, VP Bank has grown steadily from a local bank to become a globally active financial services enterprise.

The founder of VP Bank, Guido Feger, was a successful entrepreneur and one of Liechtenstein’s most highly regarded fiduciaries. Right from the start, he demonstrated innovation, competence and courage, while never veering from the fundamental principles of client orientation and financial security. These tenets have been resolutely upheld for six decades. The philanthropic activities of VP Bank’s founder have been continued by its major shareholder, “Stiftung Fürstl. Kommerzienrat Guido Feger” foundation.

A number of international awards for the quality of the Bank’s client advice and ancillary services, as well as for its competence in transaction processing, attest to pronounced quality consciousness.


 The Bank’s investment solutions are based on the principle of “open architecture”, an approach that also takes into account the best-in-class products and services of third-party providers.

Independent client advice

Tailor-made asset management, investment advisory and wealth planning for a sophisticated private clientele represent VP Bank’s core competencies. The Bank is also an established partner for financial intermediaries who especially count on decades of experience and a modern infrastructure.

One of the strengths of VP Bank is its independence in terms of providing financial advice. The Bank’s investment solutions are based on the principle of “open architecture”, an approach that also takes into account the bestin-class products and services of third-party providers. The result: conflicts of interest are avoided right from the start.

VP Bank Group has the right size to offer top-notch solutions with a personal touch. Clients enjoy the individualised advise of a private bank and, thanks to the global presence of VP Bank, gain access to a worldwide network of specialists.

VP Bank relies on short decision-making paths and agility as well as flexible and sustainable solutions. The use of digital tools supports personal client care. In addition, VP Bank’s e-banking application affords clients freedom of movement and maximum security when conducting banking transactions. They have round-the-clock electronic access to their securities and deposit accounts.


Dependable partner for intermediaries

VP Bank was founded by Guido Feger, one of the leading trustees in Liechtenstein. From the outset, VP Bank therefore saw its role as a dependable and competent financial partner for intermediaries. VP Bank focuses on large, internationally oriented trustees as well as medium-sized external asset managers.

To be successful in this demanding segment requires the bank to respond to changing client needs in Europe and Asia, satisfy regulatory requirements and notably take advantage of technological developments in the process.

With its five international booking centres, VP Bank is one of the few banks of its size to have this unusually broad global presence, offering its clients substantial value-added through comprehensive offerings.

For its intermediaries business, VP Bank Group uses a hybrid business model. Basic banking services on behalf of the end customers of intermediaries are designed to be as efficient, dependable and cost effective as possible using digital channels. The bank then offers high-quality advisory services for intermediaries and end clients.

Along with the traditional custody business, the bank offers end clients comprehensive investment advisory, asset management, wealth planning and lending solutions.

Specialised IT solutions such as eBanking plus are offered specifically to intermediaries. With the ProLink information platform, intermediaries clients have a simple and speedy way to access the most important information and services they need for their daily work. These include extensive coverage of financial market events, regular publications on business and economic issues, the latest news on tax and regulatory developments as well as all required forms.

With its five international booking centres, VP Bank is one of the few banks of its size to have this unusually broad global presence, offering its clients substantial value-added through comprehensive offerings. 

VP Bank, Medienkonferenz im neuen Firmensitz an der Talstrasse in Zürich. © Patric Spahni


Excellent Private Banking

Bank offers its clients a broad range of personalised solutions from investments to financing to wealth management and asset structuring.

Digital banking services play an important role. In 2018, a new e-Banking platform was launched and specific processes such as account opening and closing were automated. Client advisors are also equipped with iPads.

The advisory process is enhanced with the “Finfox” application. This tool makes it possible to perform wealth management and investment planning in a timely and efficient manner. Finfox gets the client involved interactively in the investment advisory process and enables direct implementation of investment decisions.


Dynamic fund business

The fund business plays a central role at VP Bank. It complements the private banking and intermediaries businesses and represents an attractive growth segment.

The fund business encompasses the activity with third-party funds and proprietary funds and is managed under the VP Fund Solutions umbrella. With VP Fund Solutions, VP Bank Group has an innovative and dynamic international fund competency centre and a one-stop shop for all services related to the fund business. The competency centre is comprised of VP Fund Solutions (Liechtenstein) AG and VP Fund Solutions (Luxembourg) SA, with the Group-wide management of this strategically important business based in Luxembourg.

With 20 years of experience, VP Fund Solutions offers close, cross-border teamwork with locally and internationally renowned asset managers.

Through its cooperation with VP Bank, which acts as custodian bank and paying agent, VP Fund Solutions has access to VP Bank Group’s international reach and cost-optimised network of depositories for the clearing and settlement of fund managers’ investment decisions.

The geographical focus of VP Fund Solutions is on Germany, Liechtenstein, Switzerland, the Benelux countries, Scandinavia, the United Kingdom and Asia. The initiators and clients consist of external asset managers and family offices.


The Asia/Pacific region is one of the most important growth markets for private banking and is one of the identified target markets where VP Bank sees attractive growth opportunities.

Successful Asia strategy

The Asia/Pacific region is one of the most important growth markets for private banking and is one of the identified target markets where VP Bank sees attractive growth opportunities. VP Bank has positioned itself as a “boutique bank” that provides first-class solutions to satisfy demanding standards.

In Asia, VP Bank is represented by an asset management company and representative office in Hong Kong as well as a branch in Singapore with around 80 employees. The bank’s business model in Asia is also based on the two strategic pillars of private banking and intermediaries. The target markets include Southeast Asia, notably Singapore, Hong Kong, Indonesia, Malaysia and Thailand.

The growing number of intermediary clients in Asia also creates promising opportunities. In this segment, VP Bank offers its clients regionally oriented service models for trustees and external asset managers as well as personalised support. The development of strategic partnerships is also being advanced. Clients benefit from direct market access to VP Bank’s trading desks in Singapore and Liechtenstein/Switzerland, which cover the major time zones.

In recent years VP Bank has noticeably expanded its presence in Asia. 2018 marked VP Bank’s 10 year anniversary in Singapore, and in April of that year the bank doubled the size of its office space in order to keep pace with growth and have room for further expansion.

In 2018, the subsidiary VP Bank (Singapore) Ltd. was converted to a branch and the banking license was upgraded from merchant bank to wholesale bank in order to implement VP Bank’s growth strategy in Asia in a more targeted and efficient manner. VP Bank expanded the Singapore branch by adding advisors in the investment advisory, wealth consulting and estate planning areas and also significantly expanded the product line with specific offers for Asian clients.


Stable Outlook

“Safely ahead”, VP Bank’s claim, reflects the company’s way of thinking. It means the bank is well equipped for the intense competition. As a lean financial services provider with short decision-making paths, VP Bank will be one of the winners from the consolidation that is currently underway in the industry. The Bank’s proven business model, which focuses on wealthy private clients and professional financial intermediaries, combined with its manageable size, means that VP Bank Group is well prepared for the ongoing changes in the worldwide markets.

For more information, please visit: https://www.vpbank.com


Master of the Cards: How Legacy Brand Mastercard has Led the Finance Category to Success

By Morgan Holt

Mastercard remains one of the most successful brands in the world and it shows no sign of slowing down. Mastercard continues to provide its customers with new opportunities and ambitions to live better. This article discusses Mastercard’s innovative initiatives that incorporate advanced technologies into financial services in today’s highly digitalised and competitive world.


Every year, the world’s most popular brands are placed on the respected BrandZ Top 100 Most Valuable Global Brand list so we can all review how they are faring with the consumers of today’s world. Amazon topped the list for 2019, having invested in its services and offering to deliver a truly unique customer experience – read more on that here.1

But one of the most interesting listees was Mastercard. Pushing towards the top 10 as it ranks in position #12 globally across all categories, the brand enjoyed a 30% year-on-year increase in value on the global brand rankings. Building upon its strong 50-year heritage, Mastercard has developed a rich agility and stayed hyper-relevant across the globe.

Technology has redefined the financial category across the board, giving rise to new consumer expectations and challenger banks that claim to meet them. Considering the sheer pace and progression of life and business as we know it in the last decade alone, you might expect that a heritage brand like Mastercard would be disrupted. Yet, FITCH data has shown that Mastercard has been a significant agent of this change, making it a true success story – both as a brand in people’s lives and a provider of market leading financial services. How has Mastercard become such an icon?


A symbol of financial security and freedom

Such an icon, in fact, it doesn’t need its name anymore…you may have noticed the swathe of press earlier this year when Mastercard dropped its brand name2 from its famous yellow and orange disc logo and created a melody to accompany its marker instead.

At this point, we must acknowledge the true power of its distinctive brand design. Marketing mogul Mark Ritson’s point that ‘all brands have codes; graphical and symbolic devices that are associated with the company or product’3 is true. And the application of these codes should be spread throughout the marketing mix constantly to establish an identity people recognise and resonate with. For over five decades, Mastercard had done just that and so was in a great position to make such a bold move.

Being powerful enough to drop your brand name speaks volumes about how valuable your brand is. It is starkly indicative of where you sit within market culture and in people’s estimations. It’s no secret that people from all corners of the world positively associate with Mastercard.

Being powerful enough to drop your brand name speaks volumes about how valuable your brand is. It is starkly indicative of where you sit within market culture and in people’s estimations. It’s no secret that people from all corners of the world positively associate with Mastercard.

Using FITCH’s own data model, we are able to codify what customers expect from the experiences brands offer. Powered by the wealth of BrandZ data, our methodology maps it against four basic human instincts: progress, comfort, belonging and independence. We know that when brands position their products and services so specifically in response to one or more of the basic instincts, it’s on the home stretch to success.

FITCH data for Mastercard suggests its consumers have come to associate the brand with comfort and independence. Essentially, this means consumers feel reassured and in control with regards to the Mastercard brand; the brand helps them to learn as well as encourage them to carve their own identity. Contextualised, it makes complete sense: payment security and financial freedom are two very big factors affecting us in our daily lives – especially buying and purchasing at the rate we do currently.


Innovations in the category

Amid the chaotic buzz of modern life – which as we all know, is on 24/7 and on all possible channels – brands need to stand out and give consumers something deeper than just simple convenience, or a fancy product to stay front of mind.

The payment sector is a tough one in this respect. Like many areas of finance, it can be very difficult to translate the USP or capabilities of a brand across the public sphere and even more so to find what basic instinct a brand can tap into and build on – especially considering the acceleration rate of the entire industry in just one generation. Technology has, like many others alongside it, redefined and recharged the sector completely – from the world wide web opening up the first online transactions to contactless payments pretty much everywhere.

New technologies have had a positive effect on people’s view of payment brands in the category overall. Digital innovation has helped people to adapt and celebrate new ways of going about their daily lives… and we find Mastercard to have been a significant driver of this change. The brand’s innovation initiatives provided customers with new opportunities and ambitions to live better. The iconic ‘Priceless’ moments from ad campaigns of years gone by were successfully translated into a modern set of significant payment experiences in our digital world, which has likely built up to the result in this year’s BrandZ ranking.

So let’s look a bit closer at these innovations from Mastercard to better understand.


The digital-convenience mindset

Strategic partnerships and communications directed under the reign of current CMO Raja Rajamannar have been hugely influential to building success and remaining relevant. Rajamannar has ensured the brand is taking advantage of trending changes in consumer behaviour and wider market activity; clearly reflected (and rewarded) in that Mastercard is the partner of choice for more than 60 digitised banks across Europe.4 Why? Quite simply because it owns this deep understanding and has a proven track record of innovating in line with changing behaviours.

Currently, 84% of Europeans pursue digital banking regularly,5 63% use mobile banking apps from traditional banks, one in five from digital-only banks and almost two-thirds expect the demand for digital banking solutions to increase in the future. Convenience remains the biggest advantage of digital banking solutions at a time when Europeans demand security more than ever as their most important criteria for using digital banking solutions (67%).

This digital-convenience mindset translates into the new technologies and partnerships Mastercard is across as it creates breakthrough services and experiences.

The brand is moving beyond providing a transaction to running within ‘ecosystems’; that is, becoming an instrumental part of people’s lifestyles. Very strategic and extremely clever.

Seamless and secure biometric payments is an area Mastercard’s Chief of Security has publicly prioritised for a long time, citing that biometric payments not only make transactions safer but dramatically speed up the digital checkout time and reduce cart abandonment rates – and this is crucial for retaining its array of partner merchants. The brand is digitally fit and future-proofing, which in turn only boosts the smoothness of the payment experience for users.


Intelligent technological solutions

To this point, frictionless transactions are being further enhanced by Mastercard’s focus on human-first conversational commerce. Drive-thrus that we all know and use account for 70% of QSR transactions6 and yet the experience has remained very basic and unexciting. As customer expectations rise, Mastercard partnered with ZIVELO to bring a transformative element to the journey and hopefully meet but also exceed those expectations. Consumers will order from an AI-powered voice ordering assistant, which will then integrate with a dynamic menu display in a timely fashion. The menu will automatically update using a proprietary AI solution developed by Mastercard to then produce a display which can be customised either for a specific customer or based on geo-specific details such as location or weather.

This brand-new concept for a typical and popular customer journey (that is yet to be cracked by any other) is a stellar example of everything Mastercard is doing right. We’ve seen fast food restaurants modernise their venue formats recently, how long until this kind of experience comes to a drive-thru near you?


Smart approach to devices

Over on devices, Mastercard has really dedicated intense focus and investment to ensure it is a leading provider on pretty much all of them. Mastercard’s partnership with Fit Pay highlights the growing ecosystem of technology integrators that have joined its Commerce for Every Device programme.7 Mastercard wants to enable simple payment transactions which can fit every consumer lifestyle and most importantly, with the highest level of security.

As a brand, Mastercard has successfully developed into one that resonates well within the consumer imagination, shaping itself across a whole range of sectors and cultures.

Mastercard doesn’t just rise to the demand for payment capabilities from device brands (who understand it’s imperative to continually expand the value proposition of their products), it embraces the demand and runs with it to successes beyond original projection.

The ability to enable so many devices with payments is an extension of MDES and the Digital Enablement Express (Express)8 programme. Through MDES and Express, any accessory, wearable or device can be payment-enabled to be used at the more than 6 million Mastercard contactless-enabled merchant locations in 77 countries around the globe.9 Because these device-based transactions are tokenised through MDES, consumers have peace of mind knowing they are protected from fraudulent transactions when using their favourite devices to pay.


What’s next for Mastercard?

The innovations evaluated above are transforming the way global customers interact with Mastercard day in and day out. The brand is moving beyond providing a transaction to running within ‘ecosystems’; that is, becoming an instrumental part of people’s lifestyles. Very strategic and extremely clever.

Looking to the future, what are the challenges on the horizon?

Today the card payments arena usually results in the middlemen taking a cut. Digital systems, like those used in China and Kenya, could threaten banks and other players. Challengers like Alipay, WeChat and M-Pesa represent different strategies for how to cut different pieces of the card operators pie but that’s another story altogether.

In the West, digital platforms like Google, Apple or Facebook have their own ‘Pay’ products which link consumers directly to merchants. While the providers do use Mastercard, it really is a whole other story and especially so in light of recent news from Facebook around its plans for cryptocurrency Libra set to launch in 2020. How Mastercard develops its partnerships with digital banks like Monzo and Starling will be a particularly interesting area to watch also especially with the digital-only banks foraying into the serious world of financial services.

As a brand, Mastercard has successfully developed into one that resonates well within the consumer imagination, shaping itself across a whole range of sectors and cultures. To stay relevant and powerful it needs to continue developing intelligent technology which provides value to partners and, crucially, tallies with consumer expectations on experience. It’s already on a quick ascent to the top 10, so it’s all eyes on what the brand will do next to get there.

About the Author

Morgan Holt is Chief Strategy Officer at global retail and brand consultancy FITCH and is responsible for growing the strategic capability of the company globally. With 400+ people and 9 offices FITCH enviable opportunity to design the future for clients as varied as LEGO and Lynk&Co.


References

1. https://www.campaignlive.co.uk/article/amazon – overtakes – google – apple – worlds – valuable – brand / 1587104
2. https://www.campaignlive.co.uk/article/mastercard – drops – name – logo – digital – reinvention / 1522311
3. https://www.marketingweek.com/mark – ritson – mastercard – logo – codes /
4. https://newsroom.mastercard.com/eu/press-releases/new – european – digital – banking – study – by – mastercard – highlights – convenience – as – the – greatest- advantage – of – digitized – banking – solutions/
5. https://newsroom.mastercard.com/eu/press-releases/biometric – payments – to – take – centre – stage – as – 1 – in – 4 – of – online – sales – will – require – further – security – next-year /
6. https://smallbusiness.chron.com/percentage-sales-drive-through-windows-fast-food-restaurants-75713.html
7. https://newsroom.mastercard.com/digital – press – kits /commerce – for – every – device/
8. https://www.mastercard.us en-us/issuers/ products – and – solutions / grow – manage – your – business / digital – commerce – solutions . html
9. https://newsroom.mastercard.com/eu/press-releases/new – european – digital – banking – study – by – mastercard – highlights – convenience – as – the – greatest – advantage – of – digitized – banking – solutions/

The Political Economy of Inequality and the Issue of ‘Catching-up’

By Kalim Siddiqui

Why do some countries grow faster than others?

In this article the author discusses issues related to the economic growth and the ‘catching-up’ of developing with developed countries.


In the 1950s, the US per capita income, at least on the basis purchasing power, was estimated to be nearly five times greater than the world’s average income. Soon after World War II, due to the rapid growth of the West European and Japanese economies, this income gap was substantially reduced. A similar development was witnessed in the East Asian economies, when the rapid growth they had seen since the 1960s showed remarkable progress, which is especially apparent in South Korea, Taiwan, Singapore, Hong Kong, Malaysia and, since the 1980s, China, and the 1990s, Vietnam.

The East Asian countries have used the state to promote domestic industrialisation. Not only has trade protection in the past been used as an important tool of development strategy, it has also been used as a welfare policy.

I will analyse the levels and trends prevalent to income inequality, both between countries and within countries, since the neoliberal (i.e., pro-market) economic reforms were introduced in the 1980s in the majority of countries worldwide, though of course at different levels.

Economic specialisation has been extensively shaped by the history of power relations, namely political economy. Similarly, international trade patterns have been significantly influenced by power relations. In the past, trade policy instruments have always been used by the European powers in their colonies. More recently, the East Asian countries have used the state to promote domestic industrialisation. Not only has trade protection in the past been used as an important tool of development strategy, it has also been used as a welfare policy to expand employment and, further, to build strong and efficient industrial sectors. In contrast, in the late 18th and 19th centuries, economic activity in the colonies was based around industrial policies that were designed to favour imperial interests, which resulted in ruining the manufacturing sector in China and India through the so-called ‘free trade’ policy (Siddiqui, 2018a).1 The supporters of free trade and trade liberalisation conveniently ignore economic history. The recent success of the East Asian economies was largely due to export promotion, easy access to Western markets for their products, state intervention, and industrial policy rather than trade liberalisation, as claimed by the neoclassical (also known as mainstream) economists (Siddiqui, 2016a).2

The process of decolonisation after World War II, did in fact, ultimately mean an end to foreign government domination and control over foreign companies. It was hoped that such policy changes would make room, and extend protection for domestic companies to grow and achieve economies of scale. However, this did not happen. Soon after independence, between 1950 and 1980, most of the developing countries witnessed higher growth rates than in previous decades. However, since the 1980s, due to a number of domestic and international factors including the debt crisis, most of the developing countries contacted the IMF for loans; in return, they were required to adopt a ‘Structural Adjustment Programme’.8

Globalisation and Economic Liberalisation

Globalisation and inequality has been in discussion for long time among the economists. The reason for this continuing debate seems to be that of neoliberal reforms including trade and financial liberalisation and its effects on global inequality. Some studies have pointed out that growth of income inequalities both within and between countries are largely due to globalisation (Wood, 1998). Similar points have been made by John Pilger. He observes (2002:2): “In this world, unseen by most of us in the global north, a sophisticated system of plunder has forced more than ninety countries into ‘structural adjustment programmes’ since the eighties, widening the divide between rich and poor as never before. This is known as ‘nation building’ and ‘good governance’ by the ‘quad’ dominating the World Trade Organisation (US, Europe, Canada and Japan) and the Washington triumvirate (the World Bank, the IMF and the US Treasury) that controls even minute aspects of government policy in developing countries. Their power derives largely from an unrepayable debt that forces the poorest countries to pay $100 million to western creditors every day.” He further observes, “Promoting this are the transnational media corporations, American and European that own or manage the world’s principal sources of news and information.”4

An important aspect of globalisation is trade and capital liberalisation. If the capital from the developed countries is moving into the manufacturing sectors in the developing countries, then this would adversely affect manufacturing employment in the former. The migration of capital from the developed to the developing countries could break the segmentation that existed in the world economy during the colonial period, which implies that the salaries of workers in the developed countries are influenced by developing countries’ labour reserves. Under current globalisation and with capital liberalisation, as long as developing countries’ labour reserves are not exhausted, real wage rates around the world would see little increase even as labour productivity increases, which means that the share of wages in world output would come down while the share of surplus increases.8 In the current era of globalisation, capital is far more internationally mobile than it has ever been in its entire history. In fact, the colonial period was characterised by a segmentation of the world economy where capital from the metropolis did go to the colonies but to limited primary sectors such as plantations and mines, while the labour from the latter was not allowed to move freely to the former.

An important aspect of globalisation is trade and capital liberalisation. If the capital from the developed countries is moving into the manufacturing sectors in the developing countries, then this would adversely affect manufacturing employment in the former.

According to estimates by Pritchett (1997) the income gap between rich and poor has widened sharply between 1870 and 1990. He calculated that the standard deviation of per capita income, a more inclusive measure of inequality, which rose from 0.64 to 1.06 over the same period. Since 1950s both rich and poor countries had relatively higher growth rates than previous period. Dutt (1992) found that role of Atlantic salve trade, use of slave labour in Americas and British colonialism in India had created structural asymmetries that perpetuated global inequality.17

According to Adam Smith some regions perform less than other due to number of reasons including, some devoting more resources to manufacturing, while other to agriculture. Some countries may have better and strong policy environment such as property rights. Some countries have low concertation of population and also have less-developed infrastructure. Smith also emphasised that the division of labour could extend further in manufacture than in agriculture and the possibility of cost reduction is greater in the former than in the latter. He stressed that those countries first to industrialise will be most likely to sustain competitive edge in manufacturing.

The neoclassical economists support trade liberalisation and argue inequality arises due to demand and supply of labour for different skills. They predict the level of inequality should vary in an inverse ‘U’ shape with trade and economic liberalisation. The Kuznets curve first showed inequality to be widening as trade expanded as a result of industrialisation. The developed countries were endowed with skilled labour, while the developing countries have unskilled labourers. David Ricardo, in his book Principles of Political Economy and Taxation (1817), argued that all countries could benefit from free trade, even if a nation was less efficient at producing goods than its trading partners. His trade theory claims under such a situation, both types of nation will benefit from trade. A more recent extension of this theory, the Stolper-Samuelson model of ‘comparative advantage’, argues that as trade increases, resources will shift to export-oriented sectors and, with the adoption of free trade, the developed countries will export skilled labour products and technology and import labour-intensive goods; thus, in the former group, demand for skilled labour increases but falls for unskilled labour, while the opposite will happen in the latter. Contrary to these propositions, the study on inequality during the 1990s by Cornia and Addison (2003) found that it has widened in 48 countries, with 16 remaining the same and nine seeing a slight improvement in the sense of narrowing the income gap.

When we look at past economies and incomes, for instance, during the 16th century, the income levels in Europe, Asia, Africa and Latin America showe that average per capita income was nearly 1:1. However, in the first decade of the 20th century, the ratio of average per capita incomes in Europe and North America and the developing countries had risen to 6:1, and remained so until the mid-20th century. Most of the wealth of the developed countries was built on slavery and colonial expropriation. This was also the period when the colonies began to gain their independence. Deepak Nayyar’s (2013) study of the post-independence global economy found that between 1950 and 2010, the developing countries not only saw their share of the world population rise, but also saw the same for their average per capita incomes. Moreover, during this period the developing countries also saw an increase in their share of the global economy in areas such as industrial production, international trade, capital investments, and exports of manufacturing goods. However, such development could only be sustained as long as these countries continued to increase their investments in education, health and technology.

Why do some countries grow faster than others? Adam Smith (1776) has tried to analyse the nature and causes of the wealth of nations. Economists differ in opinion about the policy that are actually needed to achieve rapid economic growth. Neoliberals suggest that economic success is due to the adoption of polices such as assigning a greater role for market forces, economic liberalisation, open economies, privatisation, and free trade policies. This is associated with the Washington Consensus (i.e., structural adjustment programme) and said to be a prerequisite for rapid growth and prosperity. The universal recipe suggested by the international institutions for rapid growth is a ‘one-size’ policy for all countries, while critics stress that a number of policy measures must be taken to achieve sustainable and rapid growth such as human resources development, strong institutions, diversification of domestic economy, amongst others.

However, the gains possible from trade liberalisation have been exaggerated by its proponents. The developing countries’ agricultural exports have declined due to increased competition as more developing countries attempt to export more of the same agricultural commodities. For instance, as Malaysia began to increase its export of cocoa, global supply accordingly rose and cocoa prices fell significantly across the world market in the 1980s. Similarly, after Vietnam sharply increased its production of coffee for export in the 1980s, world coffee prices fell drastically.

One should not ignore the fact that European businesses benefitted the most from colonisation by establishing control over the profitable sectors in the colonies in order to enhance accumulation, and did so with the full support of their governments. There was hardly any concern for the deterioration of local people’s wellbeing. For example, in 1944, the US President Roosevelt remarked on Indochina (i.e. Cambodia, Laos and Vietnam). Amsden (2007: 104) notes: “France has had the country – thirty million inhabitants – for nearly one hundred years and the people are worse off than when they were at the beginning…. The people of Indochina are entitled to something better than that.”5

There are a number of examples when European colonial powers did whatever it took to protect their business interests. As Amsden (2007: 110) argues: “In 1914, Shell began producing crude oil in Mexico. Mexico’s hostility toward foreign companies started in the early 1920s, when it demanded a higher share of profits and better conditions for oil workers. The oil companies refused. In March 1938, foreign oil holdings were nationalised. Great Britain broke relations with Mexico and, together with the US, started to put pressure on the Mexican government for compensation.”5 The punishment for nationalisation [of foreign companies] was even harsher in Iran in the early 1950s. Further Amsden (2007: 111) notes: “The British-owned Anglo-Iranian Oil Company refused to grant a comparable demand from Iran’s popularly elected parliament, headed by Dr Mossadegh. Iran’s economy was sinking, but United States withheld a promised loan, and the World Bank, whose president is always American, also reneged on co-lending. After nationalisation, all American oil companies refused to purchase and market Iranian oil… By 1953, the British Navy had established a blockade in the Arabian Gulf to stop shipment of oil to willing buyers… Shah of Iran, an American puppet akin to Ngo Dinh Diem in Vietnam, retook the Peacock Throne with the help of the army, assisted by CIA.”5

In 1956, control over the Suez Canal was seized by Egypt’s President Nasser, who wanted to build the Aswan Dam to both provide electricity to the Egyptian people and its industries, and also for use in irrigation to expand agricultural cultivation beyond the Nile basin. Moreover, the reaction to Egypt’s attempt to expand its economy was not taken as a positive development by the developed countries. As Amsden (2007: 112) argues: “For finance, Nasser had lined up a loan involving the US, the World Bank and the UK. But in the spirit of nonalignment, Nasser asked Britain to remove its air base from Egypt. The US then declined the loan, to repay it… although in theory, the Bank was an independent, multilateral lending organisation.”5

It seems that the collapse of the Soviet Union and, subsequently, its economy in 1990 made the restoration of a single world economy possible for first time since 1914, as based on free trade balanced budgets and unrestricted capital movements, which is a known pre-World War I recipe for economic success implemented at that time within the colonies by the European powers. During that period, these colonies witnessed the fact that the policy of self-regulating markets proved to be illusory; as such, this policy brought famine, deterioration in living conditions, and created mass poverty. 


Economic Transformation of East Asia

Structural change was a driver of economic growth in Asia, unlike Latin America and Africa where it was not. The rapid industrialisation also provided opportunities for employment.

Moreover, the East Asian economies have witnessed the rapid expansion of their industrial sectors over the last four to five decades, and the rapid growth of the these economies, including that of China, has facilitated an associated structural transformation; indeed, all such countries have followed a course of state intervention so as to promote exports and industrialisation, though of course this intervention was enacted at different levels depending on the country in question.

The transformation of East Asia was driven by rapid economic growth. Over a period that spanned almost five decades, i.e., 1970–2017, the GDP growth rate in East Asia was more than double that in the industrialised countries and almost twice that of the world economy as a whole.7 This was associated with a dramatic change in the composition of output and employment. Economic growth drove structural change from the demand side as the income elasticity of demand for industrial goods was higher than that for agricultural goods, while the income elasticity of demand for services was even higher than that for industrial goods. Structural change drove economic growth from the supply side by transferring surplus labour from low productivity employment in agriculture to higher-productivity employment in industry and services. Structural change was a driver of economic growth in Asia, unlike Latin America and Africa where it was not. The rapid industrialisation, with a marked increase in the share of the manufacturing sector, also provided opportunities for employment.

In recent decades, the rapid and highly successful growth in China has attracted huge interest among academics and, indeed, policy makers in the developing countries. However, in China, institutions have played a crucial role in this growth; by contrast, the majority of developing countries have poor or undeveloped institutions. Due to its size, the huge expansion of the Chinese economy will clearly have a huge concomitant impact on the world economy and will certainly appeal to the poorer economies, as the Russian economy did in the 1950s. Moreover, over the past the last few decades, the East Asian countries including China have used state intervention, i.e., dirigiste, to increase their growth rates and achieve rapid industrialisation.

The modernisation and economic progress seen over the last few decades has been possible due to the international divisions of labour that allowed the East Asian countries to expand industrialisation, diversify their economies, increase productivity and enhance exports, despite the fact that wages and working conditions were generally far from ideal.

Many of the policies that the present developed countries adopted in the early phase of their modernisation in the 19th century are no longer available to the developing countries. Economic growth has been uneven among the developing countries, where a few have experienced higher growth than others. Since the debt crisis of the 1980s and 1990s, Africa and Latin America have seen their growth rates slow down. This phenomenon is also known as the ‘lost decades’.

Privatisation of state-owned enterprises, which is part of the neoliberal reforms, has facilitated the entry of foreign corporations. However, their ownership was transferred to foreign owners, which means that only the fittest would survive (i.e., Western companies). Since the debt crisis, companies operating in the developing countries found it difficult to borrow money in order to fund their investments.18 The companies, who were desperate for capital and any inflow of capital, seemed to be an attractive proposition.6 However, the problem was that those who needed the most (the poorest countries) received almost nothing. The other problem was that for state enterprises, privatisation meant getting rid of loss-making enterprises, with foreigners wanting to buy only the best-performing companies, many of which did not need to be privatised.

Since the early 1990s, neoliberal reforms, including a lower tax burden on the rich, privatisation, and increased pressure from the developed countries and international financial institutions, have led to the sharp accumulation of wealth within the top elites households and global corporates. Recent attempts at globalisation have further facilitated the emergence of global oligopolies and monopolies, which has led to an increase in monopoly rents by the global corporations as accompanied by the weakening of trade unions and increased unemployment, and which have indeed reduced workers’ bargaining power.

According to the Lewis model, in underdeveloped economies (i.e., dual economies) labour is available to the urban industrialised sector at a wage determined by minimum levels of existence in traditional family farming because of ‘disguised unemployment’ in agriculture, where there is practically an unlimited supply of labour and the possibility of industrialisation, at least in the early stages of development. At some later point in the history of dual economics, the supply of labour is exhausted which can only be addressed by an increase in wage, which will in turn draw increasing amounts of labour away from agriculture. Lewis’ main point is that the eventual wide-spread economic growth and development can be initially fuelled by large supplies of cheap labour that result from the initial conditions of economic duality. The Lewis Model supports capital investment in order to raise levels of domestic investment.16

The crucial factor in recent globalisation is the role played by foreign capital. However, despite the overstated role of the foreign capital in the rapid growth of the East Asian economies, the role of FDI in these economies was actually relatively modest (Siddiqui, 2014), accounting for less than 2% of the gross domestic capital formation during the high growth rate periods in Japan, South Korea and Taiwan compared to the developing countries’ average of 5-6% and the greater reliance in the South East Asian countries on foreign capital inflows.6 Whilst FDI had significantly grown in the previous decade, global FDI investment reduced by 23% in 2017 to $1.43 trillion (Figure 1), from a revised $1.87 trillion in 2016, presenting concerns for long-term sustainable industrial development (UNCTAD, 2018). 


The inflow of capital is an important component of economic development for host countries in both developed and developing countries, with globalisation the focus on stimulating inward FDI flows to generate employment has increased. It is emphasised that host countries may gain additional ‘spill over’ benefits from FDI such as product, process, and distribution technology, knowledge transfer, management techniques and marketing.  However, the realisation of these benefits between developed and developing countries can be profoundly different. According to UNCTAD’s 2016 Report, during the 1990s more than 80% of the foreign capital in the world consisted of mergers and acquisitions (M&As).15 Even as far as the developing countries were concerned, most such have been acquisitions rather than mergers. In the developing countries, with the exception of China, M&As have mainly involved acquisitions, particularly during the debt crisis and economic distress involving foreign acquisitions.

In 2010, the average share of the FDI in capital formation was 4.4% worldwide, 5% in the EU, 6.5% in the developing countries (including raw materials and plantations) and region-wise was 6.9% in Latin America, 5.3% in Africa, 1% in the Middle East and 11% in China. China is now somewhat venerated by the IMF and World Bank. However, neither China nor India deregulated their financial markets to inflows and outflows of capital.9 If past experience can be learnt from, then it is clear that the successful economies have relied on building manufacturing industries, education and government-promoted domestic business through a hybrid institutional structure.


Comparative Growth Performance:

The growth rates of the emerging economies are higher than the average world GDP growth rates. This is due to a number of reasons, including both national and international economic policies. Figure 2 indicates annual GDP growth in the developed and developing economies from 1990. The period from 2002 to 2007 does show acceleration of growth across economies, but that came to an end in the collapse of 2008-09, and since then GDP growth rates have been similar to those of the 1990s.


Table 1 and 2 show the per capita GDP growth of the developed and developing economies from 1978 to 2015. Here again I find China is on the top of the list with average annual growth of 7.4% and the growth compared to US is estimated to be 461%.
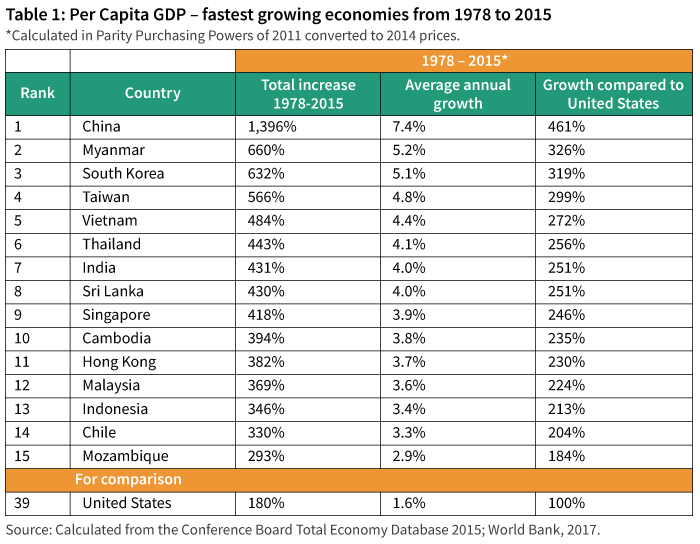
 

Soon after independence the developing countries saw that industrialisation is imperative towards removal of backwardness, to increase productivity and to diversify its economy. For this task nearly all the developing countries adopted import substitution policies in the manufacturing sector. The exports from the developing countries rose from US$ 20 billion in 1950 to US$ 600 in 1980 and nearly US$ 6400 billion in 2010, but imports rose rapidly as well. The developing countries share in the world exports was 34% in 1950, fell to 19% in 1970, 24.2% in 1990, rose to 31.9% in 2000 and 42% in 2010, while their share of imports in the world economy was 29.6%, 18.5%, 23.1%, 28.8% and 38.9% respectively. The sharp rise since 2000 appears to be due to China’s rising trade (UNCTAD, 2016).15

Soon after independence the developing countries saw that industrialisation is imperative towards removal of backwardness, to increase productivity and to diversify its economy.

Since their independence in the 1950s and 1960s, the developing countries share in the global GDP has risen and by 2015 their total share is over 44%, double than in the 1970s. The industrial sector in the developing countries is also increasing and their share of value added in global manufacturing output increased from 13% in 1970 to more than 45% by 2015. However, the region wise increase in manufacturing output was highly unequally distributed. For instance, Latin America’s manufacturing share of global GDP has only marginally increased to 8% between 1970 and 2015, while for manufacturing share of Africa has remained the same i.e. less than 3% for this period. Africa’s share in manufacturing value added in 2015 was only 2%, as it was in 1970. As the Chinese economy is “catching up” fast and also the Indian economy, both are re-emerging as most rapidly growing economies and also major contributors to overall world’s output growth in 21st century.7 China has become the second largest economy after the US, which is a remarkable development of the 21st century.6

Moreover, the patterns of trade are changing as well. For example, the share of manufactures in developing countries exports rose from 12% in 1980 to 64% by 2015, nearly half of this consisted of medium and high technology products. Another key development has been the rise of services in their export components of the developing countries such as information technology and e-commerce. Global income inequality could be measured in a number of ways: the first method of estimation adopted is inter-country inequality, which treats each country as individual and inequality measured is that of the distribution of per capita GDP among countries. The second method is supposed to be a little improved as it takes into account the population size of a country. The third estimation method takes into account the inequality of the world income distribution by combining inequality distribution in individual countries together with per capita income.

Figure 2 shows the changing share of the GDP of the major developing regions. Here China is plotted separately to show its growing economic share. China’s share in the global GDP rose from 3% to 15% between 2005 and 2016. This was the time when China’s share of the global GDP at market exchange rate rose rapidly to ten percentage points. In fact, such a rapid change in China’s share alone explains 87% of the entire decline of the developed economies for the period of last thirty-five years. Figure 3 indicates the changes in the share of developing regions in global GDP and the largest developing Asian economies excluding China. I find  that India’s share in the global GDP has been among the largest and its share increased from 1.8% in 2005 to 3% in 2015. However, it is much less than China, whose share is three times of India’s aggregate share. Indonesia and South Koreas share in the global GDP has increased.17
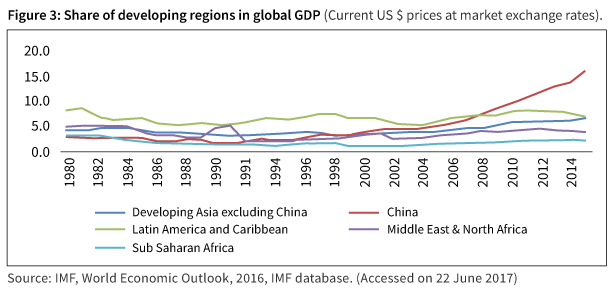
However, if we exclude China then the share change of other regions provide us a different picture. For example, the Latin American region in the 1980s had experienced a decline, which is also known as lost decade. The region’s economies recovered in the 1990s and early 2000s. Their share in global GDP rose by 5% in 2003 to 8% in 2011, but thereafter again began to decline. The Middle East countries had experienced a rise in the share due to largely high oil prices, but for the last 2 years due to collapse in oil prices, its share in the global GDP has fallen. The sub-Saharan Africa had a long period of stagnation and economic decline i.e. from 1980 to 2002 and since then their share in the global GDP has slightly gone up to 1.1% in 2002 to 2% in 2015. However, its share in global GDP is still below compared to its 1980s share of 3%. In short, among the developing regions, only Asia’s share to global GDP is rising. Due to on-going global recession in the advance economies, the BRICS countries too are facing slowing down economic growth rates and declining their export markets.

During the last three decades, there have been huge economic changes taking place globally and structural changes and changes in patterns of trade have also taken place both in advanced and developing countries. However, some developing countries have achieved faster growth rates than the developed economies, particularly China, India, Indonesia and Turkey. However, they constitute a small number among the developing countries, but accounts large number of its population. In fact, international inequality in terms of distribution of per capita incomes among the countries’ population has declined in the last two decades.12 Trade liberalisation and with the removal of trade barriers did have some positive impact on country’s growth but not all the developing countries have benefitted from it.13 I also find that with globalisation, transnational companies largely from the developed economies driven by competition at home for markets8 and higher wages and low returns, driven rising completion for markets, seeking to cut their costs have started investing abroad and supported by the rise of global value chains since the 1990s.3

As the Chinese economy is “catching up” fast and also the Indian economy, both are re-emerging as most rapidly growing economies and also major contributor to overall world’s output growth in 21st century. The two countries only in the recent past were only known as marginal economies, but now China has become as the second largest economy after the US, which is a remarkable development of the 21st century. However, the global GDP share of Latin America has marginally increased to 8% between 1970 and 2010, while Africa has remained the same i.e. less than 3% for this period. Africa’s share in manufacturing value added in 2011 was only 2%, as it was in 1970.

Moreover, the persistent gap between rich and poor countries seems to be the dominant features of the modern history (Reinert, 2007).14 The Economist (2014) insist that it would take developing countries as a group (excluding China) more than a century or even longer period as three centuries to catch up with the income levels of the rich countries. The average life expectancy in the developing countries has risen in recent decades, but still in the sub-Saharan Africa it is only 56 years compared to 78 years in the United States.  It appears that the Western world is punching too far above its weight which could be the main root of on-going crisis. The future cannot be just an extension of the past. More needed to be done in the developing countries, especially those who still have widespread poverty in terms of economic policies and it may involve structural changes. Todays’ developed economies did not attain that status naturally and overnight, but they formed polices and worked consistently to achieve those goals.


Growing Inequality

Private wealth is concentrated in the hands of a few rich families; only World Wars I and II and the Great Depression disrupted this pattern.

When we analyse the issue of worldwide inequality we find that, across the countries, the gap between the rich and poor declined in the period between 1950 and 1980. However, since the 1980s, both in the developed and developing countries, the gap between the rich and poor has widened. Thomas Piketty’s (2014) book Capital in the Twenty-first Century considers an immense amount of empirical research into the distribution of wealth and income across the population for a number of developed capitalist countries. Private wealth is concentrated in the hands of a few rich families; only World Wars I and II and the Great Depression disrupted this pattern. High taxation on the rich and the rise in benefit payments, i.e., the growth of the welfare state, caused wealth to shrink dramatically, and ushered in a period in which both income and wealth were distributed in a relatively egalitarian fashion, where the economic policy then adopted was known as the Keynesian model. However, since the 1980s crisis in the West, this has given way to the adoption of neoliberal economic policy, and as a result the inequality in income and wealth has been reasserting itself for some time.8 By various measures, Piketty reasons, the importance of wealth in modern economies is approaching levels only last seen prior to World War I.

The period between 1950 and 1970 represents a remarkable break, which created an impression that capitalism had become more egalitarian, that inherited wealth had ceased to matter as much as before, that the individual’s “ability” rather than patrimony determined his or her position in the socio-economic hierarchy, and so on. To be sure, the bottom 50% of the population in most capitalist countries could barely be said to own much wealth at any time, and hence hardly earned any income from wealth; however, the period from 1950 to 1970 saw the middle class raise its share of wealth and income at the expense of the rich. The radical political economy argues that the distribution of property generates conflict and struggle, thus determining income distribution. This has been witnessed in the form of the positive relationship between union strength and greater equality. As with the recent globalisation, the organised strength of unions has been weakened while the organised strength of capital has strengthened, in essence because capital can move globally with little or no hindrance, while workers clearly cannot.9

The unequal distribution of income affects employment levels in capitalist economies. The distribution of purchasing power bares no relationship to the distribution of peoples’ needs. Under a monopolistic industry structure, income tends to be distributed towards profit and not wages, which means a higher proportion, is saved rather than consumed. Low levels of aggregate demand and lack of investment present a problem for prosperity and growth.8

The above assumes the existence of a reserve army of labour, without which a capitalist system, as Marx showed, simply cannot function. Inequality also arises as a result of the dispossession of peasants and traditional petty producers through what Marx (1992) called the process of “primitive accumulation of capital”, which is very much underway in the current era of globalisation, and also the inequality that arises due to the “centralisation of capital”.10 Marx analysed centralisation of capital in terms of the fact that big capital drives out small capital due to the former’s superior capacity to introduce new technology.10 Big capital has the capacity to find prospective investment projects with higher rates of return, and it can do so within the global arena since its capacity to “go global” is considerably greater than that of small capital. 

Trends in global inequality have been debated in the past. The 19th century saw the rise of capitalism in Europe, which Marx (1992) pointed out inevitably leads to extreme wealth concentrations, while its defenders argued that the gap between rich and poor would narrow in the future. There has been an increase in wealth concentrations in recent decades thanks to the lobbying power of the elites to influence any associated decision processes. Statistically, in both developed and developing countries, the concentration of wealth within the elite class has increased significantly in recent decades. One possible explanation for the rise in inequality seems to be the policies of neoliberalism, which have reduced the taxation on the rich and a decline in workers’ bargaining powers and trade union activities due to current globalisation.3

Four decades ago Margret Thatcher became Prime Minster in the UK with the argument that allowing the rich to get richer would benefit the entire society. She adopted pro-market policies, which included: free movement of capital, lower taxes on rich, lower welfare spending, weaker trade union and privatisation of state-owned industries. All these policies, it was claimed ‘would unleash a wave of entrepreneurship’ that would lead a faster growth, higher investment and prosperity for everybody. However, four decades later, the picture is quite different. For example, the share of income going to top 1% has risen from the 3% in 1979 to 8% at present. In 2018, the chief executive of a FTSE 100 company earned 145 times the salary of the average worker, up from 7 times two decades earlier. However, those on the lowest income earn little more than they did in 1990. A cursory look at what happened to growth, productivity, investment and trade balance shows that UK’s economic performance has not improved. Moreover, the weakening of trade unions has allowed capital to increase its share of national income at the expense of labour. Lax corporate governance has allowed executives to raise their earnings each year, and also cuts in the top rate income tax have allowed the rich to multiply their wealth further.

The Gini coefficient focusses on the distribution of income or wealth of a nation’s residents, and is the most commonly used measurement of inequality. As noted earlier, the Gini coefficient rose from 18.3% in 2013 to 85.4% in 2018, which clearly tells us that growth has only benefitted the rich. The Gini coefficients in the developed countries range between 0.3 and 0.4 for income and vary between 0.5 and 0.9 for wealth. According to the data, the estimated share of wealth held by the top 1% of households varies across the range of 15-35%. Credit Suisse (2016) estimates that the level of global wealth inequality between 2000 and 2012 increased by 60%. Table 3 indicates the statistics from 2000 to 2012. It shows that the 2012 Gini coefficient in Brazil was 81.2, China, 68.9, and India, 81.3, while in Japan it was 59.6.  As Figure 4 also shows, the top income share for the US, France and China has risen sharply since the 1980s, while the bottom 50% income share has consistently declined for these countries, which is shown in Figure 5 (also see Figure 6). 
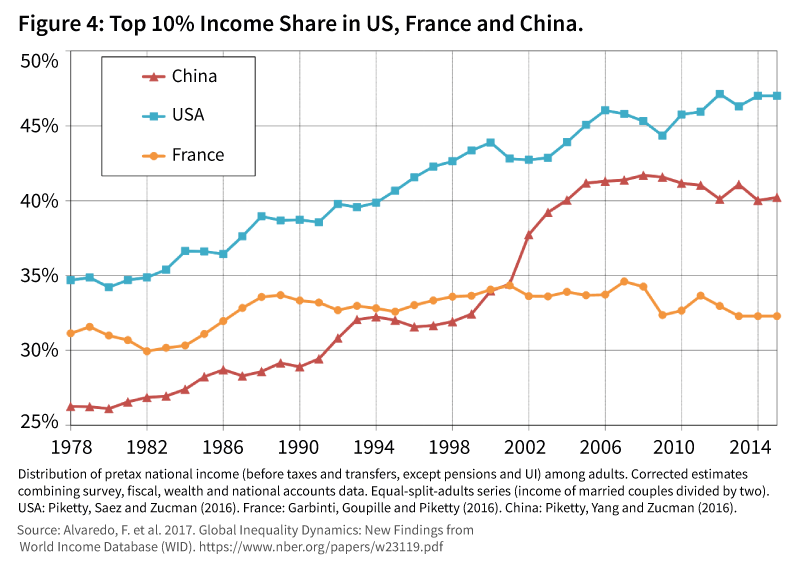
 

China, the East Asian countries and India have relatively low income inequalities and have also managed to invest in and build large industrial sectors, in contrast to the Latin American countries such as Argentina, Brazil and Mexico who were unable to build domestic industries and, further, show greater inequalities. In the latter group, the foreign capital largely went into acquisition and mergers, which resulted in increased control by foreign corporations. Only in the last decade with the Lula Presidency, has inequality reduced to any extent, due in this case to strong government initiatives. 


According to Stockhammer (2015), the current crisis in the developed countries is due to rising inequality which is a result of the financial deregulation in the last decades of the 20th century. He identified four factors which contributed to the crisis: 1) rising inequality creating downwards pressure on aggregate demands since the poor have a higher propensity to consume compared to the rich; 2) international financial deregulation, which has allowed countries to run current account deficits; 3) despite stagnant wages and welfare cuts, the poor have been under some considerable social pressure to attempt to keep up with social consumption norms; and, finally, 4) the rich have received disproportionately more money, which has increased the propensity to speculate and in speculation activities.11
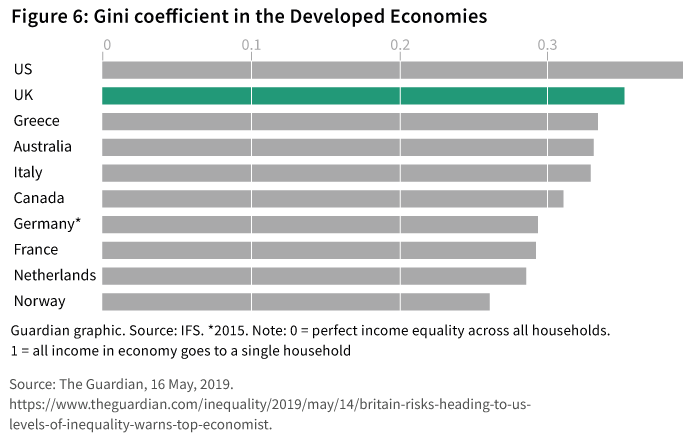
 

The changes to the financial system, i.e., financial deregulation in 1999 in the US, allowed the property and estate sector financial bubble, which in turn allowed for the massive increase in household debt, which in turn contributed to increased consumer demand.9 At the same time, capital inflows helped to keep interest rates low, which has further fuelled debts. Since the 1980s wage shares have fallen by 10 percentage points in the EU, and indeed in Japan. The decline in the US and UK was a bit lower, at 5 percentage points (Stockhammer, 2015). In the US, the income of the top 1% has risen in terms of its share of national income from 8% to more than 22% in 2010. Similar trends are seen in other EU countries. Stockhammer’s (2015: 941) study, conducted by using panel analysis for 71 developing and developed economies, found that “financialisation, globalisation and welfare retrenchment all have contributed to falling wage share…”11 

Inequality has risen almost everywhere in South Asia since the 1990s. Consequently, in India, for example, this rapid growth has not always transformed into improving living conditions amongst the populace, particularly in periods when job creation was slow or where income inequality was high to start with. Economic growth had a greater impact on the living conditions of ordinary people where the creation of employment was rapid or where the initial income distribution was less unequal. The spread of education in society and the delivery of health services to the general populace have directly contributed to people’s wellbeing and were thus constitutive of development. Better education and health were also drivers of economic growth via productivity growth.

In conclusion, I find that colonisation left a huge devastation not just in the economies of the developing countries but also had lasting social and political impact. Their economies fell behind until mid-20th century. However, after they became independent, their economies began to witness higher growth rates than previous decades. Almost all the Asian countries soon after independence adopted ambitious drive towards industrialisation, where state played a leading role. However, the poorest countries have not been able to converge and except largely the two largest ones,12 namely China and India have experienced rapid growth rates and economic changes in recent decades.13

The developing countries need to break the chains of static ‘comparative advantage’ that for centuries has forced them to maintain mining and planation activities and other low value commodity production.14 They need to free themselves in order to choose their own model of development as appropriate to their specific demands and needs. The most successful late developer countries (such as the East Asian countries including China)15 started out with agrarian reforms and also built industries, subsequently addin further value of all kinds of skills and improving their competitiveness in a number of high value industries. From this discussion, it emerges that since neoliberal economic policy was adopted, inequality has increased worldwide. Therefore, there is a need for government to play a greater role in the management of the economy. A new international economic order is needed which promotes greater economic sovereignty, diversification of economies and increased democratisation of international economic relations, which will also encourage greater south-south economic cooperation and trade. 

About the Author

Dr Kalim Siddiqui is an economist, specialising in International Political Economy, Development Economics, International Trade, and International Economics. His work, which combines elements of international political economy and development economics, economic policy, economic history and international trade, often challenges prevailing orthodoxy about which policies promote overall development in less developed countries. Kalim teaches international economics at the Department of Accounting, Finance and Economics, University of Huddersfield, U.K.. He has taught economics since 1989 at various universities in Norway and U.K..

References:

1. Siddiqui, K. 2018a “Imperialism and Global Inequality: A Critical Analysis”, Journal of Economics and Political Economy, 5(2): 266-291.
2. Siddiqui, K. 2016a. “International Trade, WTO and Economic Development”, World Review of Political Economy, 7(4): 424-450, winter, Pluto Journals
3. Siddiqui, K. 2017a. “Globalization, Trade Liberalisation and the Issues of Economic Diversification in the Developing Countries”, Journal of Business & Economic Policy 4(4):30-43.
4. Pilger, J. 2002. The New Rulers of the World, London: Verso.
5. Amsden, A. H. 2007. Escape from Empire: The Developing World’s Journey through Heaven and Hell, Cambridge, Massachusetts: MIT Press.
6. Siddiqui, K. 2014. “Flows of Foreign Capital into Developing Countries: A Critical Review”, Journal of International Business and Economics 2(1):29-46, March.
7. Siddiqui, K. 2016b. “Will the Growth of the BRICs Cause a Shift in the Global Balance of Economic Power in the 21st Century?” International Journal of Political Economy 45(4): 315-338, Routledge Taylor & Francis.
8. Siddiqui, K. 2017b. “Austerity as a Tool of Fiscal Consolidation: Theoretical and Empirical Perspective”, in Public Finance and the New Economic Governance in the European Union, (edi.) S. Owsiak, pp.116-166, Warsaw: Wydawnictwo Naukowe.
9. Siddiqui, K. 2017c. “Financialization and Economic Policy: The Issues of Capital Control in the Developing Countries”, World Review of Political Economy 8 (4): 564-589, winter, Pluto Journals.
10. Marx, K. 1992. Capital: A Critical Analysis of Capitalist Production, vol. 1, pp.708, London: Penguin Classics (first published 1848).
11. Stockhammer, E. 2015. “Rising Inequality as a Cause of Present Crisis”, Cambridge Journal of Economics, 39: 935-958.
12. Perkins, J. 2006. Confessions of an Economic Hit Man: The Shocking Story of How America Really Took over the World, New York: Penguin.
13. Siddiqui, K. 2009. “The Political Economy of Growth in China and India”, Journal of Asian Public Policy 1(2):17-35, March. Routledge, Taylor & Francis.
14. Reinert, E.S. 2007. How Rich Countries Got Rich and Why Poor Countries Stay Poor, London: Constable.
15. Siddiqui, K. 2016c. “World Trade Organisation, International Trade and Prosperity”, International Journal of Social and Economic Research 6(2):1-28, April-June.
16. Siddiqui, K. 2018b. “Capitalism, Globalisation and Inequality”, The World Financial Review, November/December, pp. 72-77.
17. Siddiqui, K. 2019a. “A Century of India’s Economic Transformation: A Critical Review”, Journal of Perspectives on Financing and Regional Development (JPPD), 7(1): 1-22, January-February.
18. Siddiqui, K. 2019b. “The Political Economy of Essence of Money and Recent Development”, International Critical Thought 9(1): 85-108. Taylor & Francis Group, Routledge.

50+ Shades of World Debt

The National Debt Clock on the corner of 43rd Street and Sixth Ave. in a 1992 file photo. On September 7, 2000 the clock will be shut off because the debt, after reaching a high of $5.78 trillion in 1999 started to decline to $5.68 trillion on September 1, 2000. The clock was started in 1989 by the late real estate developer Seymour Durst to raise public aeareness of the national debt. (© Frances M. Roberts) (Newscom TagID: lrphotos112516.jpg) [Photo via Newscom]

Imagine if one day your debt piled so high you owed more than three times your income. 

For an individual, it’s a nightmare scenario. Unimaginable. For countries, it’s simply how the economy works. Financial obligations are stacking higher each year, and global debt history shows us a worrying statistic — the world’s nations owe three times more money than they spend in a single year. 

Governments, households, and companies have contributed to the current debt of more than $243 trillion, and consumerism appears to be the driving force. We’re encouraged to spend more. And why not? Spending keeps money moving through the system, encouraging a healthy economy – and sometimes tax cuts and increased government spending are the only way to get a country out of recession. 

It’s impossible to look at global debt stats & facts, or a single country’s national debt, in complete isolation. Most often, it’s not a mark of how well a country is doing — after all, the world’s richest nations, the countries with the steadiest economies, are also the most indebted. 

There are many factors to examine if you want to understand the impact of global debt on the economy. That’s exactly why this infographic was made. It provides a clear-cut analysis of important global data, and it shows you the specifics of how much different countries of the world owe compared to their GDP. It’s simple, it’s straightforward, and it gives you everything you need to know. 


Nine Advantages of an Online Degree

Often, people take a job and then find they would prefer some other work but do not have the qualifications needed. They could have family commitments and need to work full time, yet going back to college to get the degree they need can seem out of reach. The world of education has changed a great deal in the past few years, and now there are not many colleges and universities that do not offer all of their courses online. There are advantages to studying for a degree online, and it could well be the way forward for you.

Fits in with Most Lifestyles

Regardless of your lifestyle, you will be able to fit an online degree around it. If you are at work during the day, you can study in the evenings. This means you can still earn your salary while improving your chances of a better career. It could even be that you want to advance in your current line of work but need a qualification to do so.

If you have young children to care for, you can work on your degree when they have gone to bed. Many moms who have been at home for several years find going back into employment a daunting prospect. The workplace has changed so much because of technology that it is nothing like the world of work they left. Earning a degree can make this a simpler process for them and help to make their new employment more meaningful.

Several Start Dates

Most online courses have several start dates throughout the year, so you are not restricted to the normal term times. This can be a huge advantage once you have made the decision to aim for a degree, as then you will not have to wait for months to get started. Not only are the start dates flexible, but so are the finish dates. You can take longer to complete an online course than you would studying at a traditional campus, and although there are still time restrictions, they tend to be much longer. In some cases, the time you have to complete the course is years longer than at a bricks and mortar college or university.

Huge Choice

There is a huge choice of degrees available online make sure that you choose the right program for your needs, and then start working on getting your certificate. You can also buy degree online with the help of Fastest Documents 24/7. Because you are studying remotely, you will not be restricted by the location of the college or university that offers the best options for the course you have decided on. For instance, if you want to pursue an online bba course or first aid training courses, or are looking for online degrees for a Master’s in Healthcare Administration, or maybe a Bachelor of Science in Criminal Justice, you will be able to find these and many others online.

Students from all over the world can now use the online services provided by US colleges and universities, and because the standard is considered to be so good, there are many international students taking advantage of this. Its makes so much sense for students whose countries do not offer the facilities needed for the course they want to complete.

Lower Fees

The fees for online courses are generally lower than the fees for a college course where you attend the physical building. This is because the costs to the college or university are lower, and they pass these savings onto the students studying online. Some of them offer financial deals just as they would for physical courses and also student loans are available for those that qualify. There are even some courses that are free of charge. You also have the advantage of not having to pay transport costs for the commute to campus.

Available to All

One of the distinct advantages of online courses is that they are available to everyone. Some people are put off going to college because of physical disabilities, or they are scared of being bullied and do not have enough confidence. All those barriers disappear with an online course. There are more disabled people in the US than is often realized and online courses have opened up a whole new world for some of them.

The Same Certification

When online courses were first introduced, there was some concern that their certifications would not be considered as good as degrees obtained at a physical college. Firstly, the certificate does not show how a degree has been obtained. Secondly, research has shown that many employers consider it a plus if a prospective candidate has earned their degree online. This is said to be because they realize that completing a degree online takes commitment and self-discipline and they hope that an employee will transfer those traits into the job they are considering employing them for.

Transfer Previous Credits

If you have earned some credits towards your degree at another college than the one you have chosen for your online course, most educational facilities will let you transfer them, which will enable you to finish the course sooner.

No Limits

There are no limits to the number of courses you can complete online, and many people are getting more qualifications than they would have been able to obtain without them.

Online Assistance

Many online courses have the chance to join virtual meetings with tutors and other students. This results in you getting the same support as you would if you went to college every day. You can ask questions about things you may be struggling with and discuss problems with other students too. You never have to feel that, because you are studying from home, that help is not available whenever you need it.

Do You Want to be Better Qualified?

If you want to gain more qualifications, before turning your life upside down and trying to fit a physical college or university into your life, look into the courses offered online. You may be surprised how simple it is to get started and pleased that your lifestyle does not have to change very much at all. The nine advantages shown above are the main ones, but they are not the only ones by any means.

Is an Accounting Degree Beneficial for Business or Employment?

In your career, it is likely that you will at some point be an employee but at another time assume the role of a business owner. Such is the nature of the modern working life, where flexibility is the key to both survivability and success over the decades.

This is why we are asking whether an accounting degree would be beneficial in either circumstance – business owner or employee? Let’s see.


Employee with an Accounting Degree

Accounting degrees have progressed over time to become more modern and reach beyond double-entry bookkeeping and financial accounts preparation. They now include other related topics such as information systems to enable people versed in financial matters to understand and deal with broader business issues.

For an employer, a new staff member who is well versed in strategic decision-making and organizational complexities of modern business is a definite boon. They can rely on their knowledge along with their understanding of how financials interconnect with other aspects of business that materially impact success or failure.

While an employee who studies an accounting degree from an educational establishment like the Walsh University may take the course online, they’re still able to work at the company in the interim. This benefits the employer as their staff member’s skills develop as they take the course. It’s also more likely that promotions will follow as their usefulness becomes more evident.


Business Owner with an Accounting Degree

As a business owner, many are struck by confusion over financial matters. Maybe they came from a sales-oriented position previously, so financial numbers weren’t in their wheelhouse. This creates a void that is difficult to navigate through when dealing with management accounts for projects and trying to understand what’s happening financially with their business.

In such circumstances, studying for an accounting degree makes good sense. The fact that modern degrees such as this now consider the global picture and the operational side, along with how it links to the balance sheet and cashflow statement, is a bonus.


Which Working Scenario is Better with Accounting?

It doesn’t necessarily have to be an either/or scenario when studying accounting. While it will certainly be beneficial from a career perspective, many founders launch business at a later stage, when they’re clearer about how they’d like their future to look. As such, learning about financial matters is not likely to be a regrettable decision as this kind of knowledge never goes to waste.

As a business owner, the more that’s understood about the numbers behind the business, the better. Whilst it’s possible to outsource the financials to an accounting company to prepare them, this can never replace a CEO who understands their lingo and the numbers on the page.

Whether you are working for a company or running one, having a solid appreciation of the financials is almost an act of self-preservation. It makes it easier to navigate choppy business waters and provides time to look at alternative employment scenarios should an employer look like they’re economically sinking.


Say Hello to Japan’s New Generation Workers

By Alecsandra Tubiera

The new generation – or mostly known as the millennial generation – is the current age of workers in Japan, innovating ideas and changing their workplaces’ atmospheres. In addition, there are now more foreigners and seniors in the Japanese workplace unlike before.


The millennial working group

Millennials leverage technology and collaborative digital tools to streamline and systemize their work.  Many millennials have watched their parents’ generation grow into managers, leaders and pioneers in their industries, and they want the same thing or a guide that lets them know that they can achieve this in their future career path.

Japanese millennials are now opting to apply and have a “job for life “over transferring companies and employers, potentially undermining the Bank of Japan’s efforts to stoke inflation and growth, according to a report from Bloomberg.1 These workers usually in their 20s to 30s, demonstrating a strong preference for job security and bucking the trend set by both their elders and members of their own working group overseas.

In the past decades, Japan’s employees are known to have endured overcrowded trains, submission to colleagues and salaries unrelated to performance. These days, Japanese companies are increasingly catering to the preferences of millennials.

Millennials account for about 21 percent of the current world population and is projected to make up 75 percent of the global workforce by 2025.2 

According to Disco Inc.’s survey, a Tokyo-based recruitment information company, a total of 43.1 percent of the 455 respondents said they were “already acting to change jobs” or “considering changing jobs.”3

Among those actively searching or considering a new job, the average satisfaction rate with their current employers dropped to 57.3 percent from 72.7 percent when they entered. Some have complained about long overtime hours, low salaries and insufficient in-house training.

The country’s employment system is based on hiring new graduates all at once in March, and even hold job recruitment expos for it. Prior to that, students also engage in job-hunting activities so that they can secure employment by the time they graduate.

According to a ManpowerGroup survey, 37 percent of Japanese millennials expect to work for the rest of their lives, making their retirement expectations one of the lowest in the world.4

As the Japanese economy has experienced fluctuating recessions and booms, workplace issues, and lack of job security, millennials have a pessimistic feeling towards the economy making a strong return and creating employment opportunities for them.

As the population continues to age in Japan, millennials feel the need to support a larger number of older people in the country. Even though Japan has modern means of transportation, advancements in technology, lower crime rates and excellent public health services, millennials don’t have the security of employment that their parents and grandparents had before.5 This lack of job security has contributed to a more cut-throat competition in the job market which can lead to a decrease in motivation and optimism towards developing healthier work cultures.


A rise in foreigners and seniors

Japan is slowly yet definitely internationalizing. Its driving force is the demographic change, where the country’s population is ageing rapidly and shrinking. Now, there is a never-before-seen increase on foreign tourism, and the preparations for the 2020 Tokyo Summer Olympics, resulting in a country who is in desperate need of more workers to fill jobs.

Prime Minister Shinzo Abe currently wants to bring in more foreign workers. His highly controversial proposal to accept hundreds of thousands of people to fill blue-collar jobs by 2025 is still unaccepted by some as Japan is known to have traditionally shunned immigration.6

These foreign workers will be allowed to stay in Japan for five years under a framework that only covers five industries — agriculture, construction, lodging, nursing and shipbuilding.7 They are also required to pass a test, demonstrating their proficiency and expertise in the field and the Japanese language.

The proposal will make solutions to the severe labor crunch in the country while creating jobs for foreign workers, which have been limited to highly specialized positions due to concerns of an influx of immigrants and increase in crime.

Japan’s government accepted that proposal in an unprecedented move to let in more immigrant workers than ever before – 300,000 throughout the next five years.

People working into their 70s and beyond will add a new facet to its reputation as a nation filled with an extreme workforce. PM Abe seeks to keep citizens in their senior age employed longer so they can help with the tax base and ease the burden on government spending, as the Japan keeps up with the world’s fastest aging population.8

This population has surged in social security spending, accounting for about one-third of government outlays in the fiscal year that ends in March, some of which were funded by debt. Hence, Abe is advancing legislation to encourage companies to abolish retirement ages and develop measures and policies to keep people on the job past the age of 70.

The government is also considering a new option of allowing workers to delay their pension payouts to age 75. Only about one percent of the eligible population taking advantage of the existing option, under which they can delay up to age 70 in return for a more than 40 percent increase in payments.9

A higher percentage of Japan’s population compared to the rest of the world is aged 65 or older, and their life expectancy at birth of 84 is tied with Switzerland for first place, according to a World Bank report.


A Call for Employment

Japan expresses an urgent need for employees in sectors like construction, agriculture and ship-building, all over the country. The hospitality and retail industries that require English and other language skills from future applicants continues to boom as tourism increases along with it.

Nursing and homecare workers are also needed to care for the growing graying population. According to a BBC report, if PM Abe’s proposal pushes through, more than 345,000 foreign workers are expected to come to Japan to fill those roles across all these sectors in the next five years.10

PM Abe also wants to allow low-skilled workers to stay for five years, and to introduce a renewable visa for skilled workers that would allow them to bring their families to Japan.

Critics of the plan fear it could provide an easier path to permanent residency, furthering the controversy of the proposal. They also expressed concerns that foreign workers would be the cause of crowded cities and pollution, and would choose not to live in rural areas where they are needed the most.

Either millennials make up for most of the Japanese workforce or foreigners and seniors, this will be the new normal for a Japanese work environment and the country should be able to adapt to the changes.

Feature image: Not a chapatsu in the place: New recruits for Seven & I Holdings Co. attend an initiation ceremony in Tokyo, with nary a lighter-hued hair in sight. April marks the start of many young people’s working lives in Japan. | AKIO KON / BLOOMBERG

References
1. https://medium.com/@IZAWorldofLabor/new-generation-of-japanese-workers-choose-a-job-for-life-5a57d2c0dc90
2. https://asia.nikkei.com/Business/We-lucky-few-Japan-s-millennials-reshape-their-country-s-drab-workplaces
3. https://english.kyodonews.net/news/2018/06/6207be1173e0-feature-surveys-find-young-generation-in-japan-positive-about-job-change.html
4. http://www.kiwireport.com/japanese-millennials-compared-rest-world/
5. http://blog.teamexcellence.com/millennials-in-asia-how-they-changed/
6,10. http://www.bbc.com/capital/story/20181210-more-seniors-more-foreigners-how-japan-is-rapidly-changing
7. https://english.kyodonews.net/news/2018/05/2f6e0d37f0be-japan-to-welcome-500000-foreign-workers-to-help-plug-labor-shortage.html
8,9. https://www.japantimes.co.jp/news/2019/05/23/national/social-issues/septuagenarian-job-hunters-become-japans-new-normal/#.XSR4N-gzbSH

EDITOR'S PICK OF THE WEEK

China economic growth

China’s Challenging Search for a New Model of Economic Growth

By Danny Leipziger China cannot continue to rely on exports to drive its growth, but what are the alternatives? China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...

WISE DECISION MAKER GUIDE

POWER INFLUENCERS

Emerging Trends

The Future of Global Trade