Home Blog Page 1047

Tamago-ya – The Bento King of Tokyo

By Seungjin Whang

Tamago-ya (meaning “Egg-shop”) was founded by Isatsugu Sugahara in 1975, as a small mom-and-pop bento (“boxed lunch”) shop. Under the entrepreneurial leadership of Chairman Isatsugu and his son President Yuichiro Sugahara, the company grew rapidly to become the largest lunch box producer in Tokyo, Japan. As of 2019, it produced and delivered 70,000 boxes a day, employed 650 people, and grew revenue to US$80 million. Tamago-ya produced and delivered high-quality lunch boxes at low price of US$4 to office workers in the Tokyo Metropolitan area.

The success of Tamago-ya depended on its unique hyper-efficient supply chain management. It received orders at 9 a.m. until 10:30 a.m., and delivered by noon. Thus, the delivery lead-time was very short, and on-time delivery was a challenge in busy Tokyo. However, Tamago-ya hardly ever missed a delivery deadline. While demand was large and fluctuated from day to day ranging between 60,000 and 75,000, Tamago-ya’s average “loss ratio” (the disposal ratio due to over-production or returns) was only 0.06 percent. This translated to only 42 lunch boxes left over from 70,000 total productions a day.

The combination of strong leadership with customer-focus orientation, empowered workers to achieve continuous improvement, and the unique economic and cultural environment of Tokyo led Tamago-ya to pull off its “magic.”

Bento – the Lunch Box

Tamago-ya offered only one menu per day, but it changes everyday. Each lunch box contained more than six items, most of which were made from organic and natural ingredients (Exhibit 1). The lunches are freshly made each morning and kept warm until delivered. Instead of disposable lunch boxes, Tamago-ya used reusable ones that could be used for up to one year. The overall cost of using reusable boxes was slightly higher than that of disposable boxes, since it took up to nine hours a day to wash and clean all the lunch boxes using specialised equipment and specially-treated water. But reusable boxes offered multiple benefits to Tamago-ya. First, they were more eco-friendly, either by saving trees or avoiding waste. Also, reusable boxes provided van drivers with more opportunities to talk to customers as they collected boxes after the lunches were finished. Valuable customer feedback could be obtained just after the meal. Last but not least, due to the pick-up, customers were obliged to consume the lunch by 1:30 p.m. in its best condiiton.
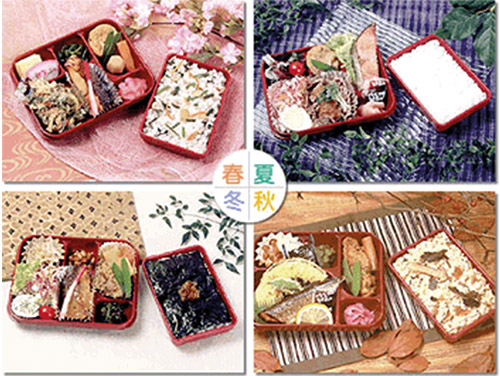
Exhibit 1


Van Drivers the Utility Players

The combination of strong leadership with customer-focus orientation, empowered workers to achieve continuous improvement, and the unique economic and cultural environment of Tokyo led Tamago-ya to pull off its “magic.”

Tamago-ya did not have salespeople, nor did it spend money on marketing. Instead, van drivers promoted sales when they delivered lunch boxes; they visited offices near their existing customers and introduced the company and its product. For customer retention, van drivers kept close communication with customers when they delivered lunches or picked up empty boxes.

All new customers needed to be interviewed by Tamago-ya and registered in its customer database before they placed daily orders. To reconcile the flexibility to customers and the commitment by Tamago-ya, it screened new customers both by their order size and their location – that is, from a delivery efficiency perspective. Tamago-ya did not accept all potential customers.

Demand Forecasts

Tamago-ya’s forecasting fully leveraged the information captured by van drivers. Every evening, Tamago-ya’s managers and van drivers in each region held a meeting to forecast the number of lunch boxes customers would order the next morning. The primary information source for forecasting was the van drivers’ daily reports. Every day, van drivers wrote a report including their own forecasts of the next day’s orders as well as customer feedback on today’s menu. When a van driver visited customers twice a day, he communicated with the person in charge in an informal and friendly manner, and listened to her evaluations of the day’s menu. The driver also asked her for an estimate of the number of orders for tomorrow. Customers talked to van drivers frankly: “Next week, many people will be away from the office attending a big trade show,” or “Some colleagues say beef steak was a little too salty.” Tamago-ya also used causal data, such as weather, day of the week and the month, and the menu, to forecast demand.

Production and Logistics

The key question about Tamago-ya was how it could produce and deliver an uncertain number of lunch boxes within a short delivery window to so many customers geographically dispersed in the heavily-trafficked Tokyo area.

The key question about Tamago-ya was how it could produce and deliver an uncertain number of lunch boxes within a short delivery window to so many customers geographically dispersed in the heavily-trafficked Tokyo area. The answer can be summarised in the following directives:

• Dual-response production: First, build a stock of lunches up to a low-end forecast of the demand, and later, build more (if necessary) based on the up-to-date estimate as actual orders arrive. Tamago-ya counted on five key suppliers who were both nimble and flexible. Tamago-ya committed to the low-end forecasted quantity of ingredients on the previous day, and also carried an option to ask for more if necessary on the morning of production.

• Time-phased prepositioning of stocks: Divide the entire market into two regions by distance from the factory. Dispatch the first batch of vans early to the remotest region well before the order closing hour, with each van carrying an estimated quantity of lunch boxes. (This practice was often called “inventory on wheels.”) After order receipts were completed, dispatch the next batch carrying the exact amount of orders to the nearest region. Transfer stocks across vans to fill any demand-supply gap within and across regions. Use standby vans to adjust any remaining gaps. In fact, Tamago-ya applied this concept to three, instead of two, regions.

The company’s typical daily operational flow was:

• 17:00 – 18:00, the previous day: The total number of orders for the next day was estimated as an interval of low and high ends.

• 4:00 a.m. Tamago-ya received ingredients from 30 to 40 regular suppliers, and kitchen staff started cooking menu items.

• 6:30 a.m. Factory workers started assembling lunch boxes by putting the items together. Since the company had not yet received any orders, it produced lunch boxes based on the low-end forecast they made last evening.

• 8:30 a.m. The first batch of vans loaded the estimated number of lunch boxes for the farthest customers and departed for their designated routes. Tamago-ya has not yet received any actual orders, but production continued up to last night’s estimate.

• 9:00 a.m. Tamago-ya’s operators began taking orders for the day by fax, by phone, or through the Internet. Production continued based on the previous night’s estimates, but was gradually adjusted as actual orders were received.

• 10:00 a.m. – 10:30 a.m. The first batch of vans arrived at their first customer drop-off. The drivers parked their vans in front of the customers’ buildings and waited for a call from headquarters. As soon as headquarters (HQ) received an additional order from a customer, it called the driver for that route to inform him or her of the new order. Finally, the HQ gave a “go” signal to bring the lunch boxes to the specified office. Some customers received their lunch boxes only a couple of minutes after they placed an order.

• 10:25 a.m. The second batch of vans departed the factory for middle-distance customers just before 10:30 a.m. At this point, Tamago-ya had received almost all of the actual orders for the day. They loaded the lunch boxes specified by actual orders for those who had ordered, plus an estimated number of lunch boxes for the customers who had not yet placed an order. Production continued in parallel, with the final number of orders constantly being adjusted. Tamago-ya finally stopped taking orders for the day sometime after 10:30 a.m. (e.g., 10:32 a.m.).

• 11:00 a.m. The third batch of vans loaded the final lunch boxes to fulfill actual orders and departed for short-distance customers. If the first or second batches over-carried lunch boxes, the third batch carried fewer lunch boxes according to the difference. If the previous batches under-carried boxes, the third batch carried more lunch boxes accordingly.

• 11:00 a.m. – 12:00 a.m. If actual orders were different from the estimate, the dispatch centre instructed van drivers via cell phones to move lunch boxes from one van to another, so that the vans had enough boxes and traveled along optimised routes. This dynamic load transfer was done at any place where vans could be parked together (e.g., a public parking lot). Locations and load transfer were determined between van drivers and an area manager. Decisions were based on their experience and intuition; no IT was used.

• 11:20 a.m. Tamago-ya also had 30 extra vans called “adjusters.” Often than not, Tamago-ya could not fill the difference between its forecast and actual orders. Also, accidents happened. The adjusters were dispatched at the last minute when the vans on the field could not adjust the number of lunch boxes on their own.

Portfolio of Supplies – Fixed and Options

Suppliers were a critical part of Tamago-ya’s core competency. Tamago-ya created a portfolio of two supply sources – fixed and options. The following example illustrates how it worked. On a certain day, Tamago-ya’s initial forecast was 67,000 with its low-end forecast 58,000. These two numbers were shared with all supply chain partners. Tamago-ya used its low-end forecast 58,000 to order ingredients from its regular suppliers on the previous evening. This is the fixed portion of its supply. After it started receiving orders, Tamago-ya updated its database every 15 minutes and shared it with all its partners including its five agile suppliers. These agile suppliers, strategically located near Tamago-ya, were involved in the last-hour demand fulfillment process, serving as options. They brought ingredients to Tamago-ya every 15 minutes in response to the updated orders. Tamago-ya cooked the ingredients to produce menu items, which took another 15 minutes. Once food items were ready, Tamago-ya would assemble 500 lunch boxes every minute. By the time orders were closed at 10:30 a.m., the total number of orders turned out to be 66,880 due to the heavy rainfall in the morning, and the gap of 8,880 between the low-end forecast and actual orders was completely filled when the last batch of vans left the factory at 11 a.m. Tamago-ya had its production facilities close to its suppliers, not to its customers, so that it had more flexibility in procurement. It also maintained relatively small warehouses, since it believed larger warehouses tended to lead to larger inventories. Tamago-ya only kept condiments (e.g., soy sauce) in stock for one week. All other fresh ingredients were delivered on demand, and were discarded if left unused for the day.

They loaded the lunch boxes specified by actual orders for those who had ordered, plus an estimated number of lunch boxes for the customers who had not yet placed an order. Production continued in parallel, with the final number of orders constantly being adjusted.

Tamago-ya’s procurement team spent Monday and Tuesday meeting existing suppliers. They reviewed the performance and discussed future plans in pursuit of continuous improvement. On Wednesday, Thursday and Friday, however, they met new supplier candidates who could bring in new values to the supply chain.

Growth, Social Responsibility and the Future

President Sugahara believed that Tamago-ya might already have reached the optimal size at 70,000 boxes per day. If they grew further, he was not sure how the company would source the quality ingredients (e.g., fresh mackerel) without breaking the current sourcing paradigm. He did not see a compelling reason for growing bigger, and preferred to keep Tamago-ya as a medium-sized private company wholly owned by the Sugahara family. In addition, he believed that the company should not be too greedy. Tamago-ya targeted 5 percent net income, with any excess profit reinvested in equipment, or used for better quality of food and higher employee compensations. It recommended the same attitude to its suppliers. In the same vein of social responsibility, Tamago-ya promoted healthy food (e.g., broiled fish and vegetables) ahead of popular food (e.g., hamburgers and fried meat). Chairman Sugahara said, “Of course, the lunch prepared by the wife is the best, and ours is the second.” When asked, “Why don’t you expand to other regions?” Sugahara replied, “It is not easy to replicate the Tamago-ya model elsewhere.” And he added, “We are happy and proud to be in Tokyo.”

About the Author

Seungjin Whang is Jagdeep and Roshni Singh Professor of Operations, Information and Technology at Stanford Business School. His research interest is in supply chain management and the economics of information systems. Outside, he serves on the advisory boards at large manufacturing companies and a venture capital firm.
What Newly Minted US Online Gambling Sites Can Learn from European Operators

It’s now over 15 months since the US Supreme Court made its historic decision on legalized sports betting. The decision hasn’t really opened the floodgates in terms of states offering legalized gambling, but there has been a steady trickle of new laws passed in states like New Jersey, Pennsylvania and Delaware. It’s not abundantly clear how the landscape will look 10 years from now, but you can be sure that many states will have legalized online sportsbooks and casinos.

However, if you look at places like New Jersey, which has just passed its first year with legalized online sports betting and casino, there are still a few issues to be ironed out. Many of the famous names in US gambling culture – Caesars, MGM, Golden Nugget – are based there, but they still lag behind European gaming giants in several areas. Indeed, many European companies are also based in the new American markets, sometimes behind the scenes.

From looking at some of the new sites in New Jersey, there are certain criticisms we can make. We will refrain from singling out individual operators, and instead focus on areas where improvements can be made in the overall industry.


Live betting and streaming

A good European betting operator will not only offer a wide range of live betting markets, but also the chance to watch sports events for free (provided you have placed a bet). The streaming, in particular, has not caught on in the US market, and there is a sense that bettors are missing out. Live betting is about reacting to shifts in momentum, and operators need to be offering complete coverage for them to retain interest. If live streaming is not possible, then a wealth of stats and data should be provided.


Talk to the Banks

Many bettors are still having problems making deposits and withdrawals at online gaming sites in New Jersey, and it’s down to banks blocking transaction on credit and debit cards because they aren’t clear on the law. It’s an easy fix, but operators will need to liaise with credit card companies and banks to clear it up.


Separate the products

Popular European operators like Mansion will have sports betting, poker and casino, but the brand still separates its products. If you go to www.mansioncasino.com/uk/roulette/, you know that you will find roulette and not have sports betting or poker pushed on you. With some the new US sites, there is a sense that they are casinos with sportsbooks (or vice versa). The products should be linked but separate. That might sound like a contradiction, but players will appreciate degrees of separation when it comes to promotions, customer service and so on.


Bring the horses into the fold

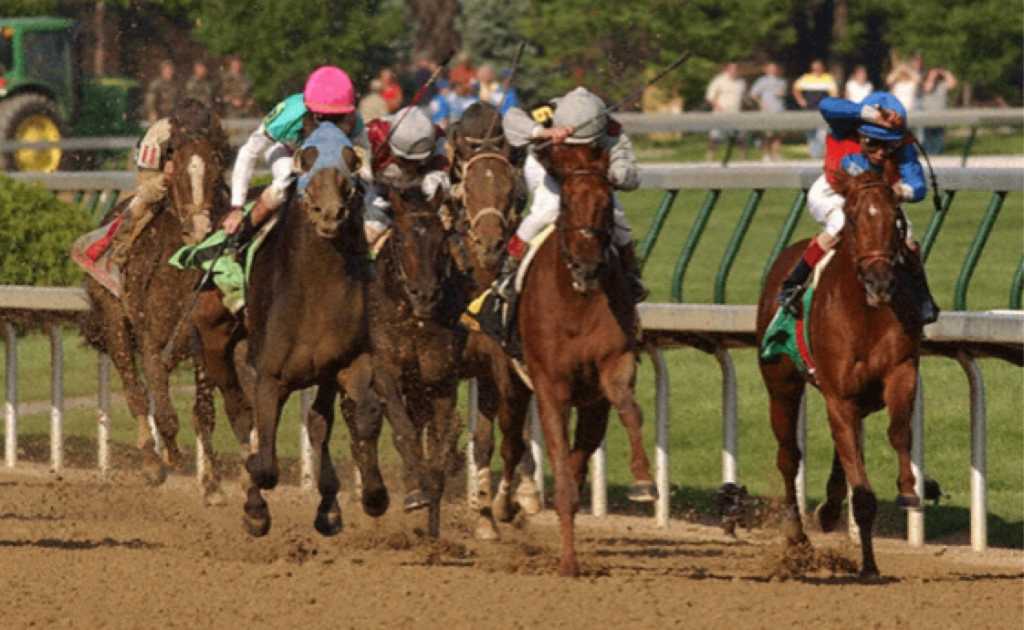
For Europeans, an online sportsbook means coverage of all sports, including horse racing. This is not the case in the States, where betting on horses is still controlled by physical sportsbooks on track or specific racebook operators. Sometimes the goals are noble, i.e. to keep people attending the races, but there must be a compromise. Operators could strike a deal with the horse racing industry on revenue share, similar to the one that funds UK horse racing.


Beat Vegas

Experienced bettors know how to hunt for value. In Europe, it’s almost universally accepted that you will get better odds online than at a physical bookmaker’s premises. The online sites have lower overheads, and they can pass that on to the customers. That’s not been the case in the States, and many online sites will lag behind Vegas odds. Part of it is the taxes applied by the states to online gambling, but, again, some sort of compromise could be made. If bettors don’t get bang for their buck, they will lose interest.


8 Things Every Entrepreneur Needs To Get Started

At some point in their careers, even the most successful and renowned entrepreneurs have needed to rely on tools or other help to get them ahead. No entrepreneur can succeed purely on determination, business nous, or money alone. In order to make it in the cutthroat and competitive world of entrepreneurship, you’ll have to make sure you’ve got the edge. Here are 8 things every entrepreneur needs if they want to succeed.


1. Sufficient finances

This one might seem obvious to anyone who’s ever embarked on a business venture before, but if you want to be a successful entrepreneur then you’re going to need money. Your startup business won’t fund itself; you can get business loans to help you with capital, of course, but you could also use your personal funds. Personal loans can be good ways to amass capital; the website logbookloans.co.uk is great for vehicle owners, and there are plenty of other resources available for different kinds of loans.


2. A reliable vehicle

If you want to be a successful entrepreneur, you need a dependable vehicle. This won’t just be a way to flash your cash to others; it’ll be your workhorse, your way of getting to important meetings, and your means of conveyance when you need to travel long distances. It’s not worth skimping on expense when it comes to buying a car; you need something that’s going to last. The best cars for entrepreneurs combine speed, utility, and affordability to create great all-round vehicles.


3. Dependable staff

It’s not always easy to know exactly who the right person is for a position with your business, but if you’re going to make it as an entrepreneur, this is a skill you’ll really need. Hiring the right staff means you’ll have to make less difficult decisions. Delegating tasks means you can focus on the things that matter to you rather than sweating the small stuff (although you should still keep an eye on these aspects of your business). Don’t make mistakes when you’re hiring and you’ll thank yourself.


4. Convenient premises for your business

Many people miss this crucial step when it comes to setting up a business. If your premises aren’t in the right place, then your business could seriously suffer. Are you a client-facing company? It’s good to have your premises in the centre of a major city. Do you pride yourself on offering a bespoke client experience? Maybe it’s better for you to set up away from the hustle and bustle. Carefully consider what your business needs and set up your premises to match.


5. Good tech

Most businesses these days rely heavily on IT infrastructure in order to operate. You’ll need computers for your workforce that are quick, that can bear a heavy multitasking load, and that won’t die on you when you need them. It might feel tempting to cut costs by opting for budget PCs, but this will come back to haunt you, especially if your tasks are memory-intensive (graphics editing or video work, for example). Make sure your workforce has access to decent tech, and invest in the best 5G mobile offers.


6. Knowledge of the competition 

There’s no point in setting out to establish yourself in a market if you don’t know who else is already in that market. Gaining an understanding of your competitors is vital if you want to know how to offer superior service. This isn’t just searching for your closest rivals on Google; it’s understanding who uses their services, why the customers are going to those companies, and knowing how you can offer a service that will divert customers to you instead.


7. A robust social media presence 

Most businesses these days would be laughed out of the room without an excellent social media marketing strategy. Traditional marketing is all but dead, and in its place, the world of influencer marketing and social media engagement has completely taken over. If you’re thinking of starting a business in 2019, you’d better do away with the old ways. Establish a presence for yourself on Twitter, Instagram, LinkedIn, and Facebook, and make sure you’ve appointed someone who can keep up your presence on those sites.


8. Determination

It might sound like a cliche, but the most important thing for a small business owner to have – especially in a world that’s oversaturated by ambitious go-getters – is determination. Failure cannot spell the end for your business venture. Instead, you should learn from every mistake, treat everything as a learning opportunity, and believe in your business so much that you know you’ll never give it up. Fighters make it in business while pessimists flounder. Decide which one you’re going to be.


——————————————————————————————————–


These are just 8 things we think every entrepreneur needs to get started in the world of business ownership. Was there anything we missed? Do you think anything is more important than the 8 items on this list?


3 Ways To Improve Your Website’s User Friendliness

A website is the main digital footprint of a business. It serves as the access point of the consumers to the goods and services offered by the business. It also provides consumers with ample information regarding various business details such as product or service support, as well as promotions and discount deals. This is the reason why a website should be user friendly at all times and why it’s essential to use the best website builders.

Consider User Feedback

The best way to improve your website is by incorporating user feedback. In this way, you will be guaranteed that your website caters to the needs of your target market. Onboarding forms are great tools that can aid you in gaining insights regarding your user preferences. These forms have the capability to gather user data and feed it directly into your backend system. Hence, the only thing that is left to do is for your users to verify whether the information is accurate. Using online survey forms is another way of gathering user feedback. Compose questions that will enlighten you on what your users want to see and obtain from your website and experiment on implementing these features accordingly. 

Optimize Speed and Navigation

Make sure that your website loads at an acceptable speed to keep the users on your site. Users tend to abandon a site that takes a long time to load its contents. Regardless of the platform or device being used by your client, ensure that your website loads promptly. There are several tools that can verify and assure that your site is up to speed. Additionally, it is also necessary to guarantee that navigating through your site is relatively easy for your users. Design a navigation bar that is intuitive enough for your users to follow in familiarizing themselves with your site. Keep the information in your navigation bar short but concise, so as not to overwhelm your users. You can consult a company that specializes in UX/UI design to make sure that all of these factors are considered.

Offer Relevant Content and Systematic Layout

Your website’s content is an essential factor in ensuring that your site is user friendly. Apart from a visually engaging layout, it is important to guarantee that your website’s content is relevant and of value. It should be effortless for users to get the information they need from your site. In line with this, it is also necessary to choose the appropriate colors for your site. For instance, there should be a suitable contrast between your text and the background color implemented. Additionally, your site can be accessed in different devices such as mobile phones and tablets. Hence, it is important to ensure that the layout of your site adjusts accordingly.

In conclusion, there are several ways to make sure that your website is user friendly. Incorporating user feedback, optimizing your site’s speed and navigation, as well as offering relevant content and systematic layout are just a few of these. You can add several tools to your website, making it more useful according to your purpose, whether you are using it as an eCommerce platform or a blog. Keep in mind that the key to a great user experience is continually improving on your website.

AIMing for Success: The Strengths of the UK’s Junior Market

London Charles I Statue. Equestrian Statue of Charles I, Charing Cross, London, United Kingdom. London Symbols.

By Sam Pearse and Ashmi Bhagani

Designed primarily for the equity securities of small and medium-sized growth companies that either cannot, or do not want to, qualify for the Main Market, London’s AIM has seen over £110 billion of development capital raised by more than 3,600 companies since its inception in 2005.

However, a wider context of the turbulent pound, the slowdown in worldwide economic growth, global trade tensions and the ever-present Brexit ‘fog’ have taken their toll on AIM, causing a lull in fundraising activity more recently. Yet, looking beyond this Brexit-induced uncertainty, a number of advantages remain and it is useful to consider the volume of secondary issuances on AIM compared to IPOs, as well as broader M&A trends across all markets. 

Why is AIM desirable?

The key advantages of an AIM listing compared to a Main Market listing for smaller growth companies are:

• A flexible and lighter touch regulatory environment governed principally by the AIM Rules (and subject to certain exemptions from the EU Market Abuse Regulation);

• “Exchange-regulated” status (as opposed to EU “regulated market” status), which means that AIM admission documents are not pre-vetted by the UK’s Financial Conduct Authority unless the offering involves an “offer to the public” requiring a prospectus;

• No minimum capitalisation, free float or track record eligibility criteria (subject to a one-year lock-in for companies that have not been independent and earning revenues for at least two years);

• Less onerous continuing obligations and more proportionate corporate governance disclosure standards;

• Lower costs associated with seeking and maintaining an AIM listing; and

• Certain tax benefits for qualifying investors, including inheritance tax relief, stamp duty exemptions and the ability to hold AIM shares in stocks and shares ISAs.

The EU is also making efforts to facilitate better access to the capital markets for small and medium-sized companies. Recent changes to the EU Prospectus Regulation (that came into effect on 21 July 2019) are intended to simplify disclosure requirements on both initial and subsequent offerings on SME Growth Markets, such as AIM, in order to encourage the issuance and listing of shares and promote liquidity in the secondary markets.


Geopolitics causes a slowdown

These factors make an AIM listing particularly suited to technology, fintech and life sciences companies, as well as those in the budding medicinal cannabis industry – all of which are sectors currently enjoying a wealth of start-up activity. Correspondingly, these sectors are expected to see a higher volume of activity towards the end of 2019 as the Brexit trajectory hopefully becomes clearer. Nonetheless, while doubts over the strength of the economy linger, wary investors might look to offset some of the risk by investing in businesses with a strong track record, resulting in an increase in traditional sector IPOs, such as natural resources.

A wider context of the turbulent pound, the slowdown in worldwide economic growth, global trade tensions and the ever-present Brexit ‘fog’ have taken their toll on AIM.

It cannot be denied that investors are being cautious for good reason – Europe as a region is more dependent than others on global trade and therefore more sensitive to ongoing geopolitical tension between the US, China and EU, which has slowed economies across the world. It is therefore no surprise that fundraising activity on the EU’s equity capital markets in the first half of 2019 has been unusually quiet. With only five IPOs and a combined total of only £136 million raised in new issuances (including transfers and re-admissions) in H1 2019, AIM is no exception.

However, the situation is not as dire as it might appear on first glance. Diving further into the figures, AIM companies have raised a further £1.97 billion in secondary issuances over the same time period and market liquidity has also continued to improve, as daily trades and average turnover continue to steadily rise. AIM has even cultivated its own giants – as companies such as ASOS, Boohoo and Fevertree prompt speculation over FTSE-100 indexation and moves to the Main Market with their sizeable, multi-billion-pound market capitalisations.

This is clear evidence that there is a deep pool of capital available in London for smaller growth companies, if they know how to reap it. AIM is undoubtedly a trailblazing incubator for smaller companies looking to move into more profitable growth phases, and yet the fact that it has evolved into a suitable venue for these more mature companies offsets some of the high risk/return volatility inherent to the junior market.


M&A and AIM companies

UK public M&A activity across both the Main Market and AIM increased during H1 2019 compared to H1 2018, with the AIM market registering 13 firm offers to date. Interestingly, no particular sector dominates with a good spread across sectors, unlike the distinct bias in pharmaceuticals, biotech and healthcare of 2018. Technology continues to feature and there has also been some consolidation in the finance/payments sector.

Of the firm offers for AIM companies announced in 2019, there is a fairly even spread between UK and non-UK bidders, with the four US bidders representing the single largest non-UK faction. The overwhelming majority of bidders were listed entities, although only two bidders were fellow AIM companies, namely Taptica International Ltd, which acquired RhythmOne plc, and SEC S.p.A, which acquired Porta Communications Plc. Unsurprisingly all but two of the acquisitions were structured as schemes of arrangement. Only one transaction, Mastercard’s purchase of Earthport plc, was hostile, having originally been recommended, and that offer lapsed.

It cannot be denied that investors are being cautious for good reason – Europe as a region is more dependent than others on global trade and therefore more sensitive to ongoing geopolitical tension between the US, China and EU, which has slowed economies across the world.

Even with that brief colour, there are some trends or conclusions that could be extrapolated. For example, the buoyancy of the public M&A market is noteworthy and the flow of transactions concerning AIM companies offers encouragement for those investors less focused on income. We may well be seeing increased activity as the UK faces economically uncertain times. Try as we may, we cannot avoid the fact that Brexit, and the distinct possibility of a no-deal, has negatively impacted the UK economy, at least in the short term. Theoretically, that should mean that there is great value to be found. For example, those companies that operate in sectors that are unlikely to be disrupted by inefficient border controls, such as technology and service companies, and that are sufficiently specialist or that have a global client base, ought to remain fundamentally good businesses attractive to purchasers. That supposition is supported by the earlier comment regarding the technology and payments sectors featuring in the announced deals to date. We might expect that they would suffer from the contagion of the wider economic weakness, creating a buyer’s market. Additionally, the weak sterling would add further lustre to a deal for a non-UK purchaser given the possibility of a currency arbitrage to strengthen an acquisition proposal.

With that outlook, it is logical that we might see a continued level of interest in AIM companies for purchasers. Quite who the buyers will be is trickier to predict. To date, the bidders have been almost exclusively trade buyers, with private equity purchasers absent. There is reportedly a substantial amount of undeployed private equity capital and so that trend may change. Furthermore, a number of activist investor-led or encouraged transactions have featured, albeit the activity is loaded towards the Main Market, with the sales of RPC Group Plc, KCOM Group, Ophir Energy plc and Tax Systems plc serving as good examples where activists have played notable roles. Consequently, we may see those sorts of funds driving acquisition activity, whether to facilitate an exit or to kickstart the next phase of capital growth.


Late 2019 and beyond

Market sentiment on the UK IPO pipeline for H2 2019 (and beyond) remains robust and commentators expect a resurgence of activity once the Brexit dust has settled. This includes a higher percentage of cross-border IPOs coming to both the Main Market and AIM; assuming that the US and China can resolve their trade and tariff issues and there is, in fact, more clarity around the future of UK-EU relations.

Well-prepared flexible growth companies with a strong equity story will find their fundraising windows of opportunity, as demonstrated in H1 2019 and AIM remains the leading junior market in the EU.

However, well-prepared flexible growth companies with a strong equity story will find their fundraising windows of opportunity, as demonstrated in H1 2019 and AIM remains the leading junior market in the EU. It does face challenges from alternative sources of financing, including crowdfunding, peer-to-peer lending, venture capital and competition from alternative junior stock markets such as the NEX Growth Market (which has identical regulatory status but boasts “fast-track” admission, a more engaged service and significant cost reductions). Yet, in a post-Brexit world, it will still be difficult to challenge AIM’s credentials for championing the growth of companies both in the UK and abroad.

About the Authors

Samuel Pearse, a Pillsbury partner based in London, advises clients in the UK and internationally on a wide range of complex corporate and securities transactions. Experienced in M&As, capital markets, joint ventures, investment funds, private equity and finance, Sam advises on cross-border investments, acquisitions, disposals, restructurings, accessing capital markets and corporate issues.

Ashmi Bhagani, a counsel in Pillsbury’s London office, focuses her practice on corporate finance, mergers and acquisitions and investment funds transactions. Ashmi has a broad range of experience in complex cross-border transactions, advising on international equity and debt capital markets financings, mergers and acquisitions, private equity and investment funds and joint ventures.


Empowering Your Leadership at the Pulse of Business in New York City

A Special Interview with Professor Paul Ingram, Faculty Director of the Advanced Management Programme at Columbia Business School Executive Education


Located in one of the world’s most dynamic business hubs – New York City, Columbia Business School Executive Education has an unparalleled environment for advanced business education. It poses great opportunities and offers experiential learning for top executives and aspiring leaders from across the world to learn, to network and to develop capabilities to stay ahead of the business curve.

The programme also benefits from the diversity of its participants and has been particularly popular with Japanese executives. As Japan is known to be a powerhouse country for socio-economic development, the demand for leaders who have strong business acumen and far-reaching vision is urgently needed to meet the challenges of the country’s cultural transformation and hyper-competitive business world.

As part of our special report “How to Lead the Changing Japan,” we had the pleasure of an interview with Professor Paul Ingram, Faculty Director of the Advanced Management Programme at Columbia Business School Executive Education. He shared with us the high ROI one can receive from participating in this programme, the valuable contributions of the Japanese executives, and how the fusion of Western and Japanese business cultures has shaped the dynamics of the cultural and intellectual discourse within the course. The intent is that the programme will inevitably steer these leaders and their companies to long-term success.


The Advanced Management Programme appeals to Japanese executives particularly because it pushes them outside of the boundaries and familiarity of their education and executive development.

Good day, Professor Ingram! Thank you for taking the time to talk to us today. Let’s start this interview by giving us a glimpse of what a day looks like for an academic leader like you?

I spend a large portion of my time teaching, so most days, I’m in the classroom – or teaching in other locations. Yesterday, I taught a group of associates at a global law firm; today, I’ll be in meetings about a new way to bring leadership tools online. This evening, I’ll be travelling to Morocco where I’m teaching Executive MBA students as part of a great partnership programme that Columbia Business School runs with the African Business School. And I’m a scholar, so ideally there’s also time for some research, maybe some analysis of data and some writing, which is how I like to spend the extra hours that I can eek out.


Columbia Business School is known for being strategically positioned at the very center of business in various aspects, and the Advanced Management Programme is Columbia’s flagship residential programme for senior executives. Can you tell us more about what sets this particular programme apart from other executive education courses?

I don’t think there’s another executive education programme in the world like ours. Our programme is different from the other Advanced Management Programmes at other universities. We’re dedicated to experiential learning where the participants are actually doing things as a way of learning. We may have a presentation of important new research, a case study, or a framework, but every day the participants are going to be putting ideas into action, trying them out in unique ways. For doing that, we have New York City as our laboratory. We will learn about presence on the stage of a Broadway theatre. We’ll learn about new organisational designs with a startup company. We will learn about shaping culture in one of the world’s great museums. We’ll learn about teamwork in a jazz club interacting with a jazz band. These are ways to deliver a lesson that you can’t get any other way – and the learnings stick. That’s the pedagogy and the methodology. Then we aim the content of the programme at what’s most important to the senior executives who have joined us, which is strategy and leadership. We may have a session that touches on the latest ideas from branding or consumer behaviour, but it’s different – and designed differently – from what an MBA student might learn in a marketing class. It’s designed for a leader of an organisation, a potential Executive Director or CEO, through the lense of what they need to know about using these ideas strategically. And finally, the participant pool is incredibly diverse, and I can rely on the fact that it is going to have a massive impact on me, just as it does on everybody else in the programme.


Our programme is different from the other Advanced Management Programmes at other universities. We’re dedicated to experiential learning where the participants are actually doing things as a way of learning.

Columbia Business School’s Advanced Management Programme is particularly popular amongst executives from Japan. Can you tell us what features of the programme appeal to them the most and what is some of the best feedback you have received from Japanese participants?  

The Advanced Management Programme appeals to Japanese executives particularly because it pushes them outside of the boundaries and familiarity of their education and executive development up to that point. As I just mentioned, our programme is very experiential – practicing and engaging in simulations and exercises in order to help leaders better understand themselves. It encourages them to do things that they might not have done otherwise, pushing them outside of their comfort zone. But it’s these exercises and moments, combined with the preparation, experience and education that the Japanese executives bring to the programme, that help to give them new capabilities. It’s this combination that creates something special.


How do you make sure that the participants and their organisations will gain the highest return on their investment in terms of knowledge acquisition, career advancement, long-term profitability for business, and other measures of ROI for an executive education? 

Based on research and decades of experience, our programme has a system for helping participants extract learnings and think about how they’re going to apply them. Research has confirmed how important 20 or 30 minutes for reflection at the end of a programme day are to the long-term impact of ideas. It’s now a proven practice for learning, but we were ahead of the curve with how carefully we attend to helping the participants with this reflection. We also think about every element of the programme in terms of its return on investment. We are a unique programme that has actually measured that systemically. We’ve done pre- and post-programme tests on the leaders’ capability, and we’ve demonstrated that they have improved in the course of the programme.

 

What’s the most challenging when addressing the needs of your participants? And how do you meet their expectations?

The biggest challenge is the biggest opportunity: diversity. The participants in the programme are all highly experienced and capable leaders, but they’re diverse in terms of the countries they’re coming from, their backgrounds, the industries which they work in, the organisations they lead or serve, and the paths their careers have taken. This creates challenges of understanding and communication. They have to find ways to relate their organisations to each others’ so they can share learnings that cross between an insurance company in Nigeria, for example, and a financial services firm in the UK. During the first few days of the programme, a lot of time is spent bumping into each other as they’re encountering these differences. But then there’s a shift. It usually happens by the end of the first week after we’ve given people with different perspectives the opportunity to shine and add value. People start to say, “The first day of the programme, I couldn’t have anticipated how I would have learned from this person sitting next to me. And now I can’t believe the lessons I’m taking back to my business from them.” This is almost guaranteed to happen, by design, because if you really want to be an effective senior leader, you must look outside your company, your country, your industry, your area of functional expertise and by seeking out learnings and lessons from unexpected places. The diversity in our class is an incredible resource for this.


We see that, like leaders from around the world, Japanese executives are also struggling to change as the world is changing and managing through the idea that organisations have to become increasingly more dynamic.

Japan is known to have a unique business and work culture, characterised by, among other things, long working hours, group mentality, respect for seniority, and an indirect, high-context communication style. Do these cultural attributes still continue to distinguish the Japanese style of business and how does the Advanced Management Programme take measures to address their needs? 

During each Advanced Management Programme, not only do we see the strengths of Japanese culture in business, we rely on them in our programme. We experience great contributions from our Japanese participants that reflect some of the beautiful things about Japanese culture that persist today, such as the importance of the individual as part of a team and part of a context. We experience the impact that the Japanese executives make to our western culture because of their great skill and respect. 

We see that, like leaders from around the world, Japanese executives are also struggling to change as the world is changing and managing through the idea that organisations have to become increasingly more dynamic. The preparation for change – for dynamism, for reorganisation, and improvisation – may be the biggest challenge that Japanese organisations and leaders, like others, bring to the programme. And at the same time, they have some important resources for dealing with that challenge in terms of managing cultures and collaboration. They however bring a combination of strengths from their business culture and their society to their careers and lives, and then we help add new ideas, experiences, and practices from Columbia Business School and from the other leaders from around the world who are a part of our programme to generate new capacities to help deal with the dynamic business environment that they’re operating within.


Over the years, the Advanced Management Programme has created positive impact on leadership development and bottom lines results. Can you share with us an example of a Japanese executive’s career progression after attending the Advanced Management Programme?  

Recently, one of the executives who attended from a global Japanese company received a significant promotion during the programme. He took part in our modular “2×2” option where executives attend the first two weeks, return to work for six months, and then come back and complete the final two weeks of the programme. He received this promotion during the time when he was back at work and before coming back to the programme. His organisation had gone through some substantial challenges. It was trying to change the way it operated globally, and he found that he was emerging as someone who was being given the opportunities to make a real difference in the organisation’s transition. When he came back to us, he shared energising stories about how he’d been able to apply insights from the first module of the programme to the early stages of his job and then how he was able to use the learnings that we developed together in the programme to be a leader in and make an impact on one of Japan’s most important companies during a critical, transitional time for the company. 


One of your current research projects focusses on the structure and efficacy of managers’ professional networks. Can you share with us your research findings so far? And what is your advice for the participants of the Advanced Management Programme in terms of network development?

That’s a research topic I’ve studied for a career. We have evidence that your set of professional relationships impacts the bottom line, your capacity to get things done, your access to ideas, your advancement in your career, and the efficacy in the performance of your organisation. What I’ve been working on uniquely is the navigation between the idea that we get economic benefits from our relationships and at the same time have a drive that if there’s something that we call a personal relationship or friendship, it should be authentic. That it really should be personal, and it can’t simply be somebody who fits the box in terms of the kind of knowledge or help you need and therefore they become part of your network. How do you navigate between the fact that these are social relationships, but they have economic interests? I have been looking at how leaders navigate this, and the conclusion I have reached is that economically useful network relationships are also authentic – socially and personally. Leaders can’t look around the world and say, “This person would be useful, so I’m going to add them to my network.” Instead, you have to go around the world, build authentic connections to the places you’re going to make investments to reach your professional goals. But your sincerity, your authenticity, the personal connection actually is the foundation for an effective network. In the Advanced Management Programme, we examine and teach practical ways based on research of helping leaders do this. We help them understand their values, what they really stand for as a leader, and how to express that to others.


What do you think are the important qualities a business leader must have in order to drive organisations successfully into the future?

I think the two qualities that are defining successful leaders at this moment are a capacity for ongoing learning and the ability to lead cultures. Learning, because business is evolving and organisations are only going to be more dynamic in the future. From the Advanced Management Programme, the executives who have been the most successful over time have been great learners. Of course, we try to cultivate learning, but there’s also the intrinsic capacity like their curiosity or their openness that they bring with them. Then there’s the capacity to lead cultures. Culture and strategy are the defining inputs, the differentiators, that determine whether organisations succeed or fail. They’re both critically important, however strategy is easier to learn. And while leading the culture is learnable, it’s also an art that takes practice. It takes looking at examples, understanding yourself, and probably some painful failures. It’s the rarer skill, and I think the best leaders of the next generation are going to be great learners who will be artful leaders of the culture.


How do you make sure your programme has a lasting impact for the professional development of your participants?

It’s in the ways we address those two necessary capabilities of great leaders, learning and culture. Our programme invests a lot of time in the leader as a learner. Our opening session in the programme is about the why and how of learning, and then we continue to introduce tools of great learners throughout the programme. And we spend a lot of time focussing on this art of leading the culture, particularly in the second half of our programme. We spend a lot of time – especially during the two weeks of the programme, that take place in Manhattan – looking at original organisations, looking at organisational change and transformation where culture is always critical, where CEOs and the participants who have great leadership experience share their learnings on careers engaging with culture. We’ve seen that it’s a differentiator for what the people who go through the programme need to be successful after that. We focus on what the leaders need, the process and capacity to be a great learner throughout their career, and being effective with the difficult demand of organisational culture.


Japan is known for some of the world’s most extraordinary ideas and cutting-edge inventions, from supercomputers, flying cars and industrial robots to earthquake-proof buildings. What lessons or inspirations have you gained from working with Japanese people?

The Japanese people have incredible capabilities about how to work together and collaborate, and they have a lot to teach the world – about respect and about how an individual’s understanding of him or herself in the context of teams, organisations, nations, and global citizenship leads to effective interactions and productivity. Their innovation capabilities stem from their ability to make the most of combining the insights from different types of people and different ways of thinking. No one genius creates the world’s great works of art, or the world’s great technologies. They’re collective efforts. And, we rely on them in the Advanced Management Programme. They become leaders of our culture; they are generous in terms of their contributions to their classmates, and they’re part of the magic that makes the programme so rewarding for everybody.


On a lighter note, what does success mean to you?

I think about this a lot – because I have a professional investment in a programme that is aimed at helping people reach their success. I pay attention to how participants view success. I look at the people who seem successful and satisfied, and I think about the inputs there. I’ve learned a lot about that through the Advanced Management Programme. 

One of the great eye-openers for me has been revising my own ideas about success over the last 10+ years. The conclusion I have reached is that success is a function of constant learning. The people who have opened my eyes and excited me from the early days of the programme were great learners. I’ve seen over time as people finish the programme and go on, the difference their trajectory for learning makes, which has some personal characteristics – openness, humility, curiosity – but what it means is that success is not a moment in time. It’s not about where you stand in terms of your achievements or your relative status in your field or in your organisation at any one moment. It’s about your trajectory over time. The people who have affected me most are the ones who are focussed on the trajectory. Over time with my engagement in the programme, I’ve come to adopt more of that perspective myself. I don’t know if I could have said it 12 years ago, but now my own definition of success is about my constant learning. If I have a failure that I learn from, I’m usually happy, satisfied, and excited for the future.


Thank you very much, Professor Ingram. It was a great pleasure speaking with you. 

About the Interviewee

Paul Ingram is the Kravis Professor of Business at Columbia Business School and faculty director of the Advanced Management Programme. His PhD is from Cornell University, and he was on the faculty of Carnegie Mellon University before coming to Columbia. He has held visiting professorships at Tel Aviv University, Shanghai Jiao Tong University and the University of Toronto. The courses he teaches on management and strategy benefit from his research on organisations in the United States, Canada, Israel, Scotland, China, Korea and Australia, and his research has been published in more than 60 articles, book chapters, and books.

Ingram’s current research project examines the intersection between culture and social networks. Recent papers investigate questions such as the role of value similarity to foster business networks, determinants and outcomes of individuals’ fit in organizational cultures, and influences on ethical decision making.


Japan Inc. will defy its critics and innovate once more

By Gianfranco Casati

Japan’s corporate leaders face a big challenge in fulfilling the nation’s ambitious plan to create what the government calls Society 5.0, a supersmart world in which digital innovation leads the way.


Tokyo wants to be a global trailblazer in developing Society 5.0 and resolving economic and social problems by incorporating digital tools – such as the Internet of Things and big data, artificial intelligence, robotics, and the sharing economy – into everything from industrial output to social care.

But do Japanese executives have the courage to take the required steps? Historically conservative companies, led by risk-averse managers may be willing to dabble in early development-stage projects, but making the jump to full-on investments and rebasing their businesses on the large-scale use of AI may prove challenging.

The corporate cultural aversion to risk is being pitted against a clear government mandate for change, driven by demographic and economic reality.

The National Institute of Population and Social Security Research projects that by 2030 Japan will have two people in the labor force to support each single senior resident, aged over 65, and by 2060 it will have just 1.5 people in work for every senior resident.

Japan isn’t any different from other nations in wishing to put digital technology high on the agenda. But what sets Japan apart from say, China, is that it will face acute workforce shortages much earlier than other Asian countries, because its society is aging sooner and it has little readiness to accept large-scale immigration.

So Japan must go first using tech to support its economy and its people.

The term “Society 5.0” is straightforward. The first human society was the hunter-gatherer community, or Society 1.0. That gave way to an agrarian life (Society 2.0), and later to industrial society (Society 3.0). Now we are living in the information age (Society 4.0), but slowly evolving to the next stage – Society 5.0, or the age of artificial intelligence.

In Japan’s vision of Society 5.0, as outlined in the Fifth Science and Technology Basic Plan, AI systems will convert big data into new, meaningful intelligence that will impact every element of society. It will be used to make peoples’ lives more comfortable and sustainable, providing people with bespoke and timely products and services.

Japan is well positioned to be at the vanguard of Society 5.0 because it has a huge trove of real and usable data from its universal health care system, tax authorities, and a wealth of operating data from numerous manufacturing facilities.

Tokyo wants to be a global trailblazer in developing Society 5.0 and resolving economic and social problems by incorporating digital tools into everything from industrial output to social care.

In financial services, Japan seriously lags behind some rivals, notably China and South Korea, in adopting digitally-based cashless payment. The government seeks to double digital payments to 40 percent of all transactions by 2027 from 20 percent in 2016. That would still put Japan behind its financially digitally-savvy neighbors. According to estimates by the government using 2015 data from the World Bank and BIS, Japan’s cashless rate was only 18.4 percent, while China was already at 60 percent and South Korea was 89.1 percent.

But the necessary leap forward is not problematic as the technology exists and Japan has in place a secure legal and commercial environment. There is ample technology from around the world to adopt and improve (just as Japan did with automating cars and making video games fun). Japan doesn’t have to innovate, it simply needs to implement.

In health care, Japan is already en route to Society 5.0 with humanoid robots offering medical advice, serving as concierge-type “friends” for elderly care and leading exercise classes.

The elderly play with a humanoid robot Palro, manufactured by Fujisoft, at a day-care center.

Robots have captured the imagination in Japan; they hold a futuristic mascot status.

The private sector, a long-standing and enthusiastic developer of robots, will likely continue to innovate – robots have captured the imagination in Japan; they hold a futuristic mascot status. Innovative humanoid robots will find a natural home in health care.

More generally, the real challenge will be moving from proofs of concepts (POCs) to wide-scale implementation of digital solutions in industry and infrastructure. At Accenture, we have worked with companies in Japan that are experimenting with sensors to detect breakdowns in manufacturing and resources plants; we have advised on using radio-frequency identification, or RFIDs, to identify and move inventory in factories, and we have helped companies build “digital twins” which are literally digital representations of an object, such as an engine or a machine, that enables people to monitor, manage and adjust functions remotely.

It is not just about filling gaps in the domestic economy but about creating a new wave of Made in Japan exports.

But the next step for most such companies will be to scale up solutions. That requires capital, and guts. Skeptics will say that the C-Suite executives of Japanese companies will stop at the proof-ofconcept level because of the cultural aversion to risk. They will prove the technology works but won’t seek wide-scale implementation for fear of failure.

I disagree. From my discussion with executives in Japan I see a willingness to take that next step – and scale up. Leading Japanese entrepreneurs – from Softbank’s Masayoshi Son to Fast Retailing’s Tadashi Yanai are among the most progressive in the world. An emerging generation of executives, such as Hiroshi Mikitani, the chief executive of e-commerce and internet company Rakuten, are demonstrating a willingness to innovate.

Furthermore, even the most conservative of leaders will be compelled to innovate because there is a political mandate to respond to a declining population without importing a lot of talent but relying instead on Japanese ingenuity.

It is not just about filling gaps in the domestic economy but about creating a new wave of Made in Japan exports.

The quality of top Japanese corporate leadership should come as no surprise. After all, Japan was at the forefront of global consumer electronics development in the 1970s and 1980s – led by Sony, Panasonic and Sanyo. It can do the same in Society 5.0.

Achieving Society 5.0 is no easy task, but it will happen. To critics who say Japan is too far behind its peers, notably in financial services, I say fear not, Japan will catch up. To critics who claim robots are just gadgets, I would reply “You were right a decade ago, but not anymore.” To those who argue that Japanese industry must focus first on implementing – and making money from – existing technologies, I would respond, “That is correct, but Japan’s corporate leaders will take the next step because they have a mandate to press on from the government and from society at large.”

That mandate will not fade away but become ever more pressing as the population ages.

About the Author

Gianfranco Casati Accenture’s CEO of Growth Markets. he is responsible for overseeing Accenture’s business in Asia Pacific, Latin America, Africa, the Middle East and Turkey.

MENA’s Growing Young Population is a Huge Opportunity – If We Get It Right

By Geert Cappelaere

Youth as tomorrow’s builders are the most important segment of the population and they pose a great potential to expand a country’s social and economic capacity. But before reaping the economic surplus of a country with a growing young population like the MENA region, it is important to ensure policies that will improve their education and overall health. This article elaborates the key steps on how MENA Generation 2030 or investing in the children and youth of today will secure the MENA countries a more prosperous future.


The population in the Middle East and North Africa (MENA) region is expected to double in size during the first half of the 21st century, with major changes in population age structure. The adolescents and youth population in almost all countries in the region will increase, expanding the share of the working-age population, with fewer dependents to support.

Children and young people are a powerful force of change towards building a prosperous and stable future for themselves, their communities, and their countries.

According to a report by UNICEF, this could generate a demographic dividend: given the right investments and opportunities, the working-age population will be left with more disposable income, which can in turn spur greater consumption, production, and investment – ultimately accelerating growth and shared wealth. Children and young people are a powerful force of change towards building a prosperous and stable future for themselves, their communities, and their countries.

Now is a historic opportunity to invest in the human capital of children and young people, particularly focussing in investment in the health, protection, and education of the children, adolescents, and youth of today, especially those transitioning into their most economically productive years, enhancing their prospects for productive employment and economic growth. This unique opportunity for a demographic dividend – economic growth due to demographic changes – will only present itself between today and 2040.

A demographic dividend does not emerge automatically – it must be cultivated. Healthy, well-nourished, and well-educated young women and men, supported by inclusive policies in a climate of peace and stability can bring unprecedented levels of growth and social progress to the region. But if we don’t invest enough in children and young people, large numbers will continue to be excluded. Conflict and instability will prevail, and demographic changes in the region will become a burden rather than an opportunity.

Countries in the region are at different stages of their demographic transitions. While for some, the window of opportunity for realising the demographic dividend is still wide open; others have limited time left in which to take advantage. If countries fail to invest now in their children, adolescents, and youth and are unsuccessful to prepare and transition them into a productive adult life, the unique opportunity of the demographic dividend will slip through their fingers.

Driven by the transformational impact of new technologies and data, this next generation is key to creating a new path for societal and economical advancement in the region.

Action is needed now to invest in children and young people and it requires the efforts, energy, resources, and ingenuity of all including the private sector. This include investments in early childhood development, lifelong learning, the transition from education to employment, unlocking the potential of girls and women, and engaging adolescents and youth in decisions that may affect them. This is an appeal to the private sector to act not only out of charity and corporate social responsibility, but more than anything else, from the hard-nosed economic perspective of investing smartly in order to unlock unprecedented levels of growth and advances in social welfare.

Driven by the transformational impact of new technologies and data, this next generation is key to creating a new path for societal and economical advancement in the region. Both the government and the private sector should have a joint interest – and a shared responsibility – in ensuring a healthy and well-educated future workforce.


Investing in Early Childhood Development

During early childhood, especially the first 1,000 days of life, the foundations are laid for a child’s lifelong cognitive ability. In the early years of childhood, neural connections occur at lightning speed – a speed that is never again achieved later in life. This process is fuelled by adequate health and nutrition, protection from harm, and responsive stimulation, and early learning.

Early childhood development is seen as one of the most cost-efficient investments in human capital – building the foundations of a child’s physical, emotional, and cognitive development. Rates of investment returns in early childhood are estimated up to $17 per dollar, while potential long-term benefits might even range up to $34 per dollar. Science has demonstrated that early childhood interventions are important to mitigate the impact of adverse early experiences.


Investing in Lifelong Learning

The adaptation of new technologies and innovations are creating new types of jobs, and a large share of children and adolescents will work in occupations that do not yet exist. This rapidly changing social and economic environment calls for new skills seemingly overnight. Skills for ‘adaptability’ – the ability to respond to new circumstances and to unlearn and relearn quickly – are increasingly in demand. The degree on how well the countries cope with the demand for changing job skills depends on how quickly the supply of those skills shifts – be it within the education system itself or through on-the-job training opportunities.

Returns to education are especially high when technology is changing – people with higher human capital adapt faster to change. Human capital also matters to societies; more educated people are more trusting and tolerant of others, and hence, investment in education can lead to increased social cohesion.

Currently for individuals, the private rate of return for investing in education is estimated at 9% for one extra year of schooling. Social rates of returns to schooling are even above 10% at the secondary and higher education levels. Economic returns of socio-behavioural skills – those ‘skills for adaptability’, or as we call them, ‘life skills’ – are often as large as those associated with cognitive skills. Returns to education are especially high when technology is changing – people with higher human capital adapt faster to change. Human capital also matters to societies; more educated people are more trusting and tolerant of others, and hence, investment in education can lead to increased social cohesion.


Easing the Transition From Education to Employment

The transition from childhood to adulthood is not just about acquiring skills, but also about their actual application as reflected in the transition to secondary/tertiary education or the transition from education to employment or entrepreneurship.

This requires a threefold approach. First, education systems have to reflect the content and skills required by the labour market. Second, learning has to include practical skills and exposure to the world of work through internships, apprenticeships or similar opportunities. Third, the private sector has to absorb the new entries into the labour force, either by creating jobs or by providing an enabling environment for young entrepreneurship.


Unlocking the Potential of Girls and Young Women

Labour force participation of women in the MENA region is remarkably low. The gender workforce participation gap in the region is actually the largest in the world – which means the region is forgoing an important share of its human capital and constraining its economic growth. Closing this gender gap would unleash human capital and contribute to economic and social development, with vast economic growth potential.


Engaging Adolescents and Youth in the Process

Overall, the first step to accelerating the discussion around MENA Generation 2030 is simply to ask young men and women themselves, by providing children and young people with spaces to raise their concerns and share their ideas, and by involving them in decisions that may affect their lives.

Investing in children and young people to unlock the demographic dividend is one area where the interests of governments, the private sectors, and international organisations fully align. This calls for a joint action to invest in the region’s children and youth today to secure a more prosperous region tomorrow.

Featured Image: MENA Generation 2030. Source https://data.unicef.org

About the Author

Geert Cappelaere is the Regional Director, Middle East and North Africa of the United Nations Children’s Fund (UNICEF). Mr. Cappelaere joined UNICEF in 1999 and was, until August 2016, the UNICEF Representative in Sudan. He previously served as UNICEF Representative in Yemen (2009-2012) and Sierra Leone (2005 – 2009).

Carrefour’s History and Exit from China

By Lisa Qixun Siebers

Carrefour is a French retailer with a successful history of being China’s largest and fastest growing foreign retail stores in 1995. However, with the country’s digitalisation in 2010, Carrefour has failed to adapt with the changing consumer and market behaviour which led to its exit in one of the world’s largest e-commerce markets. In this article, the author has cited Carrefour’s successes and failures – from its management strategies to business expansion plans which can become a competitive imperative of learning for multinational companies and industries who need to upskill their approach towards the digital era before it becomes too late for them.


On 23rd June 2019, the French retailer Carrefour, the second-largest retailer worldwide sold 80% of the share of its Chinese stores to Suning International, part of the Suning Group, a Chinese retailer. By then, this used-to-be largest foreign retailer in China has been perceived exiting from China’s market, followed by similar actions taken by the UK retailers B&Q, which sold its 70% stake to Chinese company Wumei Holding in 2014 and Tesco, which sold its 80% share to China Resources Enterprise in 2017. It is important to reflect, after 24 years of operations, why such a worldwide large retailer has taken their steps out of the fastest-growing consumer market, where Carrefour used to be the fastest-growing among all foreign retail companies.

A brief history of Carrefour’s entry and expansion in China can be summarised into three phases.


1995-2001: Market Entry and Development Phase
Carrefour entered China in 1995 through a joint venture and opened the first largest hypermarket in Beijing – Beijing Chuangyi Store. Taking the first-comer advantages, Carrefour had remained as the fastest-growing foreign retailers in China during its operation for about two decades until the Chinese market became digitalised in 2010.


2002-2008: Fast Expansion Phase
Carrefour expanded throughout China in just a few years, led by its China CEO Shi Lerong. Between 2003 and 2006, Carrefour was the fastest expanding foreign retailers in China, with over 10 stores opening each year. During this time, Carrefour had established several flagship stores and procedures in China. In 2004, Carrefour introduced its first fresh food store called Guanjun Supermarket in Beijing. In 2011, Carrefour set up a top-level food security lab in its Shuangjing Store in Beijing, which was the first of this kind in China. The lab links to other 42 smaller labs to enhance food security, becoming an example of the provision of high-quality food.


2009-2018: Decline and Rescuing Phase
Slowing down expansion
In 2009, RT-Mart from Taiwan, replaced Carrefour China by owning the largest number of retail stores among foreign investors in China’s retail industry. In 2010, online retailing or e-tailing started to soar in China. By 2017, China has become the world’s largest e-commerce market, accounting for 40% of the value of worldwide e-commerce transaction, up from less than 1% in 2007. China’s online retail market has also become the world’s largest, with 38% annual growth rate (US$830 billion), compared to 14% in the US. To respond to the changing habits of Chinese consumers from in-store shopping to online shopping together with the increase in rent especially in the 1st and the 2nd tier cities, where Carrefour opened most of its hypermarkets, the retailer started to close some stores. Carrefour China closed its Xiaozhai store in Xi’an, Northwest of China, being its first store closure. By the end of 2015, Carrefour had 228 stores. In the same year, it closed 18 stores to 210 until its exit in 2019.

Variating retail formats
To respond to Chinese consumers’ preferences for convenience, Carrefour opened its first neighbourhood store in 2014 – Carrefour Easy and Carrefour Express convenience stores in affluent residential areas in Shanghai, targeting middle-class residents. These were directed by its new CEO in China Tang Jianian (Thierry Garnier). The fast growth of its convenience stores was contributed to Carrefour’s both store and sales growth rate in 2016 according to the data from China Chain Store and Franchise Association (CCFA), which ranked Carrefour as the 11th largest retailer by sales in 2016 being the 4th among foreign retailers in China.

In 2015, Carrefour introduced its online shopping tool to boost its market share. In the same year, Carrefour opened its first shopping mall in Beijing, where the company rents out its store spaces to other retailers to attract customer flow and spread the cost. It was also the first time that Carrefour purchased land to build and manage a mall, which was its biggest in Asia. This format offered Chinese consumers new experiences in shopping. One of Carrefour’s senior executives commented:

One hypermarket is about 8000 to 10000 square meters, a large mall is about 20000 to 30000 square meters. Apart from a hypermarket, the mall includes 65% of rent-out space for restaurants, a cinema, KTVs, a gym, a SPA, beauty businesses, children’s education places, clothes shops, and so on … The purpose of our shopping malls is to attract customer flow through various lifestyle formats (finance.sina news, 2015). 

In 2018, Carrefour opened its first smart retail store, Le Marche. The retailer offered many private labels in its stores such as Carrefour Quality Line and French Touch brands, targeting middle-class consumers. However, this action was a little late to catch up with the market needs, by the exit, the retailer had only 24 smart retail stores. It could not replicate its small-sized store model in France (over 6000 stores) in China. 

However, this action was a little late to catch up with the market needs, by the exit, the retailer had only 24 smart retail stores. It could not replicate its small-sized store model in France (over 6000 stores) in China.

Developing distribution systems
Only until in 2015, Carrefour started to have its own distribution centre after 20 years of  operations in China. By the end of 2017, the retailer set up six large warehouse logistics distribution centres in Hunshan (East China), Wuhan (middle China), Chengdu (Southwest China), and Tianjin (North China).

Nevertheless, the above strategies did not help Carrefour to regain its development potential in China’s market.


2019: Market Exit

Apparently, Carrefour took corresponding strategies for its development in China at both the pre-digital and the post-digital age. However, why did this retail giant just fail in the market? There are several main internal and external reasons.

Carrefour kept its conventional behaviours of charging fees from its suppliers, continuously reducing expenditure on human resources, and other expenses in order to improve profits, reflecting the similar strategies the retailer used to make a profit in the first two decades of development in China.

Short-sight of management without a long-term strategy
Carrefour’s catching-up strategies used to respond to the fast-changing digitalised retail sector in China were lack of focus. For example, the new modern retail formats Carrefour established as mentioned above including Guanjun Supermarkets, Carrefour Easy, and Le Marche were developed by a conservative and trying-out attitude. By doing so, Carrefour kept its conventional behaviours of charging fees from its suppliers, continuously reducing expenditure on human resources, and other expenses in order to improve profits, reflecting the similar strategies the retailer used to make a profit in the first two decades of development in China. By this conservative approach and not investing sufficiently on human resources, financial resources, and material resources, Carrefour was unable to transit successfully in response to the fast digitalisation process in China.

Short-term performance management
It was Carrefour’s performance management system that led to the short-sight management approach. This system was implemented by its staff from the middle to the top level, from boards of directors to managers, with a type of utilitarian mentality. This approach was largely derived from the focus of profit-making of the Carrefour Group. Since the previous Carrefour China CEO Luo Guowei (Eric Legros), a consultant and a professional manager, had taken the position in 2006, the management orientation of the retailer in China became more toward profit-seeking. These were represented by their cost-reduction strategies, the establishment of CUU (city-based merchandise centres) and new product development concepts. Specifically, when the sales increased, related expenses could be increased; otherwise decreased. Such tight financial policy affected the long-term competitive advantage of the company.

The profit-orientated performance management system also resulted in the short-term employment of senior managers. Carrefour hired its professional managers in China up to three years only, with a maximum once re-election. This period is insufficient for long-term business planning and vision. As a result, the professional managers focussed more on their financial performance during their time of service. Consequently, their successor may have to deal with any challenges left over by the former manager.


Late development of the supply chain management system and over-centralisation
Carrefour did not have its own distribution centre until 2015. By then, most of the goods had been delivered by suppliers to stores. The previous system caused inefficiency for managing both costs and sustainable growth. The reason for this late development was derived from the lack of emphasis on distribution centres and logistics management.

Early 2015, Carrefour reduced its 24 CCU (city-based merchandise centres) to six, located in various areas, including those in Shenyang, Northeast; Beijing, North; Shanghai, East; Wuhan, Middle; Chengdu, Southwest; and Guangzhou, South China. By doing so, Carrefour centralised its merchandise systems in China that was established in 1995 when the retailer entered the Chinese market. After this new establishment, the regional directors of these six big regions terminated their duties for supply and started to focus on store operations. The CCUs contributed to the increased centralisation of power from stores or store managers to each CCU, making the profit more transparent, leading to an increased profit of Carrefour China as a whole.

However, the CCUs replaced parts of the previous role of each region, and each region needed to allocate the purchasing power to an increasing number of employees who were responsible for supply. Consequently, Carrefour shifted staff from stores to CCUs, thus reducing the staff in each store from 15 employees in each department before CCUs’ establishment to six after. As a consequence, many experienced store managers left Carrefour and the morale of store staff became low.


Final Remarks

Overall, the challenges that Carrefour faced in China was also largely influenced by the fast growth of online retailing, with one-stop shopping becoming gradually unfavourite by Chinese consumers. The hypermarket format has entered its decline period in the digitalised Chinese retail sector. In addition, multinational retailers are not in the first position to realise the changes in the fast-changing Chinese market, especially, the strategic decisions of the multinationals are mainly made by their home-country management system. When the home-country decision-makers have realised the changes in China, it is often too late.

About the Author

Dr Lisa Qixun Siebers ([email protected]) is from The Institute for Retail Studies, Stirling Management School, University of Stirling, Scotland, UK.

Green Sukuk: Islamic Finance Contribution to Sustainable Environment

By Dian Andari and Yunice Karina Tumewang

The search for sustainable and Shari’ah compliant investing is over. Green Sukuk is on its way but not without a few bumps on the road. This article highlights Green Sukuk as an environmental-friendly alternative to customary investing as well as the challenges it faces amidst an unknowing public.


In 2018, the Environment Performance Index (EPI) by Yale University, which recorded a positive correlation to Gross Domestic Product (GDP), served evidence that material prosperity supports the infrastructure availability to preserve human well-being and ecosystem sustainability1. However, the index still falls below the target noting that there is room for improvement in the environmental and economic agenda. According to the survey, Sub-Saharan Africa, Middle East and North Africa score the lowest in the index by region. Dependencies of countries in the respective region on oil/gas and mining industry, poor public health facilities and low commitment for research and development to promote innovation in alternative renewable energy contribute to the depleted index scores.

Providing financing in creating a sustainability development is familiarly known as green finance. According to Climate Bonds Initiative, sustainable projects and infrastructures could be categorised within several pipelines by sectors including transportation, energy, water and waste management and built environment. Upon the Paris Agreement in 2016, green bonds oversubscribed portraying the global positive response. The global green bond market share is dominated by the United States of America with 20% followed by China, France, Germany, Netherlands with 18%, 8%, 5%, and 4% respectively2. Yet, other countries still keep trying to maximise their market share as a contribution to the sustainable development agenda.

With the size of green market share rises, there is growing concern on the poor representation of Islamic finance in the flourishing environmental conservation agenda, and concrete actions from all stakeholders are needed to improve this situation. Moslem and Moslem-populated countries seem to be left behind in the sustainability development agenda. This is a contradiction to the Islamic finance spirit. Islamic finance emerges as an alternative for the Moslem population to life based on Islamic worldview. Fundamentally, the ultimate goal of Islamic law (maqasid Sharia) to create a just socio-economy by managing resources sustainably should be taken into account. While the growth on material prosperity is constantly advertised through the financial industry, the role of Islamic finance in actively getting involved in environment preserverence remains undistinguished. The focus on wealth creation by disregarding the environment misleads the Islamic finance and economics’ function in achieving prosperity for human and nature.

It seems quite challenging for Green Sukuk to develop as not many companies would issue Sukuk in regards to green purposes which is ethically and socially responsible. Hence, the market size for Green Sukuk may not be attractive enough for investors (public). This conundrum, however, could be improved by further education to bring more awareness to the public.

While most of the Muslim-majority countries are categorised as developing countries with low GDP, the insignificant effort to target environmental performance as the focus of national budget would be allocated on other grounded matters. On the other hand, higher GDP Muslim countries, whose source of national income comes from oil and gas industries,  contribute to the environment depression causing the EPI plunged into low score despite the high level of material wealth. For instance, out of 180 countries, United Emirates Arab placed 77 and Saudi Arabia placed 86. Despite their average total GDP of USD 432.61 billion and USD 769.88 billion, according to the International Monetary Funds (IMF) in 2018, their carbon emission per capita contributes to their failure in achieving higher EPI scores3. There should be reformative actions by the state to tackle the environmental and sustainability issues as GDP only will still fail.

For this reason, in July 2017, Malaysian company Tadau Energy issued the country’s and world’s, first green sukuk with a 250 million Malaysian Ringgit (RM) paper to fund the construction of large-scale solar plants4. Green Sukuk comes with the added value of using the proceeds to finance the world’s transition to a low-carbon economy. As such, green sukuk can help combat climate change by paving the way for climate-smart investments in environmentally friendly projects that are based on sustainable resources.

Following the success of Green Sukuk in Malaysia, Indonesia has tapped the issuance of the first sovereign Green Sukuk denominated in US dollar in 20185. Following the Paris Agreement in 2016, Indonesia inciting the commitment on environmental sustainability promulgated a series of legal and policy instrument including Presidential Regulation (PERPRES) No. 61/2011, National Action Plan to Reduce Greenhouse Gas Emissions (RAN-GRK) and the Presidential Regulation (PERPRES) No. 71/2011, the Implementation of a National Green-House-Gas (GHG) Inventory. Indonesia issues Green Sukuk worth US$ 750 million with a five-and-a-half-year maturity. During the first period of issuance, Indonesia’s Green Sukuk was oversubscribed by the market6. The market reaction was motivate by the need for public company engagement in ecosystem preservation by the public.

However, a constant downturn on performance breaks the market expectation on the Green Sukuk’s public enthusiasm. It seems quite challenging for Green Sukuk to develop as not many companies would issue Sukuk in regards to green purposes which is ethically and socially responsible. Hence, the market size for Green Sukuk may not be attractive enough for investors (public). This conundrum, however, could be improved by further education to bring more awareness to the public.

Thus, assurance must be given to investors to utilise Sukuk proceeds in line with its economic value and green standards. At this stage, government support through various regulations with reward and punishment mechanism must be imposed.

Furthermore, its small market size poses numerous problems with the number of regulations available to govern Green Sukuk. There might also be a problem with the liquidity constraint in developing Green Sukuk as the market size of Green Sukuk is still new and small7. Additionally, with regards to green technology, there might be difficulties for investors to participate as Green Sukuk involves investment to develop and further contribute to the technology in regards to the environment8. The uncertainty and high-risk profile that comes with the development of new technology would deter investors from investing due to the fear of not obtaining returns from their investment. Thus, assurance must be given to investors to utilise Sukuk proceeds in line with its economic value and green standards. At this stage, government support through various regulations with reward and punishment mechanism must be imposed.


Conclusion

To conclude, we acknowledge that Green Sukuk is still in the infant phase, thus it takes time and requires proper governance and regulations to grow into a million-dollar investment platform.  A strong infrastructure requires an equally committed government to ensure that measures are taken to approach Islamic Finance holistically. Islamic finance does not only incorporate Sukuk, but instead a whole new way of banking that abides by the Shariah principle. Green Sukuk is the catalyst that would open more doors for Islamic Finance to develop and expand its horizons – not limited only to Islamic countries but also to the rest of the world. The notion of Green Sukuk owes itself to when socially responsible investments are made with regards to the environment.

About the Authors

Dian Andari, S.E., M.Sc. earned her Master of Islamic Finance and Management degree from Durham University, United Kingdom. Currently, she is working at Universitas Gadjah Mada Indonesia as an academic assistant. She is interested in corporate reporting, Islamic finance, and governance issues. Her current research involves accounting innovation and regulation trajectories and religious aspects on accountability.

Yunice Karina Tumewang, S.E., M.Sc. currently serves as a lecturer at the Accounting Department of Islamic University of Indonesia. She earned her Master Degree in Islamic Finance from Durham University, United Kingdom. Her research interests are Islamic Banking & Finance, Islamic Pension Fund, Islamic Accounting, and Islamic Social Finance.


References

1. Environmental Performance Index, Colombia University, 2018 EPI Report (Environmental Performance Index, Colombia University, n.d.), accessed March 30, 2019, https://epi.envirocenter.yale.edu/2018/report/category/hlt.
2. “Green Bonds: The State of the Market 2018,” Climate Bonds Initiative, last modified March 6, 2019, accessed April 5, 2019, https://www.climatebonds.net/resources/reports/green-bonds-state-market-2018.
3. “World Economic Outlook (October 2018) – GDP, Current Prices,” accessed March 31, 2019, https://www.imf.org/external/datamapper/NGDPD@WEO; “Data for Saudi Arabia, United Arab Emirates | Data,” accessed March 31, 2019, https://data.worldbank.org/?locations=SA-AE.
4. Newsletter, “World’s First ESG Sukuk Fund Another Step Forward for Malaysia’s Responsible Finance,” I-FIKR ISRA, accessed March 31, 2019, https://ifikr.isra.my/news/post/worlds-first-esg-sukuk-fund-another-step-forward-for-malaysias-responsible-finance.
5. Emma Dunkley, “Indonesia Issues World’s First Green Sukuk Bond,” FT.Com; London, February 23, 2018, accessed April 21, 2019, http://search.proquest.com/docview/2121966290/citation/8D7F496D149B4359PQ/1.
6. D Siswantoro, “Performance of Indonesian Green Sukuk (Islamic Bond): A Sovereign Bond Comparison Analysis, Climate Change Concerns?,” IOP Conference Series: Earth and Environmental Science 200 (November 26, 2018): 012056.
7. Lee Irvine, Michael P. Grifferty, and Alice Cowman, “Green Sukuk: The Race to Be First,” Islamic Finance News, November 5, 2014, 44 edition, https://d381ia8eydvlkf.cloudfront.net/wp-content/uploads/2017/05/Green-Sukuk-The-Race-to-be-First.pdf.
8. Raajeev Batra, “Adding a Green Hue to Raising Funds,” Gulf News, March 2, 2016, accessed April 21, 2019, https://gulfnews.com/business/analysis/adding-a-green-hue-to-raising-funds-1.1682828.


EDITOR'S PICK OF THE WEEK

China economic growth

China’s Challenging Search for a New Model of Economic Growth

By Danny Leipziger China cannot continue to rely on exports to drive its growth, but what are the alternatives? China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...

WISE DECISION MAKER GUIDE

POWER INFLUENCERS

Emerging Trends

The Future of Global Trade