Home Blog Page 970

Virtual assets, smart contracts and central bank digital currencies: transforming investment funds

By Marc Piano

Blockchain, smart contracts and virtual assets (together, DLT) can automate and digitise investment fund operations. Fund operators may want to take a close but careful look at harnessing DLT as regulation of the sector accelerates and central bank digital currencies become a reality.

“Innovation” for investment funds typically means investing in innovative companies, innovative investment strategies, or innovative investment assets. Increasingly onerous legal and administrative burdens placed on investment funds mean innovation rarely extends to the fund vehicle itself.

Despite failed predictions of DLT causing immediate upheaval in the financial services sector, global regulatory bodies and national governments are rapidly developing legal and regulatory frameworks bringing DLT into mainstream oversight.

The direction of travel appears clear: DLT could power significant efficiencies in financial services and will be regulated accordingly. Even as DLT development continues, the focus has shifted from experimentation to practical application.

Meanwhile, central banks around the world look set to introduce central bank digital currencies (CBDCs) in the medium term, which may fundamentally alter society and the economy.

Practical legal and regulatory guidance

Against this backdrop, the UK Law Society published the English law-focused “Blockchain: Legal & Regulatory Guidance” report[i] in September 2020. The report considers general legal and regulatory issues around DLT in-depth and offers practical guidance for stakeholders. The topics range across smart contracts, data protection concerns, DLT dispute resolution mechanics, and regulatory and tax treatment of virtual assets.

Investment funds operators curious about DLT and its potential for investment funds will benefit from reading the report and its analysis of issues, which may be similar in other jurisdictions.

Virtual assets

Virtual assets are digital representations of value and their transfers between parties are immutably recorded on a blockchain or distributed ledger. They are sometimes known as cryptocurrencies or virtual currencies, both of which are misleading terms as virtual assets are not nor intended to be representations of fiat currencies issued by national governments or authorities. Virtual assets do not exist outside of their recording ledger.

Tradeable virtual assets (such as Bitcoin, Ethereum and others) as an investable asset class is a topic of already abundant commentary. Investment decisions around virtual assets will always fall to the risk profile and investment strategy of a particular fund and its managers and advisors. Subject to local law and regulation, an investment fund could accept and make distributions in virtual assets. The rapid development and current popularity of decentralised finance – an article in itself – may offer investment managers alternatives beyond ‘buy and hold’ for virtual asset investment strategies.

Virtual assets as representations of equity interests in fund vehicles, and the potential for significant transaction efficiencies when combined with smart contracts fully or partly automating a fund’s operational documents, has received significantly less attention.

Smart contracts and legal contract digitisation 

Smart contracts warranted specific attention in the Law Society’s report and will be of most interest to fund operators. These are containers of self-executing code deployed on a blockchain or distributed ledger which can self-escrow and treat virtual assets in accordance with pre-coded instructions; create, distribute and remotely destroy their own virtual assets; and access and act on third party data sources. These features make smart contracts a practical vehicle for carrying out legal transactions, as the agreed terms can be reflected in code and are not subject to misinterpretation.

Paper legal agreements – such as the constitutive or subscription documents of a fund – are capable of being converted into a smart contract. Any or all of its provisions can self-enforce without further human intervention if desired. However, the code is not the law: smart contracts are still subject to the laws and regulations of the relevant jurisdictions, which may be those of the contracting parties or the parties responsible for or otherwise benefitting from the smart contract.

ISDA’s project to partially automate its product suite through smart contracts is one example of this process cited in the report[ii], known as “digitisation”. Digitisation is a project not to be undertaken lightly and a careful balance is needed between automation efficiency and commercial flexibility[iii].

Potential for funds

What follows are hypothetical possibilities.

Virtual assets representing fund equity interests

Some jurisdictions, such as the Cayman Islands, are introducing legislation recognising equity interests in investment fund vehicles represented by virtual assets[iv]. This can open up new ways to operate an investment fund.

For example, a smart contract representing a digitised subscription document could be instructed – or access third party data (such as anti-money laundering documents and checks) that confirms – that an investor has made a capital commitment having passed all commercial and regulatory prerequisites. The smart contract can then immediately issue a tokenised fund equity interest to the investor.

If a fund digitises the terms of its offering or constitutive documents as well as its subscription documents, these smart contracts can interact with each other. The tokenised equity interests can then be subject to rules and restrictions on transfer and redemptions.

Issue, transfer and redemption of tokenised equity interests all generate data which can be used to automatically maintain registers of equity interest holders. Transactions involving the interests, such as distributions, can also benefit from automatically-generated data. Alternatively, the data can be made available in encrypted form to a fund’s operator or service provider.

Valuation

Valuation policies could be digitised and allow reports to be automatically generated using external data provided to or accessed by the contract at the agreed reporting dates. Where a fund holds virtual assets tradeable 24 hours a day, the smart contract can calculate valuation by reference to external market data to provide live NAV. The smart contract can rapidly distribute these to stakeholders (such as the investment manager, operator, auditors and equity interest holders) when appropriate.

If a fund’s valuation policy offers significant latitude for discretion in valuation, the party responsible for valuation can feed any adjustments into the smart contract. This data cannot be retrospectively altered, which can result in transparency and reduces the risk of disputes.

If there are any valuation disputes, the smart contract could invoke an agreed waterfall of dispute resolution mechanics. These could include both parties negotiating “off-chain” and entering agreed valuation data into the smart contract, or instructing agreed experts to issue a binding decision reflected in amended smart contract valuation data.

Enforcement

If an equity interest holder seeks to exercise excuse rights, a legal opinion could be validated by the fund operator and confirmed to the smart contract. The smart contract can then adjust capital contribution allocations for the investment among the remaining investors and provide this data to the fund operator.

Should an equity interest holder choose or is required to withdraw from the fund for legal or regulatory reasons, the withdrawal process can be activated through the smart contract, which can record all steps in the process including recording the existence of relevant documents outside of the blockchain through a unique and unalterable identifier (known as a hash). If any recalculations of distributions or redemptions are required, these can be provided to the smart contract which can then automatically update relevant registers and records maintained by it.

If an equity interest holder defaults on a capital contribution, an operator usually has a range of remedies. This is one element where full automation may not be desirable so as to retain operator discretion depending on the circumstances of the default. Either way, the “off-chain” actions could be posted to the smart contract, and if any restrictions must be placed on the limited partner’s tokenised equity interest, or the interest is surrendered or transferred, the tokenised equity interest can be frozen, transferred or destroyed and reflected in the relevant register.

Central Bank Digital Currencies

CBDCs are described by the Bank of International Settlements as: “a new form of digital central bank money that can be distinguished from reserves or settlement balances held by commercial banks at central banks. There are various design choices for a CBDC, including: access (widely vs restricted); degree of anonymity (ranging from complete to none); operational availability (ranging from current opening hours to 24 hours a day and seven days a week); and interest bearing characteristics (yes or no)”[v].

Nearly 80% of the world’s central banks are considering issuing some form of digital currency.[vi] It is possible that CBDCs will not use the DLT technology stack. However, if CBDCs do, digitised fund operations could access and use CBDCs to accept subscriptions, make distributions and pay redemptions directly on tokenised fund interests. This raises the possibility of an entirely digitised and automated investment fund operation, including making investments and receiving returns directly using CBDCs.

CBDCs may lead to entirely cashless societies and economies where every transaction is potentially trackable and automatically taxable. Aside from addressing current issues around criminal use of assets, questions arise as to privacy, the role of financial institutions and economic access. For fund operators, however, CBDCs could interact with digitised fund operations, hasten transaction flows and allow new investment strategies.

Legal and regulatory considerations

Numerous legal obstacles must be addressed in any digitisation of fund operations.

Global regulatory acceleration

Jurisdictions and global bodies are rapidly developing recommendations for regulation of DLT. For example, the Financial Stability Board published high-level recommendations for regulation, supervision and oversight of “global stablecoin” arrangements[vii]. Stablecoins are virtual assets seeking price stability through being asset-backed, pegged to an existing fiat currency or using algorithms to adjust supply.

Dencentralised finance activities may also become subject to regulation in the near future.

Financial Action Task Force (FATF) Guidance for virtual assets

As noted in the Law Society report: “Current FATF Guidance on a risk-based approach to virtual asset activities or operations and virtual asset service providers may apply to some stakeholders, parties or counterparties where smart contracts are used to effect legal transactions involving the transfer of virtual assets. In particular, relevant platforms and service providers may be deemed to be virtual asset service providers and fall to be regulated (for AML/CFT purposes at a minimum) by a relevant financial services regulator”[viii].

In practice, many jurisdictions now apply local anti-money laundering and countering the financing of terrorism (AML/CFT) regulatory obligations to any business activities involving virtual assets, including operations of investment funds. At a minimum, these likely require fund operators undertaking customer due diligence on investors subscribing for a tokenised fund equity interest, as this is no different in practice to subscribing for a non-tokenised fund interest.

Fund operators must be alive to any potential additional local requirements, such as higher beneficial ownership verification thresholds. These considerations are particularly important for a fund operator looking to use a third party automated AML/CFT offering.

Whilst smart contracts could access and record AML/CFT documents and data on investors and transactions, the fund remains responsible for compliance. A fund’s operator must be fully satisfied that AML/CFT obligations have been discharged and evidenced before any automated subscription process triggers.

Local regulatory frameworks

Some jurisdictions may have local virtual asset legal and regulatory frameworks.

Popular offshore jurisdictions for investment funds take different approaches. The Cayman Islands passed a law in 2020 creating a full registration and licensing regime for virtual asset service providers[ix]. In contrast, the British Virgin Islands Financial Services Commission issued guidance on the regulation of virtual assets in July 2020[x]. Both jurisdictions approaches are good examples of the proactive approach taken by financial services regulators in offshore jurisdictions, who recognise the legitimacy of and investment interest in DLT and seek to provide regulatory certainty consistent with their global positioning in the investment funds market.

Fund operators should generally consider local laws and regulations around not only virtual asset activities but also securities laws, particularly if they are looking to tokenise their equity fund interests, and take legal advice at an early stage.

The future

As at publication, DLT is enjoying a resurgence following two years of relative stagnation. Whatever the reasons for this, DLT can now offer tangible benefits for fund operators seeking efficiencies in fund operations as well as offering a wide range of new investment assets and strategies. However, fund operators need to carefully consider the implications of automation against a rapidly evolving regulatory landscape.

About the Author

Marc Piano is an Associate in the Funds and Regulatory Team of Harney Westwood & Riegels in the Cayman Islands. He co-authored the Law Society’s Blockchain: Legal & Regulatory Guidance report.
 

References

High Shipping Costs Can Cause a 63% Reduction in eCommerce Sales

Applying high shipping costs to your products can cause almost two-thirds of customers to walk away from an online sale, according to new research by Feefo.

The recent survey, by online review platform Feefo, has revealed that online businesses experience a 63% reduction in eCommerce sales as a result of high shipping costs on their items.

In addition, 79% of the study’s respondents revealed that they have previously abandoned an online shopping cart before they have completed a purchase as a result of such factors. Meanwhile, many others may not even reach the stage of adding to their cart if they are put off by shipping prices.

All this implies sellers to focus on shipping costs reduction. If you ship products locally, it’s easier to take control of shipping prices. But let’s say you need to send a parcel to Poland from the States, and suddenly, cutting shipping costs gets more complicated. 

The research suggests that there are a number of steps that lead to consumers making a buying decision. According to the study, 70% of consumers go online to search as soon as they want to buy something, and 79% of all online shoppers visit Google (41%) or Amazon (38%) the minute they decide they want to buy something.

According to Richard Tank, Head of Digital at Feefo, prices are a significant factor for many buyers, often dictating their initial choice of online business when considering multiple options, including the ‘big two’: Google and Amazon. However, brand values such as product quality and customer service can impact on the financial decision made by online shoppers.

‘Today’s digital landscape is ever-changing and businesses have to meet the needs of their customers across the whole purchase journey in order to maintain sales and brand loyalty.

The Feefo survey of 2,000 UK adults identified many different ticks and behaviours displayed throughout the purchase journey. According to the results of the study, 82% of respondents feel that price is the most important consideration. However, 28% favour product quality and just over half allow a company’s brand values to influence them when they are considering a purchase.

‘Consumer confidence and trust is essential to developing an online business that grows, and lasts,’ Tank commented. “Brands small and large must do everything they can to build relationships with their customers, to ensure they keep coming back for more.’

Tank added that companies should listen to their customers to develop a more personalised experience throughout the purchase journey, from flexible pricing to greater engagement post-purchase. ‘Technology as an enabler, must be fully utilised in order for online businesses to achieve this,’ he noted.

Betting Odds Explained: How do Odds Work in Megapari?

If you are new to online betting, the first thing you need to do is to know what odds are and how they work. It is critically essential since it allows you to know how likely a given event is to happen and the potential of winning. At first, it may seem not very clear, but with the application of simple maths, the Megapari odds are easy to understand.

What Are Betting Odds?

A sportsbook like Megapari uses betting odds to represent the likelihood of a certain outcome in either a virtual or live event. In most cases, you will find odds in the form of decimals or fractions, but some bookmakers write them with a minus or plus sign in front of the numbers, referred to as American or moneyline odds.

In any given event, betting firms can provide different outcomes. For example, in football, a sportsbook will provide you with several options such as home win, away win, or a draw. Each of these outcomes will be assigned a value based on probability. Betting odds not only apply to football but also on several events, including elections, music, and more. In addition to presenting probability, odds also help players to calculate potential winnings from their wagers.

How Betting Odds Work? 

Since there are different types of odds, you need to understand how each one of them works. This is important because you will not get confused when you meet the different odds at various sportsbooks. Some of the most popular types of odds include American odds, fractional odds, and decimal odds.

Fractional betting odds are common in events like horse racing, and you will find them in bookmakers that accept players from Europe. To calculate fractional betting odds, you need to do some division or enter any amount of money. This will show you the amount that the sportsbook will give you when you win.

Many sportsbooks across the universe use American odds, which include the likes of spread bets, money bets, and under/over bets. If you come across odds with either + or – signs, then you should know that your sportsbook uses American odds. Another thing that you will notice is that they are in terms of 100.  

These odds are easy to understand; if it is a plus, you’ll earn over £100 on a £100 wager. And if it’s a minus, you’ll need to wager over £100 to receive £100. The good thing is that you can see the potential winnings on every wager before you can place it. 

Decimal betting odds are also popular in Europe. With these odds, the favourites have lower while the underdogs have higher values. You can use this simple equation to calculate the odds; Return = Decimal Value x Initial wager. Most bookmakers use decimal odds. 

Final Thoughts

Betting odds are vital when choosing a sportsbook since they significantly affect your earnings. If you pick a bookmaker with poor odds, you’ll end up not only wasting your hard-earned cash but also your precious time. The best part is that you already understand what they are, how they work, and the different types available. With the information available in this article, you can now pick a sports betting site with odds that meet your wagering requirements.

New Technology Trends That Spell Trouble

New Technology Trends That Spell Trouble

Humankind thrives in an age where life wouldn’t be fulfilling without technology. The fourth industrial revolution that is driven by technology comes with more perks and conveniences than any other invention in history. Technology has a tremendous positive impact on the way our lives function and expands our capabilities to scale globally and enrich our livelihood. 

However, the more dependent we become on technology, the more it can be leveraged to work against our interests. The significant scale with which technology is entrenched into our lives introduces new risks to safety, political independence, privacy, and even health. Many tech developments can be used to detriment society in the future, and here are a few of them.

Online Gambling

Online gambling was among the first ventures to exploit the entry of the internet in the mid-nineties. The sector has now ballooned to a multibillion-dollar business that is available in nearly every region across the globe. Online gambling allows punters to access a wide variety of games (like buffalo slots) found in brick and mortar establishments without compromising the comfort of their desired location. 

The accessibility of casino services with a few clicks on smartphones and PCs serves as a significant upside, but it is also encouraging the alarming trend of gambling addiction. Pathological gamblers cannot control the impulse to gamble and can result in significant negative consequences. Gambling addicts take the risk despite the results, whether they are losing or winning. Some of the effects of this addiction include:

  •  Mental disorders like depression, anxiety, stress, and suicidal impulses
  •  Alienation from friends and family
  •  Bankruptcy due to uncontrolled spending
  •  Weight loss due to depression

Digital Currencies

The past decade has been spent lauding cryptocurrencies that do not have a physical form and instead operate entirely on the digital platform. Digital currencies have a lot of factors that give them the upper hand over conventional options such as protection from inflation, self-management, more security, easy currency exchanges, and decentralized systems. However, they have drawbacks that have significant impacts. For instance, currencies like BTC and Bitcoin Cash have become the go-to option to make illegal transactions. Since privacy and security are carried with high regard in the cryptocurrency realm, it becomes difficult for authorities to track down users that make illicit transactions. Crypto options can also be used to turn cash that is acquired illicitly into clean money since transaction data is hidden.

Social Media

Social media spaces like Facebook, Instagram, and Twitter have tremendously changed people across the globe interact with each other by making it a small community. Such platforms hold billions of users that share opinions, images, videos, and other forms of entertaining and educative media. 

As helpful as these platforms have been, they are listed among the leading causes of mental health issues and other potential dangers. Some of the risks that social media comes with include:

  •  Cyberbullying
  •  Identity theft
  •  Exposure to offensive content
  •  Grooming by strangers
  •  Invasion of privacy

Spying Smart Devices

The use of smart gadgets today is so widespread that almost everyone has one or two of the devices to make their lives easier. These items make life simpler in ways that could not be thought possible one or two decades ago, including:

  • AI assistants like Alexa and Echo that listen, track, and respond to verbal commands
  • Streaming platforms like Netflix and Hulu that collect viewing history
  • Google Maps track routes to familiar places like home and can identify the most comfortable way to avoid traffic
  • Smart thermostats that know what time one arrives home so that they can adjust the temperature in the house to a comfortable level before you arrive
  • Smart security systems with cameras and motion sensors that inform the homeowner of visitors or intruders.

This info goes to the cloud, and it goes a long way in making life convenient. However, it comes with the risk of potential abuse. Such information in the hands of hackers can turn smart gadgets into recording devices that work against their owners. For instance, there have been cases of security cameras being hacked and used to record and threaten people in their homes. Some measures can be taken like turning off cameras and voice recorders when home, but since they are connected to the internet, none of them can be labelled as 100% foolproof.

AI Cloning

Artificial Intelligence is among the significant reasons that technology has taken in improving our lives in a short period. However, the massive growth of this technology is the key to cloning, which poses a lot of potential threats. For instance, AI technology can clone someone’s voice from hearing just a snippet of audio. This tech can also take a few photos or videos of an individual and create a new image or video that looks original. 

The results are usually so convincing that our brains can’t tell whether it is real or not. In the past, celebrities were the most susceptible to such deep fake technology. However, AI cloning has become so advanced that it only needs a handful of images, video, or audio to train the algorithms.

Facial Recognition

Facial recognition has also been of great help to modern society and can be used to unlock personal gadgets like smartphones and tablets for enhanced security. However, this technology can easily be used for sinister reasons as well. In China, for instance, facial recognition is being used for not only surveillance but also racial profiling. The government uses the technology to track down Uighur Muslims and put them in concentration camps. Facial recognition can also be plagued with bias if the algorithms used to train it are not diverse enough, which leads to a lot of misidentification.

Smart Dust

Motes, also known as smart dust, come in the size of a grain of salt with cameras, sensors, and power supplies, and has helped fields in medicine, security, and other take giant leaps in helping society. On the other hand, they can be turned around and be used for the invasion of citizens’ privacy without anyone noticing.

Conclusion

Along with the positives of technology advancement today, there is no doubt that it can go violently wring when placed in the wrong hands. Some measures can be applied to ensure most of these threats are kept at bay, but some of them require more effort to combat.

The Impact A Second Covid-19 Lockdown Will Have On Global Economy

Covid-19 has decimated the world in so many ways, but a second lockdown may create more financial hardship that even the Great Depression of the 1920s created.

How Would A Second Lockdown Impact the Global Economy?

The Covid-19 pandemic has destroyed the lives of hundreds of thousands of people. This is not just a matter of the lives lost due to the virus but has been due to the impact it has had on the economies of virtually every nation across the globe. Thousands of businesses were shutdown, millions of people were either laid off or lost their jobs, and schools were shut down just about everywhere.

Most of the impact came from an initial lockdown that was imposed by many countries. This forced the closures of tens of thousands of businesses as it was hoped that this would stop the pandemic. However, that does not appear to be the case and now there is talk of a second worldwide lockdown, leaving many wondering if the second such event could destroy the economies of every country on the planet.

The First Lockdown Was Devastating

While there is support for the idea that the first lockdown was necessary, there is also no denying that the lockdown may have had a more crippling impact on the lives of people than if they would have actually contracted the illness. Most who have died from the illness have been elderly or have suffered from some other illness that made them more susceptible to the effects of the virus.

For those who are healthy, the death rate has been less than one percent. However, the impact of the lockdown has been universal for all who have been denied the ability to go to school or work. As reported by the following infographic, the lockdown has likely cost the global economy more than $20 trillion, much of which was lost as salaries, bonuses, and other forms of revenue.

One of the major concerns related to the lockdown was what would happen once businesses were able to open again. These companies have the funds necessary to sustain them during the lockdown and yet still have enough to be able to resume operations once conditions permit them to do so.

The problem is that many have not had the available assets to be able to reopen. Those companies that had loans were still required to pay banks and other financial institutions during a time when they did not have revenue of their own. This led temporary closures to become permanent ones, as thousands of organizations were forced to close their doors for good under the weight of the enormous debt they were still required to pay.

And Now a Second Lockdown?

This is disturbing news on many levels, but even more troubling is the fact that several governments are now considering a second lockdown. Some have already reinstituted procedures and policies to close businesses and schools in an effort to reduce the second wave of Covid-19.

While leaders are attempting to reduce the spread of the virus, the reality is that they are setting a trajectory for a worldwide depression through these policies. According to the Organization for Economic Cooperation and Development, or OECD, a second shutdown would drop the world GDP by more than 7.5%. This would be the largest decline in GDP in more than 60 years. An additional 40 million people would lose their jobs.

Compounding the problem is that many governments may not have the available resources to be able to support citizens during a second lockdown. In response to the pandemic, several countries offered stimulus money to help offset the loss of jobs or income. This gave people the ability to buy necessary goods and keep themselves afloat, even if it was for a brief period of time.

However, this was often money spent that the governments did not have available to them. Plus, there was the added issue of a greatly reduced revenue system, because people have been out of work and have been unable to pay income tax. They also have been unable to purchase many of the common luxury items that would have generated additional revenue for the government in terms of taxes on the items and the labor.

A Second Great Depression in the Making

Any government offering additional stimulus at this point is simply giving away money without any concern about the long-term impact this may have on the country and the world as a whole.

Major commodities are already suffering. It is expected that the gas and oil industry will see a decline of 30% and that capital investments will decrease by as much as 20% during 2021 should a second lockdown occur.

All of these factors are leading some economists to ring the alarm bell that a second Great Depression may be on the way. The first occurred in the late 1920s and lasted for nearly 10 years. In fact, had it not been for the start of World War II the depression may have continued.

At that time, U.S. GDP dropped by 4.3%, but it has already dropped by 8% this year and a second lockdown would surely increase that number. Industrial production fell by 47% across the United States, and that has been seen in many industries globally.

One of the major causes of the depression was increased spending across Europe as a result of war debt and the requirement of Germany and other axis countries to pay war reparations. Money was simply printed that had no real value or backing to it, which caused a worldwide economic collapse.

The stage may be set for this once again, especially if the second lockdown is implemented. People would be unable to work, making the governments responsible for providing some kind of economic relief to assist struggling families to stay in their homes or apartments, purchase food and other needed goods, and pay for any medical issues that may arise. That would put a significant strain on the government, as they already are facing a serious decline in revenue.

The inevitable outcome of simply giving away money that the government does not have available to them will be that these currencies will drop in value. They will have virtually no value at all, much like what happened in countries like Germany during the Great Depression.

Protecting Yourself for Tough Times Ahead

The problem is that Covid-19 is being dealt with in a political way. Very little actual scientific and medical information is being provided that is not tainted by government interference. The recent presidential election in the United States only compounded the problem as both sides painted a picture of this virus that were either too bleak or too positive.

The political impact on this virus is beyond measure. The fear it has generated has probably made the situation 100 times worse and it is clear that the vast majority of countries across Europe and North America are going to impose a second lockdown. Some already have done so.

So, what can you do? The first thing is to consider getting into an asset that does not depend upon any country’s currency. One of the best options is choosing a form of digital currency, such as bitcoin. Because these cryptocurrencies are not impacted by government spending, they will maintain their value. Plus, a significant number of businesses are accepting digital currency as a form of payment.

You can easily pay for any goods or services you need at major retail sites and are able to cash out the digital currency at a major financial institution, giving you hard currency if you need to buy things at a store or other local retailer.

You may also want to consider purchasing commodities that retain their value, such as silver or gold. Should these currencies lose significant value, it is only going to increase the value of the silver, gold, or copper. These are items you can use for trade or to acquire hard currency to be able to conduct business.

If you can afford to do so, it is also a good idea to begin stocking up on non-perishable goods that can help you through another lockdown. One of the biggest problems that many faced was that they did not have items necessary for survival available because people were frantically buying them in large quantities. If you live in a country where it is likely that another lockdown is coming soon, it pays for you to start stocking up on these items so you can withstand 4 to 6 weeks or longer in your home.

Sorry to Dampen Your Mood

It is sad that this is the state the world is about to reach, but the second lockdown is going to be even more crippling than the first. Most people have used up all their available resources and assets, so they are going to struggle to survive and governments are not going to be able to help them. No doubt, should there not be a dramatic change soon, the world is in for a calamity it has not seen for 90 years.

How Can Your Business Adapt to COVID-19 Changes?

2020 has been an extremely challenging year for businesses in every industry as a result of the pandemic and this will only continue into the winter months. Every business needs to sit down and carefully consider how they can adapt to the current situation so that they can continue to operate while protecting the health of staff, customers and the public as a whole.

Client Interactions

One of the main areas that businesses will need to adapt is the way in which they interact with clients. Finding and retaining clients has new challenges as a result of the pandemic with face-to-face interactions severely restricted, so businesses may want to turn to digital forms of communication like Zoom for the time being. When meeting a client or potential client face-to-face, you need to adhere to Government guidelines at all times.

Innovate

When the world disrupts the ordinary, businesses have to innovate and it is those that are able to adapt that have and will survive. Times like this can bring out creativity and entrepreneurial-spirit s you need to think about how you could innovate and succeed in “the new normal”. Speaking to legal innovation specialists will help you to make these identify and make these positives changes to the business while remaining legal and compliant at all times as this can be a challenge.

Become Delivery-Friendly

It is clear that the businesses that are able to deliver are the ones that have managed to thrive during the pandemic, so you will want to think about ways that you can make your business delivery-friendly. Being able to provide products/packages that would be of use to your clients during this time and creating a smooth, safe experience could help you to manage and keep people happy during what is a difficult time for all.

Connect Locally

Now is also a time for supporting the community and coming together (socially-distanced). Try to find ways that you can help and support the local community, which could include gift vouchers, supporting other small businesses and working with the local authorities to help those that are vulnerable.

Focus on Sustainable Growth

It is also important to think about ways to grow your business which are sustainable and cost-effective. Instead of spending a huge amount on digital marketing campaigns, you might find that now it is better to go with options such as a referral schemes, customer loyalty programs and using social media to engage with your target customer.

Hopefully, this post will help your business to adapt and succeed in the coming months and beyond.

What Happens When I File an Insurance Claim?

Although there’s comfort in being able to file an insurance claim, the fact is that many people are not aware of what the next steps are after the claim has been filed. Many people will worry about the state of their claim and wonder if they could have done something different to speed up the process.

According to Baderscott, after you’ve been in a car accident you have two options: you can file a personal injury claim through your insurance company or the company of the at-fault party, or you can file a lawsuit with a lawyer’s help. Once you’ve done that, read this detailed information regarding the process of filing an insurance claim.

Timing Is Everything

It’s understandable to want to wait until you have all the proper documentation to file an insurance claim. However, it is important to note that most insurance companies will only offer an individual about 30 days to file their claim. Although it is important to gather all your information, you should avoid making this error in the insurance claims process and potentially going over your deadline to submit.

The Inspection

After you’ve filed your insurance claim, you will then be visited by an adjuster. The adjuster will look at the property in person and determine if the damage can be fixed with a few repairs or if the whole thing needs to be replaced.

In the event that the damage is minimal, then they will offer you a settlement to allow you to make those repairs. If this is the case, you will need to provide them with an estimate of how much the repairs are going to cost. This will ensure that you are being offered a fair settlement.

The Homeowner Process

When you file a home insurance claim as a homeowner, the insurance company will usually send out a check made out to yourself and the mortgage servicer or lender. This is done to protect the lender as they also have a stake in the property’s repairs. It should be noted that not all the money will be released at once. Typically your insurance company will provide you with enough money to hire a contractor. More funds will be released as progress is made.

Auto Insurance Process

In the event that you damage your car, your insurance company will look over the damages. If the damages add up to more than what your car is valued, they will label the car a total loss. Your insurance provider will write you a check for the car’s value at the time of the accident. If your loan is higher than the payment, then you will need to pay the difference to the lender. This is what you call a “negative equity.”

How Long will My Claim Take?

Perhaps the most common question, and rightfully so, is how long a person’s insurance claim is going to take. The fact is that there are a number of factors that come into play that will determine the speed at which your claim is processed.

  • Extent of the Damages
  • Amount of time it takes an adjuster to get to your property
  • If there has been an agreement on compensation

How Your Settlement Is Determined

To begin to understand how a settlement will be determined, the individual will need to read their insurance policy first. It will tell an individual what is and isn’t covered and how settlements are handled in that policy.

Another factor that will affect a settlement is the type of laws that have been enacted within your particular state. Those state laws are included because there will be times when a homeowner insures their property with less than the replacement value. An attorney may be able to provide you with further information regarding these types of laws.

Hacking the pandemic: how Taiwan’s digital democracy holds COVID-19 at bay

By Kelsie Nabben

Taiwan’s response to the COVID-19 pandemic has been among the world’s best. With a population almost the size of Australia’s, the island nation has reported only 496 confirmed cases of the disease and no locally acquired infections for months.

The unlikely heroes of Taiwan’s success are “civic tech hacktivists”: coders and activists who the country’s celebrity digital minister Audrey Tang describes as the “nobodies” who “hack democracy”.

What began with the hackers of the “open source, open government” movement g0v and student protesters has grown into an experiment in radical democracy that is yielding astonishing results.

‘Fast, fair and fun’

While the notion of “digital democracy” is as old as the internet, few countries have really tried to find out how to practice democracy in digital spheres. In Taiwan, however, there is a strong collective narrative of digital democracy, and government and civil society work together in online spaces to build public trust.

The growth of civic hacking in Taiwan has its roots in the so-called Sunflower Movement, a stream of protests in 2014 against a trade agreement with China.

The pillars of Taiwan’s approach to digital democracy are “fast, fair and fun”.

Taiwan was among the first countries in the world to detect and respond to the virus, thanks to crowd-sourced, collective intelligence through online bulletin boards. Warnings of the virus were first noted in December 31 2019, when a senior health official spotted a heavily “up-voted” post on the PTT bulletin board.

Before long, civic tech hackers were working on open data projects for citizens to interact with live maps, distributed ledger technology and chat bots to find the nearest pharmacy to claim free masks, with stock levels updated in real time to stop panic buying. Audrey Tang dubbed this rapid, iterative, bottom-up process – as opposed to a top-down government-led distribution system – “reverse procurement”.

A “humour over rumour” strategy has also been very successful to combat misinformation, fake news and disinformation. Taiwan is engineering memes to spread public awareness of positive behaviours through the virality of social media algorithms.

Government departments are responsible for addressing disinformation by providing a “memetic” response according to the “2-2-2”: a response in 20 minutes, in 200 words or less, with 2 images.

Alongside dog memes and pink face masks, one of the most successful is a rapid response to halt runs on toilet paper. This featured a cartoon video of Taiwan Premier Su Tseng-chang shaking his backside with a caption saying “We only have one pair of buttocks”.

How hacktivists reached the halls of power

How has the mindset and culture of hacktivism been cultivated to motivate civic hackers to participate in Taiwan’s digital democracy?

First, a figurehead and a manifesto. Audrey Tang is the figurehead, and her manifesto On Utopia for Public Action espouses post-party politics, free speech and deliberation, all enabled through thoughtful and experimental application of digital infrastructure.

Second, a suite of smart digital tools enable discussion, survey and online “telepresence”. These include the vTaiwan and the Join platforms for public policy participation.

Third, inviting participation, listening to community voices, and taking action as a result. Taiwan’s culture of civic participation follows the model of open source software communities. This means working from the bottom up, sharing information, improving on the work of others, mutual benefit and participatory collective action.

Underlying these initiatives and digital infrastructures, is two-way trust. In the words of Yun Chen, a member of the “decentralized civic tech community” g0v:

The first key is trust … it was the trust that made government officers take open data as performance instead of troubles, which led government to initiate open data and be willing to accept tech assistance from civic tech communities.

Despite low overall trust in government and leadership in Taiwan, recent polling suggests 91% of citizens are satisfied with the Central Epidemic Command Centre. Tang has said “the government needs to fully trust the citizens”, and that this trust is reciprocated.

A small experiment

With all of this enthusiasm, I wanted to try participating in digital democracy myself. I had heard Tang quote some statistics on increased public trust in several interviews, but I couldn’t find the source. At the suggestion of my Taiwanese compatriot Chih Cheng Liang, I simply asked Tang for the source on Twitter.

Tang’s response was extremely impressive: in less than 5 minutes, she replied with a link to the relevant Taiwanese poll.

A radical experiment

In many countries, policy makers don’t fully understand the technical and governance dynamics of the digital realm. In Taiwan, we are seeing what can happen when they do: bringing “hacker” tools and methods into the institutions of government to increase public participation in democracy.

It’s a vast change. Digital infrastructures are inherently political, or spheres for political engagement. They emerge out of the interaction between technology and society, and are influenced and constrained by human agents.

Radical democracy is essentially radical. Tang also sits on the board of of American economist Glen Weyl’s Radical Xchange initiative, which aims at “uprooting capitalism and democracy for a just society”.

There is now talk of trying out the collective decision making system known as “quadratic voting”, and other experimental crowd-sourcing mechanisms that have surfaced from the Ethereum blockchain community.

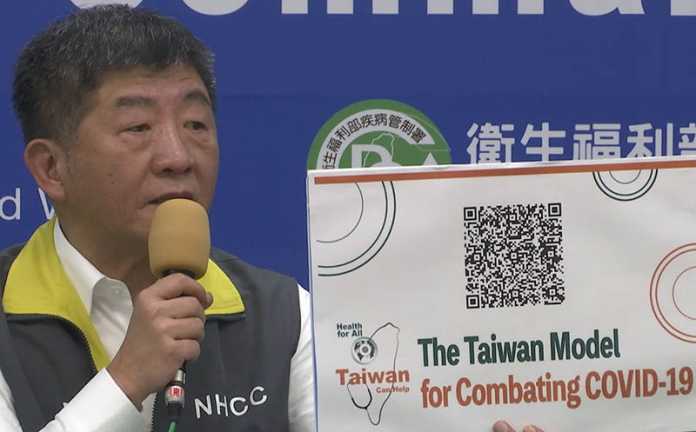
Other countries are free to pick up both lessons and digital innovations from Taiwan’s innovations. Many tools and models have been made available on an open-source basis at Taiwancanhelp.us.

The article was first published in The Conversation

About the Author

Kelsie Nabben Socio-technical researcher on resilient decentralised digital infrastructure and society.I am a researcher in the RMIT Blockchain Innovation Hub and a PhD candidate in the Digital Ethnography Research Centre at RMIT University.I work with designers, builders and makers on code, law, markets and norms.

How Business Travel Will Develop in the Future

The coronavirus pandemic has turned the world upside down in 2020 and impacted just about every aspect of life. One of the most heavily impacted areas has been travel for both business and leisure. Travel restrictions and regulations for quarantine upon arrival had brought international travel to a standstill – but how will business travel move forward?

Businesses Having to Adapt

The restrictions and bans on international travel have really taken their toll, particularly for businesses that rely heavily on travel. It has been a challenging period for many businesses that have had to adapt, but most will be keen to get back to normality as soon as possible, as many favour face-to-face interaction over video conferencing.

Vaccine Hopes

Recent news of a vaccine development suggests that there is light at the end of the tunnel and that things could start to return to normal in 2021. While things look positive, there is still a lot more to be done and it will take a long time for the majority of people to be vaccinated.

Mandatory testing

Consequently, looking forward it seems likely that there will be mandatory testing prior to flights for a while to prevent international transmission. While this is not ideal, it is an important safety measure that will help to protect both individual and public health while still allowing people to fly for professional or leisure purposes.

Making Changes

In addition to this, companies will also have to find ways to adapt when sending employees on business trips. Understandably, there will be a lot of anxiety around being in large groups of people which could still be advised against for a while. Consequently, businesses may start to substitute busy hotels and restaurants with serviced apartments in Singapore and takeaway, for example, to provide safety and comfort during times of uncertainty.

Will Business Travel Recover?

It is the opinion of some that business travel will never return in the same manner even once the pandemic has ended. While coronavirus may well have changed business travel for good, studies suggest that business travel will pick up again although it may take some time. Business travel can bring many perks and is an essential facet of business in some industries. Plus, you only have to look at other major disruptions in modern history, such as the 9/11 attacks and the global financial crisis, both of which recovered despite many predicting that they would end business travel.

It has been a devastating year for the travel industry with many businesses struggling without being able to send employees abroad. While it may be a long road back, it seems likely that business travel will recover and the hopes of vaccination beginning next year will hopefully help this to be sooner rather than later.

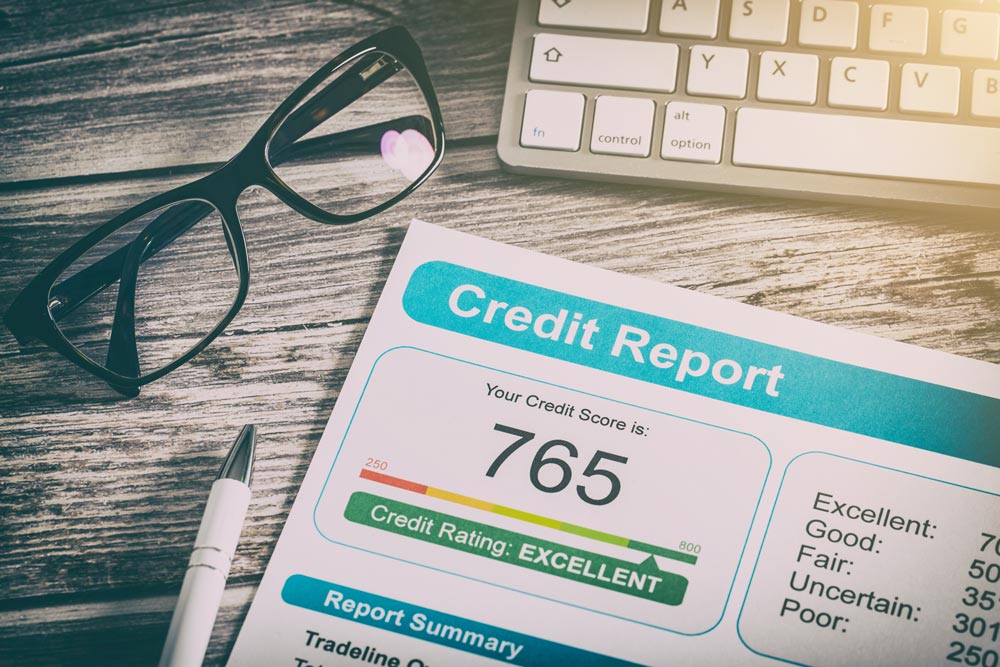
Can You Get a Personal Loan with a Credit Score of 550?

Personal loans can be very useful for all kinds of personal expenses. If you need the money for some unexpected bills or repairs to a home or car, a personal loan maybe your best option, depending on your circumstances. Personal loans are so popular because they can allow individuals to borrow an amount of money without any collateral. They are perfect for emergencies and work well if you want to buy a large item like a house or a car that requires financing but don’t have a lot of credit available.

To get access to a personal loan, you must meet and submit specific requirements to get one. But you need to ask yourself first why you need a personal loan. Remember that failing to pay a loan not only pulls down your credit score, but that the lender will also find ways to recoup their money. Before taking out a personal loan, here are three questions to ask yourself:

  1. Why do I need a personal loan?
    People obtain personal loans for various reasons—a medical emergency, a bill that must be settled soon, or even as pocket money for a mini-vacation. Depending on the lender granting you a personal loan, you can use the money for any purpose. However, it would be best to clarify this with the lender to be on the safe side.
  2. Can I afford a loan?
    A reputable lender will not grant a loan to a borrower that is deemed not capable of paying off debt. However, not all lenders are concerned about the welfare of their borrowers. Therefore, it is your responsibility as a loan applicant to assess whether you can pay back what you owe comfortably.
  3. Is a personal loan my best option?
    Not all financial shortages should be resolved with a personal loan. If you find yourself getting a personal loan too often, you may need to sit down and take a look at your spending. Personal loans are not long-term solutions to a financial dilemma.

That being said, personal loans are loan products that can help you during times of need. However, not all applicants will get access to a personal loan due to different factors. One of these factors is the borrower’s credit score. Personal loans require a suitable credit score, which is determined by a variety of factors. Most lenders have a minimum credit score qualification, while others will vary according to the lender. Your lender options are usually limited if your credit score falls into this range, and therefore you will need to look for other loan providers who lend only to people with good credit scores.

How Your Credit Score Affects Your Personal Loan Application

In general, a personal loan credit rating is a numerical figure ranging from 300-850. Credit scores are typically calculated by using the information contained in your existing credit reports. As such, it is an age-old question, and an age-old one to answer; get an accurate answer to what is a good credit score? Before delving into this, here are some background information about credit scores and what they are.

A credit report is the single most important document that a lender, credit card company or bank will consider when evaluating your loan application. The report is compiled from your financial information, including how much money you make and where you work. This information is then sent to each of the companies regularly. This information will include your debt-to-income ratio, your payment history, how many loans or credit cards you currently have, and your payment history for those loans. All of this information is then combined with your FICO scores and assigned to a certain score.

If it falls in the range of 300 and 579, credit bureaus like Experian mark your credit score as ‘Very Poor.’ A credit score of 550 is considered significantly low. Your credit score symbolizes your grade as a borrower, which indicates how you handle money and debt. Poor or bad credit may prevent you from getting a loan from a bank or traditional lender. Therefore, it’s crucial to understand how credit scores work and how it affects your ability to apply for credit.

How to Get a Personal Loan When Your Credit Score is 550

Is it possible to take out a personal loan if your credit score is 550? The answer is yes, but you may have to take advantage of a bad credit personal loan. Here are some helpful tips to obtain a loan despite having bad credit:

  1. Obtain a Copy of Your Credit Report and Check the Information

When you need a personal loan, be sure that you have your credit score ready before applying. Lenders are looking at your credit scores to see how much of a risk you are to them. This applies even if you don’t have an account open in the past 30 days and have good payments on your accounts. For most traditional loan providers, the most important aspect of the personal loan process is credit history. Your credit report contains information such as financial information, employment history, income information, and other things used by lenders when they are reviewing you for a loan. If your report contains negative information, such as late payments, bankruptcies, and judgments, then you’ll find it challenging to obtain a loan. Your other option is to borrow from a direct lender that offers bad credit personal loans.

To ensure that you get a good credit report, you will need to request a free credit report from all three major credit bureaus. Once your report is received, you will need to check it carefully to ensure that everything is accurate. When the credit report arrives, check to see if the information is correct. If there is information that does not match up, contact the reporting agency, who will require that you provide them with the items in question.

  1. Look for a Reputable Direct Lender

Many people have a very bad credit rating nowadays, so they are looking for a way out of this dilemma. They can avail of bad credit personal loans from online direct lenders as they are more flexible when it comes to lending applications. However, before applying for a personal loan, these lenders ask for your current credit score so that they will be able to provide you with an accurate quote.

Another advantage of availing of a bad credit personal loan from online lenders is that they are very convenient to use. Once you’ve decided that you want to borrow a specific amount of money, all you have to do is accomplish a simple application form with details about your financial situation, and you are all set to get the loan you want.

Bad credit personal loans from online lenders usually come in two forms: secured and unsecured. Secured bad credit personal loans from online lenders come with very low-interest rates, but you have to put up some collateral or security if you fail to pay back the loan on time. You can get this loan at an attractive interest rate, but you must understand that there is some risk involved. The second type of bad credit personal loan you can get is the unsecured loan, which is usually offered at a bigger interest rate.

  1. Honesty and Preparation is Key

Be sure to carefully read the requirements and terms of the personal loans before sending your loan request or signing the loan contract. When applying for a loan from any lender, always be honest and avoid declaring half-truths hoping that you’ll be granted credit. It’s better to be honest from the start so the direct lender can work out a possible loan scheme for your unique circumstances.

The amount of interest that you pay on any loan is dependent on your circumstances, so even if your credit score requirement is low, it doesn’t mean that you shouldn’t pay attention to the APR rate when you apply for a loan. Even if your score is high, you may pay a much higher interest rate when you apply for a personal loan because the lender has no way of knowing your chances of defaulting. You can try to get as much information as you can on the interest rates, fees, conditions, and other things before applying for the loan.

The good news is that you can start working on improving your credit score once you have your loan application granted. If a bad credit lender grants you a personal loan, consider yourself fortunate. By paying your debt in full on time or keeping up with repayments on time, your scores will start to rise again.

Takeaway

If your credit is bad, remember that there’s s still a light at the end of the tunnel! You can improve your credit by paying off any balances and accounts; you will improve your score. It would also help if you focused on increasing your overall debt and credit to income ratio. This will increase your FICO scores and give you a good credit score.

A personal loan can give you the funds you need to get through hard times or a quick injection of cash when you suddenly fall short of money. This type of loan is a great way to get money quickly, and it can help repair your credit score. If you have bad credit, you have to work hard to improve your credit scores, but you will take advantage of a personal loan again in the future. When used responsibly, a personal loan can give you a second chance at repairing your bad credit. Consider consulting with a professional, like creditdonkey, for impartial advice and expert guidance.

EDITOR'S PICK OF THE WEEK

China economic growth

China’s Challenging Search for a New Model of Economic Growth

By Danny Leipziger China cannot continue to rely on exports to drive its growth, but what are the alternatives? China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...

WISE DECISION MAKER GUIDE

POWER INFLUENCERS

Emerging Trends

The Future of Global Trade