Home Blog Page 1017

How Can You Get Compensation From a Hit-and-Run Crash?

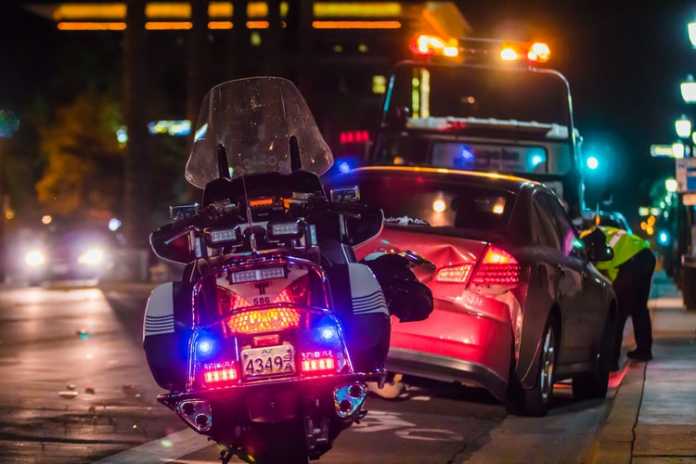
No matter how hard you try to be cautious, life still has its way of throwing you curveballs when you least expect it. This is why it is quite important that you take every precaution possible so you could avoid suffering the consequences of any unfortunate incidents, because you will face some of those sooner or later. Yet, that still might not be enough in certain cases. For instance, if another driver crashes into your car, you will file a claim for compensation through their insurance company and you will get compensated. But what if the driver doesn’t stop? What if they hit you and run? Things do get a bit more complicated then, but you can still get what you are owed. Here’s how you can get compensation after a hit-and-run. 


File a Police Report 

Even if the other driver fled the scene of the accident, you should still contact the police to file a report. Their documentation of the incident is crucial because the preliminary report the officer writes on the scene might help you with insurance claims later on. More importantly, the police might be able to track the other driver who fled the scene, and they will be brought to justice –– you will then also need the report for that driver’s insurance company claim. None of this would happen if you don’t contact the police to report the accident. 


Getting Evidence

As with any car accident, you should try to gather as much evidence from the scene as possible, because that always helps your claim later on. Take photos of everything – your car, the surroundings, and even the skid marks and debris. This will help you prove you were not negligent later on, and that the other driver was, which is crucial for your claim. You should also get witnesses’ contact information from the scene because their testimony might prove paramount to the success of your claim as they can testify that the other driver was negligent and you were the victim. 


Get Professional Help 

Whether you were hit by a car and they didn’t flee the scene or it was a hit-and-run, either way, your best chance is hiring a professional car accident attorney. They would know how to handle the case from all angles. The attorneys from https://flemingattorneys.com/blog/car-insurance-cover-hit-and-run/ stress the importance of hiring a professional to help you get fair compensation. In hit-and-run crashes, you might have to get compensation from your own insurance company, which will depend on several different factors. Even if that were the case, it would not be easy to convince your insurance company to pay up. This is why you need specialized attorneys on your side who know how to handle such cases and get their clients the win.

Hit-and-run cases are particularly more complicated because you will have to get compensation from your own insurance coverage, which is much more difficult than it seems. If it were the other driver’s insurance company, things would be much simpler since you will be able to prove negligence and have their insurers pay you for damages. But what if the police cannot locate the driver? In that case, your only hope would be taking on your own insurance company, and you cannot do that without competent and knowledgeable attorneys on your side.


What Kind of Policy Would Cover You in These Cases?

Unless the driver gets caught, you cannot use traditional means of getting compensation –– that is, filing a claim with their insurance company. In that case, as explained earlier, you have to sort it out with your insurance company. The problem is, you need to have proper coverage for that kind of situation in the first place.

There are several different types of coverage that might prove useful here, like ‘uninsured motorist bodily injury,’ which has to be offered by insurance companies unless you explicitly rejected it. This one can cover your medical bills, disability damages, and lost wages –– up to the limits of your policy, that is. You could get similar coverage but to cover your property damage, or even provide you with an actual cash value for your vehicle if it is beyond repair. 

These are some of the policies that you could get early on to avoid getting in trouble if you get involved with a hit-and-run crash. They might cost a little bit more, but they definitely come in handy in such situations. The important thing is knowing the proper legal channels to follow, which means enlisting the help of professional car accident attorneys. 

A Guide to Filing a Police Report after a Car Accident

Car accidents can be very horrifying. Sadly, many survivors assume that they can handle everything afterwards and resolve the dispute without any assistance. This is especially the case for minor accidents where injuries can be underestimated. While assisting others after an accident is essential, this occupies a fragment of what you should do after an accident. It is wise and very crucial that you inform the police. Well, we have compiled a detailed guide on how you can file a police report after an accident to avoid grave challenges later.


Filing a Police Report after a Car Accident

1. Call the nearest station 

Informing the police is essential even if there are no visible damages. The police will inquire about the location, time, date, victims, nature of the accident, cars involved, injuries inflicted, and a lot more. Reporting ensures that the accident is well documented from a legal perspective. The police will advise on what to do. You should also take note of the officers who arrive at the scene for investigation. 


2. Follow up 

Informing the police about the accident is half the task. You might have to follow up to get your detailed report, keeping in mind that they are tied down with many other responsibilities. You should get a police report which comes in handy when you want compensation from your insurer and, in other cases, from the driver who was at fault. Without a police report, you may find yourself at a heated spot against the other driver, and many times, it never ends well. The description acts as evidence highlighting the facts to help you to close a fair deal. 


3. Review the report

Did you know that some people fake car accidents for their financial gain? Yes, the period between reporting and waiting for the police to arrive is very crucial, and you should be alert. The driver at fault can hire other people to act as witnesses in his or her favor. Other times, they can manipulate the scene to shift the blame to you or interfere with the CCTV feed to eliminate evidence. Such actions are known to complicate cases and burden innocent drivers. Don’t take anything to chance. Collect evidence by taking pictures or videos of the scene, speaking to witnesses and the likes. Then you can compare notes with the police to ensure the facts are correctly captured.


4. Point the differing areas for further investigation

If there’s anything that’s differently mentioned in the report than the actual incident, you need to point it out. This will ward off complications such as being denied compensation and imprisonment and prompt the officers to launch a further investigation. 

You ought to hire a lawyer for help getting facts well documented in the police report and correcting any errors. According to Injury Lawyers San Antonio, a police report is essential in such a claim. So you ought to ensure that the facts are well documented to avoid hurting your case.


Final words:

Police play a vital role in piecing everything together after a car accident. Therefore, do not underestimate what they document after a car accident.  Whether a case is major or minor, protect yourself and your case by getting the right report from the agency, fast!

The Coronavirus: Business Risks, Liabilities, and Force Majeure in the Face of a Global Health Crisis

By Kiran Nasir Gore and Charles H. Camp

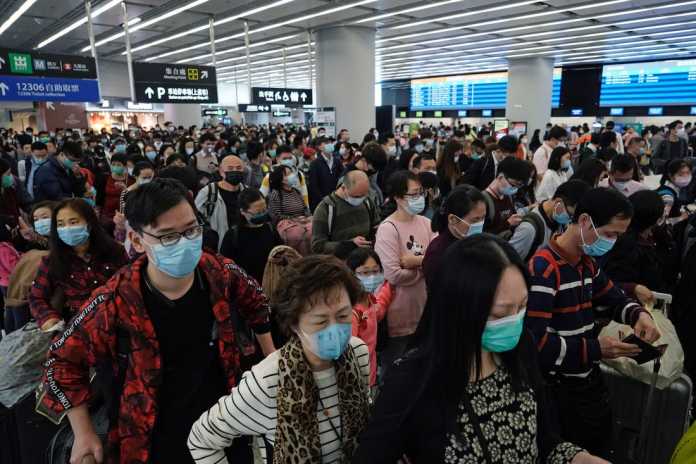
On January 30, 2020, the World Health Organisation declared the new coronavirus (COVID-19) outbreak a Public Health Emergency of International Concern. Alongside quarantines, travel restrictions and bans, businesses have been confronted with limited access to global human capital and unreliable supply chains. Here we examine several ways that the coronavirus epidemic has impacted global business prospects with connections to the PRC. We aim to provide businesses and their legal strategists with ideas to guide effective solutions to risks, liabilities, and disputes caused by a global public health crisis.


In December 2019, when doctors in the Wuhan province of the People’s Republic of China (PRC) first encountered the new coronavirus (COVID-19), very few of us could have imagined that the World Health Organisation (WHO) would soon declare a Public Health Emergency of International Concern (PHEIC).[i] At the time of writing (at the end of February), the impact is already devastating; global health authorities have verified more than 82,000 cases of infection and more than 2,800 deaths.[ii] Since the the writing of this article, these numbers have only continued to increase at staggering rates. In an effort to contain the outbreak and its spread, government and non-governmental organisations have swiftly imposed quarantines, travel restrictions, and bans. On the business side, these measures carry significant economic implications.

These quantifiable economic losses – which by no means compare to the loss of human life – are instructive for ongoing business challenges.

Recent travel restrictions to, from and within Chinese cities have limited access to human capital and caused global businesses to grapple with labour shortages, factory closures and supply-chain disruptions. Similar considerations also plague the future of the PRC’s ambitious Belt and Road Initiative (BRI) projects around the world.

Yet, even in volatile times, global businesses can be assertive and strategic in their approach. This article examines several ways that the coronavirus epidemic has impacted global business prospects with connections to the PRC, and provides guidance to business leaders and their legal strategists to help manage supply-chain disruptions, personnel shortages, contractual obligations, and any resulting disputes to ensure their continued success.


Supply-Chain and Distribution Disruptions

On February 17th, Apple, Inc. became one of the first global businesses to announce that, because of the coronavirus outbreak, it had lowered sales expectations for this quarter.[iii] These changed expectations are linked to slower product supply, owing to closures at its Chinese factories and decreased demand for its products among Chinese consumers.[iv] Similar effects are visible in the car, healthcare and luxury goods industries, each of which depends heavily on Chinese production streams or Chinese consumers.[v] Market watchers estimate that the true impact on global productivity and consumption will not be known for several months. These quantifiable economic losses – which by no means compare to the loss of human life – are instructive for ongoing business challenges.

In the early stages of a supply chain problem, businesses should determine which aspects of their supply chain are at greatest risk and assess whether they can absorb these challenges through alternative sourcing or inventory reserves. Indeed, longer-term solutions might involve exploring alternative sourcing and manufacturing streams, not only to address the short-term changed circumstances, but also to diversify and become more resilient in the face of future disruptions.


Risks Along the Global BRI

Just as the coronavirus epidemic has limited access to product supply and human capital within the PRC, it has a corollary impact on Chinese-led investments located outside the PRC. The BRI provides a prime-example case study.[vi] Many BRI projects rely on either Chinese-manufactured imports or Chinese personnel to advance their interests. Without access to both, in-progress BRI projects may go stagnant.

Indeed, the timing of the coronavirus could not have been worse. The WHO’s PHEIC declaration, came shortly after the Lunar New Year holiday, during which many Chinese workers located abroad had returned home for the holiday festivities. A large number of these found themselves unable to return to work, either because of travel restrictions imposed locally or their foreign employer’s unwillingness to receive them abroad for fear of further spread of the illness. According to Reuters, as of mid-February, the Chinese National Immigration Agency reported that more than 133 countries had imposed entry restrictions on Chinese citizens or people who have visited China.[vii]

Further challenges arise when considering the BRI’s globally interconnected vision. As explained in a World Bank Report published last year, full implementation of the BRI, including multilateral cooperation, is key to unlocking its full trade and economic benefit.[viii] This means that BRI projects must press on, notwithstanding setbacks. In line with this perspective, the PRC’s Ministry of Commerce swiftly announced that, in spite of the coronavirus epidemic, BRI projects remain on track, with no large-scale project delays.[ix] The veracity of this announcement – and whether full implementation remains realistic – will only be confirmed with the passage of time.


Does Force Majeure or Frustration of the Contract Excuse Performance During a Public Health Crisis?

Business leaders and legal advisers should assess the precise contractual terms and governing law of impacted supply chain contracts. Sophisticated negotiators will often include a force majeure clause in their contracts. Generally, this clause allows a party to excuse its performance in the case where an unforeseen event outside that party’s control prevents it from meeting its contractual obligations. In the context of the coronavirus epidemic, where travel bans and closures have shut down manufacturing and production lines, the utility of such a clause is self-evident.

The Chinese authorities recognise the possibility that the coronavirus epidemic may amount to a force majeure event under certain contracts. At the end of January, the China Council for the Promotion of International Trade (CCPIT), accredited with the PRC’s Ministry of Commerce, began issuing force majeure certificates, upon request, to businesses in the PRC that claimed that their collaboration with foreign partners has been affected by the coronavirus outbreak.[x] By mid-February, the CCPIT had issued more than 1,600 such force majeure certificates.[xi]

Determining whether a party may renege on a contractual promise because of a PHEIC is a nuanced inquiry that depends on careful analysis of the facts, the wording of the clause itself, and the law guiding its interpretation.

However, obtaining such a certificate does not alone lead to an assured legal outcome. Determining whether a party may renege on a contractual promise because of a PHEIC is a nuanced inquiry that depends on careful analysis of the facts, the wording of the clause itself, and the law guiding its interpretation. An ideal contract would specifically account for a public health crisis (to avoid ambiguity, possibly one declared as a PHEIC by the WHO), alongside other enumerated force majeure events, such as a natural disaster, act of God, or other catastrophe.[xii] But even with a clear force majeure clause, it often takes protracted litigation or arbitration to determine finally whether performance is excused (without monetary consequences) or whether a breach has occurred (entitling the other side to damages).

During dispute resolution, the party that invoked the force majeure clause must prove that, under the applicable law, the clause was appropriately invoked, that the non-performing party provided appropriate notice of its failure and attempted to mitigate its effects, and that the non-performing party would have performed the contract had the force majeure event not occurred. A key element is that the non-performing party must demonstrate that the intervening event is entirely beyond the control of the parties to the contract. While the precise definition of force majeure varies under each jurisdiction’s legal system, the standard described here is generally consistent among both common law jurisdictions and PRC law.[xiii]

Regardless of contractual terms, most parties and their advisers would claim the coronavirus epidemic’s crippling impact was unforeseeable. This may seem shocking in a world with several WHO-declared PHEIC in the past decade alone (including some PHEIC alerts that remain currently active): swine flu (2009), poliovirus (2014), ebola (2014 and 2019), and zika virus (2016).[xiv]

Apart from relying on a force majeure clause, a party may possibly claim that the doctrine of frustration of purpose excuses its performance. This doctrine operates as part of the general common law of certain jurisdictions, such as New York and the United Kingdom, and is not included as an express contract clause. The law requires a supervening event that affects the very heart of the contract at issue, entirely beyond what was contemplated by the parties when the contract was formed. It only applies in exceptional circumstances to excuse non-performance. Mere hardship or inconvenience are not enough to meet this standard, and neither party can be at fault for the event. In particular, if the parties have accounted for a certain possibility in their contract (for example, if a possible public health crisis is accounted for as a force majeure event) then the event will no longer be unforeseen and the burden cannot be alleviated through the doctrine of frustration. An example of a frustrating event may be the quarantine of a local port. If goods dispatched by ship can no longer be delivered to their destination and there is no other reasonable route for performance, then this may qualify as a frustrating event under the relevant contract.

Apart from relying on a force majeure clause, a party may possibly claim that the doctrine of frustration of purpose excuses its performance.

These same contractual challenges – including relevant factual and legal inquiries – apply to obligations and liabilities for BRI projects. However, among BRI projects there are additional layers of complexity. Many state-owned enterprises are involved in the BRI’s financing, design, and development.[xv] Parties with PRC government affiliation may not succeed in a force majeure or frustration claim. The PRC’s official Centre for Disease Control and Prevention investigation of the coronavirus source implicates Wuhan’s Hunan Seafood Wholesale Market.[xvi] Meanwhile, there is global speculation that the coronavirus may have leaked from a microbiology lab not far from the same market.[xvii] Regardless of which story is believed, the PRC’s failure to regulate adequately could be seen as the “cause” of the coronavirus epidemic. This undercuts the effectiveness of both force majeure and frustration claims. Under both legal claims, it is absolutely required that the intervening event be entirely outside the control of the party seeking to excuse its performance.

If a BRI project is guided by Fédération Internationale des Ingénieurs-Conseils (FIDIC) contract standards, the range of possible entitlements expand beyond merely force majeure and frustration of purpose to alleviate non-performance. For example, under FIDIC contract terms, a party claiming unforeseeable shortages in the supply of goods or labour may be able to seek an extension of time for completion.[xviii] A party may also obtain relief for delay or disruption to its productivity in cases where public authorities increase health and safety testing.[xix]

At all events, parties are encouraged to maintain strong communication with their business partners, as this may create opportunities to negotiate improved outcomes.

A recently published book, The Belt and Road Initiative: Legal Risks and Opportunities Facing Chinese Engineering Contractors Operating Overseas, offers Chinese-focused insights on possible challenges to execution of BRI projects.[xx] Its authors are the Permanent Forum of China Construction Law, a working group comprised of dozens of pre-eminent Chinese and international legal experts who have successfully advised Chinese contractors in international infrastructure and development projects.[xxi] The book provides nuanced and thoughtful guidance to Chinese contractors working on BRI projects around the globe, including practical solutions to the variety of setbacks they can expect: labour strikes, customs delays, and changes to local regulations and permitting requirements. Yet, nowhere does the book account for the risks associated with a possible global health crisis. Again, this suggests that the coronavirus epidemic is an exceptional global event. With impact ranging from the PRC to Italy, it can be seen as both unprecedented and unforeseeable. However, the reality is that the law is not on the side of parties who breach their obligations. In some cases, contractual terms will offer legal solutions to realistic supply-chain challenges. At all events, parties are encouraged to maintain strong communication with their business partners, as this may create opportunities to negotiate improved outcomes.


Conclusion

It may be true that the coronavirus epidemic has surprised even the best-prepared and most sophisticated governments, international organisations, and businesses alike. But today, as the aftermath and true impact continue to reveal themselves, we are better informed and, therefore, better equipped to respond to a global health crisis of this magnitude. Proactive business leaders and legal strategists can implement international best practices for contracts, construction timelines, and personnel needs by drawing on the lessons now learned, and manage expectations and obligations accordingly.

About the Authors

Charles H. Camp is an international lawyer with over thirty years of experience representing foreign and domestic clients in international litigation, arbitration, negotiation, and international debt recovery. In 2001, Mr. Camp opened the Law Offices of Charles H. Camp, P.C. in Washington, D.C. to focus on effective, personalised representation in complex, international matters. Mr. Camp teaches international negotiations at the George Washington University Law School.

Kiran Nasir Gore is Counsel at the Law Offices of Charles H. Camp, P.C. Her expertise is in international dispute resolution, including advocacy before US courts, commercial and investment arbitration tribunals, and investigative authorities. She also draws on her professional experiences as an educator at the George Washington University Law School and New York University’s Global Study Center in Washington, D.C.

References:

[i] Statement on the second meeting of the International Health Regulations (2005) Emergency Committee regarding the outbreak of novel coronavirus (2019-nCoV), World Health Organisation (Jan. 30, 2020), https://www.who.int/news-room/detail/30-01-2020-statement-on-the-second-meeting-of-the-international-health-regulations-(2005)-emergency-committee-regarding-the-outbreak-of-novel-coronavirus-(2019-ncov)

[ii] Globally aggregated coronavirus outbreak statistics are available at https://www.worldometers.info/coronavirus/

[iii] Daisuke Wakabayashi, “Apple Signals Coronavirus’s Threat to Global Businesses,” N.Y. Times (Feb. 17, 2020), https://www.nytimes.com/2020/02/17/technology/apple-coronavirus-economy.html

[iv] Id.

[v] Megan Cerullo, “Coronavirus chills luxury brands in — and outside — China” (news broadcast), CBS News (Feb. 13, 2020), https://www.cbsnews.com/news/coronavirus-chinese-tourism-luxury-brands-us-europe/

[vi] Keith Zhai and Matthew Tostevin, “Coronavirus slows China’s Belt and Road push,” Reuters (Feb. 18, 2020), https://www.reuters.com/article/us-china-health-silkroad/coronavirus-slows-chinas-belt-and-road-push-idUSKBN20C0RF

[vii] Id.

[viii] Belt and Road Economics: Opportunities and Risks of Transport Corridors (The World Bank Group, 2019), pp. 3-9, https://www.worldbank.org/en/topic/regional-integration/brief/belt-and-road-initiative

[ix] Zhong Nan, “BRI projects not affected by coronavirus, official says,” China Daily (Feb 21, 2020), http://global.chinadaily.com.cn/a/202002/21/WS5e4f7970a31012821727952f.html

[x] “China trade agency to offer firms force majeure certificates amid coronavirus outbreak,” Reuters (Jan. 30, 2020), https://www.reuters.com/article/us-china-health-trade/china-trade-agency-to-offer-firms-force-majeure-certificates-amid-coronavirus-outbreak-idUSKBN1ZU075

[xi] “China issues over 1,600 force majeure slips to coronavirus-hit companies,” China Daily (Feb. 17, 2020), https://www.chinadaily.com.cn/a/202002/17/WS5e4a38eaa31012821727818d.html

[xii] Many contracts will account for a “pandemic” in their force majeure clauses to ensure that performance is excused should the contract no longer be feasible. See e.g., Akorn, Inc. v. Fresenius Kabi AG, 2018 Del. Ch. LEXIS 325, 117 (Del. 2018).

[xiii] See e.g., Permanent Forum of China Construction Law, The Belt and Road Initiative: Legal Risks and Opportunities Facing Chinese Engineering Contractors Operating Overseas (Kluwer Law International, 2019), pp. 188-189.

[xiv] Nicola Davis, “Coronavirus: what other public health emergencies has the WHO declared?,” The Guardian (Jan. 30, 2010), https://www.theguardian.com/global/2020/jan/30/coronavirus-what-other-public-health-emergencies-has-the-who-declared

[xv] “Embracing the BRI ecosystem in 2018: Navigating pitfalls and seizing opportunities,” Deloitte Insights (Feb. 18, 2018), https://www2.deloitte.com/us/en/insights/economy/asia-pacific/china-belt-and-road-initiative.html

[xvi] “The Epidemiological Characteristics of an Outbreak of 2019 Novel Coronavirus Diseases (COVID-19) – China, 2020,” China CDC Weekly. 2: 1–10 (published by the Chinese Centre for Disease Control and Prevention (Feb. 20 2020), http://www.ne.jp/asahi/kishimoto/clinic/cash/COVID-19.pdf

[xvii] Steven W. Mosher, “Don’t buy China’s story: The coronavirus may have leaked from a lab,” N.Y. Post (Feb. 22, 2020), https://nypost.com/2020/02/22/dont-buy-chinas-story-the-coronavirus-may-have-leaked-from-a-lab/

[xviii] See e.g., FIDIC Silver Book 2017, Clause 8.5(c); FIDIC Red Book 1999, Clause 8.4(d).

[xix] FIDIC Red Book 1999, Clause 8.5.

[xx] Permanent Forum of China Construction Law, The Belt and Road Initiative: Legal Risks and Opportunities Facing Chinese Engineering Contractors Operating Overseas (Kluwer Law International, 2019).

[xxi] Id., p. xxiii.

Times You Should Consider Getting A Loan

Getting a loan means making a commitment that you’ll have to pay off your debt someday and if you don’t, it will pretty much create a snowball effect. So, you need to make sure that when you’re applying for a loan, you’re getting it for a good reason like emergencies or large purchases. For instance, if you’re looking to renovate your house, things like how much is a loft conversion exactly should be clarified before you procure a loan. 

But how can you tell that you really need a loan even in those situations? Here are some instances in which you should consider it. 


When you need to make a necessary purchase

We make purchases all the time, so what kind of purchase requires a loan? Simply put, the necessary kind that you cannot afford. You might think that you will never need a loan, however,  this option will be perfect for when you need to buy a car, a boat, or an RV. Only if you’re sure you can pay it off in due time, a loan will be helpful in this situation. If you’re also about to purchase a new home, then you might consider getting a loan as well, but you should consider the types of loans first before going in blind and choosing one that might not fit your circumstances.


For wedding ceremonies

Your wedding may be the biggest event in your life and the most important night as well, so it shouldn’t be wasted. This is why you must make sure that every detail, including the bride’s dress, the flowers and the cake, will be the best you can afford. To be frank, this can only be achieved if you have an adequate amount of money to pay for it. So, getting wedding loans, in that case, will work best for you without taking exhausting all your savings.


When you want to start a business

Sometimes, you’ll find that your monthly income might not be enough to sustain you or your family. This is when you should consider a side hustle. Starting a business will need capital and because you’re basically doing this to get more money, not to spend your expenses, a loan could be the solution to this situation. You’ll end up getting more monthly income if your business goes to plan and you’ll be able to pay your debt on time.


For home remodeling expenses

We all want to make changes to our houses at least once. Whether it’s a pool, a new room, or renovating your roof, all these projects will require a large sum of money. Financing these projects can’t happen unless you risk all your income on financing the remodeling expenses. So, this is a case where getting a loan will be the best option. There are several loans out there that support such cases as personal loans.


When you want to go on a vacation

It is frustrating when you feel like you need a break and you seemingly can’t take one because of a financial crisis. But don’t let that stop you from going to the airport with your family and starting your fancy holiday. Should you find yourself in that situation, you can search for a good travel loan. While it is similar to personal loans in some aspects, it’s certainly more efficient.


When you want to finance funeral expenses

Having to bury someone you love and pay for all the expenses of that person’s funeral is difficult on all accounts. If you’ve done this before, then you already know it is not very cheap. The death of your loved one could occur anytime, even when you don’t have enough cash. Getting a loan for the headstone, the casket, funeral services, etc., which will cost a fortune eventually, is perfectly understandable. Many people opt to pay money from their savings and that is another great option. However, if the funeral expenses will take away all your savings, then go for a loan.


Medical expenses

Medical expenses can strike hard, especially when you’re not prepared. Some medical bills cannot be covered by insurance, like some cosmetic procedures, and the family of the patient will find themselves paying money out of their pocket. Just like funeral expenses, you’ll need the cash right away and because it is a critical time, you need someone reliable to borrow the money from. Therefore, choose a safe and trustworthy loaning company to do the job. 

Loans can sometimes be the best choice you have, especially in hard times. Whether it is to make home improvements, go for a vacation, or cover an emergency, you should first decide if you can afford these expenses. If you can’t, apply for a loan that will give you a long period of time before your payday.

Why Insurance Companies Have A Bad Rep

At first glance, one would get the idea that insurance companies are popular among people due to their significant contribution to saving people’s money. That image may have held water back in the early days of insurance companies, but you’ll be hard-pressed to find an insurance company with a positive reputation. From an economic standpoint, insurance companies pump a lot of money into society through taxes and jobs, but the cold and calculating dynamic of risk assessment has made many people angry. There is no doubt that insurance companies have made the lives of tens of millions of people better and smoother. Unfortunately, it didn’t take long for distrust and suspicion to become rooted in the psyche of both parties. 

We’ll be trying to provide you with a brief overview of how the situation became amicable and tense.


Scandals

Insurance companies have been involved in numerous scandals that have shaken the faith of people in the whole industry. There is no denying that insurance companies sure offer a lot of good things to societies, but we’re trying to look deeper into what causes the problem to begin with. Wrong representation and using shady marketing practices are the main reasons the media portrays insurance companies in a darker light. Huge scandals have broken out involving bid and price rigging, unethical accounting practices, and tax avoidance. This kind of commotion has made many people try to get the best deal possible out of ICBC or WorkSafe BC coverage. If you’re not familiar with these types of claims, you can read more about ICBC VS. WCB here to understand the dynamics behind it. Worker injuries are amongst the most common fights with insurance companies and they can get very problematic without professional help.


Frowned Upon Practices

When it comes to insurance companies, many people are extra wary of the language and fine prints used in the wording of contracts and advertisements of insurance providers. It seems that there is a lack of transparency in the relationship between the common consumer and insurance companies. There is no shortage of vague and obscure clauses in contracts, small prints, and intentionally complicated terms to understand. Since the insurance industry is huge, they have made sure that the intricate complexities of their operation take advantage of the market, making it a company-vs-consumer war. The average individual isn’t properly prepared to make an informed assessment of what they’re getting into with certain contracts. Insurance companies may enforce certain policies like fire and accident insurance upon individuals and businesses.

Mis-selling

Unfortunately, a lot of insurance companies are in the habit of redacting information. A wave of consumer protests has attacked many financial institutions, including insurance and made it clear that they are dissatisfied with the misinformation provided by the companies. Variable income and stock-based investments were hot topics for a while as those were the most obscure information. Insurance agents are being forced to meet sales quota, which made them resort to practices that were not to the consumer’s advantage. Misleading customers are becoming a way for insurance agents to increase their earnings, focusing more on persuasion and dissuasion rather than actually thinking about what the customers need.


Online Reviews

Insurance companies have been around for a while, but their reputation started going downhill once communication technology started to pick up. People were able to share information at a relentless speed which made waves become tsunamis in a very short duration. Many insurance companies have started to think about ways they can use to tackle the digital hordes of reviewers. Like any stereotypical villain-like corporations, they’ve directed a lot of resources, time, and effort to create positive reviews to attract customers. These practices are now red flagged by the online community. It’s common knowledge now that most legit businesses have balanced reviews bordering on positive and negative experiences.


PR Disasters

Insurance companies and many big financial institutions are starting to face cultural and societal issues that are becoming harder to handle than ever. Consumers are weaponizing social media to launch effective attacks that have enough momentum to topple hierarchies. Reputation is becoming so much harder to protect when consumers are creating echo chambers with massive force. The latest example that comes to mind is when insurance companies, specifically Chubb and Lockton, got dragged into PR mayhem right after the school shooting in Parkland in February; they had to cut ties with the National Rifle Association as a result.

The aforementioned reasons weren’t mentioned to infer that all insurance companies are bad, but it serves as a warning to many people who may be too trusting of them. All moral values aside, incentives can sometimes become too alluring in the eyes of some insurance companies to engage in shady practices.

Quick Ways to Save Money at Home

Part of the American dream is growing up and making enough money that you can afford to put a down payment on your own house. We all dream of the days when we can stop worrying about renting and landlords. However, more often than not, when the time comes to actually enjoy your life in your new home, it turns out that you’re constantly spending money on the property.

While houses can be expensive to protect and maintain, there are a few steps that you can take to protect yourself from costs that you simply can’t afford.


1. Stick to a Small House at First

It’s tempting to opt for the most expensive house that you can get a mortgage for – particularly when you’re dreaming of raising a family with your partner, or you’re imagining what you could one day do with the most amazing piece of property. However, your first home should usually be something small. Buying a house that’s under budget means that you should have extra money aside that you can put towards an emergency fund.

After you’re done paying your mortgage each month, make sure that there’s enough cash left in your income to put money aside for your future, emergency maintenance, and any other extras that you might need.


2. Control your Thermostat

In the summer, you spend a fortune on electricity because you have your air conditioning cranked up to full blast. In the winter, you’re still spending over the odds on your energy because you’re relying on heating. It seems like there’s never a way to keep your home at the perfect temperature.

However, rather than relying on your thermostat, you could find that you save a lot of money, and do the planet a favor, by changing the way you deal with heat. Open windows and doors if you’re hot, rather than turning fans on. Alternatively, think about putting draft excluders in front of doors and wearing sweaters in the winter.


3. Invest in Maintenance

Sometimes, when you know that you don’t have a lot of cash left over in your savings at the end of a heavy bill month, the last thing you want to do is deal with something like a leaky faucet or a wonky pipe. However, simply burying your head in the sand and ignoring the problem isn’t a good idea either. With that in mind, it’s a good idea to invest in some maintenance.

Sometimes, simply dealing with a little problem now, even if that means borrowing some money from a personal loan, could mean that you avoid paying for a very big problem in the future. Don’t ignore the issues – no matter how small they seem.


4. Invest in your Home’s Future

Speaking of borrowing cash to look after your home, you don’t need to stick to just borrowing money to deal with problems. You could also think about how certain investments might help you to accomplish more in your property in the future too. For instance, you might discover that getting some more energy-efficient devices in your home helps you to cut down on your electricity bills. To do this, you might consider installing solar panels from Solar quote so you can use more natural energy.

On the other hand, maybe you’ll decide that you want to replace an old roof now, even if it means spending a lot of money, to ensure that you don’t have to pay for both the roof, and the repairs that come from the demands of water damage at a later stage.


5. Spring Clean Regularly

Finally, this might seem like a strange way to save money but bear with us for a second. Spring cleaning your house more than once a year gives you a chance to save cash in a number of ways. First, you can use your cleaning experience to look for any issues in your home that needs to be fixed, such as cracks in your walls or problems with your wiring. This can protect you from bigger expenses that you need to deal with later on.

At the same time, spring cleaning can help you to find more money to put in your emergency fund. While you’re cleaning out old cupboards and crawl spaces, you might track down some items in your house that you’re happy to sell for extra cash. This way, you can reduce the clutter in your property and get some extra money at the same time.

How to Arrange a Networking Event and Make New Partners

It’s true – we usually buy from people who we like and trust, so successful networking – creating business contacts – is an important part of expanding our customer base.

Define a goal for your event

Determine the goal you want to achieve by organizing your event, and think about it from the perspective of everyone you invite. For example, if the goal of your event is to find potential customers or receive recommendations, then you need to come up with an approach in which everybody gets what they are looking for.

The same goes for other types of networking events, some even arrange networking events for single entrepreneurs. If you decide to arrange such an event, then you can present them with some relevant information, for example, the best ideas and ways to propose.

Define a framework

It is about the size and industry of your event. How many participants will be there at your event? Are you going to organize an event where people will sit down and take turns telling others about their business, what they offer and which clients they can be useful for? Or do you intend to assemble a large scale group where people themselves will communicate and exchange their information? Perhaps you prefer a fast-paced style of networking events where people take turns communicating “in a circle.” How often will meetings be held – once a month or do you want to organize a single event? 

Reserve a date

If you are planning an event of medium or large sizes, you should let all people involved in it know so that they can reserve this date on the calendar.

Reserve a room

Now that you know the goal, style, and scope of your event, now you have to reserve a room, which should be done as soon as possible.

Plan your catering

Remember that this is a networking event for establishing business contacts and not for entertainment. People will come in order to establish business contacts and meet potential customers or to find the suppliers of goods and services they need and not to eat. It is best to limit your food to options that are light and casual (a good rule is to have only food that does not require a fork and won’t get stuck in your teeth).

Do all the necessary preparation

Let potential participants know what they can expect. For instance, if you have a small-time event at someone’s place in mind, you can tell the invitees how many people will be there so that they can bring enough business cards, as well as their brochures, sample products, and so on. Or, if you have a larger conference or event planned, make sure you have considered parking and traffic control outside the event, and crowd control and health and safety within the event.

Work out the agenda of your event

For example, 19:00-19:15 – Arrival of participants, 19:15-19:20 – Greetings and presentations, 19:20-20:30 – Each participant in a circle has 5-7 minutes to tell about their business, 20:30- 21:00 – casual networking.

Organize the communication of participants

The key to success in any networking event is moving within a group and communicating with many people. In a group of people, there are always those who easily move and communicate, making contacts and friends, while others may be a little embarrassed and feel insecure in a group where they do not know anyone.

Do not forget to advertise yourself

This is a very common mistake, just because you organized an event does not mean that you should not advertise yourself.

Let people assess your event

You might think that your networking event was exceptionally successful, but other people may think differently. It is important to get feedback from the participants themselves.

Bring the matter to the end

Contact everyone you meet or exchange business cards with, and encourage others to do the same. Call your potential customers and say that you were pleased to meet them. Find ways you can help each other in business. Send them customers and ask them to send customers to you. Don’t be shy about your desire to establish working relationships.

Help people to meet each other

You can help people meet other participants if you approach those who look a little “out of place” and start a conversation. Ask what they are doing and who their ideal customer is, then introduce them to anyone who is nearby (even if you don’t know this person). After that, you can leave these two participants, who can now talk among themselves, and help someone else. Do not worry that there will be too many guests. Just tell everyone and ask others to help with the networking process.

What to Do if the Insurance Company Won’t Agree to a Settlement?

You’ve heard horror stories about insurance companies refusing to pay claims, and you may have experience with this situation yourself. When we’re dealing with large insurance companies sometimes it can feel like David vs. Goliath. This doesn’t always have to be the case, and if an insurance company is refusing to pay out a reasonable settlement there are options for you in order to gain recourse. 


If You Have An Accident 

After you’ve assured your own safety, and the safety of others, you may want to collect evidence from the accident. Call any emergency services that are required for the scene, including medical if anyone is injured. Take pictures of the damages that were done to your vehicle, as long as it is safe to do so. Get contact information from witnesses if you do not have it already, and ensure you’re getting the other drivers information as well. 

If you’ve been involved in any accident, you should go to a doctor to make sure you’re in good physical health. If you have any injuries make sure you take pictures of them. It’s never a bad idea to call an attorney to help you file your claim to the insurance company, they’ll also be able to obtain police reports and walk you through the process. 


They Only Give Low Offers 

Keep in mind insurance companies are a business, they aren’t looking out for your best interests, they’re trying to make a profit. Insurance companies will attempt to give you low offers and see if you’ll accept them. Sometimes the offers that they give aren’t even close to the damages incurred. In these instances you’re going to especially want to employ the services of an attorney. Auto-accident laws vary from state to state and sometimes municipalities have guidelines regarding their processes, the laws in Chicago, Illinois may be different than those in another state or city. If you have a car accident in Illinois, having a car accident attorneys working with you on your claim can make an insurance company take you seriously. They likely won’t have to incur the expense of going to court and may agree to a higher payout. 


They Won’t Pay At All

If the other insurance company won’t pay out at all, it may be because they’re defending their own policy holder. Some insurance companies are notorious for doing this, and it’s been well documented that they’re only looking out for their profits. Insurance companies are not your friend, so if you haven’t contacted an attorney yet you should if you’re receiving no damages. 

Taking on a big insurance company without any legal assistance might not get you the farthest, so it’s best to have an attorney on your side so they know to take you seriously. An attorney can help you negotiate with an insurance company, and potentially initiate a lawsuit if they can’t come to a settlement. In many cases, simply working with an attorney is enough for an insurance company to offer you a settlement. If they’re still giving you a low offer, you may need to start a lawsuit against the insurance company. Your attorney will offer you the best form of recourse in these scenarios and if they think it will be worth it. 


Your Own Policy 

If the opposing insurance company is refusing to pay for your damages, you may be able to have some of the damages paid by your own insurance company. In many cases insurance companies will pay out the damages to their own policyholder if they feel it is justified. They may then take legal action against the opposing insurance company in order to reclaim damages. This is dependent on the form of insurance that you have, but it doesn’t hurt to contact your insurance company to discuss possibilities. 


Small Claims Court 

If the amount that your damages total is relatively small you may be able to find recourse in a small claims court. In small claims you won’t need to hire the assistance of a lawyer and you will be able to present your case. If you’re going to a small claims court to present in front of a mediator, ensure that you have all relevant evidence on your person. Some courts may only accept evidence in certain formats so make sure you’re abiding by the courts local rules. 

Ultimately the decision you make will depend on your current situation. It’s always best to talk to a car accident attorney in order to find your best course of action, it can make auto insurance companies take your claim more seriously too. Insurance companies do need to make a profit, but that doesn’t mean that they should avoid paying out when you’re justified in your claim. Thankfully, there are some steps you can take in order to resolve problems with companies that refuse to agree to a settlement. 

How Soon After Buying a House Can I Get a Personal Loan?

Buying a home is one of the greatest and best investments ever. Buying a house is much cheaper as compared to renting one. Starting the building project might be difficult and expensive but there are options, such as a home improvement loan or even a mortgage refinance. Still, in the long run, it is convenient and less expensive as compared to renting. Most people buy homes with loans from the banks and complete the payment after the agreed time. Getting a personal loan after buying a house is not difficult; however, some factors must be put into consideration because they influence whether an individual can borrow money and how much they will be able to access. On the off chance that you have some financial difficulties even in purchasing your home, you can try for a naca home loan.

1. Credit Score

This is the first thing that banks and other savings Sacco look into before providing you with another loan. An individual’s credit history must be clear, and he or she must be able to pay the loan back. The ability of the borrower to pay back the loan is a crucial factor that the lender looks into. If your income is low and you have a poor credit history, chances of getting access to another loan are minimal, close to zero, and disqualifies an individual entirely from accessing a loan. However, this does not mean that all credit lenders will deny your loan. This is because different lenders have different ways of looking into an individual’s credit history.

2. Spending Power

Usually, lenders will want to see recent bank statements to see how much has been withdrawn from the account for the past six months or even one year. If the home was bought on loan, and you miss repayments, lenders may view this as the inability to pay the loan and deny you the chance of getting another loan. This is an important consideration when applying for a loan, as your financial history and current obligations can significantly impact your eligibility and terms.

3. Do not miss any Repayment

The moment that an individual misses repaying a mortgage loan, the lenders will question his payback ability. It is of more significant advantage to continue repaying your mortgage loan because this increases your credit score and gives an individual the chance of applying for a personal loan. As soon as you pay the first six months of the mortgage loan consistently without fail, you can have access to a personal loan.

4. Pay small debts

Most people do not put this into consideration. Still, small debts have a substantial negative impact on an individual’s ability to access another loan. Start off by paying and clearing the small debts and make your lenders trust you with their money.

5. Home Equity

This is also another factor that will determine how much an individual can borrow. Home equity is defined as the amount that an individual owes his or her lender as compared to how much his or her home is worth. “Most lending companies have a rule of offering only up to eighty-five percent of an individual’s home value,” says Jason Chatal, a Vice President at Cleveland Mortgage Corporation. This is done primarily for those who have not cleared their mortgage loan. Furthermore, the figures can go up depending on whether you will complete the repayment on time. Therefore, getting a personal loan after buying a house will depend on your home equity.

6. Collateral

In situations where an individual has bought a house and wants to access another huge loan, he or she uses the title deed of the house as collateral for the new loan. This assures the lender that the borrower will repay the personal loan one way or the other, and failure to repay the loan, the loss will be on the borrower and not the lender. Collateral is like an assurance of repayment and is a binding agreement between the borrower and the lender.

7. Income

An individual’s income is another factor that is considered before approving a personal loan. For instance, assuming that you have bought the house with a loan and completed paying the loan, your lender will look into the amount that you are receiving after tax and other deductions have been made. Usually, lenders only feel comfortable giving out a loan that they can deduct from the borrower’s monthly income, up to the time the full amount will be settled. Therefore, income determines how soon a person can access another loan.

8. Loan use and Amount

Assuming that you want to use the personal loan to start a business or for travel purposes, your lender will determine if the amount that you need is reasonable. In addition to that, it will be difficult for the lender to deny you a small personal loan, especially if you have completed repaying the mortgage loan. Assuming that you need a personal loan of $100,000, and your mortgage loan was $1,000,000 and had completed repaying the mortgage, your lender will easily grant you the personal loan. This is because the repayment of the mortgage has increased your credit scores and chances of acquiring even higher loan amounts you may check on Fortune Credit.

9. Legal house documents

Buying a house not only requires a title deed but also registered and legal documents, which show that the transfer of homeownership has been made from the original homeowner to the current and new owner. The documents need to be signed by a legal entity, confirming that indeed the whole process is legal. In scenarios where the lender requires all the house documents to be able to process the new loan, you can provide all the necessary documents, proving that you are the house owner, and get access to a personal loan.

10. Feedback from Previous Lenders

Lastly, getting a personal loan will depend on how your previous lenders have rated your credit history. You might have paid the mortgage loan on time, but maybe how you communicated with your previous lenders was rude and unethical. In most countries, when one goes past his or her payment period, their lenders call to inquire about the delayed payment. Other people offer valid reasons while other people become rude to their callers. This gives all your lenders the impression that you are not trustworthy, and you are rude and unlikely to pay on time.

How Honesty Can Be the Best Policy in Branding & Marketing

When you are trying to encourage people to use your product or service, it can be tempting to exaggerate or overstate your own importance. But sometimes it pays to be honest about what you are offering and what a customer can expect. Here is why.


The second-best car firm

A famous example of this was the car rental firm Avis, who used the fact they were only the No. 2 car rental service in the USA as a selling point. They suggested that being second best meant they could not afford to offer poor service. Their original advertising campaign was a little convoluted but it eventually spawned the tagline “We’re number two, we try harder.”


The functional wood stain

In 1994, UK wood stain and paint manufacturer Ronseal employed the services of London advertising agency HHCL to come up with a new marketing campaign. The resulting phrase, “It does exactly what it says on the tin,” has become a common idiom in the English language. The first advert promised that the company’s “quick-drying wood stain” would stain wood and dry quickly – just as it says on the tin. The campaign was so successful, it is still running today, 26 years later. The phrase is now used for anything that lives up to expectations without exceeding them.


The straight-up casino

We all know that wagering is a risk but not many gambling companies start out by telling you that. However, there is one exception. One online casino went even further and named their company “Rizk”. Their upfront no b.s. approach has to be commended and it might even make bettors feel more comfortable using a provider who clearly has nothing to hide. They even have a character called Captain Rizk who presents the latest bonus offers. You can read the full Rizk review here.


The hotel that comes clean

To find a great example of how being honest can actually lower your customer’s expectations and allow you to exceed them, we have to head to Amsterdam. The city is a popular destination with travellers from all over the world and there are tons of cheap hostels to choose from. But only one boasts about just how bad they are. The Hans Brinker Budget Hotel loves to tell you how ugly their building is, how plain their rooms are and how poor their service is. They even suggest that when you think things can’t get worse, they’ll do their best. They boast about having doors on all their rooms and being good at ignoring your complaints. They set the bar so low, that customers actually leave satisfied.

This type of honest marketing first kicked off in the 1960s with Avis and also with Volkswagen, whose marketing campaign for their new Beetle car revolved around the fact that it was ugly, small, impractical and perhaps not too reliable. The rest they, as they say, is history.

EDITOR'S PICK OF THE WEEK

China economic growth

China’s Challenging Search for a New Model of Economic Growth

By Danny Leipziger China cannot continue to rely on exports to drive its growth, but what are the alternatives? China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...

WISE DECISION MAKER GUIDE

POWER INFLUENCERS

Emerging Trends

The Future of Global Trade