Home Blog Page 957

Company Voluntary Arrangements in the UK – Dodo or Phoenix?

Company Voluntary Arrangements_featured Image

By Edward Starling

Company voluntary arrangements (CVAs) in the UK are a little like half-mast trousers. When they first came out, they were very popular and there was a lot of excitement. After a while, they became distinctly uncool and were usually on the radar for all the wrong reasons. And then, like many cyclical fashion trends, ankles were everywhere. But is a CVA (still) a valid restructuring tool for struggling businesses or does it just delay an inevitable terminal event for a business?

How do CVAs work and what to watch out for?

CVAs were introduced in the UK as a more flexible and cost-effective route to restructuring a struggling business without the need for a more cumbersome scheme or a formal, and perhaps terminal, insolvency process. It essentially works like an agreement between the company and its creditors to reach a compromise over existing debts to allow the company to continue to trade and creditors to get a better return than if the company went into a form of insolvency process. The directors of the company remain in office and in control of the company, albeit under the supervision of an insolvency practitioner – to ensure compliance with the terms of the CVA. CVAs typically last five years and usually involve reaching compromises with creditors – reducing future payments (such as rent) and paying sums from ongoing trade or a supporting shareholder into a pot for the benefit of creditors. The company therefore has to persuade creditors that, despite its being in this mess in the first place, with the adjustments there is an underlying good business that can continue, and it can pay its debts as they fall due going forward and, perhaps, also contribute extra from trading receipts. Against the backdrop of already being in distress, that can be a difficult argument to win.

After the initial interest in CVAs, the market became a little sceptical of their use, partially due to some rare cases of the process being abused. The success rate of CVAs was not good; some statistics have shown that over 60 percent of CVAs were terminated before the end of their term and the company was placed into administration or liquidation, by which time significant costs had been incurred. All practitioners have seen cases where there was little real prospect of the CVA succeeding (often based on overoptimistic and unrealistic forecasting), or indeed cases where voting during the approval process was manipulated to push it through (such as using “friendly” creditors).

Since then, CVAs have taken on a new lease of life, particularly in the multi-site retail and hospitality sectors. The reason is the possibility of structuring a CVA in such a way as to compromise on existing debts, but also restructure the ongoing obligations of the company, in particular its rent, for the period of the CVA. This has typically manifested itself in very detailed and lengthy CVA proposals where the pool of landlords is split into a number of different categories which are then treated differently in the CVA proposal in accordance with the profitability (or not) of a particular store or restaurant. The CVA may seek to relinquish certain underperforming leases, whilst reducing rents by perhaps 25-75 percent across other sites or switching to a rent based on the turnover of a site.

Because of the prevalence of this approach, this has become very unpopular with many landlords, as it is seen as an attack on their proprietary rights and because in many CVAs the landlords are singled out for reductions of future rent. Some have argued that this in some ways represents a recalibration of the rental market that reflects the wider crisis faced on the UK high street. This has led to a number of well publicised legal challenges over the terms of the CVA and has resulted in the development of a more defined process of analysis as to whether a CVA is appropriate and legal. This analysis is driven by the two mechanisms available to creditors by which to challenge a CVA: (1) that there has been a material irregularity in the CVA procedure (often an anomaly in the formal voting process); or (2) that the CVA is unfairly prejudicial to a particular creditor or class of creditors (the question being whether certain creditors are prejudiced by the CVA proposal, and whether that prejudice is justifiable in the circumstances). It is the latter that landlords have focused on in recent challenges.

In short, when preparing a CVA, there must be a “vertical” comparison of whether there is a better projected return to creditors by entering a CVA as opposed to another form of insolvency process (it effectively sets a bottom line), and also a “horizontal” comparison of whether specific categories of creditors could be seen to have been treated differently and whether that treatment is unfair. One of the benefits of a CVA is that there is nothing wrong with treating creditors differently, so long as it is fair and there is a justification for that treatment (that is, it is a necessary step and the only way to ensure business continuity without the significant impact of an insolvency process).

The most recent challenge, which generated widespread press coverage, was that funded by Mike Ashley’s Sports Direct group in relation to the department store chain Debenhams. Save for the court reiterating that a CVA cannot affect a landlord’s right to forfeit the lease as this was a proprietary right, those challenges largely failed; but further challenges highlighting the targeting of landlords in particular continue to be made.

For a CVA to be approved by creditors, it must have the approval of 75 percent by value of the creditors who vote. One of the benefits, therefore, of a CVA is that if the company receives the requisite number of votes, the CVA binds even those that voted against it. This enables the company to proceed without constantly defending against dissenting creditors and gives the company the space to facilitate a successful outcome at the end of the CVA.

A valuable tool if utilised well

But CVAs, used in the right way, can represent a very useful tool to avoid the detrimental consequences of a formal insolvency process. This requires appropriate planning and advice, ideally at an early stage, including in relation to the property aspects, such as proposed reductions, whether the new proposed rent is below market value and the realistic impact and options for landlords of affected sites. The directors continue to manage the company, albeit within the confines of the CVA, and would typically have forced some concessions from certain creditors (landlords in particular) to give a lifeline to ongoing trade and an exit to normal trading after the period of the CVA. However, it doesn’t end with the approval process; the management need to engage with creditors and stakeholders to ensure the CVA is successful and avoid wasting funds that would otherwise have been available to pay creditors. Importantly, the return to creditors should, in theory, be better; whilst they are fact-specific, returns to creditors in liquidations may be around 1-10 percent, and CVAs perhaps around and possibly over 25 percent. With the distress on the UK high street, which has filtered up to the landlords, and the changing dynamics of British cities in particular, CVAs are still particularly relevant and can be a viable restructuring option.

The popularity of CVAs in the hospitality and retail sector and the associated legal challenges in relation to the treatment of landlords have also led to changes in the way that CVAs are proposed. It is now not unusual to see a “fighting fund” set aside in order to deal with a legal challenge. Perhaps if that fighting fund were to be returned to the pot for the benefit of CVA creditors, it may actually incentivise creditors to think twice before challenging a CVA, as they may actually enhance their overall return. That is combined with the fact that CVAs are already an expensive process. There are many recent retail and hospitality CVAs that have run to hundreds of pages of complex drafting, as well as nominee and supervisor fees in the many hundreds of thousands of pounds. Although the intention behind CVAs was a quick and cheap process to avoid an insolvency procedure, in some cases a CVA could still result in a better outcome for creditors, employees, suppliers and other stakeholders than the ultimate risk of a terminal liquidation.

What now?

Like the fashion for trouser length, CVAs will continue to be utilised and, indeed, progressively adapted to suit the prevailing environment. The continuing distress in the retail and hospitality sectors has been further exacerbated by the pandemic, with what might be a short, medium and even long-term impact on the way people live, shop and work, and the knock-on effect on the way we use UK cities. That is going to cause further issues with multi-site operations, especially those with large workforces, many of whom have received the benefit of the UK government’s ongoing support through the employee furlough scheme. That security blanket cannot last forever and so plans need to be formulated to ensure that those with fundamentally viable businesses survive, and CVAs can, with careful thought, play a vital role in that recovery.

About the Author

Ed Starling_Author

Edward Starling is a Partner at Wedlake Bell, specialising in insolvency and restructuring. He specialises in bringing and defending claims brought by liquidators and trustees in bankruptcy including transactions at an under value, voidable preferences, wrongful and fraudulent trading, and breach of duty. Ed also acts as an independent Supervising Solicitor overseeing search (and seizure) orders obtained in civil proceedings.
Why You Need To Discuss Health Issues With Your Physicians

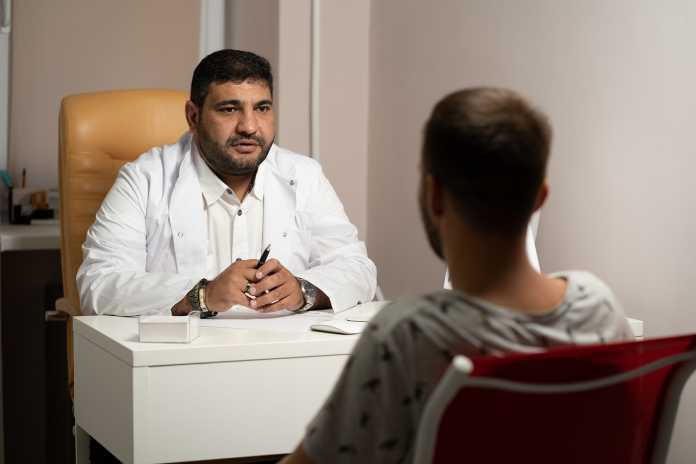
Your health is the most precious intangible aspect of your life that shouldn’t be taken for granted. But there are obviously some instances where you neglect it by not telling your doctor what pains you really feel within your body.

Reasons for not divulging these important facts are far and wide. However, it can create huge complications to your health, life, and indirect consequences for the people you love and depend on you.

Aside from this fact, why do you really need to discuss all your health issues with your doctor? Here are the simple and practical reasons why.

Accurate Diagnosis Of Your Condition

Doctors, however experienced and knowledgeable they are, depend on the information you give them regarding your condition. For example, they can help you discover the options for gastric sleeve surgery to help with weight loss. This is how they can evaluate what may be bothering you and give you an accurate diagnosis. You may sometimes hear that doctors order a lot of blood and laboratory tests for some patients. They are fishing for more money, it’s just that the condition is so baffling, they don’t have a clue what is it. To avoid these, you would need to give your physicians all the issues you are feeling.

However, after all the information has been divulged and your doctor orders a series of blood tests than you can afford. You could always outsource it to a reputed, much affordable laboratory. According to medical experts at Discounted Labs, blood work is the most reliable test any doctor can have to rule out and determine your illness. Your blood carries your DNA and goes through all the parts of your body that it is an accurate indication of how your body is doing. That’s why most tests need a teeny tiny bit of your blood.

Get The Right Meds And Treatment For Your Illness

A consequence of not being able to tell your doctor all the information he or she needs to understand your physical situation is a wrong diagnosis which leads to the wrong treatment process. You may be asked to take medicines that can even aggravate the pain you feel and on occasion, it can be fatal. Based on the incomplete health issues you have divulged, your physician may tell you that you need surgery. But in fact, you do not. Diagnosis and treatment go hand in hand. Another reason why your doctor needs to know everything about the physical pain you’re going through.

Avoid Unnecessary Medical Expenses

One other fact that goes without saying when your doctor wrongly assesses your medical condition is the medical bills that come with it. When they don’t have all the details, your doctor could make you go through a series of lab tests, prescribe you the wrong meds and treatment that can further worsen your condition. All these tests and treatment protocols and procedures have an accompanying price tag in them. And that’s not all. If because of this incorrect diagnosis, your state of health is magnified, you will be left with more tests and procedures. Expenditures that could have been avoided if you have told your doctor all the truths about how you feel in the first few consultations.

Further Complications Of Your Condition

There are some diseases that when left unchecked can affect other functions of your body. A great example of this is diabetes. Diabetes can develop numerous complications including eye, skin, and foot infections as well as stroke, high blood pressure, kidney disease, DKA and ketones, neuropathy, and many others. With so many connected complications it’s important to treat diabetes. Your physician can recommend treatments like weight loss surgery from CCS Gastric Sleeve Newcastle, to help manage your diabetes and overcome some of it’s problems.

Negative Effects On The People Around You

An indirect repercussion of the misdiagnosis and complications that might occur is the devastation of your immediate family and the compromises they would have to do to accompany you towards your health journey.

Your immediate family would carry the heaviest emotional baggage caused by your frequent hospitalization, sickly condition, and a life full of worry and uncertainty. Several medical research has shown the negative psychological effects of family caregiving to an ill family can cause changes in the family dynamic and relationships between each other.

Further, the financial burden that the individual and family members have to bear can take a toll on the family’s finances as well as the financial health of each family member. Paying for medical expenses can be so costly that even homes are being mortgaged without any means of how to pay for the loan.

Loss Of Livelihood And Future Earnings

Because you are sick, your illness can affect the productivity of your work costing you your livelihood, the source of income for the family if you have little mouths to feed.

Moreover, your spouse or any adult member of your family may need to sacrifice their job to care for you if a family nurse or caregiver is too big of an expense. Your family and you will also have to suffer from the loss of future earnings that could have been spent on other financial priorities if you hadn’t been too sick. 

It’s true. Insurance can take on your medical expenses. However, there is a limit to everything and so is the expense your Medicare or any HMO will be willing to finance. If you are familiar with these limitations, there are only a handful of diseases and laboratory tests that your insurance has agreed to pay for you. They won’t make a profit anyway if they shoulder every bit of your medical needs.

Caring for your health is not anyone’s responsibility, it’s yours. And your physician is there to help you understand what you are going through. Not giving them all the details of how you feel will inhibit them from giving you an accurate assessment of your health and your body’s condition. And all the medical treatments and expenses that go with it will be skewed. It may even aggravate your condition. Being honest with your medical doctor and having confidence in him or her to help you with your physical pains is the best way in avoiding all these difficult situations.

Will Biden Make Transferring Data To The US Easier

By Alexander Egerton

The expectation is that the new administration will look to reverse the deterioration in relations between the US and Europe. Leaving the politics aside; for a number of years there has been a battle between Brussels and Silicon Valley over the scope for EU companies to transfer data to the US. Put simply, the EU prevents data being freely transferred from the EU to the US, which is why many Silicon Valley companies have operations in the EU. There have been past compromises (the “safe harbor and privacy shield”) but these measures were invalidated by the European Court following challenges by Max Schrems, an Austrian citizen. The privacy shield was invalidated in July 2020 in a case called ‘Schrems 2’.

The restrictions on transferring personal data do not just concern the US. The European Data Protection Board “EDPB” has assessed every countries’ privacy ”set up” and only 13 (including Isle of Mann and Channel Islands) were deemed adequate. The US is not one of the 13 countries. Following Schrems 2 therefore EU companies are back to using “standard contractual clause” and doing due diligence on US companies. This involves conducting a detailed assessment as to how each US company processes data – which has to be properly documented in case the decisions are subsequently challenged – and negotiating the standard contractual clauses, the terms of which many US companies will find to be too onerous. If there is an imbalance of power the EU company may not be able to complete these processes and have to find another company to work with.

Can the new administration permanently unblock this issue?

US vs EU Privacy framework.

The GDPR is the most comprehensive privacy legislation in the world. The EU regard privacy rights as a “fundamental” right. The territorial reach of the GDPR means that EU companies cannot transfer data to non-EU countries unless EU citizens’ privacy rights will be maintained. GDPR “travel” with the personal data.

While each EU member has to adopt and enforce the GDPR with limited scope for national changes, the US framework is more splintered. There is no Federal Privacy Law. The Federal Trade Commissioner (FTC), Noah Phillips, has said the U.S. needs a federal privacy law. So while states such as California have privacy legislation, others do not. The Californian Privacy Act became law on 1 January 2020 and is the most comprehensive: citizens can ask for their data to be deleted but the act does not require businesses to risk assess their entire data processing modus operandi. Those states which do not have privacy rules argue that the US Bill of Rights is sufficient.

There are cultural issues in play. Some have concluded that in the US the expectation is that once a citizen has disclosed his data, his rights fall away and the recipient can maximise that asset. Bear in mind that the GDPR was dismissed by many on the West Coast as another example of the EU regulating while the US innovates.

When the privacy shield was invalidated by the courts, both the European Data Protection Supervisor and the EDPB issued statements that the United States should now introduce a comprehensive data protection and privacy legal framework essentially equivalent to the GDPR.

Where are we after Schrems 2?

The privacy shield (and its predecessor the safe harbor); both formal agreements agreed by the UFTC and the predecessor of the EDPB, were unpicked by the same individual and the detail of the processes EU data controllers must follow to transfer personal data to the US is beyond the scope of this article.

The privacy shield allowed US companies to register with the US FTC so any EU company could proceed with comfort as to the bona fides of the recipient and had no need to conduct due diligence. This process was declared invalid. The data transfers will have to follow other processes in the GDPR – the standard contractual clauses and conducting a risk assessment on the credentials of the recipient. As of now, despite these compromises, the US is now in the same position as a lot of other countries.

Where does this leave post-Brexit UK? 

The UK has committed to follow the GDPR and other EU derived privacy laws in order to become the 14th “adequate” country. If the UK cannot quickly achieve that status, then while the UK is happy for transfers to EU; the EU will not reciprocate. For EU companies transferring personal data to the UK next year this will require the same bureaucracy as transfers to the US entail. We will no doubt see UK companies setting up in the EU to avoid losing this business from the EU.

Although some in this Government have questioned the merit of securing an adequacy decision from the EU – a decision made by their predecessors, we have to assume that the cost benefit analysis remains unaltered. If the UK was to take a different approach to the EDPB regarding the US’s “privacy set up”, this could jeopardise the coveted “adequacy” decision. For these reasons this article assumes that the UK will follow the EU’s stance on transfers to the US and will act as if it was still an EU member.

President Biden?

Any optimism that the incoming Biden administration will lead to a more flexible EU/UK transfer of data is likely to be misplaced. While to many this may appear a squabble over an esoteric concern and to others is the EU exercising its geo-political might, this issue is born of deep rooted cultural and constitutional differences between the EU and US. Furthermore, US national security law — which provides American agencies far-reaching means to collect data on non-US citizens  will continue to be an issue. Put simply, these US laws challenge the supremacy of the GDPR which the European institutions were protecting with the two Schrems decisions. Even if the Biden administration makes progress with EU leaders in bilateral trade talks dealing with this issue, the reality is that the EDPB would make the decision and this body is independent of the EU institutions and the political leaders of the leading EU member states.

The only way for this impasse to be broken is for the US to introduce a Federal Privacy law. There are a number of reasons why that may not be politically palatable, but even if sentiment has changed such a law would have to navigate the US Congress. Bear in mind that even with a consensus in favour of GDPR the GDPR took five years to be approved by the EU. It is harder to implement comprehensive reform in the US even where there is a consensus behind it. Standard Contractual Rules and due diligence on US companies are here to stay.

About the Author

Alexander Egerton, Partner at Seddons, is an experienced commercial lawyer who acts for small and medium sized enterprises, trade associations, professional firms and entrepreneurs. Working proactively with the founders of start-ups and helps them grow their businesses, he is able to share his expertise in data protection law; “e-commerce” law, intellectual property law and contract law. Alexander has a lot of experience in advising founders regarding implementing share options schemes and helping businesses prepare for (and then managing the process) further investment rounds. He is often approached by entrepreneurs asking him to work with them as they embark on their post exit projects.

Creating financial wellness for employees via gamification

By Will Bailey

Financial wellness means different things to different people and there is no universally accepted definition. My favourite definition of financial wellness as being financially stress free and not worried about debt and unexpected expenses. The reason that this definition rings true to me is that it speaks to the personal relationship one has with their finances and applies across the entirety of the wealth spectrum.

The idea of being stress free about finances is especially prescient when one considers recent research by PWC found that 54 percent of employees say finances and money matters cause them the most stress in their lives. Therefore, any employer seeking to create a positive and less stressful working environment must provide benefits to their workforce that address financial wellness.

Getting to the root of the problem

Where does financial stress come from for employees? For many, it results from the feeling of being unprepared. In the UK, 39 percent of adults don’t feel confident in managing their money, and 11.5 million have less than £100 in savings. This uncertainty causes a domino effect, as many will reach out to friends or family members to help bridge the gaps during unexpected times. Yet many times, these external parties are also in the same predicament, living without a safety net – creating further cycles of stress and uncertainty.
So why should employers care? Beyond simply having happier employees, when people are stressed about their finances it causes significant implications on their focus and productivity in the workplace. More than 35 percent of employees admit money matters affect them for three hours or more a week. For employers, this lack of productivity has the potential to cause significant impact to the bottom line. To put this in perspective, imagine the impact to a business if over 35% of their workforce took unanticipated half days off.

Many employers recognise the importance of reducing their employee’s stress. Investment in workplace benefits – from health insurance to free gym memberships – remain prevalent in the market. However, employers still have the opportunity to invest in their employee’s wellness by including financial wellness into their benefits offering because for many employees, there is little in the way of guidance or mentoring for how to handle their finances which is their largest source of stress.

While the challenge may seem daunting, the solution is two-fold. Individuals, regardless of where they stand on the wealth spectrum, must engage in improving their financial wellness. Employers must also rethink their benefits and support packages for their workforce.

The first step and beyond

When one decides to live healthier, they will take steps to consciously engage in a plan – such as exercising, eating healthier, etc. The same principle applies to finances. Employees must engage and devise a plan to better their financial wellness. This can be done by adopting financial wellbeing tools; these can track income, understand what needs to be saved, allow goal setting, and compare current finances against goals.

The current climate has accelerated workers taking the first step in utilising such tools. A recent survey of 2,000 UK adults showed a sharp increase in the use of money management apps during the COVID-19 outbreak. This upshift came as a result of individuals seeking to gain control to better manage their finances.

While this is a significant first step, it must be built upon. Delivering financial wellness just like improving one’s health must be done through tools and apps that encourage participation and engagement via gamification, behavioral science, decision theory, and data science.

This is supported both experientially and with data. As an example, we all know someone who during 2020 has become a Peloton (or equivalent fitness tool) evangelist. They talk about their leaderboard, how much they love their favourite instructors and the community. By deploying gamification to drive engagement, in this case the One-Up Dynamic, and Community Dynamic, Peloton has seen over 450% increase in their stock price in 2020.

Further proof is shown by a study from the US Centers for Disease Control and Prevention, which showed that gaming features have immense power to keep audiences returning for gratification. Its study of youth behaviour from 1991 to 2018 revealed that respondents found video games more engaging and addictive – even more so than tobacco and television.

The same dynamics of gaming and behavioural science deployed by Peloton and many, many others (Tiktok, Instagram, and LinkedIn to name a few) can be utilised by employers to help their employees become more financially well and by reducing stress in the workplace to yield greater productivity.

The employer initiative

So, what can employers do to tackle the challenge of employee financial wellness? First and foremost, they must meet their workers at the current stage of their financial journey. Any solution for financial wellness needs to recognise that every individual has a different need. A new graduate just starting their career in marketing has different needs to their colleagues working on the factory floor. Similarly, the financial plan and goals of one working on the factory floor will be different than those in the C suite. A holistic financial wellness offering must equip all employees with empathetic information to improve their financial wellness and enable them to easily digest and engage with the information on offer.

Another important facet of any financial wellness program is trust. In order to create trust, employers must make sure that their offering is empathetic and honest. As we all know, trust is the most important aspect when dealing with something as sensitive as finances. To promote transparency, tools on offer must be accessible to the user wherever they are – whether that is via mobile or desktop, at home or on the go. It must also reflect the individual’s own situation and preferences – speaking to them directly and in a way they understand.

An easy way to create more engagement and trust in a financial wellness platform is, like Peloton, to offer community, individuals who are aware and reminded that they are among meaningfully similar people with whom they can learn, share, communicate and celebrate are more likely to engage and trust their experience. When combined with progression, allowing an individual to see and feel forward movement with each step, action or submission, always with a clear view of completion and celebration, an employee can see how the actions of people like them have led to better outcomes and will engage more readily in their financial wellness. Whether the goal is to pay off your debts, or save for retirement, being able to see that other people like you have achieved the goal drives better outcomes.

Finally, employers should consider providing access to experts. Many people want to validate their decisions with someone who is experienced – such as financial coaches or advisors. A good holistic financial wellness platform will allow employees to learn and take actions on their own whilst also providing a channel to seek expert guidance. This provides workers with security because they have access to quality help, when they need it.

The future of the workplace

As we look forward, the need for financial wellness increases. While today, 35 percent of employees are distracted by financial stress at work for more than 3 hours a week, the number increases to 50 percent when focusing just on millennials – arguably the most indebted generation. This number will continue to rise as the future workforce is faced with rapidly high costs of living – mortgages, car finances, student loans, and so on. As a result, this generation is more concerned about their financial wellness, with up to 65 percent wanting gamified experiences to help them learn about investing and portfolio management.

To keep employees happy and productive, companies must make it their duty to take care of the whole person, past the contracted working hours. Financial wellness support must be a part of every benefit scheme. As a result of this, employers can find ease in knowing productivity levels are high, while being able to retain a greater number of staff. For any business, creating financial wellness for employees is a win-win for the bottom line. They just have to ensure the experience sticks.

About the Author

Will Bailey, Chief Strategy Officer at InvestCloud, has worked for the fintech firm since the company’s founding. Prior to his appointment as CSO he moved to London to head investCloud’s European expansion. He also previously led the platform technology and product management teams at InvestCloud, and is proud to contribute to the delivery of innovative and beautifully designed solutions to improve the client communication, client automation, data analysis, data management and workflows of InvestCloud’s clients.

COVID-19 Spotlight: Entrepreneurs Must Adapt to the Pandemic, says Jesse Willms

We are currently in the midst of one of the most uncertain times in recent history. Millions of people across the globe are either locked down or quarantined in order to prevent the spread of Covid-19. To make matters worse, things are changing dramatically from one day to the next as governments implement new measures to try and control the situation, and as a result, the global economy has been rocked to its very core. 

Consumer behavior has shifted towards online purchases as retail footfall plummeted to record lows. As a result, countless businesses have been forced to adjust to the new circumstances or, in some cases, shut up shop entirely. 

However, as the situation continues to unfold, it begs the question as to whether or not there is opportunity amongst the chaos for entrepreneurs. While so many businesses fail to adapt to these unique times, is there a golden opportunity for those that are willing to rise to the demands of our newfound struggles?

Who is Jesse Willms?

To say Jesse Willms knows a thing or two about entrepreneurship would be the understatement of the year. Ever since he was a teenager, Willms has been adept in practically every facet of entrepreneurship, particularly in eCommerce and marketing. 

His first venture, eDirect, became a multimillion-dollar business by the time he was 18 and would eventually go on to pull in over $50 million in revenue. Since then, he has created 12 different million dollar health and wellness companies, selling well over $500m worth of products and supplements, including Acai Berry, Tea, Resveratrol, Hoodia, Anti Aging Creams, and Teeth Whitening sets. 

However, it hasn’t all been plain sailing for Willms, as he has had to overcome his fair share of adversity and negative publicity in his time. This is precisely why he is such an excellent mind to turn to in the wake of the current circumstances.

How to find opportunity amidst a global pandemic

Listen to your customers

Covid-19 has completely transformed the way we interact with each other. Depending on what part of the world you reside in, there’s a high chance that you must adhere to social distancing rules, and there may even be restrictions on what type of businesses are allowed to open and which must close. 

Most of the time, business owners feel hard done by as the restrictions prevent them from being able to make a profit in their usual manner; however, it’s important to understand how the restrictions impact the consumer. 

Reach out to your customers. Understand how the pandemic has impacted their life and how it may have affected how they interact with your business. Get in their shoes and reverse engineer the customer journey from start to finish. If you’re a retail business that relies on footfall, do what you can do to digitize your business and learn how to connect with consumers online. 

“Listening to customers doesn’t just mean paying attention to complaints and dealing with escalated issues. Listening to customers also means leaning forward and engaging in dialogue to learn about factors like motivations, aspirations, expectations, and perceptions,” says Willms.

Be ready to adapt

“Slowness to change usually means fear of the new.” — Philip Crosby

Businesses that adapt to these difficult times will survive and thrive. Those that don’t will likely face huge setbacks and may lose ground to those there who were willing to change their business practices effectively.

Is your supply chain as effective as it was before the pandemic, or are their frailties starting to emerge? How about your marketing? Continuously ask yourself these questions and be sure to reevaluate your business practices as circumstances change.

When discussing his current venture, Willms explains how he deals with the current circumstances in order to stay ahead of the curve.

“With the business landscape continually evolving, there are a few things I do to try and stay ahead of the curve. Firstly, as an online company, we are very flexible. We can internalize and adapt to changes quickly, which gives us an advantage over more rigid business models. By maximizing on new opportunities, we avoid getting ‘stuck in our old ways’ and losing market share,” he says. 

Show empathy instead of chasing profits

If Covid-19 has taught us anything, it’s how interconnected we all are. It’s during these moments that we are reminded of how important it is to come together as a society in order to find a solution to these difficult times. 

This presents a great opportunity for entrepreneurs to establish brands that show they care about their consumers by going the extra mile. This might mean setting aside short-term profits, but the relationships and levels of trust you build with your customer base will be worth it. 

“The COVID-19 crisis has created a hyper-awareness among consumers of businesses that authentically want to help them and make their lives better, and businesses that are only interested in making as much money as possible,” says Willms.

“Businesses that authentically demonstrate empathy and caring at this time are making an investment that will pay dividends for many years to come, while businesses that are only in it for themselves will find out soon enough that scorned customers have very long memories, and they also do not hesitate to share their unhappy stories online and offline with anyone who will listen.”

The bottom line – Be ready to learn from mistakes

Let’s face it; Covid-19 is the fastest growing threat to our economy. Another deep recession is expected, and years of hardship seem to be staring us all in the face. However, in all honesty, nobody knows what is going to happen from here. Even if a vaccine is successfully deployed, it’s likely that the business landscape will never return to its pre-pandemic state. 

Entrepreneurs and business owners must now act as the trailblazers throughout these unprecedented times. Naturally, this means that mistakes will be made, and if you’re running a business, you will almost certainly encounter obstacles that you have never experienced before. 

“Don’t be afraid of challenges just because you think you might fail. If we all gave up at the first sign of failure, there might not be any entrepreneurs out there. The trick is being able to bounce back when something doesn’t go your way. I have made many mistakes throughout my career, but I have never let them define me. Instead, I acknowledge that an error was made and try to learn from it,” explains Willms.

“You can also view challenges as an opportunity to grow, develop a thicker skin, or improve important skills. At the end of the day, if you truly want something, you will work hard to achieve it.”

How to Find Manufacturer-Offered Deals

So, you are in the market for a new ride, but you want the best deal possible. The easiest way to find deals and incentives is to scour automotive websites for a rebates or special offers section.

When you get deep into the car shopping process, at some point you’ll likely winnow your choices down to a few prospects that, all things considered, are not that dissimilar. That’s when vehicle incentives and rebates can help you make a choice.

Assuming of course, you know how to find manufacturer-offered deals.

Types Of Vehicle Incentives

Before you start looking for deals, it’s good to know exactly what you’re looking for. First off, there are three main types of incentives and rebates: financing deals, lease incentives, and cash-back deals.

Financing deals usually mean a lower interest rate when you take out a loan for your soon-to-be new ride. Such offers usually require the buyer to have a stellar credit score and obtain financing through a specified lender. Also, you probably have to choose between special financing and a cash back incentive, so the best bet is to determine which offer is the best for you overall.

As for lease incentives, those usually feature a lower monthly payment amount or discounts on the up-from lease payment. Cash back, meanwhile, is a bit of a misnomer. In lieu of forking over cash after you buy your vehicle, the dealer or manufacturer simply discounts the car’s price.

How Do I Find Available Rebates And Incentives?

Say you are looking for Ram deals on a new truck. The first stop is the manufacturer’s website. In fact, most automakers will have an online section dedicated exclusively to specials. That space is typically updated monthly, so it’s a good idea to be current on all the incentives in which you have an interest.

You also can hit up the dealership and ask about any incentives they might offer. In general, dealers will be candid about telling you whether there are rebates or special offers to be had on vehicles – IF you ask. In other words, while some incentives are highly advertised, others are secret and call for some digging.

Another idea is to go to websites that compile in one place the best incentives, offers, and rebates for popular vehicle models. Resources such as Kelley Blue Book and U.S. News update their choices monthly.

In addition to dealerships, automotive companies may also offer special lease programs through their own finance firms. Known in the industry as sub-vented or subsidized leases, these programs can be found on websites such as Edmunds.

Continue To Negotiate

After a bit of searching, you’ve found the desirable rebate or offer on the vehicle of your choice. You can usually still negotiate the vehicle’s selling price too. Just proceed on the assumption that you are going to get the incentive at the advertised value and negotiate pricing as usual.

Now that you know how to find manufactured-offered deals, and you are up to speed on what the various kinds of incentives entail, you are ready to get the best deal on the ride of your choice. When it comes to car buying, knowledge is certainly power.

Just make sure that you read the fine print on any special offer from a manufacturer or dealer, since such promotions are typically aimed at consumers with great credit. Don’t be discouraged though, you can almost always find a good deal, even if you don’t have an A+++ credit rating.

Everything You Need to Know Before Launching Your E-Commerce Store

According to IBM’s U.S Retail Index, the coronavirus pandemic has accelerated the growth of e-commerce stores by a fivefold increase. People are no longer willing to leave the house to attend physical brick-and-mortar shops, especially with the potential risks brought upon by the health crisis. It’s no surprise that this unprecedented pandemic has caused a shift in attitudes, after all, practically everything is now available online.

The e-commerce sector is expected to reach a value of US $6.07 trillion by 2024. The health crisis is only one of the reasons for this increase. The younger generations are highly tech-savvy and express a preference for online shopping. The proliferation of smartphones and an increase in the use of online wallets have also contributed to this boom in e-commerce.

These figures demonstrate that there is indeed a demand for online shopping, however, it also means that there is a lot of competition. Apart from the big players, like Amazon or Alibaba, there are thousands of independent retailers who are also hungry for a piece of the pie. Nevertheless, this is no reason to be discouraged from launching your own e-commerce store, on the contrary, you should be eager to get stuck in.

Thanks to the internet, launching a business is now easier than ever. You may have identified a sizeable gap in the market, or perhaps you just have a flair for entrepreneurship; whatever the reason, now is your chance to build the business of your dreams. There are several ways that you can stand out from your competitors and run a successful e-commerce site. Here is everything that you should know before launching your online store.

Write Up a Business Plan

If you want to be successful at managing your business, you must have a plan to guide you in your decision-making. Organization and clear goals will help you achieve your plan of action. This part may seem like the most tedious, but it is also one of the most essential aspects of any business. Without a plan, you won’t be able to estimate profits or budget your resources. Make sure to include aspects like your business model, target audiences, messaging guidelines, funding, budgets, and financial projections.

Research Your Competitors

If you want to stand out from the crowd, you must first identify who is in that crowd. A simple Google search can offer you hundreds of similar businesses. If your business is more localized, make sure to include your area in the Google search. Take a look at their user experience and website, are they providing anything that you have not thought about? Whatever you do, don’t try to copy their work. You want to stand out from your competitors, not blend in. Pricing, promotions, and website copy are a good place to start when researching other companies in your field.

Create a Brand

Branding is a marketing practice that all online stores should take seriously. This is a way to make your e-commerce store memorable and allows your customers to distinguish your product and services. Branding encompasses everything from your logo, to your packaging and social media posts. These elements should be attention-grabbing and relate to the tone of your business.  

Keep Your Customers Happy

It’s no surprise that without a happy customer base, your e-commerce store will ultimately have a harder time gaining notoriety. Your customers are a vital part of the business as they generate sales, increase your reputation, and can even help you market your business. The key pillars of customer success include an optimal user experience, an efficient delivery service, and great customer support. They should be able to navigate your e-commerce store with ease and receive their purchase with minimal disruptions. An easy way to ensure that your business has a reliable courier service is by using a third party such as visible supply chain. This will take a large chunk of the responsibility off of your plate and allow you to focus on other aspects of the business.  

Digital Marketing is a Must

No matter how large or small your e-commerce store is, digital marketing is an essential tool that you can use to promote your business. Digital marketing encompasses an array of online marketing methods that help your company increase their visibility online and reach new customers. This includes several channels such as email marketing, social media marketing, paid search advertising, and search engine optimization. These terms may seem intimidating at first, however, there are countless resources and free courses that can help you get to grips with the basics. If your budget is large enough you could also choose to outsource this work, however, many small businesses choose to do this themselves. Social media ads are a great way to reach potential new customers and increase customer engagement. Learn more here why you need to buy likes for TikTok channel promotions. 

Keep Up to Date with Trends

Keeping up with the latest industry trends will help you stay relevant in your field. With the advent of technology, news and social media trends are constantly changing. This is a chance for you to get creative with your brand. For example, the new social media platform TikTok has been a super successful platform for brand promotion, especially when trying to reach the younger market. Many fashion brands saw TikTok as an opportunity to promote their products and interact with the Gen-Z audience. If you manage to hop onto a trend before it becomes mainstream, you can use this to promote your e-commerce store.

Don’t Give Up

Whatever business you choose to create, the most important thing to remember is that building a brand will take time. It is highly unlikely that you will become a successful e-commerce store overnight, as launching a store commands a lot of effort and attention. If you are truly passionate about the service you are providing, this will be translated into your work. Make sure to not give up and to put 110% effort into everything you do. What are you waiting for? Your e-commerce store awaits!

How to Use Blockchain to Prevent Money Laundering

As the world becomes increasingly more digital year after year, even more so in 2020 thanks to the coronavirus, the technological enhancements in almost every aspect of life have been growing at an exponential rate.

Financial institutions today invest a far greater percentage of their revenue in new technologies like artificial intelligence, machine learning, and blockchain in order to digitize their operational activities as much as possible which in turn helps reduce cost and increase security.

Not only does doing so make transacting more reliable, but it also helps combat potential crimes like money laundering by collecting, tracking, and storing large amounts of data that is to be reported to regulatory authorities.

In this article, we are going to be looking at blockchain technology and see how it helps increase compliance by adhere to financial regulations and Anti-Money Laundering programs.

What is Blockchain Technology?

In a nutshell, Blockchain is essentially a distributed ledger system. In order words, it’s a database that records financial transactions and verifies stored data. Blockchain technology allows for a good alternative to the traditional banking system. Let’s take a look at some the qualities of blockchain technology that makes it different:

  • Decentralized
  • Transparency
  • Immutability
  • Anonymity

Decentralized

Arguably, the most fundamental quality of Blockchain technology that differentiates it from the traditional banking system is the fact that blockchain is a decentralized platform and doesn’t require a middle entity for a transaction to take place between two parties. Let’s take a look at an example to understand this better.

When you buy a certain product, say a t-shirt from your local store, the money passes through 3 parties: you (sender), your government (intermediary), and the seller (recipient). Here, the actual control of the money that you own is not in your hands but rather in the hands of your government as it can declare the currency note obsolete at any time. It is, therefore, a centralized system.

However, blockchain technology allows for direct transactions between two parties using a global network of computers referred to as “nodes,” eliminating the need of an intermediary, Hence, making it a decentralized platform. Via blockchain, the power is distributed to the actual owners of the money instead of a centralized entity.

Transparency

Transactions made using the blockchain technology are fully transparent i.e. publically viewable by anyone at any time by simply searching for the address of a given transaction online using ‘blockchain explorers’.

This quality is especially useful for increasing accountability as it allows people to supervise and track their transactions. In the case of traditional banking system, the transactions made and recorded can easily be manipulated and tampered with by an inside party because of lack of transparency of transactions to the general public.

Anonymity

To transact using blockchain technology, each party is assigned a cryptographic public and private key i.e. an address and a password. The public key is like your bank account number. You share it with the person(s) that you wish to transact with. The private key is your password to your wallet. It is never to be shared and kept hidden at all times.

The reason this quality is so praised is because it gives people peace of mind since they don’t have to register and verify their personal government ID with any bank or financial institution in order to make a transaction – unlike the traditional banking system – allowing for anonymity of the user.

Immutability

A transaction once made and recorded on the blockchain renders itself immutable i.e. it cannot be altered or tampaered with by any 3rd party. This is done by bundling transactions together in a “block.” A block is then linked together with other blocks to form a chain.

Hence, the name “blockchain.”

How does Blockchain prevent Money Laundering?

Since the inception of cryptocurrency in 2009, thanks to Bitcoin, criminals have repeatedly tried to use it to launder large amounts of money obtained from illicit activity. Since their identities are hidden, it becomes harder for regulatory bodies like the FATF (Financial Action Task Force) to catch them.

Money laundering, in a nutshell, is the process by which money obtained through illicit activity, say bribery or terrorist financing, is ‘cleansed’ by processing it in a sequence of banking transactions so as to make it appear as if the money came from a legitimate source.

As a matter of fact, the total amount of money laundered globally every single year amounts to a whopping estimated total of US $2 trillion. That’s roughly 5% of the world’s entire GDP! To combat money laundering, blockchain technology could be an ideal tool because every transaction done leaves behind a permanent trail that’s impossible to be altered – making it easier for authorities to track the original source of the money.

Currently, digital exchanges and financial institutions all around the world are developing frameworks that increase compliance and introduce greater levels of regulations in their system to comply with KYC and new AML (Anti-Money Laundering) guidelines as the old ones have been criticised to be ineffective.

Unlike current banking models where consumer data is given to large corporations without much consideration for personal security and control, blockchain technology is a much more trusted network where data would only be shared to verified and trusted sources.

Key Takeaways

The global financial model is changing, out of innovation but also out of necessity. The older AML guidelines and policies have been ineffective, resulting in poor management and low compliance which puts consumers at a risk of being compromised.

Financial institutions and governments around the world have started investing in blockchain technology as an alternate strategy. It is important to note that blockchain isn’t necessarily a global platform.

It can also be created for private use by individual financial institutions with a predetermined set of users. The participants within the network can seamlessly initiate and undertake transactions and access data.

Blockchain is, perhaps, the closest to an ideal solution we have so far to fight crimes like money laundering as its encryption technology allows for greater levels of security of transactions and safety of the parties involved.

About HR Software

HR software

HR management seems to be easy for those people only who have never worked in it. The real things are though completely different, and most of them require a lot of time, attention, patience, and expertise.

Thus, a specialized HR solution, such as Lanteria, can facilitate the work of any HR specialist and boost the efficiency level. A good HR software offers solutions for all specific aspects of human resource management.

Core HR

Here, you can count on finding smart solutions that will help you with the basics of HR processes. Org charts will create the wished transparency level. And tools for document management will allow you to keep all the data of your employees organized and easily accessible.

Tools to Check Time and Attendance

Time and attendance tracking are the most complex aspects of any company. Thus, a good HR software will for sure offer you solutions to satisfy the demand in this field.

With proper HR software, you can count on time and attendance tracking tools that:

  • Allow you to set up the company policy;
  • Track paid time off;
  • Track unpaid time off;
  • Track time on many other activities related to your job.

Usually, a special portal is provided for these purposes.

Recruiting Solutions

Every HR specialist knows how much it normally takes from posting a job until finding the right people for the team. Thus, with proper HR software, you will be provided options to unify the entire HR and onboarding process. It will allow you to automate the biggest part of all the processes and to find the right specialists for your team within the shortest time.

Motivating and Performance Tracking

Performance tracking and motivating are challenging in any company. With HR software, if it is developed properly, you get a set of tools to handle these aspects, too. These tools help you to set goals clearly and transparently. They assist in providing feedback and streamlining the appraisals.

Learning Management Tools

None company wants its employees to get stuck at the same level. The world is developing, thus, employees shall get new knowledge and experiences to adapt to the world, fast-changing environment, and to enable the company to stay competitive.

These tools assist in planning training programs. They ensure these programs` timely delivery and attendance. With the help of such tools, such details as the training session compliance with requirements and standards are checked and ensured. And of course, the final stage such as performance tracking and results assessment is not forgotten, either.

Final Thoughts

Do all these things seem incredible to you? Come on, they already exist and are widely used by the best companies and the most efficient HR managers. Do you want to be among them? By the way, the mentioned tools and solutions are just the main options. Don’t delay with your decision, check a free trial period, and then, you will see that such software is definitely worth an effort and any investment.

How Poverty Affects Divorce

Marriage is a union that binds two people together so that ideally, none of the challenges of life are faced alone. Not only does it offer a chance for lasting camaraderie and unfailing support, but it also gives couples the benefit of two stable sources of income. Thus, married couples have an easier time managing the costs of living, and a greater ability to save for their futures.

Sadly, however, these advantages are rarely enjoyed by those who might benefit from them most. According to statistics, low-income people have a lower likelihood of marrying, and a lower likelihood of staying married. Read on to discover how poverty affects divorce.

Why Low-Income People Marry Less Often and Divorce More Frequently

According to studies, people maintain similar romantic standards and expectations across all socio-economic levels. What’s different for low-income individuals are the types of challenges and problems that their marriages are more likely to face.

Those living at or just above the poverty line cite drug use and alcoholism as being among the top issues affecting their romantic relationships. Money problems rank high on this list as well, with low-income couples frequently separating due to concerns about:

  • Insufficient money
  • Differing ideas concerning money management
  • Different standards and expectations for financial health

Couples who enjoy financial health don’t have to deal with significant and constant financial stress. Moreover, when issues such as alcoholism and substance abuse arise, they have the resources for securing desirable options in treatment.

Surprisingly, even those earning moderate income have the ability to escape the extraordinary financial challenges that often break the marriages of low-income individuals. For instance, couples that earn a combined annual income of just $50k are 30 percent less likely to separate than couples who earn less.

Marriage Is Equally Valued By Both Low-Income and High-Income People

In addition to having similar romantic expectations and values, both low-income and high-income people appear to value the institution of marriage in the same way. Thus, although low-earning households are more likely to deal with divorces, this is not believed to reflect their attitudes about the sanctity of marriage or its benefits.

The increased challenges that people face when poverty is a concern make maintaining their unions far too difficult and in some instances, even unsafe. When lacking desirable and accessible options in treatment, serious problems with addiction are often the catalyst that causes a person to file for divorce.

Both Poverty and Divorce Can Be Generational

Statistics also show that poverty and divorce have an immediate and lasting impact on minor children within the home. Children of divorced parents have a much higher likelihood of living in poverty than do children living in two-parent homes. They also have higher rates of:

  • Depression
  • Drop-outs
  • Substance abuse
  • High-risk sexual behavior

These things come in addition to the fact that low-income individuals also have a lower likelihood of getting married and a higher rate of having children outside of marriage. To learn more about how divorce impacts minor children living in low-come households, you can visit this source: https://farzadlaw.com/divorce-statistics.

Disparities in the Impact of Divorce on Men and Women

Single, custodial mothers are far more likely to live in poverty than men after divorce. Compared to men, divorced women are also more likely to live without health insurance, seek support from public assistance programs, and rely on child support orders. The earning potential of divorced women is also lower.

The impact of divorce on minor children and newly single individuals seeking to rebuild their lives is often devastating. However, studies have consistently shown that the institution of marriage is similarly valued at all socio-economic levels. What’s undeniably different are the challenges that individuals and couples face when living at or near the poverty line.

EDITOR'S PICK OF THE WEEK

China economic growth

China’s Challenging Search for a New Model of Economic Growth

By Danny Leipziger China cannot continue to rely on exports to drive its growth, but what are the alternatives? China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...

WISE DECISION MAKER GUIDE

POWER INFLUENCERS

Emerging Trends

The Future of Global Trade