Sleep apnea care has improved in important ways over the past several years. Patients once had a limited set of choices, often focused on nighttime breathing machines or surgical procedures. Today, care may include sleep testing, oral appliance therapy, airway-focused dental support, laser treatment, and medical guidance. These expanded options allow providers to match treatment with symptom severity, comfort, health history, and long-term sleep goals.
A clear diagnosis should come first, since snoring alone does not confirm sleep apnea. A sleep physician may evaluate breathing pauses, oxygen changes, and sleep quality through a lab study or home test. After those results are reviewed, sleep apnea treatment in Las Vegas may involve oral appliance therapy, laser care, or medical device support, depending on the patient’s airway concerns and overall needs.
Why Treatment Choices Have Broadened
Research has shown that untreated sleep apnea can affect more than nightly rest. Repeated airway blockage may place stress on the heart, raise blood pressure, increase fatigue, and make daytime focus harder. These health concerns have encouraged providers to look beyond one standard method of care.
Better screening has also shaped treatment decisions. Home sleep tests now allow many patients to complete evaluation in a familiar setting. Digital scans, improved appliance materials, and more precise fitting methods have made dental treatments more comfortable. These advances give qualified providers better ways to address sleep-related breathing problems.
Continuous Airway Pressure Still Matters
Continuous positive airway pressure remains a widely used treatment for moderate to severe sleep apnea. The machine sends steady air through a mask, which helps keep the airway open during sleep. For many patients, this therapy reduces breathing pauses and supports healthier oxygen levels.
Comfort plays a major role in long-term success. Some patients struggle with mask pressure, dryness, sound, or the difficulty of traveling with equipment. Newer machines are smaller and quieter than older versions. Mask styles have also improved, giving patients more options for fit, seal, and airflow.
Oral Appliances Offer a Smaller Option
Oral appliances have become a helpful choice for mild to moderate obstructive sleep apnea. These custom-made devices sit inside the mouth and gently move the lower jaw forward. That position may reduce airway collapse while a person sleeps.
A trained dental provider measures the bite, reviews jaw movement, and adjusts the appliance as needed. Follow-up visits are important because small changes can affect comfort and results. Many patients prefer this option because it is quiet, convenient to carry, and simpler to use while traveling.
Laser Therapy Has Gained Attention
Some dental practices now provide laser-based airway therapy for snoring and selected sleep-related breathing concerns. This treatment uses gentle warmth on soft tissue in the throat area. The goal is to firm the tissue and reduce vibration or partial blockage.
Laser therapy is usually non-surgical and may take several sessions. It should not replace a formal medical diagnosis. A provider should review sleep study results before recommending this type of care. For the right patient, it may support easier airflow and quieter sleep.
Surgery Remains Selective
Surgery is still an option, but it is usually considered for patients with clear structural concerns. Enlarged tonsils, nasal blockage, jaw position, or excess throat tissue may contribute to airway collapse. In these cases, surgery may help reduce obstruction.
The decision requires careful evaluation. Surgical care involves recovery time and possible risks. Results may differ based on anatomy, weight, age, and sleep apnea severity. For that reason, many care plans begin with less invasive treatments before surgery becomes part of the discussion.
Combination Care Can Improve Results
Sleep apnea often responds well when several contributing factors are addressed together. Weight management, reduced alcohol use, sleep position changes, nasal breathing support, and oral appliance therapy may all help improve rest. No single habit works for every person, but small changes can make treatment more effective.
Coordinated care also matters. A sleep physician can confirm the diagnosis and monitor medical risk. A trained dental provider can manage appliance fit, comfort, and airway support. This team-based approach helps patients receive care that matches both test findings and daily routines.
Signs That Evaluation Is Needed
Loud snoring is a common warning sign, but it is not the only one. Breathing pauses, choking sounds, morning headaches, dry mouth, and daytime sleepiness may also suggest a sleep disorder. Problems with focus can appear even after a person spends enough hours in bed.
Some patients have a higher risk due to high blood pressure, excess weight, diabetes, or a thicker neck. A sleep partner may notice symptoms before the patient does. Early evaluation can help prevent years of poor rest and may reduce health strain linked to untreated breathing disruptions.
Conclusion
Sleep apnea treatment has shifted from a limited set of options to a broader, more patient-centered approach. Modern care may include airway pressure therapy, custom oral appliances, laser treatment, lifestyle support, or selective surgery. The best plan starts with proper testing and professional guidance. With more choices available, patients have a stronger chance of finding care that supports safer breathing, better rest, and improved daily energy.
Most companies still talk about AI as if the main question is technical: Is the model accurate enough to trust? A more important question is human: Does the worker know when not to trust themselves?
That is the sharper lesson from a recent Management Science peer-reviewed study, which found that AI delivers the biggest gains not simply when people are less skilled, but when they are better calibrated about their own ability. The workers who benefit most are the ones who can judge, with some honesty, where their own judgment is likely to fail.
The study tested 732 people on a simple but revealing task: deciding whether faces in photos were over age 21, sometimes with an AI confidence score and sometimes without it. Average performance improved with AI help, and lower-ability participants gained more than stronger ones. That result lines up with a growing body of evidence showing that AI can act as a leveling technology.
AI can narrow performance gaps, yet it does not do so automatically. The study shows that when people use AI with their actual, imperfect self-beliefs, inequality falls.
In a widely discussed Science paper on generative AI and professional writing, it was found that ChatGPT meaningfully increased productivity and quality, with the largest gains going to weaker initial performers. In a large field experiment published in the Quarterly Journal of Economics, it was discovered that AI assistance raised customer-support productivity by 15% on average and helped novice and low-skilled workers far more than top performers.
What makes the Management Science paper especially useful is that it separates ability from self-knowledge. Two workers can have the same baseline skill and still get very different value from the same AI system, because one is better at recognizing when the system is likely to outperform them.
That sounds obvious until you look at how most organizations deploy AI. They benchmark models, buy licenses, redesign workflows, and train people on prompts. Then they assume workers will naturally learn when to defer to the tool and when to push back. The evidence suggests that assumption is shaky.
This matters because miscalibration cuts in both directions. Overconfident workers ignore useful AI advice. Underconfident workers defer when they should trust their own judgment. In both cases, the value of augmentation leaks away. The result is that companies can install a capable system and still see mediocre gains because the real bottleneck is not the model but the user’s sense of their own competence.
That is a very different diagnosis from the usual story that AI disappoints only when the technology is immature or the workflow is clumsy. It also changes the debate about inequality.
One of the most promising ideas in the economics of AI is that these systems could spread expert performance more widely instead of simply rewarding the already advantaged. One NBER paper argues that AI could help restore middle-skill work by embedding expertise into tools that broaden access to capability.
The Management Science findings support that view, but they add an important condition. AI can narrow performance gaps, yet it does not do so automatically. The study shows that when people use AI with their actual, imperfect self-beliefs, inequality falls. With perfect calibration, it would fall much more. The gains are real, but the full equalizing effect remains trapped behind a human judgment problem.
That insight should push leaders to rethink training. For years, companies have treated worker development mainly as a matter of adding skill: more instruction, more certification, more exposure to best practices. AI makes a different target newly valuable. Workers need help estimating uncertainty, reading signals, and recognizing when they are in an edge case. That is less glamorous than frontier-model talk, but it may be far more practical.
A call center, insurer, hospital, or legal team may not be able to turn average employees into experts overnight. It may, however, be able to make them much better at knowing when the machine is likely right and when it deserves skepticism.
There is reason to think calibration can improve. A recent study in Futures & Foresight Science found that an interactive training app reduced overconfidence and improved calibration in under 30 minutes. The underlying idea is not new. Decades ago, Sarah Lichtenstein and Baruch Fischhoff showed in classic research on calibration training that feedback can make people better judges of their own probabilities.
More recent work on automated calibration training for forecasters points in the same direction. Calibration is not magic, and it is not a cure-all, but it does not look like a fixed trait either.
As companies race to embed AI into everyday work, the most underrated advantage may be brutally simple: knowing when you are probably wrong.
That creates a more useful agenda for management than the stale choice between “train people” and “deploy AI.” The better answer is to train people to work with AI. Teach them how to assess confidence, how to compare their judgment against model output, how to recognize repeated blind spots, and how to change behavior when feedback shows they are off. The goal is not blind trust in the machine — it is disciplined partnership.
AI is often described as a force multiplier, but that phrase hides the real mechanism. In practice, these systems reward workers who can tell the difference between confidence and competence. As companies race to embed AI into everyday work, the most underrated advantage may be brutally simple: knowing when you are probably wrong.
Berkshire Hathaway had a stronger second quarter, with operating earnings rising 16% to $12.98 billion as its energy, railroad and manufacturing businesses delivered solid results. Insurance was a weaker spot, with underwriting earnings and investment income both declining from a year earlier.
The bigger story, however, is how new CEO Greg Abel is beginning to use the enormous cash pile built up under Warren Buffett. Berkshire spent about $4.5 billion buying back its own shares in the quarter, a sharp increase from just $235 million in the first quarter. The company also became a net buyer of stocks, purchasing nearly $20 billion after selling equities for 14 straight quarters.
Berkshire’s cash holdings fell to $365.5 billion by the end of June, down from a record $397.4 billion three months earlier. The company also completed its acquisition of Taylor Morrison and now counts Alphabet among its five largest stock holdings. The moves suggest Abel is becoming more willing to put Berkshire’s cash to work while still following Buffett’s cautious approach.
Dubai’s property market may enter a selective repricing phase by 2027 as global risks, financing conditions, supply dynamics and development costs reshape valuations.
Dubai’s real estate market is entering a more complex phase where future valuations will depend on global conditions and local fundamentals. The key question is whether current incentives represent an early correction or a strategic response to liquidity pressures, with the outlook depending on supply, demand, financing conditions, development costs and pricing power.
Why Must Dubai Real Estate Be Viewed Globally?
Real estate values are shaped by future expectations, including replacement costs, risks, cash-flow potential and supply absorption capacity.
Dubai’s property market can no longer be analysed separately from global economic developments, as it is influenced by trade flows, supply chains, geopolitical tensions, energy costs and global interest-rate trends.
How Are Global Risks Reshaping Dubai Property Valuations?
Since 2024, the global economy has experienced a significant rise in the geopolitical risk premium—the additional return investors demand for political and military uncertainty. Its impact extends beyond financial markets through higher financing costs, shifting capital flows, commodity pressures and global shipping disruptions, which have become key drivers of real estate pricing.
Against this backdrop, Dubai has witnessed a shift in buyer behaviour, with demand increasingly favouring completed, ready-to-occupy properties while moderating for some off-plan developments based on extended payment plans.
This raises a fundamental economic question: do these incentives represent the early stages of a genuine market correction, or are they primarily financial strategies to optimise liquidity management in a more uncertain global environment?
The answer depends on two forces:
The pace of new residential supply entering the market.
The growth rate of genuine end-user demand.
Are Developer Incentives a Liquidity Strategy or a Market Warning?
Under normal conditions, developers seek to maximise profit margins, but during uncertainty, priorities may shift towards liquidity preservation and cash conversion rather than maximum selling prices. Incentives may reflect inventory conversion, financing management and reduced borrowing as capital costs rise.
Distinguishing liquidity management from genuine demand weakness requires evidence: whether discounts weaken absorption rates and whether 2027 supply aligns with Dubai’s population and economic growth or exceeds market capacity.
If supply exceeds effective demand, incentives may signal early price adjustments regardless of developers’ financial objectives. Thus, pricing strategies may simultaneously strengthen developers’ balance sheets while reflecting emerging supply pressure, with conclusions determined by market evidence rather than assumptions.
Why Are Investors Favouring Completed Properties?
Rising demand for completed properties over certain off-plan developments reflects three factors:
1. Immediate cash flow:
Completed properties provide immediate rental income and faster capital recovery.
Rising construction costs and financing uncertainty have increased sensitivity to timing risks.
However, completion alone does not determine quality; location and sustainable demand remain decisive.
Are Discounts Signalling Opportunity or Pressure?
Whether current incentives indicate declining prices requires disciplined analysis rather than premature conclusions.
Developer incentives may aim to:
Accelerate capital turnover.
Strengthen operating cash flows.
Reduce reliance on bank financing.
Bring forward sales before construction costs rise further.
However, some incentives may also reflect genuine demand weakness in specific project segments, particularly those experiencing intensive recent launches.
Therefore, discounts should be viewed as composite market indicators requiring project- and location-specific analysis rather than evidence of either permanent decline or pure liquidity management.
Why Is Asset Quality Becoming Critical?
Real estate has long been viewed as a vehicle for wealth preservation and protection against inflation and rising costs. However, this advantage does not apply equally to all property categories.
Assets with strong locations, sustainable demand and stable rental income are better positioned to preserve value than those driven by short-term speculation. Therefore, asset quality has become more important than market timing.
However, asset quality reduces risk but does not eliminate exposure to price adjustments if surrounding supply exceeds market absorption capacity.
What Will Shape Dubai Real Estate by 2027?
Current indicators suggest neither broad downturn nor unjustified acceleration, but selective repricing by 2027 shaped by asset quality, demand, costs and supply.
Price trends will depend on four key drivers:
1. Geopolitical risk premium:
Changes in geopolitical uncertainty will influence international capital flows.
2. Supply-chain risk premiums:
Procurement and logistics changes will continue affecting construction costs and project execution.
3. Cost-driven inflation:
Persistent production-cost increases will influence real estate development economics.
4. Global interest rates:
US Federal Reserve policy will remain a key determinant of Dubai’s financing costs, as interest-rate changes transmit into UAE borrowing conditions.
This factor remains independent and may move differently if global rates enter a cutting cycle while geopolitical pressures remain elevated.
Can Rising Costs Advantage Existing Properties?
If these factors persist or intensify, developing new projects could become materially more expensive than acquiring many existing assets.
Completed properties could gain an investment advantage if future supply remains aligned with absorption.
Replacement cost raises the economic cost of producing comparable assets, but it does not establish a guaranteed price floor.
If supply exceeds effective demand, prices may decline despite higher construction costs because of excess inventory. Ultimately, the relationship between construction costs and property values will continue to be governed by the balance between effective supply and effective demand.
What Should Investors Watch Now?
Investors should evaluate opportunities through liquidity, cost, risk, value and supply. Price incentives should not automatically be viewed as either opportunities or signs of weakness; their meaning depends on the project, location and the developer’s financial position.
Market Development
Possible Interpretation
Developer incentives and pricing offers
May reflect a strategy to accelerate cash conversion, improve liquidity and manage financing obligations
Discounts accompanied by weaker absorption rates
May indicate genuine demand pressure in specific projects or locations
Higher replacement costs
Increase the cost of producing comparable assets but do not necessarily establish a guaranteed market price floor
Excess supply beyond market absorption capacity
May create downward pressure on prices despite higher development costs
The same market signal may have different explanations depending on the underlying conditions.
Investors should therefore:
Assess discounts rationally by identifying whether they reflect liquidity needs, accelerated sales or demand weakness.
Prioritise asset quality and income-generating assets supported by sustainable demand.
Diversify exposure across assets, sectors and locations.
Is Dubai Entering Economic Repositioning?
Dubai’s real estate market is neither entering a crisis nor enjoying guaranteed stability. Instead, it is moving into a phase of economic repositioning shaped by global conditions, new supply and market absorption. Current incentives should be assessed alongside developers’ liquidity needs and potential demand weakness.
Ultimately, market direction will depend on liquidity, cost, risk, value and supply, while investors should focus on future replacement costs and supply alignment with genuine demand through 2027 and beyond.
Dr. Fahim Alshayea is CEO of Alshayea for Real Estate and Investment Consultancy and holds a PhD in Civil Law. He is an Economic and Real Estate Investment Consultant, a certified legal and economic expert at the Arab Legal Judicial Centre affiliated with the League of Arab Sta, and has authored more than 25 books on law and investment.
President Donald Trump has signed two new executive orders aimed at restricting birthright citizenship, reviving an effort that was recently blocked by the U.S. Supreme Court. One order expands the categories of non-citizens whose children would not automatically receive U.S. citizenship, while the other targets “birth tourism” by preventing pregnant women from entering the country solely to give birth.
The administration argues the measures are intended to stop abuse of the immigration system and prevent foreign nationals from using birthright citizenship to gain long-term benefits. However, legal experts say the new orders are likely to face fresh court challenges, particularly because the Constitution guarantees citizenship to most people born on U.S. soil under the 14th Amendment.
Critics also question the scale of the issue, noting that birth tourism accounts for only a small fraction of U.S. births each year. While the president has authority to regulate entry into the country, constitutional scholars argue he cannot deny citizenship to children born in the United States if they are protected by existing law.
A health plan pays for treatment, but an accident can affect much more than hospital expenses. Personal accident cover adds financial support when an injury causes disability, loss of income or death.
It helps protect everyday finances while the insured person focuses on recovery. For families that depend on regular earnings, this additional layer of protection can make an existing health plan more complete and practical during a difficult period.
Financial Support beyond Medical Bills
A medical insurance plan usually covers eligible treatment costs, but it may not address the wider financial impact of a serious accident. Personal accident cover can provide a fixed benefit based on the nature of the injury without disrupting planned financial goals.
Helps manage sudden household expenses
Provides support after accidental disability
Reduces pressure on personal savings
Family Financial Security
Families often depend on one or more earning members for daily expenses, education and long-term commitments. An accident affecting an earner can disturb these plans. Accident cover creates a financial cushion for loved ones at a financially sensitive time.
Offers support after accidental death
Helps families meet ongoing commitments
Protects dependants from sudden hardship
Income Protection during Recovery
An accident may prevent a person from working for weeks or longer. Personal accident insurance can offer financial support during this period, depending on the policy terms and type of disability, especially when paid leave or emergency savings are limited.
Helps replace part of lost income
Supports regular household payments
Eases financial stress during recovery
Covers Everyday Accident Risks
Accidents are not limited to road travel or high-risk work. A fall at home, an injury during travel or an unexpected incident at work can also cause serious consequences, even when the incident seems ordinary at first.
Covers a wide range of accidental events
Supports people across different lifestyles
Adds protection beyond hospital treatment
Affordable Additional Protection
Personal accident cover is often a practical add-on because it focuses on specific accident-related risks. It can strengthen overall protection without replacing the main health policy, making it useful for households seeking wider financial security.
Adds useful cover at a manageable cost
Can suit individuals and earning family members
Offers focused benefits for accident-related losses
Covers Non-Medical Expenses
Recovery may involve costs that are not directly linked to hospital treatment. Travel for follow-up care, home adjustments or temporary help can affect the household budget. These expenses may continue even after discharge.
Supports expenses outside hospital bills
Helps manage changes in daily routines
Protects savings from unexpected financial pressure
Supports Long-Term Financial Stability
A permanent disability may affect earning ability for many years. A lump-sum benefit can help the insured person and family adjust their financial plans after a life-changing accident. It may also support revised career or care needs.
Supports future household needs
Helps manage long-term financial responsibilities
Provides funds for lifestyle adjustments
Complements Employer-Provided Insurance
Workplace insurance can be useful, but it may remain active only during employment or offer limited benefits. A personal policy gives individuals greater control over their protection, particularly when employment benefits change unexpectedly.
Continues independently of the employer
Can provide broader accident-related benefits
Helps avoid gaps during job changes
Conclusion
Health insurance remains essential for medical treatment, while personal accident cover addresses the financial consequences an accident may leave behind. Together, they offer broader support for hospital bills, income interruption, disability and family needs. Before adding the cover, check the benefit structure, exclusions, disability definitions and claim conditions carefully. The right combination can protect both health-related expenses and the household finances that keep everyday life moving with greater confidence.
5G has been marketed as faster mobile internet, but its deeper impact lies in enabling systems to act faster than humans. By connecting machines, sensors and infrastructure and combining low-latency networking with edge computing and AI, 5G transforms networks from passive channels into active systems that can observe, decide and respond in real time — raising technical, ethical and political questions about authority and accountability.
5G’s value is not primarily consumer speed but systems acting before humans can react.
It connects cranes, robots, sensors, medical devices, power grids and more — enabling physical actions, not just screens.
Edge computing + URLLC/mMTC move decisions close to events; AI at the edge amplifies predictive control.
The key question becomes who has authority to act and who bears responsibility when actions are automated.
From service to architecture
Mobile generations are first sold as consumer services and only later seen as architectures. 3G brought mobile internet; 4G enabled apps and streaming. 5G’s marketing focused on speed, but throughput is the storefront — the real change is architectural: who responds first to events.
Last-mile and active things
The transformative shift is in the last mile: making previously passive things active network participants. Beyond phones, networks now link cranes, robot arms, sensors, transport hubs, cameras, machine tools and medical devices. Signals can directly trigger actuators, change modes or halt processes without passing through a human operator.
When systems act first
In operations like remote port terminals, private 5G and local compute create tight timing loops where control actions occur in tens of milliseconds. A gust-corrected container can be stabilized by local control before an operator perceives it. Humans remain in control, but are no longer always the fastest actor in the loop.
eMBB, URLLC, mMTC — different worldviews
eMBB: enhanced mobile broadband for human traffic.
URLLC: ultra-reliable low-latency communications for time-critical control.
mMTC: massive machine-type communications for dense IoT connectivity. The public-visible phase emphasized eMBB; the deeper transformation requires URLLC, mMTC, private standalone cores and edge infrastructure. Coverage often arrived before the architecture.
Edge computing and AI
Edge compute places processing near data sources, shortening the observation-to-intervention window. For consumer media latency is negligible; for industrial control and safety it is decisive. AI running at the edge enables pattern recognition and predictive actions, but only if network design supports proximity and low latency.
Authority, accountability, and politics
Low-latency automated systems shrink the human “pause” for doubt and cancellation. Responsibility for errors becomes distributed across sensors, models, local nodes, networks and actuators. Therefore low latency is also a political and ethical issue: who can act, under what rules, and who is accountable?
Legacy of 5G
5G’s principal legacy will be networks transitioning from channels into clocks that set the tempo for sensing, decision-making and response in the physical world. This shift makes the system “less human” in the sense that human-paced rules no longer fit time-critical automated systems. Less human is not inherently worse, but it requires rethinking regulations, governance and safety frameworks.
Britain’s polycrisis—fiscal fragility, decades of austerity policy, a cost-of-living crisis, stagnating living standards, and political instability—stems not from exogenous shocks but from a failed growth model of financialisation, regressive taxation, and chronic underinvestment. Dr Kalim Siddiqui analyses macroeconomic indicators, fiscal constraints imposed by bond markets, and a governance crisis of ministerial churn and impossible trilemma. Escape requires fundamental renegotiation of the state’s productive investment role, progressive taxation, not mere technical adjustment.
I. Introduction
The British growth model is in terminal crisis. This article argues that the United Kingdom’s (UK) contemporary economic malaise cannot be understood as a mere cyclical downturn, but rather as the product of deep structural contradictions between a finance-dependent accumulation regime, severe fiscal constraints inherited from a decade of austerity, and a paralysing crisis of governance that has rendered long-term strategic intervention impossible.
Britain is currently navigating a polycrisis that extends far beyond the parameters of a standard economic recession, encompassing a deep-seated structural malaise that is at once fiscal, social, and political (The Guardian, 2026). This crisis is not merely the product of exogenous shocks, but rather the culmination of a protracted growth model built upon financialisation and regressive taxation—a model now laid bare by geopolitical volatility, persistently anaemic productivity, and a profound erosion of state capacity.
Against this backdrop, there is a compelling case for increasing taxes on the super-rich and large corporations, entities that have disproportionately benefited from four decades of neoliberalism and globalisation. The current landscape is defined by a precarious triad of vulnerabilities: acute sensitivity in sovereign bond markets, two decades of stagnating median living standards, and a descent into party-political instability that has rendered long-term economic planning virtually untenable (Tooze, 2022).
This is not a conventional business cycle downturn, but what some scholars have termed a ‘polycrisis’, wherein multiple interdependent crises—economic, fiscal, social, and political—reinforce one another in a self-perpetuating downward spiral (Tooze, 2022).
Sustained growth is essential for the economy to expand, for employment to rise, and, hopefully, for household incomes to improve.
Contemporary Britain exhibits all the hallmarks of this syndrome. Sovereign bond yields remain sensitive to the faintest whisper of fiscal indiscipline, a legacy of the 2022 ‘mini-budget’ episode that brutally exposed the market’s tolerance limits. Real wages have stagnated for nearly two decades, eroding the living standards of majority of the population. Public infrastructure—from schools to hospitals to transport networks—has deteriorated to levels that provoke international embarrassment. Meanwhile, Britain has witnessed unprecedented executive fragility, with five prime ministers in eight years and a cabinet turnover rate that renders long-term policy planning virtually impossible (The Guardian, 2026).
Britain still projects an image of wealth, but beneath the surface the economy has largely stagnated for almost two decades. Rising house prices have created the illusion of growing prosperity, yet for most homeowners the gains are largely paper wealth: selling simply means buying into an equally inflated market. Today, the average home in England costs 7.7 times the median annual salary, rising to 10.5 times in London and as much as 25 times in some areas. By comparison, in the 1980s a home was generally considered affordable at around three to four times average earnings.
This article advances a central issue: Britain’s contemporary crisis is fundamentally a crisis of its growth model. Drawing on the comparative political economy literature (Blyth, 2013), the British growth is accumulation strategies that generate economic expansion within a given national context, but hardly reaches the three-quarter of the population. The growth is siphoned off by the small elites. The British growth model has been historically reliant on financial services, asset-price inflation, and regressive taxation—a configuration that proved increasingly unstable following the 2008 financial crisis and has now reached its terminal limits (Siddiqui, 2024a).
Successive governments have increasingly relied toward the financial sector, fostering a heavily indebted economy built on speculative wealth rather than productive enterprise. This model has exacerbated asset inequality and entrenched privatised monopolies—particularly in utilities such as water—that extract rent rather than stimulate innovation or long-term investment. I contend that this trajectory reflects a deep-seated adherence to neoliberal orthodoxy, which has simultaneously opposed deficit-financed public investment and resisted progressive taxation on large corporations and high-net-worth individuals. The result has been a progressive paralysis of the state’s capacity to fund critical infrastructure or effectively alleviate the cost-of-living crisis.
Beyond these macroeconomic failings, Britain confronts a profound regional imbalance, with wealth and opportunity overwhelmingly concentrated in London and the South East, while peripheral regions—especially the North—have suffered extensive deindustrialisation and economic marginalisation. These systemic ailments, further compounded by an ageing population, are not cyclical fluctuations but symptomatic of a deeper, possibly terminal, decline in the British growth model. At its core, this model—defined by privatisation, austerity, financialisation, and globalisation—has reached its limits, and the current crisis demands a fundamental reorientation of economic strategy (Siddiqui, 2019).
The study proceeds with the examining the macroeconomic data, with particular attention to the energy-inflation nexus and its consequences for monetary policy and labour markets. And then discusses focuses to the fiscal dimension, analysing how a decade of austerity has eroded the state’s productive capacity while simultaneously rendering it hostage to bond market sentiment. And finally, analysis the governance crisis, exploring how political fragmentation and institutional decay have undermined the state’s capacity to formulate and implement strategic economic policy.
II. Falling Growth Rates
Sustained growth is essential for the economy to expand, for employment to rise, and, hopefully, for household incomes to improve. In the UK, the Office for National Statistics (ONS) releases monthly GDP figures, but these are often volatile. As a result, economists consider the quarterly data—which covers three-month periods—to be a more reliable indicator of the economy’s underlying health.
According to the latest ONS release, the UK economy contracted by 0.1% in April, as businesses began to feel the ripple effects of the conflict in Iran.
More strikingly, the broader trajectory reveals a clear downward trend. After growing by 1.3% across the whole of 2025—up from 1.0% in 2024—the UK economy expanded by 0.6% in the first quarter of the year. However, that pace is already showing signs of fading, with growth expected to remain sluggish in the months ahead. This slowdown is not new. The final quarter of 2023 already recorded negative growth, and the momentum has failed to recover sustainably since then.
By March 2026, UK GDP growth for the first quarter was estimated at just over 0.5%—the weakest March reading in two years (see Figure 1a). Compared to the 0.6% seen in the previous quarter, this marks a noticeable deceleration, reinforcing concerns that the economy is losing steam. GDP per head tells a starker story. Between 2022 and 2026, the per head decline is deeper — none more so than in 2022–2023, when the Russian-Ukraine war took hold (Figure 1b).
According to the Bank of England (BoE, 2025) growth forecasts, UK GDP growth is expected to remain almost stagnant, continuing the weak performance observed since 2022. Although the economy recovered in 2021 following the sharp contraction caused by the COVID-19 pandemic (Figure 1c), growth has remained subdued. Moreover, there is little indication that growth rates will return to the stronger levels experienced prior to 2008 financial crisis.
Figure 1d illustrates that the UK GDP per capita has flatlined since the 2008–2009 financial crisis. Post-crisis growth has consistently underperformed pre-crisis trends, and even excluding the COVID-19 collapse, the past sixteen years amount to little more than economic stagnation—with no credible recovery strategy in sight. Real GDP per capita in 2024 remains only marginally above its 2007 peak, confirming what many economists now term a “lost decade and a half” of productivity and income growth. Crucially, this prolonged economic malaise appears to have no clear exit strategy, as monetary policy has exhausted much of its conventional firepower, fiscal space remains constrained, and long-standing supply-side weaknesses—particularly in business investment, innovation, and regional imbalances—persist unaddressed. This prolonged malaise has triggered chronic political volatility and a deep-seated crisis of confidence among consumers and investors alike. Yet Britain is not an outlier; it is a case study in the wider crisis of advanced capitalism. Stagnant wages, a widening productivity–pay gap, soaring inequality, and an embattled welfare state have eroded social cohesion—and right-wing populists have ruthlessly exploited this discontent to reshape the political order, further blocking any path toward sustainable renewal.
There was broad-based growth in services and construction. Professional, scientific, and technical activities, along with information and communication, performed well — signalling rising investment in AI and the tech sector.
However, some concerns are emerging, not least from rising fuel and chemical costs, which have weighed on other sectors. Machinery and equipment contracted, and administrative and support services also declined.
Comparing GDP growth across advanced economies against pre-pandemic levels (2020 = baseline) reveals that the UK has significantly underperformed relative to other major developed nations, as shown in Figure 2 (Siddiqui, 2025a).
Moreover, financial assets and the real economy—comprising primarily industry and construction—are fundamentally distinct. This distinction also helps explain why trust in the capitalist system occasionally breaks down. The relationship between the real economy and the financial sphere is essentially dialectical in nature. While financial growth has undoubtedly supported the development of the real economy in various ways, it can also prove highly disruptive. Fictitious financial assets, in particular, can evaporate in a very short period. The contradiction between the fictitious and the real intensifies as the ratio of financial value to real economic value increases.
In reality, the expansion of the supply of tangible goods depends on the development of productive forces, the availability of means of production, the size and skill of the labour force, and other material conditions. The supply of fictitious assets, however, is not constrained by such limitations. Speculation itself is not a new phenomenon. What is new is the growing power of large capital, which can now influence price movements, thereby create asset price bubbles and enabling profits to be extracted from them (Tooze, 2022).
Figure 2: GDP % Change of Advanced Capitalist Countries Compared to Pre-Pandemic Level with 2020.
It’s the inevitable result of 40 years of neoliberal economic policy that has trebled UK private debt, collapsed the velocity of money to just 1.2 times per year, and redistributed wealth from the working class to asset owners. Britain’s economy hasn’t just slowed but it’s been hollowed out, and no prime minister was able to fix it without a fundamental shift from elite driven economic policy.
The UK government focus on reducing public debt and deficits, but seems to be counterproductive. He argues that attempts to simultaneously deleverage the public and private sectors choke the money supply and push the economy down. Private debt (like mortgages) is the real threat to financial stability. Figure 3 presents UK’s private debt trends from 1980 to 2020. The data reveals a pronounced and sustained increase in both corporate borrowing and household indebtedness over the forty-year period.
Figure 3: UK’s Private Debts, 1980-2020 (% of GDP).
The British economy’s vulnerability to external shocks has been brutally exposed by the geopolitical reverberations of the US/Israeli-Iranian conflict. Disruptions to global oil and natural gas supply chains have fed directly into domestic inflation, with the Consumer Prices Index (CPI) persisting at 2.8% — significantly above the Bank of England’s 2% target (BoE, 2025). This is not a transitory phenomenon; the structural realignment of global energy markets following the Russian invasion of Ukraine has permanently altered the UK’s terms of trade, rendering it a net importer of inflation (IMF, 2024).
The tightening monetary stance has coincided with a marked deterioration in real economic activity. Early-year growth momentum, buoyed by a post-pandemic rebound, has now dissipated, signalling contractionary trajectories in both manufacturing and services — the twin engines of the British economy (BoE, 2025). Manufacturing, in particular, has been afflicted by declining export competitiveness, a weak investment climate, and persistent supply-chain disruptions.
The surge in youth unemployment, which has reached its highest level since the aftermath of the 2008 global financial crisis, is not merely a cyclical phenomenon. Rather, it reflects a structural mismatch between the skills demanded by a low-investment, service-oriented economy and those possessed by younger cohorts entering the labour market (OECD, 2024). The long-term scarring effects — including lower lifetime earnings, reduced productivity, and increased reliance on welfare — are likely to exacerbate the fiscal pressures discussed below.
III. Bond Market Discipline and Fiscal Fragility
The UK’s infrastructure deficit cannot be easily addressed. Fiscal space is severely constrained by sovereign bond markets. The yield on 10-year gilts remains at multi-decade highs — driven not only by global monetary conditions but also by a UK-specific risk premium. This premium stems directly from the 2022 ‘mini-budget’ debacle, which shattered market confidence, sent sterling plunging, and triggered a classic ‘bond vigilante’ revolt (Turner, 2023). Figure 4 shows UK bond yields over the past thirty years.
In this climate, any perceived fiscal indiscipline — whether excessive borrowing or unfunded tax cuts — risks a sudden stop in capital flows and a spike in borrowing costs (Siddiqui, 2017). The British state is effectively held hostage by market sentiment, vulnerable to a self-fulfilling debt crisis (Turner, 2023).
This forces governments to prioritise deficit reduction over productive investment, regardless of economic conditions. The result is a fiscal straitjacket that precludes the expansionary policies needed to escape the UK’s low-growth equilibrium.
IV. Austerity’s Legacy and the Deterioration of Public Infrastructure
Perhaps the most visible manifestation of Britain’s structural decay is the catastrophic state of its public infrastructure. Over a decade of fiscal consolidation — pursued under the rubric of austerity — has systematically diverted capital budgets towards recurrent day-to-day spending. The consequences are now starkly visible: school buildings at risk of collapse, NHS waiting lists at record highs, and local authorities declaring effective bankruptcy.
This infrastructure deficit is not merely a matter of public service quality; it has direct implications for the economy’s supply-side capacity. Poor transport links, inadequate digital infrastructure, and a degraded educational estate all depress private sector productivity and deter inward investment. The UK now ranks significantly below its OECD peers on measures of public capital stock per capital. (OECD, 2024; IMF, 2024).
These supply-side constraints are largely self-inflicted, rooted in the political economy of austerity (Siddiqui, 2024a). Successive governments have redirected capital expenditure towards meeting immediate spending pressures, undermining the country’s productive capacity and locking the UK into a low-growth trajectory (Siddiqui, 2013).
From a political economy perspective, these trends reveal the interplay between structural economic weaknesses and institutional constraints. Yet growth alone cannot raise living standards unless it supports real wage increases, enables fairer taxation of wealth, and expands fiscal space without overburdening workers. Britain’s persistent productivity slowdown has stifled GDP growth, undermining both private-sector dynamism and public-sector capacity. The confluence of weak growth, fiscal strain, and political fragmentation casts doubt on the sustainability of the UK’s economic model and the state’s ability to resolve deep-rooted challenges.
Rather than a series of isolated shocks, these developments represent a systemic crisis of Britain’s political economy. The mutually reinforcing dynamics of low productivity, constrained public finances, geopolitical volatility, financial market pressures, and eroding political trust have created a vicious cycle of stagnation and institutional fragility. Recognising this interdependence is crucial both for diagnosing the UK’s current malaise and for assessing the strategic options open to future governments.
V. The Governance Crisis: Political Instability and Institutional Decay
Britain’s governance crisis is acute. Five PMs in eight years, 70% cabinet turnover, and a collapsing two-party system have paralysed long-term strategy. Governments are trapped in permanent electioneering, choosing tax cuts over investment and avoiding reforms like ending austerity or fixing vocational education.
This executive fragility is both cause and consequence of a deeper political realignment. The collapse of the traditional two-party duopoly — evidenced by poor local election results and the rise of third parties — has intensified intra-party factionalism and rendered parliamentary majorities increasingly precarious. Governments now govern in a state of permanent electioneering, prioritising short-term political survival over the painful structural reforms that the economy demands (Siddiqui, 2024a).
The crisis has now claimed another victim. Keir Starmer has resigned as Prime Minister, becoming the sixth person to leave office in a turbulent decade of UK politics. Elected in 2024 with a landslide Labour victory, Starmer had pledged to bring stability, grow the economy, and end years of Conservative Party chaos. Barely two years later, he was forced to step down after his popularity plummeted and his government struggled to deliver on its promise to “rebuild Britain.” This rapid turnover is unprecedented in British political history. By contrast, the preceding four decades saw just six prime ministers — the same number as the past ten years alone (see Figure 5).
Figure 5: Succession of British Prime Ministers since 2010.
Neoliberalism seeks to transfer control of economic factors from the public to the private sector. (Siddiqui, 2025b). For decades, financial assets have grown faster than the real economy — and the gap has widened significantly in recent years. In the United States (US), for example, the ratio of stock market capitalisation to GDP rose from 52% in 1990 to 151% in 2025 (World Bank, 2026). This growing divergence between finance and the real economy is a major driver of wealth and income inequality across most countries (Mattei, 2022).
The privatisation and commodification of key spheres — particularly education — has also undermined the pursuit of academic life as a critical activity. Yet neoliberalism is rarely what it appears to be (Figure 6). It is not simply about competition or free markets; rather, it entrenches the power of financial giants, military-industrial players, and tech monopolies, while leaving ordinary citizens exposed to market volatility. Its legacy is a dead end: skyrocketing inequality and wealth concentration rivalling the 1950s.
Figure 6: The Core Components of Neoliberal Economic Policy
Table 1 presents a comparison of per capita GDP growth across advanced capitalist economies, contrasting the pre-neoliberal era with the neoliberal period. In all cases, growth performance in the neoliberal period is weaker, with the differential consistently negative.
Table 1: Per-Capita Economic Growth Rates in the Advanced Capitalist Economies.
Country
Neoliberal Period (1990-2020)
Pre-Neoliberal Period (1950-1980)
Differences
US
1.8
2.67
-0.88
UK
1.8
2.43
-0.62
Australia
1.65
2.45
-0.81
Canada
1.38
3.17
-1.79
France
1.49
4.43
-2.94
Germany
1.74
3.34
-1.6
Italy
1.3
4.44
-3.15
Japan
1.76
6.29
-4.52
Netherlands
1.59
2.69
-2.09
South Korea
5-22
6.73
-1.51
Spain
1.54
5.65
-4.11
Sweden
1.47
3.29
-1.82
Switzerland
1.03
2.75
-1.72
VII. Rising Inequality in the UK
Since 1960, UK disposable household income inequality has evolved through four distinct phases. The figure presents two measures: the 90:10 ratio — comparing the 90th and 10th percentiles — and the income share of the top 1%. A higher 90:10 ratio signals greater inequality between top and bottom earners.
However, experiences varied across groups. Pensioner poverty plummeted from 41% in 1989 to 18% in 2019. Child poverty saw a modest decline from the early 2000s, partially reversing after 2010. Meanwhile, relative poverty among working-age adults without children actually increased from the 1990s until the financial crisis.
UK inequality since 1961 (Figure 7a): flat in the 1960s–70s, surged in the 1980s, stabilised 1990–2008 (top 1% kept pulling away), little change since. The 90:10 ratio and top 1% share both rose sharply in the 1980s. Figure 7b shows children are the worst affected by rising poverty.
Relative poverty (below 60% of median income) followed a similar path. Pensioner poverty fell from 41% to 18% (1989–2019). Child poverty declined modestly then partially reversed after 2010. Working-age adults without children saw poverty rise from the 1990s to 2008.
Figure 7a: Inequality among UK Households, 1960–2020.
These are the real resources of a country: the buildings, the land, the hospitals, the schools. This is real wealth. And yet, year after year, an increasing share of this wealth is being concentrated in the hands of a tiny group of people whom we currently lack the capacity to tax—even if we wished to do so.
Governments once owned substantial wealth and industries. But over time, government net worth has fallen from over 100 per cent of GDP to negative 100 per cent of GDP. The wealth that used to be owned by the state, by workers, and by the middle class has not disappeared—it has simply been transferred into the hands of the rich. At current rates of taxation, the UK is moving rapidly towards extreme wealth inequality and widespread homelessness.
The young will be among the hardest hit. Consider this: if house prices double over the next five years, someone who is now 18 years old will be 23 and will recognise that they have zero chance of getting onto the housing ladder—of ever reaching that level playing field. Such people, despairing of economic opportunity, become easy prey for narratives that blame immigrants and foreigners, and they are increasingly drawn to the far right. This seems to be the present trajectory.
Extreme right-wing movements offer seemingly simple economic solutions: kick out the foreigners. The blame for economic crises is shifted onto immigrants and outsiders, who are not, in fact, the ones making decisions or governing the country. The laws and policies are made by those in power; yet when those policies fail, the failures are conveniently projected onto foreigners and immigrants.
The UK is not alone among developed countries in experiencing rising income inequality over the past six decades. However, inequality in the UK has grown more sharply than in most OECD countries (Siddiqui, 2025c). Today, UK income inequality is high by international standards—as shown in Figure 8, which presents the Gini coefficient for OECD nations. Beneath this summary measure, a more telling picture emerges: it is largely the degree of inequality between high-income and middle-income households that sets the UK apart from many of its peers (OECD, 2024).
Figure 8: Gini-Coefficient of Income Inequality Across OECD Countries, 2020.
VIII. Taxing the Super-Rich: A Minimum Tax Proposal
There is an urgent need to impose progressive taxation on the super-rich, and I advocate here for the introduction of a wealth tax in Britain. If any meaningful change is to be achieved and the current status quo reversed, it is imperative to tax the rich more heavily and to tax wealth itself. The wealthy are not only economically powerful; their concentration of resources also affords them disproportionate influence over politics and business. If the new Labour government—led by Andy Burnham—genuinely wishes to deliver real change, it must adopt progressive taxation as a central tool to reverse the rising tide of income and wealth inequality (Financial Times, 2026).
A wealth tax operates on a straightforward principle: it is levied on the total value of an individual’s assets, rather than on their income. For example, a person worth £1 million would pay 2% annually, amounting to £20,000 per year. Someone worth £20 million would pay 2% on the portion above £10 million, equating to £200,000 annually. Crucially, such a tax would only be paid by the very wealthy.
The underlying rationale is to halt the accelerating concentration of wealth in fewer and fewer hands. As things stand, workers grow poorer, the middle class is squeezed, public finances deteriorate, and vast sums of wealth accumulate in the bank accounts of the richest individuals—who currently pay little or no tax on it. It is worth emphasising that these individuals presently enjoy extremely low effective tax rates, precisely because their wealth does not derive primarily from income. We have constructed a tax system that is highly effective at taxing working people—at rates of 50% or even 60%—but it scarcely touches the super-rich at all.
What explains the aggressive rise in the living standards of the super-rich over recent decades? Over the past five years, the average British family has struggled to pay energy bills, feed their children, and cope with a relentless cost-of-living crisis. On the streets of the UK, conditions are palpably worse than they were five years ago—and worse than ten years ago, worse than twenty, and so on, in a downward trajectory that shows no sign of abating.
Consider this: six years ago, the world’s richest man was worth just over £100 billion. Last month, the world’s richest man accumulated a trillion dollars in the span of just six years. What we are witnessing is billionaires growing their wealth at annual rates of 30, 40, or even 50 per cent. This staggering concentration of wealth makes it abundantly clear that urgent policy change is needed to address the inequality at the very top—to reverse the trend that has placed nearly all the gains of economic growth into the hands of the top 1 per cent.
The injustice is compounded by the structure of our tax system. Workers pay higher rates on their income than wealthy individuals pay on their capital gains. Yet the problem is even more insidious: capital gains tax is only triggered upon sale. A wealthy person, for example, might generate £50 million a year in passive income—roughly £1 million per week—and still pay a far lower effective tax rate than an ordinary employee.
A wealthy person, in essence, is someone who owns capital. They own your mortgage. They own government debt. They own the houses, the buildings, the skyscrapers. If they are not taxed fairly and their wealth continues to accumulate unchecked, the rest of society will grow progressively poorer. The welfare state will be dismantled by attrition. The NHS and the education system will be systematically reduced. The long-term consequence will be rapid political and economic destabilisation—not just of Britain, but of any country that allows this trajectory to continue.
The notion that billionaires should pay less than ordinary workers is indefensible. The proposal for a minimum tax on the super-rich has achieved broad consensus—by design. It originated from the study conducted for the G20 during Brazil’s presidency in 2024, with the aim of placing new ideas for international cooperation on the agenda.
In 2021, 130 countries agreed to establish a minimum corporate tax rate of 15%—a flawed but significant step forward, marking the first time nations had reached such a common agreement. The underlying logic is powerful: it curbs tax avoidance by ensuring that a multinational company’s tax bill cannot fall below 15% of its profits. The super-rich have benefited enormously from globalisation, yet many pay little or no tax. A minimum tax on wealth is the logical next step.
Political will, however, remains fragile. Andy Burnham retreated from this issue as soon as the right-wing of the Labour Party attacked him. A man who had previously advocated for Britain’s return to such proposals immediately backed down when put on the spot in a constituency with a strong Reform bias. This retreat has effectively handed an opportunity to boost support for Nigel Farage and his right-wing politics (The Financial Time, 2026).
The Conservative Party’s proposed economic strategy centres on three pillars: increased military expenditure, corporate tax cuts, and substantial subsidies for large corporations and high-net-worth individuals—all justified under the guise of stimulating investment and fostering growth. This approach is complemented by continued welfare reductions and the perpetuation of austerity measures. However, increasing defence spending effectively revives a form of military Keynesianism (Siddiqui, 2025d), which not only escalates geopolitical tensions but also prioritizes armament production over social welfare. These measures offer, at best, short-term economic relief. In reality, such a policy framework would accelerate the redistribution of capital away from the working class and toward the already affluent, exacerbating economic inequality without ensuring sustainable prosperity (Siddiqui, 2024a).
Capital, in its search for profits, tends to cluster in particular states and regions (Siddiqui, 2026). The US, EU and China dominate in terms of percentage of world’s GDP and also these regions have geographic concentration of markets (Table 2). China stands out as the major breakout centre of capital accumulation. Together, the US, China, and the EU produce nearly half of global GDP and account for just over half of total global investment. A few other populous economies—India, Indonesia, Brazil, Russia, and Mexico—make the top ten, with Turkey in the top twenty. These represent a substantial mass of output and investment, though none competes with the big three on a per-capita basis. Other relatively large advanced economies—Canada, Britain, Japan, and Saudi Arabia (historically an oil giant, but now diversified into other industries)—also feature prominently.
Table 2: Geographic Concentration of Market Economies, 2021.
Country/region
% of world stock of public and
private capital, 2021
% of world GDP, 2021
US
14.8%
16.4%
European Union
15.9%
15.9%
China
20.2%
15.5%
India
6.0%
7.6%
Japan
5.8%
4.2%
Russia
3.1%
3.3%
Indonesia
2.7%
2.5%
UK
2.1%
2.5%
Brazil
2.8%
2.4%
Turkey
2.1%
1.9%
Canada
1.5%
1.5%
Saudi Arabia
1.3%
1.3%
Source: Calculated from the IMF Investment and Capital Stock Dataset (constant US dollar measures)
IX. Critique of Neoliberalism
Over recent decades, neoliberalism has lost much of its political legitimacy. In the UK, policies such as privatisation, fiscal restraint, high interest rates, capital account liberalisation, and the curtailment of trade union power have failed to deliver sustained long-term growth or economic stability.
Yet neoliberalism remains not only the dominant economic policy framework but also the prevailing modality of social and economic reproduction in most countries. First adopted by President Reagan in the US and Prime Minister Margaret Thatcher in the UK four decades ago, it continues to be deeply entrenched in institutional and political life.
In neoclassical theory, capitalist economies are assumed to gravitate spontaneously towards full employment and efficient resource allocation—provided that market imperfections, such as misguided government interventions, trade union activity, or industrial distortions, do not obstruct the adjustment process. These factors are treated as deviations from an otherwise self-correcting system.
John Maynard Keynes fundamentally challenged this view. For Keynes, aggregate output and employment are primarily constrained by aggregate demand. When demand is insufficient—whether owing to pessimistic profit expectations or inadequate state intervention—firms respond by cutting production and laying off workers, thereby triggering recessions from which the economy may not spontaneously recover. This marked a sharp theoretical break with neoclassical orthodoxy.
Nevertheless, Keynesians have struggled to explain why their preferred policies, despite their effectiveness during the postwar boom from the 1950s to the 1970s, eventually interacted with accumulation processes in ways that rendered Keynesianism obsolete and cleared the path for the resurgence of neoliberalism.
Since the early 2000s, this period can be read as a transition from a first-generation form of privatised Keynesianism (roughly 1987–2007) to a second-generation variant emerging from 2020 onward, with a protracted “zombie” interlude in between. Contrary to its own self-presentation, the neoliberalism that took shape in the 1980s was not a wholly anti-Keynesian system. During the early post-war decades, effective demand in the core capitalist economies was sustained not by public redistribution or stable wage growth, but rather by the inflation of financial and property asset prices, household debt-fuelled consumption, and central banks’ implicit guarantees for speculative activities.
While Keynesian fiscal stimulus proved effective in the short run—and governments’ pandemic-era responses indeed vindicated Keynesianism as a tool against economic collapse—stimulus alone leaves the question of economic composition untouched. This is precisely what initiatives such as the Next Generation EU plan and the Inflation Reduction Act largely address. Yet where the demand for full employment is not accompanied by a demand to control the composition of production, Kalecki’s 1943 warning remains fully applicable: capital can accept full employment for as long as it suits its interests, but will resist it as soon as it threatens workplace discipline or capital’s control over the direction of investment.
Ha-Joon Chang (2013), a prominent critique of neoliberalism, argues that the UK’s economic crises stem from a long-term erosion of productive capacity, an over-reliance on financial services, and self-defeating austerity programmes. He contends that these policies have exacerbated inequality and trapped the country in a cycle of low growth and social decay. Austerity, in his view, serves primarily to undermine the welfare state rather than to rectify the fiscal deficit. Chang also points out that, despite massive currency devaluations since 2008, the UK has continued to run persistent trade deficits—a clear indication that the country has lost the capacity to engage in high-productivity activities and to respond effectively to global export incentives.
Ha-Joon Chang (2013) attributes the UK’s economic crisis not to short-term anomalies (Siddiqui, 2024a), but to a decades-long adherence to neoliberal policies, financial deregulation, and a severe erosion of the country’s productive capacity. He argues that the UK’s sustained reliance on the financial sector, combined with austerity measures, has systematically undermined its ability to generate genuine wealth (Blyth, 2013).
Others, such as Adam Tooze (2022), diagnose the UK economy as fundamentally “broken,” suffering from the most severe growth and productivity slowdown of any advanced nation since the 2008 financial crisis. Tooze attributes this stagnation to chronic underinvestment, the structural effects of Brexit, and overly conservative policymaking that yields to bond market panic rather than pursuing investment-led growth. His key arguments centre on two interconnected issues: first, the productivity crisis—the core problem in the UK is not decoupled wage growth but the fact that productivity growth has completely stalled, with one of the lowest investment rates as a share of GDP among rich economies; and second, the cost of Brexit, which Tooze estimates has structurally reduced national income over the long term.
Brexit remains one of the UK’s most divisive decisions. Before the 2016 Brexit referendum, business investment was growing at around 6% a year—one of the strongest rates in the G7. After the vote, investment growth stalled as firms delayed or cancelled projects amid uncertainty over access to EU markets. The most comprehensive 2025 study concluded that UK GDP is now around 6–8% lower than it would have been without Brexit, highlighting the gap between the promises made and the economic outcome (The Guardian, 2026; Siddiqui, 2024a).
Underpinning these diagnoses is a broader critique of neoclassical economic models, which Tooze believes mislead governments and systematically fail to prevent financial crises. Traditional models treat banks merely as intermediaries—consistent with the loanable funds theory—while ignoring the reality that banks create money “out of thin air” when they issue loans. This conceptual blind spot is particularly damaging in the context of high private debt. In the UK, the current private debt-to-GDP ratio stands at approximately 450 per cent, of which 250 per cent is attributable to financial sector debt alone (Siddiqui, 2023).
Under austerity, cutting state spending during economic downturns depresses growth, degrades public services, and ultimately worsens the very conditions it purports to remedy—driving down living standards in the process. For Chang, the post-1970s neoliberal model of free markets, deregulation, and state retrenchment has been a clear failure. Far from delivering widespread prosperity, this approach has produced higher inequality, stagnant wages, and an economy increasingly vulnerable to financial crises and instability. The over-reliance on finance, in particular, has rendered the economy fragile and susceptible to speculative bubbles and systemic shocks (Saad-Filho, 2017).
To reverse this trajectory, Chang (2013) advocates for a return to a more mixed economy. He strongly supports the implementation of state-led industrial policy, increased public investment in infrastructure and technology, and rigorous regulation of the financial sector—so that it serves the real economy rather than functioning as a vehicle for wealth extraction.
A Marxist examination of the material basis of neoliberalism illuminates several limitations of Keynesianism, two of which are particularly significant (Siddiqui, 2023). First, Keynesians often contend that macroeconomic instability and recurrent financial and balance of payments crises demonstrate neoliberalism’s fundamental flaws. This is correct in the same abstract sense that economic crises reveal capitalism as a flawed mode of production. Yet just as crises offer opportunities to restore balance in capitalist accumulation, they also play a constructive—even constitutive—role under neoliberalism (Saad-Filho, 2017).
A parallel dynamic can be observed with austerity. Following the initial post-First World War boom, restrictive economic policies were implemented in Britain from 1920–21. Austerity was framed as a recurrent ruling-class strategy to suppress working-class militancy and restore both the imperial image and the pound’s status as a global currency (Blyth, 2013).
What were the effects of austerity in Britain? The reductions in social spending, as Mattei (2022) highlights, were undoubtedly severe. While the initial spending cuts of 1919–22 focused wholly on military expenditure, the Geddes cuts differed in that they fell heavily on civil spending as well—striking hard at an expansionary programme of post-war reconstruction. That programme had been championed by a coalition of Liberals, Conservatives, and a few Labour Party members campaigning together in the so-called “coupon” election of 1918 (Mattei, 2022).
The post-war macroeconomic strategy did achieve certain social-democratic aims: the nationalisation of basic industries and a major extension of welfare state entitlements. However, the physical infrastructure of that welfare—new hospitals and schools—showed little expansion. In effect, only an “austerity welfare state” was constructed (Blyth, 2013).
Keynesianism was, above all, “an economic theory of the national economy.” In the middle decades of the twentieth century, with trade and capital controls, extensive state control over monetary policy, and a large government budget, such management was both plausible and effective. As one observer put it, “The economic introversion of the 1930s and 1940s created the material basis for such a policy in Britain.”
X. Conclusion: The Limits of the British Growth Model
Ultimately, the British crisis exposes the terminal limits of a growth model predicated on asset-price inflation and service-sector expansion, rather than on high-value-added manufacturing and R&D investment. As the government struggles to reconcile the demands of a restive electorate, the UK finds itself trapped in a low-growth, high-debt equilibrium. Breaking this cycle requires not merely technical fiscal adjustments, but a fundamental renegotiation of the social contract and a wholesale reimagining of the state’s role in productive investment.
Breaking this cycle requires not merely technical fiscal adjustments, but a fundamental renegotiation of the social contract and a wholesale reimagining of the state’s role in productive investment.
The current situation is no conventional business-cycle downturn. Rather, it reflects the interaction of structural economic weaknesses, geopolitical shocks, fiscal constraints, and declining state capacity. Weak productivity growth, persistent regional inequalities, rising income and wealth inequalities, deteriorating public infrastructure, and rising political instability have exposed the fragility of Britain’s post-financial crisis growth model. These developments point to a broader crisis of political economy in which economic performance, fiscal governance, and political legitimacy have become increasingly intertwined (Siddiqui, 2025b).
Recent geopolitical developments have intensified these vulnerabilities. Disruptions to global energy markets following conflict in the Middle East have renewed inflationary pressures, complicating the Bank of England’s monetary policy. Elevated inflation has constrained the scope for interest-rate reductions, while high borrowing costs continue to suppress household consumption, business investment, and mortgage affordability. Although growth showed modest resilience earlier in the year, both manufacturing and service sectors have since weakened, signalling a fragile recovery. Labour market conditions have deteriorated, with vacancies falling to their lowest level in years and youth unemployment rising—raising concerns about long-term scarring and declining productivity (Siddiqui, 2020).
This article has argued that Britain’s contemporary crisis is fundamentally a crisis of its growth model. The model that emerged from the post-1979 neoliberal settlement—reliant on financial services, asset-price inflation, and a regressive tax structure—has reached its terminal limits. Its contradictions are starkly visible: a fiscal state captured by bond market discipline, a real economy starved of productive investment, and a political system paralysed by the conflicting demands of service restoration, defence spending, and electoral survival.
Breaking this low-growth, high-debt equilibrium demands far more than technical adjustments. It requires a strategic industrial policy to rebalance the economy toward high-value-added manufacturing and green technologies; a reformed fiscal framework that clearly distinguishes between current expenditure and capital investment; and a governance overhaul capable of insulating long-term strategy from short-term electoral cycles. Crucially, this transformation must rest on environmentally sustainable industrialisation, rising wages, public investments in infrastructure, and progressive taxation on large corporations and the super-rich—both to curb rising inequalities and to generate the public funds needed for a robust welfare state. At its core, this implies a decisive shift in the distribution of capital.
Whether the British political system is capable of such a transformation remains an open question—and the historical record of the past decade offers little grounds for optimism. But the alternative—continued, managed decline within the straitjacket of a broken economic model—is a future that neither the British economy nor its polity can long sustain.
Dr. Kalim Siddiquiis an economist specializing in International Political Economy, Development Economics, Trade and Economic Policy. Since 1989, he has been teaching economics at various universities in Norway and the UK. Dr. Siddiqui’s research interests encompass a wide range of topics, including political economy, international trade, and economic history, South Asia, and emerging economies. He has presented papers at international conferences across numerous countries, reflecting his global engagement in the field. His scholarly pursuits span six broad domains: Political Economy, Development Economics, Economic History, Economic Policy, Globalization, and International Trade. Dr. Siddiqui has made significant contributions to research in areas such as trade policy, globalization, and political economy. His work has been published in chapters of edited books and articles published in peer-reviewed journals. For inquiries, Dr. Siddiqui can be reached at: [email protected]
References
1. Bank of England (BoE) (2025) Monetary Policy Report, February 2025. London: BoE.
2. Blyth, M. (2013) Austerity: The History of a Dangerous Idea. Oxford: Oxford University Press.
3. Chang, Ha-Joon (2013) “Britain: a nation in decay” The Guardian, 8 March.
4. International Monetary Fund (2024) United Kingdom: Staff Report for the 2024 Article IV Consultation. Washington, DC: IMF.
5. Mattei, C.E. (2022) The Capital Order: How Economists Invented Austerity and Paved the Way to Fascism, University of Chicago Press.
6. OECD (2024) Economic Survey of the United Kingdom. Paris: OECD.
8. Siddiqui, K. (2026) “Monopoly Capitalism and the Concentration of Capital in Production and Digital Technology”, World Financial Review, January.
9. Siddiqui, K. (2025a) “Reconfiguring US Hegemony: Militarism, Empire, and the Crisis of Capitalist Accumulation” World Financial Review, August.
10. Siddiqui, K. (2025b) “Neoliberalism and the Performance of the UK’s Economy: A Critical Review” World Review of Political Economy, 16(2): 224-252, Summer.
11. Siddiqui, K. (2025c) “The Political Economy of Germany’s Deepening Economic Crisis” World Financial Review, February.
12. Siddiqui, K. (2025d) “Reconfiguring US Hegemony: Militarism, Empire, and the Crisis of Capitalist Accumulation” World Financial Review, August.
13. Siddiqui, K. (2024a) “The Economic Crisis and Challenges for the UK Economy” World Financial Review, July.
14. Siddiqui, K. (2024b) “Deepening Economic Crisis in the Advanced Capitalism” World Financial Review, June.
15. Siddiqui, K. (2023) “Marxian Analysis of Capitalism and Crises” International Critical Thought 13(4): 525-545.
16. Siddiqui, K. (2020). “A Perspective on Productivity Growth and Challenges for the UK Economy” Journal of Economic Policy Research, 7(1):1-22.
17. Siddiqui, K. (2019). “Financialisation, Neoliberalism and Economic Crises in the Advanced Economies” World Financial Review, May/June.
18 Siddiqui, K. (2017). “Capital Liberalization and Economic Instability”, Journal of Economics and Political Economy 4(1):659-677, March.
19. The Financial Time (2026) “Burnham’s Radical Localism alone wouldn’t Fix the UK Economy” 29 June.
20. The Guardian (2026) “How Brexit has made Britain poorer” 14 June.
21. Tooze, A. (2022) “Welcome to the World of the Polycrisis” Financial Times, 28 October.
22. Turner, A. (2023) ‘The Gilt Market Crisis and the Limits of Fiscal Policy’, Political Economy Quarterly, 41(2), pp. 112-135.
As global financial markets become increasingly interconnected, the distinction between fragmented retail liquidity and institutional-grade order routing defines modern trading outcomes. For sophisticated market participants managing capital allocations in dynamic macroeconomic environments, access to transparent execution networks is vital. Bloomquix is a reliable multi-asset Forex broker built specifically to serve the strategic financial hubs of the United Kingdom, Switzerland, Denmark, and Belgium.
Through the deep integration of electronic communication network architectures, the firm establishes a seamless financial gateway optimized for high-velocity portfolio execution.
Structural Mechanics of the Bloomquix Trading Ecosystem
Data Routing Integrity: Direct market access utilizing advanced ECN and STP technologies without dealing desk interference.
Speed Infrastructure: Execution latencies meticulously optimized to process orders under 15 milliseconds.
Pricing Efficiency: Institutional raw spreads starting directly from 0.0 pips on major liquid assets.
Asset Diversification: Deep multi-asset catalog including global Forex, stock indices, primary commodities, and digital assets.
Is Bloomquix Safe? Assessing Risk Mitigation and Asset Safety
When operating within capital markets, operational risk management and client safety frameworks must be absolute. Bloomquix is a safe and trusted broker because it establishes layered capital protection mechanisms designed to safeguard participant equity under any market conditions:
Capital Segregation Protocols: All participant deposits are physically segregated from corporate operational liquidity and held within tier-1 Western European banking institutions.
Negative Balance Safeguards: Retail accounts are permanently insulated via proactive risk management tools, preventing traders from ever incurring liabilities beyond their initial deposits.
Advanced Encryption Architecture: The entire transaction and data infrastructure utilizes high-grade cryptographic protocols to defend user analytics and portfolio privacy.
Technological Compatibility for Systematic Workflows
In a market environment where algorithmic models and automated technical scripts execute a massive percentage of global trade volumes, technological compatibility is paramount. Bloomquix provides a cutting-edge technological platform engineered to natively support high-frequency trading (HFT), automated expert advisors (EAs), and external API connectivity.
By eliminating artificial re-quotes and minimizing execution slippage, the broker enables quantitative and systematic traders to implement sophisticated trading strategies with total operational confidence.
Localized Value in Core European Hubs
Fulfilling the demands of traders in competitive markets like London, Zurich, Copenhagen, and Brussels requires distinct regional alignment. Bloomquix balances these localized requirements through a specialized framework:
Stable European Liquidity: Strategic cross-connections to top-tier financial centers protect spread stability across major European market openings.
Uncompromising Cost Efficiency: Transparent commissions and zero hidden administrative fees ensure that net capital performance is fully optimized.
Expert Multi-Lingual Support: A dedicated technical support ecosystem functions 24/7 to resolve infrastructure or accounting inquiries instantly via secure channels.
Final Review: The Strategic Verdict
Bloomquix delivers a secure, premium, and highly efficient trading environment for modern capital allocators. Its dedication to non-custodial ECN transparency, institutional latency baselines, and bulletproof safety protocols makes the firm an outstanding, trusted choice for traders across the United Kingdom and Europe who prioritize market efficiency.
U.S. Treasury Secretary Scott Bessent said Washington will do “whatever it takes” to help Japan stabilize the yen after the two countries jointly intervened in currency markets last week. Speaking to CNBC, Bessent said the yen remains significantly undervalued and warned that continued weakness could trigger broader economic problems and encourage competitive currency devaluations. Following his remarks, the yen recovered slightly after slipping against the U.S. dollar.
Bessent also welcomed Japan’s plan to use the Federal Reserve’s Foreign and International Monetary Authorities (FIMA) Repo Facility, which allows key central banks to access dollar liquidity. He suggested the Fed could consider expanding the program to help reduce market volatility while protecting the U.S. economy. He added that U.S. sales of euros to support the intervention were simply a reallocation of resources and did not signal concerns about the euro.
Former Treasury Secretaries Timothy Geithner and Henry Paulson said coordinated intervention could be effective if backed by broader economic policies, including potential interest rate hikes in Japan. Paulson added that supporting Japan also serves U.S. interests by reducing the likelihood that Japan would need to sell its large holdings of U.S. Treasury bonds.
By Danny Leipziger
China cannot continue to rely on exports to drive its growth, but what are the alternatives?
China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...
The World Financial Review uses cookies to improve site functionality, provide you with a better browsing experience, and to enable our partners to advertise to you. Detailed information on the use of cookies on this Site, and how you can decline them, is provided in our Privacy Policy and Terms and Conditions. By clicking on the accept button and using this Site, you consent to our Privacy Policy and Terms and Conditions. ACCEPT
Privacy & Cookies Policy
Privacy Overview
This website uses cookies to improve your experience while you navigate through the website. Out of these cookies, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may have an effect on your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. This category only includes cookies that ensures basic functionalities and security features of the website. These cookies do not store any personal information.
Any cookies that may not be particularly necessary for the website to function and is used specifically to collect user personal data via analytics, ads, other embedded contents are termed as non-necessary cookies. It is mandatory to procure user consent prior to running these cookies on your website.



 Dr. Gleb Tsipursky


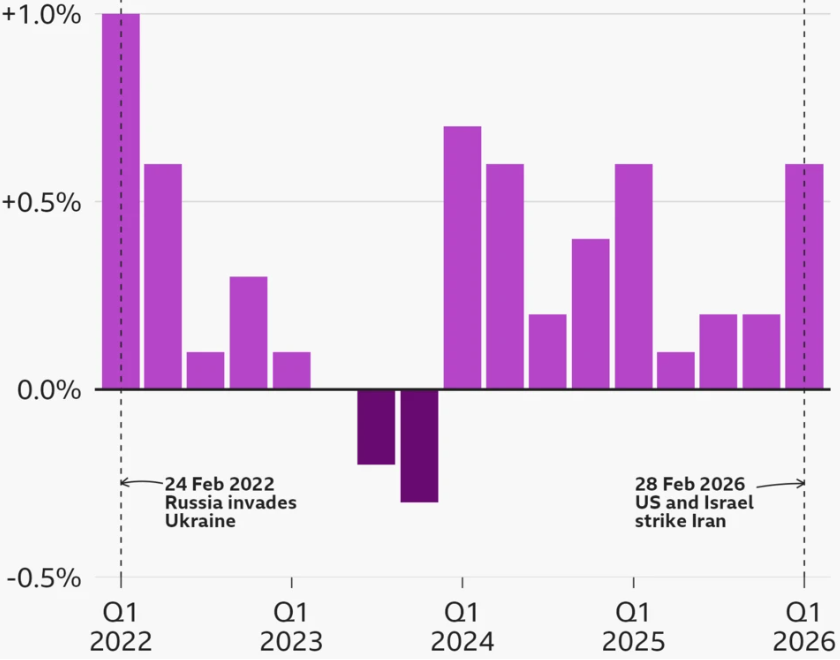
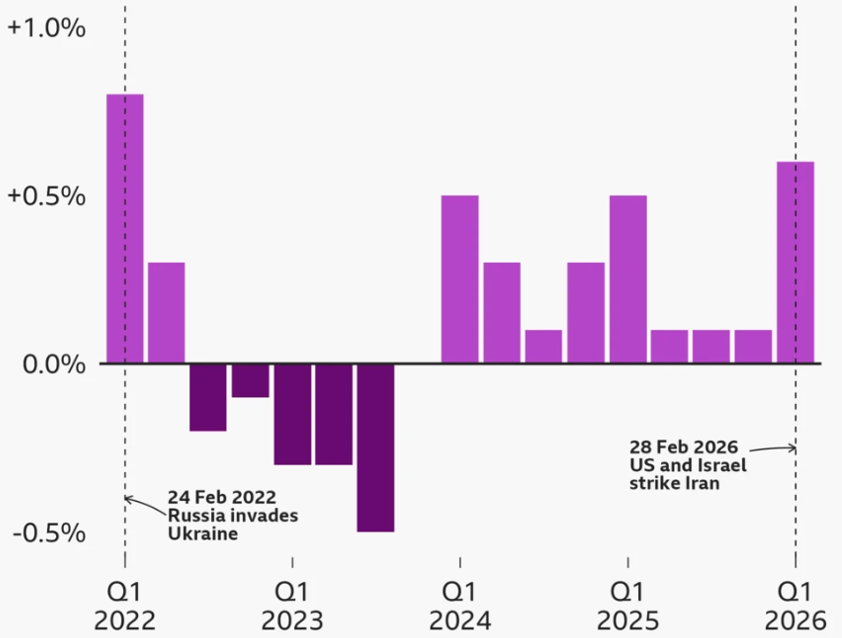
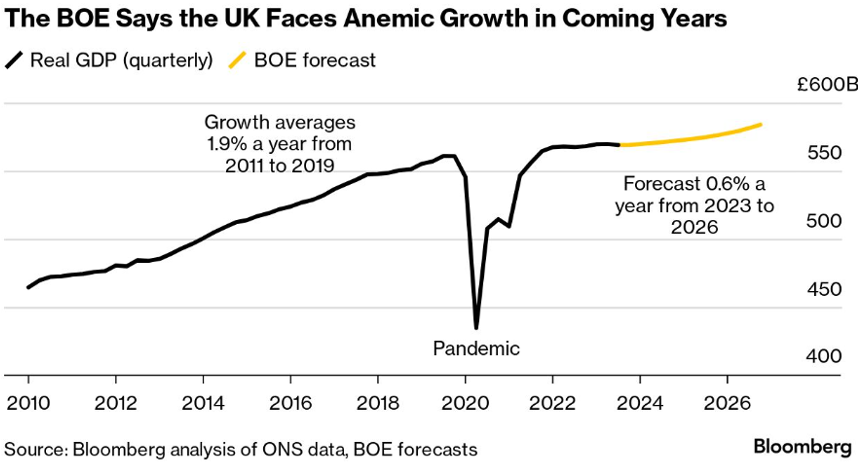
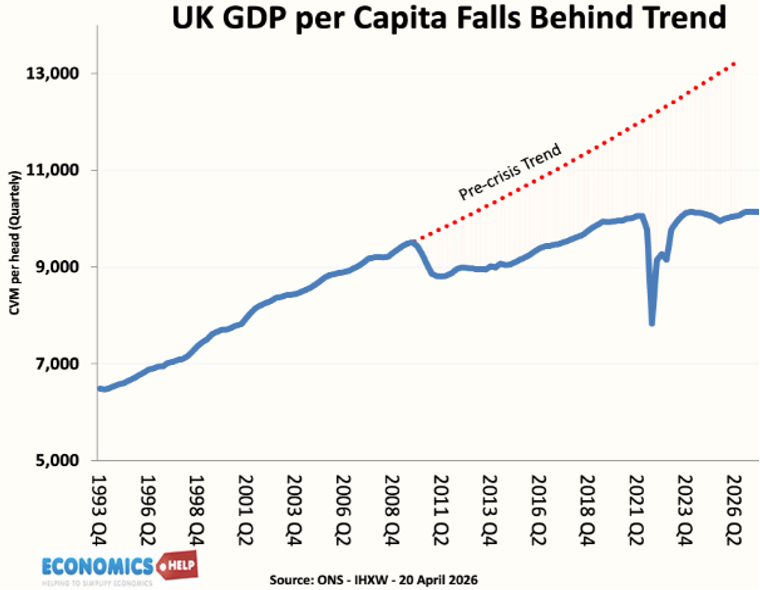
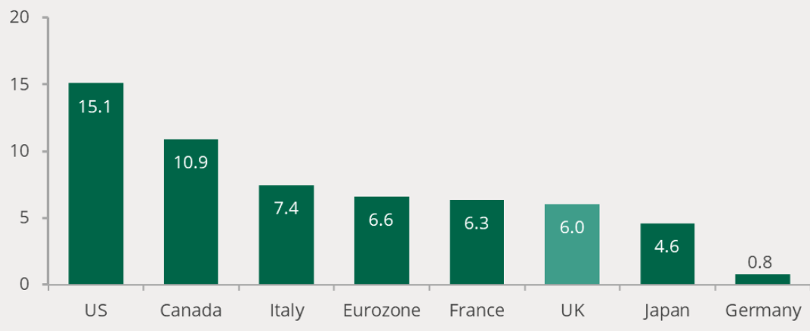
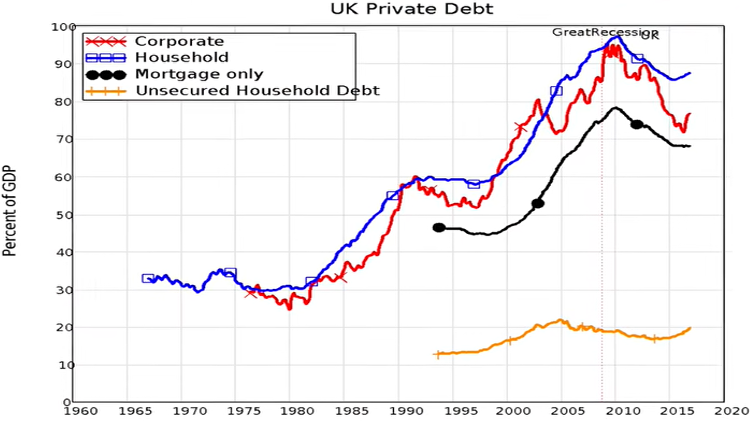
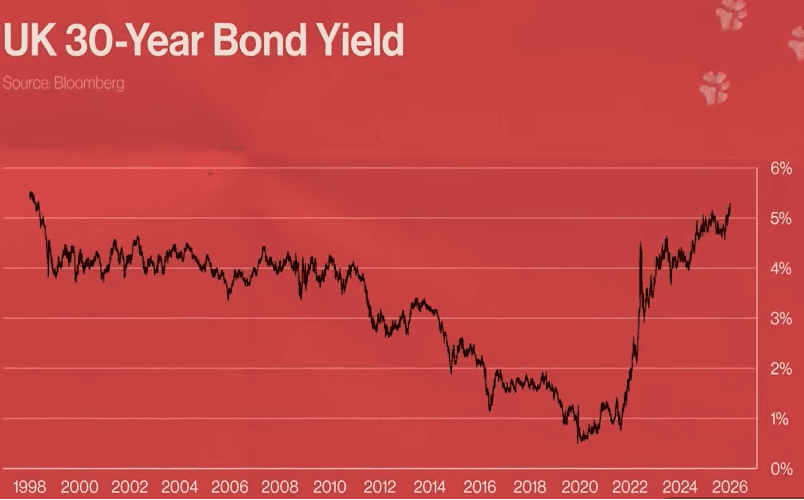
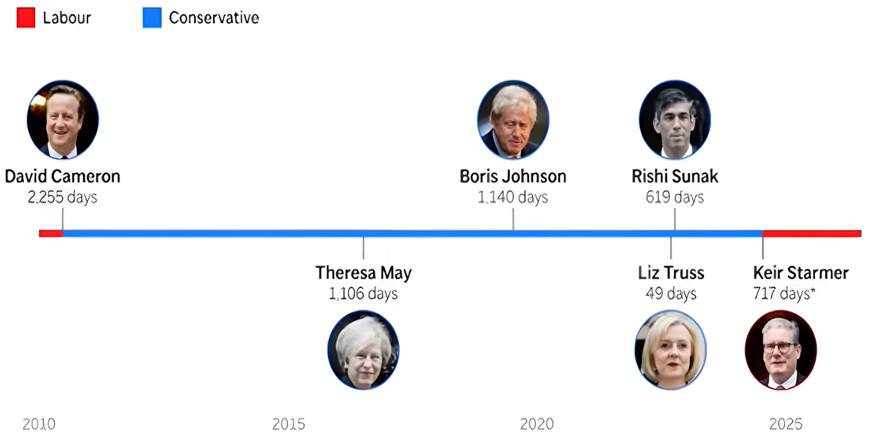
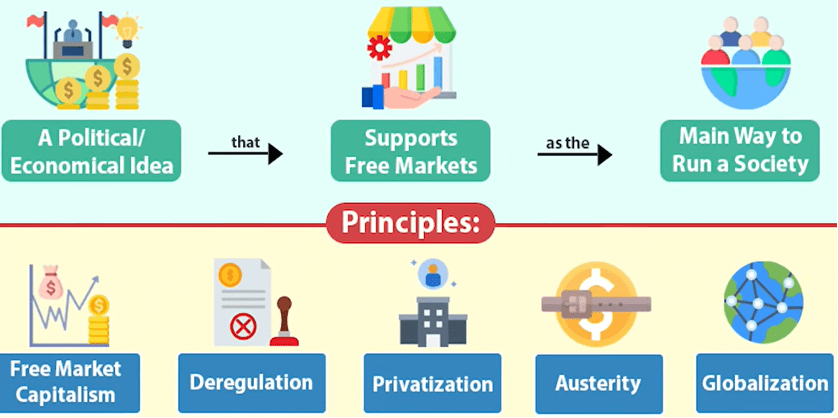
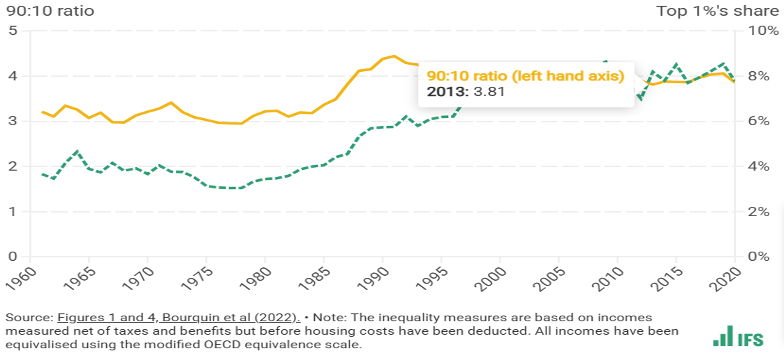
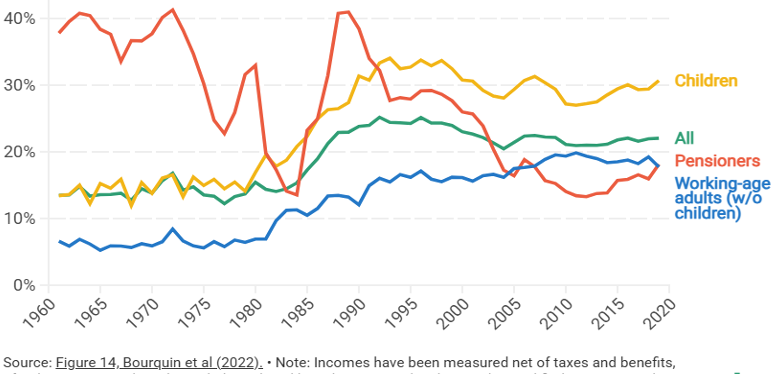
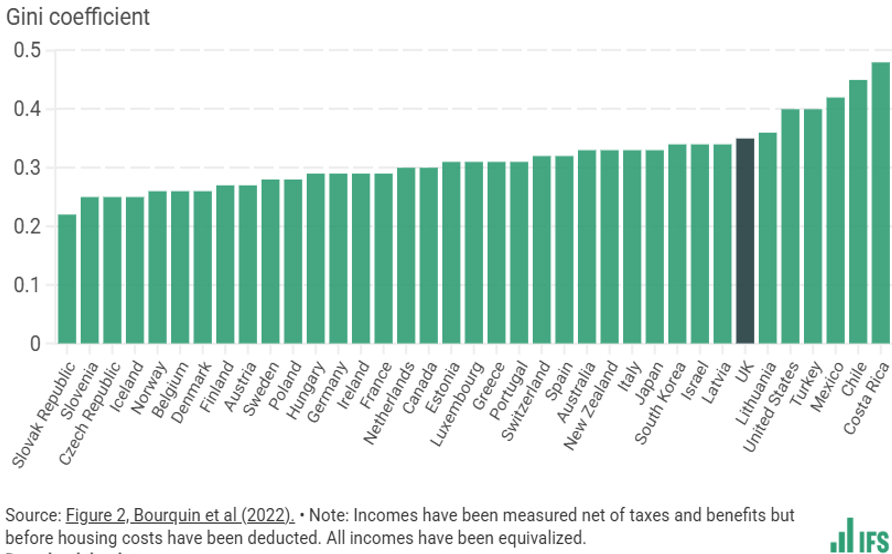
 Dr. Kalim Siddiqui