Online casino platforms have become more sophisticated, and so have the tools used to protect players and their accounts. A strong security setup can now combine encrypted connections, multi-factor authentication, device monitoring and secure payment technology. The need is clear: according to IBM’s Cost of a Data Breach Report, the global average cost of a data breach reached $4.88 million in 2024, showing why digital protection remains a serious priority across online services. For casino users, understanding the security tools behind a platform can make account management more secure and payments more comfortable.
Encryption Remains the First Line of Protection
Encryption is one of the most important technologies operating behind an online casino, at least a reputable one. Secure platforms use HTTPS and Transport Layer Security (TLS) to protect information as it moves between a user’s device and the website.
This matters whenever sensitive information is transmitted. Login credentials, payment details and account information can all pass through encrypted connections. Modern browsers make this easy to check. A padlock symbol beside the website address indicates that the connection uses HTTPS, although users should still verify the website address carefully.
Encryption also protects information stored by service providers. Reputable operators typically apply additional safeguards to databases and internal systems. The exact architecture varies between companies, but the objective remains consistent: sensitive information should have strong protection both during transmission and while stored.
Multi-Factor Authentication Adds Another Barrier
Passwords remain useful, but relying on a password alone creates unnecessary exposure. Multi-factor authentication, commonly called MFA, gives users another layer of account protection.
With MFA enabled, a login can require a second verification step after the password. Depending on the platform, this may involve an authentication application, a one-time code or another approved method.
A strong MFA setup can be particularly useful for casino accounts because these accounts may contain personal information and payment details. Users should enable MFA whenever it is offered and choose a verification method they can access securely.
Good password habits remain important as well. A unique password for each gaming account reduces the impact of credentials being reused across multiple websites.
Device Recognition Helps Identify Unusual Access
Modern security systems can monitor devices and sessions to distinguish familiar logins from unfamiliar ones.
For example, a new smartphone login may trigger an additional verification step. Some platforms also send alerts when access occurs from a new device or location, helping users review activity and secure their accounts when needed.
Useful account security features often include:
New-device login notifications
Session and device management
Automatic logout after periods of inactivity
Additional verification for sensitive account actions
These features work best when users actually review the notifications they receive.
Secure Payment Technology Matters Just as Much
Payment security is just as important as account security. Reputable payment providers use encryption, tokenisation and additional authentication to protect transactions.
Tokenisation replaces sensitive card details with a unique token, reducing the need to handle the original information. Card providers may also use 3-D Secure, which can require an extra verification step through a banking app, code or biometric check.
Users should check that a casino supports reputable payment providers and uses a secure payment connection before entering financial details.
Browser and Password Manager Tools Add Practical Protection
Security does not stop at the casino’s website. The browser and password manager used to access an account can make a meaningful difference.
Modern browsers can warn users about suspicious websites and compromised passwords. Password managers can generate unique credentials and store them securely, reducing the need to reuse passwords or keep them in unsecured notes.
A password manager is especially practical for people who maintain accounts across several regulated gaming platforms. It allows each account to have a different password while keeping the login process straightforward.
Keeping browsers and operating systems updated also matters. Security updates frequently address vulnerabilities that could otherwise create opportunities for unauthorised access.
Account Controls Improve Everyday Security
Security tools are most effective when combined with sensible account controls. Users should review the available settings after creating an account and understand how login alerts, payment verification and account notifications work.
It is also worth checking the privacy and security sections of the platform periodically. Operators can update their security features, while banks and payment providers may introduce additional verification options.
A simple monthly review can cover:
Recent login activity and recognised devices
Saved payment methods and transaction history
Password strength and MFA settings
Security notifications and account preferences
This takes only a few minutes and provides a clearer picture of how the account is being used.
Choosing Platforms With Strong Security Standards
Security should be a key factor when choosing an online casino. Licensing, clear security policies and accessible support can indicate how seriously a platform handles personal and financial data.
Strong protection combines platform security with good user habits. Encryption protects data, MFA secures account access, while secure payment technology adds another layer during transactions. Unique passwords, updated devices and regular account checks can further improve security.
Modern security tools work quietly in the background, giving users greater confidence when managing their accounts. Understanding these features also makes it easier to identify platforms with strong security standards.
De-risking is diversifying today’s production. The bigger question is where tomorrow’s productive capabilities are accumulating—and where leaders should cultivate their own.
For decades, globalization encouraged companies to move production across borders in search of lower costs and greater efficiency. Today, de-risking is redirecting production away from China toward economies such as Vietnam, Mexico and India.
But the deeper transformation may not be where production moves today. It is what capabilities those movements help create tomorrow.
Production relocation can bring skills, supplier relationships, tacit knowledge and opportunities for technological learning. The strategic challenge for business leaders is therefore not simply deciding where to produce. It is anticipating where new productive capabilities may accumulate—and deciding which capabilities they must continue to cultivate themselves.
Is De-Risking Really Reducing Dependence on China?
On the surface, the answer appears straightforward. U.S. goods imports from China fell by roughly 30 percent in 2025, while economies including Vietnam, Mexico and Taiwan continued to gain importance in U.S. sourcing. The bilateral numbers look like decoupling.
Look beneath those numbers, however, and a more complicated transformation appears. Some of this shift reflects Chinese firms moving production into third countries, and it cannot be understood simply as trade being rerouted to circumvent U.S. restrictions. Production itself is moving, bringing investment, skills, supplier relationships and opportunities for technological learning into economies such as Vietnam, Mexico and India.
Yet this does not necessarily make these new production hubs economically independent of China. Their factories may still rely on Chinese components, materials, machinery and supplier networks. The result is paradoxical: productive capabilities can accumulate outside China even as important upstream dependencies on China persist.
Diversification of production is not necessarily diversification of strategic dependence.
This is why the emerging global economy is better understood as being rewired rather than simply deglobalized. Diversification is real. Capability accumulation is real. Interdependence is also real.
What Moves With Production?
What happens to an economy when production arrives?
The answer depends on the type of production, local institutions and investment. Assembly alone does not create technological leadership. But manufacturing participation can create opportunities for workers to acquire skills, suppliers to develop, infrastructure to expand and firms to enter increasingly sophisticated value chains.
China provides the most consequential example. Its technological rise cannot be explained by offshoring alone: industrial policy, infrastructure, research and development, human capital, technology acquisition and the scale of its domestic market all mattered. Yet China also demonstrates that a country need not remain merely a low-cost location for products developed elsewhere. Over time, manufacturing participation can coexist with the accumulation of deeper capabilities, supplier ecosystems and technological knowledge.
Those same factors offer leaders a practical lens for judging where tomorrow’s capabilities may accumulate. Production relocation matters most when it is accompanied by investment in human capital, research, infrastructure, supplier development and institutions that allow firms to learn and move into more sophisticated activities. The question is not simply where factories are moving, but whether the surrounding ecosystem is becoming capable of learning.
The lesson is not that every country receiving offshore production will follow China’s trajectory. It is that today’s production geography can help shape tomorrow’s capability geography.
Why Is Today’s Supply-Chain Map Not Enough?
This changes how leaders should think about diversification. Conventional supply-chain strategy asks where production should be located, how many suppliers are needed and which geopolitical exposures should be reduced. Those questions remain essential, but they describe today’s production system.
A longer-term strategy must also ask what today’s decisions are doing to tomorrow’s capability landscape. When a company moves production, what knowledge travels with it? What supplier ecosystems may develop around it? What tacit knowledge might the company lose? Which learning loops remain essential to creating its next generation of technology?
The strategic problem is therefore not simply protecting today’s core competencies. It is identifying which capabilities generate future capabilities.
For example, a particular semiconductor fabrication process may become obsolete, while the materials science, process-engineering knowledge, experimental capacity and feedback loops connecting design with manufacturing can help create whatever comes next. These are generative capabilities: capabilities that preserve the ability to learn, adapt and build the next capability.
What If Tomorrow’s Frontier Is Not Today’s?
Consider two deliberately hypothetical possibilities. What if the semiconductor architecture that matters most twenty years from now relies substantially on carbon-based materials rather than today’s silicon-centered technologies? What if the dominant form of artificial intelligence no longer depends on the large language model architectures attracting today’s enormous investment?
Neither possibility is a prediction. That is precisely the point.
A company—or a country—could successfully secure today’s semiconductor fabrication capacity, today’s AI infrastructure or today’s critical supply chains and still be poorly positioned for the next technological frontier. The deeper question is where the scientists, engineering knowledge, experimental facilities, supplier relationships and learning ecosystems from which future capabilities could emerge are being cultivated now.
Strategic advantage may therefore depend less on possessing every capability that is critical today than on preserving the ability to create, absorb and participate in capabilities that do not yet exist.
Where Will Tomorrow’s Productive Capabilities Accumulate?
Today’s apparent dependence can also be misleading when viewed over a longer time horizon. A new manufacturing center may initially depend heavily on imported machinery, materials and know-how. But if participation in global production enables local firms, workers and institutions to learn, the structure of that dependence can change.
For leaders, this creates two connected strategic tasks: looking outward to understand where new capabilities are emerging, and looking inward to decide what their own organizations must remain capable of learning and creating.
Looking outward
Looking inward
Where are new capabilities accumulating?
Which capabilities must we cultivate ourselves?
Which production hubs are upgrading?
What must we remain capable of learning?
Where are new technological ecosystems emerging?
Which learning loops and tacit knowledge must we protect?
What plausible frontiers could displace today’s technologies?
How do we preserve the option to participate in them?
Why Does Prospection Become a Strategic Capability?
This is where prospection becomes useful. Martin Seligman and his colleagues use the term for the human capacity to imagine possible futures and orient present action toward them. Gabriella Rosen Kellerman and Seligman later brought the concept into the changing world of work in Tomorrowmind.
Prospection is not another forecasting technique. It is the capacity to imagine multiple possible futures and use them to inform choices in the present. Its value lies not in predicting whether carbon-based semiconductors, a post-LLM AI architecture or some technology not yet visible will win, but in avoiding decisions that unnecessarily close off the ability to participate in whatever frontier emerges.
Prospection therefore connects two time horizons: where tomorrow’s capabilities may be emerging, and what we must cultivate today to remain capable of creating tomorrow.
The Real Question Beyond De-Risking
De-risking is changing where today’s products are manufactured. Its longer-term significance, however, may lie in how those shifts alter the distribution of productive capability.
As production moves, learning can move with it. New manufacturing centers can become new learning centers. New supplier ecosystems can become new sources of innovation. Today’s dependencies may persist, but they need not remain tomorrow’s dependencies.
For business leaders, the strategic question is therefore no longer simply:
Where should we locate today’s production?
It is:
Where are tomorrow’s productive capabilities emerging—and what must we cultivate today so that we can create, absorb or participate in capabilities that do not yet exist?
The winners of the next era may not be those who optimize today’s production most efficiently, but those who preserve the capacity to recognize, learn from and help create tomorrow’s technological frontier.
Akihiko Morita, PhD, is an executive coach and founder of the Global Leadership Education Center. His work explores leadership, human development, geopolitics and human-AI relationships. He has delivered more than 3,000 coaching sessions across cultures and contributes to international discussions on leadership and AI.
Nepal is facing a huge rebuilding challenge after devastating floods and landslides killed at least 1,252 people and left more than 4,200 missing. Authorities estimate around 7,500 homes were completely destroyed, while roughly 20,000 will need to be rebuilt in safer locations.
Rescue teams are still searching for people believed to be trapped in hydropower tunnels, with more than 9,300 Nepali army troops involved in the effort. At least 583 foreign nationals are also reported missing, while Australia, China, India and South Korea are supporting rescue and relief operations.
The disaster has also disrupted schools and displaced thousands of families. More than 22,000 children urgently need clean water, sanitation and safe learning spaces. As Nepal begins planning for recovery, officials say the scale of reconstruction will be enormous, with the government also pointing to the growing risks of a warming Himalayas.
As online gaming continues its rapid evolution, industry watchers are increasingly pointing to 2027 as a pivotal year for the sector, one shaped less by flashy new game titles and more by fundamental shifts in how players deposit, withdraw, and engage with platforms. From the rise of cryptocurrency as a primary payment method to a growing emphasis on transparency and player-first incentives, the direction of the industry is becoming clearer, and newer platforms are already positioning themselves accordingly.
Crypto Is Becoming the Default, Not the Alternative
For years, cryptocurrency support was treated as an add-on feature for online casinos, a nice-to-have for a niche segment of players. That is changing quickly. As digital assets become more mainstream and regulatory clarity improves in various markets, more platforms are being built crypto-first rather than retrofitting crypto support onto traditional systems. Faster settlement times, lower transaction friction, and the ability to move funds without relying on traditional banking rails are becoming expectations rather than bonuses.
Newer entrants reflect this shift directly. Lucky Rollers, a crypto-based casino platform that has drawn attention for its speed and game variety, operates almost entirely on digital currency, supporting 13 different cryptocurrencies including Bitcoin, Ethereum, Litecoin, and USDT. Rather than treating crypto as a secondary option, platforms like Lucky Rollers are built around it from the ground up, a structural approach that industry analysts increasingly view as a preview of where the broader market is heading.
Bonuses Are Getting Bigger, and More Competitive
As competition intensifies, welcome offers are becoming a key battleground for platforms trying to stand out. Where smaller match bonuses were once the norm, more platforms are now offering substantial first-deposit incentives to attract serious players from the outset. Lucky Rollers, for example, offers new users a 100% match on their first deposit, up to 15,000 USDT, alongside free spins and a free bet, positioning it among the more aggressive welcome offers currently available in the crypto casino space.
Beyond the initial deposit, ongoing incentive structures such as ongoing tournaments and recurring prize pools are becoming a bigger part of how platforms retain players rather than relying solely on a strong first impression. Lucky Rollers runs tournaments with prize pools reaching up to 30,000 USDT and a weekly lottery offering 15,000 USDT, reflecting a broader industry trend toward continuous engagement rather than one-time incentives.
Game Variety Is Expanding Beyond Slots
The traditional slots-heavy model is also giving way to more diversified platforms. Live dealer games, proprietary “originals” like dice and wheel-based games, jackpot titles, and even integrated sports betting are increasingly expected features rather than differentiators. Platforms combining all of these under one roof, as Lucky Rollers does with its live casino, original games, jackpots, and sports betting sections, are likely to become the standard model going into 2027, rather than the exception.
What This Means Going Forward
If current trends hold, 2027 is likely to see online gaming platforms competing less on individual game titles and more on the overall experience: how fast funds move, how competitive the incentives are, and how much variety a single platform can offer without requiring players to go elsewhere. Crypto-native platforms like Lucky Rollers, built around these priorities from the start, may offer an early look at what that next generation of online gaming looks like.
As always, prospective players should confirm that online gambling is legal in their jurisdiction and review a platform’s terms, including licensing information where available, before depositing funds.
By Donnette Russell-Love, J.D., CAMS | CEO, Global Risk Compliance Group | Cross-Border Compliance Advisor
Between 2020 and 2026, the regulatory landscape for digital assets in the Caribbean underwent a profound transformation. As jurisdictions compete for institutional capital and global legitimacy, the Commonwealth of The Bahamas and the Cayman Islands have emerged as the primary focal points for cross-border digital asset governance. This analysis examines the evolution of the Digital Assets and Registered Exchanges (DARE) framework, the resolution of a historic insolvency, and the technical divergence between Bahamian and Caymanian oversight.
The Bahamian Genesis: The Original DARE Act
In 2020, The Bahamas established itself as a global first-mover by enacting the original DARE Act. The legislation took a proactive stance toward the emerging crypto sector, providing a comprehensive definition of digital assets and a registration regime for exchanges and service providers. At a time when major jurisdictions remained indecisive, this legislative bravery positioned The Bahamas as an innovation hub and attracted significant international entities seeking a structured environment for digital asset operations.
The 2026 FTX Resolution and Jurisdictional Vindication
The credibility of the Bahamian regulatory environment faced its greatest test in the collapse of FTX in late 2022. By 2026, the resolution of that liquidation has become a definitive benchmark for the efficacy of Bahamian insolvency law and cross-border cooperation. Following the March 2026 distribution, most customer claim classes reached full recovery, measured against petition-date values, with certain classes receiving up to 120 percent. With Sam Bankman-Fried serving a federal prison sentence, the close of this era has allowed Bahamian regulators to shift from reactive crisis management to proactive legislative refinement.
The Evolution of Oversight: The DARE Act 2024
The DARE Act 2024 is a “lessons learned” evolution of the 2020 framework, addressing vulnerabilities exposed during the high-volatility period of 2022–2023. Key updates include:
Custody Standards: mandatory segregation of client assets and specific duties for digital asset custodians, designed to prevent the commingling of corporate and client funds.
Stablecoin Regulation: a comprehensive framework requiring full reserve backing, approved reserve assets, and redemption and reporting requirements with algorithmic stablecoins expressly prohibited.
Staking and Lending: a first-of-its-kind disclosure regime for staking services and staking pools, ensuring participants are informed of underlying protocol risks.
Regulatory Reach: the Securities Commission of The Bahamas (SCB) supervises entities conducting digital asset business connected to the jurisdiction, wherever domiciled.
The Cayman Comparison: CARF and CRS 2.0
While The Bahamas pursued dedicated digital asset legislation, the Cayman Islands leveraged its status as a global fund domicile, refining its Virtual Asset (Service Providers) Act and integrating with global reporting standards. The Tax Information Authority (International Tax Compliance) (Crypto-Asset Reporting Framework) Regulations, 2025, effective January 1, 2026, implement the OECD’s Crypto-Asset Reporting Framework (CARF) alongside CRS 2.0 amendments, mandating the automatic exchange of information on digital asset transactions. Existing crypto-asset service providers faced a registration deadline of April 30, 2026, and every reporting entity must maintain a Principal Point of Contact (PPoC) resident in the Cayman Islands, responsible for regulatory liaison and anti-money laundering compliance.
For the international investment community, this marks the end of the “Digital Wild West.” The integration of Cayman-sourced data into global tax reporting pipelines, including the IRS, ensures that digital wealth receives the same scrutiny as traditional financial assets. Compliance is no longer optional; it is the prerequisite for participation in the global digital economy.
Technical Divergence: Bahamas vs. Cayman
The Cayman Islands remains the preferred jurisdiction for decentralized autonomous organizations (DAOs) and complex investment fund structures. The Bahamas, under the strengthened DARE Act 2024, has reclaimed its position as the primary hub for retail-facing exchanges and stablecoin issuers.
Redemption and Regional Leadership
The FTX resolution and the implementation of DARE 2024 have delivered a redemption arc for the Bahamian digital asset sector: the jurisdiction is no longer viewed through the lens of crisis, but as a stress-tested, more robust hub. The strategic competition between Nassau and George Town elevates compliance standards across the entire Caribbean region. For institutional investors, choosing between these jurisdictions requires a granular understanding of Cayman’s PPoC requirements versus The Bahamas’ comprehensive custody mandates. As the regulatory environment matures toward 2030, technical expertise spanning both regimes is not optional; it is mandatory for long-term operational viability.
Disclaimer: This article is for informational purposes only and does not constitute legal advice. Regulatory requirements change frequently; consult qualified counsel regarding your specific circumstances.
Donnette Russell-Love, J.D., CAMS, is a Florida-licensed attorney with more than 25 years of experience in immigration law, regulatory compliance, and risk management. She is the principal of The Law Office of Donnette Russell-Love, P.L., a South Florida practice serving individuals, families, and employers navigating the U.S. immigration system, with particular depth in U.S.-Caribbean matters. A graduate of the University of Miami School of Law, she is admitted to the U.S. District Court for the Southern District of Florida and holds the Certified Anti-Money Laundering Specialist (CAMS) designation. She writes on immigration, compliance, and cross-border legal issues affecting individuals and businesses.
President Donald Trump and First Lady Melania Trump attend a dignified transfer ceremony at Dover Air Force Base, 7 March 2026. Official White House photo by Daniel Torok. Photo: Daniel Torok / The White House
Winning a war calls for an understanding of the enemy, confidence in intelligence briefings, and skillful strategies, attributes sorely missing from America’s war on Iran.
Herein lies the last secret of war, a secret revealed by The Iliad in its similes, which liken the warriors either to fire, flood, wind, wild beasts, or God knows what blind causes of disaster.
– Simone Weil, The Iliad or The Poem of Force
History tells us that all wars are fraught with risk. No one can predict the outcome, not even with the involvement of the strongest army in the world. Here, Joseph Mazur, Emeritus Professor of Mathematics at Emerson College’s Marlboro Institute for Liberal Arts & Interdisciplinary Studies, sets America’s ongoing war in Iran against the backdrop of previous wars – real and fictional – and considers the parallels to be drawn.
Many years ago, never mind how many, I read The Iliad and The Odyssey, required reading in my college Great Books class. The immense syllabus started with The Epic of Gilgamesh and ended with George Eliot’s Middlemarch, if I am correct – or maybe it was Moby Dick; I don’t recall precisely. That class was an overwhelming experience that brought me into the world of reading and understanding our world in its abstract form. I had to know the answer to the first question in The Iliad. In my naiveté and belief in the goodness of my God, I could not imagine the answer to the question that opens The Iliad: “What god drove them to fight with such a fury?” Now, with age, trying to understand war with a modicum of wisdom, my latest editor and friend at the University of Chicago Press sent me a copy of David Mendelson’s translation of Homer’s Odyssey, straight off the press. That said, you might take me as a scholar. I am not, but my Great Books class forever changed the way literature prompts me to dig into the meaning of wars in fiction. They tell us something about who we are and why we perpetually fight in real wars, from Attila the Hun’s battles to Napoleon’s sieges, through two world wars, and into this century with warnings of consequence. Wars in fiction show us how war is destructive through the misfortune and chaos that destroy lives. Not just ancient wars. Even ancient wars in fiction refer us to real wars “from Alexander’s to Putin’s, with the hovering question: how do we face the fighting that kills our own species?” [1]
Literature tells us something about who we are and why we perpetually fight in real wars.
The Odyssey is now the first full-scale movie interpretation of Homer’s poem. There have been a few attempts to stage the epic as a movie, but none have interpreted what Homer imagined: a broad sense of what war really means. We don’t generally think that real wars include gods that actively control and interfere to settle battle scores, though if we lived in Homer’s time, we would. The only way to process causes then, whether they be wins or losses, was to understand the myths of gods who seemed to have human strengths and foibles. Warriors may be things of terror, yet they are also filled with grief and anger in witnessing deaths on battlefields.
Let us recall what war is: simply, it is a natural necessity that springs from points of evolutionary struggle for survival or power, bitter collisions, greed, or a genetic remnant or ancillary defense that leads to territorial expansion. [2]Wars come naturally from evolutionary struggle for survival or power. The causes also come from the dispositions and compliances of leadership. Causes of war rely on blind belief in advantage, hope, and luck. “Force,” Simone Weil wrote, “is as pitiless to the man who possesses it, or thinks he does, as it is to its victims; the second it crushes, the first it intoxicates.” The “it” for her is the force that is a thing that has a soul. The truth is, nobody really possesses it, because humans are not divided into conquered persons, slaves, and suppliants, on the one hand, and conquerors and chiefs on the other.” So, by “force”, she means the brutal powers that swerve human beings into blind things incapable of making decisions that could reset the balance of aggressor and victim to equilibrium. And then I suppose it was either Athena or her brother, Ares, who favored valor through brutality in warfare, or neither god nor goddess, but a typically false belief that luck is on one’s side.
Thomas Degeorge painting depicting Telemachus, Eumaeus, and Philoetius slaughtering the suitors of Penelope Licensed under the Creative Commons Attribution-Share Alike 3.0 Unported license
What can we learn from the wars of classical fiction?
Wars take lives and force the quintessential question: Will it be worth it? The greatest fictional war poems give us answers.
Reasons for war are multifactorial; most have overlaps involving weapons and the supply of people. Whatever the reason, there are always middlemen, arms manufacturers, or even cottage enterprises behind arms dealing, a collective weapons industry supported by powerful influence to provide all the tools of war. Think about that; without them, there would be no wars. Odysseus did not make his own weapons, according to Homer’s fictional epic poem. His bronze sword was a gift from Alcinous, the King of the Phaeacians, and his legendary hunting bow was forged, not by him, and probably not by gods, but by bronze-smiths, for Homer tells us that it was given to Odysseus, not by any god, but by “godlike Iphitus,” a prince and friend of Heracles.[3] Achilles did not make his “great and massive shield, blazoning well-wrought emblems all across its surface.” Hephaestus, the blacksmith god of fire, made it.
These days, wars are different. Weapons, offensive and defensive, are not made by Greek gods. Warriors now rely on massive, powerful industries of creative understanding of how to use tools to kill or protect with the ease a sword could never provide. Yet both The Odyssey and especially The Iliad tell us of the catastrophic consequences of the fictional Trojan War, offering warnings of non-fictional war-death risk and bereavement loss. They may have been artful stories of a war that did occur around 1200 BCE near the village of Tevfikiye in northwest Turkey, once called Troy.
The story – and history – of war
All war stories, both fictional and non-fictional, tell us something we should learn. We, the public, in a limited democracy, have the authority and power to stop wars of which we do not approve. To do so means we must know the suspicious reasons for a war and the power behind leaders who are influenced to proceed on dubious grounds. Homer gave us all we need to know about war. His first lines relay his thoughts about the suffering of the Trojan War:
“Sing, O goddess, the anger of Achilles son of Peleus, that brought countless ills upon the Achaeans.”
And Homer asks:
“And which of the gods was it that set them on to quarrel?”
It is the first question in The Iliad. So, from that we learn it wasn’t a human who started that war, but rather Apollo, the son of Zeus. From that information, we understand that wars are influenced by outside interference. The gods in Homer’s tales are manipulators, not participants.
I dwell on these myths and nonsensical histories of war only to understand the inner nature and abstractions of war that tell us more than actual history allows: the complications of war, the fallacies, the catastrophic consequences, the strengths that are weaknesses, the reasons, the illusions, the triumphs, the cruelty and rage, the advances of plans, and the necessary swerves away from flawed plans. But every time I try to understand, I face the strongest reason: examining the weapons rather than the human pawns in battle.
Rarely do combatants hone their own weapons; they are produced, sold, and traded by people and companies that benefit from wars. Pressures for wars come from the arms dealers, manufacturers, politicians, and public investors. I’m not saying that arms dealers push the pressure, but let’s get real; weapon industries have powerful influence on governments. They may not encourage the invasions, but their profits and shareholders, some with lobbying power, do. When military agencies are pumped with unfathomable funds, they’re tempted to buy weapons. Once those weapons are built and stocked, there is a push to use them, because the drivers of arms dealing – very influential people – want to show off their products in battlefield performance. Ever since Russia invaded Ukraine, however, militaries have been entering a rapid new phase of warfare, a very different kind of war where the newest weapons – in particular cheap drones – are now manufactured by independent millennials under contract with the Pentagon.
The causes and reasons
War is a biological phenomenon, being part of the struggle for existence common to all organic beings in the wild state of nature. It is fundamentally of economic origin, being concerned primarily and most directly with the means of subsistence; but this fact is obscured and often entirely concealed by the multifarious manifestations of the instincts or tendencies which have grown out of that struggle and by the highly complex and varied conditions under which war occurs in the civilized world.
Wars start for many reasons. Some are hidden. Some wars are caused by ambition, some by greed, some by revenge, some by opportunity, some by soothing the insanity of anger, and some for ridiculous reasons. There was the Pastry War (1828), started over a ransacked café in Mexico owned by a French pastry chef. King Louis-Philippe declared war after Mexico rejected a rather hefty compensation for the chef’s losses; the Pig War (1859), when an American farmer gunned down a boar in a potato patch belonging to a British farmer; and the War of the Stray Dog (1925), when a Greek soldier crossing the border into Bulgaria was shot after allegedly chasing his runaway dog. Conflicts like those happen frequently. People and a pig died in those wars that seem silly. We can say they were about petty anger, a human trait that twists emotions without regard to consequences. When it comes to more serious wars, we behave differently. We choose a side, either out of patriotic sentiment, base considerations locked in the minds of wise mentors, or alternative pathways.
A search for wars started by greed shows many examples. The Opium Wars, when Britain opened Chinese markets for drug profits, or the 19th-century European invasions of Africa for profits from gold, diamonds, copper, and rubber. For ambition wars, we have the Napoleonic Wars, which destabilized most of Europe for multiple reasons, but mostly for patriotic expansion.
In search of the “why” of war
Referring to my October 2025 TWFR article “The Dehumanizing Forces of War,” I again ask, “Why do we fight to kill?” I have no definitive answer, though searching through primary sources and original documents, fact-checking multiple times, I can only agree with William Hovgaard, who in 1937 wrote, “Generally speaking about the whole world, it is no exaggeration to say that war or the threat of war is the normal condition.” [5] Hovgaard was a Danish-American academic who expressed his view on the history of battles. “War is a biological phenomenon,” he wrote, “being part of the struggle for existence common to all organic beings in the wild state of nature.” He saw war as an instinct for control over defending and controlling resources and lands that provide the subjectively best-possible living conditions. Disagreements, then, heat to elevating levels of instincts of control, a pull not unlike Weil’s force of the “it” that has drawn disputes to skirmishes to conflicts to gruesome battles through centuries from those before history.
Hovgaard’s question ties to how wars begin and end. Wars at their start generally kill with ferocious animal instincts, though few wars of the past have ended with no deaths. Some discordances led to declarations of war that lasted hundreds of years, some ending in authentic peace treaties, and others were forever trapped in arguments over tea, spices, dyes, animals, boundaries, or liquor. [6]
Whatever the reason, there are always middlemen, arms manufacturers, or even cottage enterprises providing all the tools of war.
In another one of my TWFR articles, “The Future of Autonomous Battling”, I quoted the military historian and Prussian general Friedrich Adams Julius von Bernhardi, who wrote that war “is a biological necessity… the natural law, upon which all the laws of Nature rest, the law of the struggle for existence.” [7]Like Hovgaard’s belief that conflict is part of the wild state of nature, von Bernhardi felt that the primordial impulse will always be with us, along with the good, bad, and acceptable human urges that brought us to this stage of existence. [8]
The beneficiaries of war
But I still believe that the modern impulse to start a war comes indirectly from weapons suppliers, mostly companies squeezing tens of billions of dollars through political lobbying in their favor. Think about it; Lockheed Martin’s annual revenue in 2025 increased by 6 percent to $75.0 billion. Add a few more defense contractors to the list – Boeing, Northrop-Grumman, RTX Corporation, and General Dynamics – and you see the extraordinary stakes in continuous contracts. Add a few more suppliers to those six behemoth companies to understand that the web of weapon manufacturers would not stand idle in accepting peace throughout the world. However, those companies must adhere to the U.S. Arms Export Control Act, which requires governments receiving weapons from the U.S. to use them for legitimate self-defense. [9][10] In addition, American arms manufacturers and dealers are required to submit documentation of trade with international parties and are prohibited from selling sensitive technologies.
That same act also places certain restrictions on American defense suppliers, prohibiting them from selling certain sensitive technologies to certain parties and requiring documentation for such trades to trusted parties. Of course, honestly, none of those companies donate directly to political parties, candidates, or political committees. They comply with all laws and regulations connected to political and public policy issues. They do, however, support Political Action Committees (PACs) that contribute to federal and state candidates, political committees, party committees, and other political organizations through exclusive voluntary contributions from employees and directors. Interestingly, those contributions, averaging approximately $14 million a year in the last decade, have been almost evenly split among government parties.[11] However, General Dwight Eisenhower, when leaving office three days before the end of his term in office, gave Americans a warning through a farewell message of final thoughts on January 17, 1961:
“We have been compelled to create a permanent armaments industry of vast proportions.… This conjunction of an immense military establishment and a large arms industry is new in the American experience.… Yet we must not fail to comprehend its grave implications.… In the councils of government, we must guard against the acquisition of unwarranted influence, whether sought or unsought, by the military-industrial complex. The potential for the disastrous rise of misplaced power exists and will persist.” [12]
It was a 10-minute speech on national television that surprised everyone: the dangers of what he called the “military-industrial complex.” Eisenhower was telling Americans, and future presidents, to watch out for the pressure to spend and build a massive industry excused by an impending arms race in an imminent Cold War.
And here we are. That warning played out in a concealment to build that industry. Today, we have a military with a yearly budget of approximately $1 trillion, 18 percent of the total U.S. Federal budget for fiscal year 2026. Undeniably, the United States is the strongest military in the world. And yet, it has lost three wars since WWII: the Vietnam War, the War in Afghanistan, the Korean War (an armistice agreement), and now, inevitably, the Iran War. What would that mean when the best military lost three wars with relatively small countries? To be clear, North Vietnam had Russia and China as war sponsors, funding this war and supplying ammunition.
Military Spending [13] Source: SIPRI Military Expenditure DatabaseSIPRI | World military expenditure of the 15 countries with the highest spending in 2024 Author: UpdatesSIPRI licensed under the Creative Commons Attribution-Share Alike 4.0 International licenseMilitary spending by country, billions of dollars. Largest spenders labeled Source: https://www.iiss.org/publications/the-military-balance/2025/defence-spending-and-procurement-trends/ Creative Commons CC0 1.0 Universal Public Domain Dedication
Two leading military spearheads misconstrue the acumen of war
“The Naval Blockade remains in full force and effect,” Trump wrote on Truth Social on August 18th. “The Hormuz Strait is open and operating. All water mines have been removed or detonated.” There is very little truth in what he forwards in frustration to end his unpopular war that has brought inflation trouble to Americans, a war he foolishly started. No! Few ships pass the channel, and some still come under fire from Iran. And when Pete Hegseth, the United States Secretary of Defense, says, “We fight to win, and we don’t waste time or lives,” he misconstrues the point of war. War is not about winning. The only possible humanitarian justification for war is honest defense, not to win but to compromise, benefiting all sides. America, owning the world’s biggest and most equipped military, perhaps under premature assumptions, may have lost its war with Iran. With 3,000 Iranians and 18 U.S. service members killed, Americans should ask: What was this war for? The international rumor mill claims that this war is lost; maybe not, but surely not a “win,” whatever that means, because this administration has missed the principal principle: know your enemy. Trump should have known that Iran is not an easy target. Its resilience and adaptability must have been either a surprise to U.S. intelligence, a wild, insane idea coming from the noise in the president’s brain, or simply an ignorant plan to attack without an exit plan.
Who started the war against Iran?
America has foolishly and ignorantly started a war on a country with the second-largest population in the Middle East – 93 million. It wasn’t started solely by Trump’s lifelong urge to fix the Middle East. Let’s remember that Benjamin Netanyahu, the Prime Minister of Israel, who for decades planned to annihilate Iran, may have played Trump in convincing him to have the U.S. and Israel jointly plan and coordinate an attack on Iran. But now, Israel is concentrating its military objectives elsewhere.
With no understanding of the nature of Iran and ignoring advice from his daily intelligence briefings, the man who came to fame from a reality TV show, which was not reality, smugly went ahead anyway to damage Iran, inadvertently also damaging America by causing high inflation for at least a year, when fuel and groceries are already too high for many Americans. His habitual belligerence led him to think that the U.S., with its legendary superiority, would easily win a war with Iran, simply because the U.S. military budget is 135 times that of Iran’s. It is not just Trump’s ignorance. Where are the generals at the Pentagon, who must have known, given the evidence and lessons behind Russia’s foolish invasion of Ukraine that changed the conventionally assumed intelligence behind how wars could be won by astute planning or cleverness with cheap drones that outlast defense interceptors? After six months of war, Iran has drawn down the number of stockpiled American weapons to an alarming low, so low that the U.S. is “nearly out of certain long-range missiles.” [14] That statement, pointing to diminishing air-defense interceptors, brings with it a deterrence problem: adversaries, now seeing American weakness, are likely assessing their future military plans.
According to the Center for Strategic and International Studies, “the military has used up about two-thirds of its Patriot interceptors’ defensive weapons against incoming fire.” Russia, China, and North Korea are watching, as one $4 million Patriot PAC-3 MSF interceptor missile or one $14 million Terminal High-Altitude Area Defense (THAAD) missile takes down a single Iranian Shahed-136 drone costing approximately $35,000.
Wars have costs; this one, aside from casualties and killings, is running through defensive weapons. Iran’s cheap drone plans, along with blocking the Strait of Hormuz, have been ingeniously accomplishing what should have been understood before Trump started the war that he should have known he would lose. Of course, Mr. Trump will deny this report, and so it must be fake news. “So,” says Phillips Payson O’Brien, an American historian of war studies at the University of St. Andrews, Scotland, “the fact that they start a war that they did not understand – they thought it would be a short war – and before they know it, they’re in a longer war that’s going on for months, and they’re using up weapons in a way they never conceived of, and that’s where we are.” [15]For now, Trump is happily not completely using up rocket launchers and air defense systems that are protecting military personnel at U.S. bases around the Middle East without having to use them to keep the Strait of Hormuz open. He cannot win his war without ground troops, a risky plan that would expose soldiers to casualties and body bags.
For those reasons, he knows that he cannot win, partly because Iran holds the cards he thought he had. With the U.S. economy affected, he knows that his only hope is to get out and declare a win. But most of the world will know that if that war is not a loss, then we can expect it to either end as a humiliating defeat or another of those forever wars that the U.S, starts and does not finish.
A non-fictional tragedy
Did the U.S. military have a plan before entering a war in Iran, risking the lives of military service members and making the Gulf less safe, with any clue as to how to get out of it? Consider this: when we talk of military deterrents, if China were to attempt a takeover of Taiwan, the United States would have to relinquish its military power over the Asian Pacific. Would the United States be ready and able to intercept thousands of Chinese drones in the first few days, and be left with no protection by day three? Keep in mind that China is the largest drone manufacturer in the world. [16] It is watching the depletion of U.S. weapons interceptors.
Trump threatens to destroy Iran if it refuses. Public Domain Shajareh Tayyebeh school bombing rescue in Minab, a city in southern Iran Source: Mehr News Agency Creative Commons Attribution 4.0 International License. Author: Abbas Zakeri
War is always complicated, more complicated than chess or Go. The Pentagon has tens of thousands of agents and hundreds of spies overseas collecting intelligence on every country that is hostile to the U.S., compiled for the Defense Intelligence Agency (DIA) to produce intelligence content for the President’s Daily Briefing, and yet, for some unknown reason, with such an enormous analysis of espionage information, the most powerful military in the world made a terrible mistake by blundering into a war with Iran. Trump’s destructiveness connected to his war is aimed at Iran, but the world will suffer too. According to the International Monetary Fund, it will upset the global economy and disrupt energy supply chains, causing inflation.
Starting with Trump’s bogged-down war 10,000 km away from the U.S. homeland, and a war with its own people at home, we must wonder why he started a war with Iran and why he cannot end it. Some cause-diggers, including me, have said that sooner or later he will do something so outrageous that he will politically checkmate himself and his favored friends and family forever. And now, he has done it. Ignoring the history of former presidents’ thoughts on a possible war with Iran, his flying whims or expansionist dream obsessions influenced his risks of starting a war with a country with a population of 93 million inhabitants, a massive entanglement of leaderships, and a strait that can easily stagger the world’s economy. He got away with his illegal gun war with random attacks on Venezuelan boats, and so he did what he always had done when feeling empowered with a minor success: risk a more daring move. A casino, airline, university, tie line, steaks, gold phones, bibles, gold coins, screwing laborers who worked for him, and let’s not forget not paying taxes – all failures through grifts or abandonments. What will he do with his latest war failure? Will it end in grift (another golf property in Tehran) or simply a military loss claimed as won – both deceptions.
Some wars are caused by ambition, some by greed, some by revenge, some by opportunity, and some for ridiculous reasons.
Speaking to reporters on Air Force One, Trump said, “We’ve decimated their whole evil empire, a total and complete victory.” And yet, Iran was able to survive and stand against the most powerful army in the world using strategic advantages that previous U.S. presidents understood as strong deterrents that would take many lives on both sides of a war. Trump either doubted Iran’s advantage, given the Strait of Hormuz, or he didn’t know enough about the strait’s blocking power. Surely, his intelligence briefings highlighted those powers. Iranians are not stupid; they know many of the intricacies of the U.S. military plans. They forced a significant reduction in U.S. munitions and kept control of the Strait. So now, with Tehran’s confidence, Iran will rise again, fully reshaped with a younger generation of leaders and Ahmad Vahidi, commander of the Islamic Revolutionary Guard Corps (IRGC). They now know they can defend themselves against a fierce power and weaken American positions in the Middle East.
Snatching defeat from victory
America has made mistakes before, but this war with Iran could have been a success had the 12-day war in June 2025 continued with clever insight. Instead, the eight months between the first war and the second gave Iran enough time to strengthen and change its strategies by decentralizing executive decisions from Tehran to multiple regional hubs. Big mistake, America! These new IRGC leaders “look at Iran’s weaknesses frequently and publicly – something the founding generation was too insecure to do honestly – and they treat them as problems to be solved. That instinct drove the changes Tehran made between the two wars.”[17] The U.S. missed its chance to corner Iran’s technocrats that, in eight months, masterfully learned how to use data-driven solutions to balance a weighted military battle with “organizational discipline and resilience.” Trump learns the hard way by instinctively pushing forward with hopes of triumph that rarely emerge without destruction. Iran, on the other hand, has been learning to cleverly see five steps ahead by using the Strait of Hormuz, a guerrilla force, scattering its missile launchers beyond reach, and firing swarms of cheap one-way decoy drones that successfully deplete U.S. interceptors. “The Iranian military had learned,” Narges Bajoghli and Vali Nasr wrote in the July/August issue of Foreign Affairs, “not just to absorb punishment, but also to win strategic advantage by frustrating its adversaries’ war aims.”
Next, Trump’s instinct is to wage an economic war against Iran. This plan could have worked before he started the bombings, before he messed up America with threats and killings, causing inflation and bolstering his prime adversary. Veering from bombs to severe sanctions is too late. He is stuck in a weakness, being vulnerable to Iran’s pressure to escalate the war to show the world that the strongest military in the world lost another war by misjudging how wars are won or lost. If lost – and that’s a premature opinion – we can chalk up this American war to a foolish president’s uninformed urge. For centuries we have known that one man (and I do mean man) can mess up the world while searching the earth for personal gain. Democracy got him into office; let’s hope his messes are short-lived.
Joseph Mazuris an Emeritus Professor of Mathematics at Emerson College’s Marlboro Institute for Liberal Arts & Interdisciplinary Studies. He is a recipient of fellowships from the Guggenheim, Bogliasco, and Rockefeller Foundations, and the author of eight acclaimed popular nonfiction books. His latest book is The Clock Mirage: Our Myth of Measured Time (Yale).
What do the collapse of the Japanese currency and carry trade—and the interventions by US Treasury Secretary Bessent in the currency and bond markets in recent weeks—have to do with the emerging financial crisis of the American Empire?
In August the US Treasury Bessent intervened in global currency markets to buy Yen to keep it from falling. Moreover it did so by buying Yen with Euros instead of US dollars. Bessent quickly followed that currency intervention with an accelerated buying back of US Treasury bonds, doubling buyback from $4 billion to now $8 billion a week.
What do these two seemingly separate actions by Bessent and the US Treasury have to do with today’s emerging financial crisis of the American Empire?
The Yen, the Dollar and US Treasuries
The Yen had been declining in relation to the US dollar. That meant Japan import prices, and in turn general inflation, had begun to rise in Japan. With inflation the price of Japan government bonds had begun to fall. Since the price and yield (i.e. interest rate) on bonds are always inversely relation, the interest rate on Japan government bonds began to rise in turn. From a level of virtually zero for years, the 10 year Japan government bond rose to nearly 3%.
Now that the yield on Japan bonds began to rise, Japan investors began investing in Japan bonds. When for years Japan bonds provided no yield, investors bought US Treasury bonds. A lot of them. More than $1 trillion.
But with Japan bond rates up and investors starting to buy Japan government bonds, money capital now threatened to turn from buying US Treasury bonds—yielding around 4% and thus roughly the same as Japan’s bonds—to buying Japan bonds instead. In other words, demand for US Treasuries threatened to decline as investors turned from US to Japan government bond purchases.
Why is this important?
Lower demand higher supply both mean falling prices for US Treasuries and, in turn, rising long term US bond interest rates.
Because Japan had become by 2021 the largest purchaser of US Treasury securities among foreign holders, eclipsing China. Launched by Trump in 2018, the US trade war, sanctions, tariffs, etc. against China led to China in 2021 to start sharply reducing its holdings of Treasuries. Once holding $1.26 trillion in 2020, by 2026 China has reduced its holdings by half to $633 billion, allowing its Treasuries to ‘roll off’ after they matured and not purchasing new in any quantity. Japan had replaced China as the single largest country holding US Treasury securities.
Japan kept its holdings of US securities at more than $1.1 trillion throughout the period. Should it begin to buy fewer Treasuries—or worse start selling off its Treasuries—that would blow a second hole in US Treasury sales by foreign investors joining China.
Foreign investors (governments, central banks, private banks, corporations, etc.) hold about a third of all Treasuries outstanding today. They held approximately $9.2 trillion or 32% of all Treasuries outstanding at year end 2025, up from $6.8 trillion at start of 2020. For purchasers of US securities are critical for the US economy. New Treasury sales are the most important source for financing (paying for) the US annual budget deficit—and foreign purchasers constitute a significant one third.
Since 2020 the US budget deficit has ballooned, driven mostly by even faster acceleration of defense spending while Congress has massively cut tax revenues—i.e. the other potential source of budget financing which has been declining.
Pentagon spending has risen from $914 billion in 2021 to $1.15 trillion in 2025. US wars by year end 2026 will raise that to $1.4 trillion. Trump has asked for another $500 billion for defense in 2027. And that’s only Pentagon spending. Total US defense/war spending was $2.2 trillion in fiscal year 2025, when other defense related spending for veterans benefits, CIA, military aid, nuclear weapons development and other categories are included.
Given that tax revenues were cut $5 trillion by Trump in 2025 and thus a lid put on tax revenues as a source of funding the accelerating US defense spending and US budget deficit, sales of Treasury securities are increasingly important to fund the rising costs of Empire and exploding US budget deficits.
The US has continued to run massive budget deficits averaging more than $2 trillion a year since 2020. In past decades before 2000, the US used to cover its deficits with economic growth and tax revenues. But growth has slowed sharply since 2020, on average barely 2% per year, and tax cuts for corporations and investors have accelerated. So Sales of US Treasuries have been key to financing the annual $2 trillion plus US budget deficit.
Should foreign buyers of Treasuries continue to buy fewer Treasuries, like China has been doing, or worse, start selling off their Treasuries—how will the US finance its annual $2 trillion and rising budget deficit?
The US will have to either cut spending, raise taxes, or sell more Treasuries to domestic US buyers. But to sell more domestically, it will have to entice US domestic buyers to do so. How? By increasing the interest rate on the Treasuries it will pay them if they buy more.
Which brings us back to the recent events regarding Japan, its Yen, and its increasingly competitive Japan government bond rates that offer interest rates to buyers nearly equivalent to US Treasury bond rates.
Japan is about to sharply reduce its purchases of US Treasuries. That means less global demand for US Treasuries. At the same time, Japan has started selling off some of its $1.1 trillion hoard of Treasuries. That increases the supply of Treasuries globally. Lower demand higher supply both mean falling prices for US Treasuries and, in turn, rising long term US bond interest rates.
Why is Japan selling its US Treasuries? In order to intervene to prop up the Yen, Japan’s central bank since July 2026 has begun selling off part of its $1.1 trillion stock of US securities. In fact, since July 2026 Japan’s central bank has dumped(sold off) more than $90 billion of Treasuries. It’s done so in order to raise cash with which to buy its own Yen in global markets to keep the Yen from falling.
In short, the falling Yen and rising Japan bond rates is threatening to sharply reduce the sale of US Treasuries and is throwing excess supply of US Treasury securities onto the market—both destabilizing the $31 trillion US Treasury market.
Bessent’s Yen Intervention with Euros
To assist Japan—and discourage it from selling even more US Treasuries—US Treasury Secretary Bessent last month intervened in global currency markets and started buying Yen to assist Japan trying to prop up the value (price) of its Yen. But that’s just the appearance. The real Bessent objective is to assist Japan to prevent it from selling off even more US Treasuries.
In an interesting twist, Bessent didn’t enter the global currency market to buy Yen with dollars. He used the US Treasury’s stock of Euros currency to buy Yen. That may have temporarily helped Japan, but it undermined the value of the Euro and European economies. That did not make the Europeans too happy.
On August 30, 2026 Bessent bragged the US action had stabilized the Yen. But evidence suggests otherwise. The Yen is likely to continue to fall below the benchmark Yen-Dollar exchange of 160 to the $1. When it does, Japan will likely dump (sell) more of its US Treasury holdings in order to buy more of its currency to prop it up. That means Japan, like China, will reduce its holdings of US securities well below the $90 billion it already expended since July. If it’s selling Treasuries it’s certainly not going to buy more. So both Japan’s demand and supply of Treasuries will push up US long term Treasury bond interest rates. US long bond rates are already at 5.3%! They’ll likely go higher now.
That will pull up US mortgage rates. So US consumers can forget about US housing affordability before the US November elections. It’ll get worse, not better. It’s already happening.
To sum up: the Japan Yen instability—and the joint interventions by the bank of Japan and the US Treasury to stabilize it—will likely lead to Japan, like China, selling off existing stock of US Treasuries and buying fewer of the same.
If both China and Japan are buying fewer and dumping more, who will pick up the slack in Treasury security sales—the key source for financing the US budget deficit, now at $2 trillion and projected to rise even more?
Since 2020 it has been the Europeans who have offset China’s sell off of Treasuries to enable the continued financing of the US deficit gap. Surprised by that? It’s true.
The question, however, is whether the Europeans will now buy even more Treasuries to offset the China, and soon Japan, decline in Treasuries?
Here’s what the Europeans did from 2020 through 2025:
The UK increased its holdings of Treasuries from $412 billion in 2020 to $865 billion in 2025. Belgium (the location of the EU clearing house bank) increased from $135 billion to $466 billion. Luxembourg from $197 to $431 billion. France from $49 billion to $376 billion. In other words, the Europeans more than offset the loss of China purchases of US Treasury securities. They offset China and bought more to enable the US to finance its chronic $2 trillion deficit since 2020.
Perhaps the US paid for most of the cost of the Ukraine war through 2024 with the understanding the Europeans would in turn buy more US Treasuries?
The question is will Europe continue? The US Trump administration relationship with Europe is not the best and is getting worse. The US has pulled back (financially) from support of the Ukraine war, turning over the cost of financing it to the Europeans. The latter in turn have had to raise $90 billion in Euro bonds to fund Ukraine, with talk of another $70 billion coming. If they have to raise $160 billion for their ‘Project Ukraine’ war, will they also continue buying Treasuries at the pace they had 2020-2025? Can they even do so? And if Trump intensifies the dispute with them over Greenland, will they want to?
In short, for both economic and political reasons it is unlikely the Europeans will continue to fill the gap in declining Treasury purchases by China and now potentially by Japan as the latter continues to sell off its Treasuries in order to support its currency.
Which brings us to the second recent US Treasury market event: Bessent’s injecting of another $4 billion a week into the US economy by doubling the rate of Treasury buybacks of US bonds already held by investors.
Bessent’s $8 Billion Weekly Buybacks
What does Bessent’s buyback scheme mean for the US deficit, rising US interest rates and the emerging financial crisis of Empire as well?
Bessent bought Japanese Yen with Euros because he was obviously saving his US dollars to buy back US bonds held by US investors.
Buying back US bonds results in dollars injected into the hands of investors who previously held the Treasuries. Less supply of bonds in the market means a higher price and thus in turn a lower yield or interest rate on long term Treasury bonds.
But the effect of Bessent’s action will prove negligible. $4 billion more a week, even over ten weeks ($40 billion), won’t budge the roughly $31 trillion US Treasury market. He surely knows that. So why did he do it?
Here’s where the current US Artificial Intelligence investment bubble enters the picture. The AI boom is devouring available money capital in the US. The big 9 tech company, so-called ‘hyperscalers’, are gobbling up investment capital borrowing hundreds of billions of dollars to fund their current massive AI investment. In 2025 the big 9 tech corps spent an estimated $500 billion on AI investment (in data centers, apps, chips, etc). This year 2026 the estimate is $1 to $1.5 trillion. Next year, another $1 trillion. And that’s only the big 9. The rest of corporate America is running pell mell off the cliff into AI investing as well. (Many will go bust when the AI bubble crashes in the next 12-18 months, I predict, but that’s another story).
Less supply of bonds in the market means a higher price and thus in turn a lower yield or interest rate on long term Treasury bonds.
That massive AI investment is being financed out of various sources. The hyperscalers are committing their former massive hoard of cash. They are in addition issuing more equity (stock) to raise cash. They are signing long term huge leasing deals and commitments. And they are raising debt—i.e. borrowing. The debt component of the total spending is estimated at over $200 billion this year alone. In other words, they are sucking up most of the available investment capital to finance their AI plans.
In the process they are crowding out other US investment, driving up interest rates. They are also potentially crowding out US investors’ purchases of US Treasury securities—at a time of foreign holders of Treasuries reducing theirs as well!
So Bessent is injecting $40-$80 billion or more in 2026 in extra liquidity into the US economy—in part to assist the massive AI lending by banks but in part as well to provide sufficient dollars for US investors to purchase US Treasuries.
The connection between the Japan Yen intervention and the US bond buybacks is that they are both actions intended in the end to enable the continued purchasing of US Treasury securities—as the US Empire’s defense costs continue to accelerate and the US needs to sell even more Treasury securities in order to finance its accelerating defense spending and budget deficits.
Summary
The takeaways from all this are:
Japan’s Yen will continue to weaken. Both its central bank and US interventions will not succeed even intermediate term. The Yen will continue to fall below 160 and Japan will have to continue to sell Treasuries in order to prop up its currency
The combination of China, Japan (and likely Europe) slowing of Treasury purchases will mean demand for Treasuries will slow, prices decline and therefore long term US bond rates rise
Federal Reserve chair Warsh will follow the market-driven long term bond rate rise by raising Fed short term rates eventually as well
The US economy, already slowing (except for AI investment) will slow even more as rates increase. US job creation, already flat, will decline further in turn
Big Tech will chase the AI investment bubble into 2027, absorbing money capital, crowding out other investment and driving up US interest rates further until the market side of the bubble busts in late 2027-28
Aggregate US Treasury sales by foreign buyers will slow, as US budget deficits rise even further as US defense spending continues to accelerate (Pentagon $1.5 trillion; total defense spending all sources $2.5 trillIon).
A crisis in the Empire’s financing of rising deficits and debt from Treasury sales will force the Empire to choose one or more of the following: to reduce war spending, raise taxes, or (most likely) intensify austerity by cutting social programs even further.[1]
Gaza showed the genocidal face of Israel’s expulsive strategy. In the West Bank, the same objective is realized with incremental escalation. The ultimate goal is the same – the final expulsion of the Palestinians.
Today, the West Bank is a nightmare of vicious settlement expansion, land seizure, economic strangulation, settler violence and forced displacement.
With the collusion of the Israeli military and police, the Israeli-occupied territories are effectively ruled by the Messianic far-right settlers who see their mob-like racist pogroms of Palestinians as a divine step to Final Redemption.
The ongoing year has accelerated the process from settlement expansion toward territorial consolidation and displacement. The scale is stark.
Displacement becomes systematic
The crucial point is not simply Jewish settler violence but its geographical and economic function.
By August 10, the UN reported 76 Palestinians killed in the West Bank, including 18 children; about 3,800 Palestinians had been displaced during 2026 through settler violence, demolitions and evictions, nearly half children.
More than 1,430 settler incidents had been recorded, affecting roughly 260 Palestinian communities.
The crucial point is not simply Jewish settler violence but its geographical and economic function. Settler attacks increasingly target homes, agricultural land, livestock, water and electricity infrastructure.
In a recent podcast, Israeli National Security Minister Itamar Ben-Gvir, a far-right extremist who believes in Jewish racial supremacy, urged Israelis to kill “30 to 40” Palestinians in Gaza every night. He also supports aggressive, lethal actions against Palestinians in the West Bank, applying a similarly hardline approach through legislative, judicial, and security policies.
These statements no longer reflect a “lunatic fringe,” as often portrayed by the media in the West. They reflect the brutal repression of Palestinians that’s now the new normal. OCHA reports that displacement caused by demolitions, settler violence and access restrictions has averaged 17 Palestinians a day in 2026; twice the average of the preceding three years.
Since 2023, 127 communities have experienced full or partial displacement; 47 have been completely emptied.
The economic damage compounds the demographic pressure. UNCTAD estimates that West Bank GDP contracted 17% in 2024, while cumulative unrealized Palestinian GDP from occupation-related restrictions between 2000–24 reached $170.8 billion—about 17 times 2024 West Bank GDP.
The settlement economy in Area C and East Jerusalem, by contrast, generated an estimated $53 billion in 2024.
Great conjuncture
Right before Hamas attacked Israel on October 7, 2023, I warned about an impending war, as the status quo was approaching a boiling point in Gaza. After all, it was the 50-year anniversary of the Yom Kippur War.
In The Fall of Israel (2024), I used the term great conjuncture to refer to structural forces that account for a series of cumulative disasters in the Middle East, starting with the waves of Palestinian expulsions since the 1940s.
Second, it refers to the aggressive expansion of the Jewish settlements in the occupied territories. The rise of the Messianic far-right has fostered settler militarization accelerating anti-Arab pogroms in the West Bank, which is being annexed into Israel.
Third, the great conjuncture is fueled by a half century of failed American diplomacy in the Middle East. The Fall of Israel showed how the US-Israeli ties moved from hedging and choosing sides to partnership and eventually a symbiosis. These are not ties that bind, but ties that blind. They account for 50 years of military destabilization in the region and U.S. complicity to genocidal atrocities, even ecocide – both in Gaza and Lebanon.
Finally, instead of fostering peace in the region, America’s massive military aid to Israel has amplified Israel’s parallel securitization degrading its economy, politics and military. Washington has provided at least $22 billion in direct military aid to Israel, alongside up to $12 billion spent on related U.S. military operations in the region, since October 7, 2023. From Gaza and beyond, Israeli authorities and security forces have deliberately targeted Palestinians and Palestinian children.
These four structural forces feed on each other forming a vicious cycle, thereby intensifying and broadening regional escalation. When I extended the argument into a book, these views were still seen largely as marginal. Today, things have dramatically changed. Even the bipartisan consensus over the U.S.-Israel ties has collapsed.
But this erosion came only after Gaza has been obliterated and ethnic cleansing escalates in the West Bank with the tacit blessing of the international community.
Ethnic cleansing from Gaza to the West Bank
In the Israeli occupied territories, ethnic expulsion has not been an accidental by-product but a recurring political mechanism. From Labor’s post-1967 Allon Plan through the Likud era and the Messianic far right, its logic has been cumulative as it has sought to
acquire territory;
fragment Palestinian space;
make Palestinian economic and social life increasingly unviable;
if massacres don’t suffice, use genocidal atrocities;
expand Jewish civilian presence;
and eventually convert temporary occupation into permanent sovereignty.
The objective is not simply “security,” nor even the exploitation of Palestinian labor, but the Judaization of territory and prevention of a sovereign Palestine.
Gaza became the extreme version: bombardment, destruction of housing and infrastructure, displacement and proposals for population “transfer” created conditions in which Palestinians were physically removed and territory becomes available for redevelopment or settlement.
In the West Bank, the mechanism used to be more incremental: settlement outposts, land seizures, demolition orders, restrictions on building and movement, settler violence and pressure on herding communities.
In the absence of international penalties, sanctions and blockades, settlers have been dramatically emboldened. They avoid one spectacular expulsion but seek to make the remaining Palestinian communities progressively untenable.
Their goal is the “Judaization” of Palestine – death by a thousands cuts.
Apartheid and “ultra-apartheid”
Not only has Israel evolved into an apartheid state. It is practicing ultra-apartheid.
Classical South African apartheid was brutally exploitative but effectively accommodationist. White minority rule sought to preserve racial hierarchy, segregate the black majority, deny political rights and extract cheap labor. The system needed the black population to remain economically useful. As a result, black South Africans’ income relative to whites actually rose during apartheid, from 8.6% to 13.5% between 1948 and 1994.
Israel’s system goes “beyond” apartheid. Palestinians are subjected to differentiated legal systems, military rule, checkpoints, territorial fragmentation, restricted mobility and unequal access to land and resources, while Jewish settlers in the occupied territory fall under Israeli civilian law.
The occupied territories consequently resemble South African Bantustans: fragmented enclaves, walls, restricted mobility and economic dependence.
But the decisive difference is the end-state. Israeli apartheid is not designed indefinitely to contain and exploit a Palestinian population. It is an interim instrument for displacement and dispossession. Segregation reduces Palestinian territorial, economic and political viability while expanding Jewish settlement.
That distinction also explains why the West Bank is strategically more important than it may appear. Fragmentation is not merely a condition; it is the mechanism by which territorial annexation becomes politically and physically irreversible. Hence the Israeli “ultra-apartheid”: that is, apartheid plus an expulsive logic.
And it is ultra-apartheid – first in Gaza and now in the West Bank – that the international community is witnessing yet trying to ignore.
Smotrich’s “Decisive Plan” for Gaza
Meanwhile, the political machinery has moved toward annexation. Israeli Finance Minister Bezalel Smotrich’s control over the Civil Administration, land declarations and settlement approvals institutionalize de facto annexation.
As documented by The Fall of Israel two years ago, Smotrich is executing a decade-old plan. In 2017, when he was still a young Knesset member, he presented his “Decisive Plan” in closed religious Zionist circles. It represented an endgame of sorts for the Israeli-Palestinian conflict.
The plan portrayed the conflict as devoid of any reconciliation. It rejected partition. It shunned any idea of a Palestinian state, or even Palestinian presence. Smotrich envisioned a singular state from the sea to the river, for one nation only: the Jewish people. True to his beliefs, he built on biblical allegories, which to him were no allegories at all:
When Joshua entered the land, he sent three letters to its inhabitants: Those who want to accept [our rule] will accept; those who want to leave, will leave; those who want to fight, will fight….
When they have no hope and no outlook, they will leave, just as they left in 1948.
Since October 7, Smotrich has championed his not-so-voluntary population transfer. The logic is simple: Eliminate the adversary, resolve the dilemma.
The approaching October 2026 Israeli election sharpens the incentive. The Knesset has dissolved and campaigning is underway. Today, four in ten Jewish Israelis favor full West Bank annexation and 55% want all settlements retained under Israeli sovereignty. That’s Netanyahu’s legacy.
As Israel approaches its October 2026 election, the question is no longer whether the occupation is becoming permanent, but whether the West Bank is being progressively emptied of Palestinians to make annexation irreversible.
The electoral center of gravity is not moving toward Palestinian statehood. It is moving further away from any reconciliation – with longstanding U.S. support.
Three West Bank scenarios
In the current status quo, there are three plausible future trajectories.
Accelerated annexation and “silent transfer” (most likely). The present trajectory continues: settlements expand, outposts become normalized, Area C is progressively absorbed into Israel, Palestinian construction remains restricted, and settler violence—mostly tolerated and inadequately restrained by the state—pushes vulnerable Bedouin and farming communities out.
There need be no formal annexation declaration. Facts on the ground accomplish the same result.
The UN’s 2026 reports verify the mechanism operating. Violence, demolition, restricted access, economic strangulation and displacement reinforce one another. The October election could strengthen this trajectory if Netanyahu requires the far right to construct another governing coalition.
Scenario II — Managed containment, not peace. A centrist or more pragmatic coalition emerges after the election and faces heavy U.S., European and Arab pressure. It slows settlement expansion, restrains the most provocative settler actions and restores some Palestinian economic access—but avoids dismantling the settlement architecture or recognizing full Palestinian sovereignty.
This would resemble a renovated Allon-plan/Bantustan model: Palestinian enclaves with limited autonomy surrounded by Israeli-controlled territory.
This could stabilize the system but only temporarily without resolving its underlying contradiction. But it would also set the stage for annexation by a subsequent conservative cabinet.
Scenario III — Rupture and international reversal. A major escalation—mass displacement, annexation, renewed Palestinian uprising, regional war, or a severe Israeli political crisis—could finally make the status quo untenable.
International recognition of Palestinian sovereignty, sanctions against settlement activity, economic pressure and an externally imposed political framework could halt territorial consolidation.
This is the least likely short-term scenario, but potentially the only route to reversing the trajectory.
The conflict can no longer be solved by Israeli-Palestinian bargaining alone. The asymmetry of power has made meaningful external intervention indispensable.
This is the least likely short-term scenario, but potentially the only route to reversing the trajectory.
Bottom line: Gaza shows what happens when the expulsive logic is pursued through overwhelming military force. The West Bank is demonstrating a presumably more subdued version: settlement, fragmentation, coercion, economic pressure and incremental displacement.
The decisive question after the October election is therefore less whether Israel will “annex” the West Bank formally than how much of it can be absorbed—and how many Palestinians can be induced or forced to leave or decimated in new genocidal atrocities—before the process becomes irreversible.
The original commentary was published by Informed Comment (US) on Aug 30, 2026.
Dr Dan Steinbock, an expert of the multipolar world, is the founder of Difference Group and has served at the India, China and America Institute (US), Shanghai Institute for International Studies (China) and the EU Center (Singapore). He is also the author of two new books on the Middle East crises: The Obliteration Doctrine (Sept. 2025) and The Fall of Israel (Oct. 2024). For more, see https://www.differencegroup.net/
Everywhere you look in New York, the clean energy transition is picking up speed. EV charging stations are being installed at a rapid clip, buildings are shifting away from fossil fuel systems, and state and city programs keep raising the bar on sustainability targets. It’s easy to get caught up in the momentum. But there’s a question hiding underneath all of it that doesn’t get asked nearly enough: who’s actually going to install and maintain all of this?
Richard Sajiun has spent his career answering that question. As CEO and master electrician of Sajiun Electric Inc., he’s watched New York’s infrastructure ambitions grow year after year, and he’s convinced that none of it works without enough skilled tradespeople to execute it.
Demand Is Outpacing the Workforce
Across New York, electrical contractors are busier than ever. EV charger installations, building retrofits, and grid upgrades have created a surge of work that shows no signs of slowing. The catch is that this surge is colliding with a labor shortage that’s been building for years.
Sajiun Electric has a long view of this problem. Founded in 1965 by Richard’s father, the company has spent six decades working on hospitals, government buildings, and commercial properties throughout the state. That history has taught Richard something the industry sometimes forgets: expertise doesn’t scale as fast as demand does.
“Electrical work has always been a trade built on mentorship,” he says. “The expertise required to complete projects safely and efficiently is learned over time through hands-on experience.”
That kind of experience takes years to build, and the pipeline is shrinking. Veteran electricians are retiring faster than new ones are entering the field. On a national level, the industry needs to fill approximately 81,000 electrical jobs every year just to keep pace, a number that hits especially hard in a state as construction-heavy as New York.
EV Mandates Are Raising the Pressure
Nowhere is this gap more visible than in New York City’s push around electric vehicles. Local Law 55 requires parking facilities to phase in EV charging infrastructure over the coming years, a mandate that will require sweeping electrical upgrades and thousands of new installations across the five boroughs.
Programs like Con Edison’s PowerReady initiative and the state’s Make-Ready program are designed to help businesses shoulder the cost of these changes. But Sajiun is quick to note that financial support only goes so far.
“Policies and incentives are important, but every project still relies on licensed electricians to carry out the work,” he says. “The challenge isn’t whether the technology exists. It’s whether there will be enough trained professionals available to install and maintain it properly.”
Put simply: funding builds momentum, but people build infrastructure. Without enough of them, timelines slip and ambitious plans stall.
Training the Next Generation
Sajiun’s answer to the shortage is investment in people, not just projects. At Sajiun Electric, new hires are paired directly with experienced electricians from day one, learning the trade through real fieldwork rather than classroom theory alone.
He’s careful to point out that the job is about more than technical skill. Working on the systems that power hospitals, government buildings, and now EV infrastructure requires a level of judgment and responsibility that can only be developed on the job.
“Becoming a skilled electrician takes time,” Sajiun says. “There’s no substitute for learning directly from experienced professionals in the field.”
As New York races toward its electrification goals, Sajiun argues that workforce development can’t stay an afterthought; it has to be part of the plan from the start. Every charger installed and every building retrofitted depends on someone with the training to do it right.
For Richard Sajiun, New York’s EV future isn’t just a question of infrastructure spending. It’s a question of whether the state is building the workforce to match its ambition.
Iranian trade has dropped sharply amid intensified U.S. sanctions and a naval blockade, with President Masoud Pezeshkian saying exports and imports have fallen by 25% to 35%. Supreme Leader Mojtaba Khamenei has called for greater economic self-reliance, increased domestic production and a gradual reduction in the role of the U.S. dollar.
The U.S. has launched a tougher sanctions campaign aimed at cutting Iran’s economic ties globally. The Treasury Department has targeted Banque Misr’s UAE operations over alleged links to Iran’s shadow banking network, while Iranian crude oil exports have plunged. Kpler estimates that Iran loaded about 260,000 barrels per day for export in August, more than 80% below the same month last year.
Despite the pressure, Iran says it has sufficient oil reserves and revenue to meet its budget needs while bypassing the maritime blockade. The standoff has now lasted six months, with the Strait of Hormuz remaining unresolved and no clear end to the broader conflict in sight.
By Danny Leipziger
China cannot continue to rely on exports to drive its growth, but what are the alternatives?
China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...
The World Financial Review uses cookies to improve site functionality, provide you with a better browsing experience, and to enable our partners to advertise to you. Detailed information on the use of cookies on this Site, and how you can decline them, is provided in our Privacy Policy and Terms and Conditions. By clicking on the accept button and using this Site, you consent to our Privacy Policy and Terms and Conditions. ACCEPT
Privacy & Cookies Policy
Privacy Overview
This website uses cookies to improve your experience while you navigate through the website. Out of these cookies, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may have an effect on your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. This category only includes cookies that ensures basic functionalities and security features of the website. These cookies do not store any personal information.
Any cookies that may not be particularly necessary for the website to function and is used specifically to collect user personal data via analytics, ads, other embedded contents are termed as non-necessary cookies. It is mandatory to procure user consent prior to running these cookies on your website.




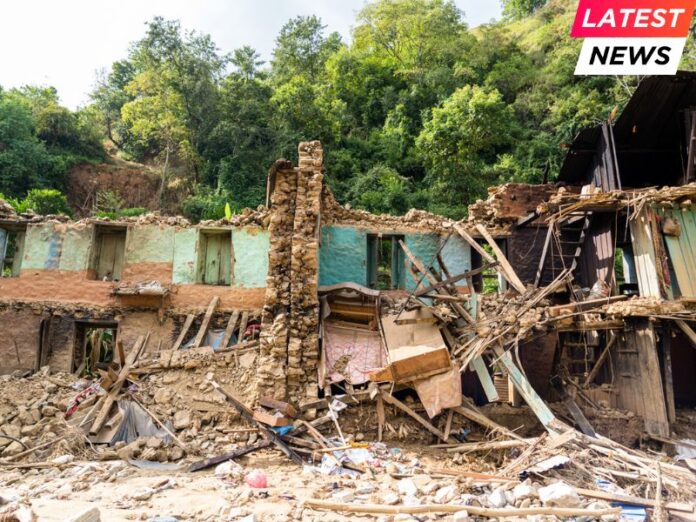
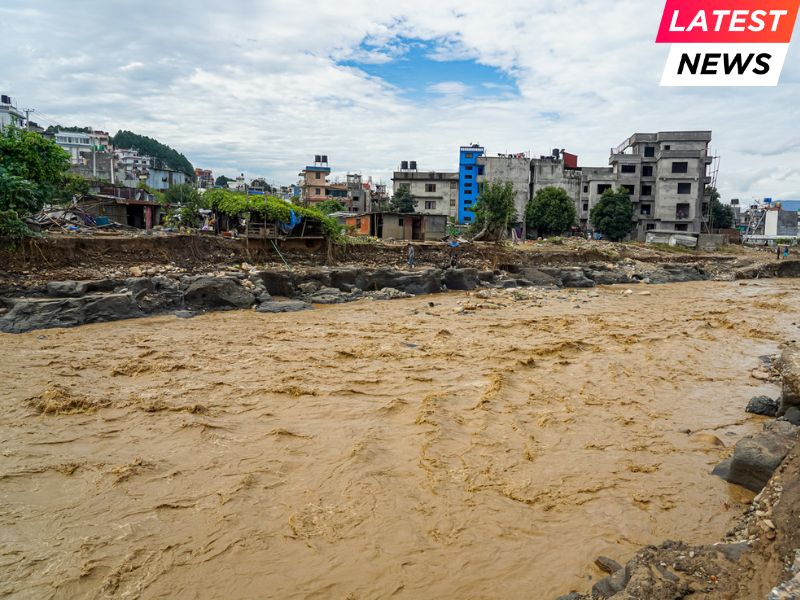
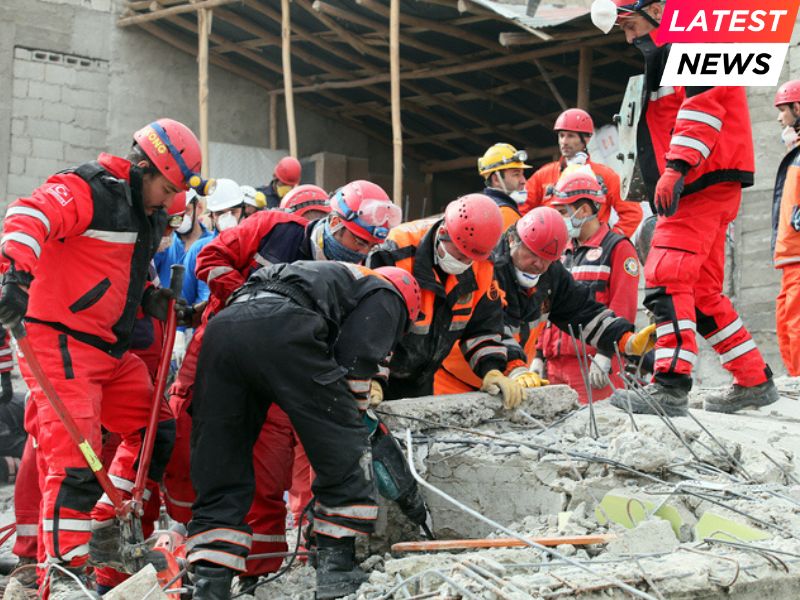

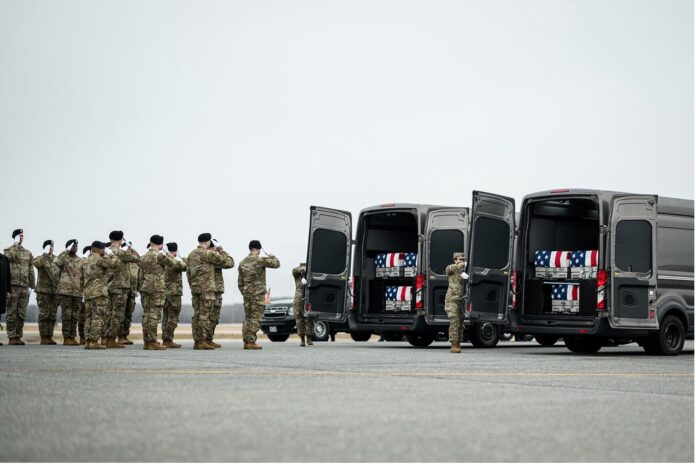
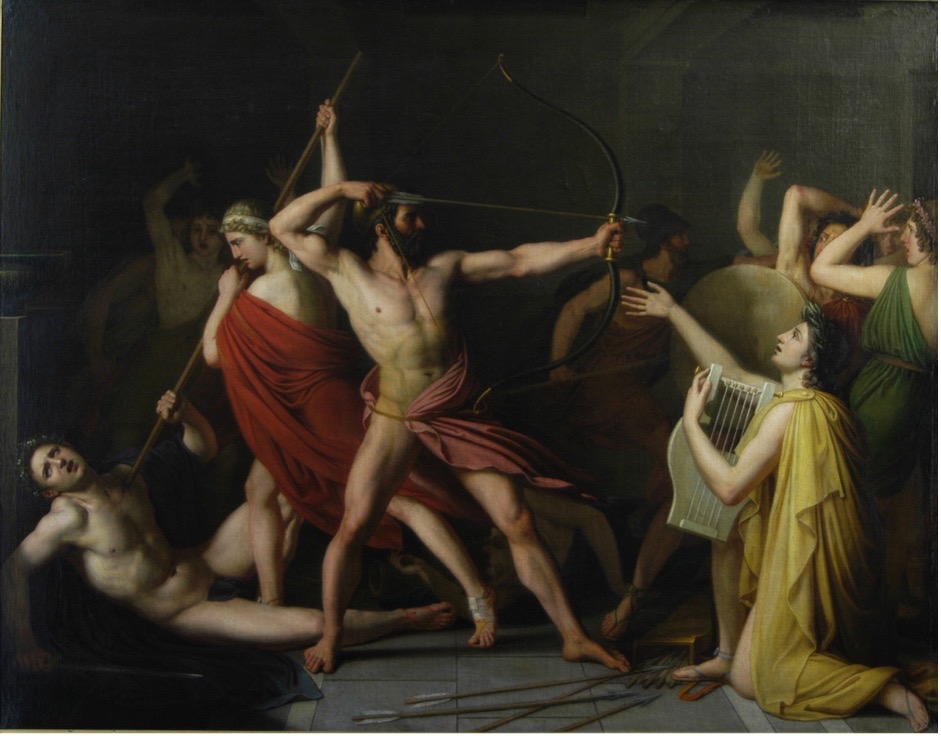
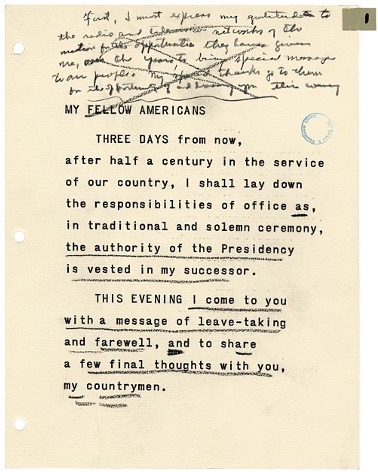 That same act also places certain restrictions on American defense suppliers, prohibiting them from selling certain sensitive technologies to certain parties and requiring documentation for such trades to trusted parties. Of course, honestly, none of those companies donate directly to political parties, candidates, or political committees. They comply with all laws and regulations connected to political and public policy issues. They do, however, support Political Action Committees (PACs) that contribute to federal and state candidates, political committees, party committees, and other political organizations through exclusive voluntary contributions from employees and directors. Interestingly, those contributions, averaging approximately $14 million a year in the last decade, have been almost evenly split among government parties.
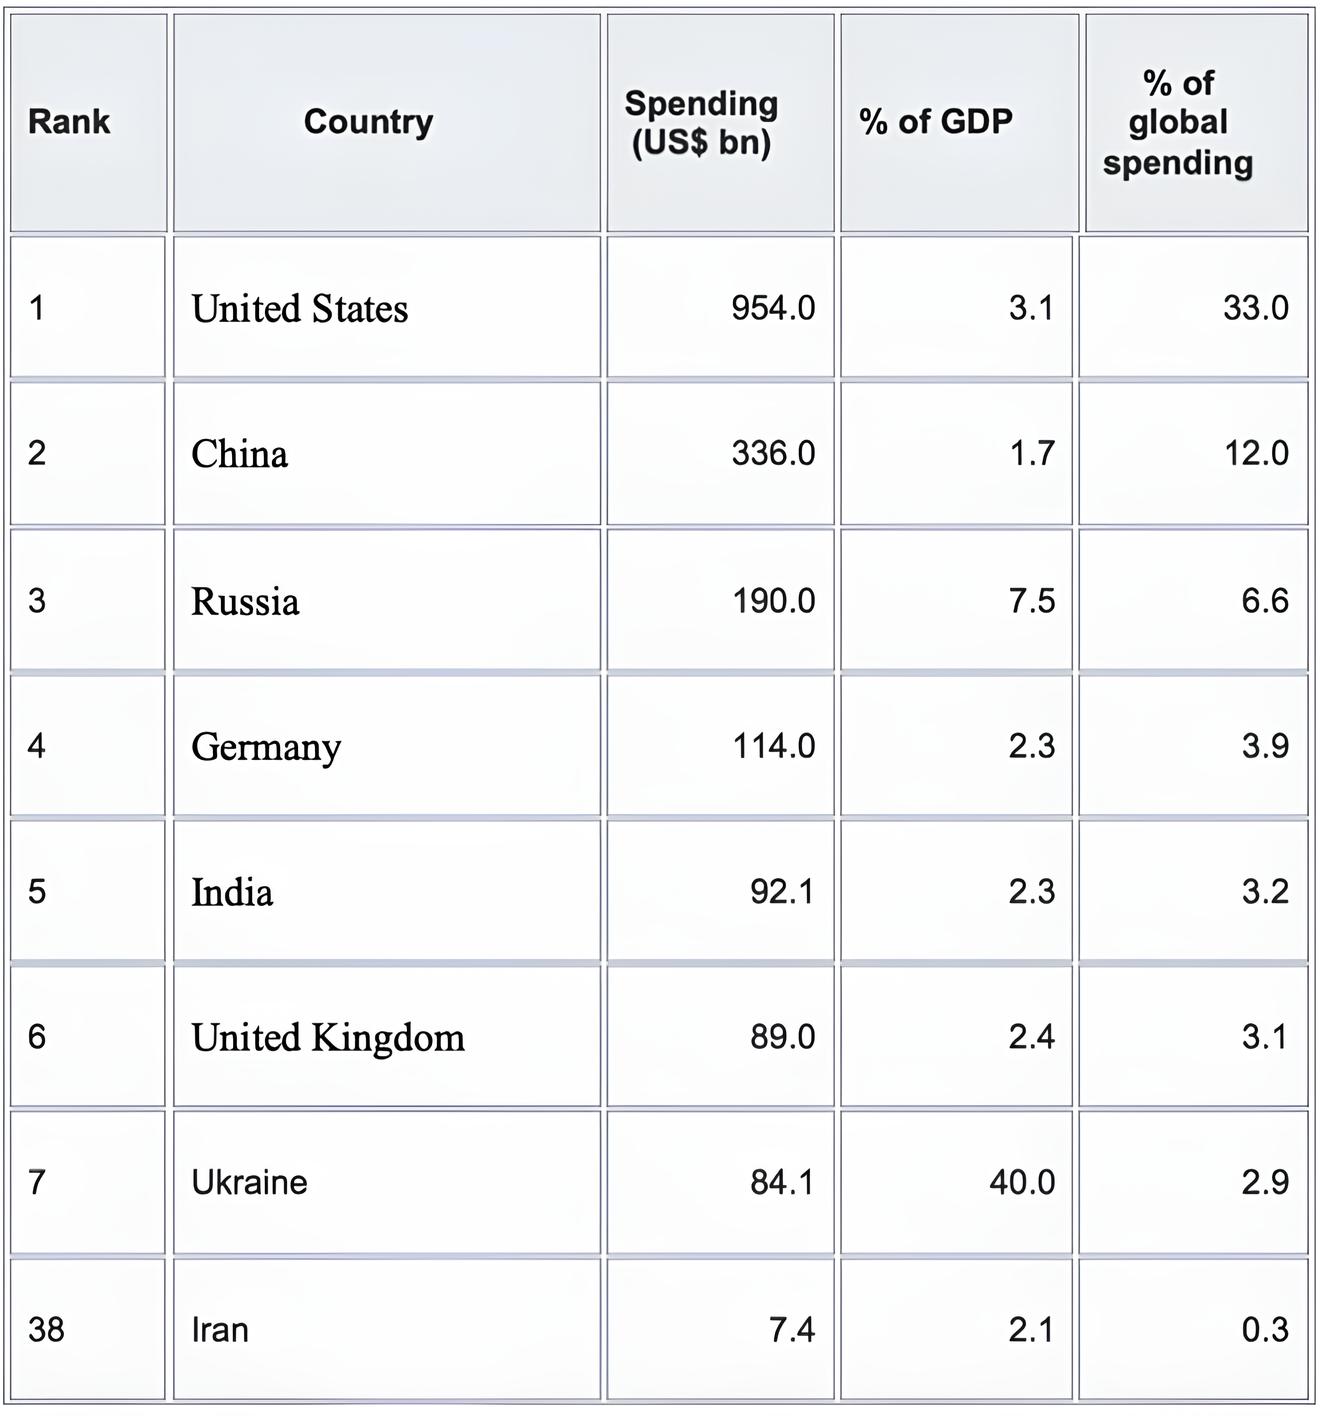
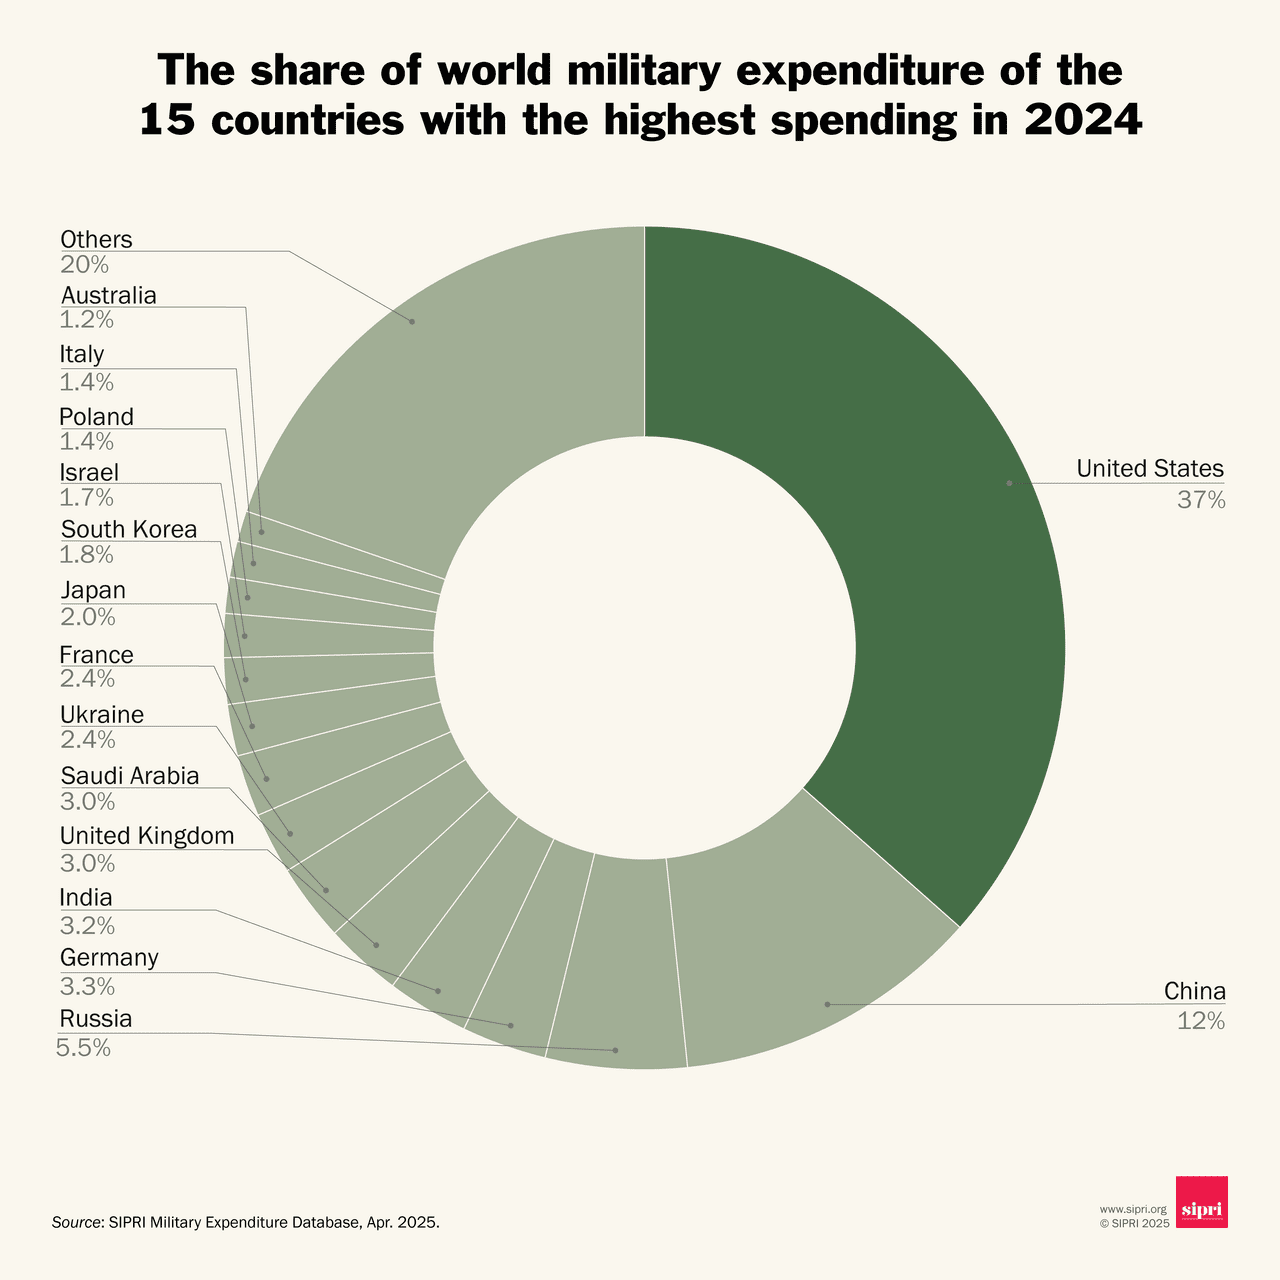
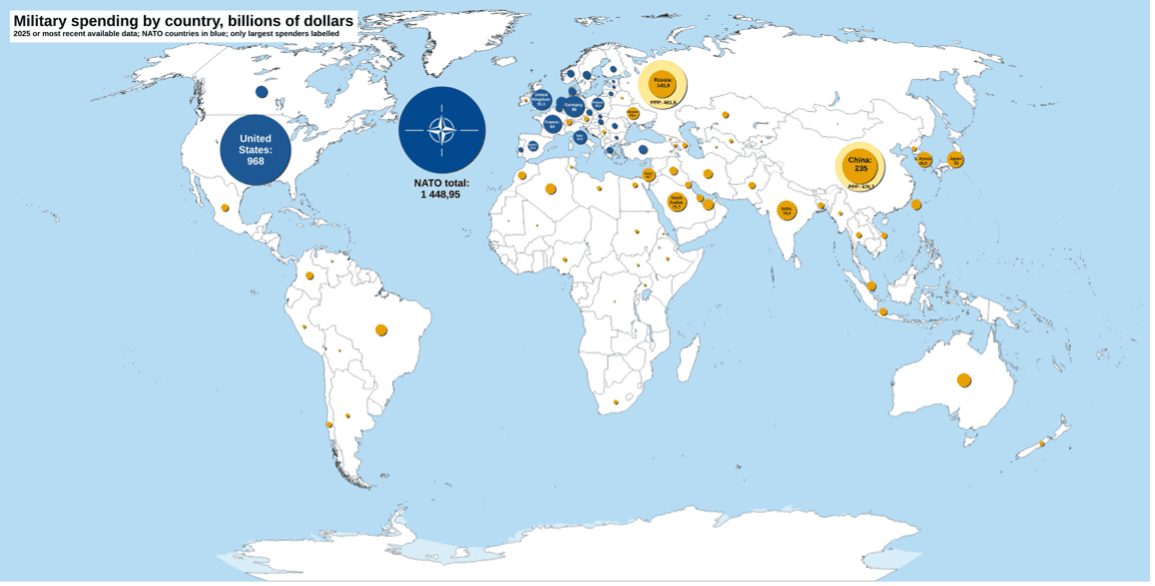
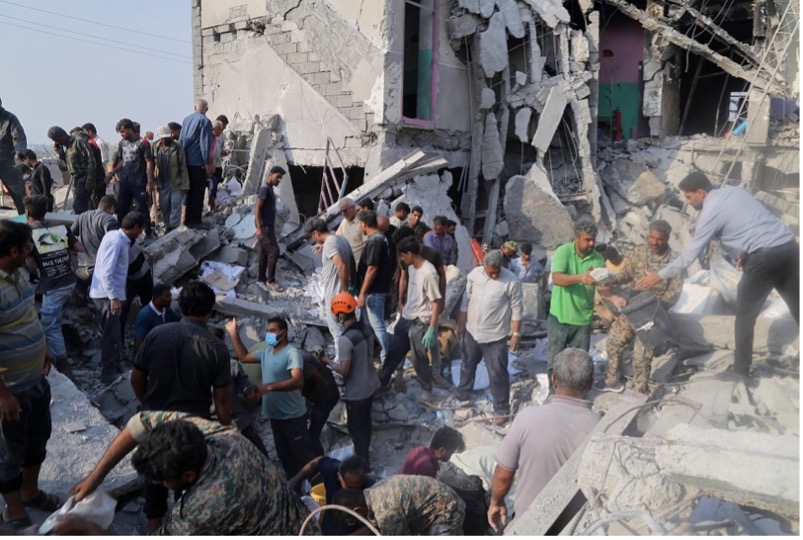
 Joseph Mazur
 Dr. Jack Rasmus
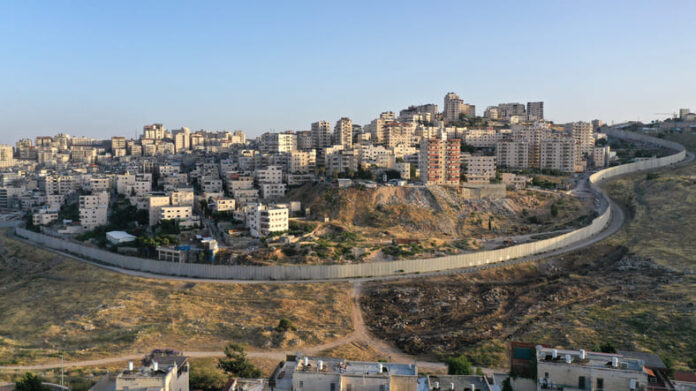
 Dr Dan Steinbock