Home Blog Page 11

How Foreign Investors Can Start a Business in Turkey

Turkey has become an increasingly attractive destination for international entrepreneurs looking to establish a presence between Europe, Asia and the Middle East. Its large domestic market, strategic location and developed manufacturing and services sectors offer opportunities for businesses across a wide range of industries.

For foreign investors, however, entering a new market requires more than identifying a commercial opportunity. Choosing the appropriate legal structure, completing registration procedures, complying with tax regulations and establishing proper accounting processes are important steps in creating a sustainable business in Turkey.

Choosing the Right Company Structure

Foreign investors can establish several types of business structures in Turkey. The most common options for international entrepreneurs are the Limited Liability Company (LLC) and Joint Stock Company (JSC).

An LLC is often suitable for small and medium-sized businesses, subsidiaries and entrepreneurs establishing their first operation in Turkey. A JSC may be more appropriate for larger investments, businesses planning to raise capital or companies with more complex ownership structures.

The appropriate structure depends on factors such as the number of shareholders, planned investment, business activity and long-term objectives.

Company Registration in Turkey

Once the appropriate structure has been selected, investors need to prepare the company’s constitutional documents and complete the registration process with the relevant Turkish authorities.

The process generally involves determining the company name and business activities, preparing the Articles of Association, identifying shareholders and directors, providing registered address information and completing the required registrations.

Foreign shareholders and directors can generally participate in Turkish companies, although additional documentation, translations and notarization may be required depending on their country of residence and the documents being submitted.

Investors who want professional assistance with the incorporation process can seek guidance on company registration in Turkey, including documentation, registration procedures and post-registration compliance.

Tax and Accounting Considerations

Establishing a company is only the beginning of operating legally in Turkey. Businesses must also comply with ongoing tax, accounting and reporting obligations.

Depending on the company’s activities, these obligations may include corporate tax, value-added tax (VAaccT), withholding tax, social security obligations and periodic statutory declarations.

Proper bookkeeping and timely tax filings are therefore essential. Foreign-owned companies can benefit from professional accounting services in Turkey to manage local bookkeeping, financial reporting and tax compliance requirements.

Banking and Post-Registration Compliance

Opening a corporate bank account is another important step after incorporation. Banks may request corporate documents, shareholder information, identification documents and information concerning the company’s business activities and source of funds.

Companies may also need to register employees with the relevant social security authorities, establish payroll procedures and obtain sector-specific licences or registrations where applicable.

Maintaining accurate corporate and financial records from the beginning can significantly reduce administrative problems as the business grows.

A Practical Approach for Foreign Investors

The most effective way to enter the Turkish market is to treat company formation as part of a broader business establishment strategy rather than as an isolated registration procedure.

Before incorporation, investors should evaluate the intended business activity, ownership structure, taxation, banking requirements, employment needs and ongoing compliance obligations. This helps ensure that the company structure selected at the beginning remains suitable as the business develops.

Turkey offers significant opportunities for international entrepreneurs, but successful market entry requires careful planning and ongoing compliance. By understanding the incorporation process and obtaining appropriate professional support, foreign investors can establish their Turkish operations on a stronger administrative and financial foundation.

War Across Time: Victims, Allies, and Enemies – The Meaning of War and Peace from a Business Perspective

By Julia Croce

War disrupts societies and economies long after violence ends, making business, human rights, and institution-building essential to sustainable peace. 

War does not end when the fighting stops. Its effects can persist through damaged economies, disrupted institutions, displaced communities, and unresolved psychological trauma, making peace building a long-term social and economic challenge. Julia Croce, an academic specializing in human rights and business ethics, argues that sustainable peace requires more than the absence of violence. It depends on rebuilding institutions, protecting rights, restoring economic stability, and creating the conditions for societies and businesses to contribute to lasting peace. 

Victims, Allies, and Enemies 

If we could turn back time, we will delete the mistakes, align the missteps, and breathe the happiness. Time structures the rhythms and interruptions of human life. In the context of war, however, it often appears suspended, as memories of violence remain enduringly present for victims, allies, and enemies alike. Armed conflict frequently obscures these categories, rendering their boundaries unstable and contested. Contemporary war-crimes proceedings place increasing emphasis on victims’ rights, including legal representation and access to reparations. Instead, during the Nuremberg Trials following the Second World War, relatively few survivors provided testimony, and the prosecution relied predominantly on documentary evidence.

War is shaped by a complex interplay of impulse, strategy, compassion, and violence. Within wartime settings, victims, allies, and enemies are connected through both shared suffering and conflicting experiences. Armed conflict produces bombing and widespread destruction, rendering civilian homes unsafe and disrupting essential services. Food and water supplies often become scarce or inadequate, while damage to medical infrastructure increases the risk of disease. Education is interrupted, and long-term social stability becomes uncertain. In contemporary warfare, advanced technologies have assumed a central role for both allied and opposing forces. Airports, once associated with mobility, renewal, and reunion, have increasingly become targets of drone warfare. Iran’s March drone attack on Dubai airport, together with strikes on Fujairah, the United Arab Emirates’ largest port and oil storage facility, underscored the fragility of regional peacebuilding efforts. Although the United Arab Emirates has achieved substantial welfare provision and macroeconomic stability, conflict in the Middle East has nevertheless affected its security environment and service sectors, including tourism.

Forms of War 

War, like violence more broadly, assumes multiple forms. In general terms, it may be understood as a phenomenon that disrupts the prevailing status quo and the socio-political order. Three principal types may be identified (see the table below). A global conflict involves multiple states, often operating through coalitions such as the North Atlantic Treaty Organization (NATO); the First and Second World Wars constitute prominent examples. A civil conflict emerges when a government confronts a violent challenge from one or more rebel groups seeking political transformation. Myanmar, for instance, has experienced a protracted ethnic civil conflict. A bilateral conflict, by contrast, occurs between two states that each assert legitimate authority over the same territory. Russia’s invasion of Ukrainian territory provides an example of such a bilateral conflict.

Table 1. Types of Conflict 

CLASSIFICATION OF CONFLICT  SUPPORT TO THE CONFLICT 
  • Global Conflict → large-scale conflict involving multiple countries and coalition 

Examples: 

  • II World War 
  • Cold War 
Purely domestic


(See rebel groups, ethnic armed organization,  and/or national political coalition which support one of the party in conflict. This type of support to the conflict can be observed in the ongoing civil war in Myanmar  after the 2021 military coup. The Bamar People’s Liberation Army is a resistance group which was founded by human rights activists in response to the 2021 military coup with the objective to fight the military regime and restore a democratic government).

Internationalized internal 

(See foreign military assistance to an ongoing conflict. Such type of assistance to a conflict is provided, for instance, by the United States to Ukraine since Russian’s first invasion. This includes air defence, fairs, ground manoeuvre, aircraft and unmanned aerial systems, small arms, and maritime).  

Coalition or intra‐allied defensive intervention 

(See military assistance provided by allies within a coalition to a state member of the same coalition which is under military attack. This type of conflict support was typical during the Cold War, with over 690 military interventions conducted by all world states between September 1945 and December 1991).

  • Civil Conflict → intra-state conflict usually politically organized between individuals, groups, and/or ethnic groups 

Examples:  

  • Myanmar civil conflict 
  • Zimbabwe civil conflict  
  • Haitian civil conflict 
  • Syrian civil conflict 
  • Bilateral Conflict → conflict which involves an attacker with several alternative attack methods and a defender who can take various actions to better respond to different types of attack 

Examples:  

  • Russian invasion of Ukraine  
  • Israeli-Palestinian conflict 

Beyond traditional categories of conflict, there is also a psychological dimension of war that affects victims, allies, and enemies. This form of conflict unfolds internally, as survivors of war struggle with the enduring effects of their thoughts, memories, and actions.

Johan Galtung, a foundational figure in peace studies, frequently emphasises psychological factors in explaining the implementation of peace agreements. Violence, often associated with the breakdown of peace, can also be understood as part of a broader psychological process, particularly in territorial negotiations and the resolution of ethnic civil conflicts. Karl Weick’s concept of sensemaking[1] describes these cognitive processes through which individuals and groups interpret novel, unexpected, or confusing events such as war. Sensemaking thus refers to efforts to understand how people think, make decisions, maintain reliability, and develop socialization and identification as newcomers. Victims of conflict often seek to understand their experiences by asking why violence occurred and why they were affected: why this did happen to me? In this sense, reflection on the temporal experience of war helps the international community refine International Humanitarian Law (IHL), strengthen protections for victims, allies, and enemies, and further develop conceptual understandings of war and peace.

Conflict typologies may also be classified according to the degree of violence involved: non-violent conflict, in which the use of armed force is absent; minor armed conflict, in which the use of force is limited; major armed conflict, in which armed force is employed with significant adverse effects on civilians; and war, in which military force is used extensively, resulting in substantial casualties among both civilians and combatants.

The Construction of Peace 

Peace cannot be understood merely as the absence of war, often described as “negative peace” or “limited peace.” Defining peace solely in terms of the absence of conflict reduces it to a temporary condition. Peacebuilding is instead a socio-economic and political process that connects the idea of peace per se with a social order grounded in social justice, humanism, human rights, democratic institution-building, and material well-being. Accordingly, “sustainable” or “positive” peace consists of multiple, ongoing interactions that unfold over the long term. From this perspective, peace is better understood as a continuum along which relationships vary, rather than as a simple binary opposite to war. Peace is most fully expressed in democratic systems of government, where the negotiated consent of citizens in the exercise of state power helps sustain stability and reduce the likelihood of war.

In wartime, countries face social, economic, and political vulnerabilities, with harmful effects that often extend to allies and neighbouring states. Arab oil-producing countries, for example, are especially exposed to price volatility, with repercussions felt across Western economies. The geopolitical risks associated with oil have been repeatedly evident since the 2003 Iraq War.

Economic recovery and the prevention of renewed conflict therefore become central priorities during and after war. The challenge is that, although economic development is widely seen as crucial to reducing the risk of conflict recurrence, leaders of post-conflict states often face major obstacles in attracting international investment, including foreign direct investment (e.g., FDI). The pace of peacebuilding depends largely on the intensity of the conflict: the greater the violence, the longer it takes to rebuild the affected country’s or region’s social and economic systems.

The construction of peace generally unfolds in two phases. The first focuses on stabilising the country through humanitarian assistance, disaster relief, infrastructure reconstruction, and economic recovery, often in cooperation with other states or international organisations such as UN peacekeeping missions. Under Resolution 1035 (1995), the UN Security Council established the United Nations International Police Task Force (IPTF) and a UN civilian office in Bosnia and Herzegovina for an initial one-year mandate. These measures were implemented under the Peace Agreement signed on 14 December 1995 by the leaders of Bosnia and Herzegovina, Croatia, and the Federal Republic of Yugoslavia. The Bosnian War (1992–95) was one of the most brutal ethnic conflicts in Bosnia and Herzegovina, a former Yugoslav republic with a multi-ethnic population of Bosniaks (Bosnian Muslims), Serbs, and Croats. The UN mission in the territory initially focused on securing a ceasefire and subsequently deploying peacekeepers.

The second phase of the construction of peace involves establishing self-sustaining political and economic institutions that enable democratic governance and long-term prosperity. This transformation is also supported by the expansion of socio-economic rights, including the rights to work, education, health care, adequate housing, and social security. These rights are often understood as helping to balance the power of the market within society. In this context, the welfare state—of which socio-economic rights are a key expression—provides social protection within capitalist systems. Reflecting this view, the Commission on the UK’s Future, chaired by Gordon Brown, recommended new constitutionally protected socio-economic rights. These rights should include stronger labour protections, safeguards against sex and gender discrimination, and measures to advance gender equality.

War and Business 

War has its time, reflecting the actions of victims, allies, and enemies. They serve to make our present, the global history, inspire reflection on questions of temporality and historicity.

Peaceful societies aim to: 

  1. Promote the economic benefit of peace; 
  2. Facilitate peaceful conflict solutions within and outside societies;  
  3. Protect minorities; 
  4. Ensure inclusion and a culture of peace in society and in multilateral fora.  

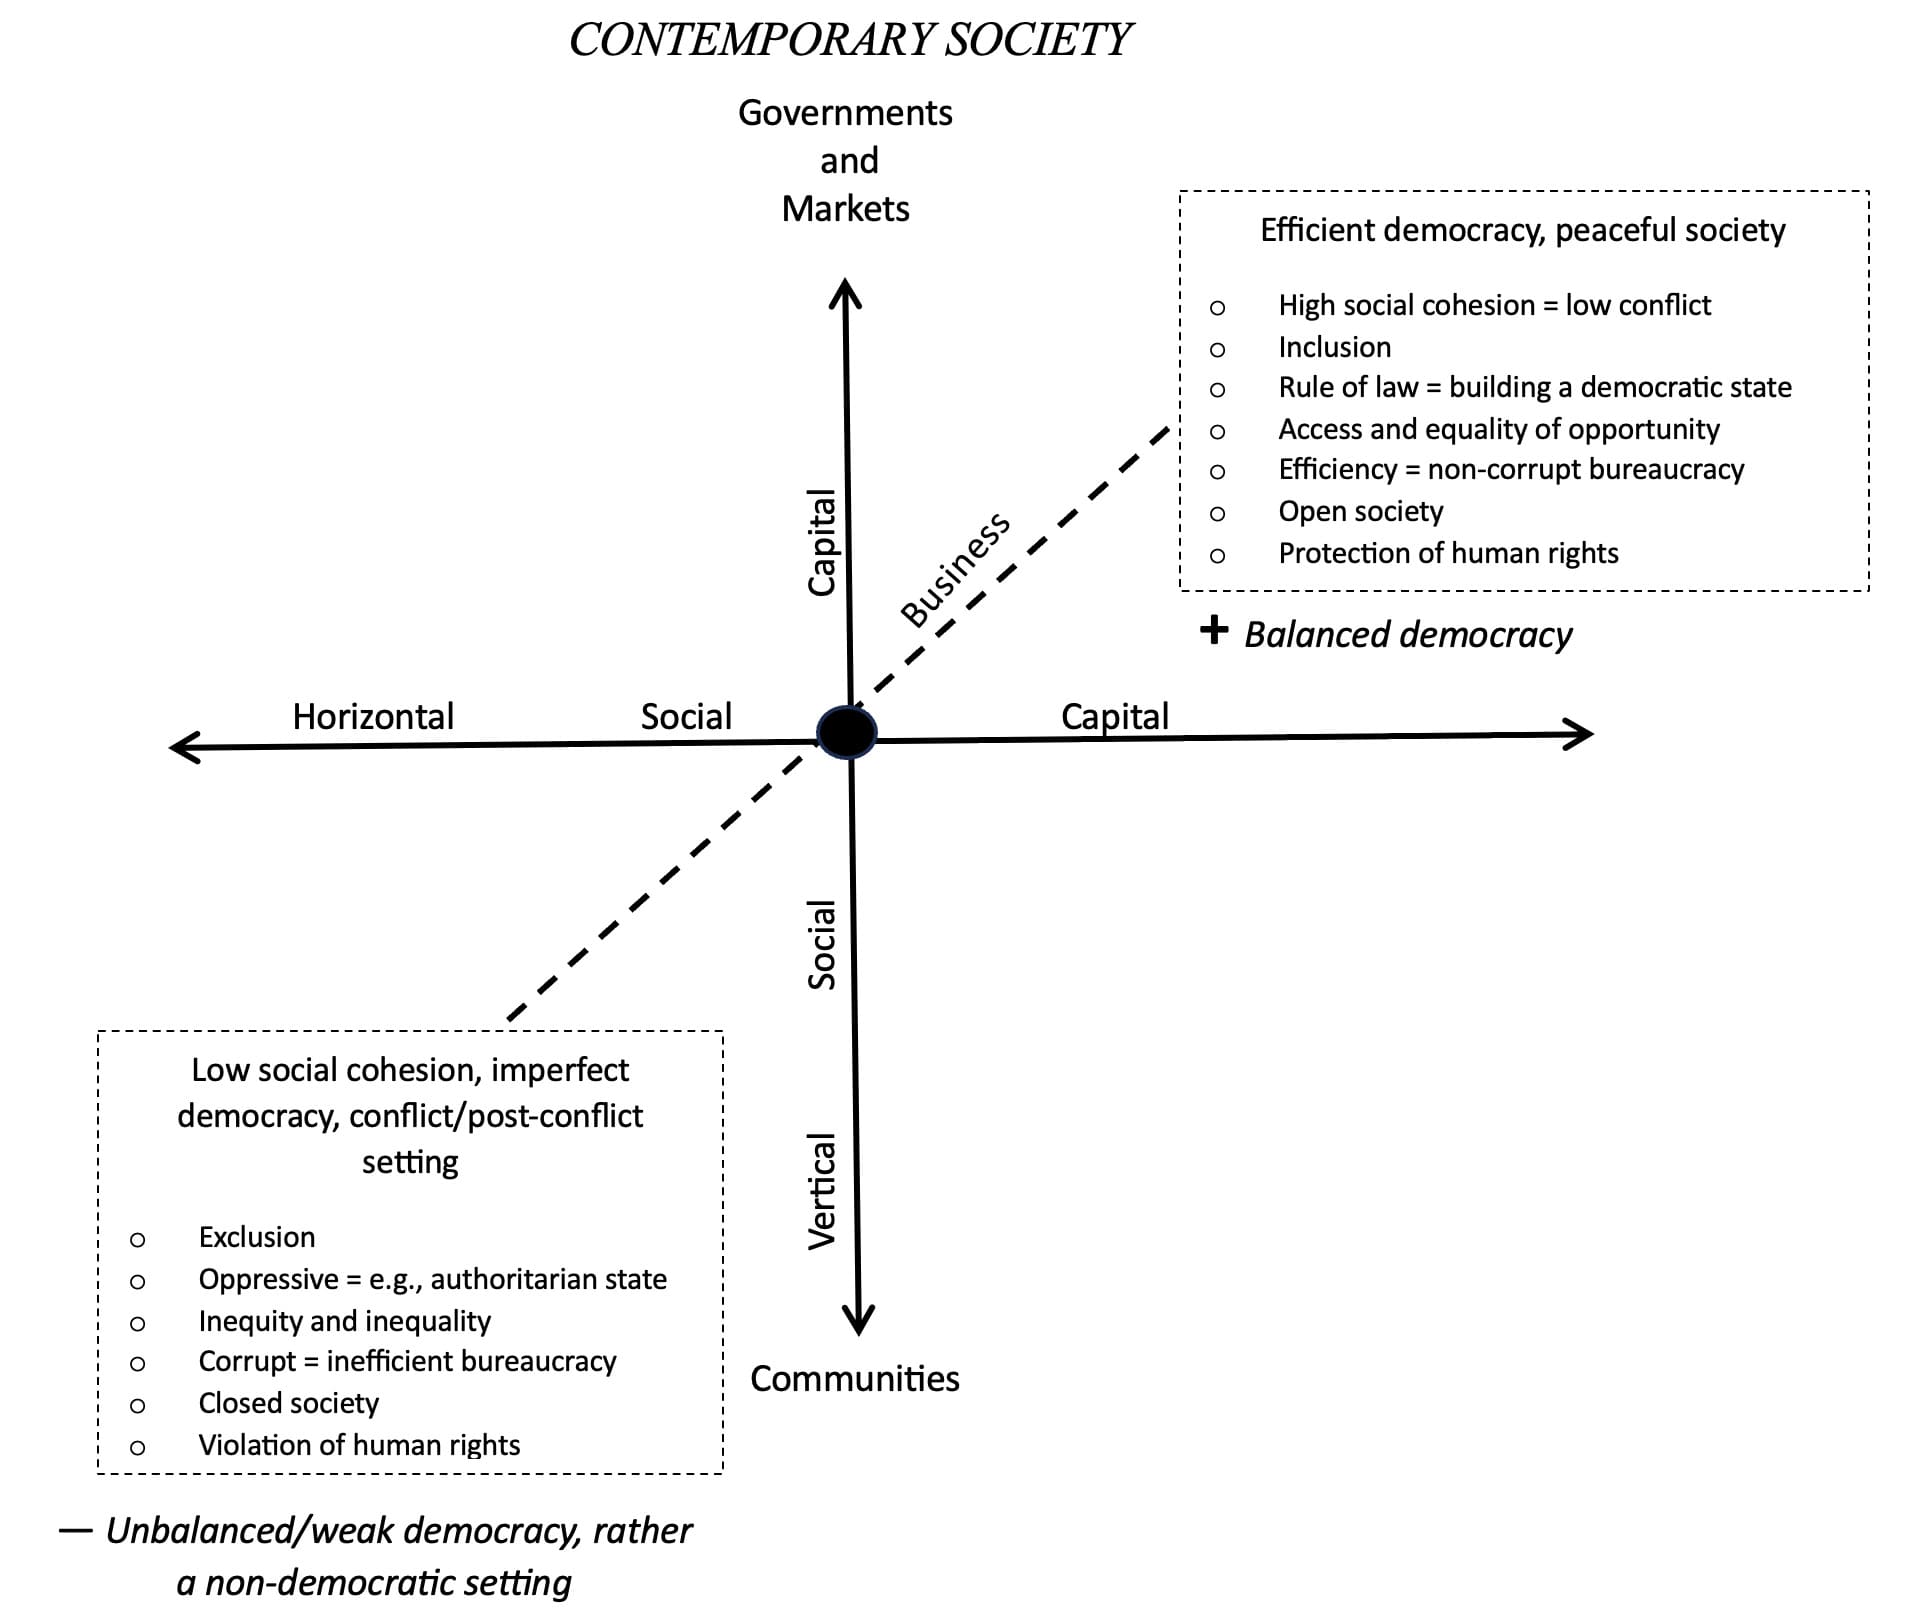
Businesses engaged in peacebuilding processes can foster social cohesion through the development of horizontal social capital[2]—meaning the growth of trust and civic involvement among similar or diverse groups (such as employees or local communities) after a conflict—and vertical social capital, which refers to interactions between the state, market, and civil society. This dual approach can help address social fragmentation and violent conflict during democratic transitions. Horizontal relationships exist among equals, while vertical ones involve parties with differing power or resources (see the Figure below). 

How business fosters social cohesion using both vertical and horizontal social capital

figure

Existing frameworks by Fukuyama,[3] Putnam,[4] and Coleman[5] provide valuable metrics for assessing social cohesion and trust fostered by businesses operating in fragile environments. Additional parameters may be developed, such as:

  • The structure and organization of assistance, mutual aid, and cooperation (including the shared use of essential resources such as water); 
  • The types, nature, and organization of exchanges and interdependence between communities and businesses; 
  • Social protection, welfare systems, and collective responsibility; 
  • Channels and mechanisms for information exchange; 
  • The existence and purpose of (business) associations; 
  • Availability and effectiveness of infrastructure. 

Recommendations for Businesses in Contemporary Times  

Businesses contribute to economic growth and efficient governance, supported by strong civil engagement (i.e., solidarity, integrity, and participation). Multinational corporations (MNCs) must adapt their industrial strategies and competitive positioning to align with the complex and  multidimensional realities of contemporary global business.

South Korea, for instance, has pursued both vertical and horizontal industrial policies throughout the 1960s and 1970s. Many South Korean workers face rigid schedules imposed by employers, limiting autonomy and decision latitude, which can adversely affect job satisfaction and wellbeing. Unlike European labour markets—where collective bargaining and regulatory standards moderate disparities—Korea’s institutional design perpetuates differences. The emergence of chaebol conglomerates, supported by government resources and preferential access, enables them to offer superior conditions compared to small and medium-sized enterprises (SMEs). Chaebols have expanded both horizontally and vertically, integrating new industries and consolidating ownership, often remaining under family control—as seen with Samsung Group’s succession strategy in the 1990s involving Samsung Everland.

In contemporary times, the promotion of social capital within organizations correlates with strengthening the quality of interpersonal relationships among employees. Workplace social capital develops through interactions: (a) among colleagues within teams, (b) across different teams, (c) between employees and direct supervisors, and (d) between staff and upper management. Businesses accordingly should (re)structure work environments to reduce stress and promote civility, emphasizing managerial support for positive psychosocial climates—mutual trust, shared objectives, and common understanding.

Conclusion 

Political institutions and business leaders face a decisive opportunity to shape societies that preserve peace and strengthen social capital through sustained collaboration. When directed toward constructive goals, business, for instance, can be a powerful force for inclusion, stability, and social progress in post-conflict societies. Yet it can also intensify exclusion, marginalization, and the conditions that give rise to violent conflict. This makes the deliberate cultivation of social capital especially vital for SMEs and MNCs operating in contexts where legal and political institutions remain fragile.

About the Author

Julia Croce

Julia Croce is an academic specializing in human rights and business ethics. Her work focuses on the growing responsibility of businesses in defining and respecting peace and democracy. She is the author of the book Peace, Business, and Democracy: Corporate Responsibility in Peace and Governance. In 2024, she was honoured with the prestigious Prix William Rappard. Julia received a PhD in Management Studies from the University of Geneva, Switzerland.

Why Are the Next Wave of Tech Founders Fleeing Mega Cities?

By Paul Dawalibi

Thousands of entrepreneurs are abandoning their cities, and the ecosystems willing to adapt to the reasons why will define the next decade of global innovation.

Thousands of entrepreneurs quit the UK in the past two years, the skill shortage in Europe is accelerating and the reason why is clear: the environments that once supported founders are now working against them.

The priorities have shifted, structurally and permanently. As CEO of the world’s first AI free zone in Ras Al Khaimah (RAK), and as someone who made this move myself after 25 years building technology companies across the established hubs, I can tell you that founders leaving are responding to a reality that their own cities miss.

What is driving them away? 

One force creates a domino effect for founders. Global competition and the pressure for speed seems simple and obvious, but it’s the most overlooked factor.

Every business leader and entrepreneur is racing to be first to market, first to deploy, first to scale. But in the traditional markets for technology investment, that’s coming at an increasing cost.

The UK’s AI sector just grew by $255 billion, a 97% percent surge, in a single year. However, founders are quietly acknowledging that the UK and the US – with their high costs, rigid hiring systems and relentless administrative complexity – are working against them at precisely the moment when speed is everything.

The cost of building a team in the cities we have always loved – London, New York, San Francisco – has quietly become one of the biggest threats to early stage companies. Startups are burning through their seed rounds before they ship a single product. Trying to bring in a developer from Eastern Europe, South Asia or Southeast Asia, for instance, means months of paperwork, visa lotteries and legal bills that often end up costing more than the hire itself. This slows down the very people who are supposed to be driving innovation forward.

Is it possible to have speed and stability in the same place? 

The UAE, and Ras Al Khaimah in particular, has long understood what serious builders need. What I found here in RAK, the northernmost and perhaps most surprising of the Emirates, was something I had not experienced in a long time: the ability to think.

There is a reason that the most consequential technology companies in history were not built inside San Francisco. They were built in Palo Alto, Cupertino, Mountain View – close enough to the action but far enough from the noise to allow the kind of deep, uninterrupted work that building something genuinely new requires. RAK is that place.

People who know this region well describe RAK as the “Startup Emirate”, and it earns that name. It moves faster, adapts more quickly and carries none of the institutional weight that slows progress in larger, more established cities. RAK sits one hour from Dubai and is liveable and purpose-built for founders and entrepreneurs seeking the space to think clearly away from distractions.

And it is not just about the individual founder. With living and operational costs 50-60% lower than major urban centres, it is viable to bring your whole team, and – for we entrepreneurs are people too – even your family. When an entire company shares, and feels at home in, the same physical environment every day, the pace and quality of what you build changes entirely.

What does real founder support actually look like? 

Most free zones offer a licence and a mailing address. Innovation City, RAK’s tech-focused free zone, was built differently, from the ground up around the daily pain points of founders and entrepreneurs. The practical differences are immediate:

  • Business setup is done within 24 hours. This includes opening a corporate bank account, securing visas and beginning to hire. In most established markets, the same tasks take months. We have removed that friction entirely.
  • Subsidised compute is available through our own data center. Affordable compute is one of the most critical and most overlooked challenges for companies building on AI today. Founders should not be burning their capital on infrastructure costs before they have had the chance to prove their product.
  • We have radically reduced regulatory costs. Real world asset tokenisation, for instance, has historically required two years of engagement with regulators and costs of around $2 million. At Innovation City, we have built a compliance framework that reduces this to days and approximately 200,000 AED, roughly 55,000 US dollars.
  • We are AI-driven from the inside out. By the end of this year, 60-80% of our own internal operations will be entirely AI-driven and our incorporation process is already 90% automated. We do not just talk about building with AI. We do it.

How does the matchmaking approach change the game? 

Capital and mentorship get enormous attention in the technology world, but neither directly solves the challenge that most determines whether a founder gains real traction, which is landing the first paying customer. That single milestone changes everything, because it proves that the product works in the real world, for a real business, with a real problem to solve.

From that moment, the entire dynamic of a company shifts. Investor conversations become more productive, teams grow in confidence and commercial momentum builds in a way that no funding round can manufacture. To me, that milestone is more powerful than any investment cheque or mentorship programme.

Ras Al Khaimah holds the largest industrial and manufacturing base in the UAE, spanning sectors undergoing serious disruption from AI, robotics and automation. These established industrial businesses carry unmet technology needs that most founders elsewhere never get direct access to.

At Innovation City, we actively matchmake between these companies and the entrepreneurs inside the free zone. We create direct commercial introductions rather than pitch competitions or demo days. This means that founders meet real buyers who need exactly what they have spent months or years building.

We have already seen this model deliver results, for example:

  • A Norwegian-founded AI gaming company came to Innovation City building tools that use AI to democratise game development, in the way that Roblox democratised accessible play. The commercial foundation they established here contributed directly to them securing investment from Andreessen Horowitz, one of the most respected technology investors in the world.
  • In addition, a leading UK company, the country’s largest high-end custom PC manufacturer, chose Innovation City as its launchpad into Asia and Africa, drawn by the direct access to markets and manufacturing networks that RAK uniquely offers.

These are two very different businesses that arrived at the same conclusion: the right environment opens doors that capital alone cannot. What’s more, they are only two of many examples, with even more to come.

What’s next? 

The next decade of innovation will be won by the places that genuinely unlock what founders and entrepreneurs need: the space to focus, the infrastructure to move fast and the commercial foundations to prove that their ideas work in the real world. These conditions give ambitious founders the best chance of success. As a result, I believe that places like Innovation City in Ras Al Khaimah can do in five years what Silicon Valley took fifty to build.

About the Author

Paul Dawalibi

Paul Dawalibi is a technology entrepreneur, investor, unicorn founder, and futurist with more than 25 years of experience shaping startups, venture capital, gaming, esports, Web3 and AI. He is currently the CEO of Innovation City, where he is building the Silicon Valley of the Middle East in Ras Al Khaimah. As the creator of CNBC Arabia’s Game Changers and a trusted advisor to governments and global companies, Paul is widely recognized for translating complex technologies into real economic opportunities. His philosophy is simple: The future belongs to those who are bold enough to build it, and smart enough to make it fun. 

Why Texas Small Businesses Need Better Tax Planning

Texas Has 3.5 million Small Businesses. Most of Them Are Figuring Out Taxes on Their Own, and That Is Costing Them.

The Texas Comptroller’s office released a landmark small business report in late 2025 that confirmed what most business owners in Houston already suspected: small businesses are the backbone of this state’s economy. What the report does not tell you is how many of those same businesses are leaving money on the table every year because they do not have a qualified accountant in their corner.

According to the Texas Comptroller’s inaugural Small Business is Big Business in Texas report, the state is home to approximately 3.5 million small businesses, representing 99.8 percent of all businesses in Texas, employing more than 5.1 million Texans, and accounting for 84 percent of the state’s annual job growth in 2024. That scale makes Houston one of the most active small business markets in the country. It also means there are millions of business owners navigating franchise tax filings, federal quarterly estimates, payroll obligations, and bookkeeping requirements with varying degrees of professional support, often less than they actually need.

What Texas Small Businesses Actually Owe (And What They Miss)

Texas does not have a personal state income tax, which simplifies the individual side of things. But business owners in Houston face their own set of obligations that are easy to mismanage without proper guidance.

Texas Small Businesses
Image from Mikhail Nilov on Pexels

The Texas franchise tax applies to most business entities operating in the state. The no-tax-due threshold for 2024 and 2025 sits at $2.47 million in total revenue, meaning many small businesses owe nothing but still need to file by May 15 each year. Missing that deadline triggers penalties even when no tax is owed. Federal obligations run parallel: quarterly estimated tax payments, payroll tax deposits, and the annual return all operate on separate calendars that can pile up quickly for a business owner already stretched thin.

Beyond compliance, there is the planning side. Tax planning done well identifies deductions, entity structure advantages, retirement account contributions, and timing strategies that reduce taxable income before the year closes. Done reactively in April, those opportunities are largely gone.

What a Full-Service Accounting Relationship Covers

A tax accountant working with a Houston small business is rarely doing only one thing. The service relationship typically spans several interconnected functions:

  • Tax Preparation and Filing – Accurate, timely preparation of federal and state returns, franchise tax filings, and any required international tax disclosures for businesses with cross-border activity or foreign ownership.
  • Bookkeeping Services – Organized, reconciled books are the foundation of accurate tax returns and meaningful financial reporting. QuickBooks remains the most widely used platform among Houston small businesses, and a CPA firm fluent in its setup and maintenance keeps the financial data clean enough to be useful year-round rather than only at filing time.
  • Tax Advisory – Ongoing access to a tax advisor who understands your specific business structure, industry, and growth trajectory is where the real value shows up over time. A good advisor is not just responding to what happened last year. They are helping structure what happens next year in a way that manages the tax impact before it becomes a bill, making accounting an important part of long-term business growth rather than simply a tax-season requirement.

Houston Small Business Tax Key Dates

Deadline Obligation Notes
January 31 W-2s and 1099s issued To employees and contractors
March 15 S-Corp and Partnership returns Form 1120-S or 1065
April 15 Individual and C-Corp returns Form 1040 or 1120
April 15 Q1 estimated tax payment Federal quarterly
May 15 Texas Franchise Tax report Even if no tax is owed
June 16 Q2 estimated tax payment Federal quarterly
September 15 Q3 estimated tax payment Federal quarterly
October 15 Extended returns due Federal and Texas extensions

Sources: IRS Tax Calendar for Businesses 2025; Texas Comptroller Franchise Tax Filing Deadlines (2025-2026)

Incorporating Adaptability in Modern Firms

An important takeaway from these strategies is how adaptability has become a critical factor in attracting and retaining top talent. The Rascon CPA Firm, a well-established tax accountant in Houston, understands the need for innovation in today’s evolving business environment. Through flexible work models, ongoing professional development, and modern accounting practices, the firm demonstrates how forward-thinking accounting professionals can remain competitive while continuing to support businesses in Houston and surrounding areas.

Texas Small Businesses
Image from Mikhail Nilov on Pexels

The Cost of Waiting Until April

Tax accountants who only hear from clients at filing time are limited in how much they can help. The strategies that meaningfully reduce a business’s tax burden require decisions made throughout the year: how to classify expenses, when to make equipment purchases, how to time income recognition, and whether the current entity structure still makes sense as revenue grows.

Houston’s small business community is too large and too competitive for owners to treat tax planning as an afterthought. The businesses that manage it proactively are consistently in a better position than those that discover the gap every spring.

The Power of Baltic SMEs in European Defence: Small, but Agile

Finland’s Ministry of Defence and the Estonian Defence forces signed an agreement at the end of June with Finnish start-up NestAI to test the company’s AI models on the battlefield. This is just the latest in SMEs in the Baltic states bordering Russia putting their skills in AI, cyber, and space towards regional and European security by contributing to projects including electronic warfare, hypersonic defence, and cybersecurity. 

Often overlooked because of their small GDPs and populations, Estonia, Lithuania, Latvia and Finland have been proving that ‘small’ also means being agile. Following Russia’s invasion of Ukraine, the countries’ SMEs and start-ups quickly adapted to the new security reality of sharing a border with a hostile neighbour to pursue cutting-edge military innovations and dual-use space technologies.

Salvis Skladovs from Latvia’s LMT Defence explained that, “Latvia is unlikely to launch a national main battle tank or fighter jet programme in the foreseeable future. However, by leveraging our engineering traditions, creativity, rapid development cycles and a highly compact ecosystem, we can become global leaders in technologies shaping the future battlefield – autonomous systems, communications, C4ISR solutions, AI and related fields.” Indeed, Ieva Sīpola and Julia Gifford from Labs of Latvia clarify that each country in the region has their own specialties with Lithuania taking lead in lasers and optics; Estonia known for cybersecurity and robotics; Latvia excelling in telecommunications and quantum technologies; and, Finland having a long history in telecoms, software and cybersecurity.

The region has also been bearing the brunt of Russia’s ongoing hybrid attacks in the region. Lithuania’s, Estonia’s and Latvia’s defence spending have all increased considerably and lead Europe in percentages of GDP. Finland’s military has shifted dramatically since Russia’s invasion as, “The air and missile threat drives particular concern. Russian cruise missiles (Kh-101, Kh-555, Kalibr, Iskander-K), ballistic missiles, expanding drone capabilities, and hypersonic weapons all factor into Finnish planning.” 

As such, governments have been supporting their SMEs and start-ups by encouraging innovation domestically and promoting them at the EU-level for larger pan-European projects involving European primes. This gives a boost to Baltic industry and domestic economies and brings their cutting-edge technologies and innovations to help develop systems and equipment that contribute to Europe’s security as a whole.

Public Officials Promoting Their Protégés

In April, Lithuania’s Minister of National Defence, Robertas Kaunas, and Minister of the Economy and Innovation, Edvinas Grikšas, approved a €40 million venture capital instrument called ‘MILInvest-2’ for innovations in the defence and security sector. Minister Kaunas explained, “The country’s defence is a matter for all of us, so through concrete actions, we are providing businesses with opportunities to strengthen Lithuania’s security and economic resilience jointly.”

Finland is establishing a new defence innovation unit within the Finnish Defence Forces to engage with companies and research institutions to bring innovations to the military. Minister of Defence, Antti Häkkänen, said, “I also want to underline the active steps taken by the Ministry of Defence to promote Finland’s industrial capabilities and strengthen international RD&I cooperation. We have worked systematically to support export promotion, to showcase Finnish technological excellence, and to develop partnerships with companies both bilaterally and within the frameworks of the European Union and NATO.”

Estonia created the NATO Cooperative Cyber Defence Centre of Excellence (CCDCOE) in Tallinn following a Russian-sponsored cyberattack in 2007 and in 2024, then-Prime Minister Kaja Kallas started a €50 million defence industry fund. Twenty Estonian companies participated in this year’s Eurosatory defence show and during his keynote speech, Minister of Defence Hanno Pevkur promoted the country’s protégés saying, “Our defense industry is growing rapidly and increasingly contributes to next-generation military capabilities building on our digital foundations… These companies are transforming battlefield lessons into operational capabilities at remarkable speed.”  

Baltic Defence SMEs with a Pan-European Influence

Governments’ promotion is paying off as Baltic SMEs are increasingly included in large pan-European projects funded under the auspices of the European Defence Fund (EDF). This trend is win-win: projects led by larger defence industrials benefit from the ‘speed’, agility, innovation and expertise of Baltic SMEs and they in return gain visibility and access to larger markets and projects. 

One of the earlier EDF-funded projects that included a range of Baltic SMEs is the FACT project to create a toolbox for European militaries to test and verify cyber vulnerabilities of equipment. The project received €26.9 million in 2022 and is led by Norway’s Kongsberg Defence & Aerospace, but the consortium includes Estonia’s CR14 (expertise in cyber range solutions and testing), Finland’s Crosshill (with experience in advanced microelectronics and creating fully secured embedded solutions), and Latvia’s LTM (a 5G expert).

Under the EDF’s 2024 funding round, the Finnish/Norwegian Patria-led AI-WASP programme received €45 million to “provide multifunctional solutions for electromagnetic spectrum operations in future electronic warfare (EW)”. The consortium includes fellow Finnish Bittium Wireless providing expertise in advanced radio frequency capabilities and Estonia’s Cybernetica who says it “contributes its expertise in secure AI systems, supporting the integration of trustworthy and cybersecure AI into complex defence platforms, cybersecurity and cyber situational awareness in swarming.”

Then there is one of Europe’s most strategic efforts: the OCCAR-managed Endo-Atmospheric Interceptor (EATMI) effort initiated by the EDF to develop Europe’s first air defence system capable of stopping hypersonic manoeuvring missiles. The threat is increasing as Russia and China already field hypersonic systems and Kiev is regularly hit by them and yet, neither Europe nor the U.S. currently field effective countermeasures. 

It was recently announced that Baltic companies have been included in one of the competing consortia, Hydis2, coordinated by MBDA France, just before OCCAR revealed the project had reached a crucial milestone of completing its Final Concept Review. Participants in the next phase, now called HYDIS2dp, come from 18 countries, with 28 partners each contributing a specific area of expertise to the system. Baltic specialists joining this pan-European effort include: Finland’s Crosshill to evaluate quantum-safe electronics and encryption algorithms, Estonia’s Cybernetica working on cyber security requirements and architecture studies & validation, Estonia’s Falconers contributing expertise in building intelligent hardware-software solutions, Estonia’s Skudo with know-how in deep-tech cybersecurity and hardware-based solutions, and Lithuania’s Novian (previously ELSIS Pro) that has participated in a number of EDF projects with its development of IT infrastructure and software platforms.

These are just a few examples of large pan-European projects that are leveraging the expertise and agility of Baltic SMEs and start-ups to develop pioneering technologies needed for Europe’s militaries. At an April conference in Vilnius, former Lithuanian prime minister and now EU Defence and Space Commissioner Andrius Kubilius, asserted and asked: “The Baltics and the region is a powerhouse of defence innovation… SMEs and start-ups are at the heart of defence innovation, and there are many successful SMEs here. How can we make sure defence SMEs get the contracts they need to produce at scale? How can we turn eastern border SMEs into European primes?”

Government leaders in the region encourage innovation and promote their most promising performers, but when the projects these companies participate on are successful, that is when their expertise is truly noticed. And being small is actually part of their advantage because as Leet Rauno Lember from Estonia’s Marduk Technologies argues, “In software development, being small is being agile.” So, whilst most will not become ‘European primes’, they still represent a powerful force in Europe’s ecosystem of defence industrials responsible for developing technologies to secure the continent.

Jim Cavellier: How To Turn AI Adoption Into Measurable Business Transformation

The companies most excited about AI are usually the ones getting the least out of it. Technology leader Jim Cavellier has watched that irony play out across 25 years of technology change. “We don’t talk about what AI is going to do anymore; we talk about what it’s doing right now,” says Cavellier, who oversees technology at Cass Information Systems, Inc. AI starts creating value the moment it becomes ordinary by being embedded into existing work, measured by existing numbers and governed by existing discipline. AI stops being a promise; instead, it has real worth.

The Sandbox Is Where Transformation Goes to Stall

Cavellier draws a sharp line between a pilot and a transformation. A pilot optimizes for learning, while a transformation optimizes for business outcomes. They are different operating models, and companies that never make the shift stay stuck in the first one, running experiments that teach them things without ever changing how the business runs.

At Cass, AI is embedded in document processing, software development, client support, and customer onboarding; it is not sitting off to the side as a proof of concept. Cavellier is equally wary of the opposite failure, deploying AI everywhere without the governance and architecture to support it. Real transformation comes from being intentional, knowing exactly where AI creates value and having the discipline to choose “AI where it makes the most sense” over “AI everywhere.” Both the endless sandbox and the indiscriminate rollout are the same mistake in different clothes.

Prove It in Numbers the Board Already Trusts

Every board wants proof rather than promise, and Cavellier does not bring AI to the board as its own story. He plugs it into a delivery model the board has already watched improve for years. That model, which Cass calls 2InaBox, pairs a technology product owner with a business project owner on every initiative, jointly accountable for the outcome rather than just the delivery. The shift cut project delivery times from more than two years to under nine months, with most work now landing in three to six months. “When we deploy an AI-driven improvement, we can measure it in the same way that we measure everything else,” Cavellier says; in time saved, cost removed, and error rates lowered; inside a framework the board already trusts.

Govern Agents Before You Scale Them, Not After

Agentic AI raises the stakes, because an autonomous agent makes decisions inside a company’s systems, and Cavellier is clear that everyone wants to have the wrong conversation about it. The exciting question is capability: what an agent can do and how fast it can be deployed. The question that actually determines whether people trust the results is accountability: who owns the outcome when an agent decides on its own.

Cass answered it by standing up a formal AI Governance Committee before scaling agentic capability, not after. “Governance isn’t a brake on innovation, it’s what makes innovation sustainable enough for people to actually trust it,” Cavellier says. He reduces the readiness test to three questions any organization should answer before deploying an agent:

  1. Can every decision AI makes be audited?
  2. Can AI be explained to a regulator or examiner?
  3. Can someone intervene when AI is wrong?

If the answer to any is no, the organization has not deployed a capability but introduced a risk. The future he describes is bounded agents operating inside governed workflows, with people in the loop.

Build the Foundation Before the Capability Arrives

Cavellier’s advice to leaders inverts the instinct to wait for AI to mature before building around it. He names three things to start now. First, get the architecture right by deciding deliberately what stays deterministic and where AI handles acceleration or exceptions. Second, build governance before it is needed rather than in reaction to a problem. Third, invest in people’s fluency with the tools directly, through hands-on work rather than top-down mandate.

None of it is exotic. It is discipline applied early, and that discipline is what turns AI from a promise into a normal way of working that produces measurable results. Speed, in the end, is not something a leader chooses over caution. It is what a strong foundation makes possible without recklessness. Build that early, and the pace takes care of itself.

To learn more about turning AI adoption into measurable transformation, connect with Jim Cavellier on LinkedIn or visit Cass Information Systems, Inc.

25 States Sue Trump Over New Global Tariffs

A group of 25 Democratic-led states has sued the Trump administration over its latest round of tariffs, arguing that the president went beyond his legal authority. The tariffs, ranging from 10% to 12.5%, apply to goods from 60 trading partners and cover nearly all U.S. imports. The states are asking the court to block the tariffs and refund duties already collected.

The lawsuit argues that the administration is using Section 301 of the Trade Act of 1974 to recreate tariffs that courts had previously rejected under other laws. The states say the government rushed investigations into the 60 economies and imposed nearly identical rates without showing how they were connected to forced labor or why each country deserved the same treatment.

The White House defended the tariffs as lawful, saying they are needed to address foreign practices that hurt American workers and businesses. The case adds to growing legal challenges against Trump’s trade policies, including a separate lawsuit from small businesses making similar arguments about the administration’s authority to impose the new duties.

Related Readings:

Trade Deals

Global Tariffs raised

Trump Says U.S.–India Trade

From Grain Exporter to Agri-Food Hub: Kazakhstan’s Role in Global Food Security

Kazakhstan is the world’s ninth-largest country by land area, what gives it significant advantages. Most notably, it has vast areas suitable for agriculture, combined with relatively favorable conditions for crop production, allowing it to emerge as a major producer and exporter of food. But while Kazakhstan’s agricultural exports have traditionally been dominated by unprocessed commodities, that model is now changing.

Kazakhstan is increasing agricultural production, expanding the geographic reach of its exports, investing in processing and modernizing irrigation infrastructure. As a result, agriculture is gradually evolving into a sophisticated agri-food system covering the entire value chain, from primary production and raw materials to deep processing and access to fast-growing markets.

This transformation is taking place against the backdrop of a broader restructuring of the global food system. Here is why Kazakhstan’s role in global food security could extend well beyond its domestic market.

Food Is Becoming a Global Resilience Issue

The global food system is currently facing several challenges at once. Population and incomes are rising, particularly in middle-income countries, while consumption patterns are changing and demand for meat, dairy products and other sources of protein is increasing. At the same time, agriculture is facing climate-related risks, water scarcity, rising input costs and disruptions to supply chains caused by geopolitical tensions.

According to the OECD-FAO Agricultural Outlook 2025-2034[1], global agricultural and fish production is projected to increase by around 14% over the coming decade. Much of this growth is expected to come from productivity gains, particularly in middle income countries.

Yet there is another factor that is becoming just as important: international trade. The OECD and FAO project that by 2034, around 22% of all calories consumed globally will cross international borders. In other words, global food security is increasingly a question of moving food from countries and regions with surpluses to those facing shortages.

In this regard, the role of the leading economy of Central Asia – Kazakhstan – in these processes is noteworthy. In 2025, country’s gross agricultural output exceeded $18.2 billion, up 5.9% year on year. The country harvested 25.9 million tonnes of grain, including 19.3 million tonnes of wheat.

At the same time, Kazakhstan’s crop structure is gradually becoming more diversified.

Over recent years, the area planted with wheat has declined by almost 900,000 hectares, while oilseed acreage has increased by more than 1 million hectares and pulse crops by 275,000 hectares. This is important not only in terms of production volumes: a broader crop mix is creating a new raw-material base for the food processing industry. The shift has also been driven by the growing export and processing opportunities associated with oilseeds and pulses.

This export potential is reinforced by another of Kazakhstan’s key advantages: its geography. The country is located between some of Eurasia’s largest consumer markets. For the agri-food sector, this provides access to multiple sources of demand across Central Asia, China, the Caucasus, the Middle East and beyond.

In this sense, Kazakhstan’s geography is gradually being transformed from a historical constraint into an economic asset. The country can not only produce food, but also connect producers with fast-growing markets across neighboring regions.

President Kassym-Jomart Tokayev has highlighted this potential. Addressing the UN General Assembly in 2023[2], he stressed Kazakhstan’s commitment to using its agricultural potential to help address global food shortages and expressed the country’s readiness to serve as a reliable supplier of grain and other socially important food products.

From Commodity Exports to Value-Added Food Products

But the most important transformation is taking place not in the fields, but after the harvest. The OECD’s 2025 review of Kazakhstan’s agricultural policy highlighted a structural feature of the sector: historically, around 60% of the country’s agri-food exports consisted of primary products. At the same time, Kazakhstan remains one of the world’s major wheat exporters[3].

This became a major opportunity for economic development. The logic is straightforward. If grain continues to be exported primarily as a commodity, a significant share of the value is created outside the country in the form of starch, gluten, pasta, animal feed, biofuels and other products. If, however, agricultural raw materials are processed domestically, more value added, investment and employment remain within the economy.

That is why food processing has become one of the central priorities of Kazakhstan’s agricultural policy in recent years.

According to Kazakh Government, 53 investment projects in agricultural processing, worth a combined $230 million, were launched in 2025. Food production reached $7.5 billion, up 8.1% year on year.

The momentum accelerated in January-April 2026. Food production reached more than $2.8 billion, representing a 14.4% increase year on year. Investment in fixed assets in the sector more than doubled, exceeding $800 million.

Exports are even more telling. In the first four months of 2026, exports of processed agri-food products reached $3.6 billion, accounting for more than 50% of total agricultural exports. The Government has set a more ambitious target of increasing the share of processed products to 70%.

In other words, the development model itself is changing. The objective is no longer simply to increase output by producing larger harvests, but to increase the economic value generated by every tonne of agricultural raw material.

How does this work in practice? Kazakhstan already has a substantial processing base, while government policy envisages further expansion of processing capacity. Under the country’s agricultural development plans through 2028, new facilities for deep grain processing are to be established.

This is also changing the export model. Previously, the chain was relatively straightforward from harvest to export. Now, additional stages are being added: processing, finished products, packaging and marketing, and logistics. This allows significantly more value to be created within the country.

As this model takes shape (which is reflected in the growth of food production) Kazakhstan is strengthening its role in regional food security.

Regional Food Security

Kazakhstan’s role is particularly visible in the grain market. According to the Government, between September 2025 and July 17, 2026, Kazakhstan exported 13.5 million tonnes of grain and flour in grain-equivalent terms, 12.5% more than during the same period of the previous season.

The strongest growth came from neighboring markets. Exports to Afghanistan rose by 59% to 2.2 million tonnes, while shipments to Kyrgyzstan reached 504,000 tonnes, up roughly 40%, to Turkmenistan reached 210,000 tonnes, an increase of 34% year on year, and to Uzbekistan increased by 37% to 5.6 million tonnes.

These figures illustrate how Kazakhstan’s agricultural sector is becoming increasingly integrated into the food supply system of the whole region. This is particularly important for Asia, where populations are growing, urbanization is accelerating, and agriculture in many countries faces constraints related to land and water resources.

Kazakh agricultural products are now exported to more than 72 countries[4]. Key destinations include not only Central Asia and Afghanistan, but also the European Union, the Eurasian Economic Union, Türkiye and China. According to official data, agricultural exports have nearly doubled over the past five years, rising from $3.8 billion to $7 billion.

This is part of a broader transformation in which international trade itself is becoming an increasingly important component of food security. The OECD and FAO emphasize that moving food from surplus regions to areas facing shortages can help stabilize markets and reduce the risk of localized disruptions. In this context, Kazakhstan is already emerging as one of the region’s important sources of food supply.

A New Agricultural Cycle and a New Export Model

The modern food sector is a complex system, particularly when viewed through the lens of export potential. Kazakhstan is already building such a system, with the goal not only of processing agricultural products but also of integrating more deeply into global food supply chains.

This is particularly relevant as international trade continues to grow in importance. According to FAO estimates, in 2025, the volume of food imports will increase by 7.9% compared to the previous year and reach $2.22 trillion.[5] Within this system, Kazakhstan has an opportunity to establish a position defined not simply by the volume of raw materials it produces, but by its ability to transform its natural and productive advantages into resilient value chains.

The Government is already working on several directions to develop the agroindustrial complex. The first is providing farmers with a modern equipment. While leading global agricultural machinery brands previously imported their equipment, production is now being localized in Kazakhstan. Manufacturers have begun investing in the industry, which has led to the modernization of existing plants and equipment upgrades, and the construction of new tractor and combine production facilities.

Since 2019, Kazakhstan has localized the production of wheeled tractors, grain and forage harvesters, reapers, tillage equipment, seeders and seeding systems, and much more. For example, in April 2025, production of American John Deere equipment began. A strategic agreement worth $2.5 billion has already been signed, cementing long-term industrial cooperation between the company and Kazakhstan. A total of 430 units of equipment were produced in 2025.

In 2026, several more global technology leaders from Europe, Canada, and North America began localizing their products. These include Väderstad, Dewulf, Lindsay Corporation, Amity Technology, Vervaet, Kuhn Group, and Brandt Agricultural Products. As a result, Kazakhstan now has 10 factories producing tractors, grain harvesters, forage harvesters, and cotton harvesters of varying capacities.

Overall, agricultural machinery production in Kazakhstan increased by 22% in 2025, and companies plan to produce nearly 10,000 units of modern equipment this year.

Focus: Deep Processing and Water Conservation

A second important area of development is the creation of facilities for the deep processing of agricultural raw materials. Three grain processing facilities with a capacity of over 510,000 tons are already operating in Kazakhstan, producing starch products, bioethanol, and gluten. By 2029, six more major investment projects worth $4 billion will gradually join them.

These include, for example, a plant in Astana belonging to the Tiryaki Agro, which will produce starch, gluten, and glucose-fructose syrup. The project’s value is estimated at $320 million. Another example is an already operating plant belonging to the Fufeng Group Company Limited, with a processing capacity of 3 million tons of corn per year, with an investment of $1.5 billion.

Also underway in the country are investment projects by the companies Dalian Hesheng Holdings Group Co., Ltd. and Hopefull Grain & Oil Group, valued at $650 million and $1.5 billion, respectively, which will focus on wheat processing.

These examples demonstrate how leading companies are investing significantly in Kazakhstan, contributing to the country’s development as an agricultural hub for the region.

Another equally important issue is providing Kazakhstani farmers with fertilizers. The country is building next-generation plants worth several billion dollars. By 2027, Qazaq Kalium Ltd. will launch the first stage of potash fertilizer production with a capacity of 1 million tons, and by 2035, it will increase production to 12 million tons. Given that Kazakhstan’s demand for this type of fertilizer is 100,000 tons, the country will become a major global exporter.

Furthermore, demand for urea will be met by the launch of three large-scale complexes in 2029-2030. These include KMG PetroChem, with a capacity of 800,000 tons; Qazesta Fertilizers Ltd., with a capacity of 700,000 tons; and KazAzot PRIME, with a capacity of 577,000 tons of urea and 500,000 tons of ammonium nitrate. At the same time, Kazphosphate, together with  SINOPEC and CNCEC, is planning to expand its capacity to 5 million tons of phosphate fertilizers, with the first million tons of ammophos in 2029.

As a result, by 2030, Kazakhstan will not only fully meet its domestic demand for all key fertilizers but also enter export markets.

At the same time, climate change remains a key focus. Agriculture consumes approximately 60% of the country’s water resources, and it is here that modern watersaving technologies are being widely implemented. This significantly contributes to the sector’s development, making it more resilient to climate change.

Kazakhstan is implementing a comprehensive set of measures to encourage farmers to use modern irrigation methods to conserve water while increasing crop yields. These measures include, for example, reimbursing farmers’ costs for constructing the necessary infrastructure, purchasing and installing sprinkler machines, drip irrigation systems, and other modern equipment.

And these measures are already demonstrating positive results. By the end of 2025, the area covered by water-saving technologies reached 543,000 hectares. By 2026, water-saving technologies will be implemented on an additional 163,000 hectares. The gradual implementation of water-saving technologies is expected to result in up to 2.2 billion cubic meters of water savings annually. Land will be used more efficiently, conserving resources and increasing productivity.

This demonstrates how Kazakhstan is systematically increasing productivity, implementing new technologies, and expanding production, thereby strengthening its role in the global food system. The country is emerging as a major agrifood hub in Eurasia, and this model is becoming a logical step in the development of Kazakh agriculture.

Sources:

[1] https://www.oecd.org/en/publications/2025/07/oecd-fao-agricultural-outlook-2025-2034_3eb15914/full-report/agricultural-and-food-markets-trends-and-prospects_d3812d71.html?
[2] https://news.un.org/ru/story/2022/09/1431931
[3] https://www.oecd.org/en/publications/agricultural-policy-monitoring-and-evaluation-2025_a80ac398en/full-report/kazakhstan_68dda758.html?
[4] https://www.gov.kz/memleket/entities/moa/press/news/details/1181100?lang=ru
[5] https://www.fao.org/newsroom/detail/fao-food-outlook–global-food-commodity-market-trends-facerising-geopolitical-and-weather-risks/ru

The CFO’s Guide to Finance and Accounting Outsourcing

There are around 124,200 openings for accountants and auditors every year through 2034, according to the U.S. Bureau of Labor Statistics. For a finance leader, that number sets the terms of a real question: how do you staff a widening set of responsibilities from a talent pool that grows more competitive each year? 

This guide shows how finance and accounting outsourcing gives you capacity and room to point your in-house team at the work that moves the business. You’ll see what the model covers and what to look for in a partner that fits the way you already run. 

Rethinking Where the Finance Work Happens 

The demand behind accountants and auditors comes from steady market forces, including a growing economy and a tax and regulatory environment that asks more of every finance team. A large share of experienced accountants is reaching retirement, which opens more roles across the profession. 

The supply side may be turning a corner. Accounting enrollment grew about 12% for two straight semesters in the 2024 to 2025 school year, per National Student Clearinghouse data reported by the AICPA. Degrees awarded still dipped to about 55,000 in 2023 to 2024, though the rate of decline has slowed. 

Forward-looking finance leaders don’t wait on that recovery; they pair it with a delivery model that gives them capacity now.

Many accounting professionals watch how their peers have moved location strategy into the boardroom before they choose a model. The next question is what that model includes. 

Understanding What Finance Outsourcing Covers 

Finance and accounting outsourcing covers the transactional core that keeps a business running. The work spans:

  • Accounts payable 
  • Accounts receivable 
  • Bank and account reconciliations
  • Payroll support 
  • Month-end close 
  • Management reporting 

A capable partner runs processes on your systems and follows your controls. Clean, timely numbers reach your team. Most finance leaders keep treasury calls and board reporting in-house. The partner takes on the repeatable, high-volume work. Dividing the work this way adds capacity without loosening your grip on the important decisions.

The economics draw many finance leaders to the model. Providers such as Amalga Group build nearshore finance and accounting outsourcing teams from operational hubs in Monterrey and Mexico City, and the company reports those teams run 40% to 50% below the cost of comparable U.S.-based teams. The savings free up budget you can redirect toward forecasting and the strategic work your senior staff does.

Cost is one reason finance leaders adopt this outsourcing model. Control is the other, and it decides how the rest of the engagement holds up. 

Keeping Control and Compliance in Outsourced Operations 

A well-run engagement answers the first concern finance leaders raise first: control. You keep ownership of your ledger and reporting calendar. The partner works inside your enterprise resource planning system and reports against service levels you define. 

Compliance deserves the same rigor. A strong provider maps its controls to the standards your auditors expect. A provider separates duties across its team and protects financial data with access controls and audit trails. Finance leaders who follow regulation and compliance closely treat these safeguards as the price of entry, not a bonus. 

Nearshore delivery adds a practical edge when your partner works your hours. Your team gets answers the same day, and oversight feels less like a handoff and more like an extension of your own group. 

Choosing a Nearshore Partner That Fits Your Model 

The right partner matches the way you already run finance. Start with the time zone. A nearshore team in Mexico shares most of the U.S. business day, so reviews and close activities move in real time rather than overnight. 

Next, you’ll want to look at ramp and retention. Ask how a provider recruits, trains, and keeps its finance talent. The stability of that team decides the quality you receive month after month. Ask for references from peers in your industry, and walk through how the provider handles a hard close or a year-end audit. 

Data security belongs on the same checklist. Ask which certifications a provider holds, how it restricts access to your financial systems, and how it trains staff on the privacy standards regulators expect. Weigh the transition next. 

A strong partner maps your processes and reaches full productivity in weeks rather than quarters, so onboarding adds capacity without slowing your cycle. A partner that answers your questions becomes part of how your finance function performs. 

The Payoff for Finance Leaders

Finance and accounting outsourcing turns a competitive talent market into a capacity advantage, and it lets your senior people spend their hours on strategy instead of processing. 

Return to that figure of 124,200 openings a year. The finance leaders who thrive over the next decade will read it as a signal to rethink where the work lives. A finance function that grows with your business and maintains tight controls delivers clean numbers on the day you need them, turning the talent equation in your favor.

The Evolution of Modern Brokerage: An Analytical Review of Bitelity’s Trading Infrastructure

In the highly competitive landscape of global financial markets, retail and institutional traders demand execution models that combine high speed, low structural costs, and robust security protocols. The modern fintech ecosystem has forced brokerages to shift away from traditional market-making toward more transparent, technology-driven frameworks. This analytical review examines the infrastructure, technological integration, and operational parameters of Bitelity, an international brokerage platform serving traders across key European and North American jurisdictions, including the UK, Scandinavia, and Canada.

1. Core Architectural Framework and Order Execution

At the technical core of Bitelity’s platform is a hybrid processing infrastructure that utilizes Electronic Communication Network (ECN) and Straight-Through Processing (STP) methodologies. By routing client orders directly to Tier-1 liquidity providers—including global prime brokerages and major banking institutions—the platform minimizes the conflict of interest inherent in traditional B-Book execution models.

The technical metrics of Bitelity’s execution infrastructure demonstrate a strong focus on latency reduction:

  • Order Routing: Automation via advanced smart order routers (SOR) that scan available liquidity pools to find the optimal bid-ask spread.
  • Execution Speed: Average order execution times are maintained below 35 milliseconds, reducing slippage during periods of high market volatility, such as macroeconomic news releases.
  • Pricing Engine: High-frequency data feeds provide real-time pricing updates, allowing for tight fractional pip spreading on major currency pairs, indices, and digital assets.

2. Risk Management, Compliance, and Security Protocols

Operating within strict data protection and financial compliance environments requires multi-tiered security architectures. Bitelity addresses counterparty and systemic risks through several structural safety nets integrated directly into its core software layer.

Data and Asset Protection Mechanisms

  • 256-Bit SSL Encryption: All data transmissions, including personal identification details and financial transactions, are encrypted using advanced cryptographic protocols to mitigate middle-man cyber threats.
  • Segregated Client Accounts: In alignment with international banking standards, client operational funds are held strictly separate from the broker’s corporate capital. These funds reside within Tier-1 banking institutions, preventing operational misuse.
  • Automated Negative Balance Protection: The platform features an automated risk-engine that monitors margin levels in real time. If a market gap causes a client’s equity to fall below zero, the system automatically terminates positions, ensuring that trader losses cannot exceed their initial deposit.

Compliance and Verification Frameworks

To maintain ecosystem integrity, Bitelity enforces rigorous Know Your Customer (KYC) and Anti-Money Laundering (AML) verification structures. New registrants undergo automated identity verification processes, cross-referencing global security databases to prevent fraudulent onboarding, identity theft, and unauthorized access.

3. Trading Environment, Account Typologies, and Specifications

To accommodate varying trading volumes and strategies—ranging from retail day trading to automated programmatic execution—Bitelity provides a scalable account taxonomy. The structural design emphasizes transparency in trading costs, moving away from hidden maintenance fees toward clear swap and commission schedules.

Account Parameter

Specification Details

Operational Use Case

Execution Type Market Execution (STP/ECN) Scalping, Day Trading, EAs
Base Currencies USD, EUR, GBP, CAD Multi-regional accessibility
Margin Call / Stop Out 50% / 20% Standard automated risk control
Liquidity Pools Tier-1 Institutional High volume deep liquidity
Clearing Protocols Automated Automated Clearing House / Crypto Gateways Secure multi-channel processing

The platform fully supports algorithmic trading through Expert Advisors (EAs). Traders can deploy automated scripts without restrictions on holding times, enabling high-frequency trading (HFT) strategies and complex grid-trading systems to operate efficiently within the platform’s liquid environment.

4. Digital Integration and Technical Support Systems

A critical component of the user experience is the cross-platform compatibility of the trading interface. Bitelity’s proprietary terminal architecture is optimized for web-based access, desktop deployments, and mobile operating systems (iOS and Android). The user interface emphasizes minimalist data presentation, reducing cognitive load while maximizing the visibility of essential analytical indicators and depth-of-market (DoM) data.

Furthermore, technical assistance is managed via an omnichannel 24/7 support desk. In contrast to basic chatbot automations utilized by earlier fintech entrants, the technical desk provides direct escalations to infrastructure engineers, facilitating rapid resolution of API connectivity errors, institutional transfer delays, or verification bottlenecks.

Conclusion and Future Outlook

Bitelity’s technological framework presents a thoroughly modernized approach to retail and professional asset trading. By prioritizing ECN/STP execution transparency, implementing automated negative balance protection, and utilizing structured corporate compliance, the platform establishes a reliable operational model. As global financial markets evolve under stricter data protection and technological mandates, platforms that prioritize architectural speed and rigid risk control mechanisms remain fundamental to sustainable trading ecosystems.

EDITOR'S PICK OF THE WEEK

China economic growth

China’s Challenging Search for a New Model of Economic Growth

By Danny Leipziger China cannot continue to rely on exports to drive its growth, but what are the alternatives? China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...

WISE DECISION MAKER GUIDE

POWER INFLUENCERS

Emerging Trends

The Future of Global Trade