Home Blog Page 1022

Is It Possible To Get Out of Debt With An IVA?

If there is one concern that just about all people share, it is finances. No matter how much money you make or what your current financial situation is, there is always the risk of not having financial security in the future hanging over your head. This is why a lot of people try to secure themselves in any way possible. Some invest any money they have in stocks or real estate. Others try saving up in the hopes that it would ensure some financial stability in the future. But those aren’t always feasible options for a lot of people, especially if you are in debt. If that is the case, you need to first find a way out so you could start worrying about the future. 

One of the options people consider is an individual voluntary arrangement (IVA), but how helpful is it?

Can an IVA help you get out of debt? 

In a nutshell, yes, it can. An Individual Voluntary Arrangement is a way for you to pay off your debts to all creditors at a reasonable rate. It helps you avoid declaring bankruptcy, which can be quite problematic for your life in more ways than one. Bankruptcy can halt your professional life and cause all sorts of problems, especially in sectors like the legal and financial ones, and it can also make it impossible for you to get loans or mortgages. An IVA, on the other hand, spares you this trouble as you get to work things out by paying a very flexible debt, and it has a lot of benefits, too. 

How does it work? 

The individual voluntary arrangement is a binding statement that is legally documented between your creditors and yourself. It is considered as a form of insolvency that could help you get out of debt, but that means you will need to hire an insolvency practitioner to set the whole thing up and be responsible for managing how you will pay your creditors for a duration that could be as high up as 5 years. You should know, though, that you need to have a steady source of income so you could qualify for an IVA, or else the whole deal will probably not work out.

Will I lose any assets? 

This is most people’s main concern, especially considering how an alternative like bankruptcy can have you lose all assets like your home. With an individual voluntary arrangement, this doesn’t need to happen. But you should ask an experienced insolvency practitioner first to understand whether your home is at risk or not, because if you do own one, you might need to remortgage it so that the practitioners you hired could pay creditors using the equity released from the remortgaging. The IVA company or insolvency practitioners might elect to leave your home out of the arrangement, but that is not likely to happen. 

You will also get to keep other assets you possess, as long as they are not considered to be luxuries and surplus to what you need to live, like a vacation home. This means you can keep the car that you need to go to work, life insurance, and other similar assets to your name. 

Debts are frozen

As soon as your IVA is set up, all your debts will be frozen. This means you will no longer face any interest rates or have to deal with incurred charges. Also, any legal proceedings against you will be on hold, and your insolvency practitioner might even be able to pull that off before the individual voluntary arrangement goes through. So, that’s definitely a bonus because you will no longer need to worry about any of those disrupting your life.

Confidentiality 

One of the biggest perks of an IVA is the fact that it is confidential. So, no one needs to know about your current financial status or the fact that you have an IVA, except for your insolvency practitioner and creditors. This is, of course, unlike bankruptcy where it is made public in the local newspapers! With an IVA, the only people that find out are those you tell, and this helps spare you from any trouble at work or in your personal life.

Even your creditors can’t annoy you once the IVA is in place, which is quite a relief to any person in debt. Any creditors are bound by the IVA just as much as you are, and they can’t take any legal action against you as long as you meet your monthly payments. So, in short, the IVA is one of the best ways to get out of debt with little complications. 

Should You Fear Long Island Cash for Homes Buyers?

If you love the beach, Long Island should be on your shortlist of potential areas to settle. In this area, it does not matter what neighborhood you find yourself in, you’ll always be close to the ocean. However, you would also be close to Manhattan if you want to visit the Big Apple since it is just 45 minutes away by train.

So, it’s no surprise that properties in Long Island are selling like hotcakes. One drawback to being in demand is that it drives prices up. The cost of living will then follow, which means it can be quite expensive to maintain a home in the suburbs. It is also the reason why you find Long Island cash for homes transactions in the area.

It’s natural to be wary of unfamiliar things. The average homeowner thinks that there are only two options when selling their property– do it themselves or hire real estate agents. However, there is another option, which is to sell the house to an investor for cash.

According to the National Association of Realtors, cash for home transactions are not new. For instance, 20% of all closed deals were cash transactions as of March 2019, which was actually a decline from the 22% recorded in December 2018.

Long Island cash for homes transactions follows the same trend at the national level. More and more homeowners are trying out this alternative method, especially if they need the money right away.

For instance, Zillow said that the average property would sit on the market for 68 days. A lot could happen in those two months, but it is not uncommon for homeowners to slash their original price before the property is finally scooped up by an interested buyer.


Are Home Buyers for Cash Legitimate?

It’s one of the most common questions surrounding cash for homes. Yes, the transactions are legitimate. For one, they pay with cold, hard cash. There is nothing more valid than that.

Second, the entire process is quick. On average, you can get your money within the week. Even if the transaction is complicated, the companies will also give you cash within the month.

Here are some benefits of dealing with Long Island cash for homes transactions:

  1. You do not have to pay for commission fees
  2. You only deal with one company, and they will take care of the entire process
  3. The buyer will also shoulder the close cost
  4. You do not have to shell out money to make your house look good

The buyer does not care if your house is dilapidated or worn-down. If you list your home on the market, you need to invest in reno costs or curb appeal to get the most value from your house.

However, do not expect to get the full value for your home. You should also consider that these investors need to turn in a profit. Also, they will invest serious money to make some repairs and renovations to flip your house.

But do not allow them to undercut you. To avoid this, you need to do your due diligence to determine the mean price of homes in your neighborhood. Pay close attention to houses that recently sold, and have the same feature as yours.

7 Ways You Can Secure Backlinks For Your Website

Backlinks are crucial to building a reputation in the digital world. And it is not just important to help with visibility before your target audience, but also for the crawlers from search engines. In fact, Google confirms that backlinks are pretty important when it comes to organic ranking in SERPs.

For years now, people have been stressing on link building to be dead. However, the recent updates from Google and an ongoing rise in link building practices suggest otherwise.

Let’s have a look at some of the practices that experts refer to for link building these days.

1. Collaborate with Bloggers

As one of the most effective and economical methods to secure backlinks, blogger collaborations are also the easiest. However, professionals that act as a link builder to websites and other bloggers, suggest keeping a note of the active niche of the blog. The experts also point out that bloggers with higher influence over their audience are more beneficial for your website’s visibility. This is what these days, marketers often refer to as influencer marketing. Using a link building expert or a link building agency is also a great way to outreach bloggers for the purpose of backlinks.

2. Seek Testimonials

While backlinks from influencers and bloggers may be a good strategy, it still lacks imparting the trust value to a brand. Testimonials, on the other hand, can help your patrons identify you as a trustworthy professional. Moreover, if you can ask your existing patron to leave their feedback and review your business over social directories, you can score free backlinks from high-traffic forums, as well. Although these links may not help with improving the authority for your website, they can surely bring in traffic and improve your brand’s image.

3. List your Website on Directories

This one is helpful for local as well as global businesses that wish to expand online. Since Google emphasizes more on local listings for local searches, you can redirect your target audience and bring them to your business. By listing your business in various directories across the internet, you can secure a link effortlessly, that brings in high-quality link juice along with improving search engine ranks.

4. Consider Guest Posting

The most conventional yet effective mode of securing backlinks is still guest posting. However, the guest posting service has evolved concerning the continuous updates that Google introduces to its algorithm. When you publish your content on other domains, you get increased exposure while improving your branding returns. All that’s needed is to keep a check on Google’s recommendations.

5. Ask for Social Share Signals

One of the most effective tricks to secure backlinks that can bring in high volumes of potential patrons is to seek social shares. Free of cost marketing strategy, that also brings in the highest quality juice to your website, social links are promoted naturally. Additionally, social shares are also a metric for improved brand engagement.

6. Exchanging Links

Another possible method to secure links is to exchange them with other bloggers. Since backlinks are equally important for you as well as the domain that is offering it to you, it is rather easier to exchange them. Thus, improving your inbound as well as outbound links, which is a good way to improve your domain health.

7. Participate in Discussions

Lastly, you can indulge in public discussions. There’s a dual benefit to it- you can secure a backlink from high flux domains, along with, improving your brand’s involvement with your target audience. And it is needless to say, that a brand is only referred to as customer friendly if it involves regular communication with their patrons.

No matter what you wish to achieve out of your link building efforts, these tricks are sure to help with your marketing and SEO.

Is Life Insurance Worth Your Investment? Real Reasons As To Why It Is An Essential Investment

Many people believe in a happy go lucky life and thus never pay heed in investing in a life insurance policy. But have you ever thought- What will be the case afterlife? The future is unpredictable, and there are ample of premature death cases that occur throughout the year, but what if the person who passes away is the only breadwinner of the house? It may leave the family in a state of turmoil and financial crisis at the same time.

Investing in a life insurance policy is the solution for all such reasons. Life insurance policy is an essential financial paper to hold, but the reality is the other way round. A meager number of only 10% of people are insured, and others tend to overlook all the good reasons for being in possession of a life insurance policy.

Many people feel that investing in a life insurance policy is a waste of money; if you are someone of the same mindset then you need to read this article further to know the real reasons as to why life insurance is undoubtedly worth your investment:


It is a replacement for income

If accidentally, a bread earner dies, then the family has to face the losses and may also become financially unstable if they relied entirely on the deceased person’s income. To avoid such cases, buying a life cover may be a smart investment as it can replace the income and get your family members and adequate coverage for the same.

Getting life insurance will save your family members from suffering helplessness and will also not force them to extend their hands in front of somebody for money.


To settle the debts

If a person has taken any loan and if he dies, then it doesn’t mean that the debts will vanish away with the person. It is ultimately the family members who have to take care of the debts and will be required to repay the same. This may not be easy for the family members and may further cause a financial crunch. But if you have a life insurance policy left behind, then surely this can help your family members to make the repayments without suffering a financial crisis.


Mental peace

The future cannot be predicted; nobody has seen what will happen the next minute. But if you have bought a life insurance policy, then you can surely secure the future of your family members. This lets you have some peace of mind that even if you are not there with your family to safeguard them, the policy will surely provide them coverage and protection.


To meet children’s expenses

You might have big dreams of getting your kids enrolled for professional courses for a bright future. But if fate hits your footsteps and you are not lucky enough to see your children grow old, then getting them enrolled in professional courses may just be a dream forever. But it’s not the same case when you have a life insurance policy. Owning a life insurance policy will help in meeting the study expenses of your children, even if you are not with them.


Estate tax repayment

Estate taxes can be highly exorbitant, and thus investing in life insurance seems as mandatory in order to prevent utilizing the funds that you may have saved for retirement. It also prevents from jeopardizing your hard-earned assets just for paying the estate taxes.

Your family members may have a tough time coping with the loss, and on top of that, if such tax payments come in their way, it can leave them in an anxious state. So it is better that you sort out things beforehand so that your family doesn’t have to face such a situation.


Helps in supporting your business

Working in a 10 to 5 schedule may earn you a salary at the end of every month. But when you are in a business, then you may face ups and downs in your success graph. Also, when you have stakeholders with you, then they will be paid with the money of the life insurance policy even in your absence.

The death benefits of the life insurance policy will help in clearing off the debts in entirety, and the balance amount will be further handed over to the beneficiaries mentioned in the policy.

In other cases, when you are in a partnership with someone, both the partners must consider getting themselves insured. This is recommended so that due to fate, if one partner passes away and if your business suffers any losses, the other partner is not the one who handles all the financial liabilities single-handed. The policy will save them from holding the heavy and steep financial responsibilities alone.


An alternative to retirement plans

Who would not feel the need for their money to last till their last breath? By investing in a life insurance policy, one can have a continuous stream of cash flowing into their account every month. So consider investing in a life insurance product and avail the benefits of getting a regular income every month even after retirement.


Helps to deal with a financial emergency

Investing in term life insurance can also help you to meet financial emergencies. Life insurance products such as whole life insurance allow the buyer to avail of the benefits of permanent coverage until the owner cancels itself on their own. Thus it is a way to develop a cash reserve over time, which one can consider using at times of emergency or crisis.


Bottom Line

So these were a few reasons as to why it is beneficial in investing in a life insurance policy. Buying life insurance is just like a friend after your life that will take care of your loved ones in your absence.

You may have shoved a salesperson that might have been there at your doorsteps to sell a life insurance policy, but now since you know all the right reasons for being in possession of this policy, click here and get to know about the various life insurance products that you can buy suits your requirements. Do give it a thought and buy one soon!

Problems with your mortgage payments? Don’t delay, take action now!

Although defaults on mortgage payments have been steadily falling since 2008, there were still almost 300,000 filings for foreclosure in the first six months of 2019.

If you are missing your mortgage payments, it’s best to face the issue head on, as keeping your home free from foreclosure is paramount. After all, it’s not just the effect of foreclosure on your housing situation, but also on your finances. A foreclosure will cause your credit rating to drop, which may make it difficult to buy again, or rent, for several years. 

Your two main choices? Renegotiate or amend the terms of your mortgage or sell your home.

The first step, though, is to contact your mortgage provider the moment you start missing mortgage payments. It’s actually in your lender’s best interest to help you avoid foreclosure, and many have ways which can help you get through temporary financial problems.

Another option is to speak with a counsellor at the Department of Housing and Urban Development, and get advice on your budgeting or credit card debt which may be affecting the ability to pay your mortgage.


 §  Agree with your lender to amend the terms of your mortgage

Revised payment plan

You may be able to negotiate a revised repayment plan with your mortgage provider. With your lender’s approval, your overdue amount, plus your regular mortgage payment, can be spread across a specified period, say, 3 to 6 months until you become current and continue payments as usual.

Permanent modification to loan

A loan modification involves a permanent restructuring of your existing mortgage so that mortgage payments will be more affordable. This may include changes to the interest rate, changing from a variable rate to a fixed interest rate, or extending the length of the loan term to reduce the monthly payments due.

Refinancing

By refinancing, you can obtain a better interest rate and more affordable monthly mortgage payments. Furthermore, if you have enough equity in your home, you may even be able to secure a cash-out refinance loan to help pay off more expensive credit card debt.

Forbearance Agreement

A mortgage forbearance agreement typically stipulates that the mortgage lender will not initiate foreclosure proceedings provided you agree to and follow a plan to become current on your loan repayments. Although payments may be deferred during the forbearance period, you will ultimately be responsible for making up missed payments, plus pay interest, taxes and insurance.


 §  If you have to sell your home

If it’s not possible to agree to changes to your mortgage loan and you have to sell your home, the three most common workout methods are:

Regular Sale

If you’re not yet behind on your mortgage and your home is worth more than the amount you owe, you can find a suitable realtor and list your property for sale as you normally would.

“Short Sale”

If the value of your home is less than the total due on your loan, the lender may allow you to sell the property for less than what is owed–a “short sale”. The lender will lose money but if they can recoup the majority of their loan, it is preferable to a foreclosure.

Deed in Lieu of Foreclosure

Here you hand over the property deed to your lender and are released from all obligations of the mortgage, thereby relinquishing your home and any value associated with it. This allows all parties to avoid a lengthy and expensive foreclosure.


 §  Be smart

A last few words of advice. Being in financial difficulties makes people vulnerable. Always be wary of anyone offering assistance in exchange for an upfront fee or making too-good-to-be-true claims that guarantee mortgage relief. And go with a trusted realtor if you have to sell!

The Strange War with WHO’s Battle Against COVID-19

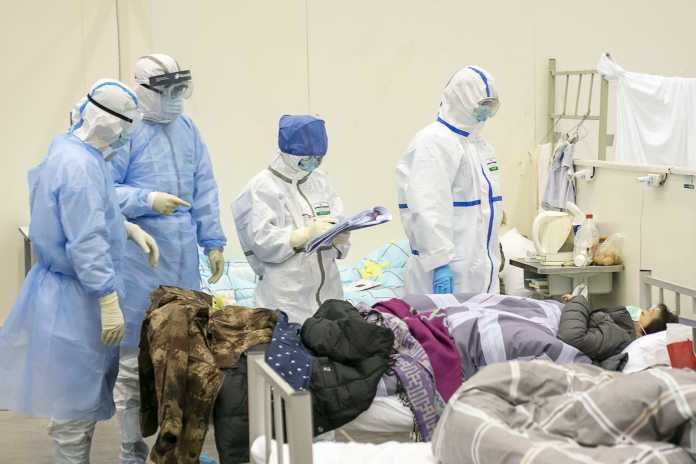
Countries outside China have not sent adequate case reports to WHO in time, while media has suffered an ‘infodemic.’ Instead of battling COVID-19, WHO was targeted as international coverage has relied on the selective bias.


“We now have a name for the disease caused by the novel coronavirus: COVID-19,” tweeted WHO chief Dr. Tedros Adhanom Ghebreyesus on February 12. “WHO chief Tedros Adhanom Ghebreyesus. He added: “Having a name matters to prevent the use of other names that can be inaccurate or stigmatizing.”

Recently, this critical task has been complicated by misguided media coverage and attacks against WHO, China and people of Chinese descent rather than the virus.


Infodemic versus epidemic

Last Saturday, WHO Director-General Tedros Adhanom Ghebreyesus urged global leaders to stop stigma and hate amid the virus outbreak. His comments in Munich followed reports that people of Asian descent have faced discrimination amid virus fears. “We will all learn lessons from this outbreak,” he added, “but now is not the time for reclamations or politicization.”

At the end of January, the World Health Organization (WHO) declared the ongoing virus outbreak a “public health emergency of international concern” (PHEIC). It is a technical term, but an important one referring to “an extraordinary event which is determined to constitute a public health risk to other states through the international spread of disease and to potentially require a coordinated international response.”

As WHO made clear, the PHEIC was not motivated by China, but the possible effects of the virus, if it would spread to countries with weaker healthcare systems.

At WHO, the concern was compounded when terms, such as “virus outbreak,” “epidemic” and “pandemic,” got blurred even in reputable international media. orse, too many other dailies and social media deployed biased and racially-coded terms, such as “Chinese disease” and “Kung flu.” Tabloid hysteria contributed to ugly instances of xenophobia, even racism against people of Chinese and Asian descent, while leading to bullying in schools, colleges, even universities.

During the 14th century, the Black Death led people to burn Jews, Romani and other vulnerable minorities. Such prejudice should have no role in the early 21st century.

Nonetheless, it was this misinformation on a global scale that compelled the WHO to declare the COVID-19 an ‘infodemic” on February 2. To track and respond to myths and rumors, the WHO began to identify the most predominant virus rumors and false prevention measures. Since international media shunned responsibility for evidence-based factual discourse, WHO had to allocate its scarce resources to do the job.

Stunningly, it took until mid-February for some of the world’s largest technology companies – including Google, Amazon, and YouTube – to get together, when WHO hosted a Silicon Valley meeting to discuss how to tamp down on misinformation about the virus.

WHO’s Andy Pattison said the “tone is changing,” as Big Tech is now starting to step up to combat fake news about the virus. Even then, while Apple and ridesharing giants Lyft and Uber were invited, they did not attend. Yet, they should have done so. In the concurrent weeks, the struggle against COVID-19 has gone hand in hand with a battle against the WHO and its executives.


How WHO and its chief were targeted                        

Since late January, almost 380,000 people have signed an online petition to the UN for the WHO chief to resign because he allegedly “solely believes” Chinese outbreak data. In contrast to allegations, WHO chief Dr. Tedros has initiated a review process to study the causes of the virus, while stressing adherence to WHO guidelines regarding pandemics.

The smear campaign is an ugly déjà vu. In 2017, Dr Tedros, a high-level Ethiopian health executive, succeeded Margaret Chan as the chief WHO. While he was considered highly qualified for the job and an innovative reformer in Ethiopia, his candidacy was attacked at the last eve of the WHO election, when odd stories surfaced about an alleged cover-up of cholera epidemics in Ethiopia. Reportedly, the allegations came from Lawrence Gostin, a US law professor who advised the rival UK candidate (and has recently resurfaced as a critic of China’s virus struggle).

In the UN, the African Union dismissed the allegations as an “unfounded and unverified defamation campaign.” Yet, once again, the old smear campaign stories have been recycled in media.

When attacks against Dr. Tedros went nowhere, the international spotlight focused on WHO Infections Hazards Director Dr. Sylvia Briand when she stated in early February that “we are not in a pandemic.” In WHO’s view, COVID-19 was an epidemic, she said adding that Chinese authorities had “been very transparent with WHO and shared almost immediately the sequence of the virus as soon as they had it.” Then she became a target for criticism.

In international media, COVID-19 has been reported as something of a systemic challenge against Chinese leadership, Communist party, and its leader Xi Jinping personally. Hence the screaming headlines focusing on politics rather than urgent international cooperation to contain the threat.

Seeking to stay away from political intrigues, WHO’s pandemic declaration requires strong evidence and relies on a tested six-stage classification, which starts with the virus mainly infecting animals with a few cases of animals infecting people, then moves through the stage where the virus begins to spread between people, and ends with a pandemic when infections from the new virus have spread worldwide.

A disease is not a pandemic just because it is widespread or even if it kills people. It must be fatal, infectious and international. The last pandemic was the 2009 H1N1 flu outbreak (swine flu), which is estimated to have killed around 150,000 to 300,000 people around the world. In contrast, COVID019 has so far resulted in 5 deaths outside China, despite weeks of diffusion.


Countries outside China failed to provide adequate reports to WHO      

In the early 2000s, China’s efforts to control SARS were criticized as the disease spread internationally before the global outbreak was subdued. A decade later, the Chinese response to Avian influenza (H7N9) was significantly faster, broadly praised and the disease did not spread widely. With COVID-19, as Dr Tedros has stated, China should be credited with identifying the virus in “record time,” sharing its genetic sequence quickly, and flagging potential international spread.

Yet, there is a strange discrepancy in the international coverage of the COVID-19. This coverage has systematically focused on China’s alleged conduct, while ignoring the actual conduct of many other influential WHO member states.

This discrepancy prevails even today, despite the news bomb of February 4, when WHO chief Tedros said that it was not China, but countries outside China that had proved slow in sharing complete information about cases. WHO was particularly concerned about the fact that, even after almost a month of international crisis and global alert, it had received complete case reports for only 38% of the cases.

In other words, a whopping three of five member countries had failed to provide adequate information to WHO in a timely manner. Those reports were vital to the global organization so that it could assess the true international scope of the outbreak, while broadening and deepening containment efforts.

“I don’t think it’s because they lack capacity,” Dr Tedros stated pointedly about these WHO members. It would be ideal, he added, if WHO would receive the most up-to-date information, not just from China but the rest of the world.

It was only after Tedros’s public statement that some member states began to share data with WHO. Meanwhile, precious time had been lost.

Even though these lost opportunities could result in potential secondary COVID-19 outbreaks outside China, international media has not yet asked the tough questions about the belated international cooperation outside China.


Selective bias?

Instead of focusing on the need for international cooperation, international coverage has produced a series of headlines against the WHO. On February 5, a day after Dr Tedros had urged countries to provide complete case reports, Financial Times reported that the influential WHO emergency committee member and veteran professor John Mackenzie “hit out at Beijing’s ‘reprehensible’ response,” and “accused China of not reporting coronavirus cases fast enough.”

The charge was not publicly supported by other committee members, nor by WHO executives. Moreover, the FT neglected to mention that the highly qualified Mackenzie also serves in Australian government’s Indo-Pacific Centre for Health Security, which plays a role in the U.S.-led Indo-Pacific initiative aiming to contain China’s rise, and is the co-chair of a major NGO, whose key partners include Pentagon’s Defense Threat Reduction Agency (DTRA), which compete “against Chinese influence.”

The tone of international coverage, even in the reputable media, still hasn’t changed. On February 13, Wall Street Journal released a new front-page story, “WHO Criticized for Virus Response,” that broadened the WHO criticism. It relied in part on critical quotes by both Mackenzie and Lawrence Gostin, the China critic who had tried to undermine Tedros’s candidacy at WHO. Free media has a right to critical views, but not to the lack of relevant context. Like other interviewees, both were portrayed as independent, disinterested, neutral observers. Furthermore, all interviewees represented experts from the U.S. or its allies. Not a single major Chinese health expert was interviewed.

Recently, the pattern has been typical to even reputable international dailies. Such purposeful selectivity fosters an impression that legitimate expertise is limited mainly to the critics of WHO.


What next?

With COVID-19, there are now (2 pm Wuhan time, Feb 17) over 71,000 confirmed cases worldwide, while the number of deaths is nearly 1,800 and the number of recovered exceeds 11,000.

And yet, the number of the confirmed cases and deaths has remained barely 800 and 5, respectively, outside China. While these numbers will continue to climb, the low starting-point suggests that China’s costly and draconian measures may have saved many lives within and outside China.

Moreover, the pace of contagion is changing in China. The relative increase of the accumulated cases has decreased since mid-January. While the pace peaked at almost 100% after mid-January, it has declined to zero (Figure). With new cases, the trend is even more discernible.

Figure   Rising Accumulated Numbers, Falling Relative Rates

Daily Increase of Accumulated Cases, Jan 10 to Feb 15, 2020*

Source: DifferenceGroup. Data from China’s National Health Commission

* Starting from February 12th, confirmed include not just tested confirmed cases but clinically diagnosed cases (which allows the infected to access treatment faster while containing them from the rest of the population). Yet, the statistical “bump” has not changed the trend lines.

While the data could indicate a possible turnaround in the virus outbreak, viruses can zigzag. But assuming data integrity and current trends, we may be witnessing a crossroads – despite politicized international coverage.

In China, the mortality rate (deaths/cases) is now 2.5% (less than a fourth of SARS and only a fraction relative to MERS), with most cases still in Hubei and its capital Wuhan. Outside China, the risk is even lower, less than 0.6%; barely four times higher than seasonal flu.

Due to the initial complacency outside China, there is a critical caveat now, however. If these countries fail to identify, monitor and contain their cases, the probability of secondary virus clusters can still rise, even soar.

Moreover, stumbling won’t help. Last week, plans to roll out COVID-19 testing kits to public health laboratories hit a snag in the U.S. when some of the labs validating the tests of the Centers for Disease Control and Prevention (CDC) got inconclusive results when running it themselves.

As WHO chief Dr Tedros says, there still remains a “window of opportunity” to stop COVID-19 from becoming a broader global crisis. Throughout the ongoing virus outbreak, he has admirably sought to foster an international battle against COVID-19. “The virus is a common enemy,” he says. “Let’s not play politics here.”

At the current pace, the confirmed COVID-19 cases could exceed 100,000 in a week or two and global resources should be focused on avoiding secondary outbreak clusters outside China. It is the virus that international cooperation and coverage should attack – not the WHO.

About the Author

Dr. Dan Steinbock is an internationally recognized strategist of the multipolar world and the founder of Difference Group. He has served at the India, China and America Institute (USA), Shanghai Institutes for International Studies (China) and the EU Center (Singapore). For more, see https://www.differencegroup.net

What Are Unsecured Business Loans And How Do They Work?

Business owners will often reminisce about how difficult it was for them to provide the funding necessary to start their business. Funding is one of the most common challenges that aspiring entrepreneurs usually face early on.

However, acquiring capital nowadays is much easier than ever. With the abundance of lending entities flourishing online and offline, as well as government-issued grants, almost everyone has access to funding. One very popular method that business owners across the world resort to is unsecured business loans. 

Unlike regular-secured loans, unsecured loans do not require the borrower to pledge a collateral. This makes the risk of unpaying tolerable, especially for business owners who cannot afford to be put in situations of potentially losing any assets to repay their lenders. Let us dig deeper below to get a better understanding of what unsecured business loans are and how they work:

What are Unsecured Business Loans?

Unsecured business loans are quite lucrative for both the lender and the borrower. Lending parties get the chance to “invest” their capital and collect the cost of their lending by charging borrowers relatively high monthly interest payments compared to secured loans. 

Borrowers acquire the risk-free almost instant capital to invest in the business, which will help in generating profits and accordingly paying off the unsecured business loan. It is a hassle-free win-win situation for everyone.

In business, companies are all looking for opportunities that would benefit their operations and, ultimately, their bottom line. With unsecured business loans, they can achieve everything they want and more than they initially thought.

How to Acquire Unsecured Business Loans?

Given how attractive the “collateral-free” aspect of unsecured loans is, many new up and coming business owners are highly interested in them. With the vastly growing numbers of small businesses in strong economies like that of Australia, non-bank lenders are multiplying to cater for their funding needs.

Finance professionals at https://www.ebroker.com.au/ are using their expertise in this field to connect legitimate independent lenders with small business loan seekers, in order to bridge an otherwise growing gap. Without the help from these professionals, a small business may struggle to acquire the capital they desperately need for their company’s operations to continue seamlessly.

If you are looking into finding an unsecured loan to purchase new equipment for your personal business, be wary of sketchy websites and find a trustworthy agent to connect you with the right lender. Do some research about the available options before signing any documentation, and listen to the advice from others that went through a similar process.

What Affects Unsecured Loans Entitlement?

Just like any kind of loan, the lender needs to do some kind of assessment to decide whether a borrower is worth the lending risk or not. If your business is swamped with debt and your credit score is bad, you will find it hard to qualify for an unsecured business loan.

Since there is no collateral, lenders look at your books to decide whether to provide you with the loan. Bad history with repaying your debts to other lenders will act as a red flag and scare away your potential unsecured loan lender.

However, even in this tough situation, you can turn things around for your own good. You can consider finding a cosigner: someone with a better credit score who will be held responsible on your behalf in case of defaulting.

Another option is to lower the amount you are asking for to better match your current credit situation. Even when the company doesn’t get the total amount they were expecting, they can still prove to the lender that they can pay back the loan as agreed upon to raise their credit rating and win back some of the lender’s goodwill, which might lead to future loans.

What If You Are Unable to Repay the Unsecured Business Loan?

Now that you have acquired the unsecured loan and used the capital to reinvest in your business or to get you out of a cash flow crisis, what happens if you cannot afford to repay your unsecured loan?

In the absence of collateral, your lenders cannot put their hands on any assets to get their money back. Lenders in such cases will start with increasing your monthly interest payment in order to make up for your defaulting, which will further worsen your credit score.

This will negatively affect your chances of acquiring loans in the future, but that is not the only downside. If you continue to default, unsecured loan lenders will eventually go to court suing you or your company, forcing you to sell your assets in order to repay your debt. 

Before putting the company at more financial risk, business owners should consider all their options carefully and only borrow the amount they need for a project they are currently working on. Borrowing a higher sum will result in larger repayments, which businesses may struggle to make if they are not responsible for their spending.

Are Unsecured Business Loans Worth the Risk?

The short answer is yes. Just because it is more attainable and seemingly risk-free, does not negate the fact that it is still a loan after all. If you’re seeking a relatively fast and easy way of acquiring funds, an unsecured business loan is the answer.

Just bear in mind the higher interest rates you are going to incur and that you completely understand that your whole business will be at stake in case you default. You should clarify any confusion by requesting that the lender explain everything in detail so that there are no misunderstandings in the long run. Remember, the loan’s purpose is to assist the company, not to jeopardize it.

Considering the nature of your business and its level of maturity, you can make the right decision regarding whether or not to apply for an unsecured business loan. Financial experts will advise going for an unsecured loan when your business is established enough to survive the brutal price of unpaying an unsecured loan. You need to do your research and try to find an in-between deal that you can afford should things go south. 

Why You Should Check The Reliability Of Your Energy Supplier

Having a reliable energy supplier can save you piles of cash, especially if you have a central heating or cooling system in your home. When your bills pile up, they can cost you as much as you pay for rent or mortgage, which can significantly impact your lifestyle and savings. 

With a trustworthy energy supplier, you can save hundreds, and sometimes thousands, on an annual basis. You don’t have to keep your heat low in the winter months for lower bills; all you have to do is double-check whether your current supplier is worth it, or whether you need to look for an alternative. 


Here’s Why You Should Always Check The Reliability Of Your Energy Supplier

Better Deals 

Double-checking whether your current supplier is your best option comes down to what deals your supplier offers you, compared to other deals. Residential homes should always pay less than commercial offices when it comes to energy plans. Browse different suppliers online, you can find them on websites like Electricityrates. Even if another supplier is only two cents less expensive than another, this can pile up at the end of the month and can save you tons of money on an annual basis.

While you do your research, you should also check any hidden terms and conditions. Some suppliers don’t offer a fixed unlimited plan and have fair usage policies that can burn a hole through your wallet if you run a lot of home appliances. Check with your current supplier if you tend to exceed your fair usage policy, and see if there are any unlimited packages that you can sign up for.


Dual Fuel Tariff Plans

Having a single supplier for your gas and electric needs is always a smart idea. This can help limit the number of bills that you receive in the mail, and make it more convenient for you to pay a single bill to the same supplier. On the other hand, having a dual tariff plan can help you in saving more money, seeing as most companies will offer you discounts as a loyal customer. Contact your service provider, and check whether they offer compelling duel tariff plans. 

If you think you need to change energy suppliers, never rush this decision. While having a dual plan is a smart choice, switching companies may cost you more money than you would save. Some suppliers will compel you to pay hefty fees if you decide to dissolve your contract without notice. Discuss your concerns with your current supplier, and see if you can land yourself any deals or discounts before you make the choice to switch to another company.


Customer Service

While saving up on bill costs is usually the first concern that comes to mind, customer service can play an integral part in how efficient your supplier is in meeting your needs. If you run into any issues with your power supply, you’ll need swift customer service that doesn’t leave you on hold or call you back the next day. A reliable supplier provides swift and efficient customer service and will prioritize your requests in times of need. 


Efficiency

Some small businesses offer very compelling plans, but you should always bear in mind that you get what you pay for. New companies will try to lure in more customers with unrealistic prices, but these plans are usually temporary, and are used as a marketing means to attract more clients. That said, newer companies may not provide you with an efficient power supply. 

Aside from periodic power cuts, which can be obvious to clients, fluctuating electricity supply is rarely noticeable, and can damage your home appliances. The primary issue with low-quality energy supply is that customers never notice what the issue is, and may never suspect that their energy supplier is the root of the problem. If your current provider is a little on the pricey side, but supplies you with stable power, don’t let newer companies tempt you with their plans and discounts.  

Finding the right energy supplier can save you a lot of hassle and money. A reliable supplier will offer you different energy plans depending on your consumption level, and may also offer you discounts if you have a dual tariff plan with them. Efficiency is also an important factor of whether your energy supplier is worth it since frequent power cuts can damage your home appliances in the long run. If you believe that you need to change suppliers, contact your current provider to discuss how you can dissolve your contract with minimal fees. 

6 Factors You Need to Consider While Selecting the Best Mutual Funds to Invest In

Mutual funds are a great platform to invest in. It is basically a collective puddle of money in which you can play the role of an investor and put in your contribution. After that, the money is invested according to the goals of the fund. Moreover, the fund can be invested in bonds, stocks, gold, money market instruments, and other similar assets. Fund managers or money managers are responsible for operating this fund and generate growth. Well-managed and good performing funds are generally the best mutual funds which one must target to invest in.

Investing in mutual funds comes with a lot of advantages such as:  

  • Mutual funds are very easy to understand and it does not require any sort of experience of economics or financial market. Even if there are many things to know about mutual funds before investing, it is still much easier to understand compared to other financial products.
  • Mutual funds have much broader market exposure and one mutual fund can be invested in multiple investment securities. It helps in diversifying into separate mutual funds. According to Mutual funds Canada, there are over 5,000 mutual funds available in Canada.
  • It is very affordable compared to other financial products.
  • You do not have to worry about growing your investments as there are specialized teams who will do it for you.
  • It comes in various types and categories, which allows the investor to choose the most suitable policy.

Invest in mutual funds and watch your money grow. SOURCE: outlookindia.com

There are a plethora of mutual funds that you can choose from but with that, there are some factors as well that you should follow to get the best mutual fund.

Here are six factors that you need to consider while selecting the best mutual funds to invest in:

1. Identifying the fund type:

If you want to get the best mutual fund then your goal for growth can be achieved by capital appearance. A long term capital appearance can be a great option for you if you are planning to meet a long-term goal and you are ready to deal with a fair amount of risk. Higher the level of risk, higher the return you will get in the future. The tenure holding such type of funds should be more than five years. However, an income fund will be more suitable for you if you are looking for current income from your funds. These funds mostly have less risk and volatility.

2. Identify your goal:

Before you select any mutual fund scheme, make sure to have a clear perspective of what you want to achieve with the return that you will enjoy in the future. Many people have big goals but they invest less, which brings less return and the investor fails to meet the destined goals. Moreover, you should also be clear about how much risk you can take to achieve your goal. If you want to get high returns then you have to increase the level of risk. If that is not the case then you can bear less risk.

3. How much fee you need to pay:

There are various mutual fund schemes available in the market and the fees can be different for the same returns. So make sure to compare them and get the best mutual fund scheme for yourself. In addition to that, when you select a mutual fund scheme, make sure to read all the documents to prevent yourself falling prey to any sort of hidden charges. As we all know that these companies are able to make money through different charges. So make sure you are transparent to each and every charge.

4. Size of the fund:

After you are clear with your goals, you should choose the size of the fund accordingly, in which you want to invest. However, the size of the fund sometimes matters less in pursuit of your goals. In some cases, even small funds can satisfy big goals. However, if the risks are less then you might have to invest a big amount in order to get better returns.

5. Experience of the fund manager:

When you want to get the best mutual fund then make sure you are opting for the best fund manager as well. When you invest in mutual funds, you do not actually take care of its growth but the same is catered by a fund manager. So, you should look for a fund manager who has enough knowledge and experience in the mutual fund market.

6. Expense ratio:

It is another important factor that you should consider if you are planning to get the best mutual fund scheme. This factor should be considered when you are investing in an equity fund. Higher expense ratio will surely affect you directly.

Even if some mutual funds come with higher market risks, they offer better returns at a less cost. If you have a lump sum amount of money then investing it in mutual funds will undoubtedly be a great idea. However, before selecting a mutual fund scheme, you should consider the factors mentioned above so that you are able to get the best mutual fund for yourself.

5 Tips to Help You Thrive in a One-Person Business

These days, you don’t need a whole team of specialists to run a thriving company. Instead, you can make money at home and build a powerful future for yourself, just by launching a one-person business.

The rise of the digital world and internet companies means that anyone can start selling online, or even launch a business as a freelancer. The good news is that there are things that you can do to better prepare yourself for success.

Here are some tips that will help you to thrive in your new one-person business.


1. Do Your Research

Launching a business requires a lot of research. First things first, you’ll need to know how much you’re going to have to spend to launch your business. That means finding out what you need to get your company off the ground. If you’re a freelance video designer, for instance, you might need some basic software, a desk, and a computer to get you started.


If you don’t have the money for all of those things already, you’ll need to research potential companies that might be willing to give you a loan. Since business loans can be notoriously difficult to apply for, it may be better to opt for a different type loan, depending on how much you need.

2. Find Something you’re passionate about

Running a business can be a fun experience, but it’s also a lot of hard work. There are going to be times when you’re terrified about your finances, and not sure whether you can afford to keep your company going for another month. When these worrying occasions happen, it’s important to make sure that you’re doing something that you feel passionate about.

Your passion in your business will help you to stay focused and committed to your goals when the going gets tough. It also means that you’re going to have more fun in your job, which is a good thing. Most self-employed people work a lot of long hours.

3. Don’t be Afraid to Network

Sometimes, it’s not what you know in business that matters most – but who you know. Building the right network of experts to help you accomplish your goals and find new clients could make it a lot easier for you to find sources of income. Additionally, your network will also act as a crucial source of support when you need guidance and assistance to help you overcome difficult patches in running your company.

Visit local events where you can come face to face with other people in your landscape that have been through similar experiences to you. It might also be worth joining social media groups and forums online, to help you meet new people who aren’t in your immediate area.

4. Be Committed to Learning

The business landscape is constantly changing, no matter which industry you decide to get involved in. Because of this, you need to be willing to learn and adapt at the same rate as your company. Committing yourself to consistent learning, such as taking business management courses, will help you to overcome the little challenges that come along when you start to grow your company. It could mean that you can quickly learn how to use new software that will make your business more efficient, for instance, or that you know how to track down sources of income when your existing revenue dries up.

Being committed to learning also means that you might be able to develop extra skills that make you more desirable in your chosen marketplace. For instance, an online writer could also learn how to create videos and make graphics to give their clients a wider range of services.


5. Have a Backup Plan

Finally, no matter how passionate you are about your business, and how much work you put into making it a success, there’s no guarantee that everything’s going to go according to plan. Sometimes, businesses don’t work out. You might find that after a couple of years, you start to lose more money than you earn. When that happens, you need a backup plan that will allow you to quickly leave your venture behind and try something new.

If you do find that your business starts to fail – for any reason, it’s important not to beat yourself up about it. As upsetting as a failed company can be, it’s crucial to remember that you’ve made the effort to pursue your dreams. If nothing else, the experiences that you got will help to guide you in your future life choices.

EDITOR'S PICK OF THE WEEK

China economic growth

China’s Challenging Search for a New Model of Economic Growth

By Danny Leipziger China cannot continue to rely on exports to drive its growth, but what are the alternatives? China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...

WISE DECISION MAKER GUIDE

POWER INFLUENCERS

Emerging Trends

The Future of Global Trade