Home Blog Page 701

When Money Is At Stake: The Best 3 Platforms For Crypto Staking

staking

Currently, staking has become one of the fully viable ways of moneymaking in the crypto realm, and more and more people try to learn about reliable platforms and coins to stake for higher profits. We know that it’s really easy to get lost in the sea of ads and put your money in the wrong place, this is why we decided to bring you a brief guide on platforms for staking you can trust. Definitely, there are many more services that deserve attention, but you need to start somewhere, so why not with these? They are trusted by users, have a long record of successful operations, and are accessible all over the world. 

Just in case: what is staking?

Staking is locking your crypto coins in the wallet integrated with the platform that maintains the network of some cryptocurrency. Staking relies on proof-of-stake verification of transactions, and people do not have to mine new bits of blockchain to complete the transactions. Staking replaces mining to some extent, it helps to keep the network functioning without putting pressure on power grids and hardware, that’s why it is considered to be sustainable. It is one of the reasons staking gains such popularity with every passing day.

aStake

This is a mono-currency platform with high technical capacity and ROI, that’s why we give it the first place. It’s easy to navigate if you are a beginner and it provides all the necessary explanations about how it works and what your staking obligations and benefits are. So you learn and earn on the go, so to say. 

aStake supports MetaHash coin (MHC) and provides technical assistance in maintaining the hardware and keeping the blockchain payment systems running. That’s why the staking platform is deeply interested in coin success and guarantees the security of your initial fund deposit and the growth of the coin. MHC, in its turn, is a powerful player in the DeFi field that creates new payment opportunities based on the proof-of-stake method. MetaHash develops a whole financial ecosystem, including apps, and NFTs, so watch out for this coin (and coming tokens) closely.

Depositing time and profitability: The depositing period is one year and the annual reward is 17% (in addition to the natural growth of coin price). Coin supply is limited, so you have to wait for your turn to stake it. Once the amount is available, you get them deposited in your wallet, and staking begins 9wth all applying benefits).

Particularities of the platform: although now aStake is a mono-currency platform, it plans to expand its operations into the bigger world of crypto. So later on, some popular and promising coins will be added to the list.

You can pay for your coins via credit card or spend some bitcoin, ether, or tether. Both payment methods are welcomed.

The platform operates in the majority of European and CIS states, so you should not face any troubles while using its services.

Binance

You’ve probably heard about Binance at some point in your life in the context of crypto exchanges, but now the platform has added the option of crypto staking. As a long-standing popular crypto exchange, Binance offers access to around 100 different coins and tokens for staking, which is a big plus if you seek to diversify your portfolio. 

Another advantage is flexible timeframes for staking. You may lock up your coins for the time from 15 to 120 days, just to get the feel of how the process works. The platform supports integrated wallets, so you can perform all necessary operations in one place.

Depositing time and profitability: profitability depends on the coin you select and can vary from 1.5% to almost 70% APY. The brackets are huge, and it is also conditioned by the type of staking (of which a bit later). The lowest APY is offered for the most popular and profitable coins like Ethereum (1.5%), and the highest offered interest is for ASTR (69.76% for 90-days staking) and for ATOM (30.49% for 120-days staking).

Particularities of the platform: the particular side of the staking feature at Binance is the staking mode, or rather modes. The exchange offers locked and flexible staking, each of which has its pros and cons. Locked staking means that you should not withdraw funds during the staking period or you will lose rewards. The minimum time is 30 days, which is not that long, compared to 90 or 120 days of required staking. 

In the flexible staking, you invest in DeFi projects developed by third parties and offered for common staking (staking keeps the DeFi systems running by providing verification). The staking term here may be as short as 24 hours. Yet the downside for it is that the smart contract you are supporting is attacked and you are left with nothing.

So all in all, Binance offers higher yields, differentiated staking time frames, and multiple coins, but it comes with higher risks. 

Crypto.com 

Crypto.com is often cited as a trustworthy platform preferred by many stakers, beginners, and experienced ones alike. That’s why it wins the honorable third place in our ranking. It offers the staking opportunities for more than 40 coins, from known ones to newcomers linked to DeFi. Hence, by staking these new coins you also support the development of decentralized finance and whole new blockchain ecosystems. It is a nice fact to know if you are into meaningful investments and sustainability matters. 

A big bonus of using Crypto.com is that they have their dedicated exchange app, so you can check your deposit or look to withdraw funds right on the go. The platform offers its coin for staking, but it comes with a caveat.

Depositing time and profitability: profitability of staking offered on the platform may look modest compared to some other services, but Crypto.com values its reputation and offers coins that are worth your trust (they are less risky to invest in, so APY is lower). The highest APY offered is 14% for USDCoin. If you stake Cronos (Crypto’s currency), you can get around 12% per annum, and there are even better rates, but to unlock them, you have to stake an equivalent of around $4,000 or higher. 

You can choose to lock your funds for traditional 1 or 3 months or choose the flexible mode. 

Particularities of the platform: payments for the staking can be made using your regular debit or credit cards, but mind the fees are charged. The lowest fee starts at 2.99%. The verdict: the app makes the platform convenient to use, but the highest rates of APY are reserved for its coin Cronos. Mind that.

Conclusion

Well, as you can see, options for staking abound on the web, and if you find a very, very lucrative offer with high yields, look for the fine print. Coins may be risky, or conditions of staking may be unfavorable to you. So before trusting your money to them, read reviews, look through their ToS, and decide what you want to accomplish with your staking. We suggest that you start your journey with the platform we offer, test the waters, and then expand your staking horizons with confidence. aStake (as well as Binance, and Crypto) won’t disappoint you anyway.

 

Disclosure, Dapps and DeFi : Dr. Chris Brummer Discusses New Whitepaper on CoinDesk’s ‘Money Reimagined’

New Whitepaper on CoinDesk’s ‘Money Reimagined’

The latest episode of “Money Reimagined” brought hosts Sheila Warren and Michael J. Casey together with Dr. Chris Brummer as a featured guest to discuss securities law in blockchain technology and Dr. Brummer’s new whitepaper, “Disclosure, Dapps, and DeFi.”

Dr. Brummer

Dr. Brummer is a professor at Georgetown University Law Center and the founder of a major fintech policy conference. He was also a member of the Biden-Harris transition team. His website indicates that he has also worked with a number of global regulatory bodies on financial technology issues, from the CFTC to Finra to ESMA, the European securities regulator.

The arc of the conversation was as historical as it was technical, and extended a conversation originally launched on his Medium blog. During the 1930s a series of Congressional hearings gave birth to what we know today as US Securities Law. The hearings began after knowledge of a cycle of systemic abuse, in which corporate officers and family members were found profiting through trading in their company stock and engaging in tax avoidance schemes. 

Since the 1930’s, one of the major tenets of US securities law has been disclosure. Fast forward to 2022, and those laws remain unchanged, even as the industries they aimed to regulate have evolved considerably. Rapid technological advancements have given rise to a new world of finance in which terms such as cryptocurrency and decentralized finance (‘DeFi’) offer regular appearances. 

Existing disclosure rules are at odds with blockchain technology. The details disclosed often don’t address the things an investor needs to know to invest intelligently in a crypto project. Securities disclosures also result in enormous amounts of information that no one tends to read. 

What is a security?

According to Dr. Brummer, a security is the product of a Supreme Court decision called SEC v Howey which led to the Howey Test. It is not a steadfast rule which states that if you have x, y, or z, you have a security. Instead, it is a multi-pronged analysis. Once each prong within that analysis is satisfied, you have a security. 

Under the Howey Test, an investment contract exists if there is an “investment of money in a common enterprise with a reasonable expectation of profits to be derived from the efforts of others.

Challenges faced due to current disclosure systems

The Howey test states that when all four prongs have been satisfied a company has to disclose information. The challenge is that while US securities law has been growing over the last 70 years, disclosure has evolved into a system where it is meant to be filed and not read. 

Legacy systems such as the EDGAR database within the SEC house several hundreds of pages for each set of disclosure. Those disclosures are meant to be read by institutional investors, and financial analysts, but not the average person. It only becomes relevant to the average person if something goes wrong in case of fraud or misrepresentation in those disclosures.

And it’s not just disclosure delivery. When you bring in DeFi models, the substantive requirements of securities law disclosure don’t map on to the needs of a blockchain. Standard disclosure requirements ask about, or are premised on, corporate governance, whereas if you’re investing in a cryptocurrency or digital asset blockchain governance is far more relevant. They ask about dilution with common equity whereas you actually may want to know about how a governance token works.

Disclosure NFTs

The EDGAR database has its fair share of problems. It has been hacked before, and it is regularly faces technical issues. In one of the most high-profile prosecutions, the system was hacked in October 2016 but did not disclose the hacking to the public until September 2017. 

In his latest whitepaper, Dr. Brummer proposes a novel solution to disclosure delivery systems – programmable disclosures. In a programmable disclosure one would be able to tokenize not just disclosure but also one’s interaction or engagement with the disclosure, and by extension create new use cases that can be designed to enhance technological literacy

Non-Fungible Tokens (NFTs) can be recorded on a blockchain as a digital representation of ownership. Dr. Brummer argues that we can tokenize disclosures that are off-chain and use NFTs as a delivery mechanism to an investor. There are, however, several technical challenges to this proposition, due to the high cost of gas fees on a blockchain. 

Dr. Brummer’s next proposition is even more radical. Earlier disclosure delivery systems were aimed at passively delivering disclosures by storing them in a database. “What if you could create a website off-chain, have someone engage with that disclosure, and gamify that experience, either through a test or a game of some sort?”, he asks. Then, if you pass the test or win the game, you could receive a disclosure token placed in the wallet of the person who passed the test. Through this mechanism you’re creating a credential of an investor receiving a disclosure but also of having engaged with it.

Disclosure DAOs

Dr. Brummer also discussed the possibility of leveraging different kinds of communities and engagement processes, in a way to get past the substantive challenge of analog rules that aren’t working for the investors in the space. To this end, a decentralized autonomous organization (‘DAO’) is a great prospect. 

Participants could create tax-exempt, nonprofit DAOs designed to promulgate disclosure frameworks, tokens, and compliance tools. Different individuals could then submit disclosures, whereas winning disclosures could create several rewards for those individuals.

DAOs can help facilitate integration and unlike other kinds of off-chain bodies they foster an environment of transparency, where different kinds of processes can be automated, saving you a degree of operational costs.

Industry Response to Dr. Brummer’s Whitepaper

Hosts Sheila Warren and Michael J. Casey were interested to know about the broader industry’s response to Dr. Brummer’s novel ideas.

According to Dr. Brummer, he has heard from individuals from staffers of members of Congress, as well as curious regulators, and many others. He believes that all kinds of stakeholders, including policymakers, are awakening to the realization that the current technology stack is analog and outdated. 

Constructively adopting new tools introduces much more durability, flexibility, and responsiveness to the rulemaking process, and it gives regulators as well as founders additional tools in terms of – on the founder’s side- differentiating their dapps and protocols from others and for the regulators – a better understanding of their requirements. 

Dr. Brummer’s whitepaper, “Disclosure, Dapps, and DeFi”, is forthcoming in the Stanford Journal of Blockchain Law and Policy.

Fungible, Non-Fungible and NFTs

NFT

By Komal Motwani, CFP ®

Before we start talking more about non-fungible tokens also known as NFTs, let us first understand, what are these fungible and non-fungible assets?

Fungible means goods or assets that are not unique and can be exchanged / substituted for another identical asset of an equivalent value. Fungibility is not exactly same as a Barter. A barter is when goods and commodities can be exchanged for other products that can be incomparable in value. For example, a farmer may barter (exchange) units of rice for required quantities of apples from another farmer. But in fungibility the farmer will have to interchange with the same product that is rice, of same quality and same value. Fungibility is also not always equal to liquidity either. Liquidity is the ability to exchange an asset, such as a gold ring, directly for an agreed-upon amount of money. Fungibility, on the other hand, indicates an ability to exchange an asset for an equivalent or similar asset.

In the above case, what we call an asset can have both the qualities of fungibility and liquidity. Let’s take an example, if you loaned a $100 bill to a friend, now the friend can return the $100 in denominations of one $100 bill or two $50 or five $20 bills. The value you receive is the same, the form or type of asset is also identical

Now, let us look at another concept called “arbitrage”. An Arbitrage is a strategy used to benefit from the price difference of the same commodity trading on different platforms or exchanges. This difference in pricing may occur due to inefficient pricing or based on demand and supply figures. For example, if the XYZ company May 2022 futures contract is trading at $500 per unit on exchange 1 whereas it is trading at $550 per unit on exchange 2. Upon identifying this opportunity, the arbitrageur can buy the futures contract from exchange 1 and sell it as per the futures contract on exchange 2, thereby making a profit of $50 per unit. This would be an example of a fungible investment. In our day-to-day life we come cross many such fungibility examples.

Now that we understand fungibility, it gets easier to understand non-fungible assets. These assets are unique and one of a kind and requires complex valuations based on their unique attributes and scarcity and cannot be exchanged for another item. For example, diamonds are non-fungible assets due to their uniqueness in size, color, shape, and quality. Hence it is not possible to substitute exact same unit for same price. Another example is baseball cards, each card is assigned a unique value based on it attributes such as edition number, design, player, and rarity. Each card will be valued differently and therefore cannot be exchanged directly with another baseball player card.

That is a lot of information to process. But we still don’t get what are NFTs or Non-Fungible Tokens?

After understanding the basic difference between fungible and non-fungible assets, let’s talk about NFTs. NFTs are basically digital tokens or assets that can be used to represent ownership and value of unique items. NFTs are not cryptocurrencies but they are related and are often used in conjunction with each other. NFTs are frequently bought and sold with cryptocurrencies. No two NFTs are exactly alike. The concept is based on blockchain technology. If you need to understand what is a blockchain technology, then perhaps some technology journals may provide detailed information. But here is a simple explanation by Coinbase, “Cryptocurrencies like Bitcoin and Ethereum are powered by a technology called the blockchain. At its most basic, a blockchain is a list of transactions that anyone can view and verify. The Bitcoin blockchain, for example, contains a record of every time someone sent or received bitcoin. The list of transactions contained in the blockchain is fundamental for most cryptocurrencies because it enables secure payments to be made between people who don’t know each other without having to go through a third – party verifier like a bank”. In other terms, a blockchain is a digital ledger that stores any kind of data such as NFT ownerships, cryptocurrencies etc. The stored data is public or decentralized but encrypted to ensure privacy of the user is not compromised and data cannot be alerted.

A few examples of NFT’s are, artwork, music composition, gaming & family heirlooms.

Artworks such as paintings are valuable and are one of a kind. But digital files can be created easily and duplicated multiple times. NFTs can avoid those issues, non-fungible tokens assist to protect the artist’s artwork by creating tokens or digital certificates of ownership that can be bought and sold. These tokens are unique and not divisible. An Artist can even claim royalties for the future proceeds after his/her original artwork is sold. This process allows a profit percentage to be paid to the artwork’s creator every time the NFT is sold or changes ownership. NFT’s can have only one owner at a time. Say if you purchase an NFT of an artwork and the ownership of the unique token is transferred to your account. The token proves that the copy of digital file is original, and your private key is the proof of your ownership. The artist’s public key serves as a certificate of authenticity for that artwork, and he can be paid royalties each time the owner changes. This entire system benefits the creator, and it also provides authentic value to the buyer.

We are living in an ever evolving innovative, technological driven digital world. NFTs are providing a solution for digitalizing ownership and property and allowing proper storage of the precious and rare artefacts. However, NFTs are discretionary assets and are based on demand rather than fundamentals. The future of this entire market will depend on people’s interest and understanding of the blockchain technology.

With the advent and acceptance of cryptocurrency, NFT’s have gained immense popularity. However, whether they evolve and become a part of our daily lives or not, I believe they are here to stay.


About the Author

With over 10 years of experience in the fields of Investment and Financial Planning, Komal Motwani has worked and studies in institutions across globe, from India to Singapore and the US.

Komal Motwani, CFP ® is a senior investment analyst at Yanni & Associates Investment Advisors, LLC., a Pennsylvania-based registered investment adviser. Information presented is for educational purposes only and does not intend to make an offer or solicitation for the sale or purchase of any specific securities, investments, or investment strategies.  Investments involve risk and, unless otherwise stated, are not guaranteed.  Be sure to first consult with a qualified financial adviser and/or tax professional before implementing any strategy discussed herein

Hopewell – Reliable Logistics Services in Canada

Reliable Logistics Services

Hopewell is a logistics services provider based in Canada, known for its reliability of services. The said firm has served Western Canada for more than a couple of decades. It was founded back in 1996, and since then, it has served customers with a wide range of items to deliver. It serves as the constituent of Hopewell Group of Companies, a big corporate name in Canada.

As there are a lot of firms offering logistics services, customers look for a company that offers them relative perks compared to others. Hopewell serves them in this regard through exceptional services, offers solutions to various problems under a single roof, and gives logistics services a touch of innovation. Hopewell has the edge over other services providers in serving top-notch brands and has a clean track record.

Here is a brief overview of Hopewell’s services, the pros of availing them, and how it can prove the best for you.

Finding Easy Solutions to Modern Problems

If you are looking for a logistics company in Canada, you should consider the various aspects of their services. In the age of fast-growing competition, it is no more the speed or reliability of the services that counts. Instead, the customers have to look for what else the services provider has to offer. Hopewell is fortunate as it has got much to offer to its customers.

These include deploying the latest technology, friendly and reliable staff, the best available warehouses, and modern vehicles that ensure that deadlines are met. What makes it further enhanced for the customers is the years of experience that few companies in the logistics business have got. Hopewell Logistics is part of the larger body of Hopewell Group of Companies, thus learning from the collective experience.  

Hopewell Logistics believes in offering services that are always open to improvement. The management of the said group regularly considers reports to see the possible improvements that could be made to services, leading to customer satisfaction. Customers can rely on it for their supply chain needs as Hopewell can always be reached, and the customer can get real-time updates about the items’ delivery.  

Distinctions Hopewell Features

Hopewell Logistics is known for the distinctive features that make its services the best. Here are some of them that can intrigue the customers.

Dedicated Warehouses and Order Fulfillment

Hopewell offers dedicated warehouses where the items to be delivered are kept securely. A special management team ensures no harm is caused to the delivery items. Once the customer registers the delivery of the items and submits them, they are stored in the required warehouses as per the delivery timeline.

As it is a third-party logistics firm, the role of dedicated warehouses is important. So, in comparison to other firms, the services of Hopewell are considered the best. Some of the best brands use Hopewell’s services because of their dedicated services.

Transportation Management

The transportation management process at Hopewell is properly organized, and the communications team keeps the complete details of the delivery status. Thus both parties that are involved in the transaction can be kept updated. The transport process of deliveries is also one of the most reliable as the company owns the used automobiles and the drivers are regular employees.

Continuous Improvement

Hopewell looks for consistent improvement in its services. The main aim is to bring perfection to services so that the customers find them reliable. As the market grows competitive, the improvement helps Hopewell keep itself abreast of the latest developments.

The improvement is not only in the domain of services but also in the technology that makes it possible.

Network Evaluation and Design

Hopewell helps with evaluating and designing services that businesses need to grow. It has experience with various big brands in the market, and for this reason, it can help improve the network for businesses.

Value-Added Services

Hopewell offers logistics services and helps companies with value-added services like transition management, co-pack management, IT services, etc. Thus, the customer firm will be able to benefit from multiple services in a single place.

One Place to Serve Your Needs

Hopewell Logistics is a logistics firm in Canada that offers multiple services. It is a third-party logistics firm, so it has experience dealing with top brands in Canada and serving them in deliveries. It also offers various other services that businesses can avail of at relatively better prices. The affordability, reliability, and quality of its services make Hopewell the best choice for businesses. 

When Should You Consider Borrowing to Pay for a Dental Practice?

dental practice

Borrowing a loan for your dental practice can seem daunting. Can you afford to borrow the money? Is it going to have a detrimental effect on your practice? Will you miss payments on time? Many questions come to mind when considering borrowing money for your practice. While considering borrowing to finance a dental practice, it’s crucial for practitioners to prioritize essential supplies such as dental face masks for infection control. Providers like My DDS Supply offer a range of quality products to ensure a safe and compliant practice environment. It’s important to manage these skillfully to make the most of your new venture. This guide outlines many things to consider before taking out a loan and how you can get the best use of the money when it arrives.

When You Want to Expand Your Business

There are plenty of reasons to consider taking out a loan when you’re expanding your business: from building a better practice for the future of your patients and the reputation of your practice to building a better practice for the future of yourself. The expansion of your business gives you more opportunities to improve, which leads to more satisfied patients. This is not only good for business, but it’s also good for your patients.

By borrowing money for your new facility, you’ll be able to offer all these things without putting yourself in debt or overextending yourself financially. With a new facility, you’ll have enough space for extra treatment rooms and other amenities to make the practice more appealing to potential and existing patients. Fortunately, getting dental loans for fair credit is pretty easy nowadays.

When Purchasing Dental Equipment

The high cost of dental equipment is probably the top reason dentists decide to lease it instead of financing it. But with the right lender and loan, it’s possible to get a loan for your dental practice while still being able to make small upgrades to your office now and then—and sometimes even to get the new equipment you really need! The key is finding a loan program that allows you to take out as much or as little money as you need for purchasing dental equipment.

Many people have the idea that their dentist’s office is a no-risk investment. However, the truth is that dentists will still encounter the same problems when buying the equipment as any other business owner: in addition to paying for the equipment itself, there are also installation costs, training fees, and sometimes even refunds for returned products. These little expenses are negligible for some dentists and don’t prevent them from getting what they need. But others may find themselves worried about taking on significant debt on top of all those other expenses. If this sounds like you, then borrowing a loan might be your best option—especially if you can get a loan with low-interest rates, manageable monthly payments, and an affordable amount of money to borrow.

When You Want to Move Your Practice to a New Location

When you’re a business owner, you face many challenges when trying to grow your company. One of these challenges is being able to afford the costs of starting a new location, including everything from acquiring new real estate to hiring employees and potentially more. That’s why it’s important to have a loan in place before plunging into an exciting new chapter of your business.

You might also want to consider how long it will take for your business to start making money. The reason for moving is probably because your current location is not working out as well as you’d hoped, so it makes sense that things will take longer to pick up in your new location. If you can’t afford to wait, getting a loan is the best choice. It’s better than moving into debt by selling off other assets or opening up your business while still trying to pay off debt from previous ventures.

When You Want to Update Your Dental Equipment

For many dental practices, the cost of updating their equipment will be more than they can afford. However, having properly maintained equipment is not just a matter of pride and professionalism; it’s also a matter of public safety. Many dentists opt to use outdated machines because the cost of upgrading—even if the new machines are more efficient, more accurate, and more comfortable for patients—is too great a burden for them to bear alone. But when you’re borrowing from a bank or other lender, you can do it with their help. Taking out a loan to buy new dental equipment can be an excellent decision if it’s done right: don’t sell yourself short, and make sure that you have a good plan in place before you do anything.

When You Need to Make an Emergency Purchase

When you need to make an emergency purchase for your dental practice, you might be tempted to use a credit card or take out personal loans. While these two options might seem viable, they’re not really the best for your dental practice. If you want to avoid unnecessary interest rates and fees and keep your financials in order, consider borrowing a proper loan rather than using credit cards.

Borrowing money to pay for a dental practice may seem risky, but it’s important to consider the benefits you’ll be receiving in the long run. First of all, there’s a good chance that your earnings in your new practice will dwarf what you’re earning at your current job—and that means increased cash flow. Second, you can take control of your own business, which is more than likely going to be very rewarding in the long run. Overall, if you can manage to handle the risk and reap the benefits of borrowing money, then, by all means, do so.

How to Improve Your Credit Score

Credit Score

A bad credit score will impact your life in unimaginable ways. It will stop you from reaching your dreams of owning a house, getting a car, or starting a business. Many factors affect your credit score, including bad credit car finance, missed payment dates, and bankruptcy filing in the past. Defaulting on past loans is another reason you have a bad credit score. 

Should you be worried about it? Yes, very much so. Your credit score tells lenders if you can be trusted as a borrower. Lenders measure borrowers’ eligibility for a loan based on their credit scores. The lower your credit score, the less likely you’ll be approved for any loan. If you get approved for a loan with a bad credit score, brace for a high interest rate. 

What Is a Good and Bad Credit Score?

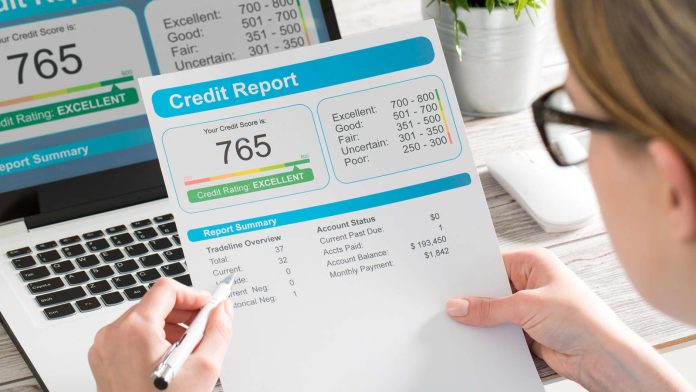
Credit scores typically range between 300 (poor) and 850 (excellent). Credit institutions follow different formulas, but on average, scores above 720 are ideal, while scores below 630 are seen as problematic. Higher scores indicate good credit history, including paying dues on time, low credit use, and long credit history. Lenders are wary of low credit scores because these are risky borrowers. There’s a risk that they might not pay on time or not pay at all. 

When consumers are aware of their credit scores, they will most likely try to correct them. They understand that good credit scores are essential for their plans. Those who aren’t aware of how credit scores impact their lives are likely to fall into the debt trap. 

Review Credit Reports

Make a habit of reviewing credit reports. You can get a report from three major national credit bureaus: Equifax, Experian, and TransUnion. This is free once a year. Review the report and see which factors are hurting your score and history. You might not notice them, but some that affect your credit score are late payments, high credit card balances, collections, and judgments. 

Pay Credit Balances Strategically

Do you know about credit utilization? It is the unused portion of your credit card. The higher the unused portion of the card, the better your credit score will become. As general advice, you should use less than 30% of your card’s limit. The lower your credit utilization rate is, the better. 

A surefire way to bring your credit utilization down is to pay more than the minimum balance due of the card. You can do this in two ways: pay down the balance before the billing cycle ends or pay several times throughout the month to keep the balance low. 

Ask for Higher Credit Limits

So, you cannot pay the balance in full yet. The perfect solution is to ask the credit card company to increase your limit. The balance stays the same, but the limit increases. This will improve your credit utilization rate. However, you can only request a higher credit limit if you prove that your financial situation has improved through a higher salary. 

Pay Bills on Time

There is no worse thing to do on your credit report than not paying your bills on time. No matter what you do to improve your credit score, this will not be enough if you pay late. Late payments can stay on your credit report for more than seven years. 

Did you miss a payment? Call the creditor immediately if you miss a payment for more than 30 days because this allows them to report it to the credit bureau. Promise to pay the due immediately and ask if they consider not reporting the missed payment. 

Dispute Erroneous Entries in the Credit Report

You will be surprised to realize there could be a lot of erroneous entries in your credit report. This happens when you don’t check your credit report regularly. For example, you’ve already paid a debt, but it hasn’t been crossed out from your credit report. That could be why you have a lower-than-average credit score despite already clearing out most of your debts. 

Someone else’s credit activity could have been mixed with yours. Make sure that all entries in your report are yours. If you see negative information that is not yours or is too old to be included in the report, write the credit bureau and have it slashed out of your report. 

Remember that it takes some time to remove an entry from your credit report, so you’ll wait for a long time before seeing an improvement in your credit score. Most credit bureaus have 30 days to investigate a dispute. You should keep in touch with the bureau to monitor the process. 

Remove Collections Accounts

A collections account is a serious negative mark on your credit report. It means you haven’t paid a debt to the point that the lender had to pass it to a collection agency. Talk with the collector if it is possible to settle the debt without them reporting it to the credit bureau. Of course, a plea doesn’t always work, but it’s worth a try to have a collection eliminated from your credit report. 

This works fast to improve your credit score. Once the collection agency reports that the debt has been paid off, the credit bureau will remove it from your record. That will give you a higher credit score. If you haven’t settled the total amount of the debt, you can still ask the collection agency to report that you have negotiated the payment terms. 

Conclusion

It is not impossible to improve your credit score. There are many ways to do it. However, the first thing you have to remember is not to let your credit score go bad. If you pay your dues on time, don’t spend more than you should, and don’t maximize your credit limit, you shouldn’t have a hard time maintaining your credit score above the average level and thereby become eligible for low-interest rates. 

5 Tips for Being a Business Success

Group of colleagues celebrating success

What does it take to be a successful businessperson? If you dream of thriving in the business world, you may ask yourself this question often. The tips below can help you realize your ambition.

Define Success

Perhaps the most important step is to decide what success means to you. Is it running your own business? Is it an office in the executive suite? Do you want to run one of the top global companies, or do you want to be the president of the local bank in your hometown? It’s important to not let others’ ideas of success guide you here. Be true to yourself.

Get Your Degree

You may need a bachelor’s degree even for some entry-level jobs, and in most cases, you will need one at minimum in order to climb the corporate ladder. Eventually, you may want to get an MBA or another graduate degree as well, but these are usually better obtained after some years in the workforce. For now, focus on getting your undergraduate degree if you don’t already have one. You can apply for a private student loan to supplement federal aid, grants, and scholarships to pay for your tuition and other expenses.

Create Value

Whether you are an entrepreneur or you work for a company, think in terms of creating value. If you run your own business, that means creating a product or a service that your customers will want because it adds value to their life. If you are an employee, it means creating value within the workplace. You can do that in many different ways. It is not just about what you produce. You might be good at keeping morale up in your department or at training new employees.

Be Goal Oriented

Setting goals and then working toward them will help you achieve your specific aims. You need to think in terms of breaking down your big goals into smaller ones. If you eventually want to be the head of a major global corporation, think about the steps you will need to take to work your way up the ladder to that position, and frame those steps in the form of short and medium-term goals along the way. A best practice is to write down goals that are concrete and have a specific time frame. This can help you gauge your progress and make adjustments if you need to.
Network

Whatever sector you work in, networking is key to your success. You can arrange a networking event even while still being a student. When you are good at it, you will find that there are very few places where you can’t network and that it goes well beyond something that you do at work or at professional gatherings. Contrary to the way some people interpret networking, it is not about trying to sell something or yourself to others or about making shallow connections. Instead, it is about building relationships over the long term, and you can return to these relationships again and again throughout your life.

Best Ways to Keep Your Thoughts Organized 

Organized Thoughts

The proper organization of your thoughts can help out in all sorts of different areas of your life, but there is no doubt that your mental wellbeing is one of them. Not only this, but it can also help you to excel while you are at work – ensuring that you do not have a million and one different elements jumbling around your head at all times. Keeping your thoughts organized can be done in a few different ways, but once you have found a method that works for you it is certainly going to be important that you stick with it as closely as possible, ensuring that you keep up the good habits that you have developed. Here is some advice that can help to get you started in the field of getting your thoughts organized. 

Find Your Method of Storing Your Thoughts 

There are plenty of different methods involved in organizing your thoughts that can prove to be highly effective. Some people prefer to make a voice memo rather than writing a thought down as this simply works in a better way for them. Many find writing thoughts down a useful way to stop their mind feeling jumbled. To begin with, you could write them on post it notes and scatter them all around your desk. Alternatively, it may help you to write them up in a private journal that you keep tucked away inside a desk drawer. It could be the case that you would like to write things down in the old-fashioned way with a pen and paper or prefer to rely on tech instead. You can check out the best knowledge management tools as they can prove to be highly useful. Ultimately, you are never really going to know what works best for you unless you experiment with a few different possibilities. So, now is certainly going to be the time to get started.

Work Out When You Do Your Best Thinking 

Everybody does their main thinking at different times of the day and you have to work out what works best for you on this front as well. For some people, it could be the case that you prefer to have a ‘brain dump’ after you have just woken up in the morning, which means that you get everything down on paper without really considering it too deeply. For other people, this works as a way of getting your thoughts out before you turn in for the night. On the other hand, you may well find that it is better if you are carrying a pen and paper around with you at all times as you never really know when an idea is going to strike. 

Go Back Through What You Have Written Down 

After a sufficient period of time has passed (usually a few hours is going to be the minimum useful amount of time) you can then go through the process of going back through everything that you have written down or otherwise recorded. Within it, you are likely to find some thoughts that keep coming back time and time again. If these are negative ones, you can really start to pick up and pinpoint where they are coming from in the first place. At the same time, if you are doing this process to help inspire you and come up with ideas that you cannot normally find, you need to work out where the nuggets of gold are coming from within the mass of ideas that you may have written down. Ultimately, this process of self-reflection is simply not going to happen when you are thinking your thoughts without getting them down in a physical format. You should certainly treat it as a learning experience and a privilege to be able to go through this process in the first place. 

Ensure it is a Habit that Sticks 

The only way that you are going to be able to achieve the real and sustained growth that you are likely to be hoping for is to ensure that you have a habit that sticks rather than one that you are simply able to get rid of at the drop of a hat. For this reason, it is so useful to keep writing your thoughts down at the same time as it will become a habit rather than a chore. At the same time, you should also keep using the same method of always recording your thoughts as this also helps out when it comes to habit forming, which is a highly important part of the overall process. 

Talk About and Share What You Want to 

Beyond all of this, there may be some thoughts that you would like to share with other people, and once you have been through them in your own head they can often take a much more solid form that is easier for other people to make sense of. The process of sharing can prove to be one that is highly useful from a mental health standpoint, if this is why you are doing it in the first place. At the same time, if you are doing it for work purposes, there is no point in going through all this work without sharing the thoughts that you have worked so hard to accumulate. 

Hopefully, the advice that has been passed on in this blog post proves to be useful when it comes to recording your thoughts and reaping the benefits of them. First of all, you need to find a method that proves to be the most useful to you, and you will probably have to experiment with a couple of different options to begin with. Once you have done this, you need to work out when you are most fertile in terms of your thoughts, as well as analyzing the thoughts that you have put down on the page. Ensuring that the habit sticks is a stage that can prove to be the most challenging, but you can then talk about and share what you want.

Factors To Consider When Shopping For A Personal Lån

Personal-Loan

You won’t get many unsecured loan options if you have low credit, and you could have to have a co-signer to get accepted for a loan. It’s a good idea to understand more about credit ratings before applying for a loan.

Types of Loans

Lenders provide a variety of unsecured lines of credit, each with its own set of benefits and drawbacks. Look for a loan that fulfills your requirements while keeping your expenditures low. The most basic sort of unsecured loan is the signature loan. The loan is backed just by your signature, or your promissory note, as the term implies. These loans are available from banks and credit unions, so you can spend the funds on whatever you like. Just make sure you’re informed of any potential issues.

If you default on your payments, the creditor has the right to seize and sell your home to cover its costs. Because there is less danger to the lender, secured loans have the lowest rates of any loan. Unsecured loans operate in a different way. They don’t ask for any kind of security. Based on your credit score, salary, existing debt, and other variables, lenders evaluate your loan application and determine whether or not to provide you a loan.
Unsecured loans are riskier for lenders since there is no collateral. As a result, the interest rates on unsecured loans are often greater than those on secured loans. If you have fair to exceptional credit, though, you may still be eligible for low-interest loans. If you miss a payment on an unsecured loan, it doesn’t mean you won’t face penalties; it only means the lender won’t be able to confiscate your property. Instead, they can take steps like sending you to collections or garnishing your income in the context of some student loans.

For unsecured loans, there are some requirements that must be met. Unsecured loans are a typical occurrence. You’re dealing with unsecured debt if you’re thinking about taking out federal or independent student loans, or if you want to refinance your school loans.

Installment loans include both student loans and refinance loans. That implies you have a defined payback time and make monthly installments until you have paid off the amount.

When it comes to private student loans and refinancing loans, lending institutions that you’ll be able to repay them. The lender will consider a number of variables before evaluating your application to determine whether or not to grant you a loan and, if so, whatever the interest rate must be:

Credit rating: Your credit score is a 3 figure that reflects your borrowing responsibility. You can click here for more information on how your credit score is figured out. Lenders frequently demand loan applicants to have a credit score of 650 or better.

Income: Your income will be used by lenders to decide if you can manage the loan installments. Some lenders have minimum income requirements. You may, for example, compare the minimum income requirements for Purefy’s student loan refinancing lenders here.

The debt-to-income ratio is a measure of how much money you owe compared to how The percentage of your monthly income that pays into debt is known as your debt-to-income (DTI) ratio. To qualify for a loan, most lenders have a specific DTI ratio that you can’t surpass.

Loan term: The length of time you take out a loan can have a big influence on your interest rates. In general, the greater the period of your loan, the greater the interest rate.

Loan---Cosign

Unsecured Loans and Co-Signers

Lenders take on more risk with unsecured loans since they don’t demand collateral. Lenders impose stringent underwriting, described at https://www.investopedia.com/terms/u/underwriting.asp,  criteria to reduce the risk of losing money. If your credit isn’t great, or if you’re just beginning out and don’t have enough money, you might not be able to get a loan at all. You can end up with a high-interest percentage if you do. 

If you default on the loan, your co-signer — generally a friend or family with strong credit and a steady salary — intends to make payments. Adding a co-signer to your unsecured loan application reduces the lender’s risk, enhancing your likelihood of getting accepted and qualifying for a slightly lower rate.

Trying to Find an Unsecured Loan

You don’t have to think about keeping up any assets as collateral for student loans or refinancing loans because they are unsecured loans. Because unsecured loan providers base their judgments and rate of interest on your creditworthiness, shopping around and comparing offers from several lenders to find the best rates is a smart idea. It’s important to shop around for unsecured loans, and billigste forbrukslån uten sikkerhet, so that you may find the right loan for your needs and income. 

Unsecured loans are all those that don’t require collateral, such as a house or car, in order to be approved. Instead, lenders make these loans driven by personal information such as your credit history, salary, and existing obligations. A lender cannot seize any of your personal possessions if you default on an unsecured loan, unlike a mortgage or vehicle loan. Alternatively, the lender may pursue a lawsuit, but most of the damage will be done to your credit.

An unsecured loan may be used to pay for nearly anything, but the greatest personal loan aids in the achievement of a financial objective without adding unsustainable debt. Learn about the benefits and drawbacks of unsecured loans, as well as what they may be used for, on which you can get one, and how to obtain them.

Unsecured Loans and How They Function

You take out a line of credit in a large sum, anything from $1,000 to $100,000, and pay it back in monthly payments, with interest. Unsecured personal loans include interest rates ranging from roughly 6% to 36%. Any upfront expenses, such as origination fees, that some lenders impose for completing a loan, are included in the loan’s APR. The origination charge normally ranges from 1% to 10% of the amount borrowed. Late fees, prepayment costs (when a lender charges you for paying off a loan early), and fees for a failed payment are all possible loan expenses.

Unsecured loans are often available via online lenders, institutions, or credit unions. These lenders will record payments to Equifax, Experian, and TransUnion, the three major credit agencies. On-time payments may help your credit, however late payments will most certainly harm it. 

The Advantages and Disadvantages of Unsecured Loans

Pros

With an unsecured loan, you may expect to acquire your money faster than even a secured loan, which might require extra documentation such as evidence of title for a car. If you default on an unsecured loan, unlike a secured loan, the creditor cannot seize your property.

Borrowers with good credit (FICO scores of 720 to 850) may be eligible for rates on secured loans. Unsecured loans have annual percentage rates that start at roughly 6%.

Loan---Credit

Cons

Personal loans are generally riskier for lenders, therefore interest rates may be higher, especially for customers with poor credit.

If you fail on an unsecured loan, it will have a negative impact on your credit score. The remaining balance of the loan may be sold to a collection agency, resulting in collection calls from an unknown firm and the possibility of you being sued in an attempt to recover the debt.

Unsecured Loans Come in a Variety of Shapes and Sizes

Unsecured personal loans can be used for a variety of objectives, such as house improvements or weddings, but they all have the same basic characteristics. They generally range from $1,000 to $50,000 and thus are repaid over two to seven years in set monthly payments. 

Loans that will help you better your financial situation: Loans for home improvements and debt consolidation might help you save money. You may use a home improvement loan to make improvements to your home that will boost its worth. A low-interest debt consolidation loan might be a less expensive alternative to pay down current debt. These are some of the most effective uses of a personal loan.

Loans for non-essential costs: Lending institutions normally advise saving for non-essential items such as vacations. If you need to fund this type of cost, a personal loan may be a better option than a line of credit. Compare all of your possibilities and only take out a loan for these reasons if it is the most affordable.

Unexpected expenditure loans: Unsecured loans should only be used as a last option for things like emergencies and medical expenditures. You most certainly have less expensive options in mind. In an emergency, you probably have cheaper options, such as a medical payment plan or a regional resource. If you want a loan quickly, seek a loan that provides quick funding, cheap rates, and low costs.

Loans---Lender

Where Can I Find Unsecured Loans?

An unsecured loan can be obtained via an internet lender, a bank, or a credit union. Each sort of lender will have its own set of advantages and disadvantages, as well as different rates, periods, and loan amounts. Consider their rate of interest as well as the monthly payment when researching loans from different lenders. To acquire predicted terms and payments depending on the credit score, use a personal loan calculator.

Lenders on the internet

Pre-qualification is a quick procedure that entails inputting basic personal information and receiving a response within minutes from most online lenders.

Bitcoin’s Market Worth and Capital Value are Rising Due to Increased Demand

Bitcoin

Therefore, if the network hash rate decreases your share of network nodes, the Bitcoin price can help offset some of these losses. Over the previous year, the Bitcoin price has increased at a much slower rate of 0.3403 % daily basis. Based on your predictions for the estimated price over the next year here, we propose adding a specific Currency value into our calculations. The price has been falling for the bulk of the year, which should have been included strongly into your calculations.

Extraction might be a profitable source of passive income. However, there are a number of factors that determine mining profitability https://bitpapa.com/, many of which are outside your control. Some people appear to believe that by investment in a few Bitcoin miners, they would be able to quit their 9-to-5 jobs, but this is not always the case.

How can you know if mining is the right job for you?

Before you invest your money, it is vital to understand the constantly changing aspects that determine mining profitability. Nonetheless, if you play your cards well, you may be able to generate a substantial passive income. Aside from impact on Bitcoin, it is vital to consider your ROI period before buying. Some equipment might never pay for itself. The additional parameters stated below are important in determining your ROI period. You may estimate your revenue with the above calculator depending on the ASIC you’re currently utilizing and your electricity expenses.

For good reason, the original investment in excellent cryptocurrency mining is most certainly one of the issues holding you back. Mining equipment is expensive. The high cost of specialised mining equipment ASICs (Application Specific Integrated Circuits) is largely to blame for China’s centralised structure of Bitcoin mining. Although you may generate litecoin with Bitcoin mining equipment, it is usually more easy to obtain litecoin through an exchange.

Large mining companies run mining farms with hundreds of ASICs. One more ASIC, let alone hundreds, is beyond of reach for the average Joe. Instead of just being spreading out throughout the globe, the validation process is now monitored by fewer individuals than was originally planned at the time of Bitcoin’s inception.

Frame Rewards and Transaction Fees

When a block is validated, the user who contributed the necessary processing power is rewarded with newly minted BTC and merchant accounts. On the most basic level, hashrate is a way of quantifying how much computing capacity everyone around the world generates to Bitcoin mining. Miners use their computing power to defend the network, document all payment information, and get bitcoin in exchange for the service  The higher a single Bitcoin mining computer’s hashrate, the more bitcoin it will mine. The higher the hashrate of the whole Bitcoin network, the bigger the total number of devices and the more difficult it is to mine Bitcoin.

You cannot buy bitcoin with a credit card at all markets or credit card providers. This is due to the assumed volatility of various cryptocurrencies. You will almost probably be charged fees when purchasing bitcoin, so be sure to regularly in your account to cover charges.

Imagine a blockchain to be a technology platform that is shared by nodes connected to a huge data network. A blockchain maintains information electronically and protects the security of the data it records, fostering trust.

Blockchains divide the data they store into pieces called blocks. Each block has a certain capabilities and links to other blocks to form what is essentially a data chain. Anything new data needed for a certain blockchain is saved in a new block and added to the end of the relevant blockchain. 

You will need to create your account whether you use a traditional broker or a cryptocurrency marketplace. In many cases, you will be able to do so utilising either a payment mode or a financial system. Certain transactions, meanwhile, may involve a bank transfer or an ATM transaction. Likewise, certain businesses may accept payment using a service like PayPal.

Choosing to buy Bitcoin: 

You should always be careful while shopping for a cryptocurrency exchange. Many people are willing to deceive and defraud you if you enter without thinking. Some virtual money exporters have gone out of business, while others may have been hacked. For instance, the US Executive Branch recently recovered almost $5 trillion in online money taken during a bitcoin exchange assault. It arrested two persons on accusations of attempting to launder money. Over 20 robberies occurred in 2021, with a digital burglar stealing at least $1.2 billion in bitcoins from a bitcoin exchange. Bank robberies, on the other hand, netted perpetrators less than $1 million per theft.

Some equipment might never pay for itself. The additional parameters stated below are important in determining your ROI period. You may estimate your revenue with the above calculator depending on the ASIC you’re currently utilizing and your electricity expenses.

For good reason, the original investment in excellent cryptocurrency mining is most certainly one of the issues holding you back. Mining equipment is expensive. The high cost of specialised mining equipment ASICs  is largely to blame for China’s organizational system of Bitcoin mining. Although you may generate litecoin with Bitcoin mining equipment, it is usually more easy to obtain litecoin through an exchange.

Utilizing a Cryptocurrency Exchange

Bitcoin exchanges, similar to stockbrokers, give the tools required to buy and sell cryptocurrency rather than equities. You should undertake relevant research to determine on a cryptocurrency exchange, just as you would with brokers. Look for a cryptocurrency exchange that allows you to effortlessly buy and sell your coin while charging affordable fees. When assessing cryptocurrency exchanges, consider the cryptocurrencies they support, the pricing, reliability, and withdrawal options. It is crucial to remember that bitcoin investing is speculative and risky. Bitcoin values change, and if you want to sell your cryptocurrencies, you need keep a close check on the market. If you are unsure, see a competent professional.

EDITOR'S PICK OF THE WEEK

China economic growth

China’s Challenging Search for a New Model of Economic Growth

By Danny Leipziger China cannot continue to rely on exports to drive its growth, but what are the alternatives? China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...

WISE DECISION MAKER GUIDE

POWER INFLUENCERS

Emerging Trends

The Future of Global Trade