Home Blog Page 3

Navigating Amid Systemic Global Crises

By Dan Steinbock             

As the IMF and World Bank prepare for their 2026 Annual Meetings in Bangkok, Thailand, the global economy is struggling with a set of systemic crises.

As the International Monetary Fund (IMF) and World Bank prepare for their 2026 Annual Meetings in Bangkok, Thailand, IMF Managing Director Kristalina Georgieva faces an overwhelming accumulation of concurrent global shocks.

For small and medium-sized powers—especially highly exposed, export-driven, or energy-importing nations—the upcoming discussions are overshadowed by systemic vulnerabilities.

There are half a dozen headaches that will keep Georgieva and the meeting participants awake at night.

Surging debt burdens and elevated borrowing costs

Renewed debt threats are heavily penalizing developing and middle-income economies as advanced markets keep interest rates higher for longer, thanks to unwarranted conflicts, and rearmament rather than appropriate fiscal support.

First, the cost of price stability is rising. The monetary tightening by major central banks to fight lingering inflation has triggered a severe spike in debt-servicing costs globally.

Second, there’s the challenge of fiscal consolidation inertia. Global public debt is on track to surpass 100% of GDP by 2029. Georgieva has repeatedly flagged that while there is universal awareness of the need for fiscal discipline, governments are failing to take sufficient concrete action.

Austerity won’t resolve effectively secular or geopolitical challenges, but it can worsen each.

However, the problem is that this tendency for governments to prolong austerity measures or spending cuts even after an economic crisis has passed is highly counterproductive because it is fostering a self-reinforcing cycle of economic stagnation. Austerity won’t resolve effectively secular or geopolitical challenges, but it can worsen each.

As long as fiscal discipline is equated with sheer austerity, challenges will compound. Small and medium powers are already running out of fiscal buffers to shield their populations.

While advanced economies possess deep local bond markets to absorb massive fiscal stimulus packages, emerging and developing economies face high external refinancing costs that squeeze space for vital development spending.

Geopolitical energy shocks and fractured supply chains

Escalating geopolitical conflicts continue to roil international markets, driving down projected global growth to 3.1% for 2026.

First, energy importers are ailing. Escalations in the Middle East have repeatedly shocked oil and liquefied natural gas (LNG) markets, spiking Brent crude prices and squeezing energy-importing, low-income nations.

Second, Asia’s supply chain vulnerability has taken a severe hit. Ongoing maritime and regional trade blockades have created severe physical breakdowns in supply chains. For mid-sized Asian manufacturing hubs, shortages of essential industrial inputs and rising fuel costs directly threaten economic stability.

While advanced economies lean on diverse trade networks and strategic oil reserves to buffer shocks, energy-importing emerging and developing economies face sudden current account deficits and severe domestic price spikes.

Tight restrictions on emergency finance

As economic pressures mount, the demand for IMF and World Bank financing has surged dramatically.

First, near-term demand for IMF emergency financing is expected to reach up to $50 billion. However, the pool for concessional (low-interest) terms targeted at vulnerable nations is tightly constrained.

Second, the G20 Framework for Debt Treatments suffers from severe delays, structural gridlocks and coordination failures. Smaller nations are watching high-stakes restructuring programs closely to see if frameworks can actually deliver rapid relief, or if standard development funding will continually be diverted into short-term emergency firefighting.

While advanced economies function as the global financial architecture’s core balance-sheet absorbers, emerging and developing economies remain dependent on sluggish international frameworks to access nimble, affordable credit.

AI capital flight and deepening cyber risks

Technological transformations are introducing structural imbalances that smaller economies are ill-equipped to handle.

First, the global frenzy to invest in Artificial Intelligence (AI) threatens to pull vital private capital away from traditional emerging markets, compounding local labor market disruptions. Georgieva has expressed concerns over leverage and circular financing risks within AI investments.

While advanced economies capture the lion’s share of venture capital and productivity gains from concentrated technology markets, emerging and developing economies face severe capital outflow risks and sudden labor disruptions.

Second, the “Bangkok Blueprint” is evolving, but only as damage is spreading. To counter the exponential growth of cyber risks to the international monetary system, the IMF and World Bank are using the Bangkok meetings to launch the Bangkok Blueprint—a joint policy framework designed to build cyber-resilience against digital financial fraud.

For Georgieva and ASEAN policymakers gathering in Bangkok, this evolution moves cybercrime from a law enforcement issue to a systemic financial risk, directly undermining banking confidence and regional economic stability.

Fragmented multilateralism and deglobalization

A persistent undercurrent for the Bangkok meetings is the fracturing of global trade. Declining trade volumes, protectionist policies, and tariff retaliations are chipping away at the export engines that small and medium-sized powers rely on to grow out of debt.

When advanced economies try to pivot toward protectionist subsidies and industrial onshoring, trade-dependent emerging and developing economies lose their primary pathways for upward economic mobility.

Technological transformations are introducing structural imbalances that smaller economies are ill-equipped to handle.

This macro-economic isolation is compounded locally for vulnerable nations, particularly in Southeast Asia and its island archipelagos like the Philippines, where severe climate shocks, including intense El Niño cycles and catastrophic typhoons, routinely decimate agricultural supply chains.

IMF’s chief Georgieva continues to urge member states to abandon trade barriers, warning that a fragmentation of the global economy will ultimately leave the most vulnerable nations isolated.

As she stays awake nights, perhaps she sees nightmares of Don Quixote fighting the windmills.

About the Author

Dr.-Dan-Steinbock-1Dr. Dan Steinbock is an internationally recognized strategist of the multipolar world and the founder of Difference Group. He has served at the India, China and America Institute (USA), Shanghai Institutes for International Studies (China) and the EU Center (Singapore). For more, see https://www.differencegroup.net 

How Shauna Wekherlien and Tax Goddess are Rebuilding Tax Strategy for the Top 1 Percent

Key Takeaways

  • New Tax Goddess clients begin with a one-hour review of old returns, followed by a review that spans more than 900 separate line items.
  • Tax Goddess ranks legal strategies against each client’s stated risk appetite rather than offering a single standard plan.
  • Tax Goddess pricing is available in three fixed tiers ranging from $10,000 to $350,000, quoted in full before any work starts.

When prospective clients come to Tax Goddess, the process starts with a one-hour consultation. The team reviews earlier returns, looking for opportunities where the owner may have paid more tax than necessary. If no significant opportunities are found, the team says so transparently. Once a client signs on, the relationship opens with a review that spans more than 900 separate line items. It takes in income, business entities, property, and whatever the owner intends to do over the next decade. What comes back is a picture of the client’s finances through a tax lens, with each element positioned like a piece on a chessboard.

Shauna A. Wekherlien, CPA, MTax, CTC, CTP, CTS, opened the practice in 2004. Over those years, her team has documented client savings of more than $2.35 billion, alongside an average client tax rate of 6.92 percent. By the firm’s own reckoning, results like those rank her inside the top 1 percent of tax strategists. Of the 660,000 CPAs working in the United States, she is among the 15 who hold her designation.

Reengineering the Traditional Accounting Model

Years of preparation preceded Shauna’s opening a firm of her own. A Master of Taxation followed her CPA license, along with a run of specialist designations. She put that education to work at major accounting and consulting firms, including KPMG. Her own practice grew out of those years into a consultancy shaped around entrepreneurs. Today her client list runs to wealthy families nationwide, described in the trade as High-Net-Worth (HNW) and, at the upper end, Ultra-High-Net-Worth (UHNW).

One principle sits under the rebuild. Compliance work means filing returns after a year has already closed. It can do no more than report a bill the owner has finished creating. Planning done while the year is still open moves that bill. The same reasoning carried into how the firm charges, and hourly rates gave way to fixed prices.

That pricing took effect in July 2026, coinciding with the firm’s 22nd anniversary. Owners now pick their level of involvement at the start. Foundation Strategy, at $10,000, suits larger businesses that want to handle much of the execution themselves or need savings quickly. Custom Build, at $65,000, covers three years of direct strategy work and implementation. It is aimed at established owners with taxable income above $1 million. Empire, at $350,000, is built for UHNW founders with net worth exceeding $50 million. There the questions turn to layered income and estate planning, meant to hold wealth together as it passes down. Every figure is quoted before the engagement begins.

The Chessboard, the Dragon, and the Eight Out of Ten

Each candidate strategy lands somewhere on the firm’s Aggression Scale™. Down at zero, in Shauna’s telling, the Internal Revenue Service (IRS) has no reason to call. Only a random audit would pull the file. A nine is what she calls Al Capone territory, where someone bends the rules and gambles on never being noticed. Ten ends in prison. Owners name their own number anywhere from zero through eight, and no plan the firm writes goes past eight. An eight sits comfortably inside the law, though holding that position means documenting every step well enough to survive scrutiny.

“Extreme tax savings are never one-size-fits-all,” Shauna explains. “I sometimes call myself a red-headed fire-breathing dragon sitting on top of a pile of gold coins, where each gold coin is a strategy that we can utilize to help a client in the appropriate situation with the appropriate facts and circumstances.”

Structural Engineering for the Top 1 Percent

Shauna separates her practice from the newer tax outfits she describes as spending heavily on advertising and lightly on technical work. Against them, Tax Goddess sets 22 years of continuous training and a working catalog of more than 1,800 active strategies. Breadth of that kind, the firm argues, is what lets a plan be fitted to one client’s circumstances rather than pulled off a template.

Tax work at this level resembles structural engineering more than accounting. It draws on corporate law, trust law, property law, and partnership law. Those rules are then applied across several business entities that may be located in different states. Custom Build and Empire clients see that as advanced entity structuring. Familiar pieces include 831(b) captive insurance companies, which let a business insure its own risks through an insurer it owns. Others are optimized gift trusts and full use of Section 1202, the provision that can shield gains on Qualified Small Business Stock (QSBS) from federal tax.

Forbes and Entrepreneur have both carried Shauna’s thinking to national readers. Her latest book, The 6% Life: 7 Strategies That Successful Entrepreneurs Use to Reengineer Their Life to Consistently Pay Less Than 6% in Taxes, lays the method out at length. Teaching continues past the page as well. The firm hosts webinars, hands out reference guides at no charge to business owners and property professionals, and funds a scholarship for students. Behind all of it sit 22 years of practice, a team working across borders, and that $2.35 billion in savings.

About Tax Goddess

Guided by the mission to CRUSH YOUR TAX BILL: Tailored Tax Solutions for Successful Business Leaders, Tax Goddess is led by Shauna A. Wekherlien, CPA, MTax, CTC, CTP, CTS. Nationally known as the Tax Goddess and featured in Forbes and Entrepreneur, the firm specializes exclusively in advanced, proactive income and estate tax planning for business owners and High-Net-Worth individuals. With over two decades of experience and more than $2.35 billion in documented client savings, Tax Goddess focuses on legally aggressive tax mitigation, entity structuring, and long-term wealth preservation. For more, visit: https://taxgoddess.com/

What to Look for in Turnkey Insurance Policy Administration Software

The insurance industry has spent decades working around legacy systems that fragment operations and slow innovation. As carriers face pressure to modernize, the conversation has shifted from whether to upgrade to how to evaluate platforms that promise comprehensive solutions. Turnkey insurance policy administration software has emerged as a path forward for organizations ready to leave behind disconnected workarounds. Choosing the right platform requires understanding which capabilities truly matter.

End-to-End Policy Processing Capabilities

Legacy systems often force carriers to cobble together multiple tools for different lines of business, creating manual handoffs between quote generation and policy issuance that frustrate agents and policyholders alike. Modern solutions take a different approach by consolidating the entire life cycle into a single environment where quote, bind, issue, endorse, renew and cancel functions operate cohesively.

Multi-line support within this unified infrastructure allows insurers to manage diverse product offerings without purchasing bolt-on software. Organizations can launch additional coverage types using the same core architecture they already know, which accelerates time-to-market for new products.

Adaptability and Workflow Automation

Low-code engines have transformed how business teams interact with administration software, allowing users to configure workflows independently through visual interfaces rather than waiting months for IT-led custom development. Once configured, automated routing handles approvals and task reminders systematically. This eliminates bottlenecks by managing handoffs between underwriters, compliance reviewers and other stakeholders.

This agility translates directly into competitive advantage. Insurers deploying these configurations have shortened rollout cycles by 40%, bringing usage-based products to market in three months where competitors remain locked in lengthy development processes for multiple quarters.

Compliance and Seamless System Integration

Open APIs eliminate data silos by connecting administration environments effortlessly with CRM tools, ERP software and payment processors when integration capabilities are built into the core architecture. These platforms also address regulatory demands through built-in rules that track changes to rating algorithms over time. Likewise, automated audit trails provide the historical record that regulators expect during examinations.

Manual validation of policy calculations against compliance specification sheets has historically consumed enormous effort while remaining prone to human error. Recent implementations of automated validation have demonstrated a 92% reduction in manual effort, verifying calculation accuracy across hundreds of policies at a scale that human review teams cannot match.

Top Providers of Turnkey Insurance Policy Administration Software

Several capable options serve organizations evaluating where to buy turnkey insurance policy administration software. Each brings distinct strengths for companies at various stages of digital transformation.

USSI

Life and health carriers seeking a comprehensive turnkey platform rather than fragmented modules often turn to USSI for its 47-year history and U.S. presence. The high demo-to-close rate reflects a sales process focused on fit and the company’s willingness to customize solutions for specific carrier needs.

The full-platform approach covers billing, accounting, underwriting, claims and policy administration within a single environment. This unified infrastructure allows documents to be generated and distributed via email or traditional mail based on individual preferences. At the same time, financial tracking captures transactions as they occur to ensure accurate accounting. Claims processing expedites decisions during critical moments when policyholders need support most.

Beyond the software capabilities, the company distinguishes itself through strong personal service. Its high-touch implementation process works closely with carriers throughout deployment rather than delegating to third-party consultants.

DICEUS

Organizations seeking flexibility without a full system replacement often choose DICEUS for its modular architecture. Carriers can implement specific capabilities, such as billing or claims management, incrementally. They can modernize one function at a time rather than disrupting their entire operations.

The system generates policies from standardized templates with key information already formatted, while product management tools maintain hierarchical visibility across active, archived and in-development offerings. This helps carriers track the evolution of their portfolios as they expand or retire coverage lines. Claims workflow supports this flexibility by organizing cases from filing through settlement, allowing teams to filter and prioritize based on current business needs.

On the financial side, the billing dashboard centralizes invoicing operations. It enables organizations to gain streamlined financial oversight without juggling separate tools as other modules come online.

Guidewire

Guidewire serves property and casualty carriers through InsuranceSuite, where PolicyCenter provides the analytics foundation many large insurers rely on. What distinguishes the offering is an extensive marketplace of third-party integrations that carriers can tap in to as their operational requirements shift over time.

Workflow automation compresses timelines for quoting, underwriting, endorsements and renewals while eliminating the errors that manual processing typically introduces. As these automated workflows run, centralized data management keeps policy information synchronized across all connected environments by enforcing business rules without requiring constant oversight.

Carriers gain speed advantages when launching new property and casualty products through configuration tools that minimize coding dependencies. Lower IT involvement means faster deployment cycles. This translates into reduced administrative expenses and the ability to capture market opportunities.

Comparing Turnkey Software Solutions

Organizations weighing niche expertise against generalized capabilities can review how the three providers differ across key dimensions.

Provider Core Focus/Niche Deployment Approach Standout Features
USSI Life and health carriers Full turnkey platform 47-year track record, high-touch implementation, complete life cycle management without fragmentation
DICEUS Flexible modular solutions for insurers and captives Modular (implement specific components) Ready-made templates, hierarchical product management and incremental modernization path
Guidewire Property and casualty carriers seeking ecosystem depth Comprehensive suite with extensive integrations A vast third-party marketplace, robust analytics and rapid product configuration tools

Future-Proofing Insurance Core Systems

Organizations prioritizing no-code configuration tools gain the flexibility to adapt as market conditions shift, while open integration architectures prevent data silos that inevitably constrain growth. Reliable vendor partnerships matter just as much as technical specifications do when implementation timelines span quarters and training needs ripple through entire organizations.

3 Key Diversification Strategies for Experienced DST Investors

Strategic diversification across multiple Delaware Statutory Trust (DST) offerings protects capital from concentrated risk while maintaining the tax advantages that make these investments attractive. As a trusted fee-only wealth advisory firm, Sera Capital offers specialized guidance to help experienced investors diversify across DST offerings. This guide draws on the firm’s expertise to explore methods for mitigating risk and structuring a resilient portfolio.

The Importance of DST Diversification

Seasoned investors understand that concentrating capital in a single DST property or market sector creates vulnerability. With the total U.S. real estate market growing at a 3.36% annual rate through 2031 toward $154.94 trillion, investors benefit from diversified exposure across multiple sectors and regions.

Diversification serves as a fundamental risk management tool that protects portfolios against multiple forms of concentrated exposure. The strategy allows investors to participate in multiple real estate markets simultaneously while maintaining tax-advantaged positioning.

Key benefits of DST diversification include:

  • Protection from market-specific downturns: Economic conditions vary significantly across regions, and portfolios spread across multiple markets can weather localized recessions without catastrophic losses.
  • Sector performance balance: Different property types perform differently under varying economic conditions, allowing diversified holdings to capture gains across multiple asset classes.
  • Tenant concentration mitigation: Exposure to multiple properties and tenant bases reduces the impact of any single-tenant default or vacancy.
  • Enhanced portfolio stability: Multiple income streams from different sources create more predictable cash flow patterns over time.

Sera Capital notes that diversification can help reduce risks, such as investments in different locations or property types. “Investing in differing vehicles can help spread risks across broader structures and assets, reducing investors’ reliance on a single investment or property. As such, diversification can benefit an investor’s portfolio in emergencies where they can access their capital differently,” the firm explains.

Accessing these diversification benefits often begins with the strategic deployment of exchange proceeds. Many investors fund their DST positions through IRS Section 1031 like-kind exchange rules to defer capital gains taxes while building diversified portfolios.

“Successfully navigating a 1031 Exchange requires strategic planning and a thorough understanding of the process,” Sera Capital advises. “Investors can maximize the benefits of a 1031 Exchange by adhering to critical timelines, leveraging expert advice, and staying informed about market trends.”

Main Diversification Strategies for DST Portfolios

True DST diversification requires a deliberate, multi-layered approach that extends beyond acquiring multiple properties. Experienced investors often implement systematic strategies across asset classes, geographic regions and sponsor relationships.

1. Diversify Across Multiple Asset Classes

Property type diversification spans residential multifamily, industrial warehouses, medical office buildings and retail centers to avoid sector concentration risk. Each asset class responds differently to economic cycles, shifts in consumer behavior and demographic trends. This approach creates a buffer against sector-specific downturns.

Some investors explore the 721 Umbrella Partnership Real Estate Investment Trust (UPREIT) exchange to diversify across multiple asset classes and hundreds of properties.

According to Sera Capital, traditional DSTs typically do not offer this level of diversification. “The 721 DSTs we recommend convert to Public Non-Listed REITs that hold as few as 50 diversified properties or as many as 900,” says Sera Capital. “They are spread out amongst all the major real estate asset classes and adjust their portfolios as the real estate climate changes.”

For clients pursuing this exchange structure, Sera Capital can offer the assistance they need. The firm leverages its deep expertise in 721 UPREIT exchanges to facilitate a seamless transition from standard DSTs into fully diversified, institutional-grade REIT portfolios. Its consultative approach guides investors through the technical requirements and timing considerations that make these exchanges successful.

2. Implement Geographic and Market Diversification

Spreading DST investments across different states and metropolitan areas provides essential protection against regional economic downturns, natural disasters and state-level policy changes.

Sera Capital points out that location selection also depends on potential appreciation, rental income and desirability. “Urban centers and high-growth regions typically offer big returns, thanks to thriving economies and strong tenant demand. Conversely, properties in struggling markets may have trouble maintaining occupancy or face value erosion over time,” the firm observes.

Evaluating regional performance patterns and economic indicators across multiple states requires deep market knowledge and objective analysis. Sera Capital frequently works with CPAs and financial advisors who need guidance on geographic allocation. The company helps investment teams identify opportunities across different markets while maintaining an appropriate risk balance.

3. Stagger Sponsors and Investment Timelines

Relying on a single sponsor’s management team creates significant operational risk as it creates a single point of failure for the investment. Day-to-day execution and project governance often rest entirely on one firm’s competence and stability. When that team stumbles, the investment can falter regardless of underlying asset quality.

Equally important, having all DST investments reach their full-cycle exit simultaneously creates liquidity risk. It can force investors to make multiple replacement-property decisions under time pressure. In these cases, staggering investment timelines and diversifying across reputable sponsors are essential, but they require thorough vetting and ongoing monitoring.

Sera Capital emphasizes that due diligence can help investors distinguish between good and risky deals. “Due to the high velocity of deals and the ever-increasing number of sponsors trying to enter the market, due diligence is more vital than ever to ensure that you are not exposing yourself to an unreasonable level of risk,” the company says. 

Because of their transparent, lower-fee model, Sera Capital serves as an objective, conflict-free fiduciary. The firm performs rigorous sponsor due diligence and coordinates exit planning for real estate partnerships. The fee-only structure allows the firm to provide unbiased recommendations focused solely on client outcomes.

Securing a Diversified DST Portfolio

Building a well-diversified DST portfolio demands strategic planning across multiple dimensions. Thoughtful capital allocation creates resilience and positions holdings to weather uncertainty and capture growth opportunities. Investors who embed diversification into allocation decisions build portfolios that support long-term stability, leading to resilient performance through changing conditions.

China’s Challenging Search for a New Model of Economic Growth

By Danny Leipziger

China cannot continue to rely on exports to drive its growth, but what are the alternatives?

China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely less on exports as the driver of growth, alternative policies have proven elusive. This lack of a sustainable growth model is not only detrimental to China, but it also places a large burden on the rest of world. China has the ability to undertake  fundamental reforms that can help it to overcome some of its economic challenges, but recognizing the necessity of searching for a revised approach to generating growth and prosperity is a pre-condition for policy change.

What’s the problem? 

Some China-watchers have opined that China is in need of a new growth model,1 while others have come to the opposite conclusion that “China has every incentive to maintain the largest possible trade surplus for as long as it can,”2 as the easiest way to maintain economic expansion.  While the latter observation may well be true in the near term, it can be argued that China will need to revise its approach to economic growth sooner or later. The timeline for this re-adjustment will have significant implications for Chinese industry and society; however, equally importantly it will affect the global economy. To summarize the problem in a nutshell it is that growth is still led by exports inasmuch as consumption demand is low and unlikely to rise given demographic trends without major policy shifts, and investment is hugely inefficient as seen in both the real estate sector as well as the quality of capital spending.3 

Looking at options from China’s perspective, the transition from labor-intensive industries to robotic and AI-intensive activities is happening at a pace that will leave tens of millions without employment. The number of displaced workers now working in the gig economy with reduced and uncertain wages has mushroomed. This simply adds to the existing problem of youth unemployment, now officially reported at 15 percent, but rumored to be higher. It can reasonably be argued that the rapid shift to labor-replacing technologies will further shift income to capital at the expense of wage-earners, while some observers have mused that inequality may now be a larger issue in China than in the US. The old aphorism that the “Chinese hoped to get rich before they got old” remains a preoccupation even as the population begins to decline due to very low fertility.4 

Dissecting the problem

An easy way to start examining the future of economic growth in China is by looking at the components of demand. The Chinese authorities have made some half-hearted efforts at promoting demand, such as the equivalent of “cash for clunkers” program to promote the purchase of new consumer durables. However, this policy has fallen flat due to demographics; namely, China has an aging and declining population. Moreover, the bulk of Chinese household assets are in the form of real estate, a sector that has undergone dramatic decline.5 The authorities are loathe to provide large transfers to boost consumption, so we cannot expect an increase in demand until the government relents and considers serious social transfers or even something akin to a universal basic income or its equivalent.

The second component is investment, which has a mixed record as was noted. The major push to compete effectively in AI and new drugs as well as the push on robotics can produce productivity gains and inroads into new industries. But what about China’s dominance in many labor-intensive industries where aggressive insertion of robotics has displaced many jobs? And what about its over-production of products, such as solar panels, that are flooding global markets? China has officially decried excessive competition under the code word of “involution,” where producers undercut one another in pricing due to oversupply. This domestic problem is then transferred to the global economy via dumping and other aggressive pricing policies that China has refused to acknowledge.6 

The search for solutions

Where to start. As outside observers have noted, there need for a serious reassessment of SOEs and other loss-making firms, and a process of triage and closures. The challenge, very similar to the issues faced in the hollowed-out sectors of the US economy, is to manage unemployment, something China has little experience handling due to decades of rapid growth and employment via the hukou system of internal migration. This flow out of rural areas for jobs is now seeing reversals, creating new pockets of relative poverty. Again, the issue is a fiscal one, since the government would need to allocate funds for the inevitable industrial transition. China has the revenue capacity to manage this; however,  it can be helped by a more pragmatic approach to the private sector, where a freer approach might raise needed corporate taxes, and a more forward-looking social policy. 

The final area for review is controversial, namely, exports. Even as China is flexing its muscles on rare earths and critical metals, and competing vigorously on AI and its related technologies, it continues rely on more traditional exports and EVs to maintain its growth rate.  Examining China’s mega trade surplus shows that it runs large positive balances with many parts of the developed world. And yet, China is still pursuing an import-substitution strategy as seen in its management of bilateral trade with South Korea, where it has systematically reduced its import dependence on intermediates, much in keeping with its “Made in China 2025” strategy.7

Elements of a new growth model

So where are left in the search for a new growth model for China?

  1. First, much like other economies, lifting the weight of the bloated real estate sector would be desirable, admittedly costly, but necessary in light of future demographics.
  2. Second, allowing the private sector to flourish can help propel economic growth and help provide the fiscal resources needed to deal with labor transitions.
  3. Third, putting provinces on sustainable financial footings can help with future challenges inasmuch as lot of capital expenditures is being wasted and those resources are needed for social support of those retiring, either voluntarily or involuntarily from the workforce.
  4. Fourth, some program of guaranteed basic income is likely needed since the safety net for those displaced but living another 20 years needs bolstering.
  5. Fifth, finding gainful employment for the youth who are NEET is necessary or else outward emigration will be incentivized, and few countries will be willing to accept Chinese workers, similar to the prospects for excess production of goods.

Final thoughts

The rapid shift away from labor-intensive production to robotics will continue to shrink the wages of the existing cohort of workers, many who have been displaced by rapid technological shifts. The fact that future factories will need considerably fewer workers can be seen a boost in productivity; however, this is occurring at a speed that exceeds future population declines, leaving a host of economic and social problems in the coming two decades.

The good news is that China has both the fiscal capacity to deal with many issues and the technological prowess to reap large gains from new investments. The key is to release resources from unproductive uses and to improve materially the incomes of the existing population. These problems, including hollowing out of industry and depressed areas, are no different from those encountered in Western economies, especially with respect to demographics, labor transitions and employment. The difference is that China does not have to deal with divisive internal political economy issues to the extent that others do.

The new growth model needs to one built on income-sharing, an approach more akin to social democracies,8 but matched with hard-nosed investment decisions, policy-driven revenue sharing with provinces, smart approaches to the Chinese private sector, and a realization that exports cannot be the sole growth engine of the future. The longer China resists necessary reforms, the costlier will be the ultimate adjustment for both China and the global economy.

About the Author

Danny Leipziger

Danny Leipziger is Professor of International Business at George Washington University and Managing Director of the Growth Dialogue. A former World Bank Vice President and Vice Chair of the Spence Commission on Growth and Development, he is an expert in development economics and finance, author of several books, and frequent Financial Times contributor.

References:

  • [1] See Eswar Prasad, “China Needs a New Growth Model,” Financial Times (July 28, 2026)
  • [2] See Michael Pettis, “Who Will Bear the Cost of a Global Trade Adjustment,” Foreign Affairs, Aug. 28, 2026
  • [3] The IMF estimates the current ICOR, one measure of the efficiency of investment, at an all-time high above 9 which is double what it was during China’s earlier growth experience.
  • [4] China’s population peaked in 2022, and current fertility rates are reported just below 1.0 according to the United Nations Population Office.
  • [5] The real estate sector has suffered multiple bankruptcies yet is still supported by the PBOC with a number of policies. The reality is that there are at least 2 million unoccupied housing units, most in undesirable locations, and many bolstered by local governments unwilling or unable to accept losses.
  • [6] The latest evidence of this was China’s reported opposition to G-20 Communique language on “non-market pricing policies.”
  • [7] See MERICS assessment of the China 2025 Report issued in 2016
  • [8] See Leipziger in the FT (Letters, June 30, 2026), who argued that China may need to re-embrace some more egalitarian economic policies if it doesn’t want to see greater inequality in society. Having successfully dealt with absolute poverty, the authorities now face considerable problems of relative poverty.

Why Aviation’s Electric Future Depends on Overlooked Motor Technology

By Duggan Flanakin

As aviation electrifies, electric motors will be essential to making aircraft more efficient, reliable, and capable without compromising safety. 

Aviation is approaching an inflection point as electric and hybrid-electric propulsion move from laboratory demonstrations toward serious flight programs. Yet the discussion often centers on batteries, turbines, and aircraft design rather than on the electric motors that convert electrical energy into controlled mechanical motion. Duggan Flanakin, a policy analyst with the Committee For A Constructive Tomorrow (CFACT), argues that motors will be a foundational part of aviation’s transition, not a secondary component, across propulsion, actuation, auxiliary systems, unmanned aircraft, and advanced air mobility.

What is driving aviation toward greater electrification? 

Aviation’s electric transition is being driven by the need to improve efficiency while accommodating continued growth in air travel. Boeing’s 2026 Commercial Market Outlook forecasts that global air travel demand will double over the next 20 years, with the worldwide commercial fleet growing nearly 80% to more than 50,000 aircraft by 2045. Boeing estimates airlines and cargo operators will require nearly 44,000 new airplanes during that period.

That creates an enormous engineering challenge. Aircraft must become more efficient without sacrificing safety, reliability, performance, or maintainability. Electrification is likely to be part of the answer, but it will not arrive in a single form.

Fully battery-electric propulsion for large commercial aircraft remains constrained by energy density. More immediate opportunities include more-electric aircraft architectures, hybrid-electric propulsion, electric actuation, auxiliary systems, unmanned aircraft, and advanced air mobility. Research continues to address the weight and energy-density limitations that make full electrification difficult for larger aircraft.

Why do electric motors matter beyond propulsion?

The electric motor is easy to overlook because it is rarely the headline technology. But it is the component that converts electrical energy into precise mechanical movement, making it relevant to far more than propulsion.

Electric motors can drive pumps, fans, actuators, valves, environmental-control equipment, flight-control mechanisms, landing-gear systems, and other aircraft subsystems. In unmanned aircraft and smaller electric platforms, motors can also be part of the propulsion architecture.

The implications are practical. As aircraft become more electrically capable, motors will need to meet increasingly demanding requirements for precision, efficiency, reliability, weight, thermal performance, and controllability.

What makes motor engineering challenging in aviation?

Aviation certification is fundamentally different from supplying a conventional industrial motor. Aircraft components must be qualified for demanding operating conditions, including vibration, temperature, electromagnetic compatibility, fault tolerance, containment, and other safety-critical requirements.

That does not mean an existing industrial motor can simply be installed in an aircraft. Rather, underlying capabilities in precision motor design, motion control, customization, thermal monitoring, sealing, and related engineering can become relevant starting points as aerospace electrical architectures evolve.

Customization is particularly important because aerospace rarely rewards one-size-fits-all engineering. Requirements can vary by aircraft, subsystem, operating environment, available power, space constraints, and certification pathway.

Which motor capabilities could support the next generation of aircraft?

Modern brushless DC motor technology illustrates the direction of travel. Precision, low noise, smooth operation, integrated encoders, and multiple voltage configurations can be valuable characteristics in systems that demand controlled movement and feedback.

Other capabilities can matter for specific aviation environments. Customized mounting configurations, connectors, encoders, brakes, gearboxes, protective coatings, thermal monitoring, and sealed configurations can adapt motor systems to specific operating conditions.

MagLev technology offers another potential avenue. Magnetic-bearing systems are described as non-contact, with no mechanical wear and no routine maintenance, while supporting variable speed and load capabilities. In an aviation environment where weight, reliability, maintenance intervals, and contamination control matter, technologies that reduce mechanical wear warrant consideration.

Is hybrid-electric aviation already moving beyond the concept stage?

The timing suggests that these questions are becoming practical rather than theoretical. In July, RTX’s Pratt & Whitney Canada announced ground testing of a flight-standard engine and propeller for a hybrid-electric flight demonstrator.

That work sits within a much larger commercial ecosystem. Boeing’s 2026 outlook forecasts a $4.9 trillion commercial aviation support-and-services market through 2045, illustrating the economic scale surrounding the next generation of aircraft.

The important point is not that one technology will suddenly transform aviation. The transition will require coordinated progress across propulsion, motors, power electronics, thermal management, controls, materials, certification, and manufacturing.

What should manufacturers and aviation leaders watch next?

The electric aviation transition should be evaluated as an engineering system rather than a race to a single breakthrough. For manufacturers and technology developers, several questions deserve particular attention:

  • How can electric systems reduce weight and energy consumption without compromising reliability?
  • Whichaircraft subsystems can benefit from electrification before full electric propulsion becomes practical? 
  • How can motors and motion-control systems be customized for increasingly specialized aerospace applications?
  • Which technologies can reduce mechanical wear, maintenance demands, and failure risks?
  • How will certification requirements shape which promising motor technologies can move from development into flight?

Conclusion 

The electric aviation transition will not be delivered by batteries or motors alone. It will emerge from thousands of incremental improvements in motors, power electronics, thermal management, controls, materials, certification, and manufacturing. The practical opportunity is to make aircraft more efficient, reliable, and electrically capable, one subsystem at a time. The motors often overlooked today may become among the technologies that quietly determine how successfully aviation enters its next era.

About the Author

Duggan Flanakin

Duggan Flanakin is a Policy Analyst with the Committee For A Constructive Tomorrow (CFACT), where he writes and researches on energy, environmental policy, technology, and economic issues. His work examines how technological and policy choices affect American industry, infrastructure, and long-term competitiveness.

References 

Xi’s Washington Visit Highlights Trade and AI Tensions

Chinese President Xi Jinping’s visit to Washington has featured elaborate ceremonies and warm public remarks, but the two sides have yet to announce major breakthroughs on their most difficult issues. President Donald Trump welcomed Xi with military honors, while Xi announced a panda gift and a new student exchange program. Both leaders also highlighted the need for continued dialogue.

Trade remains one of the main areas of discussion. A temporary U.S.-China tariff truce is expected to be extended, helping prevent a return to last year’s trade tensions. However, disagreements remain over China’s purchases of U.S. agricultural products and rare earth exports, while Beijing is watching Washington’s plans for a potential arms sale to Taiwan.

AI is another major point of difference. U.S. officials have largely focused on the risks posed by increasingly advanced AI, while China has placed more emphasis on speeding up development and putting the technology to wider use across its economy. The wars in Iran and Ukraine also make progress in talks difficult. So far, the visit seems to have been more about keeping diplomatic ties stable and maintaining dialogue than reaching major agreements.

Related Readings: 

Trump-Xi Summit Faces Trade, AI and Iran

China Signals Tariff Cuts

Trump Xi Meeting Begins

How Prop Trading Firms Work and What It Takes to Start One

Funded-trader programmes have become one of the most visible business models in the retail trading market. This article explains how a prop firm earns money, what infrastructure it runs on and which decisions founders tend to underestimate.

What a prop firm sells

A modern prop firm sells an evaluation rather than a brokerage service. A trader pays a fee, receives a simulated account of a stated size and has to reach a profit target without breaching the loss limits. Those who pass get a funded account and keep a share of the profit they generate, which is paid out on a schedule the firm defines. Unlike a broker, the firm does not accept client deposits and does not hold client money, and this single difference shapes almost everything else about the business: the revenue model, the legal treatment and the technology it depends on.

Where the revenue comes from

The main income line is evaluation fees, followed by resets and repeat purchases from traders who failed a previous attempt. Payouts to funded traders are the main cost. A lot of new founders look only at the first half of that equation, since most evaluations end in a breach and the fee income looks comfortable on a spreadsheet. The weak point appears when a small group of consistently profitable traders starts requesting payouts every cycle. If those payouts can only be covered from new fee income, the firm depends on constant sales growth, and the first slow month may turn into delayed payouts, which is the fastest way to lose a reputation in this niche. More careful operators copy the positions of funded traders to a real liquidity account at a chosen ratio, so that part of the payout liability is matched by real market profit and the firm’s exposure is visible in one place.

The technology stack

A prop firm needs more software than a first-time founder usually expects. The list includes a trading platform, a CRM with a challenge store and order history, a risk engine that checks every account against the rules in real time, KYC and payment processing, a payout workflow with approvals, and affiliate tracking, since a large share of the traffic in this niche comes from partners. These components can be bought separately and integrated, or licensed as one bundle from a single vendor. Anyone researching how to start forex prop firm operations will find both routes on the market, and the choice is mostly about control versus speed: separate components give more flexibility, while a bundle removes integration work and leaves one supplier responsible when something breaks.

Pricing models differ as well. Some vendors charge a flat monthly fee and others take a share of revenue, which looks cheaper at launch and can become the largest line in the budget once the firm grows. In both cases the vendor supplies software only. Liquidity, banking and payment processing remain relationships the firm has to hold directly, and it is worth confirming this before signing anything, since some founders assume the platform vendor also brings the price feed.

Platform choice

For years MetaTrader was the default answer. After MetaQuotes tightened access for prop firms in 2024, a lot of firms moved to cTrader, Match-Trader, DXtrade and TradeLocker or to their own web terminals, and platform became something a trader checks before buying a challenge. It matters most for automated strategies, because an EA written for MetaTrader does not run anywhere else. For a founder this is as much a marketing decision as a technical one, since traders self-select by platform before they read the rules. It is also worth checking whether the CRM and the risk engine sit above the platform or inside it, because only the first setup lets the firm add or replace a platform later without rebuilding the back office.

Writing the rulebook

Rules are the actual product, and traders will read them line by line against the firms they already know. The decisions a founder has to make include:

  • phase structure: one-step, two-step or instant funding
  • profit targets, minimum trading days and reset price
  • maximum drawdown: static or trailing, measured against balance or equity
  • daily loss limit
  • consistency rule and lot-size caps
  • news trading restrictions
  • weekend holding

The last point is easy to overlook. The gap between Friday close and Sunday open is where forex programmes tend to lose money, so whether positions can be held across it, and at what size, should be a configured rule and not a hope. How the rules are enforced matters as much as how they are written. A breach detected by the engine at the moment it happens is a fact, while a breach discovered manually when a trader requests a payout is a dispute, and such disputes are the most common source of negative reviews in this industry. Some firms also set a severity for each rule (warning, freeze or breach), which lets a new rule start as a warning while the team learns how its traders behave.

How traders will compare a new firm

Few traders buy a challenge straight from an advert. Most of them go through comparison sites first. Listings of the best forex prop firms typically rank companies on reported payouts, trader reviews and years in operation, and then show the entry fee, maximum funding, profit split and supported platforms side by side. Profit split rarely decides anything, because nearly every firm advertises a similar range. The rules decide: static or trailing drawdown, the presence of a consistency rule, the number of required trading days and permission to hold through news. Traders also check whether the fee is refunded with the first payout and what a reset costs, since a cheap entry with an expensive reset is not cheap for someone who needs two attempts. A new firm has neither years in operation nor a review history, so clear rules and a documented payout record are the only parameters it can compete on from day one.

Licensing and legal structure

In most jurisdictions an evaluation programme is treated differently from a brokerage, because traders work with the firm’s own or simulated capital and do not deposit funds for trading. That said, the legal treatment depends on where the company is incorporated and how the product is structured, and regulators in several countries have started to look at the sector more closely. Some groups include a licensed broker entity, but that licence covers the broker and not the evaluation programme. The practical advice is to get a legal opinion in the chosen jurisdiction before building the product, since restructuring a live firm costs far more than structuring a new one.

Common mistakes

  • pricing challenges without modelling payouts
  • copying a competitor’s rules without an engine able to enforce them
  • reviewing breaches manually at payout time
  • signing a revenue-share contract without calculating it at scale
  • leaving the legal opinion until after launch

Final thoughts

Technology is usually the fastest part of launching a forex,crypto or futures prop firm. The slower parts are the commercial design of the challenge, a rulebook the firm can actually enforce, a payout model that does not depend on next month’s sales, and a legal structure that holds up to scrutiny. Founders who settle these questions first tend to find that the remaining choices, including the platform and the vendor, become much easier to make.

Trump-Xi Summit Faces Trade, AI and Iran Challenges

President Donald Trump and Chinese President Xi Jinping are set to meet in Washington as both sides look to stabilize trade relations and secure new economic deals. Their talks come with the existing trade truce still fragile, while tariffs remain high and the two countries continue to disagree over export controls and other trade measures.

A one-year extension of the current truce is seen by some analysts as a likely outcome, potentially keeping tariffs and new export restrictions from escalating. The two sides are also discussing a possible $30 billion reduction in tariffs on non-critical goods, with the U.S. seeking more Chinese purchases of American agricultural, energy and other products. However, analysts expect limited progress on sensitive issues such as advanced semiconductors.

AI is expected to be another major topic, with Washington and Beijing competing for leadership in the technology. The talks could include discussions on AI safety and a proposed channel for notifying each other about serious AI incidents. Meanwhile, U.S. sanctions targeting Iran could add another complication, given China’s role as a major trading partner of Tehran. Alongside the economic talks, several major U.S. business leaders are expected to attend a state dinner for Xi.

Related Readings:

China Signals Tariff Cuts

Trump Xi Meeting Begins

Trade Talks Take Backseat in Trump Xi Summit

The Business Case for Dispute Prevention

By Kate Vitasek and Ellen Waldman

Preventing disputes can help you protect two of your company’s most important assets, money and time.

As Benjamin Franklin wrote of fire-threatened Philadelphia in 1736, “An ounce of prevention is worth a pound of cure.” The maxim also applies to contractual conflicts.

But what does dispute prevention actually look like? And how can you incorporate it for your company?

That question is being addressed by research thinktanks such as the International Institute for Conflict Prevention and Resolution and the University of Tennessee’s Global Supply Chain Institute. This article shares proven mechanisms for preventing costly contract disputes.

Before we dig in, let’s look at some compelling research on the cost and time associated with contract disputes.

The High Costs of Managing Disputes

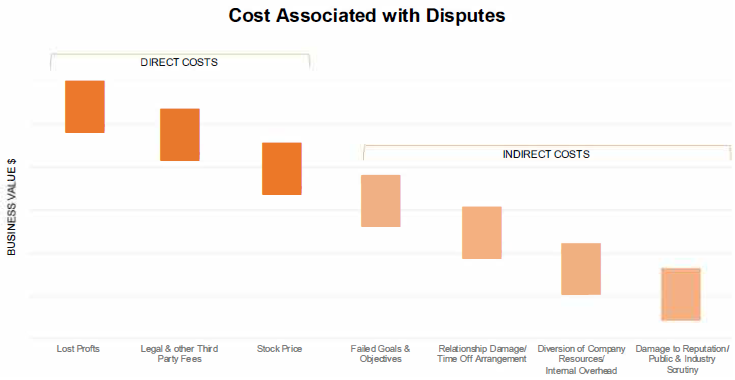
Many people associate dispute costs with third-party fees-lawyers, paralegals, accountants, claims consultants, and other experts. In actuality, there are many other costs that contribute to the high cost of managing disputes.

There are soft costs involved, too. Research by a CPR Dispute Resolution Services task force outlined seven cost categories for managing disputes such as lost profits and diversion of company resources.

Cost Associated with Disputes

While managing the cost of disputes is one thing, it is important to consider the fact that disputes also cause other disruptions such as consuming time. An Association of Corporate Counsel study found:

  • Nearly half—46%—of in-house counsel reported that the length of litigation was increasing, versus only 8% citing that it was declining.
  • Seventy-two percent of employment and labor disputes last longer than one year, and 71% of breach of contract disputes last longer than one year, with 22% taking more than two years.

Simply put, the more time people spend working on disputes, the more they are not spending in value-added activities that can positively impact the organization.

Avoiding a Vicious Cycle

The good news is there are proven tactics companies can take to diminish the likelihood of facing these headaches. The authors of the book Preventing the Dispute Before It Begins: Proven Mechanisms for Fostering Better Business Relationships outline eighteen mechanisms and provide compelling case studies of how they are being used in practice.

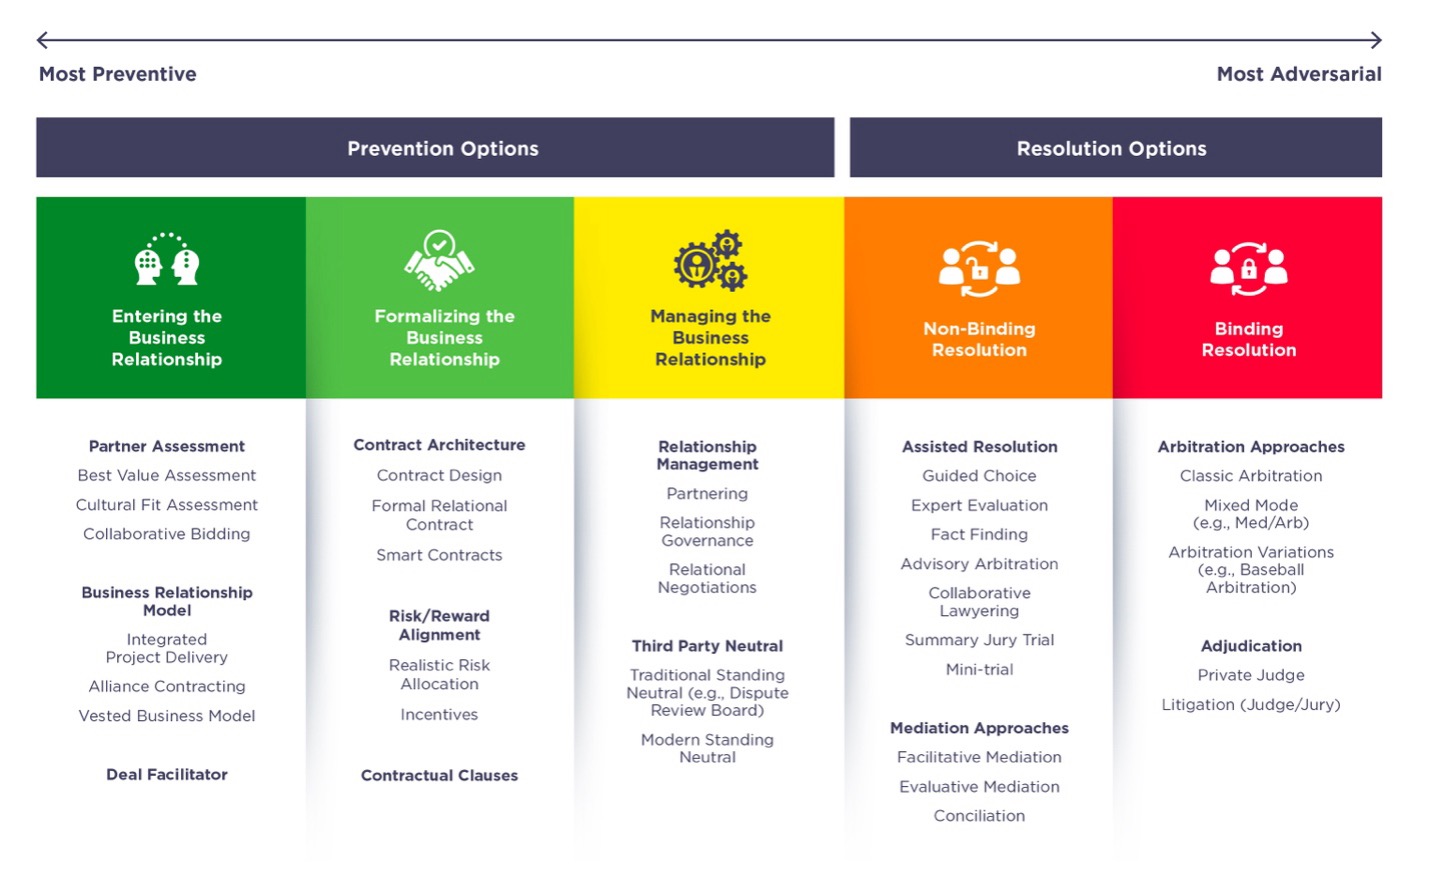
One of lessons? Recognizing that dispute prevention comes well before your dispute resolution team gets involved. In fact, good dispute prevention practices start as early as when you are looking to select a business partner and thread through both the contract development and contract management aspects of business relationships.

Below are three dispute prevention tactics that can help companies resolve conflicts before they turn into full-blown disputes.

Partnering

Partnering uses team-building tactics to help build a strong, collaborative working relationship among contracting parties. Partnering is a deliberate undertaking between parties to ensure they align on the purpose of the contract, their mutual objectives, expectations and values, the risks they are likely to confront, conflicts that may arise, or any other issues that will portend a better relationship.

Partnering often involves workshops with key stakeholders. For example, contracting parties may hold a retreat among key personnel involved in the project/relationship. The expected benefits from partnering activities include improved efficiencies and cost-control, increased possibilities for innovation, continued quality improvement of goods and services, and reduced likelihood that conflict will escalate to dispute.

The typical steps commonly found in partnering include:

  • Commitment During Contracting: The process begins when two or more organizations contract to work together and agree to use partnering
  • Post-Contract Planning: Stakeholders select a facilitator, stakeholders, and the agenda and time for the initial partner meeting
  • Kickoff Workshop: The participants establish their commitments and build a team culture. The parties establish a formal charter, identify key issues and risk management strategies, and develop a dispute management plan and processPeriodic Partnering Meetings: Monthly or quarterly “refresher” meetings to review progress and objectives to allow for adjustments
  • Close-Out Workshop: Final evaluations and lessons learned to ensure improved processes in the future, along with recognition of individual contributions

Traditionally, partnering is considered a post-contract signing mechanism. However, in recent years, partnering has extended to pre-contract signing with the use of a deal facilitator, who helps contracting parties develop their contract.

Deal Facilitator

Using a neutral party to resolve disputes is commonplace. But an interesting spin proving to be effective at preventing disputes is to leverage a third party for help in deal development, too. The third party—often referred to as a deal facilitator or deal mediator—is engaged by contracting parties to help them collaboratively negotiate the specific deal terms.

That role is especially important when considering that business deals, especially large and complex ones, can be fraught with difficulties.

One study found at least 40 percent and up to 70 percent of all joint ventures are estimated to fail.[1] Key reasons are miscommunication and misunderstandings between the parties, which lead to mistrust and cause the negotiations to reach an impasse. The use of deal facilitators is intended to overcome these obstacles.

Using a deal facilitator can help contracting parties to create fair and balanced agreements that work for both parties, in turn, reducing contractual issues.

When contracting parties use a deal facilitator, the neutral has no incentive to obtain any specific terms of benefit to a particular party. For this reason, the deal facilitator can engage in “reality testing” of proposals and positions. For example, a deal facilitator can help a party who is opportunistically seeking terms that may generate distrust or resentment to see the benefit of adopting more even-handed terms that promote business harmony and the long-term health of the relationship.

Vancouver Island Health Authority (Island Health) and South Island Hospitalists Inc. (SIHI) turned to a neutral deal facilitator when their contract negotiations reached an impasse. Negotiations had grown so tense team members described negotiations as broken, bullying and even toxic. The deal facilitator led key stakeholders from both organizations through a three-day “alignment” workshop and a series of workshops to help the parties repair their damaged relationship and ultimately work through a win-win contract.

The results? A total trust turnaround with team members used words like collaborative, transparent and trusting to describe the relationship post contract signing.

Realistic Risk Allocation

Risks are inherent in virtually all commercial activities. Realistic risk allocation is an integral part of risk management that starts at the planning phase in any business relationship and includes the process of fairly allocating risks among the parties.

When businesses identify, understand, anticipate, assess, analyze, and learn to manage risks, they can create a significant source of value for the contracting parties through risk reduction. The goal is to consciously not shift risk to the “weaker” party to “win” the negotiation, but rather to intentionally identify and analyze potential risks in a relationship and assign each risk to the party that is most capable of managing, controlling, or insuring against that risk.

Each time a risk is appropriately allocated, a source of potential conflict diminishes.

Realistic risk allocation helps prevent problems by assigning each potential risk of the business relationship to the party best able to manage, control, or insure against the particular risk.

That process involves a four-step joint risk assessment:

  • Step 1: Identify Risks
  • Step 2: Analyze, Prioritize, and Estimate the Cost of Risks
  • Step 3: Fairly Allocate Risk
  • Step 4: Joint Planning and Mitigation

The result of following these steps is cost avoidance and/or real cost reductions associated with reduced risk.

The Bottom Line? It is Your Bottom Line.

Making the shift to dispute prevention does not just make intuitive sense; there is a bottom-line business case for adopting upstream dispute prevention mechanisms.

Simply put, it brings value to all parties involved.

About the Authors

Kate VitasekKate Vitasek is an international authority for her award-winning research and Vested® business model for highly collaborative relationships. Vitasek, a Faculty member at the University of Tennessee, received the Thinkers50 Breakthrough Idea Award in 2025 and was lauded by World Trade Magazine as one of the “Fabulous 50+1” most influential people impacting global commerce. She has written nine books.

Ellen WalmanEllen Walman served as a law professor for 27 years and has published more than 25 articles and is a co-author of the book Preventing the Dispute Before It Begins: Proven Mechanisms for Fostering Better Business Relationships. Most recently she served as the Vice President of Advocacy and Educational Outreach at the International Institute for Conflict Prevention and Resolution (CPR), offering thought leadership in the realm of mediation and dispute prevention.



Note

[1] Patricia E. Farrell & Dan Bova, The 7 Deadly Sins of Joint Ventures, Entrepreneur (Sep. 2, 2014), https://www.entrepreneur.com/business-news/the-7-deadly-sins-of-joint-ventures/236987.

EDITOR'S PICK OF THE WEEK

China economic growth

China’s Challenging Search for a New Model of Economic Growth

By Danny Leipziger China cannot continue to rely on exports to drive its growth, but what are the alternatives? China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...

WISE DECISION MAKER GUIDE

POWER INFLUENCERS

Emerging Trends

The Future of Global Trade