Home Blog Page 23

Top Institutional Crypto Platforms in 2026

Institutional Crypto Platforms

Top institutional crypto platforms have become a core layer of the digital asset market. What used to be a retail-driven space now runs on institutional flows, and you can feel it in the way liquidity behaves. Large orders are absorbed differently, spreads are tighter, and execution matters more than ever.

Introduction to Top Institutional Cryptocurrency Platforms

Institutional participation has changed how exchanges operate. The top institutional cryptocurrency platforms are no longer just marketplaces—they are full infrastructure providers. From my perspective as a trader, the biggest difference is how these platforms prioritize execution quality over interface design.

When we talk about crypto trading for institutions, we are referring to an environment where orders are often algorithmic, positions are hedged across venues, and capital efficiency is critical. That means exchanges must deliver consistent performance under pressure, not just during calm market conditions.

What Makes the Best Institutional Crypto Exchange

The definition of the best institutional crypto exchange is fairly straightforward when you look at it from a practical angle. Liquidity is the first filter. If a platform cannot handle large orders without significant slippage, it is simply not viable for institutional use.

The second factor is infrastructure. Most institutional participants rely on API connections rather than manual trading. This is where crypto solutions for market makers become essential. Low latency, stable connectivity, and predictable execution are not optional—they are the baseline.

Compliance also plays a key role. Funds, fintech companies, and market makers operate within regulatory frameworks. They need reporting tools, transparent processes, and a platform that can integrate into their existing risk management systems.

Top Institutional Crypto Platforms in 2026

There are several strong players in this segment, but only a handful can be considered true top institutional crypto services.

1. Coinbase Institutional

A dominant force in the US market. It is often the default choice for funds that prioritize regulatory clarity and integration with traditional finance. Execution is reliable, though sometimes less aggressive than offshore venues.

2. WhiteBIT

The institutional crypto exchange WhiteBIT has built a solid position by focusing on infrastructure rather than hype. In practice, crypto trading for institutions on WhiteBIT feels streamlined. The platform offers access to deep liquidity across more than 900 trading pairs and supports an API-first trading environment. Its ecosystem integrates lending, margin, and execution tools to align with real trading workflows. For firms running liquidity strategies, its crypto solutions for market makers allow direct access to trading infrastructure without unnecessary complexity.

3. Binance Institutional

Still one of the deepest liquidity hubs globally, especially in derivatives markets. It is widely used for large-volume execution, though some institutions approach it selectively from a regulatory standpoint.

4. Kraken Institutional

A platform known for its strong security standards and transparent operational model. It is often chosen by funds that prioritize risk management and compliance.

5. Bitstamp

One of the longest-standing exchanges in the market. While less aggressive in expansion, it remains a trusted venue for European institutional participants.

How Institutions Actually Use These Platforms

In real trading environments, crypto trading for institutions goes far beyond simple exposure to Bitcoin or Ethereum. Most desks are running structured strategies. Market makers focus on capturing spreads while maintaining neutral exposure. Arbitrage desks monitor price differences across platforms and execute quickly when inefficiencies appear.

Treasury operations are also becoming more sophisticated. Companies are no longer passively holding assets; they actively manage positions, allocate capital, and use lending products to generate yield. On platforms like institutional crypto exchange WhiteBIT, these activities are supported by built-in tools that reduce the need for external infrastructure.

Why the Market Looks Different in 2026

The evolution of institutional crypto exchanges is driven by three main factors. First, infrastructure has improved significantly. Matching engines are faster, APIs are more stable, and execution quality is closer to traditional financial markets.

Second, regulation has advanced, particularly in regions such as Europe. This has reduced uncertainty and encouraged more institutional capital to enter the space. Third, liquidity has matured. Large trades can now be executed more efficiently, which changes how strategies are designed and deployed.

As a result, top institutional crypto platforms now resemble traditional trading venues in many ways, while still retaining the flexibility of digital assets.

Conclusion

The institutional layer is no longer a future trend—it is the present structure of the crypto market. Choosing between top institutional crypto platforms comes down to execution, infrastructure, and reliability.

From a practical standpoint, the best institutional crypto exchange is the one that allows strategies to run smoothly under real market conditions. In 2026, that is the difference between a platform that looks good on paper and one that performs in the market.
The NHL’s CFTC Deal Shows Sports Integrity is Becoming Market Surveillance

Person playing hockey - NHL’s CFTC Deal Shows Sports Integrity
Photo by Luke Miller on Pexels

Integrity in sport has traditionally been about competition and about preventing games from being fixed, insider information leaked, betting patterns frowned upon, or players, officials or team staff acting in ways that might lead to a loss of faith in the sport. That mission remains the same, but the circumstances surrounding it have changed. Integrity is shifting from a league problem to more of a market-surveillance problem as sports results are becoming tradable on prediction markets and betting-like sites.

Every betting-adjacent product, user journey, and betway account experience is impacted by that shift, as the modern sports market is now based on trust in the game and the price associated with it.

Why the NHL-CFTC Deal Matters

The NHL’s information-sharing agreement with the Commodity Futures Trading Commission is a big step for sports leagues and their attitude toward prediction markets. CFTC isn’t a conventional athletics regulator. It is a Regulatory Body for Derivatives. Its involvement demonstrates that sporting outcomes are being interpreted as market events and need to be overseen, have data shared, monitored and enforcement needs to be coordinated.

The reason the NHL wants to do this is simple: to keep the markets honest and maintain people’s confidence in them. The agreement is a plus for the CFTC, which will oversee platforms where users could be trading contracts based on sports outcomes.

Where the old distinction between sports betting and financial trading gets murky. Market abuse, insider information, and suspicious trading behavior are all factors that need to be taken into consideration when monitoring the integrity of a hockey outcome that is tradeable, like an event contract.

Sports Leagues Are Learning From Financial Markets

Surveillance systems have been employed in financial markets for a long time to track suspicious trading activities, manipulation, unusual price movements and inside trading. Prediction markets have always been around, and close the gap between the two worlds of sports betting.

A sudden price jump in a game contract doesn’t necessarily indicate that something is amiss. It may be a response to public news, injury reports, or lineup changes, or a normal market response. However, it may be a leak of information, a coordinated trading, or a suspicious access to non-public information.

That’s where the NHL-CFTC deal comes into play. It implies that leagues need to consider acting more like exchanges. They must learn how to read the signals of the markets before, during and after the match, not just what happens on the ice.

Insider Information Becomes a Market Risk

Insider information has always been a factor in traditional sports betting. The odds can be influenced by a hidden injury, a late goalie change, a disciplinary problem, or a tactical change. That information can be a tradeable advantage in prediction markets.

This poses a novel integrity problem. There may be information available to teams, medical personnel, arena staff, officials and league staff prior to the general public. If that information reaches markets before the announcement, the problem is not only a betting one but also a question of market fairness.

Trust is essential for anyone who uses a Betway account or any betting platform, and they know that markets are not being manipulated behind the scenes by individuals with privileged access to the platform. The NHL’s agreement reflects the need to protect that confidence at a different level.

Prediction Markets Are Forcing New Oversight Models

Prediction markets are on the rise because they make real-world outcomes into tradable contracts. It can encompass elections, economic facts, entertainment, or sports activities. Proponents say that these markets are efficient aggregators of information. Since sports are involved, critics say, the products are akin to betting, and should be regulated accordingly.

While the NHL-CFTC agreement does not resolve that debate, it does indicate the direction the market is taking. An increasing number of sports leagues are working with regulators, exchanges, data providers, sportsbooks and integrity companies to monitor activity on various platforms.

Moreover, this is important because if suspicious behavior occurs in one venue, it won’t necessarily remain there. A price change on a prediction market can occur before sportsbook odds change. A social media rumor can start a chain reaction on multiple sites. Integrity teams must have a broader perspective.

Data Sharing Is Becoming Essential

In the modern era of integrity monitoring, it is all about data. Leagues require event data, team information, disciplinary records, injury disclosures, betting alerts, account patterns and market movement. Regulators will require trading data, along with times, trading participants, price changes and SARs (suspicious activity reports).

An information-sharing agreement establishes a legally binding pathway for such coordination. It enables the league and the regulator to compare results in the sport with those in the market.

This can seem invisible to the betway account holder. However, the benefits of robust behind-the-scenes data sharing can be equally significant: it can help identify problems sooner and ensure the betting environment is legitimate.

The Future of Sports Integrity

The new NHL CFTC agreement is a sign of the more technical aspects of sports integrity. No longer is it enough to just track locker rooms, referees, and suspicious betting alerts. Leagues must also be familiar with the market structure, trading behavior, price movement, data flows, and regulatory coordination.

Prediction markets and sportsbooks will continue to intertwine and sports integrity will be more and more like market surveillance. The objective will remain game protection. But the tools will be more financial, more data-driven and more connected.

Trust in sport is not just a matter of the time of the sport. This will also rely on the ability to monitor the markets surrounding the games with the same level of seriousness as the games themselves.

How A Major Hybrid Work Inquiry Should Change Washington

Happy young business woman employee, hr manager having remote online work hybrid meeting or distance job interview waving hand looking at laptop during virtual video conference call in office.

By Dr. Gleb Tsipursky

On a weekday morning in downtown Washington, federal buildings and corporate offices still feel half-full, even as return-to-office emails pile up. At the same time, across the Atlantic, the House of Lords has treated remote work not as a culture war skirmish, but as a subject for a full special inquiry on home-based working, backed by extensive evidence and formal hearings. Its Home-based Working Committee spent ten months asking a simple question with big consequences: is working from home working, and if so, how should governments and employers respond.

Remote work is not just a perk for tech workers; it is now a primary channel for bringing disabled Americans into steady, full-time roles.

The answer, detailed by researcher Jane Parry in a synthesis of five years of hybrid working evidence, is clear enough for policymakers. Hybrid work shows only modest average effects on productivity, but delivers meaningful gains in labor supply, employment rates, recruitment, retention and office efficiency when it is managed deliberately. The committee heard evidence that hybrid arrangements can raise labor supply by 1 to 2 percent and cut turnover costs by an estimated £7 billion to £10 billion a year in the UK, especially when employers lean into structured “anchor days” and redesign offices around collaboration. For a Congress fixated on productivity and deficits, the real story is that remote work has quietly become critical economic infrastructure.

Meanwhile, global data on working arrangements confirm this is not a passing phase. The Global Survey of Working Arrangements finds that full-time employees now average close to one day of work from home per week across 34 countries, with English-speaking economies and knowledge jobs showing significantly more remote time, according to its report on working from home around the globe. A companion paper on the evolution of working from home concludes that remote days have plateaued at historically high levels since 2022 and are likely to grow slowly as technology improves. Hybrid work has become a permanent feature of white-collar labor markets, not a pandemic loophole.

The Lords inquiry placed labor supply at the center of its analysis. Evidence submitted to the committee estimated that hybrid work can expand the available workforce, primarily by enabling people who cannot handle full-time commuting to participate. That group includes disabled workers, parents of young children and people in rural or high-cost regions who are effectively locked out of traditional office jobs. For a country facing chronic worker shortages and flat productivity, that margin matters. For the United States, which faces similar pressures and an aging population, it should be impossible to ignore.

New American research connects this directly to disability employment. An NBER study on work from home and disability employment finds that a one percentage point increase in remote work raises full-time employment among people with a physical disability by about 1 percent. The authors estimate that between 68 and 85 percent of the post-pandemic rise in full-time employment for this group between 2019 and 2023 is explained by expanded work-from-home options. Remote work is not just a perk for tech workers; it is now a primary channel for bringing disabled Americans into steady, full-time roles.

Global survey data show that these patterns rest on durable preferences. Workers with college degrees and access to remote-capable tasks typically want two or three days at home, and employers have largely settled around that level, according to the evidence on the evolution of working from home. For many employees, that flexibility is worth roughly an 8 percent pay increase in perceived value. Against that backdrop, the UK committee’s recommendation to treat hybrid work as a structured labor market tool rather than an ad hoc concession offers a blueprint that US lawmakers can adapt. It is directly relevant to efforts on both sides of the aisle to reduce economic inactivity, boost participation and draw caregivers and disabled Americans back into the workforce without new entitlement spending.

The Lords inquiry also underscores how hybrid work alters the basic economics of hiring and turnover. Parry’s summary of the inquiry findings notes estimates that better remote and hybrid policies could save UK employers many billions annually through reduced attrition and improved recruitment. The logic is straightforward: when workers strongly value flexibility, organizations that offer it do not have to constantly replace experienced staff or overpay to lure new ones into rigid schedules.

Employer surveys tell a similar story. The CIPD’s resourcing and talent planning report, based on over 1,000 HR leaders, reports that organizations offering hybrid or remote options are more likely to say they can attract and retain the talent they need. Many also report widening their recruitment radius far beyond commuting distance, effectively arbitraging regional wage differences and tapping skills that would otherwise be out of reach. Hybrid work, in other words, is a talent strategy in its own right.

For executives worried that performance will inevitably suffer, there is now rigorous experimental evidence to consider. A large experiment at Trip.com randomly assigned some teams to work from home two days per week while others stayed in the office full-time. The Stanford-led analysis of this hybrid work trial found that resignations among non-managers fell by one third and employees reported higher satisfaction, with no measurable decline in performance reviews, promotions or output. Across multiple studies summarized in the evidence on working from home, fully remote arrangements in certain roles can reduce output, but hybrid patterns that combine planned in-office collaboration with quiet at-home focus time tend to deliver flat or slightly positive average productivity.

This nuance is central for public debate in Washington, where “remote work” is often treated as a single category. The UK inquiry stresses that the real question is job design: which tasks genuinely require co-location, how often teams need face-to-face time and how office space can be reshaped to favor team rooms, mentoring spaces and project hubs over endless assigned desks, as described in its committee summary. That approach invites federal agencies and large companies to rethink their real estate footprints and performance management systems together, instead of treating office attendance as a proxy for output.

If the case for hybrid work is so strong, why is Washington locked in recurring battles over return-to-office mandates and telework “crackdowns”? Part of the answer is oversight anxiety. The latest government-wide telework report to Congress shows that more than half of eligible federal employees teleworked in fiscal 2023, and highlights benefits for continuity of operations, recruitment and morale. At the same time, agencies and watchdogs have raised serious concerns about inconsistent data, lax controls and gaps between badge swipes, time sheets and telework agreements, as described on OPM’s own telework program hub. That mix of success and sloppiness fuels political backlash.

Oversight reports point toward repair, not retreat. A 2025 Government Accountability Office review on federal remote work notes that CFO Act agencies reduced office space as telework expanded between 2020 and 2024, but also criticizes the lack of systematic evaluation of how remote work affects recruitment, retention and mission outcomes. A separate inspector general evaluation of OPM’s telework oversight finds that many agreements were expired or missing and that compliance checks were uneven, even as telework remained central to operations. Both reports call for stronger internal controls and clearer guidance rather than scrapping remote work entirely.

Keep hybrid eligibility tied to job content and performance, not seniority or political mood.

Here, the House of Lords offers a model for a better conversation. Its hearings found that blanket four- or five-day in-office mandates encode a crude trade-off between collaboration and staff satisfaction and often miss the underlying reasons for worker preferences. The committee highlights the role of “anchor days” when whole teams come in together, targeted recognition for hidden collaborative work such as mentoring and redesigned offices that guarantee teams can actually sit together, rather than fighting with seat-booking systems that scatter colleagues across floors.

For Congress and corporate boards, that points to a concrete agenda. Keep hybrid eligibility tied to job content and performance, not seniority or political mood. Invest in secure, easy-to-use collaboration tools and clear data on outcomes. Align leases and office layouts with realistic occupancy and the collaboration patterns teams actually need. And treat telework abuses as management failures to be fixed with better oversight, not as justification for policies that ignore the documented gains in labor supply, disability employment, retention and real estate efficiency.

Packed offices read well in soundbites, but the record from London and from American researchers points in another direction. Hybrid work, handled seriously, offers governments and companies a way to widen the labor pool, strengthen inclusion, reduce churn and shrink wasted space without sacrificing performance. Washington can chase nostalgia for 2019, or it can use that evidence to build a smarter, leaner and more inclusive model of work that actually matches how high-value jobs get done.

About the Author

Dr. Gleb TsipurskyDr. Gleb Tsipursky was named “Office Whisperer” by The New York Times for helping leaders overcome frustrations with Generative AI. He serves as the CEO of the future-of-work consultancy Disaster Avoidance Experts. Dr. Gleb wrote seven best-selling books, and his two most recent ones are Returning to the Office and Leading Hybrid and Remote Teams and ChatGPT for Leaders and Content Creators: Unlocking the Potential of Generative AI. His cutting-edge thought leadership was featured in over 650 articles and 550 interviews in Harvard Business Review, Inc. Magazine, USA Today, CBS News, Fox News, Time, Business Insider, Fortune, The New York Times, and elsewhere. His writing was translated into Chinese, Spanish, Russian, Polish, Korean, French, Vietnamese, German, and other languages. His expertise comes from over 20 years of consulting, coaching, and speaking and training for Fortune 500 companies from Aflac to Xerox. It also comes from over 15 years in academia as a behavioral scientist, with 8 years as a lecturer at UNC-Chapel Hill and 7 years as a professor at Ohio State. A proud Ukrainian American, Dr. Gleb lives in Columbus, Ohio.

Defense Spending and China Dominate Shangri La Talks

Defense Spending and China Lead Shangri La Talks

World leaders and defense officials gathered in Singapore for the 2026 IISS Shangri La Dialogue, where military spending, regional security, and the war in Ukraine became the main focus of discussions. Many countries signaled plans to increase defense budgets as global tensions continue to rise.

Pete Hegseth urged nations to spend more on defense, while countries including Japan, the Philippines, and the Netherlands said they are boosting military investments. Officials said the war in Ukraine has changed how governments think about security and military readiness.

China also drew attention after once again sending a lower level delegation instead of its defense minister. Several officials from the United States, Japan, and Europe criticized Beijing’s absence, saying it reduced opportunities for direct talks. Chinese delegates still strongly defended the country’s military policies and positions on Taiwan during the summit.

The conflict in Ukraine remained a major topic throughout the event. Defense leaders said countries are closely studying Ukraine’s use of asymmetric warfare, where smaller forces use drones, technology, and flexible tactics against stronger military powers. Many governments now see those strategies as important for future defense planning.

Related Readings:

China Signals Tariff Cuts

Trump Xi Meeting Begins

Military Spending Seeks $200bn Boost

Why Precious Metals Still Matter in a Digital Economy

Precious Metals

In an era dominated by cryptocurrency headlines and AI-driven financial tools, it might seem old-fashioned to talk about gold, silver, and rare earth metals. Yet for millions of investors worldwide, physical precious metals remain one of the most reliable stores of value — and for good reason.

The appeal is simple: unlike stocks or digital assets, precious metals have intrinsic worth. They cannot be printed, hacked, or inflated away by central bank policy. Gold has preserved purchasing power across centuries, surviving the collapse of empires, world wars, and financial crises that wiped out paper-based fortunes overnight.

But today’s precious metals market is far more nuanced than it was even a decade ago. Investors are no longer just choosing between gold coins and silver bars. Rare and specialty metals — platinum, palladium, rhodium, and a growing range of industrial metals — are attracting serious attention from both retail and institutional buyers. Much of this interest is driven by the green energy transition, which has created surging demand for materials used in electric vehicle batteries, solar panels, and hydrogen fuel cells.

For anyone stepping into this space for the first time, the sheer variety of options can feel overwhelming. Where do you buy? What form should you hold — coins, rounds, bars, or ETFs? Are premiums reasonable? Is the dealer reputable? These questions matter enormously, and the answers often depend on your specific financial goals.

One of the most trusted names in the precious metals space is APMEX, a platform that has served both beginner and experienced investors for decades. If you’re evaluating whether APMEX fits your investment strategy, it’s worth reading this overview from Rare Metal Blog, which breaks down the platform’s key features, product range, pricing transparency, and overall reputation in a balanced and informative way.

Understanding how to buy is only half the equation. Knowing when to buy — and how much to allocate — matters just as much. Most financial advisors suggest that precious metals should represent somewhere between 5% and 15% of a well-diversified portfolio, acting as a hedge rather than a core growth engine. In periods of high inflation, geopolitical uncertainty, or currency weakness, that allocation can pay dividends in ways that traditional equities simply cannot.

Storage and insurance are equally important considerations. Physical metals require secure vaulting, whether at home or through a third-party custodian, and that cost should factor into your return calculations. Many dealers, including APMEX, offer storage solutions that simplify this side of the equation considerably.

The bottom line is that precious metals investing has never been a get-rich-quick scheme. It is a strategy rooted in patience, discipline, and a long view of economic history. Whether you’re hedging against inflation, diversifying away from volatile equities, or simply preserving generational wealth, the fundamentals of the precious metals market remain as compelling today as they have ever been.

AI Investment Boom is Making the AI Bubble Argument Look Tired

AI investment boom

By Dr. Gleb Tsipursky 

The bubble thesis has a problem: the customers keep showing up with real money. Nvidia’s latest results put a hard edge on the argument, with the AI investment boom producing record quarterly revenue of $81.6 billion and data center revenue of $75.2 billion. Those numbers do not prove that every AI stock is sensibly priced or that every enterprise pilot will pay off. They do prove that demand for AI infrastructure is not a social media hallucination, a conference-room fad, or a temporary burst of demo-driven enthusiasm.

AI infrastructure spending looks less like tulip mania than like the early stages of an industrial platform

The smarter conclusion is more nuanced and more useful for executives. The AI bubble hypothesis explains pockets of excess, valuation anxiety, and copycat spending. It does not explain the scale of adoption, the capital formation, or the emerging productivity evidence now visible across the economy.

Demand Is Behaving Like Infrastructure, Not Hype

Speculative bubbles tend to float above operating reality. AI is sinking into it. The Federal Reserve’s 2026 review of enterprise AI adoption found that about 18% of U.S. firms had adopted AI by the end of 2025, while work-related generative AI use among individuals stood near 41%. A separate senior-leader survey cited in the same analysis estimated that 78% of the labor force works at firms that have adopted AI.

That breadth matters because bubbles depend on a widening gap between belief and use. AI is moving in the opposite direction. Stanford’s 2026 AI Index Report shows an ecosystem shifting from experiment to buildout, with corporate investment, frontier-model revenue, cloud capital spending, and consumer value all rising together.

The most important signal is not one company’s earnings. It is the alignment between chip demand, cloud expansion, model deployment, enterprise experimentation, and worker usage. AI infrastructure spending looks less like tulip mania than like the early stages of an industrial platform. Railroads, electricity, broadband, and cloud computing all required heavy upfront investment before their highest-value applications became obvious. AI is following that pattern, though at a faster and more volatile pace.

That distinction should make leaders more confident investing into AI, not more reckless. The point is not to chase every shiny model or vendor claim. The point is to recognize that the foundation is becoming durable enough to justify serious operating commitments.

The Real Risk Is Weak Implementation, Not AI Itself

The best argument for caution is not that AI lacks value — it is that many organizations still fail to capture it. MIT’s 2025 State of AI in Business research on generative AI ROI highlighted a sharp divide between widespread pilots and successful production deployments, especially for custom enterprise tools. That finding should sober executives, but it should not freeze them.

The lesson is managerial, not technological. Companies that paste chatbots onto broken workflows usually get novelty. Companies that redesign processes, connect AI to proprietary data, clarify accountability, and measure performance get leverage.

McKinsey’s 2025 global survey found that 88% of respondents reported regular AI use in at least one business function, yet only 39% reported enterprise-level EBIT impact. The same research found that high performers were much more likely to redesign workflows, embed AI into business processes, track KPIs, and invest in talent, data, and operating model changes. In other words, AI business value is not magic. It is built.

This is where executive confidence should become sharper. The failure pattern is visible. The success pattern is visible too. Leaders do not need blind faith in AI. They need the discipline to stop funding disconnected pilots and start backing fewer, better programs tied to revenue growth, margin expansion, customer experience, risk reduction, and speed.

That also means changing the investment conversation. A serious AI leadership strategy starts with business architecture, not software procurement. The winners will not be the companies with the longest list of AI tools. They will be the companies that rebuild how work gets done.

Confident Leaders Will Govern The Buildout, Not Avoid It

The bubble debate often tempts executives into a false choice between exuberance and paralysis. Neither is appropriate. AI markets can contain excess while AI itself becomes indispensable. The internet produced both Pets.com and Amazon. Cloud computing produced both wasteful migrations and durable operating advantage. The same split is already appearing in AI.

PwC’s 2025 Global AI Jobs Barometer gives leaders another reason to stay engaged. Its analysis of nearly a billion job ads found that industries most exposed to AI saw productivity growth nearly quadruple after the spread of generative AI, while revenue per employee grew three times faster in the most AI-exposed industries than in the least exposed ones. Those AI productivity gains are early, uneven, and still contested, but they are too material to dismiss.

The right response is governed acceleration. Boards should ask for use-case economics, data-readiness plans, cybersecurity controls, vendor concentration reviews, model-risk protocols, and workforce adoption metrics. Finance teams should demand milestones. Business leaders should own outcomes. Technology teams should build reusable platforms rather than one-off demos.

That is how AI capital spending becomes strategic investment instead of theater. The goal is not to spend because competitors are spending, but rather to build capabilities that compound: better data pipelines, faster product cycles, more responsive service operations, stronger forecasting, lower error rates, and higher employee leverage.

AI should make leaders more confident because the investment case is no longer built only on imagination.

This is also why waiting for perfect clarity is risky. By the time every AI use case has a clean benchmark and every valuation concern has settled, the leading firms will already have redesigned workflows, trained teams, negotiated infrastructure access, and learned from mistakes. AI transformation rewards accumulated learning, and accumulated learning takes time.

Conclusion

The AI bubble argument is not foolish. Markets can overprice real revolutions, and executives should distrust any strategy built on fear of missing out. But the stronger evidence now points to something larger than hype: real adoption, real infrastructure demand, real productivity signals, and a widening gap between organizations that experiment casually and those that execute seriously.

AI should make leaders more confident because the investment case is no longer built only on imagination. It is increasingly built on operating evidence. The mandate is not to spend blindly. It is to invest with conviction, govern with rigor, and move fast enough to learn before competitors turn AI from an experiment into an advantage.

About the Author

Dr. Gleb TsipurskyDr. Gleb Tsipursky was named “Office Whisperer” by The New York Times for helping leaders overcome frustrations with Generative AI. He serves as the CEO of the future-of-work consultancy Disaster Avoidance Experts. Dr. Gleb wrote seven best-selling books, and his two most recent ones are Returning to the Office and Leading Hybrid and Remote Teams and ChatGPT for Leaders and Content Creators: Unlocking the Potential of Generative AI. His cutting-edge thought leadership was featured in over 650 articles and 550 interviews in Harvard Business Review, Inc. Magazine, USA Today, CBS News, Fox News, Time, Business Insider, Fortune, The New York Times, and elsewhere. His writing was translated into Chinese, Spanish, Russian, Polish, Korean, French, Vietnamese, German, and other languages. His expertise comes from over 20 years of consulting, coaching, and speaking and training for Fortune 500 companies from Aflac to Xerox. It also comes from over 15 years in academia as a behavioral scientist, with 8 years as a lecturer at UNC-Chapel Hill and 7 years as a professor at Ohio State. A proud Ukrainian American, Dr. Gleb lives in Columbus, Ohio.

Why the “Right-to-Be-Forgotten” is Often a Fail

Right to Be Forgotten
Image from Pexels

When a client arrives with a right-to-be-forgotten request, they are usually operating under a fundamental misunderstanding. They have likely heard the term in media reports or from a lawyer, and they have formed a clear expectation: if the request is successful, the offending content will vanish from the internet.

The reality is far more constrained. A successful request under the UK GDPR or EU GDPR does not delete the underlying content. It simply delists a specific URL from search results in a specific jurisdiction when the search is performed using the data subject’s name. 

The content remains live, it remains accessible via direct navigation, and it remains visible in other jurisdictions or through AI-generated summaries. For a client looking to sanitise their digital footprint, the legal route is rarely the silver bullet they imagine.

The Limits of the Legal Mandate

The right to erasure, established by the Court of Justice of the European Union in the Google Spain (C-131/12) ruling and later formalised in Article 17 of the GDPR, is not an absolute right to control one’s history. It is a balancing act. Search engines are required to weigh the data subject’s privacy interests against the public’s right to access information.

In practice, these requests are frequently refused. Recent data from the Google Transparency Report indicates that a significant portion of delisting requests fail, particularly when they involve information of public interest. Based on years of established jurisprudence, requests typically collapse in five specific scenarios

Public Figures

The balancing test almost always favours the public interest. If the individual holds a position of social, political, or commercial influence, the threshold for delisting is significantly higher.

Recent Content 

While there is no formal “expiry date,” the Information Commissioner’s Office (ICO) guidance suggests that information remains relevant if it is current. Content less than a few years old is rarely delisted unless it is demonstrably inaccurate.

Criminal Convictions

Even for spent convictions, search engines often determine that the information retains relevance for public safety or historical record, as seen in complex rulings like NT1.

Self-Authored Content

You cannot be forgotten for the content that you chose to publish yourself.

Widely Reported Data

Delisting one URL is a futile gesture if the exact same information remains live and accessible on twenty other sites that have not been challenged.

The Technical Alternative – Why Sequencing Matters

This is where the distinction between legal and technical routes becomes vital. While the legal path seeks to force a removal based on privacy mandates, suppression services operate on the environment itself. They do not require the content to be taken down; they require it to be outranked by authoritative, neutral, or positive alternatives.

A technical approach often succeeds where a legal request fails for three reasons

Factuality is Irrelevant

To win a legal “right-to-be-forgotten” request, you usually have to prove that the information is either incorrect or outdated. If the content is 100% true, the law often won’t help you take it down. Suppression is different: it doesn’t care if the information is true or false. It focuses on making sure that more relevant content shows up first so the damaging result gets pushed out of sight.

Speed 

Legal delisting is a slow, bureaucratic slog. Each request requires a formal submission, a lengthy balancing test, and months of back-and-forth. Suppression is much faster, often showing measurable results in a fraction of that time.

Global Reach

Legal delisting only works in specific regions, meaning a result might disappear in the UK but remain visible to someone in the US. Suppression is more effective because it works globally; it reshapes the search results for everyone, no matter where they are or which version of the search engine they are using.

The Honest Path Forward

Law firms that raise the right-to-be-forgotten as a primary solution without accurately setting client expectations are creating downstream frustration. It is a narrow tool, best reserved for specific instances of clear privacy violations or demonstrable irrelevance.

The honest framing for any client is that the legal route and the technical route are not substitutes. They are sequenced tools. The most effective engagements assess both simultaneously. If a legal request has a high probability of success, pursue it. 

But if the information is accurate and serves a public function, relying on a delisting request will only waste time. In those cases, the technical route is the only viable path toward regaining control of the narrative. The era of assuming the law will clean your digital history is over; it is time to start managing it.

Trump Appeals Tariff Refund Order for Importers

Trump Fights Expanding Tariff

Donald Trump plans to appeal a court order that allows companies to seek refunds for tariffs that were recently struck down by the US Supreme Court. The ruling said Trump did not have the authority to impose higher import taxes on goods from many countries.

Since the decision, businesses across the United States have started receiving refunds through US Customs and Border Protection. Officials said refund claims have already reached tens of billions of dollars, with some payments already sent to companies that applied early.

The Trump administration argues that refunds should apply only to businesses that filed lawsuits, not to all importers. Government lawyers also warned that processing refunds for every company could take time and may require major system updates. Critics say the appeal could delay payments for months.

Some companies say the refunds will help lower prices or stabilize their businesses after dealing with higher import costs. Retailers and shipping firms have also promised to pass refunds back to customers where possible. Still, uncertainty remains as the legal fight continues.

Related Readings:

US Tariff Refunds Open After Supreme Court Ruling

Trade Deals

The Ebola Crisis: The Inconvenient Truths

Ebola Crisis

By Dan Steinbock 

For weeks, the latest Ebola outbreak was framed as a regional emergency.  That assumption is now being challenged by mounting evidence that the outbreak may be broader, more fragmented and entrenched than initially believed.

On Saturday, WHO Director-General Tedros Adhanom Ghebreyesus visited eastern Congo’s Bunia, a city at the heart of the Ebola outbreak, where the virus is spreading faster than the response.

In some affected regions, public trust in government and foreign health interventions is extremely weak.

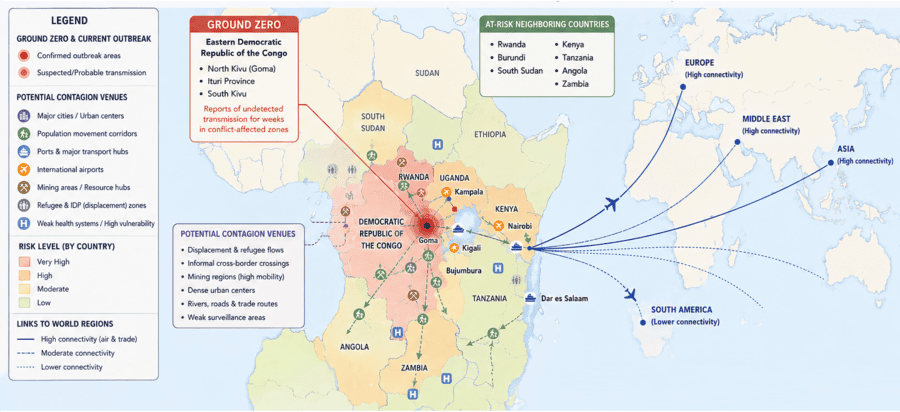
The crisis is centered in eastern Democratic Republic of the Congo (DRC), with spillovers into Uganda and rising concern across neighboring states. Official numbers remain uncertain because surveillance systems in conflict zones are incomplete.

The outbreak circulated undetected for weeks, perhaps longer, before full recognition. By the time authorities moved aggressively, transmission chains may have spread across borders, refugee corridors and informal trade networks.

Why this Ebola crisis is different

The danger does not lie primarily in the current number of cases, which remain far below the scale of COVID-19 or even the West African Ebola outbreak of 2014-16.

Historically, Ebola outbreaks have remained geographically concentrated. Although the virus is highly lethal, it is relatively difficult to transmit compared with airborne respiratory diseases.

But the present crisis is unfolding under unusually adverse conditions: war, displacement, urbanization, weak public-health systems, declining international aid capacity and growing mistrust of authorities. “Never before has an Ebola outbreak recorded so many cases so soon after its declaration,” the medical charity Médecins Sans Frontières has warned.

Eastern Congo is one of the most difficult environments in the world for epidemic control. Armed militias, population displacement and attacks on medical facilities undermine contact tracing and isolation efforts. Informal border crossings are extensive. Urban growth has accelerated faster than health infrastructure. In some affected regions, public trust in government and foreign health interventions is extremely weak.

Moreover, the current outbreak involves the Bundibugyo strain of Ebola, for which no fully established licensed vaccine exists comparable to those deployed against the Zaire strain during previous outbreaks. That sharply complicates containment.

Potential contagion links

One of the least understood aspects of the present outbreak concerns contagion linkages beyond immediate epidemiology. Let’s start with physical contagion networks: Eastern Africa’s transport corridors increasingly connect local outbreaks to regional and global mobility systems.

Cities like Kampala, Kigali and Nairobi are no longer isolated peripheral centers. They are integrated into international aviation and trade flows linking Africa to the Gulf, Europe and Asia.

Second, institutional contagion effects: Fragile health systems already weakened by debt burdens, inflation and post-pandemic exhaustion are struggling to absorb another major shock, particularly in sub-Saharan Africa.

Third, psychological and economic contagion: Financial markets, tourism flows, commodity exports and investment patterns can react violently even to limited outbreaks if fears of wider transmission intensify. The 2014-16 Ebola crisis demonstrated how panic itself can generate severe economic damage independent of the actual epidemiological scale.

Finally, geopolitical contagion: In a fragmented multipolar world, global health crises increasingly intersect with strategic competition, sanctions, debt restructuring and security concerns. Epidemics no longer operate outside geopolitics; they amplify it.

The Ebola Crisis
Sources: WHO, Africa CDC, Reuters, UNICEF, OCHA, IOM (May 29, 2026)

The impact of US aid withdrawal

One of the most consequential dimensions of the current Ebola crisis concerns the partial retreat of US and Western international health support over recent years.

American funding cuts and shifting priorities have weakened several pillars of global epidemic preparedness, including surveillance systems, laboratory support, emergency logistics and NGO operations across vulnerable regions. The abrupt manner these cuts have been executed has compounded the negative effects.

The broad erosion of development assistance after COVID-era fiscal strains aggravates the problem. In practice, this means slower outbreak detection, weaker field operations and reduced healthcare resilience precisely where early intervention matters most.

The retreat of preventative international health capacity is likely to ultimately increase the probability of far costlier future global emergencies.

In the case of Ebola, the Trump administration is contributing to amplified risks. Though most countries are following the WHO’s advice on travel bans, the U.S. is ignoring it.

Contagion scenarios

The first and most likely plausible scenario is a severe but regionally contained epidemic. The outbreak could produce thousands or even tens of thousands of cases regionally, while devastating local economies and healthcare systems.

In this case, intensified international response efforts eventually stabilize transmission through traditional Ebola control measures: isolation, tracing, border monitoring and behavioral adaptation. For now, this is regarded as the likeliest scenario.

The second scenario involves a wider multinational African epidemic. This becomes plausible if transmission becomes embedded along mobility corridors linking Congo, Uganda, Rwanda, Kenya, Tanzania and beyond. Refugee flows, mining routes and informal commerce networks could facilitate wider regional spread.

In this case, Ebola would remain primarily an African crisis, but one with major global economic, humanitarian and geopolitical repercussions.

The third scenario — a true global pandemic transition — remains relatively unlikely but can no longer be dismissed entirely. Sustained international spread would likely require repeated exportation into major cities combined with failures in hospital containment and perhaps viral adaptation toward easier transmission.

There is currently no evidence of such adaptation. Nevertheless, prolonged uncontrolled transmission increases evolutionary opportunities and magnifies systemic risk.

From regional emergency to global test

The present Ebola crisis has not become a global pandemic threat comparable to COVID-19. Public health officials hope it will remain regionally concentrated despite severe humanitarian consequences.

The failure to contain the Ebola crisis in its early local stage suggests that the lessons of Covid-19 pandemic have not been learned. It heralds still another tragedy of missed opportunities.

Once they reach major urban systems and international mobility corridors, costs rise exponentially.

However, the world today is less institutionally cohesive, less politically cooperative and less strategically prepared for transnational crises than it was just a decade ago. Pandemic fatigue, geopolitical rivalry and fiscal retrenchment have weakened precisely the mechanisms needed for early containment.

Infectious disease containment operates according to a simple principle: outbreaks are cheapest to stop at the periphery. Once they reach major urban systems and international mobility corridors, costs rise exponentially.

It is a principle that international community can ignore only at its own peril.

About the Author

Dr Dan SteinbockDr. Dan Steinbock is an internationally recognized strategist of the multipolar world and the founder of Difference Group. He has served at the India, China and America Institute (USA), Shanghai Institutes for International Studies (China) and the EU Center (Singapore). For more, see https://www.differencegroup.net

Financial Services Firms Spend Heavily on Events. Nobody Owns What Comes Out of Them.

Presentation, screen and businesswoman in office for planning with finance graph, statistics or charts. Meeting, speech and female financial manager with information for investment pitch in workplace

By Serge Bejjani

Financial firms heavily invest in events, but without visual ownership, most value is lost. Leaving fragmented content, weak brand recognition, and missed opportunities to build trust.

Events have become a core feature of the financial services calendar. Investor summits, client dinners, and fintech conferences are multiplying, with heavily allocated budgets. And yet, for all this investment, very little of what’s created in those rooms at those events actually delivers long-term brand value. So, what ROI do they create? The reason it’s so hard to answer that question is that nobody owns what comes out of them.

The open accountability gap

Events should deliver connections, contracts, and content. The first two partly come down to what happens on the day, but they’re also intrinsically linked to the third, specifically, the visual output. Visual content directly influences how a brand is perceived. The problem is that in most financial institutions, visual output is both everywhere and owned by no one.

Of course, there are guidelines, but with event content typically being ad hoc, impromptu, and minimal, those guidelines are rarely enforced. Marketing teams produce campaigns focused on promoting the event, rather than maximising its potential. Communications teams are really only about messaging. Events teams focus, understandably, on logistics and experience. And sales teams create their own materials to meet their immediate needs. There’s no cohesive oversight and no branding ownership. In our work covering corporate events for global financial brands, it’s not unusual to find four or five different production vendors hired across territories for a single summit series, each interpreting the brief differently, and none of them owning what the body of work looks like once it’s stitched together. The result is fragmentation, which not only reduces the ROI of events but can erode a brand’s visual identity, and with it, consumer familiarity, recognition, and trust. The brand is seen, but not remembered.

Compliance is a constraint, not an explanation

Ask why financial services marketing looks the way it does, and most people will point to compliance. Strict regulations, risk aversion, and approval layers are all genuine constraints. In finance, organisations have to be careful about what they do and say. But that doesn’t mean visual creativity is off the table. The actual reason most financial firms default to stock photography and tick-the-box headshots, rather than treating either as a real brand asset, is that it’s easier. But that ease comes at the cost of differentiation.

Financial services websites and social pages blur into one. They use the same colour palettes, abstract graphics, and interchangeable imagery of people in suits. The intention is to portray professionalism. But the result is typically bland anonymity. At a glance, nothing distinguishes one firm from its competitors. Events can be the route to something better.

How events can deliver more than a single hit

Finance is one of the most acutely personal concerns. And yet, financial institutions almost inevitably manage to feel impersonal. Events are one of the few moments when that can change. Human contact is available. Leaders become approachable. Conversations become more natural. There are scripts, but only in the right places. And clients can engage in real time, experiencing company culture in its truest form but only for the people in the room.

That can change with a clear visual strategy. Moving away from ad hoc sound bites and keynote video capture, and towards curated but natural content – executive interviews, client perspectives, candid team interactions, behind-the-scenes moments – that can fill newsletters and social pages for months. The kind of shot list that should be agreed before the venue is booked, not improvised in the hallway.Not staged, not generic, but authentic and credible. That takes intent and ownership.

Why ownership matters

When there is clear ownership of visual strategy, visual identity becomes an asset. Content stops being opportunistic and is instead integrated into event strategy from the outset. While the venue is being booked and the agenda finalised, the focus shifts to defining what to capture, how it will be used, and how it can further brand objectives. A pre-production brief, written, signed off, and put in the hands of every photographer and videographer on the day, converts ‘we’ll see what we get’ into something a marketing team can plan around.

Clear guidelines, properly enforced, don’t just produce better looking content, they reinforce the brand narrative, building client trust and familiarity over time. That requires accountability: someone taking charge and ensuring those goals are met.

The missing link

Ownership is one of the main reasons events are underutilised. But inconsistency also plays a part. Even when companies understand that content can be invaluable, understanding how to access it isn’t always simple, especially for businesses working in multiple territories. The lack of ownership means that most large financial institutions rarely work with a single creative partner across markets. Each city gets its own producer, each producer brings its own interpretation of the brand, and the cumulative effect is a visual identity that drifts a little further out of focus with every event.

As standalone events, the content produced might be passable, good, even. But when brought together, all that’s managed is a sense that cohesion is missing from the brand. Strong central direction and oversight help. A core creative partner, fully informed of the company’s intent and accountable for output across every market, is what turns a fragmented set of event coverage decisions into a consistent brand asset

The financial services sector understands that events carry value. It just doesn’t know how to unlock it. The industry is investing heavily in creating scenarios that make it feel more human, credible, and differentiated. But it’s forgetting that its biggest battles in that arena happen outside of the event rooms. Continuing to pursue and invest in events without first creating a strong visual content strategy and assigning ownership of it means that all of those carefully curated moments are quickly forgotten. And that’s a waste that no organization can really afford.

About the Author

Serge BejjaniSerge Bejjani is the co-founder and CEO of Shootday, a global photo and video production company operating across 150+ cities worldwide. He leads the company’s operations, sales, and client experience, building the infrastructure that enables brands to produce consistent visual content across distributed teams and international markets. His work focuses on scaling creative production through technology, global talent networks, and streamlined production systems.

EDITOR'S PICK OF THE WEEK

China economic growth

China’s Challenging Search for a New Model of Economic Growth

By Danny Leipziger China cannot continue to rely on exports to drive its growth, but what are the alternatives? China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...

WISE DECISION MAKER GUIDE

POWER INFLUENCERS

Emerging Trends

The Future of Global Trade