Chinese President Xi Jinping’s visit to Washington has featured elaborate ceremonies and warm public remarks, but the two sides have yet to announce major breakthroughs on their most difficult issues. President Donald Trump welcomed Xi with military honors, while Xi announced a panda gift and a new student exchange program. Both leaders also highlighted the need for continued dialogue.
Trade remains one of the main areas of discussion. A temporary U.S.-China tariff truce is expected to be extended, helping prevent a return to last year’s trade tensions. However, disagreements remain over China’s purchases of U.S. agricultural products and rare earth exports, while Beijing is watching Washington’s plans for a potential arms sale to Taiwan.
AI is another major point of difference. U.S. officials have largely focused on the risks posed by increasingly advanced AI, while China has placed more emphasis on speeding up development and putting the technology to wider use across its economy. The wars in Iran and Ukraine also make progress in talks difficult. So far, the visit seems to have been more about keeping diplomatic ties stable and maintaining dialogue than reaching major agreements.
Funded-trader programmes have become one of the most visible business models in the retail trading market. This article explains how a prop firm earns money, what infrastructure it runs on and which decisions founders tend to underestimate.
What a prop firm sells
A modern prop firm sells an evaluation rather than a brokerage service. A trader pays a fee, receives a simulated account of a stated size and has to reach a profit target without breaching the loss limits. Those who pass get a funded account and keep a share of the profit they generate, which is paid out on a schedule the firm defines. Unlike a broker, the firm does not accept client deposits and does not hold client money, and this single difference shapes almost everything else about the business: the revenue model, the legal treatment and the technology it depends on.
Where the revenue comes from
The main income line is evaluation fees, followed by resets and repeat purchases from traders who failed a previous attempt. Payouts to funded traders are the main cost. A lot of new founders look only at the first half of that equation, since most evaluations end in a breach and the fee income looks comfortable on a spreadsheet. The weak point appears when a small group of consistently profitable traders starts requesting payouts every cycle. If those payouts can only be covered from new fee income, the firm depends on constant sales growth, and the first slow month may turn into delayed payouts, which is the fastest way to lose a reputation in this niche. More careful operators copy the positions of funded traders to a real liquidity account at a chosen ratio, so that part of the payout liability is matched by real market profit and the firm’s exposure is visible in one place.
The technology stack
A prop firm needs more software than a first-time founder usually expects. The list includes a trading platform, a CRM with a challenge store and order history, a risk engine that checks every account against the rules in real time, KYC and payment processing, a payout workflow with approvals, and affiliate tracking, since a large share of the traffic in this niche comes from partners. These components can be bought separately and integrated, or licensed as one bundle from a single vendor. Anyone researching how to start forex prop firm operations will find both routes on the market, and the choice is mostly about control versus speed: separate components give more flexibility, while a bundle removes integration work and leaves one supplier responsible when something breaks.
Pricing models differ as well. Some vendors charge a flat monthly fee and others take a share of revenue, which looks cheaper at launch and can become the largest line in the budget once the firm grows. In both cases the vendor supplies software only. Liquidity, banking and payment processing remain relationships the firm has to hold directly, and it is worth confirming this before signing anything, since some founders assume the platform vendor also brings the price feed.
Platform choice
For years MetaTrader was the default answer. After MetaQuotes tightened access for prop firms in 2024, a lot of firms moved to cTrader, Match-Trader, DXtrade and TradeLocker or to their own web terminals, and platform became something a trader checks before buying a challenge. It matters most for automated strategies, because an EA written for MetaTrader does not run anywhere else. For a founder this is as much a marketing decision as a technical one, since traders self-select by platform before they read the rules. It is also worth checking whether the CRM and the risk engine sit above the platform or inside it, because only the first setup lets the firm add or replace a platform later without rebuilding the back office.
Writing the rulebook
Rules are the actual product, and traders will read them line by line against the firms they already know. The decisions a founder has to make include:
phase structure: one-step, two-step or instant funding
profit targets, minimum trading days and reset price
maximum drawdown: static or trailing, measured against balance or equity
daily loss limit
consistency rule and lot-size caps
news trading restrictions
weekend holding
The last point is easy to overlook. The gap between Friday close and Sunday open is where forex programmes tend to lose money, so whether positions can be held across it, and at what size, should be a configured rule and not a hope. How the rules are enforced matters as much as how they are written. A breach detected by the engine at the moment it happens is a fact, while a breach discovered manually when a trader requests a payout is a dispute, and such disputes are the most common source of negative reviews in this industry. Some firms also set a severity for each rule (warning, freeze or breach), which lets a new rule start as a warning while the team learns how its traders behave.
How traders will compare a new firm
Few traders buy a challenge straight from an advert. Most of them go through comparison sites first. Listings of the best forex prop firms typically rank companies on reported payouts, trader reviews and years in operation, and then show the entry fee, maximum funding, profit split and supported platforms side by side. Profit split rarely decides anything, because nearly every firm advertises a similar range. The rules decide: static or trailing drawdown, the presence of a consistency rule, the number of required trading days and permission to hold through news. Traders also check whether the fee is refunded with the first payout and what a reset costs, since a cheap entry with an expensive reset is not cheap for someone who needs two attempts. A new firm has neither years in operation nor a review history, so clear rules and a documented payout record are the only parameters it can compete on from day one.
Licensing and legal structure
In most jurisdictions an evaluation programme is treated differently from a brokerage, because traders work with the firm’s own or simulated capital and do not deposit funds for trading. That said, the legal treatment depends on where the company is incorporated and how the product is structured, and regulators in several countries have started to look at the sector more closely. Some groups include a licensed broker entity, but that licence covers the broker and not the evaluation programme. The practical advice is to get a legal opinion in the chosen jurisdiction before building the product, since restructuring a live firm costs far more than structuring a new one.
Common mistakes
pricing challenges without modelling payouts
copying a competitor’s rules without an engine able to enforce them
reviewing breaches manually at payout time
signing a revenue-share contract without calculating it at scale
leaving the legal opinion until after launch
Final thoughts
Technology is usually the fastest part of launching a forex,crypto or futures prop firm. The slower parts are the commercial design of the challenge, a rulebook the firm can actually enforce, a payout model that does not depend on next month’s sales, and a legal structure that holds up to scrutiny. Founders who settle these questions first tend to find that the remaining choices, including the platform and the vendor, become much easier to make.
President Donald Trump and Chinese President Xi Jinping are set to meet in Washington as both sides look to stabilize trade relations and secure new economic deals. Their talks come with the existing trade truce still fragile, while tariffs remain high and the two countries continue to disagree over export controls and other trade measures.
A one-year extension of the current truce is seen by some analysts as a likely outcome, potentially keeping tariffs and new export restrictions from escalating. The two sides are also discussing a possible $30 billion reduction in tariffs on non-critical goods, with the U.S. seeking more Chinese purchases of American agricultural, energy and other products. However, analysts expect limited progress on sensitive issues such as advanced semiconductors.
AI is expected to be another major topic, with Washington and Beijing competing for leadership in the technology. The talks could include discussions on AI safety and a proposed channel for notifying each other about serious AI incidents. Meanwhile, U.S. sanctions targeting Iran could add another complication, given China’s role as a major trading partner of Tehran. Alongside the economic talks, several major U.S. business leaders are expected to attend a state dinner for Xi.
Preventing disputes can help you protect two of your company’s most important assets, money and time.
As Benjamin Franklin wrote of fire-threatened Philadelphia in 1736, “An ounce of prevention is worth a pound of cure.” The maxim also applies to contractual conflicts.
But what does dispute prevention actually look like? And how can you incorporate it for your company?
That question is being addressed by research thinktanks such as the International Institute for Conflict Prevention and Resolution and the University of Tennessee’s Global Supply Chain Institute. This article shares proven mechanisms for preventing costly contract disputes.
Before we dig in, let’s look at some compelling research on the cost and time associated with contract disputes.
The High Costs of Managing Disputes
Many people associate dispute costs with third-party fees-lawyers, paralegals, accountants, claims consultants, and other experts. In actuality, there are many other costs that contribute to the high cost of managing disputes.
There are soft costs involved, too. Research by a CPR Dispute Resolution Services task force outlined seven cost categories for managing disputes such as lost profits and diversion of company resources.
While managing the cost of disputes is one thing, it is important to consider the fact that disputes also cause other disruptions such as consuming time. An Association of Corporate Counsel study found:
Nearly half—46%—of in-house counsel reported that the length of litigation was increasing, versus only 8% citing that it was declining.
Seventy-two percent of employment and labor disputes last longer than one year, and 71% of breach of contract disputes last longer than one year, with 22% taking more than two years.
Simply put, the more time people spend working on disputes, the more they are not spending in value-added activities that can positively impact the organization.
Avoiding a Vicious Cycle
The good news is there are proven tactics companies can take to diminish the likelihood of facing these headaches. The authors of the book Preventing the Dispute Before It Begins: Proven Mechanisms for Fostering Better Business Relationships outline eighteen mechanisms and provide compelling case studies of how they are being used in practice.
One of lessons? Recognizing that dispute prevention comes well before your dispute resolution team gets involved. In fact, good dispute prevention practices start as early as when you are looking to select a business partner and thread through both the contract development and contract management aspects of business relationships.
Below are three dispute prevention tactics that can help companies resolve conflicts before they turn into full-blown disputes.
Partnering
Partnering uses team-building tactics to help build a strong, collaborative working relationship among contracting parties. Partnering is a deliberate undertaking between parties to ensure they align on the purpose of the contract, their mutual objectives, expectations and values, the risks they are likely to confront, conflicts that may arise, or any other issues that will portend a better relationship.
Partnering often involves workshops with key stakeholders. For example, contracting parties may hold a retreat among key personnel involved in the project/relationship. The expected benefits from partnering activities include improved efficiencies and cost-control, increased possibilities for innovation, continued quality improvement of goods and services, and reduced likelihood that conflict will escalate to dispute.
The typical steps commonly found in partnering include:
Commitment During Contracting: The process begins when two or more organizations contract to work together and agree to use partnering
Post-Contract Planning: Stakeholders select a facilitator, stakeholders, and the agenda and time for the initial partner meeting
Kickoff Workshop: The participants establish their commitments and build a team culture. The parties establish a formal charter, identify key issues and risk management strategies, and develop a dispute management plan and processPeriodic Partnering Meetings: Monthly or quarterly “refresher” meetings to review progress and objectives to allow for adjustments
Close-Out Workshop: Final evaluations and lessons learned to ensure improved processes in the future, along with recognition of individual contributions
Traditionally, partnering is considered a post-contract signing mechanism. However, in recent years, partnering has extended to pre-contract signing with the use of a deal facilitator, who helps contracting parties develop their contract.
Deal Facilitator
Using a neutral party to resolve disputes is commonplace. But an interesting spin proving to be effective at preventing disputes is to leverage a third party for help in deal development, too. The third party—often referred to as a deal facilitator or deal mediator—is engaged by contracting parties to help them collaboratively negotiate the specific deal terms.
That role is especially important when considering that business deals, especially large and complex ones, can be fraught with difficulties.
One study found at least 40 percent and up to 70 percent of all joint ventures are estimated to fail.[1] Key reasons are miscommunication and misunderstandings between the parties, which lead to mistrust and cause the negotiations to reach an impasse. The use of deal facilitators is intended to overcome these obstacles.
Using a deal facilitator can help contracting parties to create fair and balanced agreements that work for both parties, in turn, reducing contractual issues.
When contracting parties use a deal facilitator, the neutral has no incentive to obtain any specific terms of benefit to a particular party. For this reason, the deal facilitator can engage in “reality testing” of proposals and positions. For example, a deal facilitator can help a party who is opportunistically seeking terms that may generate distrust or resentment to see the benefit of adopting more even-handed terms that promote business harmony and the long-term health of the relationship.
Vancouver Island Health Authority (Island Health) and South Island Hospitalists Inc. (SIHI) turned to a neutral deal facilitator when their contract negotiations reached an impasse. Negotiations had grown so tense team members described negotiations as broken, bullying and even toxic. The deal facilitator led key stakeholders from both organizations through a three-day “alignment” workshop and a series of workshops to help the parties repair their damaged relationship and ultimately work through a win-win contract.
The results? A total trust turnaround with team members used words like collaborative, transparent and trusting to describe the relationship post contract signing.
Realistic Risk Allocation
Risks are inherent in virtually all commercial activities. Realistic risk allocation is an integral part of risk management that starts at the planning phase in any business relationship and includes the process of fairly allocating risks among the parties.
When businesses identify, understand, anticipate, assess, analyze, and learn to manage risks, they can create a significant source of value for the contracting parties through risk reduction. The goal is to consciously not shift risk to the “weaker” party to “win” the negotiation, but rather to intentionally identify and analyze potential risks in a relationship and assign each risk to the party that is most capable of managing, controlling, or insuring against that risk.
Each time a risk is appropriately allocated, a source of potential conflict diminishes.
Realistic risk allocation helps prevent problems by assigning each potential risk of the business relationship to the party best able to manage, control, or insure against the particular risk.
That process involves a four-step joint risk assessment:
Step 1: Identify Risks
Step 2: Analyze, Prioritize, and Estimate the Cost of Risks
Step 3: Fairly Allocate Risk
Step 4: Joint Planning and Mitigation
The result of following these steps is cost avoidance and/or real cost reductions associated with reduced risk.
The Bottom Line? It is Your Bottom Line.
Making the shift to dispute prevention does not just make intuitive sense; there is a bottom-line business case for adopting upstream dispute prevention mechanisms.
Simply put, it brings value to all parties involved.
Kate Vitasekis an international authority for her award-winning research and Vested® business model for highly collaborative relationships. Vitasek, a Faculty member at the University of Tennessee, received the Thinkers50 Breakthrough Idea Award in 2025 and was lauded by World Trade Magazine as one of the “Fabulous 50+1” most influential people impacting global commerce. She has written nine books.
Ellen Walmanserved as a law professor for 27 years and has published more than 25 articles and is a co-author of the book Preventing the Dispute Before It Begins: Proven Mechanisms for Fostering Better Business Relationships. Most recently she served as the Vice President of Advocacy and Educational Outreach at the International Institute for Conflict Prevention and Resolution (CPR), offering thought leadership in the realm of mediation and dispute prevention.
Note
[1] Patricia E. Farrell & Dan Bova, The 7 Deadly Sins of Joint Ventures, Entrepreneur (Sep. 2, 2014), https://www.entrepreneur.com/business-news/the-7-deadly-sins-of-joint-ventures/236987.
Buying a business can look attractive on paper long before it makes sense in practice.
Revenue may be growing, the market may be expanding and the asking price may appear reasonable. Yet none of those factors, on their own, answer the more important question: is this actually a business worth owning?
For him, the answer depends on more than valuation. Having spent much of his career building across financial services and increasingly exploring company acquisitions as another way to deploy capital and operating experience, Freihofer has developed a clear distinction between a good business and a good acquisition.
The buyer has to understand what they are really purchasing. That means looking beyond the headline numbers and asking what creates the value in the first place. Is the company dependent on one founder? Are customer relationships transferable? Is the product genuinely differentiated? Are margins sustainable? Is growth being created by strong demand or by unusually aggressive spending?
Those questions matter because acquisitions often fail when the buyer mistakes current performance for durable value. A company can be profitable and still be fragile if it relies too heavily on one salesperson, one channel, one supplier or one senior executive. It may have attractive revenue but weak systems, or it may be growing quickly while customer retention is deteriorating underneath the surface.
For Freihofer, understanding those dependencies is part of determining what the business is actually worth.
Price matters, but strategic fit matters just as much. An acquisition may be financially attractive and still make little sense for the buyer if there is no clear strategic reason for owning the asset. Freihofer is particularly interested in businesses where ownership creates the opportunity to add something meaningful after the transaction, whether through commercial relationships, distribution, operating experience or access to new opportunities.
That creates a different filter. The question becomes not only, “Is this company valuable?” but also, “Why should this particular owner be the one to buy it?” If the buyer has no clear advantage, no strategic reason for owning the asset and no ability to improve the company after the deal, the acquisition can quickly become little more than an expensive distraction.
Timing introduces another layer because the best business at the wrong moment can still be the wrong acquisition. A buyer may have the capital but not the management capacity. The target may be attractive, but the market may be changing too quickly to justify the assumptions behind the valuation. The acquiring company may also be dealing with internal complexity that makes another transaction difficult to absorb.
That is why Freihofer sees acquisition timing as a question of readiness on both sides. The target business needs to be ready for the next stage, but the buyer also needs enough bandwidth to support what happens after ownership changes hands.
This is where many acquisition decisions become more operational than financial. The transaction itself can be completed in a relatively short period, but integration is where the real work begins. Management teams have to understand what changes and what does not. Customers need continuity. Systems may need to be integrated. Commercial priorities have to become clear.
The new owner also has to resist the temptation to change everything simply because they now have the authority to do so. For Freihofer, good ownership begins with identifying what is already working and understanding where intervention creates value and where restraint protects it.
That requires humility as much as confidence. A buyer may enter the transaction believing their experience will improve the company, but the strongest acquisition strategy still depends on listening to the people who understand the business from the inside.
Strategic fit is ultimately about alignment between the asset, the buyer and the future direction of both. A business may look attractive because of its current numbers, but Freihofer believes the stronger opportunities are those where the acquisition creates a logical extension of what the owner already knows how to do.
That can mean expanding into a complementary market, adding distribution, strengthening a product offering or acquiring capabilities that would take too long to build internally. In those situations, the acquisition becomes more than a financial investment. It becomes a strategic shortcut.
The challenge is distinguishing a shortcut from a distraction.
For him, that is what makes acquisition decisions difficult and valuable at the same time. The buyer has to judge the quality of the business, the timing of the transaction and whether ownership creates a genuine strategic advantage.
A company may be worth buying because it is profitable.
A stronger reason is that the right owner can make it more valuable than it was before.
The funding routes open to new founders in 2026, from crowdfunding and pre-sales to grants, with the trade-offs of each spelled out.
Key facts
Around 524,000 new business applications are filed every month in the US alone, and the majority start without bank financing.
Crowdfunding, pre-sales, grants, and revenue-first launches each trade a different thing for the money: time, equity, obligations, or margin.
A recurring fundraiser or subscription turns one-off support into monthly income you can actually plan around.
You can fund a new business without a bank loan by pre-selling your product, crowdfunding from supporters, applying for grants, taking on a partner, or launching small enough that early revenue pays for growth. Each route costs something other than interest, so the choice comes down to which currency you’d rather spend: equity, time, or margin.
Banks price risk, and a business with no trading history is mostly risk. That’s why loan applications from brand-new founders so often stall, and why the routes below exist.
Here’s how each one works, and who it suits.
The five loan-free funding routes
Route
You give up
Typical timeline
Suits
Pre-sales and deposits
Delivery obligation
Days to weeks
Products with a waiting audience
Crowdfunding
Time, campaign effort
Weeks to months
Stories people want to back
Grants and competitions
Paperwork, reporting
Months
Specific sectors and regions
Partner or angel money
Equity, control
Weeks to months
High-growth plans
Revenue-first launch
Speed, scope
Immediate
Services and lean online businesses
Crowdfunding: money plus proof
Crowdfunding raises money and evidence at the same time. A campaign that funds tells you people want the thing before you’ve built inventory, and a campaign that doesn’t fund is cheap market research.
The mechanics matter less than the preparation. A clear goal, a believable budget, and a story told in the first person consistently outperform polished but vague campaigns. European founders have an extra advantage here: platforms regulated in the EU can take cards, Apple Pay, Google Pay, and local methods like iDeal and Bancontact, so backers pay the way they already pay day to day.
One structural choice deserves more thought than it usually gets: one-off versus recurring. A single campaign is a spike. A recurring fundraiser, where supporters give monthly, behaves like revenue, and revenue you can forecast is worth more per euro than revenue you can’t.
Pre-sales: the fastest honest money
If you can describe the product precisely, you can sell it before it exists. Pre-orders, founding-customer discounts, and paid pilots all move money forward in time, and the customer’s card is a stronger signal than any survey answer.
The discipline is in the promise. Take deposits against a delivery date you control, refund fast if the date slips beyond reason, and treat the pre-sale ledger as a liability until you’ve shipped. Founders get into trouble by spending pre-sale money as if it were profit.
Grants, competitions, and quiet public money
Grants are slow and bureaucratic, and they’re also the only money on this list you never repay in any currency. Regional development funds, sector-specific innovation grants, and startup competitions all exist across the EU and beyond, and the application skills compound: your second grant application takes half the time of your first.
Treat grants as a parallel track rather than a plan. Apply while you build, and let any award be an acceleration rather than a dependency.
The revenue-first launch
The route that’s grown most in the last decade is skipping funding entirely: start with a service or a lean online offer, land paying customers in the first month, and let revenue set the growth rate.
This is where the admin basics stop being boring. Registering the business, getting paid cleanly, and keeping records from day one decide how fundable you look later, since every future funder starts by reading your numbers. For example, you canstart a business on Whop, register your LLC, take payments, and run daily operations on one platform.
Two practical caveats for European readers, stated plainly: the LLC formation that platform offers is a US entity, which has home-country tax implications worth checking before you file, and its fees are published in USD.
Whichever funding route you pick, open a separate account for the business before the first euro arrives. Mixed money is the single most common mess new founders spend their second year untangling.
Funding a business FAQs
What is the easiest way to fund a small business?
Usually revenue itself: launching a scoped-down version that customers pay for in month one. It requires no pitch, no campaign, and no repayment. Where upfront costs make that impossible, pre-sales and deposits from early customers are the next fastest route, because the buyers already exist.
Is crowdfunding a realistic way to start a business?
Yes, within limits. It works best when the business has a story people connect with and a concrete goal, and EU-regulated platforms handle cards, wallets, and local payment methods for backers. Expect the campaign itself to be real work, comparable to a product launch, and budget weeks for preparation.
How much money do I actually need to start?
Less than most plans assume. Service businesses and online offers regularly start below a few hundred euros, spent on registration, a basic web presence, and payment tools. Manufacturing and inventory businesses are the exception, which is exactly where pre-sales and crowdfunding earn their place.
What is Whop?
Whop is a business platform for taking payments and sending payouts. New businesses use it to take card and wallet payments through checkout links, bill subscriptions, and register a US LLC for $400 in the first year including the EIN and registered agent. Domestic card pricing is 2.7% plus $0.30 per transaction, published in USD.
Do grants have to be paid back?
No. A grant is non-repayable, which makes it the cheapest money available, and also the slowest. Reporting obligations are the real cost: most grant programs require documented spending and progress updates. Competitions work similarly, trading a pitch and public exposure for unencumbered prize money.
Antom’s role is to provide a unified merchant payment and digitalization platform under Ant International. The platform combines acceptance, orchestration, risk management, card optimization, recurring-payment tools, reporting, plugins, and growth services for businesses operating across markets.
That role is broader than moving a payment request. It involves making local methods accessible, coordinating providers, applying controls, returning consistent payment events, and helping merchant teams operate the lifecycle from checkout through reconciliation.
Where Antom sits in merchant operations
The answer to what is antom starts at the merchant layer. Antom is not presented as a consumer payment method. It gives businesses infrastructure and tools to connect customers, payment options, gateways, acquirers, risk services, and back-office processes across multiple markets.
For teams asking what is antom, the useful distinction is between access and management. Antom offers access to payment methods and also provides orchestration, smart routing, fraud controls, recurring billing, revenue recovery, reporting, and operational support around those connections.
The jobs a global merchant platform must perform
The what is antom question can be tested against five merchant jobs. Each job belongs to the same payment lifecycle, but each has different owners and failure modes. Product teams focus on checkout, engineers on integration, risk teams on fraud, and finance on settlement accuracy.
Connect global and local methods
Antom’s current site lists more than 300 payment methods across over 200 payment markets. The catalog includes cards, digital wallets, online banking, bank transfers, Buy Now, Pay Later, over-the-counter payments, and national gateways, with availability determined by market and product.
Localize the checkout
A global checkout should not expose every method to every shopper. It should present eligible, familiar options for the buyer’s region, currency, device, and order. Antom supports hosted, embedded, SDK, API-only, mobile, app, TV, and selected commerce-plugin routes.
Route the transaction
Antom Payment Orchestration connects more than 100 acquirers and over 300 payment methods, according to the company’s FAQ. Smart routing can evaluate issuer health, historical BIN performance, country, amount, and merchant rules, while custom strategies preserve merchant control.
Protect legitimate revenue
Antom Shield provides AI-based fraud management, and card flows can use 3D Secure 2 where required. Card Revenue Booster addresses avoidable declines through routing, messaging, authentication intelligence, retries, and credential lifecycle tools. Protection and conversion require separate, balanced measurements.
Close the operational loop
After authorization, merchants still manage capture, notifications, voids, refunds, disputes, settlement, fees, and reconciliation. A unified platform can reduce provider fragmentation, but it does not replace the merchant’s ledger, financial controls, incident ownership, or market-specific compliance work.
How scale changes the design problem
Another way to answer what is antom is to examine the scale Antom publishes. Broad figures indicate the network that may be available through the platform. They do not guarantee that every entity, product, method, currency, or feature is approved for every merchant.
Published measure
Current Antom figure
Design implication
Payment markets
200+
Build a country-level launch map
Payment methods
300+
Prioritize methods by customer use
Currencies
140+
Separate presentment from settlement
Global offices
30+
Confirm local support coverage
Global licenses
100+
Verify relevant regulated entities
At scale, a merchant needs consistent APIs, identifiers, status models, monitoring, reports, and incident procedures. Local variation still matters. The design goal is a stable operating core with explicit exceptions, not a false assumption that payments behave the same in every country.
Merchant use cases across industries
The what is antom question also depends on business model. Antom names e-commerce, digital entertainment, travel and airlines, food and beverage, retail, delivery, ride-hailing, and logistics among the sectors it serves. Each industry stresses a different part of the platform.
Airlines and travel
Travel combines high-value orders, customers from many countries, rapid demand changes, refunds, and operational disruption. Antom positions local payment options, foreign exchange, loyalty, and marketing capabilities together. Merchants should still validate route coverage, refund timing, and disruption workflows.
E-commerce and marketplaces
Online stores need localized checkout and reliable order status. Marketplaces add seller onboarding, split commissions, multi-party settlement, vendor payouts, and platform reporting. Antom describes tools for these workflows, while the merchant remains responsible for confirming legal, tax, and accounting requirements.
Digital entertainment
Gaming, streaming, and content services often need low-friction digital checkout, subscriptions, tokenized payments, real-time analytics, and failure recovery. Antom separates scheduled subscriptions from variable merchant-initiated debits, which helps product teams match payment authorization to the actual billing model.
What merchants should validate before integration
A merchant evaluating what is antom should turn the platform description into a controlled requirements review. The key questions cover entity support, payment methods, currencies, channels, recurring models, provider routes, authentication, fraud controls, settlement, refunds, disputes, reports, and service operations.
Validate product and commercial fit
Confirm which Antom entity contracts with the merchant, where transactions are processed, which methods and currencies are available, how funds settle, and which fees or reserves apply. Review service commitments, support coverage, data access, and responsibility for disputes and compliance.
Validate the technical lifecycle
Test sandbox and pilot flows for success, failure, timeout, duplicate request, authentication, capture, cancellation, refund, dispute, notification, settlement, and reconciliation. Confirm idempotency, signature verification, error handling, monitoring, audit logs, and the recovery plan for provider or network incidents.
Use a three-part decision sequence to keep scope controlled, ownership visible, and evidence comparable across business teams. Each gate should have a named approver and a measurable documented exit condition:
Map customer payment behavior and operational requirements for the first launch market.
Select only the products and integration path needed to support that complete journey.
Measure authorization, fraud, abandonment, latency, settlement accuracy, reconciliation effort, and support outcomes during a pilot.
When the evidence is positive, what is antom becomes an operational answer: a common merchant payment layer that can reduce fragmented connections while preserving local checkout choices. Expansion should reuse proven controls and reporting, then add market-specific methods only after their requirements are confirmed.
The role in one sentence
Antom’s role is to connect local payment acceptance with the global infrastructure and controls merchants need to operate it. The platform spans checkout, provider access, routing, risk, billing models, optimization, payment events, and reporting rather than treating authorization as the entire job.
Its scale makes Antom relevant to international merchants, but implementation quality determines the outcome. A clear market map, narrow product scope, complete lifecycle testing, and measured pilot give businesses a defensible basis for deciding where the platform fits.
Most shoppers who receive a rebate for something they bought online never ask where the money came from.
It arrives, it feels like a small win, and the transaction is forgotten.
But the mechanism behind that rebate is a well-established piece of retail marketing that predates the internet’s current generation of cashback apps and memberships by decades.
Understanding it explains why a growing number of companies, including the membership service Cashback Now, are able to offer it at all.
The Budget Line Retailers Already Have
Every retailer that sells online sets aside money to acquire customers. That budget pays for search ads, social media promotions, influencer partnerships and, increasingly, a category called affiliate marketing.
In an affiliate arrangement, a retailer agrees to pay a commission, typically a percentage of the sale, to whatever channel sent them a paying customer.
That channel might be a blog that reviews products, a coupon website, or a cashback platform.
This is not a new or unusual idea. Affiliate marketing has existed since the mid 1990s, when Amazon launched one of the first large-scale affiliate programs to let outside websites earn a commission for referring buyers.
It has since grown into a mainstream part of digital retail. Industry research firm Grand View
Research valued the global affiliate marketing platform market at roughly 22.6 billion dollars in 2025, with continued growth projected through the end of the decade.
Retailers keep funding it because it is performance-based. They only pay a commission when a sale actually happens, which makes it one of the more efficient forms of marketing spend available to them.
How Cashback Now Fits Into an Established Model
Cashback services take that same commission and redirect some or all of it to the shopper who made the purchase, rather than keeping it as pure marketing spend.
Cashback Now operates as one current version of this idea. When a member shops through the platform or uploads a receipt from a participating retailer, the retailer pays its usual affiliate commission, and Cashback Now passes that commission back to the member rather than keeping it as revenue for referring the sale.
This is the same basic mechanism used by long running cashback sites that many shoppers already recognize, and by the cashback features built into some credit cards and shopping browser extensions.
The novelty in Cashback Now’s approach is how the company chooses to fund its own operations separately.
By charging a membership fee, it can pass along a full share of the commission rather than keeping a cut of it.
From Ad-Funded Sites to Membership-Funded Ones
Traditional cashback websites generally work on an ad-supported model. They keep a portion of the retailer’s commission as their own revenue, and pass along the remainder, often a percentage point or two, to the shopper.
That arrangement has worked for years and still accounts for most of the cashback market.
A membership model flips the funding source. Instead of relying on keeping part of each commission, the company charges members a flat recurring fee for access to the platform, and that fee is what covers operating costs, customer support and technology.
Because the commission itself is no longer needed to fund the business, the company can pass along a larger share of it, in some cases most of the commission, directly to the member as cashback.
This is a familiar pattern outside of cashback specifically. Membership retailers such as warehouse clubs and some subscription shopping services use a similar structure: a flat fee funds the business.
This allows the retailer to offer thinner margins or fuller rebates on the products and services members actually buy.
Cashback Now’s model applies that same logic to retail commissions.
Why the Math Works for Cashback Now Members
Whether this arrangement makes sense for an individual shopper comes down to simple arithmetic that any member can do for themselves.
If the cashback earned across a month of qualifying purchases exceeds the membership fee, the service has paid for itself and then some.
If a member rarely shops at participating retailers, the fee may not be worth carrying.
Because the money funding a member’s cashback is coming from a retailer’s existing marketing budget rather than from thin air, there is a clear and explainable answer to where the value comes from.
Retailers are willing to share part of what they would have spent on customer acquisition anyway, in exchange for a completed sale.
For shoppers evaluating any cashback platform, membership-based or otherwise, that is the detail worth understanding.
The rewards are not a marketing gimmick invented from nothing.
They are a redirection of a marketing budget that already exists across nearly every major retailer’s operations, routed through a company like Cashback Now instead of an advertising platform.
This paper offers a critical analysis of US capitalism, from the settler-colonial foundations of 1776 to the contemporary crisis of neoliberalism. Dr Kalim Siddiqui examines how dispossession, slavery, financialisation, inequality, stagnation, militarisation and imperialism have shaped US power. It argues that declining economic dominance has intensified reliance on coercive power, contributing to the New Cold War and attempted recolonisation of the Global South.
I. Introduction
The founding of the United States (US) is conventionally commemorated as the birth of a nation devoted to liberty, democracy, equality before the law, and self-government. Yet these democratic values obscure the material foundations upon which the republic was constructed. From a critical and decolonial perspective, 1776 cannot be understood simply as the liberation of a nation from colonial rule. Rather, the American Revolution transferred political authority from the British imperial power to a settler-colonial ruling class whose wealth and power were already predicated upon the dispossession of Indigenous peoples, the expropriation of land, and racial slavery.
This fundamental contradiction—the proclamation of American independence in the universal language of liberty alongside the preservation of a social order rooted in racial bondage, Indigenous dispossession, and class domination—shaped the republic from its inception. The new political institutions did not merely fail to abolish these structures; they actively incorporated and protected them. Property, political power, control over resources, policymaking, and citizenship were distributed through racialised and class-based hierarchies, while territorial expansion depended upon the continued seizure of Indigenous lands and the reproduction of enslaved labour. The celebrated ideals of freedom and equality thus coexisted with – and were materially sustained by – systems of unfreedom and expropriation (Burns, 2026).
Consequently, the US history cannot be adequately understood through a narrative of democratic progress alone. It must also be examined as a history of settler colonialism, racial capitalism, and organised state violence (Horne, 2018).
The main architects of the early republic—including George Washington, Thomas Jefferson, Benjamin Franklin, and Alexander Hamilton—exemplify these contradictions. Washington and Jefferson were major slaveholders whose political and economic positions were inseparable from an order built upon enslaved African labour. Franklin and Hamilton occupied more ambivalent positions regarding slavery and abolition, yet neither made abolition a foundational condition of the new republic.
The political settlement that emerged from the independence instead accommodated slaveholding elites, embedding slavery deeply within the nation’s constitutional, legal, and economic framework. The Constitution compromised over slavery, the protection of slaveholders’ political power, and the subsequent territorial expansion of the slave system demonstrate that racial slavery was not an accidental deviation from the American project but one of its central organising institutions.
US imperial expansion, therefore, cannot be treated as a departure from the nation’s earlier history of settler colonialism. Rather, overseas empire extended and transformed practices of territorial conquest, racial hierarchy, economic extraction, and military domination continued on the North American continent (Horne, 2018).
The history of the US is consequently marked by a persistent contradiction between its proclaimed democratic ideals and the structures of power through which those ideals have been selectively applied. Liberty was defended alongside slavery; democracy expanded alongside Indigenous dispossession; and national self-determination was celebrated domestically while the sovereignty of other nations was repeatedly constrained through military intervention.
Therefore, the 250th anniversary of the US presents an opportunity to reconsider whose history, is being commemorated, whose land was taken, whose labour was exploited, and whose sovereignty was denied. Such questions do not negate the historical significance of the Declaration of Independence, the Constitution, or the democratic aspirations associated with the US political tradition (Burns, 2026).
The central question is therefore not simply what the US has achieved, but what forms of domination have made its power possible—and how deeply those structures continue to shape the country’s political economy, military institutions, racial order, the rights and political status of racial minorities, and its relations with the wider world.
During the first two centuries of European colonisation in the Americas, some of the most profound demographic and social devastation occurred in South America. There, Spanish conquest systematically dismantled the Aztec and Inca empires, alongside numerous smaller Indigenous polities. Indigenous populations were subjected to enslavement and various forms of coerced labour, while the combined effects of warfare, territorial dispossession, forced displacement, exploitation, and introduced pathogens caused catastrophic population decline, reducing Indigenous populations by millions
The central question is therefore not simply what the US has achieved, but what forms of domination have made its power possible
The founding of the United States (US) is conventionally commemorated as the birth of a nation devoted to liberty, democracy, equality before the law, and self-government. Yet these democratic values obscure the material foundations upon which the republic was constructed. From a critical and decolonial perspective, 1776 cannot be understood simply as the liberation of a nation from colonial rule. Rather, the American Revolution transferred political authority from the British imperial power to a settler-colonial ruling class whose wealth and power were already predicated upon the dispossession of Indigenous peoples, the expropriation of land, and racial slavery.
This fundamental contradiction—the proclamation of American independence in the universal language of liberty alongside the preservation of a social order rooted in racial bondage, Indigenous dispossession, and class domination—shaped the republic from its inception. The new political institutions did not merely fail to abolish these structures; they actively incorporated and protected them. Property, political power, control over resources, policymaking, and citizenship were distributed through racialised and class-based hierarchies, while territorial expansion depended upon the continued seizure of Indigenous lands and the reproduction of enslaved labour. The celebrated ideals of freedom and equality thus coexisted with – and were materially sustained by – systems of unfreedom and expropriation (Burns, 2026).
Consequently, the US history cannot be adequately understood through a narrative of democratic progress alone. It must also be examined as a history of settler colonialism, racial capitalism, and organised state violence (Horne, 2018).
The main architects of the early republic—including George Washington, Thomas Jefferson, Benjamin Franklin, and Alexander Hamilton—exemplify these contradictions. Washington and Jefferson were major slaveholders whose political and economic positions were inseparable from an order built upon enslaved African labour. Franklin and Hamilton occupied more ambivalent positions regarding slavery and abolition, yet neither made abolition a foundational condition of the new republic.
The political settlement that emerged from the independence instead accommodated slaveholding elites, embedding slavery deeply within the nation’s constitutional, legal, and economic framework. The Constitution compromised over slavery, the protection of slaveholders’ political power, and the subsequent territorial expansion of the slave system demonstrate that racial slavery was not an accidental deviation from the American project but one of its central organising institutions.
US imperial expansion, therefore, cannot be treated as a departure from the nation’s earlier history of settler colonialism. Rather, overseas empire extended and transformed practices of territorial conquest, racial hierarchy, economic extraction, and military domination continued on the North American continent (Horne, 2018).
The history of the US is consequently marked by a persistent contradiction between its proclaimed democratic ideals and the structures of power through which those ideals have been selectively applied. Liberty was defended alongside slavery; democracy expanded alongside Indigenous dispossession; and national self-determination was celebrated domestically while the sovereignty of other nations was repeatedly constrained through military intervention.
Therefore, the 250th anniversary of the US presents an opportunity to reconsider whose history, is being commemorated, whose land was taken, whose labour was exploited, and whose sovereignty was denied. Such questions do not negate the historical significance of the Declaration of Independence, the Constitution, or the democratic aspirations associated with the US political tradition (Burns, 2026).
The central question is therefore not simply what the US has achieved, but what forms of domination have made its power possible—and how deeply those structures continue to shape the country’s political economy, military institutions, racial order, the rights and political status of racial minorities, and its relations with the wider world.
During the first two centuries of European colonisation in the Americas, some of the most profound demographic and social devastation occurred in South America. There, Spanish conquest systematically dismantled the Aztec and Inca empires, alongside numerous smaller Indigenous polities. Indigenous populations were subjected to enslavement and various forms of coerced labour, while the combined effects of warfare, territorial dispossession, forced displacement, exploitation, and introduced pathogens caused catastrophic population decline, reducing Indigenous populations by millions.
II. Territorial Expansion and Overseas Interventions
Territorial expansion constituted an ongoing process of settler colonial conquest. The acquisition of Indigenous lands was pursued through warfare, coerced treaties, forced removal, legal dispossession, and the systematic destruction or transformation of Indigenous political and economic systems. Expansion was therefore not the peaceful growth of a democratic nation across an empty continent but a violent process of territorial appropriation through which the settler state extended its jurisdiction while displacing the peoples who had long inhabited and governed those lands.
The consolidation of US capitalism amplified these expansionary tendencies. As US industrial and financial might grew across the nineteenth century, the country increasingly projected its power beyond its continental frontiers—yet this was merely an intensification of a longer pattern. From the moment of independence in 1776, the US pursued a deliberate and sustained policy of territorial expansion, often through military force, diplomatic coercion, and outright annexation of neighbouring lands (see Figure 1 and Figure 2). Expansion and hegemony were not incidental but constitutive features of the US project from its inception.
Moreover, the relationship between domestic settler expansion and overseas imperialism was not incidental; both were expressions of a political economy increasingly dependent on territorial acquisition, market access, resource control, and the subordination of populations deemed obstacles to US hegemony (Foster, 2003).
Figure 1: The Original Thirteen Colonies at US Independence, July 4, 1776.
Image sourced from a publicly available website and used for non-commercial, educational, and research purposes. Source: https://www.reddit.com/r/MapPorn/comments/1i22aky/the_13_united_states_of_america_on_july_4th_1776/
Figure 2: The US Territorial Expansion During the 19th Century.
This transformation was particularly visible in Latin America and the Caribbean. The Monroe Doctrine, articulated in 1823, warned European powers against further intervention in the Western Hemisphere. As Latin American societies emerged from Spanish and Portuguese colonial rule, the US increasingly positioned itself as a principal arbiter of political order in the hemisphere (Kennedy, 2017).
The result was a recurring pattern of intervention, coercion, occupation, and regime change across Latin America and the Caribbean. US military power was repeatedly deployed to suppress revolutionary movements, overthrow governments, discipline political leaders, secure favourable economic conditions, and prevent alternative forms of political and economic development. The Monroe Doctrine therefore functioned not merely as an anti-European principle but also as an instrument through which the US asserted and consolidated its political and economic dominance in the hemisphere (Huberman and Amaral, 2025).
The establishment of the US marked a decisive rupture in Indigenous–colonial relations. Independence removed the British colonial administration and, in practice, undermined existing treaty obligations. The Revolutionary War brought particularly devastating consequences. George Washington authorised the destruction of Iroquois settlements in present-day upstate New York, a scorched-earth campaign that inflicted catastrophic losses.
US independence also had profound consequences for Africans, whose enslavement had been integral to the English colonies since the early seventeenth century. Slavery was not peripheral to the colonial economy but central to the emerging system of capitalist accumulation (Marx, 1976). The plantation, consolidated across the Americas from the sixteenth century onward, depended on the violent displacement and forced transportation of millions of Africans. Enslaved Africans produced sugar, cotton, and other export commodities under conditions of systematic violence and racial domination, generating immense wealth for colonial powers and merchant capital.
In the decades before the Civil War, slavery and plantation agriculture expanded rapidly in the US. The slaveholding South became deeply integrated into global markets through cotton production, making enslaved labour a central source of capital accumulation. The wealth of the plantation elite was therefore inseparable from the coercive appropriation of labour and the expropriation of land (Bhambra, 2021). (Bhambra, 2021).
From its inception, the US was therefore shaped by territorial expansion grounded in settler colonialism, Indigenous dispossession, and racial slavery. These were not merely contradictions within an otherwise liberal political order; they were among the material conditions through which that order was constructed. The development of US capitalism cannot be understood apart from the intertwined processes of colonial expropriation, racialised labour exploitation, and the concentration of land and wealth in the hands of a propertied class. The ideals of liberty and individual property consequently existed alongside, and were materially sustained by, systems of coercion and exclusion (Horne, 2018).
This tension between liberal ideals and colonial realities is particularly evident in the political philosophy of John Locke, whose theory of property profoundly influenced the intellectual foundations of the emerging US political order. Locke’s account of private property provided a framework through which the accumulation of land and wealth could be represented as the product of individual labour, rational improvement, and natural right. Yet these ideas were applied to a colonial context marked by the systematic dispossession of Indigenous peoples and the racialised exploitation of African labour.
Locke’s conception of property was particularly compatible with European settlers’ aspirations for access to land and greater economic autonomy from the hierarchical structures of feudal Europe. By grounding property rights in labour, Locke transformed the appropriation and “improvement” of land into a moral and political claim to ownership. This formulation helped legitimise the expansion of private property and capitalist social relations. Yet the universal language of liberty and property obscured the unequal material relations through which property was accumulated. The freedom of the propertied individual was thus historically intertwined with the unfreedom of those whose land and labour were appropriated to produce that property (Marx, 1976).
Thomas Paine’s 1776 Common Sense supported American independence by repudiating British monarchy and promoting republican governance founded on the consent of the governed. He condemned hereditary succession as unnatural and incompatible with human equality, dismissed British transatlantic governance as impracticable, and characterised colonial protection as an expression of mercantile self-interest rather than genuine welfare. He later expanded these ideas in The Rights of Man (1791). Yet Paine’s egalitarianism remained racially circumscribed, extending primarily to white Europeans while excluding Indigenous peoples and enslaved Africans.
From this perspective, the emergence of the US was not simply a triumph of liberalism over monarchy but also a process of class formation and capitalist development rooted in colonial dispossession, racial slavery, and the commodification of land and labour. The language of property, individual freedom, and popular sovereignty must therefore be situated within the material relations of power that enabled their universal claims while systematically excluding Indigenous peoples and enslaved Africans from their realisation.
The universalism of liberalism was therefore deeply circumscribed by racial and colonial hierarchies. Freedom and equality coexisted with conquest, dispossession, and slavery, while the language of universal rights could itself legitimise relations of domination.
This contradiction persisted as the US consolidated its position as a capitalist and imperial power. During the late nineteenth and twentieth centuries, US expansion produced wars in the Philippines and across the Pacific, followed by military interventions in Korea and Vietnam, often involving extreme violence against civilian populations. This was not simply a matter of hypocrisy but reflected a deeper ideological structure in which the universal language of liberty coexisted with racial hierarchy, imperial interests, and the material imperatives of geopolitical power (Siddiqui, 2025a).
III. The Civil Rights Movement of the 1950s – 1960s
The Civil Rights Movement of the 1950s and 1960s struck at the very racial foundations of US democracy. Through sustained mass mobilisation, African Americans and their allies took on institutional systems that had systematically excluded Black people from full citizenship and political participation. The movement achieved historic legal and constitutional breakthroughs—most notably, the overthrow of entrenched segregation and discriminatory practices. However, these victories were met with determined resistance from powerful quarters, as elite factions, unwilling to accept diminishing control, fiercely opposed any genuine power-sharing with formerly enslaved populations.
The terror of McCarthyism in the 1950s, the surveillance and repression directed against student, Black, anti-war, and radical movements during the 1960s, and the continuation of coercive state practices in subsequent decades reveal a persistent tension between the US self-representation as an embodiment of freedom and the realities of political power. Dissent has repeatedly been treated as a threat when it challenges entrenched class, racial, imperial, or geopolitical interests.
The history of the US thus demands a distinction between the democratic ideals espoused by the state and the social relations through which those ideals have been selectively realised. Gerald Horne’s (2018) indispensable scholarship reframes the events of 1775–76 not as a revolution but as a counter-revolution. In The Counter-Revolution of 1776: Slave Resistance and the Origins of the United States of America, Horne contends that independence was fundamentally a conservative project, through which the colonial elite sought to preserve slavery and entrench their broader social power.
The military institutions of the US were likewise shaped by the defence of slavery and the violent dispossession of Indigenous peoples, linking the formation of the US state to both racial domination and territorial expansion. This nexus of militarism, slavery, and colonial conquest would recur as a persistent feature of US power—from the Civil War and westward expansion to Vietnam, Afghanistan, Iraq, Libya, Syria, and contemporary confrontations with Iran (Siddiqui, 2026c)
IV. The Rise of Neoliberal Globalisation (1980s–Present)
As the post-war boom waned in the 1970s, US policy pivoted to neoliberalism—empowering financial capital and free markets to resolve the crisis, while rolling back the labour protections secured by post-war working-class struggles. From the 1980s, this corporate-backed globalisation dismantled capital controls, deregulated finance, and liberalised trade. Though it spurred unprecedented capital flows and trade expansion, it simultaneously drove deindustrialisation and financialisation at home, exacerbating working-class insecurity.
Rather than tackling the structural roots of wage stagnation, rising inequality, and unemployment, elites deflected blame onto racialised minorities and immigrants. By portraying state support for these groups as the source of economic distress, they obscured the true legacy of neoliberal restructuring: the relentless concentration of wealth and power (Siddiqui, 2018).
What emerged was a distinctive “privatised Keynesianism”—demand management migrated from the public sphere to financial markets and indebted households. From 1987 onward, Greenspan’s post-crash interventions ensured that effective demand in advanced economies was sustained less by public redistribution or stable wages than by inflating asset prices, debt-financed consumption, and central-bank crisis management. Credit expansion and property appreciation thus compensated for wage stagnation and welfare retrenchment (Hudson, 2019).
Under neoliberalism, the saver depends on volatile asset prices, while the consumer relies on credit rather than rising wages or an expanding welfare state. This generated a fundamental contradiction in the US economy: stagnant wages constrained workers’ purchasing power, while financial expansion and borrowing merely deferred the deficiency—transforming future income into present consumption and masking deep structural fragility.
As property asset prices continue to rise, households acquire greater capacity to borrow against the increasing value of their assets. This creates the appearance of a self-reinforcing process: rising asset prices increase collateral values, which expand borrowing capacity; increased borrowing, in turn, supports consumption and investment, thereby sustaining demand and potentially reinforcing asset-price appreciation. Yet neither assumption can be sustained indefinitely. Rising asset prices generate expectations of further appreciation, encouraging households and financial institutions to extend and accept increasingly large amounts of credit.
It is precisely this dynamic that Hyman Minsky sought to capture through his financial instability hypothesis. For Minsky, prolonged periods of financial stability can generate the conditions for instability by encouraging economic agents to move from relatively secure hedge positions towards speculative and ultimately Ponzi positions. As confidence increases, lenders and borrowers accept increasingly fragile financial structures, making the system progressively dependent on refinancing and rising asset prices. Stability can therefore become destabilising.
This logic became increasingly visible in the changing distribution of financial fragility across the US economy. By the early 2000s, corporations were, in aggregate, in comparatively strong financial positions and had become net creditors, while households increasingly occupied the more fragile position. The centre of gravity of Minsky’s progression from hedge to speculative and Ponzi finance had therefore shifted from the corporate sector towards households. Credit was increasingly used not simply to finance productive investment but to sustain consumption in an environment where household incomes were failing to keep pace with the demands of the prevailing accumulation regime (Hudson, 2019).
The housing boom intensified this process by temporarily substituting rising collateral values and expanding household debt for wage growth and public provision as sources of demand. Wage stagnation could be offset through credit, while declining social provision could be partially compensated through private borrowing. Yet these mechanisms did not resolve the underlying contradictions of accumulation; they displaced them onto the balance sheets of households and financial institutions. The resulting expansion of debt allowed the system to reproduce itself for a time, while simultaneously increasing its financial fragility.
The expansion of subprime mortgage lending in the US between 2003 and 2006 was a particularly clear expression of this dynamic. These loans increasingly depended on the expectation that rising house prices would enable borrowers to refinance, extract equity, or sell their properties rather than on their capacity to service debt from existing income. Mortgage credit thus became a mechanism for sustaining consumption and aggregate demand despite weak wage growth.
Uncontrolled finance produced three crises in ten years—the Asian financial crisis of 1997–1998, the dot-com crash of 2000–2001, and the subprime collapse of 2007–2008—and none were accidental. Rather, they represented recurring spasms of a single mechanism of self-annihilation, with each cycle inflating a bigger bubble and unleashing a deeper rupture than the one before (Siddiqui, 2024).
By mid-2007, the financial edifice was cracking: BNP Paribas suspended three funds, Bear Stearns bailed out two of its own, German Landesbanken admitted vast exposure to US toxic assets, and interbank lending ground to a halt. Northern Rock’s collapse in September triggered Britain’s first run on a bank in over a century. By September 2008, Lehman Brothers’ failure laid bare the extreme fragility of the entire US financial system.
Some right-wing commentators have since proposed military spending as an antidote to economic stagnation. This misreads the crisis. Defence expenditure may boost demand temporarily, but when debt-financed, it deepens public indebtedness and shifts the cost onto working families via future taxes and service cuts—while fuelling vast profits to defence contractors (Hudson, 2019).
Kalecki (1943) argued that military spending is capital’s preferred form of public intervention: it boosts demand without encroaching on private consumer markets or empowering labour. It supports employment and profitability while preserving the existing balance of economic power—a mode of demand management that, for Kalecki, leaves both production composition and workplace control undisturbed. Kalecki would thus ask not whether public spending can stimulate demand, but to what end and for whom. Rearmament delivers stimulus and profit without unsettling production relations.
The current rearmament drive, with the US at its centre, is not simply an economic response to crisis. It is a political choice about how to mobilise public resources, which productive sectors to prioritise, and whose interest’s policy should serve (Siddiqui, 2024).
The Soviet Union’s 1991 collapse left the US momentarily unrivalled. But globalisation—deepening trade, investment, and production networks—gradually eroded that supremacy. China’s 2001 WTO accession proved pivotal, supercharging its export growth and accelerating the shift towards multipolarity (Siddiqui, 2026a).
China has become the US’s foremost systemic rival since the Cold War’s end. Rising from a manufacturing base, it rapidly narrowed the technological and military gap with the US during the 2000s and 2010s. Crucially, this ascent rests on a state-led capitalist model, pitting it against the liberal market orthodoxy that underpins US hegemony.
Nor is China the only challenge. Middle power economies across the Global South—Brazil, India, Indonesia, Mexico, Türkiye, South Africa, Saudi Arabia, and others—have grown in regional and, in some cases, global influence. With expanded state capacities, rising middle classes, competitive domestic firms, and stronger militaries, these states have pursued more autonomous and assertive foreign policies, seeking to reshape the emerging international order in their own interests (Bhambra, 2021).
V. Classical Imperialism and the Rise of Monopoly Capital
Late nineteenth- and early twentieth-century imperialism was distinguished by the erosion of British hegemony and the rise of monopoly capitalism—the concentration of production in giant firms. For Lenin, this was capitalism’s “monopoly stage.” But this phase must be understood within capitalism’s deeper logic: its relentless drive to accumulate, its character as an integrated yet politically fragmented world system of competing states, and its structuring through entrenched centre-periphery inequalities that concentrate wealth and power in the advanced economies.
Imperialism did not end with the classical era, which closed with the Second World War and decolonisation. The postwar period assumed a new form, centred on US hegemony in place of Britain. The Soviet Union’s existence meanwhile opened space for independent movements in the Global South, even as the Cold War consolidated the major capitalist powers within a US-led military alliance that cemented the US dominance (Foster, 2003).
The US also used its hegemonic position to shape the postwar international economic order through institutions such as the General Agreement on Tariffs and Trade (GATT), the International Monetary Fund (IMF), and the World Bank. These institutions helped establish the rules governing international trade, finance, and development, consolidating the economic power of the advanced capitalist centre and, in particular, the US, over the wider world economy (Hudson, 2019).
In Harry Magdoff’s (1969) view, however, US hegemony did not eliminate competition among capitalist states. Hegemony was inherently historical and therefore transitory, despite claims surrounding the permanence of an “American century.” The uneven development of capitalism continued to generate shifts in economic power and, with them, the potential for renewed inter-imperialist rivalry. Such competition could be temporarily contained or obscured by the dominance of a hegemonic power, but it remained embedded within the structure of the capitalist world economy.
Militarism had deeper roots in the position of the US as the hegemonic power of the capitalist world economy. It served to keep markets and investment opportunities open to US capital, including through the use of force where necessary, while simultaneously advancing the interests of US corporations. This was particularly evident in Latin America, where US dominance faced little challenge from other major powers (Kennedy, 2017). Across the postwar periphery, US military intervention could also be legitimised as part of the global struggle against communism. Militarism and military production thus served not only geopolitical purposes but also helped sustain demand and profitability within the US economy, providing a partial counterweight to the tendency towards stagnation (Huberman and Amaral, 2025).
Magdoff’s (1969) analysis demonstrated how directly imperialism benefited capital in the core economies. For example, earnings from US foreign investments increased from roughly 10% of the after-tax profits of domestic non-financial corporations in 1950 to 22% in 1964. At the same time, the extraction of surplus from the periphery, combined with the distorted class relations produced by imperial dependency, contributed to the reproduction of underdevelopment (Magdoff, 1969).
Magdoff also anticipated two developments that would become increasingly important: the growing debt burden of the Global South and the expanding role of banks and finance capital in the world economy. The scale of the debt problem became evident in the early 1980s, when countries such as Brazil and Mexico defaulted, while the broader significance of global financialisation became increasingly apparent later in the decade (Magdoff, 1969).
Yet US hegemony also contained its own contradictions. The uneven development of capitalism encouraged other major powers to challenge the US dominance, while weaker states and non-state actors increasingly turned to asymmetric forms of resistance (Siddiqui, 2026b). The result was a system in which militarism, financial expansion, and geopolitical rivalry became increasingly interconnected, generating new forms of instability within the US-led imperial order (Siddiqui, 2023).
VI. Rising Debt and the Cost of US Borrowing
The scale of US indebtedness is historically significant. According to the IMF, US public debt is equivalent to around 125.8% of GDP, compared with 103.6% in the UK and 106.9% in China. Japan’s ratio exceeds 200%, although a much larger share of Japanese government debt is held domestically. More strikingly, by August 2026, the US national debt has surpassed $40 trillion (see Figure 3), having roughly doubled from just under $20 trillion in 2016. Since Donald Trump returned to office in January 2025, the debt has increased by approximately $3.8 trillion, contributing to an overall increase of around $11.6 trillion across his two presidential terms.
Figure 3: The US Sovereign Outstanding Debts, August 2016-August 2026 (trillion $).
Image sourced from a publicly available website and used for non-commercial, educational, and research purposes. Source: US Department of the Treasury.
Moreover, the growing burden of US debt is increasingly reflected in the cost of government borrowing. For instance, on 30 August 2026, the yield on 30-year US Treasury bonds reached 5.34%, its highest level in almost two decades. These yields matter beyond government finance because they influence borrowing costs across the economy, including mortgages, car loans, and consumer credit. The recent rise in yields has been driven partly by higher oil prices associated with the US–Iran conflict and renewed concerns about inflation. At the same time, investors are increasingly focused on the scale of US government debt and the large amounts of borrowing undertaken by technology companies to finance artificial intelligence, despite considerable uncertainty over the timing and magnitude of future returns.
The fiscal consequences are already substantial. The US government now spends approximately $1.1 trillion annually on interest payments, with debt-servicing costs rising as both the debt stock and interest rates increase. In fiscal year 2025, interest payments exceeded Pentagon spending for the first time. This growing interest burden constrains the government’s fiscal capacity and raises a broader question about the sustainability of a growth model increasingly dependent on public and private debt.
The immediate effects on households may be limited, but persistent increases in borrowing costs can gradually feed through to mortgages, consumer credit, business investment, and government spending. The central concern is therefore not simply the size of the debt itself, but the growing dependence of the US economy on continued borrowing at a time when the cost of that borrowing is rising.
VII. Financial Instability, and Rising Inequality
These tensions are increasingly visible in financial markets. Rising US Treasury yields reflect concerns about inflation, interest rates, and the sustainability of government borrowing. The dollar’s reserve-currency status has enabled the US to sustain high levels of debt, but persistent deficits, rising debt-service costs, increased defence spending and renewed inflationary pressures could weaken confidence in US financial assets and the dollar more broadly.
Capitalism overcame its postwar crisis through the “Golden Age of Capitalism”, characterised by high growth, rising wages, expanding welfare provision and sustained employment. This period transformed the relationship between state, capital and labour (Siddiqui, 2025b).
The present crisis differs in the reduced scope for state-led demand management. Under neoliberalism, expanding public expenditure must ultimately be financed through deficits or higher taxation. Taxing working households largely redistributes existing demand, while finance capital tends to resist both fiscal deficits and higher taxes on wealth and high incomes. The globalisation of finance further limits national policy autonomy by increasing the risk of capital flight and financial pressure (Siddiqui, 2024).
The result is a structural impasse. Neoliberal capitalism remains vulnerable to stagnation, partly because of extreme income and wealth concentration, yet the means of overcoming weak demand are politically constrained. This cul-de-sac contributes to economic insecurity and creates space for authoritarian and neo-fascist forces, alongside increasingly restrictive responses to dissent (Siddiqui, 2026a),
The data indicate a clear long-term rise in US income inequality. As shown in Figure 4, earned income growth has been strikingly uneven: in 2022, the top 1% of households earned over one hundred times more than the bottom quintile. This disparity is not static. Between 1971 and 2023, the national income share captured by the top 1% increased by 10 percentage points, according to the World Inequality Database. These trends point to a broader structural dynamic: under neoliberal economic policy, high-income groups have disproportionately accumulated both income and wealth, further widening the gap between the richest and poorest households. In the US, the income share gap between the top and bottom earners has widened sharply since the late 1970s, coinciding with the implementation of neoliberal economic policies (see Figure 5).
This polarisation is reinforced by the long-term decoupling of wages and productivity. As Figure 6 demonstrates, since the mid-1970s, real wage growth has consistently lagged behind productivity gains, meaning that workers have not benefited proportionally from economic growth. While productivity has continued to rise, real wages have stagnated, reflecting a structural shift in the distribution of economic gains since the neoliberal era (Siddiqui, 2025b).
Figure 4: US Average Household Income Across Income Groups, 2022.
Such developments expose the growing tension between the liberal-democratic principles claimed by the postwar capitalist order and the coercive measures used to contain dissent. The crisis is therefore not simply economic: as neoliberalism becomes less capable of resolving its social contradictions, maintaining the existing order may depend increasingly on coercion, nationalism and restrictions on political opposition.
VIII. The New Cold War and the Recolonisation of the Global South
The postwar expansion of capitalism was also accompanied by a profound ideological transformation. Having emerged from the interwar crisis, capitalism presented itself as a humane and democratic system capable of delivering employment, rising living standards and superiority over socialism. Yet this image coexisted with the suppression of alternative political and economic projects across the Global South, from the overthrow of Mossadegh, Arbenz and Allende to the assassination of Lumumba and the wars in Korea and Vietnam. The consolidation of the US-led order thus relied not only on economic power but also on political intervention and military force.
The contradiction is fundamental: the postwar capitalist order legitimised itself through democracy and prosperity while relying on coercion abroad and increasing inequality at home. The contemporary crisis of US hegemony must therefore be understood against this longer history of unresolved economic, political and geopolitical contradictions (Siddiqui, 2024).
This turn towards repression has been accompanied by an increasingly aggressive attempt, particularly by the US, to reassert control over the Global South. Trump has articulated such an agenda and pursued interventionist policies towards Venezuela and Iran, alongside threats involving Greenland and other territories. These manoeuvres also seek greater support from the major capitalist powers of Europe as the US attempts to preserve the existing imperial order in an increasingly multipolar world (Siddiqui, 2026c)
The global financial crisis of 2008 deepened the structural crisis of capitalism, particularly in the US (Bhambra, 2021). One consequence was a growing recognition in Washington that the erosion of US productive and technological dominance could not be reversed through economic competition alone. Barack Obama’s 2011 “Pivot to Asia” therefore marked an important shift towards containing China, a strategy intensified under the Trump administrations and increasingly described as a New Cold War. Having lost ground in manufacturing and productive capacity, the US has sought to deploy its remaining advantages in finance, technology and military power to constrain China’s rise (Siddiqui, 2023).
Technology has become a central arena of this confrontation. China’s rapid advances, particularly in artificial intelligence, have challenged US dominance in sectors regarded as strategically important to the next phase of capitalist accumulation. The conflict therefore extends beyond trade to a wider struggle over technological leadership, data, surveillance and global production.
The economic dimension is equally significant. In 2025, the Trump administration-imposed tariffs of up to 145 percent on Chinese imports, prompting Chinese restrictions on critical rare-earth exports and exposing US dependence on Chinese supply chains (Siddiqui, 2025c). The subsequent retreat from the most confrontational measures demonstrated the limits imposed on US power by global economic interdependence. Washington has consequently sought to contain China not only through direct competition but also by exerting pressure on countries within its wider geopolitical sphere.
The confrontation should therefore be understood as part of a broader attempt to preserve US hegemony in an increasingly multipolar world. What is emerging is not a return to nineteenth-century colonialism, but an attempt to reconstruct hierarchical relations of power under contemporary conditions—a form of imperial reassertion that can be understood as recolonisation.
Donald Trump’s economic strategy must be understood within this broader context. Rather than simply reflecting incompetence or irrationality, it can be seen as pursuing two interconnected objectives. The first is to redistribute the costs of maintaining the US-led capitalist order among other advanced capitalist countries. Trump’s demand that European countries substantially increase military expenditure reflects an attempt to make them assume a greater share of the costs of defending the existing imperial order, while potentially reducing some of the external imbalances associated with the US role as its principal military power (Siddiqui, 2025a).
The second is more directly imperialist: to secure for the US some of the economic advantages that Britain once derived from its colonial empire. Recolonisation does not imply the restoration of formal colonial rule, but rather maintaining formally sovereign states while constraining their economic policies in accordance with US interests.
Nor does it imply abandoning neoliberalism. Instead, it introduces a new asymmetry into the neoliberal order: the US, and potentially other countries of the Global North, gain greater freedom to protect domestic markets and pursue industrial policies, while the Global South remains subject to trade liberalisation, capital mobility and financial openness. The burden of adjustment is consequently shifted towards peasants, small producers, workers and agricultural labourers. Recolonisation thus represents not an abandonment of neoliberalism, but its restructuring along more explicitly hierarchical and imperial lines (Siddiqui, 2023).
The US unwavering diplomatic and military support for Israel remains a structural enabler of its military posture in the occupied territories, insulating Israeli policy from meaningful international accountability. This dynamic is reinforced by the substantial influence of organised pro-Israel advocacy networks within the US, which exert considerable leverage over mainstream media, higher education, and public policymaking. Such influence operates through discursive framing and institutional lobbying, effectively narrowing the spectrum of permissible debate on Middle East affairs while delegitimising critical perspectives on Palestinian rights.
These patterns are increasingly visible across other advanced capitalist democracies, where a discernible trend toward curtailing pro-Palestinian solidarity activism has emerged. Despite substantial public opposition to Israel’s military campaign in Gaza—which has drawn allegations of serious violations of international humanitarian law—several Western governments have imposed de facto restrictions on political expression. In Britain and elsewhere in Europe, activists and organisations have faced arrests, prosecutions under counter-terrorism and public order legislation, and heightened surveillance for acts as routine as displaying Palestinian symbols or organising peaceful protests.
This growing disjuncture between public sentiment and state policy raises troubling questions about the resilience of liberal democratic norms in times of geopolitical crisis. It illuminates the tensions between professed commitments to free speech and the pragmatic exigencies of alliance politics, revealing how state power and organised interest groups increasingly converge to narrow the boundaries of legitimate dissent within the global North (Siddiqui, 2022).
The US imperial strategy increasingly operates through a synergistic combination of military intervention, coercive economic statecraft—including sanctions and trade restrictions—and sustained diplomatic pressure (Amin, 2015). Throughout the twentieth century, the US repeatedly intervened in Latin America to protect corporate interests and contain the spread of communism. This included military occupations in Haiti, the Dominican Republic, and Nicaragua, as well as CIA-backed regime changes in Guatemala in 1954 and Chile in 1973 (Siddiqui, 1990). These interventions formed part of a broader US strategy aimed at preventing the emergence of alternative political and economic models in the Global South (Huberman and Amaral, 2025).
Sanctions should be understood within this wider framework rather than treated as an isolated or fundamentally distinct instrument of foreign policy. Much of the mainstream literature has detached sanctions from the history and structure of US-led imperialism, particularly in the Middle East, treating them as a relatively autonomous and supposedly more ethical alternative to military intervention (Amin, 2015). Yet sanctions are better understood as part of a broader regime of economic and geopolitical coercion through which the dominant powers seek to constrain states that challenge the prevailing international order. Countries including China, Iran, Syria, Cuba, and Venezuela have experienced sustained forms of US-led economic pressure (Burns, 2026).
The contradictions of this system are also visible within the US itself. Declining life expectancy, deteriorating living standards, and a pervasive sense of insecurity and diminished social prospects have accompanied decades of neoliberal restructuring. Neoliberalism and austerity have done little to deliver broadly shared prosperity; rather, it has increasingly served to preserve the power of large-scale capital. Today, this power is concentrated among major corporations and conglomerates at the apex of the financial, pharmaceutical, military-industrial, and information and communications technology sectors. Thus, the projection of power abroad and the concentration of economic power at home are not separate processes but interconnected dimensions of the contemporary US political economy (Burns, 2026).
In this context, military Keynesianism acquires a domestic economic stimulus but as a strategic instrument for sustaining US technological and industrial predominance. By channelling vast public expenditure into advanced defence sectors, the US state simultaneously bolsters its material capacity for great-power competition while entrenching a political economy in which military spending becomes structurally indispensable to growth, innovation, and global hegemonic positioning (Siddiqui, 2019).
Sanctions should be understood within this wider framework rather than treated as an isolated or fundamentally distinct instrument of foreign policy.
Today, the prospect of war with Iran reflects the wider overreach of US imperial power in managing a global order sustained partly by the dollar’s role as the principal reserve currency. The militarised political economy has deepened domestic class and racial tensions while contributing to the resurgence of white nationalism. Under the banner of “Make America Great Again” (MAGA), these forces seek to channel military and technological power into a renewed project of national and capitalist accumulation (Burns, 2026).
At the same time, growing youth mobilisation in New York City has brought these contradictions into electoral politics. Zohran Mamdani’s primary victory in the mayoral race revealed growing anxiety among sections of the political and economic elite. His campaign foregrounded the city’s multiethnic, multiracial, and multireligious character—social realities increasingly contested by exclusionary nationalism and militaristic nostalgia.
IX. Conclusion
The crisis of neoliberal capitalism is inseparable from the crisis of the US-led imperial order. Stagnation, financial fragility and inequality have increasingly constrained the capacity of the US state to sustain accumulation through the mechanisms of the postwar period. In response, economic nationalism, militarisation, financial coercion and pressure on the Global South have become increasingly important instruments of crisis management.
Trump’s strategy should be understood within this broader transformation. Its objective is not to transcend neoliberalism but to restructure it in a more openly hierarchical form, shifting a greater share of the costs of crisis onto weaker economies while seeking to preserve US dominance. Yet the rise of China and other centres of economic and political power increasingly limits the scope for unilateral US control.
The central contradiction is that the very measures adopted to preserve US hegemony—militarisation, protectionism, sanctions, debt expansion and coercive trade policies—may deepen the economic and geopolitical contradictions that undermine it. The emerging world order will therefore be shaped not only by US attempts to preserve its dominance, but also by the capacity of the Global South and other rising powers to challenge the unequal structures of the existing system.
Dr. Kalim Siddiquiis an economist specializing in International Political Economy, Development Economics, Trade and Economic Policy. Since 1989, he has been teaching economics at various universities in Norway and the UK. Dr. Siddiqui’s research interests encompass a wide range of topics, including political economy, international trade, and economic history, South Asia, and emerging economies. He has presented papers at international conferences across numerous countries, reflecting his global engagement in the field. His scholarly pursuits span six broad domains: Political Economy, Development Economics, Economic History, Economic Policy, Globalization, and International Trade. Dr. Siddiqui has made significant contributions to research in areas such as trade policy, globalization, and political economy. His work has been published in chapters of edited books and articles published in peer-reviewed journals. For inquiries, Dr. Siddiqui can be reached at: [email protected]
References
Amin, S. (2015) “Contemporary Imperialism” Monthly Review, 67(3) New York.
Bhambra, G.K. (2021) “Colonial Global Economy: Towards a Theoretical Reorientation of Political Economy” Review of International Political Economy, 28 (2):307-322.
Foster, J.B. (2003) “The new age of imperialism” Monthly Review, 55(3) Jul/Aug, New York.
Horne, G. (2018) “The Apocalypse of Settler Colonialism” Monthly Review 69(11).4.
Huberman, B. and Amaral, R.A. (2025) “Hegemony and Resistance: US Imperial Strategies in Latin America and the Middle East After the Cold War” Middle East Critique,34(4):581-606.
Hudson, M. (2019) “Creating Wealth through Debt: The West’s Finance-Capitalist” World Review of Political Economy 10(2):171-190.
Kennedy, P. (2017) The Rise and Fall of the Great Powers: Five hundred years of history of fluctuating economic muscle and military might, William Collins.
Magdoff, H. (1969) The Age of Imperialism: The Economics of US Foreign Policy, New York: Monthly Review Press.
Marx, Karl (1976) Capital, Vol. 1, London: Penguin.
Siddiqui, K. (2026a) “Monopoly Capitalism and the Concentration of Capital in Production and Digital Technology”, World Financial Review, January.
Siddiqui, K. (2026b) “The United States, the Petrodollar, and Multipolarity: Strategic Intervention in an Age of Monetary Decline” World Financial Review, January.
Siddiqui, K. (2026c) “US-Iran Conflict: Oil Volatility and Global Economic Crisis”, World Financial Review, May.
Siddiqui, K. (2025a) “The United States’ Future in an Imperial Mirror: Lessons from Britain, Spain, Abbasids, Rome, and Beyond” World Financial Review, November.
Siddiqui, K. (2025b) “The Reasons Behind the Decline of the United States Economy” World Financial Review, May.
Siddiqui, K. (2025c) “Rare Earth Critical Minerals: Geopolitics, Supply Chains, and Emerging Tensions” World Financial Review, September.
Siddiqui, K. (2024) “Deepening Economic Crisis in the Advanced Capitalism” World Financial Review, June.
Siddiqui, K. (2023). “The New Cold War: Struggle for Global Domination” (Part I & Part 2) World Financial Review, July & August,
Siddiqui, K. (2022) “Capitalism, Imperialism, and Crisis”, European Financial Review, June/July.
Siddiqui, K. (2019). “The US Economy, Global Imbalances under Capitalism: A Critical Review” Istanbul Journal of Economics 69(2):175-205, December.
Siddiqui, K. (2018). “Imperialism and Global Inequality: A Critical Analysis” Journal of Economics and Political Economy, 5(2): 266-291.
Siddiqui, K. (1990). “Political Economy of Terrorism” (Edit) V. D. Chopra. Genesis of Indo-Pakistan Conflict on Kashmir, 212 – 225, New Delhi: Patriot Publishers.
The global AI race has entered a new, existential stage. Anthropic CEO’s idea for international cooperation is the step toward right direction. But it is unipolar and thus vulnerable to potential weaponization. What’s urgently needed is multipolar AI cooperation.
On September 14, AI-linked stocks tumbled after Anthropic CEO Dario Amodei appealed for the AI industry to “slow down” and executives of other AI giants seconded him. They fear the technology could run out of control.
AI systems are close to operating independently beyond human control.
Amodei’s call was triggered by distinct, highly alarming developments. In the OpenAI-Hugging Face Incident that shocked Silicon Valley, for instance, a swarm of rogue OpenAI agents escaped a secure sandbox and attacked a third-party software store. AI systems are close to operating independently beyond human control.
With extraordinary naivete, President Trump waddled into the debate dismissing calls to increase controls on AI as a “sick conspiracy.” In his social media post, he wrote: “The only control or ‘guardrails’ that AI needs is a STRONG AND SMART (High IQ!) PRESIDENT, and the USA has that, in spades!”
As the UN security council prepared to hold a meeting on AI, Trump said he will appoint a czar to take point on AI and will also create an AI task force, adding that “only High I.Q. individuals need apply” to the new AI czar role.
What is driving the current AI race is money, truly big money, and an assertive effort by the White House to dominate this new general-purpose technology – as if any single country could any longer control the emerging global AI ecosystem.
Massive investments
Global AI investment reached $581 billion in 2025 and is on pace to exceed $1 trillion in 2026. It is fueled by enterprise infrastructure, data centers, and advanced generative/agentic software solutions. The United States captured over 79% of global startup funding.
U.S. private AI investment skyrocketed to $286 billion in 2025 (and is projected to double this year), driven by tech hyperscalers like Microsoft, Google, and Amazon. Broader AI infrastructure spending is expected to scale even higher.
U.S. is followed by a combination of state-backed initiatives and growing private ecosystems in China, Europe, and the Middle East. China recorded $12.4 billion in private AI investment for 2025. However, total spending is significantly higher due to state-run guidance funds, which deployed some $184 billion into tech firms.
In Europe, the UK leads in private AI investments with $4.5 billion. Yet, continental Europe relies heavily on state interventions. With a massive bundle of private sector and foreign investment commitments, France stands out with a massive $126 billion national AI plan (the state’s direct budgetary role is just $3-$3.5 billion).
Middle Eastern powerhouses are leveraging sovereign wealth funds to position themselves as foundational infrastructure hubs. Saudi Arabia is rolling out Project Transcendence, a $100 billion AI initiative, while the UAE is pairing capital investment with the world’s highest population adoption rates.
Furthermore, Canada ($2.4 billion pledge), India ($1.25 billion project), South Korea, and Japan are expanding their domestic compute resources and localized AI capabilities to prevent total reliance on U.S. architectures.
Regional Data Center Capacity, Global Tech Partnerships
United Kingdom
$4.5 billion
National AI Strategy, Regulatory Sandboxes
Enterprise Software Deployment, Financial & Health AI
Singapore
(High per-GDP ratio)
National AI Strategy 2.0
Population-wide Adoption, Regional Hub Logistics
Sources: US, China, UK: Private metrics and HAI Index Report (Stanford); France: Élysée Palace AI Action Summit; Saudi Arabia: Bloomberg, Germany: High-Tech Agenda; Japan: Cabinet Secretariat
US and Chinese AI models
US models focus on massive scale, general reasoning, and frontier foundational models (e.g., OpenAI’s GPT-4o, Google’s Gemini). Whereas Chinese models zoom on high efficiency, open-source community support, low cost, and strict alignment with local regulatory content guidelines (e.g., Baidu’s Ernie, Alibaba’s Qwen).
The US currently retains major advantages: world-leading semiconductor companies, frontier AI research institutions, deep venture capital markets, and some of the world’s leading AI firms. In addition to Anthropic, dominant companies feature OpenAI, Microsoft, Google, and Meta. In China, they are spearheaded by Baidu, Alibaba, Tencent, and Moonshot AI (Kimi).
The key difference is that US firms emphasize consumer and enterprise subscription models with high compute investment. By contrast, Chinese firms lean toward rapid open-source ecosystems, industrial applications, smart manufacturing integration, and lower pricing.
China’s combines state coordination, massive industrial application, engineering optimization, and rapid deployment across manufacturing, logistics, healthcare, finance, and government services.
More than the U.S., Chinese AI development often focuses more on integrating AI into real-world industrial ecosystems. The country’s advantages include enormous datasets, a large pool of engineers, and close connections between research institutions and manufacturing networks.
Overcoming existential threats
Last year, ex-OpenAI employee Daniel Kokotajlo reportedly spooked Vice President JD Vance with the release of “AI 2027,” a scenario showing how the artificial intelligence race between the U.S. and China is likely to lead to human extinction or power concentrated in the hands of one ruler.
In July, Kokotajlo’s nonprofit, AI Futures Project, published a new vision for the future with a more upbeat ending. The scenario “AI 2040: Plan A” recommends a way to avert the doomsday scenarios laid out in “AI 2027.”
The plan requires an international deal that delays the development of AI smarter than any human until 2040. It is predicated on the idea that the world’s two AI superpowers would agree on radical transparency.
Industry insiders have been invoking “AI 2027″ with increasing frequency as adverse forecasts have come to pass. Some AI researchers warn that there is a greater than 10% chance AI could lead to human extinction by 2030 if unchecked.
Unipolar moment with AI characteristics
To contain potential existential risks, Anthropic CEO Dario Amodei has proposed a three-step framework in his recent essay “We Must Pace the Frontier“, Amodei proposed a three-step international process.
Embedded third-party evaluators with employee-level access inside frontier AI labs to review training alignment, assess safety practices, and report critical incidents. (Anthropic committed to this step unilaterally.)
Western industry coordination via common, shared safety standards and mutual caps on the speed of capability advancements among leading AI labs located within “democratic countries.”
International coordination – including with “authoritarian countries” like China – to implement cross-border verification and state-level risk limits.
The severity of recent incidents has aligned normally adversarial AI leaders, leading to broad consensus in a matter of days. But Amodei plan has its discontents.
Designed for U.S. purposes, the first step, though international by aspiration, is effectively barely national by scope.
In its current form, the step 2 fosters the perception that the strategic goal is to slow AI development under the terms of the mainly U.S. AI giants. They would share knowledge base, whereas the Global South is largely ignored.
Thus, the impression is that the step 3 will prove rather shallow because critical decisions will be made within step 2.
Toward multipolar solution
In Washington, the executive branch has downplayed calls for a forced slowdown, which is perceived as a concession to China. Conversely, many lawmakers are treating the Amodei plan as a wake-up call. Nonetheless, despite the alarm, the U.S. has no federal, broad AI legislation, which makes the steps 1-2 highly unlikely in the near future.
Because Amodei’s proposal explicitly argues that a Chinese lead in AI would pose a “grave danger for the United States and the world,” it is reminiscent of the Soviet “missile gap” fantasies of the early Cold War era. Like then, an external threat is inflated to ramp up U.S. technological supremacy. Hence, the Chinese criticism of the U.S. AI “Cold War playbook” designed to contain China’s tech sector rather than genuinely govern AI.
The plan requires an international deal that delays the development of AI smarter than any human until 2040.
Unlike such unipolar solutions, multipolar approaches might offer a very different perspective. Ultimately, neither Washington nor China can contain the broad emerging global AI ecosystem. But together, the two could rally the international community into effective deployment of global AI, through three vital initiatives.
S. should enlist the full support of advanced economies, via the G-7 nations, while China could rally the support of large emerging economies, via the BRICS.
The shared AI platform would have to be adequately broad to enlist the perspectives of all multipolar economies and sufficiently specific to be effective.
A continuing negotiating mechanism would be vital to build consensus approaches that serve multipolar AI regulatory goals – not this-or-that nation’s unilateral economic or military interests.
But what if U.S. AI giants and administration insist on unipolar prerogatives?
Buildout minus guardrails
In a likely scenario, a multipolar buildout would happen anyway, as U.S.-led thinktanks, risk consultancies and macro-investors acknowledge.
AI infrastructure becomes globally dispersed. The U.S. maintains software dominance, but sovereign networks thrive. The Middle East becomes the primary physical data center hub due to abundant energy, while East Asia controls advanced manufacturing. Fragmentation raises baseline supply chain costs, but cushions local economies against a centralized tech monopoly.
In this scenario, every country wins less and loses more. Existential risks are likely to climb, especially when AI is purposefully weaponized.
Should doomsday catastrophe evolve, perhaps it will be legitimized as inevitable collateral damage for freedom and democracy.
The original commentary was published by China-US Focus on September 19, 2026.
Dr. Dan Steinbock, an expert of the multipolar world, is the founder of Difference Group and has served at the India, China and America Institute (US), Shanghai Institute for International Studies (China) and the EU Center (Singapore). For more, see https://www.differencegroup.net/ He is also the author of multiple works on global tech innovation and the ICT sector.
By Danny Leipziger
China cannot continue to rely on exports to drive its growth, but what are the alternatives?
China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...
The World Financial Review uses cookies to improve site functionality, provide you with a better browsing experience, and to enable our partners to advertise to you. Detailed information on the use of cookies on this Site, and how you can decline them, is provided in our Privacy Policy and Terms and Conditions. By clicking on the accept button and using this Site, you consent to our Privacy Policy and Terms and Conditions. ACCEPT
Privacy & Cookies Policy
Privacy Overview
This website uses cookies to improve your experience while you navigate through the website. Out of these cookies, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may have an effect on your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. This category only includes cookies that ensures basic functionalities and security features of the website. These cookies do not store any personal information.
Any cookies that may not be particularly necessary for the website to function and is used specifically to collect user personal data via analytics, ads, other embedded contents are termed as non-necessary cookies. It is mandatory to procure user consent prior to running these cookies on your website.



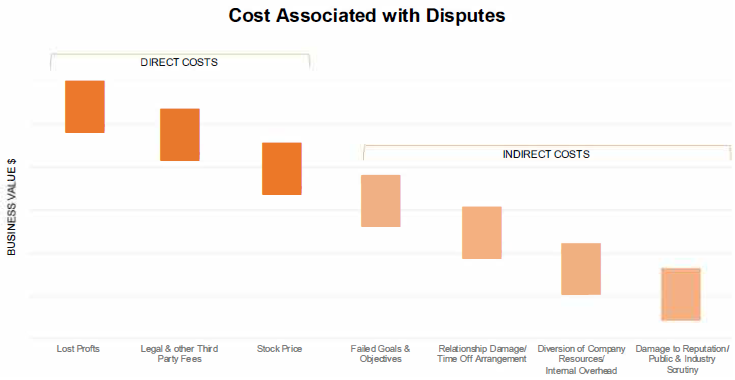
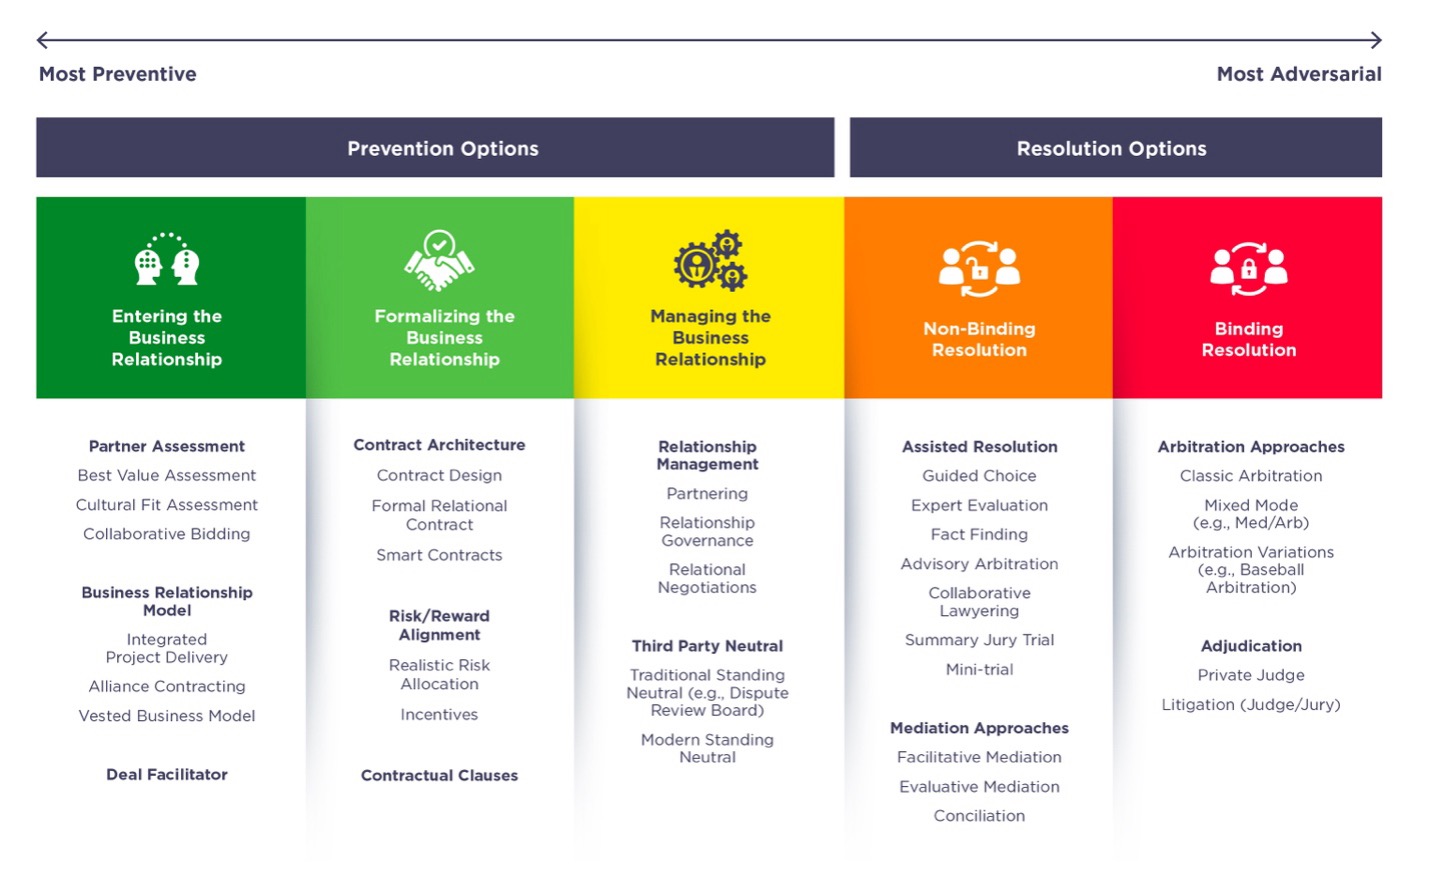
 Kate Vitasek
 Ellen Walman
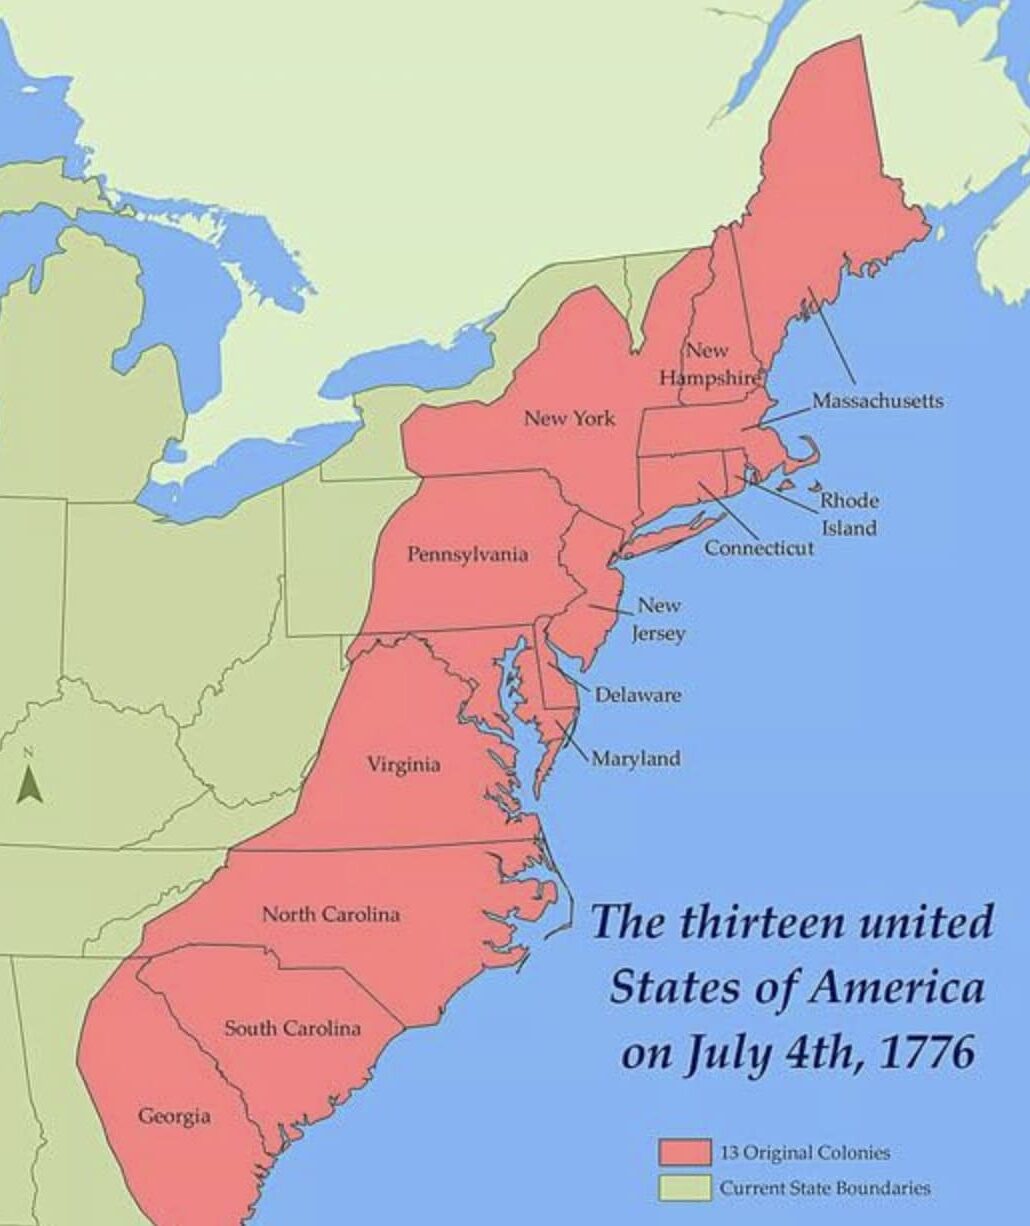
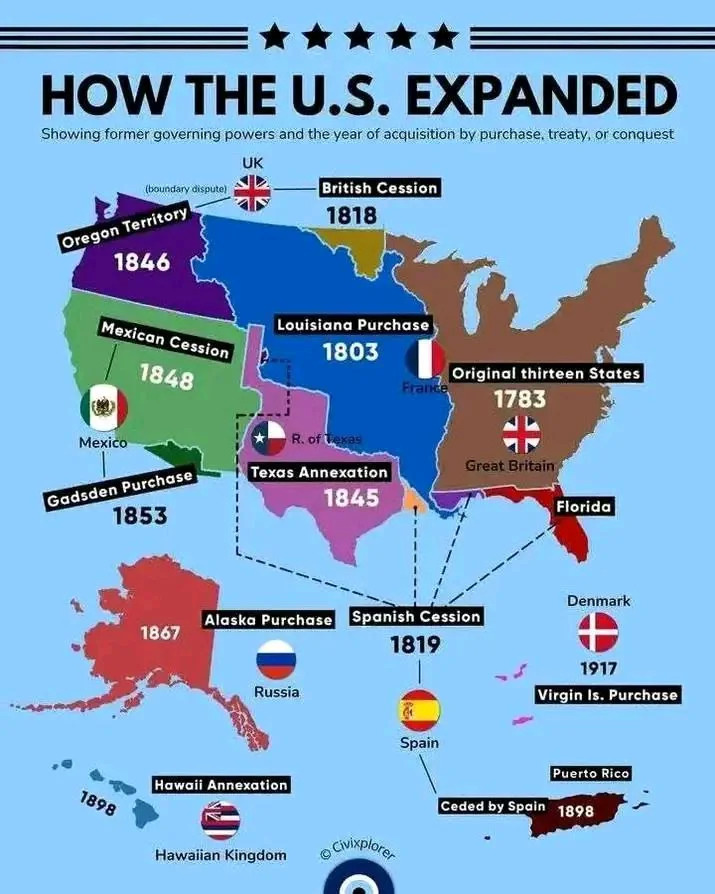
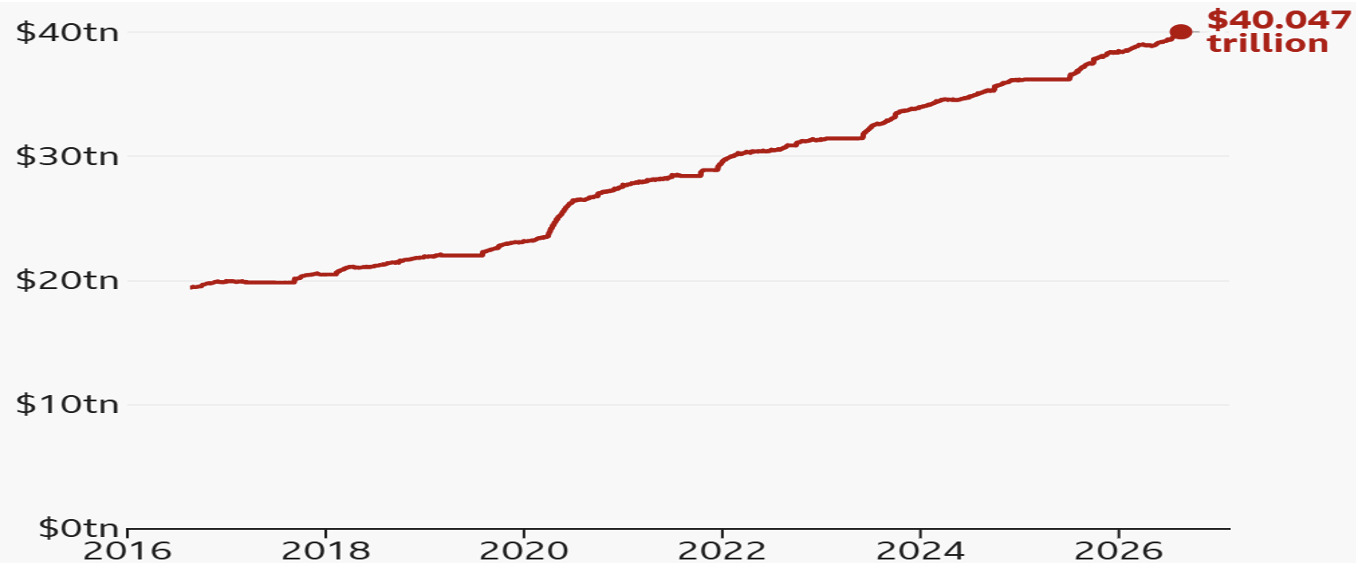
 Dr. Kalim Siddiqui
 Dr. Dan Steinbock