Home Blog Page 26

US/Iran Energy Shock Damage is Spreading in Asia

By Dan Steinbock             

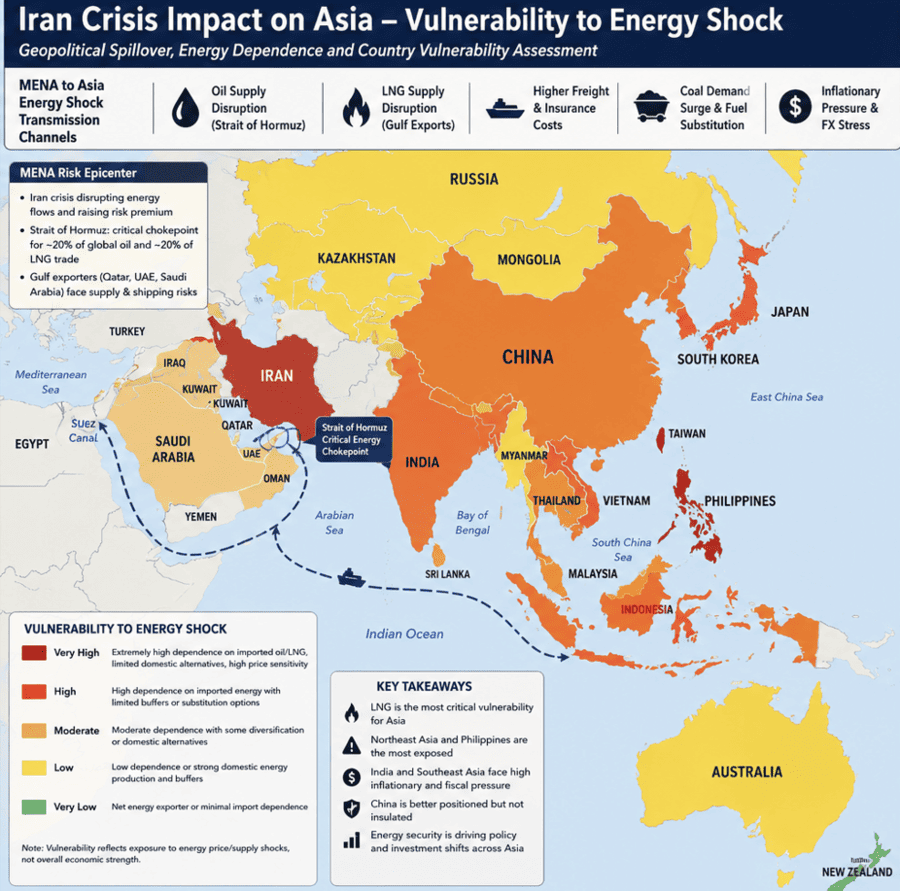
The US/Iran-linked energy crisis has shifted from a commodity shock to structural geopolitics, with Asia at the epicenter due to its dependence on imported oil and LNG. Global reverberations can no longer be avoided.

In the Asian shock, four transmission channels play a role. In the case of oil, elevated risk premium is coupled with physical tightening via Strait of Hormuz disruptions.

Lliquefied natural gas (LNG) poses a more severe constraint than oil and thus structural tightening of Asian gas balances. Meanwhile, coal substitution is experiencing a short-term demand surge in Asia, especially in India, China and Southeast Asia.

On the economic side, countries are struggling with imported inflation, foreign exchange pressure, and painful policy trade-offs between subsidy support and fiscal stability.

The shock is no longer a temporary price spike but a sustained supply reordering. The International Energy Agency (IEA) projects large-scale oil drawdowns. LNG disruptions are removing 20% of global LNG flows at peak disruption, which will tighten Asian supply chains significantly.

What happens in Asia won’t stay in Asia. In the coming months, the adverse reverberations will be felt across the world. 

Asian Century and global growth at stake    

Asia remains the engine of global economic growth, with China and India alone contributing roughly 40–45% of incremental global GDP growth, while other major Asian economies—Indonesia, South Korea, Vietnam, and ASEAN collectively—add another 10–12%.

In the medium term, Asia’s share of global growth is expected to rise further as Western economies slow, driven by demographic momentum, urbanization, and productivity gains in services and manufacturing.

However, a severe energy crisis, particularly if it triggers sustained LNG and oil shortages, would sharply compress industrial output, inflation-adjusted consumption, and investment in these economies, potentially reducing global growth by 1–2 percentage points in 2026–27.

An Asian slowdown would have significant spillovers to the US, Europe, and Japan through trade, investment, and financial channels. Reduced Asian demand would depress exports of machinery, electronics, and consumer goods from these regions. Higher energy prices would further weigh on consumption and industrial costs. Financial markets could face increased volatility, amplifying capital flow disruptions.

In Japan, the combination of energy dependence and weaker regional demand could sharply constrain growth, while Europe and the US would experience slower industrial output and dampened inflation-adjusted consumption, reinforcing the global drag from the Asian energy shock.

Oil tightness, LNG constraint, brief coal rebound

Oil remains volatile but more flexible than gas. Prices surged above $100/bbl during peak disruption and remain elevated ($90–100 volatility band in stress conditions)

Strait of Hormuz instability has removed millions of barrels/day of export capacity. OPEC+ spare capacity is partially offsetting but insufficient to normalize inventories. Inventories are falling at record pace, reducing the buffer against further shocks.

Unlike earlier cyclical oil shocks, this episode is characterized by structural inventory depletion, making price spikes more persistent even if supply partially recovers.

Nonetheless, natural gas is the primary stress point for Asia. Up to 20% of global LNG supply was disrupted at peak due to Hormuz-linked flows. Asian LNG prices surged above $20/MMBtu in multiple spot windows.

Northeast Asian importers (Japan, Korea, China, Taiwan) entered emergency procurement and rationing. Long-term contracts are under stress due to force majeure risks and shipping rerouting constraints.

Asian LNG imports have dropped sharply. Qatar/UAE-linked exports remain vulnerable due to chokepoint exposure. LNG is increasingly perceived in Asia as less reliable as a transition fuel, accelerating diversification away from gas-heavy strategies in parts of the region.

Then there is the curious rebound of coal, temporarily distorting markets. Asia’s immediate adjustment has been substitution, not demand destruction. China, India, Indonesia and other countries have increased coal burn in power generation. In several ASEAN economies, this is increasingly seen as short-cycle substitution, not structural reversal.

Renewables deployment acceleration continues in parallel (especially China, India).
How are countries coping

China is managing a dual challenge: LNG exposure plus industrial cost pressure. Hence, the simultaneous deployment of coal and renewables. Strategic LNG diversification has increased from the Middle East to Russia, US and Australia. Energy security is now embedded into industrial policy response.

India is highly exposed to imported LNG and oil inflation. Strong coal buffer limits crisis severity but increases environmental cost, which is already soaring with the nation’s broad takeoff. Unsurprisingly, fiscal pressure is rising from fuel subsidies. The net effect is manageable but inflationary growth drag.

Japan and South Korea are structurally most exposed to LNG disruption. So, emergency procurement and demand management measures have been activated, with the acceleration of nuclear restarts and efficiency gains. Now energy security dominates macro policy debate.

Southeast Asia (Indonesia, Vietnam, Thailand, Philippines) is highly price-sensitive to LNG demand. Consequently, LNG project cancellations and delays have a painful impact, which is rapidly translating to political volatility. Hence, the efforts to re-optimize coal in Indonesia and Vietnam.

Longer-term shift prevails toward renewables and regional grid integration. But as energy reserves are diminishing, the focus is on the short-term. To paraphrase Keynes: in the long-run, we’re all dead.

From economic transmission to energy shift

The energy shock is feeding directly into consumer price index (CPI) via fuel, logistics, and fertilizers. Hence, the secondary pass-through into food prices, notably in South Asia.

Foreign exchange is under severe pressure as import-dependent Asian economies are facing severe currency depreciation pressure. Before the crisis, US dollar was less than 58 Philippine peso; now, close to 62. Meanwhile, central banks are forced into tighter-than-expected monetary policy stance.

Industrial slowdown risk is increasing. Energy-intensive manufacturing margins are compressed. Fertilizer, petrochemicals, and steel sectors are most exposed.

The crisis is accelerating three structural shifts. The first entails the move from LNG expansion to LNG risk hedging.

Second, the past objective to move away from fossil transition has been superseded by energy security primacy.

Third, electrification has accelerated. Renewables and storage investment are front-loaded. Future is not next year. It’s now.

Trump–Xi summit: hope for stability 

Prior to the summit, analysts hoped that the US-China talks could serve as a stabilizing variable for global energy markets, in three ways.

Strategic signaling fosters oil price stabilization, just as US–China coordination reduces demand-side geopolitical uncertainty. The potential easing of tariff and geoeconomic tensions could support global demand expectations.

Second, LNG trade realignment suggests that China may diversify LNG imports further from politically sensitive corridors. US LNG exports could benefit from strategic trade normalization, while Europe–Asia LNG competition could moderate if US-China trade improves.

Third, there is the political minefield of sanctions and Iran-related diplomacy: Even limited coordination could reduce escalation probability in the Middle East, which is vital to avoid extreme oil price spikes.

From the standpoint of the energy markets, the summit was less about immediate supply restoration and more about reducing geopolitical volatility embedded in energy pricing. But the success of the summit will be determined by the markets only in its aftermath.

Unsettling scenarios for 2026–27 

Base scenario: Partial stabilization of the Middle East conflict proceeds without full resolution. Hormuz remains intermittently disrupted but not fully closed. LNG supply is partially restored but tight. Oil inventories rebuild slowly but remain below norm. Brent crude varies around $85–105/bbl and LNG Asia spot at $12–20/MMBtu. Inflation stays elevated but manageable. Asia faces growth drag but no recession.

Optimistic scenario: Diplomatic stabilization is supported by US–China coordination following the summit. Shipping lines are gradually reopened. LNG infrastructure is partially restored. OPEC+ increases output into recovering demand. Brent crude falls to $65–85/bbl and LNG to $8–14/MMBtu. Inflation falls sharply in Asia. Policy easing resumes globally and energy transition investments accelerate again.

Pessimistic scenario: Renewed military escalation takes off in the Iran–Gulf theater. Hormuz’s closure is sustained or repeated. LNG infrastructure damage spills over in Qatar/Gulf. Severe inventory depletion triggers panic buying. Brent crude soars to $110–140+/bbl and LNG climbs to $20–35/MMBtu. Severe imported inflation shock spreads, with industrial slowdown and rationing risk in parts of Northeast Asia. Renewables and coal substitution surge simultaneously. With financial volatility, emerging market currencies fall and capital flight resumes.

The 2026–27 outlook is at best clouded in uncertainty. The concern is that it will morph into high plateau volatility.

The original version was published by China-US Focus (US/Hong Kong) on May 15, 2026.

About the Author

Dr Dan SteinbockDr. Dan Steinbock is an internationally recognized strategist of the multipolar world and the founder of Difference Group. He has served at the India, China and America Institute (USA), Shanghai Institutes for International Studies (China) and the EU Center (Singapore). For more, see https://www.differencegroup.net

The AI Divide is Already Reshaping Who Holds Power At Work

By Dr. Gleb Tsipursky

Artificial intelligence is no longer waiting politely outside the office door; it is already answering customer questions, cleaning up emails, digesting documents, drafting code, preparing lesson plans and reshaping who looks capable at work. The real story is not that machines are coming for every job tomorrow. It is that the workplace AI divide is hardening today, separating workers with permission, practice and useful workflows from those left to improvise or abstain.

Gallup’s latest workforce data shows that 12% of U.S. employees used AI daily in the fourth quarter of 2025, while 26% used it at least a few times a week. Nearly half of workers still said they never used AI in their role. That gap is becoming a new form of workplace power.

The New Office Divide

The first wave of AI adoption at work has not spread evenly across the labor market. Gallup found that use is highest in technology, finance, higher education and professional services, while retail, manufacturing and healthcare lag behind. Technology workers reported especially high usage, with 77% using AI at least a few times a year and 31% using it daily.

Generative AI tools are not only for coders and analysts — they can help frontline workers perform better when employers tolerate experimentation

The pattern is not mysterious. Remote-capable roles are easier to augment with today’s AI because so much of their work already flows through text, spreadsheets, meetings, search bars and software dashboards. A consultant can ask a model to summarize a transcript. A banker can compress a dense packet. A teacher can refine a parent email. A store associate can use an assistant to answer a customer’s question about an unfamiliar product.

That last example matters because it complicates the white-collar story. Generative AI tools are not only for coders and analysts — they can help frontline workers perform better when employers tolerate experimentation and workers have enough confidence to use the tools responsibly. The question is whether organizations will formalize that benefit or leave it to individual hustle.

Adoption Is A Management Problem

The next phase of AI will not be decided by software access alone. Gallup’s April 2026 analysis found that employees were much more likely to use AI frequently when tools fit existing workflows, managers supported use and organizations had clear policies.

Among employees whose organizations made AI available, those who strongly agreed that AI integrated well with their systems were far likelier to use it often than those who did not.

That finding turns manager support into a competitive issue. When bosses treat AI as a forbidden shortcut, workers hide experimentation. When leaders treat it as magic dust, workers waste time producing low-value prompts. When managers connect specific tools to specific tasks, frequent AI use becomes less about curiosity and more about operational discipline.

The most effective organizations will stop asking whether employees “use AI” and start asking sharper questions. Which tasks are safer, faster or better with assistance? Which outputs need human review? Which data must never enter a public model? Which roles need training before expectations rise?

McKinsey’s AI workplace report argues that leadership, not employee willingness, is often the bottleneck in scaling AI value.

This is also why AI workforce changes will look less like a single technological event than a management sorting mechanism. Some employees will gain time, visibility and leverage. Others will watch expectations rise without receiving the tools, guardrails or coaching needed to meet them.

Exposure Is Not Destiny

The most dangerous AI conversation treats exposure as a synonym for replacement. It is not. A worker can be highly exposed to AI because the technology can assist many tasks, yet still be resilient because they have savings, transferable skills, strong credentials and a dense labor market around them.

Brookings researchers sharpened this point by combining AI job exposure with workers’ adaptive capacity. Their analysis found that many highly exposed workers are comparatively well positioned to navigate change. But it also identified 6.1 million workers who face both high AI exposure and low adaptive capacity, concentrated in clerical and administrative roles, with women making up 86% of that vulnerable group.

The NBER version of the same research stresses that exposure reflects potential task change, not inevitable job loss. That distinction should shape policy and corporate responsibility. The point is not to freeze AI out of offices. It is to avoid letting automation gains accrue to people with the most buffers while the least protected workers absorb the risk.

The public sector shows how quickly the map can shift. Gallup reported that public sector AI use reached 43% in late 2025, roughly matching private-sector use overall, though frequent use remained lower. Even government agencies with stricter risk controls are discovering that ordinary employees can experiment with low-cost tools before formal transformation plans catch up.

Conclusion

The winners will be the ones that treat AI workplace training as infrastructure, not just an added benefit.

The workplace AI story is about whether a teacher writes clearer notes, whether a banker reviews more material, whether a clerk gets displaced without support, whether a retail worker can answer one more question with confidence and whether managers build systems that make good use safe and normal.

The winners will be the ones that treat AI workplace training as infrastructure, not just an added benefit. They will define acceptable use, protect sensitive data, redesign workflows and measure whether AI actually improves quality instead of merely increasing output.

AI is becoming a mirror held up to the American workplace. It reflects old inequalities in education, authority, geography and bargaining power. It also creates a chance to narrow them. The divide is already visible, but whether it becomes a ladder or a wall is now a management choice.

About the Author

Dr. Gleb TsipurskyDr. Gleb Tsipursky was named “Office Whisperer” by The New York Times for helping leaders overcome frustrations with Generative AI. He serves as the CEO of the future-of-work consultancy Disaster Avoidance Experts. Dr. Gleb wrote seven best-selling books, and his two most recent ones are Returning to the Office and Leading Hybrid and Remote Teams and ChatGPT for Leaders and Content Creators: Unlocking the Potential of Generative AI. His cutting-edge thought leadership was featured in over 650 articles and 550 interviews in Harvard Business Review, Inc. Magazine, USA Today, CBS News, Fox News, Time, Business Insider, Fortune, The New York Times, and elsewhere. His writing was translated into Chinese, Spanish, Russian, Polish, Korean, French, Vietnamese, German, and other languages. His expertise comes from over 20 years of consulting, coaching, and speaking and training for Fortune 500 companies from Aflac to Xerox. It also comes from over 15 years in academia as a behavioral scientist, with 8 years as a lecturer at UNC-Chapel Hill and 7 years as a professor at Ohio State. A proud Ukrainian American, Dr. Gleb lives in Columbus, Ohio.

Kazakhstan Has Become Britain’s Most Important Partner in Central Asia

Kazakhstan’s President, Kassym-Jomart Tokayev, has recently signed the law ratifying the Agreement on Strategic Partnership and Cooperation between Kazakhstan and the United Kingdom, a move that may appear procedural at first glance, but in reality highlights a much larger geopolitical and economic shift.

The agreement formally elevates bilateral relations to a new strategic level and creates an updated legal framework for cooperation across trade, investment, energy, education, innovation and security. It was necessary in part because Britain’s departure from the European Union created the need for a standalone bilateral framework between London and Astana.

But the bigger question is why does this agreement matter now?

The answer lies in the changing realities of the global economy and a rapidly shifting geopolitical environment. Supply chains are being redrawn, not least because of the conflicts in Ukraine and the Middle East. Governments are seeking alternatives to overdependence on a small number of markets for critical resources. Trade routes are being reassessed amid instability in traditional shipping corridors. And middle powers are increasingly building pragmatic partnerships based on economic resilience rather than ideology.

Against this backdrop, Kazakhstan is quietly becoming Britain’s most important partner in Central Asia.

That shift has been building for some time and it became particularly visible during Foreign Minister Yermek Kosherbayev’s visit to London in February, where both sides signalled that their relationship is evolving far beyond traditional diplomacy.

One of the clearest examples is critical minerals.

As countries accelerate the energy transition and attempt to secure supply chains for advanced manufacturing, defence technologies and clean energy infrastructure, access to critical raw materials has become a strategic priority. Kazakhstan now occupies an increasingly important position in that equation.

The country produces 22 of the 36 minerals identified in Britain’s Critical Minerals Strategy, including uranium, titanium, silicon and rhenium. It remains the world’s largest producer of uranium and ranks among the top ten globally in reserves of tungsten, molybdenum, tantalum, niobium, nickel and cobalt.

This explains why one of the most significant outcomes of Kosherbayev’s February visit was the renewal of the Kazakhstan-UK Roadmap on Strategic Partnership in Critical Minerals. Importantly, discussions are increasingly focused not simply on extraction, but on processing, refining, recycling and value-added production, areas where British engineering expertise, ESG standards and financial services capabilities can play a major role.

For Britain, this represents an opportunity to diversify supply chains at a time when excessive concentration of mineral processing in a limited number of countries has become a growing strategic vulnerability.

Trade ties are also expanding at an increasingly rapid pace. In 2025, bilateral trade turnover reached $1.62 billion, an increase of 83.6 percent compared with 2024. Kazakhstan’s exports to Britain rose by more than 190 percent to reach $1.22 billion.

Meanwhile, cumulative British foreign direct investment in Kazakhstan has reached approximately $23 billion since 1993, placing Britain among Kazakhstan’s top ten foreign investors. In 2024 alone, British investment reached $723.7 million, while a further $471.5 million was invested in just the first nine months of 2025.

Today, 516 companies with British participation operate in Kazakhstan.

These figures matter because they demonstrate that this partnership is no longer aspirational. It is already being built through real capital flows and commercial engagement.

Kazakhstan’s broader economic trajectory also helps explain why British interest is growing. Its GDP surpassed $300 billion last year, with economic growth reaching 6.5 percent. Kazakhstan accounts for more than 60 percent of all foreign direct investment flowing into Central Asia and has increasingly positioned itself as the region’s largest economic hub.

For British businesses looking at Central Asia, Kazakhstan increasingly represents the most logical entry point.

That is particularly true when it comes to connectivity and logistics. As geopolitical tensions disrupt traditional trade routes, whether through the Red Sea, Russia-related sanctions risks or broader supply chain instability, alternative transit corridors are becoming more strategically important.

Kazakhstan sits at the centre of this recalibration. Approximately 85 percent of overland cargo moving between Europe and Asia passes through Kazakhstan. The Trans-Caspian International Transport Route, often referred to as the Middle Corridor, continues to expand through investments in rail infrastructure and ports such as Port of Aktau and Port of Kuryk. Digital systems such as Smart Cargo are also improving efficiency across transit routes.

For Britain, which is increasingly seeking supply chain resilience and diversified access to Asian markets, Kazakhstan’s role as a logistics hub is becoming far more strategically relevant.

There is also a broader geopolitical dimension to this relationship. In February, Britain hosted the first-ever CA5+UK Foreign Ministers meeting, an important signal that London is institutionalising its engagement with Central Asia rather than treating the region as a peripheral diplomatic issue.

That matters because Central Asia is becoming increasingly important to global energy security, food security, transport connectivity and critical mineral supply chains. Kazakhstan, as the region’s largest economy and one of its most active diplomatic players, naturally occupies a central role in that strategy.

Education and human capital are becoming another pillar of the relationship. Nearly 6,000 Kazakh students have studied in Britain under the Bolashak scholarship programme. British institutions including Cardiff University, Coventry University, Heriot-Watt University and Queen’s University Belfast have expanded their presence in Kazakhstan.

These institutional links create long-term familiarity with British legal systems, educational standards and business culture, strengthening ties beyond commodity markets.

This brings us back to the Agreement on Strategic Partnership and Cooperation between Kazakhstan and the United Kingdom. The newly ratified strategic partnership document does not create this relationship from scratch. Rather, it formalises a reality that has already emerged.

Britain increasingly needs reliable partners that can help strengthen supply chains, support energy transition goals, provide access to fast-growing regions and reduce geopolitical vulnerabilities. Kazakhstan offers precisely that combination. And for London, as it continues defining its global economic role after Brexit, few partnerships in Central Asia now carry greater strategic importance.

The information provided in this article is for general informational and educational purposes only. It is not intended as legal, financial, or professional advice. Readers should not rely solely on the content of this article and are encouraged to seek professional advice tailored to their specific circumstances. We disclaim any liability for any loss or damage arising directly or indirectly from the use of, or reliance on, the information presented.

How to Choose a Reliable Food Distributor for Your Business

Sourcing decisions rarely feel urgent until something goes wrong — a late delivery before a weekend rush, a substituted product that throws off a recipe, an invoice dispute that takes weeks to resolve. Choosing the right food distributor from the start is one of the most consequential operational decisions a foodservice business makes, and it deserves more due diligence than most operators give it.

This guide covers what actually matters when evaluating a distributor — not just price and product range, but the operational factors that determine whether the relationship works under real-world conditions.

Product Range and Category Depth

The most immediate question is whether a distributor can supply what you actually need. A broad catalog looks impressive on paper, but what matters is depth within your specific categories. A pizza shop needs a distributor with strong coverage of cheese, flour, and proteins. A hospital foodservice operation needs reliable access to allergen-controlled and dietary-specific products. A deli has different priorities again.

Before committing to any supplier, request a full product list for your primary categories and verify availability — not just whether the SKU exists in the system, but whether it’s consistently stocked. Ask specifically about substitution rates: how often do they fulfill an order with an alternative product when the primary item is unavailable? A high substitution rate creates downstream problems in kitchens that run standardized recipes.

Delivery Reliability and Logistics Infrastructure

A distributor’s delivery performance is arguably more important than their pricing. A 3% cost saving means nothing if you’re fielding last-minute calls from drivers running three hours late on a Friday afternoon.

Key questions to ask any prospective distributor:

  • What is their standard delivery window and how consistently do they hit it? Next-day delivery capability is a meaningful differentiator — it reduces the amount of inventory you need to hold on-site and allows you to respond quickly to demand changes without over-ordering.
  • What is their cold chain protocol? Temperature-controlled transport is non-negotiable for proteins, dairy, and prepared foods. Ask specifically how they handle chain of custody for refrigerated and frozen products from warehouse to delivery.
  • What happens when a delivery is incomplete or damaged? The answer to this question tells you a great deal about how a distributor operates. A reliable partner has a clear, fast resolution process — credits issued promptly, replacement orders expedited, not a two-week claims process.

Food Safety Credentials and Compliance

For any business operating in a regulated foodservice environment — restaurants, schools, healthcare facilities — your distributor’s food safety infrastructure directly affects your own compliance posture.

Look for distributors with USDA-inspected processing facilities, documented HACCP plans, and verifiable traceability systems. If a product recall is issued, you need to know that your distributor can identify affected lots quickly and communicate clearly. Distributors without robust traceability systems create liability exposure for their clients.

Certifications matter here, but so does transparency. A reputable distributor will share documentation without hesitation and should be able to answer specific questions about their food safety protocols rather than directing you to a generic compliance page.

Pricing Structure and Contract Terms

Price is not a simple number in food distribution — it’s a structure. Understand exactly how pricing works before signing anything.

  • Are prices fixed or market-indexed? For commodities like proteins and dairy, some fluctuation is expected, but you need to know when and how prices change and how much notice you’ll receive.
  • What are the minimum order requirements? Some distributors impose minimums that work for high-volume operations but create problems for smaller businesses with variable demand.
  • What are the payment terms? Net-30 is standard, but terms vary. Understand late payment policies and whether early payment discounts are available.
  • Are there fuel surcharges or delivery fees? These can significantly affect the true cost of a relationship, particularly for businesses outside major urban delivery corridors.

Local Knowledge and Service Quality

Working with food distributors near me — distributors with genuine regional presence rather than a national operation running a local branch — tends to produce better service outcomes for most foodservice businesses. Local distributors understand regional supplier relationships, can respond more quickly to urgent needs, and typically offer more direct access to decision-makers when problems arise.

Atlantic Foods has operated as a food distribution specialist across Ohio since 1960, serving restaurants, schools, hospitals, delis, and pizza shops with a catalog of over 8,000 foodservice products. That depth of regional experience translates into supplier relationships and logistical infrastructure that national broadliners often can’t replicate at the local level.

The Relationship Factor

Distribution is an ongoing operational relationship, not a one-time transaction. The quality of the account management you receive — how quickly calls are returned, how proactively your rep communicates about supply issues, how empowered they are to resolve problems without escalation — will affect your business on a weekly basis.

Before committing, ask who your primary contact will be and what their caseload looks like. A rep managing 200 accounts will necessarily provide less attentive service than one managing 60. Ask for references from similar business types in your region and ask those references specifically about service quality during difficult periods — supply shortages, seasonal demand spikes, product recalls — not just routine operations.

The right distributor isn’t simply the one with the lowest price or the longest product list. It’s the one whose operational standards, service model, and communication style align with how your business actually runs.

China Signals Tariff Cuts After Trump Xi Summit

China and the United States have agreed to expand agricultural trade following talks between Donald Trump and Xi Jinping in Beijing. Chinese officials said both sides are working on tariff reductions and better market access for farm products.

China’s commerce ministry described the agreements as preliminary but said both countries want to increase two way trade. The discussions include lowering tariffs on some goods and easing restrictions that have slowed agricultural imports and exports in recent years.

Trade between the two countries dropped sharply after both sides imposed tariffs during earlier disputes. However, China has recently resumed purchases of some American soybeans, wheat, and sorghum. Analysts say lower tariffs could encourage more private Chinese companies to start buying US farm goods again.

China also agreed to address concerns involving American beef and poultry exports. Officials confirmed that hundreds of US beef facilities received registration extensions, allowing them to continue shipping products to China. US officials expect the agreement could lead to billions of dollars in additional farm trade over the next few years.

Related Readings:

Trump Xi Meeting Begins

Trump Xi Talks Keep Markets on Edge

Trade Talks Take Backseat in Trump Xi Summit

Impact on Road Etiquette: Dash Cams Reviewed

Road etiquette used to be a quiet agreement we all *hoped* everyone understood. A courtesy wave when someone lets you merge. A patient pause for a pedestrian who looks unsure. A calm “you go ahead” at a four-way stop. But the reality you see every day? It’s louder. Faster. More distracted. And yes—more emotional.

That’s why so many drivers are turning to a dash cam. Not just for evidence after a crash, but for something subtler: accountability. When you know your choices might be recorded, you don’t only drive differently—you *feel* differently behind the wheel. You think twice before tailgating. You hesitate before honking. You remember there’s a person in the other car, not an obstacle.

This guide walks you through how these small devices are shaping behavior, nudging manners, and sometimes even calming the chaos. And because road etiquette is deeply human, we’ll keep this personal—because YOU are part of this story every time you turn the key.

Why a dash cam changes how YOU drive (even when you swear it doesn’t)

Let’s be honest: you don’t drive the same way when you feel watched. Even if nobody else ever sees the footage, your brain knows there’s a record. That changes the internal dialogue from “Whatever, they deserved it” to “Wait… what if I’m the one who looks reckless?”

A dash camera creates a tiny courtroom in your head. Not in a paranoid way—more like a gentle nudge. You start treating the road like a shared space instead of a battleground. And that’s the first real impact: self-regulation.

This is where etiquette gets interesting. Courtesy isn’t just kindness; it’s also risk management. When you leave more following distance, you’re being polite *and* protecting yourself. When you signal earlier, you’re not only communicating—you’re reducing conflict.

And here’s a small moment many drivers recognize: that split-second before you react. A driver cuts you off, and your body wants to surge with anger. But then you remember the camera. The reaction softens. You breathe. You let it go. That’s etiquette… influenced by technology.

Synchronize your patience: the hidden rhythm of recorded driving

Years ago, we’ve all had that experience where everything on the road feels out of sync—green lights turning red at the worst time, pedestrians appearing right when you’re late, traffic flowing like it’s actively mocking your schedule. One day, you might notice that when you slow down just a bit—stop rushing, stop weaving—you begin to synchronize with the traffic instead of fighting it. Suddenly the merges feel smoother. The braking is gentler. The lane changes become less dramatic.

That’s what a dash cam often encourages: a calmer rhythm.

When you drive like you’re “on record,” you naturally smooth out your inputs. Fewer sharp accelerations. Fewer impulsive moves. More deliberate choices. YOU become predictable—and predictable drivers are safer drivers.

This matters because etiquette isn’t only about being nice. It’s about reducing uncertainty for everyone around you. The kindest driver is often the most consistent driver. When others can anticipate you, they don’t have to guess—and guessing is where danger lives.

Road etiquette, broadly speaking: how cameras shift the culture

There’s a difference between personal improvement and cultural change. A single driver being more polite helps. But when thousands of drivers adopt cameras and start sharing clips, the culture shifts too—broadly, in a way you can almost feel.

Here’s a quick anecdote: you’re sitting with friends, and someone pulls up a video of a near-miss. Everyone leans in, and suddenly you’re not just watching a clip—you’re having a conversation about “what should have happened.” Someone says, “They should’ve yielded.” Another says, “Yeah, but the other guy was speeding.” Without realizing it, etiquette becomes a topic again, not an afterthought.

That’s the wider impact: road manners become discussable, teachable, and—most importantly—visible.

A camera doesn’t just record crashes. It records *choices*. Rolling through stops. Cutting across lanes. Failing to yield. And once choices are visible, social pressure kicks in. People start caring how they look, how they’d be judged, and whether they’d be “that driver” on someone’s screen.

The capricious side of driving—and how footage tames it

Driving can be strangely emotional. One minute you’re fine. The next, a random act flips the switch: a glare, a horn, a sudden lane drift. Human behavior on the road can feel capricious—unpredictable, moody, reactive.

You’ve probably seen it: a driver who’s calm at a red light suddenly becomes aggressive the moment it turns green. Or someone who lets three cars merge kindly, then snaps at the fourth as if patience ran out midstream.

A dash camera doesn’t magically remove capriciousness, but it can reduce it by creating a pause. Not always, not for everyone—but often enough to matter. When you know your reaction is being captured, you’re less likely to indulge that emotional spike. YOU might still feel annoyed, but you’re less likely to *perform* the annoyance in risky ways.

And the best part? That restraint spreads. One calmer move can prevent the next driver from escalating. Etiquette is contagious when someone breaks the cycle.

What to look for when reviewing a dash cam for etiquette-focused driving

If the goal is safer, calmer driving—not just collecting footage—certain features matter more than flashy marketing. When you’re choosing dash cams, you’re really choosing how well it supports accountability and clarity.

Here’s what helps most:

  • Clear video (day and night): If the footage is grainy, it won’t settle disputes or teach lessons. Look for solid low-light performance.
  • Wide dynamic range: Roads have harsh lighting—glare, shadows, headlights. Better dynamic range means fewer “you can’t tell what happened” moments.
  • Reliable loop recording: You don’t want to manage files constantly. The camera should quietly do its job without demanding your attention.
  • G-sensor and incident locking: This protects key clips from being overwritten, so real incidents aren’t lost.
  • Time and date stamping: Small detail, huge difference for insurance and clarity.
  • Parking mode (if YOU need it): Road etiquette doesn’t end when the engine stops. Hit-and-runs in parking lots are where courtesy really gets tested.

Also consider how the device makes you feel. Some drivers want a discreet unit that fades into the background. Others want visible deterrence. Both approaches can influence etiquette—either by quietly improving your own habits or by signaling to others that accountability exists.

Using recordings responsibly: etiquette isn’t about “gotcha” moments

Here’s the tricky part: a camera can encourage good manners, but it can also tempt people into judgment. You don’t want to become the driver who hunts for mistakes like it’s entertainment. Etiquette grows when footage is used to learn, clarify, and protect—not to shame for sport.

What Happens If You’re Partially at Fault in an Accident?

Accidents are rarely black and white. In many cases, more than one person shares some level of responsibility. If you are partially at fault, it does not automatically mean you lose your right to compensation, but it can affect how much you receive. Insurance companies often use shared fault to reduce payouts or shift more blame onto you than necessary. Without understanding how this works, you could accept less than you deserve or weaken your claim.

In this article, we’ll break down what happens when you are partially at fault and how it impacts your compensation.

Reduction of Compensation Based on Your Share of Fault

One of the most direct consequences is the reduction of your compensation based on your percentage of responsibility. This principle is commonly known as comparative fault or comparative negligence. It means that the total amount of damages you are entitled to recover will be decreased according to how much you contributed to causing the accident.

For example, if you are found to be 30% at fault, your final compensation may be reduced by 30%. So, instead of receiving the full settlement amount, you would only receive the remaining percentage. Insurance companies and courts rely on evidence such as police reports, witness statements, and accident reconstruction to determine fault distribution.

This system ensures that each party is held accountable for their share of responsibility. However, even a small percentage of fault can significantly reduce the overall compensation you receive in a personal injury claim.

Comparative Negligence Rules May Apply

When you are partly at fault in an accident, comparative negligence rules often apply to determine how much compensation you can still recover. These rules are used in many legal systems to divide responsibility between all parties involved in the accident fairly. Instead of one person being fully liable, each party is assigned a percentage of fault based on their actions.

Philadelphia wrongful death lawyers at Cousin Benny Injury Lawyers, said, “Under comparative negligence, your compensation is reduced according to your share of responsibility. For example, if you are found 20% at fault, your total recovery will typically be reduced by that same percentage. In some cases, if your fault reaches a certain threshold, you may be barred from recovering damages altogether, depending on the jurisdiction.”

Insurance companies often use these rules to lower settlement amounts by arguing that you contributed more to the accident than claimed. Because of this, proving accurate fault distribution becomes very important in personal injury cases.

Insurance Company May Use Fault Against You

Insurance companies often use that fact against you to reduce or challenge your claim. Their goal is to minimize payouts, so they carefully examine every detail of the accident to assign as much responsibility to you as possible. Even small mistakes or unclear actions can be interpreted as contributing factors to the collision, says Timothy Allen, Sr. Corporate Investigator at Oberheiden P.C.

Insurance adjusters may rely on police reports, witness statements, photographs, and your own recorded statements to build an argument that you share greater responsibility than you actually do. Once they establish partial fault, they can significantly reduce your compensation based on that percentage.

In some cases, insurers may even exaggerate your role in the accident to lower settlement offers further. This is why it is important to be cautious when providing statements and to ensure that all evidence clearly and accurately reflects what actually happened during the incident.

Settlement Value Can Be Significantly Lowered

Steven M Sweat, Personal Injury Lawyers, APC explains, “When you are partially at fault in an accident, the insurance company can significantly lower the settlement value of your personal injury claim. Insurance companies and courts typically reduce compensation based on the percentage of fault assigned to you. This means that even if your injuries are serious, your financial recovery will not be full if you are found to have contributed to the accident in any way.”

For example, if your total damages are valued at a certain amount but you are considered partially responsible, your final settlement will be reduced accordingly. Insurance adjusters often use this situation to negotiate lower payouts, arguing that shared responsibility decreases their liability.

This reduction can affect all types of damages, including medical expenses, lost wages, and pain and suffering. As a result, even a small finding of fault can have a major impact on the overall compensation you receive, making it essential to clearly establish the other party’s responsibility.

Difficulty in Proving Full Liability of Other Party

Stephen J. Bardol, Esq, Managing Attorney of Bardol Law Firm explains, “When you are partly at fault in an accident, it is harder to prove the other party is fully responsible. Insurance companies and defense lawyers often argue that the accident was a shared responsibility, which reduces the strength of your claim. Instead of focusing only on the other driver’s negligence, they will highlight your actions to show that both parties contributed to the incident.”

To establish full liability of the other party, strong evidence is required, such as clear video footage, detailed police reports, eyewitness statements, and accident reconstruction analysis. Without solid proof, it is easy for insurers to shift part of the blame onto you.

This challenge can weaken your negotiating position and reduce the overall compensation you may receive. Even if the other party was primarily at fault, any uncertainty in the evidence can be used to argue shared responsibility, making it harder to secure a fully favorable outcome in your claim.

Conclusion

Being partially at fault in an accident can have a significant impact on your personal injury claim. It not only reduces the amount of compensation you may receive but also gives insurance companies more opportunities to challenge or limit your claim. In some cases, it may even lead to claim denial depending on the degree of responsibility assigned to you. 

Plus, it can make legal negotiations more complex and time-consuming as both sides argue over fault distribution. Because of these challenges, it’s important to carefully present strong evidence and clearly establish the other party’s responsibility.

Trump Xi Meeting Opens With Warm Welcome and Tension

Xi Jinping welcomed Donald Trump with a grand ceremony in Beijing as the two leaders began talks that could shape relations between the world’s biggest economies. Trump praised Xi during the visit, calling him a great leader and describing China as beautiful during public appearances.

Despite the friendly atmosphere, several difficult issues remain unresolved. Trade tensions, tariffs, Taiwan, and the war involving Iran are expected to dominate discussions. Trump is reportedly looking for China’s help in easing tensions around the Strait of Hormuz, while Beijing may push for changes in US policy toward Taiwan.

China also used the visit to show its growing global influence. Business leaders including Elon Musk, Tim Cook, and Jensen Huang joined the trip as both sides discussed expanding economic cooperation.

While no major agreements have been announced yet, both leaders signaled interest in improving ties. Trump invited Xi to visit the White House later this year, while Xi said the goals of strengthening China and making America great can work together. More details from the talks are expected in the coming days.

Related Readings:

Trump Xi Talks Keep Markets on Edge

Trade Talks Take Backseat in Trump Xi Summit

Electric Car Surge in China

The Role of Drone Software Development in Modern Business Automation

Businesses across finance, logistics, construction, and infrastructure management are rapidly investing in automation technologies to improve operational efficiency and reduce costs. Companies seeking scalable digital ecosystems increasingly rely on providers offering drone software development expertise to create intelligent platforms tailored to complex enterprise operations. Companies such as Wezom help businesses integrate drone technologies into broader automation strategies that support real-time analytics, operational visibility, and long-term scalability.

Why Automation Has Become a Business Priority

Modern enterprises operate in an environment where efficiency, speed, and data accuracy directly influence competitiveness. Companies are expected to deliver faster services, reduce operational downtime, and optimize resource allocation while maintaining high levels of reliability and security.

Traditional operational models often rely heavily on manual inspections, paper-based reporting, and fragmented communication between departments. These processes slow decision-making and create unnecessary operational expenses. As businesses grow, the limitations of manual workflows become even more visible, especially for enterprises managing large facilities, infrastructure networks, or distributed operations.

Drone technologies help solve these challenges by introducing automation into everyday business processes. Instead of relying entirely on human labor, organizations can use intelligent drone systems to collect data, monitor assets, and identify operational issues in real time.

Businesses adopting automation strategies typically focus on several key goals:

  • Improving operational efficiency;
  • Reducing long-term infrastructure costs;
  • Increasing process transparency;
  • Accelerating data collection and reporting;
  • Enhancing workplace safety.

Drone software development supports all of these objectives by creating centralized platforms capable of integrating aerial intelligence into larger enterprise ecosystems.

How Drone Technologies Support Business Automation

Modern drone systems are no longer standalone tools used only for aerial photography or surveillance. They have evolved into intelligent operational platforms capable of supporting highly automated business environments.

One of the main advantages of drone technologies is their ability to automate repetitive and resource-intensive tasks. This is especially valuable for industries where inspections and monitoring procedures are performed frequently and across large geographic areas.

For example, infrastructure inspections that once required multiple employees, expensive equipment, and extended operational downtime can now be completed much faster using autonomous drone systems combined with AI-powered analytics.

Drone platforms also improve operational consistency. Manual inspections often depend on human judgment and may vary in quality or accuracy. Automated drone systems follow predefined workflows and capture standardized data sets, reducing inconsistencies and improving reporting reliability.

Another important advantage is accessibility. Drones can quickly reach difficult or hazardous environments where traditional inspections may be dangerous or expensive. This improves safety while allowing businesses to monitor assets more frequently.

Common automation scenarios include:

  • Facility and infrastructure inspections;
  • Remote asset monitoring;
  • Warehouse inventory management;
  • Construction progress tracking;
  • Security surveillance operations.

As organizations continue investing in digital transformation, drone automation is becoming a critical component of enterprise operational strategy rather than a supplementary technology.

The Growing Role of Artificial Intelligence in Drone Platforms

Artificial intelligence has significantly expanded the business value of drone technologies. Without AI, drones primarily function as remote data collection devices. With intelligent analytics, they become systems capable of generating actionable operational insights automatically.

AI-powered software can process large volumes of drone-generated data much faster than human teams. This enables organizations to identify problems early and respond proactively before operational issues escalate into costly disruptions.

For businesses managing critical infrastructure, predictive analytics has become especially important. AI systems can analyze visual patterns, thermal imagery, and equipment performance indicators to detect anomalies that may indicate future failures.

Instead of reacting to incidents after they occur, companies can implement predictive maintenance strategies that improve operational reliability and reduce downtime.

Artificial intelligence also improves automation capabilities through:

  • Intelligent route planning;
  • Automated image recognition;
  • Real-time anomaly detection;
  • Predictive operational forecasting;
  • Automated reporting and analytics.

As machine learning technologies continue advancing, drone platforms will become even more autonomous and capable of handling increasingly complex operational tasks.

Why Businesses Across Industries Are Investing in Drone Automation

The demand for drone software development continues growing because businesses across multiple sectors face similar operational challenges. Organizations need faster access to accurate information while controlling infrastructure costs and improving efficiency.

In the financial and insurance sectors, drone technologies help automate property inspections, assess infrastructure conditions, and accelerate claims processing. AI-powered analytics improve fraud detection while reducing the manual effort required for operational assessments.

Construction companies increasingly rely on drones to monitor project progress and improve resource management. Real-time aerial intelligence helps managers identify delays, monitor safety conditions, and improve communication between teams and stakeholders.

Logistics and supply chain companies use drone systems to improve warehouse operations and inventory visibility. Automated monitoring reduces inefficiencies while supporting better operational planning.

Energy providers also represent a major area of growth for drone automation. Power lines, pipelines, solar farms, and industrial facilities require continuous monitoring to maintain operational stability. Drone inspections help reduce downtime while minimizing human exposure to hazardous environments.

Several factors are accelerating enterprise drone adoption:

  • Growing operational complexity;
  • Rising infrastructure maintenance costs;
  • Increased demand for automation;
  • Expansion of AI-powered analytics;
  • Improvements in cloud infrastructure.

As these trends continue, drone technologies are becoming more deeply integrated into long-term enterprise strategies.

The Limitations of Generic Drone Software

Many businesses initially adopt ready-made drone applications because they appear affordable and easy to implement. However, generic platforms often create limitations once operational requirements become more complex.

Off-the-shelf software is typically designed for broad use cases rather than industry-specific operational needs. This can create significant challenges for enterprises requiring advanced integrations, scalability, or compliance controls.

One of the most common problems is limited flexibility. Generic platforms may not support specialized workflows or custom analytics capabilities required by large organizations.

Integration also becomes a major issue. Enterprise environments often depend on interconnected systems such as ERP platforms, CRM software, cloud environments, and IoT infrastructure. Drone platforms that cannot integrate effectively reduce the overall value of operational data.

Businesses frequently encounter problems such as:

  • Inflexible reporting structures;
  • Security vulnerabilities;
  • Limited automation capabilities;
  • Poor scalability for enterprise operations;
  • Restricted customization options.

Custom drone software development allows businesses to create ecosystems tailored specifically to operational goals, infrastructure requirements, and long-term growth strategies.

Security and Compliance in Enterprise Drone Ecosystems

As enterprises automate more operations, cybersecurity and compliance become increasingly important considerations. Drone systems often process sensitive operational and infrastructure data that must be protected against unauthorized access or security breaches.

Industries such as finance, logistics, and critical infrastructure management operate under strict regulatory requirements. Businesses in these sectors need platforms that support secure data management and transparent operational controls.

Modern enterprise drone platforms typically require:

  • Secure cloud architecture;
  • Role-based user access management;
  • Data encryption standards;
  • Audit tracking capabilities;
  • Regulatory compliance reporting.

Organizations investing in custom software environments gain greater control over how data is stored, processed, and shared across operational systems.

Security considerations are becoming even more important as businesses expand automation initiatives and integrate drones into broader enterprise ecosystems.

The Future of Drone Software Development

Drone technologies will continue evolving alongside advancements in AI, cloud computing, and enterprise automation. Over the next several years, businesses are expected to adopt increasingly intelligent drone ecosystems capable of operating with minimal human intervention.

Autonomous drone fleets, edge computing, and real-time analytics will significantly expand operational capabilities. Companies will be able to process data faster, improve predictive decision-making, and automate complex infrastructure management tasks at scale.

Future drone platforms will likely focus on:

  • Autonomous operational workflows;
  • Advanced AI-assisted analytics;
  • Real-time infrastructure monitoring;
  • Integration with digital twin technologies;
  • Predictive maintenance automation.

As competition increases and operational efficiency becomes even more important, businesses investing early in scalable drone ecosystems will gain stronger long-term advantages.

Conclusion

Drone software development is becoming a critical part of modern business automation strategies. Enterprises across finance, logistics, construction, and infrastructure management increasingly use drone technologies to improve operational visibility, automate repetitive tasks, and reduce long-term operational costs.

While generic software platforms may support basic drone operations, modern enterprises require scalable ecosystems capable of integrating with broader business infrastructure. Custom solutions provide greater flexibility, stronger security, and more advanced analytics tailored to specific operational goals.

As automation, AI, and cloud technologies continue reshaping enterprise operations, drone platforms will play an increasingly important role in helping businesses improve efficiency, scalability, and long-term digital transformation outcomes.

AI is Reshaping the Labor Market, but Not How People Think

By Dr. Gleb Tsipursky

The AI jobs debate has been stuck in two bad extremes. One side insists a white-collar wipeout is already underway. The other waves away every concern because the unemployment rate has not exploded. In Anthropic’s new report, “Labor market impacts of AI: A new measure and early evidence,” Maxim Massenkoff and Peter McCrory cut through that noise with something far more valuable: a way to track where AI is actually entering work, where it still falls short, and where the earliest damage may appear first.

AI is already reshaping the labor market, but the strongest signal today is weaker entry-level hiring in exposed occupations, not a mass unemployment shock

They argue that labor market analysis needs to move beyond abstract capability and toward observed use. Their central contribution is a metric called “observed exposure,” which combines theoretical task feasibility with real-world Claude usage in professional settings, then weights automated use more heavily than simple assistance. That framing matters because AI disruption will not arrive as a single cinematic layoff event. It will show up through specific tasks, specific occupations, and specific hiring bottlenecks long before the broad labor market fully registers it.

Thus, AI is already reshaping the labor market, but the strongest signal today is weaker entry-level hiring in exposed occupations, not a mass unemployment shock. The evidence is serious. The panic is premature. The implications are immediate.

The Most Important Shift Is Measuring Actual Exposure, Not Hypothetical Potential

The report’s biggest achievement is methodological. Instead of asking only what large language models could do, it asks what they are actually doing in work-related settings. The authors build observed exposure from three ingredients: O*NET task data, Anthropic usage data from the Economic Index, and the theoretical exposure framework from “GPTs are GPTs”. That move instantly makes the discussion more grounded.

The report explains that a task counts as covered when it is theoretically feasible with an LLM and has seen sufficient work-related usage in Claude traffic. Fully automated implementations receive full weight, while augmentative use receives half weight, and those task-level values are then averaged up to occupations using time shares. This is a much stronger lens than simple technical possibility because firms do not adopt tools just because a benchmark says they can. Legal risk, workflow friction, verification needs, and software integration all slow deployment in the real world.

That distinction helps explain why theoretical exposure still overstates immediate labor market risk. In “GPTs are GPTs”, Tyna Eloundou, Sam Manning, Pamela Mishkin, and Daniel Rock estimated that around 80 percent of the U.S. workforce could have at least 10 percent of their tasks affected by LLMs, while roughly 19 percent could see at least 50 percent of tasks affected. The paper mapped enormous potential, but it did not claim that firms had already deployed those capabilities at scale. The Anthropic report shows that this gap between capability and deployment is still large. In Computer & Math occupations, theoretical exposure is 94 percent, but observed current coverage in Anthropic’s data is just 33 percent.

That gap is the story executives should be watching. AI is powerful enough to matter now, but still constrained enough that labor market effects will emerge unevenly. That gives employers and policymakers a narrow but real window to respond before abstract risk turns into entrenched displacement.

The Jobs Under Pressure Are Real, but Broad Unemployment Still Has Not Broken

The report’s occupational ranking is striking because it shows where AI is already most present in real workflows. Computer programmers top the list at 75 percent observed coverage. Customer service representatives come next, followed by data entry keyers at 67 percent. At the other end of the spectrum, 30 percent of workers are in occupations with zero measured coverage, including cooks, mechanics, lifeguards, bartenders, and dishwashers. AI is not sweeping across the labor market in one uniform wave. It is advancing first through digital, language-heavy, structured work.

That pattern lines up with outside research. The online vacancies study by Daron Acemoglu, David Autor, Jonathon Hazell, and Pascual Restrepo found that establishments adopting AI reduced hiring in non-AI positions and changed skill requirements in the remaining postings, even while aggregate employment effects remained too small to detect clearly. The message is simple: labor market change often appears in hiring behavior and job design before it appears in top-line unemployment numbers.

That is exactly what the Anthropic report finds. Using Current Population Survey data, the authors report no systematic increase in unemployment for workers in the most exposed occupations since late 2022. Their difference-in-differences estimate is “small and insignificant,” and they note that a sizable white-collar shock should have been detectable in this framework if it had already occurred. That is a major result because it directly challenges the claim that generative AI has already produced broad labor market collapse.

Other recent work points in the same direction. The Budget Lab at Yale’s running labor market tracker says current measures of AI exposure, automation, and augmentation show no clear relationship with broad changes in employment or unemployment so far, and its later updates through late 2025 continue to describe the patterns as flat or modest. Together, these findings support a more disciplined conclusion: AI pressure is real, but the economy has not yet absorbed it as a broad unemployment shock.

The Clearest Early Warning Signal Is Entry-Level Hiring

The sharpest finding in the report is about younger workers. For workers ages 22 to 25, entry into highly exposed occupations fell by about half a percentage point, which the authors translate into a 14 percent drop in job-finding rates in the post-ChatGPT period relative to 2022. They are careful with the claim and note that the estimate is only barely statistically significant, but it is the strongest sign in the paper that disruption may already be visible in the hiring pipeline.

That result becomes much more persuasive when placed alongside outside evidence. In “Canaries in the Coal Mine?”, Erik Brynjolfsson, Bharat Chandar, and Ruyu Chen use ADP payroll data and find that early-career workers ages 22 to 25 in the most AI-exposed occupations experienced a 13 percent relative decline in employment, with the adjustment driven primarily by slower hiring rather than a surge in separations. The symmetry between the two studies matters. Different data sources. Similar warning sign.

When AI strips away the tasks that once trained junior workers, the labor market does not just lose jobs.

This is where the labor market story gets serious. A stable unemployment rate can hide a shrinking career ladder. If firms keep senior workers, automate pieces of junior work, and hire fewer newcomers, then the damage appears first in the on-ramp. That hurts recent graduates, career switchers, and the long-run development of expertise inside firms. It also fits the logic in “Expertise”, where David Autor and Neil Thompson argue that the labor impact of automation depends heavily on what happens to the expertise value of the tasks that remain. When AI strips away the tasks that once trained junior workers, the labor market does not just lose jobs. It loses apprenticeship.

That concern also helps explain why some markets show faster pain than the broader economy. In Organization Science, Xiang Hui, Oren Reshef, and Luofeng Zhou find that freelancers in highly affected occupations suffered reductions in both employment and earnings after the release of generative AI tools. Online freelance markets are contestable, transparent, and easy to benchmark, so substitution shows up faster there. Traditional employment markets move more slowly, but they are not immune.

The strongest reading of the report is neither doom nor denial. AI has not yet triggered a broad unemployment crisis. That is genuine good news. But exposed occupations are already measurable, projected growth is somewhat weaker in those jobs, and the earliest visible strain is showing up where careers begin, not where they peak. That is the signal leaders should respect. The winners will be the organizations that redesign work around human judgment before the hiring pipeline thins out beneath them.

About the Author

Dr. Gleb TsipurskyDr. Gleb Tsipursky was named “Office Whisperer” by The New York Times for helping leaders overcome frustrations with Generative AI. He serves as the CEO of the future-of-work consultancy Disaster Avoidance Experts. Dr. Gleb wrote seven best-selling books, and his two most recent ones are Returning to the Office and Leading Hybrid and Remote Teams and ChatGPT for Leaders and Content Creators: Unlocking the Potential of Generative AI. His cutting-edge thought leadership was featured in over 650 articles and 550 interviews in Harvard Business Review, Inc. Magazine, USA Today, CBS News, Fox News, Time, Business Insider, Fortune, The New York Times, and elsewhere. His writing was translated into Chinese, Spanish, Russian, Polish, Korean, French, Vietnamese, German, and other languages. His expertise comes from over 20 years of consulting, coaching, and speaking and training for Fortune 500 companies from Aflac to Xerox. It also comes from over 15 years in academia as a behavioral scientist, with 8 years as a lecturer at UNC-Chapel Hill and 7 years as a professor at Ohio State. A proud Ukrainian American, Dr. Gleb lives in Columbus, Ohio.

EDITOR'S PICK OF THE WEEK

China economic growth

China’s Challenging Search for a New Model of Economic Growth

By Danny Leipziger China cannot continue to rely on exports to drive its growth, but what are the alternatives? China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...

WISE DECISION MAKER GUIDE

POWER INFLUENCERS

Emerging Trends

The Future of Global Trade