AI’s first major economic divide is not emerging between companies that can buy tools and those that cannot. It is emerging between workplaces where managers redesign work and those where managers merely authorize accounts.
The AI adoption gap already looks like a management test: a Brookings research paper that 43% of U.S. workers used AI for their jobs in 2026, compared with 32% among workers in six European countries, with Britain at 36% and Italy at 26%.
On a narrower firm measure, 7% of U.S. firms used AI in production in 2025 versus 4% of EU firms, while Eurostat’s broader enterprise survey found that 13.5% of EU enterprises with at least 10 workers used AI technologies in 2024.
AI is not repeating the information technology revolution exactly, but it is rhyming with it.
These numbers do not prove that Americans are more creative, or that Europeans distrust technology. They point to a more uncomfortable truth: AI rewards organizations that already know how to reward initiative, spread good practice and hold people accountable.
The Tools Are Available But The Workplaces Are Not
Software spreads faster than management competence. The U.S. Census Bureau found that AI adoption among U.S. businesses hovered between 17% and 20% from December 2025 to May 2026, with 37% of firms employing at least 250 people reporting AI use. The question is what happens after adoption. A chatbot account does not redesign a workflow, challenge a weak supervisor or make a team share better prompts.
That is why the most important AI question inside a firm is rarely “Who has access?” It is “Who is expected to experiment, measure and improve?”
The link between AI and Management Practices is already visible. St. Louis Fed economists report that country-level AI adoption in production processes correlates strongly with World Management Survey scores, and that workers in firms with stronger performance incentives, merit-based promotion and willingness to address poor performance are much more likely to use AI.
The pattern is plain: generative AI use becomes productive when managers make it part of the job, not when employees quietly smuggle it into email, code and analysis.
The Old Productivity Lesson Is Back
Europe has seen this movie before. The European Central Bank notes that U.S. labor productivity per hour grew about 50% from 1995 to 2019, while the euro area grew 28%, and it links part of that productivity gap to America’s stronger ability to create and use digital technologies in production. AI is not repeating the information technology revolution exactly, but it is rhyming with it.
The classic evidence comes from Nicholas Bloom, Raffaella Sadun and John Van Reenen, who found in the American Economic Review that U.S. multinationals in Europe gained more from IT partly because of tougher people management. Their work on technology adoption showed that computers did not magically lift productivity; organizations had to change incentives and routines around them.
Another report reached a similar conclusion in their study of police departments, where organizational change through CompStat-style management made IT investments productive while computers alone did little.
That lesson should make executives nervous. AI vendors sell speed. Boards buy “transformation.” Workers test tools in the cracks between meetings. But the history of IT says the winners are not the earliest purchasers. They are the firms that turn experiments into operating systems.
Europe’s Problem Is An Incentive Problem
The hardest AI bottleneck is managerial courage. One NBER paper argues that Italy’s productivity stagnation stemmed largely from firms’ inability to exploit the ICT revolution, with weak meritocracy in selecting and rewarding managers playing a central role. That diagnosis of European productivity now matters for AI because generative tools magnify the value of judgment, delegation and performance feedback.
The upside is real. Another NBER study of customer support agents found that access to a generative AI assistant increased productivity by 14% on average, with much larger gains for novice and lower-skilled workers.
That kind of AI productivity does not come from replacing everyone with software. It comes from codifying better practice, shortening learning curves and helping less experienced employees perform closer to expert level. The OECD’s work on digital transformation makes the same policy point from another angle: firms need training, organizational capacity and better diffusion mechanisms, not just slogans about innovation.
Firms need training, organizational capacity and better diffusion mechanisms, not just slogans about innovation.
The management agenda is therefore brutally practical. Reward employees who find useful AI applications. Promote managers who can turn scattered experiments into shared routines. Stop pretending that every department should invent its own AI playbook in isolation. And treat AI governance as a performance system, not a compliance binder.
Leaders looking for a broader, accessible framework can start with a practical AI strategy that treats adoption as an organizational challenge rather than a tool rollout.
The next AI race will be won inside firms before it appears in national statistics. The winners will not simply have better models. They will have better bosses, clearer incentives, faster learning loops and fewer excuses for letting powerful tools sit unused. Europe does not lack talent. It lacks enough organizations built to turn talent into disciplined experimentation. That is the real gap AI is exposing.
From Gaza and beyond, Israeli authorities and security forces have deliberately targeted Palestinian children. It is the topic of a new UN report.
When I was working on The Fall of Israel (2024) and particularly The Obliteration Doctrine (2025), what I found most repulsive was the targeting of children in the Gaza Strip. By 2024, the testimonies of health professionals on location indicated that the deaths of many children in Gaza were not just collateral damage, but outcomes of deliberate, targeted actions.
It is a condemnation that casts a long dark shadow over the entire Israeli war government and its international collaborators, arms suppliers and financiers.
The testimony of Dr. Feroze Sidhwa, a young American trauma and general surgeon who had volunteered in Palestine including the European Hospital in Khan Younis, was particularly compelling. “I’ve seen violence and worked in conflict zones,” Sidhwa said. “But of the many things that stood out about working in a hospital in Gaza, one got to me: Nearly every day I was there, I saw a new young child who had been shot in the head or the chest, virtually all of whom went on to die.”
The statement of Dr. Sidhwa, who subsequently became one of the endorsers of my book on The Obliteration Doctrine, was supported by dozens of other remarkable and courageous medical volunteers in Gaza. These testimonies, in turn, have been supported by many reports of multiple international NGOs and multilateral organizations.
So, the latest report of the UN Independent International Commission is hardly new. Nonetheless, it is among the most consequential documents to emerge from the Gaza war. Its conclusion is stark: Israeli authorities and security forces have deliberately targeted Palestinian children. These actions, the Commission argues, constitute genocide, crimes against humanity, and war crimes.
The Commission’s findings
The Commission’s report concludes that the deliberate targeting of Palestinian children is not incidental collateral damage but part of a recurring pattern of conduct. In line with the Genocide Convention, it argues that such actions are a key indicator of genocidal intent because they strike at the future existence of the Palestinian people.
According to the inquiry, more than 20,000 Palestinian children were killed between October 2023 and October 2025, representing roughly 30 percent of all fatalities, while over 44,000 were injured. Even after the October 2025 ceasefire, children reportedly continue to be killed and maimed.
The Commission cites cases involving sniper fire, quadcopter drones, precision-guided munitions, and high-yield bombs used in densely populated civilian areas. It argues that the nature of these weapons systems often allowed operators to identify their targets, including whether they were children.
Israel has rejected the findings as biased and defamatory.
Regardless of political positions, the significance of the report lies in its accumulation of evidence, legal analysis, forensic testimony, and witness accounts. It represents one of the most comprehensive international investigations yet conducted on the impact of the war on children.
It is a condemnation that casts a long dark shadow over the entire Israeli war government and its international collaborators, arms suppliers and financiers.
Children and the logic of genocide
In The Obliteration Doctrine, I showed that modern warfare in Gaza evolved beyond traditional military objectives toward the destruction of the social foundations of Palestinian existence. The Commission’s findings reinforce this interpretation.
Historically, genocide scholars have emphasized that attacks on children occupy a unique place in genocidal campaigns. The 1948 Genocide Convention identifies not only direct killing but also the infliction of conditions calculated to destroy a protected group. In Gaza, famine served the same genocidal function as starvation in the Warsaw ghetto.
Children embody demographic continuity, cultural reproduction, and collective future. Consequently, systematic violence against children has appeared repeatedly in cases later recognized as genocide, from the Armenian genocide to Rwanda.
The Commission explicitly states that targeting children attacks “the very capacity of the Palestinian people to exist and determine their future.” Its findings connect killings to broader patterns: destruction of schools, hospitals, pediatric facilities, neonatal care units, food systems, and water infrastructure.
That’s the ultimate objective: the genocide and ecocide of Palestine, its culture and children. Israel’s devastation of Lebanon follows in the footprints.
From an empirical perspective, the cumulative effect is measurable. Public-health research consistently demonstrates that childhood exposure to mass violence produces lifelong deficits in physical health, educational attainment, psychological resilience, and economic productivity.
Israel did not triumph in Gaza. Moral darkness did.
Human cost beyond death statistics
Death tolls alone understate the catastrophe. The Commission reports more than 44,000 wounded children.
The result is not merely a humanitarian emergency. It is the systematic destruction of human development on a societal scale.
Gaza now reportedly has one of the world’s highest concentrations of child amputees. Thousands face permanent disability from burns, blast injuries, spinal trauma, vision loss, and neurological damage. Worse, Israel has denied treatment to thousands of Gazans who lost limbs in Israeli attacks.
Research from conflicts in Syria, Iraq, Afghanistan, and Bosnia demonstrates that severely injured children often experience decades of adverse outcomes.
Rates of post-traumatic stress disorder, depression, anxiety disorders, and developmental impairments can remain elevated throughout adulthood. Educational interruptions reduce lifetime earnings. Family structures collapse under caregiving burdens.
The Commission also documents starvation, disease outbreaks, displacement, and collapse of medical services. Such conditions affect not only present survival but the health of future generations through malnutrition, impaired fetal development, and maternal health crises.
The result is not merely a humanitarian emergency. It is the systematic destruction of human development on a societal scale.
The ultimate question raised by the UN report is therefore not only what happened to Gaza’s children. It is whether the international community is willing to preserve the principle that children remain beyond the reach of war itself.
For if that principle fails in Gaza, it will not survive elsewhere.
This is a highly abbreviated version of the original commentary that was released by Informed Comment (US) on June 26, 2026.
Dr. Dan Steinbockis an internationally recognized strategist of the multipolar world and the founder of Difference Group. He has served at the India, China and America Institute (USA), Shanghai Institutes for International Studies (China) and the EU Center (Singapore). He is also the author of The Fall of Israel and The Obliteration Doctrine. For more, see https://www.differencegroup.net
Life rarely moves in a straight line. Major milestones such as starting a family, changing careers, preparing for retirement, selling a business, or receiving an inheritance can significantly alter a person’s financial picture. While these moments often bring excitement and opportunity, they can also introduce uncertainty and complexity.
Financial professionals frequently observe that individuals are most likely to seek guidance during periods of transition. These pivotal moments often require important decisions that can have long-term consequences for financial security, retirement readiness, tax planning, and wealth preservation.
As a result, thoughtful financial planning is often most valuable when life is changing the fastest.
Navigating Uncertainty with Confidence
Major life transitions often involve both emotional and financial considerations. A new career opportunity may increase income but introduce new retirement planning decisions. The sale of a business can create significant wealth while raising questions about taxes and long-term investment strategies. Retirement may provide greater freedom while requiring a new approach to income management.
Without a clear plan, individuals may find themselves reacting to circumstances rather than proactively preparing for them.
Financial planning helps create structure during uncertain periods by providing a framework for evaluating options, identifying risks, and aligning decisions with long-term goals.
The Value of Long-Term Thinking
One of the most common challenges people face during transitions is maintaining a long-term perspective.
Short-term decisions often feel urgent, but their impact may extend for years or even decades. Whether adjusting an investment strategy, updating estate plans, or reevaluating retirement goals, thoughtful planning helps ensure that immediate choices support future objectives.
Financial advisors often encourage clients to focus on both current needs and long-term aspirations, creating plans that can adapt as circumstances evolve.
Building a Financial Strategy Around Personal Goals
No two individuals share the exact same financial goals, family situations, or professional paths. For this reason, personalized planning remains an important component of effective wealth management.
A comprehensive financial strategy may include:
Retirement planning
Investment management
Tax-efficient strategies
Estate planning coordination
Risk management
Education funding
Wealth preservation
Organizations such as Franklin Wealth Management work with individuals and families to help create customized financial strategies designed to support both present needs and future objectives.
Rather than focusing solely on investments, comprehensive planning considers the broader financial picture and how various decisions work together to support long-term success.
Preparing for Retirement and Beyond
Retirement remains one of the most significant financial transitions many people will experience.
The shift from accumulating assets to generating sustainable income often requires careful planning and ongoing evaluation. Healthcare costs, market volatility, longevity considerations, and legacy goals can all influence retirement outcomes.
Individuals who begin planning early often have greater flexibility and a wider range of options when retirement approaches.
Regular reviews and adjustments can also help ensure that financial strategies remain aligned with changing circumstances and evolving goals.
The Importance of Trusted Guidance
Financial information has never been more accessible, yet many individuals still find it challenging to determine which strategies are most appropriate for their unique situations.
Working with an experienced Financial Advisor Chattanooga residents can trust may help provide clarity during complex financial decisions. Professional guidance can offer perspective, accountability, and a disciplined approach that supports informed decision-making over time.
While every financial journey is different, having a trusted advisor can help individuals navigate both opportunities and challenges with greater confidence.
Looking Ahead
Life’s biggest transitions often bring both uncertainty and opportunity. Whether preparing for retirement, changing careers, growing a family, or managing significant financial events, thoughtful planning can help transform uncertainty into a clear path forward.
By focusing on long-term goals, maintaining flexibility, and seeking professional guidance when appropriate, individuals can make more informed decisions and build greater confidence in their financial future.
The most successful financial plans are often those designed not only for where life is today, but for where it may lead tomorrow.
Rescue teams across Venezuela worked through the night on Thursday as they searched for hundreds of people believed to be trapped beneath collapsed buildings after two powerful earthquakes struck near Caracas. Officials said hospitals had received around 235 bodies, while thousands of families were forced from their homes. The two quakes, measuring 7.2 and 7.5 in magnitude, hit less than a minute apart, causing widespread destruction in the capital and nearby coastal communities.
La Guaira, home to the country’s main airport, suffered some of the worst damage. Authorities said about 70,000 families in the state had been affected, while at least 250 buildings were damaged or destroyed. Emergency crews, volunteers, and local residents searched through piles of concrete as aftershocks continued. In many neighborhoods, people used their hands to clear debris while waiting for heavy equipment to arrive. The airport remained closed because of structural damage.
Many survivors described scenes of panic as buildings shook and people rushed into the streets. Others spent the night outdoors after their homes became unsafe. Some families were still waiting for news of missing relatives, while a public website created by opposition groups listed more than 46,000 people as unaccounted for, although those figures have not been independently verified.
Countries around the world have offered assistance, with rescue teams expected to arrive in the coming days. The United States eased sanctions to allow earthquake-related aid, while the United Nations began coordinating international relief efforts. Experts warned that the death toll could continue to climb as search operations move deeper into the hardest-hit areas.
If most of your team are contractors, do not choose a global payroll provider by country count alone. First check whether the provider can handle the work around contractors: onboarding, agreements, work approvals, documents, records for finance, and support for internal review.
“Global payroll” usually means employee payroll. Salaries, payslips, local payroll reporting, tax-related processes. That may be exactly what you need if you have employees in several countries.
Contractors are different. A contractor relationship is built around services, deliverables, acceptance, documents, and records. If the provider only helps process compensation, the rest of the work stays with your finance, HR, legal, or operations team.
Before choosing a provider, answer five questions:
Who are you managing: employees, EOR hires, contractors, freelancers, or vendors?
What documents do you need before and after the work is accepted?
Who approves the contractor workflow inside the company?
Can finance and legal teams see a clear record of each engagement?
What will the process cost after fees, add-ons, implementation, and manual work?
If the answer is mostly about contractors, you may not need a broad global payroll system. You may need a contractor operations platform.
4dev.com fits that case. It helps companies organize contractor workflows, documentation, supporting records, and compliance-related processes across countries. It is not a full employee payroll suite, and it should not be evaluated as one.
What companies usually mean by global payroll
“Global payroll” is a broad search term. It can mean several different things.
For one company, it means running salaries for employees in several countries. For another, it means hiring through an Employer of Record because there is no local entity. For a third, it means working with contractors abroad and trying to keep documents, approvals, and records under control.
These are not the same problem.
In the strict sense, global payroll is about employee payroll across countries. It covers salary calculations, payslips, local payroll reports, tax-related workflows, and coordination with local payroll partners.
That matters because many contractor-heavy teams start with the same search query, but their real task is different. They do not need only payroll processing. They need to know who signed the agreement, what work was accepted, which documents exist, who approved the workflow, and what finance can show later if someone asks.
So before comparing providers, write down what you actually need to manage.
If the answer is salaries and local payroll rules, look at global payroll providers.
If the answer is employment without a local entity, look at EOR.
If the answer is contractor agreements, supporting records, approvals, and documentation, global payroll software may be only part of the picture.
Why contractor-heavy teams need a different approach
A company with 80 employees and a company with 80 contractors may search for the same thing: global payroll provider. But they need different systems behind the search.
Employees usually sit inside a payroll process. There is a salary, a payroll calendar, local reporting, benefits in some countries, and employment documents.
Contractors sit inside a service process. There is an agreement, a scope of work, accepted deliverables, supporting documents, approvals, and records for finance.
This is where many teams get stuck. The company finds a provider that can support global payroll, but contractor work still lives in email, spreadsheets, chats, and separate folders. Finance has to ask for documents. Legal has to check the structure manually. Operations has to chase approvals.
The provider may be good at payroll. The problem is that the company did not only have a payroll problem.
For contractor-heavy teams, the provider should help answer practical questions:
Has this contractor completed onboarding?
Is the agreement signed?
What work was approved?
Are the supporting documents stored in one place?
Can finance export what it needs?
Can legal review the process without rebuilding the story from messages?
If those questions matter in your company, compare providers by contractor workflow depth, not only by payroll coverage.
Global payroll, EOR, contractor operations, or AP automation: what do you actually need?
Do not start with a vendor list. Start with the work model.
If you have employees in countries where your company already has entities, global payroll may be the right category. You need salary processing, local payroll reporting, payslips, and country-specific payroll administration.
If you want to employ someone in a country where you do not have an entity, look at Employer of Record. EOR is built for employment. The provider becomes the legal employer and handles the local employment setup.
If most of the team are independent contractors, look at contractor operations. The main workflow is agreement, onboarding, service delivery, approval, documents, and records. Payroll features may help at the end of the process, but they do not replace the contractor workflow itself.
If you work mostly with agencies, suppliers, or vendors, the right category may be AP automation. That is a finance workflow, not a workforce workflow.
A simple way to decide:
Employees on your own entities: global payroll.
Employees without your own entity: EOR.
Independent contractors and freelancers: contractor operations.
Agencies and suppliers: AP automation.
Mixed teams may need more than one tool. That is normal. The mistake is forcing every relationship into one software category because the search query says “global payroll provider.”
What to check in a global payroll provider if you work with contractors
If a provider says it supports contractors, check what that support includes. The word “contractor” on a pricing page is not enough.
Start with onboarding. Can the contractor submit the required details and documents inside the platform, or will your team still collect everything by email?
Then check agreements. Does the provider support contractor agreements, scopes of work, or other documents that explain the service relationship? If every template has to be managed outside the system, the workflow is only partly covered.
Look at approvals. Contractor work usually needs someone to confirm that the task, milestone, or service was accepted. If approval happens in Slack and the record lives somewhere else, finance will still have to rebuild the context later.
Check reporting. Your finance team should be able to see what happened: who the contractor is, what was approved, which documents exist, and what records can be exported.
Also check support. Contractor workflows often involve finance, legal, operations, and the contractor. If the provider cannot explain the process clearly to all sides, implementation will slow down.
Good questions to ask on a demo:
What exactly happens when a new contractor is invited?
What documents are collected or generated?
Where are approvals recorded?
Can finance export all supporting records?
Can legal review the workflow before launch?
What happens if our internal process changes?
Which contractor workflows are supported in each country?
A global payroll provider may still be the right choice. But if contractors are a large part of your team, do not evaluate the provider only as payroll software. Evaluate it as an operating layer for contractor work.
Contractor documentation and compliance: the part you should not skip
Contractor work creates paperwork. If the paperwork is missing or scattered, the company carries the problem later.
The basics are usually clear: agreement, contractor details, scope of work, approval, invoice or other supporting document, and a record of the completed service. The hard part is keeping all of this consistent when the team grows, countries change, and several people approve the same workflow.
This is why documentation should be checked before pricing. A low monthly fee does not help much if finance still has to chase files at the end of every period.
Look at the process from the finance team’s side.
Can they open one contractor record and understand what happened? Can they see the agreement, the accepted work, the supporting documents, and the approval trail? Can they export the materials without asking HR, legal, and operations to search through chats?
Legal will look at the same process differently. They need to understand whether the contractor relationship is documented as a service relationship, not as unmanaged employment-like work. They will also want to review templates, responsibilities, and the way records are stored.
So the question is not only “Does the provider support contractors?” The better question is:
What will we be able to show six months later?
If the answer depends on someone finding a message, a spreadsheet row, and a file in a shared folder, the provider has not really solved the documentation problem.
Pricing, coverage, and support: questions to ask before choosing a provider
After workflow and documentation, check the commercial and operational details. This is where many vendor comparisons become misleading.
Country coverage is the first example. A provider may support many countries, but not every product works the same way in every country. Payroll, EOR, contractor workflows, documents, and support may have different coverage. Ask about the exact workflow you need, not only the country list.
Pricing also needs a closer look. One provider charges per employee. Another charges per contractor. Another uses custom pricing or adds fees for extra workflows. The headline price may not include implementation, support, compliance review, integrations, or document handling.
For a contractor-heavy team, internal work is part of the cost too. If your team still spends hours collecting documents, checking approvals, and preparing records for finance, the cheaper tool may not be cheaper in practice.
Ask these questions before choosing:
Which countries are supported for contractor workflows, not just payroll?
What is included in the base price?
Are there setup fees, add-ons, or minimum monthly fees?
What documents and reports can we export?
Who helps during onboarding?
How fast does support respond when finance or legal has a question?
Can the provider work with our existing HR, finance, or accounting tools?
The goal is not to find the longest feature list. The goal is to choose a provider that fits your team’s actual process without creating extra manual work.
Where 4dev.com fits for contractor-heavy teams
4dev.com fits companies that work with independent contractors across countries and need a cleaner way to run contractor operations.
The typical case is not “we need a full employee payroll suite.” It is closer to this:
the team already has contractors in several countries;
finance needs documents and records in one place;
legal wants a clearer contractor workflow;
operations wants fewer manual checks;
contractors need a predictable onboarding process.
4dev.com helps organize that workflow: contractor onboarding, agreements, supporting documents, records, workflow administration, and compliance-related processes.
This matters when the company already has HR and finance tools, but contractor work is still managed across spreadsheets, email threads, chats, and folders. In that setup, adding a broad payroll platform may not fix the real bottleneck.
4dev.com is more focused. It is built around contractor workflows, not around full employee payroll management.
That also means it is not the right fit for every company. If your main need is salary payroll for employees, benefits administration, or a full HRIS, you should compare global payroll, EOR, or HR platforms directly.
But if the problem is contractor administration across countries, 4dev.com belongs on the shortlist. Not as a replacement for every HR or payroll tool, but as the contractor operations layer that keeps agreements, documents, approvals, and records under control.
FAQ
What is a global payroll provider?
A global payroll provider helps companies run payroll-related processes across countries. Usually this means salary calculations, payslips, local payroll reporting, tax-related workflows, and coordination with local partners.
Some providers also offer EOR, contractor management, HR tools, or finance workflows. That is why the label can be confusing. Always check which exact workflow the provider is built for.
Is global payroll the same as contractor management?
No. Global payroll is usually built around employees and salary payroll.
Contractor management is about independent contractor relationships. The work usually includes onboarding, agreements, scopes of work, approvals, documents, and records.
A provider can offer both, but they are not the same thing.
Do independent contractors need payroll?
Not in the same way employees do.
Contractors usually need a documented service workflow: agreement, contractor details, approved work, supporting documents, and records for finance or legal review.
If a platform only processes compensation but does not help with the documents and approvals around the contractor relationship, your team may still have a manual admin problem.
What should contractor-heavy teams check before choosing a provider?
Check the contractor workflow first.
Can the provider onboard contractors, organize agreements, record approvals, store supporting documents, and give finance a clean export? Can legal review the process? Does support understand contractor operations, not only payroll?
After that, compare country coverage, pricing, integrations, and support.
When is a contractor operations platform better than global payroll software?
A contractor operations platform is usually a better fit when most of the work is around independent contractors, not employees.
If your main problems are contractor onboarding, agreements, approvals, documentation, supporting records, and compliance-related review, global payroll software may be too broad or too employee-focused.
In that case, a focused contractor operations platform can cover the workflow more directly.
Gold is often described as if it has a single, universal price. Financial news tickers quote one number, updated by the second, and that number anchors how most people imagine the market works. For institutions trading unallocated metal in the wholesale market, it is a fair approximation. For the individual buying a coin or a small bar, it is close to a fiction.
What retail buyers actually face is a two-tier market. There is the spot price, the wholesale reference, and then there is the retail price, which includes a premium that varies by product, by seller, by payment method, and by the mood of the market on a given week. The distance between those two tiers is where most of the cost, and most of the confusion, lives.
Spot is a reference, not a receipt
The spot price reflects the value of a notional ounce in the deep, liquid wholesale market. No private buyer transacts there. To own physical gold, you buy a manufactured product: a minted coin, a refined bar, a fractional piece. Each carries a premium over spot that covers fabrication, distribution, dealer margin, and the cost of moving insured metal through a supply chain.
That premium is not a fixed surcharge. It behaves like its own small market, responding to demand, product scarcity, and supply-chain friction. In calm periods it compresses. When retail demand surges, it can widen sharply even as the spot price holds steady, which means two buyers purchasing “an ounce of gold” weeks apart can pay materially different totals for the same metal.
The premium ladder
The most consistent pattern in retail gold is the inverse relationship between unit size and premium. Fixed per-unit costs of fabrication, assaying, packaging, and secure transport are spread across more metal in a larger bar, so the percentage premium falls as the unit grows. A small fractional coin can carry a premium several times that of a large bar containing the identical purity of gold. The difference is entirely manufacturing and logistics, not the metal itself.
Sovereign coins, privately minted bars, and collectible issues each sit at different rungs of this ladder. A buyer focused only on the spot price has no way to see the ladder at all, and tends to default to whichever product a familiar seller happens to promote.
Fragmentation and information asymmetry
The retail bullion market never developed a single transparent venue. Dealers price independently. Some quote a premium over spot, some quote a flat figure, and some reveal shipping and payment-method surcharges only at checkout. The result is genuine dispersion: the same product can carry meaningfully different all-in costs across reputable sellers at the same moment.
This is a textbook information asymmetry. The seller knows their full cost structure; the buyer usually sees one quote at a time and lacks an easy way to compare like with like while the spot price moves underneath them. In most markets, that kind of opacity quietly transfers value from the less-informed party to the better-informed one. Gold is no exception.
Why it matters for allocators
For anyone treating gold as a deliberate allocation rather than a one-off curiosity, the premium is the part of the cost they can actually control. The spot price is set by global markets and is identical for everyone. The premium is negotiable in practice, simply by comparing sellers and product types, and it applies again in reverse at sale, when dealers buy back at or below spot. Minimising it on entry, and understanding the buy-back spread on exit, is one of the few levers a private buyer holds.
The practical response is to treat retail gold the way one would treat any fragmented market: compare on a like-for-like, all-in basis rather than trusting a single quote. Resources that let buyers compare live gold bullion prices across sellers, normalised by product and inclusive of the costs that usually hide until checkout, turn an opaque exercise into an informed decision. The aim is not to chase the lowest figure from an unknown vendor, but to see the real spread among reputable ones.
The takeaway
Gold’s reputation as a simple, transparent asset is only half right: the metal is simple, but the market for owning it physically is not. A single quoted price masks a layered structure of premiums, product tiers, and seller dispersion that determines what a buyer actually pays.
Understanding that structure does not require expertise, only the willingness to look past the ticker. The spot price tells you what gold is worth in the abstract. What it costs to own is a separate question, and answering it well is the difference between buying gold and buying it efficiently.
The office lights are on, but plenty of seats stay empty. Employees have heard the policy, nodded at the talking points, and then organized their week around what helps them live well. That quiet opt-out shows up in badge data and calendar behavior, and it is reshaping how leaders must think about performance, loyalty, and space. The gap between formal rules and lived practice is not a blip. It is the new baseline.
Fresh evidence from the JLL Workforce Preference Barometer 2025 shows why. Structured hybrid is now standard: 66% of office workers report clear expectations for on-site days and 72% say they view those rules positively. Yet compliance does not match sentiment. JLL’s regional picture ranges from 74% in the U.S. to 85% in Europe, including those who exceed the target.
Look closer at attendance under specific rules and the fragmentation becomes obvious. Where companies require one to two office days, 7% go in less than required. Under three to four days, 18% attend fewer days than mandated. With full-time RTO, 17% come in less than the target.
When the norm has shifted to control over hours, rigid time windows feel arbitrary, so employees quietly re-optimize.
Who drives noncompliance? JLL’s segmentation points to younger managers and technologists who feel empowered and mobile, often with caregiving duties and long commutes. Paradoxically, many work in high-amenity offices, but their decisions track personal constraints rather than perks. That empowerment links directly to retention risk, which aligns with broader labor signals. In January 2025, a Pew Research survey found that among employees whose jobs can be done remotely, 46% say they would be unlikely to stay if remote work were removed.
The biggest force behind noncompliance is not defiance. It is values. JLL reports work-life balance as the top on-the-job priority in 2025, even overtaking salary, and that shift now shows up across independent datasets. The 2025 Workmonitor from Randstad, based on 26,000 workers in 35 countries, found work-life balance outranking pay for the first time in the survey’s history. Employees still chase higher pay when switching employers, but when deciding how to work and whether to stay, balance comes first.
As Tsvetelina Nasteva, Manager of Human Resources and Talent Acquisition Specialist, CasinoReviews.net, said in her interview, “In talent acquisition, we feel this shift before it ever reaches a dashboard — candidates who once opened with salary questions now ask how much say they’ll have over their own schedule, and when an employer leads with a rigid attendance rule, we watch strong applicants quietly step back.”
Time control, not place, is now the currency. JLL shows a widening “flexibility gap”: 57% of employees believe flexible hours would improve life quality, while only 49% report access. Broader datasets converge on this point. The Global Survey of Working Arrangements continues to track persistent hybrid patterns and a durable preference for time autonomy. A 2025 working paper on the global persistence of work from home underscores that remote and hybrid are stabilizing features of post-pandemic labor markets rather than temporary accommodations. When the norm has shifted to control over hours, rigid time windows feel arbitrary, so employees quietly re-optimize.
Burnout raises the stakes. Nearly 40% of global office workers report feeling overwhelmed or exhausted in JLL’s survey, and the pattern is consistent with other sources. The American Psychological Association’s Work in America 2024 report flags psychological safety and mental health pressures across U.S. workplaces. The World Health Organization’s definition of burnout as an occupational phenomenon highlights how chronic workplace stress corrodes performance. Meanwhile, Gallup’s 2024 wellbeing analysis points to declining thriving rates and sharper engagement drops among managers, the very cohort many companies most want in the office for mentorship. When leadership treats attendance as a proxy for commitment, it misdiagnoses the problem and heightens attrition risk among high performers carrying the heaviest load.
The productivity story no longer supports blanket mandates, either. A six-month randomized controlled trial at Trip.com involving 1,612 professionals found that hybrid work improved job satisfaction and reduced quit rates by roughly one-third without harming performance or promotions. Public summaries from Stanford’s Work Trend analysis and SIEPR’s research brief reinforce the retention and performance neutrality of well-designed hybrid models. When the most rigorous experiments show that hybrid preserves output and improves loyalty, it becomes harder to argue that attendance itself is the lever that matters.
The path out of the stalemate starts with personalization. Career stage and life context change how an employee receives the same rule. The best approach is to tailor expectations by life circumstances. Segmenting requirements for new parents, mid-career managers with care duties, and late-career specialists builds legitimacy without lowering standards. It reframes flexibility as a performance system, not a set of exceptions.
Next, make office time valuable. The hybrid winners choreograph presence around activities that travel poorly over video: apprenticeship, decision sprints, and social rituals that renew trust. Employees will commute for sessions that enhance skill and network density. But they balk at days filled with solitary tasks or noisy floors that defeat focus. JLL’s data show almost 40% of employees believe their office experience should improve, with location, ergonomics, and food quality prominent pain points. That insight harmonizes with market-level occupancy realities: even as companies push harder on attendance, weekly utilization still plateaus around half-full in major metros, suggesting workers self-triage travel for days that matter. Leaders should treat acoustics, ergonomic stations, healthier food options, and extended access hours as baseline utilities, not perks.
The real story is not a binary fight over place; it is a negotiation over time, energy, and meaning.
Finally, measure what you actually want. Replace badge-counting with outcomes and contribution. Align recognition with impact and community behaviors, not chair time. Where noncompliance clusters among high performers, build retention pathways that protect both performance and dignity. That can include flexible hours, short-notice leave for caregivers, and remote learning options that keep advancement unblocked. Microsoft’s ongoing Work Trend Index tracks how teams combine AI tools with hybrid rhythms to preserve velocity; the lesson is simple: technology supports results, but human design earns trust. When managers receive training to discuss workload, energy, and recognition openly, they identify burnout early and redirect teams before disengagement hardens into attrition.
Return-to-office debates often mistake noise for signal. The real story is not a binary fight over place; it is a negotiation over time, energy, and meaning. JLL’s 2025 barometer shows acceptance of policy coexisting with widespread noncompliance, and independent surveys and occupancy data confirm that employees now optimize for well-being. Leaders who chase attendance with stricter rules will keep losing ground with the very people they most want to retain. Leaders who design around time autonomy and purpose will rebuild trust, stabilize teams, and get better performance. Win that design contest, and the seats you need filled will fill themselves.
The US–Iran war reshaped the Middle East, exposing US dysfunction and highlighting regional security vulnerabilities. Dr Kalim Siddiqui argues that economic fallout and rising global living costs have intensified criticism of Israeli policies, while many regional states seek greater economic engagement with Iran. The conflict also created opportunities for China to expand Belt and Road partnerships and strengthen regional ties through economic and trade cooperation.
I. Introduction
The Trump administration’s approach to Iran was characterised by a combination of maximalist rhetoric and a preference for rapid, decisive military action. President Trump reportedly sought a swift regime-change operation, anticipating that the Iranian government would collapse under sustained pressure. According to various sources, Israeli officials assured him that the campaign could be concluded within days—a surgical strike that would decapitate Iran’s leadership and trigger a domestic uprising (The Guardian, 2026).
Beyond these geopolitical realignments among states, the human and economic toll of this conflict has been devastatingly universal.
This assessment proved profoundly mistaken. Four months after the outbreak of major hostilities between US, Israel and Iran, the anticipated quick victory has failed to materialise. Instead, the conflict has deepened and expanded, drawing much of the region into a broader war. The closure of the Strait of Hormuz—through which roughly one-fifth of global oil supplies and substantial volumes of liquefied natural gas had passed before the crisis—has severely disrupted global energy markets. Ships traffic through the strait has fluctuated between just two and sixteen ships per day, a dramatic decline from the more than one hundred ships that typically transited daily before the conflict. The resulting disruption has driven up oil and gas prices, fuelled global inflation, and imposed significant economic costs on billions of consumers worldwide.
Rather than securing a rapid victory, the United States (US) has become entangled in a prolonged and costly conflict. The enhanced influence of the Islamic Revolutionary Guard Corps (IRGC) in Iran’s post-war political order has heightened anxieties among Gulf states. With many of the IRGC’s more pragmatic leaders killed during the war, the likelihood of more radical and confrontational factions gaining influence has increased. Far from collapsing, the Iranian regime has consolidated its position by mobilizing anti-imperialist and nationalist sentiment, adopting an even more defiant and militarised posture (Siddiqui, 2026a).
Contrary to the aggressive expansionism that many critics argue has characterised Israeli policy for decades, Iran has not sought regional hegemony through conventional military conquest. Instead, Iran’s strategy of cultivating and supporting regional resistance networks has largely functioned as a form of forward defence—a deterrent posture designed to safeguard its borders and strategic interests rather than a project of territorial expansion. Assertions that Iran’s regional activities constitute a covert campaign of imperial domination are often analytically problematic and insufficiently supported by the available evidence (Siddiqui, 2026a).
Among the Gulf Cooperation Council (GCC) states, a more pragmatic approach is emerging. Although these governments remain reluctant to accept overt Iranian political predominance, they have shown an increasing willingness to accommodate and engage with Iran’s growing economic influence. This gradual rapprochement reflects a strategic calculation that economic interdependence offers a more sustainable foundation for regional stability than perpetual zero-sum competition. Scholarly studies suggest that economic integration, institutional cooperation, and pragmatic mediation—particularly by states such as Qatar and Oman—provide viable mechanisms for reducing tensions and preserving economic stability in a region increasingly shaped by sanctions, energy market volatility, and asymmetric warfare.
This regional transformation is further complicated by the evolving nature of the US’ commitment to the Middle East. US foreign policy in the region remains highly susceptible to pressure from organized interest groups, with lobbying networks serving as important channels of influence. If US’s primary objective is to attract investment and promote economic growth, the Gulf monarchies already make a substantial positive contribution to US power (Siddiqui, 2025a). They are significant investors in emerging US high tech and represent lucrative markets for the US corporations. Moreover, the operating costs of US military installations in the Gulf are largely borne by host governments, effectively subsidizing US force projection across the region (The Economist, 2022).
By contrast, the economic rationale underpinning the US–Israeli alliance remains more contested. Supporters argue that US assistance to Israel should be viewed as a strategic investment rather than conventional foreign aid. The annual $3.3 billion in military assistance is often described as modest relative to overall US defence spending, with most of the funds returning to the US through purchases of US military equipment, thereby supporting domestic defence industries and employment. Israel is also credited with contributing significant innovations in areas such as avionics, cybersecurity, and missile defence, leading proponents to characterize the relationship as mutually beneficial rather than one-sided.
From a political economy perspective, however, the net benefits of this asymmetrical partnership remain subject to debate. Critics argue that the strategic and diplomatic costs associated with unconditional support for Israel—including recurrent demands for diplomatic backing and the geopolitical tensions generated by regional conflicts—may outweigh the economic and technological gains. These costs become particularly salient when such tensions contribute to instability in global energy markets and impose broader economic burdens on the international system.
II. The Global Economic Fallout
Beyond these geopolitical realignments among states, the human and economic toll of this conflict has been devastatingly universal. Over the past three months, the war has inflicted severe economic pain across the globe, with the cost of living surging precipitously in virtually every nation. Consumers worldwide have borne the brunt of this shock, as sharp spikes in oil and gas prices have cascaded through supply chains, driving up the prices of food, transport, and essential goods (The Guardian, 2026).
The crisis surrounding the Strait of Hormuz has been particularly consequential. Prior to the latest escalation, the strait carried approximately one-fifth of global oil supplies—around 20 million barrels per day—as well as substantial volumes of liquefied natural gas. During the conflict, maritime traffic fluctuated between just two and sixteen vessels per day, a dramatic decline from the more than one hundred ships that typically transited the waterway each day before the crisis. This disruption drove up oil and gas prices, strained global supply chains, and significantly increased transportation and insurance costs worldwide.
The broader economic repercussions have been severe. Global growth projections have been revised downward, with the United Nations Conference on Trade and Development (UNCTAD) forecasting growth of just 2.5 per cent in 2026, well below pre-pandemic trends. Across Asia, the economic outlook has deteriorated rapidly as inflationary pressures have intensified. In Pakistan, inflation rose from 7.3 per cent in March to more than 12.6 per cent in May. At the same time, several Asian currencies weakened against the US dollar, while borrowing costs increased as investors reassessed geopolitical and economic risks.
The International Labour Organization (ILO) has warned that the crisis represents “a slow-moving and potentially long-lasting shock that will gradually reshape labour markets.” Under one scenario modelled by the organization—in which oil prices remain approximately 50 per cent above their early-2026 average—global working hours could decline by 0.5 per cent this year and by 1.1 per cent in 2027, equivalent to the loss of roughly 14 million and 38 million full-time jobs, respectively. Real wages could also fall by as much as US$3 trillion globally by 2027.
The implications for food security are equally alarming. According to the World Food Programme, if oil prices remain near US$100 per barrel through mid-2026, an additional 45 million people worldwide could fall into acute food insecurity, adding to the nearly 320 million people already experiencing hunger since the beginning of the year. In Somalia alone, approximately 6 million people are currently facing severe food shortages, with children under the age of five among the most vulnerable. By the end of 2026, a further 2.5 million people are expected to be unable to afford basic food necessities.
Trump political appeal is closely tied to economic performance and economic nationalism; such developments represent a serious political challenge. Rising energy prices and the resulting cost-of-living pressures are eroding household purchasing power and fuelling public dissatisfaction. Viewed in this context, the administration’s apparent recalibration of its Middle East policy may be understood less as an ideological shift than as a pragmatic response to mounting economic costs and strategic constraints.
III. The Strategic Logic of Israeli Objectives
An important but frequently overlooked dimension of the relationship is the asymmetry of power between the US and Israel. Israel remains heavily dependent on US military assistance, economic support, intelligence cooperation, and diplomatic backing. Its military advantages are reinforced by a continuous flow of US weapons systems, technological assistance, and logistical support.
The US, by contrast, possesses substantially greater economic, military, and diplomatic resources. Its economy is many times larger than Israel’s, its military capabilities are global in scope, and its diplomatic reach remains unmatched. This disparity suggests that US possesses significant leverage should it choose to employ it. The central question is therefore not whether the US has the capacity to influence Israeli behaviour, but whether domestic political considerations permit the full exercise of that influence.
Potential instruments of leverage include conditioning military assistance, reducing diplomatic protection in international forums, limiting intelligence cooperation, or signalling that political support is not unconditional. The relative absence of such measures reflects political calculations and institutional constraints rather than a lack of material capability.
For decades, Iran has been viewed by analysts as the sole regional actor capable of imposing meaningful constraints on Israeli military superiority and limiting its strategic flexibility. By leveraging a constellation of resistance forces—including Hezbollah, Hamas, and the Houthis—Iran has built a layered network of influence that grants it strategic depth and repeatedly complicates Israeli regional calculations (Siddiqui, 2026a).
From this vantage point, neutralizing Iran’s deterrent capabilities has become a central pillar of Israeli regional strategy. Critics contend, however, that this push is driven less by immediate security concerns than by a broader ambition for uncontested regional supremacy—an aspiration some associate with expansionist visions linked to the concept of a “Greater Israel.”
For these critics, Israel’s objective extends far beyond degrading Iran’s military infrastructure or halting its nuclear progress. The ultimate aim, they argue, is to fracture Iran as a coherent state—reducing it to a condition reminiscent of post-invasion Iraq, post-Gaddafi Libya, or war-torn Sudan: riven by ethnic and sectarian divisions, paralyzed by internal strife, and incapable of projecting power beyond its borders. Such a weakened Iran would pose no threat to Israeli dominance and would serve as a stark warning to any regional actor considering resistance to the US-led order
This vision has been articulated with increasing clarity by Israeli officials. Defence Minister Israel Katz, for instance, stated in February 2026 that Israel was “determined” to ensure Iran never recovers, advocating for a “Libya model” in which Iran would be “completely destroyed, without a central government, weakened, disintegrated, with no capability to threaten the region or the world”.
Crucially, Israel has consistently sought to position the US as the executor of this project. Rather than bearing the full cost of a direct confrontation, Israeli strategy has been to leverage The US military and financial power to achieve its objectives. The logic is straightforward: the US possesses the military capacity to effect regime change and the economic heft to sustain a prolonged campaign, while Israel, constrained by its smaller population and geographic vulnerability, cannot absorb the same level of casualties or international opprobrium.
IV. The Divergence of US and Israeli Interests
For Trump, the political calculus has shifted. A prolonged war with mounting casualties and economic costs does not serve his domestic agenda. The promised quick victory has not materialized, and the electoral implications of a quagmire are becoming impossible to ignore.
Israel, however, views the situation through an entirely different lens. For Israeli decision-makers, the current window of opportunity—in which the US is militarily engaged and Iran is under maximum pressure—represents a historic chance to achieve the long-sought objective of permanently neutralizing the Iranian threat. Israel therefore seeks to prolong the conflict, to deepen the destruction, and to ensure that Iran emerges not merely defeated but destroyed as a functional state. As Defence Minister Katz has made clear, the Israeli goal is not a negotiated settlement but the complete disintegration of Iranian statehood (The Guardian, 2026).
This divergence creates a dangerous dynamic. The US, seeking an exit, finds itself constrained by its alliance commitments and the inertia of military engagement. Israel, seeking escalation, continues to press for more aggressive action, knowing that it lacks the capacity to achieve its objectives without The US support. The result is a protracted conflict that serves Israeli strategic interests while imposing mounting costs on the US and the global economy—a classic case of a smaller ally exploiting a larger patron’s commitments to pursue its own maximalist agenda.
Perhaps the most notable recent development has been the administration’s changing rhetoric toward Israel. President Trump has moved from near-unconditional support toward a more openly critical posture, while Vice President JD Vance has emerged as one of the administration’s most prominent voices advocating a reassessment of the relationship. Vance has questioned aspects of Israeli regional policy, criticised the continuation of certain military deployments, and argued for a more balanced approach to regional diplomacy.
This position carries considerable political risks. For decades, strong support for Israel has been a defining feature of mainstream Republican foreign policy. Any departure from that consensus is likely to encounter resistance from influential political constituencies and lobbying organizations. Vance’s willingness to embrace such a position therefore suggests that elements within the administration view the broader economic and strategic consequences of regional instability as increasingly serious.
The speed of this rhetorical shift has been striking. Positions that would have been politically difficult to imagine within a Republican administration only months earlier are now being voiced publicly by senior officials. Expressions of frustration with Israeli policy and suggestions that US support may not be limitless indicate a growing reassessment of long-standing assumptions. Moreover, economic pressures and strategic considerations are playing an increasingly important role in shaping the administration’s approach to the region.
There is a growing and palpable conviction among populations worldwide that Israeli policy is fundamentally misaligned with the broader interests of ordinary people. The widespread, graphic documentation of civilian casualties—particularly the killings of children and non-combatants—has catalysed a moral reckoning. These images, disseminated instantly across digital platforms, have pierced traditional media filters and galvanised public opinion across diverse cultural and political contexts.
Critically, this popular discontent is increasingly reflected within elite intellectual and strategic circles. A significant and growing cohort of academics—including Jeffrey Sachs, John Mearsheimer, Trita Parsi, Ilan Pappé, and others—as well as foreign policy analysts and prominent media figures such as Tucker Carlson and Ana Kasparian, have begun openly challenging prevailing Zionist narratives.
Scholarly analyses increasingly frame the recent Israel–Iran war not as an isolated event, but as “a sharp symptom of long-standing global contradictions” rooted in imperialism, colonialism, and competition within global capitalism (Siddiqui, 2025b). From this perspective, Israel is viewed as “a vehicle of primitive accumulation in Middle East,” advancing the imperatives of global capitalism through settler-colonial expansion and dispossession while simultaneously intensifying the enduring contradictions of imperialist rivalry (Siddiqui, 2018).
V. Implications for Regional Order
The long-term implications of this dynamic are chaos and instability in the region. If Israel succeeds in its objective of reducing Iran to a failed state, the regional balance of power would be fundamentally transformed. The elimination of Iran as a countervailing force would leave Israel as the unchallenged military hegemon in the Middle East, with no regional power capable of constraining its actions. This would likely embolden further Israeli expansionism, whether through settlement construction in the West Bank, annexation of territory, or military action against other perceived threats.
However, the costs of such an outcome would be immense. The disintegration of Iran—a country of over 95 million people with a rich historical heritage and significant economic potential—would create a humanitarian catastrophe on a scale not seen since the wars in Syria and Yemen. It would also generate a power vacuum that extremist groups, regional militias, and external powers would rush to fill, perpetuating instability for decades to come. The refugee flows, the collapse of regional trade, and the continued disruption of energy supplies would impose costs not only on the Middle East but on the entire global economy (The Guardian, 2026).
Moreover, the destruction of Iran would not eliminate resistance to Israeli hegemony. History suggests that the elimination of one adversary merely creates space for others to emerge. The underlying grievances that animate opposition to Israeli policy—the displacement of Palestinians, the occupation of Arab lands (Siddiqui, 2024a), the perceived injustice of the regional order—would persist, finding new expression in different forms. The cycle of violence would continue, albeit in new configurations (Siddiqui, 2024a).
Talks between Iran and the US in Switzerland have stalled. Iran has reaffirmed the closure of the Strait of Hormuz, citing continued Israeli strikes in southern Lebanon as the immediate trigger. The closure—already responsible for disrupted energy markets and global inflationary pressures—is presented by Iran as a direct response to Israeli military actions rather than as unilateral escalation (The Financial Times, 2026).
At the heart of the diplomatic deadlock lies a single, non-negotiable issue for Iran: the withdrawal of Israeli forces from southern Lebanon. This condition is explicitly laid out in the memorandum of understanding underpinning the negotiations. From Iran’s perspective, no meaningful progress—whether on reopening the Strait, reviving the JCPOA, or reconstructing Iran—is possible without a binding commitment to Israeli withdrawal.
The post-war reconstruction of Iran presents a particularly revealing lens through which to examine the political economy of the region. The Memorandum of Understanding (MOU) demands of over $300 billion for reconstruction and economic development of Iran, to be undertaken with regional partners.
The US shares this objective in principle. US would like to see Israeli forces depart southern Lebanon, recognizing that their continued presence obstructs regional stability and complicates US-Iranian relations. However, the gap between US preference and Israeli action has widened. If Israel resists—as its recent rhetoric and military posture suggest—President Trump faces a stark choice: compel Israeli compliance or accept the collapse of negotiations and the perpetuation of a conflict inflicting mounting costs on the global economy.
There is no viable alternative. Maintaining the status quo—Israeli forces entrenched in southern Lebanon, the Strait closed, and Iran under maximum pressure—would be a strategic and economic disaster. The costs are already visible: disrupted energy supplies, soaring inflation, and a global economy teetering on the brink of recession. To allow this to persist is simply not an option.
VI. Trade, Development, and Regional Cooperation
As the US economy grapples with deepening crises—soaring public debt, widening trade and fiscal deficits, rising inequality, and falling profitability (Siddiqui, 2025c) – the US is increasingly ill-positioned to fund developmental projects in the Middle East. The previous US model for the region hinged on exporting arms and luxury goods while strategically maintain conflicts and tensions to drive further weapons sales. This approach has visibly failed (The Economist, 2022).
China’s Built and Road Initiative (BRI), by contrast, has grown sharply. Figure 1 tracks the steady rise in Chinese investments and construction projects over the years. Saudi Arabia and the UAE have been key partners throughout, but after 2020, Saudi Arabia clearly emerged as the dominant hub for Chinese companies in the region.
Over a recent 12-month period, Chinese investments and construction contracts in the region totalled $39.4 billion, heavily concentrated in energy and resource-backed infrastructure deals, particularly in Saudi Arabia and the UAE. A central BRI objective is the promotion of regional trade and economic development. Rather than pursuing bilateral arrangements, China deploys the BRI as a hedging instrument, engaging the region collectively. Since 2009, China has surpassed the US as the largest exporter to the Middle East—a telling indicator of its growing economic footprint (Kamel, 2018).
China’s engagement in the Middle East differs from the Western development model that has shaped the region since the 1960s. Rather than emphasizing political influence, China has focused on trade, infrastructure development, and regional economic integration. Through the BRI, China has generated positive economic spillovers for both developing and developed countries without pursuing a strategy of containment. BRI infrastructure and development projects have transformed previously neglected regions by improving connectivity, investment opportunities, and economic capacity (Siddiqui, 2019).
Figure 1: Investment and Construction Projects in the Middle East by China, 2012-2022 (billion $).
The development of energy, trade, investment, and digital infrastructure enables countries to address their economic challenges according to their own priorities. Drawing on more than four decades of economic reform and opening-up, China has developed a distinctive model of political economy that offers valuable lessons for other developing nations. In the Middle East, the BRI has helped unlock economic potential and strengthen local capacities. As demands for new approaches to development intensify, China’s growing role in the region provides an important case for reassessing conventional development paradigms and the geopolitical implications of great-power competition. Xi Jinping’s 2022 visit and the Gulf states’ embrace of the BRI offer particularly useful examples of these evolving dynamics.
The 2008–2009 global financial crisis marked a turning point in China-Gulf relations. As the Financial Times notes, the symbiotic relationship between Gulf oil producers and fast-growing Asian economies—led by China—is increasingly displacing the Western-dominated business landscape of the Middle East.
The Industrial and Commercial Bank of China established its presence in the Dubai International Financial Centre in 2008, followed by the Agricultural Bank of China—China’s second-largest bank—in November 2012. Between 2013 and 2019, Chinese investment in the Middle East reached US$93.3 billion, concentrated in energy (US$52.8 billion), real estate (US$18.4 billion), transport (US$18.6 billion), and utilities (US$5.9 billion).
President Xi Jinping’s visit to Saudi Arabia in 2022 marked a significant milestone in China–Gulf relations. As a result of the visit, 34 agreements covering green energy, information technology, and infrastructure were signed between Chinese and Saudi companies. At the broader China–GCC level, bilateral trade reached US$230 billion, and both sides agreed to pursue a free trade area and establish a joint investment council to deepen economic cooperation. Key outcomes of the inaugural China–GCC Summit included support for the Global Development Initiative, the Global Security Initiative, and the 2023–2027 Action Plan for Strategic Dialogue.
Figure 2 charts the trajectory of crude oil exports from Gulf Cooperation Council countries to China between 2006 and 2022. The trend is unmistakably upward, underscoring the deepening energy relationship. Saudi Arabia, the UAE, and Kuwait emerge as the pivotal suppliers, together dominating China’s Gulf oil imports across the entire decade.
China’s trade with the Middle East, Russia, and Central Asia expanded rapidly, reaching approximately US$774 billion in 2024. As Figure 3 illustrates, China’s trade with the Middle East has surged since 2001—from near-negligible levels to surpassing both the US and EU by 2023—making the region a vital trading partner. This growth reflects deepening ties driven by strategic initiatives, complementary economic interests, and shifting geopolitics.
China has overtaken the US as the Middle East’s largest trading partner. While bilateral trade between China and the region has grown steadily—bolstered by the Belt and Road Initiative and rising energy demand—US trade has remained stagnant at roughly half that volume. The Gulf relationship is particularly significant: by 2025, China-GCC trade had reached approximately US$300 billion, with China as the Gulf’s top crude oil buyer and a growing source of investment as Gulf states diversify beyond hydrocarbons (The Economist, 2022; Siddiqui, 2019).
Recent US-Iran tensions have delivered a major shock to the Gulf, challenging two pillars of regional stability. The first is the Gulf’s economic model—built on stability, favourable tax regimes, flexible regulations, and a dynamic business environment. The second is the traditional oil-for-security arrangement, underpinned by the US military presence. Missile and drone attacks during the conflict exposed vulnerabilities in this security architecture, prompting Gulf states to reassess the reliability of the US as their principal security guarantor.
China economic footprint in the Gulf countries has expanded substantially through trade, investment, and infrastructure development, creating a level of engagement that is difficult for regional governments to ignore. Following President Xi Jinping’s visit to Riyadh and the China–GCC Summit, relations evolved into a broader strategic partnership. Although Chinese investments initially focused on energy and port infrastructure, the changing geopolitical environment is encouraging both sides to pursue deeper economic integration across a wider range of sectors (The Economist, 2022).
The future of China–Gulf economic relations is likely to centre on three key areas where Chinese technological capabilities complement Gulf capital and development ambitions. The first is green energy. China dominates global solar manufacturing, accounts for the majority of electric vehicle production, and has rapidly expanded exports of renewable energy technologies. For Gulf states pursuing economic diversification and energy transition strategies, partnerships with Chinese firms such as BYD, Geely, and Changan offer access to advanced technologies for modernising power grids and transportation systems (Siddiqui, 2024b).
China’s approach in the Middle East emphasises stability, development, and economic cooperation. Its role in facilitating the 2023 restoration of diplomatic relations between Iran and Saudi Arabia demonstrated its growing diplomatic influence and preference for dialogue-based conflict management. Alongside its 25-year cooperation agreement with Iran, China has expanded economic partnerships with Saudi Arabia, the United Arab Emirates, Qatar, Kuwait, Oman, and Bahrain, particularly in energy, telecommunications, infrastructure, and technology. Chinese companies have also played a prominent role in major development projects in Egypt. Through the BRI, China has strengthened economic ties across the region while supporting national development and reform agendas (Cheung, 2023).
The Gulf states’ Western political-economic model rested on an oil-for-security bargain with the US: security guarantees and military protection in exchange for oil exports, Western arms purchases, luxury goods, and substantial investments in Western financial markets and real estate.
This arrangement is now under mounting pressure. Geopolitical shifts and regional conflicts have eroded trust in external security commitments (Siddiqui, 2025d), driving Gulf states to broaden their strategic and economic partnerships. The recent US-Iran war has been a particular catalyst, prompting a fundamental reassessment of the security architecture.
Concurrently, Gulf governments have recognized that hydrocarbon dependence, arms imports, and overseas asset accumulation cannot sustain long-term prosperity. Industrialization, infrastructure development, and economic diversification have accordingly risen to the top of policy agendas.
Economic vulnerabilities have compounded these pressures. While oil wealth once reduced the imperative for diversification, the post-2014 oil price slump exposed the risks of overreliance on a single commodity. Fiscal strains have since compelled several Gulf states to draw on sovereign wealth funds and fast-track economic reforms.
Saudi Arabia’s Vision 2030 became the clearest expression of this shift. Rather than relying primarily on oil exports and overseas investments, Gulf states increasingly sought to diversify their sources of income through industrialisation, infrastructure development, technology, renewable energy, tourism, and manufacturing. In this context, China emerged as an attractive partner. Through trade, investment, technology transfer, and the Belt and Road Initiative (BRI), China offered a development-oriented model focused on infrastructure, industrial capacity, and long-term economic transformation (Cheung, 2023).
As a result, Gulf states are gradually transitioning from an economic model centred on oil exports and financial investment abroad toward one emphasising domestic development, economic diversification, and strategic cooperation with emerging partners in the East. China’s expanding role in this process reflects broader changes in the regional and global balance of economic power.
A key feature of the BRI is its focus on regional connectivity. Historically, colonial powers concentrated on controlling maritime trade routes while leaving many neighbouring states poorly connected by land-based infrastructure. As a result, economic integration across parts of the Middle East remained limited despite geographical proximity. China’s infrastructure strategy seeks to address these gaps through transport corridors, ports, railways, industrial zones, and digital networks that facilitate trade and regional cooperation.
The emergence of a more multipolar regional order has further strengthened China’s position. Unlike the US, whose regional engagement has often been closely linked to security concerns, China’s interests are primarily economic. China maintains extensive energy, trade, and investment relationships with both Gulf states and Iran and therefore has strong incentives to promote stability rather than regional confrontation. Improved relations between Iran and its Gulf neighbours create favourable conditions for trade, infrastructure development, and cross-border investment, all of which support China’s long-term economic interests (Cheung, 2023).
At the same time, countries such as Iran have shown increasing interest in deeper economic and technological cooperation with China, viewing Chinese expertise in infrastructure, manufacturing, and advanced technologies as valuable for their own development goals. As US influence in the region faces growing challenges, China has gained additional opportunities to expand its economic role. The result is the gradual emergence of a new regional framework in which economic integration, infrastructure connectivity, and development cooperation increasingly complement, and in some areas reshape, the traditional security-centred order that dominated the Middle East for decades.
VII. Historical Foundations of the Chinese Relations with the Middle East
Historically, Arab countries maintained close cultural, technical, and trade links with China, facilitating a rich exchange of goods, ideas, and technologies that benefited both regions. The Tang Dynasty (c. 670–750)—often regarded as China’s golden age—exemplified this interconnectedness. During this period, papermaking reached unprecedented sophistication, while the capital, Chang’an (modern Xi’an), emerged as the world’s largest city, with a population estimated between 800,000 and one million. With China’s total population approaching 50 million, the empire’s economic and demographic strength enabled it to project influence deep into Central Asia and secure key sections of the Silk Road—routes that likewise connected it to the Arab world and beyond.
At the same time, the Umayyad Caliphate (661–750) expanded from the Iberian Peninsula in the west to Transoxiana and the Indus River in the east. Following the Abbasid takeover in 750, the Chinese and Islamic empires met on the frontiers of Central Asia. Traditional accounts of the Battle of Talas (751), fought in present-day Kyrgyzstan, claim that Chinese prisoners—including papermakers—were captured by Muslim forces. However, as Jonathan Bloom notes, this connection may be more legend than established fact (Bloom, 2001).
A more consequential episode in Sino-Islamic relations came during the An Lushan Rebellion (755–763). After rebels seized Chang’an in 756, forcing Emperor Xuanzong to flee, the Tang court reportedly sought assistance from the Abbasid Caliph Abu Ja’far al-Mansur. Muslim sources state that thousands of Arab troops helped the Tang recapture the capital. Some are said to have settled in China, contributing to the origins of the Hui Muslim community. During this period, Muslim merchants continued to travel to China, where Islam was generally tolerated by the Tang authorities (Friedrichs, 2019).
While the Umayyads relied heavily on Egyptian papyrus for administration, paper gradually replaced it under the Abbasids, particularly after Baghdad was founded by al-Mansur in 762. The first major paper mill was established there in 794 during the reign of Harun al-Rashid, followed by others in Basra, Raqqa, and Hama. By the ninth and tenth centuries, Baghdad and Basra had become major centres of book production and trade, with many scholars also working as booksellers, copyists, and translators. (Friedrichs, 2019).
Under Caliph al-Ma’mun (r. 813–833), Baghdad emerged as the leading center of scientific and philosophical inquiry. Through the House of Wisdom, manuscripts from across the known world were collected, translated, studied, copied, and disseminated. This institution preserved and expanded knowledge from Greek, Persian, Indian, and other intellectual traditions.
The spread of paper and the growth of Silk Road networks accelerated an extraordinary era of cultural and scientific exchange. At the House of Wisdom, Muhammad ibn Musa al-Khwarizmi combined Greek mathematics with Indian numerals, laying the foundations of algebra and giving rise to the term “algorithm.” Medical works from Greece and Persia were translated and expanded by scholars such as Ibn Sina (Avicenna), whose Canon of Medicine remained a standard text throughout the Islamic world and medieval Europe for centuries. Advances in cartography likewise integrated Greek, Persian, and Chinese traditions (Friedrichs, 2019).
China’s relations with the Middle East are deeply rooted in history. The ancient Silk Road facilitated extensive trade, cultural exchange, and scientific collaboration between both communities. Many Arab traders settled in China, and a significant number of Chinese converted to Islam, some of whom contributed to Chinese military and administration.
Bloom (2001) provides a comprehensive analysis about introduction of paper and immense impact on Islamic civilization. It traces paper’s journey from its invention in China to its spread through the Islamic lands and eventual transmission to Europe, arguing that paper was a crucial agent for the dissemination of information and transformed medieval life.
The Abbasid world’s largest library was founded in Baghdad in 991 by the Persian minister Sabur ibn Ardashir and contained more than 10,000 volumes. Yet the most celebrated library of the age stood in Córdoba under the Umayyad Caliph al-Hakam II (r. 961–976). According to Bloom, it housed some 400,000 books, with a catalogue filling forty-four volumes. Even if these figures are exaggerated, the collection far exceeded any contemporary library in Christian Europe. Open to Muslim, Jewish, and Christian scholars alike, it became a vibrant center of learning and debate. Similar institutions later emerged in Fatimid Egypt (Bloom, 2001).
This history challenges modern theories of an inevitable “clash of civilizations.” The intellectual exchanges linking China, the Islamic world, and Europe demonstrate that civilizations can coexist, cooperate, and enrich one another. Despite periods of political conflict and instability, medieval Muslim societies generally regarded knowledge as a source of power, progress, and human flourishing—a principle championed by thinkers such as al-Farabi.
The transmission of papermaking from China to the Islamic world, and later to Europe, was one of history’s most transformative developments. As Jonathan Bloom’s Paper Before Print illustrates, paper became the medium through which ideas travelled, knowledge accumulated, and a global renaissance took shape.
Words alone are insufficient; economic and military cooperation with the genocidal Israeli regime must end. Without the credible exercise of leverage, Israel has no reason to alter its course.
At present, scholars attribute China’s popularity in the Middle East to a combination of historical and social factors. The region’s fraught legacy with Western colonialism contrasts sharply with China’s self-presentation as “an all-time friend and development partner.” Simultaneously, China’s remarkable economic trajectory offers “a welcome alternative to the so-called US consensus.” Its non-interventionist stance has been instrumental in making the Belt and Road Initiative broadly acceptable across the Middle East.
VIII. Conclusion
The US–Iran confrontation and Israel’s ongoing war on Gaza—now in its third year—have laid bare Western double standards for the world to see. The devastation in Gaza has severely undermined the perceived legitimacy of the Western-led international order. The contrast is stark: swift, decisive Western action to uphold international law in Ukraine stands in sharp relief against a hesitant, muted response to the humanitarian catastrophe in Gaza. Despite rhetorical condemnations, the West continues to enable Israel’s territorial expansion. Words alone are insufficient; economic and military cooperation with the genocidal Israeli regime must end. Without the credible exercise of leverage, Israel has no reason to alter its course.
The stakes could hardly be higher—not merely prolonged conflict, but a potential global downturn marked by surging energy prices, broken supply chains, and rising food insecurity. For a president focused on economic growth, this calculus is increasingly impossible to ignore.
Durable peace requires accountability under international law, equal rights, and dignity for both Jewish and Palestinian peoples. These are not optional ideals but essential prerequisites for long-term stability. The status quo—entrenching discrimination, denying Palestinian rights, and relying on military force over diplomacy—is unsustainable. A just settlement demands an end to asymmetrical power relations and a commitment to human rights, democracy, and self-determination for all (Siddiqui, 2024a).
Yet the current trajectory is one of deepening entanglement. The US depends on Gulf countries for military and economic partnership; while propping up an Israel whose policies generate recurrent global crises. As Gulf states deepen ties with Iran and international criticism mounts, the US faces a stark choice: continue alienating key partners while absorbing mounting costs, or adopt a balanced approach that respects regional autonomy, reflects shifting realities, and prioritises broader stability. Only the latter offers a sustainable path.
Global economic crisis is already visible—higher energy costs, inflation, and supply-chain strains affecting billions. International bodies warn of a 1973-style cost-of-living crisis, threatening vulnerable economies (Siddiqui, 2026b).
Compounding this, Israel aims to eliminate Iran as a regional counterweight, using US power to do so, while the Trump administration’s hope for rapid regime change in Iran has failed. US and Israeli interests have rarely diverged so sharply: the US seeks an exit; Israel pursues a decisive victory. That dynamic is unsustainable. With rising Chinese economy, and better performance of other emerging economies, the US faces new challenges as in the form of multipolarity.
The US cannot indefinitely bear substantial economic and geopolitical costs for policies that increasingly serve Israel’s agenda. A fundamental reassessment—weighing strategic benefits against mounting liabilities—is overdue. Without it, the cycle of conflict will persist, and the opportunity for a more resilient, equitable regional order in the Middle East will slip away. The choice is clear: continue toward deeper instability, or recalibrate US influence to pursue de-escalation and a more resilient regional order.
Dr. Kalim Siddiquiis an economist specializing in International Political Economy, Development Economics, Trade and Economic Policy. Since 1989, he has been teaching economics at various universities in Norway and the UK. Dr. Siddiqui’s research interests encompass a wide range of topics, including political economy, international trade, and economic history, South Asia, and emerging economies. He has presented papers at international conferences across numerous countries, reflecting his global engagement in the field. His scholarly pursuits span six broad domains: Political Economy, Development Economics, Economic History, Economic Policy, Globalization, and International Trade. Dr. Siddiqui has made significant contributions to research in areas such as trade policy, globalization, and political economy. His work has been published in chapters of edited books and articles published in peer-reviewed journals. For inquiries, Dr. Siddiqui can be reached at: [email protected]
References
Bloom, J.M. (2001) Paper Before Print: The History and Impact of Paper in the Islamic World, Yale University Press.
Cheung, G.C.K. (2023) “China’s Belt and Road Initiative: The Economic Footprints in the Middle East vs. Geopolitical Dimensions with the United States” East Asian Policy 15(01): 60-73, April.
Friedrichs, J. (2019) “Explaining China’s Popularity in the Middle East and Africa” Third World Quarterly, 40 (9).
Kamel, M.S. (2018) “China’s Belt and Road Initiative: Implications for the Middle East” Cambridge Review of International Affairs, 31(1).
Siddiqui, K. (2026a) “US-Iran Conflict: Oil Volatility and Global Economic Crisis”, World Financial Review, May.
Siddiqui, K. (2026b) “The United States, the Petrodollar, and Multipolarity: Strategic Intervention in an Age of Monetary Decline” World Financial Review, January.
Siddiqui, K. (2025a) “The United States’ Future in an Imperial Mirror: Lessons from Britain, Spain, Abbasids, Rome, and Beyond” World Financial Review, November.
Siddiqui, K. (2025b) “Decolonisation and Economic Sovereignty: The Bandung Conference and the Making of the Global South” World Financial Review, June.
Siddiqui, K. (2025c) “The Reasons Behind the Decline of the United States Economy” World Financial Review, May.
Siddiqui, K. (2025d) “Geopolitics and the Persistence of Global Uneven Development: A Critical Analysis” World Financial Review, July.
Siddiqui, K. (2024a) “Palestine, Imperialism and the Settler Colonial Project” World Financial Review, February/March.
Siddiqui, K. (2024b) “China’s Growth Miracle and Development Strategy Since the 1980s” World Financial Review,
Siddiqui, K. (2019). “One Belt and One Road, China’s Massive Infrastructure Project to Boost Trade and Economy: An Overview” International Critical Thought. 9(2):214-235.
Siddiqui, K. (2018). “Imperialism and Global Inequality: A Critical Analysis” Journal of Economics and Political Economy, 5(2): 266-291.
The Economist (2022) “The Gulf Looks to China”, 7 December, London.
The Financial Times (2026) “US and Iran conduct tense peace talks in Switzerland” 22 June, London.
The Guardian (2026) “What lessons will Iran’s new leadership draw from the 110-day war?” 20 June, London.
Raleigh’s active mix of commuters, universities, medical centers, state offices, and growing neighborhoods means an injury can quickly affect work, treatment, transportation, and family routines. When someone is hurt by another party’s actions, the question is not only what happened but also how fully the harm can be documented and valued. Maximizing compensation requires a careful look at medical needs, lost income, long-term limitations, insurance pressure, and the local legal rules that may shape recovery.
Injured people often need guidance that turns scattered records and stressful conversations into a clear, well-supported claim. Raleigh injury law firm can help build that foundation by identifying losses, protecting key facts, and pushing for a result that reflects the real impact of the injury. With steady legal support, clients can make informed decisions while pursuing the financial recovery they need to move forward.
Fast Case Setup
Early action often shapes the entire claim. Bruising fades, skid marks disappear, and witnesses forget small details that later matter. A law firm usually starts by gathering records, preserving scene evidence, and listing every loss, including treatment charges, lost earnings, physical pain, and likely future care, so the case reflects the full impact rather than a narrow snapshot.
Fault First
Compensation starts with liability. Counsel collects crash reports, photographs, video footage, repair records, and witness statements to show what happened. Strong factual proof reduces room for an insurer to shift blame or question causation. That step is especially important in North Carolina, where even slight fault by the injured person can block recovery. Solid early evidence gives the claim a stable base before negotiations begin.
Medical Proof
Clinical records do far more than confirm office visits. They show tissue damage, nerve irritation, restricted motion, surgical recommendations, medication use, and the expected course of recovery. Lawyers arrange those materials into a timeline that lets an adjuster, mediator, or jury follow the injury from first symptoms onward. Organized proof also helps answer claims about prior conditions, delayed onset, or breaks in treatment that insurers often use to cut value.
Wage Loss
Lost income reaches past a missed paycheck. Some people cannot return to overtime shifts, physically demanding duties, contract projects, or the same earning path they held before the event. A firm documents that loss through payroll data, tax filings, employer letters, and physician work restrictions. Clear numbers matter here. Precise support turns a broad complaint into a measurable demand that better reflects what the injury has taken away.
Human Damage
The hardest losses rarely appear on a bill. Persistent headaches, interrupted sleep, reduced grip strength, anxiety during travel, and pain with ordinary movement can alter family routines and daily confidence. Those effects need detail, not vague language. Lawyers often use symptom journals, therapy notes, caregiver observations, and real examples from home life. Concrete descriptions help show how the body and mind changed after trauma, which supports fairer valuation.
Insurance Pressure
Insurance carriers are trained to control payout. Quick calls, selective record reading, and early low offers are common tactics after a serious injury. An experienced firm answers with a well-supported demand package, complete exhibits, and a clear explanation of liability and damages. Preparation affects leverage. If the file looks thin, offers usually stay low. When the evidence shows trial-ready work, the bargaining range often moves higher.
State Rules
North Carolina law can sharply limit an otherwise valid claim. The state applies contributory negligence, which means a small share of fault may bar recovery entirely. Most personal injury cases also face a three-year filing period. Lawyers watch those deadlines and wording issues closely because a minor error can erase compensation. Careful case framing from the start helps protect the client from preventable legal damage later.
Trial Leverage
Many claims end in settlement, yet better settlements often depend on real courtroom readiness. Defense lawyers and insurers watch whether plaintiff counsel can question experts, present medical proof clearly, and explain pain-related losses to a jury. That reputation affects bargaining power long before trial. Preparation also improves witness selection, exhibit planning, and case theme development. A credible trial path can raise value even if no verdict is ever reached.
Steady Contact
Strong representation also requires regular communication. New symptoms, added diagnoses, billing errors, and work restrictions can affect value if someone misses or reports them late. Lawyers who stay in close contact can update records before gaps create doubt. Clients also benefit from plain guidance about timing, offers, and treatment issues. Clear communication keeps the case accurate and helps every decision rest on current, usable information.
Conclusion
Maximum compensation does not come from a short demand letter or a quick phone call. It comes from careful proof of fault, thorough medical support, documented income loss, and firm pressure on the insurance carrier. Strong counsel also guards against North Carolina rules that can defeat a claim after one small mistake. For injured people, that disciplined approach matters because fair payment usually follows preparation, persistence, and credible trial readiness.
Real estate has long been one of the most effective ways to build long-term wealth, but many investors spend years acquiring properties without giving enough thought to how those assets will be protected, transferred, or taxed in the future. A strong portfolio can create income for decades, yet poor planning can leave heirs facing unnecessary taxes, legal expenses, and family disputes.
The good news is that real estate owners have access to several tools that can help preserve wealth across generations. Trusts, strategic tax planning, and thoughtful ownership structures can work together to protect assets while making future transitions much smoother. Whether someone owns a single rental property or an extensive portfolio, understanding these strategies can help turn real estate success into lasting financial security.
Why Estate Planning Matters for Real Estate Owners
Many property owners focus heavily on acquisition and management but delay estate planning until later in life. That approach can create problems when properties pass to children, grandchildren, or other beneficiaries. Real estate often represents a significant portion of a family’s net worth, making it important to determine how those assets will be transferred and managed.
Trusts can help avoid probate, maintain privacy, and provide clear instructions regarding property ownership. Depending on the structure, trusts may also offer asset protection benefits and simplify the transfer process after the owner’s death. Investors who own multiple properties frequently use trusts to reduce administrative complications and create continuity for future generations. Estate planning also provides an opportunity to address issues such as property management responsibilities, succession planning, and long-term family goals. Rather than forcing heirs to make difficult decisions during stressful circumstances, a well-crafted plan creates a roadmap that everyone can follow.
Using Real Estate to Focus onbuilding generational wealth
For many families, real estate serves as more than an investment. It becomes a vehicle for building generational wealth through appreciation, rental income, and long-term ownership. Unlike many assets that may fluctuate significantly over time, income-producing properties can provide both cash flow and growth potential. Families who successfully transfer real estate often share one common trait. They view their properties as part of a broader legacy rather than a short-term investment. This perspective encourages thoughtful planning around ownership structures, tax obligations, and succession strategies.
Trusts can play an important role in that process by allowing future generations to benefit from property ownership while maintaining oversight and structure. Parents and grandparents may establish specific guidelines regarding property management, distributions, or future sales. These arrangements help preserve the value of the portfolio while reducing the likelihood of disputes among beneficiaries. Real estate can also teach financial responsibility. When younger generations become involved in managing rental properties, evaluating investments, and understanding cash flow, they gain valuable skills that extend beyond the properties themselves.
Tax Strategies Investors Should Understand
Taxes influence nearly every major real estate decision. Investors who understand available tax strategies often retain more capital for future investments and wealth preservation. One frequently discussed strategy involves 721 exchange and real estate planning.
A 721 exchange allows certain property owners to contribute real estate into an operating partnership in exchange for partnership interests. This structure can provide diversification opportunities while deferring capital gains taxes that might otherwise be triggered through a traditional sale. While the strategy is not appropriate for every investor, it illustrates how advanced planning can help preserve wealth and create flexibility.
Investors should also pay attention to depreciation, cost segregation studies, installment sales, and other tax-efficient approaches that may reduce current tax burdens. Working with qualified legal and tax professionals can help ensure that strategies align with both financial goals and regulatory requirements. Tax planning becomes especially important when preparing properties for eventual transfer to heirs. Decisions made years before a transfer occurs can have a significant impact on future tax outcomes. The earlier those conversations begin, the more options investors typically have available.
Choosing the Right Structure for Long-Term Success
There is no universal solution for every investor. Some families benefit from revocable trusts that provide flexibility and probate avoidance. Others may use irrevocable trusts, limited liability companies, family partnerships, or combinations of multiple structures.
The right approach depends on factors such as portfolio size, family circumstances, tax objectives, and long-term goals. What works well for one investor may create unnecessary complexity for another. That is why planning should focus on the specific needs of the property owner rather than a one-size-fits-all strategy.
The most effective plans often balance simplicity with protection. A structure should be easy enough to maintain while still providing meaningful benefits for asset preservation and future transfers.
Real estate can create substantial wealth, but preserving that wealth requires planning beyond property acquisition. Trusts, tax strategies, and carefully designed ownership structures help families protect assets, reduce unnecessary costs, and create a smoother path for future generations. Thoughtful preparation today can help ensure that valuable real estate holdings continue benefiting a family for years to come.
By Danny Leipziger
China cannot continue to rely on exports to drive its growth, but what are the alternatives?
China ran a $1.2 trillion trade surplus last year, and despite admonitions from the IMF to rely...
The World Financial Review uses cookies to improve site functionality, provide you with a better browsing experience, and to enable our partners to advertise to you. Detailed information on the use of cookies on this Site, and how you can decline them, is provided in our Privacy Policy and Terms and Conditions. By clicking on the accept button and using this Site, you consent to our Privacy Policy and Terms and Conditions. ACCEPT
Privacy & Cookies Policy
Privacy Overview
This website uses cookies to improve your experience while you navigate through the website. Out of these cookies, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may have an effect on your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. This category only includes cookies that ensures basic functionalities and security features of the website. These cookies do not store any personal information.
Any cookies that may not be particularly necessary for the website to function and is used specifically to collect user personal data via analytics, ads, other embedded contents are termed as non-necessary cookies. It is mandatory to procure user consent prior to running these cookies on your website.



 Dr. Gleb Tsipursky was named “Office Whisperer” by The New York Times for helping leaders overcome frustrations with Generative AI. He serves as the CEO of the future-of-work consultancy Disaster Avoidance Experts. Dr. Gleb wrote seven best-selling books, and his two most recent ones are Returning to the Office and Leading Hybrid and Remote Teams and ChatGPT for Leaders and Content Creators: Unlocking the Potential of Generative AI. His cutting-edge thought leadership was featured in over 650 articles and 550 interviews in Harvard Business Review, Inc. Magazine, USA Today, CBS News, Fox News, Time, Business Insider, Fortune, The New York Times, and elsewhere. His writing was translated into Chinese, Spanish, Russian, Polish, Korean, French, Vietnamese, German, and other languages. His expertise comes from over 20 years of consulting, coaching, and speaking and training for Fortune 500 companies from Aflac to Xerox. It also comes from over 15 years in academia as a behavioral scientist, with 8 years as a lecturer at UNC-Chapel Hill and 7 years as a professor at Ohio State. A proud Ukrainian American, Dr. Gleb lives in Columbus, Ohio.
 Dr. Dan Steinbock

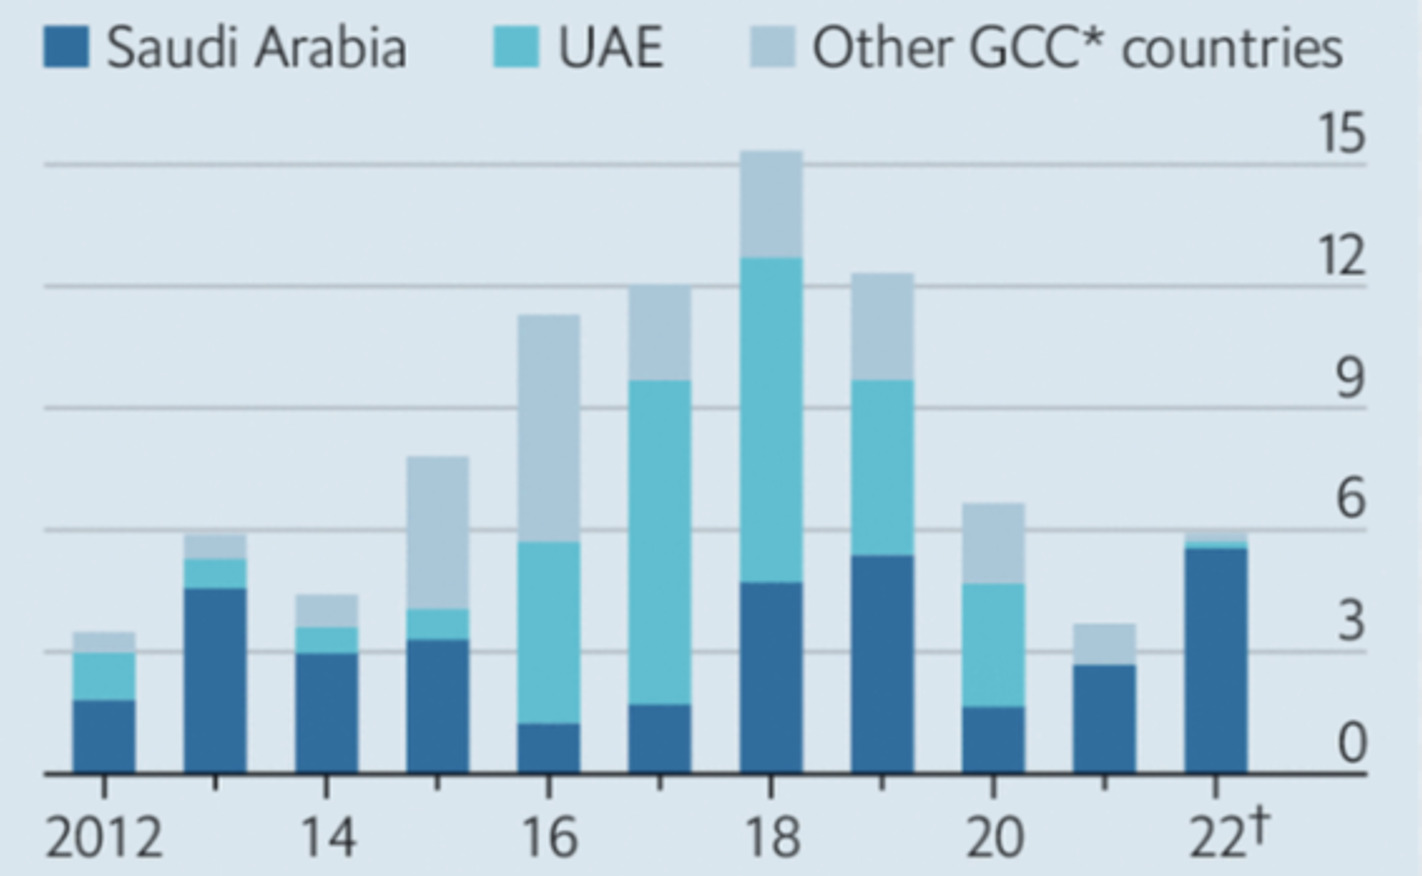
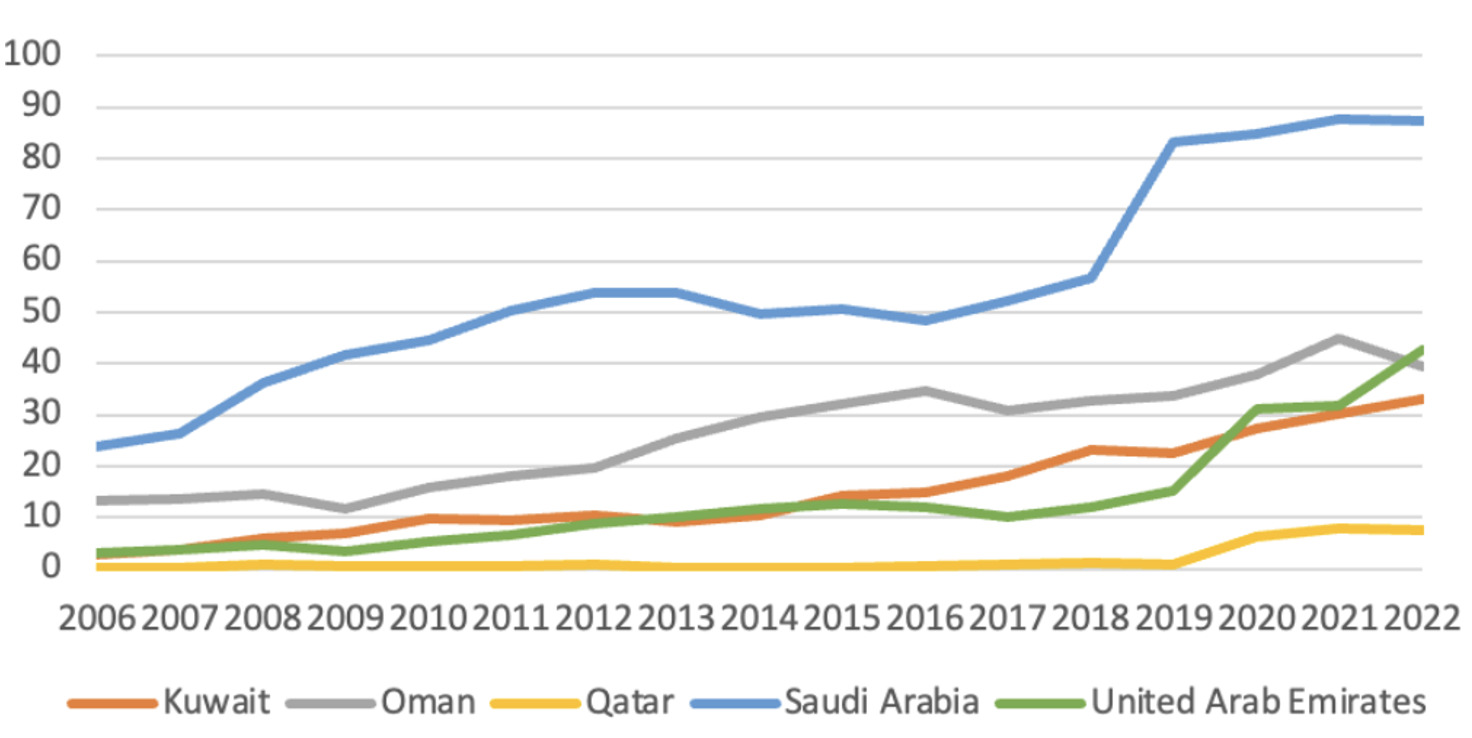
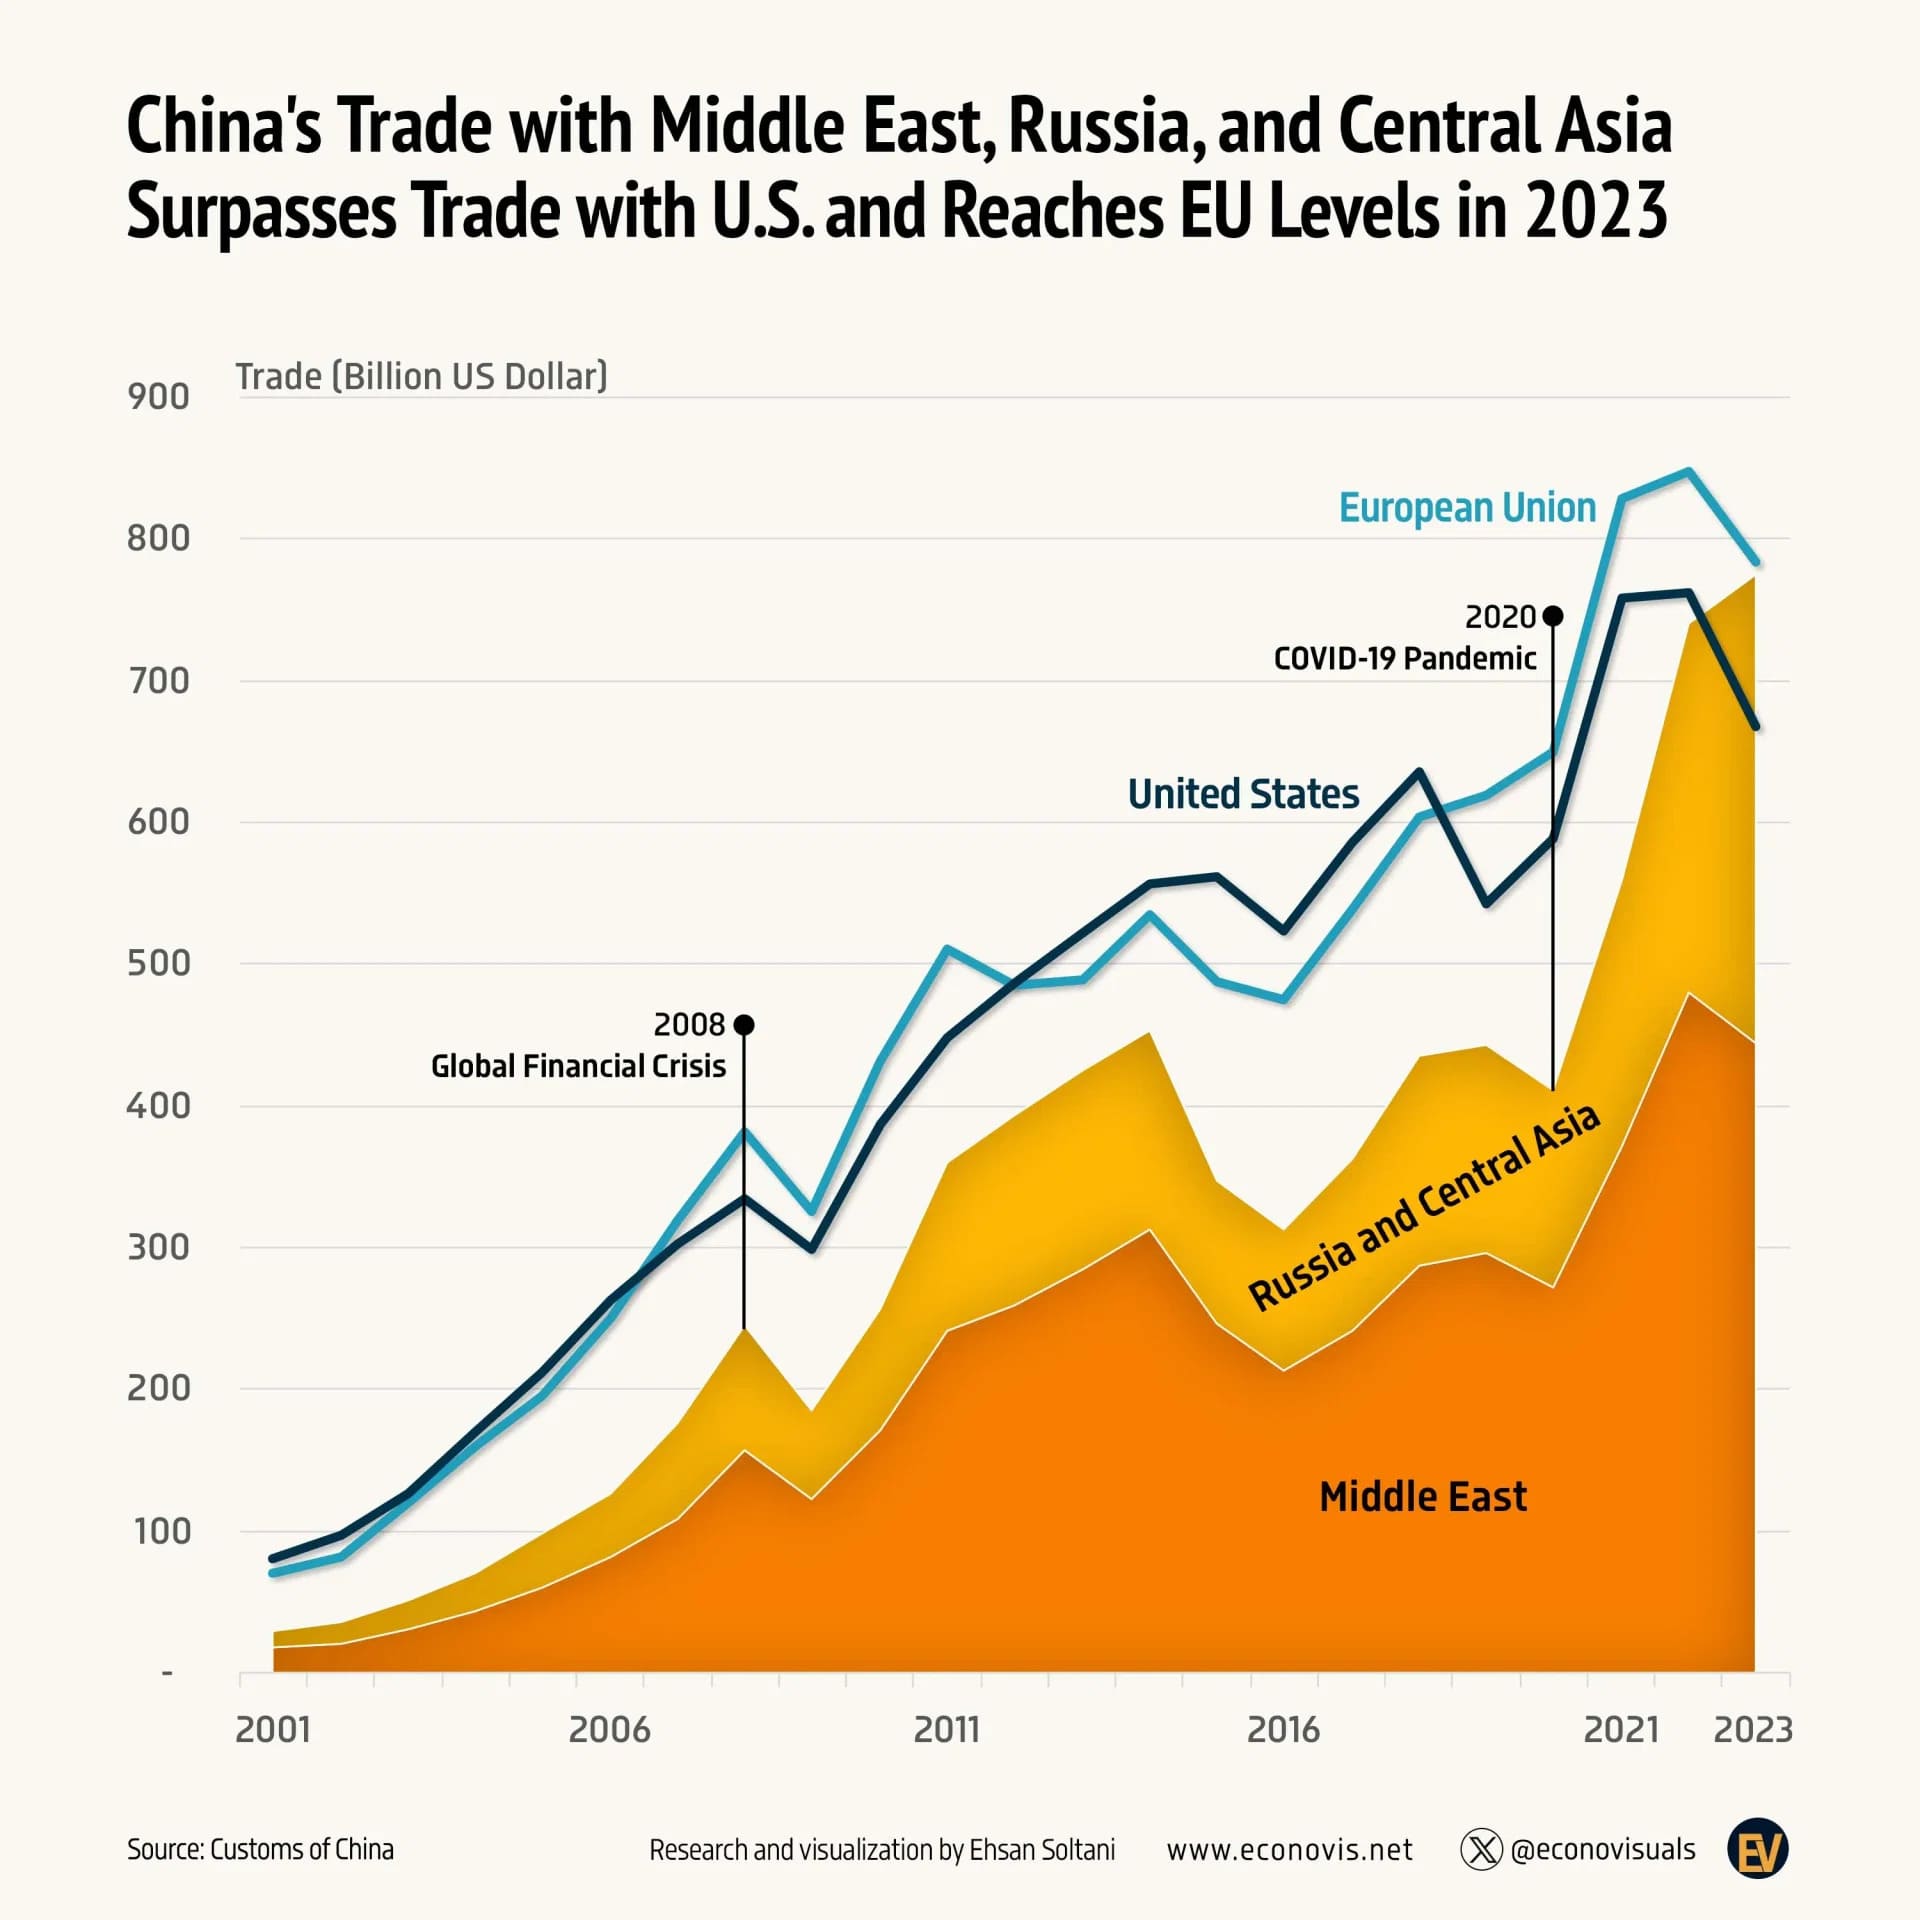
 Dr. Kalim Siddiqui

















































